Small Cap Value Report (Weds 15 Dec 2021) - GDWN, MIDW, SAA, ITS, AVON, CINE

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Agenda -
Paul's Section:
Goodwin (LON:GDWN) (I hold) - interim results show improved profit vs LY. Strong balance sheet. Looks priced about right for now, but there's interesting potential upside from new contracts kicking in.
M&c Saatchi (LON:SAA) - another positive trading update from this PR group. It looks good to me, so am regretting having sold out recently!
In Style (LON:ITS) - interim results from this fast fashion eCommerce (and wholesaling) business aren't bad considering the sector-wide impact from supply chain costs/problems. ITS eked out a small (albeit reduced) profit, and has a strong balance sheet with plenty of cash.
Cineworld (LON:CINE) - terrible news today, as this hugely indebted cinema chain has now lost a big legal case. It looked insolvent even before the adverse judgement, and by my calculations doesn't have enough cash on hand to pay the legal damages. With over $5bn in gross interest-bearing debt, equity holders look very vulnerable to being wiped out either completely, or through a discounted equity raise. Massively risky, I think the equity is worth nothing. Bargepole. That said, it was propped up by the lenders last year, and 4-bagged from the lows (a surge that has since dissipated). So who knows? A share only for reckless gamblers, not investors.
Jack's Section:
Midwich (LON:MIDW) - full year profits to be materially ahead but also notes ‘ongoing product shortages’. Resellers tend to have low margins and struggle to create enduring value, although some do break free and act as larger-scale consolidators. I’m neutral here - good trading, but I'm not sure the company deserves too high an earnings multiple.
Avon Protection (LON:AVON) - another fall for the troubled former High Flyer. Winding down the body armour business is not Avon’s finest moment, but the share price reaction has been extreme, while brokers are forecasting a fairly swift rebound. Ongoing supply chain issues are a concern. It’s worth keeping tabs on, but management has made some big errors and not much has been done to explain these or convince me that lessons have been learned.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Goodwin (LON:GDWN) (I hold)
3200p (down 7.5% at 08:10) - mkt cap £253m
Goodwin is a family-controlled engineering group. It used to rely on the oil & gas sector, but has been diversifying in recent years. The investment case has been explained to me by several shrewd investors, who point to large, long-term contracts (e.g. nuclear waste storage containers) which are coming on stream in the future. Hence it’s all about the future potential for earnings to grow. In the meantime, the business has proven resilient during the pandemic, and is conservatively financed & run.
H1 revenue up 10% vs H1 LY at £68.9m, and is flat vs H2 LY
Profit before tax of £7.7m shows a decent profit margin of 11.2%, and is up 33% on H1 LY
Profits are reported simply, with no adjustments, which emphasises that this is a traditional, conservative company (as we often find with family-controlled businesses - they tend to take less risk than companies run by hired hands trying to maximise their personal gains from share options, and who can walk away if it all goes wrong)
Diluted EPS in H1 is 72.12p, up 30% on H1 LY - which seems a decent result, although I can’t find any broker forecasts, so don’t know what was expected.
Note the significant minority interests (called “Non-controlling interests”) which accounts for £458k of retained profit, or 7.6% of total profit (this relates to minority shareholders in subsidiaries whose entire profits are consolidated into the group accounts). This is adjusted for in the EPS calculations, so it’s best to always use EPS when doing a valuation.
Balance sheet - looks good. NAV of £114.6m, less £24.5m intangible assets, results in NTAV of £90.1m, which is more than adequate. It’s a fairly capital-intensive business, with fixed assets of £82.9m.
Working capital looks very healthy, with a current ratio of 2.37 - helped by bank loans moving down from current, to non-current liabilities last year - which must have been due to extending the maturity of bank facilities.
I’ve checked the last annual report, which shows £32.8m of freehold property, which are on the balance sheet at cost (see note 11), hence could be under-valued compared with current market value. Family-owned businesses like this can sometimes be a treasure trove of hidden property assets, which lowers risk for investors, often without us even being aware of it.
Net debt is £34.8m (ignoring lease liabilities), which seems OK to me. The going concern note refers to this as “modest”, which I don’t entirely agree with. I would say it’s acceptable, or not excessive, rather than modest. Banking headroom is described as “acceptable”.
I've searched for the word "pension", which doesn't appear, so hopefully that means no legacy issues?
Overall, no issues with the balance sheet - this is a solidly financed business.
Cashflow statement - working capital increases have absorbed most of H1 cash generation.
Capex was quite heavy at £9.2m in H1.
Outlook - generally sounds positive -
At the half year the Group's workload remains steady at £156 million and does not yet contain some of the major projects that the Mechanical Engineering Division has confidently been pursuing within the military, nuclear waste re-processing and surveillance markets.
Even with the expectation of an increased order input over the next six months, we expect the second half year pre-tax profits of this financial year to be possibly slightly better than the first half and for the benefit of increased activity and profitability to be realised over the next eighteen months.
This improvement is a feature of the strategic transformation of the foundry and its progress in creating an efficient environment to deliver high volume, high quality products for nuclear waste and cast naval components for its new customer base following the decline of its traditional oil and gas business. Furthermore, whilst we continue to experience inflationary pressures, the offsetting benefit of increased selling prices will be recognised within the next financial year.
The momentum within the Refractory Engineering Division shows no signs of slowing and the Group's eight companies supplying consumables to the jewellery casting, fire protection and construction sectors are well placed moving forward to continue to deliver strong results subject to raw material availability and consumer demand.
Valuation - is tricky, with no broker forecasts available to me.
Taking a stab at it, H1 was 72.1p, and the outlook comments say H2 could be “slightly better”, so maybe 80p? That gives c.152p for the full year, a PER of 21 times - not an obvious bargain, but not excessive either.
Given the upside from large, long-term contracts, alluded to in the outlook comments, I think this valuation seems reasonable, with medium term upside perhaps?
My opinion - for long-term holders, this looks a reassuring update.
There’s probably not enough excitement to attract new investors at the moment, especially given how strangely bearish & short-termist the small caps market seems to have become in recent months.
The share is extremely illiquid, with few traded, as it seems to mainly be held by long-term investors. I like it - it’s good to have some really solid, traditional companies in a portfolio, to provide stability and dividend income. There’s also interesting growth potential with GDWN from its diversification strategy away from oil & gas.
.
.
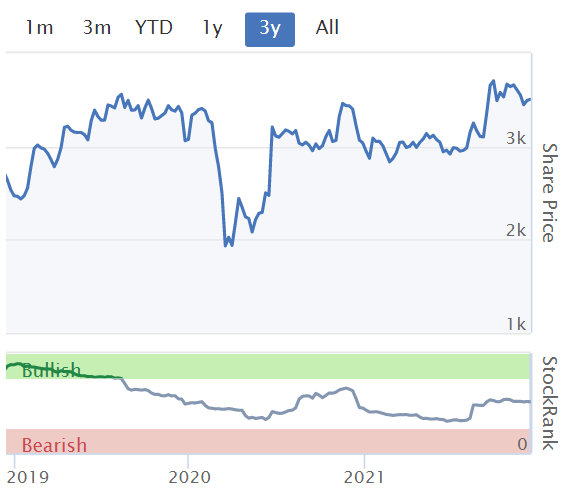
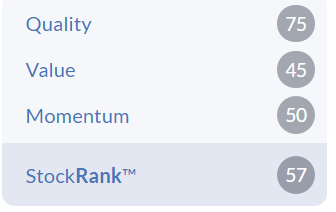
GDWN has an upper-medium StockRank, although with no forecasts available, the algorithms don't have key forward-looking data to assess -
M&c Saatchi (LON:SAA)
155p (up c.3% at 08:51) - mkt cap £189m
This PR/marketing group has been putting out positive updates for a while now, and we get another good one today -
Further to the last trading update on 23 November 2021, the Company is pleased to announce that trading has continued to be strong and, as a result, management now believes full year 2021 operating profit will be materially ahead of expectations.
Activity in the final quarter has been strong across the group, particularly in the Performance Media and Global and Social Issues divisions and the UK Agency. The strong performance was largely driven by new assignments from existing clients, and we expect this continued trend to be reflected in the December results.
Valuation - as you can see, the broker estimates are on a recovering trend, and today’s update will see a further rise in forecasts.
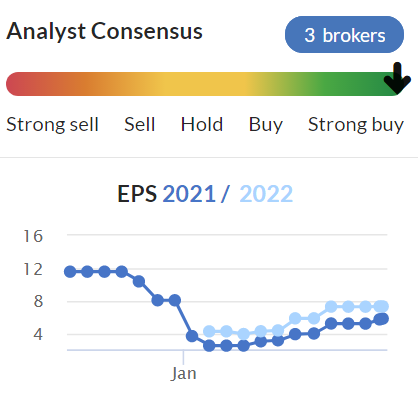
Should we be valuing the share on the old forecasts of 12p earnings maybe, since the group seems to be recovering towards pre-pandemic trading? That would drop the PER to about 13, which is good value.
My opinion - I dipped my toe in here with a small starter sized position a few months ago, but it didn’t survive a recent portfolio trim. Maybe that was a mistake to sell them, given the continuing positive newsflow? This share does look quite good, with historic problems seemingly now resolved, and a strong recovery in earnings underway.
.
.
In Style (LON:ITS)
91.5p (down 9%, at 09:25) - mkt cap £48m
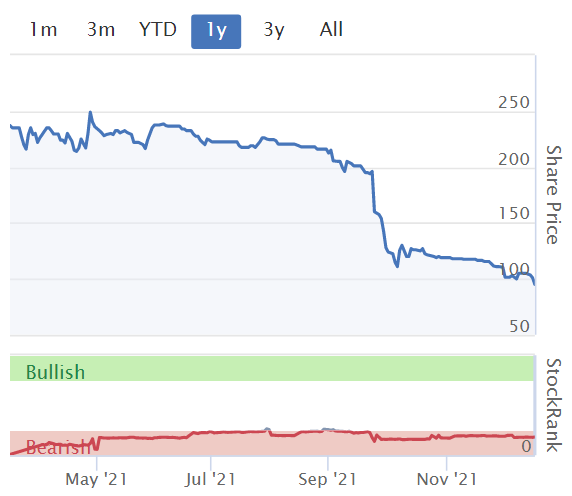
Checking our archive, I reported on a profit warning from this fast fashion eCommerce business here on 24 Sept 2021. That set off a steep fall in the share price, which has continued with today’s update. There were some positive elements in the last update, but overall I was inclined to sit on the sidelines because ITS did not give enough factual information on the key problem areas - supply chain freight costs & delays (no surprise there), and a much higher customer returns rate.
Moving on to today’s update, we have -
In The Style, the fast-growing digital womenswear fashion brand with an innovative influencer collaboration model, announces its results for the six months to 30 September 2021 (the "Period"). Financial highlights in this report are provided on both a year-on-year basis and two-year basis, reflecting the exceptional trading performance and growth in the prior year period:
A period of very strong revenue growth across all channels against an exceptional prior period
H1 revenue £29.8m (up 39% on H1 LY, and up 246% vs 2 year comparative pre-pandemic)
Growth was strongest in the relatively smaller wholesale channel, up 139% to £6.9m (23% of total revenues)
Profit before tax halved to £890k in H1 - but to be making any profit at all, as a small player in a highly competitive sector, is not too shabby.
Supply chain disruption and a higher customer returns rate are mentioned as adverse factors, previously flagged in the 24 Sept update. Action has been taken to try to reduce returns rate -
Since the Period end, return rates have reduced in line with expectations reflecting the seasonal change in the product mix, and we are confident of achieving a lower underlying returns rate over the medium term.
Supply chain - sounds under control, and at some point the stock market should start to anticipate upside on profits from supply chains improving, and shipping rates normalising -
As previously indicated by the Group, industry-wide global supply chain disruption and increased associated costs are expected to continue through at least the second half of the year. We continue to actively manage these external challenges as far as is possible and, so far, have successfully amended collection launch timings and deliveries into wholesale partners to minimise disruption. Detailed plans are in place to mitigate the longer-term cost impact of these external headwinds through both sourcing and product pricing initiatives.
Current trading & outlook - sounds OK to me, overall -
● | Since the end of the Period and through the important Black Friday and December trading period so far, the business has continued to perform well with direct-to-consumer sales continuing their strong growth trajectory. |
● | As anticipated, sales to wholesale partners have been lower than the prior year since the period end reflecting the phasing of orders, however the Group remains confident in achieving continued progress through this channel in the second half. |
● | Notwithstanding the industry-wide supply chain disruption that is expected to continue into the second half, the Board remains very confident in achieving the Group's growth plans and the brand's very exciting potential. This is underpinned by the strength of In The Style's differentiated business model and distinctive brand as well as the investments made in the Group's leadership team and infrastructure in recent periods. |
Balance sheet - looks good. £12.1m NAV, less £1.6m intangible assets = NTAV of £10.5m, including £9.9m of net cash.
Trade receivables looks very high at £6.0m, which suggests to me that ASDA and other wholesale customers might be using ITS like a bank - paying ITS invoices very late?
Overall, there are lots of very similar companies competing in this space, some of which are precariously financed (e.g. Missguided). Therefore having plenty of cash in the bank, and operating at a (modest) profit gives ITS a good chance of survival, where others may fall by the wayside.
My opinion - I was expecting to completely dismiss ITS as a potential investment, but at £48m market cap, and with reasonable numbers published today (considering the sector headwinds), risk:reward actually doesn’t look too bad.
My main problem with fast fashion eCommerce, is that the sector is so competitive, a small player like ITS just doesn’t have the marketing budget to take on the bigger competitors.
Also, with investor sentiment currently so negative towards this sector (e.g. Boohoo (LON:BOO) and Asos (LON:ASC) - both of which I hold), then I can’t see any reason to pick a small, me-too competitor, over the much more dominant (and now much cheaper), larger companies in the sector.
Some investors are worried about the impact of Chinese competitor Shein, which could keep the sector under a cloud for a while, who knows? I think it all depends what growth these companies can deliver going forwards, once the effect of the pandemic has washed through.
Overall then, on ITS I’m neutral. There are some attractions to the share, but I see larger competitors as probably having more upside potential on current bombed out share prices.
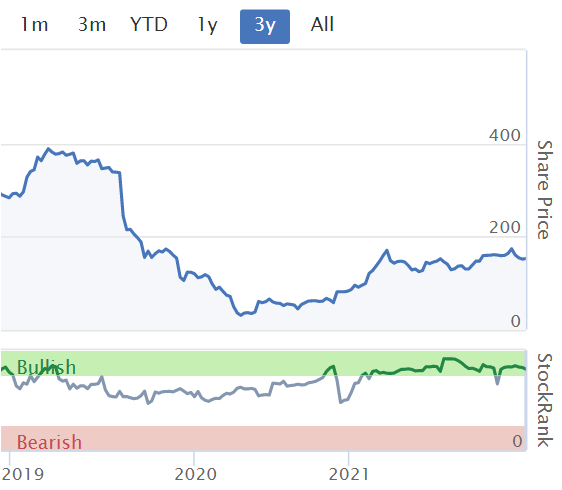
A disappointing IPO, but to be fair, the whole sector has de-rated massively since ITS floated -
.
Cineworld (LON:CINE)
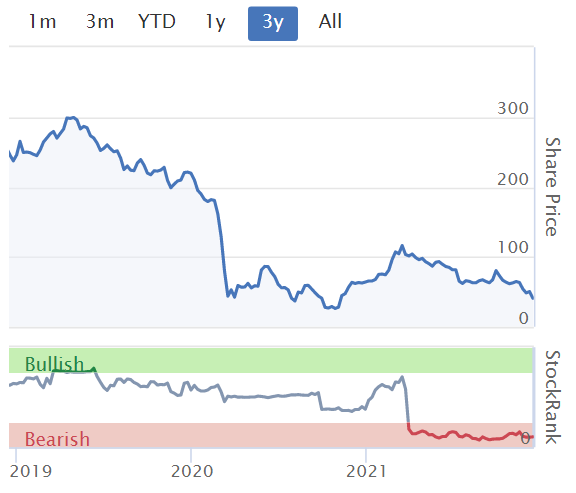
33.0p (down 27%, at 10:44) - mkt cap £461m
This cinema group embarked on an extremely reckless, debt-fuelled acquisition spree, and ended up with an insolvent balance sheet, just as the pandemic struck last year.
My review of it here on 12 March 2020 pointed out that with NTAV negative at $(3.1)bn, there was an extremely high risk of insolvency. As it turned out, the shares bottomed out in Oct 2020, then annoyingly went on to 4-bag by spring 2021, as people gambled on it surviving. It just shows, that market sentiment can be wildly wrong, both on the upside and the downside sometimes. Fundamentals have reasserted their dominance, with CINE shares crashing back down again, having lost the speculative froth.
I remain of the view that the equity is worth nothing, because the company is in such dire straits with the balance sheet debt. Not to mention on-off restrictions with covid hurting cinemas, but also stoking pent-up demand when they can re-open maybe? The last trading update showed a steadily improving trend in attendances.
Maybe the banks want to keep the equity afloat, to provide a route to refinance the company with fresh equity in due course, thus reducing the risk for the lenders? Who would want to put in more equity though, and at what price? Even if CINE survives, there’s a big risk of a highly dilutive equity fundraising being forced on the company - giving existing holders that awful quandary of whether to accept massive dilution and write off your investment, or to stand your corner and put more money into a bad investment in the fundraising.
More bad news today, Cineworld has lost a big legal action against it regarding an aborted takeover deal -
On 6 July 2020 Cineworld confirmed that Cineplex had initiated proceedings against Cineworld in relation to Cineworld's termination on 12 June 2020 of the Arrangement Agreement relating to its proposed acquisition of Cineplex (the "Acquisition"). The proceedings alleged that Cineworld breached its obligations under the Arrangement Agreement and/or duty of good faith and claimed damages of up to C$2.18 billion less the value of Cineplex shares retained by Cineplex shareholders.
Cineworld defended these proceedings on the basis that it had terminated the Arrangement Agreement because Cineplex breached a number of its covenants and counter-claimed against Cineplex for damages and losses suffered as a result of these breaches and the Acquisition not proceeding, including Cineworld's financing costs, advisory fees and other costs.
The Ontario Superior Court of Justice has now handed down its judgment. It granted Cineplex's claim, dismissed Cineworld's counter-claim and awarded Cineplex damages of C$1.23 billion for lost synergies to Cineplex and C$5.5 million for lost transaction costs. Cineworld disagrees with this judgment and will appeal the decision. Cineworld does not expect damages to be payable whilst any appeal is ongoing.
My opinion - Google tells me that 1 Canadian Dollar is worth 59p, so C$1.23bn damages payable by Cineworld is about £730m - considerably more than CINE’s current market cap, so this is a seriously big deal. Is this liability enough to sink the company?
I’ve checked through the RNSs, and the last reported liquidity position was on 12 August 2021, with the interim results. This showed cash of $436.5m at end June 2021, plus another $200m term loan raised in July 2021, so $636.5m in total, or £482m in sterling. That’s not enough to pay the £730m damages, so I think CINE would need to raise yet more debt, and/or equity, to pay this fine.
The scale of its existing debt is mind-boggling. It had $4.86m gross borrowings at end June, so with the $200m new loan in July 2021, the total interest-bearing debt will now be over $5bn.
How much are its assets worth? There’s only $395m shown on the last balance sheet as land & buildings. The rest is leased. Plant & machinery of $861m probably doesn’t have that much resale value secondhand. So it’s a hopelessly insolvent balance sheet, with the only value coming from hope that cinemas can trade normally (and profitably) again at some point in the future, when the pandemic’s over. Or maybe some cinemas could be sold, to raise cash?
All in all, a dire situation. Therefore the equity is a pure gamble on CINE somehow surviving (maybe its appeal against the judgement might succeed)? Even if it does survive, at some stage this horrendous balance sheet will need to be refinanced.
I wouldn’t touch it with a bargepole, because the risk of a 100% loss is so high.
.
Jack’s section
Midwich (LON:MIDW)
Share price: 635.50p (+9.57%)
Shares in issue: 88,735,612
Market cap: £563.9m
Midwich distributes audiovisual (AV) tech to the trade market, with operations across EMEA, North America, and Asia Pacific. It was founded in 1976, specialising in computer distribution, before shifting to AV in 1995, and since 2006 it has been acquiring smaller distributors at pace.
Shares are roughly double the IPO price but have only just recovered to pre-pandemic highs (but note the softer share price in 2019, before Covid).

The group’s strategy has seen the top line grow at a good rate, while the operating margin has remained around the 4% mark. Understandably, Midwich made a loss in 2020 but EPS are forecast to bounce back more or less immediately.

This is a short update so I’ll quote the bulk of it.
Despite ongoing product shortages, the Group's trading performance has been stronger than expected since the Interim Results, published on 7 September 2021, with the UK & Ireland and EMEA performing particularly well. As a result, the Board expects that adjusted profit before tax for the year ending 31 December 2021 will be not less than £30 million, which is materially ahead of its previous expectations.
The group expects to make its scheduled trading update on 19 January 2022.
Conclusion
Distribution and reselling tends to be a low margin business and is not typically where the real value accrues in the food chain. That said, there are some good operators that have proven themselves over longer periods of time. Typically those that are well-run and have reached a large enough scale to begin acquiring smaller players.
For these companies, their economies of scale allows for a higher level of reinvestment, financial security, and the ability to consolidate fragmented markets. Given Midwich’s history here, it seems as though it might fit into this camp.
And the group is materially ahead of expectations - perhaps, in a tough market, this is an operator that has managed to take share and stands to benefit more from a recovery in demand.
That’s just a hypothesis though, and “supply chain disruption” is the phrase on most investors’ lips. Midwich is not immune here. It’s a dynamic situation so, while it’s not having an impact right now, that can always change.
There have been some significant director sells over the past couple of months too, coinciding with the recovered share price. I’m not about to draw a link between these sales and the short term outlook just yet, but it’s understandable if management thinks this is an opportune time to crystallise some value.
This isn’t the kind of business model I’m focusing on in the current conditions, so I’m neutral despite the ‘trading ahead’ announcement. I’m looking for higher margins and more obvious pricing power.
Avon Protection (LON:AVON)
Share price: 931.5p (-13.59%)
Shares in issue: 31,023,292
Market cap: £289m
This is one of the more intriguing situations around at the minute - previously viewed as a very high quality (and highly rated) but the story has come undone quite dramatically due to a concerningly fundamental aspect of its recently-acquired body armour business.
The market reaction has been brutal.

Highlights:
- Orders received +34.9% to $282.7m and closing order book +40.6% to $143.1m,
- Revenue +16.2% to $248.3m,
- Adjusted operating profit -42.9% to $22m, reported operating profit down from $8.9m to -$29m,
- Adjusted basic earnings per share of 60.6 cents (-38.5%) and a reported basic loss per share of 79.9 cents,
- Net debt has grown to $55.9m ($26.8 ex-leases), from a net cash position of $118.7m.
Armour
Having conducted an in-depth strategic review of our armor business, we have concluded that an orderly wind-down of the body and flat armor business over the next two years to fulfil our existing body and flat armor customer commitments is in the best interest of our stakeholders as a whole.
Expected net cash costs of closure and right sizing the continuing operations of between $3 and $5m in total across FY22 and FY23.
A wind down suggests Avon has not even contemplated a sale. They're closing down a recently acquired business, which is never a good look. This division was supposed to be central to the group’s future, so how has it all unwound so quickly? When you talk about management’s capital allocation skills as a key driver of future growth, this is an example of pretty dire misallocation.
No surprise, then, to see a capital allocation policy review:
Given the strong financial position, expected cash generation in our 2022 financial year and the Board's intention not to initiate any further major merger and acquisition activity until after our 2022 financial year the Board is undertaking a review of the Group's capital allocation policy.
Interestingly, this might include a share buyback programme.
Net exceptional non-cash costs of $31.1m consist of asset impairments of $46.8m, partially offset by a $15.7m contingent consideration provision release. This does not fully explain the substantial $51m difference between adjusted and reported operating profit. Other charges include $14.2m of amortisation of acquired intangibles and $5m of acquisition and integration costs related to Team Wendy and Ceradyne.
Respiratory and head protection
Respiratory protection remains well invested and is a ‘growing business with strong profitability and cash generation’.
The ramp-up of NATO framework contract for FM50 is a key growth driver and there are further opportunities with the U.S. Department of Defence (DOD), Rest of World Military, and First Responder customers.
Outlook
Growth expectations for FY22 and beyond are underpinned by long-term contracts in respiratory and head protection; opening order book excluding armor of $116.5m.
We are continuing to experience the impact of disruption in global supply chains and customer order pattern volatility, which we are actively working to mitigate, Given the ongoing challenges, we are taking a cautious view on the anticipated rate of growth for FY22 at this stage in the year. As such, the Board is guiding to revenues excluding armor, in FY22 of between $260 and 290 million, being growth of between c. 8 and 20%, with further revenue of up to $25 million from the armor business depending on the timing of DLA ESAPI product approvals
We expect our adjusted EBITDA margin to recover materially in FY22 given operational leverage and the actions to address overheads.
Conclusion
Avon has fallen from a High Flyer to a potential turnaround. That typically attracts a different crowd of investors. With sentiment shot and likely some churn in the shareholder base, my assumption is that there is no rush to make a decision just yet.
Brokers have reduced their earnings per share forecasts for the current year from 134.44p at the start of the year to just 54.64p, with the company figure coming out at 60.6c - quite a change, and I’d be surprised if anybody has a firm handle yet on the group’s revised prospects, although forecasts do assume a swift rebound.
The recent director buys at 2,000p-3,000p are perplexing. I listened to the investor call this morning and the tone did not encourage me - not much time at all spent on past mistakes, but there has been a profound misjudgement here which needs to be addressed. Otherwise, why should we provide capital?
There could be value at these levels - there was a lot of growth priced in just a few months ago - but credibility and market sentiment have taken a big knock. It’s a bad time for turning around, too, with ongoing supply chain issues, so it could be that the bad news is not over.
I’m keeping it on the watchlist given the revised valuation and remaining healthy business lines, but I don’t feel the need to rush in and call the bottom, and I’m not convinced at present.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Not looking great but have a look at Next (LON:NXT) last few pages of reviews also not great. It seems a lot of the negativity surround delivery timescales and lack of stock. Finally I believe Boohoo (LON:BOO) s reviews are too good. I can't understand why boohoo would have much better ratings than their sisters nastygal and PLT for example. I'd be interested in thoughts on this. I believe PLT are fulfilled from another distribution centre but that surely can't explain the disparity.
Well, red across the board again today.
I'm seeing a lot of stocks well entrenched in downtrends, sitting below the 10day Moving Average.
Markets are just horrendous right now.
yep, red right across my portfolio, again!! Red might be a festive colour but I’d much prefer green!!
Yes, a very poor day today and mine have fallen considerable more than the indices.
Even the US is catching the Omicron or whatever the latest is called cold. Or more likely inflation risks.
Anyone know about the Hong Kong exchange - invest in the perps methinks.
Results from Hollywood Bowl (LON:BOWL) look reasonable but wondering what will happen if Covid restrictions get worse?
Especially as the govt has so far been reticient to roll out financial support measures for affected businesses. In the form of furlough, business rate reliefs, rent moratoriums, etc.
Arguably allowing all hospitality businesses to continue to run but asking the public to minimise socialising and hitting trade by 30%, 40% - and not giving financial support to businesses - means many will now go against the wall.
Its a very different dynamic to last year, where businesses could close 100% with lots of support provided.
Re Pensions & Avon Protection (LON:AVON)
"I've searched for the word "pension", which doesn't appear, so hopefully that means no legacy issues?"
Comparing the leverage (total vs. +pension) ratios on the Stockreport would confirm this. Thought this might be a useful tip to share.
(Don't hold AVON)
@Paul - could you have a quick look at my post in the Boohoo (LON:BOO) general discussion pls. Would be interested in your take given your fashion retail background
Paul may I second David’s request on Boohoo (LON:BOO)
Thank you.
Regards
Michael
Boohoo (LON:BOO), Revolution Bars (LON:RBG) ....all big (paper) losses and mounting!
So glad I did not go into Joules (LON:JOUL) . I looked at trust pilot reviews of Joules yesterday, all horrendous and customers echoing they had not rec'd goods in line with the supply chain issues reported.
Boohoo (LON:BOO) has much better Trust Pilot reviews.
"I looked at trust pilot reviews of Joules yesterday, all horrendous and customers echoing they had not rec'd goods in line with the supply chain issues reported.
Boohoo (LON:BOO) has much better Trust Pilot reviews."
Hmmm.. I think you need to recheck your TrustPilot 'facts'....
Epsilon,
I think it is actually you that needs to brush up on their Trustpilot interpretation skills. Of the last hundred reviews for Joules (LON:JOUL) , just 5% are 5* and 4% are 4*; however 85% are 1*.
They may have been excellent in the past but they seem to be trashing their brand at present.
To illustrate:
A dismal trend, I would suggest.
Tks Effortless Cool! Exactly....
How do you find that graphic on the website?
Thanks
L1
"See a detailed overview". Lots of interesting info there.
https://uk.trustpilot.com/revi...
Ooh...... liquidity is super high atm (laugh)
Just noticed that National World (LON:NWOR) has fallen over 6% (£3.7m) on....drumroll......£4800 worth of shares traded :D
From a market perspective looks like institutions have closed shop for the year a couple of weeks earlier than usual and retail investors are flocking to the hills - with any selling met by FOSI (fear of staying in) selling. Can't see this mood changing till at least the new year now alas.
Don’t be too despondent David. Here are 3 reasons to be optimistic:
1. Everyone is gloomy/despondent which is a sign we might be near a turning point
2. With such tight liquidity it will only take a few buyers to push prices up significantly
3. Omicron cases are rising so fast that we will know by Christmas if it’s a big problem. Or storm in a tea cup. If it’s the latter then the buyers will return rapidly.
Maybe I’m delusional but a classic Santa rally is supposed to happen after Christmas. Assuming good news regarding Covid then maybe this year will be a good one.
If anyone is not confident in their stock picks they shouldn’t be in them in the first place. If they are it is where they are in 2 or 5 years that matters not this week or this month or even this year. my shares are almost all looking cheap if not very cheap, for me now is most definitely not the time to sell and probably the time to buy
That is the key point. If you are going to sell then sell early. Don't wait until it's all gloom - that's the way lots of people lose money longer term. I'm not generally trading and I'm broadly comfortable with my investments over a 1-5 year view, though any serious or persisting economic woes may disrupt some of them of course.
I'm not despondent, just observing where we appear to be. When stocks are moving around 6-8% on £5k worth of trades you know that the market is so illiquid its probably best to do nothing at all. It means anyone making a market doesn't want stock on their balance sheet so prices will get buffeted about - it becomes a matched book. In essence the market is closed. Often the same is true in the lead up to (and just after) Christmas but usually people are in a cheery mood so prices are pushed upwards. This year the opposite is true unfortunately. So now we wait.
We had a lockdown last December, I still managed a 4.7% month, I think the MM's are making hay while they can. I'm regularly seeing shares in my portfolio pushed down 7,8,9% during the day and then recovering, it's all money for the MM's. At the moment it's Sanderson Design (LON:SDG) turn.
I believe a greater correction lies around the corner. Remember the large caps have had little selling pressure applied to date globally.
Avon Protection (LON:AVON)
One would hope there are investigations going on in the manner of Autonomy. A recently acquired business found worthless - this doesn’t pass the sniff test.
No position. Briefly held Avon got out for a moderate loss on the body armour news.
Very frustrating that Time Finance (LON:TIME) cannot even provide a guidance to market expectations, more than halfway through the financial year.
Despite that, it looks like lending volumes are increasing (slowly) and a bit of value situation is developing, with NTAV of £30m and market cap of £21m. Rare to see a 30% discount on TNAV for a profitable business not in distress.
(I Hold)
Time Finance (LON:TIME)
Very frustrating that Time Finance (LON:TIME) cannot even provide a guidance to market expectations, more than halfway through the financial year.
I think this is a symptom of many listed companies - and frankly is a bit of a disgrace when it happens -so nil marks out of ten for this company today from me - really all companies should follow the lead of next and communicate in every update curent year end expectations with regard to a range for sales and profits. I am sure fyffes many years ago did this and was listed on aim so i am not convinced there is reason why all companies cannot go down this simple route. I really don't care how wide the range is here - to me its fine to start off with ridiculkously high spread if you are unsuare early in the year - just give us some numbers and not waffle.
an example this week was the Victorian Plumbing (LON:VIC) when many peeps thought the reason for the shareprice drop was to do was unexplained or didn't make sense based on the release that day - when actually the company was dropping a mother darling of a profit warning for the current year worded in such a manner that many didn't even noticethat they were doing that - Paul was spot on with his comments that the company was without really saying clearly taking a complete hatchet job to current year expectations - as can be evidenced by updated figures that are now showing on stocky - i think the P/e this year is still expected to be nearly 20 ! - so comments that this share is now cheap after the drop were mind of the mark due to the huge downgrades that have been met. I would concede the share may be cheap if this sets a low bar from which the company can outperform going forward.
an example this week was the Victorian Plumbing (LON:VIC) when many peeps thought the reason for the shareprice drop was to do was unexplained or didn't make sense based on the release that day - when actually the company was dropping a mother darling of a profit warning for the current year worded in such a manner that many didn't even noticethat they were doing that
The problem with that is that the near immediate price drop indicated that the market did understand it was a profit warning. It just required a bit of effort to go through the figures rather than just taking in the headlines: the devil is in the detail.
I agree that the company should have been clearer in its communication, but ultimately they gained no advantage by being opaque, and could never have done so. But obviously many PI's operate off the headlines and not the details. As ever, caveat emptor applies.
timarr
Victorian Plumbing (LON:VIC) I don't agree, the shares fell 40% on the day, so why are you saying the market did not realise it was a profit warning? Also the directors have now been buying shares at around 95p. Paul said "it looks good value now, at 99p. Tempting."
Shares have since gone up around 15% from the lows.
PE(f) has gone from 18 to 18.6 on Stockopedia. Brokers rating has gone from hold to buy.
Victorian Plumbing (LON:VIC)
Rustbucket
I don't agree, the shares fell 40% on the day, so why are you saying the market did not realise it was a profit warning?
I did not say the market did not realise it was a profit warning - i am aware the market knew it was a profit warning and i knew it was a profit warning and the company knew it was a profit warning - just that some people did not realise it was the huge profit warning it was - if you check the early comments on the day of the news there was surprise from some as to why the shareprice dropped as much as id did whne the announced numbers werent that bad - when really there would not have been surprise if company had clearly said we expect to only do 5p eps current year now - if that had been communicated at 7am everyone would have said before 8pm share price is gonna tank big style. The issues here is that until we get updated broker forecasts made availble hours or days later we don't know how bad the bad news is if the company doesnt say. IMHO thats an unfair market for smalll shareholders until they can view updated broker notes.
Victorian Plumbing (LON:VIC) But broker forecasts are not very accurate anyway. Well lots of people did realise otherwise the share price would not have dropped so much. If these forecasts are out today then the share price should fall considerably, going by what you are saying. The same brokers doing the forecasts, have increased their average rating from hold to buy.
I agree that PIs, should have access to the same information, as professionals, but that does not happen in the UK. Yes it's unfair. Also we often don't get to buy shares at a discount when new shares are placed.
Does Victorian Plumbing (LON:VIC) look cheap though?
According to stockopedia it has a value of 48. The PE has obviously dropped from ipo but still looks high compared to market sector.
It was a good sign the bod buying but let’s face it, it was pocket change to him considering the amount he sold and the price when it ipo’d.
There is no real sign of a reversal in the charts but you can’t read too much into that as there is very little chart data due to recent ipo
I remember talking to a friend a couple of years ago who sits with the board at Lakeland Ltd. I asked if they would likely ipo. He said yes, but only when they have peaked so they could sell at maximum profit. Always makes me skeptical off ipos.
RE: Victorian Plumbing (LON:VIC)
if you check the early comments on the day of the news there was surprise from some as to why the shareprice dropped as much as id did whne the announced numbers werent that bad
The first of those comments was from me, having skimmed the RNS while in the middle of a stream of meetings. And so what?
We can't rely on broker's notes, we have to do our own research. Brokers are often as biased as everyone else to the point I no longer bother reading most of them. Relying on other people is just outsourcing your errors, but we can never outsource our losses.
timarr
The first of those comments was from me, having skimmed the RNS while in the middle of a stream of meetings. And so what?
My point was that IMHO its poor crack for the company to not really adequately explain what the new expectations are clearly , particulalry if its a huge profit warning (as it clearly was) , my sympathy was with everyone left speculating as to why the shareprice was down 40% when it was done in slightly sketchy manner - you were far from being alone in thinking the drop seemed excessive at an inital glance. Similar to Time today - not really saying anything helpful whatsoever , very unhelpful for us small shareholders to try and make sense of whats up - if we dont get some firm numbers given or reference to numbers that may exist.
"... we can never outsource our losses"
Maybe we can't, but a litany of suspicious price movements, director sales and IPOs suggests that others still can.
Secure Trust Bank (LON:STB) is on a discount too, and for my money a better business than Time Finance (LON:TIME)
Avon Protection (LON:AVON)
Closing the troubled division and costs thereof revealed.
Upbeat noises about what remains - growth of between 8% to 20%.
Would be interested in Jack's/Paul's comments (and any others).
Currently down 16% (been worse).
Phil
(Don't hold)
So what's left of Avon Protection (LON:AVON) now? So single product line and concentrated client list? That worries me.
I’m no Avon expert, but helmets and respirators suggest more than one product.
Theres always cosmetics
- sorry wrong co.
Character (LON:CCT) (I hold)
"The Board believes that margins will be under pressure due to high freight rates and increased materials and labour costs, however, it is satisfied that the Group remains on target to meet current market expectations."
I don’t know whether to be relieved that they’ve managed to stay on target despite the headwinds, or be disappointed it’s not better.
I'm pretty pleased with those results. Firstly they seem to be selling more and more to the US. Cracking that market is tough so to be doing it organically bodes well for future growth.
Demand is strong but despite the inflationary costs and supply chain issues we all know about they are managing to hold onto margins to meet expectations. At some point in next 6-18 months those headwinds should dissipate.
And that's all with circa 30% of the share price now in net cash - that's around 175p. So really it's trading around 400p. Not expensive in my view and reasonable dividends
Character (LON:CCT) I noted the reference to developing own IP to replace licenses as they wind down and expire. It sound s like Peppa is only on a short term reprieve so there'll be volatility over the next few years.
Hopefully only Peppa?
Pan African Resources (LON:PAF) not a share covered here as it’s a gold miner. TU today, it’s beating forecast and making an acquisition funded from current cash. Looks extremely cheap.
I hold Pan African Resources (LON:PAF) and am wondering when I will receive Monday's dividend as I am keen to re-invest in the same.
Same. I’m waiting too. Probably have the dividend today or tomorrow.
I got mine this morning.
I held Pan African Resources (LON:PAF) for years, years ago. It always looked cheap. I have no idea what might change that. Sentiment or whatever can persist a very long time. Good yield while you wait though.
Well all miners are low in terms of PE. I mainly bought in as a hedge against a market crash.
This update looks extremely positive. Very cheap acquisition and saying they look to beat forecasts.
Any experts on here in the mining sector that can give their insight?
This mornings RNS briefs are worth a look at, I'm neither expert on miners or investing but I do know that gold miners have to keep finding gold on the one hand and on the other investor sentiment in gold miners comes and goes across the board. At present there is little of the second.
Silver
Shanta Gold (LON:SHG) looks outstanding value just now after recently being punished by the market over supply issues of a raw material (I hold again after re-entering last week), no debt, cash rich and pretty much zero forward hedging. AISC, current and future, is the thing to look at for gold miners ;)
It’s also worth mentioning that Pan African Resources (LON:PAF) is on track to repay almost all of its outstanding debt over the next 12 months. However, it recently restructured its debt on more favourable terms. That will give it a ZAR1 billion (Decreasing over time) revolving credit facility that will stretch out to June 2024.
The way it delivered on its largely debt-financed Elikhulu tailings project has, in my view, made it a far more bankable proposition than most of its competitors. So it’s in a strong position to pick up any possible bargains in a country where credit is frequently difficult or expensive to obtain. While operationally, a growing proportion of its output comes from tailings operations - more predictable and less risky production than underground mining. And, yes, I continue to be a shareholder.