Small Cap Value Report (Weds 16 Feb 2022) - FLTA, FRAN, RAI, OOUT, ARBB

Good morning, it's Jack & Roland here with Wednesday's SCVR. Paul's off for a couple of days while the news flow is quieter. If you see anything of interest leave us a comment and we'll see if we can get around to it.
Agenda
Jack's section:
Ra International (LON:RAI) - H2 Covid disruption means FY EBITDA has halved to $7m. The order book has also dropped by 50% year-on-year due to delays to contracts, and the group is moving away from commercial opportunities as a result. The valuation looks cheap on the face of it, and trading could recover, but the shares are illiquid and the update lacks detail, so I’m happy to remain on the sidelines for now as it looks high risk.
Ocean Outdoor (LON:OOUT) - an encouraging rebound in trading for this digital out of home specialist. The group has spent an awful lot of money on acquisitions, and Covid has obviously had an impact, so underlying progress is difficult to gauge. It could be that an enlarged group is poised to rapidly become much more profitable, but it remains a relatively unknown entity for me so I’m currently neutral. There's an ongoing strategic review as well and the company has received offers for a potential sale, so we could hear news on that front at some point.
Roland's section
Filta Group (LON:FLTA) - a recommended all-share offer from Franchise Brands (LON:FRAN) values Filta at a shade under 171p and looks almost certain to succeed. I think this could be a logical and reasonably priced deal, assuming both businesses are able to maintain historic rates of growth.
Arbuthnot Banking (LON:ARBB) - this unusual family-controlled banking group has issued a brief trading statement confirming a strong end to 2022. The Stockopedia metrics present a mixed picture, but I think the group’s record suggests it might be worth further research for patient long-term investors.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Jack's section
Ra International (LON:RAI)
Share price: 30.25p (-20.39%)
Shares in issue: 171,791,843
Market cap: £52m
RA is a specialist provider of complex and integrated remote site services to Humanitarian, Governmental and Commercial organisations around the world.
Trading update for the 12mths to 31 December 2021
RA expects to report FY revenue of $54m and underlying EBITDA of $7m, with the reduced level of revenue set to impact gross margin and profit. The group says revenue is in line but I actually have it as slightly ahead of the £52.1m Stockopedia consensus figure.

Gross margin sounds less reassuring, however. This has been impacted not just by the revenue reduction, but by travel restrictions, quarantine requirements, and supply chain delays. G&A costs are up by $2m in the year and EBITDA has more than halved from $14.2m to c$7m.
The order book as at 31 December 2021 was $100m, just half of the $200m reported at the end of the last financial year. Some contracts and tenders have been delayed, so a resumption of more normal operating conditions might see these come back. It’s likely not enough to make up the $100m difference though.
Net debt of $1m excluding lease liabilities, with cash on the balance sheet of $9m.
CEO Soraya Narfeldt comments:
This has been a frustrating period, with client and COVID-19 related operating constraints continuing to cause inefficiencies and exceptional delays in executing projects, in tender issues, awards and in project mobilisations. This has impacted our profitability for the last six months of 2021 and also stalled our order book momentum. However, the underlying business has remained profitable through this disruption and our solid balance sheet supports our forward looking requirements.
It sounds like the group’s commercial sector opportunities are largely to blame.
we have seen particular risks and delays with new business activity in the Commercial sector. As a result, going forward, we will be more selective in the projects we look to undertake in this sector, and it will be less of a focus of our business development activities.
RA will instead refocus on government and humanitarian projects.
Conclusion
This is a short update and I’m happy to stay on the sidelines as we wait for the full year results.
There’s no earnings guidance given by the management unfortunately, and the tone of the update hardly suggests it is worth digging through previous accounts to get a handle here. Directionally, it will be down so I’m just going to hold off until we get more commentary.
It looks like some holders might have been figuring this out in January.

Momentum has been hit hard by Covid disruptions in the second half, with several projects unexpectedly (and recently) delayed. That suggests a poor level of visibility. The $100m order backlog is presumably some way below target. There’s also been a knock-on effect of increased net debt due to elevated levels of Mozambique-related inventory.
Lower capex as a result of delays suggests the balance sheet will remain ok, but that’s a small positive in context.
Having said all of the above, the valuation here is notably low already. There’s a forecast yield of 4.27% (now up to around 6.9%) - that wasn’t mentioned at all in the update, so presumably this is still on the cards. I think there's now a question mark over the forecast PER measure.

The share price is very illiquid. You can only reliably buy around £1k with a 526bps spread, and the free float is just 18%. No surprise then to see the shares marked down c20% currently, volatility can be expected. The company is quite capex heavy during normal operations too, and net cash has fallen.
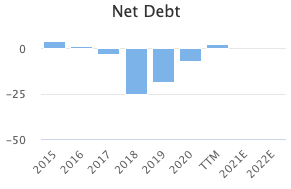
There is a chance of a recovery over the next year or two if things pick up, but for now I’m waiting for the dust to settle and a chance to get more detail from management. It seems high risk to me.
Ocean Outdoor (LON:OOUT)
Share price: $9.80 (+6.52%)
Shares in issue: 53,930,223
Market cap: £390m
This is a leading operator of premium digital out of home (DOOH®) advertising in the UK, the Netherlands, the Nordics and Germany, focusing on iconic assets like flagship shopping centres in high footfall locations.
- Revenue +44.3% to £124.4m
- Adjusted EBITDA up to £18.6m from a loss of -£0.4m
An encouraging recovery here, with a strong bounce back in demand for Digital Out of Home (DOOH) advertising from Q2 onwards (tracking the vaccine rollout and phased lifting of restrictions). This includes appointments for its digital advertising products and services in Edinburgh, Copenhagen, and Canary Wharf.
Importantly, Ocean also experienced a renewed confidence among the high-spending advertising categories, with the 'power brands' committing a greater proportion of their budgets to DOOH® as well as an increasing number of new adopters, reflecting the long term structural tailwind within the sector.
But it’s not just familiar faces driving demand. The group says it is seeing an increasing number of new adopters too, giving some weight to what it describes as a ‘long term structural tailwind within the sector’.
Strategic review
This is interesting:
On 15 November 2021, Ocean announced that it had initiated a strategic review to evaluate potential strategic and financial alternatives to maximise shareholder value. This decision was taken after the Board and management felt that Ocean was undervalued, with the share price continuing to face technical trading challenges unrelated to Ocean's strong business fundamentals and intrinsic value. The Board is continuing to evaluate a number of options, including a potential sale, following interest and conditional offers received which may or may not lead to a transaction. Another update will be made when appropriate.
The shares are up by nearly 50% since November, so if offers are still being entertained then presumably the figures being discussed are above today’s share price.

Current trading - some ongoing restrictions in leisure and hospitality but trading has started ‘very strongly’ and FY22 revenue and adjusted EBITDA is expected to be ahead of FY19 levels of £104m and £52.7m respectively.
Balance sheet - Stockopedia flags this up as a risk. The liquidity ratios do look low and there are a fair amount of liabilities, so I’d want to be more comfortable with the financial health. Particularly given Ocean’s penchant for large acquisitions.
Conclusion
Some 90% of Ocean Outdoor’s income is from DOOH, and it looks to be a leader here, which makes it a relatively unique proposition. It’s a shame Covid disruption over the past two years makes the company’s prospects hard to gauge.
This is compounded by the fact the group has spent a lot on acquisitions in its short listed life. In fact, it’s spent more than its market cap on buying businesses.

Ocean says it remains on the acquisition trail, but that its Europe markets present organic growth opportunities as well. It’s apparent that the group provides a premium service across popular locations and yet it remains under the radar of most investors.
The Covid recovery has played out in the share price though, so we’re left considering the growth potential of the company.

I’m neutral for now - an interesting company with what looks like a leading position in a growing market. Not one I’m familiar with though, and the substantial acquisition spend is slightly off putting, as are the low liquidity ratios.

Roland’s section
Filta Group (LON:FLTA)
Share price: 158p (pre-open)
Shares in issue: 29.1m
Market cap: £46m (pre-open)
Recommended offer from Franchise Brands
AIM small cap Franchise Brands (LON:FRAN) has made a recommended all-share offer for Filta, which provides maintenance services for commercial kitchens. Under the terms of the offer, Filta shareholders will receive 1.157 new Franchise Brands shares for each Filta share.
The deal values Filta at £49.8m or 170.7p, based on yesterday’s closing prices. That’s a modest 7.7% premium to yesterday’s close, but a more reasonable 23.8% premium to the three-month volume-weighted average price for Filta shares.
The valuation seems reasonable to me. Franchise Brands’ offer puts Filta stock on around 22 times 2022 forecast earnings - this graphic is based on yesterday’s close:

Filta released a strong trading update on 7 February, so that might account for the recent share price gains. However, looking at the share price chart for Filta, I can’t help wondering if the news slipped out early for some traders yesterday:

In any case, congratulations to Filta shareholders. However, as this is an all-share offer, shareholders will now have to make a further decision. Do they want to own shares in Franchise Brands?
With this in mind, I’m going to take a look at Franchise Brands and consider how the combined business might look.
Franchise Brands (LON:FRAN)
Share price: 147.5p (pre-open)
Shares in issue: 95.9m
Market cap: £141.4m (pre-open)
Franchise Brands owns a group of businesses operating on a franchise model. B2B brands include drainage and plumbing specialists Metro Rod and Metro Plumb. The company’s B2C operations include ChipsAway and Ovenclean.
The group’s largest shareholder is well-known UK investor Nigel Wray, with 23.3%. Chairman Stephen Hemsley also owns around 23%, so his interests should be aligned with those of shareholders.

Franchise Brands has continued to grow throughout the pandemic. The recent FY trading update reported a “continued strong trajectory” and struck an upbeat tone.
Broker forecasts suggest Franchise will report record profits and sales in its 2021 results (due on 3 March):


Franchised businesses can be wonderfully profitable and cash generative. Franchise Brands’ seems to be a good example of this so far - the group’s free cash flow per share has consistently exceeded earnings since its 2016 flotation:


That cash flow isn’t cheap, though:

Ahead of today’s news, Franchise Brands was trading on around 23 times FY22 forecast earnings:

So where does that leave the combined Franchise/Filta business?
Rationale for the deal: Franchise Brands’ existing operations are mostly reactive - fixing blocked drains or plumbing problems, for example. Filta’s main business is scheduled maintenance. Franchise’s management believe that combining the operations would enhance UK growth opportunities and enable the company to develop a broader “Water In, Waste Out” service for commercial clients in the UK. This sounds reasonable to me.
Alongside this, Franchise hopes to be able to capitalise on Filta’s stronger US presence to expand the combined group’s operations into this market. I’d guess this might be more challenging, but not impossible.
The combined group: Combining the group’s operations and eliminating duplicated overheads is expected to generate some cost savings. But there’s no figure provided in today’s offer document, so my feeling is synergies may not be all that material. Growth seems to be the main aim of this deal - rightly so, in my view.
Valuation: The combined group is expected to have a market cap of around £190m, based on yesterday’s closing share prices (which haven’t moved much this morning).
Based on broker forecasts for 2022, the merger could create a business with £90m of revenue and around £8.8m of net profit. My sums suggest that’s equivalent to a P/E of around 22x FY22 earnings, with a dividend yield of around 1%.
Profitability: My sums suggest an operating margin of around 12% is likely for the combined group in 2022.
Balance sheet/cash flow: Franchise Brands has reported a small net cash position since 2020, while Filta has a minimal amount of net debt. So I’d expect the combined group to report a small net cash position.
Both businesses have historically demonstrated strong free cash flow conversion. I don’t see any reason why this should change.
I’m quite comfortable with the financial strength I’d expect to see in the combined business.
My view: Franchise’s offer appears to be almost certain to go through, as shareholders controlling more than 80% of the stock have already provided irrevocable undertakings to accept.
Unlike Franchise, Filta’s business has suffered badly during the pandemic due to widespread hospitality closures in the UK and US markets. However, performance appears to be bouncing back. If the Filta business can recapture its pre-pandemic form, I think that this could prove to be a reasonably-priced acquisition by Franchise Brands.
My feeling is that combining these two businesses is logical. The valuation of the combined business doesn’t seem excessive to me, if the combined business can maintain the growth both companies have shown individually in the past.
If I was a Filta shareholder today, I would be inclined to accept the Franchise Brands shares and continue to hold.
Arbuthnot Banking (LON:ARBB)
Share price: 940p (unchanged at 08.45)
Shares in issue: 15.0m
Market cap: £141m
This must be a contender for the shortest RNS of the year, but I don’t think shareholders will be too concerned.
This private banking group traded well during the fourth quarter and expects to report pre-tax profit in line with market expectations for the year. Full-year results are scheduled for 24 March.
Arbuthnot Banking Group is a private banking and wealth management group which operates under the Arbuthnot Banking and Arbuthnot Latham & Co brands. The business is controlled by chairman and chief executive Sir Henry Angest, who owns 56% of the stock.

Trading update: I have pretty much quoted today’s trading update verbatim in the paragraph above. There really was no other information provided. However, we can learn a little more about the market expectations mentioned by the company using Stockopedia’s invaluable archive of forecast data.
This tells us that analysts FY21 estimates improved steadily last year, while the outlook for FY22 turned a little more cautious:

Valuation & profitability: The valuation of this closely-held stock looks a little strange at first glance.

The combination of a high P/E and a fairly high dividend yield might normally suggest a business that’s highly profitable. That doesn’t seem to be the case here. Arbuthnot’s return on equity is weak, according to Stockopedia data:

However, last year’s interim accounts showed a strong capital surplus position. I don’t have any immediate concerns in this regard.
One potential source of dividend cash may have been the gradual sale of the group’s previously large shareholding in Secure Trust Bank (LON:STB) (I hold). This was recently completed.
Another interesting development is the company’s recent move into commercial finance, through the acquisition of Asset Alliance Group Holdings, a commercial vehicle leasing group.
My view: I think it’s worth considering the performance of this family-controlled business against a better-known listed rival. Here’s a chart showing Arbuthnot’s share price performance against that of Lloyds Banking (LON:LLOY)

I wonder if rising interest rates and the move into asset financing might rejuvenate the profitability of Arbuthnot’s business? If so, then I’d guess the shares might be attractively valued at a c.30% discount to their last-reported book value of 1,292p.

I’d have to do more work to understand this business, but my feeling is that Arbuthnot might be of interest to investors who share the patient, long-term viewpoint of family management.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Arbuthnot Banking (LON:ARBB) is a tricky one. I looked at it a couple of years ago, and they seem to be in the process of building up the lending side of their business, setting up lots of specialist lending divisions (property finance, asset finance, etc) . At the moment these aren't particularly profitable, hence Arbuthnott doesn't look very cheap on earnings based measures. But it is trading at decent discount to book value and the team have strong track record so wouldn't bet against them. Should also benefit from higher rates.
Hi
As it seems to be a bit of slow news day I thought I'd pick up on the Tesla ($TSLA) conversation we all had a few weeks ago (obviously not a UK small cap though) (I hold $TSLA).
The macro influences around going green and thus EV's are significant and ripple into all parts of our lives and thus our investment portfolios.
If you invest in motor dealers EVs effect these. Our demands for energy sources will be effected by adoption rates of EVs. Our personal finances will be effected by prices of EVs and their running and maintenance costs. Petrol station distribution systems versus EV charging stations are central, thus companies like Shell and BP are effected (we have a newly build EV only charging station here in SW6 which replaced an existing Shell petrol station). Our day to day movements are effected by EVs with the City low emission zones. Here is the new EV charging station near me ..... (BTW it is often well over 50% full when I walk by which is quite often).
If you have an interest in the EV companies and the evolving technology, this video is a pretty comprehensive presentation of multiple aspects of this space.
It explores vehicle prices, production costs, running costs, market and adoption growth rates, different technological solutions (battery swapping vs charging), different EV manufacturers. The Vlogger draws heavily on ARK Invest research but also uses his own in depth research of this space and innovation in general.
It's 19 mins (and expect not to everyone's tastes, but some might like it). The Vlogger has a strong technical/engineering background and does in depth research (clearly a few Americanisms are present)
Regards
Howard
Good post Howard and a vital theme for the future. I play it by investing in related semiconductor stocks (Infineon, Qualcomm etc) charging infrastructure (ABB, Alfen etc) and cable suppliers (Volex et al).
Howard,
I cannot see a link to the vid .
Richard
Hi Dicktrade
Sorry, not sure why it disappeared,
Regards
Howard
Hi Again Dicktrade
The link has disappeared again ???
I'll try this approach.
This is the Vlogger's channel
https://www.youtube.com/channe...
The vid I'm referring to is this one
It should be right the first one you see in his list.
Sorry for not being able to give the full link
Regards
Howard
Thank you for your perseverance Howard !!
Good read-across from Ocean Outdoor (LON:OOUT) strong recent trading, to Spaceandpeople (LON:SAL) . While the product is different (DOOH vs physical kiosks / marketing spaces) both are ways to do offline marketing, in high footfall areas. Both types of marketing activities come from usually the same marketing budget pots within companies, and are both included in the same campaign plans.
For what is worth, my two cents is that there's some exciting stuff happening in Digital OOH advertising over the next few years. Potentially we might see ways to track and measure performance to sales (which isn't possible with standard OOH) but might be with DOOH. However, there are still privacy hurdles to jump through and no-one has a viable scalable solution/product yet, but whoever does will be a 10x multi-bagger or more.
(I hold Spaceandpeople (LON:SAL) )
Would just like to thank Paul,Heather, and David for the open invite to their Share shindig yesterday evening.
What a great evening, All the best, the markets are up , the sun is shinning,top night out, doesn't get much better than that.
Yes. A very enjoyable evening and thanks to Heather and David for organiaing. It was a pleasure meeting you too Oliver.
Hi, does anyone know why Gear4music Holdings (LON:G4M) has dropped 7% two days in a row? Thanks in advance.
Re: Gear4music Holdings (LON:G4M)
Sorry, I don't have an obvious answer for you but I did add to my already overweight position! The company's an odd one. It seems to polarize views a bit. I think there are a lot of solid holders who believe in the company's long term future and then there are those who are trading momentum. There must be a lot of PIs who multi-bagged on the last upswing and are looking to protect some profits as they see it fall. The price has fallen on relatively small volumes, especially when you consider that Liontrust bought 10% of the company at £7-30 about 3 weeks ago! Do this small group of PIs know something that we don't. I suspect not.
Gear4music Holdings (LON:G4M) starting to look interesting now. Not sure why its down around 25% in a month on no new news. They did around 60p EPS in 21 - that was clearly an exceptional year, but if they can sort out the issues in Europe then they should be able to get back towards that and the company would then look very cheap.
Hi 55555 - the problem with Gear4music Holdings (LON:G4M) and many other small to mid caps is liquidity. Given the uncertain geopolitical backdrop we are seeing that MM's are not really offering liquidity at the moment. Instead they are acting almost like brokers, trying to "match" bargains. This means that tiny trades have a disproportionate impact on price (and thus market cap). Lowering their price panics other small retail holders into selling and drops the price a bit further. The volume last few days has been minute.
To put it into context - one day recently there was £100k worth of shares traded. The market cap of the company dropped by £10m!
In times like this you have to be very clear on your investment strategy. If you are not prepared to invest in a stock like this for 3-4 years then I'd think very carefully about owning it at all because small weak hands can, as we see here with Gear4music Holdings (LON:G4M) ,cause disproportionate drops. Retail investors often lose money because they buy high and sell low, which is the wrong way round.
I hold Gear4music Holdings (LON:G4M) and am expecting to do so for the next 3-5 years. On that basis I have to think about annual compounding returns. The minimum I expect is 12% p/a so I need the share price to return me a 75% profit over 5 years to even come onto my radar. Given the operational gearing I expect the company to generate 40p of EPS next year and in excess of 60p within 3 years. On that basis at a reasonable PE of 17 or 18 I anticipate £11+ thus am happy to hold here. Liontrust will have done the same calcs and clearly also see value at £7.30. Of course none of us can predict exactly what the future holds, particularly external macro or geopolitical factors, that may affect the company so nothing is certain. The key is to reassess each time the company reports to determine if the investment logic still remains valid.
Hi David, that’s really helpful and informative. Thank you, and the others, for taking the time to help, what you say makes perfect sense.
Couldnt agree more - who knows what will happen to Gear4music Holdings (LON:G4M) share price in short term, but on a 2-3 year view this looks pretty safe bet to roughly double your money.
This is one of the reasons I really like this place. I held for years until last year, sold out after seeing some distribution issues. No idea that it had dropped this far and taken a medium stake here. In fact I also bought back into £boo this week given that it was under £0.90, that’s just plain wrong in my view - especially seeing as my 44 year old partner has just started buying things from there for cheap holiday wear. Previously she was a Debenhams type gal, seeing her move to Boohoo gives me confidence that others will too.
Thank you for this overview of the Franchise Brands (LON:FRAN) acquisition logic, and the future shape of the new enlarged business. This did not seem expensive by my rough calculations. It appears to have strong strategic rationale, and the newly combined management team now have broader experience - including knowledge of building and running a US operation. As a long term 'buy and build' play this could be interesting (I hold).
Kistos (LON:KIST)
Following a number of comments from retail shareholders,
Is that us plebs getting a mention ?
It is the Company's intention to purchase shares in the market where possible to satisfy awards when they vest and to minimise any dilution arising from the plan.
A skeptic here would comment that one of easiest ways to pump the shareprice to reach their chosen target can be by buying back shares en masse. Is this new cunning plan totally ignorant of the potential that the new plan will probably aid their stated goal of yesterday. They seem to have the pr powers of a top young russian ice skater at present.
If i was a shareholder here my direct question for the board would be if the VCP measurement period started in late may - why are they only now announcing that the base period included a calendar year months before and after. The averaging dates seem selected to include the early part of 2021 when shareprice was much lower. How can the presence of a 10% potantial share dilution for owners not be materially info that needs releasing - would love to know exactly when the 9.5% number was first posulated and exactly when and how they decided upon the base price calcs. Its possibly they are lucky now based on past decisions (share price has increased) but surely stuff like this should be laid out in plain public site at fomulation stage so it doesnt look like a stitch up?
Kistos (LON:KIST)
What is even worse here is that they have gone to PWC for advise ref this plan and they still come out with these two shambles of an updates - doesnt reflect well on PWC albeit they may have ignored some of the recommendations perhaps? all very very poor here.
KISTOS - I like the way that referring to one of the Big 4 is supposed to give some sort of credibility/prestige to this, but they are some of the most self-serving/turn-a-blind-eye businesses going - see any of the audit failures/fines/lack-of-change in the last decade!
Mgt.'s excuse for not telling us about the start of the measurement period on 21 May 2021 (!!) was that they've "substantially been in a closed period". I don't buy this at all. Firstly, use of 'substantially' means they weren't in a closed period for that time. Secondly, my (very limited) understanding of a closed period, it doesn't prevent you from properly disclosing price sensitive information - which this is.
I can't tell what it says about mgt.. In my view, it says either:
If I was a shareholder, I'd sell. If I was an employee, I'd leave. As rmillaree points out, there's only 3 of them in the scheme! Hardly bringing the company together. What would you think if you were in charge of one of their licence interests, i.e. a person responsible for exceptional performance?!
I wish they'd just brazened it out rather than put out this nonsense today.
Happy Wednesday.
Chris
Ra International (LON:RAI)
Main thing here is the huge reduction in order book. On 31st March 2021 they advised order book was approaching $200 million and now its down to $100 million (exactly).
They did get hit very hard by troubles in mozambique last year so the poor outtake for 2020 and 2021 in not surprising when you add in the covid related issue. This company has posibly been very unlucky the last couple of years.
What is a huge red flag is the continual cash reduction - $20 mil at june 2020 is now net debt situation - they did have large capoitalisation costs ref projects - its not immediately clear if this cashflow will flow back in over the near term or not?. It was a big attraction having the safety of a cash buffer here now that is gone one would worry about the continual lowly rating meaning any fund raising could potentially be very dilutive.
Hopefully their plan to concentrate on more quality work will do the job - they seem to be able to geenrally get decent contracts and mostly fulfill those so less could be more.
Without the cash backup and with the lower orderboook i would be wanting to see tangible clean progress ref earnings and cashflow in 2021 before buying back in here. I have held in the past (bit of a punt when shareprice was previously bombed out) but sold out when the shareprice was quite bouyant despite the outlook worsening/remaning tough last year.
One of the drawbacks of Ra International (LON:RAI) is the dominant position of the Narfeldts, owning 80% and in full executive control. But I think it should mean that any heavily dilutive share issuance is likely to be very much a last resort. Other strings to preserve cash are likely to be pulled first. But the decline in cash since the 2018 IPO is worrying.
Generous dividends in the Past have contributed to the general decline, funds diverted to the Narfeld pocket, mainly. I hold Ra International (LON:RAI), I admit the dividend attracted me , meanwhile I hope for better times to come.
Silver
Ra International (LON:RAI) reading between the lines I suggest that Mozambique is a huge issue. It has absorbed a huge amount of working capital and Total shows no sign of returning whilst the area remain troubled. presumably they have declared fore majeure on any payments. They quid pro quo on RAI getting high rewards for what in the west would be low margin business is that they take the political risk and this particular chicken has come home to roost. This accounts for 60% of the order book reduction.
From interim results "Given the ongoing uncertainty in Cabo Delgado province, Mozambique, we have excluded the USD 60.5m contract to provide IFM services in this region and reset the order book to USD 129m as at 30 June 2021."
Secondly it is quite possible that the second big expectation, Danakali is having an issue. They expect it to be another huge project. From interim results "during the period we agreed commercial terms with Danakali Limited for the construction of a 1,200 person camp facility and to provide IFM services."
Ra International (LON:RAI)
Hello Richard
Thanks for adding that useful info - yes that probably mostly explains the drop in orderbook - i would say they were very unlucky with the events that have unfolded in Mozambique and it is probably to their credit things didnt turn out worse than they have done this year end (caveat full results not seen yet) - shoott happens simply put. In some respects i applaud the fact that they don't back away from these dangerous areas (presuming they are honest and transparent in dealings when other may not be as much) - certainly as a holder i was fine with the whole risk profile here - for pe or 3 , 4 or 5 as this company has been in the past it aint all gonna be a bed of roses.
I agree!
Worth looking at gold miners Shanta Gold (LON:SHG) (trading update) and Pan African Resources (LON:PAF) (interim results). Both look like they will see an uptick in the share price today.
Kistos (LON:KIST) - big reverse ferret by the board, after yesterday's VCP announcement.
Comes down to how much you believe this statement in todays RNS:
"It is the Company's intention to purchase shares in the market where
possible to satisfy awards when they vest and to minimise any dilution arising
from the plan."
..which summarises to "trust us, it'll be fine". I'm sceptical.
That looks like tax efficient bonuses for the team to me.
They hit 87% of hurdle in December last year (general market has pulled it back since) - 2 months before the 5 year target was even mentioned. That isn't really a future performance bonus it claims to be, it is a salary boost for keeping up with inflation. In fact it probably doesn't even have to do that to trigger the "bonus". The team is only 3 of "the team".
My faith in shareholder power is marginally restored. They got a kicking from the institutions. Frankly I still think a bonus that is paid by drifting with inflation is nothing about exceptional performance recognition.
I see no reason why directors should get a bonus for doing the job they are already paid well to do.
A long time ago Government and others opposed Director salary increases which were not in keeping with wages policy at which point company directors found a way around constraints, the Incentive Bonus Scheme, to screw the private investor with as it happens.