Small Cap Value Report (Weds 16 June 2021) - SCS, ELTA, GTLY, BWNG, STU, RNO, BOTB, MOTR

Good morning! It's Paul & Jack here with the SCVR for Weds.
Book recommendation - several friends have suggested The Art of Execution to me, by Lee Freeman-Shor.
I tried the audiobook, and found it full of contradictions. However, I found a nice spot at a pop-up beach bar in Bournemouth last night, and found the same book on my kindle. I read a quarter of it, and thought it was excellent. Maybe more for traders than long-term investors? However, still full of pearls of wisdom, much of which is based on statistical analysis of several years' worth of trades from top fund managers. I won't spoil it by giving anything away, it's just an excellent book that I think many of you will find useful, and enjoy reading. I certainly picked up some tips on how I can improve my investing performance.
Timing - today's report is now finished.
Agenda -
Paul's Section:
Scs (LON:SCS) (I hold) - strong trading & beating market expectations for this year & next year. Still looks cheap to me.
Electra Private Equity (LON:ELTA) (I hold) - a strong trading update from its main investment, TGI Fridays. Sales since re-opening are running +12.5% on 2019 comparables, despite restrictions on trading. I remain bullish on this, seeing it as a cheap entry into two forthcoming floats, TGI Fridays and Hotter Shoes.
Nwf (LON:NWF) - correction re last week's SCVR.
Gateley Holdings (LON:GTLY) - the company has been hit by a computer hack, but at this stage it doesn't sound too serious. Introduces uncertainty, and might induce some punters to bank profits?
N Brown (LON:BWNG) (I hold) - big increase in potential liability from Allianz legal dispute. I'm worried about this, and thinking about exiting from this position.
Studio Retail (LON:STU) (I hold) - Capital Markets Day coming up, with ambition to grow revenues to £1bn. Could be interesting.
Renold (LON:RNO) - (I hold) - accounts publication date is delayed, for the second time.
Jack's Section:
Best Of The Best (LON:BOTB) - FY21 figures more or less as expected, with growth opportunities going forward. But a reduction in customer activity as lockdowns ease hits the share price and makes sustainable growth rates harder to gauge for now.
Motorpoint (LON:MOTR) - interesting used car company that looks to have made a lot of progress in its online proposition. Competition could be a concern, but there's potential here. Management hopes to double revenue in the medium term - the margins it can generate on this will be important.
Scs (LON:SCS)
(I hold)
290p (last night’s close) - mkt cap £110m
ScS, one of the UK's largest retailers of upholstered furniture and floorings, today issues the following trading update for the 46 weeks ended 12 June 2021.
SCS has an unusual July year end, so this looks like an unscheduled update.
PR summary - no less than 3 of them, all of which are delightful for shareholders -
Current trading very strong and the Board now expects FY21 to be ahead of market expectations
Outlook for FY22 substantially better than current market forecasts
Resumption of dividends with interim dividend declared today
A table of like-for-like (“LFL”) order intake (NB not the same as revenues, due to the time lag in making product to order) is provided. I’ve highlighted below the more relevant comparison column, with uninterrupted trading in FY 07/2019. Whereas the middle column (comparing 2021 with 2020) is a bit of a red herring, as the eye-catching +370.8% is comparing re-opening this year, with lockdown 1 last year, so best ignored I think.

.
I’ve highlighted that this year was (13.1%) down on 2019 at the H1 stage. The latest figure has improved a bit to (9.5%) year-to-date (“YTD”). So better, but still down on normal trading in 2019. To be fair, I would expect that, given that the main sales channel (the shops) have been closed extensively this year (and last).
For comparison, here is the SCVR from 10 June 2021, where I looked at the most recent update from larger rival Dfs Furniture (LON:DFS) which published considerably stronger order intake, up 10.4% on 2019, versus (9.5)% down for SCS announced today.
Online sales - strong, as I would expect, but they don’t give the key number of what % of total sales are online. DFS indicated this had settled at c.19% post-reopening. Based on what they’ve told us before, I think SCS is probably a bit behind that, but moving in the right direction.
Order book - strongly up, unsurprisingly given bumper order intake catching up after lockdown easing. Currently stands at £116.6m (inc VAT) or £97.2m exc. VAT assuming all sales are vatable.
Liquidity - cash is up to a ridiculous £101.3m, with no debt (ignoring IFRS 16 lease liabilities, because they’re not debt). Plus an unused £20m taxpayer-backed CLBILS facility that’s not likely to be used.
Furlough - £3.0m in taxpayer grants have been repaid - well done SCS. Take note scumbags at other companies who’ve pocketed the money, and paid yourselves big bonuses (see recent press).
Dividends - a very modest 3.0p interim dividend is announced. The company has the capacity to pay huge dividends if it wishes, the cash is just sitting in a bank account doing nothing. Favourable working capital cycle means that the cash pile largely revolves permanently. So I see this as just the start for potentially much larger divis.
Outlook - substantially better than forecasts. I can’t find any broker notes unfortunately, these are clearly only available to the select few, not riff-raff like us!
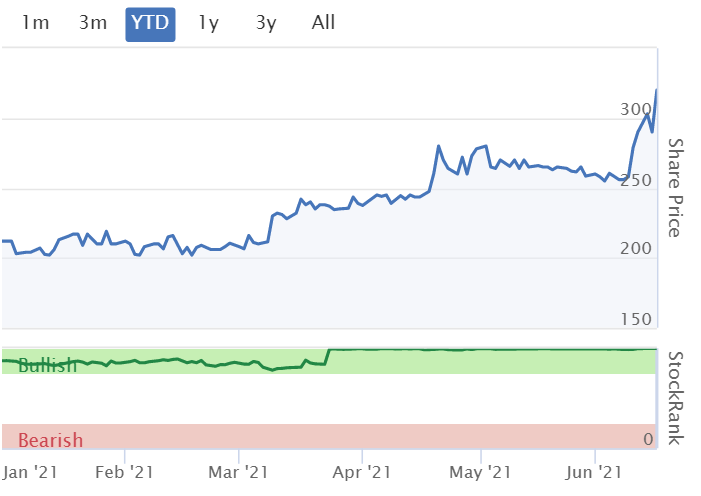
Stockopedia shows consensus of 23.4p for FY 07/2021 (which we’re now told will be beaten, but they don’t say by how much).
FY 07/2022 has a ridiculously low 12.9p broker consensus forecast, so no surprise that’s going to be beaten substantially.
My opinion - I’m valuing SCS on normalised trading which I estimate to be c.30p per share. It’s probably therefore on a PER of about 10, which combined with tons of cash on the balance sheet, means it’s too cheap, if my figures are correct.
.
.
Electra Private Equity (LON:ELTA)
(I hold)
590p (unchanged) - mkt cap £230m
Trading update & company announcement
This is a special situation which I’m keen on. It’s an orderly winding-down of an investment company, with 2 remaining businesses - TGI Fridays (casual dining chain), and Hotter Shoes. Plus some cash at the holding company. Both restructured during the pandemic, and look excellent businesses to me.
ELTA shares will morph into holdings in TGI and Hotter, with both being listed as standalone businesses in the next 6 months.
ELTA says today that its plans for listings are progressing as expected.
Hostmore - this is the name for the new company which will be demerged, and listed on the main London market in Q3 of this year, owning TGIs and 63rd+1st (a start-up new brand, with one site). If you do some research, you’ll discover that TGIs has been revitalised under new management, and has very good prospects in my opinion. It is targeted to generate c.£30-40m p.a. EBITDA once full trading resumes.
Interestingly, management (experienced in hospitality sector) sound ambitious to grow a larger group -
Following the demerger, Hostmore will seek to add rapidly growing, early-stage businesses to its portfolio of complementary brands, exploring opportunities to extend its offering in experience-led hospitality and leisure concepts.
TGI Fridays (they’re calling “Fridays” now) current trading - this looks encouraging to me, given that there are still considerable restrictions on inside dining -
In the 4 weeks since re-opening for dine-in customers on 17th May 2021, Fridays stores have recorded like-for-like 'LFL' growth vs the equivalent period in 2019 of 12.5%.
This LFL growth excludes the contribution from new stores including that of the first 63rd+1st store, which is trading in line with management expectations following its opening on 24th May 2021.
If that level of performance is maintained, the outlook is good. If anything, growth might accelerate once restrictions are lifted, supposedly in July, but who knows if that happens? Trading at +12.5% 2019 LFL, TGIs will already be profitable, see the table which compares the sales uplift with forecast EBITDA from the last results statement -

As you can see, current trading at +12.5% is off the table. Whether it can be maintained at that level, who knows? This is being achieved with the existing pandemic restrictions remember, so it could even increase further on full re-opening.
What the market values Fridays at, will remain to be seen. 10x EBITDA looks a sensible guess, based on peers Fulham Shore (LON:FUL) and Restaurant (LON:RTN)
Take off £60m debt, and that gives a potential market cap for Fridays of about £340m. Very nice upside on ELTA’s current £230m mkt cap. And we only have to wait a few months.
Hotter Shoes - this company is basically thrown in for free. It sells comfy shoes for the over 50s, assembled in the UK from components manufactured in the Far East. The shoes are indeed comfy, I have 2 pairs recently purchased in the mid-season sale online.
Most of the shops were closed in a restructuring, so it has successfully switched to mainly online sales.
We’re told it is trading strongly today. May 2021 sales up 38% on May 2020.
Gross margin is up 7%, quite a big improvement.
Who knows what it’s valued at when it floats? I see this as icing on the main cake (TGIs).
Online Capital Markets Day - this should be interesting. It’s focused on the much larger business of TGI. Hotter Shoes will have a separate CMD later this year. Obviously ELTA needs to drum up some interest in these 2 floats.
Diary date - 09:30 to 12:30 on 29 June 2021.
How to attend - details to be announced the day before.
Guidance - detailed guidance for analysts is provided, I won’t repeat that here.
My opinion - this is a very good update, on the strong trading at TGI Fridays.
It’s such an obscure share, that not many people seem to be aware of it, buried within ELTA.
I remain of the view that this share provides a cheap entry point into 2 forthcoming floats, both of which are things that I would want to buy anyway. ELTA is a bargain way in, if my figures are correct. Ultimately the stock market will decide what Fridays and Hotter are worth, not me! So it’s educated guesswork at this stage.
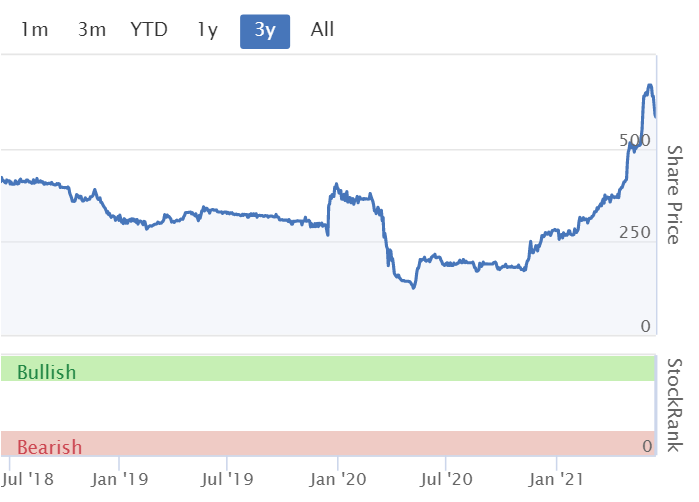
Looks like a bit of profit-taking going on at the moment, as with lots of shares that have risen a lot. Personally I've not sold any of mine, because I want to wait for the 2 floats to happen, which could deliver good upside, if they are well received.
.
.
Correction
Nwf (LON:NWF)
Last week I moaned about NWF not including a footnote to detail what market expectations are.
A friend emailed me shortly afterwards, to indicate that there is a footnote that I hadn’t spotted!
It wasn’t asterisked, and was right at the end of the RNS, after the disclaimers, in a small font, so I missed it unfortunately. Sorry about that.
We’re more than happy to put the record straight when we get anything factually wrong here, so when I have time later I’ll go back and amend the relevant report from last week.
With my apologies to NWF & its advisers. I do like their idea of putting market expectations on a company’s investor relations website, then it can be updated regularly, which seems a nice idea that helps investors. Let’s hope more companies follow suit.
.

.
Gateley Holdings (LON:GTLY)
Down 6% to 186p - mkt cap £219m
Notice of Cyber Security Incident
The share price has wobbled today, on news of its computer systems being hacked.
It doesn’t sound serious at this stage -
The Company has carefully but rapidly re-established its core systems to enable its staff to continue to work and communicate with its clients. The Board has seen no evidence that the financial performance of the Company has been impaired.
A data breach is embarrassing for a firm of lawyers, and could involve costs from IT consultants, to possible damages for clients, if their interests were harmed?
My opinion - data breaches are becoming depressingly regular occurrences for many companies. It does highlight that cyber-security is of paramount importance, and clearly wasn’t up to scratch at GTLY.
It doesn’t sound particularly serious, but it introduces uncertainty into a market which is clearly wanting to bank profits on a lot of shares which have gone up a lot recently.
.
N Brown (LON:BWNG)
(I hold)
58.4p (down 8% at 13:48) - mkt cap £268m
We already knew about a large & complex litigation going on between BWNG and Allianz Insurance, being a historic dispute about the historic sale of insurance products.
Unfortunately for BWNG, it announces today that Allianz has applied to the Court to increase the scope of its claim by up to a further £36m. Checking my notes here on 20 May 2021, I flagged up the existing estimated £29m claim & counter-claim re Allianz, and that this business is fraught with regulatory risk.
Putting those two sums together, and we get a possible case size of £65m, which is pretty horrible.
For that reason, I’ve decided to sell half my position, whilst I ponder what to do next.
The court case could be settled by a compromise maybe? But do I really want to hold a share for a turnaround, where a large legal action is underway, with an unknown outcome?
Is the trading turnaround sufficiently convincing that I should take a flyer on the legal action maybe not being that important?
Would an adverse settlement of the legal case require another equity fundraising? Possibly. There again, the controlling family have been increasing their stakes, and I wouldn’t be surprised if they take it private, so a potential premium on a takeover bid might ensue?
On balance, I’m leaning towards probably getting out of this one at some stage, due to the increased uncertainty. What do readers think?
.
Studio Retail (LON:STU)
(I hold)
264p (up c.3% today) - mkt cap £230m
This is a very similar business model to BWNG - selling things online, but making most of the profit from high interest finance charges.
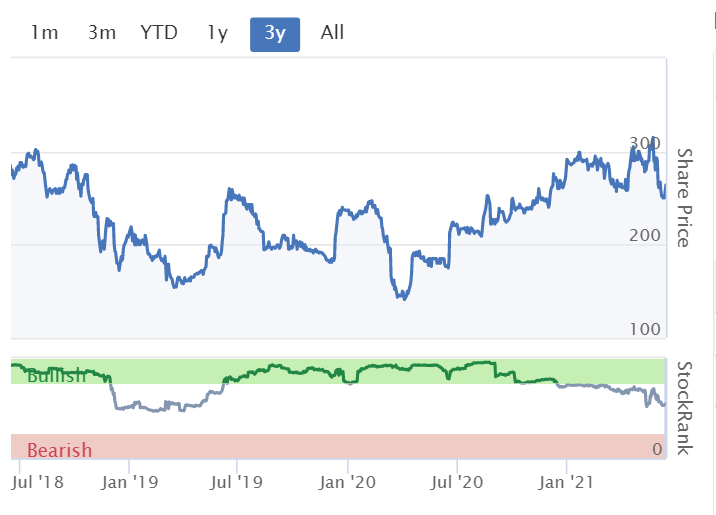
I thought this share looked good, on a recent positive-sounding trading update, but like a lot of other online retailers, it’s de-rated quite a lot recently. Worries about an online sales tax maybe?
Diary date - 30 June 2021, for publication of FY 03/2021 results.
Capital Markets Day - signup link here - this caught my eye, and looks to be a significant shift in strategy to grow the business more aggressively. I like the sound of this -
On the same day as the results, the Company will be hosting a virtual Capital Markets Day for investors and equity analysts. The event will include a series of presentations by senior executives and operational management to provide greater insight into the Company and its ambitions to reach £1bn of sales in the medium term.
I think it was Andy Brough who mentioned this share in a recent interview, saying that management want to get EPS up to c.100p. If they do that, then the current share price of 264p would be a distant memory. Mind you plenty of companies want to grow profits strongly, the question is whether they can actually achieve it or not?
The forward PER already looks very low for STU, so it could be worth a closer look. I picked up a few at the recent high, unfortunately.
.
.
Renold (LON:RNO)
(I hold)
22.1p (down c.10%, at 15:00) - mkt cap £51m
It’s one thing after another today, I seem to have been fire-fighting all day so far!
On 28 May 2021 Renold announced that its FY 03/2021 results would be delayed to 17 June, due to covid disrupting the audit. Fair enough, not ideal but these things happen. It’s not the only company that has delayed results for this reason. Audits are more difficult when everyone is working remotely.
Today, 16 June 2021 we get another delay. No firm date is now set.
Both announcements confirmed that trading is in line with expectations.
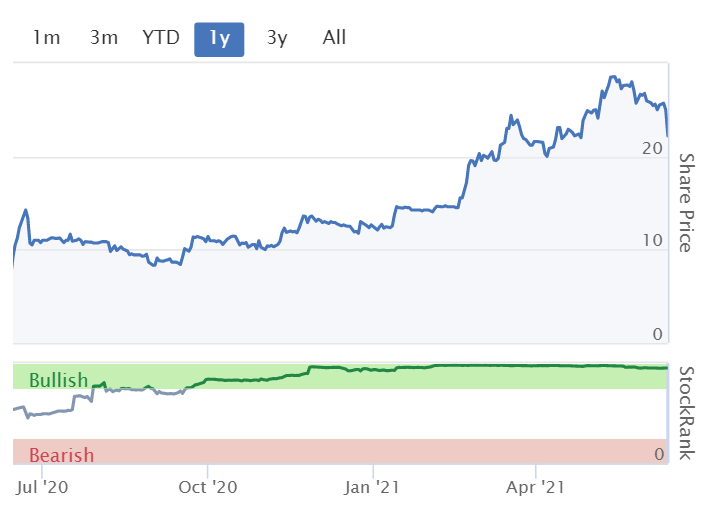
Inevitably, the market doesn’t like this, and the shares have sold off. Although to be fair, many small caps have come off their recent highs, with people understandably wanting to bank some profits after a massive rally since Oct 2020 in practically everything.
Checking my notes here on 14 April 2021, I reviewed Renold’s year end trading update, and it all looks fine. Net debt in particular was only £18.4m at 31 March 2021, down by about half.
So I can’t see any obvious risks here.
Personally I wouldn’t want to speculate on why the audit process is taking longer than expected. Maybe there’s an underlying problem (if there is, I can’t see any particular risk), and it sounds procedural, given that underlying trading is confirmed as in line.
Some people have clearly been irked by this, and decided to sell now, and ask questions later. Personally I think the company is soundly financed, so will sit tight. But clearly risk has increased, as delaying accounts twice does imply there might be something wrong. Let’s hope it’s resolved quickly.
.
.
Jack’s section
BOTB (LON:BOTB)
Share price: 1,825 (-30.6%)
Shares in issue: 9,382,253
Market cap: £171.2m
(I hold)
Best Of The Best (LON:BOTB) is an online provider of competitions in which users pay a small fee to ‘spot the ball’ from a football photo. It sounds simple, but it has proven to be immensely popular, particularly during lockdowns.
There’s a debate around whether this is a truly skill-based competition. If it was to be classified as gambling, that would have licensing implications.
At present it is classed as the former but the fact that this could change in future represents a regulatory risk. It’s probably the primary longer term risk to bear in mind here.
That’s because the company transitioned away from its original model of providing physical competitions at retail sites and airports and has now become an online-only service. The group exited its final site by September 2019, months before the first lockdown - fortuitous timing.
Apart from that, full credit goes to the management team however. The strategic pivot has been truly transformational, enabling much faster revenue growth, increasing the total addressable market, decreasing costs, increasing cash flows, and significantly improving marketing efficiency and impact.
The share price has come off a little bit recently after a tremendous run following an in-line update and are down sharply this morning. The market was getting used to beats but now BOTB is flagging a reduction in customer activity as lockdowns ease.
Whether or not this develops into a more sustained reduction in growth rates remains to be seen.
Even if it does, I would argue that the 99 StockRank, market-leading returns on capital, and strong CAGRs mean BOTB has earned a little patience. But that’s scant consolation for shareholders this morning.
The shares are illiquid, so we can expect ongoing volatility.
Highlights:
- Revenue +156% to £45.68m,
- Gross profit +187% to £28.27m; gross margin up from 59.1% to 61.9%,
- Operating profit +235% to £14.1m; operating margin up from 23.6% to 30.8%,
- Profit before tax (PBT) +236% to £14.06m,
- Cash flow from operations of £14.27m,
- Earnings per share (EPS) +227% to 122.52p,
- Net assets of £8.96m, substantially underpinned by property and cash,
- Cash balances of £11.8m and no debt as at 30 April 2021,
- Proposed 5.0p Final Dividend and Special Dividend of 50.0p.
It looks like revenue is slightly ahead of forecasts (£45.68m vs. £44m) and earnings per share are slightly behind (122.52p vs. 125p). Taking into account this morning’s steep drop, that values BOTB at 3.75x sales, 6.1x gross profit, and 14.9x earnings.
The balance sheet is spotless with no debt and £4.3m of trade and tax payable easily outweighed by the net cash balance. Retained earnings are up 235% to c£8m.
BOTB is highly cash generative, with just £150,000 spent on financing activities. That makes for free cash flow of £12.4m after subtracting from net CFO of £12.6m.
The move to online has ‘significantly improved capital efficiency’ and the MidWeek competition continues to drive growth. This, coupled with the significant year-on-year growth in online marketing investment and player acquisition, are the key drivers of today’s results.
William Hindmarch (founder, CEO, and 32% shareholder) says:
BOTB's ability to generate cash, our strong balance sheet and the fact that we have no debt gives us confidence in our ability to deliver continued future growth.
We are excited about the opportunities that the year ahead holds for BOTB, with a recovering economy and hopefully a return to normality. However, in contrast to the summer 2020 period, we have experienced somewhat of a reduction in customer engagement since the latest easing of lockdown restrictions on April 12, 2021, specifically relating to the understandably long-awaited re-opening of hospitality and non-essential retail. We are closely monitoring this, but with our flexible model, growth strategy and plans for the year ahead, we expect customer engagement to return to normal levels before too long.
It’s likely this reduced customer activity that shareholders will focus on and the shares will open down.
Putting that to one side for the moment, the growth strategy remains focused on driving digital sales, with the 'Dream Car' and 'Lifestyle' competitions joining the 'Midweek Car' competition. BOTB now has native iOS and Android apps. This is a positive step, as a large slice of current business (and likely even larger proportion of future business) will be done by smartphone.
The group points out that the vast majority of website visits and over half of group revenue now comes from mobile devices. This is a key area of focus in terms of IT development.
Marketing is predominantly digital media, complemented by traditional advertising channels. All marketing investment is strictly calibrated on the cost per acquisition of a new customer versus their predicted lifetime value. This is a key shift in the nature of BOTB’s marketing and has so far generated stellar results.
Social media remains a core marketing channel, driving both customer acquisition and brand awareness. BOTB’s Facebook page now attracts over 400,000 followers, and the YouTube channel stands at over 60,000 subscribers, with Instagram followers nearing 300,000.
Two new TV ads were produced and aired during the period, with ongoing testing and optimisation for different audiences.
Conclusion
Sharp drops are never pleasant but if you strip out shareholder expectations and the cautious near term outlook, BOTB has had a stellar year and continues to have good growth opportunities.
It has generated triple digit revenue and profit growth, it’s highly cash generative, dividend-paying, with expanding margins and market-leading returns on capital, and is operated by the founder-owner.
Longer term, the question is how much of the recent growth is a one off Covid boost that will dissipate. It’s still too early to comment clearly on this and we’ll just have to see how the data plays out. But it has coincided precisely with people being able to go to the pub etc.
FinnCap has so far maintained its forecasts but there’s a chance it might revise these down in time.
Given the lack of liquidity and a raft of new investors that have been attracted to the shares over the past year, I’d say share price risk is to the downside in the short term. But this could overshoot and end up too cheap.
At 14.9x FY21 earnings, given the returns on capital being generated, you could make that argument now. Again though, we need more visibility on trading prospects. For most companies that have benefitted from Covid tailwinds, you can refer to FY19 results as a rough benchmark. This is impossible with BOTB given the change in strategy. Lots of people will be trying to figure out fair value in the weeks ahead.
But BOTB has a flexible model, and clear growth plans for the year ahead. There’s no debt so whatever the share price does, the actual risk to the company is limited to whatever 'normal' levels of trading are. The database of over 1.7 million supports existing competitions and can also provide new opportunities. I think there’s a path for sustainable, high quality growth but that’s just one opinion and there’s no doubt the uncertainty will weigh on the share price.
BOTB is doing the right things but the external conditions have changed, and so too has sentiment. I’d pay a penny for Slater’s thoughts, as they bought in just two months ago at £24 or so.
Motorpoint (LON:MOTR)
Share price: 279.7p (+0.25%)
Shares in issue: 90,189,885
Market cap: £252.3m
Motorpoint (LON:MOTR) is the largest independent vehicle retailer in the UK. It sells ‘nearly-new’ vehicles, most of which are up to two years old and have covered less than 15,000 miles. It does this from 13 sites.
The group’s Auction4Cars.com is a business to business digital auction platform that provides a quick route for sale of part-exchange vehicles that do not fall into MOTR’s nearly-new retail criteria.
This is a car supermarket group, with quite different investment characteristics to other car dealers by the looks of it. Emphasis is on a more omnichannel approach to the car market. Operating margins are higher, as is its price to sales multiple, and its return on capital figure is much better.

It could be worth monitoring, particularly when you pair the returns on capital with a track record of relatively steady revenue growth:

The group trades on a forecast rolling PE ratio of 24.9x but the forecast PEG is just 0.7 as earnings are predicted to normalise and revert more towards pre-Covid trading.

Mark Carpenter, the group CEO, owns nearly 10% of the company.
Highlights:
- Revenue -29.1% to £721.4m as a result of Covid and lockdowns,
- Gross profit -20.8% to £62.5m and PBT -48.4%,
- Gross margin +90bps to 8.7% due to improved vehicle sourcing, improved controls, and strong demand following the first lockdown,
- EBITDA -33% to £18.3m,
- Operating cash conversion down from 98.4% to 148.9%,
- Basic earnings per share -48.8% to 8.4p,
- £3.9m of government job retention support and £1.8m in rates support.
Of the 68,000 vehicles sold in the year, c25,000 were sold on the Auction4Cars.com ecommerce platform.
Motorpoint looks to have moved quickly with its online offering, which could be promising. Investment in upgrading technology and marketing infrastructure substantially increased during the period and has so far exceeded management expectations. Motorpoint now has a fully ‘digital end-to-end customer journey’ so the experience has presumably improved quite a lot.
In Q4, online retail sales grew 89% year-on-year, with Home Delivery (launched in May 2020 and has since delivered 9,300 cars) representing 57% of this growth.
The group also notes ‘significantly increased opportunities for new sales-only branches to complete hub and spoke network, due in part to OEM rationalisation of franchised network’
Current trading
All employees have returned from furlough and, since branches reopened, trading has been strong and significantly ahead of the same period in FY20. Margins for both retail and wholesale sales are ‘well ahead of seasonal levels’ due to increased use of data in pricing decisions and strong demand.
The group notes the semi-conductor shortage impacting new car production. This is expected to benefit sales of nearly new cars in the short term. This could then of course become a headwind further down the line.
Motorpoint talks us through its new strategic objectives: the group plans to significantly increase its rate of growth, with the aim of at least doubling FY20 revenue to over £2bn of total revenue in the medium term, with an improved margin and strong cash generation.
This will be achieved through:
- Growing E-commerce revenue to over £1bn by substantially increasing investment in marketing, technology and data,
- Opening 12 new sales and collection branches to service revenue growth, increasing investment in the customer proposition, and expanding our supply channel,
- Leveraging the Auction4Cars.com platform to accommodate new supply channels and to launch a marketplace offering,
- Increasing operational efficiency through further automation and technology investment as customers migrate to E-commerce channels.
The CEO adds:
I believe Motorpoint is the best in class in the nearly new car market with leading national brand awareness metrics, an unrivalled heritage, enhanced digital presence and expertise that will ensure we continue to strengthen our competitive position. We now have an opportunity to grow rapidly as we continue our transformation into an E-commerce led business with huge potential.
Conclusion
This reads well to me. Motorpoint has clearly been busy over the past year. The group is exposed to cyclical spending habits but the ecommerce progress and ambition is promising.
It has invested in E-commerce and now has a fully scaled Home Delivery service, an integrated, end-to-end digital customer journey, additional capacity to grow through its enlarged branch presence, and has an ambitious growth strategy to more than double revenue and profit in the medium term through increased investment in technology, marketing, data and talent.
It is ‘well advanced on its journey to become the dominant E-commerce led omnichannel used car retailer in the UK’ and its digital-led auction channel has potential. The business model seems quite differentiated, making it more interesting than most in what can be a brutal and low margin industry.
Competition could be a concern, but Motorpoint is confident that it enjoys a dominant market position. Perhaps this is a particularly talented management team? If so, it could be worth backing them, particularly if they can nail online which looks to be the case.
Everyone’s saying they are prioritising online at the moment, and most are doing well from it given the present conditions. Turning that into a more sustainable, longer term growth opportunity probably requires more skill however. The rewards could be big, so it will pay to back the right horse.
If you apply the FY20 profit margin of 1.5% (prudent hopefully, as the group anticipates margin expansion) to the £2bn medium term revenue target, then that would lead to medium term net profit of c£30m. Divide by 90,189,885 shares in issue and that would be 33.1p of earnings per share.
Against today’s share price of 282p, that suggests to me the shares are probably fairly valued at these levels, but a lot of this comes down to just how much margin expansion management can generate. I could be undercooking the potential here.
With such a large amount of revenue, small changes in this critical margin assumption make a big difference to the investment case.
It’s potentially a brave new world of online nearly-new car retailing and if there is a long runway for growth, it could be worth paying these prices. That requires some thinking and a bit of vision. For now, it’s on the watchlist due to the management shareholdings, intriguing business model, and high returns on capital.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
Paul will recall myself selling down my SCS (LON:SCS) holding @ 205 to 210p.
I think I need a sofa to rest on... staggered by the +57% performance of this stock, which I did not have the conviction in, and alas only a trivial holding for me.
Well done SCS (LON:SCS) shareholders for picking and backing a winner.
Re: Best Of The Best (LON:BOTB)
Quite a few people have highlighted some of the potential issue with Best Of The Best (LON:BOTB)
1. The recent slow downward mentioned in the results
2. Large spread
3. Changes to Facebook ads
4. Other competitors emerging
In this situation we need to assess whether
1. The overall business model has been compromised
2. Is management competent
3. Is there still scoop for growth.
As a long-term holder, I was very happy with the large dip in price yesterday as it allowed me to add a few more shares for under £20.
We will have to wait and see if this was the right decision in a few years time!
I know we have a separate Boohoo (LON:BOO) thread but my question is on CFDs and director dealings, just so happens to be on Boohoo...
I saw from today's announcement that an NED "bought" 100,000 shares via Contract for Difference.
Why would a director acquire shares via CfDs instead of just regular purchases on the market? Is he using leverage? Is there a tax advantage? And is this a signal of a short term play on the share price rather than a long term hold?
Good question. Only a CGT advantage via spread bets not cfds
re BOTB - I believe we are now trading well below the bid level for the company that was turned down by the board. That should now represent a new line in the sand. That the market can be quite so surprised with a slowdown in activity as lockdown lifted suggests consensus became too dreamy. But the ROCE and Cashflow generated are a reality which suggests value is on offer below £20.
One day, perhaps, Renold (RNO) will turn out to be a multi-bagger but the history of my investment in the business explains why it is no longer a key prospect on my watch list. I first bought in at 76.75p in July 2008, and, after the share price collapsed more than doubled my stake by backing a 20p a share rights issue in November 2009. Over the next few years I topped up my stake at 30.7p and 23.5p in 2012 before selling out at 27.6p for a modest overall loss in 2013. But I still believed that RNO's new management could harness the company's potential to be a global leader in a niche chains business so I bought back in again at 30p in April 2019 before selling out at 25p in July 2019 after yet another accounting problem, always a red flag in my non-accounting mind. I like to think I am a long-term investor but after more than a dozen years RNO has exhausted my patience. Good luck to all current shareholders.
This. When I read Paul's analysis today on Renold (LON:RNO) I highly recommend any investor currently invested or thinking to go back to 2019 archives. They had an accounting irregularity then too. Can't remember the specifics as I had not been watching Renold closely then.
Causing trouble...
I'm a bit butt hurt with Scs (LON:SCS) performance as I owned if from <150p to 220p (did get a near 10% dividend) and felt it should trade at 300p when I bought. But it was unloved back then. How things change.
Anyway, I think the quality of the company has deteriorated since then. I sold as I felt they were not doing the right thing with their excess capital (they were bidding for sofa.com). There's significant capital risk in going for anything other than steady growth and IMO they should grow earnings partly through buying back stock (then they could maybe make themselves a sustainable 10% earnings growth stock (or more like cash flow per share growth as cfps>eps due to working off some old onerous leases and underperforming shops when they went too ambitious on growth in mid Noughties). Throw in a nice dividend and good operational management and the stock can re-rate above 300p.
But it seems to me that the mgt want to build out their empire. There's so much for them to prove in doing this.
At time I sold they had been unlucky with the closure of HoF franchises. That was a great little investment. In addition, their carpet biz was starting to falter and it had been a great new earner for them massively increasing sales per foot in stores. These things hid some underperforming poorly placed stores (eg Reading) that were limping on until they could close them. Not sure how many they still have (in city and bad out of town sites).
IMO without a clear capital return plan there's high downside risk. 6 mths from now trading could really fall back as we go 'post-covid' (just don't know). SCS wont go under but could go back to looking value trap
Gus
BOTB
In a long life I find it unwise to believe in coincidences.. however you may be right (Blackstone said he would rather nine guilty men go free than one innocent man be found guilty and I like that.) so let the milk of kindness flow in this case. Perhaps a yellow card system then?
But for the likes of the twerps who founded Quindell Portfolio, NMC, Patisserie etc "The Index!"
I noticed Morses Club (LON:MCL) had increased yesterday by 15% (I hold) - I could not see a reason why but after a bit of searching on ADVFN bulletin board I spotted the following research by DKvalue ( Never heard of them but they hold shares in MCL) https://dkvalue.blogspot.com/ - Very interesting piece of research and may be of interest to other followers of MCL (still not sure if it was this article that increased the SP ! )
An excellent and very thorough write up on Morses Club which I also hold and see a lot of potential to take market share, while still being extremely cheap and also good counter cyclical play if unemployment pick up. Regulatory concerns overblown if you actually look at the detail, which this piece covers well. Not seen this blog before - would be surprised if that's what caused yesterday's rally, but perhaps it is widely followed?
I thought it was another IC tip yesterday?
Paul, N Brown (LON:BWNG) (I hold). I too was dismayed by the increased legal claim and counter-claim. I was hoping that the price would pick up from today's low point, and that the trading up-date expected tomorrow would bring good news. The increasingly aggressive stand-off in the legal dispute does not augur well for an out of court settlement, and there will be significant legal fees too, and management distraction.
I do not feel comfortable so will probably sell my small position soon.
Keep up the good work.
Richard
I sold out today on the news. TBH I was getting frustrated by the poor price action and have been reducing and this was the final straw.
"Never Glad confident morning again.", a quote from Robert Browning's famous poem the "Lost leader." It's all about losing trust. It's hard to win "trust" and like virginity, it goes in a flash.
I think private investors would do well to share a list of directors and professional advisors (Lost leaders) who have indulged in what we perceive as sharp practice. Not criminal mind, we can leave that the the authorities to deal with but sharp.
We should have a panel to judge who deserves to be listed and who does not, Lets start with those who have let us down. The directors - and professional advisors - of Rev Bars perhaps: now the directors of BOTB. There is no way the BOTB directors could have been unaware of problems looming ahead 2 months back when they sold their slug of stock. i am sure what the did was within an inch of the rules. But I never want to hold stock ever again in anything these people are involved in. And if there had been a watch list (we would have to take legal advice on defamation) maybe we would never have bought shares in the first place.
Much as I love a bit of Robert Browning, I think we’re maybe being a tad unfair on the Best Of The Best (LON:BOTB) board. The PB placement of the founders’ shares was made on 31st March, whereas the softening of sales in today’s announcement is attributed to the period after April 12th, “since the latest easing of lockdown restrictions on April 12, 2021, specifically relating to the understandably long-awaited re-opening of hospitality and non-essential retail.” Absent miraculous clairvoyance, I’m not sure they could reasonably be expected to have known at the end of March what would happen from mid-April onwards.
This said, I do like your idea of a director/adviser s**t list and can think of several suitable candidates!
Gus.
Not sure a 'wallstreet bets' style blog would be useful. Don't look at it much but their is a Benish M Score - perhaps add an algorithm for "selling big prior to bad news".
But I did read somewhere that directors are not always the best at timing their sales - running a business rather than trading methinks. Capital (LON:CAPD) springs to mind which Mr Scott noted their selling but then the share price improved considerably - so maybe was to improve liquidity after all.
Still when ethics meet business I tend to have a cynical eye. The 100 baggers book has a chapter that is less complimentary of company boards, advisors et al.
Best Of The Best (LON:BOTB) without trying to sound like a hindsight trader, I sold out a few weeks ago. The reason was the iOS 14.5 privacy update. I run an e-commerce site in my spare time and ever since, sales from Facebook and Instagram have dropped off a cliff. The reason being, the loss of personalised ads as most people choose not to opt in when asked. It’s been a bit of a nightmare!
As an investor in Facebook - I am interested to know what your ad strategy will be going forward?
The bull thesis I have read around this is, all ads will now be less targeted on iphones, but due to the data Facebook can still collect on how users interface with its app, it will still offer the most targeted ads.
We’re still getting a positive ROI (just about) on our Facebook spend, but we’ve reallocated a good % of our marketing budget to improving our SEO and affiliate/referral marketing on Instagram (rather than Instagram ads). We’ve also set up a TikTok account and are working with influencers to generate following/sales. Email marketing and generating revenue from our existing customers/subscribers is another channel we use.
It’s an e-commerce business I landed in by accident, and I’ve probably learnt more about (digital) marketing in the past 6 months than the previous 40 years!
Thanks, appreciate the response and best of luck!
Scs (LON:SCS) (no position)
I found the update quite unusual.
There's a lot of focus on the order book, with less guidance on revenues or, more pertinently given recent events, gross margins and lead times.
It seems especially strange to exclude any information on gross margins, unless of course Scs (LON:SCS) are relatively unaffected by the increase in raw costs and shipping fees.
It will be interesting to see full results when they are out.
A
I have now had it confirmed that CakeBox £cbox had a huge data breach confirmed in April 2020. As a customer- they only told me on Monday. They are still refusing to tell the market of this price sensitive information. A few investors have got wind of this & the share price is starting to fall. Are they allowed to do this?
I too am curious about their responsibilities here - can anyone shed some light on if they have to make an RNS on this? surely, they should have made the market aware at the same time they emailled customers to advise of the breach?
I have now had it confirmed that CakeBox £cbox had a huge data breach confirmed in April 2020.
It's in the public domain, the lawyers are ambulance chasing already:
https://celsolicitors.co.uk/fi...
If you’ve been affected by the Cake Box data breach and would like free initial, no obligation advice on making a data breach compensation claim then you can contact us on 0808 273 0900.Under GDPR a company has an obligation to inform customers about a breach "without undue delay". I'd be more worried about GDPR fines (2% to 4% of global turnover or £20 million, whichever is lower) than anything the toothless FCA might do about failing to disclose price senstive information.
timarr
Motorpoint (LON:MOTR) - I hold - I like the more aggressive expansion plan announced today, particularly with online going well.
You've probably all the TV ads for Cazoo, which has a pretty similar business model to MOTR. Actually, with car supermarkets and online, I'd say MOTR is probably a better business.
MOTR currently has larger revenues than Cazoo, and checking their respective websites, MOTR has a similar number of cars for sale to Cazoo.
So similar valuations, you might imagine? Wrong! MOTR is currently valued at about £250m.
Cazoo has done a deal with a New York listed SPAC (blank cheque company) which values Cazoo at $7bn. Yes, seven billion dollars! Cazoo has somehow managed to convince a load of gullible fools in the USA that it's going to dominate online car retailing across Europe, and has been valued on that basis.
Cazoo's investor presentation is here, and is actually worth a look, partly for a good laugh, but also to reinforce the pockets of madness which are abounding in the more speculative parts of the US markets at the moment.
For example, it says the $7bn valuation is 1.3x 2023 estimates of revenue! Yet it's actually 7x estimates of 2021 revenue!
What's the betting that Cazoo's entrepreneurial founders (who now own 78.7% of the SPAC) will be ditching as many shares as they can, as soon as they can? I don't know what the lockin agreement is (if any), but they're easy enough for determined people to get round (e.g. open a short via a CFD on the quiet).
Obviously I can see that the valuation of Cazoo is extreme bull market frenzy, but it does highlight that MOTR could be valued a lot more aggressively, if it steps up its game.
Hence I think MOTR could do well with this faster expansion. Maybe it should send someone to New York to sniff out a SPAC to reverse into too?
Regards, Paul.
With a hat tip to David Thornton of Growth Company Investor, who flagged up this idea, and the Cazoo SPAC deal, on a Mello or PIWorld interview. I followed it up & confirmed what he was saying.
I held Motorpoint (LON:MOTR) for quite some time. A friend introduced me to following Norbert Lou of Punch Card Capital who has made some astonishing investments.
We saw he had invested in Motorpoint and followed him in.
We also followed him in to Naked Wines (LON:WINE) at £2.20
My understanding is they still hold Motorpoint which in my mind suggests it is a worthwhile investment.
With bullish ambitions like what Motorpoint (LON:MOTR) just announced, one always has to take it with a pinch of salt whether management are just trying to pump up the share price to meet LTIP targets or make their out-of-the-money options worth something. You see it all the time with so many failed AIM companies that promise the moon.
However, as Jack has mentioned, CEO holds nearly 10% of shares. What he failed to spot was that the Chairman also holds 10% of shares. So combined, they really do have a vested interest in both preserving the existing equity value, but also looking to grow it prudently over the years.
I'm not invested yet but it is on my watchlist. The one big red flag I can see is that in the USA, the latest retail trends have seen car sales drop back in April and May. The big risk is that everyone who needed a car in 2021 brought forward their plans in to 2020 and early 2021, and the volume boost we've seen in the last few months wasn't incremental, but substitutional.
Hence why I think management haven't issued a bullish FY or HY statement vs market expectations, as part of the results. Its usually what's missing that is important!
Has anyone seen an explanation for the rise in Mti Wireless Edge (LON:MWE) today? Up 15% as I type, on higher than usual volume, mostly steady small purchases, not in round numbers of shares (so looking like retail purchases for money amounts).
Has anyone seen an explanation for the rise in Mti Wireless Edge (LON:MWE) today?
Tip by Simon Thompson of the IC.
timarr
That explains it. Thanks, Timarr.
Here are my SCVR heat maps for today (prices as at ~12noon).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents. I'm also starting to experiment with other visualisations.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Best Of The Best (LON:BOTB) (I hold)
UK/INTERNATIONAL SPLITS
UK sales make up a growing portion of revenues - now 91% for the financial year just finished vs 82% just 2 years ago.
Note also the +47% growth in non-UK sales.
I think this is a good thing as it highlights the untapped international opportunity.
PRIZES + GROSS MARGINS
I track prize giveaways (and assume a 5% discount to the published figures)
So far this year, prize values are tracking much higher than previous years (£5.8m in the current half vs £5.1m in the half just finished, though note the former number is 1.5 months of actual data + 4.5 months of extrapolated data).
I find this interesting as the value of prizes is something that can be flexed up or down (by increasing or decreasing the discretionary cash bonus).
Management have left discretionary prizes elevated, so one would presume they are still confident going forward.
If we assume that:
I can't imagine management allowing gross margins to drop so low, so realistically I think that year-on-year growth might actually still be positive.
And if things do start heading south and management want to increase gross margins, then I would expect to see those discretionary cash prizes decreasing in the next few months. We shall see.
MARKETING
The total marketing spend above is my estimate and it's a shame that we have to guess this.
Note that marketing spend is c26% of revenue generated, and 42% of gross profit, not bad at all.
Which leads me to....
CASH
Management have previously indicated a need to keep £5m on the balance sheet. At the year end cash was £12.6m.
That's a £7.6m surplus (I'm assuming anything paid out in dividends is quickly replenished.)
What are they going to do with this excess cash? A marketing drive or another special dividend perhaps?
I'm surprised there wasn't more indication on what their plans are.
Which leads me to...
MANAGEMENT
I've liaised with Rupert Garton (Commercial Director) in the past and given the wider shareholder base, he implied that more metrics - e.g. Lifetime Values, Cost of Customer Acquisition, marketing spend, etc... - would be supplied going forward.
Today's report shows that this has not happened.
I know that they are discussing these things privately as I've seen people mention them on social media and management have confirmed that those details are accurate.
This is quite disheartening and puts me off wanting to hold.
Company metrics should be shared publicly, especially important ones such as ROIC (incidentally it's 2-3 months.)
I personally look forward to management selling more of their shares so that such details might actually be shared, or at the very least that they start engaging with some of the investor-friendly websites such as piworld or investormeetcompany.
CONCLUSION
I'm not put off by today's fall. In fact, I think the share price got a little ahead of itself over the last 12 months and has receded to a more reasonable valuation.
As the financials still look good and there is decent scope for international expansion, I will continue to hold and enjoy the nice stream of dividends.
A
I do not hold Best Of The Best (LON:BOTB) nor have I done in depth work on it. But I am cautious about putting a high multiple on a business such as this - which has been on an enormous growth run. On-line fashions can change fast.
One example of this is HQ Trivia which in 2018 was handing out six-figure prizes daily and would have millions playing on its app each night. But suddenly it went out of fashion and it went bankrupt in 2020 - with its last game having a prize fund of just $5. I understand the business models are somewhat different and HQ Trivia was aimed at a youth audience (where fashion changes even more rapidly).
Re Best Of The Best (LON:BOTB) volumes, your data is wrong - as of 12:04pm, 85k shares have traded, and as of your post at 9:56am, 57k shares had traded. Market makers need to be compensated for the risk in providing you a market to deal in, and when the stock is down 30% and is volatile, I don't see an issue. They won't have made £2 x 85,000 in profit, as they'll typically always be the wrong side of adverse price movements with the stock moving significantly intraday.
Regarding Best Of The Best (LON:BOTB) as a holder, I am somewhat disappointed today.
However digging around I wonder if companies like Omaze, have taken some of their biz. If the web traffic site I use can be believed (similarweb), they have gone from 200k visitors to 2m visitors in the last six months and offer cars, houses and other stuff as prizes, which will attract a similar customer base. They appear to have launched in the UK circa December 2019, previously being a US only business.
BOTB on the other hand has seen quite flat/declining traffic over the last few months:
Best Of The Best (LON:BOTB)
Management have told me similarweb is unreliable for botb.com and not to use it.
I then started using the website for trends, but that did not provide much insight.
Cheers
Oh that is interesting - thanks. Were you given a steer to anything more reliable?
Best Of The Best (LON:BOTB)
Hi Is2g08
Sadly the general advice was to not use any web-tracking services.
Cheers
A
AGFX - who knows something ? the price has done nothing for weeks, months, no news up 6% today
Argentex (LON:AGFX) - who knows. Big volume yesterday (1.8m shares traded) had little impact on the price.
Higher volume today (2.6m).
The co-CEO and co-founder resigned a few days ago - he may be selling down with institutions taking advantage of the liquidity.
It is on a very cheap rating compared to close competitor (Alpha fx) and results should be out next month.
A PI with a large twitter following bought Argentex (LON:AGFX) - Myles McNulty
On the subject of investment books there is a guy called the Swedish Investor who makes excellent summary videos of investment books (amongst other stuff) - well worth a look. https://www.youtube.com/channe...
Diaceutics #DXRX Capital Markets Day 1pm today 16.6.21. I've just been told everyone is welcome, which is great. The event includes a demo of the DXRX platform, views from an expert industry panel & strategic update from management. To register contact diaceutics@almapr.co.uk
Hi Paul - what are your thoughts on Renold (LON:RNO) delaying the results announcement for a second time - share price has taken a hit and I know you hold share in them - do you think this is a sign that all is not well?
On Best Of The Best (LON:BOTB), the spread makes it utterly uninvestable from my perspective. At around £200m, its not got a huge market cap, but currently sells are going through at £19 and buys at £21, and that is on a high volume day where over 1m shares have been traded. If we assume that these are half buys and half sells, the MMs have taken £1m in profit from shareholders in a couple of hours. I think it is a prime example of an area where the LSE is utterly broken. MMs don't provide liquidity, as we are all familiar with being unable to trade when they don't want to play ball, so why they are allowed to take such a huge cut is beyond me.
What about the highly suspicious downward movement in sp prior to these results. Maybe perfectly innocent of course but if not there is zero chance of any comeback which only encourages such activity even further. These suspicious events are depressingly common and I wonder how widely such news is known prior to rns.
yes, and I would add that “people are drinking more so we expect them to gamble less” is one of the less plausible explanations I’ve ever heard.
Agreed. Given the relative cost of drinking cheap supermarket hooch at home and expensive pub/restaurant drinks when out and about (with a standard added 15% service charge for table service), I think a more plausible chain of causality would be “now the pubs are open people are drinking less so we expect them to gamble less”, although I guess it would be a bit non-woke to say so.
Gus.
The spread is usually less than what is listed down for most small caps companies. If you plan to trade I can understand why its uninvestible but for longer term holders it doesn't matter too much. Think I bought these at about £2.5 a few years ago and at this stage have top spliced several times and earnt dividends equal to my original stake I am not bothered in the slightest about the spread
Hi Paul,
Can you look at Renold (LON:RNO) after today's announcement about the audit process requiring more time and what does this mean. Are you still a holder ?
Thanks in advance,
Tel
Best Of The Best (LON:BOTB) - That is some excellent analysis Jack and a very well balanced bull/bear case.
Hi Jack,
Thanks for the update on £BOTB
My opinion is that I'm looking at a possible downside scenario of EPS falling, maybe to 80p? That would make the PER about 24 - pretty reasonable for a business with stunning ROCE, cash generation, etc.
So with the downside scenario actually looking OK, I'm happy to continue holding for the foreseeable future. Obviously a bit of the gloss has come off the share, and management, coming so soon after big Director sales. But they've got a fantastic long-term track record.
Regards, Paul.
Sorry this posted twice without me realising, and too late to delete it. Got an error message the first time.
N Brown (LON:BWNG) - I hold - don't come across very well in this news release:
https://www.proactiveinvestors.co.uk/LON:BWNG/N-Brown-Group-PLC/rns/990356
The RNS notes current ongoing action and new action with a claim to 36m.
I hold. Sitting on a small loss now.
Can understand the fall in SP. We have not been told "this will be between £0 and £... M"
It looks to (now) be 0-36+28+...costs?
From last years notes to accounts
Until 2014, JD Williams & Company Limited (“JDW”), a subsidiary of N Brown Group plc sold (amongst other
insurance products) payment protection insurance (“PPI”) to its customers when they bought JDW products.
This insurance was underwritten by Allianz Insurance plc (“Allianz”). JDW was an unregulated entity prior to
14 January 2005 in respect of the sale of PPI insurance. The regulated entity prior to 14 January 2005 was
Allianz.
In recent years, JDW and Allianz have paid out significant amounts of redress to customers in respect of
certain insurance products, including PPI. In July 2014 JDW and Allianz entered into an indemnity agreement
in respect of certain PPI mis-selling liabilities (Indemnity Agreement). In September 2018 JDW and Allianz
entered into a Complaints Handling Agreement (CHA) to regulate complaints handling and redress payments
for both parties in respect of pre-2005 PPI claims.
In January 2020, a claim was issued against JDW by Allianz in respect of all payments of redress Allianz has
made to JDW’s PPI customers together with all associated costs. Allianz have made a claim in contribution as
well as asserting a number of direct claims against JDW in relation to:
• the Indemnity Agreement;
• alleged negligence as its agent; and
• alleged breaches of the CHA.
On 5 March 2020 JDW issued its defence which refuted each element of the claim and also issued
counterclaims in respect of the losses JDW has suffered in respect of two separate insurance policies
underwritten by Allianz. JDW has claimed that:
• Allianz is liable to compensate JDW for such loss and damage by way of a contribution to JDW’s liability in
relation to Product Protection Insurance sales (a separate product to PPI);
• Allianz has been unjustly enriched to the extent that its liability to the complainants was discharged and
JDW seeks restitution of all such sums; and
• JDW seeks contribution from Allianz in respect of sums paid by JDW pursuant to the CHA as Allianz was
also liable for the same damages in relation to Payment Protection Insurance.
On 9 April 2020 JDW received a Reply and Defence to JDW’s counterclaim. This document confirmed that the
amount of Allianz’s claim was £28m plus interest.
All claims made by Allianz, and counterclaimed by JDW, remain subject to final determination by the court,
both as to their success and quantum. The claim and counterclaim are extremely complex, are at an early
stage of proceedings and both parties will need to gather detailed and factual expert evidence in relation to
multiple elements of the claim and counterclaim.
Having taken legal advice on its own position, the Group has concluded that these issues mean it is not
possible to reliably estimate the amount of any potential settlement and has therefore not provided any
amount for this claim at this time.
There is also considerable uncertainty as to the timing of any cash outflows/inflows from the
claim/counterclaim given that the legal process remains at an early stage and the potential disruption to court
timings and process as a result of Covid-19. Legal fees are expected to continue to be incurred during FY21
but it is possible that the cashflows resulting from the claim and/or counterclaim may not arise until FY22.
Re Best Of The Best (LON:BOTB) - Looking at the monthly log of price, it puts the drop today into a better (more favourable?!) perspective, so I continue to hold for now.
Not a holder of Best Of The Best (LON:BOTB) but as an observer surprised at the extent of today’s mark down. Share price was already well off the £34 peak at or around the time of the discounted PrimaryBid placing but currently seeing them offered around £20.50 which seems excessive in response to what seems a relatively innocuous statement.
Was there also some speculative bid froth in the putative sale process that has been blown off by the comment “Following extensive talks with a range of parties, the Board concluded that it was is in shareholders' best interests to focus on the continuing growth of the business under its existing strategy as a publicly quoted business.”?
Gus.
Morning Paul, all,
Another great book that may be of interest is "Richer, Wiser, Happier: How the World’s Greatest Investors Win in Markets and Life". I found the stories very interesting and there are many good lessons in there too.
Cheers,
I am part way through this book and highly recommend it.
I wonder if BOTB drop off in activity is anything to do with Omaze?
To my mind they must have spent more than £3m advertising their raffle for their £3m house. Looking at their international site, it seems that cars and other prizes could be on the way if it turns out to be sucessful.
I don't think anyone plays their games for the enjoyment of spot the ball, neither do I think the charity aspect that Omaze promotes is particularly persuasive for the target market; it'll be interesting to see what competitive advantage comprises of if they go head-to-head.
Re Best Of The Best (LON:BOTB)
Apart from the regulatory risk pointed out by Jack and the illiquid nature of the share, the other risk that you rightly point out Snoo is competition. I’ve always been sceptical that they will scale substantially as if they start to be that successful then competitors are bound to emerge and it already looks like that is happening.
https://www.spottheball.com/
No position
Second thoughts of Severfield (LON:SFR): most eps/profit stats down on last year (March 2020) but not unexpected given the last 18 months.
Could they benefit from the rumoured infra-structure boom ? this would normally be an area of the market I would avoid but this looks a possible exception to the rule.
Unicorn who are shrewd in small caps hold a large stake and used to think if the Indian part of the business was spun out it would be worth near the current market cap of the remainder of the business, again current problems in India will have put a spoke in that idea.
Yields just under 4% and dividend is well covered also.
Regards Andy
Re Scs (LON:SCS) all the comments so far from the new boss is that he seems to be a fan of the Joules-type model of expansion into other market opportunities. Maybe he will be more expansive than the ultra cautious guy who he is replacing (no criticism of him from me. He built a great business). I take your comments, Paul, on the scope for much bigger divis but presumably, there is also the scope for development into a different type of company. Lets hope any change is a change for the better, but the £100m is IMHO ridiculous.
PS I share your thoughts on the scumbags, furlough money and bonuses. The guy you are referring to has been in the chair when that particular company has delivered for shareholders and staff alike. However, cometh the time, cometh the man and this man failed at this particular hurdle.
Given the Scs (LON:SCS) (I hold) working capital model, I don't believe that all the £100m can be viewed as "surplus cash". Some of it will be required to pay creditors. In my quick analysis, I deducted £40m (based on the interim figures), giving £60m surplus cash. Dividing by 39m shares in issue gives 154p to which we add Paul's 30p eps x 10 (conservative IMHO) giving a target price of 454p against a share price of 320p.
It will be very useful to see some updated broker forecasts
IMO The Art of Execution is a charlatan piece of work.
Its intuitive inference using a very narrow time period and sample. Much of the inference occurs around events of the GFC in 2008 when moves were dramatic on way up (commodity and EM super cycle etc), then down (the world is over) and then back up (global synchronised central bank fed recovery).
Hi mojomogoz,
That's a really good point. The data period he uses in Art of Execution is indeed quite short, and covers a highly disrupted market around the Great Financial Crisis. So the statistics in the book may not stand up to closer scrutiny. Some of them did seem a bit extreme to me.
That said, the narrative is still highly engaging, and the main lessons (running winners, cutting losers, etc) all make a lot of sense to me.
"Charlatan piece of work" is over-doing it a bit ! ;-)
Regards, Paul.
I may be prone to a touch of exaggeration at times :) ...my nickname in an investment team I worked in was by-Paula (ie bipolar...I'd always be really for or against and refused to have a lukewarm opinion...I would state I have no view or lack of understanding tbc...not a total psycho).
My profession was doing what this guys does but with a lot a more data and access (did it for the world's biggest Russell Investments and then for my own business on global and regional basis, long only and hedge fund). Some points are valid but they are not much more than opinion and narrative but he wraps it up in pseudo scientific way. This is why I'm critical and using the time period he does is simply an analysis crime.
I've heard a lot of PIs really praise this book...that's why I make my point with drama. He may give some useful tips and insights on how professional fund managers do it (he loves Odey...who I knew well)...but the book is not worthy of being viewed as a definitional investment piece
Best Of The Best (LON:BOTB) tanking a bit. 3 trades @ 8:00 2700p for zero shares, what's that about. I think there statement that lockdowns hadn't had an effect has come back to bit them.
Best Of The Best (LON:BOTB) have released final results RNS. It was all looking good, until you get to this statement
"We are excited about the opportunities that the year ahead holds for BOTB, with a recovering economy and hopefully a return to normality. However, in contrast to the summer 2020 period, we have experienced somewhat of a reduction in customer engagement since the latest easing of lockdown restrictions on April 12, 2021, specifically relating to the understandably long-awaited re-opening of hospitality and non-essential retail. We are closely monitoring this, but with our flexible model, growth strategy and plans for the year ahead, we expect customer engagement to return to normal levels before too long. I look forward to updating shareholders in due course."
Which I think is why the shares have dropped by 30%. I would have thought this presents a good opportunity to top up, but only if you think growth is still sustainable. This is impossible as there is no indication on how bad the reduction of customer activity has been. I am planning on continuing to hold and see what the outcome will be.
Best Of The Best (LON:BOTB) I decided to buy some @1900p as that seem like good value assuming they maintain the growth.
It's a big assumption to make and impossible to guage based on the given metric of "somewhat of a reduction" - that could be anything in the range of a few percentage points of reduction to a dire drop off in customer engagement. It's poor communication in my view and doesn't engender trust in a management who just a few months ago sold £60m of shares at 2400p.
Re Best Of The Best (LON:BOTB) - they have clearly built a great business but it now faces 2 big risks outside its control. The first is regulatory but the second is competition.
When it was tiny but better than other tiny competitors; it had a distinct product heritage/marketing niche ( in airports over 10+yrs now complemented by online). Now it is 100% online and capitalised at £250Mn. If the market potential and ROCE is that good, how much would it take for 1-2 big gambling firms to enter, leverage their datasets/IT teams and cashflow to build an audience and alternate brand. It wont kill BOTB (loyal players, good brand etc) but could easily reduce revenues by >50% quite quickly.
The more successful they are, the more likely these risks are to eventuate. Maybe I am bitter (I sold out out at 6-800p!!) but I think there are substantial hidden risks - perhaps explaining why the mgt took some cash out with share sales and discussions over a sale never completed.
When I last spoke to PR company (don’t rate them tbh) I wondered whether the in line stmt prior to the results was the start of things to come. I did trim but should have trimmed more - quite clear that news was in the market that trading was softening hence the SP performance IMO.
Think today’s reaction is harsh but not unexpected with a thinly traded share.
It’s a shame that management couldn’t have been a bit more detailed and quantity the impact given were 2 months on from April.
I was actually shocked at how much the share price dropped this morning - I read the RNS and made a note of the potential hit but without the specific guidance on numbers its literally impossible to quantify 'somewhat of a reduction'.
when i initially read it, it didnt sound like -%20 was going to result. Maybe its vagueness is what has caused investors to become a bit spooked with further growth potential?
To be honest, now i think about it, I really hate their choice of words. It leaves us in limbo.
Strong update from sofa specialist Scs (LON:SCS) this morning - seems to be firing on all cylinders.
https://www.investegate.co.uk/...
Revenues well up on 2020/2019 comparator, furlough cash repaid and dividends reinstated. Ahead of market expectations prognosis for 2022. No (reported) issues about supply problems or rising costs.
Gus.
Morning chaps, any chance you could look at ScS today? Would be much appreciated.
The Art of Execution is a book I would highly recommend to all. I am not a big reader but the book is written in an easy to digest format and I found it extremely useful.
There is plenty in there for the long term holder - see later chapter on how to be a 'Connoisseur'.
Reading at the moment and agree. It is very simplistic but that is its genius.
I'd certainly recommend The Art of Execution. It is a simple quick read but the stats are useful and what it does, in my opinion, is to make it clear that you can get stock-picking wrong so you need a plan for when it goes awry.
Hi, I would love to see some thoughts on Severfield (LON:SFR) and Motorpoint (LON:MOTR) who are reporting today!
Take care,
S,
Renold (LON:RNO) news that their auditors have requested additional time to complete their audit processes. Is that ominous or does it happen all the time? They say results are still in line with expectations.
Renold (LON:RNO) news that their auditors have requested additional time to complete their audit processes. Is that ominous or does it happen all the time? They say results are still in line with expectations.
I've seen that from several other companies, it's not particularly irksome in my view, unless you think there are underlying problems at a company.
Hello Paul,
Until I retired last year I worked for a small homelessness charity and even we had to delay our results due to the practicalities of being audited during COVID restrictions. I don't think it's a problem, all other things being equal.
Hope to meet you for a drink or three soon.
Steve
They had issues in the past (Aug 19) with misstatement of results due to intentional mis-reporting at a local level - a potential reoccurrence of this may have spooked the city I guess. Last time it was due to one division (gears) which worked out to be an overstatement of £2.5m. Any whiff of bad news is being hammered today!!
On 28th May Renold (LON:RNO) said:
Following a request from its auditors, Deloitte LLP, as a result of the impact from Covid-19 remote working, the disruption caused by the resurgence of the new Covid-19 variant in India and in order to provide Deloitte sufficient time to complete the audit process, the Company's final results will now be published on 17 June 2021 .
They now say Deloitte's need more time. There's always a possiblity that someting messy is hidden, but given the current contex, and the trading in line statement, I don't feel unduly concerned.
Morning Paul,
I really enjoyed The Art of Execution, lots of tips on how to make a bad trade in to a good one etc!
Currently re reading "100 Baggers", outstanding book...
Looks like decent news from Electra Private Equity (LON:ELTA) this morning, TGI Fridays doing well.
I hold.
Regards.
The Electra Private Equity (LON:ELTA) RNS isn't on the Stockopedia (new) site, but it's on ADVFN and elsewhere. Thanks for alerting me to its existence.
I'd welcome Paul's view on the trading update. The demerger plans for Fridays and Hotter are said to be on track for Q3.
I have downloaded The art of execution and look forward to reading it Paul. I am sure it is excellent but I have to say 'a pop up beach bar in Bournemouth' sounds even better - well deserved for your invaluable contributions on here. Cheers!
My morning smallcap tweet:
Time Finance (LON:TIME) Diaceutics (LON:DXRX) Filta Group (LON:FLTA) N Brown (LON:BWNG) Elixirr International (LON:ELIX) Electra Private Equity (LON:ELTA) Westminster (LON:WSG) SCS (LON:SCS) Mercantile Ports & Logistics (LON:MPL), Fireangel Safety Technology (LON:FA.), Christie (LON:CTG)
Time Finance (TIME) guides FY(May) New business origination down 30%, adj pretax flat at c. £3m. Deal arrears at below pre-pandemic levels. Strategic Update: more than double the Group's gross lending book organically; focus on funding on the Group's own balance sheet wherever possible... [SP=30.7 Cap=28m]
Diaceutics (DXRX) KPI update: Over 40% of sales pipeline generation for Q2 is currently represented by DXRX-enabled products; 16% increase in average sales prices per project for Pharma clients; 10% increase in Gross Margin %... [SP=124.25 Cap=104m]
Filta (FLTA) AGM stmt: continues to experience an increasing level of demand. Strong growth in US. UK reopening more cautious, some momentum building. Europe lagging. [SP=180 Cap=52m]
N Brown (BWNG) ongoing litigation with Allianz Insurance: "not possible to reliably estimate the amount of any potential financial outflow and has, therefore, not made provision for this claim at this time and instead a contingent liability has been disclosed...in Annual Report." [SP=63.3 Cap=291m]
Elixirr (ELIX) guides FY(Dec 21) in the upper range of £44-47m guidance. That's Grreat. [SP=558.5 Cap=258m]
Electra Private Equity (ELTA) listing prep proceeding as planned. TFI Fridays LFL since re-opening up 12.5% on 2019. Lots more. [SP=587.3 Cap=229m]
Westminster (WSG) wins 10 year managed service contract in Liberia. Worth $1.1m in first 12 months. Deployment expected to be completed within 18 months. [SP=5.7 Cap=16m]
ScS (SCS) guides FY(June) ahead of market expectations as Apr - Jun LFL orders up 79% on 2019. Restarts divs with 3p interim. Guides FY22 substantially better than market forecasts. SP rose strongly after recent DFS trading stmt. [SP=286.63 Cap=109m]. I hold.
Mercantile Ports & Logistics (MPL) bargepole tinpot renegotiates debt interest from 13.45% to 9.5%, commencement of the amortisation of the principal loan amount has also been extended by 24 months. [SP=0.53 Cap=10m]
In line: Fireangel Safety Technology (LON:FA.) Christie (LON:CTG)
Morning Both,
Would appreciate your views on Best Of The Best (LON:BOTB) which looks like it has fallen victim to the reopening with a rather wobbly outlook re customer engagement.
As a shareholder, I've personally found the company rather difficult to engage with and the PR company not overly helpful to be honest.
As a player it is good to see the ESG element creeping in with a lot more electric / PHEV vehicles combining with the other 'dream cars' - something I did suggest to the PR company.
I'll be interested to see what Finncap come up with re their projections for FY 22 and 23 after todays update, but not surprised to see the SP track down over recent days - suspect news was already out in some areas!
Regards,
Dave S.
finncap have left their forecasts unchanged as things are too uncertain. Only a month and a half in to be fair.
finnCap no change in £BOTB forecasts as yet but not putting much weight at all behind them
Rough start to the day for Best Of The Best (LON:BOTB) holders with the immediate share price hit but there still appears to be some good things to come. For example:
- New iPhone and Android apps launched
- Conversion improving due to better mobile registration, playing and the payment experiences
- Engagement growing across social channels
- Database of 1.7 million customers
On a positive note stockopedia forecast 44p dividend whereas the total payout will be 55p. Does that indicate management confidence going forward? They also refer to potential new products and partnerships.
Best Of The Best (LON:BOTB)
On a positive note stockopedia forecast 44p dividend whereas the total payout will be 55p. Does that indicate management confidence going forward?
If the company uses the wording "special dividend" i always presume that there is no certainty with regard to that amount being repeated in the future. i.e. more a reflection that based on what has happened in the past they feel comfortable paying that amount now.
I don't know this company well enough though to know their thought processes and its slightly non common to use the term specical dividend for what seems to be more akin to a final dividend - especially if there was already an expectation that there would be sucgh a chunky level of dividend being paid.