Small Cap Value Report (Weds 17 Mar 2021) - ANP, TRB, SIS, HSW

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
Timing - I'm taking a break for lunch now, and will try to do some more sections this afternoon.
Agenda -
Paul:
Anpario (LON:ANP) - good final results, but shares look pricey after a strong run up recently (like so many other things).
Tribal (LON:TRB) - Preliminary results - an earnings miss at adj EPS level, which is glossed over. Weak balance sheet. I'm not keen any more.
Science In Sport (LON:SIS) - 2020 results - in line with the January trading update. Reduced losses, and looks potentially interesting now breakeven is possibly within reach.
Jack:
Hostelworld (LON:HSW) - Covid disruption continues but cost controls and June 2020 share placing should see this OTA through
Paul’s Section
Mello Tuesday was very interesting last night, a 3-4 hour investment webinar all about gold & other miners. I never invest in this sector, because it’s so difficult to pick the winners from all the dross. Also I feel that some sector knowledge is needed, which I don’t have. That said, I found the presentations by Caledonia Mining (LON:CMCL) and Afritin Mining (LON:ATM) very interesting.
For me (Paul) though, I think too much of it is guesswork, and having a business with lots of capital (it’s very expensive to start, and maintain a mine), which sells a product with an almost random selling price, subject to wild swings from boom to bust, just doesn’t appeal to me.
All very interesting though, and I can see why a lot of subscribers here like low PER producers (as opposed to speculative explorers). Plus of course so many shares in the natural resources sector have done tremendously well in the current “everything rally” as one commentator describes it. I’ve probably missed the boat, so think I’ll stick to my knitting, rather than branching out into the resources sector.
Anpario (LON:ANP)
612p - mkt cap £142m
Anpario plc (AIM:ANP), the independent manufacturer of natural sustainable animal feed additives for animal health, nutrition and biosecurity is pleased to announce its full year results for the twelve months to 31 December 2020.
Like practically everything it seems, Anpario shares have risen strongly. Results day is crunch time, when we find out if the increased valuations of late are justified or not. It can sometimes be a bit of shock, once people crunch the numbers and realise how expensive many shares have become of late.
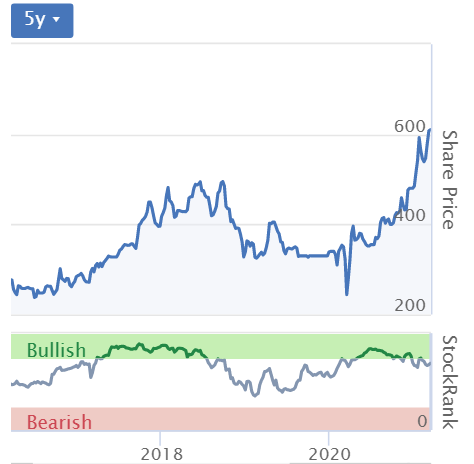
Note from the 5-year chart below, that after a great run in 2017-18, Anpario shares had quite a big, and prolonged correction, before embarking on the current run, which has seen it almost double in the last c.18 months. At times like this, it’s worth reminding ourselves that share prices can go down, as well as up. If we overpay for things, then it can take a long time to recoup losses after a correction.
.
Headline figures today look fairly good -
· 5% increase in revenue to £30.5m (2019: £29.0m)
· 9% increase in gross profit to £15.8m (2019: £14.5m)
· 22% increase in profit before tax to £5.4m (2019: £4.4m)
· Diluted earnings per share up 13% to 19.89p (2019: 17.61p)
· Proposed final dividend of 6.25p (2019: 5.5p) per share, total dividend for the year 9.0p (2019: 8.0p) an increase of 12.5%
· Cash balances of £15.8m at the year-end (2019: £13.8m)
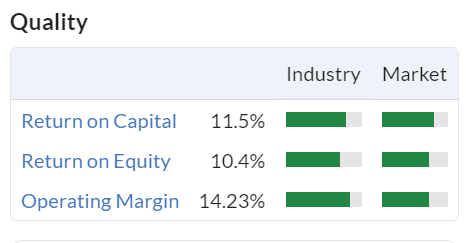
High profit margin of almost 18% (profit before tax, divided by revenues), indicating this is a quality business, with pricing power. Stockopedia flags the high quality of Anpario -
.
Earnings beat - the reported 19.89p looks to be nearly 4% ahead of the broker consensus of 19.2p - pretty good. Further down, it gives a different EPS figure (diluted, adjusted) of 21.15p.
Valuation - share price of 612p, divided by 19.89p EPS, gives a PER of 30.8 - a punchy rating. I think growth would need to accelerate, to justify such a high rating.
The PER comes down to a still high 28.9 times, using the diluted, adjusted EPS figure.
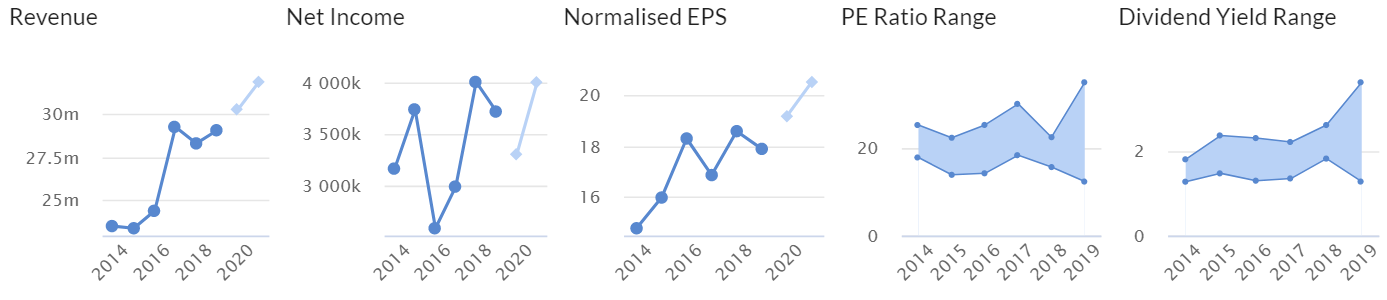
Looking at the Stockopedia graphs, Anpario’s track record looks respectable, rather than exciting. This is an 8-year period (including forecasts), so the EPS growth over that time has been rather pedestrian for a stock that’s valued on a premium rating -
.
.
Given that animal feed must be a vast market worldwide, Anpario’s revenues of only £30.5m, suggest that it’s very much a niche product. Is that likely to change, if so why?
Anpario seems to have proven very resilient during covid, so shareholders here don’t need to worry about the impact of future pandemics.
Dividends - 6.25p final divi announced, making total divis of 9.0p for the year (LY: 8.0p). That’s a yield of 1.5%
Outlook -
There has been a strong start to trading in the current year...
Travel restrictions may inhibit sales opportunities.
Setting up a European warehouse, to help alleviate “customs discrepancies” re Brexit.
Mentions the possibility of using the cash pile to make acquisitions.
Balance sheet - is really strong. NAV: £37.5m, less intangibles of £11.5m, gives NTAV of £26.0m. The company seems to generate very good profits from a light capital base - there’s only £4.1m in property, plant & equipment.
There are few creditors, so the £15.8m net cash pile looks largely surplus to requirements, providing potential upside if they do a decent acquisition for example. Share buybacks wouldn’t make sense with the valuation this high. Too much cash is a high quality problem to have!
I would regard about 10% of the market cap as being surplus cash, so it’s sensible to adjust the PER down by 10% as well, which would bring it down to a cash adjusted PER of about 26..
Cashflow statement - looks clean, this is a genuinely cash generative business. Note that £663k in development costs were capitalised - which needs to be taken account, when using EBITDA (which ignores these costs, and the amortisation of them too).
Directors Remuneration - considering the company made a profit of £5.4m, the 2 Executive Directors seem very well paid. 100% bonuses take their total remuneration to £568k and £361k, £929k in total (up from £456k in 2019). Add that back to profit, of £5,350k, gives £6,279k profit before Directors remuneration. That makes the £929k Director remuneration 14.8% of the company’s profit! That’s too much.
Looked at another way, the 9.0p divis multiplied by 23.16m shares = £2.08m cost. Executive Director remuneration (only 2 people remember) is 45% of the total amount paid in the year to shareholders. Again, that strikes me as excessive. It does make me wonder exactly whose benefit this company is being run for? Directors seem to have small personal shareholdings too, so not much skin in the game.
This does put me off a bit, from wanting to buy this share.
My opinion - this is a small, niche, decently profitable business. The balance sheet is strong, with surplus cash, and there’s a smallish dividend yield.
I’ve got three gripes with this share;
- Lacklustre growth. Sure, covid might have limited the growth this year, but longer term, considering it has also made 4 acquisitions along the way, the growth isn’t impressive. I’d want to see a step-change in the growth rate to make this share appealing. If its products really start to take off, then it could get very exciting, but there’s no evidence that is happening.
- Valuation - the shares have had a great run, and now look too expensive to interest me. We’re in danger of over-paying for things, as we’re in a roaring bull market right now. I’m not convinced that risk:reward makes sense at 600p+
- Director remuneration looks excessive, due to 100% bonuses in 2020.
Overall therefore, I don’t see the appeal of this share, at the current price, whilst recognising that it’s a good quality little business.
.
Tribal (LON:TRB)
104p (up 8% at 10:33) - mkt cap £214m
The market seems to like results out today from this supplier of software & services to the education sector, internationally. Share price up 8% as I type this.
I reviewed this company’s trading updates 4 times in 2020, and have just re-read my notes from 28 Oct 2020, which covers the main points. I was impressed with the positive trading update, and thought the valuation looked reasonable at 70p, and gave it a thumbs up (always just my personal opinions, never a recommendation - you need to always do your own research, because I might have missed something, or got something wrong). Moving on to today...
Preliminary results - for year ended 31 Dec 2020
EBITDA is meaningless for software companies that are capitalising a lot of costs, as Tribal does. So I prefer to value it & measure performance on adj EPS.
It’s quite difficult to find the adj EPS numbers, because the results statement tries to steer us towards EBITDA. Looking back to my previous notes, we were expecting 4.6p adj EPS, and this looks like a significant earnings miss at the EPS level -
Adjusted diluted earnings per share from continuing operations before other costs and intangible asset impairment charges and amortisation, which reflects the Group's underlying trading performance, decreased by 10% to 4.0p (2019: 4.4p) due to the increase of the overseas current tax charges.
Revenue is down 6% to £73.0m - not bad considering how disruptive covid has been, so that’s fine by me. Below the surface, there’s a good trend on annual recurring revenue (ARR) -
ARR committed as at 31 December 2020 increased 12% to £47.5m (2019: £42.3m) thanks to a strong sales performance in the second half of the year, increasing revenue for future years but having minimal benefit to 2020 results.
That’s important because lockdowns have given many organisations a push into buying cloud-based software, so that staff can work from home more readily, if required. Tribal seems to be in the right place for this trend, moving its customers over to its cloud product.
Outlook - sounds positive - I like it when companies tell us that they expect to beat FY expectations so early in the year. That’s a good sign that things are looking positive.
The Group has had a positive start to trading in 2021 compared to 2020 and now anticipates performance for the year to be slightly ahead of the Board's expectations
Product development - I see heavy spending on developing new products as a positive thing, providing the money is being spent well, which we don’t really know until the new products are launched -
The Group spent £11.6m on Product Development, of which £6.6m was capitalised in relation to Tribal Edge and £0.2m was capitalised in relation to Tribal Dynamics. (2019: £10.7m spent, £6.1m capitalised).
Going concern note - is very useful, with lots of interesting information about the business, so well worth a read. It concludes that having stress-tested forecasts, the risk of breaching bank covenants & being unable to pay creditors is “so remote” that it doesn’t present a going concern risk. That’s fine. I agree that, with strong recurring revenues, and proof from the last year that customers continue paying in tough times, then the business looks resilient, despite not have the best of balance sheets. Recurring revenues from financially strong customers, is more important than balance sheet strength, in my opinion.
Forecasts - many thanks to N+1 Singer, whose analyst Harold Evans has crunched the numbers in much more detail than I can here. He’s pencilled in 5.1p adj EPS for FY 12/2021. That sounds feasible or beatable to me, given that we hope covid restrictions should ease over time. Also, Tribal has high visibility on revenues & profits. Winning big contracts recently is a good sign too that more could follow.
At 104p per share, that gives us a PER of 20.4 times forecast 2021 earnings. That looks about right to me, maybe with some upside in a frothy stock market?
Balance sheet - I really don’t like this, it’s quite weak. NAV of £38.2m becomes NTAV of negative £(12.8)m once we write off £26.7m goodwill and £24.4m other intangible assets.
Working capital looks particularly weak, with current assets of £24.6m, compared with current liabilities of £40.8m, a poor current ratio of 0.6.
The liability that jumps out at me is £(23.1)m called “contract liabilities” - which sounds like deferred income - i.e. the other side of the double entry for cash paid up front by customers for future periods.
Does this matter? Maybe not, but I think it’s worth flagging that the balance sheet doesn’t have any fat in it. The company’s running on advance payments from its customers. Lots of software companies do that, and for a business which has hardly any tangible fixed assets, maybe we shouldn’t worry too much about a precarious-looking balance sheet? Personally I like to see a much more solid balance sheet. Should it be paying dividends whilst the balance sheet is this weak? I think not.
Cashflow statement - this leaves me uneasy. It didn’t really generate any cash in 2020, and not much in 2019. Certainly the cash generation numbers are nowhere near the headline adjusted profit figures. That’s a concern.
My opinion - there are lots of things to like about this company, e.g. cloud products, high development spend, high recurring revenues, sticky clients, proved resilient during covid.
On the downside, the accounts leave me uncomfortable - lots of adjustments, and little in the way of cash generation.
Also, it’s glossed over in the narrative, but the adj EPS figure was a significant miss - 4.6p was expected, and 4.0p was delivered. Therefore the Oct 2020 positive trading update turned out to be wrong, if you measure things at the EPS level, as I always do.
The shares have had a great run (what hasn’t?!) hence I’m not interested in chasing up the price. Given my concerns over the accounts, then I think this share looks high enough for now. For me, the bullish story doesn't stand up to closer scrutiny of the numbers.
The longer term track record could be described as patchy.
.

.
Science In Sport (LON:SIS)
54.5p (up 3%, at 15:22) - mkt cap £74m
I’ve haven’t looked at this company here since 2017, so can’t remember anything about it. Thankfully Jack wrote up a very interesting briefing here on 14 Jan 2021, which has motivated me to take a closer look.
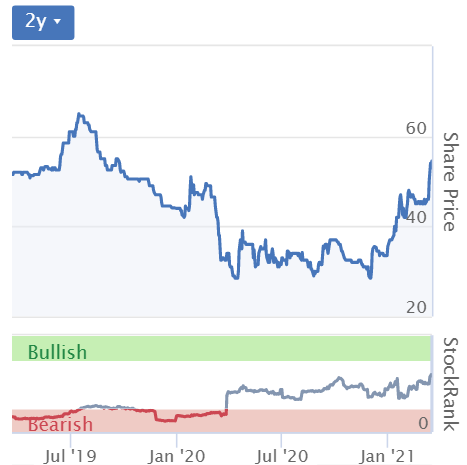
The 2 year chart looks like everything else at the moment - a big hit from the covid crash a year ago, then a big bounce back from Oct 2020 to date.
.
.
I’ve just missed an online presentation at 14:30 today on InvestorMeetCompany (“IMC”), but they’re usually recorded & can be watched later, so I’ve added SIS to my followed companies list, and should then get an email when the video is available. The link is here, but at the moment it says “not ready yet”. IMC is a superb platform, I’m looking forward to meeting the founders of IMC once lockdown ends, to buy them a nice lunch to say thank you for providing us with a brilliant, and free service, that is helping connect PIs to many companies.
This is alongside the wonderful work also being done by our friends Tamzin & Tim at PIWorld, and of course the wonderful David Stredder and his team at Mello Events. All doing excellent work that informs & educates us. Bravo to them, and other companies also providing online webinars. They’re incredibly helpful, and definitely have improved my stock selection, and introduced me to many interesting companies. I seem to have two or more webinars or zoom meetings every day at the moment, it’s so much more efficient that having to traipse into London, using up a whole day.
Science in Sport plc (AIM: SIS), the premium performance nutrition company serving elite athletes, sports enthusiasts and the gym lifestyle community, is pleased to announce its audited final results for the financial year ended 31 December 2020.
- Revenue £50.4m (similar to 2019: £50.6m) - growth crimped by lockdown impact on retailers
- Online sales grew 39%, now 50% of all sales - impressive
- Gross margin improved to 49% (2019: 44%) - that’s a good improvement
- Underlying EBITDA profit of £1.1m (2019: loss of £0.2m) - I’ll dig into the numbers below to see how real or not this number is! As you know, I don’t trust EBITDA as a performance measure, although it does have its uses in our toolkit of various measures.
The above numbers are all exactly as previously announced in the 14 Jan 2021 trading update, so this is an in line with expectations announcement today.
Profitability - the real numbers (i.e. profit before/after tax) show that it’s still loss-making, £(2.27)m loss before tax, but improved from £(5.06)m in 2019. The figures are moving in the right direction, with gross profit improved by £2.4m, and admin expenses down by £0.4m. Therefore I’d say breakeven looks within sight, especially if sales improve in 2021 when lockdown eases.
Current trading -
Trading for January and February is in line with the same period in 2020, despite the current COVID-19 lockdown in the UK and other key markets. We have continued to make gross margin improvements, and this will underpin EBITDA progress.
Our Online business continues to perform very well with strong growth of 65% versus the same period in 2020, representing 54% of group sales and offsetting the adverse effect of COVID-19 on UK Retail. We continue to see good recovery in our International Retail business.
Trading in March is in line with plan, and we are well placed for growth as lockdown lifts in our key markets.
Outlook - bit of a cop out here I think, companies really should be reinstating guidance now that we have a timeline for re-opening in the UK -
Whilst it is too early to reinstate market guidance, given the current COVID-19 lockdown, we are well funded and remain very optimistic about the long-term growth prospects for the Group".
That sounds encouraging, the tone of the announcement & commentary is certainly upbeat. Although talk is cheap!
Balance sheet - is decent, in good shape. NAV: £48.0m, less intangibles of 32.1m, gives NTAV of £15.9m, which includes net cash of £10.5m.
There’s very little in tangible fixed assets, and the commentary mentions enlarging its warehouse, so I’d be curious to know how much it plans to spend on expansion capex? Providing future capex is not excessive, then the cash pile looks ample to sustain the business without another fundraising, given that losses have now fallen to c.£2m p.a. and are on an improving trend. Jack rightly pointed out in January here that SIS has previously diluted shareholders heavily with repeated fundraisings. That doesn’t bother me though, as I’m not an existing shareholder, and am only interested in the situation as it stands today.
I’ve learned the hard way not to back cash-burning, early stage growth companies, as they never come anywhere near to the IPO forecasts. There will practically always be repeated fundraisings, often at lower prices each time, as they miss targets. The trick is to buy when everyone else is fed up, yet they’re on the cusp of achieving profitability. Easier said than done!
Overall then, I don’t have any solvency concerns, and think this balance sheet looks quite safe now that losses have been reined in, therefore it shouldn’t deteriorate much before hopefully the breakeven turning point is achieved.
Cashflow - nothing unusual here. Note that it’s capitalising £1.4m p.a. in development spend (hence why EBITDA isn’t meaningful).
£4.5m in fresh equity funding was raised in 2020, which appears on the cashflow statement, which is the main reason for the cash pile growing from £5.1m to £10.5m during 2020.
My opinion - I was expecting to find a crock here, but it actually looks a fairly decent punt. The company’s achieving meaningful revenues, half online, growing well, with the prospect of retail sales improving when lockdown ends.
The balance sheet is sound, so it looks fully funded I think.
The market cap is now £74m, which looks a bit steep, given that the company hasn’t ever made a profit yet. So you're paying for the future potential, not the historic results.
Breakeven & future profits now look in sight. It only needs to grow revenues another 10% which would be enough to reach breakeven at a 49% gross margin. That looks achievable.
Overall, I think SIS shares look worth a closer look. I haven’t got time, as I just quickly review the numbers here, but readers might want to delve deeper. I think the key things are to investigate the products - are they any good, and crucially, do customers become repeat customers? If the product is popular then good profits are far more likely than if SIS is on a treadmill trying to recruit new customers all the time, who don’t repeat buy. How do its products compare with the competition? I would imagine this is quite a crowded space.
.
Jack's section
Hostelworld (LON:HSW)
Share price: 90.89p (+2.12%)
Shares in issue: 116,321,185
Market cap: £105.7m
Hostelworld (LON:HSW) is an online travel agent (OTA) for ‘budget-conscious travellers’ - we were all skint university students once.
The group’s core online platform provides the opportunity for hostel owners and other low-cost accommodation providers to advertise their accommodation to independent travellers. Most of the revenue is generated through taking a commission from bookings made through its technology platform, including the Hostelworld website and related Apps.
This efficient business model has favourable working capital attributes and strong cash conversion. It’s a profitable, cash generative operation that was previously seeking to hold its own against some deep-pocketed, big tech competition. But then Covid came and bodyslammed the industry.
Cue a €15.2m share placing in June 2020, representing up to 19.9% of the existing ordinary share capital, and a cancellation of dividend payments.
This dividend was also reduced in 2019, before Covid. So clearly Hostelworld has been through the wars. What is immediately interesting here is the scale of the share price fall over the years, coupled with the group’s track record of free cash flow generation.

Here’s the free cash flow per share:

True, that has turned negative on a trailing twelve month basis and had also dropped in 2019, but if you take the average for that period it comes to about 15.5p, which would value the group at around 5.7x ‘normalised’ free cash flow.
So if the group stands to not just recover but grow as an OTA, that’s a potentially attractive entrypoint. But then again, in more normal times, Hostelworld faces stiff competition from well-funded operators.
And the above aside, the financial results for 2020 are pretty grim. Hopefully this is as bad as it gets.
- Full year net booking volumes declined by 79% (2019: -6%),
- Net revenue of €15.4m, a decline of 81% compared to 2019 (2019: €80.7m),
- Net Average Booking Value ("ABV") of €9.33, a 22% decline versus 2019 (€11.97), due to the impact of increased cancellations and reduced bed prices,
- Marketing costs reduced by 72% to €9.3m in 2020 (2019: €32.7m), aligning spend to sales volumes,
- Administrative expenses reduced by 43% to €36.1m in 2020 (2019: €63.4m), including both fixed and variable costs,
- Adjusted EBITDA loss of €17.3m, down from €20.5m profit in 2019, and
- Adjusted free cash flow absorption of -71% (2019: 53%).
The balance sheet has been strengthened by the placing and a post-year end €30m term loan facility. Total cash at 31 December 2020 was €18.2m (2019: €19.4m) of which €1.2m was a short-term invoice financing facility (2019: €nil).
But there’s no getting around the fact that these results are poor. The question is whether Hostelworld can recover over the next year or two and then compete effectively against other OTAs going forwards.
Conclusion
In a previous update back in August 2020, the group pointed to improving demand with revenue down 69%. Six months later and FY revenue is down 81%. Obviously lockdowns have a direct impact so perhaps we shouldn’t read too much into this.
The group CEO, Gary Morrison, comments:
As vaccination programmes continue to be rolled out in our key geographies across the world, I am confident our loyal customer base has a strong desire to travel once restrictions allow, even more so after a prolonged period of confinement… I remain confident that Hostelworld will emerge from the pandemic stronger than before and able to seize market opportunities when normal travel patterns resume.
And that’s the crux of the investment case here. Can Hostelworld not just survive current conditions, but thrive on the other side?
Shares have already rerated from the Covid crash and the recovery across multiple geographies could be bumpy and inconsistent. Hostelworld is not giving any guidance for FY21 and dividends are still off the table. And there’s no getting around the fact that FY20 results are poor.
So the group is not out of the woods yet, and the share price has recovered strongly over a one-year period. But Hostelworld has raised cash, strengthened liquidity and the balance sheet, and enhanced its core platform.
It looks like there’s plenty more work to do around its core tech stack though, which does make me wonder how well it will compete in future against some very sophisticated OTAs.
Hostelworld has a resilient and flexible business model, with good control over its cost base, but this recovery is likely to take time. A global, vaccine-led recovery from Covid would obviously be a strong tailwind but longer term, competition continues to be a threat in my view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Interesting comment from Lpa (LON:LPA) that their sales are being deferred as their customers can't source other parts for their manufacturing, so having to delay/pause until those parts come in...! Due to Brexit.
Quote from profit warning: "Other parts of our customers' supply chains have not performed so well and, as a consequence, our customers have production issues caused by lack of supply of parts needed to run their production lines. Following programme reviews by customers, further supplies of many of the parts we manufacture are now not expected to be required for several months."
Doesn't bode well for any company that does extensive manufacturing in the UK, especially complex ones (cars for example?)
It looks like Brexit as well as the shipping congestion is a perfect storm for UK manufacturing...
To answer Pauls’s £SIS question on expansion capex here are details from their website: ”Consolidate Nelson sites and 3PLs into single site
• Capacity to deliver £200m revenue with limited additional capex
• Installing new Gel filling and packing line
• December occupation, Q1 FY22 completion
• £4.3M Factory & Gel line total cost
• £2.2M from cash, balance lease financing
And re. the question on the product and whether there are repeat customers, I started looking at Science In Sport (LON:SIS) on the back of their products (I rate) and the fact that all my friends use them and they seem a top seller on wiggle/well used at triathlons. Considering their massive growth online, flat sales compared to 2019 despite retail closures and gyms and mass sporting events largely closed/cancelled, together with growth plans online/overseas/football backed by investment in capacity and the decent balance sheet, I think there is (very) good upside potential here. I’m holding onto this one., but did buy in some months ago.
Kape Technologies (LON:KAPE) FY20 results released today. ido Erlichman, CEO & Moran Laufer, CFO run through the the main events of the last year. The Group experienced strong revenue growth, with EBITDA ahead of expectations and improved profitability underpinned by organic growth initiatives. Trading in the first quarter of 2021 has remained strong with solid traction for Kape's solutions. It is anticipated that the enlarged group will generate revenues of between $197-202 million and Adjusted EBITDA of between $73-76 million for the full year 2021 on a reported basis. The Board remains confident in the Group's growth prospects in 2021 and beyond.
Video & Podcast.
Sthree (LON:STEM) Q1 Trading Update given on Monday 15.3.21. Mark Dorman, CEO & Alex Smith, CFO update analysts on the performance. The group delivered a strong performance ahead of management expectations. USA has bounced back robustly with net fees up 19% driven by Life Sciences. They also give an update on market trends they observe, companies are focussed on rebuilding global supply chains, much attention to ESG and sustainability, and obviously tech and automation are strong especially advanced robotics and digital commerce.
Hear the full analyst presentation here:
Video & Podcast.
Hostelworld (LON:HSW) I’ve been a holder as I liked the recovery potential. I was concerned when management did not further reduce marketing spend when hostels were closed, but I changed my favourable opinion entirely when the terms of the €30 million five-year term loan facility were announced (RNS 19.ii.21). 9% above EURIBOR plus 3.3 million essentially free warrants plus quite restrictive terms and high fees flag up a certain desperation. An inability to find acceptable funding was too worrying for me.
There was a change of CFO a few months ago. The current CFO does not appear to own any shares in HSW. I am aware that if I stick to my rule of never owning more shares than the CFO, I avoid quite a bit of carnage.
Unusually late in the day and extremely succinct (disdainful maybe?) trading update from Games Workshop (LON:GAW) (yes, not a small cap but widely held here including by myself):
"trading in the three months to the end of February 2021 has been in line with expectations, notwithstanding the majority of our UK and European retail stores were subject to Covid-19 closures and distribution disruption during the period."
No indication of whose expectations or what they may be. Struck me as a little bit too haughty if I'm honest.
A lot of their announcements come over that way. It’s part of their policy of underpromising and over delivering :)
I agree neils. I've been a holder for many years of Games Workshop (LON:GAW) so am used to their mid-afternoon RNSs which are brief and give away very little. Relative newbies to GAW may not be used to this style of updates and have a greater level of frustration.
As I pointed out on ADVFN, I think the timing is due to there being a Board meeting today hence the reference to the Board in the dividend decision. GAW seem to take quite seriously their responsibility of releasing market sensitive information immediately rather than waiting until 7am the next working day.
Market reaction seems a little harsh for an "in line" announcement, however in recent months this share has bounced quite a bit between £90-£120. Historically share price movements have been quite significant when they've happened so 25% has to be tolerated (I say this as an experienced GAW holder who's seen these patterns many times, have stuck the course to see a 15 bagger (as of today)).
Yes, you have to ignore the noise. I’ve held for a long time. Average buy price £2.62 so it’s ”a lot bagger” for me.
yes it did seem a bit light on detail...
although they are firmly on my buy list when i have spare funds. I worked with them on a playstation2 game (WarHammer40K) and they were excellent compared to most licence holders.
Does anyone know what happened to Team17 (LON:TM17) Final Results promised yesterday. I don't seem to see this on Stocko or hl.x ?
£TM17 results were out yesterday but missing on Stocko for some reason.
They are on HL and Investegate. https://www.hl.co.uk/shares/sh...
I reported the missing results for TM17 and indeed there is an issue which which they reported to their suppliers.
Interestimg comment from Stonegate in an FT article today.
"warned that if there was another lockdown this winter it would have to consider raising more debt or selling assets."
The fact that this needs to be stated or mentioned makes me question my own assumptions on full return to normal by Q3. Are markets not pricing in any risk of another lockdown this coming Dec?
Why should there be another lockdown?
Most people will have been vaccinated by then.
"Why should there be another lockdown?"
There shouldn't - unfortunately that doesn't necessarily mean there won't.
Government advisors already getting in their early markers that another wave is entirely possible/probable in the winter. They also say that we can expect a much worse influenza season as there will be virtually no natural immunity in the population.
And the people supposedly in power have so far proved more willing to follow than lead.
Remember, no "thumbs down" option available any longer although I guess you can still Report this post for deletion .
I'm off to Cardiff now to have my hair cut.
Yes it's possible but only if the current vaccine is ineffective.
Flu maybe worse but we have never locked down because of it.
But I don't think the markets are considering it. Although I don't think everything will be back to normal by Q3.
Who is worried by flu? Surely the flu jab differs every winter once they know what's afoot the vaccine is made. Personal y I''e never had a flu jab and it must be 20 years since I last had the flu but surgeries get paid for each one administered......
Why should there be another lockdown? Most people will have been vaccinated by then.
Lockdown hasn't occurred to save lives but to ensure the NHS isn't overwhelmed, so if we got a lot of cases we'd probably have to have some form of restrictions.
Possible reasons:
Basically CV-19 isn't going away. I think there's a small but not insignificant risk that we have another set of restrictions next winter.
timarr
Basically CV-19 isn't going away.
Timarr - would you not agree that one of the possible outcomes is that exactly that happens though and the CV-19 does go away ?- i would say i am not partiucalrly expecting it to go away but that surely that is one possible outcome if enough worldwide immunity is built up and immunity lasts long enough and the covid doesnt mutate to a significant enough a degree over the next 9-12 months? - it would be nice to have some hope even if thats only an 18-1 shot like Justin Thomas in the golf last weekend :) - lets hope the odds of it going away arent the same as Lee Westwood getting over the line in a big golf tourney as that may mean its here for keeps.
Forget Lee Westwood, there is more chance of me winning a major than CV-19 going away in our lifetimes. We can estimate the % of population that need to be vaccinated, given vaccine effectiveness against transmission and R0. With the numbers as currently understood for the variants that would be dominant without lockdown restrictions, we come up with a number greater than 100% i.e. impossible.
We will likely improve our vaccines but probably not enough to allow eradication. There are so many other factors that would go in to that question too. A key one is that CV-19 is likley present in animals. The one comparable disease that we have eradicated (smallpox) is not.
We have much greater grounds for optimism now than we did 6 months ago, but that does not extend to CV-19 going away. We can take steps to protect ourselves individually and as a society/economy but the disease will still be there and people will carry on dying from it. Sorry, I wish it wasn't true but it is.
Sorry, I wish it wasn't true but it is
Thanks for nailing your colurs to the mast in that regard , i have been an avid follower of Dr John Campbell on you tube and he has come across as being slightly more optimistic that practicably speaking we could potentially see the threat go away in this country to the extent that it would be a non issue (kinda similar to new zealand and australia **) - that might be my biased intepretation of what he has been saying and its not that simple as that is as its not really gone away in australia or new zealand so i am probably semi guilty of over pimping the gone away aspect - however it seems strange that everything should be so uncertain as to what will happen other than there being less than 0.0001%** chance that this will burn out naturally where you seem to have complete certainty with regard to your viewpoint. ** i am presuming your day job is not pro golfer or you intend to make that your day job in the future :). Ref Dr John campbell - ok he could be as wrong as the next person with the assumptions he is making but the one thing i can say is that his opinions are not fixed and he updates his views as new evidence comes out - i can say with assurity the amount of hours he has spent researching covid over the last year will be more than 99.999% of the population and his research tends to concentarte on factual scientific papers that contain proper data first - so whilst not being a total sheep generally speaking i wouldnt disagree with his thoughts. Hopefully there is a middle ground here in that it might not go away but be at such neglibile rates that you are more at risk of getting killed by a cow than dying of covid.
rmillaree. How very well put.
thank you.
About 100 people are killed by a cow each year in the UK. I don't think we'll get below that for covid but it's theoretically possible if there were some major breakthroughs, say in treatment. But that's a different issue to saying that CV-19 has gone away.
You talk about the disease going away, or it being a non issue, but it's not clear now what you mean by this. Obviously it hasn't really gone away in Aus/NZ. They are protecting themselves from it. If they opened up it would be straight back. Yes we could do the same as they are doing now, but we'd be kidding ourselves if we said it had gone away. As for non-issue, perhaps that could mean 10,000 to 20,000 deaths per year, which would mean it was comparable to flu. In that case, then yes I would see that as possible but I wouldn't describe that as having gone away either (and neither, personally would I describe it as a non issue but I can see why some might).
As I said before I do think we can be optimistic, but optimistic about our ability to deal with it, not optimistic that we wont have to.
p.s. I am surprised you imply that John Campbell would disagree with what I said above. Can you refer to a specific day where he talks about this so I can check it out?
As for non-issue, perhaps that could mean 10,000 to 20,000 deaths per year, which would mean it was comparable to flu.
No i was pretty much talking at the level of cow related deaths before we could really say its gone practicably speaking - anything at the levels of flu and i would say we are still either papering over the cracks or it mostly certainly isnt gone away - even if it is deemed to be at acceptable levels then or levels we will have to deal with.
p.s. I am surprised you imply that John Campbell would disagree with what I said above. Can you refer to a specific day where he talks about this so I can check it out?
Its tricky as he has soooo many vidoes - taking a quick look if we look at the long term immunity labelled one from 18th november right at the end he does cut to the chase - obviously thats before the new more strains turned up late december and before the manaus second wave - so its possible he may have toned down his thinking after that date , although i have been avidly watching and cannot recall him having changed his tune later on.
Thanks for the John Campbell reference. I watched the video. He makes a number of claims around immunity and reinfection that are contradicted by the evidence we now have from Brazil. Then at the end he says it's his belief that the virus will be eradicated without offering any evidence as to why. If the only evidence is the prior contents of the video then, given what we have subsequently learned, it can be discounted. I'm sure what he says about general immune response is true, but the conclusions he draws from that appear now to be contradicted by the evidence.
Even if everything in the video was still true, it doesn't address issues such as vaccine effectiveness and limited take up (in the UK 77% of adults say they will take the vaccine which is good by international standards). There are a number of other factors that count against the eradication of the virus.I dont wish to disparage him that's just where we are.
If you read this, I have a suggestion. As you watch him regularly, how about contacting him and asking him the question directly: is it realistic to hope that the disease might just go away?
Thanks for taking the time to come back to me cmpeckham - there are other videos i think where he has gone into things in more depth - i just dug out the obvious one last night - there is probably 365 to trawl through altogether
I think his main thrust is that the people who got sars are still showing good antibody or t cell response many years later - the basic form of covid is sort of stable in that the mutations are not raeally anything along the level of what happens with flu or ebola or aids (as evidenced that the virus is mostly workuing for now agaisnt different strains and if it turns out they don't work hopefully is formulaic tweeking that is needed) , the maths can work in your favour - if R0 remains below 1 then in theory a whack a mole attack should be able to target out of existence so there is always that simplt track and trace route to success, natural herd immunity possibilities - in some countries we have already proved that rate of transmision can be kept at next to zero and finally the old chesnut that pandemics do turn to burn out - albeit we may be left with undesirables.
So i have well more than 0.00000005% or lee westwood hope (0.01%) hope that we can find a plan -or get lucky - i have no expecatations than the outcome will be good anytime soon but i disargee with those who say there is no hope.
If you read this, I have a suggestion. As you watch him regularly, how about contacting him and asking him the question directly: is it realistic to hope that the disease might just go away?
He is a busy man woth 1 million subscribers i did contact him once and didnt get a reponse - being honest his vids are contstant reavaluations of the overall state of play so if we keep an eye out probably not to long to wait to see what his current thoughts are - i suspect its fimly in the wait and see category and any speculation is simply idel speculation - i suspect if you emailed and asked directly current odds of us making this something less than a cow killer in 3 years i guess he would say 25% plus - thats idel speculation on my part tho.ugh
”Forget Lee Westwood, there is more chance of me winning a major than CV-19 going away in our lifetimes.”
I just don’t think one can be that certain about anything when it comes to C19. I am sure your outline is “one possible future” (as they say in the Terminator films) one of many possibilities.
Timarr - would you not agree that one of the possible outcomes is that exactly that happens though and the CV-19 does go away ?
Hi rmillaree
Yes, it is a possibility. But I don't know how we'd work out how likely that possibility is.
I think the safest thing is to assume we learn to live with it rather than it will go away. If we oldies all get vaccinated every year, a la flu, then it stops being so deadly. Hopefully we get home treatments for younger people who get a bad case.
But next winter - maybe a bit early for that?
timarr
You may like £GOLF or $GOLF aka Acushnet. Currently down a bit so $6 off it's high. Believe we are gagging to go end of the month so some new kit seems appropriate to lift the spirits.
"You may like £GOLF or $GOLF aka Acushnet."
Cheers for that GarryC i will have a butchers when i get time - i have had Calaway ($ELY) on my watchlist for a short while - unfortunately like lots of stuff on my watchlist the price spikes up before i ever get a chance to make a purchase - the callway price has doubled since november (what hasnt we may say - excep the t stuff i hold) . possible worth of a side by side comparison these two as the market caps are are very similar
Tim
“Basically CV-19 isn’t going away”. Do you mean is never going away or isn’t going away in the short term?
“Basically CV-19 isn’t going away”. Do you mean is never going away or isn’t going away in the short term?
Hi MichaelFBS
Very good question.
No one is actually quite sure why diseases stop or at least stop being very dangerous. The best that I've seen is that if children and young people get repeatedly infected they tend to build up an immunity. There's also a suggestion that diseases tend to mutate into less dangerous variants but I'm not convinced that's a certainty.
Spanish flu seemed to lose its power after 4 or 5 years, although it never really went away. There was another pandemic in the 1950s that was based on it, although it wasn't as dangerous.
I think the most likely thing is that it stays around forever, but we learn to deal with it.
timarr
Thx Tim.
I will be honest I have no idea but do hope that the “learn to deal with it”/live with it comes quicker than most people seem to wish.
Regards
Michael.
I will be honest I have no idea but do hope that the “learn to deal with it”/live with it comes quicker than most people seem to wish.
I'm not clear why some people who disagree about the potential risks of covid assume that those disagreeing, or in fact anyone, "wishes" for the pandemic and the consequential effects to continue!
Why should there be another lockdown?
The big risk is variants. There are going to be large pools of infection round the world for the next year at least. Some of those may be among younger people in the UK, and an enthusiastic exit from lockdown could easily lead to a significant rise in infection rates there. Any of those pools could give rise to a variant that is not controlled by exisiting vaccines, could be more dangerous to younger people, etc ..... And, particularly in the absence of stong internation travel controls, such a variant could easily become prevalent in the UK. That could force further lockdowns.
We all hope not and with luck and careful actions by government it will be avoided, but it can't be ruled out. I'd give credit to any business that looking that far ahead in risk planning.
”Any of those pools could give rise to a variant that is not controlled by exisiting vaccines, could be more dangerous to younger people, etc”
But it is quite possible that:
“Any of those pools could give rise to a variant that continues to be controlled by exisiting vaccines, is much less dangerous to the general population as a whole etc”
Firstly the simple fact is that we just don’t know and secondly I just don’t get the negativity over the virus. We are vaccinating against in a huge rate (where the political will is there US/UK/Israel), better at testing for it, better at treating it etc
There were 465 patients admitted to hospital with C19 on Friday. I hardly see that as overwhelming the NHS and that surely was the only reason ever given for lock down?
Full disclosure I get vaccinated tomorrow and have been stuck in the same house for 6 months and frankly............
I think some of the key scientists have done us a significant dis-service by attributing some kind of sentience to the virus. "Immunisation will encourage the virus to mutate" I heard something or something similar to this recently.
Virus development is just evolution in double (plus some) quick time compared to what we normally consider. Viruses throw off a huge number of mutations very quickly; the rubbish ones die out quickly, the more effective (in terms of their ability to procreate and spread) will flourish.
So whilst there no doubt will be lots of variants that are less harmful or less contagious, those are irrelevant. The important consideration will be whether any random mutations occur that happen to be resistant to the immune response prompted by the current vaccines; those would be the survivors.
I do actually feel quite optimistic for where we are currently, but I just think that some of the views that "they think it is all over" are not really based in science.
On the subject of things that are not really based in science, here's my left field "win win" scenario (for us and the virus.) Imagine if a mutation emerges that :
I am being a bit "SciFi" I will confess but it is a scenario that could happen and would allow us to co-exist with this virus. Great for biodiversity surely?
Just as a random example : Wolves were essentially eradicated from the UK because of the threat they posed to humankind.
I do actually feel quite optimistic for where we are currently, but I just think that some of the views that "they think it is all over" are not really based in science.
More practically, the market reaction to the "they think it is all over view" looked very optimistic even before the vaccine supply chain issues that emerged late yesterday. The models and the words coming out of SAGE clearly indicate that they expect a fourth wave when restrictions are lifted - the difference this time is that they expect less deaths.
We should note that pandemics do "just go away". The fact that we are all here and weren't permanently plagued before last year is evidence of that. But the death rates to get to that point are probably not acceptable in a society in which we have the science to prevent them.
Beyond that, this is a coronavirus - and we have never managed to eliminate any of those, ever. There will remain vast pools of unvaccinated people in other parts of the worlds for many years where the virus can circulate freely - possibly forever.
Take-up of the vaccine in India, for instance, is relatively low - but the average age of the billion plus population is under 30, most of them aren't at any risk. The vaccine supply to Africa is nowhere near the need - and that's before you consider the challenges of rolling it out on minimal healthcare infrastructure - and then doing it again every six months. And Brazil - well, that's a disaster in technicolor.
This also makes a point that I've been pondering for a while. Countries with younger populations - India, much of South East Asia, all of Africa - ought to suffer less economically than countries with older populations while posing a health threat to those same countries. We need vaccines to function, they don't.
timarr
Timarr
Beyond that, this is a coronavirus - and we have never managed to eliminate any of those, ever.
Errr what about SARS?
Errr what about SARS?
It's a fair point - there have been no cases of SARS reported sinc 2004. On the other hand it was far less transmissable than CV-19 (becauses it infects the lower respiratory tract rather than the upper one).
And, of course, it was contained. CV-19 quite clearly isn't.
timarr
And, of course, it was contained. CV-19 quite clearly isn't.
Totally agree CV-19 is a different beast entirely - The fact that the R0 number is higher makes it a harder job to tackle - but i would start from the viewpoint that the principle for tackling should and could be the same - get the R0 below 1 for long enough in every area of the planet and in theory we could have the same end result - perhaps we won't be able to do this if its core charatceistic is that it will always find a way to get R0 above 1 - perhaps it will always mutate enough so we are alawys chasing the tail each year - i have no idea how it will pan out but there is a decent precedent set here set with SARS that this is not an impossible task IMHO.
What is slightly annoying is that if we had learned the lessons of SARS and not buried our heads in the sand ref plan of attack in the intervening period things may have been much less bad with regard to proetcting the vulnerable - the WHO and political posturing of countries combined that delayed the confirmation this was even a pandemic for possibly a couple of months was a complete disgrace IMHO. I think we were ranked second in the world behind us ref preparadness for this - that glossy brouchure of PR spin was also a complete disrace - although perhaps thats an execution issue that we should lay the door firmly at the goverment - possibly to easy to compain with hindsight here as there was a whole chain of obscurification when we needed the opposite.
there is a decent precedent set here set with SARS that this is not an impossible task
Well, you'd hope so but in practice I don't think we can put this genii back in the lamp. There are huge swathes of the world's population with little access to healthcare and lots of younger populations who don't need it for themselves. How do you vaccinate Africa? Repeatedly?
The lesson from SARS is go hard and go early but even then there was luck involved, because it was relatively hard to transmit and, in particular, didn't spread asymptomatically. But let's face it - the UK saw this coming - China, Italy and then Spain - and still didn't react. Are we in any position to criticise other countries for failing to react?
For the UK the main problem is that the NHS is underresourced. When it's already running permanently at 95% with the lowest number of intensive care beds per head of population in Europe it doesn't take much to cause a crisis. To the extent that the reason for lockdown was protecting the NHS then the economic downturn can be traced directly to the governments of the last ten years systematically underfunding it.
Perhaps the recognition that economic growth depends on having surge capacity built into the NHS will lead to a proper long-term funding plan for health and social care. But frankly, I'm not counting in it.
timarr
" with the lowest number of intensive care beds per head of population in Europe"
I don't think that is correct, do you have a link to those figures?
The ones I'm seeing say the UK has more ICU beds per 100,000 persons than Ireland, Slovenia, Netherlands, Finland, Sweden, Greece and Portugal has the lowest number.
The ones I'm seeing say the UK has more ICU beds per 100,000 persons than Ireland, Slovenia, Netherlands, Finland, Sweden, Greece and Portugal has the lowest number.
Ack, yes, I was thinking of is the "accessibility index" which is a combination of the number of beds / 100,000 people plus the physical access. On that basis the UK is ahead only of Sweden (which is twice the size of the UK with a sixth of the population).
I think you're at least partially right - this article suggests that we're ahead of Sweden, Ireland and the Netherlands at least:
https://www.health.org.uk/news...
The other points it makes are also relevant, though - the UK is at the bottom end of international comparisons for beds and doctors per head of population.
Overall the NHS has done a remarkable job, given the pressures, but the price in terms of waiting lists and lowered quality of life for people who haven't been treated is yet to be calculated. The latest squabble over wage rises for the NHS isn't likely to help matters, this government does seem inclined to pick fights it's bound to lose.
timarr
Is there any correlation between spending on healthcare by European nations and the level of deaths or mortality rate from Covid? I think it is probably a rather poor correlation.
I don't hear any discussion about capacity in the NHS, but it's something we need to be acting on now. The key point being that in a normal year, it is seasonal illness (primarily flu) that gives us capacity problems. This year seems to have been the best year ever(?) for seasonal illness - there basically wasn't any. I guess the jury's still out on whether CV-19 is seasonal.
If we assume that we are opened up next winter, then we have normal seasonal illness making a return, which in a normal year without CV-19 pushes us to capacity. Some say that next year will be bad for flu because we're now more of an open goal for the viruses. So that would take us over capacity and that's before we even start thinking about CV-19. So how exactly will current plans protect the NHS without needing another lockdown? Let's not forget about the backlogs of other treatments and surgeries that have built up and the higher level of urgent surgeries that will presumably happen going forward as a result. I can't quite see how all of this is supposed to work. That pattern would then repeat every year (unless CV-19 goes away). Lockdowns 4 and 5 next winter??
I guess we have to hope that the power that be co me up with a cunning plan , i couldnt underrstand the lack of use of the nightingale hospitals - to me i would have tried to ensure these were suitably staffed (is there enough emergeny capicity with retired bods / students and people doing other stuff / arm medics etc ??) so that as many normal hospitals within those localities remained covid free - check all the covid bods into these nightingale hospotals - i would preume that would have helped mitigate the amount of vulnerable people catching covid in the main hospitals - and make a paln to have more of these places available if needs be. I know nothimng about the nhs though so my random musings simply may be too much to put into practice and may have more downsides that positives eg if the level of care in the nightingales was always going to be substandard compared to your hopefully efficient local normal hospital - i guess practicably speaking everything stretched to breaking point before anything goes wrong so it can't be easy finding the solutions without the combo of well targetted extra wonga and waiting for that investment to deliver.
"i couldnt underrstand the lack of use of the nightingale hospitals - to me i would have tried to ensure these were suitably staffed (is there enough emergeny capicity with retired bods / students and people doing other stuff / arm medics etc ??) "
I think the simple answer to the staffing question is no, there were not enough (latent) staff to fully do that - I think most of the deployments you suggest were utilised. I was working on a project for a Community Healthcare Trust during the first wave and a lot of the community based clinicians (and admin staff) were redeployed in to Hospital settings.
However, based on what we have learned I think there could be a smarter solution in terms of redeployment, but the 'next time' might be sufficiently different as to invalidate that.
And in relation to cmpeckham's mention of the next round of seasonal illness, I have seen quite a few references to the fact that the next flu season could be particularly bad. I don't share those fears to be honest - I think flu vaccinations will again be offered to the younger cadre in the coming season, some of the mitigating habits we have learned will stick for a while (hand washing in particular) and many of the people that would be particularly vulnerable to a worse flu season are sadly no longer with us.
”Any of those pools could give rise to a variant that is not controlled by exisiting vaccines, could be more dangerous to younger people, etc”
But it is quite possible that:
“Any of those pools could give rise to a variant that continues to be controlled by exisiting vaccines, is much less dangerous to the general population as a whole etc”
Of course, Michael. I didn't suggest otherwise. However I was responding to post suggesting there was no point in speculating about the possiblity of a further lockdown. My point was simply that the possiblity exists. As I said hopefully that won't happen, and there's a good chance it won't, but recognising the possibility in a company's forward risk planning seems a sensible approach.
"That makes the £929k Director remuneration 14.8% of the company’s profit! That’s too much."
Science in Sport's remuneration is even worse. Not made a profit yet but the chief pays himself nearly £1m a year! Not a bad gig if you can get it.
I was looking at UBER (not to invest I hasten to add) and the CEO earned $42,000,000 last year including $2,000,000 in “business related expenses”.
That ($42m) by the way means he earned what an Uber driver on average earns per hour ($25) every 20 seconds (assuming the CEO works 24 hours a day 7 days a week) and on top of that he will receive a bonus of $100m if manages to achieve a $120 billion valuation for Uber and keep it there for 90 days!!
Egregious?
I believe Coinbase CEO has a package that should deliver him $1m per day for 10 years.
He's very strident that Bitcoin is a tool for greater social justice in the world...
I held the same view as you regarding the mining sector but I have slowly changed over the last 6 months as it become obvious that structural changes responding to climate change and the pandemic are having far reaching effects on this sector. Caledonia Mining (LON:CMCL): Caledonia mining presented at a Share Soc Investor meeting in Autumn 2017 and I invested at that point because not only were they a hedge play but there was huge potential to grow as they completed the "central shaft" project . As with other readers I was wary of the " jurisdiction " and came out in late 2018 when there was a regime change . In hindsight I was wrong and I re-entered a couple of months ago . Their cash generating potential now they have completed the "central shaft" from internally generated funds is potentially enormous . Like you I also found the Afritin Mining (LON:ATM): Afritin presentation fascinating as well and I bought an initial position this morning - not only do you have a mine producing tin ( you need tin for all that solder going into the Internet of Things ) but you get lithium and tanatalum for free. They regarded the latter two metals as waste !!!
Agreed. I too bought some Afritin today. Already had Caledonia Mining.
I've owned Caledonia Mining (LON:CMCL) since H2 2015. A great growth company (regardless of whether gold or not)...but got to accept that funky Zim risk obvs. The imminent completion and operationalisation of new central shaft (paid for purely thro operational cash flow...impressive...whilst paying a dividend) is a significant moment.
Going forward they are going to have massive excess cash-flow. This is good and a little problematic. Zim govt doesn't want dollars to flow out so can't assume there is a massive cash windfall. However, on the positive, Zim has masses of unused pristine gold deposits. Caledonia are a favoured operator and likely can get access to development of these on good price and terms. They may even become a necessary JV partner for any outside bigger operators coming in which may give Caledonia a tinge of almost a sort of gold royalty operation going forward in that they get assets developed for little cash and then receive a slice of operational cash too down the line.
Its risky but I believe the kosher Zim operator label they sport provides quite a degree of optionality to the upside going forward. Zim awkwardness is a risk...but also their moat
Hi mojomogoz,
I agree that Caledonia Mining (LON:CMCL) (I hold) are likely to get access to further developments with good prices and terms. Glenn Humme and Connemara North explorations are on-going and I expect this could be just the start. The company appears to have productive discussions with senior government ministers which seems a positive sign.
Sure, there's a risk that Zimbabwe could throw up some problems; however, my personal view is that there's lots to like about this company and the reward currently outweighs the risk. Let's see how things go :)
Cheers,
Yes. My comment was perhaps implicitly a bit too negative re dividends...I think they'll go up but there will be a quid quo pro with govt whereby they need to invest in Zim too.
However, lets imagine 2-3 yrs from now and they have a large and good resource to exploit...perhaps they speak to BigGold Co and say they can have 80% of it if they pay development costs and pay them a nice USD sum (outside of Zim) for the privilege ->
Monetisation through a different route. Obstacles to it of course as BigGold Co needs to believe they can get cash out of the country too...but then the govt needs external investment (which comes ahead of the cash out).
Caledonia Mining (LON:CMCL) is good value without any of the above. It has a chance at being phenomenal value
How to reclaim withholding tax on foreign dividends
https://the-international-inve...
Reclaim withholding tax on foreign dividends in an ISA or SIPP
https://the-international-inve...
Too much trouble for what I could claim, but may help some with more to claim.
Here are my SCVR heat maps for today (prices as at ~8:40am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Advanced Medical Solutions (LON:AMS) as expected but positive commentary.
I hold. This might be a decent entry point but that depends on performance returning to how things were going a couple of years ago. If they do, and as a bigger company now with more ranges, hopefully they will once again justify my holding.
I'm a patient, long term sort of chap.
Kape Technologies (LON:KAPE)
Great results today but market less impressed -reading through, due to a merger last year, it is difficult to really decide how good or bad they are. The number that grabbed me was that their number of subscribers has only gone up c20% but revenue has nearly doubled......
Thinking of taking my gains on this one unless anyone has views / thoughts about future performance?
Any chance of another look at Anpario, the animal feeds additives company?. Paul reviewed the company at the time of the January trading statement and the shares remain richly valued. Is its long promised growth story about to materialise at last?
Interesting comment from £SSP about the air and rail travel outlook for the year:
“New variants of the virus, vaccine supply constraints and various lockdown and travel restrictions mean that the pace of the recovery in 2021 has been delayed relative to the group’s expectations towards the end of 2020,”
Hi Paul, would appreciate a view on Dignity (LON:DTY) - in particular the fight that seems to be going on at board level between the incumbents and Phoenix.
Does anyone know if Gary Channon of Phoenix Asset Management has created value from boardroom coup’s before? My Google search has revealed nothing. I wonder if he is biting off more than he can chew on Dignity (LON:DTY) given the regulatory investigation of the sector that is underway?
they've got a great alpha track record...and have delved into taking over and running whole companies now and then e.g an online wedding present company and a stamp company which appear to have done well. Obvs DTY a different kettle of fish but I would back them as a rigorous intelligent team.
Phoenix took a 58% stake in Stanley Gibbons (LON:SGI) a few years ago; company was tied up in knots with huge overhead and a vast inventory of stamps, coins and other numismatic collectibles that only they were in a position to put a valuation on. Potential gold mine or value trap depending on your point of view together with a large prime West End freehold as I recall. Company is still listed and share price continues to be in the doldrums but there may be good stuff going on beneath the surface if you care to dig into it.
https://www.stockopedia.com/sh...
Just found the RNS (link above) detailing the terms of the Feb 2018 refinancing that Phoenix did. Take a look at the discussions thread too, in particular the Graham Neary SCVRs.
Gus.
Ferrexpo (LON:FXPO)
(Not for Paul but I think a lot of this community hold, including myself)
Very good results - with significant beat on EPS and another special dividend. Just wish the Swizz didn't get 35% of it.
Phil
Is there any way in which one can claim the withholding tax back off the Swiss Govt.?
surprised the shares are so muted on open. Is this really what the market expected?
It looks like it is possible to get tax back from a quick search. Form 86 seems the way to go.
You can get 20% of it back, but not if it is held in an ISA or a SIPP.
i think the first broker who took the bother to reclaim this tax for its clients may find increased business coming their way
yes good news especially about the special dividend. I hold and will continue to hold Ferrexpo (LON:FXPO) and Evraz (LON:EVR) but uncertain about the stuttering iron ore price at the moment. By my reckoning and limited understanding of the markets it should be rising...
I don't understand why they continue to be domiciled in Switzerland. It would be beneficial in my view if they redomiciled as this would lead to them trading on a higher multiple. Saving that I would prefer they do share buybacks rather than dividends.
Investor's Chronicle don't agree: https://www.investorschronicle... Good to get an alternative view but I will continue to hold. This will never be an expensive share given all the risks around governance, ownership, geography, iron prices etc but it just looks too cheap. I like it that they are handing out the cash because it at least that takes some of the risk off the table.
If you’re free at 1pm today and interested in emerging market real estate stocks please come to the Grit Real Estate Income (LON:GR1T) GRIT Real Estate Income Group webinar.
Register: here
The company recently released HY results which showed the recovery coming through yet the shares trade at a 40% discount to the 88p NAV/sh. Decide for yourself is this is unjustified.
Strix (LON:KETL) today announced a results webinar next week. The sentence "The online presentation is open to all existing and potential shareholders to ensure that all investors are treated fairly." is music to my ears.
Compare that to Tracsis (LON:TRCS) "This event is only available to institutional users" https://www.finncap.com/research-portal?#/portal/finncap/events/tracsis-plc-interim-results-conference-call-roadshow.
That's a shame, I had always thought of Tracsis (LON:TRCS) as one of the better, more engaging companies.
I got the notice of final results for Sourcebio International (LON:SBI) this morning. They are doing an analyst call at 13.30 on April 13th and then an InvestorMeet Company call open to all at 15.00.
So half marks there I guess but I don't know how they justify the earlier closed session for analysts? I think I know what my first question for them will be.
I think Tracsis (LON:TRCS) are doing a PI World presentation in April. You can register for it if interested
Tracsis (LON:TRCS) - thanks, Trident - yes, have found it on PI World. However, that is on Tues. 13th , five days after the institutions get their presentation on the actual day of the results. Their 3 trading day head-start makes a mockery of the statement in the last trading update that "The Board is committed to communicating with all investors equally".
My morning smallcap tweet: Get your tiny violins out for LPA
LPA (LON:LPA) Toople (LON:TOOP) Bytes Technology (LON:BYIT) Ricardo (LON:RCDO) OptiBiotix Health (LON:OPTI) Journeo (LON:JNEO) Deepverge (LON:DVRG) Kape Technologies (LON:KAPE) Supply@Me Capital (LON:SYME), Science in Sport (LON:SIS)
LPA (LPA) AGM stmt: "We have been victims of our own success in managing the business successfully through the UK lockdown." Some customers delaying orders by several months due to supply chain issues. C. £2.7m or sales delayed into next FY. [SP=86 Cap=11m]
Toople (TOOP) monthly orders and gross margin materially higher than pre-pandemic. Cash burn down 60%, trend is expected to be sustained. [SP=0.07 Cap=3m]
Bytes Technology (BYIT) guides FY(Feb) somewhat ahead of market expectations, with comfortably double-digit % gross profit growth and adjusted operating profit growth in the upper teens. [SP=414.2 Cap=992m]
Ricardo (RCDO) wins three-year, $89m contract to provide critical safety upgrades to US army. [SP=489 Cap=304m]
OptiBiotix Health (OPTI) a Commercial strategy update: co will "extending product lines and territories with existing partners, and grow profitability by moving up the value chain to sell more product than ingredients." [SP=51 Cap=45m]
Journeo (JNEO) wins orders totalling £1.1m. Also "The DfT announcement of 15 March 2021 of the first National bus strategy for England is a significant market driver". [SP=103 Cap=9m]
DeepVerge (DVRG) initial data for ongoing Phase III clinical studies on the detection of SARS-CoV-2 on breath samples shows Microtox BT can deliver results in under 60 seconds from breath samples. [SP=33.5 Cap=58m]
Kape Technologies (KAPE) FY(Dec) "strong revenue growth, with EBITDA ahead of expectations" but are in fact in line with Jan trading stmt. Guides this FY rev of expanded group $197-202m and adj EBITDA $73-76m. [SP=272 Cap=573m]
Supply @ME Capital (SYME) to buy a FinTech-powered commodities trade enabler, focused on SMEs, based in Singapore. "The acquisition will allow SYME's Platform to complete its global offering, by monetising inventory (in particular, commodities) "in-transit". Not least, it would generate a number of attractive synergy benefits for SYME from both a funding and customer origination perspective." No nae or price paid for this 'leading' company. [SP=0.48 Cap=160m]. I'm short.
In line: Science in Sport (LON:SIS)