Small Cap Value Report (Weds 18 Nov 2020) - BOTB, WYN, BEG, HFD, SDY, FCAP

Good morning, it's Paul here with the SCVR for Wednesday.
Agenda - today I’ll be covering;
Best Of The Best (LON:BOTB) - Trading update & update on FSP (formal sale process)
Wynnstay (LON:WYN) - positive trading update
Begbies Traynor (LON:BEG) - Trading update
Halfords (LON:HFD) - Interim results
Speedy Hire (LON:SDY) - Half year results
Finncap (LON:FCAP) - Interim results
.
Best Of The Best (LON:BOTB)
Share price: 1400p (pre market open)
No. shares: 9.38m
Market cap: £131.3m
(I hold - but only a small position)
Trading update & update on FSP
Best of the Best plc, (LSE: BOTB) the online organiser of weekly competitions to win cars and other lifestyle prizes is pleased to provide an update on trading for the interim six month period to 31 October 2020. The Company will announce the date for the release of its interim results shortly.
Trading update -
The Company is very pleased that trading for the period has remained as strong as previously announced on 16 September 2020 and that momentum remains within the business. The Group's online strategy has continued to gain traction.
Looking back to the 16 Sept 2020 AGM trading update, my notes are here. Even though BOTB said it was once again trading ahead of expectations, the broker forecast doesn’t seem to have moved. Therefore, I speculated whether c.100p per share EPS might be on the cards for this year, FY 04/2021. So it will be interesting if the house broker updates its forecast today or not, because it didn’t seem to update its forecast on 16 Sept.
Outlook - sounds good;
The early signs are that the second half of the year will be strong and the Board remains confident about the prospects for the business in the second half of the financial year.
There must be some extent to which BOTB benefits from lockdown, since some customers may have more disposable income available, given that we can't eat out, go on holiday, or go to the pub.
Update on formal sale process (FSP) - still ongoing, with several parties;
The Company, together with its advisers, remains in ongoing discussions with interested parties from a number of sector verticals and including private equity.
My opinion - the broker forecast of 69.8p is already lagging behind the positive Sept update. Today seems to be saying the same, but not a further upgrade. Therefore, I wonder if EPS this year might be heading for say 80-100p? That’s guesswork mind you.
The share price has drifted down to 1400p, so looks attractive on a PER of 14-17.5 (based on my estimate for earnings), which strikes me as very good value, considering how well the company is performing.
As regards the FSP, I’m not convinced management will want to work for private equity, so I think it would take a blockbuster bid to persuade them to recommend any such deal. As regards a takeover offer from another company in the gaming sector, that is possible, but with the market cap at £131m, a bid premium might take it to £200m, and at that level surely it would make more sense to simply replicate what BOTB has created, with a very large budget to do so?
So I’m not convinced a bid is likely to happen, but nobody knows except insiders. The fact that talks are ongoing, suggests there’s serious intent from buyers (and BOTB management).
Personally, I’d like to buy back into BOTB properly at some point, as I banked most of my profit earlier this year, to load up on other things where I see greater percentage & more immediate upside.
Overall though, today's update looks share price neutral, as nothing has changed with either trading, nor the FSP.
.

.
Wynnstay (LON:WYN)
Share price: 352.5p (up 14%, at 08:56)
No. shares: 20.05m
Market cap: £70.7m
Trading update & organisational change
The Board of Wynnstay, the agricultural supplies group, is pleased to provide the following update on trading for the financial year ended 31 October 2020.
Good news -
Overall trading since June, when the Group reported interim results, has been stronger than anticipated, especially in September and October. This is across both the Agriculture and Specialist Agricultural Merchanting Divisions. As a result, the Board now expects that underlying Group pre-tax profit* for FY 2020 will be significantly ahead of current market forecasts.
Outlook -
More generally, the Board believes that the outlook for agriculture and farm commodities in the UK remains positive despite uncertainties around Brexit and that the Group is well placed to take advantage of the opportunities that are expected to present themselves.
Restructuring charges (not quantified) will be incurred as 3 depots are closing.
A management restructuring is underway, full details will be given near the end of Jan 2021, with the full year accounts for FY 10/2020.
Valuation - note that broker forecasts had been reduced, so being “significantly ahead” is probably just recouping the previous shortfall.
EDIT - I've just seen a broker update today, with EPS forecast for FY 10/2020 raised by 21% to 33.5p. Therefore at 352.5p the now historic PER is 10.5
End of edit
,

.
As we’ve had confirmation of trading being ahead of expectations, then we should be able to rely on the forecasts (it’s difficult at the moment, as so many have been withdrawn). The valuation metrics are a sea of green;
.

.
Although the share price is up 14% today, that should be offset by increased broker forecasts, so these numbers should still be in the right ballpark (they’re updated daily, overnight, so you have to manually adjust them if a share price shoots up or down a lot intraday).
My opinion - it’s frustrating that the update doesn’t contain any numbers, and that there are not any broker notes available freely. The company needs to be more open, and engage with private investors a bit more, and provide us with the information we need. After all, we’re the people who create the liquidity & set the price, for small caps.
I can see the attraction of this share, for income investors. In a time of near-zero interest rates, probably forever, then I find reliable dividend paying shares very attractive, and a time could come when they re-rate, as people can’t find yield elsewhere. So a possible double benefit, providing income, and a future capital gain too, maybe?
WYN seems a solid, but boring, and ex-growth company. However, it’s forecast to pay out divis yielding about 4.6%, almost twice covered by earnings. That’s a decent proposition. Even if it pauses divis for now, they’re likely to resume, given that trading is ahead of expectations.
Worth a look, for income-seeking investors, in my opinion.
Stockopedia loves it, with a super-high StockRank.
.

.
Begbies Traynor (LON:BEG)
Share price: 89.5p (up 3%, at 10:42)
No. shares: 127.9m
Market cap: £114.5m
Begbies Traynor Group plc ("the group"), the business recovery, financial advisory and property services consultancy, announces an update on trading for the six months ended 31 October 2020.
Trading has been good -
The group is pleased to report a strong financial performance in the six months. Group revenue in the period grew by c.10%, with adjusted profit before tax growing by c.25%, having absorbed the downside impact of lockdown in the first few months of the financial year.
Liquidity looks good too. Bear in mind that insolvency practitioners typically have an extended receivables book, as they often get paid at the end of long-running jobs. So having net cash is very good. I wonder if any creditors were stretched, e.g. under VAT/PAYE deferred payment schemes? This should have been confirmed either way in today’s update, but wasn't. Bit of an oversight there.
The group has maintained its strong financial position with net cash at 31 October 2020 of £0.7m (30 April 2020: net debt of £2.8m, 31 October 2019: net debt of £2.3m) and significant levels of headroom within our committed bank facilities.
Full year guidance - reassuring, with some possible upside, by the sounds of this -
Overall, the board expects results for the full year to be at least in line with current market consensus*, which would represent a further year of growth….
* Market consensus for adjusted PBT of £9.8m (as compiled by the group)
Many thanks to the company & its advisers, for helpfully including a footnote as to what market consensus is. Why can’t all companies do this? It’s so simple, and helpful, a complete no-brainer.
Other points -
- Increased market share, and larger cases, has partially mitigated weakness in the market.
- Govt covid financial support schemes have led to a subdued insolvency market (a good thing for everyone else, if not Begbies!)
- First time contribution from prior year acquisitions (no figures given)
- Strong recovery in all parts of the business impacted by covid
- Property advisory division is trading well
My opinion - the decision to diversify into other advisory services, looks to have been a good one, smoothing out the peaks & troughs of the insolvency market.
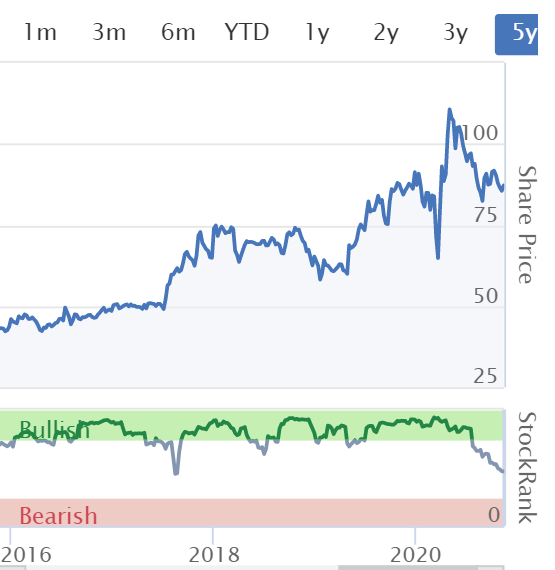
The current year looks to be on a forecast PER of 14.5, which doesn’t look demanding.
If you’re worried about the economy tanking in 2021, and lots of insolvencies emerging, then this share seems a good hedge. I like it, at this valuation.
.
.
Halfords (LON:HFD)
Share price: 250.5p (down 5%, at 13:00)
No. shares: 199.1m
Market cap: £498.7m
Halfords Group plc ("Halfords" or the "Group"), the UK's leading provider of Motoring and Cycling products and services, today announces its interim results for the 26 weeks to 2 October 2020 ("the period").
Here are my notes from 1 Oct, when Halfords considerably upgraded its profit before tax expectation for H1, to be “in excess of £55m”. With an uncertain outlook for H2.
Today’s actual profit before tax is only slightly higher, so I take that as effectively being in line with expectations;
A very strong H1, with Group revenue growth of +9.6% and profit before tax of £56.0m2. All product areas and businesses returned to growth towards the end of the first half.
This is 116% up on last year’s H1, so a superb result. The popularity of cycling seems the main driver, and with electric bikes & scooters also now growing, maybe this strong performance could continue? Less so over the winter of course, as this is seasonal business.
Current trading - some impact from lockdown 2, although stores remain open;
Trading for the first five weeks of H2, to 5 November 2020, continued to be relatively strong, with good growth and increased market share in cycling, alongside resilience in our motoring products and services businesses.
Since the 5th of November we have seen some impact on trading as the second national lockdown came into force. Cycling has continued to grow; we saw an immediate upturn in our Mobile Expert business; and we have seen another shift towards our digital and home delivery channels. However, sales of motoring products have been impacted, with Government data showing car traffic last week at 70% of pre-Covid-19 levels. Unlike the previous lockdown, we have been able to plan and mitigate against some of this risk early.
Outlook - due to uncertainty, no guidance is provided for H2.
Government support - many thanks to Shanklin100 and doublelutz for your interesting points in the comments section below. These two subscribers discuss the issue of Halfords reporting a huge increase in profits, with Govt support fuelling some of that. From the RNS;
Business rates relief and furlough income totalled £24.5m, but these benefits were partially offset by increased costs of operating under Covid-19 which, to date, amount to £11.4m in our retail business. This includes PPE, additional store payroll, digital fulfilment costs and over £2.4m of initiatives launched to support colleagues including a Frontline Colleague Support Fund and the Here to Help Fund.
Should Halfords return some or all of the furlough monies, at least? Some companies have done so already. Is it right for companies to take Govt money, after it transpires they didn’t need it? Maybe the furlough scheme should have had a clawback provision, or would companies have then just made everyone redundant instead? All good discussion points.
When the business rates suspension comes up for ending or renewal, or adjustment, at end March 2021, I feel that the Govt should refine eligibility. For example, it’s crazy that supermarkets in particular, and DIY retailers, that have done a roaring trade in 2020, should have received hundreds of millions in taxpayer subsidies (esp. business rates) during a period that has been buoyant for them. Let’s hope taxpayer support is provided where it’s needed in future, intelligently targeted.
Balance sheet - quite weak. NAV: £408.4m, but worthless intangibles are £393.4m, so NTAV is only £15.0m - next to nothing, for such a big business.
There are large lease commitments, which could make it difficult to exit from loss-making sites possibly.
Cashflow statement - note that inventories are down £27m in the 6 months, due to very strong sales in October, but trade & other payables are up £79.3m - when they should be down! This seems clear evidence of creditor stretch (VAT, and payroll taxes), but I did a search for “VAT” and it is not mentioned in the RNS at all.
For this reason, I suspect the company may have gained considerable cashflow benefit, on a temporary basis, from stretching creditors, but doesn’t seem to have disclosed this. Although I haven’t read through all the text, so please point out if I’ve missed details of this.
For these reasons, I think we have to treat the £109.6m cash pile as being an aberration, boosted by short term factors, rather than a long-term position.
My opinion - I can see why people may think the cycling boom could continue. Electric bikes in particular look interesting, as they’re much easier to use if you don’t want to arrive at your destination drenched in sweat, and a great way for older & less fit people to get out and do some gentle exercise. I used to enjoy riding electric hire bikes in London, but haven’t really felt like doing any exercise this year, so must remedy that.
There’s no interim dividend, which is good as it would have been distasteful if HFD had paid shareholders, after receiving generous taxpayer support. Its weak balance sheet means that paying divis would be foolish anyway. The strategy should be to build up its balance sheet strength, so that it can cope if cycling demand ebbs away. After all, once you’ve bought a bike, you don’t need another one for a long time, although accessories and repairs might continue to provide revenue for Halfords. Internet competition concerns me too.
For me, the price looks high enough, so it doesn't appeal, when there are so many other interesting recovery shares shooting up almost indiscriminately, why park our money in this?
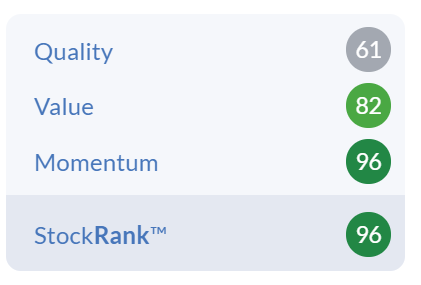
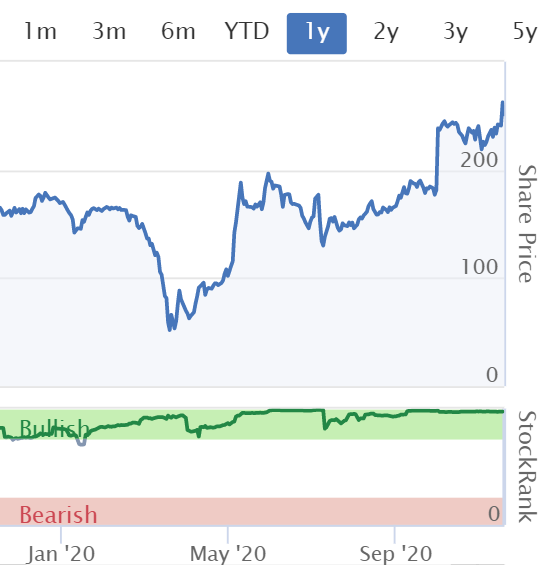
Stockopedia disagrees, with a very high StockRank.
.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

100 comments
I remember when Paul Scott said that Best Of The Best (LON:BOTB) was a hold forever Stock, looking at £40 to £50 a share. Then he sells most of his stock & wants in cheaper???
Best Of The Best (LON:BOTB) - I will regulate my tick up. A valid point but there are no 'recommendations' and as they say DYOR so no flak on anyone. I would just like to understand the process this annoying share has been in for a long time now. As a newbie it's hopefully a learning curve - but sometimes like 'learning to swim in the shark pool'.
Saga (LON:SAGA) Could this have been the culprit behind the meteoric rise today ? - hTTps://www.bbc.co.uk/news/health-54986208#:~:text=The%20coronavirus%20vaccine%20developed%20by,all%20ages%2C%20races%20and%20ethnicities
Then again Carnival (LON:CCL) down 0.75%. So perhaps not the explanation for Saga (LON:SAGA) 's rise.
Newbie here. Carnival CCL $23 on a 'teacup' to $27 with $5 upside be compared to Saga (LON:SAGA) £3 upside - so seems a good correlation (as I will lose $2 in FX etc or more).
Looking for the US blog or dare I say China - would like to invest in Company No. 65483 - sounds enticing (sorry - just scrambled some numbers).
Fully agree, ESG does represent the current direction of travel, see eg https://www.professionalpensio... or
https://www.investmentweek.co....
But (sorry for the tobacco analogy) it's been a very slow burn. It's almost 30 years since I sat through a presentation on the concept by an earnest young lady from Jupiter (Bonham Carter??) with a reactionary old phart like me thinking she was from Mars! But now I think you'll be hard pressed to find a decent occupational DC fund that doesn't include any ESG options.
Interestingly, China is keen to paint its ESG credentials to the mast https://www.ey.com/en_cn/china...
Another trend on the horizon is the concept of firms acting in the interests of all 'stakeholders' as opposed to shareholders (ie considering employees, customers etc). Radical for some, but there is an underlying logic. Funny how trends like this can rumble along in the background for ages then suddenly break out and gain real traction. Next decade should be fascinating.
Looks like you have slightly more influence than me !! £volex up 18% £Luceco down 5% - ten nil to you !!!!
Thanks Paul for the Halfords (LON:HFD) write up, I rode the price up from below a pound, figuring folk would be buying bicycles but a month ago sold and switched to buses! So it’s worked out very nicely. It might be worth revisiting the share in spring, also when the motor car gets used again, and people are feeling the pinch so self repairing. Electric bikes and scooters will be back then too.
I value your analysis of the books, my weakness, and your experience of reading what’s not their as much as what’s their.
As you say there is so much out there still that looks like good value, it feels like a once in a life time opportunity to get the pension of tomorrow squared up to having great dividends, particularly for those of us late to the task.
Halfords (LON:HFD) From the Times yesterday
The price of electric bikes could be cut by up to a third under
government plans to offer commuters a “sweat-free” alternative to
conventional bicycles.
Ministers will launch a taxpayer-backed scheme to boost the number of
people using battery-assisted bikes, appealing directly to commuters
riding in business outfits and those who are older or less fit.
Trials of the programme will begin in the next five months before
details of a full-scale support package are unveiled in spring next
year.
Although the details are yet to be finalised, The Times has learnt that
the government favours a system of direct subsidies similar to grants
for plug-in cars, motorbikes, vans, taxis and trucks. They are worth a
maximum of 20 to 35 per cent off the purchase cost depending on the type
of vehicle.
One Whitehall source said it was “wrong that the only electric vehicles
we don’t provide any taxpayer support for is a bike”.......
Let’s face it the government has gone completely bonkers.
Mostly used on pavements which I thought was illegal - but hey ho - until plod have them the no worries.
Been a Begbies Traynor (LON:BEG) holder for some time. The fact that the fundamentals are improving even with so many businesses being kept afloat by the government is incredibly encouraging to me. Plan on holding for quite some time longer.
Today's update on Begbies Traynor (LON:BEG) is good, but there is one glaring omission.
Paul sort of picked it up with his comment: "First time contribution from prior year acquisitions (no figures given)"
The glaring omission of how the business is performing like-for-like, excluding acquisitions from the prior year, is worrying. They could have said something like positive like-for-like revenue, or positive organic growth in revenue. But they didn't say either in the trading update, so there's a red-ish flag for me about their growth prospects going forwards.
Based on that, paying about 12-14x current year PE seems a bit of a stretch.
Even if company insolvencies pick up in Jan-June 2021, the revenues from that will probably only feed in a few months later. So H2 results I would say have limited scope for earnings beat.
OT apologies
Whats the odds - the vaccine news just keeps getting better and better - if i didn't know the drug companies were scrupulously honest (sarcasm intended) , i may think there was some one-upmanship at play here.
It starts with interim Pfizer numbers showing vaccine success rate of 90%
next day the Russinas announce 92% success rate for their version
Then Moderna announce 94.5% for their itermin numbers.
and today we have Pfizer announcing trial complete (was only a matter of days with current covid cases in circulation) with the final number being 95%
Honest guys there is no one-upmanship going on here they will say :)
I think we still have Glaxo and Astra to come - i doubt they will try and trump those numbers though.
Speaking of Trump - the rumours are (started by me) that has he has a ceo position lined up starting february in a drug company currently running trials where they anticipate 110% success rate - they are just waiting for trump to be formally announced in the post to ensure the good news will well received with his name behind the 110% numbers.
Or we could be celebrating the enormous efforts and innovation that these companies have brought, supported by US government money. In rather stark contrast to the frankly incredible stories here of the ‘chumocracy’ helping themselves to hundreds of millions for the procurement of PPE, a lot of which was unusable and is currently clogging up the Port of Felixstowe.
If the rumours are true, terrible state of affairs in the UK..... :(
Test and Trace a billion (telephone numbers) and what is HS2 all about (why would I want to go to Birmingham when could zoom/MST or possibly (sold today) Loopy.
Rumours are he's going to drop the MOAB on the Pharma industry.
Here are my heat maps for today (prices as at 11:30am).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR filtered to 'interesting' instruments (reporting soon or recently, trending, breaking out, or moving more than the 20d EMA of ATR):
Big movers today (moving more than 20d ATR EMA against either yesterdays close, or today's open - not limited to small caps):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 80 instruments.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many as part of my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria ('T': profitable, low-debt, reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the individual instruments further using the Stockopedia Stock Report.
How (or indeed if) you use the heatmaps is up to you, I contribute them here in the hope that others may also find them interesting or useful.
greensiax
PS: If any of these are not useful, or if you have any suggestions of more useful heat maps, please feel free to let me know (obviously I can't promise anything, but if I can I will).
Hi Paul
Thanks for the SCVR today. Yesterday I asked about standard spread bet prices offered on online platforms in comparison to the tighter spreads when dealing within a share trading account. Thanks for the tip that tighter spread can be offered by calling the spread betting dealing line. IG are telling me they charge a fee for telephone dealing. Is that the case in your experience?
BW
MPR
Hi maillot,
I've never paid a telephone dealing fee for spread bets with IG, but don't know what they charge for a normal share dealing account. Most online brokers do charge a telephone dealing fee for a standard share dealing account. But I was only talking about spread betting where they don't charge for telephone dealing, as far as I am aware.
Regards, Paul.
Thanks for the reply Paul. I was referring to spread betting - probably didnt make it clear. After some initial confusion as the ‘help centre’ staff thought I was referring to share dealing they put me through to an IG dealer who suggested they could only improve the bid-offer spread on the prices quoted on the spread bet app for large trades (>£100k).
Ah OK, I'm surprised at that. Spreadex are usually happy to improve prices on spread bet accounts. Although I think generally they do this is you're dealing in reasonable size (but not £100k!) and/or frequently. Worth having a chat with Spreadex, I've found they're very good for small caps. But watch that gearing! Safest not to use any gearing.
P.
Is you account a professional one? I know IG like to look after their bigger hitters.
Hi Paul. Just doing the research on companies who can benefit from the shift to renewables and green energy. Like yourself, engineering is not my field but the opportunities are starting to take off. The one that's off the radar at the moment is £pres Stockopaedia stats are cautious and you last commented on Pressure Tech in Sept where you decided it was too erratic to continue to comment on. In the light of events regarding the desired speed of shift to green energy I think it may deserve reappraisal. Its exposure to the high pressure cylinder market is high as its its revalidation team (pretty much grounded during lockdown but vital to operational safety in multiple high risk arenas). It has already stated that it will make a loss this year and is going to write down £14m goodwill and intangibles. The MCap is currently only £11m but the book value of assets including intangibles is £31m. That allows an awful lot of room for any loss this year and the outlook seems to be shifting in the companies favour.
Hi Adastra,
Thanks for the idea, but Pressure Technologies (LON:PRES) strikes me as a bit too high risk, and illiquid. I've already got quite a lot of illiquid things, so am trying to move up the food chain a bit. There might be something bigger/safer, if you want exposure to green energy/renewables. It's not a sector I know much about, so haven't got any stock ideas there I'm afraid.
Regards, Paul.
Hello Adastra
As someone who closed a renewables company in 1991 to ensure his family could still eat, I would be wary of any small company with new technology or those pivoting from oil and gas. The recent CEO summary was
"A focus on decarbonisation by governments worldwide is establishing hydrogen firmly in the global energy mix and I expect to see this sector become an increasingly significant part of the Group's business over the next few years.
Depressed oil and gas markets and slower than expected turnaround of operational performance have impacted the PMC division and the outlook remains uncertain. Management actions are focused on maintaining customer service levels and completing operational improvements, while preserving cash and protecting the capabilities built over the past two years."
Will hydrogen be a big enough market before they collapse from lack of orders from the O&G sector? As an investor, it's a punt, not an investment. Having been luck enough to be able to 'retire' from manufacturing I thought of re-starting in the renewbales industry with an idea I have. Having established it would take about £5m to prove it and that worldwide heavweights are throwing £bns in at a rate of knots, I've put it on ice: it is too hard to predict winners.
This is where, if you can face it, Investment Trusts come in. People like Bluefield Solar Income Fund (LON:BSIF) have a lot of experience now in known solutions and are growing all the time. You'll not get any serious capital gain, but a reliable yield of 6%+.
And I have just increased my stake Gresham House Energy Storage Fund (LON:GRID) in the subscription offer for a yield of 6.75%. They are the first and likely to continue the biggest publicly quoted British investor in USS, Utility Scale Storage. Basically at the moment, socking great batteries with fantastically responsive electronics that can stabilise as well as feed the grid. This did not get a mention today as far as I know. But responsive storage is what unlocks wind and sun power worldwide and is why there needn't be a problem feeding an electric transport system.
I hope this helps.
Afternoon JTG - Excellent and intelligent reply to Adastra (I have green thumbed it)
However as its wobbly Wednesday my concentration is wandering and I have had my Eureka moment
Surely all Boris needs to do is to promote science to crack Water into the Hydrogen you refer to and as a by product we get Oxygen to breath!
Oh and the Midas touch is we reduce the rising sea levels
- I'll get my (waterproof) coat
Surely all Boris needs to do is to promote science to crack Water into the Hydrogen you refer to and as a by product we get Oxygen to breath!
ITM Power (LON:ITM) already doing that ezlifeme but yes, it would be good if Boris & Co promoted that more (green transport doesn't all need to be down to EV).
A bit more reading for those interested in producing hydrogen from water (already being done) - recently published government plans for "Green Revolution" - see Page 11 for specific reference to ITM Power (LON:ITM)
https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/936567/10_POINT_PLAN_BOOKLET.pdf
Re Begbies Traynor (LON:BEG), Paul wrote:
"Bear in mind that insolvency practitioners typically have an extended receivables book, as they often get paid at the end of long-running jobs."
Personal anecdote. On Monday I received a cheque from the administrators of DealGroupMedia, who went into administration in 2010(!). So long-running may be understating the time-scale.
Jon
PS 13p in the £, which is more than I was expecting, and made the endless form-filling worthwhile.
Best Of The Best (LON:BOTB) Paul says ".... it will be interesting if the house broker updates its forecast today or not, because it didn’t seem to update its forecast on 16 Sept".
The house broker is finnCap and issued its 69.8p eps forecast on 15/6, two days before the FSP was declared. finnCap now has the status of "Offeree concert party member" and I am wondering whether that precludes it from making public forecasts.
Great point, that sounds sensible, that FinnCap might be precluded from updating forecasts. Unless "Chinese Walls" might enable it to get around that issue? Maybe anyone with a City background could clarify this point?
Thanks, Paul.
Hi Paul
Re Best Of The Best (LON:BOTB) - not sure if they are precluded from updating their forecasts during a FSP but it seems as if they have refrained from doing so on another identical occasion recently. Redcentric (LON:RCN) initiated a FSP on 2/9/20. They issued a TU on 15/10/20 and ended their FSP on 12/11/20. FinnCap did not issue a morning note for Redcentric (LON:RCN) TU on 15/10/20 in the same way that they haven't done so today for Best Of The Best (LON:BOTB) .
I'm a little bit sad that I missed the Boohoo (LON:BOO) discussion yesterday, especially after I posted I bought it at 250p here a while ago, and took so much slack for it; for being a gruesome unethical investor by the seemingly Guardian reader brigade (obviously now all turned out to be media 'fluff' - shall we put it).
I fully acknowledge the need to account for sentiment of investors as well as consumers on these matters but it is important when investing to not project our own opinion on the opinion of the consumers of that company, and be objective to the business.
Speaking of (un)ethical investing and my extra 5p worth:
I can't help but think oil companies are very oversold - still around half pre-covid levels (I own one which I bought two weeks ago before the rebound). The govt and the energy industry is putting billions into carbon capture (New Green plan) so oil use is not going away any time soon. China has reached a record high in oil use recently and Shell and BP said oil demand is back within 7% of pre-covid levels in the month of October.
There is of course a slow drag of electrification but only 5% of new cars sold in the UK in 2020 were electric (70+% petrol and diesel) and it is much lower in the developing world, so I think the pace of change-over is exaggerated and I see people waiting right up until the second half of 2020s to really change over to electric cars, (purely because many will not pay £40k for a new electric car and the £25-30k ones are rubbish compared to what you can get in the petrol variety) which could present many upward revisions of oil use over the next decade because projected expectations are pretty low at the moment...
I know, how unethical of me.
I'm a little bit sad that I missed the Boohoo (LON:BOO) discussion yesterday, especially after I posted I bought it at 250p here a while ago, and took so much slack for it; for being a gruesome unethical investor by the seemingly Guardian reader brigade (obviously now all turned out to be media 'fluff' - shall we put it).
The ESG thing is interesting on the whole - in July 50% of all global fund inflows went into ESG marketed funds: https://www.internationalinves...
ESG funds are exploding in popularity. Each of the last four months has set a new record for inflows. Moreover, the total £1.2bn that has flowed into ESG funds since April is greater than all the previous five years combined across the entire FFI on record.
Frankly, Guardian readers won't make much of a real difference to share prices unless regulators get interested, but if all those damned millennials stick their inheritence monies into ESG funds it will matter. Of course, it may just be fashion ...
timarr
Ethical investing is a great virtue signalling buzzword to attract investors but I wasn't arguing ESG wasn't a new investor trend, I was simply arguing, perceived ethical investing isn't always correct and it also doesn't negate the need for certain things. e.g. oil and clothing.
The world will grind to halt without oil (Used for all building, infrastructure, resources and most transport, heating and energy in the world) and we are a long way from that ever not being the case.
I will likely buy an electric car in the future because I do think climate change needs to be tackled but it doesn't make sense to now because there still isn't any good options, and carbon capture looks the more likely route to carbon neutral than anything else for much of the world at this stage.
Removing my own view of what I would like for climate change, I don't see how oil will go away for a very long time and I don't see how Boohoo (LON:BOO) supplier issues raised were anything but overplayed spin; partly because the right side of the media see the Khamani family as flashy like the Kardasians and partly because the left of the media wants to stamp out anything which isn't Tesla electric cars and vegan meat.
Ethical investing is a great virtue signalling buzzword to attract investors but I wasn't arguing ESG wasn't a new investor trend, I was simply arguing, perceived ethical investing isn't always correct and it also doesn't negate the need for certain things. e.g. oil and clothing.
I largely agree - although I think labelling it as "virtue signalling" potentially diminishes the importance of the ESG trend by making it sound like a fringe behaviour. Presumably most people here are Boomers and our attitude to investing is different from millennials who figure they're going to have to live with whatever we leave behind. Utimately allocation of capital will drive returns, regardless of whether its done for ethical reasons or otherwise.
As I posted earlier on yesterday's SCVR - a study earlier this year indicated that millenials are far more concerned about ESG issues than people of my generation. That group is in process of receiving the largest inter-generational wealth transfer in history, so we should be careful about dismissing this as a fad:
https://www.triplepundit.com/s...
On oil you're probably right, but I think we are at the beginning of the end. It'll take longer than anyone expects.
As for the Boohoo (LON:BOO) issues - I never really understand why people get worked up about this kind of media reporting. If you think they're wrong then back your judgement and buy more. Only day traders should care and they're all going to go broke anyway :-)
timarr
As for the Boohoo (LON:BOO) issues - I never really understand why people get worked up about this kind of media reporting. If you think they're wrong then back your judgement and buy more.
See below: people are fundamentally good in my experience, and it pains them to think that the stock that will likely make them money is based off the back of pittance wages earned in defiance of a lockdown that likely caused a COVID outbreak in Leicester. How to square the circle?
It's all a lefty media agenda driven by virtue signalling.
Problem solved- the nagging voice in the back of our heads can be shushed and profits eagerly anticipated.
I am a millennial (1981-96) and recognise their is a clear man-made issue with regards to climate change but I'm not stupid and the idea of oil going away anytime soon is just fantasy.
The wider point about ethics is not really for here but I'm sure some would argue the ethical case of the world grinding to halt if draconian measures were taken to stop its use because a better alternative was available (hence my virtue signalling label but also because asset managers love to market these so called products as if they add value). That doesn't seem like it will be a very long time if you look outside of Europe - and even in Europe, the weaning off oil is not as fast as people think, as I described above.
there* typo. An edit function on the app would be useful...
Felt I had to respond & give an uptick - as someone had given a downtick for "Thornabian" simply giving a view. Not great behaviour.
I get a bit weary of investors long in oil, tobacco, and fast fashion describing ESG as 'virtue signalling'. It's never anything other than a dismissive gambit, a way for those looking to make money in things with a bit of a whiff about them feel better about themselves. 'Those ESG funds aren't REALLY concerned about the methane bubbling out of the arctic sea bed, it's just virtue signalling.' etc. and so on.
I get it, no-one likes to think they are the bad guy, but maybe, just maybe, some (other) people do genuinely not want to invest in fossil fuels, tobacco, et al. The implication is that they do care more about public health or the future generation's ability to grow crops than you do, in which case own it, rather than chalk it up to the unprovable spectre of 'virtue signalling'.
I think the point is, it doesnt matter what your opinion of it is, or my opinion that it is virtue signalling for that matter, rather, people need oil, so they will buy oil.
Simple.
You won't get very far investing if you can't separate emotion from fact.
I do find it very funny that people also said the same thing when I last posted Boohoo (LON:BOO) was a buy at 250p (cause covid spike, low wage blah blah) and it is now over 300p in a short space of time.
And even though it has been proven to be nonsense, people are still trying to say I am being dismissive.
Funny that.
The regulators have got interested and are bringing in increasing requirements for reporting on ESG areas. I went to a meeting at one of the big consultants last year where they explored what forms of this reporting were helpful to consumers. Will try and dig out my notes on it
The regulators have got interested and are bringing in increasing requirements for reporting on ESG areas. I went to a meeting at one of the big consultants last year where they explored what forms of this reporting were helpful to consumers. Will try and dig out my notes on it
Yes please. The IFRS foundation are working on standards to sit alongside global accounting rules. I'm not sure whether that will translate across into a financial impact, but I'd guess that's the direction of travel.
timarrLast time I went to an ACCA conference they said the same but I don't think shareholders really pay that much attention to the 200 pages of CSR to be honest, let's face it, most care about pounds and pence and ROI.
I think that 5% of cars being electric is an overstatement. Does that not include hybrids, which are basically internal combustion with a green fig leaf?
"I think that 5% of cars being electric is an overstatement. Does that not include hybrids, which are basically internal combustion with a green fig leaf?"
Regardless of where you sit on the spectrum regarding green issues, that statement is not really accurate for the majority of current hybrids. It fits a few which are basically an almost unmodified 4x4 with a small battery to dodge the congestion charge, but the majority of hybrids, and the hybrid concept generally, is so much better than that, particularly in this country (no long Alpine ascents).
The standard ICE basically has to be sized for peak power demand, generally acceleration. This power demand is vastly higher than that used in almost all normal driving under normal traffic conditions. But the oversized engine has to be run in all traffic conditions, using far more fuel than required which you are paying for at the pump. Some mitigation is possible - autostop at lights is now common, and a few engines can selectively disable a piston(s), but that is complex and rare.
A well designed hybrid though, even non-plugin, can do much better than this. The engine can be sized for much lower demand, and the battery can supply the extra when peak demand is required transiently, and then be topped up by the engine as required. Because the engine is smaller less fuel is used, and because transients are less harsh (the battery handles them instead of the engine) less harmful tailpipe pollutants are emitted. In addition, a small petrol engine is typically used instead of a larger diesel engine in the non-hybrid alternative, resulting in less harmful tailpipe emissions since the petrol engine running stoichiometric with a three-way catalyst cleans up so much better than a diesel. And finally, battery life in a non-plugin hybrid is generally excellent, since the charging limits and profile are under the control of the ECU, and hence can be controlled far better by the engineering designers than a plugin hybrid or pure electric vehicle can be.
There's a good reason why diesel Passats and Octavias are much more rarely seen these days as private hire and Uber cars, replaced instead by Toyota Priuses, and it's not because of fig-leafing. They're simply more economical to run, even without subsidy.
Where this falls down of course is when peak demand is required for sustained periods of time beyond the battery capability, such as towing, or long Alpine ascents. Then the hybrid can be underpowered. That's unlikely to be an issue for most in the UK.
I'll stop now, and try to stick to shares in future!
What happens in 5-7 years when the battery no longer charges - like the little AA's in my torch. Buy shares in car crushers. My 6yr old Audi good for 250k but worthless come next November (in London) - makes a mockery of recycling a plastic bottle. The direction is great - the execution is politics.
Saga (LON:SAGA) is on a tear today. Has there been any updates? I was dithering at 215p yesterday. Typical :-)
It has been doing that for the last 10 days. I keep on thinking it will reverse more noticeably on the down days, but it hasn't. Luckily I am on the other-side and own some
Saga (LON:SAGA) I suspect is going up because the Pfizer vaccine has just shown it is 94% effective in adults over 65 years old. This is a key piece of the puzzle because it potentially means you can open up all cruises/travel etc if you have an effective vaccine for the most vulnerable population.
I am long from 130p but I plan on being that way for a long time unless the story changes. Markets will always climb the wall of worry, so the fact the odds are increasing of an early opening for cruises based on vaccine data will be starting to get priced in.
I have positions at 130p and 160p but was contemplating an entry around the 200-210p mark. Last week, as the week faded as did the price so interested to see if it balances out towards the end of the week.....
Saga (LON:SAGA) has been on a remarkable streak. Today, I had expected the SP to dampen.(drawing a comparison to Carnival stock). However, it has run away. The sellers that Paul mentioned about previously that were lurking last week have not shown their faces in the past 3 days or have sold out their positions.
Saga (LON:SAGA) my timing is brilliant I dare say. Having profited the past 2 days (trading in and out), on Tues evening I bought in at 215p nearing closing time. Being the guru that I am, I sold out at 225p in anticipation that the SP could not longer rise given its projectory over the past 3-4 days and that I could buy back again at a lower price. If only my walls were clad with foam, when throughout the afternoon, to my horror, there was little to no retracement. Now I know what it means when people say "don't time the market". :)
maxistaxis - I think we all have at least one story like that to be told. So my advice is don't beat yourself up too much about it.
On another site I wrote a couple of weeks ago that it in my view it was not yet the time to buy hospitality shares - just Pfizer/BioNTech announced their vaccine results.
I doubled down and wrote later that I thought the market had over-reacted (in the specific context of pubs & restaurants) and Moderna announced their results!
One just has to take these things on the chin and reflect on whether you were wrong or just unlucky. If the former learn from it, if the latter shrug shoulders and move on.
FWIW I still stand by my call on Pubs & Restaurants, whilst I do get that the market is (supposed to be) forward looking; I do not think the market has adequately priced in how awful things may be for this sector before we get some vaccine relief in the spring. In fact it seems to me there is a very real chance that the government bungles another start-stop-start and really damages hospitality before we get to spring.
On the other hand (not wishing to seem smart) I think the holiday/cruise sector is largely banking on some semblance of normality from the spring - which imv is looking increasingly possible.
Thanks Gromley for the encouragement. Overall, it was a probably a good day for my portfolio, albeit it would have been a super duper day had I kept £SAGA. Could have bought my future cruise tickets for me and missus with the forgone profits!
"on a tear"?! This is a British website - we speak English. ;-)
My apologies :-) I shall not make reference to your username at all.... ;-)
I suggest reporting him to the English Academy for violating the rules of the language. Ah, that's right, we don't have one. That's not how English works.
Im not an investor in Saga (LON:SAGA) but have become interested with all the comments. I have spent some time looking at the annual accounts and concluded that its like a conglomerate and that insurance not cruises is the base business. Because they consolidate the insurance, cruise and travel agency businesses into one balance sheet this becomes difficult to unravel - the insurance business is highly regulated, will be in a separate regulated subsidiary and will have to hold a certain percentage of liquid assets to meet claims. I tried going to Companies House to find the accounts of the subsidiaries - there are many - and couldn't find the insurance one. I did find Saga Cruises which made a PBT of £4m on sales of £100m in 2019 - though it made a bigger loss on a cash flow hedge.
in terms of valuation I think you have to do it on a Sum of the Parts - there is some crosss selling but not enough to think of it as a single business. For example the £90m PBT of insurance might be compared to say Direct Line (PE of 10) or Admiral (PE of 20). Then you have to value the cruises and travel and a large amount of 'central' costs - £27m. I wouldn't know how to value the cruise and travel businesses at this time. But possibly the value of the insurance less the central costs is roughly equal to the EV. So I guess you're getting the trace business for nothing.
Sorry meant travel not trace!
As far as I am aware, SAGAs insurance business is Acromas and might be registered in Gibraltar. This might explain why it’s difficult to find.
SAGA will also act as a broker for other companies – so trying to determine the figures for the insurance business could be a challenge.
From personal experience, SAGA is fairly expensive if you just accept the renewal quotation at face value. It’s worth bargaining renewals.
The UK insurance business will be in a UK subsidiary. I did find Acromas on Companies House but all companies with that name had been dissolved in 2016. As I said it was at that point i gave up. Good luck to those who invest in it but I decided it was not for me.
Why would it necessarily be in a UK subsidiary? It could be anywhere in the EU. Gibraltar, as someone mentioned, is most likely, as it has a favourable tax regime and is English-speaking. A good proportion of UK motor business is insured in Gibraltar.
When the boat sets sail - whoop whoop.
Micro Focus International (LON:MCRO) trading update today looks encouraging....unless posters here or Paul IF he gets the time think otherwise.
Share was up 77p to 347p just now, but that’s after the share fell to a multi year low of 214p just over a week ago, and the share price is still down over 80% from the price at the start of the year.
MICROFOCUS share price crashed after their disastrous Hewlett Packard software buy in 2017. But is the worst now behind them and their long suffering shareholders?
Update today included EBIDTA margin of 39% which is upper end of expectations.
Debt is high at $4.2 billion but they have $1.1 billion available liquidity and next maturity not until 2024.
“Strong cash generation,” and “working capital management strong,” sounds OK.
4% improvement and uptrend for licensing revenue.
No commitment to paying a dividend. They’ll update on that with results, but surely better to use that cash to pay down debt?
They are 9 months in to their 3 year turnaround programme, and seem quite upbeat on progress.
MICROFOCUS looks a classic turnaround share and with chance that it might attract a bid.
OR are there still big negatives?
I’ve held for a while and was losing until today,
MCRO- Microfocus, I too was making a largish loss having purchased at ave price of 295p , but had faith - likewise loss has reverted to nice profit. Will continue to hold to at least 400 an then top slice some profits
Re £BOB
I can’t believe that management would have engaged in giving more info to potential competitors without some sighting shot of an offer price or deal structure. Confidentiality agreements would have been signed before giving further info so a competitor has to think whether they will risk setting up a similar operation depending on confidentiality terms
Knowing PE they love lots of analysis. So a data room would need to be set up and they will spend a small fortune on lawyers and on reviewing the financial data. This can be very time consuming and will be a bit of a strain on management.
The PE guys will have to satisfy their investment committee before an offer is formalised.
it could be under a PE deal structure that some of the upside is plugged into the future PE vehicle and growth etc, for management going forward which will not fully benefit existing Shareholders if a sale goes through.
So be wary of a full value being paid by a PE acquirer.
Dealing with more than one interested party is a good omen for a decent outcome but will create extra demands on management time, and it’s surprising how it can all evaporate quite quickly if they don’t like what they see under the bonnet,
Paul,
I've read you have dropped or reduced your Sosandar (LON:SOS) shareholder but I am sure you still follow them. From their RNS today announcing H1 results out on 1 Dec 2020.
"Following the results Sosandar will be hosting webinars for analysts and retail investors on 1 December at 9am and 12pm respectively. If you would like to register, please contact: sosandar@almapr.co.uk"
Why - o - why do analysts need to be given a 3 hour headstart over private investors? I know that no new info should be released in the webinar vs the 7am results announcement but the reason analysts go and we want to follow is because questions are asked and management tone/ expertise is on display. This has value.
Last year I remotely watched my son play a softball match abroad via 1 iphone lashed to a pole. It was fine. The technology is no longer even remotely difficult. It is the attitude and practice that needs to change. As a shareholder, I have written to the PR company address (given in RNS except above) to complain about being a second class shareholder.
Can you suggest why this needs to occur. If you cannot, please write or comment as well. I will be registering to ask this question but I am sure a quote from you will carry more weight (and I expect my question will be headed off before the webinar).
I recognise it is perhaps unfair to pick on Sosandar who have been more PI friendly than most. So many companies still ONLY have analysts to 1-on-1 presentations on results which has, to my simple mind, be insider trading and an injustice - even if the law does not agree.
But the explicit 3 hour difference is such an explicit kick in the teeth that I am annoyed into action!
Perhaps it was the casual use of respectively when "respect" is clearly not something I am getting.
A (second class) Sosandar shareholder
Hi Zipmanpeter,
As stated previously, my recent portfolio update was just my top 10 largest positions. Sosandar is not in my top 10 any more, but I still hold and like the company & management.
None of this is new, I've been saying for most of this year in the SCVRs that I'm not as keen on SOS as I originally was, because it's taking longer, and needing more cash than originally planned. Hence less upside potential for the shares than originally, since there are almost twice as many shares in issue now.
You make a good point, that it would be nice if PIs could view the analyst meeting, in listen only mode maybe? I'll suggest that to them. Although I do think SOS deserve praise for being shareholder friendly, and holding a presentation for us too. Does 3 hours really matter? They don't give out anything price sensitive in the meetings, it's all in the RNS, which we have equal access to at 7am. So I think you're a little more angry than is perhaps justified?! ;-)
Best wishes, Paul.
Blood pressure perhaps dropping as my early morning coffee metabolises (and I did say say I was probably unfair to pick on Sosandar, it is a widespread issue). Probably a bad conjunction that I had just read reporting on the National Audit Office findings on PPE purchases......
As someone who is strongly pro-business and believes a market economy is also the best way forward for social justice, there just seems so much skewed in favour of insiders, making it hard to sustain mass support. Sunlight (and even handedness) is the best disinfectant and all that.
Anyway, apologies for the outburst and back to investing......
(NB re Sosandar (LON:SOS) - I looked them up on the Next platform the other day. I was disappointed that the 'test' there seemed to be only 5 items. Unlikely to transform results short term. Will be interesting what they will say about it on 1st Dec)
That's right, SOS told us that the Next trial would only be a few styles to begin with, so it's never been seen as transformational in the short term.
P.
I noticed Cloudcall is not in your top ten
Paul, in your previous update you thought that a 2000p+ bid was attainable for BOTB, which I agree to.
Now you are not convinced anymore of the FSP anymore. However, when the FSP started, the share price was at about the same share price. So why would these prospective buyers not be wanting to pay up now? They were interested at these prices in the first place! Besides that, trading has significantly improved during the start of the FSP, making a possible bid cheaper on valuation terms.
IMHO, it's promising that there are still multiple parties interested after such a long time after the FSP started. In itself that is a positive sign to me instead of a neutral sign.
We'll know more soon enough. Holding and best of luck to everyone.
I think the reality is none of us know whats really going on. The facts are its been ongoing now for 5 months and it should be a very simple company to review and value.
You can argue if there was going to be an acceptable bid it would have happened by now, equally you could argue that if the potential bidders were scared off it would have been scrapped by now.
My own view is that a deal will go through eventually and I do expect it'll be between 20-25 a share based on the current trading the company is experiencing. If it doesn't then I will keep it anyway and pick up the generous dividends.
Disclosure: I am still long on this and it's my biggest holding - 9% of my portfolio despite some top slicing during the summer
Hi Martin,
As Brookeda mentioned below, it's the considerable time taken already by the FSP that makes me lean towards thinking a bid is now unlikely. Nobody knows other than insiders, but generally I've found that if a bid is going to happen, it usually happens quite quickly (a few weeks) after the original announcement. But who knows, it could go either way.
I feel it would be a pity for BOTB to sell up, given that they've only recently really cracked online marketing, so there could be more upside keeping it as an independent company, possibly?
I like BOTB on fundamentals, and as mentioned in the main article, I think it's now good value. But holders probably need to be braced for a spike down, if bid talks fall through. I doubt that would last long though, or be too deep, as the fundamentals look attractive.
Regards, Paul.
Hi Martin - fully agree and think that there is probably more benefit to come from being fully online. They clearly have strong operational momentum and why should that not continue. They may have benefited from lockdown to a degree but is that really significant as the cost of the various competitions is fairly low.
The argument that anyone could set up and do this doesn’t convince me, as surely if that was the case this would have happened by now. Such an argument ascribes no significant value to the brand , the expertise of management and the current market position. I doubt that setting up and running such a business well is particularly simple
Regardless of a bid to me the shares are now good value - which hopefully will be confirmed once earnings forecasts have been produced (of course I hold)
Wynnstay (LON:WYN)
Reporting above market expectations. Looks very undervalued. (See graph below)
DYOR.
BSV
Yes it is very undervalued - I bought a few months ago following it being recommended somewhere - it looks like a nice steady business that will continue growing (subject to the vagaries of the farming industry)
£WYN. It's a tempting buy. Feels like I'm getting it for half price and health dividend for free.
Good luck with your investing.
BSV
I bought Wynnstay (LON:WYN) about a year ago as they are clients of an agricultural software business in which I am a private investor. My reasoning was two fold, firstly I wanted greater exposure to the agricultural sector and secondly as well as the stock rank I believed the management must be on the ball to have subscribed to the SaaS business in which I am an investor.
On a secondary note, my godson is a farmer and retail client of Wynnstay, he says they can be good but are often inefficient in terms of stock management (the required product available in the wrong depot) so any sort of re-organisation may also be helpful.
Halfords (LON:HFD),
Halfords profit more than doubles on British cycling boom. British bicycles and car products retailer Halfords on Wednesday reported a more than doubling in first-half profit, boosted by a COVID-19-driven cycling boom. The firm said it made an underlying pretax profit of 56 million pounds ($74.3 million) in the six months to Oct. 2, up from 25.9 million pounds in the same period last year.
"Business rates relief and furlough income totalled GBP24.5m, but these benefits were partially offset by increased costs of operating under Covid-19 which, to date, amount to GBP11.4m in our retail business."
So £13.1m of £30.1m PBT increase due to Government money they look they are planning to keep.
I have not read the Halfords (LON:HFD) report but I presume that the extra costs of £11.4M relate to matters other than wages. The furlough income will have enabled them to carry on paying wages to employees who otherwise would have been laid off and received no pay. In this case they are obviously entitled to keep the money, the whole purpose of the scheme being to keep people in employment.
Obviously its legal to keep all the £24.5m or Halfords (LON:HFD) would not be doing so.
Assuming the company's figures are accurate, there is a also a reasonable argument for keeping £11.4m of the £24.5m.
As with the supermarkets, that are also thriving due to Covid, I cannot see any reasonable argument for keeping the rest.
Somewhat surprised the ESG thought police are not all over companies taking this approach.
If Halfords are making so much money then they don’t need taxpayer support and should hand it all back as other companies have done.
Tatton Asset Management (LON:TAM) have interim results out today and are hosting an investor presentation at 3pm this afternoon. You can register here: https://zoom.us/webinar/register/8916056850379/WN_RwhCT8hGQUyVQDtb0-9D-w
Obscene levels of share based charges at Tatton Asset Management (LON:TAM) take the gloss off the numbers, IMHO.
Tatton Asset Management (LON:TAM) It is all covered here, grumpy5, at 8.30 mins and 44 mins. Look back over the last three years, you can see it's simply the knock on effect from such a low charge last year. https://www.equitydevelopment.co.uk/research/investor-presentation-covering-interim-results
Hi Paul & Jack. Yesterday you mentioned Dotdigital (LON:DOTD) - are you planning on doing some analysis on this company? Also, thank you for your work. It's a must read for me each day.
Morning MarkB,
I ran out of time yesterday, having spent about 10 hours on the report, and so had to drop something from the running order. The DOTD share price didn't move yesterday, and with EPS dropping slightly (due to higher tax), and a high PER, I thought it didn't look like a buying opportunity.
Tell me if I'm wrong! Happy to circle back to it on Friday, if there's a compelling reason to do so.
Best wishes, Paul.
Hi Paul. Thank you for replying. I wasn't thinking of a buying opportunity, actually the opposite, but not shorting. I bought in around June this year and set a sell price of 2.20. I re-evaluate all my positions whenever a new set of financial reports become available. Now i think that sell price is too high and sometime this weekend i will re-evaluate and re-set. I am thinking that my sell price will be around the 1.80 mark. I'm a fundamental long term investor who looks to hold for 10 years plus and I was hoping this company would grow inline with it's history. I was interested in your take on the company, but spending 10 hours working is too much for anyone. Thank you again for taking your time out to reply to me.
My morning smallcap tweet: VRS hope, not sales as usual
Innovaderma (LON:IDP) DP Eurasia NV (LON:DPEU) Versarien (LON:VRS) International Personal Finance (LON:IPF) Begbies Traynor (LON:BEG) Wynnstay (LON:WYN) Best Of The Best (LON:BOTB) Finncap (LON:FCAP) Speedy Hire (LON:SDY)
InnovaDerma (IDP) CEO steps aside to be Exec chmn. New CEO Blake Hughes. [SP=56.2 Cap=8m]
DP Eurasia (DPEU) last 10 months rev up 12% in Turkish Lira. "The momentum in current trading is encouraging." [SP=31.1 Cap=45m]
Versarien (VRS) preliminary study of modified graphene materials provided by Versarien shows that they significantly inhibit viral infection and possess anti-viral activity towards covid. Validates hypothesis that graphene nanoplatelets doped with metal oxide nanoparticles can be anti-viral in the lab at least. [SP=34 Cap=58m]
International Personal Finance (IPF) Oct trading: Collections effectiveness increased 200bp to 97% and further increase in credit issued to 60%, both re pre-Covid expectations. [SP=82.5 Cap=185m]
Begbies Traynor (BEG) guides FY at least in line with market consensus which is for pretax of £9.8m. H1 rev up 10%, adj pretax up 25%. [SP=86.4 Cap=110m]
Wynnstay (WYN) trading stronger than expected, especially in September and October. Guides U/L pretax significantly ahead of market forecast. [SP=307.25 Cap=62m]
Best of the Best (BOTB) trading since Sept RNS still strong. Bid talks continue. [SP=1448.44 Cap=136m]
Finncap (FCAP) H1. Trading: Q3 has started well and pipeline looks promising, guides FY profits well up. Cautions that "economic environment remains uncertain and is likely to be so for some considerable period ahead". [SP=19.5 Cap=34m]
Speedy Hire (SDY) H1. Guides FY towards the top end of analysts' expectations. [SP=64.4 Cap=339m]
Hi MrC,
I can't say it often enough, but your early snapshots are so useful, and a great help to me in homing in on the most interesting company updates, for me to then take a deeper look into.
Amazing consistency too, you never seem to take any time off!
Thanks very much indeed.
Best wishes, Paul.
Are you sure I'm even human?
The AI's haven't cracked quick fire snarky comments that make us laugh - yet. Perhaps humour is the final hurdle for the Turing test?
I'm going to ask Mrs Contrarian for an opinion.