Small Cap Value Report (Weds 19 Oct 2022) - SDG, RBG, LIO, PFG, ASC

Good morning from Paul & Graham! Today's report is now finished.
Agenda
Paul's Section:
Sanderson Design (LON:SDG) - yes this one again! Just to flag that I've typed up (took about 3 hours, nightmare!) my recent audio with the CEO of SDG. It's quite long, so I've published in a separate post, to make it easier to find for future reference, here's the link.
Revolution Bars (LON:RBG) - the acquisition of Peach (operator of 21 gastro-pubs) looks an OK deal, but funding it from debt does increase risk. I also question the timing of this deal, as we seem to be going into a downturn. Overall, I'm a bit underwhelmed.
Update: a separate section on the FY 6/2022 results has just gone up. I think the figures show that, despite management doing a good job operationally, it's such a tough sector right now. It's difficult to be positive on the figures, although it has returned to modest profits, and generated strong cashflows, funding a big refurbishment programme. Is it running to stand still? It does look that way a bit. Shares are amazingly cheap though.
ASOS (LON:ASC) - a rather rushed review of its FY 8/2022 results. It seems a catalogue of problems, but immediate worries about the bank facilities appear to have been resolved, probably why there was a relief rally this morning. Overall, I think the business has many, and deep-seated problems, which could take several years to resolve. For that reason I'm happy to sit on the sidelines and watch. Gamblers could do well on it though, if sentiment turns positive.
Graham's Section:
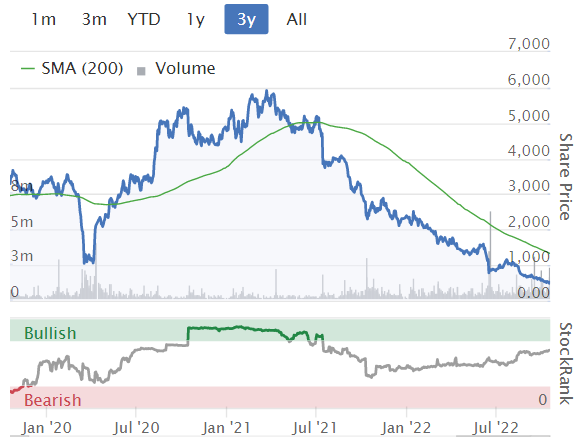
Liontrust Asset Management (LON:LIO) (£528m) - this company reports net outflows and a reduction in AuMA (assets under management and administration) in H1, neither of which are a surprise. However, it did make a substantial acquisition (Majedie Asset Management) and the reduction of AuMA would have been much more severe, in the absence of that deal. I’m sceptical when it comes to the longevity of the themes emphasised by Liontrust’s funds, particularly in a recessionary environment. I previously studied a cross-section of their holdings and found many speculative holdings which looked vulnerable to me in this bear market. So while Liontrust shares are very cheap, I wouldn’t be optimistic about future AuMA trends and would look to invest elsewhere in the fund management sector.
Provident Financial (LON:PFG) (£394m) - this trading update is in line with expectations, and the company says it will meet targets for FY 2022. This suggests that EPS of 36p may be possible (latest share price: 155p). The history of this stock is not at all encouraging to potential shareholders, which may help to explain why it’s trading at a significant discount to book value and at extremely low earnings multiples. The economic conditions are also very worrying, as Provident’s credit card and vehicle finance customers are likely to be hit hard by the cost-of-living crisis. All of that having been said, I am open to the idea that these shares are now simply too cheap and offer an attractive risk/reward at current levels.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Revolution Bars (LON:RBG)
10.75p (down 8% today at 09:05)
Market cap £24m
Acquisition of Peach Pub Company (Holdings) Ltd (co. no. 04336195)
As expected, this deal was completed yesterday, and announced after hours.
Key points -
21 premium food-led pubs (sites are leasehold)
Cash consideration is £16.5m (on cash/debt free basis) - £16.0m up-front, plus a small earn out of £0.5m.
Funded entirely from RBG’s bank facilities, with no equity issued - a good thing, given how low the share price is.
See Peach’s website here, for details & photos of its pubs.
Average site revenues is about £1.5m, so this should bolt on about £31.5m extra revenues for RBG, a 22% increase in group revenues on FY 6/2022 revenue of £140.8m.
Some numbers on Peach -
Trading in Peach's current financial period (since 3 January 2022) has been strong with LFL sales up over 10% compared to 2019. The Board anticipates 12 month site EBITDA for Peach in Revolution's current financial year to be over £5m with central costs in the region of £3.5m on turnover over £30m.
Significant cost synergies are expected to result from the Acquisition. It is estimated that cost savings through increased buying power, business combination and improved systems will generate at least £1.5m of synergies, taking pro-forma EBITDA to £3m once synergies have been fully realised. We expect these synergies to be largely delivered in FY24 (£1m) before being fully achieved in FY25. The costs to achieve such synergies are expected to be minimal.
My opinion - this deal looks OK, but not madly exciting to me. Paying £16.5m for a business making £1.5m EBITDA doesn’t look great, but synergies are expected to double EBITDA to £3.0m, making the purchase multiple 5.5x EBITDA, which looks OK, providing of course those synergies actually do come through (the risk is that acquirers sometimes over-estimate the costs they can strip out without harming performance).
However, the timing is questionable, just as we’re going into a consumer downturn, which might have been why the founders wanted to sell up?
Funding it with debt also increases risk. So I’ve got to say, I’m lukewarm on this deal. Although I can see the logic for a different type of bar (food focused, outside city centres, all day trading) might balance up the portfolio, and increases scale & expansion possibilities.
Revolution Bars (LON:RBG)
10.75p (down 8% at 09:14)
Market cap £24m
Revolution Bars Group plc ("the Group"), a leading UK operator of 69 premium bars, trading predominantly under the Revolution and Revolución de Cuba brands, today announces its preliminary results for the 52 weeks ended 2 July 2022.
I’ll refer to this as FY 6/2022, as the 2 days spilling over into July don’t matter (you often see this with companies which use weekly accounting internally).
Company’s headline -
A strong return to more normalised, profitable trading with careful cost management
The headlines table demonstrates what a mess IFRS 16 is, as it completely distorts EBITDA into a completely useless figure, that massively overstates real world profitability (by missing out a large chunk of property rents) -
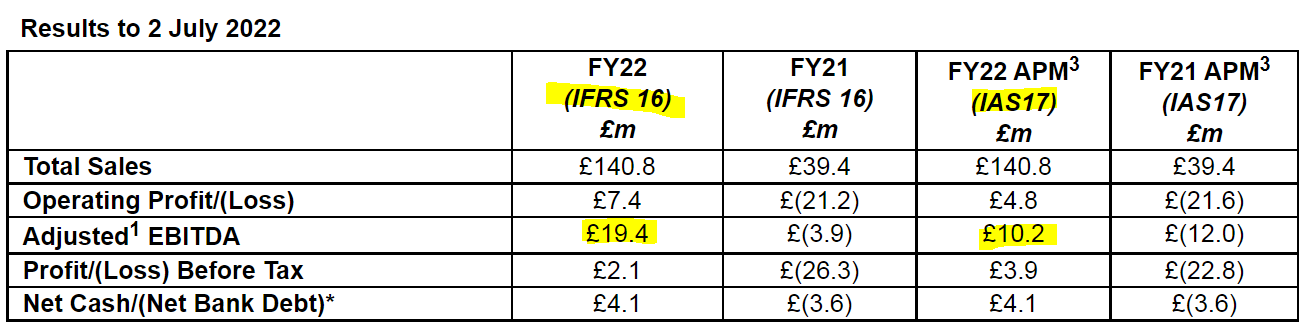
“APM” stands for alternative performance measure.
Key points -
Returned to profitability, obviously positive.
Softer trading in Q4 (Arp-Jun 2022)
Big improvement in gross margin, up from 71.3% to 78.2%, that’s impressive, although partially helped by reduced VAT on food & non-alcoholic drinks.
Net cash of £4.1m at end June 2022, improved from £(3.6)m a year earlier, so good cash generation, despite capex of £8.3m, funding a bar refurbishment programme & 2 new sites. Bear in mind the company’s just spent £16m on the acquisition of Peach Pubs, so is now in a net debt position again.
Refurbs performing well, with 2-year payback. New sites also doing well.
New concept sites “performing well” - Playhouse, and Founders & Co.
“Forensic and relentless” focus on cost control.
Energy costs largely fixed until April 2023, and consuming less.
Current trading -
Not good at all. LFL sales down 10% for first 11 weeks’ trading. Recently improved to -4.5% for weeks 12-13. Q1 of FY 6/2023 in total was -9.1% LFL, blamed on the rail strikes and other factors. However, the context is that the LY comparatives were incredibly strong in Q1, at +17.2%. That was a one-off, and greatly reduced to only +1.3% in Q2 last year. So I wouldn’t panic over the negative performance in Q1 this year, this should improve due to LY comps normalising from Q2 onwards.
Outlook for peak Christmas/New Year season sounds encouraging - Xmas bookings “well ahead” of last year, which was harmed by Omicron remember. That should give a soft LY target to compare with this year. Therefore, there’s a strong chance that the poor Q1 LFL this year of -9.1% should improve as the year goes on.
New sites - I’m taken aback by this, as it’s such a good time to be sourcing high quality new sites at cheap rents -
The acquisition of Peach has redirected our capital, and thus we won't be opening the previously announced six new sites in FY23...
Guidance -
Taking into account the contribution from Peach for the rest of the financial period, we now expect the FY23 outturn to be APM3 adjusted1 EBITDA c. £10 million
In FY24 we expect an increased contribution from Peach post-synergies, although this is expected to be somewhat tempered by increased energy costs for the Group as a whole as we come out of the March-23 energy cap.
Broker update - many thanks to Finncap for updated forecasts this morning. Revenues grow, from inclusion of Peach, but overall adj PBT is barely above breakeven, at £1.3m FY 6/2023, and £1.7m next year. In the current climate, I wouldn't want aggressive forecasts, and the risk of a profit warning. There's no guarantee though, that with potentially falling demand, and higher costs, that it remains profitable at all. Almost 80% gross margins mean that changes in revenue make a magnified effect on profits or losses, on a cost base that's mostly fixed or semi-fixed. So there's risk here (and for the whole sector), if the consumer downturn really turns ugly. There's also upside potential, as profits would soar, if revenues recover strongly in future. The young target audience benefits from having full employment, and less exposure to utility bills. A good night out is exactly what people in depressing times, so I don't take it as a given that RBG would necessarily see a big fall in revenues. Plus of course many competitors are likely to bite the dust.
Going concern note - this is very surprising. The auditors (who decide these things) seem to have required a “material uncertainty” note over going concern, despite the Directors saying that there’s no forecast breach of bank covenants even under a downside scenario.
This is due to -
The material uncertainty caused by COVID-19, guest confidence, and higher input costs, coupled with forecasting difficulties as a result of constantly changing economic impacts means that the Group cannot be assured that it will not breach covenants…
This seems very confusing, mixed messaging.
I suppose it does highlight the risk to the entire sector (and many others), that if covid (or another different pandemic) returns in a bad form, requiring more lockdowns, then businesses like this are the worst affected. Maybe that means shares in leisure, travel, hospitality, retail, etc, should trade on a permanent discount to other less affected sectors?
It seems all the more odd, that RBG has just taken on a load of fresh bank debt, to buy Peach’s gastropubs. Why would anyone do that, if there’s a material uncertainty over going concern?
Balance sheet - tangible net assets are negative, at £(23.0)m. That’s despite raising £34m in 2 placings in the previous year. The culprit is mainly the IFRS 16 lease entries, with a £62.7m Right of Use Asset, but £5.4m + £99.5m lease liabilities. Net those off, and it suppresses NAV by a whopping £42.2m. If we remove the lease entries (my preferred method), then NTAV turns positive to £19.2m, which looks OK. However, a big deficit on the lease entries suggests that there must be some significantly loss-making sites again, which is odd, because I thought those had been dealt with in the previous restructuring & CVA.
Bear in mind that the acquisition of Peach will generate a new goodwill figure of maybe something like £12m (my guess) in this year’s accounts, which weakens the balance sheet, and the £18.8m gross cash pile will have largely gone too for the same reason. Offsetting that, it is cash generative, which could reduce debt a bit as this year progresses.
Cashflow statement - is flattered by the distortions of IFRS 16, and also some favourable working capital movements probably related to re-opening last summer, which are unlikely to repeat.
Overall though, the cash position has improved by £6.7m, despite funding £8.3m in capex, which is pretty impressive. Note that capex is high, due to a big refurbishment programme being underway. So resting capex, once the refurbs are done, and assuming no new sites, would be a good bit lower.
My opinion - the main attraction of this share is that it’s so cheap. You’re getting a significant sized business for peanuts market cap.
Personally I’m not enamoured by the big acquisition of Peach, due to the timing, and increased debt risk it brings at an inopportune time.
Also I’m disappointed that this has blown the budget for new sites, when good sites should be available on attractive terms (as XP Factory (LON:XPF) [I hold] is demonstrating). I was hoping the Playhouse format would be developed faster, as that seems a buoyant area at present.
I think management at RBG are doing a good job, in tough market conditions. But maybe there’s not enough to differentiate this concept from the competition?
Overall, I can feel my loyalties transferring to XPF. Although at the current market cap of only about £24m, I also think RBG is too cheap to ignore, so it’s staying on my watchlist for things I’d like to buy back once economic conditions are at least becoming a bit clearer.
(for anyone not already aware, I’ve mentioned several times in recent weeks that I had a total clear out of everything in my geared account, where most of my small cap positions were held, so this was more driven by necessity in a dire market, than any changes in my fundamental view of various companies).
.
ASOS (LON:ASC)
541p (up 10% at 11:51)
Market cap £541m
For FY 8/2022.
Key numbers -
Revenue £3,937m - so this is a big business.
Gross margin very low at only 43.6% (down from 45.4% LY) - this has always been Asos’s problem, ecommerce fashion companies need higher margins, to mop up the big costs of handling extensive customer returns.
Gross profit down 3.3% to £1,717.5m
Costs have shot up, especially administrative expenses, up 13.7% to £1,224.2m.
Put that lot together, and profit has been squeezed out completely, with a loss before tax of £(31.9)m, versus a £177.1m statutory profit last year. No wonder the share price has collapsed, because profitability has collapsed.
Adjusted figures are also presented, with adjusted PBT of a £22m profit. I’m very sceptical about these adjustments, especially the “ASOS Re-imagined” costs of £25.4m - a footnote says this is mostly payments to “external consultants”! That’s a colossal amount, and seems an admission by management that they don’t know how to run the business.

Other income of £20.6m is mostly a one-off benefit from closing out forex hedges re Russia. But that doesn’t seem to have been stripped out of the adjusted profit, which I think it should have been, so it looks as if profit is over-stated by that amount.
Although its new CEO has come up with a fairly serious list of things that need to be fixed -
New CEO has identified problems, which include -
international operations that have lagged expectations on ROIC, particularly in the US; a need to review and renew the customer acquisition and commercial model; a supply chain operation which has become inefficient in the face of supply chain disruption and macroeconomic challenges; the need to better leverage data and digital improvements to successfully engage the customer; and the need to strengthen the leadership team and refresh the company culture
Banking arrangements - these seem to have now been agreed, a key concern raised a few days ago in the press.
To navigate the continued macroeconomic volatility, ASOS has agreed additional financial flexibility through the renegotiation of core banking covenants, with cash and committed facilities of over £650m at year end
Changes to Group funding
Post the balance sheet date, the Group has agreed an amendment to its £350m revolving credit facility (RCF), with existing financial covenants ceasing to apply until February 2024, and providing the Group with much enhanced flexibility. A new minimum liquidity covenant will apply until the maturity of the RCF. As part of this amendment, the Group's bank lenders have agreed an accordion option to increase the RCF to circa £400m, allowing the incorporation of newly committed ancillary facilities. The amendment also provides for additional reporting disclosures and security by way of fixed and floating charges over certain Group assets.
Stock write-offs - a £100-130m write-off is needed against inventories. Why is this going through the FY 8/2023 accounts? Surely it should have been booked in the FY 8/2022 results. That’s a very large number, on a year end inventories position of £1,078m. Remember that inventories are recorded at cost, so if a provision is needed, it means the stock is having to be sold really, really cheaply, to shift it. This really worries me, as it implies a lack of control over inventories.
Actually, the commentary implies there’s so much wrong with this business, that there seems a lack of control over practically everything!
Balance sheet - NAV is £1015m, but that includes £684m of intangible assets, making NTAV £331m. But they’re telling us than inventories are worth at least £100m less than this book value, so that reduces NTAV to c.£200-231m.
Note also that the lease liabilities are high, so some hefty warehouse obligations.
Working capital looks fine, but there’s a very large long-term borrowings figure of £475m, although that’s mostly offset by cash of £323m. Remember though that, at a £4bn revenues company, working capital swings could be large intra-month, so I’d say the business is probably quite dependent on its bank borrowings, which increases risk.
Net debt (excl leases) is £152.9m.
Overall then, I’m not comfortable with this balance sheet, given that Asos is now loss-making.
Cashflow statement - “Payments to acquire intangible assets" of £109.2m stands out. This looks like internal development costs, because last year’s acquisition of TopShop is shown in a separate line further down. So it looks like Asos is aggressive in how it’s accounting for It spend internally. Another good reason to ignore EBITDA. The amortisation charge through the P&L is £88.8m.
Overall the cash outflow was horrendous, at £(339.8)m, with the bulk of that being due to greatly increased inventories (up £258.7m).
Outlook - lower costs in some areas (freight) and active cost-cutting under restructuring plan, are expected to more than offset higher costs elsewhere, in H2.
Capex will be reduced.
Expecting to raise gross margin.
Free cash for the full year between £0 and £100m negative.
My opinion - I’ve had to rush through these numbers, due to having an obligation this afternoon. I’ve seen enough to be really quite wary of this share. It looks an absolute can of worms, with numerous operational & structural problems. That’s going to take a long time (and cost a lot) to fix.
So I can see why the share price down 90%, because things are a mess, and it’s now loss-making.
The shares are therefore a straightforward choice. If you think the strategy will work, and the business can be turned around, then it could be worth a dabble.
Personally, the problems, and reliance on bank debt, worry me too much.
So I’ll watch from the sidelines, but for me this share is too much of a gamble at this stage. Sentiment can change quickly though. When we get back into a bull market, people might start thinking about the previous highs of this former stock market darling, and it could bounce strongly.
Someone might bid for it. I see a Danish clothing company, Bestseller, owns 26% of Asos.
If all the operational problems can be fixed, then the leverage on £4bn of sales could be interesting. So it remains to be seen if Asos is paying us a fleeting, once in 10 years visit, or whether it's taking up residence in the SCVR's spare bedroom?!
.
Graham’s Section:
Liontrust Asset Management (LON:LIO)
Share price: 813p (-1%)
Market cap: £528m
We last covered this company when it issued results for FY March 2022.
Today, it issues an update for H1 (i.e. the six months to September 2022).
Key points:
- Net outflows £2.2 billion (of which £1.6 billion in Q2)
- Assets under management and advice fell by £1.8 billion to £31.7 billion.
CEO comment:
It’s helpful to know what other investors are thinking - and I give particular weight to the comments from fund management companies to their owners.
While I expect them to portray their own performance in the best possible light, I still find the comments useful as a barometer of their mindset.
The Liontrust CEO remains positive:
We have great confidence in our robust investment processes, which is reflected in our long-term performance and the fact that, despite stock market de-ratings, operationally the majority of the companies that the teams hold continue to perform as the fund managers expect. The volatile markets, while challenging, are presenting opportunities to invest in many high-quality companies around the world on highly attractive valuations…
Looking ahead, we will continue to focus on expanding our sales by funds, geographies and clients. With the excellence of our investment teams, distribution and brand, underpinned by our strong balance sheet, Liontrust is well positioned to generate future growth."
Investment types
Here is the latest breakdown of Liontrust’s AUM:

Comparing this table to the equivalent table in June, there are some huge percentage moves in AUM over the six-month period:
- Sustainable Investment (largest category) down 17%
- Economic Advantage (second largest category) down 16%
- Global Equity down 60%
- Global Fixed Income down 33%
But if markets have been routed and if Liontrust experienced outflows of £2.2 billion, how is it that AuMA only fell by £1.8 billion?
The explanation is that Liontrust’s acquisition of Majedie Asset Management completed on the first day of the new financial year. That brought in £5.1 billion of new assets:
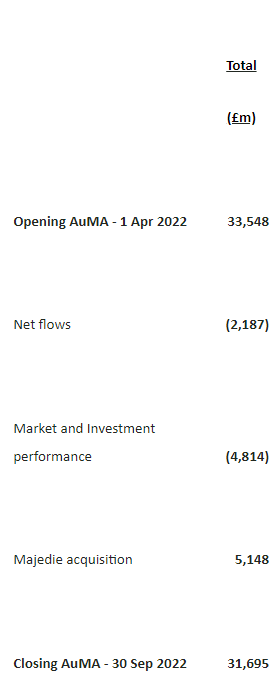
Without the Majedie acquisition, it looks like AuMA would have fallen by something closer to 20%, instead of only falling by 5.5%.
In its highlights, Liontrust could have emphasised and explained its “organic” performance, excluding the impact of the acquisition on AuMA. Instead, it chose to simply compare post-acquisition AuMA with the pre-acquisition AuMA.
Fund performance
I don’t tend to pay much attention to how the average fund management company presents its overall long-term investment performance, because I assume that any underperforming funds have been shut down or merged with better funds.
For what it’s worth, here is the 5-year performance of Liontrust’s current funds:
- 16 funds are top-quartile (i.e. in the top 25% of comparable funds)
- 6 funds are second quartile
- 4 funds are third quartile
- 9 funds are bottom-quartile
In order to give Liontrust credit for having more funds in the top-quartile than in the bottom-quartile, I would need to go back and check that any of their underperforming funds from five years ago had not been shut down or merged. See survivorship bias.
Two of the large, multi-billion pound funds that I analysed last time - the Sustainable Future Managed Fund and the Sustainable Future Global Growth Fund - are top-quartile, so that’s good.
My view
Back in June, I explained that I was nervous about Liontrust’s “Sustainable” investment approach: many of the companies in these funds had terrible StockRanks and no track record of profitability.
I’m still worried about them. Assets in their Sustainable category are down by 17% in six months, and I don’t see why this trend won’t continue.
In an era of higher interest rates and compressed valuations, I continue to believe that investors will demand strong returns first and foremost, and will have less interest in whatever popular themes the fund management industry wants to offer them.
What can be said in Liontrust’s favour is that its shares are cheap. I believe that this is correct: its shares should be cheap, to reflect the difficulty that active managers have in justifying themselves against passive and cheaper investment alternatives.
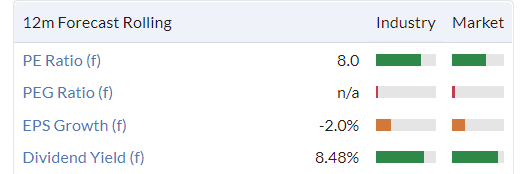
I should also mention that this stock passes no fewer than nine of Stockopedia’s stock screens, all of them bullish.
The sheer cheapness of it is likely to attract buyers. But I expect that other fund management stocks will turn out to offer better prospects than this one.
Provident Financial (LON:PFG)
Share price: 155.3p (-6%)
Market cap: £394m
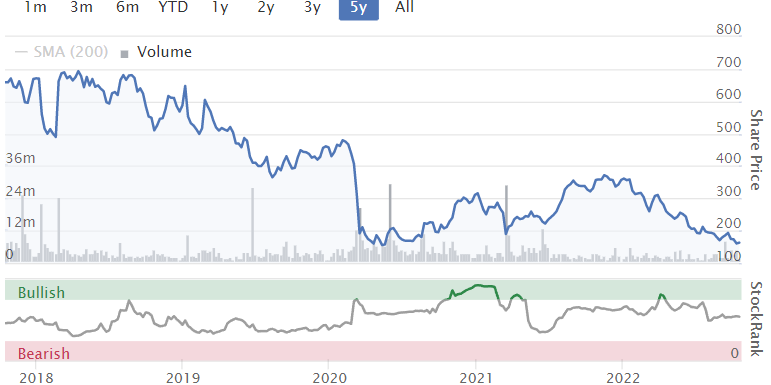
This old name in lending has been a poor investment:
These days, it describes itself as “a leading specialist bank for the 12 million UK adults not served by mainstream lenders”.
It has 1.7 million credit card customers, and says that it promotes “financial inclusion and rebuilding of credit card history”.
That’s a noble way of describing credit cards having a representative APR of between 29.5% and 39.9%.
It’s the same story with vehicle finance. They are “helping” people improve their credit score. At the low price of 31.9%.
They also provide a range of savings products (the six-month bond pays 1.35% while the 5-year bond pays 4.35%). These retail deposits are an important part of their balance sheet funding - more on that later.
Let’s check out their Q3 trading update:
- In line with expectations. On track for FY 2022 (the EPS forecast is 36p).
- Moved the business to lower risk customers (in the “mid-cost”/”near-prime” parts of the market)
- Credit cards: stable delinquency trends. Higher spend per customer; receivables grew 5%. Google Wallet enabled.
- Vehicle finance: improving arrears trend. New retail distribution agreement. Receivables grew 3%.
- Personal loans: receivables have exceeded £50m for the first time.
Balance sheet: the ratios disclosed are strong, and there is £145m of headroom (or £240m of “liquid resources”).
My view
Without having looked at Provident for a while, I’m open to the possibility that it’s too cheap at current levels.
Balance sheet equity was £600m as of June 2022, and the overall leverage employed by the group is significant but does not appear excessive.
Key balance sheet items:
- Customer receivables (amounts owed from customers) £1.67 billion
- Total assets £2.5 billion
Funded by:
- Retail deposits (amounts owed to customers) £927m
- Bank borrowings £825m
- Total liabilities £1.9 billion
This looks fine. We have to think about the economic risk, of course: the average credit card customer is spending more and we must sadly assume that this reflects inflation and an element of financial stress in households.
Total customer receivables of £1.67 billion are stated net of an “allowance” for £600m of impairment losses. We could argue that high levels of financial distress have already been priced into the asset values.
Overall, I don’t view this as an investment that would let its shareholders sleep easy at night, but I do think it looks too cheap at current levels. I say that cautiously: many people will have thought that Provident’s shares looked cheap at various points in its history, and it has nearly always disappointed them.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
“If all the operational problems can be fixed, then the leverage on £4bn of sales could be interesting. So it remains to be seen if Asos is paying us a fleeting, once in 10 years visit, or whether it's taking up residence in the SCVR's spare bedroom?!”
Excellent.
In my view the RBG acquisition is way too early to judge and therefore would leave it alone. As planetx points out acquisitions can be a 50/50 play and with all the macro issues of the moment it just seems this raises the risk significantly. In addition RBG is a Cocktail Bar operator not a classy pub operator. I appreciate they are both in the entertainment slot but quite different clientele. I think I will pass.
Hi Paul, thanks for your reply re spreadbetting. I’m coming to the same conclusion as you. I find if you can withstand some volatility, you can often get to a positive outcome but with gearing you just don’t have much leeway for volatility.
Regards,
Andrew
Re £RBG - it is all in the execution - it seems to me like a potentially good deal but upped the risk (again!)
The first question is main bar group. This needs to deliver the cash or else the whole thing falls down.
Signals here are at best mixed based on results so far but.......it does seem to be recovering its mojo and with so many bars refreshed by end of 2023, should be in its best phase (refurbs drive sales so its a cycle).
The unknown is demand which is a factor of both demand and supply. The number of 20-25yr olds is near bottom so that's very bad and exacerbated by the cost-of-living crisis. However, that crisis is worst for the 30-50- year olds (fuel and food bills up, housing costs up, graduate tax repayments). Younger than that and there is full-but-shitty employment and with so many living at home or in shared city digs they will want to get out. Undergrads (now 50% of relevant age cohorts) are given sizeable grants (which they can easily top up with casual work) and still believe its their time to party (based on my 2 in this age group!). So I suspect demand will hold up better than we think.
But nightclub supply has been decimated. The analyst packs say 20% gone since COVID. I read over 40% of nightclubs closed in last few years ie started closing before COVIDand more will go down in next 18M; it seems surprisingly hard to open new clubs - planning restrictions, cash investment to deck out location and attract a crowd - today's young (those who go to clubs!) show no sign of wanting raves in warehouses or now empty retail stores. I do however dispute the claim that Revolution is premium!
If the demand wheels stay on, I think £RBG will generate a lot a cash and could thus bring down its debt quickly (conservative option) or drive growth. On the latter, I think buying sites out of administration/bankruptcy would have been better but maybe that is a strategy better suited to a real wheeler-dealer entrepreneur. RBG is a stock market option so arguable needs a more predictable strategy than "I will pounce on new sites as they come up"
On Peach, I understand that it a good sized to acquire for existing group, offering a major jump in scale and a stabilising revenue pattern. I can even be persuaded on price IF the central costs can be absolutely smashed down with a bigger group. But this is a risk as they seem to be v optimistic - few costs to integrate? Half costs gone in 18 months?
Net, I think this is a bet on the CEO - if he can integrate and run a much bigger group well, shareholders (like me) will be fine and do well. If it works, a virtuous circle appears ie cash generation is bigger, sooner and thus even more sales in 2024 can be bought. So far, I think he has done a decent job and he now needs to show he can pull such a deal off (before he goes to a much bigger group).
Personally, given how my portfolio has done this year, I would have voted for the less risky strategy. Based on history I will wait and see. (Long term and battered shareholder)
Paul - Thanks for the SDG interview and the transcript, my what a task
Graham - Great stuff there on LIO, much appreciated
Revolution Bars (LON:RBG)
.... and another thing: They talk about "cost savings through increased buying power". Really? Looking at https://makinglifepeachy.com/f... they talk about buying from specialists, many being Royal Warrant holders. How many of those supply Revolucion de Cuba? Try switching Peach to suppliers of catering for the masses will lead to loyal clientele deserting.
They think that having part of the group serving middle to older age foodies and the other part serving the young out-to-the-early-hours brigade will mean that "The combined business will benefit from diversification". Peter Lynch in his very good book 'One Up on Wall St.' called that diworsification.
Bang on the money, I sold my small restaurant group to a PLC, they were very confident that they could make huge savings by economies of scale in purchasing. It was mostly illusory as I had a long term relationship with good suppliers and often paid 30 or in some cases 14 days from statement to get good prices. In the end they cut quality to make savings with the usual results, alienation of core business.
Also running leasehold bars in town centre locations is a hugely different game in terms of estate management to what appear to be character pubs in period buildings. Not sure that it is synergy, more likely long term entropy.
Hi
ASOS (LON:ASC) up over 11% as I type. It's now £490m Mkt cap so in SCVR territory.
Here are but three points from its RNS today, so it suggests a possible turnaround strategy with new CEO.
The UK, ASOS' core operation, delivered good performance (+7%) despite the weakening consumer environment. This has been supported by a curated offer and differentiated visual language, leading to a growth in active customer base ahead of the Company average (+5%) and a further increase in Premier customers (+6%), resulting in an increase in average order frequency (+5%)
Strong Topshop performance (+105%) reinforcing revenue growth in the UK, US and EU and driving margin expansion
New CEO now in place with a diagnostic of the issues ASOS faces including: international operations that have lagged expectations on ROIC, particularly in the US; a need to review and renew the customer acquisition and commercial model; a supply chain operation which has become inefficient in the face of supply chain disruption and macroeconomic challenges; the need to better leverage data and digital improvements to successfully engage the customer; and the need to strengthen the leadership team and refresh the company culture
Rest of RNS here ....
https://www.investegate.co.uk/...
I don't hold but I know Paul and others are interested in the online retail sector.
Regards
Howard
considering Pauls scathing summary on ASOS (LON:ASC) (I hold) they merit a stock rank of 64 (quality 80 !!) - becoming very weary of these stock ranks (I know you also have to DYOR but still) are they worth the screen space ?
Or maybe Paul is too bearish on ASOS (LON:ASC) ? And the SR system is right that this is a decent enough company, just possibly struggling temporarily?
Sure, the current financial results are bad. But so much of it has been identified as just lack of good operational control and governance. That's easy to fix, and fully within their own control.
For me, they have secure long term debt and also bank facilities until 2024, mostly covenant free, to get things in shape at ASOS over the next 12-18 months. All the problems are not rocket science, just needs better operations. With a new Chairman and CEO (who seems to have a very COO and operational background), looks like a credible pathway to fix?
I think the Revolution Bars (LON:RBG) purchase of Peach is potentially interesting, and I am turning bullish on the company.
What strikes me is that central costs seem to be £3.5m, and site level EBITDA is (they say) around the £5m mark. Thus the multiple of site ebitda is only 3.3x. A lot will hinge on how much central cost can be stripped out. £3.5m of central costs appears to be huge in relation to the size of the group (£32m sales, 21 sites). I'm in hospitality myself (4 sites + 1 JV) and our HQ costs are large in relation to our (somewhat sub scale) £5m of sales but I can't imagine having anything like £3.5m of head office costs even for 21 sites. I'd love to see a further breakdown of this item.
I think it's a good deal on the face of it but if those central costs can come out it's a great deal.
I have also been informally keeping a rough log of the M & A in this sector for a while and what also strikes me is how the valuation metrics have plummited over about 2 years (no surprise there!). Looking at my table this looks to be the one of the cheapest, at least for a business that is not (as far as we know) in trouble. There have been some cheaper deals of course but these have been genuinely distressed situations.
I think it may be a bottom of the cycle deal. Makes you wonder why they sold...but botton of the cycle deals are good for the acquirer.
Revolution Bars
Sorry looks a shocker of a deal to me.
With the next year going to be awash with opportunity “it’s a buyers market”
Quite simple they have paid too much .
Got to acquire at the right price because whilst acquisitions always look good on paper and everyone involved gets very happy a year down the line in the slog of integration it rarely goes to plan .
I did 5 acquisitions, one went very well , two ok , and two were total disasters . So I’d say 50/50 chance of it going well is a good generous rule of thumb .
Bad deal it’s pretty clear and they have to really make that work .
Think deal looks expensive and can’t really see the businesses will be similar to run, revs are a late night business with very wet lead business peach looks more like a gastro pub heavily into food. Looks like a big price in current climate but the revs buiness has had a great year! £19m ebitda and a market cap of £24m
Digging into this further the restaurant group plc were under offer to buy peach pub co in 2018 for a reported 26m but withdrew then to focus on buying wagamama. Peach turnover has grown since then by £5m pa and have acquired 1 additional site, profit seems to be similar then to what is reported now. does look to be a much lower purchase price than they were looking for then but still feels a expensive for a wholly leasehold estate that makes £1.5m ebitda
Am curious to know Pauls thoughts on Revolution Bars (LON:RBG) now, given the latest announcement gas he was quite bullish about the company after its decision to revamp many of its premises during the Lockdown. From what I see, its SP has just been going south over the last few years, and is this really the right time to buying another business via debt financing. Looks a dead duck to me.
I didn’t say the results were good! Lack of TVs in bars also likely to whack pre-Xmas numbers again with the coming November FIFA World Cup.
For those that may have missed it Revolution Bars (LON:RBG) announced an acquisition and issued interim results after the close last night. Si
Note out by Finncap slashing numbers as well
At first glance the Revolution Bars (LON:RBG) acquisition looks interesting, but the growth forecasts and increased risks using debt put me off.
Finncap has reduced forecast EPS to 0.5p and 0.7p for 2023/2024 so is trading on a forecast P/E of 22
With added debt and recent large government tax rises it looks way overvalued to me.
Will be really interested in Paul's thoughts on this one, as I know he knows the company well. My overall concern is that, if, as previously was the case, they were very content with their two formats (including the supposedly promising Founders), why would they go out and spend on goodwill in acquiring a competitor, especially when sites are so cheap to acquire?
I've half-written up a section on Revolution Bars (LON:RBG) last night, so will finish that off now, should be up here by about 10am.
Following on Graham's analysis of Smiths News (LON:SNWS) on Youtube and the recent contract renewal of its magazine distribution contract with Frontline and Seymour, it has this morning announced a contract renewal with Associated Newspapers publisher of the Mail, Mail on Sunday and the 'I' to 2029.
Combined, these long term contracts represent 35% of the company's revenue and I would suggest bode well for the likelihood of a similar outcome with its other clients.
Do you have a link to Graham's analysis, thanks
Graham Neary's Investment Show - 18th October 2022 - YouTube
A “confident” trading update from Brickability (LON:BRCK) (I hold).
Thanks Mr C for these morning updates. They are a welcome start to my day, with a flat white of course :)
I will have liked this, having read it..
MrContrairian you have competition! :-)
https://twitter.com/andrewdc20...
Regards
Michael
Pithy!
It's not as good and it doesn't give names, only tickers. I can't remember all the tickers.
I was being tongue in cheek as Mr C was being criticised a couple of days ago.
Regards
Michael
Cambridge Cognition (LON:COG) wins £1.1 million 2year eCOA contract win for rare blood disease trial with existing major pharma client.
eCOA for clinical trials is a sizeable growth market, valued at over US$1bn per annum and growing at more than 15% according to market research.
It is not easy to understand eCOA so this is what it is:
' eCOA (Electronic Clinical Outcome Assessment) is a digital version of a COA (Clinical Outcome Assessment), which measures and records how a patient is feeling or functioning. It is used as part of a clinical trial to measure the efficacy of a health intervention.'
This contract win comes soon after COG's announcement last week of the bolt-on acquisition of eClinical for £1.7m.
Extends virtual clinical trial solutions
Expand VCT offering considerably in rapid growth market
Deliver strategic goal increase TAM
Additional customer base
Could add 5-15% revs 2023
There seems to be steady progress at this now well-managed, fast growing and profitable minnow with net cash of around 25%. With gross margin of 80% additional contracts make a difference.
The main bear point is that the shares are illiquid but if you are in for the long term, hopefully this doesn't matter. It is also possible that a contract is lost, although no large contract has been lost for several years now. Positively, COG receive a large payment at the start of contracts which is helpful.
I hold
Investegate |Cambridge Cognition Announcements | Cambridge Cognition: £1.1 million eCOA contract win
Investegate |Cambridge Cognition Announcements | Cambridge Cognition: Acquisition of eClinicalHealth Limited
in your opinion did Cambridge Cognition Holdings (LON:COG) win this contract by virtue of last weeks acquisition ?
joshwood976
No, the acquisition and contract are independent of one another.
Completion of the acquisition is not expected until 25 October 2022
Begbies Traynor (LON:BEG) red flag report makes for very sombre reading indeed, and can be viewed from their RNS today.
They talk a lot about debt and its effect on companies going forwards as interest rates rise, so companies with large debts should be avoided.
Sectors with the highest levels of distressed companies are
Construction
Support services
General retailers
Real estate and property services
Bars and Restaurants
Automotive
Other Manufacturing
Industrial Transportation and logistics
Food and drug retail
Telecommunications and Info tech
Financial Services
mmmm not sure there are many sectors left untouched...
Many cyclical sectors.
Capitalism working as expected. The survivors will benefit.
Yes FREng you are right, stock picking is key.
That's all then. Doesn't look like it..