Small Cap Value Report (Weds 2 Oct 2024) - SNWS, TPT, WYN

Good morning from Paul & Graham!
Interesting news from the BRC today, saying that shop prices are falling, down 0.6% for year to Sept 2024, a slightly steeper fall than -0.3% in the year to Aug. This might possibly help the Bank of England cut interest rates from the current excessive (in my opinion) level -
"Helen Dickinson OBE, Chief Executive of the BRC, said: “September was a good month for bargain hunters as big discounts and fierce competition pushed shop prices further into deflation. Shop Price inflation is now at its lowest level in over three years, with monthly prices dropping in seven of the last nine months. This was driven by non-food, with Furniture and Clothing showing the biggest drops in inflation as retailers tried to entice shoppers back. Food inflation edged up slightly as poor harvests in key producing regions led to higher prices for cooking oils and sugary products."
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
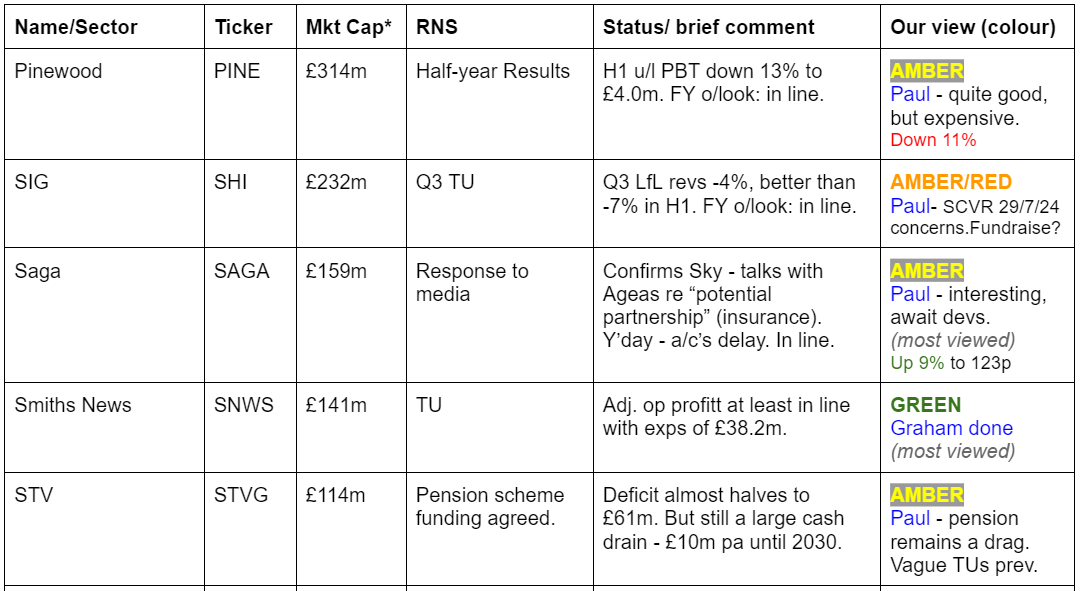
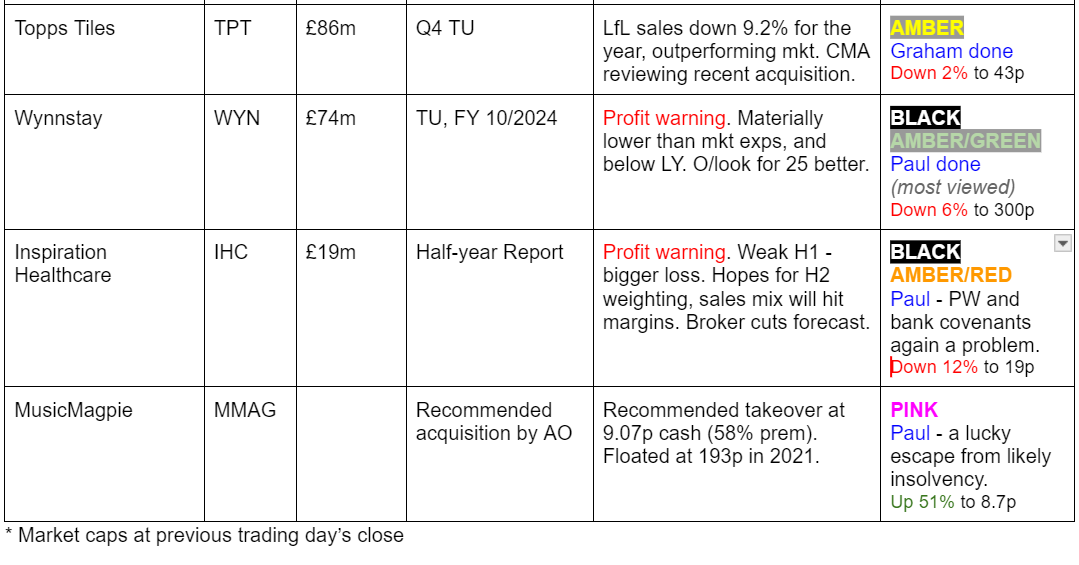
Summaries
Smiths News (LON:SNWS) - up 2% to 58.5p (£145m) - Post Close Trading Statement - Graham - GREEN
A positive update with performance described as “resilient” and “solid” at the UK’s largest wholesaler of newspapers and magazines. I like the valuation multiples on offer here even if it’s undeniably ex-growth and most likely facing a long-term decline.
Topps Tiles (LON:TPT) - down 0.5% to 43.7p (£86m) - Q4 Trading Update - Graham - AMBER
There have been no changes to Edison’s forecasts here. TPT previously warned on profits for FY Sep 2024 but with that year finished, investors can now reasonably look forward to a bounce in performance in FY25, boosted by a recent acquisition.
Wynnstay (LON:WYN) - down 6% to 300p (at 12:28) £70m - FY 10/2024 Trading Update [profit warning] - BLACK (PW) / AMBER/GREEN (on fundamentals)
Quite a nasty profit warning, with Shore reducing FY 10/2024 forecast earnings by a third. So the 6% drop in share price today strikes me as surprisingly lenient. The bulletproof balance sheet has probably acted as a shock absorber. Plus shareholders may be relaxed about holding, given the 20 year unbroken record of rising divis, and a near-6% yield. I still like it, but have moderated a notch from green to AMBER/GREEN, to reflect the profit warning and only a slight share price fall.
Paul’s Section:
Wynnstay (LON:WYN)
Down 6% to 300p (at 12:28) £70m - FY 10/2024 Trading Update [profit warning] - BLACK (PW) / AMBER/GREEN (on fundamentals)
“The Board of Wynnstay, the agricultural supplies and specialist merchanting group, provides an update on trading for the financial year ended 31 October 2024 ("FY24").”
Oh dear, it’s not had a good year unfortunately, with the seasonally important season having disappointed -
“As highlighted in the Group's interim results, reported on 25 June 2024, the outturn for the financial year was expected to be driven by the Group's performance in the second half. With more challenging conditions being experienced in seasonally important months, it is now clear that results for the financial year will be materially lower than current market expectations and lower than the previous financial year.”
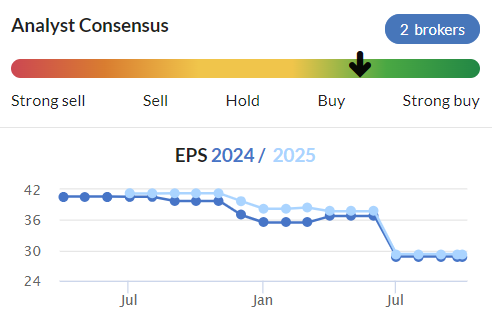
Forecasts had already been slashed, and will take another fall after today’s news -
Reasons given for weak performance -
Lower demand and prices for poultry feed. Farmers are being cautious, after heavy rains.
Outlook -
“The Group has a well-established market position and benefits from a strong balance sheet and good cash flows. While there are a number of headwinds in the short-term, the Board expects a better outlook for the livestock and dairy sectors and anticipates an improved financial performance in FY25 compared to FY24. The Group will continue to focus on operational improvements and efficiencies and continue to invest for the future.
The Board expects to announce its trading results for the year ended 31 October 2024 towards the end of January 2025 and will provide a further update on current trading at that time.”
Broker updates - Shore Capital helps us out with an update available on Research Tree. It’s really helpful when brokers provide a “Old” and “New” table for revised forecasts, which Shore does. It’s taken an axe to FY 10/2024 forecast, down from 37.9p to 25.2p (adj diluted EPS), down 34%. That also triggers a 28% drop in next year, to 27.3p, because broker spreadsheets tend to be based on year-on-year movements, so if the base year is dropped, all the following ones also drop.
Could this be low cycle earnings though? WYN does say that it expects 10/2025 to be better, but it only makes tiny profit margins, so the profit numbers are quite unpredictable.
Anyone who watches the brilliant Clarkson’s Farm has been educated into how difficult & problematic farming is (even more so considering Clarkson is a total clot! How much is put on for the cameras though?!), with weather, pests, and often onerous or even nonsensical rules & regulations making it a very difficult way to make a living.
Do we have any farmers in the house? If so, I'd love to hear your perspectives.
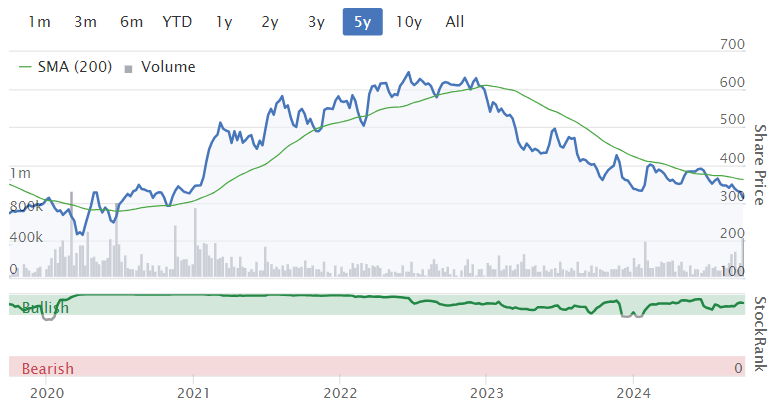
Valuation - I can’t justify a PER of more than 10 for this type of very low margin business, so I get to a price of 250p. The strangely resilient share price today (only down 6%, despite forecasts plunging by a third) to 300p strikes me as a bit too rich.
Balance sheet - this is a stand-out feature of WYN. The last balance sheet at 30/4/2024 is quite remarkable for a company valued at £70m market cap.
NAV was £136m, less £20m intangible assets, gives NTAV £116m. So you’re getting 40% of those net assets for free. However, given WYN makes a poor return on its assets, maybe it should trade at a discount?
It has about £12m in freehold property (note 16, last Annual Report) within fixed assets, plus £1.85m in investment property which is rented out.
Working capital is large, with £172m current assets (mostly inventories & receivables, but also £25m cash) at 4/2024.
All creditors (short and long term) total £101m, so you can see it’s a very healthy overall position, that might possibly attract a financial buyer who could maybe sell off assets, squeeze working capital down, gear it up a bit, and end up owning a business that almost paid for itself.
Does a strong balance sheet matter? I think it does, yes. As we’ve seen today, it’s a cushion. So even if trading is weak, a lot of investors won’t be perturbed because they know it’s so strongly asset backed. Hence a 34% drop in profit expectations today only triggered a 6% share price fall. I’d be surprised if that would have happened if WYN had a weak, geared up balance sheet.
Cashflow statement - nothing much of note, other than that it seems to have quite large swings in working capital, in the last year figures.
Dividends - Shore has not changed its dividend expectations for FY 10/2024, static at 17.5p - yield of a nice 5.8% - note the unbroken 20 year track record of rising divis, and of course the balance sheet strength to be able to afford generous divis, even in a bad year.
Paul’s opinion - this section has been a nightmare to write, as I’ve wasted most of the morning getting all the numbers muddled up, and had to start again, so sorry it took so long to write. Never mind. Can I stay at green, considering this is a hefty profit warning, with forecasts down by a third? I don’t think so, as we have to reflect reality. So I’ll trim back to AMBER/GREEN, because the 6% fall in share price today is not enough to make the shares look a raging bargain. If the share price had crashed to say 200p then I would happily have stayed at green. At 300p though, I think it might have got off a little too lightly on today’s bad news.
Fundamentally though, it’s an OK company, working hard to eke out a tiny profit margin each year, which is rather volatile.
Yet I expect long-term holders are probably quite happy with the reliable, rising, generous divis, and can wait out the weakness in its markets to improve.
Graham’s Section:
Smiths News (LON:SNWS)
Up 2% to 58.5p (£145m) - Post Close Trading Statement - Graham - GREEN
We have a “resilient” and “solid” H2 trading performance from this newspaper and magazine distributor.
Full-year adj. operating profit will be “at least in line” with expectations of £38.2m (last year: £38.8m).
Revenue growth for the year of 1.1% was boosted by various factors including an additional week of trading. Last year’s results were for the 52-week period ending 26/8/2023, while this year it’s the 53-week period ending 31/8/2024.
Since there’s an extra week involved, I would chalk up the real underlying revenue growth for the year as zero.
Cost savings: £5.6m of savings delivered, in line with budgets. At the same time “growth initiatives” are making an increasing contribution to profit. So it sounds to me more like a redirection of spending rather than anything else.
Refinancing agreement: the company no longer has to follow a dividend/distribution cap of £10m p.a., so more cash can be returned to shareholders. Paul mentioned this in his coverage in May.
Graham’s view
This is only a brief update - more detail will be provided in the full year results in November.
But for what it’s worth, I’m amazed at how cheaply this is trading.
Paul covered the key points in May, and I would highlight the following:
Results are clean, with few adjustments. Only a small gap between adjusted operating profit and actual operating profit.
Net debt fell to only £10m.
Mid single-digit earnings multiple.
This stock enjoys a perfect ValueRank of 99 (can’t get better than this) and a StockRank of 99, too.
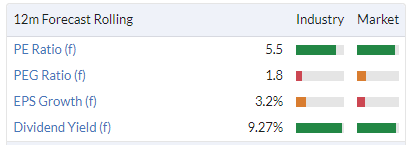
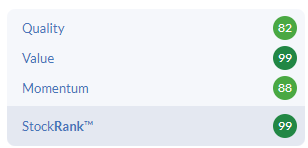
The market is apparently treating this as a “cigar butt” with only a few puffs left before it runs out.
I can’t deny that this is ex-growth and doesn’t deserve to trade at an above-average multiple. But at only around five times earnings, I’m a bull.
Topps Tiles (LON:TPT)
Down 0.5% to 43.7p (£86m) - Q4 Trading Update - Graham - AMBER
Topps Tiles Plc ("Topps Group", or the "Group"), the UK's leading tile specialist, announces a trading update for the 52-week period ended 28 September 2024.
We last looked at this one in April, when Paul was neutral on the day of a profit warning. FY September 2024 estimates were clobbered, but there were hopes of a rebound for FY September 2025.
Visually this is the trend in EPS estimates:
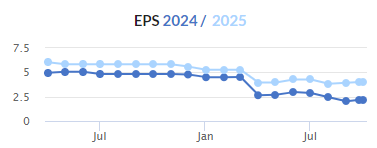
FY September 2024 is now over, and here’s the update.
Group sales (excluding an acquisition) of £248m, down 5.7%.
Like-for-like sales at Topps Tiles (i.e. online sales plus same-store sales) down 9.1%.
The year-on-year performance was slightly better in Q4 than in the rest of the financial year.
The trading environment was “very challenging” and TPT believes the wider market has declined by 10-15%, i.e. that it outperformed the market as a whole.
Acquisition - a recent £9m acquisition of a tiles company including 30 stores will be reviewed by the Competition and Markets Authority. This isn’t good news but I find it hard to imagine the CMA taking any action here.
CEO comment:
We remain focused on the delivery of our new Mission 365 goal [GN note: the goal to reach £365m of annual sales]...
"Looking ahead, macro-economic indicators point to a stronger market in 2025. While the timing and trajectory of the recovery remains hard to predict, we are confident that our clearly articulated and proven strategy will enable the further development of the Group in all market conditions."
Estimates: Edison has published a note this morning that makes no changes to estimates. For FY24, they are expecting revenues of £247.3m and adj. PBT of £6.5m. For FY25, they are expecting revenues of £294.4m and adj. PBT of £11m.
Graham’s view
I can’t get away from our existing stance that TPT is priced about right.
At a tax rate of 25%, £11m of PBT translates to £8.2m of adjusted net income.
Based on results from previous years, we can expect a large gap between the adjusted and unadjusted numbers.
But I’m not taking a bullish stance on TPT, so I don’t need to be too strict on the adjustments. I am just checking whether the valuation is reasonable and I think it is - it’s trading at about 10x forward earnings, if you allow the adjustments.
Stockopedia’s calculations roughly agree with me:
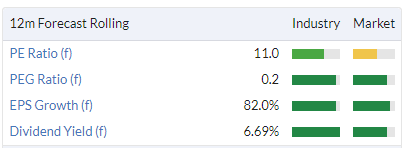
Net cash at the interim report was £19m. That will be significantly lower after the acquisition, but according to forecasts it should still be positive. So I don’t think I need to make any adjustment for valuation related to the balance sheet.
In summary: if you like this business and are willing to look past the earnings adjustments, you can make this valuation make sense. So I’m fine with a neutral stance.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
AO World (LON:AO.) - "Synergistic acquisition of musicMagpie" - link to research note: https://www.equitydevelopment....
AO has announced a recommended cash offer for consumer technology re-commerce leader musicMagpie. We believe this is an exciting opportunity for AO, given musicMagpie’s expertise and trusted brand in consumer technology re-commerce, with over 9m customer contacts. AO is offering 9.07p per share, equating to £10m cash and a c. £24m Enterprise Value which, in our view, represents good value at c. 0.2x EV/LTM Revenues and 3.4x EV/LTM EBITDA. Whilst we do not, at this early stage, forecast the consolidated profit impact of musicMagpie, we expect the acquisition to be value-accretive in the medium term.
AO is retaining musicMagpie’s senior management team, including its CEO and co-founder Steve Oliver and will work with the team to leverage synergies across the combined group. This will include benefits from a larger combined customer base and from enabling musicMagpie to leverage AO’s trade-in volumes of mobile phones and other electronics. AO will undertake a 6-month evaluation process post-acquisition, and we anticipate the acquisition will be value-accretive in the medium term.
Wynnstay (LON:WYN) It's a cyclical business so after 2 bad years, it will likely improve. Forecasts are down from c30p to c25p EPS are they not, so its down a 1/6th not a 1/3rd? I'm tempted to add a few more as its a reasonably high quality business. Feed margins are low but effectively cost plus so always profitable. The fertiliser business is very volatile. The stores are fairly steady. Anyway, the dividend is still well covered, so there should be a very small increase again this year. Balance sheet is rock solid.
Hi topvest,
No that's incorrect. As I mentioned, Shore reduced its forecast EPS by 34% -
The consensus forecast on Stockopedia was showing as under 30p so the brokers (only 2 of them) must have been miles apart which seems odd for this type of business?
Cannot believe Card Factory (LON:CARD) is now down at 99p just how much further can this drop?
I hope not much further. I bought back into today!
Card Factory (LON:CARD) It was trading between 90p to 100p for the best part of a year (before it rallied after Telios sold out). Can't stay I'm that surprised after the lacklustre H1 results and the risk they don't meet FY guidance.
Paul, Many thanks to you and others for your thoughts on WYN. I started buying in early 2021 as the company stock ratings shouted at me at the time. As I am an investor, not a trader and try and hold for the long term this is my worst-performing share since buying in including adding a few more today. One key positive IMO that nobody has mentioned is the RNS of 13.09.24. Alk Brand has been appointed CEO from 01.10.24. Whilst I have learnt painfully that supporting farmers doesn't necessarily translate to a company worth investing in with so many variables I see his CV as a real positive going forward. It might take time to increase ROE but I hope to continue to hold.
I just watched the live Interview with the Paul's - Great content as always Gents, !
Breedon (LON:BREE) supplies aggregates and cement, with a strong presence in the UK and Ireland, and is expanding into the US. Its exposure to housebuilding comes through related infrastructure projects. While the sector requires a lot of capital, Breedon's quarry assets are difficult to replace, giving them a solid local market share. Stocko stats and chart signals look pretty good at the moment.
The last Broker rating raised Breedon to a target price to 465p from 455p, Breedon qualifies for James O'Shaugnessy Cornerstone Growth
I have bought a medium opening position on today's drop in SP.
Thank you for your analysis on Wynnstay Paul, we do appreciate the dividend record while agreeing it's got off fairly lightly...so far...today. We will add a few more shares to our holding shortly and wait for the sun to eventually shine for farmers and suppliers.
Agreed; good summary; NTAV good with P/TB 0.64 ...
Even going back to last years numbers FCF yield still at a decent 15%.. .
I'm a fan (but not a holder) of Wynnstay (LON:WYN) -
For me to hold It would need to relocate to a country that doesn't suffer Polar/Artic/Martime/Continental weather fronts -all in the same week.
The shipping forecast always sounds like a horror story at the moment.
Solid State (LON:SOLI) up almost 15% on todays acquisition announcement.
Today is also the ex date of their 4 for 1 bonus issue. Happy holder.
https://www.stockopedia.com/sh...
Acquisition highlights:
· Gateway is a specialist in ferrite and magnetic components and solutions.
· Gateway has a range of own brand machined ferrite products which can be sold internationally and complement the Group's existing products and technologies.
· Gateway has a strong and experienced team who add specialist industry knowledge and expertise to the Group.
· Gateway has a long-standing customer base with an engineering and technology led approach, consistent with Solid State's model.
· The Acquisition provides Gateway with access to an enlarged sales force and customer base, enabling incremental mid-term cross-selling opportunities.
· The Acquisition is expected to be earnings enhancing, and accretive to the gross margin of the Components division in the first full year.
Acquisition consideration
The Acquisition will be funded from the Group's existing cash resources.
Hi
Can’t comment on the Solid State (LON:SOLI) acquisition though the market does seem to like it.
But the bonus issue is just a share split. There is no benefit to shareholders there aside from managements assertion that the share price is held back by a liquidity constraint so now they have 5* the number of shares in issue. Not sure I buy that argument, it’s not as though people are trying to buy fractions of £12!! Always think this is a waste of management time and resource - good for the broker that recommended it of course ;)
Anyway love the job management have done - used to hold from 400p up to 1400p and sold out there about 3 years ago as felt it would take time to grow into that valuation but probably looking interesting again - must look at Gateway and see what I think.
Pretty sure today's rise was driven by the 'bonus issue', most websites won't have updated their data (sharepad hasn't), so for the casual observer a 240p share price + an acquisition + a pre bonus issue EPS forecast figure of 65.5p would have looked very appealing indeed!
Not sure I see any reason for SOLI to attract a PE of over 20x on declining YoY growth, so expect it will be back at 235p soon.
Saga (LON:SAGA) would be a good UK fit for Ageas with their huge over 50s database as it looks to expand in Europe.
Ageas, which presented a new strategic plan in September, is aiming to capitalise on the growing demand for pension and savings products from aging populations in Europe and Asia.
Ageas declined to comment on the Saga partnership agreement.
Sky News, which first reported on the talks between the two companies on Tuesday, said that under the proposed deal, Ageas would make an up-front payment to Saga.
https://www.reuters.com/busine...
Restore (LON:RST)
Further to my recent post and IHT or not, I have this morning purchased an opening position at 244p. The relentless selling of he shares appears to have stopped, presumably as a result of IHT rumours and the budget. The document storage division, about 70% of revenue is recurring and very sticky. The other parts of the business are making progress, except perhaps Harrow Green, the office relocation division and operating margins are forecast to improve from 16.5% towards 20%. Debt is also starting to reduce.
Charles Skinner, the recently reinstated CEO knows the business inside out and has shaken it up, reducing the head office count from 50 or so to 7 together with other cost saving initiatives eliminating the hubris of his predecessor.
What really clinched it for me was the director buying; Charles Skinner bought 300,000 at 280p and Dan Baker bought 25000 shares at 271p. Directors especially CFOs don't splash the cash unless the business is heading in the right direction. One never knows it may become a bid target for the American company, Iron Mountain, the dominant player in this part of the market. Harwood is also a significant holder via Rockwood Strategic (LON:RKW)
IHT or not if the company performs the share price will follow.
Hi Jonno. I can only see that Charles bought 100,00 at 280p not 300,00 shares. See RNS dated 02/09/24. Am I missing something?
On the subject of interest on cash, and IHT, I have a question. Skip this if you object to off-topic posts.
As part of IHT minimisation, we give away almost all of our surplus income because, under current IHT rules, such gifts are immediately exempt from IHT so long as we maintain clear documentation of income and expenditure.. As we understand it (and have been advised) income from all sources can be counted in the calculation, including share cash interest and dividends in ISAs, even if the income isn't withdrawn but is reinvested.
Here's the question: are dividends and cash interest in SIPPs also allowable as income for this IHT exemption?
i suspect you'll need expert tax advice for this ,the SCVR board is awesome... but the level or risk potentially involved suggests getting advice from someone with lots of experience in this... innspite of the varied superlative skills of the stocko collective !
I suspect you might get variance from advisers around this point TBH.
We were told that income must be received to constitute income from which gifts might potentially be made. On this basis the returns within a SIPP wrapper must also not count.
Otherwise the key issues are record-keeping and that gifts must be "regular" as in a series of gifts, albeit of different sizes.
Hi FREng,
Do you have a template of your income/expenditure sheet? How much detail do you keep? Is it monthly or more often? tia
My wife used to do our company accounts, so she's good at detail. We keep bank statements on paper and annotate gifts to distinguishe "out of income" from Potentially Exempt Transfers (PETs). She has a spreadsheet that records expenditure monthly from bank statements and credit card statements, using the (small number of) headings in the IHT forms. She records our annual income and (as we have joint accounts and give gifts from income jointly) allocates 50% of income and expenditure to us each and shows the excess of income over expenditure.
It should make it easy to fill in the IHT forms when the first of us dies, and to explain the figures if HMRC challenges. Our.IFA agrees.
But please take your advice from someone qualified to affer it. We are not accountants or IFAs and this is just what we do and not general or specific advice - it may be wrong!
Schedule IHT403 (publishing.service.gov.uk)
This is part of the IHT 400 form and sets out the type of expenditure HMRC are looking for.
Monies generated within a SIPP be it interest or dividends would not count as allowable income. Some other forms of income such as a purchase life annuity would not count as allowable income as an element is deemed a return of capital.
Monies generated within a SIPP be it interest or dividends would not count as allowable income. Some other forms of income such as a purchase life annuity would not count as allowable income as an element is deemed a return of capital. HMRC tax manual provides further informtion
Thanks - are you able to tell me the reference in the Tax Manual? The guidance in the Pensions manual says (as I recall) that the definition of income isn't the same as HMRC's definition for income tax, but that normal accounting usage should be followed.
IHTM14231 and the following sections provide further information, there are also links to other relevant sections within the tax manual, such as income from discounted gift trusts. If you are in any doubt as to whether your income would qualify you may wish to contact HMRC. I hope the above helps
The section which references purchase life annuity is IHTM14250
Hi FREng if you don't mind me asking what are the actual records do you need to keep as proof of this bank statement from the day you start gifting out of income, a letter of wishes expressing what you are intending to do etc ?
Thanks
Andy
Does anyone know the following: I'm using iweb presently as my main isa trading / investing account. Unlike other commonly used platforms, cash balances (in the ISA) on iweb do not earn interest. Are there funds or equivalent which I can use to earn interest overnight / weekly whilst my cash is idling? Any suggestions would be very appreciated.
P.S. I tend to be quite active in trading so ideally an ETF or equivalent that provides daily return would be fab. Thanks in advance!
Dojosan, Lyxor Smart Overnight Return - IE (LON:CSH2) will likely fit the bill. Daily return.
JPM GBP Ultra-Short Income UCITS ETF - GBP (dist) (LON:JGSA)
PIMCO Sterling Short Maturity UCITS ETF GBP (LON:QUID)
iWeb allows JGSA and QUID, too. These don't use swaps; CSH2 does.
Thanks, Laurie!
Thanks WOSS!
Iweb is a bit fussy over what money funds it will accept. Royal London Short Term Money Market should be OK
Great - thanks!
A J Bell pays quarterly interest on overnight money in ISAs and SIPPs
Wynnstay
Seems to acquisition they isnt going to plan .
Very risky to put acquisition earnings into company forecasts too soon because they rarely go to plan.
Watch out for these golden acquisitions that are transformational such as mpac
They sometimes are indeed transformational but not in the direction anticipated
Integrating acquisitions is risky with at best a 50/50 success rate .
Wynnstay is a good dividend payer so Ill keep in my ISA but clip some out of trading account .
Not much point holding high yielding shares when the dividend gets taxed at lord knows what .
Im using the funds to buy a 6m zulu warrior statue
Planetx
I think the difference with MPAC (LON:MPAC) is twofold. Firstly they have a good track record of integrating purchases and secondly these businesses all stand on their own. Ie they are upstream and downstream of MPAC (LON:MPAC) current offering and are run by the founder owners of those businesses.
So whilst synergies, cross sell etc. are notoriously hard to predict there should be no real technical integration required. Those types of deals are usually much more successful than absorbing a business into your own.
MPAC (LON:MPAC) have a very well considered strategy from an acquisition perspective. Broker forecasts seem to only be including the ebitda on those businesses achieved last year yet both are considerably ahead of that in current FY.
Nothing is without risk of course, if it were there would be no returns either, but comparing Wynnstay (LON:WYN) with MPAC (LON:MPAC) is a bit magnums and mars bars……… (couldn’t resist the poor MPAC (LON:MPAC) joke…………)
Hello David
Agree with both yourself and Planetx on this theme of the difficulties of making acquisitions successful.
To add my two penny's worth, I spent a good chunk of my career as an FD in various private equity owned businesses which subsequently exited to trade buyers.
The only successful one of these was to an acquisitive plc with a minimal head office facility, whose acquisition strategy was to not change a thing about the acquired company but to help it grow in anyway they could. No attempt at ‘group integration’. They did their proper due diligence, especially on the people, so that they had total confidence in the business they had bought.
All the rest were failures because of meddling, diktats from on high and the destruction of entrepreneurial spirit whilst at the same time being flooded with large company corporatism including cost. Result :- management teams quickly got fed up, left and went on and started afresh elsewhere, generally in competition after their non-competes had elapsed. Performance plummeted and ill qualified head office appointees parachuted in to fill the void. Shambles ensued.
I was only commenting because if the fanfare mpac haf witj its acquisition.
At best 50% chance of going well yet no one highlights the perils in the exciting early days
Quite often its just people .
I know an outdoor company based in Derbyshire that bought a welsh one .
They soon hated each other and wasnt much to do with business .
I find a bit of a “pile on” mentality sometimes on stocko with everyone re/enforcing the positive vibes fanning the flames .
Card factory springs to mimd tecently .
Im being a bit brutal on my own portfolio right now and moving out of some previous strong holdings . i think the writing is on the wall for a lot of sectors /companies
Totally disagree on the 50/50 success statistic when it comes to listed businesses that are serial acquirers / rollups.
Off the top of my head, JDG, KITW, KWS, DPLM, FAN, ELIX & HILS have all made multiple acquisitions over the last 5+ years and continued to perform well.
Success depends on many factors, however experienced listed management teams have a much better than 50/50 record, primarily because they will know what they are looking for and how to execute.
MPAC don't have an experienced CEO, however the FD has been there for 6.5 years and successfully bedded in Lambert (acquired in 2019 for £15m and had 160 staff, £17m turnover) and Switchback (September 2020, $13m turnover). Both businesses have continued to trade under their own brand names, so have retained their identity. I am sure that is a large part of the reason CSi agreed to sell to them.
I think pretty pointless exercise listing a selection of 7 companies as some sort of proof that acquisitions are succesful in listed companies .
I think 50/50 is pretty generous and. Its probably much lower .
“Well, according to Harvard Business Review, between 70% and 90% don't quite make it across that elusive finish line. Imagine all those dreams dashed, market share hopes crushed under the weight of reality!
You might wonder why this happens so often; after all these are calculated moves by seasoned business leaders who surely know their art & science. It turns out there is a great deal more at play here than just number crunching or gaining operational efficiencies.”
i rest my case
According to the Harvard Business Review, the rate at which M&As fail to achieve their expected value stands at 70-90%.
Aiming Higher and planetx. Do either of you have a qualified source to back up your assertions on success or failure of takeovers? I don't and may have a faulty memory from Business School days but I'm fairly sure that our Lecturers were broadly of the view that the acquirer usually overpaid. Perhaps that was poorer quality management from the 70s and before.
Personal experience puts no greater confidence in large companies than small. For example Ronnie Halstead at Beechams bought a series of adhesives businesses, many household names at the time, and lots of cosmetics brands like Yardley. He didn't last long as they proved to be vanity projects and the 'strategy' highly questionable.
Beechams then successfully sold off their soft drink brands to the formative Britvic. The buyers paid through the nose to add Quosh and following the demise of that brand not long after had to pursue another expensive acquisition of the Robinson's brand from Colman's. 35 years later it may have worked out well....but I don't have the means to run the analysis as it wasn't always in the public domain as a single entity.
The easiest evidence to spot is on the new issues market where many suggest IPO stands for it's probably overpriced. Not the same thing I appreciate and I'd be very interested in any academic or financial institutions that could provide a quantitative and impartial assessment.
You certainly provide a interesting and more current list AH but it is selective and not quantified, IMO.
I did quote the Harvard business review .!
No statistics from my point of view, I just fundamentally disagree with taking a broad brush approach to M&A. I think assessing small cap M&A is similar to stock picking, whereas large cap M&A is infinitely more difficult due to the level of complexity involved.
This is the HBR article being referred to https://hbr.org/2011/03/the-bi...
Reading that article you can draw several conclusions;
1. LBM (Leverage my Business Model) M&A is far riskier; this is effectively buying a company to gain access to a resource which will make the existing business better & killing off the rest of the acquired business. This is rarely successful, due to some of the reasons outlined earlier by Lochinver.
2. RBM; "But a company can buy another firm’s business model, operate it separately, and use it as a platform for transformative growth. We call that a “reinvent my business model” (RBM) acquisition. As we shall see, there is far more growth potential in purchasing other companies’ business models than in purchasing their resources."
The MPAC deal is almost certainly an RBM deal, just as their 2019 acquisition of Lambert was. It's complimentary to their existing operations & intended to help the group fulfil turnkey projects, something they can't do at present.
If you want an example of an LSE company that in my opinion does LBM deals then look no further than THG. They went on an M&A spree in 2021, buying brands for their prestige & then almost certainly taking operational / strategic control from head office.
Every deal is different, the skill is in doing the DD & assessing the risk reward. I.e. Had MPAC funded their deal with debt rather than equity, I think the market would have taken a different initial view (as it did with the Iomart deal announced on the same day). However, Iomart also paid 17x Adjusted EBITDA whilst MPAC paid around 6x. Straight away those two facts tip the scales in terms of likelihood of success...
Niox (LON:NIOX) returning up to £21 million to shareholders via a tender offer this morning. Tender offer is 80p/share representing 21.9% premium to the weighted 3-month average SP.
Niox (LON:NIOX) returning up to £21 million to shareholders via a tender offer this morning. Tender offer is 80p/share representing 21.9% premium to the weighted 3-month average SP.
Have you seen anything new today? I thought the offer closed on October 15.
I find that offers like this create a dilemma: should I take a short-term 20% profit on some or all of my shares, or hold for potentially greater long-term gains?
I have just found out this morning from my broker.
For what it's worth, I tendered my entire holding and bought back the holding at 67.15p. Obviously, not all my original holding will be accepted, so my holding will increase.
Theoretically, the new SP post tender should reflect the outflow of £21 million so net net, there should be no difference, but theory and actuality rarely meet.
The other issue is I think NIOX will be taken over sooner rather than later, and you must ask yourself about the timing and motivation for this tender offer.
I also think Advanced Medical Solutions (LON:AMS) will be taken over at some point and I have a short-term position there.... only short term, as the declining ROCE (currently a meagre 3.6%) does not point to an excellent business with a significant sustainable moat. Niox (LON:NIOX) is the better business and I would like to hold for the long term, but I doubt I will be presented with that option.
Advanced Medical Solutions (LON:AMS)
AMS has some R&D and manufacturing based in Haifa (Israel, a mile or two from the oil refinery, 3 or 4 miles from the fuel depots for the airport and port, and 20ish miles from the Lebanese border). I couldn’t determine from the annual report what the financial impact on AMS might be if the Israeli operations were disrupted. To be clear, this isn’t a huge part of the total business, but it has financial ramifications and a serious disruption would lead to a profit warning. The risk statement in the FY23 report mentions Israel repeatedly; it is something management is thinking about and managing from both a business and humanitarian perspective. Balance sheet assets in Israel are only c £20 million.
I have asked Investor Relations some questions, but these were not answered. I imagine that it is complicated and quickly changing at a time when humanitarian concerns are paramount.
Reply from a friend re Advanced Medical Solutions (LON:AMS) Israeli operations:
"Looks like a buyout of a technion startup. The offices are at the technion where my father is prof ameritus and his wife in the.faculty. I have a friend who also has startups in bio glues.Not sure what the concern is. Their offices explode? My brother in law works for biotech in a more threatened area up north, work continues. The bottom line is I don't see a major risk, more like people are afraid seeing the news and headlines".
Google translate will translate this for you if you cut and paste:
אקזיט לטכניון: מפתחת חומרי האטימה הרפואיים סילנטיס נמכרה ב-25 מיליון דולר (calcalist.co.il)
The long and short of it is I am not too worried and as you say, the impact of AMS's balance sheet is not that material.
I have just found out this morning from my broker.
For what it's worth, I tendered my entire holding and bought back the holding at 67.15p. Obviously, not all my original holding will be accepted, so my holding will increase.
Understood. I tendered my basic entitlement of 6.2% at 80p and bought in the market at 67p. After dealing fees I will end up with the same number of shares and a few pounds in my account when everything is settled in late October, rather than doing nothing and having the same number of shares and no extra cash in my account.
Paul, any chance of a quick comment on JD. Sports - bigger than that normally covered but you do like to comment on retailers as a bell weather.
Interesting piece on the R4 today show this morning.
Rant alert
Obvs the UK is the sick man of Europe; 4 different obesity strategies in 10 years with 13 different Health Ministers in the same period.
The Result ? We're Going large. ( I mean that was literally an offer at Mcdonald's (NYQ:MCD) . Little wonder that Ozempic (Novo Nordisk A/S (NYQ:NVO) is growing.
But did not know from R4-Today that business confidence suffered the sharpest fall in September.
Lowest point since the pandemic.
I mean without an actual pandemic.
Maybe 16 different business secretaries in 16 years, 6 different plans for growth in 10 years, 5 business department reorganisations and 25 corporation tax changes- might add to the uncertainty?
Dunno. Just a thought.
Some say running a business is about 'Learning to dance on the shifting carpet'. But there's a difference between a shifting carpet and a monthly rug pull. It's exhausting.
Here's hoping for stabler times and for certainty which I imagine will come when the unicorns join hands with the pigs in the sky, GTA V launches (Take-Two Interactive Software (NSQ:TTWO going sideways until then) & all dogs have learnt to scuba dive...(it's a meme...)
Rant over.
And relax.
Does it coni side with the worst set of government ministers for the last 40 years?
Just a thought!
It's the same with skills further education ministers. I can't even work it out because the job title has changed.
It's Labour and their miserable messages / lies around the economy; that's the problem.
The Middle East situation does not make the governments decision to close North Sea oil very sensible!
It wasn't sensible before that.
sensible is a total contradiction when it comes to government
With respect, a decision to "close" existing sources and not awarding new licenses are not the same thing.
But a policy to invest in solar, wind, and nuclear, plus reinstatement of our gas storage facilities etc seems to be an extremely sensible idea.
Anyone else holding Virgin Finance shares/ old Clydesdale bank. I know it is not small cap .... the listing vanished from my IG account which I believe is because it has been acquired but I was expecting payment for my shares. Is there usually a time lag in this situation? Showing my inexperience here and appreciate any thoughts. Thanks
VMUK: Payment is usually 10 business days after the effective date. So I would be expecting to receive the cash on 15 October.
Many thanks , I will keep an eye out :-)
Live this afternoon at 2pm on Vox Exchange, I will be interviewing legendary UK smallcap investor Paul Scott .
It's sure to be another fascinating conversation - including lots of stock ideas such as #CARD, #SPSY, #OTB, #GMS, #BKS, #IGP, #GMR, #RNO, #FCH, #JDW, #BOWL, #JHD, #OSB and possibly even #POS if I can twist Paul's arm a little.
If you'd like to ask any questions, then please feel free join us here on Youtube.
Everyone is welcome.
G&T ready with the Twiglets.
The smell of Chicken Katsu slices is wafting thru the house …..
Paul is a legend
Live from the Mary Shelley or Greggs, or is it from a forecourt with a slice of pizza and the laundry?
I see Ireland are due to receive a big windfall from Apple and they intend to spend it on infrastructure and housing. Could give a boost to Cairn Homes (LON:CRN) ....https://www.cnbc.com/2024/10/0...
WYN I would be interested in what Paul had to say. I bought into this in Oct 2020 at 325p. Roll on 4 years and the price is 320p, and I think likely to get cheaper when the market opens.
When I bought it had a high stock rank and passed the Screen of Screens.
I'm in two minds about it now. On the one hand it's cheap, on the other hand, its growth (per share) has been anaemic. Meh, I'm not enthused.
I know there are some contributors here who are very familiar with Wynnstay (LON:WYN) and I would welcome their thoughts - as to whether anything in today's RNS changes their longer-term investment thesis, or whether they are happy to shrug it off as an inevitable bump in the road.
For those of us who like to buy things and potentially sit on them for a decade it has its merits although I've not yet been a shareholder , those who sell after profit warnings will of course disagree!
I suspect I am not the only one who has a list of AIM stocks to keep an eye on over the next month or two in case of IHT ructions (some of which is of course already priced in, but how long is a piece of string - you only need one careless seller to knock a stock in thin markets).
We are holders of Wynnstay Monty Carlo, it wasn't included in our recent de-risking ahead of the budget but should have been, I would have felt better about today's pw and have bought back in on the initial drop. As it is we will add when the price settles on a belief in it's balance sheet and the importance of farming!
The background for farming is the confluence of several things:
The weather has been disastrous
The pre Brexit farm subsidy scheme is being run down to zero, and a new set of land stewardship schemes are very slowly being released. Food farming, especially in uplands, has taken a huge hit to profits as a result. Sheep farmers are often trading below break even.
Grain prices are down at the same time as volumes grown are down. The depressed prices may be due to Ukrainian grain entering Europe instead of Africa.
Most people don't realise that the USA provides immense subsidies to it's low quality and intensive food producers. Something like $25 billion a year. And yet a lot of people voted for Brexit because of their perception that European support for farmers was a waste of money.
Wynnstay holds considerable stocks of fertiliser and the prices are dropping, leading to write offs.
So Wynnstay has been hit by a perfect storm.
I mystery shopped a store. It seemed very quiet but the manager said that lamb prices are up and store trading was down, but not that much.
I think that things may not get worse, but I'm less sure about when they'll get better.
I'm inclined to Hold but not Add.
Farming in the UK is in serious trouble and successive Governments have done little or nothing to help and have even made matters worse. I'm a long time customer of Riverford Organic, a real farm with an outspoken founder who gave away his shares to his employees such is his belief in what is best for the business.
You can read more on what is wrong here
https://stopfarmwashing.co.uk/...
Hope no-one minds if slightly OT but Wynnstay isn't the only business that suffers when farming suffers.
"The depressed prices may be due to Ukrainian grain entering Europe instead of Africa."
I heard about that. Traditional sea-faring routes were dangerous because of the conflict. Europe, in its benevolence, said not to worry, we'll transport it across land for you before it heads off to Africa. Only, they forgot the bit about sending it to Africa. Bit cheeky, that.
I don't know if darker motives are at play. The EU seems to have been particularly hostile to farming lately. Just ask the Dutch. Perhaps I'll leave the politics there for now.
My morning smallcap tweet: Magpie, take these broken wings and learn to fly.
Musicmagpie (LON:MMAG) One Heritage (LON:OHG) Equals (LON:EQLS) Tribe Technology (LON:TRYB) Saga (LON:SAGA) Wynnstay (LON:WYN) Westminster (LON:WSG) Topps Tiles (LON:TPT) Celadon Pharmaceuticals (LON:CEL) Time Finance (LON:TIME) Smiths News (LON:SNWS) Beximco Pharmaceuticals (LON:BXP) Minoan (LON:MIN) £PCH Inspiration Healthcare (LON:IHC), SIG (LON:SHI), Pinewood Technologies (LON:PINE)
◄musicMagpie (MMAG)► rec offer of 9.07p from AO World. A 58% premum for a co that looked like a bust [SP=6 Cap=6m]
◄One Heritage (OHG)► to buy 30% of owner of One Victoria project, OHPD for £3m. Will sell £7 of of completed residential and commercial properties. Axquisition is likely to constitute an RTO so co will will continue to explore its options regarding a transition to the Aquis Stock Exchange or the implementation of a Matched Bargain Facility or a complete delisting. [SP=5.3 Cap=2m]
◄Equals (EQLS)► you guessed it, a PUSU extension as the bidding Consortium has substantially completed its due diligence and negotiations between the Company and the Consortium are at an advanced stage. [SP=114 Cap=215m]. I hold.
◄Tribe Technology (TRYB)► good preliminary results from testing of reverse circulation sample system technology. [SP=3.75 Cap=9m]
◄SAGA (SAGA)► re press speculation - talks with Ageas with regard to a potential partnership arrangement for its Insurance business. [SP=111.4 Cap=157m]. I hold.
◄Wynnstay (WYN)► warns FY-Oct results materially lower than market expectations and lower than FY23 due to "more challenging conditions being experienced in seasonally important months". [SP=320 Cap=74m]
◄Westminster (WSG)► wins contracts worth over $1.2m to provide a range of security services to a major international services organisation. [SP=2.34 Cap=8m]
◄Topps Tiles (TPT)► guides FY-Sept rev down 5.7% (excluding CTD Tiles acquisition) and LFL down 8.2%. Q4 rev down 4%. "As previously announced, we believe that the market has declined by 10-15% year-on year, indicating that the Group has continued to outperform the wider market." In line? [SP=44.9 Cap=88m]
◄Celadon Pharmaceuticals (CEL)► wins £10.5m min five year order from a newly established healthcare company for the supply of its medicinal cannabis. [SP=24 Cap=17m]
◄Time Finance (TIME)► has renewed and increased its back-to-back invoice finance funding facility with NatWest to £65m. Total funding facilities available now over £225m. [SP=59.8 Cap=53m]
◄Smiths News (SNWS)► guides FY-Aug rev up 1% and adj op profit at least in line with market expectations of £38.2m. [SP=57.2 Cap=142m]. I hold.
◄Beximco Pharmaceuticals (BXP)► update on Writ Petition and Interim Order - Bangladesh appeal judge passed "No Order" and referred the appeal to a full-court hearing. [SP=24.5 Cap=NA]
◄Minoan (MIN)► £1.1m of loans exchanged into new convertible loans. Mostly interest free and convertible if SP exceeds 0.9p for seven days. 10% redemption or convert fee. [SP=0.52 Cap=4m]
◄Pacific Global (PCH)► new name and ticker for imitless Earth effective today. [SP=NA Cap=NA]
◄Inspiration Healthcare (IHC)► H1-July. Outlook -"As previously announced, we expect revenues for FY25 to be H2 weighted...sales mix will continue to impact gross margins and consequently earnings expectations for the full year". Not clear if this is a worsening. [SP=21.25 Cap=19m]
In line: SHI, PINE
Wynnstay (LON:WYN) results to be “materially lower” than expected. House broker suggests 12.5% fall in EPS relative to consensus but nearly 20% fall in PBT. Claims it is the trough! One to watch. If it holds above 300p on this then I reckon the bottom is in. But I wouldn’t be surprised to see it break below. There’s a buying opportunity here, but not sure that it is today as weather continues to confound farmers’ plans.
Farmers may get the rough end of the Labour stick while the peaks and valleys of weather has always been with us. I don't hold Wynnstay (LON:WYN) , too risky now.
There's an issue at the moment of an underspend in the budget for the last tax year - the fear is that the Treasury will expect to make this a permanent cut. This was under the previous government, which promised more to farmers post-Brexit. They delivered less. Labour's making the right noises, but only time will tell whether they stick to (or even improve on) what the last iteration of the previous government promised.
Nasty profit warning out of Wynnstay (LON:WYN) today, I hold, sadly. It annoys me that no guidance was given to PI's about what the likely result will be. EPS of 20 pence or below?
UK farmers are really struggling with the weather, reduced grain prices, and the complete tearing up of subsidies post Brexit.
I'm kicking myself for putting sentiment before investment sense.....
The only good news is the strong balance sheet.
Smiths News (LON:SNWS) reports "resilient trading". Oh no!!!
Smiths News (LON:SNWS) Opportunity to increase divis from above 9% currently!
Apologies if this article already got circulated but according to research reported in City AM:
My AIM stocks have definitely weakened lately having given up about a third of my profits for the year in the last few weeks.
Worth keeping some cash on the sidelines this month for buying opportunities I reckon.
Sorry forgot to include actual link (and I can't edit posts on the stockopedia app): https://www.cityam.com/london-...
Explains why Cavendish Financial (LON:CAV) is on a constant down trend ATM -24% this month.
Yes. On plus side it's now trading close to last tangible NAV of 8.5p and the only is surely up from here??
As it's also likely many IHT relief funds and individual qualifying companies will be shorted pre-budget Tortoise investor, we de-risked on Monday by selling several winners with the hope of buying them back cheaper post budget. We are now 60% cash. Wynnstay's profit warning this morning and a looming widespread Middle East war is not helping, we hold Wynnstay and watch in sadness the latter affecting millions of displaced people.
Saga (LON:SAGA) As posted elsewhere on Stocko and a little later than SKY News. https://newsfile.refinitiv.com...