Small Cap Value Report (Weds 21 Sept 2022) - ZOO, MOON, TEG, FDEV, ABDP, WAND, COG

Good morning from Paul & Graham!
Agenda -
Paul's Section:
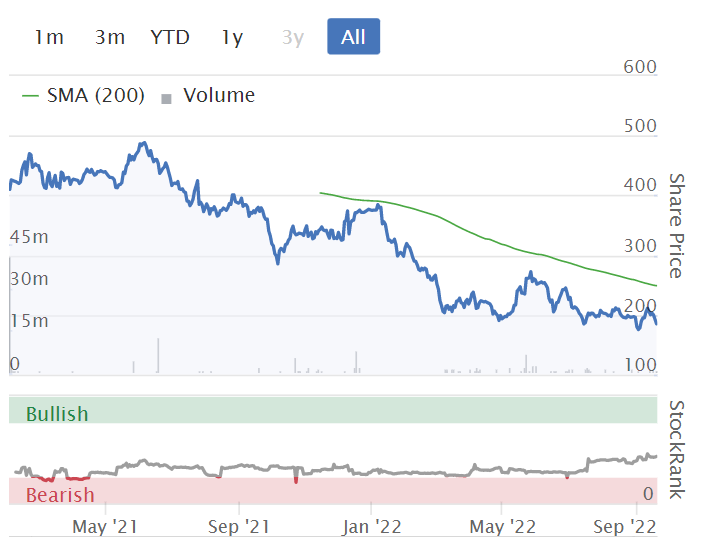
Moonpig (LON:MOON) - from yesterday. It's trading in line with previous guidance. Interesting that it doesn't seem to be having a problem with input cost inflation. The company reckons greetings cards are proven to be resilient in previous downturns, but personally I have my doubts. On closer inspection, and following a large acquisition, the balance sheet now looks over-stretched. I think MOON could have taken on too much bank debt, and overpaid for the acquisition, at the worst point in the cycle (as we go into a likely recession).
Ten Entertainment (LON:TEG) - impressive interim results. Liberum raises forecast profit for FY 12/2022 and the new forecasts don't look challenging, so I suspect it might out-perform again. Everything looks fine in the numbers, and the PER seems low - providing the "new baseline" of higher sales is maintained. The risk is that we're still seeing an element of pent-up demand, that could subside as consumer incomes are squeezed. On balance, I'm leaning towards a positive view of this share.
WANdisco (LON:WAND) - certainly not a value share, but the strongly rising share price, and a series of big contract wins with the same key customer, does suggest that something interesting might (at long last) be starting here. Continued heavy losses are forecast though.
Cambridge Cognition Holdings (LON:COG) [no section below] - I had a quick look at COG (I hold) shares yesterday, but didn't think there was anything much to say about them. P&L is a bit disappointing, with higher revenues absorbed into higher costs. Balance sheet look fine, as it gets paid cash up-front (at least in part). Order intake & outlook sound good. Probably priced about right for now, but a nice longer-term growth stock, with a strong moat. [no section below].
Graham's Section:
Zoo Digital (LON:ZOO) (£125m) (+11%) [no section below] - we covered this company’s results in July, and I suggested that Zoo finally, at last, had grown into its valuation. Today’s AGM statement and trading update confirm that the company continues to grow at a fantastic pace: H1 revenues +89% to at least $51 million (vs. H1 last year) which also represents growth of 17% sequentially (vs. H2 last year). The company expects “a significant increase in EBITDA, benefitting from operational gearing as the business scales”, with “a substantial improvement in our cash position”.
I’ve found this company’s public emphasis of EBITDA very frustrating over the years, as its EBITDA has typically not translated into net income and cash profits. However, with the help of operational leverage, it may have finally turned a corner and reached a point where the cash profits become meaningful - so that it might be able to start funding its growth plans without diluting shareholders. Or, even sending money back to shareholders for once! This share provides exposure to the secular trends of increased content streaming and the internationalisation of media consumption. Despite my long-term scepticism, I now think it’s easy to come up with bullish arguments for it, from this valuation. [no section below]
Frontier Developments (LON:FDEV) (£483m) - this video game designer and publisher releases full-year results. The numbers are tarnished by a significant impairment charge, as development work done on an existing title failed to translate into profitability. The future prospects continue to look interesting, however: the company has recently released a flagship Formula 1 game to good reviews. It has already successfully published Jurassic World Evolution 2 and a 3rd-party Warhammer game. Valuation isn’t cheap by any means but if it hits targets over the next two years it will start to look much better value.
Ab Dynamics (LON:ABDP) (£291m) (+4.9%) [no section below] - this company provides testing and simulation products to the transport industry (mostly car manufacturers). Today’s update is ahead of expectations: FY August 2022 is expected to see revenues of c. £80m, up +22% against last year, with healthy profitability thanks to a “robust margin performance”. A positive book to bill ratio gives the company good momentum as it heads into FY 2023. Additionally, the company today announces the £19m acquisition of a Norfolk-based provider of products for car simulation (testing driver assistance systems, autonomy, etc.). Max consideration is £32m, subject to performance.
My view: The rationale for the acquisition makes sense - good synergies with ABDP’s existing offering - and the company can afford the purchase, thanks to a strong cash balance. Overall, ABDP has a fine track record of profitability and it appears to be getting back on track after a couple of difficult years during Covid. Unfortunately, the shares are never cheap and the PE ratio remains in the high 20s or even low 30s. For this reason, I have a neutral view on the stock. The car industry in general is struggling: Ford shares dropped by 12% yesterday after it announced huge increases in costs and parts shortages. As an alternative to the car manufacturers, a company like ADBP might be a nice way to invest in the industry but without the same exposure to raw material price increases and supply chain problems. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Moonpig (LON:MOON)
185p (down 8% yesterday)
Market cap £633m
Moonpig Group plc (the "Group"), the leading online greeting card and gifting platform in the UK and the Netherlands… provides an update on its performance for the current financial year (commencing 1 May 2022) to date.
So that’s FY 4/2023 in the terminology we use here. I wish everyone would refer to financial years like this (including the month), as it saves having to check what it is, if companies refer to 2023, or 2022/3, which they usually seem to. Moonpig refers to FY23.
Overall, this is reassuring, although it doesn’t actually say what the guidance is! -
Overall trading performance is in line with our expectations and hence we reiterate existing guidance for the full financial year.
Other points -
Focused on greetings cards sales, which are proven to be “resilient across the cycle”
Average order is up (no figures)
Margins resilient (no figures)
Costs - very interesting, unusual, and positive - “... absence of any significant pressure from input cost inflation.”
Seasonality - is returning to pre-covid levels.
H2 weighting expected, with H2 forecast at 58-60% of full year revenues (worth bearing in mind when the interim results come out).
BuyaGift acquisition (announced in May 22, completed in July 22) - is a sizeable deal, at £124m (cash)
Guidance - a glaring omission from this latest update. I’ve had to waste time rummaging through previous RNSs to find it - this is from the FY 4/2022 results, published in late June 2022 - guidance for FY 4/2023 is -
- Revenue £350m
- Revenue growth expected to be mid-teens underlying, in medium term (that looks too ambitious to me, given the slowing economy)
- Margins expected to be resilient in short & medium term.
- Buyagift acquisition will raise margins further
- Adj EBITDA guidance is 25-26% (that’s nice, but EBITDA isn’t real profit)
My opinion - it’s good that Moonpig is trading in line. Although on closer inspection, I have 2 concerns with this share -
- EBITDA is not profit, or cash generation. If you inspect the last full year accounts, operating cashflow of £64m is then reduced by 3 real world outgoings, namely £9m tax, £8m capitalised development spend, and £9m interest (incl. leases). So free cashflow on that basis (a much more meaningful number, surely) is £38m.
- Debt - net debt was £84m at last year end of 4/2022. After that, a £124m acquisition was paid from cash. So that means net debt is probably nearer £200m now - about 6 years’ worth of free cashflow. That looks worryingly high to me, given that the economy now seems to be slowing.
Overall then, I suspect Moonpig might have chosen a very bad time to further gear up an already geared balance sheet. It looks like they might have overpaid for the Buyagift acquisition.
Other concerns are Royal Mail strikes, which Moonpig is emailing customers to say it might disrupt deliveries - not good for time-sensitive items like birthday cards/presents. Also, from the last 2 years's accounts, the company seems overly generous with share based payments to management. In a bear market, I can't be the only investor who winces with annoyance at Directors loading up with free or cheap shares, particularly when (as is often the case) the amounts look excessive, and share price performance is weak.
Personally, I only want to be holding shares in companies with really solid finances at the moment, due to the economic uncertainty. Moonpig is a nicely cash generative business, but nowhere near as much as the EBITDA numbers suggest. At some point, who knows when, banks might start to realise that measuring gearing on EBITDA is actually quite foolish, because companies cannot (long-term anyway) just stop paying interest, tax, and doing capex. Therefore why would we value companies on a multiple of EBITDA? It can make sense in some sectors, but for many other companies it doesn’t make sense at all - I would include Moonpig in that.
So with net debt probably now approaching £200m, and a balance sheet that’s now heavily negative NTAV, I think Moonpig is looking financially stretched, especially if people cut back on sending expensive cards & presents in the coming economic slowdown.
If none of that bothers you, and you only look at earnings, then MOON looks quite good value, on a forward PER of just over 13.
.
Ten Entertainment (LON:TEG)
199p (up 5% at 08:12)
Market cap £135m
Ten Entertainment Group plc ("Ten Entertainment" or "The Group"), a leading UK based operator of 48 bowling and family entertainment centres, today announces its half-year results for the 26 weeks to 26 June 2022. H1 19 has been used in some selected comparisons because it is the last H1 that traded for a full 26-week period.
Value for money entertainment driving sustainable growth in sales and profit
The company’s headline above, and repeated use of the phrase “new baseline” in the commentary today, is for me (and the market, judging from the low earnings multiple) the big question mark.
If TEG really has reset its baseline at sales 30% higher than 2019, then the shares are cheap. If however (as seems more likely to me), it is still enjoying a post-pandemic boost, and sales might slip back somewhat in future, then the shares are not necessarily cheap - it could be enjoying unsustainably high profits. That’s something you have to judge for yourself.
For now anyway, the figures are very good, e.g. -
H1 revenues of £63.2m
Adj PBT £15.7m - a very good profit margin of 24.8%
Adj EPS in H1 was 20.2p
In the past, pre pandemic, I see from the Stockopedia half year table, that there wasn’t any noticeable H1:H2 seasonal bias. Therefore, does this mean EPS in FY 12/2022 could be heading for double the H1 number, implying c.40p EPS?
Liberum (many thanks) has updated us today, saying that it’s factoring in some cost headwinds (e.g. business rates relief ending, wage rises, etc) for H2, hence it today increases forecast adj EPS by 8% to 30.0p for FY 12/2022 (on an IAS 17 basis).
My hunch is that the forecasts are probably still too low, given the strength of H1 trading, so the downside risk of a profit warning strikes me as low. In line, or better, looks more likely for the next trading update.
Good cashflows are enabling new sites to be built, and refurbs of existing sites, including enhancing them with new karaoke rooms.
The Liberum note also provides interesting background on TEG’s focus on value for money – it hasn’t raised prices for the bowling games since 2019. This means customers see bowling as an affordable treat, and it may prove resilient in a consumer downturn. Possibly, we’ll have to wait and see.
H2 trading has also been resilient, basically flat against strong comps from last year, on an LFL basis (+0.5%). That’s pretty good, considering the exceptionally hot weather this summer, when I imagine people would have not particularly wanted to go bowling, when sunbathing & beaches are a big alternative draw.
Energy costs - no need for TEG shareholders to worry, as they’re fixed to Sept 2024, at 2020 prices.
Dividends - 3p interim divi, and a forecast 6p final divi, so 9p total, a healthy (and rising) yield of 4.5%
Balance sheet - looks fine to me. I wish TEG would split out bank borrowings, and lease liabilities into separate lines. It’s such a bad presentational own goal, combining them. Nearly all the “debt” is actually lease liabilities, which of course are actually just future operating costs, which will be paid from future revenues & profit, so really shouldn’t be on the balance sheet at all. Net bank debt is negligible, at just £0.7m - so this is a very securely funded business, with very little dilution risk, even in a recession.
My opinion - this is a very interesting company, and indeed sector. So far anyway, it looks as if demand for bowling remains strong, and as an affordable treat, maybe that could continue? Refurbished sites, and widening the range of entertainment on offer, could be driving sustained higher sales. Or it could reflect an element of pent-up demand - now that we can get out & enjoy experiences again, after 2 years of restrictions, people are bound to relish the newly recovered freedom. Will that, longer-term, subside though? That’s the big question.
Overall, I think TEG shares look very interesting. The business is humming along nicely, generating plenty of cashflow, which is enabling it to self-fund refurbs and new sites, and now divis too.
As regards demand, we still have full employment, and households now know their energy bills are capped. So I can’t see why demand would collapse, for what is an affordable leisure activity.
On balance then, this share looks good value to me, and I’d be tempted to have a dabble at the 200p level, maybe holding back some cash to top up, if it takes another lurch down.
Note that, positively, the share count has only risen from 65m to about 68m in the last 6 years. A lot of profit & EPS growth has occurred over that time, so this looks a fundamentally good sector to invest in. Although increasing competition might, over time, reduce the high profit margins, possibly?
WANdisco (LON:WAND)
429p (up 6% at 09:32)
Market cap £293m
This share is about as far as you can get from a value share! Its track record is dire - minimal revenues, heavy losses year after year, repeated fundraises as it misses forecasts, etc.
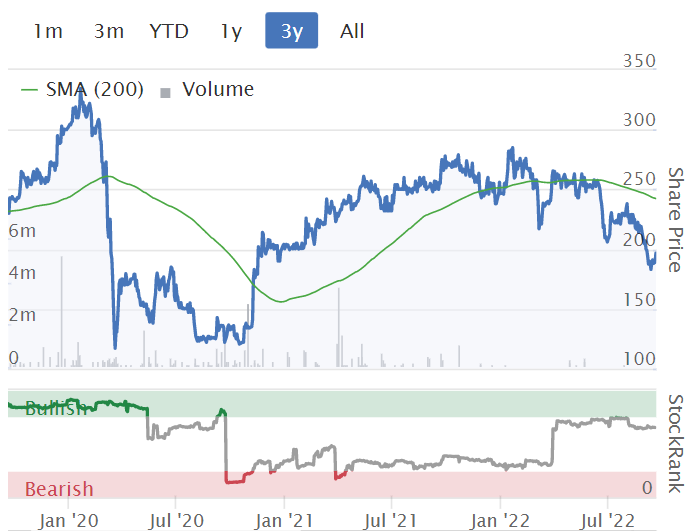
However, it’s one of those shares, where in the back of my mind, I think this could get interesting, if demand takes off. Could we be at that kind of tipping point this year? The last fundraising was done at a good price, and the chart has been doing something very strange - going up! Although there have been several false dawns before.

.
Record Contract, and Outlook Update
A “top ten global communications company” seems to have become of key importance, with another big contract won with the same customer. This one customer has now signed contracts worth $39.3m in 2022 with WAND. That must include the latest one, WAND’s biggest ever contract, of $25m. It doesn’t state over what period these contracts extend. If it were say 5 years, then that’s about $8m revenues per year, not a huge amount given that WAND tends to report losses of $20-40m year after year. However, if it’s the long-awaited start of properly commercialising WAND’s software into potentially huge markets, then this could get a lot more interesting. The £300m market cap already anticipates a much brighter future.
Overall -
Following this latest contract and our robust pipeline, we expect bookings for FY2022 to be significantly ahead of current market expectations."
That’s good, but do remember there’a big difference between bookings, and revenues (which tend to be much lower).
My opinion - Edison’s updated note this morning still forecasts heavy losses, but they’re hoping that up-front monies from contract wins might render another fundraising unnecessary. Although Edison’s own forecast shows WAND running out of cash again by end 2023. There again, with the share price soaring, and a market cap of £293m, I’d say raising some more cash now would be a smart move for relatively little dilution.
It’s impossible for me to judge WAND’s prospects, but just thought I’d flag up these material contract wins to anyone who likes speculative tech stocks!
Graham’s Section:
Frontier Developments (LON:FDEV)
Share price: 1,228p (+3%)
Market cap: £484m
Frontier Developments plc (AIM: FDEV, 'Frontier', the 'Company', or the 'Group'), a leading developer and publisher of video games based in Cambridge, UK, publishes its full-year results for the 12 months to 31 May 2022 ('FY22').
I covered this one in June, thinking that its risk/reward prospects for shareholders had improved considerably in recent years, for two simple reasons:
- The share price had come back to earth so that, overall, it had made little progress since 2017-2018.
- The company had grown revenues and profits considerably over that time.
The tricky feature of FDEV, however, is the lack of diversification. There are a handful of important titles and a few new releases each year or two, and they determine the financial fate of the company.
Results
FY May 2022 was a good year. Jurassic World Evolution 2 was well-received and the revenue result of £114m is in line with expectations which had previously been raised.
Operating profit is less impressive at just £1.5m, and it relates to the dangers of companies who capitalise development work. Sometimes, they realise that this work isn’t going to result in the profits they were hoping for, and you get large impairment charges. FDEV suffered a £7.4m impairment charge.
So if you are willing to give them the benefit of the doubt for the rest of their development spending, you could write up their operating profit result for the year to £8.9m.
The company also provides an alternative measurement of “cash profits”: adjusted EBITDA with all game development expenses expensed as they are incurred, instead of capitalised. This measure comes in at £6.7m.
As you can see, profits can be a matter of opinion and in the case of FDEV, there are at least three different numbers you can use for FY 2022. In coming up with a range of valuations for the stock, I’d be inclined to use the actual operating profit result (£1.5m) but I’d also allow for the possibility that future results will be impairment-free. In which case, the £8.9m number I came up with is more relevant.
Game list
Jurassic World Evolution 2 has been a hit with £60m of revenue in its first ten months after release.
Planet Zoo is still selling strongly with expansion packs helping it to generate almost as much revenue in FY 2022 as it did in FY 2021.
Elite Dangerous has missed expectations (resulting in the impairment charge) and the company also continues to sell copies of Planet Coaster.
F1 Manager 2022 was released in August and received a score of 8/10 from IGN.
Then there are the games which FDEV publishes but does not create. Among these is a Games Workshop (LON:GAW) title: Warhammer 40,000: Chaos Gate - Daemonhunters. This is the most successful 3rd-party game ever published by FDEV.
Outlook
There has been a “pleasing start” to FY 2023, and the Board is “confident” that it can deliver on analyst expectations for the year. Initial sales of F1 Manager are “strong, as expected”.
And they remain positive on the prospects after this year:
Over the medium term, the Board expects Frontier to continue to grow revenue by around 20% on average per annum, with any annual growth rate variability largely driven by the timing and scale of new releases in each year.
The CEO and Founder is stepping back to become President, but he says that he “will still be actively involved, retaining oversight and involvement in strategic direction and key external relationships”. It’s worth noting that he’s a 33% shareholder, i.e. he has fantastic alignment with external shareholders.
My view
As I said before, I’ve grown to like this company more over time, both as a company and as an investment.
As a company, it has delivered some excellent games, branched out into new genres, become a successful publisher, and lengthened the lifespan of its existing titles with lots of fresh downloadable content. Diversification is still far below what could be achieved, but it has certainly improved.
As an investment, the market for small-caps has become more discerning (i.e. cheaper) and the nosebleed valuation this stock enjoyed in 2020-2021 has been eliminated.
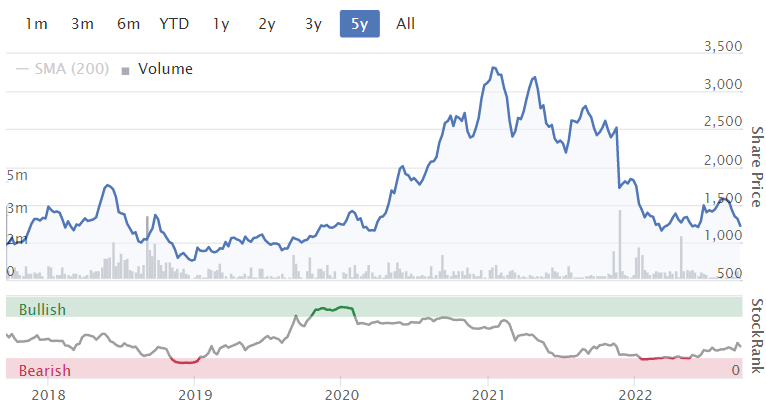
It still only gets a ValueRank of 10, but it at least has the possibility of giving investors a proper earnings yield this year or next year. According to forecasts, net income should come in at £17m this year (FY May 2023), with further improvements next year.
Overall I view this as a weak buy: the valuation still requires the company to achieve a lot in the next two years. In particular, it requires the Formula 1 game to be a big success, and it requires a long stream of paid-for expansion packs from existing titles. However, despite the stretched valuation, I have now come around to the view that FDEV has done enough to justify its premium rating.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

59 comments
Ten Entertainment (LON:TEG) (no position)
I'm a little late to this, but I thought I'd share a quick finding.
The yellow row below shows #customers/site/year.
The 168k I've calculated for FY22-H1 ties in with the 150k customers per week mentioned in the interim results presentation, so I'm going to assume that my 2019 and 2021 calculations here are also fairly accurate.
So it looks like footfall really has gone through the roof since 2019 (128k ---> 2022-H1 168k customers/site/year).
The company says this is a new baseline, but for prudence I'm assuming it slips back down to 128k customers/site/year in FY23 across their soon-to-be 54 venues (up from 48 at the moment.)
I've accounted for some price inflation (£15.98 --> £16.78 spend/head) and come to annualised revenue of £116m.
That's still excellent growth, but I fear that if maintenance/refurbishment capex continues at its current pace, then there won't be much left to fuel geographic expansion and/or pay a dividend without some share dilution or debt funding.
I'm going to continue to twiddle my thumbs here and no doubt miss an excellent buying opportunity.
A
Warpaint London (LON:W7L) I realise that you and Graham are wading through vast numbers of results at the moment (& doing a sterling job thank you) but if you have time I would appreciate you circling back to todays Interims results from Warpaint
They added a little more colour to the recent ‘ahead of expectations’ TU with more details on the US orders secured. In addition, there was an excellent webinar with the management team this evening at which energy costs were discussed & the current higher levels of inventory (seasonal & will reverse by year end)
Those who know me will recognise my question
Hi AstonGirl,
Absolutely, I'll put rings & asterisks around Warpaint London (LON:W7L) on my pad, as it's a share we very much like here at the SCVR, and have reported positively on several times this year.
Usual problem at the moment - about 15 companies reporting each day, and we can only generally look at about 5. When we do more, we get fewer thumbs ups, so readers don't seem to like being overwhelmed with large numbers of shares being reported on each day here.
I'm also trying to line up some more CEO interviews, but those take a lot of work behind the scenes to prepare for.
Looks like SThree (LON:STEM) might talk to me, and I'd like to also talk to Warpaint London (LON:W7L) - both interesting value/GARP shares, in my opinion (disclosure: no personal holding in either, currently).
Regards Paul.
Looks like SThree (LON:STEM) might talk to me
This might be an unconventional offer Paul, but I’d be happy to join you on that call with the CEO if you’re both amenable. I founded and ran a similar LSE-listed multi-disciplinary recruiter back in the 90s and since owned a prominent IT recruiter until I sold in ‘17. Might add depth to the operational detail - and I believe Timo Lehne is an operations, rather than a financial guy.
No probs if not appropriate :-)
A little surprised that no comment on the interim results announcement from Hostmore (LON:MORE) (down 18%+) in SCVR today given the previous discussions on this company and the associated £UBG I recall that the flotation of these two businesses out of the Electra Private Equity Investment Trust was viewed as badly handled and the result was a significant fall in value which has worsened dramatically. Using Paul's valuation model that was discussed at the time the valuation fo these two businesses combined implies an equivalent share price of 73p:
As the price of the Electra Trust was around £5.50 pre the demerger and as I understand it these were the only two businesses remaining in the trust this is close to a 90% fall in valuation. Even allowing for the mishandling of the demerger have conditions really deteriorated this much since the demerger or were investors misled by the valuation put on these businesses by the Private Equity managers? Would be interested to know what people think and have I missed something or interpreted things incorrectly.
A little surprised that no comment on the interim results announcement from Hostmore (LON:MORE) (down 18%+) in SCVR today given the previous discussions on this company and the associated Unbound (LON:UBG)
We had 14 companies on our to do list today (see below). We just had to pick the ones that looked most significant. A restaurant group saying demand was slowing shouldn't have been a surprise to anyone, so we thought TEG was more interesting, saying that things were going surprisingly well.
We cannot cover everything. Judging from the number of thumbs ups, readers prefer us to cover 4-6 of the more interesting companies.
Previous coverage doesn't matter. It's what is most interesting on the day, amongst what is, at the moment, a blizzard of news.
Thanks.
Actually, we can knock ITIM (LON:ITIM) off that list. I read the results this afternoon, and thought it looked disappointing, and was lucky to get away with a 19% drop in share price today. The story on that recent float, was that it was seeing good growth. But results today actually showed a big increase in costs, and profits disappearing. So I think we can forget about that one.
Ten Entertainment (LON:TEG) v Hostmore (LON:MORE)
Interesting to compare the operating profit per centre for TEG v operating profit per site for MORE for FY22 by using 1H22 run rates. I've done some back of fag packet calculations:
TEG operating profit per centre for 1H22 is £414k which equates to £38.9m for 12 months
MORE operating profit per site for 1H22 is £66k which equates to £11.9m for 12 months
Enterprise value of TEG is £137m giving a valuation per centre of 3.5x
Enterprise value of MORE is £55m giving a valuation per site of 4.6x
So, assuming 2H mirrors 1H and both businesses manage their cost headwinds, which they have indicated they will do, then Ten Entertainment (LON:TEG) looks more compelling.
I think there has been a profit warning at Strix - Strix (LON:KETL)
* STRIX GROUP PLC - MACROECONOMIC AND GEOPOLITICAL UNCERTAINTY LOOKS SET TO CONTINUE IN NEAR TERM
* STRIX GROUP PLC - ADJUSTED PROFIT AFTER TAX CONSENSUS FOR FULL YEAR IS ANTICIPATED TO BE IN RANGE OF £27M TO £29M
I *think* the original guidance was 31.5m
as at now, down 17%
Strix (LON:KETL)
Yes, that is a drop in expectations and the market is not impressed (memo to self - should have sold before 09 00):
There is a webinar at 11 30 next Wednesday. You can register here: https://www.equitydevelopment....
I was just about to ask Stocko for an easy way of seeing relevant announcements.
However as Strix (LON:KETL) was in one of my Folios and there is a "NEWS" tab that can be filtered for "ANOUNCEMENT"
... no need. One pleasant surprise at least.
One thing I do every morning is go to the "Today" tab around 07:10 and look for what news is in my portfolio.
Re Ab Dynamics (LON:ABDP) I've never been able to get my head around the valuation, good company though it is. Yes, it's a picks and shovels play on increasing automation in automobiles, but there are US equivalents with similar growth prospects whose valuations, unusually for the US, are far less intimidating. Mind you, they make crap cars over there ;-)
Ab Dynamics is more about using computers and virtual modelling for testing cars rather than automation in cars isnt it? (at least it was unless I've missed something!)
Ab Dynamics is more about using computers and virtual modelling for testing cars rather than automation in cars isnt it?
Yes but a high proportion of the the parts they are modelling/testing are the automated bits!
Morning,
Does anyone have any views on the pub group City Pub (LON:CPC) which released interim results this morning. Trading has remained resilient and it has a good freehold estate and trading well below its net asset value. Perhaps one to look at again for value investors?
Paul - would love to read a commentary about stocks on your watchlist (as I'm sure would other Stockopedia subscribers), on a less busy day for news.
This bear market is no fun, so using the time to plan where to invest when the green shoots start to appear - My view on this is when inflation starts to come under control and the FED signals that it no longer needs to be so aggressive with the interest rate hikes. Perhaps a black swan event, such as the toppling of Putin, would improve sentiment somewhat.
Bsharman - re your 'Swan' events, I think if Putin goes it is a "good 'black swan" . Putin goes nuclear, a nuclear reactor gets blown up or Putin is relaced by an even more extreme general are all bad 'black swan'. Markets would then really tank!
When everything else is so fragile, a big knock from the truly unexpected can have a disproportionate effect (and of course none of these are truely 'black swan' events because we know about them already.)
Morning Paul, if at some point you get some time may I please ask of you can have a look at Clean Power Hydrogen (LON:CPH2)
https://www.cph2.com/ is a new company - I'm keeping a watch on ITM Power (LON:ITM) too as these folks have a technology that supersedes theirs and has got a patent - could be a future big player.
Clean Power Hydrogen (LON:CPH2) Whilst a recent IPO and small compared to ITM Power, Cenkos do anticipate CPH2 being profitable in 2023 (£3 million), so worth looking at.
Have you all been keeping a close eye on Hydrogen shares? The profits for punters were all made 4 years ago in the big blast off, the dream time.
Since then they have largely been slaughtered. Why is that? They are not destined to achieve profitability for some years.
Ceres Power Holdings (LON:CWR) is the best performer, but for example ITM Power (LON:ITM) and the similar companies on the continent £NEL in Norway and £MCPHY have all sunk deeper and deeper.
There was a rise coinciding with the Glasgow Climate Change summit, but it was a short lived extension of the dream,, and those who invested on the back of that have had their fingers burned.
ITM Power (LON:ITM) is a great company but the government has put very little support behind hydrogen, and / or the time to reach fruition is much longer than simple people like me might expect. Certainly in the short term market we work in, they are dead ducks.
Hi ridavies
Sadly I concur with your views. I have watched and invested over quite a period in Hydrogen. UK, European and US.
I did, and continue to do so, quite deep research (I even read the EU Hydrogen report cover to cover) into the sector but conclude, at this point in time, the sector is too embryonic for me as a small investor.
With regard to green energy plays, I have directed my attentions to solar, wind, battery and biomass and these do seem to be performing quite well.
Regards
Howard
Hi Lee,
Sorry, but we're mainly value-focused here at the SCVR. So a blue sky thing like Clean Power Hydrogen (LON:CPH2) which seems to have almost zero revenues, but a £114m market cap, is not something I could give a view on.
Happy to listen to why you think it's great though, if you want to brief us.
We always keep an open mind, here at the SCVR. Occasionally blue sky stocks do deliver on their promises. VERY occasionally!
Regards, Paul.
Still unable to access research-tree.com despite trying on several different laptops. notice comes up as "may have changed web address" or "having issues on site".
Any suggestions would be helpful
Research Tree is working fine for me today.
Run your anti-virus software, just in case.
works fine for me too. One thing to possibly try is to delete all browser cookies related to research tree? Although the error messages you describe are a bit odd ... are you caching DNS entries somewhere in your local network?
Hi Paul
Thanks for the write-up on £MOON.
Just FYI, the year-end results put the post-acquisition net debt at 2.3x Adj EBTIDA, so £172.5m. The plan is for the combined business to deleverage below 2x by early 2023.
I also get to c.£50m of free(ish) cash flow for 2023, based on their forecasts, so gearing is planned to be 3-4x cashflow.
As you point out though, that's reliant on trading remaining on plan.
Cheers
Re Moonpig (LON:MOON) - Also worth comparing it vs old school £CARD for a contrarian thought. Although Moonpig are keen to trumpet their growing market share and dominance of the online card market, they fail to point out that >80% (of the singles card market) is expected to remain in physical stores where CARD is the clear market leader, with a lowest cost base from vertical integration. CARD is finally rolling together its card & gifting businesses onto a single platform online and developing a Click&Collect offer.
Given CARD's brand salience and mostly short leases which will enable it move into more prime spaces at a great time, it is still not too late for it to build a decent complementary no 2 online position (albeit far too late). Together with better filling the better retail space with complementary high margin categories (balloons, stationery, knick-nacs), this is a very viable overall business long term as high streets and retail parks evolve over the next few years.
CARD is still burdened by debt and will pay no divis until 2024 but it is now doing the right things and is arguably cheap. Having just checked, Stockopedia algorithms agree - CARD stockrank = 83, MOON = 47
I hold a little £CARD - no more only because there are so many consumer stocks on offer at the moment if you are willing to wait a couple of years.
RNS yesterday: Frasers Group ("The Group") today announces that Mike Ashley will not be standing for re-election as a Director at this year's Annual General Meeting and he will therefore step down from the Board upon the conclusion of the AGM on 19 October 2022. Mike Ashley will continue to be available to the Board and Senior Management in an advisory capacity when called upon.
Frasers (LON:FRAS)
M.A.'s son-in-law is the CEO.
For information only. I found it surprising.
It's just the way that Dynasty works today but still, if shareholders can find rewards good luck to them.
Results from Warpaint London (LON:W7L) look impressive. No position at present. Need to do some homework on the company. Thoughts?
I'm aiming to take a look at Warpaint London (LON:W7L) a bit later, probably this afternoon. It's one of my current favourite value/GARP shares (no position).
I'm at work again, so not much time to look through everything for Warpaint London (LON:W7L) . However I notice that cash has reduced by £2.4m since this time last year, anything to worry about there?
Good morning Paul & Graham, any chance of covering COG interim results from yesterday please?
Many thanks DH2.
Hi Dieselhead2 - sure, I did have a quick look at Cambridge Cognition Holdings (LON:COG) (I hold) shares yesterday, but didn't think there was anything much to say about them. P&L is a bit disappointing, with higher revenues going into higher costs. Balance sheet look fine, as it gets paid cash up-front (at least in part). Order intake & outlook sound good. Probably priced about right for now, but a nice longer-term growth stock, with a strong moat. That's the short version! Actually think I'll copy this into the summary section above, to save work.
Regards, Paul.
Hi Paul, thanks for covering. I noticed profit was only £20K, although Mathew Stork does say that that was what they had forecasted. There is still a nagging thought in my mind as to why the previous FD left the company without any explanation. I know that's history now. Hopefully some good growth to come and not at miniscule margins either.
I too am a holder.
cheers Paul, DH2.
Hi Dieselhead2
Re: (LON:COG)
The long-standing CFO Nick Walters (since 2013) decided to retire. He was replaced by Michael Holton who left after a very short spell. It seems to me the issue may have been that Michael just was not a very good fit but we will probably never know for sure. Nick Walters returned for the interim period until Stephen Symonds was appointed.
Last night I watched the #COG webinar with Matthew Stork and CFO Stephen Symonds. Stephen came across very well and the chemistry between the two appeared very good to me. Obvs this is only my opinion.
Also, the accounts at COG are clean and quite simple to understand.
Michael
Hi Michael, that's good to know and much appreciated. I must get round to watching the webinar.
atb DH2
Hi Paul, thanks very much for your thoughts on COG. I too noticed profits were only £20K! Although that's what Mathew Stork said they would be. I still have a nagging concern as to why the former FD left the company without any explanation. I know it's history and a new broom has taken over...Fingers crossed for some decent profit in the future on their new product offering with decent margins.
I am a holder too.
Atb, DH2.
Sorry to repeat my message, I forgot to 'refresh' the page and hadn't realised that I'd managed to have posted it first time! Doh!
Hostmore (LON:MORE) half year results look good to me saying it has seen a ‘strong improvement in revenues’ which rose by +147% over HY21. It says it has seen ‘both volume and customer spend per head increasing.’ Revenues were £98.5m with adjusted EBITDA up from £7.3m to £17.8m.
I'll be interested to hear Paul's thoughts on today's Hostmore (LON:MORE) (I hold) announcement which includes a £17m impairment charge.
11 am today, an Investor Meet presentation. Should be interesting, especially the the questions and answers at the end of it.
I'm disappointed with Hostmore (LON:MORE) results. Adjusted EBITDA of £17.8m seems fairly meaningless as it ignores the significant lease payments of £13m.
I note they had a chunky impairment charge of £17.8m and whilst this has no cash impact, it suggests a number of sites that are performing below expectations. The presentation today alluded to an expectation these would recover in time but we are talking years rather than months away. At the end of the days, there was cash paid out for these sites which have now taken a hit.
£14.7m of the impairment related to ROU assets and represents 13% of opening net book value of ROU assets. That's quite a material hit.
From a cash generation perspective, the Adj EBITDA translates into a cash outflow of £7.3m when taking into lease payments and working capital movements.
The webinar referred to having a strong balance sheet. However, removing Goodwill, ROU Assets and adding back lease liabilities results in a flat NTAV position. The webinar referred to a reduction in the net debt position but this was comparing the position at 1H22 with 1H21. In the 6 month period to 3/7/22, net debt has actually increased. Small point, but slightly misleading.
Unit economics aren't convincing either: there are 90 sites in operation. This results in revenue per site per month of £182k and costs (cost of sales + admin) of £171k. That's a £11k operating margin per site per month with more potential cost head winds to follow. I haven't looked at how competitors are faring and that would be something of value.
The webinar talk about a very experienced management team, but they have brought on 2 new hires: a marketing officer and a operational officer.
Overall, even at the battered valuation, I'm not seeing the opportunity here.
I have mixed feelings after watching the webinar today with Hostmore (LON:MORE) (I HOLD).I understand the effect of the economic situation we are in and that people are scared to spend money as much as they used to but I am concerned about the financials. CFO said that he agreed a new deal with the banks about the loans and he paid the leases up to December ( If I understood correctly). I think it is going to be a couple of years before the price goes north, sadly.
Another big Director purchase at Cake Box Holdings (LON:CBOX) I see - £208k spent by the CEO. This comes on top of £274k spent by the same Director (CEO) at end August.
I know a lot of people look to big Director buying as a sign of confidence, although as we've discussed before, there are pros and cons.
Good morning Paul,
The same person you are referring to has pocketed around £17m between September 2020-November 2021. I am not even going to check , if , and how much he has sold during the IPO process.
hi Paul - sorry I had missed the discussion. What are the cons to big director buys?
Director buys/sells - over confident, deluded, pressured or token'ish.
Morning !
Ten Entertainment (LON:TEG) interims out today. Stockopedia has EPS forecast at 26.9p for the full year, giving a p/e of 7x based on yesterdays price of 190p. But the interims show EPS already at 26.75p for the half year ! So if we can expect this to roughly double for the full year are we looking at EPS around the 50p mark ? Giving a current p/e of 4x ? Or have I missed something ?
Yes, had a quick skim and the interims look really good!!
Ten Entertainment (LON:TEG)
You are probably like me somewhat bowled over by the results here. They have had massive tailwinds here so I don’t particularly expect the amazing performance to continue - but they certainly seem in rude health operationally speaking - and even if they can’t match this performance going forward if costs shoot up and operational gearing does somewhat reverse (softening customer spending) it seems like they are well place d for decent self funded growth in profits (all other things being equal) from the extra sites they are adding.
Thanks for the heads up on Ten Entertainment (LON:TEG) - I'll be sure to take a look, leave it with us!
Galliford Try Holdings (LON:GFRD) Paul? big share buyback results out dividend up
Ten Entertainment (LON:TEG) trade and trade receiveables at 14.7million£s any idea why so high v revenue of 63million?
Ten Entertainment (LON:TEG)
davidalen77
trade and trade receiveables at 14.7million£s any idea why so high v revenue of 63million?
It will be amounts as flagged up today -details copied below - note balance sheet confirms the £14.7 mill is actually "trade and other receivables" - so prepayments accrued income and presumably other misc debtors will likely be parked here too - look at last annual report for more detail of what you can expect to find included in this number.
per company today
In H1 22 £7.0m has been invested in the existing estate through refurbishments and enhancements to the bowling equipment. This includes £2.1m of advance payments to suppliers for forward orders of critical equipment that have long lead times.£8.7m was invested in invested in estate expansion, with the acquisition andrefurbishment of Harlow and the building of Walsall, which will open at the end of September. £7.6m of this expansion capital is in respect of advancepurchases of equipment needed for our development pipeline and includes a payment in respect of monies held inescrow for a freehold acquisition that completed in July.
ok but those are payables not receiveable for £TEG
Ten Entertainment (LON:TEG)
It might be slightly confusing but those amounts most definitely are receivables - a payment to suppliers as an advance deposit (money has gone from them to suppliers this period) goes as a debit in the balance sheet (asset) as the money has left their bank account - in theory if the future transaction was cancelled they would be receive that money back hence why it is chucked in receivables - the entry will move from receivables to capital additions and possibly P&L expenses in the later accounting period