Small Cap Value Report (Weds 24 March 2021) - HAT, QTX, TUNG, BMY, SPE, TPFG, CTO

Good morning, it’s Paul & Jack here with the SCVR for Wednesday.
Timing - today's report is now finished.
Agenda -
Paul -
H & T (LON:HAT) - FY 12/2020 results. Resilient, but lots of moving parts. Bullet-proof balance sheet. Tricky to value.
Quartix Holdings (LON:QTX) - AGM trading update sounds upbeat, but valuation now looks sky-high
Tungsten (LON:TUNG) - loses a major client, but says pipeline is strong. Its track record is poor.
Bloomsbury Publishing (LON:BMY) - another ahead of expectations update. I try to work out what upgraded EPS might be.
Sopheon (LON:SPE) - review of FY 12/2020 results. Interesting company, maybe a bit too pricey given sluggish growth? (covid, and SaaS transition blamed)
Jack -
Property Franchise (LON:TPFG) - resilient results and an acquisition from this sensible estate agency franchising group.
Tclarke (LON:CTO) - improving outlook and ambitious 3Y revenue growth target from this low margin, low multiple engineering and services group.
Let’s start with some comments on a few of yesterday’s backlog items;
£H&T
286p (down 3% yesterday) - mkt cap £114m
Preliminary results for year ended 31 Dec 2020
There are lots of moving parts in these accounts from the UK's largest pawnbrokers. Reading through the commentary, performance in some activities were impacted by covid lockdowns, but the high price of gold greatly boosted profits from gold scrappage. Retail sales of jewellery have been strong. Demand for forex has been weak, due to reduced international travel. There’s also the uncertainty over the ongoing FCA review of High-Cost Short Term Loans, with the outcome now delayed to Q2 of 2021.
Taxpayer support has included furlough funding, and business rates relief, boosting “other income” by £3.8m. It looks like the company is pocketing these, rather than repaying them to the taxpayer.
Considering all the disruption from covid lockdowns, the overall result for FY 12/2020 looks resilient -
Profit before tax down 22% to £15.6m
Diluted EPS down 27% to 32.1p - giving a PER of 8.9 - which looks cheap
Divis of 8.5p (up 81% on 2019) - yielding 3.0% and with clear scope to raise divis in future, due to the strong balance sheet.
Receivables loan books are down sharply though, which means future profits are also likely to fall, as less interest would be earned on these loan books, e.g.
- Pledge book (for pawnbroking) was £48.3m at 31 Dec 2020, down 33% from a year earlier
- Personal loan book was only £5.9m, down 64.5% on end 2019.
Balance sheet - this is a stand-out feature at HAT, it’s outstandingly strong.
NAV of £134.5m includes £22.0m intangibles, so writing those off, NTAV is £112.5m - almost identical to the current market cap. It’s very unusual to see a market cap fully backed with liquid assets.
All the bank borrowings have been repaid, so there is cash of £34.5m, and no bank debt. Although as the receivables books are built up again once demand returns, then the company might see cash fall, and possibly dip into its undrawn £35m bank facility.
Overall, it’s absolutely bulletproof, and I’d say insolvency risk is as close to zero as you can get. Unless there was some kind of regulatory calamity, with a gigantic fine imposed, but that’s the only risk I can see. There’s no commercial risk at all, given that it owns the receivables books outright, and has £34.5m cash on top of that. This is an amazingly strong balance sheet.
Outlook - sounds uncertain at the moment, but seems poised to benefit from unlocking -
The extent to which social distancing and pandemic restrictions remain necessary will determine the pace at which the Group returns to pre-pandemic activity levels. A successful roll-out of the vaccine program will likely lead to increased demand for our services and will determine the extent to which we are able to rebuild our pledge book.
My opinion - neutral. I don’t know how to value this share, because earnings are quite erratic. It does look very cheap on a balance sheet basis though. Pawnbroker shares often look irrationally cheap, it’s difficult to see why the stock market would change its mind on that.
As you can see below, over a c.12 year period, the share price has ended up back where it started. Although there have been a good stream of divis over that time. So maybe it’s best to think of it as an income share, with little prospect of much capital gains?
.
.

.
Quartix Holdings (LON:QTX)
550p (up 8% yesterday) - mkt cap £266m
Quartix Holdings plc, one of Europe's leading suppliers of subscription-based vehicle tracking systems, software and services, issues the following trading statement ahead of its Annual General Meeting later today.
The Board reports that trading for the two-month period to 28 February 2021 was consistent with meeting market expectations for the year*.
* The Board believes that consensus market expectations for 2021 prior to this announcement, were as follows: Revenue: £25.6m; Adjusted EBITDA £5.1m; Underlying Free Cash Flow (before expenditure on 3G swap out in the US - see 2020 Annual Report): £4.0m.
Useful footnote, thanks.
EPS forecast from Finncap is for only 8.2p in 2021, down from 13.6p adj EPS in 2020, which is due to increased overheads to drive top line growth. The PER on 2021 forecast is 67.1 times. How that makes sense, I have no idea.
Clearly the market is not valuing this share on a PER basis at all any more.
The strong progress seen in the second half of 2020 has continued into 2021. New subscriptions in January were somewhat impacted by the national lockdown in the UK, however activity levels increased in February and this momentum has continued into March. As such, Management estimates that the Group will achieve growth of 6% in the first quarter of the year (circa 12,450 subscriptions versus 11,768), despite being down 4% after the first two months of the year.
International growth is showing good progress, from a low base.
My opinion - an encouraging update. The market clearly likes the potential from international expansion, and is putting a big premium on that.
It’s way too expensive for me now, although as stated before many times, I do like the recurring revenues, strong cash generation, and divis. The growth rate would need to considerably accelerate to justify a £266m market cap though.
The rocketing share price & super-high PER just don’t seem consistent with the history, or the current forecasts (lighter blue blobs) -
.

.
Tungsten (LON:TUNG)
30p (down 19% yesterday) - mkt cap £38m
Tungsten provides accounting software.
It is going to lose a customer that accounts for 5% of revenues. Total revenues have been flat-lining around £36m p.a., so that implies about £1.8m in revenues from this one client, quite a hefty hit to take.
It’s not immediate though, an extension to April 2022 is being executed.
Andrew Lemonofides, Tungsten's Chief Executive, commented: "We are disappointed to be advised of this decision and to be losing an important customer. However, we have a healthy pipeline of new business opportunities and will concentrate our efforts on replacing the volume relating to this transitioning contract over the coming 12 months."
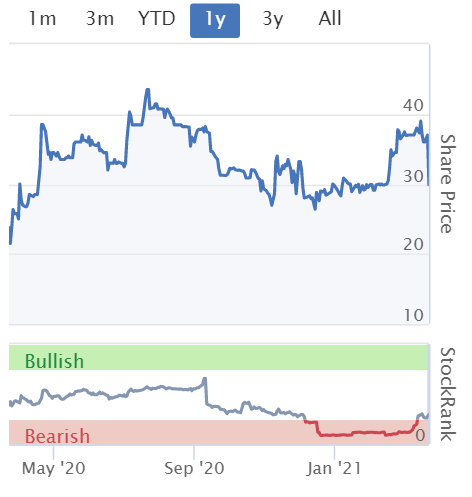
My opinion - a hit of 19% to the share price seems quite savage. Although as the chart shows below, it’s only giving up recent gains.
This announcement does call into question whether Tungsten’s product is good enough though? If a large client is going through all the rigmarole of taking 12 to 18 months to transition to a different system, then it might suggest they’re not happy with the existing Tungsten system maybe? Although there can be other reasons for changing software, so I’m speculating there.
Overall, I don’t rate Tungsten. It’s spent years struggling on, paring back huge losses to smaller losses, restructuring, etc. It’s difficult to see any appeal to this share. Why get involved then?
The last reported balance sheet was weak, with NTAV negative at £(10)m, and a current ratio of only 0.44 - therefore I think the risk of another fundraising, and more dilution for shareholders, look high. Who would want to put more money in though? The story feels very stale now. Maybe a sale of the business to a competitor might be the best option, as it doesn’t seem to have worked being a standalone listed company since Oct 2013.
.
.
Bloomsbury Publishing (LON:BMY)
268p (pre market open) - mkt cap £225m
There are lots of really dull companies updating us today, but this one stands out as interesting, hence why I’m covering it first.
Last time I looked at this book publisher was here on 29 Jan 2021, when the company put out a positive update, informing us that profit for FY 02/2021 would be “well ahead of market expectations”, with a lovely footnote saying that adj PBT of £12.1m was consensus market expectations.
In the absence of any available broker research, I worked out manually that BMY looked to be heading for around 15p EPS for FY 02/2021.
Today’s update - better still, it says -
Trading significantly ahead of upgraded expectations
Bloomsbury announces that revenue is expected to be ahead and profit significantly ahead of upgraded market expectations* for the year ending 28 February 2021. This surpasses the guidance provided in our statement on 29 January 2021.
* The Board considers current consensus market expectation for the year ending 28 February 2021 to be revenue of £171.0 million and profit before taxation and highlighted items of £14.8 million.
To summarise then, adj Profit was forecast at £12.1m, guidance was then raised to £14.8m in January 2021, and is now being raised again! Significantly ahead of £14.8m, so what does that mean? Last time they said “well ahead”, which turned out to be a rise of £2.7m in profits. Is significantly ahead ahead of well ahead? Isn’t this ridiculous! Why don’t they just give a figure! Or a range, e.g. between x & y. Or approximately x, subject to audit adjustments?
We have to guess what profit might be. Let’s use a similar increase to last time, so maybe £17m adj pre-tax profit? Take off 20% corporation tax, and that’s earnings of £13.6m. To complicate things, the share count has gone up due to a placing, from 78m to about 84m, so let’s take an average of say 81m, which gives my estimate of 16.8p EPS. That’s only an estimate remember, so could be wrong.
Valuation - at 268p per share, I make that a PER of 16.0, which looks about right to me.
Balance sheet - checking out the last one as at 31 Aug 2020, it looks excellent, so this group is very soundly financed.
Reasons given & comment on the profit upgrade.
- Lockdown - Feb 2021 saw an “exceptional sales performance”
- Not known how reopening will affect consumer behaviour (hence not known if surge in profits is sustainable, or a one-off)
- Digital - strong demand for academic publications
- Net cash of £54m at 28 Feb 2021 (up from £44.1m at end Aug 2020) - looking at options for investing the cash pile
- Modest taxpayer support of £63k furlough has been repaid - well done
My opinion - very good indeed. There could be some upside on the share price, but not a huge amount in my opinion. I can’t see that a book publisher would sustain a PER above say 20. It’s 16 at the moment, and has benefited from lockdown, so maybe 10-20% upside? Not madly exciting. Still, it’s a very solid company, with a lovely balance sheet, trading very well. There’s a lot to be said for that.
.
Sopheon (LON:SPE)
865p (down 3% at 09:34) - mkt cap £91m
Sopheon plc, the international provider of software, expertise, and best practices for Enterprise Innovation Performance, is pleased to announce its results for the year ended 31 December 2020, in line with market expectations, together with an outlook for the current year.
It’s useful when the heading explicitly states how profits compare with market expectations, as above.
SaaS transition is a key theme with this share - i.e. like many software companies, it’s gradually shifting from one-off licence fees, to annual recurring revenues. That results in lower revenues in the short term, but a higher quality recurring revenue base gradually building for the long term, providing greater forward visibility and lower risk of profit warnings.
The trouble with this, is that it makes the business look ex-growth, and the transition takes about 5 years, which is a long time to wait for growth.
Plus of course covid is bound to have had some impact in 2020.
· Revenue of $30.0m, maintained in the face of challenging year due to COVID, whilst embarking on a SaaS transition (2019: $30.3m)
· ARR1 rose from $15.9m at the start of 2020 to $18.0m at the end of the year
As you can see above that means the run rate of recurring revenues is now about 60% of the total.
Visibility is indeed improving -
Full year 2021 revenue visibility2 is now at $24.5m (last year at this time: $21.2m)
Profit before tax is only $1.7m (down from $2.5m in 2019) - that doesn’t seem much for a company valued at £91m.
If you want a higher profit figure, then here it is - adj EBITDA is $5.9m (down from $6.4m in 2019). Capitalised development spend was $3.66m in 2020, so that burns up more than half EBITDA. Hence EBITDA is meaningless, and not a true cash generation number at all, as is the case at many software companies.
Cashflow statement - after all costs, SPE added $2.3m to its cash pile in both 2020 and 2019. Of that, note that 2020 benefited from a $845k favourable forex movement. Dividends are de minimis at only $430k in each of the last 2 years. Overall it’s not bad - the company is self-funding a big R&D effort, and adding to its cash pile each year.
Impressive client wins, so there’s no doubt this software must be good -
10 new customer wins including DuPont, LG, Hochland, Clif Bar and Mondelez. Six of the new customers signed had deal values over $1m.
Sales & marketing expense of $9.1m on the P&L seems very high. That's consuming 43% of gross profit. Why would this be so high, given that overall no revenue growth has been achieved in the year?
Churn looks fairly low, with “gross retention” of 91.5% (down on 94.2% in 2019), improved from H1 to H2. So it sounds as if a few clients ditched the product to save money during the covid first wave.
Outlook - a bit vague, but the good visibility for 2021 is the main point, and reduces the likelihood of a mishap -
Although SaaS will dominate new deals and represents our future, I should emphasize that we fully expect to continue to sign some perpetual licenses, driven mainly by existing customers. Adding our year-to-date license sales and consulting services backlog to ARR takes overall revenue visibility for 2021 to $24.5m at the time of this report, compared to $21.2m a year ago. With this solid revenue base already in place for 2021, plus our strong balance sheet, a superb customer base and a team of great people - I am confident that Sopheon has a great future. We also continue to believe in sharing success with shareholders, and I am therefore pleased to announce that we will again maintain our dividend at 3.25p per share.
M&A - says it is actively researching (takeover) opportunities. This makes sense - if you have cash, and expensive paper, then it makes sense to buy in some growth, when there’s only limited organic growth.
R&D spend is noticeably large, which is a good thing in my view, as it should drive future growth & competitive advantages. $5.9m R&D is expensed through the P&L. Hence you could argue that’s why operating profit is low at only $1.78m.
Balance sheet - really excellent, this is very safe - a strong balance sheet, combined with high recurring revenues creates a really comfortable position.
There’s a $21.7m cash pile, with no debt. In fact the cash pile is more than enough to pay off all creditors, over 3 times! What a lovely position to be in, the CFO has a very pleasant job!
My opinion - tricky one this. I can see what the bulls like about this share - a great client list and lowish churn suggests a very good product, hence lots of growth potential.
Trouble is, the growth isn’t enough to excite me. That might have been impacted by covid, and SaaS transition is a factor in slowing headline growth, but even so revenues have barely moved in the last 4 years.
It’s profitable, but not hugely so, hence the share price is anticipating several years’ growth, if we try to value it on a PER basis.
I know that the market is not valuing software companies on a PER basis at the moment, but will that last? We’ve seen in the past what happens to fashionable sectors that hit a brick wall and valuations reset downwards. I still remember 1999-2002, it was carnage. That’s why personally this time I’m avoiding chasing up valuations to levels that I can’t justify.
For me personally, I think the valuation of SPE factors in too much future upside, but I do like the company & can see the potential.
Note there are 2 broker updates available today, from Finncap and Progressive.
Surprisingly perhaps, for a popular tech stock, the 3-year chart below shows it’s only see-sawed sideways overall. Middling StockRank.
.

.
Jack’s section
The Property Franchise Group (LON:TPFG)
Share price: 227p
Shares in issue: 25,822,750
Market cap: £58.6m
Property Franchise (LON:TPFG) is now the UK’s largest multi-brand lettings and estate agency franchising group. There are a couple of other listed players with a similar business model - Belvoir and M Winkworth come to mind - and all of them have attractive quality metrics due to the high-margin, low-cost, and cash-generative nature of this business model.

The big news at TPFG is the recent completion of the cash and share offer of Hunters on the 22nd of March. It’s quite possible that the past year has opened up a range of M&A opportunities for stronger operators in the real estate agency operations industry. Foxtons has also signalled its desire to find acquisition candidates here.
In fact it looks like perhaps the move has been a bit of a catalyst for the TPFG’s share price recently.

The management at TPFG are a prudent bunch, so I’m hopeful that this recent acquisition is a good cultural fit.
Highlights:
- Network income up from £93m to £94m,
- Revenue up slightly from £11.4m to £11.5m,
- Managed Service Fees (MSF) down from £9.7m to £9.4m,
- Tenanted managed properties stable at c58,000,
- Sales agreed pipeline at year-end almost double December 2019 at £10.3m (2019: £5.2m)
- 11 assisted portfolio acquisitions by franchisees, adding 1,305 managed properties
- strong balance sheet, with net cash of £8.8m at the year-end (2019: net cash £4.0m)
FY20 was a volatile year for the estate and lettings agency industry given the period of full closure and subsequent restrictions in place for the remainder of the year.
The group says that the stamp duty holiday has had a positive impact on underlying activity levels, but extended lead times mean that this surge of activity will largely flow through into fees in early 2021.
Hunters acquisition
TPFG provides some useful info into Hunter’s trading for FY20 as well:
- Network income increased to £43m (2019: £42m)
- Adjusted revenue decreased by 4% to £12.5m (2019: £13.0m)
- Management Service Fees of £3.4m (2019: £3.2m); 64% Sales and 36% Lettings
- Average branch revenue of c.£207,000 (2019: c.£205,000)
- Tenanted managed properties of c.15,000 (2019: c.14,000)
- Sales agreed pipeline increased 84% to £17.3m (2019: £9.4m)
- Improved balance strength with zero net debt at the year-end* (2019: net debt £3.2m)
TPFG acquired Hunters for around £24m. With £12.5m of revenue that values it at c1.9x sales compared to TPFG’s much loftier sales multiple of 5.17x. TPFG has more of its business in lettings though, which is more resilient. Still, I would imagine this is a good price to pay relatively speaking and is probably better value than the group’s Ewemove acquisition, which drew criticism in some quarters.
TPFG hopes this acquisition will ‘supercharge [its] expansion plans’, and it looks like both the group and Hunters have performed well given the circumstances. There were times last year when it looked like there could be a market crash, so broadly stable revenue and a meaningful acquisition is a creditable result.
Conclusion
The extension of the stamp duty holiday announced in the March 2021 Budget and the intended easing of lockdown restrictions should bolster trading over the coming months. The stamp duty is an artificial dynamic that should be monitored though, and its removal is a risk to business.
That aside, TPFG has made it through a tricky period relatively unscathed, and now the outlook actually sounds quite positive.
The strong pipeline and momentum generated through late FY20 has continued into the current year and TPFG and Hunters both came into 2021 with sales agreed pipelines in their networks up more than 80% on the end of the prior year.
As a result, at the end of February 2021, the sales agreed pipeline had only reduced by 6% since the end of 2020, when they were at record highs. Sales agreed pipelines have also started to convert into completions at faster rates.
TPFG is a sensible, high quality, profitable operation with a track record of underlying growth and plenty of scope for steady expansion. You can probably make similar comments for Belvoir and M Winkworth, too.
The recent acquisition adds a point of difference though, and increases TPFG’s scale: now the portfolio of managed properties stands at c73,000 properties. Uncertainties remain in the outlook but, external market considerations aside, the pipeline is robust and integrating Hunters could provide another growth lever going forward.
At 18.6x TTM earnings, TPFG is not obviously cheap and it might not shoot the lights out in future, but I think it can grow steadily and is worth considering as a solid, longer term quality hold.
TClarke (LON:CTO)
Share price: 103.7p (-1.71%)
Shares in issue: 43,052,558
Market cap: £44.6m
Tclarke (LON:CTO) is a UK-wide specialist engineering and business services group. It focuses on five key sectors:
- Infrastructure - well positioned in the key growth sector of healthcare, which requires complex, technical engineering solutions,
- Residential and Hotels - hotel projects include The Peninsula Hotel at Hyde Park Corner and the Pan Pacific Hotel, in the City of London,
- Facilities Management - market-leading in-house Facilities Management (FM) expertise,
- Engineering Services - major new London landmark office projects include 8 Bishopsgate, City of London, Bankside Yards, Southwark, and Facebook, Kings Cross,
- Technologies - currently has live opportunities on four significant schemes in the South East.
TClarke comes with considerable business model risk and it tries to mitigate this as best it can. It strives for long term relationships and continuous repeat business ‘which is as close to achieving reoccurring revenues as is possible in our markets.’
It’s got a long heritage, stretching back to 1889, and is no doubt good at what it does, but the fact remains that this is a lower margin part of the market prone to turbulent trading and large, complex contracts.
You can see this fact reflected in the group’s low valuation multiples:

Highlights:
- Revenue -30.7% to £231.9m,
- Underlying operating profit -41.1% to £6m; reported operating profit -79% to £2.1m,
- Net cash -17.7% to £10.2m,
- Underlying diluted earnings per share -46% to 9.66p; basic EPS -84.4%,
- Total dividend steady at 4.4p,
- Forward order book +13.2% to £456m.
TClarke faced significant challenges in 2020, but this is far more evident in its results than it is in TPFG’s, for example. It’s probably the reason why one is on a TTM PE ratio of 18.9 while the other is on 8.9x.
That said, TClarke has remained profitable and its average daily net cash balance was positive throughout 2020.
No doubt the group’s operating margin of 2.6% is low, but it turns out that CTO would have reached its 3% target were it not for the lockdowns, over which the group just about broke even. The group hails this as ‘an outstanding performance given the significant impact this [lockdown] had on our sector through site closures and major client driven project delays and reschedules.’
TClarke has also maintained its dividend over the year and the forward order book, which stands at a record £456m, is being powered by entirely new projects rather than just Covid-delayed projects. Still, if I were a shareholder, I would possibly prefer to see the cash paid out in dividends to instead be used to bolster the balance sheet.
The group has set a 3Y target of increasing revenues to some £500m - that would be a good jump from FY20’s £231.9m and FY19’s £335m. In fact, it would make for a 3Y revenue CAGR of 29%.
This target is supported by a year end record forward order book of £456m: £288m for 2021 and £168m for 2022 and beyond.
So there could be top line growth here if you are prepared to tolerate the risky mix of lumpy trading and low margins. But I would imagine scope for multiple expansion is limited, while the operating risks are considerable.
Conclusion
There are certainly things to like about TClarke. It has a long and proud heritage. It places emphasis on recruiting and training up apprentices (even during global pandemics). And FY20 results could have been much worse.
With a modest valuation and a hopefully improving outlook, there could still be an opportunity here. But on balance, the risks are too great for me. Given the business model risk, I’m surprised the company doesn’t build up its cash balances and fortify its balance sheet.
Margins are low, contracts are big and complex, and a bad profit warning is never far away as a result. On those grounds, and while the top line may well grow in the near term, I think the mix of risks here justifies a lower earnings multiple.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

89 comments
Funko and NTF's
thanks for the headsup here peeps intersting stuff - seems the mere mention of NFT's is similar to bitcoin in that it immediately makes your company value increase by 20% - shame i didn't sell on the temporrary spike - i have now tracked down the specific comments that were made (i think they were informal rather than being included in an official release)
All i can't presume here is that practicably speaking its some clever wheeze probably akin to the panini stickers back in the day where some items are rare and the rarity creates extra sales - i think the company may (cough) be over egging the situation when it says its "new" "disruptive" and "only we can do it" - to that i would say pull the other one. Hey if it creates a mania 1/4 the size of cabbage patch dolls or even enusres "souble digit medium term growth" i won't be complaining. I do slightly worry whether this companies products could be a flash in the pan - but on the balance of probabilities i think their products are unique and collectable enough with decent brand recognition to drive a great long term brand that might interest to one of the big boys- if you watch enough you tube videos with presenters adding their "pitch" from their spare room you will almost certainly have seen a Funko toy on the shelf in the background - and there is a decent chance it may have been baby yoda :)
per the company at Toy News International
“We are going to be out in the market fairly soon. But we’re going to be out in the market in a very different way. We have the ability to disrupt this space in a way that nobody else is doing right now. We can tie digital NFTs to our fan base and link entities with physical products. So for example, we had a pack of NFTs– I won’t mention, licenses right now, and there’s a few rare ones. If you have those rare ones, we’re going to give you a free product that’s tied to that rare NFT, which means you have a super rare physical product that ties to your super rare NFT. That’s disruptive, that’s new, it’s different, it’s only what Funko can do.”
i kind of think they may have missed the "Yeah Baby!" from the end of that statement.
Hi Paul,
On Quartix Holdings (LON:QTX), you wrote
"It’s way too expensive for me now, although as stated before many times, I do like the recurring revenues, strong cash generation, and divis. The growth rate would need to considerably accelerate to justify a £266m market cap though."
I think that there are a couple of other things worth noting. If memory serves, Quartix applies very conservative accounting policies, that result in a lower profit than most other management would report for the same business. I think that when it sells a bit of its install kit it takes all the expense in one go or something???
Quartix also retains a cash balance, £10.6m reported with the most recent results (not enough to put a dent in the market cap though!)
Stockopedia reports the free cashflows produced by Quartix Holdings (LON:QTX) over the last five years as pretty level, around the 11p per share mark, so the shares are atill at a big premium by that measure too.
Perhaps the stock is just in very strong hands?
Asagi (no position)
How gracious of the Chairman of Sophen to “continue to believe in sharing success with shareholders” .
Paul & Jack, great report as ever ! I don't know if this is possible, but when displaying charts such as £TPFG today, is there an easy way to include a link to the Stockopedia chart with the settings, overlays and indicators used. Apologies if there are templates in Stockopedia I could use to recreate, but I haven't been able to find them. Thanks !
OT question 2
I fancy taking out a long position on a US company (Corsair Gaming) via some sort of spreadbet type situation if it is possible to buy at or near what i would be paying were i to buy the underlying security - does anyone have suggestions as who would offer the best value here ? and whether i am likley to be able to get a position without paying an arm and a leg ? - i do have a spreadex account that i could use but corsair didnt seem to appear on the list of stocks i could go long on - there seems to be many type of new companies apps and stuff offering solutions it all looks pretty daunting working out who is likely to be best value.
Cheers.
Looking at Marketsmith, Corsair is in a downtrend and living below the 50 day so I wouldn't be buying anytime soon. Most of the Tech stocks have their day in the sun and then go down quite fast. Its 3132 to sell 3147 to buy on IG index. The cost is in the spread and in the holding cost. You can bet .25 a point, so you maximum exposure if it went bust (i.e. to £0 left) would be £786.
Looking at Marketsmith, Corsair is in a downtrend and living below the 50 day so I wouldn't be buying anytime soon. Most of the Tech stocks have their day in the sun and then go down quite fast. Its 3132 to sell 3147 to buy on IG index.
Thanks for that Marketsmith i will take a look at IG Index cheers - i am not adverse to taking the charts on but i must admit i am in no hurry to buy with the general trend in place here - i think i may be doubly going against the flow too as i think there are numerous lock ins expiring about now for this company. I am reasonably happy that the financials of this company are solid enough for IMHO this not to be tarred with the speculative "had their day in the sun tech bubble" brush - the company generated $150 of operating profit in 2020 - revenue 2019 was $1.1 bill 2019 and $1.7 bill 2020 and q4 revenue 2020 was up 70% on prior year - ok there may be a lockdown tailwind here but their market segement is only going to be growing over the medium term with the popularity of gaming/egames - the pe at present may be highish at 28 for normal uk standards but thats not bad IMHO for what i see is a very reasonably solid company with good short term growth prospects - ask anyone under 25 who likes gaming if their mouse and keyboard combo is Corsair or logitec or which of the two they would pick if they had a freebie choice and i know which one would win that poll (i think - feel free to correct me here) - hey ho i have been wrong many times before in my belief that some bottom fishing may work.
Slightly OT question - does anyone have a clue what a non fungible token play (NFT) may be?
One of my stocks is up on NFT rumours and i havent got the foggiest what that means - the company is Funko - they do collectable not a doll but doll type toy stuff - ahhh possibly more a figurine than a doll type.
does anyone have a clue what a non fungible token play (NFT) may be?
'Tis that there blockchain thing.
Non-fungible means, roughly, unique.
A token, in this sense, is a digital identity that represents something else.
So, for instance, you could have a figurine with a unique identifier somehow stamped on it which would be linked to the digital identity - the token - and put on a blockchain. This could, for instance, link you as the owner to the figurine.
There are lots of tokenization things happening out there at the moment, particularly around designer goods where if you can establish provence and ownership you can prevent copying and create an item with a specific history.
Some of this is utter nonsense, but some of it is genuinely interesting and creates real use cases for blockchain, as opposed to the silly replacements for databases that many early blockchain "opportunities" were.
timarr
Thanks to MoneyLab for a curated set of links: these will give you a taste for NFTs. I'm interested, though I don't currently hold any positions.
NFTs, Explained by Digital Artist Addie Wagenknecht - https://hyperallergic.com/626382/the-world-of-nfts-explained-by-digital-artist-addie-wagenknecht/
Artists on collectings NFTs - https://foundation.app/blog/why-artists-are-collecting-each-others-nfts
Seth Godin: NFTs are a Dangerous Trap - https://seths.blog/2021/03/nfts-are-a-dangerous-trap/
Erik Trautman crypto art: hype or long-term development Twitter thread - https://twitter.com/ErikTrautman/status/1367820459383926788
'Ecological nightmare' backlash forces ArtStation to drop NFT plans - https://cointelegraph.com/news/ecological-nightmare-backlash-forces-artstation-to-drop-nft-plans
thanks for trying to educate me one_eyed_jack
Strewth - struggling to make much sense of that though my over 50 brain cells are popping :)
Perhaps the NFT fad is already over - Funko started the day at $18.30 - peaked at $24.40 and is now back to $19.74 - hey ho it was fun riding the NFT bandwagon while it lasted - whatever it was.
Hi one_eyed_jacks
The hype about NFT's is all around nonsense opportunities - essentially putting digital items on the blockchain. So you can claim ownership of Jack Dorsey's first tweet, for instance.
The real opportunity is in putting physical items on the blockchain - which is what the OP sounds like he's talking about. Once you can uniquely identify an item that is otherwise indistinuishable from any other all sorts of opportunities open up. And that's before we consider tokenization of shipping containers or, heaven forfend, shares.
Tokenization is coming, figuring out how to invest in it is the immediate challenge.
timarr
The real opportunity is in putting physical items on the blockchain - which is what the OP sounds like he's talking about. Once you can uniquely identify an item that is otherwise indistinuishable from any other all sorts of opportunities open up.
We already have this. It's the Land Registry. Every piece of land is uniquely identifiable and you can go to the Registry to find out who owns it and why they have good title.
Moving this to a distributed database seems like a recipe for chaos. For ownership of paintings and antiques I can't see that shifting certificates of provence onto some sort of distributed database, whether you call it a blockchain or something else solves any problems and probably creates new ones.
We already have this. It's the Land Registry. Every piece of land is uniquely identifiable and you can go to the Registry to find out who owns it and why they have good title.
Or you can go to it to get someone else's property transferred to yourself.
A Freedom of Information request to the Land Registry has shown that there have been 678 claims for property fraud over the last 14 years.
https://propertyindustryeye.co...
And, indeed, the Land Registry is looking at using blockchain:
https://hmlandregistry.blog.go...
As they say:
We believe that blockchain technology could enable:
Top tip - don't pay your mortgage off, because if you have one then the LR need to check with the mortgagee before transferring title. If you own outright then sign up for the notification process:
https://propertyalert.landregi...
All a bit 20th century though.
timarr
We believe that blockchain technology could enable:
increased transparency for participants in the transaction
As has been said before "if you can replace 'blockchain' with 'database' then what you're doing is boring"
The description of what the LR is doing suggests they plan to manage workflow through a centralised database. That might make it a bit more efficient, but there is nothing 'blockchain-y' about it. The point of bitcoin and monero is there is no centralised control and transactions are booked through a trust-less consensus.
In relation to land transfers, every property is unique with unique problems. It seems particularly unsuited to a blockchain type solution.
As has been said before "if you can replace 'blockchain' with 'database' then what you're doing is boring"
And I've said the same many time to my clients. Most blockchain opportunities would be better fulfilled with a BGD (Bloody Great Database).
However, where you have tradeable assets then there may be an opportunity to use some form of blockchain. LR is a reasonable fit - it removes the need for the risky middlemen (aka the LR), ownership is a matter of public record, transferring title is better done by a secure digital transaction than an insecure paper one (even if the latter is recorded in a database as it is now) and it crushes the settlement period (which with the LR can take weeks).
For LR there's no need to have a distributed ledger, other than for implicit resilence, and the consensus mechanism will be a combination of the existing title owner and an approved third-party (probably their solicitor) approving the transfer to the new title owner certified by their own third-party (ditto). Property fraud has bankrupted law firms, so it's an area of interest to them.
In this case the difference between databases and blockchain is that in the former a transaction occurs outside of the database and is recorded on it, while with a blockchain the transaction both occurs on the blockchain and is recorded on it. In other cases, where you already have a secure digital transaction going on (e.g. a credit card payment) then the business case for moving to blockchain doesn't exist.
It's horses for courses, but moving the Land Registry to a blockchain looks like the cheapest and quickest way of digitising the service.
timarr
Hi Tim / timarr,
A basic example of a NFT (non fungible token) is to imagine a painting, such as, say the Mona Lisa. There are umpteen copies around the world of this painting but only one is the original oil painting by Leonardo da Vinci back in 1503. When something has a NFT token attached to it then it means it is the only true genuine original.
I don't know if you watch the TV programme CLICK on BBC NEWS each weekend (channel 107 HD or 231 SD) but two weeks ago they brilliantly explained what NFTs are and show some examples. If you visit BBC iPlayer, search for CLICK and scroll down to the programme episode WHEN ART GOES DIGITAL, Laura Lewington and Spencer Kelly explain NFTs very well.
Cheers David.
Hi Logical David
A basic example of a NFT (non fungible token) is to imagine a painting, such as, say the Mona Lisa.
I know, I do this for a living :-)
The Mona Lisa is the classic example always given - but you can't just attach a token. It works something like this ...
1. I prove I own the Mona Lisa (a process that will presumably involve lots of lawyers).
2. An irrepudiadable identifier of the Mona Lisa is created - imagine a unique algorithim to generate a spectroscopic analysis of the painting that ends up as a string of digits. This can be the token.
3. The token is added to the Priceless Artworks Blockchain and I am granted ownership of the token (in the same way I have ownership of a Bitcoin).
Someone tries to sell the Mona Lisa. The buyer firstly scans the painting to regenerate the identifier - the token - and they can then compare this with the token held on the Priceless Artworks Blockchain.
If the token matches then they fork out several hundred million to buy the ownership - but this won't work unless I actually have the keys to transfer the ownership of the artwork in question.
The important thing is that the actual unique real-world item can be linked to a digital identifier - the token. With something like the Mona Lisa you need some kind of non-invasive process, with something like a Gucci handbag you need some kind of chemical stamp (since all Gucci handbags of a specific type will be otherwise indistinguishable).
So, in future, the dress that was once owned by Kim Kardashian will be worth more than the identical dress owned by my daughter. Such is progress.
timarr
I liked Timarr's response to this although I would simplify it; if you have to "attach" the NFT identifier to the original item - presumably this means something like a sticker, tattoo or engraving - can those labels not be forged? Or can they not be removed or attached to a different object?
NFTS are AFAICS a total nonsense when it comes to physical items, they are no better (perhaps worse) than provence established through public sales.
They maybe have some value in terms of 'digital assets'; like the digital image that was recently 'sold'. AFAIK, you can view that image online, you can even print it off and stick it on your wall (although that might be "technically" illegal). You are probably not 'allowed' to repost it online, but you could link to the owners website where they display it.
I cannot really see here how the "ownership rights" gained from ownership of the NFT amount to more than bragging rights "I own this".
I have seen all of the BBCClick stuff on this, but I think this is one of those cases where Spencer and the crew have been somewhat blinded by the shinies they are presented with.
I may though just have genuinely not 'got' it, so I am happy to be educated.
If you have to "attach" the NFT identifier to the original item - presumably this means something like a sticker, tattoo or engraving - can those labels not be forged? Or can they not be removed or attached to a different object?
Labels are sometimes used but that's not really the best way of doing this. With new goods there are methods by which you can embed a unique identifier into the material. Something like this:
https://pufin.id/technology/
Don't be misled by the term "label" - these identifiers can be added to paper (for instance) but can also be integrated into physical material as well. This is just one example of identifiers which, to all practical purposes, are unfakeable. Never, say never, of course, but if the cost of faking the identifier is greater than the value of the underlying asset then attackers will go elsewhere.
With something like the Mona Lisa that's more tricky since we don't really want to modify the artwork, so performing a scan of some kind to produce a unique signature is more likely. Those, however, potentially can be faked so it would still need ownership of the asset, ownership of the token and expert provenance checking to confirm the authenticity. It would be virtually impossible to make a believable fake artwork that generated the same signature.
There are lots of applications of the technology. Shipping containers, for instance - lots of them are lost, and ownership can get switched. Tracking them and restoring ownership is a business in its own right and generates lots of cross-border friction. Heaven knows, we could do with a bit less of that right now.
On digital assets - there are digital things where NFTs are useful - shares for instance. Stock exchanges are looking at how to use the technology to reduce the cost of ownership and speed of settlement. This is a good entry point to the world of tradeable security tokens:
https://thetokenizer.io/2021/0...
People coming to this afresh tend to confuse this with cryptocurrencies - but it's not the same. WIth cryptos the token is the asset, with security tokens the token represents the asset.
NFTs are the light entertainment end of a huge industry, which it's well worth acquainting ourselves with as it's going to make a lot of things tradeable that previously weren't. Once you can put the Mona Lisa on the blockchain you can fractionalise ownership and then trade those fractions.
timarr
great post - deserved many more likes
Hi Birdiemachine.
Oil & Gas and to a lesser extent mining stocks get little coverage on SCVR. Fair enough - both are quite specialised sectors and lend themselves less well to the sort of analysis based on company reports that Paul and Jack do so well.
Both sectors feature quite heavily on various bulletin boards, but small O&G in particular can be a graveyard for novice punters falling for the next big thing. (Been there, done that - still got the scars).
If you’re interested in the sector/particular companies you can usually find some topical commentary on Malcolm Graham Wood’s O&G daily blog. Be aware that he’s a bit of a cheer leader for the sector and has potential conflicts of interest (I think he’s an NED of Ascent Resources (LON:AST) and may well have ties/interests in some of the other stocks he discusses) but by and large he seems fairly even handed.
Here’s a link to some of the stuff he’s written recently about Sdx Energy (LON:SDX) including some comment on the 19th March Earnings statement.
https://www.malcysblog.com/?s=...
Hello SCVR...a topic of conversation by Paul and others has sometimes been MMT (modern monetary theory). I listened to this podcast today from the Queen of MMT Stephanie Kelton (The Deficit Myth author):
https://www.bloomberg.com/news...
Its informative. They're american so you can listen to it at 2x speed comfortable.
I'm always an ideological agnostic as my view is we never truly understand or place the pieces together well enough in advance...but I believe MMT is more correct than the doubters of it are correct. I think it explains economic and policy factors better than a lot of received wisdom....and its also convenient for our current high deficit, debt worry times.
Enjoy!
I think the biggest problem with MMT is the notion that the way to deal with inflation is to raise taxes or reduce public spending. It's just that old Keynsian approach again really, that the government should spend when times are difficult and save when they get better, only in practice, it always ends up with the government spending lots in good times and even more in bad. Whether the chickens ever need to come home to roost is another issue.
Its quite orthogonal to Keynesianism. It can be used to support Keynesian demand side policy but it could also be used to support a more Thatcherite supply side agenda.
At heart its a wonkish assessment of how government finances really work and this is where I think it is an improvement. As the idea is associated with 'progressives' it is is seen as left wing...but perhaps the most significant covert Western user of the idea has been this Conservative govt with the BoE employing significant and explicit debt monetisation through the pandemic to fund the government. This really is magic money tree. No debt is created through it and no one is owed...but the money circulates so enabling real economy activity (and some excess saving at the moment). This is straight out of MMT....minimal inflation as economy was working below capacity etc.
Legislation prevents the Fed from such direct monetary financing and so MMT has not been employed directly in US. Instead a more convoluted financing circle has been created...
...this has now created some financial market stress as it means that US Treasuries are issued into the market before being sequestered from it by the Fed (or US banks in the last year due to the Fed's supplementry leverage ratio exemption...which now unwinds at end of this month). So the US has a greater debt creation per $ spent than the UK as they are not employing direct MMT...
And MMT's fundamental truth around all this is that govt spending comes first and not the financing. The idea that debt needs to be issued to match spending is a myth. Whenever the US govt wants to spend it just does it through history....and then, due to convention, it has matched that spending with a roughly equal amount of debt to "finance" the spending. A great misperception of technically what happens.
An acceptance of reality is an improvement. MMT is not magic though and we can still blow ourselves up with the knowledge. MMTers don't think the solution to inflation is interest rates...they think it is taxation.
Hi mojo,
Thanks for the link on MMT, I'll listen at the weekend.
This is such a fascinating area, and I think you hit the nail on the head here in particular, when you said;
I'm always an ideological agnostic as my view is we never truly understand or place the pieces together well enough in advance
I agree completely. We have an army of experts, all talking about the future in such strident certainty, yet practically all of them are practically always wrong! Much better I think to admit that we have no idea what the future holds, and to consider all options.
I'm so glad I read the mind-bending Stephanie Kelton book. I can see a lot of flaws in it, but you can't argue with reality - which is why I read it - that something clearly has changed, at least for now, and as you correctly point out, conventional wisdom doesn't work at the moment.
I find it all fascinating, and love reading, listening & discussing these macro topics, whilst admitting freely that my opinions are no better than anyone else's! We'll probably all be wrong in the long run.
Best wishes, Paul.
Yes, its a funny business....we'll be terribly wrong and then a few years later we'll always have thought it obvious.
I try to think of paths of least resistance combined with 'restraints' that influence where things can't easily go. Of course, this wont see the truly big occasional surprise
Hi Jack,
Re: TClarke (LON:CTO) (I hold).
Thank you for your review of today's final results. I take your point about the risks in this sector and the low margins. Against this, the company has an excellent management team and I feel, based on its past record, that their ambitious targets are more likely than not to be achieved. If this turns out to be so, I feel the prospective earnings multiple makes the shares look excellent value at the current price.
Bloomsbury Publishing (LON:BMY) (I hold)
To add numbers to some comments here, the Academic Segment had increased revenue in H1, which the company attributed to a higher proportion of Digital sales.
This makes sense.
What I didn't expect was a decrease in Gross Margins in this channel, implying that Academic Digital sales actually have a lower gross margin.
I doubled checked the last results and confirmed that the company makes no mention of higher margins for digital sales. Instead it says that they had "predictable margins."
I queried this with the company and their response was that they wouldn't disclose margins by channel.
So yes, more digital sales, but from the numbers I calculated at H1, there's also a lower associated gross profit.
I've no idea why.
A
(for reference digital sales were only £5.6m in H1 FY21 out of £29.7m within the Non-Consumer channel, still quite small, but up from £3.8m in H1 FY20)
So yes, more digital sales, but from the numbers I calculated at H1, there's also a lower associated gross profit ... I've no idea why.
At a guess ... royalties. They're usually much higher on e-books than the physical variety.
timarr
Bloomsbury Publishing (LON:BMY)
Yes, royalties might explain the lower e-book sales...
until May 1 2020, digital books were also subject to 20% VAT unlike their print counterparts. This was a result of the UK being slow to implement a 2018 agreement by the EU’s ECOFIN committee to zero-rate vat on digital publishing . This might have had a small effect for the first month of H1.
A likely factor in the wider depression in margins is a Government scheme (called the Curriculum Fund) which is essentially concentrating market share in the hands of a few academic/educational publishers on the proviso that they lower prices. If you’re interested in this topic I’d get in touch with the Publishers Association as they will likely be able to give you an indication on why ebook margins are lower.
Bloomsbury Publishing (LON:BMY)
Thanks, that's interesting to know on the digital books VAT reduction being delayed.
From memory I think Bloomsbury lowered their prices when the VAT reduction came into place to pass on the full savings to the customer (with no actual benefit to themselves), so it might not explain the lower gross margins.
Anyway, it doesn't really matter as every other number is going in the right direction, I merely wanted to point out the dark side of those higher digital sales.
I'll look forward to seeing those margins when the full year results are released.
Cheers again
A
Edit: better answer below!
I broadly agree with Jack's analysis of Property Franchise (LON:TPFG)
The previous CEO referenced the scope for generating more income from ancillary services, and one of these from memory seemed to be Mortgages. Don't know how that has developed but hope to see more streams of revenue being generated, which the recent acquisition should hopefully enhance.
Inflation drops from 0.7% in January to 0.4%, due to cheaper clothes and cars. UK Inflation
Sopheon (LON:SPE) They have coped ok with the Covid 19 year . Their track record is not brilliant neither are the current results so why according to Stockopedia do they have a PE 75?
Hutchison China Meditech (LON:HCM) - Published a detailed report on progress of cancer treatments this morning. Highly technical - anyone out there who can tell us in a few words of plain english what this means for the company ? It is a favourite share of Slater UK Growth which I hold.
Softcat (LON:SCT) up 14% today (I hold) on publication of Half Year results. 10% increase in Revenues have lead to what looks like a 41% increase in Operating Profit. Need to look into it further. Seems like dramatic operational leverage on the face of it!
I agree re Softcat (LON:SCT) - I bought at 959p in Oct. 19 when Keith Ashworth-Lord first revealed that he had built up a holding for the Buffettology fund. Now 1799p - can't grumble with that! But hold on - Mcap £3bn and this is the SCVR - I think you should have started this conversation elsewhere.
True, but when you see an elephant not just running, but apparently driving a Ferrari, I think I could be forgiven for a slight reference, if it benefits others?
HI, any chance of adding a review of SDX oil in a SCVR soon? It's jumped from 74-93 in stock rank, fundamentals look good, the best amongst the small "oilers" but the SP doesn't seem to be moving in the right direction. I'd just like to understand a little better. Many thanks in anticipation.
Hi Birdiemachine,
Sorry we don't cover the natural resources sector here. That's because there are far too many of them, and I don't have the specialist sector experience that is needed to make sense of them.
Regards, Paul.
Hi Birdie, Note that you are newish to the site. From my experience, if there is a specific share you want to get input on (and the SCVR does not cover it) then I would start a separate thread and share your initial thoughts. This allows users to pick up on the topic later. Also put the prefix in front of the the ticker so there is not confusion.
Hi Birdiemachine, one of the issues with investing in companies that are responsible for extracting or producing commodities is that many investors use them as an option on the commodity price, which means that as the price of the underlying commodity goes down, so goes the share, regardless of the fundamentals.
One way to proceed is pick excellent managements that are generating cash, paying down debt regardless of commodity price (within reason - it has to be above extraction cost), so that when the commodity moves up again they can turn bonus spot price into pure profit. On the flip side, if mgmt are taking on loans at time of high price to expand extraction, I would sell quickly- it does not end well.
Essentially though, you are looking at a leveraged option on commodity.
Yep they are all price-takers
Update from Parkmead (LON:PMG) this morning confirming they have divested some of its non-core acreage acquired in Aberdeen for a planned wind farm site (the land is currently opposite an existing Siemens-run wind farm). The remaining land has excellent wind speeds and technical studies are underway.
The sale for £4m brings the cash pile up to c£30m, meaning just over 80% of the current share price is backed up by the cash pile. I continue to retain a stressed NAV of 53p (actual BV is 66p) for the company based on substantial haircuts to the exploration assets and PPE.
Thank you for your thoughts on Bloomsbury Publishing (LON:BMY) Paul (I hold) I agree with your 'solid' and 'not madly exciting' comments, although I do think the academic digital publishing (sort of BAAS Books as a service - my definition) is a growing differentiator. Also that cash pile might go into a canny acquisition?
Completely agree, think it is the Digital Education that is the growth engine. It was Richard Leonard's pick for 2021, he enthused a lot about the digital side. I hold £BMY.
Plus a phenomenal store of IP. A lot to like about £BMY I think.
Yes there is an increasingly strong argument that Bloomsbury Publishing (LON:BMY) does deserve a higher multiple given a large part of revenues now come from digital subscriptions on the academic side - higher margins and recurring revenues usually highly rated.
.
Couldn't agree more with this. I love Paul's analysis hugely but I think he may have sped past what is actually being built up in the background here, just my opinion, I'm probably wrong but it feels like the business is growing out of its original form
You could be right biggsy!
I like Bloomsbury Publishing (LON:BMY) as mentioned in the article. It's trading well, has a great balance sheet, there's lots to like. Valuation still reasonable.
Bear in mind that the "My opinion" section is just a personal conclusion on whether I'd want to buy any personally. We all come to different conclusions. For me, I don't really see enough upside % to get me excited, that's all. In all other respects, it looks good!
Hope that clarifies.
Regards, Paul.
Thanks everyone for their comments on Bloomsbury Publishing (LON:BMY) so far. Very informative! Did they mention any further licensing of franchises such as Harry Potter into e-gaming or e-commerce markets in Asia-Pacific region. While I’m not as much a believer in the subscription model for digital books (I used to work in EdTech/digital publishing and Perlego, academic book version of Spotify, has stolen a march in the university sector here) I’d been intrigued by news that Bloomsbury has licensed Harry Potter to a Chinese digital publisher last autumn.
As an avid China follower, I’d noticed this article in the South China Morning Post (Hong Kong national newspaper) in January https://www.scmp.com/tech/apps... which notes that Chinese companies including Tencent and the lesser known NetEase are turning to traditional publishers to purchase licenses.
Agreed (also a holder). The wfh dynamic, e-learning etc are themes this company should benefit from.
Frontier Ip (LON:FIPP) (I hold) half year results out this morning and looking good (on a quick skim), albeit with a fairly consistent (oversubscribed) dilution rate of 16%. I'm quite interested in this one and thinking about topping up.
Strix (LON:KETL) Strix ( I hold ) had an unexpected drop yesterday - does anyone have any idea why as the results this morning do not justify such a drop with Revenue £30.09 v £29.06 , EPS 14.9 v 14.08 and DPS 7.85 v 7.70 all ahead of consensus estimates . All of this with a PE of 17.2 .This company is one of the success stories of the SVCR as I found it here but has grown to a point where it might now be too big .- - great news as far as I am concerned. Only negative I can see in a sea of positives is commodity and transport inflation but I believe this will be temporary as the world gets back to normal. On the positive side :
"Strix has continued to deliver on its strategic plans during 2020 which has strengthened the Group's position across its three product categories; kettle controls, water, and appliances. The Group has expanded its market leading value share of the global kettle controls market whilst significantly expanding the size of its water category through both strong organic growth and the strategically compelling acquisition of Italian-based LAICA in October which despite the disruption caused by the pandemic has delivered strong double-digit revenue growth over the period. In addition, the Group's medium-term strategy was updated at a Capital Markets Day hosted in November outlining a path to double Group revenues over the next five years primarily through organic growth in its water and appliances categories."
The drop in price is a buying oppurtunity and i continue to hold
I think the price fall yesterday was on the back of a Shore Capital sell note due to annual price erosion in kettle controls market and the battle to protect its IP against Chinese co's. Shore capital has kept its sell rating following todays results citing 'At 16x our FY2021F EPS forecast, we consider the shares overvalued and see more upside from Porvair & Renew'
Conversely Stiefl have issued a price target of 320p - still a discount to peers.
Todays results looked good IMO with continued strong momentum from H2 and management reiterated the ambition / expectation to double revenues by 2025
I hold
I have held Strix for over a year now, and am slightly surprised at this morning's price drop.
On the bear side, I worry that the company's IP in Ketl controls might not be quite as good as suggested. Falling Kettle controls prices (as refered to by Shore capital) suggest this may be the case. Kettle controls aren't exactly new tech, though to be fair, there are other everyday products e.g. razors which somehow command high margins and I think have associated IP or brand value
The water filtration side is just something I don't know anything about. It could be great, or equally one of those product areas ripe for hype.
Overall I'm neutral to postive on £Ketl . Pre-pandemic is had a good ROCE, modestly growing sales, and was set for better margins ( I think) as its new production facility in China got completed.
It's not exceptionally cheap as a share, but far lower rated than typical IT/Internet/online retail stocks. Markets are fickle and in a share like £Ketl does not set the heart racing. Yet as (when?) share prices correct, I think this type of boring stock will be a blessing to a portfolio, with likely lower percent loss in value whilst dividends continue to flow.
Their foray into water purification pipework for agricultural use is interesting.
The only other initial negative I spotted in Strix was a 41% increase in debt
Hi Ben, I noted this as well in Strix (LON:KETL) (as I'm a holder for at least a couple of years now). I gained some assurance on the debt since it was explained as the LACIA acquisition and net debt to adj EBITDA is now 1.0 so not too onerous. I haven't got as far as the cashflow statement in the results yet so will analyse that carefully.
Paul was quite sceptical of the accounts a few weeks ago in his analysis of the trading update. I wonder with results now published he might consider a revisit to see if his view has been reinforced? Maybe something for a slow Friday?
As a further follow up on reviewing Strix (LON:KETL) (which I hold) quite a few things struck me in the results, particularly the deterioration in working capital with a significant rise in inventories, receivables etc, although most could maybe be explained by the LACIA acquisition (£5.5m inventories acquired in Oct with the acquisition). I do wonder though if inventories are a risk here since the note says:
"
15. INVENTORIES
2020 2019
GBP000s GBP000s
------------------------------------- -------- --------
Raw materials and consumables 9,154 5,071
Finished goods and goods in transit 6,070 4,426
------------------------------------- -------- --------
15,224 9,497
------------------------------------- -------- --------
The cost of inventories recognised as an expense and included in cost of sales amounted to GBP39,052,000 (2019: GBP35,037,000). The provision for impaired inventories is GBP2,513,000 (2019: GBP302,000). There were no reversals of previous inventory write-downs."
That is quite a jump in provisions.
Trade and other payables in current liabilities have jumped year on year from 17.7m to 27.1m. That is a hefty increase, again due to LACIA yet per the note in October they acquired £5.4m of trade and other payables in current liabilities.
Per my earlier comment on net debt, having now seen the cashflow I can see there is nearly 13m for purchase of property, plant and equipment. (Putting 2 and 2 together I would see a lot of this being related to the new facility in China which is due to be operational later this year. So hopefully not as high a fixed asset cost next and future years.) There is also 6.7m for the LACIA acquisition, again not a normal trading cash outflow.
After reading Paul's opinions on this a few weeks ago I decided not to add further to my position and see how the results look. Now results are in I'm reviewing my position, probably going to hold as there is good momentum and targets of doubling revenue in 5 years. However I would like to understand more if there are issues over working capital or this is just a Covid impact which unwinds this year. (My holding is only 2% of my portfolio so it is not too expensive if my judgement is wrong.)
re Strix (LON:KETL) - a number of questions raised by several people including wildshot who says "However I would like to understand more if there are issues over working capital ..."
Well, the best place to air these is tomorrow's webinar at 2.45 p.m. The more people who attend, and the more questions asked, the more these companies and their advisors will feel it is useful to engage with PIs. The access link was given earlier here: https://www.stockopedia.com/co...
If that does not work on the new site try https://app.stockopedia.com/co...
Thanks for sharing the link again sharw. Sadly I'm unable to attend. (Should anyone be able to and report back for the benefit of the community it is appreciated.)
I’d be interested to hear Paul’s view on Strix. I hold. The potential doubling of revenue in 5 years is attractive, if it can be achieved. Good margins, but a weak balance sheet.
I'm not planning on covering Strix (LON:KETL) sorry about that.
I looked at it in the SCVR for 27 Jan 2021, and concluded that I don't like the weak balance sheet, and the cashflows look questionable.
It doesn't work for me on a basic common sense level - how can simple technology in a kettle produce such a high profit margin? When made in China?
I don't understand the numbers, so am steering clear.
Hi Paul, I don't hold STRIX (LON:KETL) either. I used to hold them and my recollection is that they hold a lot of patents on kettle safety cut outs ( that come into operation when someone turns the kettle on without any water in it). They are not shy about defending their patents in court. So their intellectual property provides a form of moat.
So it's like having a patent on a basic widget?...but does it mean any market dominance? I'm not sure on it anymore...and i think they've gone into water/filtering so not sure if they are convicted about kettle elements as their no.1 strategy?
Bonhill (LON:BONH) FY2020 results presentation by Simon Stilwell, CEO & Sarah Thompson, CFO. Transitioned to virtual events, which had a positive impact on margins, and provides new product and revenue opportunities going forward. Granted a hit from lack of physical events. The start to 2021 is promising and they are confident of revenue growth of c12% and EBITDA c£1.2m. Video & podcast.
Bloomsbury Publishing (LON:BMY) TU today, 'revenue is expected to be ahead and profit significantly ahead of upgraded market expectations”. It was Richard Leonard's pick on the piworld 2020 round up interview. Hear him talk about it in full here on the BMY website! Or get a flavour with a very short clip here.
Note piworld have started a new Instagram page, full of clips of some of the best or most recent interviews. It's quite entertaining seeing these c1 minute clips of best ideas or other gems. We'll see how it goes, if we get lots of followers we'll keep it going. Please follow us there.
Yesterday we posted results presentations for Somero Enterprises Inc (LON:SOM), Eagle Eye Solutions (LON:EYE) & £LIT. Find them all at https://www.piworld.co.uk/ and lots of other results presentations for the month including: Emis (LON:EMIS), Empresaria (LON:EMR), Kape Technologies (LON:KAPE), Sthree (LON:STEM), Brand Architekts (LON:BAR), Ultra Electronics Holdings (LON:ULE) & Headlam (LON:HEAD)
Kenmare Resources (LON:KMR) published an excellent set of FY results this morning. Production numbers had already been released but there was encouraging news on the dividend which has been raised 22% to 10 UScents vs 9.2US cents consensus. Looking forward to 2021 the company has confirmed production guidance and said they are already seeing the benefits of higher production in lower unit costs. Strong market demand for their products has resulted in prices 9% higher in 2020 and pricing momentum has improved going into 2021. Looking at analyst notes their assumptions for prices are approximately 25% below current spot prices. Management confidence in future performance is reinforced with a commitment to raise the payout ratio to 25% of PAT. With the increase in profits expected the dividend is forecast to more than double in 2021 and this is before higher prices are factored into performance. Scope for further upgrades.
There is a webinar later today at 5.15 when MD Michael Carvill and Head of Corporate Development and Investor Relations will be presenting and answering your questions.
Register: https://us02web.zoom.us/webinar/register/5116142671285/WN_aO_FcjIvR7SWma7ImTI7tQ
Thanks for this - I have held this for years so still nursing a bit of a loss. It does seem to have transformed into an exciting profitable company. My only concern is the terrorist situation in the country - maybe we will hear something on this in the webinar later today
My morning smallcap tweet: Bloomsbury sales not just pottering around
Tavistock Investments (LON:TAVI) Tclarke (LON:CTO) STM (LON:STM) Novacyt SA (LON:NCYT) Property Franchise (LON:TPFG) Microsaic Systems (LON:MSYS) Immotion (LON:IMMO) Deepverge (LON:DVRG) Feedback (LON:FDBK) Fox Marble Holdings (LON:FOX) Bloomsbury Publishing (LON:BMY) Arden Partners (LON:ARDN) Hargreaves Services (LON:HSP) Surface Transforms (LON:SCE) Circassia (LON:CIR) Conduity Capital (LON:CCAP)
Tavistock Investment (TAVI) rejects all paper approach at nil premium. An uncanny coincidence that the board recently tried (and failed) to get through a new incentive scheme that would have gifted them 25% on a change of control. What kind of perverse incentive is that anyway? [SP=2.45 Cap=15m]
T Clarke (CTO) FY(Dec) rev down 30%. Outlook "Following a lightly slower start we expect revenues and profit to build rapidly throughout the course of the second half of the year as our recently secured projects gain momentum." [SP=104.5 Cap=45m]
STM (STM) sells Gibraltar CTS and Tax Compliance businesses for £2.45m plus net assets upon completion of c. £0.57m. Only gets £1.25m on completion, rest over 18 months. £0.325m is contingent. [SP=30.3 Cap=18m]
Novacyt (NCYT) launches CE-Marked PCR test to detect six COVID-19 variants. VariPLEX can be deployed on-site in near-patient settings to generate results in under two hours. [SP=726 Cap=621m]
Property Franchise (TPFG) FY(Dec) rev up 1%. Outlook: s"ales pipeline has continued at strong levels. As a result, at the end of February, the sales agreed pipeline had only reduced by 6% since the end of 2020, when they were at record highs." [SP=226 Cap=71m]
Microsaic Systems (MSYS) 3 year technical and commercial framework agreement with DeepVerge. Initial order of £100k plus commitment worth up to £150m. "Microsaic will generate a margin on any future unit sales to DeepVerge, which DeepVerge will distribute to its underlying customers...Current intellectual property will reside with each of Microsaic and DeepVerge." [SP=0.23 Cap=14m]
Immotion (IMMO) most USA partner sites are now open. Other encouraging signs. [SP=4 Cap=16m]
Deepverge (DVRG) see MSYS update. [SP=32.44 Cap=56m]
Feedback (FDBK) Bleepa wins 1 year £84k contract from the Royal Berkshire Hospital. [SP=1.27 Cap=14m]
Fox Marble (FOX) wins €190k order. [SP=2.2 Cap=8m]
Bloomsbury Publishing (BMY) guides FY(Feb) rev ahead and adj pretax significantly ahead of upgraded market expectations which are £171m and £14.8m resp. [SP=268 Cap=219m]
Arden Partners (ARDN) AGM stmt - trading has remained strong, with all areas of the business performing well. [SP=11.25 Cap=3m]
Hargreaves Services (HSP) earthworks subsidiary wins HS2 contract, the largest in its history. No £££. [SP=318 Cap=103m]. I hold.
Surface Transforms (SCE) gets cheap £1m loan from the Merseyside Special Investment Fund. Loan linked to certain continuing employment levels. [SP=75.5 Cap=147m]. I hold.
Circassia (CIR) £5m raised at 25p, an 11% discount, because it needs money. Also FY(Dec). Outlook: "early signs of recovery in Q1 2021 trading in our Clinical business. Our Research business has made a strong start to the year. Beyond this period of disruption the Company anticipates a return to strong revenue growth in the medium to long-term." [SP=28 Cap=111m]
Conduity Capital (CCAP) the cash shell has failed to find an acquisition in the 6 month limit so is exploring a fundraise of £6m min to become an investing company. Shares will be suspended 6 Apr. [SP=2.24 Cap=4m]
Agree with Paul’s sentiments that H & T (LON:HAT) is quite a tricky company to read. I have been a long term holder and while happy with the general performance and dividend stream I’m a little disappointed that the wider market seems to view the sub prime finance sector as somehow distasteful. Lots of threads to yesterday’s report. Clear benefit from rising gold prices (now winding back a little) but marked shrinkage in the Pawn loan book.
One thing that does come through loud and clear in the commentary is a desire by the company to be seen as being in partnership with rather than exploiting their customer base. Lots of initiatives during lockdown such as payment holidays while their shops are shut to help borrowers etc.. Good corporate citizenship that will engender long term customer loyalty (while conveniently playing to the regulatory audience that they’re helping sub prime borrowers) or just a cynical spin on actions they’ve had little alternative in taking? You can choose to read it both ways although I’m inclined to give them the benefit of the doubt. Interesting read across to other players in this space such as Morses Club (LON:MCL) who have a reputation for being “reasonable” and one or two others that do not. Longer term I think stricter regulation will benefit the likes of H & T (LON:HAT) .
Gus.
Agree both that sub-prime (now self called non-standard!) is both unreasonably hated by the market and that the regulatory risk is a potential positive barrier to entry to those that can work within guidance (as sharks get squeezed) and whose processes are liked by FCA.
In fact, I see a lot of sub-prime at a bit of a people business with a data analytics backstop. Impairment (ie non-repayment) is higher where there is no relationship or F2F contact eg over internet. Morses Club (LON:MCL) consistently get 97% good/v good customer satisfaction scores and are attracting good, stable agents who in turn have good customers. Conversely, Amigo Holdings (LON:AMGO) after a brief burst is broken and Provident Financial (LON:PFG) continues to struggle in its Home Credit business.
As Covid unwraps, a lot of new (better quality) customers will find themselves needing non-standard financial support and willing to pay higher rates whilst quite a lot of credit has been withdrawn as some go bust. Strong balance sheet, conservative and well established players like H & T (LON:HAT) and Morses Club (LON:MCL) will do well. (Disc, I hold the latter as one of my largest positions).
(I hold H & T (LON:HAT) )
I think the current SP does not reflect H&T's stronger market position after it acquired shops and clients from insolvent rivals in 2019. Also the payday loan market (which for years competed with pawn loans) has now been regulated away which likely means additional demand for the remaining alternative finance players. Finally COVID-19 has changed social behaviour and I have doubts that doorstep lenders like Morses will reclaim their previous market share. This may also benefit pawnbrokers.
A nice update from Bloomsbury Publishing (LON:BMY) this morning (which I hold) with revenues ahead of market consensus and PBT materially ahead.
The company helpfully provides a note on market expectations:
"The Board considers current consensus market expectation for the year ending 28 February 2021 to be revenue of £171.0 million and profit before taxation and highlighted items of £14.8 million."
For reference FY20 revenue was £163m.
By my estimates Operating Profit will come in >£20m vs £13.4m achieved in FY20, which is a nice result for a company with a current EV of £171m.
Happy holder.
A
No RNS yet to say who bought the 19% of Checkit (LON:CKT) sold in yesterday’s RNS.
If you re-read yesterday's you will see that two of us replied and told you who bought the 19% of Checkit (LON:CKT) since you missed that RNS
Thanks, both, for the reply about Checkit (LON:CKT) and the useful research.
Is Strix (LON:KETL) still a small cap?! An unexplained move down at the end of yesterday but strong numbers in a tough market out today. Join us Thursday 2.45pm for their investor presentation https://zoom.us/webinar/register/6816142709242/WN_rLMPUO3mReaTfSuiTl_xsw
HI Paul, thank you for your writings. As an example, none of the three companies you carried over from yesterday interest me, but your way of analysing, interpreting and laying out the data is so so easy to read and follow that I take the time to read it just to help me in my understanding of how to analyse companies.
I am sure I am not alone in having you to thank and credit for my increased wealth and knowledge and am now completely hooked on looking into and investing in small caps. Please keep up the great work and best wishes.
Kevin
What a nice start to the day, thank you!
I know what you mean about being "completely hooked" on small caps research & investing, it's such a fascinating area, like doing a puzzle, trying to work out what's what for each share. We never stop learning either, there's something new to learn every day, I love it! Especially when share prices keep going up, like we're seeing at the moment. It never lasts sadly, the market is always lurking, ready to snatch the money back, from the unwary and the over-confident.
Best wishes, Paul.
I totally agree with KevinS1, I've been reading these every day you've done them and its making me do a lot more work before I buy a share. Not that I always do but...
Thanks Paul
Yes, Paul I echo KevinS1's comments and thanks for your work here (already 28 ticks!) and also your contributions to the Mello Bash. The last contribution you made SNWS was a cracker and typical of the ones you seem to be able to pull out of a hat!
Re your comment on the market always ready to snatch the money back, did I read somewhere recently which said that £1.4bn had moved out of small caps over a short period, or is that in my imagination. Sorry I cant be more precise on the source or its veracity.
hi Paul - would you ever take some time your to share your approach or view on top-slicing when bearish sentiment abounds, and/or when a share becomes over-valued?