Small Cap Value Report (Weds 24 Nov 2021) - UNG, AO., SAA, IGP, APP, HARL, WYN, MUL

Good morning, it's Paul & Jack here, with the SCVR for Wednesday (first few sections prepared last night by Paul).
Agenda -
Paul's Section:
Universe (LON:UNG) - bumper payday for shareholders here, with a >100% premium cash takeover bid, from a trade buyer.
Ao World (LON:AO.) - very poor interim numbers, with growth low, and fleeting profitability during the pandemic having vanished. This is a very poor business model, in my opinion, as the figures clearly show. I also have concerns about the heavy reliance on commissions from extended warranties, etc.
M&c Saatchi (LON:SAA) (I hold) - another upgrade to expectations. Not cheap, but forecasts keep rising, so is the company now in an "upgrade cycle"?
Intercede (LON:IGP) (I hold) - nothing spectacular in these interim results, but it's tracking in line with full year expectations. The balance sheet has been transformed, with net cash now 18% of the market cap. It has the best blue chip client list I've ever seen for a micro cap, and under the surface a lot has been done to (hopefully) lay the groundwork for fast growth, in this 3-year turnaround. The valuation can be justified on a PER basis too, very unusual for this type of company.
Appreciate (LON:APP) - I'm still quite sceptical about this gift voucher company. But we'll keep it on the radar, as there's a possibility of a turnaround with the digital strategy. I need to see more evidence though, nothing doing so far.
Harland & Wolff Group (LON:HARL) - a blast from the past, for those of us old enough to remember the industrial strife of the 1970s. Can this Belfast shipbuilder rebuild profitability with wind farms, and apparently tightening capacity constraints at competitors? You can be the judge of that, I have no idea!
Jack's section:
Wynnstay (LON:WYN) - trading ahead of expectations and managing inflation well. Reasonably valued with a great dividend track record, so worth considering for longer term investors, although the shares are very illiquid and the company's fortunes depend upon farmgate prices.
Mulberry (LON:MUL) - turnaround of British luxury lifestyle brand could be gaining traction. The share price remains down on historical levels and there has been no equity dilution. But the group has struggled to generate revenue growth and decent operating margins in the past. If management can address this then there could be an interesting opportunity, although the free float is, unfortunately, very small at just over 5%.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Universe (LON:UNG)
11.7p (up 123% yesterday) - mkt cap £31m
An outstanding, and very lucky outcome for shareholders here -
Recommended Acquisition
It’s a 12p cash bid, a remarkable 129% bid premium.
Holders of 51.2% of the company have given indications of support, so this looks a done deal - as you would expect with such a generous premium being offered.
Clearly the bidder sees value in Universe, which is far from obvious in the published accounts - where Universe has disappointed for many years.
The bidder (called PDI) seems to be a much larger software business -
PDI is a leader in enterprise management software for the convenience retail and petroleum wholesale markets.
Therefore, UNG looks a good fit, since it also specialises in areas relevant to this.
So this looks like a case where the business is worth more to a trade buyer than as a standalone listed micro cap.
My opinion - given UNG’s long-term under-performance, this bid seems an exceptionally good outcome for shareholders. Also coming at a good time, since there are many bargains around currently in UK small caps, so the cash windfall can be deployed much more effectively than a few months ago when prices were higher.
Ao World (LON:AO.)
106p (down 14% yesterday) - mkt cap £509m
This online only electricals retailer issued a profit warning, which I covered here on 1 Oct 2021.
I’ve long been bearish about this company, since the business model seems poor to me (very low margins, shifting other people’s brands, with high costs). The valuation has seemed excessively high for a long time. The last profit warning made it clear that the boom from lockdown was a one-off, so the share price has now given up nearly all the boom it enjoyed when the pandemic began.
We’ve seen very severe downward moves across most of the eCommerce sector, not just in the UK, but also internationally, in the last year, as the whole sector de-rates due to concerns about growth, increased competition, and supply chain delays/costs.

.
AO World plc ("the Group" or "AO"), a leading European online electrical retailer, today announces its unaudited financial results for the six months ended 30 September 2021 ("HY22").
This table below is a good way of showing that the negligible growth in H1 this year, comes on top of very strong growth in H1 last year. So the 2-year growth rate is still very good. That’s fine, but the big problem for me, is that the decent rise in EBITDA last year, has not been maintained - it’s actually disappeared. Which suggests to me that they’re back to square one, with a business model that doesn’t really work. Margins, and costs must be under pressure, for EBITDA to have wilted back to just above breakeven.

.
Increased digital marketing costs & recruitment of lorry drivers (500 new drivers recruited) are mentioned as increased costs. Trouble is, AO makes such a low profit margin, that it hasn’t got scope to absorb increased costs.
Outlook - this is the whole of the outlook section, as it’s all interesting -
At the start of our financial year in April, we planned for continued revenue growth and built up our cost base accordingly. However, since then, growth in the UK has been impacted by the nationwide shortage of delivery drivers and the ongoing disruption in the global supply chain, and the German online market has seen significantly increased competition.
As we now look to the second half, we continue to see meaningful supply chain challenges with poor availability in certain categories, particularly in our newer products where we have less scale, experience and leverage. In addition, shipping costs, material input prices and consumer price inflation remain challenging uncertainties.
As a result of these factors, the all-important current peak trading period is significantly softer than we anticipated only eight weeks ago. As a result, we now expect full year Group revenue to be flat to minus 5% year on year, with Group Adjusted EBITDA in the range of £10m to £20m.
While a substantial amount of short-term uncertainty remains, we are taking decisive action to address and mitigate the issues and are confident in our ability to trade our way resiliently through this period. In the medium-term, our international expansion ambitions remain entirely unchanged. We remain confident about AO's future prospects, based on the strength of our business model, the quality of our customer proposition, and the ongoing structural shift online.
Net debt - alarm bells rang in my head when I saw that net debt is reported at £102.2m which would be a problem, given that the company is now loss-making.
However, it turns out that this includes £93.3m in lease liabilities. Most companies report net debt excluding lease liabilities, or provide both numbers in the headlines. So AO has scored an own goal here, by quoting the artificially high IFRS 16 net debt figure. The real world net debt (under IAS 17) is modest, at £8.9m, which is not a concern. So we can reset the alarm bells!
Balance sheet - overall looks adequate, with NTAV of £47.3m, and only modest bank debt.
However, there are a number of large items which concern me - in particular receivables seem extremely high for a retailer (where customers pay up-front, so receivables should be very low).
Tracing things through to note 8, the reason is “Contract assets” of £173.6m, sitting in receivables. The note explains -
Contract assets
Contract assets represent the expected future commission receivable in respect of product protection plans and mobile phone connections. The Group recognises revenue in relation to these plans and connections when it obtains the right to consideration as a result of performance of its contractual obligations (acting as an agent for a third party). Revenue in any one year therefore represents the estimate of the commission due on the plans sold or connections made.
The cash for this seems to be received over c.1-2 years, with £73.7m cash received in H1 - that’s a huge number. It seems to suggest that AO is effectively selling goods at a loss, once its overheads are taken into account, but makes money on extended warranties, product protection plans, etc. Even after those revenues, it’s still managed to be loss-making in H1.
This strikes me as a very poor business model. What happens if this is the next area to attract mis-selling, or other regulatory attacks? Something adverse happening in that regard could cripple AO. Hence I think this share could be quite high risk.
My opinion - this company looks very poor to me. It’s got a low margin, and now a loss-making business model. I’m concerned about how heavily reliant it seems on profits from extended warranties, and other add-ons - the huge receivables balances on the balance sheet demonstrate how material this income is. We’ve now had 2 profit warnings in 2 months.
There’s only been one year where it made a significant profit, due to lockdowns. Now we’re back into losses (at the operating & profit before tax levels - i.e. real profitability!)
We’ve seen several other eCommerce companies complain that digital marketing has become more expensive, as competition for advertising & search words increases. AO also mentions this in its commentary today.
All of this leads to me viewing AO very negatively. I think this is a marginal business, that is not likely to ever generate significant and sustainable profits. The space it’s in is too competitive, with low margins, and AO has adverse costs (e.g. 2-person deliveries).
Hence even though the shares have now lost three-quarters of the peak price in Jan 2021, I still see absolutely no attraction to this share whatsoever. The £509m market cap still seems far too high, given that there’s little growth, and no profitability now.
I suppose the upside story is that growth might resume, and excess costs could moderate in future, but why would I want to gamble on that happening? The only other hope, is that the stock market has previously valued this share at irrationally high valuations, so that could happen again, which is speculation rather than investment.
If you really want to invest in an online electricals retailer, there’s now another option - much smaller, but more profitable (as a % of revenue) competitor Marks Electrical, which floated on AIM on 5 Nov 2021. I’ve had a quick skim through its admission document here, and my main concern is that it looks an opportunistic float, on the back of stellar growth in profits in the pandemic year FY 3/2021. That may not be sustainable, as we’re finding out from lots of other eCommerce businesses.
Interim results from Marks Electrical cover the same period as AO World’s interims above, but show continued very strong growth, and a much better EBITDA margin than AO. So perhaps smaller is better, in this sector? AO’s figures look bloated & inefficient, in comparison. I really don't want to own either AO or Marks Electrical, it's just not a sector that interests me.
M&c Saatchi (LON:SAA) (I hold)
166p (up 1.2% yesterday) - mkt cap £203m
The Company is pleased to announce a further trading upgrade for 2021.
Since the last trading update on 21 September 2021, the Company has continued to trade well.
As a result of the continued strong performance, management now believes the Company's headline profit before tax for FY21 will be ahead of consensus expectations, with both revenue and operating profit margin ahead of market forecast.
New business continues to be strong with new client assignments including projects for Apple and Mars. We extended relationships with Commonwealth Bank, Whoop and TikTok, and 'Icelandverse' became one of the most talked about campaigns of the year.
Going through the archive here, I can see my previous comments gradually turning positive earlier this year, as the company resolved previous problems (of potentially bad dilution), and issued increasingly positive trading updates. Getting another positive update today (albeit with no numbers, frustratingly) strengthen my view that this PR/marketing group seems to be on a roll.
Broker forecasts - many thanks to Liberum who update us today. Forecasts are -
FY 12/2021 - eps 5.6p = PER of 29.6
FY 12/2022 - eps fc 6.5p = PER of 25.5
Hmmm, that doesn’t look good value. The assumption must be that SAA continues to out-perform. Indeed, the Liberum analyst Ciaran Donnelly does talk about a potential "upgrade cycle", which has been happening already -

I wish I could remember more about why I bought these shares, and can only remember that at the time they looked reasonable value, and the company was out-performing, so likely to upgrade more. Today seems to confirm that, although the valuation doesn’t look a bargain.
The long-term chart suggests there may be more upside, but remember that the share count has increased a fair bit since the previous highs.
Also with this type of business, where by far the largest cost is staff, who want a slice of the action when things are going well, so that might limit the upside for shareholders possibly?
.

.
Intercede (LON:IGP) (I hold)
83p (down 3% yesterday) - mkt cap £47m
Intercede, the leading specialist in digital identity, credential management and secure mobility, today announces its interim results for the six months ended 30 September 2021.
Revenues of £4.9m in H1, up only 2%, but up a more respectable 9% on constant currency basis (most revenues are earned in USA, but costs are mostly UK).
The most notable item on the P&L is that finance costs in H1 fell from £295k last time, to £53k this time, due to the convertible loan notes having converted into shares - this is the first period to benefit from this reduced interest cost, which is material to profitability.
Taxation is negative, due to R&D tax credits, and again is material.
H1 profit after tax is £539k, up slightly on £441k last time. Note there’s an H2 weighting to profits, due to contract renewals at the year end.
Balance sheet - is absolutely transformed for the better, now that the £4.8m loan notes have converted into equity. Therefore all previous concerns about this issue have completely gone. For the size of business, we now have a strong balance sheet - £5.2m NTAV (there are no intangibles, the accounting is very conservative, writing off all development spend, capitalising nothing, which I like).
There’s £8.5m net cash, which is 18% of the market cap - a very comfortable position. Management started to talk about the possibility of bolt on acquisitions in future, when they last presented to investors. Although costs have been suppressed for several years now, hence it should be expected (and welcomed) that some staff pay rises and bonuses have been implemented.
Many staff are very long-serving - a point which came across strongly when I was delighted to be invited to join a short section of Intercede's staff Zoom conference some time ago, to give my perspective as a small shareholder. What a great initiative, connecting staff and a small shareholder, more companies should do this.
What came out of it was that many staff are very long-serving, and are also small shareholders. I emphasised that the stock market really values growth above all else - so accelerating the growth rate is key to a higher share price. Plus I emphasised that as a small shareholder, I'm just a back seat passenger, so thanked the team for everything they do, and expressed my confidence in the company and its prospects, whilst also emphasising that I'm only speaking for myself, and other shareholders may have different views.
Commentary - there’s always a lot of interesting information in Intercede’s results commentary, so I’ll pick out items which I think are worth flagging -
Record new customer wins of 8 in H1 - the business model has been changed to focus on partnerships, which I hope could accelerate growth. The investing opportunity as I see it with IGP, is that it has very sticky long-term client recurring revenues, so if it can accelerate new client wins, then the operational gearing from an already profitable base position, could be exciting, and give us a multibagger. Easier said than done, of course.
The key point with IGP is its astonishingly high quality client base - UG Govt Depts, major aerospace multinationals (Boeing, Airbus, etc), international banks, etc. Once installed, these relationships can last 10-20+ years, with recurring revenues, support revenue, and hardly anything goes wrong with the software, so new clients can be easily supported due to the low level of support tickets, I understand.
M&A - I think IGP could be a target for a larger software group. However, it is also considering its own deals -
Phase 2 of the Intercede turnaround plan is underway to push scalability and accelerate revenue growth. The Company is building an M&A pipeline to expand its footprint across the authentication pyramid and to address adjacent market segments.
I’m a bit nervous about this. The last thing I want, is for management to be distracted by deal-making. That said, the CEO has established a track record of being shrewd, and cost-conscious. So I’m confident they’re not likely to let egos run wild, and destroy shareholder value. The CEO strikes me very much as a man who would walk away from a deal, rather than doing a bad deal. That’s obviously subjective though.
Another key point on M&A, is that personally I would only want to see deals done, if the story could be sold to enthusiastic institutions, prepared to fund any placing at the current share price, or even a premium. I think it’s important that small shareholders like us are protected, as we don’t usually get access to placings. Also that adviser fees are kept under control, as we’ve seen some utterly ludicrous deal fees recently.
Ultimately, one of the key advantages to being a listed company, is access to fresh capital. If there are good M&A opportunities, executed well, then this could build into a bigger group.
Outlook - plenty of interesting stuff in here -
Whilst the nature of Intercede's business and customer profile is such that the precise timing of orders is difficult to predict, the first half of this year gives us several reasons to be cautiously optimistic. We have continued to demonstrate the strength of our product suite in our core market (PKI), which offers our Blue Chip client base the highest levels of authentication technology available. We are encouraged by the long-term nature of these customer relationships, which remain sticky and grow incrementally over time and provide us with a solid sales pipeline to support management's revenue target.
At the same time, Intercede has ambitions to generate further top line growth and we have identified various avenues to achieve this in the medium-term. We have expanded our TAM (Total Addressable Market) by moving into the FIDO space, which requires a rigorous but lower level of authentication technology and makes our products more relevant to a wider customer base.
Initial indications from the proof of concept phase are promising and we look forward to rolling this new solution out to both existing and new customers. With a renewed focus on growth, we have also implemented an M&A strategy which will concentrate on gaining exposure to adjacent and attractive markets.
With various positive structural growth drivers in play and expansion into new markets, the Board remains positive about the medium and long-term prospects for Intercede. As a such, whilst we remain cautious of the effects of COVID-19, the Board can confirm that the outlook for the second half of FY22 continues to remain in line with management's expectations.
My opinion - I remain astonished that Intercede is only valued at £47m, yet provides vital cybersecurity software for some of the world’s largest organisations, including various USA Govt Depts. The commentary explains how recent cybersecurity attacks are driving legislation in the USA to require more controls in this area.
Usually, small software companies like this trade at a hefty loss, and bleed cash, needing repeated fundraisings. Yet Intercede is already profitable, cash generative, and sitting on a cash pile that’s 18% of its market cap.
As I always say, if it can accelerate growth, then there’s a chance the market cap could really take off, and become a multibagger. I’m not saying that’s definite, because nobody can predict the future. But in terms or risk:reward, the company is reasonably priced as things stand now without any new contract wins, so accelerated growth would be a game-changer that we’re not having to pay for up-front.
Broker consensus is EPS of 2.6p for FY 3/2022, and 3.6p for FY 3/2023.
At 83p per share, those are PERs of 31.9, and 23.1 - which doesn’t include any adjustment for the £8.5m net cash pile. We would be looking at a PER just under 20 for next year, if we adjust out the cash. I find that an appealing valuation for a business in such a relevant, growth sector as cybersecurity. Which is already profitable & world-renowned.
What’s not to like? In terms of risk, the main one would be if the software fell over & customers abandoned it. Given that it has a 20-year record of serving major organisations, and many long-serving staff (so expertise retained), hopefully that’s very unlikely.
Other risks could be if the biggest clients which renew year after year, suddenly sprung a surprise and decided to cancel instead of renewing. Again probably not likely, but nobody outside the company really knows.
To conclude then, I think risk:reward for Intercede shareholders looks excellent. The way I see things, the current valuation of £47m seems tiny, considering this business provides vital software for so many major organisations.
The PER is reasonable on the existing level of profits, and there’s no dilution risk because it’s securely funded - although acquisitions could involve a placing - introducing risk, but also opportunity. Ultimately we have to trust management to get it right.
Then we have the potential upside from increased contract wins through the recently widened product range, and the partnership programmes which have already begun to bear fruit (8 new customers in H1).
Not a share for traders, I think IGP remains an excellent, and reasonably priced long-term investment. I’ve been in since 2018, and am very happy to remain on board. Can you imagine what it would be valued at, as a fresh IPO? Probably multiples of the current valuation. That’s one of the things I like about turnarounds - it takes the market a while to realise that the outlook has improved. Whereas IPOs are usually over-priced on hype. I'd much rather buy the cheap, overlooked turnaround, than an over-hyped newcomer. Then we have to just sit back & wait. Some do well, some don't.
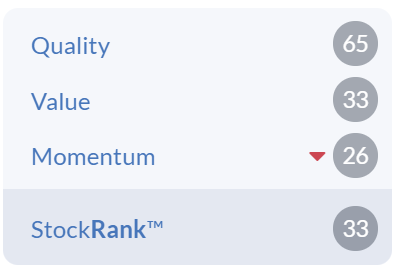
Stockopedia's computers don't really share my positive view, with a disparaging StockRank. A low StockRank makes me pause, and reconsider - is there anything I've missed?
.
Comments from Andy Hornby of Restaurant (LON:RTN)
Many thanks to the superb Propel Newsletter, which is essential reading.
I read its daily newsletter, if I can find the time, alongside the always superb & amusing daily updates from Langton Capital - both are hospitality sector experts.
I find hospitality interesting, because it’s so similar to my own sector specialism (where I was a CFO for 8 years in ladieswear retail, for those that don’t already know me here) - the dynamics of multi-site operations targeting consumers, are really very similar, except that in fashion retail, the customers are usually sober.
The reason I mention this, is that Propel recently published an excellent article with RTN’s CEO sector comments, which I summarise as follows -
VAT support ends 1 April 2022
Rent moratorium also ends at same time - so landlords can kick out tenants who are refusing to, or cannot pay rent
Net living wage also rises, about 6.5% I think
90% of staffing problems are back of house (i.e. kitchen). This got me thinking - why do most chains actually need chefs? If they simplify menus, and give proper training, they could employ (much more cheaply) cooks, not chefs. Millions of people know how to fry an egg, or a steak, etc. Most mass market casual dining food does not actually need a chef, who are notoriously difficult, and always want to do things their own way. My own restaurant startup was a disaster, I’ll tell you all the awful details when we have more time, but basically I threw away about £200k because I thought it would be fun to own some pubs & start up a restaurant. BIG mistake! It took years to get out of the personal guarantees on the rents (£2m over 10 years - what on earth was I thinking?!)
Launching apprenticeship scheme (good! Train up people, rather than exploiting cheap labour from abroad, which strips other countries of their best/trained people, so a form of negative foreign aid - deeply unethical, if you think about it)
Reviewing policy on sharing of tips (again - good. After all, why should the waiters get the tips, when the main driver of customer satisfaction is the quality of the food? Share the tips with the kitchen staff, at least 50%, I reckon)
Supply chain - it’s all about price rises, more than shortages.
Quick comments -
Appreciate (LON:APP)
Interim results - this company provides gift cards. The bull case is that it’s shifting online, hence might have good upside.
I’m not convinced, but am happy to keep an open mind. Numbers today show a reduced H1 loss on H1 last year. It’s an H2 seasonal biased business.
Lots of cash on the balance sheet, but it’s in trust, belonging to customers. Net tangible assets are negligible.
I’ve got 2 problems with Appreciate -
To be blunt, I don’t rate management - the last presentation was poor.
I don’t rate the business model - most people would love a £10 M&S voucher, but would not rate a £10 voucher from this company.
Poor customer journey - someone, I think it was the ONS, sent me a £10 “Lovetoshop” voucher from Appreciate, and it turned out to be worthless - I had to register on its website, and give an intrusive level of personal data (including date of birth) and then I forgot to redeem the voucher, and found it had expired when I did a very unusual removal of debris from my workstation. In my experience, and talking very generally, any business that leaves a tail of unhappy customers in its wake (e.g. Purplebricks) , is probably going to struggle to maintain profits, or even survive. I try to avoid investing in anything like that.
My opinion - based on everything I’ve seen to date, Appreciate could be a dud. Not something I would want to own, but we could be pleasantly surprised, who knows? I’ll keep an eye on it, because when the market cap gets this low, the potential upside can be quite nice if things improve. Some of my best profits have come from buying shares that everyone else hates & dismisses, where I’ve spotted a turnaround.
Well known investor, Richard Crow is very good at this, often spotting good turnarounds early. They don’t always work, obviously. I think the trick with turnarounds is to make 100%+ on the good ones, and to ditch the losers early, hence incurring a loss of under 50%. As always, easier said than done!
.
.
Harland & Wolff
Down 31% to 19.75p
Reason - equity fundraising for £7.7m after fees, including a Primary Bid element (flippers?)
The name “Harland & Wolff” rings multiple bells in my mind. The loudest are probably for strikes, and inefficiency in the 1970s & 1980s, then Mrs Thatcher losing patience, and withdrawing taxpayer support for old-fashioned, moribund operations like this.
But there’s more - they made the Titanic! Here’s the Wikipedia page.
Imagine millions of rivets, of possibly inadequate tensile strength, being banged into place, and occasional episodes of men plunging to their deaths from creaking platforms - it’s barely imaginable to think how cheap life was back then. People complain about elf n safety, but personally I think it’s a damned good thing we do value human life now. That should not be controversial at all.
My opinion - totally uninformed, as I’ve only just started looking at the numbers.
My first point is that a c.30% discount on a small £7m placing, means the institutions aren’t interested. A few are just taking a punt on it, with play money (for them), and want to dilute other shareholders, on a put up or shut up basis.
Secondly, on reading the most recent update from this company, I notice it has 250 acres of dockside land. Has this been sold & leased back I wonder? If it’s freehold, it could be worth a bob or two to someone else, I don’t know.
Thirdly, H&W seems to be pivoting to wind farms & stuff like that. As well as shipbuilding. It talks about £500m p.a. Revenues which seems very ambitious.
Overall, I wish them well, but it sounds a total punt, good luck to all involved. The commentary makes good points about a strategic need to revitalise the UK’s shipbuilding capacity. I couldn’t agree more. Maybe there’s a high risk opportunity here? If I was groaning with cash, I’d probably have a small punt, but … sadly not. South Korea & places like that seem to trounce the UK with shipbuilding.
.
Jack’s section
Wynnstay (LON:WYN)
Share price: 571.2p (+7.77%)
Shares in issue: 20,298,868
Market cap: £115.9m
A short ‘trading ahead’ update from this agricultural supplies group today. Wynnstay shares are illiquid, and the company itself can be seen as boring, but that can often be a positive for those not chasing lottery-type returns.
It’s a sensibly managed, dividend-paying enterprise that has been operating for more than a century now, and a solid long term hold candidate for those who can afford the liquidity and cyclical risks.
Trading since June, and for the key trading month of October in particular, has been strong across all core activities.
Certain areas have outperformed the Board's expectations especially fertilizer blending activities, which experienced certain one-off benefits, and joint venture activities. As a result, the Board now expects that underlying Group pre-tax profit* for FY 2021 will be significantly ahead of current market forecasts.
The group is experiencing strong farmgate prices across almost all categories, which has continued to buoy farmer confidence and farm re-investment. Tonnages and yields have reverted to more normalised levels following a poor harvest last year, boosting arable activities in the important final quarter of the financial year, and grain prices remain strong, while the Specialist Agricultural Merchanting Division experienced strong demand from farmer customers across all major categories.
The group has so far avoided significant disruption due to inflationary and supply chain pressures, and ‘expects to be able to continue to manage these operational and cost challenges effectively, although some imported product lines have experienced delays and this may continue.’
Outlook - The board believes that the short and medium term outlook for agriculture and farm commodities in the UK remains positive.
Conclusion
A short update to confirm that trading is ahead of expectations. Agricultural commodity prices can be cyclical, but Wynnstay has a fairly low risk expansion plan revolving around organic growth and bolt-on acquisitions to build out its presence across the UK.
It’s got a great dividend track record and is prudently run.

While margins are low, they are resilient, and the group is reliably cash generative. Returns on capital employed are also fairly low, but the group has good asset backing and shares trade at around 1.35x net tangible book value.

The valuation is returning to the higher points of its historical range and has recovered strongly since 2020. It’s also likely that, at some point in the future, Wynnstay will be forced to navigate less favourable farmgate conditions. But the conditions are currently positive and, as a long term hold, this continues to strike me as a good candidate. Unfortunately, building up a meaningful stake can be tricky.
Mulberry (LON:MUL)
Share price: 340p (+12.58%)
Shares in issue: 60,077,458
Market cap: £204.3m
Mulberry is a British luxury lifestyle brand famous for its iconic bags. The shares bombed a couple of years ago after poor trading exposed its hefty cost base. Today, the share price is up significantly but still well down on levels seen four years ago, and commercial leasing dynamics have changed for the better.

Looking at the historical results, revenue held up reasonably well until FY20 while profits deteriorated, so perhaps it’s been more of a cost base issue than fading popularity? Checking back through the Mulberry archives, Graham covered a poor trading update and exposure to the House of Fraser collapse back in 2018.
Turnarounds can be very lucrative when successful, and Mulberry has the same number of shares in issue as it did back in 2017/18, but a lot here will depend on the quality and popularity of Mulberry’s products. So if anyone has any insights there as a customer then please do share.
Highlights:
- Group revenue +34% to £65.7m,
- Profit before tax of £10.2m, up from a loss of £2.4m (including £5.7m profit on disposal of Paris lease),
- Gross margin of 69%, up from 59%, ‘due to a strategic focus on full-price sales and increased volume efficiencies’
- Period end net cash of £30.3m (2020: £8.6m) and deferred liabilities of £5.0m (2020: £4.6m)
Breaking down the group revenue, UK retail sales were up 36% to £38m, Asia Pacific sales grew by 23% to £11.8m (helped by China, up 38%), and US retail sales increased by 57% to £3.3m. International retail sales in total represented 40% of group revenue. Franchise and wholesale sales jumped 67% to £10.1m. Meanwhile, digital sales were 29% of total - down on last year but up 20% on 2019 ‘reflecting the ongoing strength of this channel’.
Supply chain challenges have been managed:
The combination of our UK factories, careful planning and agile supply chains has enabled us to successfully navigate the well-publicised difficulties in global logistics, with no impact on fulfilment to our sales channels.
Current trading - Retail revenue in the 8 weeks to 20 November 2021 increased 35% compared to the same period last year. Gross margin in the second half is expected to be similar to, or slightly higher than, the 67% achieved in the second half of last year. The Group is expected to continue generating cash from operations in the second half and, with its deferred liabilities expected to unwind, the Group will maintain a strong cash position at the year end
Sales are expected to continue to grow in the second half, and retail revenue in the 8 weeks to 20 November increased 35% compared to the same period last year. Gross margin in the second half is expected to be similar to, or slightly higher than, the 67% achieved in the second half last year.
In view of the strong performance in the first half and the Group's substantial cash reserves, a progressive increase in marketing expenditure is planned in the second half to continue building brand awareness worldwide.
Projects are in place to move the group's legacy systems forward, and to develop the next generation of digital and omni-channel platforms. This is expected to lead to increased capital expenditure next year and beyond.
Longer term, Mulberry hopes to become the leading responsible British luxury brand ‘and a pioneer in sustainability’, which sounds promising from both ethical and marketing perspectives. The group says:
We believe the opportunity is substantial and we have taken a progressive leadership position in this space, investing in products that are made to last, and offering customers circular repair and buy back options through the Mulberry Exchange.
The balance sheet could do with more work and lease liabilities remain significant at £70.9m, although this is down from £88.2m. The current ratio is solid at 1.7x and the cash balance has improved, so the direction of travel appears to be positive.
Conclusion
It should be noted that the outlook continues to be subject to a degree of uncertainty as the important festive period commences. Lockdowns over these key trading months would materially change the prospects in the short term.
That aside, it looks like the turnaround is worth digging into here:
The reduction in lease liabilities (current and non-current) by £17.3m to £70.9m (2020: £88.2m) is primarily due to the renegotiation and termination of certain leases.
That’s an encouraging reduction in the lease cost base. Meanwhile, the company is confident of ending the year in a strong cash position.
Store sales are roaring back post-lockdowns and the group is gearing up to invest in marketing and systems. The latter brings disruption risk if anything goes wrong while updating legacy systems, but assuming there are no issues then this should make for a more efficient operation.
No equity dilution, either, unlike Ted Baker (LON:TED) for example. The shares have more or less trebled since the 2020 low, but remain well down on the 1,000p+ range they were trading at a few years ago.
It would be good to see more director buys and institutional interest, but the free float is so small that there’s really not much liquidity for statement purchases. It’s a tiny free float, just 5.7%, meaning the amount of shares you are able to trade is again a consideration.
Can the brand reclaim its former glory? The company is confident, as you would expect, and the results suggest signs of life. Oddly though for a luxury lifestyle brand, Mulberry has really struggled to generate good margins in the past, so with a market cap now north of £200m, the company has to prove its profitability.

Mulberry operating margin
Compare that to Burberry (LON:BRBY) , for example (below). I wonder why this huge gap in margins existed even when Mulberry was more favourably perceived by the market. The group’s H1 2021 operating margin is a much improved 18%.

Burberry operating margin
Signs of meaningful revenue growth could be a strong catalyst, given the group has struggled here in the past.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
I bought Wynnstay (LON:WYN) August 2020 as a speculative buy at 334p it's been one of my better choices. thanks to Stockopedia.
Is it just me......... or is just about anything on AIM getting crushed at the moment?
Hoping Santa turns up next week after the American Friday Fake Offers Day.
Crushed. Could not agree with you more, Jack. The MM's are truly extracting the Michael.
Santa won't be able to make everyone happy this Christmas.
And in a lot of cases on pretty light volumes.
Maybe MM's trying to shake out the new (Covid WFH) breed of trader ? You dont want to be holding anything that has a T/U , or is reporting any results unless they are stella ATM.
Richard
Wow Richard, you certainly like your acronyms, four in one sentence!!!
Everything is getting crushed! I agree. Today's losses are tomorrow' profits. If we keep focused on the fundamentals, it should be great. I can see a 10% divi yield from things like Scs (LON:SCS) (I hold). Salivating at some of these valuations for smashing businesses!
(although we have to be serious - if something is badly wrong, then it deeriorate)
Would appreciate a second opinion from somebody on Rotala (LON:ROL) - a previously profitable and now recovering bus company with a tiny £15m market cap.
They have been kept in great shape by the government during the pandemic (revenue's actually up because of grants) ansd busses deemed an essential service. One that seems at the mercy of future political situations if ridership doesn't recover (do bus routes get nationalised, or does government just pay private companies more?)
Regardless, the valuation is strinkingly attractive in my opinion (price to sales 0.17 as one metric), and the directors are buying in spades.
Interesting write up on Appreciate (LON:APP)
I just watched the presentation here https://www.piworld.co.uk/comp...
The CEO is very uninspiring but thought it was OK. Company looks on course to meet expectations for the year. I did zone out near the end when the CEO started droning through his script. Hes like a really annoying Irish text to speech bot.
Liberum thought H1 were better than expected. They have EPS for 2022 and 2023 as 3.25p and 4.12p
Historically its been on a multiple of approx. 11-15, so on a PER of say 12x you get towards a price of 39p and 49.5p compared to todays price of 22p.
No dilution during pandemic so back to historic EPS of 5p would be a target of 60p.
There seems to be a decent selection of retailers (Including M&S) Can exchange for e gift cards in other retailers.
https://www.highstreetvouchers...
I didnt like the reduction in net cash or dropping the ring fencing of funds from digital balance's. Liberum have net cash at £15m for 2022, down from £19m at last update.
Company dont expect to need RCF tho.
6-7% yield is nice.
I suspect many businesses will scrap Xmas parties again this year so there should be demand for vouchers?
Overall I quite like it. Personally dont think theyll have to do blow the doors off, just getting back towards pre pandemic levels of profitability in the next 1-2 years would be enough I think to double the share price. Theres been a big seller for a while here by the looks of things, so this hasnt helped the price.
Ive bought a few this morning
I also don’t believe that Appreciate is a turnaround business, yes they are trying to drive growth and yes there has been a Covid hit.
Total billings in the business have been relatively flat for a number of years. With a decline of £419m in 2020 to £406m in 2021 and £388m forecasted in 2022, this is due to Covid.
At the same time the business, because it has struggled for growth (and has been flat) is moving towards a digital model whereby it can recruit customers in a more targeted way. They have sold their hamper business in a move towards digitization and yes they are making some changes but I don’t see it as a turnaround as the business isn’t in decline apart from the hit from £419m to £388m impacted by covid.
In terms of the decline in profit, there have been a number of non-cash expenses including depreciation and impairment. They have no debt and hold net cash of circa £15m (not the ringfenced funds in trust, that is of course separate). At the same time as this, the business has been heavily investing in intangible assets in it’s move towards digitisation but has not had to take on any debt or raised any further funds. The business has also managed to keep paying dividends.
I agree that vouchers can be pretty uninspiring but it’s a big market. They only currently have 3% of the vouchers market and they see the move to digitization as a big opportunity to drive market share. However alongside this they have the Christmas savings business which is around 40 years old and is 43% of the billings, in this sector they dominate with a 76% market share. The Christmas savings business seems to keep delivering year after year and was hit with a drop in sales of 16% due to covid. The business has stated they don’t know yet if they will recover this 16%, but this feels like a worst case. So if the 16% drop is lost next year aswell, then it’s still a very solid business even if only at 84% of what is was 2 years ago it still delivers approximately £176m of billings.
In terms of the management, yes probably uninspiring. I see appreciate as a form of short-term bank. People pay in money to save for Christmas or to buy a voucher which is redeemed at a later date, the funds are held in Trust in the meantime. The board have a lot of experience working within the finance/banking sector.
Ao World (LON:AO.) Paul you say "It seems to suggest that AO is effectively selling goods at a loss, once its overheads are taken into account, but makes money on extended warranties, product protection plans, etc".
I agree, and not a lot changes, anecdotally years ago I worked closely with what were then the REC (Regional Electricity Companies) retail arms. It did not take me long to learn that the entire business model was based on selling extended warranties. These policies were all written by insurers in the Channel Islands (owned by the RECs and therefore 'captives') for 'tax planning' reasons and the directors used to have very extravagant annual board meetings on the islands to celebrate another bumper year.
Triples all round!
Hmm! I have that effect on people LOL :-D Whoop Whoop!
Belfast whoop whoop! Lovely
With Ab Dynamics (LON:ABDP) am I correct in reading a share price decline of 12% over the previous two trading days, prior to their Final Results, and a relatively flat day today upon the actual news release? Hmmm.
Having followed the travails of Harlands Harland & Wolff Group (LON:HARL) in a previous life, this placing (seemingly the third in a year!) has prompted me to take a spool through their most recent RNS and to be pleasantly surprised by the coherence of what they are trying to do. The company now known and H+W is essentially an amalgam of four operations - including the Queen's Island site in Belfast and the Appledore yard, along with two fabrication yards in Scotland. The company used to be called Infrastrata but quite sensibly changed its name to something that anyone with a passing knowledge of the shipping industry will recognise. Heritage Brand and all that, if sometimes remembered for the wrong reasons. But as has frequently been pointed out in Belfast, that very famous boat 'was all right leaving here'.
In recent years the Belfast yard has made a living doing repair work and fabrication, having the advantage of one of the biggest dry docks in Europe. It seems the current owners are trying to put together an integrated business in the fabrication/refit/repair part of the shipping/offshore/renewables industries, and without recourse to bank facilities to fund the upgrading of the facilities and human capital, they've used a series of placings to raise the money to cover the increased overheads before contract income starts to kick in. They claim to be in a position where they will stop burning cash by the end of the year, with a strong pipeline of contracts/interest.
Definitely not a widows and orphans stock, but if, and its a big if, management can execute on their strategy then it might be quite interesting at a market cap of only £24m. Would be interested to hear from anyone with a detailed knowledge of the sector, but am tempted to take a very small position. Tempered by decades of watching the old yard shrivel to a shadow of its former self, despite repeated promises of a bright future.
For those who keep an eye on De La Rue (LON:DLAR) (in-line as MrContrarian helpfully pointed out while we were still making coffee), there is a section in the results presentation that summarises the pension position:
The IAS pension valuation moved to a small net surplus of £0.3m as at 25 September 2021 from a net deficit of £18.5m at 27 March 2021 as a result of a positive performance of the scheme assets which was partially offset by an increase in liabilities primarily due to a lower discount rate used in the valuation due to a small decrease in corporate bond yields during the period
• Agreed contributions of £15m per annum (for three years to March 2023 then £24.5m thereafter to FY 2028/29) under the Recovery Plan pension contributions agreed in June 2020
• Additional contributions payable only in exceptional circumstances
• Next triennial valuation in 31 December 2022 (results by April 2024)
De La Rue (LON:DLAR)
Being frank based on those quoted numbers De La Rue is pretty much uninvestible for me at or around current levels(8-10 pe is cheap but on the basis their profits are their profits to keep which they are clearly not). Why would anyone take the risk when the first 30% + of earnings (will be higher if profits take a hit) is going straight to the pension pot. Its a warning also that the lack of a deficit for other companies doesnt mean they won't be putting their hands into their pockets going forward in material fashion compared to what they are doing now. (I hold norcros - thankfully their current contributions are orders of magniturd less at present but they are not without risk of being forced simialr random increases going forward)
What are pension contributions exactly? Why does a company has to pay historical contributions to its employees? Is this something that is no longer applicable these days?
@luckystrike23. 'Pension contributions' usually means that a company has a defined benefit pension (DB) pension scheme that the actuaries say has liabilities that exceed its assets. The company then has to agree with the trustees of the pension fund a plan of contributions to eliminate the deficit over a few years. Companies have been closing their DB pensions to new entrants, but many still have pensioners whose pensions the scheme is responsible for.
To expand on FREng's explanation, my DB company pension was closed by a completed take-over by a company and the new-style pension put in place for existing the workforce. The DB pension scheme had already been sold on to a company specialising in these things and which is now in talks about dealing with the deficit with another manufacturer who has recently bought the company from the first buyer. The Trustees of a pension scheme need to stay very alert, in the passing on of prior-made agreements during take-overs things could go very wrong for pensioners like myself.
"What are pension contributions exactly? Why does a company has to pay historical contributions to its employees? Is this something that is no longer applicable these days?"
Silver moon and FREng - have hopefully clarified suitably.
My take is that you need to check every company you may invest in too see if there is historic or even current pension issue. It was traditional to have defined beenfits (DB) but they are very rare now. The problem is even when these schemes are closed for future entrants you are still in Hock for what your past promises were (and future stuff too posibly).
Ref De La Rue - at March 2020 they had current obligations owing to pensioners of over £1 billion. They have a matching pot of funds invested give or take (the defecit or not).
However if the investment pot doesnt generate expected returns or the pensioners live longer than it is estimated they will live onow r if inflation is too high or if anything else goes wrong - then the company is on the hook for the shortfall compared to what they have put aside. Like a giant bank of mum and dad that should never run dry.
On a scale of 1-10 ref size of pension obligations pot compared to profits made (simple measure of risk) i would say De La Rue is probably 9.5 out of 10 - ie very risky.
With £1 billion pot if they had 2 % shortfall each year either with bods living longer than expected or investment pot not making sufficient returns that would cost the £20 mil quid a year.
Note practicably speaking i may be over egging the risk somewhat i am no specialist here but facts are as per quoted figures today - they will have as things stand cash cost of £24 mill year that they need to fund from ongoing "cashflow" that will be out of business profits unless they take more drastic action to find that cash from other means.
• Agreed contributions of £15m per annum (for three years to March 2023 then £24.5m thereafter to FY 2028/29) under the Recovery Plan pension contributions agreed in June 2020
Clarity in the murky pool of pensions! Well done !
It's firms which have defined benefit pension schemes ie they have backed a scheme which has promised workers a certain level of benefits on retirement. If that scheme has insufficient funding to meet present or future benefits levels then the firm (in the first instance) takes the hit. The reality is a lot more complex as it is a whole area of specialist accounting and actuarial work based on schemes liabilities and assets forecast many years into the future. The situation wasn't helped by many companies awarding themselves money back from the pension scheme or contribution holidays for while when times were good 30 years ago.
These days most firms do not now have these types of pension schemes open to join but the old members still have guaranteed entitlements.
Sometimes companies pay the insurance sector to take the whole issue off their hands (and balance sheet/P&L).
My past employer did in fact take 7 years of pension holiday straight in the good times. There was some kind of excuse enabling this but of course employee contributions did not enjoy the same holidays. The Unions representing the various groups of workers resented it but seemed to be unable to successfully challenge these decisions.
Silver Moon
For Ao World (LON:AO.) low margins aren't particularly an issue for a company with a very low equity ratio (shareholders funds/total assets). Shareholder's funds are only £97m and it has revenue of £1.7bn. Even a 5% net margin is £85m and a 87% ROE.
This is a relatively low capital, high volume business but there is risk associated with rising costs and sustaining revenue because that's where churn degrades the cash position.
It seems Ao World (LON:AO.) World need to be careful of not overstretching but I don't think the business model itself is particularly bad, it is just like any other retailer or bank: have good working capital by extend payable days and reduce receivable days. Unfortunately, they are having to extend credit terms to customers to draw in business and sustain revenue levels which I think is risky.
Comparing this to Currys their main competitor, for example, their net margin is only c. 1% which is why it trades at 0.15x sales.
It's hard to take a position on what is a good share price level at the moment but I do think people are too quick to run when they hear 'supply chain issues' at the moment.
I've got to take issue with you on this -
For Ao World (LON:AO.) low margins aren't particularly an issue for a company with a very low equity ratio (shareholders funds/total assets). Shareholder's funds are only £97m and it has revenue of £1.7bn. Even a 5% net margin is £85m and a 87% ROE.
AO is nowhere near a 5% margin. It's actually at a 0% or below margin. See the interim numbers issued today.
It's a rubbish business, that loses money.
The lunatic running it, needs to be kicked out.
I would say the equity is worth nothing.
Good luck - you'll need it!
Paul.
Rather childish reply but looking past that...
Every single retailer gets their inventory in August time for the holiday season so gross margins flat in Q3 is nothing surprising. They had flat margins last Q3 and positive for the next three. Q4 is the main trading obviously.
Aside from that, I wasn't saying I owned it or it was worth buying (I rather said the opposite above) but I was pointing out your analysis that a low margin business is a 'poor business model' is wrong as many businesses; like banks, have extremely low margins but low capital and high volumes/revenue comparatively.
Eneraqua Technologies (LON:ETP) IPO'd on Monday here's and introduction by management. Video and podcast.
They are "a specialist in energy and water efficiency. The Group has two divisions: energy and water. Energy is the larger division, with the Company focused on clients with end of life gas, oil or electric heating and hot water systems. The Group provides turnkey retrofit district or communal heating systems based either on high-efficiency gas or ground/air source heat pump solutions that support Net Zero and decarbonisation goals."
UK only at the moment looking for international expansion. Growth through organic growth including NPD and international expansion and M&A. Slater took 5%, management still have a large stake. Admission doc is on their website but took me a while to find.
Appreciate (LON:APP) interim results presented to analysts yesterday 23.11.21. Video & podcast. Normal H2 weighting. 'H1 robust'. Obviously a strong bounce back from last year. Continuing the strategic rollout with an improved digital offering and platform which is more scalable.
Ig Design (LON:IGR) H1 22 results presentation to investors yesterday 23.11.21. Video & podcast. CEO Paul Fineman is a very compelling presenter. Demand is strong but supply chain challenges and cost headwinds have hit margins. Longer term they are still positive to hit $1.5bn turnover and 10% adjusted EBITDA of $150m.
Do join us next week for Tpximpact Holdings (LON:TPX) interim results webinar with CEO & CFO including a Q&A session. Thursday 2nd December at 11am. Register here.
And, for the incredibly popular Stockopedia/PIWORLD StockSlam, which is on Wednesday 19th January at 6pm. Register here.
Morning Paul,
I was very interested to read your experiences in the pub and restaurant business and wondered when you had more time you could give more detail .I also have had a variety of different businesses over the years ,not all winners .
I must congratulate both yourself and jack for your daily contributions as to write on any subject daily needs a great deal of focus and dedication, please keep up the good work.
I second that..after exiting my business very well in 2008 I thought I could walk on water and promptly made some very bad decisisions and fell flat on my face!!
Join the club!!
Hi Spongbob,
I was very interested to read your experiences in the pub and restaurant business and wondered when you had more time you could give more detail .I also have had a variety of different businesses over the years ,not all winners .
I must congratulate both yourself and jack for your daily contributions as to write on any subject daily needs a great deal of focus and dedication, please keep up the good work.
Oh my goodness, it's too painful. Why not? Just constant cash outflows. So whatever entrepreneur seems credible. The initial maybe £40-50k cash investment is the first. Then they want more, and more, and more. I had to pay £5k just for for fckuing cuttlery - because the locals were stealing it.
My advice - NEVER OPEN A PUB OR RESTAURANT.
lOVE, pAUL.
There's one sound, against my window! Doodle dibble! Aganist the pillow, where his head used to lay!]BOOOOHHHH!!!!!! I cant stand the rain!!!!!
oh woah the pillow!!!
I cant I cant stand the rain!!!!
OOOOOOOOOOOHHHHHHHHHHHHHHHHH
Just wish to add to the Harland & Woolf comments. I am fascinated by the progress of the management team behind this business. The started out with a gas storage project (Islandmagee) in Northern Ireland. Gas storage is desperately needed in the UK but even more so in the island for Ireland. Project is progressing slowly as these things do but still has great potential. H&W were to be the M&E contractor to build the gas processing unit for this storage project. They are engineering this storage so that it can take hydrogen as well, future proofing this project.
They saw an opportunity to acquire H&W (in the cheap?) and have since added Appledore in Devon and a Scottish ship yard. They are now touting for MOD contracts. Claim to have one of only two docks capable of taking the Queen Elizabeth aircraft carrier.
In my opinion very impressive the way they are building this business and who knows with on-shoring / supply chain issues / Brexit etc their timing might be very good for establishing a UK heavy engineering business involved in shipping, energy security and renewable energy.
As to whether it will make a good investment, I haven't got a clue!
Marlowe (LON:MRL) has reported a strong trading update this morning.
Trading in the first half of the financial year was strong and the Group now
expects to report FY 2022 full year results ahead of current market
expectations as a result of strong organic growth and the successful execution
during FY 2022 to date of our Deepen, Broaden, Strengthen and Digitalise
compliance software and service strategy:
H1 FY 2022 Group revenue up 61% to £134.5 million
Organic revenue growth of 15%1, 8% when adjusting for COVID
impact(2)
H1 FY 2022 Divisional adjusted EBITDA(3) margin increased 300 bps
to 17.8%
H1 FY 2022 Adjusted EPS up 50% to 16.0p
H1 FY 2022 Adjusted profit before tax up 127% to £15.2 million
I'd welcome Paul's forensic accountant's view of the adjustments.
FREng
Paul, thank you for your very clear views, which are always helpful. With Intercede (LON:IGP) the stock performance has been very strong over the last three years relative to Sales growth (even given the recent correction), so I believe management needs to demonstrate that they can deliver significant top line growth before we return to summer highs, maybe the strengthened balance sheet will allow this, but valued on a v high sales multiple, with good margin capture there is little room for performance otherwise. M&c Saatchi (LON:SAA) looks like the reverse, really poor margin capture and continued dilution through share issuance - it would appear the there is significant room for performance there if management can refocus the business and take some cost out - S4C for instance is trading on a sales multiple of roughly 10 times stronger. For M&c Saatchi (LON:SAA) I can only agree with your commentary that management/staff want a slice of the action, indeed there needs to be some evidence that shareholder returns are a priority before this stock performs.
Kin And Carta (LON:KCT) the CEO’s private investment vehicle has just done a secondary placing of 5 million shares at 301p via Numis yet the shares are up slightly this morning.
No explanation given for the sale although the shares have set new highs in the last few weeks. To be fair to him though the SP is a million miles away in the transformation he has led compared to when he got involved and since nearly going under when it was St Ives a few years ago.
They said it was on behalf of his children and done for Estate planning - ie tax.
What I didn't like was the share price went down 36p during the day on no news to guess what, 301p which is exactly where the placing was then done in an ABB. Hmm that doesn't sit well as suggests it was leaked.
But that is why the shares are flat on the day. Clearly someone or various instis are happy to pay 301p for 5m shares so that theoretically should form the base, though it doesn't always.
Thanks for that observation davidjhill, I have, in truth, been so amazed at the share price growth that I was focussing on Schwann getting out at the top not the possibility of new investors joining the broomstick for the ride. Back to greater fool theory!
Great effort Paul & Jack!
Come on fellow readers - 50 likes for an outstanding contribution by Paul & Jack is rather pathetic! These guys provide outstanding content so please ensure you hit the thumbs up to show you're appreciation!
I can't even find my way to the bathroom when these guys are analysing the RNS's!
Revolution Beauty (LON:REVB) have H1 results out. Looks strong results and there is a note out on Research Tree for those that can access.
Hartland and Wolff Harland & Wolff Group (LON:HARL) I don't hold. From memory they do not own their own land (in a valuable location) rather it is held on a fairly restrictive long term lease from Belfast Harbour Commissioners. I could be wrong, but that's how I remember it from when I used to know about these things.
Re IGP
Looks quite interesting but raises some major questions. If its customers include Boeing and Wells Fargo, not to mention the US govt, why is its turnover barely in double figures (m)? It must form a minuscule portion of their cyber spend, while potentially being squeezed out by the horizontal expansion of identity giant OKTA and other fast growing identity management leaders like PING, or even slow-growing security giant Thales. Would that make it a take-out target? Perhaps - it’s certainly accretive, but is it too small to register as worthwhile? I have no comment on their tech unfortunately.
RE Intercede (LON:IGP)
If its customers include Boeing and Wells Fargo, not to mention the US govt, why is its turnover barely in double figures (m)?
It's because access to end customers is controlled by integrators who take the bulk of the revenue. That's generally typical when a tiny tech company contracts with a massive organisation - no major company will risk working with a small one for something that's business critical, so the integrators take the risk. Integration used to be a complex process, that may have changed.
They tend to target specialised sectors like US government agency identity, which has specialised requirements and isn't the kind of thing OKTA is interested in. So the difference in market cap is explicable in terms of the relative addressable market, for starters.
A takeover would be tricky as if it comes from an existing partner it would upset all of the other partners. So that would depend on the technology being of interest to someone. Which is may be, it's years since I was close to it.
timarr
Very helpful, thanks. However, if they have no hook into the end user, then there is no land and expand opportunity and they are vulnerable to two sets of commercial imperatives instead of just one, the integrator’s as well as the end user’s. Of course the same could be said of Calnex Solutions (LON:CLX), which I like a lot, and which transacts through Spirent acting as a reseller. I’m probably more concerned about the glacial growth to date, which hints at declining traction in an area of major expansion of demand and budgets. On the other hand, finances could be at a major inflection point. There’s no doubt about the potential operating leverage of revenue growth from here. An interesting balance of risk and opportunity.
It's worth noting that IGP aren't an identity provider. The product they offer is meant to support the actual identity providers capability, not replace it.
Another disappointing set of numbers from Iqe (LON:IQE)
They do seem to be serially unlucky, as the reasons given for the issues are outside their control. Whether it be a ban on supplying Huawei or slow roll out of 5G there’s always something holding them back it seems. But surely they should be making more progress on sales into the 5G handset and infrastructure markets, despite this, as they have great products for that, or so they tell us.
Unfortunately I still hold some. Stop tittering at the back!
I once had a tour round IQE's Newport fab something like 20 years ago, and listened to the pep talk on the wonders of VCSELs and gallium arsenide. Very little appears to have changed except the number of shares in issue....
Drew Nelson has probably done OK out of IQE, unlike many of his shareholders. Graham Neary has covered the LTIP/dilution issue on numerous occasions here on Stocko - it is worth going back and reading his posts.
The story has always been tempting, despite the perennial disappointments and some questions over the accounting.
A similar company is Filtronic...which I note Stocko is now awarding an 87 quaity score to...
These companies get sandwiched between hefty fixed costs (semi fabs and reactors don't come cheap) and huge swings in demand from much bigger customers who seem to extract most of the margin.
Hi Monty
re Iqe (LON:IQE), I agree - the sandwich has always been too thin, and they have too little leverage over pricing. My feeling has been that the former CEO, Drew, was a poor negotiator on price.
Great effort overnight Paul - I always really admire your speed and work rate and would like to hear how you do it someday as there's something for me to learn there!
On Appreciate (LON:APP) can I challenge that I think the short-term bull case is a bit more than the switch to digital products. I think it is:
1. This hasn't recovered from the pandemic yet so it is a play - now rare among shares - on recovery from COVID. Specifically it's Christmas savings product in this financial year was hit by the 2021 lockdown because it reduced the ability to do face to face marketing at the key selling point at the start of the year. The company didn't do any fundraising during the pandemic, so there is a potential for 100-200% upside here if it can return to pre pandemic profits (5p EPS and above) and goes back to its historic rating of 11-15x earnings
2. This share is also a play on interest rate rises because it makes money on holding customer cash. In its last note before ending coverage, Edison noted that a return to 0.5% interest rates would have increased profits by 25% in the current financial year. The most recent broker forecast from Hardman does not factor in any interest rate rise which looks guaranteed now in my view.
While we wait for all that there is a nice 6.5% dividend to keep us happy.
I definitely wouldn't want to hold this business long term but i think it's a good short term opportunity. This has been a key holding for Lord Lee in the past although I haven't checked whether he still holds it currently.
The most recent free broker note from Hardman and Co goes into a lot of detail about the business for anyone who would like to research further.
Appreciate (LON:APP) is still on Lord Lee's register of shareholdings: https://members.parliament.uk/...
Hi Paul. Thanks for the comprehensive write up on IGP: (I hold this time!). I have traded a couple of times. Sometimes its quite liquid and other times quite tricky to buy in any volume. At the moment the market hasn't been keen to buy, with some persistent smallish sellers. I noticed yesterday somebody parted with 16,000 shares @81p. He pointed out the newbie on the holders register this year, Lion Trust Investments have been buying again. I have had a couple of exchanges of email with the CEO recently. Klaas pointed to the 9% increase being 'heading in the right direction after a massive turnaround.' No concerns about competition from bigger companies like Darktrace, very different products. A record 8 new contracts and high retention of customers in Fincapp's report yesterday keeps their £1.25 target and underlined global partnerships ( they seemed pretty quick to slash targets in 2016 when things were not so good) for potential growth and the man hours in developing their unique software as undervaluing their 'government grade' intellectual property.
Klaas dismissed the sell off as general AIM drain. Whilst that is true to an extent there are a few AIM companies that have exceeded expectations. He wouldn't be drawn on whether there might be a larger weighting to contracts in the second half, which is what some companies claim. Whilst risks abound with the speed of advancement and change in technology, as they pointed to several cases of breaches in security this year which can lead to heavy fines and losses and undermines the integrity of those companies. Ultimately it has to be cost effective too. I am totally confident that these guys know as well as anyone about that. Meet the Company presentation tomorrow to follow.
Paul,
I think it was Vin Murria’s involvement that drew your eye to M&c Saatchi (LON:SAA)
Fantastic amount of work here Paul, it amazes me how much you and Jack get through.
I live near Harland & Wolff's dockyard in Belfast, so was tempted by the IPO but haven't got much cash sitting around at the moment. The wind turbines they knock out are very impressive to see in terms of size, would be a big boost for the area if they could keep upgrading.
if anyone ever gets a chance to come over then the Titanic centre is worth a look as they really do show you what the dockyard workers went through to make the ships.
Yes. Great effort Paul. I did buy some Harvard International Ord (LON:HAR) in the placing. It is sized at an amount where I can afford to lose 100%.
The bull case is (1) the Govt support for UK shipbuilding and the offshore wind industry - with local production requirements; (2) the Islandmagee gas/ hydrogen underground cavern storage project, which management estimate on its own is worth more than the market cap (even after the recent raise).
The fact that the shares are trading where they are is a reflection,in my opinion, of:
a) the market giving a heavy discount to any statement from the current management;
b) exasperation at the remuneration of the current management;
c) a history of repeated fundraises and despite management talking about the business turning cash flow neutral imminently and having access now to (very expensive) debt, a belief that this my be unlikely to be the last
Sorry. Wrong ticker. My last comment refered to Harland & Wolff Group (LON:HARL) - Harland & Wolff
Hi Wimbledonsprinter
You can normally edit your posts for about 20mins after publication - small pencil symbol at the bottom.
Did they not find the skeleton of a young boy inside the hull or was that a half remembered nightmare?
Wow Paul - amazing effort. You must have been up all night. Great work & thank you.
I listened to yesterdays presentation of Hostmore (LON:MORE) on InvestorMeetCompany last night and was hugely impressed.
The CV's of the CFO & especially the CEO show a huge amount of experience in expanding a brand/business and their strategy for the future appeared well grounded and realistic. They both came across really well.
They confirmed that the current SP weakness is due to an overhang of stock from the demerger where people who cannot hold single Co's have been selling out. I am hopeful of a major rerating over the next few months as the strategy begins to be delivered.
Whilst the presentation/interview is just over an hour long its a lot shorter if listening at x1.5 or x2 speed - cant remember who told me that trick, but it saves a lot of time on podcasts etc.
I Hold.
Come on Jack - keep up!
Come on Jack - keep up!
Not at all, it's me catching up from a day of inefficiency yesterday! ;-) I couldn't handle all the company updates on my own, so having Jack on hand to take up the strain is invaluable.
Best wishes, Paul.