Small Cap Value Report (Weds 25 Nov 2020) - G4M, SCS, D4T4, FUL, DLAR

Good morning, it's Paul here with the SCVR for Wednesday.
Timing - I've got essential travel today, so will have to finish early - estimated at noon. Update at 11:26 - change of plan, I'm going to print off the results for DLAR, and review them on the train home to Bou'mth. Then I'll type up my notes once I'm home, so late afternoon.
Agenda - these announcements look interesting;
Gear4music Holdings (LON:G4M) - Director selling (Paul, done)
Scs (LON:SCS) - AGM Statement & Board changes (Paul, done)
D4t4 Solutions (LON:D4T4) - Half year results, six months to 30 Sept 2020 (Paul, done)
Fulham Shore (LON:FUL) - AGM statement & trading update (Paul, done)
De La Rue (LON:DLAR) - Half year results (Paul, to do later)
.
Gear4music Holdings (LON:G4M)
(I hold - Paul)
730p (unchanged) - mkt cap £157m
There were 2 announcements last night, detailing that 4 Directors of this online musical equipment retailer are selling some of their shares at 730p (market price). These have been placed with institutions?
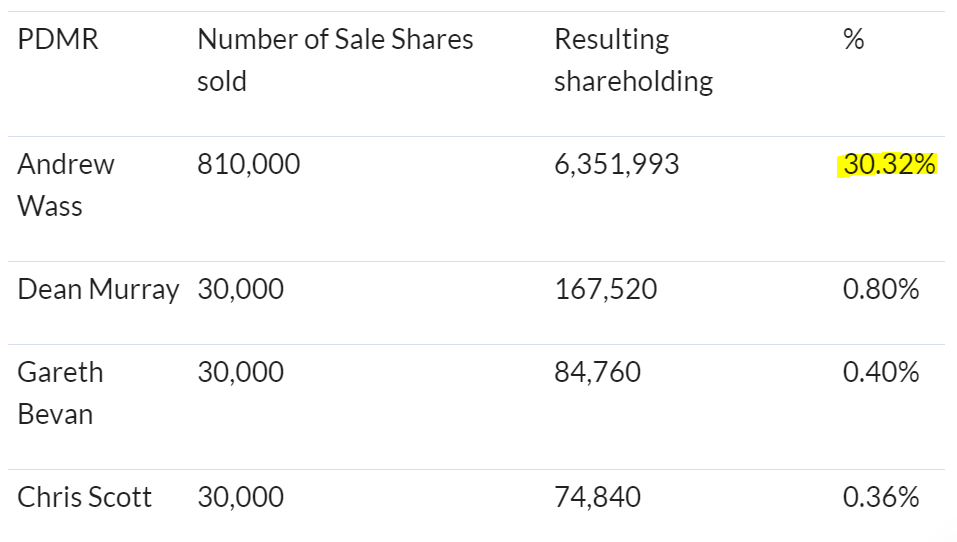
Should we be concerned about this? I don’t think so, because the Directors (mainly the founder CEO) still have tons of skin in the game;
Following the sale, these PDMRs would in aggregate hold approximately 6,679,113 ordinary shares, representing 31.88 per cent. of the Company's issued share capital (a decrease from 36.18 per cent.).
In my opinion, it is only to be expected that founders of successful businesses want to take some money off the table at some stage. People want to buy nice houses, help others, and enjoy themselves a bit, and why not? For me, it’s all about the scale of their remaining holding. If Directors with big shareholdings (i.e. £millions) sell more than half their holdings, then that rings an alarm bell for me, and I would probably follow them out of the door.
However, in this case, the founder CEO still holds a huge stake, so I don’t have any concern about this part disposal. The fact that institutions lapped up the sale shares quickly, and at no discount, shows encouraging stock market demand.
I recently bought back into G4M, as numbers published were impressive. The downside scenario is that very strong trading this year could be a one-off, due to lockdowns. That might be true in part, but I think the sector is clearly one where people seem to be shifting structurally to buying online. Hence my view is that growth may have accelerated in 2020 due to one-off factors, but is likely to continue long-term.
G4M’s strategy of focusing more on margin than revenue growth (it’s actually achieved both this year) is the right way to go, and is working very well, with a series of upgrades throughout this year. I think the current forecasts still look too low. By my calculations, I reckon a share price of c.1000p looks more rational that the current price of 730p. Mind you, shareholders need to be braced for possibly poor results vs strong lockdown comparatives from 2020, in H1 of FY 3/2022.
.
.
EDIT: An additional point that irks me, and many other investors, namely this claptrap in the RNS;
The PDMRs have advised the Company that their sales of ordinary shares in the Company are to satisfy existing market demand.
This is nonsense, that we often hear when Director sales happen at many companies. It's simply not true! They are selling because they want to turn some of their shareholding into cash, and find the market price acceptable. The fact that there is market demand is helpful, but it's clearly never the main reason for selling.
End of edit.
Scs (LON:SCS)
Share price: 194p (down 2%, at 08:46)
No. shares: 38.0m
Market cap: £73.7m
(I hold - Paul)
ScS, one of the UK's largest retailers of upholstered furniture and floorings, provides the following update ahead of the Company's Annual General Meeting ("AGM")
The summary says;
Trading in line with the Board's expectations; new CEO appointed
Strong order intake this financial year 07/2021 - note the pent-up demand in Aug, Sept, Oct. Then a drastic fall more recently, to be expected due to the second lockdown, forcing most of its shops to close. This is not a concern to me, because ScS has already demonstrated that it recoups lost sales in lockdowns, when demand returns afterwards. Plus, it benefits from people wanting to spruce up their homes.
.

Lockdown 2 should be less disruptive than the first, because it’s shorter, and less severe;
Unlike the first national lockdown, and in line with government guidelines, our regional distribution centres have remained operational and continue to deliver goods to our customers.
Liquidity - ScS is swimming in almost embarrassingly large amounts of cash - substantially more than its market cap! (although a lot of the cash is up-front deposits paid by customers);
At 21 November 2020, the Group's cash balance totalled £113m and had no debt.
Further liquidity is available through the £20.0m CLBILS revolving credit facility (RCF) granted on 25 August 2020.
Note that larger competitor Dfs Furniture (LON:DFS) was forced to raise fresh equity earlier this year, due to its desperately weak balance sheet, with large negative NTAV. Whereas ScS has actually reduced its share count in the last 5 years, due to a share buyback. ScS is a superior & safer investment, in my view, due to its low PER and bulletproof balance sheet. Whereas DFS looks precariously financed, so only of interest to investors who don’t look at balance sheets!
My opinion - I reckon the broker forecasts at ScS seem too cautious still, so am hoping for a good boost when we see the next interim results in spring 2021. I’m also more optimistic about the resumption of dividends, than the cautious broker forecasts. My personal price target on ScS is c.300p, so good upside from the current level of c.200p. It's safe as houses too, with that balance sheet strength.
Note that IFRS16 has mucked up the debt & enterprise value figures on the StockReport, so that has to be manually removed.
Note that the StockRank is consistently in the green, over the last 2 years;
.

.
D4t4 Solutions (LON:D4T4)
Share price: 209p (down 3%, at 09:48)
No. shares: 40.2m
Market cap: £84.0m
(I hold - Paul)
D4t4 Solutions Plc (AIM: D4t4, "the Group", "D4t4"), the AIM-listed data solutions provider, announces its half year results for the six months to 30 September 2020 (H1 2021).
Preamble - This share has been on my watchlist for a long time. I recently had some spare cash, so decided to dip my toe in here with a starter sized position (c. 1% of my portfolio). Is there any point in opening such a small position? I find it tends to get me more interested, and pay closer attention to something, research & think about it a bit more. Then I either chuck it out, if it does nothing in the next year or so, or buy more to make it a proper position.
Interim results today are in line with expectations.
The company issued a half year trading update, which I reported on here in Oct 2020. I was a bit sceptical about the assurances given that H2 would be strong enough to recoup the H1 shortfall. However, the company then backed up its confidence with contract wins, which I covered here on 5 Nov 2020. Once I’d slept on it, this gave me the confidence to dip my toe in with a small purchase.
My thinking now is that data seems an area that everyone tells us is incredibly important, and as D4T4 is winning contracts with big organisations, it must provide good software & services. Quite simplistic really, the way I’m looking at this. The reason to hold this share, is not so much about valuation (which looks expensive), but the opportunity if it can scale up.
Recent broker notes indicated that a lot of the required H2 sales are already in the bag, so it’s not such a stretch to imagine full year forecasts can be met, despite the weak H1. These notes are available on Research Tree.
To save me re-typing it all, here is slide 7 from the presentation pack for today’s interims;

.
The above is all self-explanatory. I’ve reviewed the accounts, and it all looks fine.
Balance sheet - very strong, with plenty of cash.
Note that it hardly capitalises any development spend, which I like - conservative accounting.
Online capital markets day, Oct 2020, is available to watch on a recording here. You need to just put in your details, then it goes straight through to the video. It’s over an hour long, so I’ll park that to one side and watch it later.
Outlook - an excellent pipeline with a healthy increase in new opportunities. ….
Although a number of contracts slipped past the half year end by a few weeks they have since closed and we now have exceptional revenue visibility for this financial year.
We continue to invest in our international markets, product innovation and strengthening our partner relationships in line with the substantial market opportunity that is presented to us.
Overall, we are in a good position. The strength of the Group's balance sheet and excellent short, mid and long-term prospects provides the Board with significant comfort and a high level of confidence in prospects for the current financial year and beyond.
My opinion - D4T4 looks quite interesting, but is difficult to value at this stage. Previous results have been lumpy, shareholders just have to accept that’s the nature of the business.
.

.
Fulham Shore (LON:FUL)
Share price: 9.125p (up 6%, at 10:54)
No. shares: 609.6m
Market cap: £55.6m
AGM Statement & Trading Update
This update is for FY 03/2021 to date. The group operates mainly Franco Manca pizza/pasta restaurants, and the smaller chain of The Real Greek casual dining restaurants. Both are good, popular, and well differentiated formats in my opinion.
Here’s my summary of today’s update;
- Q1 - loss-making due to lockdown 1
- Q2 - reopened, should recoup most of Q1’s losses, but at the headline EBITDA level (i.e. approximates to cashflow)
- Q3 & Q4 - not possible to predict, as performance depends on Govt restrictions
- Most branches are currently open, but just for delivery & takeitaway
- Lower rents being offered for new sites
- A few new sites opened
My opinion - the opportunity here is to look past covid, and imagine that trading is likely to be buoyant after Easter 2021, when I imagine restrictions are likely to be permanently removed, due to widespread vaccinations of the vulnerable. Let’s hope so anyway, but that’s looking a reasonable viewpoint, and was recently confirmed by the Health Secretary as being likely. This gives a lot of potential upside for retailers, hospitality/leisure, travel, and other sectors which have been under so much pressure due to covid/lockdowns.
For this reason, I’m looking at what companies are likely to be worth, once they can trade normally again. The market seems to be doing the same thing in the last few weeks, substantially re-rating a lot of cyclical shares. I think the big recovery in many cyclical stocks is justified (in most cases), but maybe some have run up too much, too fast? Profit taking seems to be happening now.
The problem I have with FUL, is that the valuation now seems to have already baked in most of the upside. Therefore, on a valuation basis, I don’t see enough upside to get me interested. Whereas some other shares, e.g. Saga (LON:SAGA) (my 2nd largest position) I see a possible multi-bagger with a 2-year view. So why would I want to put money into FUL, where I see little upside on a rational valuation basis? It just doesn’t appeal to me, due to the high valuation. Although it’s possible that investors may chase the share price higher, because they like the format of the restaurants. It’s been over-valued in the past, and the 5-year share price history is quite poor, because it started off far too expensive.
I’m also concerned that competitors doing CVAs, which large numbers are currently doing, could leave FUL with an over-rented estate, facing stiff competition on lower rents. Business rates are likely to kick in again in 2021/22 too, maybe phased in, at a reduced level to begin with, but the Govt needs the tax revenue longer term (unless you buy into Modern Monetary Theory, where they can just print the money instead!).
.

.
I have to leave it there for now, but should be able to finish off the section on DLAR late afternoon (or worst case, tomorrow).
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

102 comments
GPSS A warning for anyone holding Golden Prospect Subscription Shares through HL. I discovered today that HL had written to their clients on 2nd Nov about their options but I had bought 10k on 10th November so did not get the email of 2nd Nov.
Had I not phoned them my Subscription Shares would have lapsed.
Deadline day is tomorrow at 12noon for HL clients.
£SAGA is an insurance company that has a travel business - " The Insurance business is the largest part of the Saga Group" 2020 Annual Report. I would be a little wary of buying shares unless I was happy with the company's reserving policy. Looking at 2019 and 2020 FY profits of £180m and £110m respectively , £71m and £30m contributions came from reserve releases.
Jarvis will operate an account in a company name, through its shareDeal Active platform, My company has such an account. sharedealactive.co.uk £9.50 per trade.
Can anyone here recommend a platform that allows you to buy / sell shares in name of a limited company? I've a fair amount of cash tied up in my business and it seems surprisingly hard to find a platform that allows a company account. Thanks!
edit: Thanks for all the replies so far - I should have said that it sounds like HL have now stopped offering a company account (one of the changes they have made apparently due to Covid!)
Before I retired and closed down my company I did the same. Hargreaves Lansdowne allowed me to set up a trading account the company names.
I have one with Hargreaves and have been told by IG that they also offer.
to trade as corporate you'll need a legal entity identifier too
I have a company account with HL but wonder if it is a good idea. This is because if you make a capital gain you pay Corporation Tax at 19% on the gain. Then when you take the money out of the company you pay income tax on the dividend you receive. This can be 37.5% of the 81% so you end up with a tax rate of over 50%. Also if you have losses you may not be able to offset them against trading profits.
Re, Limited Company's trading stock.
As far I know, losses are allowable.
The Accounting is complicated and the Corporation Tax Return and calculations is about 50 pages, but my Chartered Accountant has the specialist software to do all the computations.
He charges an extra £350 a year for this bespoke work... but Limited Company investing has doubled our turnover. (Not bad for a one employee company working from a kitchen office!)
Tax is tax... By paying it, I am serving fellow mankind.
Trading profits can offset capital gains. Capital losses can only be carried forward against future capital gains. You are perhaps suggesting that your company is not investing but trading in shares. If you make a profit HMRC are not likely to be bothered how you treat it as you are paying tax. If you made a big loss that you wanted to offset against your main trading income you may get some queries to establish whether it is a trading loss or a capital loss. The normal default position for shares is capital gain or capital loss.
kgb1953
I have a company account with HL but wonder if it is a good idea. This is because if you make a capital gain you pay Corporation Tax at 19% on the gain. Then when you take the money out of the company you pay income tax on the dividend you receive. This can be 37.5% of the 81% so you end up with a tax rate of over 50%.
I would agree with your summary that its not the ideal route - i would say this measure is probably the least worst option for sum perhaps? - if they have excess liquid funds they can't take as dividend (higher rate taxpayer) and they don't want to add into sipp (pension route not for them for whatever personal reason) It's not so bad with regard to high dividend payers if thats likely to be where you earn you buck as the dividend income isnt taxed (strange but true) and/or if you don't need to extract the cash (tolerate 19% as you have made a profit) - but as you say the tax on profits per share sold and extra tax on extraction make it a non tax efficient solution at times if you want the money soon after for a nice new (non electric car) - if you wnat a shiny tesla now is the time to bank your profitsfrom company share trades and buy one through the business that makes the tax issues go away almost completely.
It's also worth considering if investing in shares would have any impact on a potential claim for Business Asset Disposal Relief (previously Entrepreneur's Relief) which may be available on sale / liquidation of the company. This is only available for trading activities so would need to be careful with the extend of non-trading activities in the company.
I’m taking tax advice on this very issue at the minute - I’ll make a post when I get it all sorted in my own head. As far as I understand it, you absolutely need to be able to offset capital losses against capital gains (otherwise share trading of almost any sort would be unworkable). But tax is tax - it has to be paid no matter what you do. Dividends are treated differently (but they always have been). TS23’s point is key - have to very careful that investments the company makes are at least 51% in assets the inland revenue classifies as “trading”
I have an account with HL for a ltd company
You can trade in a pension (SIPP).
On a relatively quiet day for comments, I wonder if anyone has any insights into Powerhouse Energy (LON:PHE) (no news today)? Sounds wonderful:
- converts unsorted plastic waste into hydrogen (and other usables), producing hydrogen at prices to match other existing production methods
-construction has commenced of its first plant on a industrial site in Ellesmere Port
-it raised £5m this year, including £1m from Peel Energy, which, on its asset-lite model, is claimed to be sufficient to bring it to profitability
-Peel Energy is identifying some 40 sites around the country for further plants, and planning permission is to be applied for on sites two and three shortly. Preliminary franchises have been granted to energy companies in Japan, Australia, and recently, Poland
Tim Yeo (ex Environment Minister) took over the Chairmanship (currently Executive) this year
BUT:
Despite Peel backing of £1m, I can find no mention of on the Peel website, so do they rate the technology? Despite Tim Yeo's involvement, and Powerhouse Energy (LON:PHE) potential to solve the plastics problem as well as produce hydrogen, I can find no mention of Gov backing or interest. Who is funding construction? - once Peel's £1m is exhausted, does everything stop? Is the whole thing a mirage? An optimist and chancer, I hold some, and am in the black
Powerhouse Energy (LON:PHE) - "where theres muck - theres brass" - "where theres plastic - theres wind" not the same ring to it, so suggestions on a postcard.
"Covid quarantine to be lifted for business and tour groups"
https://www.thetimes.co.uk/art...
Re Saga (LON:SAGA), the headline on this article looks extremely positive but then for cruises goes on to say something pretty negative...
"However, the report dashed any hope of a quick return for cruise holidays, a trade devastated by the pandemic. It said that cruises could not be resumed until the national coronavirus alert level, which was set at four in September, dropped to at least three, with a move to two “being considered by the chief medical officer”.
This is unlikely until well into next year, when a vaccine should become widely available."
My bold.
Re. Saga (LON:SAGA) - I think people are working on the basis that cruises should resume maybe April-May 2021, once widespread vaccinations have hopefully been done. I'd be surprised if anyone was thinking any sooner than that. That means a few more months of £6-8 per month cash burn, then we're off to the races with fully booked cruises for the foreseeable future, generating £80m p.a. EBITDA. On top of the profits from the insurance division (which made c.£70m in H1).
What about the staff that work on cruise ships mostly non uk,usa,european where are they going to get vacinated? is my concern, can saga/ccl pay for them to have the vaccine, would i want my parents on a cruise ship with un vaccinated staff?
depends how much you like your parents ;)
haven’t millions of Saga customers had their cruising careers prematurely cut short? Younger people will be too worried about the looming recession to go splurging on cruises. Operating costs are likely to rise too, vaccinations for staff, ppe extra cleaning etc
Argentex (LON:AGFX) H1 results presentation given by Carl Jani, Co-CEO last Friday 20.11.20. They IPOd last June 19. A very sales led organisation, with strong ambitions. The business which happened at start of CV19 seems to have taken away from H1 where clients have been in 'decision paralysis' mode. In extreme market conditions, like March 20, a lot of Fx hedging happens, when calm returns there is not such a catalyst, but there is a business necessity for Fx, so expect a strong H2. This presentation is really helpful, and provides most investors with their first presentation by management. Video and podcast.
Other webinars forthcoming:
Today, Ig Design (LON:IGR) H1 20 results: Wednesday 25th November, 2.30pm
Paul Fineman, CEO & Giles Willets, CFO will present results followed by Q&A. A great management team. Looking forward to hearing an update. Register here.
Tomorrow, Tracsis (LON:TRCS) FY20 results: Thursday 26th November, 1pm
Chris Barnes, CEO & Max Cawthra, CFO will pesent results followed by Q&A. They've been lying low since Chris took over, but a great opportunity to catch up on this quality business. Register here.
Next Monday, Panoply Holdings (LON:TPX) H1 20 results: Monday 30th November, 12 noon
Neal Gandhi, CEO & Oliver Rigby, CFO will pesent results followed by Q&A. They've been on a roll during CV19, helping Government and Local Authorities gear up for all the challenges. Great insight to what's going on behind the scenes generally, and how they see it translate for their business going forward. Register here.
Next Tuesday, Sosandar (LON:SOS) H1 results webinar: Tuesday 1st December, 12 noon
Julie Lavington, Joint CEO & Steve Dilks (new) Finance Director will present results followed by Q&A. This is one Paul has followed from the very beginning and written extensively about. They're always so busy, so difficult to track down, but we're delighted we've been able to do so. Register here.
Just announced yesterday, Creightons (CRL) H1 results webinar: Wednesday 9th December, 2pm.
Bernard Johnson, Managing Director, Pippa Clark, Joint Deputy Managing Director and Paul Forster, Group Finance & Commercial Director will present results followed by Q&A. Register here.
My view is that if senior employees start selling then either hold with a view to no progress in share price or sell. I made this mistake with AVCT recently. There is always a plausible reason for the sale but in truth you don't sell something if you think it is going to do well short term. AVCT the CEO was buying a house but frankly with int rates as they are had he thought the shares offered any value he would have organised a bridging loan. Long term well sometimes these sales offer value for buyers if its the right investment. So yes I can see why G4M are sellers plenty of stock etc but I don't expect the shares to do well short term. Lets sit back and allow time to prove me wrong.
with int rates as they are had he thought the shares offered any value he would have organised a bridging loan.
Any director who chooses not to hock/leverage their shares for personal purposes is probably doing the right thing IMHO- there has been so many disasters where directors have gone down the security route only to be forced sellers later when things go pear shaped. Much better to keep it "clean" and have the lesser evil of share sale IMHO if they can't get mortgage purely on their sa302's (or whatever equivalent is for rich bods)
cantab,Agree in principle but bridging loan finance is expensive, 8-10% pa, so share price would need to go some to make that worthwhile?
Gear4Music
Paul,
Yes I think your thoughts are correct here and musical instrument sales are going more online and being commoditised somewhat which will effect selling margins in the future. Some musical online retailers have had a real boost over the summer from furloughed customers wanting to learn an instrument in their extra time, demand as such was so that there was a shortage especially in guitars and keyboards with retailers unable to meet demand. My view is that demand will slow next year significantly. Incidentally I went into a G4M store 3 months ago to buy a digital piano for my wife to practice and when I enquired about the price and availability the first thing the guy did was check the internet for the best price available so they could beat it. The item was on back order with no stock available, but I was told I could leave deposit for an expected delivery. As a retired Sales Director of two FTSE companies I cringed at the weak sales practice.
I do think there are headwinds for G4M and my view is the Directors are taking some risk off the table. Yes Andrew Wass still has plenty skin in the game but the other three directors sales are significant to the remaining holdings. Firstly I think their sales have benefitted from covid significantly and will slow from next year but secondly they export a considerable amount to Europe where there is significant risk from Brexit and exchange rates on low margin products. They have a number of European competitors waiting to take advantage but unwilling to compete at the present margins. Brexit and exchange rates could create an opportunity for them.
In summary I think this as good as it gets for them for some time and will not see the growth again as this year, margins will be pressured but Investors and the market will expect more of the same until they realise the music has stopped.
I have been an investor here but recently sold on results. And yes I do know and speak to one of their competitors and as such have a good understanding of their market but have no inside or privileged information on G4M. The above is purely my own thoughts.
Regards
Andrew
Hi Andrew,
You seem very emphatic about your ability to correctly predict the unknown future! I lost count of the number of "will"s in your post! The truth is, we don't currently know, and you're guessing. We all are.
Fair points you make though, in the main. Although I think you're wrong about Brexit. G4M has already set up operations in Germany & Scandinavia, which not only distribute, but can buy independently. Therefore its European sales are not dependent on being able to freely import products from the UK.
Given the points you make, I agree that it's sensible to forecast for next year showing maybe only modest growth over the bumper figures for this year. Broker consensus shown on Stockopedia look ludicrously low, given that H1 beat the full year forecast, and H2 is the seasonally busier half year! Hence why I think the price should be c.1000p if you work out what they should do this year. That stacks up, even if there's no earnings growth at all next year.
Anyway, time will tell!
Regards, Paul.
Paul
thankyou for pointing my short comings, I will try to use If, maybe or could in future posts. The truth is I've never been one for sitting on the fence.
;-)
Andrew
Sorry Andrew, it's just my pet bugbear! :-)
Best wishes, Paul.
His sentence started with "I think" .
I think you're getting a bit over sensitive to this.
Posters using WILL (not Will Smith)
One thing that struck me after ploughing through the last few sets of results that I believe may be being missed by investors is the operational gearing effect on EPS. It strikes me that admin costs are relatively static YoY so increases in revenue are now impacting the bottom line at almost the same rate as the gross margin (which is also increasing).
If that is the case then focusing mainly on revenue growth and fretting that this may slow acts as a bit of a red herring to the investment case. It looked to me like even a small 5-10% increase in revenues next year adds an awful lot to the EPS number. The Covid effect appears to have been around £10-11m on revenues so to replace this "one off" will equate to around a 4% growth rate,
It feels to me like a number of investors may be looking the wrong way; focused too much on revenue and not enough on Operational gearing.
Shares look to have been taken by Aberdeen Standard
Re Gear4Music (LON:G4M) - yes and a whole lot more.
Reassuring.
Re £G4M
Portcall909, I'd be interested to know which shop you went into as, as far as I know, the only showroom the company has in this country is attached to their warehouse in York.
Regarding sales in Europe, which are increasing, and possible problems regarding Brexit, The company has two European distribution centres, one in Sweden and one in Germany and they have said that, as a consequence, they expect minimal impact, whatever Brexit may bring. Of course, currency is another matter, one could argue that a "bad" deal would devalue sterling thereby making increasing overseas sales even more valuable to the company offsetting the increased costs of imported goods to this country (admittedly a lot of their products are imported).
Some recent positive news:
The Times reported on Monday that "Guitar Center, the largest US seller of musical instruments and equipment, has filed for Chapter 11 bankruptcy protection after being hit by the shift to online shopping."
and
Last week the largest French chain of musical instrument shops closed.
Directors sales never a good sign (as far as I'm concerned). They say sales were to institution(s).
Would have been good to hear that all the sales were to the same institution - that would have been much more of an endorsement.
I have been a long term holder and am happy to carry on and see how this pans out.
Laughton,
They actually have a large store on a retail park in Leeds, West Yorkshire.
I don't like or dislike this Company as with all my trades and investments I have learnt to leave my emotions at the door because I know it clouds my judgement. I have been bitten most by companies I loved.
All I was saying was they have had an uplift from covid which they will not get again and without a moat products that move online usually suffer from an amount of devaluation over time, from smaller companies looking to feed on the crumbs under the table. Success always brings competitors to steal your margin.
Regards
Andrew
I don't believe they do, or at least they don't appear to know that they do if indeed they do:
https://www.gear4music.com/inf...
Any ideas what a "Qualifying Shareholder" is re the Venture Life (LON:VLG) placement? I'm trying to work out whether Venture Life private shareholders will be able to subscribe for the surplus shares or whether they'll be confined to institutional investors. It's not clear to me!
Venture Life (LON:VLG) : It's a defined term in the placing statement. You'll be fine.
"Qualifying Shareholders"
holders of Existing Ordinary Shares on the register of members of the Company at the Ex-entitlement Date that are not resident in a Restricted Jurisdiction
pj8 / Effortless Cool - I haven't followed Venture Life (LON:VLG) chat since the placing.
Has anyone been making the positive case for this raise beyond (rather hackneyed) 'dry powder' sort of claim?
To my eyes it looks like a total sidewinder of a raise that is hard to fathom...
(I am not very knowledgeable on biz beyond the cursory analysis I provided elsewhere)
The Venture Life (LON:VLG) fund raising is ok but discount too large.
But the directors instead of buying shares at a discount are selling "Jerry Randall, Sharon Daly (née Collins), and Gianluca Braguti and certain of his associates intend to sell an aggregate of 8,173,343 Sale Shares at the Offer Price."
I have a small holding and I'm looking to sell as well.
I remain puzzled why such a large raise and such a discount is a needed and good thing at Venture Life (LON:VLG)
They've invested in capacity. They have new-ish brands to promote. They have a huge Chinese deal that leverages their new capacity. Why do they need £30m ish? Buying brand(s) that absorb much of that then probably means a commensurate investment in incremental capacity and infrastructure? (Its highly unlikely that their current sales and distribution infrastructure is under-utilised given recent expansion in product and sales).
I can't help but think that the raise indicates there is something else going on and therefore there may be a problem too?
I had a look on a BB about Venture Life (LON:VLG), some talk about pre-emption rights changing on 1st December, 2020 which I don't understand, also some talk about funds for acquisitions.
Investors Champion have written a negative article about it but I don't have access to the full content. I may hold mine for a while and see what happens, I don't think they will fall much more.
Venture Life (LON:VLG) ...
3rd Nov - Slightly rampy RCS (in the 1000 best companies list or something like that)
16th Nov - Slightly rampy RNS (our mouthwash kills COVID better than the competition in testtubes)
20th Nov - Out of the blue mysterious placing announced for possible acquisition targets, justified as "unconditional funding puts the acquirer in a stronger position that having conditional funding".
20th Nov - In the same RNS, the directors sell more than half their shares (~8m sold, ~6m remaining).
I sold a third of mine into the test-tube spike, and liquidated the remainder when I saw the directors had sold. If they had instead shown support by participating in the placing as a buyer I would have held. To be fair I hadn't considered the possible CGT change worries at the time. Even so, they can't have that much confidence in the upside of these possible acquisitions if they're selling down so heavily.
Just before this raise the price spiked on the mouthwash news. Prior to this average price was average 100p . I do not think the 90p raise is at a large discount to an average price of 100p for a massive raise of £34m. VLG were clearly able to convince institutions to part with a lot of funds so they must buy into the plan which I view this positively.
The potential brands are classic acquisitions which fit smoothly into their manufacturing and marketing channels. VLG strategy is to grow both organically and via acquisition and these acquisitions should be immediately earnings accretive.
Yes VLG invested in the factory and now have 40% available capacity so again this fits. They can bring manufacturing in-house.
Chinese deal is more of a framework with a lower price if the Chinese partner buy a minimum amount of product. Not a large part of rev. Chinese sales in H1 were £2.3m out of £17m total revs. VLG merely supply to the Chinese partner who collects and distributes.
I hold
DYOR.
Venture Life (LON:VLG)
£34m is meaningfully greater than their sales which were £20m in 2019 and estimated c.£30m for 2020. 2020 should be marked down as lots of hand wash plus the accounts have shifted a lot from white label to VLG brand which is a little odd and feels like a bit of gamesmanship to get the reported brand margin up as white label has been more profitable to date as having brand plays better than being a manufacturer.
Its not obvious what's happened in 2020 with this shift of revenue from manufacturing to brand - what's going on and why is it associated with a pick up in brand margin?
Previous raises have not been fully used for stated acquisitions and have been used to clean up financial position. Is that going to happen this time? Working capital position is quite large.
If they are going to acquire similar opps and they use all of the £34m then we are talking about something north of £20m acquired. This is much bigger than what they have tried to swallow before. This is not necessarily easy...a jump in scale and processes.
I'm suspicious that 'Target B' (UK heritage dermatological brand) valued at up to £20m is really about covering the fact that much of 2020s growth in revenue and profits is from opportunistic covid hand wash (the shift from manufacturing to brand sales is a clue). I am also suspicious of the idea that taking UK heritage dermatological brand global is immediate and easy win.
VLG are moving fast to monetise their new high market cap as they need to buy some sales to fill it.
Yes directors are selling just over half their shares but they have not sold any shares since 2010 when they founded VLG and still retain over 6million shares plus options so they are aligned to shareholders. And obvs they are now locked in for 24 months. I think I might want to sell some after 10 years if i were them.
I bought these way back at 47p and sold enough shares to get my investment back a while ago when they hit giddy heights, so now riding the 'free' shares. I must be thick as I cannot see the bargain in the 1 for 37 held at 90p offering given they are just about that to buy anyway. Will stick with them but if they sink slowly to the 70s may reconsider.
Venture Life (LON:VLG) initially I was sceptical, but once I'd digested the announcement and realised it was for acquisitions (of which they highlighted three potentials) and recognised that they had issued shares regularly in the past to fund such acquisitions I became more comfortable.
In fact I've topped up on the prospect of further gains. Time will tell........
HOT NEWS!
Future (LON:FUTR) has just now announced that it is to buy Goco (LON:GOCO) . Also results published today. Would you like to comment on this please Paul?
The market reaction looks in line with my thoughts that Future (LON:FUTR) are leveraging their high stock price and Goco (LON:GOCO) are selling at an opportune time given the Competition and Markets Authority is gunning for the price comparators business models.
They recently announced a £17.9m fine for Compare The Market and declared illegal the "most favoured nation" clauses whereby insurers agreed never to let anyone undercut the pricing on the comaprison websites. This looks to me like a better deal for Goco than Future.
https://www.gov.uk/cma-cases/p...
Edit - The comments about entrepreneurs selling up to avoid CGT increases is almost certainly a factor here too with Sir Peter Wood owning 29.7% of GoCompare. It may well have been the initial driver.
What's "hot" about it?
Future (LON:FUTR) is nearly £2bn market cap now, and I don't have any insights into it, so it's not one I cover here any more.
The "hot" bit is that it has only just been announced this morning. Maybe you would like to comment on it from the point of view of Goco (LON:GOCO) which is a much smaller company? But I can see that you are up against the clock, so will understand if you are unable to.
£LTHM Might I commend subscribers to take a look at James Latham half year results today. No flannel, no adjustments, just the facts. Not the most exciting company perhaps, but a classic buy, hold and do nothing for me - up about 12 times in the 20 years or so I have held, plus decent divis and that will do for me.
I think there’s been a recent raft of directors selling which has been connected to the rumoured CGT increases, not a reflection on single business outlooks.
I think there’s been a recent raft of directors selling which has been connected to the rumoured CGT increases, not a reflection on single business outlooks.
Very good point PeterM, thanks for flagging this.
Paul
Just commented above re Ig Design (LON:IGR) Paul Fineman vast sale of stock
Just to amplify this, the reduced rate of CGT called entrepreneur's allowance feels like it's in jeopardy. Certainly enough threat to bring forward a sale decision.
The relief is currently only on the first £1M whereas it was previously on the first £10M. I would be surprised to see the already substantially reduced relief eliminated. It is after all now only worth £100,000 at best so the prospect of any further reduction would not be a good reason to persuade anyone to dispose of very substantial shareholdings.
The relief is currently only on the first £1M whereas it was previously on the first £10M.
I think use of the word "only and "£1 million" are at odds here - we have a huge added recent national debt and huge negative cashflow (ignoring funnies) - if the entrepreneurs/capital gains rate isn't changed to 20% (temporarily ) and other taxes ARE raised this will rightly so go down very poorly with the normal bod in the street who is paying minimum of 32%(employees) 29% sole trader (25% limited company) marginal rate. I am well aware that ane raise may lose taxes overall but that won't wash with pleb in the street. Being honest anyone who gets a chip on their shoulder ref paying the extra 10% should be told to sling it buddy :) - 20% would still be a very decent deal however much that rich person will moan. In some respetcs if Rishi doesn't act in this regard he won't be doing the right and proper thing - there has to be similar danger ref capital gains exemption for some (eg rental property owners who gain tax free profits)
Being honest with things as they are generally - extra money being pumped into NHS and extra moeny being spent on state pensions (triple lock and older populaton) - i feel a freebie for the well to do (the powers that be and their mates) is a bit of an insult even with the current state of play. Rant over.
My point was more related to the suggestion that large shareholders are selling to beat a CGT rise and the elimination of the 10% relief. They may want to beat a possible CGT rise which I don't expect to happen but the prospect of having to pay an extra £100,000 tax is not going to be a key factor in determining whether anyone sells a large number of shares in their company.
Worst case is they abolish Entrepreneur's relief and then align the CGT rate with income tax rates so they could be paying 45% instead of 10%. That might be enough to persuade you to crystallise your gains now.
I am not sure we had capital gains tax at that rate years ago under Labour. Genuine capital gains are different from income. Those from a business may have been built up over very many years and are quite rightly taxed differently to income.
Risk:-
I've had two startup businesses swallow up the seed capital and disappear to zero. Investing in resources and taking on staff is expensive!
Lessons learnt!
Those well to do! They never took any risks or provided millions of jobs or did anything good anyway. There are so many often overlooked other taxes for being the owner of a limited co, e.g. Employers NI which stings hard just for employing people. And Employer Pensions contributions (which are steadily rising). Dividend’s tax advantages have also been reduced a lot in recent years to the point it isn’t really advantageous. I appreciate your perspective, but aligning us to the bod on the high street for CGT does not consider the whole story! It’s actually one of the only remaining financial carrots
Whatever your thoughts on the rights or wrongs of taxation, it’s fair to say that it is almost certain taxes are going to rise over the next few years. And we aren’t talking about small amounts so the rich are going to feel hard done by and poor are going to equally feel it’s not enough.
The key issue to remember is how do you continue to incentivize growing the economy while doing so? Because there is a line to walk here no matter how much people would like to ignore it - I for one am happy to pay more tax as long as I feel we aren’t snuffing out all incentive to create jobs and wealth in the process. The one thing that must be protected above all costs (even though it must be so tempting for governments) is entrepreneurs relief. Second behind that is CGT - not the threshold that simply creates a bizarre disincentive to sell above a certain level for wealthy people but the rate itself - it should not be raised as it disincentivizes people to make money.
JamesHolmes
Those well to do! They never took any risks or provided millions of jobs or did anything good anyway. There are so many often overlooked other taxes for being the owner of a limited co, e.g. Employers NI which stings hard just for employing people. And Employer Pensions contributions (which are steadily rising).
I sort of see where you are coming from with your argument that oits all trouble and strife - but surely most bods don't start up in the business for the tax perks alone - surely that is a bonus or a marginal reason for going down that route. Traditionally we have been seen as business friendly compared to other countries but paying 1/3 of the tax compared to another bod with same income level isn't just or fair however you tart it up - nice if it exists but it really shouldnt be seen as a right or something you have earned by being self employed. I am playing devils advocate here in that i am all for a low Entrepreneur's rate of tax
Note employers NI and employers pension contributions are costs just like any other cost of doing business - they aren't a tax on you earned income they are just an expenses that needs to be met if you want to be in business in tis country.
Note i am not particulalry against alow entrepeanours rate personally overall but that doesn't mean i don't see the obvious unfairness of it. Particulalry if its a time when taxes are going to increase.
Dividend’s tax advantages have also been reduced a lot in recent years to the point it isn’t really advantageous.
I guess most employee bods would be happy if they could chop 20% plus off their tax bills (marginal rate 25% compared to 32% employee presuming not higher rate tax) - and also choose to not have to pay higher rate tax on their earnings by temporarily parking it in a bank acount and not spending it or better still make ita joint venture with ones spouse - there are plenty of advantages still of running a limited company IMHO - heck you can even buy a telsa via your company this year and knock that of your business profits (time to get rid of your Jag perhaps Paul ?).
anyways thats me over and out with my fairness rant for the day
I don't focus on The Tax. I focus on my vast profits.
There's money (free money) for everyone. It is what it is.
We here, as Stocko subscribers and wealthy investors, and I.M.s are in a privileged position in society that we are able to generate unbelievably huge sums of wealth, unattainable to most people.
Let them eat cake.
"There are so many often overlooked other taxes for being the owner of a limited co, e.g. Employers NI which stings hard just for employing people. And Employer Pensions contributions (which are steadily rising)."
LOL, like they are personal taxes. They are ultimately paid for by your customers. Your costs go up, your prices go up, customers pay. Hold your margins and your absolute profit goes up. I used to love those minimum wage increases, those extra pension costs to justify increasing my prices to grow revenue.
I don't take on staff anymore. Its too much hassle (administratively). There's H&S, Political Correctness and The Compulsory Pensions Regulator bullshit.
Its easier just to pass Contracts between other businesses.
I think it was a bad policy - of the Conservative governments - to make it harder for small (1-10) businesses take on staff.
The result of these policies is contracts, some, go overseas, err outside The E.U..
Northern Bear (LON:NTBR)
Interims out show an adjusted operating profit of £0.5 mill - perfectly acceptable under the current conditions, Outlook looks fine (strong order book) - there is an intangible w/off that puts the figures into statutory loss but i will choose to ignore that adjustment. Share price has shown no signs of upward movement like the rest of the market - current 52p well down from the 70p plus that existed pre covid. Curent market cap is £10 mill and this company can churn out approx £2 mil of profit in a good year - so i will continue to hold on the chips as chips theory. Probably not for most bods due to small cap nature and the building sector which some see as an accident waiting to happen sector ref the next recession - to be fair to Northern Bear (LON:NTBR) they are on track for 11th year ish of profits in a row if we ignore adjustments ref intangibles. Other items to put one off this share - some don't like the communication with the market or the perceived multiple business structure salary levels - also the balance sheet isn't fantasticlaly stong (high payables both ways). I am happy to continue to hold and would possibly add some more if mr market would sell them to me at 50p a pop and nothing else tempts me first (LoopUp (LON:LOOP) price seems to be go trending lower by the day - i am happy to take on the chartists at times if the price is right)
Gear4music Holdings (LON:G4M) / Director Selling
With the current discussion around proposed increases to the rate of capital gains tax and potentially other changes (restriction of reliefs), I can see a flood of director sales across the market.
Paul's proposed rule of thumb " If Directors with big shareholdings (i.e. £millions) sell more than half their holdings, then that rings an alarm bell for me, and I would probably follow them out of the door" is very sensible.
2020/21 HALF YEAR RESULTS for De La Rue (LON:DLAR) (I hold). I think they are quite positive, with turnaround plan that seems to be working.
Turnaround Plan on track.
H1 2020/21 highlights:
· Adjusted operating profit significantly improved at £15.3m (H1 2019/20: £2.2m)
· Positive operating cash flow
· Cost reduction programme on track to contribute £23m of savings in FY 2020/21
· Authentication orders secured with total lifetime contract value exceeding £120m
· Currency 100% full for banknote printing in H2 2020/21
· £100m equity capital raise completed July 2020
· Exclusive Bank of England banknote printing contract extended to 2028
· Net debt reduced to £21.6m (H1 2020/21: £170.7m; FY2020/21: £102.8m)
Pension Deficit
The new Recovery Plan to address the pension deficit has lower payments than the previous recovery plan agreed in 2015.
2020
2021
2022
2023
2024
2025
2026
2027
2028
2029
total
New Recovery Plan
7.7
15
15
15
24.5
24.5
24.5
24.5
24.5
14.8
190
2015 Recovery Plan
22.2
22.2
23.1
23.1
23
23
23
23
23
205.6
The funding of the Recovery Plan is to be sourced from cash generation of the future business activities, but the Trustee has contractually agreed not to request any portion of the equity capital raising proceeds.
CEO statement
Trading for the financial year 2020/21 has been positive, with the outlook for revenue, adjusted operating profit and net debt for the full year in line with the Board's expectations.
There is also talk that De La Rue (LON:DLAR) may get the HMG contract to produce secure CV19 Vaccination certificates........
I hope Paul will be able to cover De La Rue (LON:DLAR) results today or tomorrow as they looked OK but share price reaction suggests otherwise! Or is it just profit taking on a down day generally following a good run for the shares ahead of results?
Paul, In respect to Gear4music Holdings (LON:G4M), there is a piece in today's FT that notes that accountants and brokers have seen a rush of entrepreneurs and owners of smallish businesses asking for advice ahead of Rishi's likely hike in CGT. We need to look at dirctors' share sales in coming months with this in mind.
Grumpy5
Just listened to Ig Design (LON:IGR) webinar courtesy of PIWorld and thats exactly the reason Paul Finman the CEO gave for selling the vast majority of his holding (?!?).
Of course if he does not sell he has no CGT liability
Great results from Future Future (LON:FUTR) - should be a good read across for Reach Reach (LON:RCH) both capitalising on the radically accelerated societal trends brought about by the virus... i.e. the stampede to get online.
Expecting fireworks on Friday when results are out.
Changes afoot with Reach (LON:RCH) :
Regional newspapers pivoting online
Local news at forefront of covid and boosting readership
5th largest site on amalgamated basis behind facebook amazon etc
Data is the new steam, in this informational revolution.
Data is the change Reach have been working on... their real mission to fix it on data with their stable of newspapers and magazines and they are doing this. They have taken on digital wave and are succeeding.
With Data - you can find out many things about people like how old they are what they’re hobbies are when you have this, you have a footprint - you get to understand the reader... what do they like? Sport, home, travel, fashion? Tailor your ads to this. You get a step ahead. Sport and fashion are high margin for ads...
5 PE now should be 15
They are cutting costs (print) and pivoting
Next year - will see big turn around
Hi greenhat2,
I understand the bull argument for Reach (LON:RCH) but want to counter with a couple of points. Firstly, the physical newspaper business is in long-term decline. Hence the huge profits it currently makes are going to vanish, sooner or later. Therefore, you can't meaningfully value the share on a PER basis, since that would require the newer digital business to recoup all, and more, of the profits currently being made by the newspapers. That seems a tall order to me.
The actuarial deficit on the pension funds is gigantic, over £700m I understand. This is likely to be a big drain on cashflow for many years to come.
Does RCH give a split of the profits between digital & physical newspapers? I think we need to see that split, to be able to value the share on anything other than guesswork. We need to see how much profit is made from digital, and how fast it's growing. Likewise with the newspapers division. Then we could model on a spreadsheet a gradual decline (to eventual zero) of profits from the newspapers, and growing digital profits. Then we would need to value the business based on the digital division alone. Would that be enough to provide much upside on the current share price?
Another concern I have, is that a lot of people seem to have latched onto RCH shares at the same time this year. So it's starting to look a crowded trade.
For me, it goes into the "impossible to value" tray!
Good luck with it.
Regards, Paul.
Paul - excellent insight, you have countered very well as usual raised a lot of food for thought.
Hi Paul - where do you get the actuarial deficit being £700m? The accounts show £200m after taking into account adverse changes to assumptions and following actuarial advice.
I think people completely miss the point on £RCH. This is about a huge cash generator from its traditional business that can continue to generate significant cashflows for a long period of time. But more importantly the digital offering and their strong regional news ownership means that if they can execute the digital strategy then they can be worth significantly more.
I don't buy the crowded trade argument either. The share price was above current levels pre covid so it really has only retraced what appears to be a massive panic selling in the first place. Early sight that the key drivers of the digital strategy are working is what has given investors more confidence. They are targeting 10m digital account sign ups and went from something like 700k to 3m already.
Panmure have a price target of 310p on it and are looking for it to replicate peer Future.
Other brokers have targets of 160p so there is quite a variance of opinions, which doesn't suggest a crowded trade either.
David,
The £700m Reach pension deficit is referenced in note 20 in the 2019 R&A - together with the expectation that this will be eliminated by 2027.
The next valuation (as at Dec-19) is due to be completed by March (they expected it would probably be ready by December, but whether that the remains the case I don't know). The updated figure could well go up based on what we are seeing with interest rates.
Of course this is a know drain on cash and one that they have been comfortably able to service so far.
Reach (LON:RCH)
Of course this is a known drain on cash and one that they have been comfortably able to service so far.
The thing though is they need to have over £50 mill per year available every year up to 2027 (and beyond potentially) to be able to keep on top of the issue as things stand - so its not the ability now that could scupper the shareprice but the ability in the future if the market thinks the same profits (or cashflow) wont be there in the period say 2024 to 2027 - if the market thinks the company won't have those sums of cash then i guess the shareprice will dive as soon as the trend becomes clear. Thats all based on no material changes to deficit - those changes could go either in right or wrong direction.
The main thing about Reach (LON:RCH) is that the share price is a small residual between very large negative and positive numbers. The next is that it appears to have been very well managed for a number of years.
It's easy to become stuck on interest rates re the pension fund deficit. But the funds are long closed and the life expectancy of its members is rapidly becoming more important.
Reach (LON:RCH) and Future (LON:FUTR) are two completely different companies, although both are obviously publishers. Success in publishing in 2020 comes in two forms: distribution and niche. The platforms triumph in the first because they don't have to create nor pay for any content, nor worry about any of the legalities around said publication. The specialist publishers triumph at the second because they have highly defined and engaged audiences that are also motivated to spend money on these passions. Think of it as a pyramid with arcane academic publications at the top where readers will happily pay thousands of pounds for a subscription down to mass market tabloids and regional newsbrands at the bottom where stories are replicated with ease and appear on multiple sites and platforms. People will not pay for this - or, if they do, it will be pennies, not pounds. Google and Facebook also have such a firm grip of the advertising ecosystem - something like 70-80% of the world's digital advertising revenue between them - that it is almost impossible for publishers to compete. This allows them to keep investing in product innovation, allowing better customer experience and ultimately widening their defensive moat. Google in particular operate both the sell side and the buy side of the advertising ecosystem - just imagine the outcry if the same occurred in the financial markets! So, Future (LON:FUTR) is further up the value pyramid; has a series of specialist titles; a smart, one-size fits all digital approach that maximises advertising and also generates very significant e-commerce revenues from that highly-engaged, passionate audience. Reach (LON:RCH), on the other hand, is playing at the bottom of the digital pyramid. If you visit any of their sites, you will see the bind that those types of publishers are in: so many ads that it is almost impossible to read the content. The content is rarely (never) unique. And, anyway, you could get it free of charge and free of ads over on the good old BBC. Reach (LON:RCH) are doing a good job of managing the P&L, but we are a long way from cracking the digital publishing code for mass market brands. Do not confuse scale for value - unless you own the distribution.
Not quite. Don't underestimate the value of the regional news which Reach (LON:RCH) have an almost monopoly on. That is very valuable and akin to the specialist titles you talk about on Future (LON:FUTR) which is partly where the CEO is heading in his digital strategy.
This reads as a bit of a ramp. Are you on the right bulletin board?
Reach (LON:RCH) is one I hold. It has gone up a lot since I bought so it is possibly ahead of itself. Richard Leonard mentioned when it was 90 odd pence that it could be 150p by March or April. So perhaps it has got there too quickly and may come back somewhat, who knows. I think he did go on to say that it could be worth 450p one day without giving a time scale. My son is involved in creating websites so I hear of little else! There is nothing of more potential value today than getting hits on your website but Reach have to work out how they fully monetise this.
They have the fifth highest number of visits to their websites in the UK. Also, that figure arises not from just one website but from over 100. They own practically all of the local newspapers in the UK and some nationals and to me it is the local papers that are the selling point. I do see a day coming when there will be little physical sales but people want to see tailored local news and the numbers visiting their websites (which could be improved) is only likely to increase. It would be very difficult for anyone else to get into this space. Who is going to try to set up 160 local newspapers from scratch.
I think what looks like horrendous pension liabilities will become irrelevant with time and that if this share were quoted on Nasdaq it would be worth a lot more.
Too often it is said "if this was on Nasdaq it would be worth many times more". That is not a case for buying a share. Presumably it is not on Nasdaq and there is a reason for that. Over my years investing I have heard many times that the market is wrong. The market is never wrong.
If the market is never wrong, why are we here?
Jon
It is a fact that technology based shares are worth more on the Nasdaq! So was the market right in the summer when Reach (LON:RCH) was 50 odd pence. Or is it right now when the price is nearer 160p! The real value of the company cannot have changed in that time by a multiple of 3.
I think that as someone who held Reach (LON:RCH) previously as an income share, and when the dividend was cancelled it nose dived and I sold along with a number of other income holdings to preserve capital, which I suspect a lot of folks did too.
With the lack of sight on whether dividends would be reinstated I missed the bounce, so congratulations for catching it!
Tommy
I missed that comment earlier on, but I think it really hits the point.
I have been invested in or watching Reach (LON:RCH) (TNI as was) off and on for over a decade and I have often said that market sentiment towards the company is key (sentiment has mostly been poor, occasionally indifferent and almost never - 'til possibly now - ebullient.)
During that time I held TNI (as it was then) whilst it 10 bagged. Sadly I bought very few at the very bottom, sold some on the way back and sold none at the very top. It has still been pretty good to me though.
During the time of that 10 bag I actually do not think the "real value of the company" changed too much.
As for the recent 3x change, I would agree that the real 'value' has not changed by that much; although I do think the digital progress has made a difference to the "real" value of the company.
I remain unconvinced that we should regard Reach as a Tech stock (we are not back in the 90s when it was not necessary for tech stocks to have even the first idea of how their tech might generate revenue and profits) so I am personally thinking it is beginning to look fairly (perhaps fully even) valued.
On the other hand if Reach can become recognised as a UK FAANG (perhaps implied by some of the site visit stat) then there could be a long way to go yet - as implied by some of the price forecasts being bandied about.
It might be an exciting ride from here, but I am fairly comfortable, even without being convinced on the "sunny uplands" scenario, I don't think the current valuation is to wacky.
This probably the most bullish post I have ever written on the company, so I do feel compelled to add the rider :
ALL IMHO and please DYOR
Camtab, You're the 1st person Ive met who truly believes in the Efficient Market Hypothesis (EMH) ! If that is the case you should be looking at Passives.
I don't think any of our learned friends on this forum would fall for ramps Freng.
My error was not looking at the bear side - Paul has thankfully brought that front and centre.
Future (LON:FUTR) are now down 17% today so hopefully not too much read across to Reach (LON:RCH).
D4t4 Solutions (LON:D4T4) - So difficult to judge the outcome for the year with so much in the H2!
Re D4t4 Solutions (LON:D4T4) - yes, despite their contracts increasingly being (annually) recurring, they are 100% recognised in the half year they renew, which (with recent covid-related delays etc) now seems to be H2 for everything! So scary-looking H1 followed by massive H2 (repeated every year) despite the underlying business being (at least) stable with little churn and lots of good stuff going on in a hot market...
For a software company in the midst of a revenue- and profit- hitting SAAS-transition, it is in my view worth not just looking at profit multiples (which can get temporarily high) but also look at EV/Revenues - which should give some comfort here. (As does £12m cash)
Hi Paul Calnex Solutions (LON:CLX) results a boring new issue use 85million share in issue for eps 5g testing.
fantastic results from Calnex Solutions (LON:CLX)
Tullow have their Capital Markets Day presentation today from 9am
My morning smallcap tweet: AA rescued after long wait
AA (LON:AA.) Sourcebio International (LON:SBI) Fulham Shore (LON:FUL) Nanoco (LON:NANO) RDL Realisation (LON:RDL) Xeros Technology (LON:XSG) Irish Continental (LON:ICGC) SCS (LON:SCS) James Latham (LON:LTHM), De La Rue (LON:DLAR) Northern Bear (NTBR)
AA (AA.) at last, a 35p rec offer. [SP=31.95 Cap=199m]. I hold.
SourceBio (SBI) Renewal of covid testing services contract with Spire Healthcare. Co "continues to build capacity for testing services to support expected further demand into 2021". Guides FY rev £50m and EBITDA c. £14m. [SP=183.59 Cap=136m]
Fulham Shore (FUL) AGM stmt. Hard to divine the overall picture. [SP=8 Cap=49m]
Nanoco (NANO) gets 80% grant funding to develop a heavy metal-free quantum dot testing kit for the accurate and rapid visual detection of covid. 18 month project to cost c. £1m. [SP=16.8 Cap=51m]
RDL Realisation (RDL) this fund in wind-down aims to delist early 2021. [SP=63.1 Cap=10m]
Xeros Technology (XSG) Indian license partner has received an order for 9 denim finishing machines incorporating Xeros' technologies. It's the first for the XDrum design. Xeros will receive a mid to high single digit royalty plus royalties for the ongoing use of XOrbs. [SP=9.75 Cap=25m]
Irish Continental (ICGC) rev down 26% in first 11 months as car ferry volume collapsed. Vulnerable to fall in Ireland-UK trade. [SP=4.26 Cap=NA]
Scs (SCS) AGM stmt. "Whilst it is too early to provide clarity on the outlook for the weeks and months ahead, we are encouraged by the trading pattern the Group experienced following the first lockdown, when the business benefited from significant pent up demand." [SP=220 Cap=84m]. I hold.
James Latham (LTHM) H1(Sept) rev down 15% though Q2 up 5.3%. H2 started strongly with margins slightly ahead. [SP=832 Cap=166m]
In line: De La Rue (LON:DLAR)
Also Northern Bear (NTBR) H1(Sep) rev down 28%, EPS -13.3 (+5.4). Outlook: co has traded well since H1. I hold.