Small Cap Value Report (Weds 26 Jan 2022) - SOM, BMY, RST, IGR, GMR, ZOO, SRT, SENS

Good morning, it's Paul & Jack here with the SCVR for Weds. Today's report is now finished.
I don't recall it being so manically busy in previous Januarys. Maybe we're covering more companies this year in the SCVRs? Or it could be that the general market plunge this year to date has made everything more intense?
Agenda -
Paul's section:
Somero Enterprises Inc (LON:SOM) (I hold) - 2021 ended with a flourish, and has yet again beaten previous guidance, which was raised as recently as 7 Dec 2021. Looks terrific value still. Outlook for 2022: another good year expected. Increased spending on S+M, and product development, so expect flat profits (which they'll probably beat). This remains one of my favourite shares - a high quality business, performing very well, at a remarkably cheap price.
Ig Design (LON:IGR) - another profit warning, it's down 52% today. Now only breakeven expected for FY 3/2022. Supply chain & logistics problems have crushed its margins. Is that fixable though? It might be in time. I don't think there's any rush to bottom fish here, but at some point it might become a turnaround, who knows? Balance sheet looks sound enough for it to get through these problems. The danger is that it has another profit warning in it. So I'll avoid for the time being.
Gaming Realms (LON:GMR) - a positive sounding update, but it actually looks a little behind forecast, and H2 was down on H1. Large EBITDA turns into small PBT! This company does look interesting, but in a more sceptical market, I'm not finding the valuation appealing.
Srt Marine Systems (LON:SRT) - a big contract win confirmed, looks like it was expected, as share price hasn't moved much. I question the market cap, given how there's been such a long track record of missing forecasts, and historically almost no visibility on the pipeline converting.
Sensyne Health (LON:SENS) - avoids insolvency, with an emergency cash loan from major shareholders. This is to provide enough time to (hopefully) sell the company. Incredibly high risk, with a high chance of a 100% wipeout for equity. Very dangerous, beware!
Jack's section:
Bloomsbury Publishing (LON:BMY) - trading is again ahead of expectations, with strong trading across both Adult and Children’s publishing, plus a major milestone of £5m in profit reached at Bloomsbury Digital Resources. The share price still does not look expensive assuming there has not been a temporary Covid-related boost to reading, so I think it’s well worth a look.
Restore (LON:RST) - FY results ahead of expectations. This looks like a good business - critical activities for customers, with high retention rates, customer satisfaction, and repeat trade. The balance sheet is a little weak, with nearly half of total assets as intangibles and goodwill, but recent approaches from Marlowe suggest others see value in the company at these levels.
Zoo Digital (LON:ZOO) - profits ahead of expectations and will be reinvested into the company to support further growth. No doubt Zoo is in an attractive space, localising streaming content with major media companies spending more than ever on their streaming content platforms. Revenue growth should continue. The ‘primary vendor’ announcement is a good vote of confidence and I can see the share price doing well on the back of this update, but the group’s lack of profits so far makes me pause given the £125.7m market cap.
Paul's Preamble - Valuations re-setting
Whatever the reasons, which I listed in yesterday's market commentary here, it's becoming clearer to me by the day that what we're seeing at the moment is a reset of valuations in the USA, which is spilling over into UK markets.
As a value/GARP investor, I've been worried for years, as to why valuations had become so stretched for growth companies. The only logical explanations were ultra low interest rates (driving investors into riskier assets), and the complacency that comes with a long bull market. Plus a lot of speculative money, and new punters coming into the market, who haven't experienced a prolonged bear market before, who believed that all you have to do is "buy the dip" - which worked brilliantly for a long time, to be fair! But it's not working any more.
It seems to me that all this is coming out in the wash now, with the market scrubbing off a lot of speculative froth, and over-valuations. That's music to my ears in a way, but of course it also drags down almost everything in its wake, even things that are not over-valued. So not a pleasant process. That said, my SIPP is currently down 13% year-to-date, which is a rapid move down, but I just see it as a sharp, but fairly normal market move. Things go down sometimes. Then they go back up again, if they're good companies, reasonably-priced. It's just a question of being patient. 13% is a walk in the park, compared with what happened in Feb-Mar 2020.
I'm not able to accurately predict general market moves, hence it's not logical to try to sell & buy back, attempting to time the market. I'll leave that to the traders with their charts - and good luck to them, but it's not generally my thing. My SIPP is long-term money, in decent companies, so the short-term gyrations in value don't matter at all, because I don't need the money for many years (hopefully). What does worry me, is if an individual company under-performs for any reason, that's when I need to think about selling it. So I remain completely focused on the individual companies I hold, and their fundamentals, not the background noise of general market moves.
I've been looking at the US market closely of late, trying to figure out what's going on. Reaction to large & mega cap results so far has been revealing. For example $MSFT last night - despite posting a beat against expectations for quarterly earnings, the shares dropped 7% in after-hours trading. They got some analysts onto CNBC to explain it, and the rationale for the fall was mainly that MSFT normally beats by more. Also growth was less than expected in the most valued parts of the company. However, a couple of hours later, MSFT shares rebounded to recover all of the initial after-hours dip. Probably due to confidence returning after an earnings call with management?
One phrase from an analyst last night stuck in my mind, about US stock markets right now -
"Fundamentals are strong, but valuation is in question".
I think that's good, and a sign of a healthy market, erasing the most speculative over-valuations. All very interesting, but where does this all leave us in the UK small caps space? Above all, I think this is a time to -
Ditch speculative, story stocks, if you haven't already, and don't get sucked into any more (this is mainly a memo to self by the way, that I'm sharing with you) - because there's less appetite for, and lower valuations on these things.
Avoid companies with weak balance sheets, that need to raise fresh cash from investors. It could be a lot more difficult to raise money now. Placings could now come at discounts, if they can be done at all?
Avoid (or at least be very sceptical of) recent floats, as they're probably over-valued - having floated in more speculative markets (e.g. Microlise (LON:SAAS) which I looked at earlier this week - nice business, but far too expensive for what it is, based on actuals & forecasts)
Watch out for fund managers, that may experience outflows in the coming months, because people tend to pull money out of the market when they see big falls. That could put some funds under pressure, and make them forced sellers, possibly.
Don't anchor to peak prices. Just because something is down 20-30% from its peak, doesn't mean it will necessarily rebound to that level any time soon. As we pointed out here last year, almost every day, many shares became over-valued when the big rally after vaccines were launched (began Oct-Nov 2020) and ran too far, and for too long. That's resetting now.
Decent companies, which are growing earnings, and reporting a positive outlook (and most importantly have pricing power, so can pass on cost inflation to customers), which are reasonably priced (a PER under 20), remain good investments, and shouldn't be panic sold just because they've fallen in price.
Even if you're not ready to buy yet, it's worth using the time in a market correction to compile a watchlist of things to buy. Then push the button when ready - bearing in mind that the best purchases are often the most uncomfortable purchases - i.e. buying when other people are panic selling. If you wait for things to settle down, you'll probably have to pay more.
If you can now buy Netflix on a PER of 25 (was 40), and Microsoft on a similar PER of about 25 (was 30), then why would you prefer some speculative minnow in the UK? And why would you pay a PER of 25+ for something with uncertain growth prospects?, when you can buy top quality US mega caps for a similar rating? I think we need to be very careful about not over-paying for UK small caps.
In conclusion: valuation matters, and has always mattered. We're just coming out of a speculative period where sensible valuation metrics were suspended. Hence we need to be much more careful about making sure we don't over-pay for anything.
Also, if you look at a long-term chart for good companies, you don't look at the low points, and think, "I wish I'd sold at that low point"! You say to yourself, why didn't I buy at that low point? Probably because fear had taken over at the time. It's so important to remember that good companies recover from big falls, and buying at the best time can often feel scary at the time.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Somero Enterprises Inc (LON:SOM) (I hold)
535p (at close, yesterday) - mkt cap £300m
Somero is right up there, as one of my favourite value/GARP shares. It produced a series of positive trading updates in 2021 (despite issuing a cautious outlook at the start of last year).
I wrote very positively about Somero most recently here on 7 Dec 2021, when it upgraded guidance again for FY 12/2021.
It’s obvious from the Stockopedia graphics what to like about this share - a high quality business, with earnings & price momentum, that’s also cheap (I’m surprised the value score is only 66) -

.
Lots of long bars/green below too, feast your eyes on this -

.
For reasons unknown, the stock market seems to always apply a deep discount to SOM shares, sometimes blamed on it being cyclical. Plenty of other companies are cyclical, but don't have a steep discount applied. So that doesn't make sense to me.
There is an issue of US withholding tax, which deters some investors from buying SOM shares.
It’s beaten expectations yet again, in a final flourish to end the year -
Strong finish to 2021 that exceeds previous guidance, healthy North American market drives results
Revised guidance for FY 12/2021 -
Revenue $133.0m (old guidance: $130m)
Adj EBITDA $48.0m (old guidance: $45.0m)
Cash $42.0m (old guidance: $39.0m)
Finncap kindly runs the numbers through its spreadsheet, and forecasts 63.1 US cents EPS for FY 12/2021. That converts to 46.7p EPS at £1 = $1.35
PER is 11.5 at 535p per share - very cheap, assuming earnings are sustainable at this level.
Remember that surplus cash is paid out in divis, so we have upside there too.
Outlook - is positive, and more money is being deployed on product development (including new products to increase addressable markets), sales & marketing. Hence profits expected to be flat in 2022. Although they said something similar a year ago about 2021, then went on to smash forecasts!
... the Board expects 2022 will be a highly profitable year with healthy cash generation, modest revenue growth, and EBITDA comparable to 2021 that reflects the planned investment in resources for future growth and the full-year impact of 2021 staffing additions required to support the growth of the business.
My opinion - this share remains strikingly cheap, which is bizarre for such a high quality business.
Outlook comments sound positive for 2022.
Management strike me as experienced, capable, and trustworthy, with a long track record of success and looking after shareholders well.
This share could easily re-rate upwards to a PER of say 15, and would still be good value even then. So significant upside here, in my view.
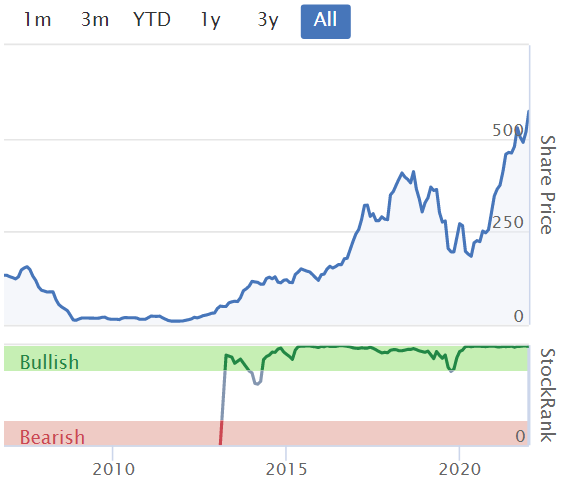
As you can see from the long-term chart below, it's been a major multi-bagger. Although it did come close to going bust after the 2008 financial crash, so was high risk at that point. Scarred by this experience, management now retain a healthy cash buffer, to protect the business in the event of another major downturn - very sensible, I wish more companies would be that careful.
.
.
Ig Design (LON:IGR)
121p (down 52% at 08:29) - mkt cap £119m
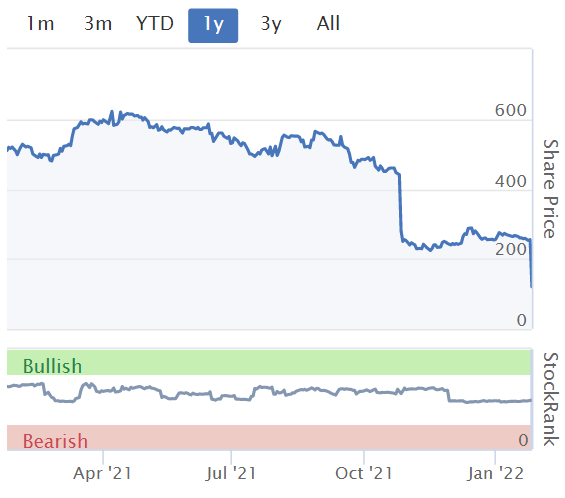
This is a massive faller today, down by just over half, which follows from an already lamentable crashing share price from a previous profit warning in Oct 2021. IGR peaked at c.767p in Feb 2020, so now down 84% from the peak. It’s so surprising, as this was previously a good turnaround, becoming a multibagger from 2014 to early 2020, which has now almost completely unravelled. I can remember writing positive reviews of it, when the numbers were improving nicely in 2016-2018.
I turned negative on the share at 306p, here on 26 Oct 2021, concluding that the inability to pass on cost inflation to customers, had exposed the weakness in the business model.
It’s another situation where big Director sales (£25m!) was a clear warning sign before the rot set in.
IGR had previously warned on 24 Aug 2021 about “challenging cost headwinds”, at 522p per share. However, it reckoned then that it could mitigate these costs, and expected to trade in line with expectations.
Looking back, it’s difficult to see how anyone could have predicted such a disastrous fall in share price down to only 121p today. Is it now cheap enough to consider bottom fishing, catching this falling knife? Let’s find out…
IG Design Group plc, one of the world's leading designers, innovators and manufacturers of celebrations, craft, gifting, stationery and creative play products, today issues a trading update for the nine months ended 31 December 2021.
The current financial year ends 31 March 2022.
Good revenue growth (up 12% on a LFL basis) at $828m - a substantial business, for a market cap of £119m.
Supply chain and logistics problems have incurred additional fulfilment costs.
It also mentions reduced sales of craft products in the USA, from previous peak driven by the pandemic.
Problems seem to be in the US division, and have hit group profit margin hard -
As a result, and despite the International business performing in line with expectations, the US division has incurred significant supply chain costs, specifically in relation to freight, labour and raw materials, which alongside the lower craft revenues has resulted in Group adjusted operating margins in the nine-month period of 4%, down 460 bps year on year.
That’s a big reduction in operating margin, it’s dropped from 8.6% to 4.0%.
Full year guidance - is only breakeven! That’s clearly bad news -
This year to date performance, together with the expectation of the continuation of the cost headwinds and lower craft sales in the final quarter, means the Group now expects its full year FY22 adjusted operating profit to reduce to a breakeven position, resulting in full year earnings significantly below current market expectations.
That must mean a loss, once all costs are included, as operating profit excludes finance costs, which can sometimes include an element of property rentals. Finance costs were £5.2m last year.
Dividends - cancelled for FY 3/2022, but hoping to reinstate in future.
Outlook - too early to say, as they’re busy trying to sort things out -
It is expected that these external challenges will continue into FY23 bringing heightened uncertainty and it therefore remains too early to give firm guidance on FY23 financial performance.
Consumer demand remains strong and discussions with customers and suppliers to mitigate the headwinds are progressing.
The Board will provide a further update to the markets in April 2022 as part of the year end trading update.
Board review of its US operations - not clear what this involves, but they want to restore profitability. Possible sale/closure of parts of the business, I’m wondering?
Liquidity - is fine for now, but remember IGR has a large borrowing requirement for seasonal peak, in the run up to Christmas each year. So I think investors need to look into the terms of the bank facilities, and in particular any interest cover, and debt:EBITDA covenants, which could come under pressure now the company is only trading around breakeven maybe?
Although banks are generally more relaxed about lending which only covers seasonal peaks, and is then repaid from seasonal cashflows, as they generally perceive little risk with that type of temporary lending.
CFO resignation - looking back for telltale signs of things going wrong, the announcement on 16 Aug 2021 of the CFO Giles Willits tendering his resignation for “personal reasons” could have been a warning sign.
Today’s update says he’s still with the business, extending his notice period until a replacement is found.
CEO commentary - nice to see a slice of humble pie appearing here, but I can’t help feeling this all sounds a bit behind the curve, and could result in exceptional restructuring costs maybe? -
Paul Fineman, Group CEO, commented:
"To say that I and the whole Board are disappointed with our financial performance over FY22 to date is a huge understatement. Without any end to the supply and cost challenges in sight we cannot simply wait for these external challenges to improve.
We have therefore instigated a review of our US operations, analysing our cost base and identifying improvements that can be made quickly.
We remain confident in our long term strategy but with the current challenges unlikely to ease in the short term we plan to undertake this review to ensure it remains appropriate. We will update on progress over the next few months."
My opinion - IGR made $19.9m adj PBT in H1, and had $58.8m net debt at 30 Sept 2021.
Therefore, it now saying FY 3/2022 is looking to be c. breakeven, suggests a hefty loss in H2 - clearly worrying.
I’ve reviewed the last balance sheet, and it’s quite strong. So I’m not worried about solvency, as things stand today.
That the outgoing CFO has stuck around for almost 6 months, waiting to be replaced, suggests there’s probably not much risk of something really ugly lurking in the accounts, but you never can be sure, with any company.
Are the problems fixable? It all seems to stem from supply chain disruption, which then seems to have triggered excessive warehousing & distribution costs, to get product out to customers in time for Christmas. I can picture in my mind an overflowing warehouse, with temps drafted in to work 24 hour shifts, which of course is very costly. A business that hinges so much on peak Christmas products, can’t tell customers they won’t get the goods until January, as they would be effectively worthless by then. Tricky.
Taking a longer term view, I imagine the logistics problems should be fixable. For that reason, I’m starting to think this share might have recovery potential. But there doesn’t seem to be any rush to buy, because situations like this often bump along for months before any signs of recovery become evident. Or if a major holder decides to dump them at any price, then it could keep drifting down.
Overall then, it’s not something I’m in any rush to buy, but can see possible recovery potential at some point later in 2022 maybe? That’s assuming things don’t get worse of course. It might have another profit warning in it, who knows? I am concerned that management don't seem to have things under enough control. Some companies have coped with supply chain problems. Others have fallen over. That could be telling?
.
.
Gaming Realms (LON:GMR)
30.5p (down c.2% at 10:24) - mkt cap £88m
Gaming Realms plc (AIM: GMR), the developer and licensor of mobile focused gaming content, announces a pre-close trading update for the full year to 31 December 2021 ("FY21").
The headline sounds good -
FY21 Revenue and EBITDA* Growth of 27% and 70% Respectively Complemented by New Regulated Market Launches
[their bolding]
Revenue of £14.5m - Stockopedia shows a forecast of £14.8m, so this looks a bit behind.
H1 revenue was £7.7m, so H2 lower at £6.8m
Adj EBITDA of £5.6m looks good, but the company capitalises development costs, which this number ignores (along with lots of other costs, eg share based payments, restructuring costs, plus of course depreciation, amortisation, interest, and tax!!!)
In H1 adj EBITDA of £3.1m turned into £0.8m profit before tax (PBT). So H2 EBITDA is £2.5m, which looks like it would only be about £0.2m PBT. Giving us perhaps £1.0m PBT for the full year - not much for a £88m market cap company in today’s more sceptical markets. That looks a tad warm actually, as a very detailed research note from Cannacord (many thanks for this) on Research Tree, suggests £0.6m adj PBT for FY 12/2021 (based on £5.4m adj EBITDA forecast published in late Nov 2021).
Outlook - no specific guidance on numbers, but this sounds positive -
Michael Buckley, Executive Chairman of Gaming Realms, commented: "We are delighted with the performance in 2021, where we launched in new markets and increased the distribution of our expanded Slingo portfolio. We have a strong pipeline of opportunities and the outlook is very encouraging, with further expected expansion of our international footprint coupled with additional deals within the markets where our content is already distributed. We believe that the strong momentum of last year will continue into 2022 which is demonstrated by entry into regulated markets announced today."
My opinion - the crux is how much of the dominant revenue stream (licensing) are one-offs, and how much is recurring revenue share? I can’t find the split in the Canaccord note, or any of the company’s announcements.
Canaccord does mention that contracts include a revenue share, so some of the revenues do seem to be recurring, but I need to know how much? Also I recall mgt saying in a webinar that the more customers play, the more revenue GMR receives, so there is definitely an element of repeating revenues within licensing.
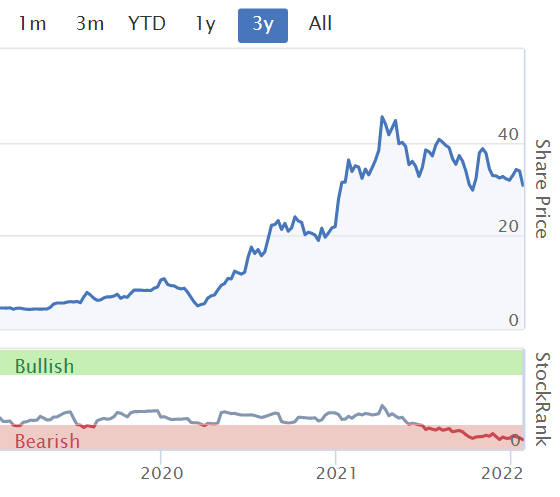
There is something interesting here, GMR does intrigue me, because it’s growing revenues, has now moved from losses into (modest) profits. Plus its games seem popular (mainly “Slingo”) internationally, with new clients being won. Hence I wonder what the potential market size is? If it’s very big, then there could be nice upside.
Until I properly understand the revenue model, I wouldn’t want to take the risk here. The stock market tide has very much gone out, against speculative growth companies on high valuations. For that reason I perceive valuation risk here, so will give it a miss. Too much of the valuation (almost all of it actually) is based on revenues & profits continuing to rise strongly. That’s fine in a roaring bull market, but a lot less attractive when investors are being so much more cautious & critical on valuation. So this risk is that it could continue to drift down, with occasional spikes up on contract win announcements.
I'll keep it on the watch list, but don't see any rush, or an attractive valuation, to get involved now.
.
.
Sensyne Health (LON:SENS)
19p (up 24% at 11:12) - mkt cap £31m
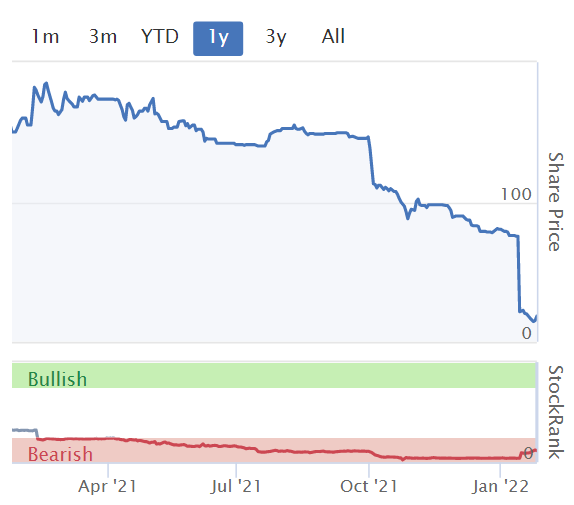
This has spiked up today on completion of an emergency debt funding, to avert insolvency.
I just want to reiterate to readers my warnings here on 14 Jan 2022 - this company is teetering on the brink of insolvency, having run out of cash.
Institutional shareholders have loaned it (not fresh equity) short-term funding, to allow it to continue trading long enough to sell the company.
The new loan funding has warrants attached, so dilution at 10p from them, if the company survives at all.
This share is now incredibly high risk - and people buying the shares now, need to realise that there’s a significant chance of a 0p outcome. It all hinges on whether the company can collect in a disputed receivable balance, and find a buyer for the business, which is haemorrhaging cash.
We don’t know who potential buyers are, nor what value (if any) they see in the company.
Therefore, it’s an extremely high risk punt.
The downside risk, that equity gets wiped out, with a buyer of the business (if they can find one) maybe not prepared to pay very much, and of course the owners of debt rank ahead of equity, so you often see equity wiped out in a distressed sale.
If you want to take the risk of a wipeout, that’s up to you of course, I’m just pointing out how risky this situation is. It’s not worth risking all your money, just on the possibility of a favourable outcome for a company that is close to going bust. I wouldn't touch this with a bargepole.
.
.
Srt Marine Systems (LON:SRT)
47.5p (up 3% at 11:19) - mkt cap £78m
Good to see SRT has won a major contract - it’s been promising big deals for many years, and visibility seems non-existent, with p[ipeline rarely turning into revenues or profits as expected. That’s not the company’s fault - they’re dealing with numerous Govt agencies in other countries, which means wading through complex bureaucracy, and project delays that can run into years.
Simon Tucker, CEO of SRT Marine Systems, commented:
"I am very pleased to be announcing the signing and commencement of the first phase of this £40m SRT-MDA System project. Our project delivery team and in-country partner are well prepared and implementation will therefore commence immediately. This is an important new customer for SRT and we expect that further contracts will follow as they build up their national maritime surveillance capabilities in the years to come."
The track record is way too volatile for me to consider investing here, but good luck to holders. The £78m market cap looks very generous to me, given that we’ve had so many years of upbeat pipeline, but not much conversion into reliable, repeat revenues. that could all change, and a £40m contract win is a very good start!
.

.
Jack's Section:
Bloomsbury Publishing (LON:BMY)
Share price: 357p (8.18%)
Shares in issue: 81,608,672
Market cap: £291.3m
Trading update for the year to 28 February 2022
Bloomsbury is pleased to announce that revenue is expected to be comfortably ahead and profit materially ahead of market expectations for the year ending 28 February 2022.
Consensus is for revenue of £197.1m and profit before taxation and highlighted items of £20.1m.
Trading has remained strong in the Consumer division for both Adult and Children’s publishing. Meanwhile, in Bloomsbury Digital Resources, the group has reached a ‘major milestone’ of £15m in revenue and £5m in profit. That’s very high margin, well ahead of group levels. There’s also the benefit of recently acquired ABC-CLIO (£17.3m in cash) to come through in this division.
Conclusion
A short update, but one confirming ongoing positive momentum. The growth in Digital Resources is a real point of interest, while the group’s Consumer division continues to perform well due to its quality and depth.
The StockRanks still love Bloomsbury.

And the margins are improving. It looks like there could be a real opportunity here. I had been concerned about the potential of a lockdown reading boost that might wind down, but so far this has not happened.

The shares fell slightly after the recent market drop, but are now right back to where they were. Still, the valuation is not demanding and the group is trading very well. It’s really putting itself forward as a strong candidate for further research.

Restore (LON:RST)
Share price: 472.35p (4.03%)
Shares in issue: 136,674,067
Market cap: £645.6m
This is the UK's leading provider of integrated information and data management services, secure technology recycling, and commercial relocation solutions. It has recently been in the news for fending off a couple of approaches from Marlowe (LON:MRL) .
Trading update for the year to 31 December
Restore expects to report record levels of revenue and underlying operating profit for FY21
Activity levels continued to grow through Q4, with positive organic performance further enhanced by very strong commercial execution and ongoing efficiency gains.
The eight acquisitions completed in 2021 are all contributing financially and are either in line with, or ahead of, plan. That’s quite a pace of acquisition. Management says this buying spree has enabled the business to significantly extend its geographic footprint and service offering.
New debt facilities announced to support long-term objectives. A £200m unsecured, multicurrency revolving facility agreement ("RCF") on enhanced terms with a syndicate of six lenders, which replaces the company's previous £160m secured revolving credit facility.
Outlook
- Strong, scalable platform, ESG-friendly,
- Underlying organic growth, market share gains, and new customer wins in FY21,
- Expected market share gains and new organic wins in FY22 from significant customer pipeline,
- Ongoing cost reductions and synergies from acquisitions,
- Substantial and high-quality acquisition pipeline.
Conclusion
This looks like a nice business performing critical activities for customers, with high retention rates, customer satisfaction, and repeat business.
The share price has had a few false starts over the past five years, despite encouraging revenue growth.


Net income has been more volatile, but still trending upwards. Restore is acquisitive, so perhaps exceptional integration costs are obscuring underlying progress? That’s just a hunch to be investigated.

It looks like the group did not have to pay much tax until FY17, and there have been some exceptional costs reported. See diluted EPS pre and post-exceptionals below, on the left and right respectively.
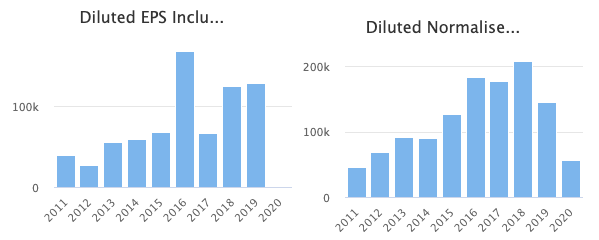
There has been a degree of equity dilution here, and net debt has crept up recently although this is mostly down to around £104m of capital leases being added into the equation as of FY19. Goodwill and intangibles make up around 50% of total assets, which is on the high side.
A middling balance sheet I’d say, with some areas to investigate, a bit of a shame but perhaps not serious enough to take the sheen off of these results. There’s acquisition risk here, too, so it’s worth digging into management’s track record in this regard.
The group has fended off a couple of approaches from Marlowe (LON:MRL) recently (see the coverage in the most recent SCVR posts on Restore’s Discussions page), so it’s in demand and that appears to have provided a decent floor for the share price over the past six months.

A forecast rolling PER of 16.9x does not scream ‘cheap’ but neither is it particularly expensive. Restore is trading well and has consistently grown its top line over the years. All in all, the company comes across positively, albeit more fairly priced post-Marlowe approach.
Zoo Digital (LON:ZOO)
Share price: 143.3p (+10.23%)
Shares in issue: 87,684,094
Market cap: £125.7m
A world-leading provider of cloud-based localisation and media services to the global entertainment industry
Trading update for the year ending March 2022
Revenues for the year are anticipated to be ahead of market expectations, yielding additional profits that are being reinvested in staff, infrastructure, facilities and international operations to extend ZOO's capacity and support growth.
Zoo Digital says it is ‘cement[ing] its position as a leading provider of end-to-end services for the streaming video industry’. H2 trading has benefitted from the resumption of new productions, the ongoing migration of catalogue titles to streaming platforms, and regional territory launches.
FY revenue is now expected to be at least $57m (up 44% on FY21’s $39.5m), with H2 up 11% on the first half and at least 29% ahead year-on-year. The group also notes a ‘strong and growing’ pipeline of orders across all service lines.
Localisation revenues are expected to grow by at least 55% and media services by at least 30%.
ZOO has been appointed as a primary vendor for the forthcoming European launch of a global streaming video service and expects that this will lead to significant orders commencing in Q4 and delivering meaningful revenues in FY23.
That’s encouraging. I wonder who this global streaming video service is? The last part of that quote suggests to me further upgrades might be in store.
Conclusion
Zoo has struggled for profits previously, while shares in issue have more than doubled over the past five years. The group’s CEO remains its largest shareholder, however, so he is incentivised to build shareholder value.
And there’s no doubt that the group appears attractively placed with some strong tailwinds. Major media companies are building out their streaming video platforms and are seeking to offer greater volumes of exclusive content. Specialist media analytics firm Ampere Analysis reported that spend grew to a record $220bn in 2021 and forecasts further growth in 2022.
WarnerMedia, NBCUniversal, and ViacomCBS have launched streaming video platforms in North America and have all announced plans to make these services available internationally in 2022. So there’s unprecedented levels of demand.
There’s just the actual profitability of the enterprise to prove. The group is valued at £125.7m but is forecast to eke out a $2.5m net profit by FY23E, which is well above anything it has achieved so far. In fairness, Zoo does seem to reinvest in its tech.

How valuable are its services in a mature market, and does it have an edge over competition? Perhaps thoughts of maturity are too early given the strong market growth trends, but the degree to which intellectual property sets it apart from the rest strikes me as important. If there’s not too much in it, then competition and pricing will become a factor.
By the sounds of it, Zoo’s in-house software enables faster and cheaper subbing and dubbing services. So it could have enough about it to start generating meaningful profits. Presumably there will be a degree of operational gearing should revenue growth continue (which it looks like it should).
The story sounds good and I can see how additional upgrades might lead to a strong share price. Zoo could go on to do very well, but for now the valuation is a little too rich for me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

91 comments
Tesla results out look pretty sound.
Would be interesting to know if any of the Tesla skeptics or ex skeptics are starting to change their viewpoint ref this company?They seem to be churning consistently good numbers that surely all the bods previously shouting it’s all a fraud must soon admit they got it completely wrong ?
I can understand the taking viewpoint that it may be expensive but surely anyone looking at the figures today has to give the company respect for the reasonably good job they are doing bearing in mind supply chain issues most car manufacturers are facing.
Forecast Growth next year - sorry now this year - should be easy Peasy with the investment they have put in this year into China and Germany factories - can’t really can’t see any scenario where tesla don’t have a good 2022and they are now so well capitalised no need or probably want anymore to pimp up the numbers.
Love the preamble Paul, some wise words and interesting market musings
Zoo Digital the commentator changes but not the opinion yet the price continues to rise
Is this rational or human
"I don't recall it being so manically busy in previous Januarys."
Paul, could it possibly have something to do with last year when you decided to increase the size of the Market Cap of the companies you look at SCVR from around £400 million-ish to around £750 million-ish??
Good discussion on Somero Enterprises Inc (LON:SOM) today which has prompted me to look back at my decision to sell at the end of September 2019 only to see it increase x3 since then! This followed a number of profit warnings and had I been using my current selling rules (only applicable to a NAPs type short/medium term sub portfolio) these would also have signalled a sell. These are stock rank <80, Trailing stop loss -25% (for an adventurous stock), -10% or more relative strength since purchase and price less than the 200 day MA. The Stockreport for end September 2019 (available via the print button) confirms these negative measures but highlights the excellent Quality & Value ranks with plenty of 'green' flags throughout the report including passing 6 guru screens. Somero Enterprises Inc (LON:SOM) was rated a contrarian style and this combined with some strong metrics suggests despite the sell signals (and the profit warnings) I would have been better advised to buy more shares! - a decision which would have proved profitable in hindsight. Unfortunately I am now anchored to my 2019 sell price (£1.87) which in itself was at a significant loss and find it very hard to press the buy button on a repurchase of Somero Enterprises Inc (LON:SOM) despite apparently excellent results and prospects. I guess this is the reverse of the price anchoring behavioural bias that Paul referred to in his preamble! On the plus side the experience and retrospective analysis might prove useful if a similar situation arises with another stock that hits a bad patch.
Has anyone looked at Safestyle Uk (LON:SFE) today, with profits increasing despite the current head winds of material costs. 2 broker reports out both stating under valued. Increase in cash position and a dividend likely to resume mid 2022.
Thank you for your preamble, Paul. You came out with a thought-provoking concussion today:
"Also, if you look at a long-term chart for good companies, you don't look at the low points, and think, "I wish I'd sold at that low point"! You say to yourself, why didn't I buy at that low point? Probably because fear had taken over at the time. It's so important to remember that good companies recover from big falls, and buying at the best time can often feel scary at the time."
While I am generally a long-term investor in smaller companies and specialist investment trusts, I do have a version of trading, and that is:
Look at long-term charts of a few FTSE 100+ stocks, set targets at low points. Buy around the low point, with a view to selling when they re-rate back 15%. Often it works within a year. For instance, feeling fed-up at unscrupulous touts last year and in need of defending my family, I held my nose and bought Imperial Brands (LON:IMB) @ 1380 and sold @ 1600 a few months later, banking a div along the way. This was definitely not a long-term investment in a quality company, but just a convinction that something still robust was oversold. I bought some Persimmon (LON:PSN) at the end of last week on this basis....
Joules (LON:JOUL) I held, but sold out after being alerted to their recent (last 6 months or so) trustpilot scores. They have been truly terrible. I know that this will only be a small sample of all sales and that a (relatively) few negative could actually be caused by them doing such good business they've struggled to keep up, but I wasn't willing to hold during results in case they were indicative of broader issues.
Here's today's list. Sorry we missed Forterra (LON:FORT) (Doug likes it, see post below for a nice review of it), just ran out of time, we can't cover everything - so we prioritise profit beats or misses, which sometimes leaves behind less important in line updates. Although I see FORT shares are up decently today, so looks like there might have been something positive in there. Looks a good value share, best for income seekers with a decent divi yield. Nice strong operating margins.
Joules (LON:JOUL) haven't made their usual annual January Christmas Trading update this month. Their latest announcement was a pre-close trading update on 14th December (effectively a profit warning). SP has continued to slide since and Interim Results are due to be announced next week on1st February.
The silence on Christmas trading could be signalling more bad news at the Interim Results announcement.
Doesn't bode well (I hold).
Joules will be reporting on the 1st of Feb fyi
The same thing crossed my mind Snazzytime regarding Joules ( JOUL) which I hold.
Im hoping that reporting rules would mean that they would get into very deep water if they failed to advise the market of a further profit reduction of which they are aware, which I am sure they would know about by now and certainly before they report on I Feb.
And I too was pretty shocked by reading the trustpilot reviews but these have since been mitigated by a couple of factors :
- The first being that I every christmas buy the grandkids a range of nice stuff from Joules. Whilst they apologised online at the time of order that there would be some delay from their usual delivery timescales, in the event there was no issue.
- The second was that I figured that if it really was as bad as the trustpilot reviews made out , then it must have made life pretty horrific for the poor shop staff in the run up to Xmas and since . In the event I could find no reference to these problems on Glassdoor, where generally the response of Joules’ people was pretty positive .
Fingers crossed for the Ist Feb - I’ve convinced myself it will be ok !! Always dangerous ….!
Hi RutlandRam
Not a Joules (LON:JOUL) specific comment, but I would say that reporting rules are regularly abused, especially on AIM, and nobody ever seems to get into shallow water, let alone "very deep water" as a result.
I work in the ecommerce sector and have good relations with a number of review companies but not Trustpilot. They are a shady lot with questionable marketing and sales tactics. Joules does not have a commercial account with Trustpilot so this means Trustpilot do not collect their reviews. A customer has to proactively visit Joules on Trustpilot to review them and they're only going to do this if they have a bad experience. Trustpilot will not let Joules reply or moderate to reviews unless they sign a commercial arrangement. This is why companies who have an arrangement with Trustpilot have far better scores. You should not use Trustpilot to judge a company. Use Google reviews would be far better.
Three little points on Paul's comments
1) I think you are an excellent reader of the broad market. You triumphed by shorting early in 2020 and have correctly indicated here your concerns about what we in hindsight all know - interest rates, supply chains, and (perhaps?) politics hitting the stock market. So full marks here no need for modesty
2) I do think you are too sweet on the retail apparel sector. It is a sector full of remembered favourites, changes in fashion, eco problems and Chinese competition. I am the twit who sold my BooHoo at 40p with a great profit and who was recommended to buy Asos at 12 or 20p about 25 years ago so I am no expert - but I do think is is a tough and increasingly competitive sector.
3) On SOM (which I also hold) I personally doubt that there will be any huge upward re-valuation. It remains highly dependent on the US commercial market which could be impacted by future rate rises and there was that year about ten ago when earnings just disappeared. I agree that the chance of that recurring are very slim and that the company and market - thanks largely to Amazon and the growth of online - is quite different. But it does make construction machinery and that can be a discretionary spend if demand contracts.
But as usual many thanks for the most useful input from you both
Lucky you who sold Boo for profit at 40p.
at 104 it is my second biggest loss after BOTB.
Time to buy 'exceptionally cheap'
"British stocks are undervalued and represent a golden buying opportunity despite recent market turmoil, two of Wall Street’s biggest banks have declared."
If you can now buy Netflix on a PER of 25 (was 40)
I would be careful with Netflix, that forecast PER is 2 years out and a lot can happen in that time period. This years forward PER is 32 with zero earnings growth forecast. The chart also looks terrible. If 2023 guidance gets revised down during 2022 it could fall a lot more.
I mentioned Netflix yesterday and will repeat here that it is now seeing intense competition from Disney, Amazon and others. It is therefore (in my view) losing the economic moat that justifies a high (20+) multiple. I would personally stay well away.
I was taking a look at recent IPOs from the previous 2 years last night.
Most seem to have have been overpriced and performed terrible after any initial excitement.
Its an area I wish Id taken more of an interest in last year for possible shorts. Difficult to time right in a roaring bull market but worth keeping an eye on I think.
The liquid large (over £1billion m/c) loss makers seem to have been the best candidates to short.
£THG
£TRN
£ROO
£AML etc
Will be keeping an eye out for any large loss makers coming to market in future.
Ig Design (LON:IGR) (no position)
I'm somewhat baffled by the very heavy fall this morning.
At the interims the group said the following:
"...the Group continues to expect FY22 full-year operating margins to be 175-225 basis points lower year-on-year resulting in full-year earnings being significantly below the prior year."
OP% in FY21 was 2.3%, so I simply assumed that operating profit % in FY22 would be zero, which was confirmed today.
Based on the Year-on-Year cash position, it looks like there has been some cash burn, but nothing to suggest insolvency is close.
I note from the Stock Report that Operating Profits were >$20m back pre-covid and the company is much bigger now with an EV as I write of £85m.
Give the perceived lack of solvency issues I a, tempted to buy some at such a low price on the hope of a re-rating in the next couple of years.
A
Thx for the great preamble and the write up on Somero Enterprises Inc (LON:SOM) (I hold and topped up today).
Regards
Michael
Dear Paul
In case you have not yet seen it, this morning Edison has published a note on Hostmore (LON:MORE) (I hold). Forecasts for the year ended 2021 have been upgraded following strong Winter trading, whilst debt is estimated to be around £25 million versus £29 million previously. Assuming the analyst is correct in his forecast for this year, it looks as though Hostmore could deliver £15 million of pre-tax profits to generate around 10p of earnings, implying a modest PER of 10.
The only concern I have is the high level of debt estimated to be £160 million of which lease liabilities represent £138.5 million. Should that be worrying? Edison estimates the company will pay £26 million in interest this year and I wonder whether investors will want to see a stronger trend of cash generation before a re-rating can occur.
Kind regards
Phillip
re Hostmore: The only concern I have is the high level of debt estimated to be £160 million of which lease liabilities represent £138.5 million. Should that be worrying? Edison estimates the company will pay £26 million in interest this year
That can't be £26m interest - that's more than the debt. Presumably they mean interest plus lease payments? Looks a bit different like that!
Interesting, albeit brief, note on 10 baggers in the UK here: https://www.schroders.com/en/u...
Interesting but is because quite a few US 10 baggers were not around in 2011?
Stocko really ought to be looking closely at FORT. My largest holding and only a tangible surplus of c7% of current MCap, possibly less after today's 11% price increase.
Why would FORT be may largest holding when it produces the lowest net tangible surplus of any of my holdings, how can this be when I am wedded to the tangible surplus with apparent religious zeal!
In reality, the tangible surplus is a starting point, a base for a wider analysis, by far the most important metric for company valuation, but the wider context of the business and what is unfolding has also to be assessed. This is heresy a betrayal of principle!
Alas with FORT, they have maintained a tangible surplus of c7% of MCap despite the ongoing investment in their new Desford brick plant. A remarkable achievement in itself, and as for the Desford brick plant, well, it begins production later this year, Europe's largest brick plant I believe. The UK imports nearly 20% of its bricks currently, mainly from Holland, that import ratio is likely to increase in the coming years despite FORTS new facility. Bricks are very expensive to transport relative to cost, the required imports create a strong pricing moat for UK based producers. FORT's tangible surplus will likely be up into the teens in % terms within a couple of years, relative to its current MCap
There’s a lot of energy used in brick making. I would want more detail from Forterra (LON:FORT) on the cost impact there. They were only hit in one quarter so far and they say they have locked in 2022 pricing - but at what level?
My understanding is that a combination of long term protective energy contracts held by FORT and increases in brick prices going forward has meant that FORT do not see the gas price increases as a significant risk to the business at all. FORT are the most obsessive business when it comes to under promising and over delivering and yet they are embarking on a share buy back programme due to strong cash flows, even before the new Desford plant opens.
If gas prices go through the roof and stay high long term, brick prices will rise accordingly. FORT are not the vulnerable low hanging fruit within the sector, they are a low cost producer, about to be become an even lower cost producer with the new brisk plant.
Re Forterra (LON:FORT) and energy costs - Unless they have more relatively energy intensive brick making than their (UK) competitors or less forward buying, the costs will be passed on to builders, perhaps with a 3-6month lag. The UK brick market is a tri-oply with a big moat; they will all go up. Imports are important (up to 20% mkt share) but only really competitive in areas close to ports in the SE.
Energy efficiency in newer brick making plants/lines has improved a lot, so capital (still cheap) has increased but operating costs have been permanently cut. (I think this theme of investing still cheap capital to save energy will be a big theme this year).
I hold and prefer IBST, partly on this basis as they closed /mothballed some old small plants. This was allegedly for ESG reasons but I believe equally for cost reasons .
We are in a great, rare, moment where many 'green' decisions make financial sense for companies.
What is a "tangible surplus"?
It’s a new religious.
This share hasn’t gone anywhere for the last 10 years and will certainly be the same story for the next 10.
Comments like this (unsubstantiated statements) should be removed. Rampers and derampers are not welcome here.
Forterra (LON:FORT), I cant help thinking that all construction is getting hammered regardless of the sector....very low PEs and some great value companies.. i don't get it. Recently got into Persimmon (LON:PSN) as the SP I think is fantastic, but still dropped a little more from bargin basement stuff.
Keen to know your thoughts on £CMCX. In line trading update today and looks way oversold given current volatility.
The last time Cmc Markets (LON:CMCX) have an in-line TS, they then followed it shortly afterwards with a "we're going to miss by a wide margin" update. They obviously clung for far too long to the forecast they had previously given.
Can't say I am prepared to give them the benefit of this doubt on an "in-line" TS any time soon. That's not to say they may not be correct on this occasion
Yes Cmc Markets (LON:CMCX) huge downgrade last year due to very quiet August. I thought perhaps they were being cautious on case markets remained flat. However, volatility clearly picked up since then, but seemingly not their trading and they are sticking with their hugely downgraded estimates. Compare with Plus500 (LON:PLUS) who produced very strong update recently.
Yes, will be interesting to see if Cmc Markets (LON:CMCX) are erring on the side of caution this time or if they genuinely haven't benefited from the recent market gyrations (or if the uptick from market gyrations have been offset elsewhere).
They are now well through their financial year and we've had a few months of choppy markets so it doesn't look like things have picked up at all. If they were expecting to beat (massively downgraded) expectations then they are obliged to say so.
Not looking pretty for Ig Design (LON:IGR): this morning profits expected to be significantly below expectations due to supply chain problems.
This could be one to stick on the watch list as this was a good preforming stock in pre-covid times so might come good again when supply chain problems normalize.
Regards
Andy
Somero Enterprises Inc (LON:SOM) (I hold)
A nice update today, with many positives. There was, however, one thing that confused me.
How is it possible for Revenue, EBITDA and Cash to all increase by $3m in one month?
Given historical EBITDA margins of c33% surely the increase in EBITDA should have been a more realistic $1m, not the $3m announced today?
Given that cash has also increased by $3m, it's almost as if $3m of revenue has been booked without any associated costs.
---
On a separate note I noticed that H2 Sky Screed revenues are flat vs last year ($0.7m) & the Broom+ Cure sales have slightly declined vs H1 ($1.2 vs "<$1.1m").
It's interesting that these are the numbers published today given the growth must be coming from other products.
---
The above points aside, I remain a big fan of the company (and its management) and have a decent sized holding, which I don't plan to sell.
Cheers
A
Somero Enterprises Inc (LON:SOM)
"How is it possible for Revenue, EBITDA and Cash to all increase by $3m in one month?"
well they didnt say that - they simply updated their expectations for the "whole year" by that amount in the last month - subtle difference there.
The obvious answer is that they left something in the tank that is being booked now (or not taken out now) and that causes anomalies - note its probably also the case that they will not necessarily have sat down and done the formal numbers right up to 30th November at the time the announced the update early December. It would perhaps make sense to keep something in the tank ref bad debt - stock adjusts blah - warranty provisions - it mightly only be now that year is finished that they say ok that reasonable provision will clearly not be needed so we are happy to say that the numbers can be upped now.
Somero Enterprises Inc (LON:SOM) (I hold)
This could make sense but it wouldn't explain the cash position changing by the exact same amount as the other movements.
If it's like every other organisation I've worked for the management accounts will be produced every month. In any case I would expect management to know their revenue/costs quite easily whatever day of the year it is.
As a holder I'm not concerned and merely pointing out some quite circumstantial numbers. I'm sure all will be revealed once full year results are out.
A
Somero Enterprises Inc (LON:SOM) (I hold)
A nice update today, with many positives. There was, however, one thing that confused me.
How is it possible for Revenue, EBITDA and Cash to all increase by $3m in one month?
This is me just speculating, if all the sales are from inventories, then all the revenue from these additional sales will convert to EBITDA and to cash. (I hold too)
Somero Enterprises Inc (LON:SOM)
This is me just speculating, if all the sales are from inventories, then all the revenue from these additional sales will convert to EBITDA and to cash. (I hold too)
It doesnt work like that as there is the adjustment from inventory (bs)to cost of sales (p&l) for anything sold from inventory.
Interesting preamble, hard to disagree with any of it, apart from Microsoft perhaps, but let me come on to that.
Somero Enterprises, one of Stocko's darling stocks, let's take a look. Tangible equity has inceased at an average rate of just over 1% pa over the past 4 years. Add that to the above yield and you get an tangible surplus of just under 8%. This suggests that Somero is indeed a buy. Is it a compelling buy? Not quite, I am looking for a tangible surplus of nearer 10%.
Do the quality metrics for Somero override the fact that the tangible surplus is a little below my target of 10%. You would have to take a view on this, most important would be your view on earnings growth (hence the rate of equity growth) over the next couple of years.
In summary: Kicking myself here. Up until early 2021, the valuation for Somero was utterly compelling and I missed it!
Microsoft - net tangible equity has grown at an average rate of c0.7% pa for the past 4 years. The yield is c0.8% and sahre buy backs add c0.6% to the net equity gain. Put it all together and you have a tangible surplus of just of 2% realtive to the current MCap.
This is a poor return, meaning that the current share price is over 2x a fair price and a long long way off being a bargain, over 3x higher than a bargain price. And what are you getting for your just over 2% tangible return? An established giant, yes, but so what! I can assure you that Microsoft is not going to readily grow into its current over valuation, not unless it opens an inter galactic division - I understand that the Marshan Word softwear is coming on nicely!
Interesting assessment on Microsoft. Do you have an assessment on Facebook by any chance?
Interesting assessment on Microsoft. Do you have an assessment on Facebook by any chance?
Facebook, very similar, a net tangible surplus around 2.5% when you factor in the share buy backs. About half a fair price. You should expect some price declines from here.
Excellent comments Doug2b.
One question here do you ever project your calculations forward? if we take the viewpoint that 2021 and 2022 numbers will be bumper i guess that could at that time (january 2023 when 2022 numbers are finalised?) perhaps lift the numbers above the 10% if the 2022 numbers directly replace a year when they did less well stats wise? I am guesing you wait till numbers are in the bag and then add it up - that would make sense. Presumably thats dependent on shareprice going nowhere in the meantime. Final question have you included the waht will be ecellent 2021 numbers in your calcs ? these should certainly be more appealing than the year they replace (well i am presuming that is the case).
If you add back the special dividends that have been paid and are material (nor included in the current yield estimates) to the average increase in tangible equity you would be in excess of 10% I think.
Microsoft probably did not look good value 10 years ago, but still went up 10x, even if it goes down to fair value it would be up 5x. Not a bad return.
Not sure you can compare technology stocks with brickmakers.
Somero Enterprises Inc (LON:SOM) must have been screaming bargain in 2020, dividend was 10%, shares have since tripled and are still better tangible surplus rated that Forterra (LON:FORT)
So what are the stock that are have over 10% tangible surplus?
I am simple minded but the point 'Microsoft - net tangible equity has grown at an average rate of c0.7% pa for the past 4 years '
It is a software company.. surely you'd not expect a bulk of tangibles..?
if that is stupid happy to be schooled and learn.
This is starting to go round in circles a bit - Doug2b has their metrics and they stick to them whatever the the business type. Its a simple formula that takes nothing else into account -ref business type.
Please correct me if i am wrong here Doug2b
pointless arguing that you think the formula is wrong as from Dougs perspective it works very well and its their golden rule whatever the business type.
My blunt opinion is that the formula is great for flagging up shares that are more risky in that they havent proven to be great roi type companies based on dougs metrics. However the fact they fail the test does not mean they won't be a great investment - albeit we know they wont be right for Doug :)
PS its great to have your presence here as its really useful to know if it passes the Doug2b test or not. Certainly for more novice investors - investing in more proven buisness is probably less risky - albeit we should be always looking forward imho -Somero stats might say "nearly great" investment but if we know the race to build new warehouses and the like will end in 9 months time it could be a poor investment howver good the prior metrics are.
[dupe]
Hargreaves Services (LON:HSP) Interim. Reduce revenue due to exiting Coal business, but increase in profits.
Wentworth Resources (LON:WEN) Production report. Record quarter. Nice 8% divi yield.
wentworth is a small company with predictable revenue. it has a fixed contract with government of Tanzania and would not benefit from increasing gas prices. Single product in single country has risks. The high spread put me off buying.
Try asking your broker. On smaller companies with fairly thin trading, automatic spreads can look big, but I can almost always buy within the spread. Tanzania with the new president is not a basket case and is opening up mining licences again, for instance. Single property yes, but they are printing money now. Even at the uplifted price the forward div of 8%+ on a company at about half its total tangible NAV.
Cenkos says
"Our NAV of the Company’s 2P reserves is 33p per share – a 58% premium to the
current share price. At US$22.8m, Wentworth’s YE21 cash position represents c48% of its market cap – the highest of any producing AIM E&P company. We believe the combination of a sustainable and progressive dividend policy and one of the lowest emissions footprints in the sector makes for a compelling investment case. We maintain our price target at 44p, c2.1x the current share price."
I'll be happy with my 32p price, given the single-asset risk.
Brilliant preamble today Paul.
I got sucked in a little to IPO's on Primary Bid, but only buying after they had come on to the market. However, I have not actually purchased any shares at 'bid' level.
Having kept an eye on a lot of these offerings, I have come to the conclusion that it is far too risky at the moment, because, as you point out, most are significantly overvalued and then the price drops considerably, when they finally come to the market.
I like the idea of compiling a watchlist of shares to buy, when the market dips.
Many thanks.
Ig Design (LON:IGR) absolutely smashed this morning down 54% due to supply chain issues.
Massive drop indeed Ig Design (LON:IGR) I hold and bought at 77p a few years back. So lucky to have sold 80% - some at £2, some at 368 p and then Jan 2020 at 773p. Not normally that lucky!
Great stuff Paul, I agree if what you say regarding the markets. SOM seems like a good company at good valuation. I did it a write-up about the company you may find useful... https://capitalemployed.substa...
oops
Bloomsbury Publishing £BMY - another outperform trading update
Would value your thoughts Paul please
(I hold)
Oakley Capital Investments (LON:OCI) update this morning is a cracker. SP has drifted to 380p, they announced an NAV of 538p, of which near enough £1 per share is cash. So the discount for the actual investments is something like 445 v 287, of around 38%. Further, 76% of the NAV growth was driven by EBITDA expansion: in other words, they buy companies and help grow them. There aren’t many companies that invest directly in European PE, and I struggle to understand why OCI can’t trade at around NAV in due course, as it’s closest comparator Hgcapital Trust (LON:HGT) does. For those in a buying mood and looking for something that has a long runway and a great track record, it is worth a deep dive.
There are many other bargains hidden away in the minority interest Investment Trust sectors including other Private Equity Trusts as can be seen here:-
https://www.theaic.co.uk/aic/f...
I hold Harbourvest Global Private Equity (LON:HVPE) as well as £OCI.
Like OCI, Harbourvest is also trading at a very big 28% discount to NAV. If these were Unit Trusts/Open ended Funds they would be trading at NAV!
Note the performance figures too!
Oakley Capital Investments (LON:OCI) Up 37% 1 yr and 164%. 3yr and 228% over 5 years. HVPE Up 35% 110% and 538%. Yet for some unfathomable reason they are at big discounts to NAV.
Two others on big discounts worth checking out are Icg Enterprise Trust (LON:ICGT) and Standard Life Private Equity Trust (LON:SLPE)
3i is now only on 26% premium!
not sure why HVPE and OCI are on such high discount.
PSH also is on big discount with its investment mainly in US.
jayrannejad
First, apologies for the error in my previous post. The performance figures were over 1, 5 and 10 years.
The main reason Private Equity Trusts Harbourvest Global Private Equity (LON:HVPE) and Oakley Capital Investments (LON:OCI) are on such huge discounts to NAV is that investors don’t like them anywhere near as much as they do, overvalued 3i (LON:III) . Note that both HVPE and OCI shares have done better than 3i except for 10 year performance. The OCI update today was impressive and the share price finished up 10% but it’s still at a very big discount.
Neither do I. I hold Oakley Capital Investments (LON:OCI), Nb Private Equity Partners (LON:NBPE) and Bmo Private Equity Trust (LON:BPET), which span the world and styles between them, and as they say, their NAVs should always be understating the value, as they have to be conservative estimates, which they hope to (and do!) beat handsomely on re-sale.
Hi Donald will we ever see your podcasts with Dave again used to love them back in the day.
Regards Andy
Long-suffering Srt Marine Systems (LON:SRT) shareholders (like me) have finally found a pot of jam at the end of their rainbow.
https://www.investegate.co.uk/...
Apparently, however, there are more and bigger pots at the other end ......
Morning Paul and Jack,
Decent update from Instem (LON:INS)
Revenue growth of 64% organic and from acquisitions and in-line.
The Company continued to generate strong profits and operating cash during the Period,
Outlook
The Company remains well placed to take advantage of a growing pipeline of opportunities generated by new and existing clients. Given the positive market backdrop, the Company's proven platform and continued strong growth trajectory, the Board is confident that the Company will continue to build organically on recent momentum. Whilst, in the near term, the Company is focusing on the integration of recent acquisitions, it continues to evaluate potential acquisition opportunities in existing and closely related adjacent market areas.
Phil Reason, CEO of Instem plc, said:
"We are delighted with the tremendous performance,"
"We exit the Period stronger than ever, with increased scale and strong relationships across all our target client segments."
I hold
Hi Paul,
I doubt you need much encouragement to review the trading update from Somero Enterprises Inc (LON:SOM)
A company that keeps beating its guidance. Can they keep growth going in 2022? I feel they are tempering expectations with the comment:
"the Board expects 2022 will be a highly profitable year with healthy cash generation, modest revenue growth, and EBITDA comparable to 2021"
Even if growth is modest we can still expect significant cash generation and presumably good dividend. Highly desirable in todays market environment.
Looking forward to your thoughts.
Morning Revs8,
Yes, Somero Enterprises Inc (LON:SOM) (I hold) is top of my list to write about today. Section should be up in under an hour.
Regards, Paul.
Thanks Paul for the wise words, helps to steady the nerves!
think many are put off by the USA withholding tax. It’s a hassle
Somero Enterprises Inc (LON:SOM), Not really, the broker should sort it out. If you have it in a SIPP, then no tax is deducted.
Somero Enterprises Inc (LON:SOM)
Rustbucket
Not really, the broker should sort it out If you have it in a SIPP, then no tax is deducted.
To the best of my knowledge not all brokers offer that ability so the broker might say no can do - in which case you would need to change broker.
Note also if W8-ben thing is needed then the individual must complete the form and ensure broker has processed - you cant simply ask the broker to sort with completing the W8-ben thingy if that has not previously been done.
It's not a big issue for me as I buy US stocks anyway. Both my platforms can manage it.
Yes some brokers don't want to deal with it.
W8-ben lasts for 3 years, so you don't need to do a form everytime you buy Somero Enterprises Inc (LON:SOM) shares.
Morning Paul
Another fab early morning preamble as you call it. Find myself nodding in agreement. I too find it much more enjoyable then the individual stock chat although that too has great interest and benefit especially if one owns the stock.
long may you continue and thank you
Agree
Morning Lolarose,
Yes, Jack & I noticed that whenever I publish some general market commentary, there's a big uptick in thumbs ups & lots of positive reader feedback. Plus it starts an often interesting wider discussion, which we like. So we've listened to that, and I'm getting up an hour earlier than usual, to make time to writing a preamble, and I often wake up with ideas in my head that must have somehow gestated whilst I was asleep! Strange how the mind works.
Particularly during turbulent phases in the market, I think people like some calming commentary, reminding us that it's nothing new, and keeping a cool head is essential to good decision-making.
I'm not sure how long I'll be able to sustain getting up before 6am, but it's definitely helped by Dry January, which minimises early morning grogginess! :-)
Also I'm developing a taste for Heineken 0%, it's actually very nice, and the placebo effect (?) makes you feel pleasantly woozy, as my brain thinks - "Oooh! Beer!!" and releases happy chemicals, but with no downside! :-)
Best wishes, Paul.
You're a wizard with the pen/keyboard Paul, lovely reply.
Your commentaries and insights, whether about volatile markets, unreliable Jags or boozers in Bournemouth, are terrific and a great helping in maintaining a sense of perspective in testing times. Thank you.
Morning Paul,
Completely agree with some of the other comments here about the pre-amble. It really is thoroughly enjoyable to read your thoughts on the market over a cuppa in the morning, and it does bring some sanity.
However, there are a few comments about this being more interesting than the individual share chat, which I have to wholeheartedly disagree with. These individual company write ups are what the majority of us use as a base for further research and investing in the companies that comprise our portfolio, rather than understanding how much impact Putin will have on £BMY (hint: it won't).
So please, long may that continue indefinitely, and as Peter Lynch says "the market itself is completely irrelevant" and we shouldn't use that to bail out the performance of our individual companies.
Josh
Big Drop do a lovely set of non alcoholic beers - can highly recommend.
Particularly during turbulent phases in the market, I think people like some calming commentary, reminding us that it's nothing new, and keeping a cool head is essential to good decision-making
Absolutely and thank you.
Hi Paul
Thank you for your kind response. as for getting up early you know what they say
"Early bird catches the worm "
Although with the way the markets are reacting to news both at home, Geopolitically and trading updates on stocks it appears makes it even harder to understand what directions things are going to go, no matter what ever ones experience of market is or what time I wake up.
Thats way your calming morning preamble makes me think twice before I press any buttons.
As others have said, your commentary on market dynamics is superb and very helpful to people like myself . I actually find your market views of more interest than comments on individual companies, although obviously the latter are very useful.
I reiterate that (although the analysis of companies is often very high interest) . With a full time job I don't have time to sit back and reflect on what the markets are doing so your commentary is absolutely invaluable in helping to inform my own decisions.
At these times I also like to remember 2020. I was down -20% at the bottom but it turned out to be one of my best performing years and wish I had bought more when others were panicking!