Small Cap Value Report (Weds 26 May 2021) - RBG, SDI, GYM, DLAR, ZTF, CHRT

Good morning, it's Paul & Roland here with the SCVR for Wednesday.
Timing - as I have visitors, we'll need to be finished here by late morning.
Update at 12:23 - visitors have gone home now, so I have an unexpectedly free afternoon! Hence I'll keep plugging away here until mid-afternoon.
Update at 17:12 - today's report is now finished.
Agenda -
Paul's section:
Revolution Bars (LON:RBG) (I hold) - deeply discounted placing will not please private shareholders.
N Brown (LON:BWNG) - (I hold) - Alliance family increasing stake again - Joshua Alliance RNSs an increase in his stake from 4.61% to 6.21%. I reckon there's a chance of a bid for the company by its controlling shareholders. No section below, this is just a quick note.
Electra Private Equity (LON:ELTA) (I hold) - a quick note to point out a new research note here has been published (yesterday) by Edison. As commissioned research, obviously this will be effectively the company itself talking to us. It's essential reading for all holders of this stock. It demonstrates that there's still strong upside potential once TGIs and Hotter Shoes are separately listed shares, with ELTA shareholders morphing into holders of those two stocks, through an in specie distribution, then what's left of ELTA turning into Hotter Shoes. My only criticism of this research note, is that it doesn't pull the valuation together, to arrive at a conclusion, it just leaves the individual valuations of TGI & Hotter dangling. Still, it's easy enough to work out sum-of-the-parts ourselves. As mentioned before, I'm coming out at 800p+ hence still upside here I reckon, and both TGI & Hotter Shoes are shares that I actually want to hold, as both are good growth companies. Hence ELTA remains, in my view, an attractively cheap back door into forthcoming TGI & Hotter Shoes floats. No section below.
Sdi (LON:SDI) - another positive trading update for FY 04/21. Guidance for FY 04/22 left the same, but upside potential on forecasts looks likely. Valuation seems about right to me.
Gym (LON:GYM) - a surprisingly strong trading update, which has read-across for other sectors such as hospitality, and travel, in my view. This is a smashing business, and expansion has resumed. My only quibble is the high valuation, which seems to already factor in re-opening recovery. Personally I'm not interested in chasing this any higher.
De La Rue (LON:DLAR) - a very impressive turnaround, and FY 03/2021 results out today are strong (a little above most recent guidance). However, the pension scheme planned cash outflows are gigantic, and put me off.
Roland's section:
Zotefoams (LON:ZTF) - This specialist foam manufacturer has upgraded revenue guidance but left profit expectations unchanged. There’s also encouraging news on a new product - but are the shares up with events?
Cohort (LON:CHRT) - a profit warning from this AIM-listed defence group. However, Cohort’s long-term track record is good and lumpy profits are not unknown. This stock remains on my watch list.
Paul's Section
Revolution Bars (LON:RBG)
(I hold)
33p (pre market open - expect a big drop today) - mkt cap £41m
Bombshell news last night on another deeply discounted fundraising by Revolution Bars (LON:RBG) (I hold). I'll be starting today with some comments on this, but have already made my views known that I see this as very damaging to the interests of small shareholders (I got wind of this deal late last week, and have been bracing myself for the flak ever since).
To be fair, they wanted to do a larger Open Offer (like last time), but apparently were prohibited from doing so due to some ridiculous rule that limits open offers to 8m euros per year. Surely a strong candidate to go on the bonfire of unnecessary & indeed harmful regulations? Hence only a £1m Open Offer this time, because £6m was done last time (summer 2020).
Share count is increasing from 125m to 230m - that's awful dilution - RBG had 50m shares in issue before covid, and look at things now, with 230m. All the extra have been issued at 20p.
On the upside, I think the company is probably worth c.30p post re-opening (that would be a market cap of £69m which looks about right). Hence 50% upside from the placing price. But of course that's not much consolation to existing holders, since the share price was 33p yesterday, hence their upside has basically disappeared.
The bottom line is that it's the institutions & HNWs who dictate placing prices, and RBG only has a few institutions on the shareholder register. I would have thought , being on the cusp of full re-opening, and with strong trading just reported, there would be great appetite for a fundraise, but apparently not. 20p was the level which generated enough demand, it seems. As I mentioned yesterday, placings now are a lot tougher, and we need to be very careful investing in anything that needs to raise cash.
Sorry I didn't see this coming, I thought RBG would be able to get through to re-opening without another fundraise, but management has decided that they need to do what's best for the business, and to give them the firepower to do deals in a once-in-a-decade market for new sites, and of course bonanza trading imminently when restrictions lift. Plus they want to refurb a load of sites quickly, for peak trading.
Anyone buying in the market in recent days, paying 34p+ was being ripped off, and buying in a false market. The system really must be changed, it's absolutely outrageous that the share can keep trading at a false price, when a deeply discounted fundraising is underway. People who had been made insiders, knew not to buy in the market (and are not allowed to), giving an unfair advantage. Whereas most people who are not insiders, might decide to buy at say 35p in the market, completely unaware that a 20p placing is underway.
Urgent action is needed, to adopt the Australian system of suspending all shares whenever a placing is underway. We need to lobby for this, so let's get some letters in to our MPs, and to the financial authorities, otherwise nothing will ever change.
I'm really surprised that Peel Hunt & Finncap combined couldn't generate more buyers at a higher price for this placing. After all, we've seen a lot of interest, and high prices for other floats & fundraisings in the hospitality sector, e.g. Various Eateries (LON:VARE) , Restaurant (LON:RTN) placing at 100p, various pubcos like Marston's (LON:MARS) , Nightcap (LON:NGHT) , etc. So I'm flummoxed as to why investors could only be tempted into backing RBG at a deep discount. A city friend tells me that there's "deal fatigue" now, and not as much spare cash sloshing around as there was previously.
Contrast this heavily dilutive, discounted fundraise with the admittedly much smaller fundraise from Sosandar (LON:SOS) which was done at market price, with no discount, and only modest dilution. That was done by N+1 Singer, and achieved an excellent result.
EDIT at 08:06 - price has opened down 35% to 21.0p/22.0p - horrendous for existing holders. Although buying at around the 20p placing price would set up a good trade for the re-opening which is imminent, in my opinion. Hence not a time to panic.
.
.
Sdi (LON:SDI)
176p (down 2%, at 08:37) - mkt cap £174m
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications, is pleased to provide an update on trading for the year ended 30 April 2021.
Another strong update from this impressive little group of companies -
Following the Company's February Trading Update, March and April sales and order intake have been robust across all of our businesses, evidencing a further and welcome return towards normality in our served markets.
Subject to any audit adjustments, we now expect to report Revenue of approximately £35.3m and Adjusted* Profit Before Tax of approximately £7.4m, both of which are higher than those provided in our 10 February 2021 Trading Update.
* before amortisation of acquired intangible assets, reorganisation costs, acquisition costs and share-based payments
Guidance for the new financial year - see below, admirable in its clarity, if only all companies would report like this, it makes life so much easier for investors/commentators -
We have not changed our expectations for our current financial year ending 30 April 2022 compared with the update provided on 10 February 2021 (Sales > £42.0m, Adjusted PBT > £8.7m).
Valuation - many thanks to Finncap for a 1-page update note this morning, very helpful.
It pencils in 6.1p for FY 04/2021, and 7.1p for FY 04/2022, with a hint that there could be upside on the 7.1p forecast for this year.
PERs come out at 28.9 and 24.8 respectively - not exactly a bargain, but if it beats FY 04/22 by 1p for example, then 8.1p turns into a PER of 21.7 - which looks about right to me.
My opinion - an excellent company, that appears to be adept at making decent acquisitions.
Valuation looks fair to me.
Well done to holders. Top-slicing can sometimes be a good idea, as it banks some of the profit, and gives a cash buffer to deploy if the price subsequently sells off, as things can do over the summer. That’s obviously a personal decision for each individual shareholder. Running winners is also a good strategy, so who knows what the future holds?!
The only issue I can think of, is that previous updates mentioned large, one-off orders. So that could be flattering results perhaps? There again, winning large orders is inherently good, and may lead to follow-on orders possibly?
.

.
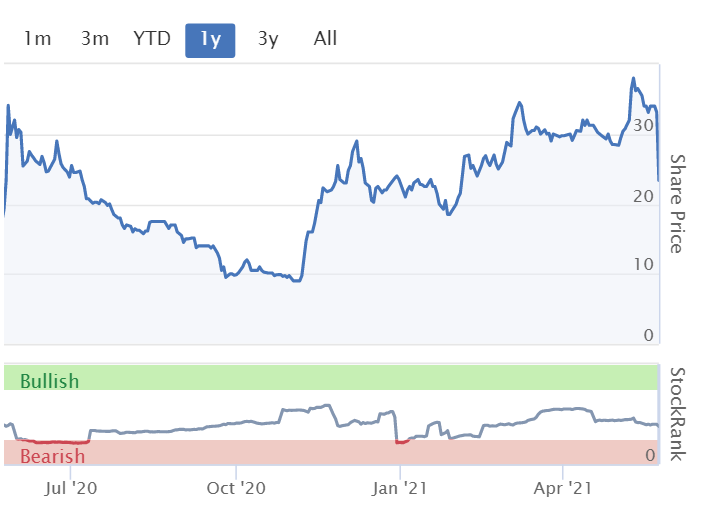
StockRank is good - and it’s classified by the Stockopedia algorithms as: Speculative - Small Cap - High Flyer
.

.
Gym (LON:GYM)
280p (up c.8% at 12:41) - mkt cap £464m
The Gym Group plc ("the Company"), the no-contract, nationwide operator of 187 low-cost gyms, announces a trading update following the re-opening of its gyms after the recent nationwide lockdown.
Outperforming expectations since re-opening
I’m keen to cover re-opening trading updates here, to get a feel for how customers are behaving, as that has wider read-across for many other shares.
12 April - gyms in England re-opened
26 April - Scotland followed suit
3 May - Wales next
17 May - group exercise permitted to restart
Social distancing restrictions still in place.
Key highlights - this is impressive, and seems a lot better than I would have guessed -
Trading since re-opening has outperformed the Company's expectations, reflecting strong demand for the return to gyms; total membership has increased from 547,000 at the end of February 2021 to 729,000 by 24 May 2021 versus 794,000 in December 2019.
All members are now paying, with the free freeze option having been removed upon re-opening.
- Customer satisfaction scores are high
- Average weekly visits per customer is also high, at 1.5 vs 1.1 comparative in 2019 (I wonder how long this honeymoon period will last?)
- Summer months are seasonally quiet, expecting to see that pattern return
- 4 new sites opened recently, all trading “extremely well”
- Opportunities to acquire new sites on affordable rents
- New joiner rates “at record levels”
Net debt - admirable clarity here on stretched creditors -
Net debt at the end of April was £63.1 million, with outstanding deferred rent and VAT of a further £9.4 million, versus a total bank facility of £100.0 million.
At current levels of membership, in May the Company expects to be cash-flow positive pre-expansionary capex and therefore expects to generate cash flow towards its new site rollout…
...Now that all gyms are open and trading, we have commenced discussions with our lending banks to increase our financial flexibility as we look to accelerate our new site opening programme.
My opinion - people of all ages go to gyms, but it’s probably fair to say that the bulk of the customers are 18-50. Therefore I see this bullish update today as strong evidence that younger/fitter/healthier people seem ready to get back to normal. Maybe older people are too, who have been vaccinated?
The market cap is nearly £500m though - for a company that had pre-pandemic (FY 12/2019) revenues of £153m, and only made adj post tax earnings of £10.57m (per results RNS), and adj EPS of 7.7p in 2019.
Also bear in mind dilution - it issued fresh equity in April 2020: 27.4m new shares issued at 150p, and still has a lot of debt on top of that.
Overall, this update is clearly very good, but I do question whether the price might be getting ahead of reality? It’s a roll-out, so some investors might be happy to over-pay, given that new sites should hit the ground running in terms of profitability and what the members do!
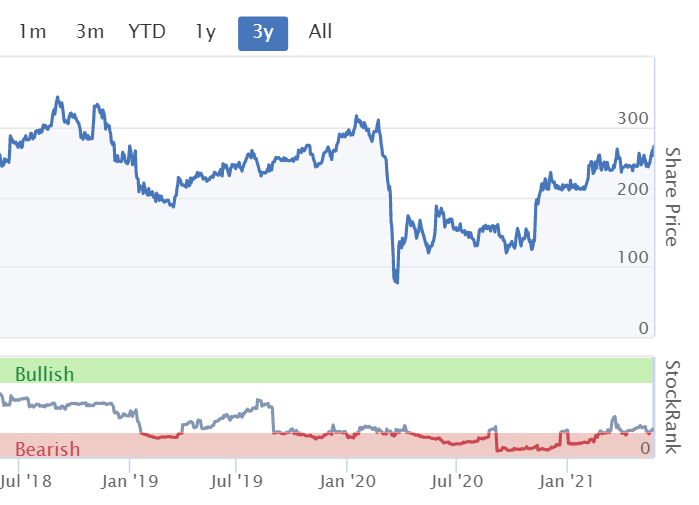
Overall, I think the price already reflects re-opening & recovery in earnings. Therefore, I struggle to see much upside. It could easily run to an over-valuation though, so who knows what the share price will do? The chart certainly looks well set up for continuing strong momentum, so maybe it's a good shares for momentum traders? Whereas I tend to view shares through a value/GARP (growth at reasonable price) prism, hence generally value things lower than some other investor/traders might do. It takes all sorts to make a market! Please remember we're not short term traders here at the SCVR, so we have no idea what Mr Market will do in the short term. We're looking at the fundamentals, and the longer-term. Lots of shares run to excessive valuations in a bull market.
.
.
De La Rue (LON:DLAR)
194p (down c.3% at 15:25) - mkt cap £380m
De La Rue plc (LSE: DLAR) ("De La Rue", the "Group" or the "Company") announces its full year results for the year ended 27 March 2021 (the "period", "FY" or "full year"). The comparative period was the twelve months ended 28 March 2020.
I’ve reported on De La Rue (LON:DLAR) several times this year, so for background reading here are my notes from 29 Jan 2021 (ahead of expectations trading update, and a slightly ahead of expectations update here on 11 April 2021. Those reports also cover the elephant in the room - £15m p.a. cash outflows into the pension scheme deficit (growing to £24.5m pa).
It’s a very impressive turnaround, which has been reflected in a big recovery in share price. Taking into account the pension deficit, I thought the price looked about right.
Moving on to today’s results, it looks in line with expectations, with adjusted operating profit of £38.1m (up an impressive 60.8% on last year) - versus most recent guidance of c.£37m, so actually that’s a beat of about 3%, pretty good so far.
This result is all the more impressive because revenues were down 10.2% to £388.1m. A combination of higher gross margin, and deep cost-cutting in overheads, drove the increase in profitability.
A further £7m of cost savings are in the pipeline for FY 03/2022.
Adj EPS is up 32.4% to 14.7p (a PER of 13.2 - cheap due to the big pension deficit cash outflows of £15m pa, remember)
Net debt down 49% to £52.3m, again that’s in the right ballpark compared with guidance of c.£53m.
Outlook - April & May 2021 said to be in line with management expectations.
The rest of the outlook section is a bit too vague for me -
We have a target of returning the Company to a strong financial position and an operating platform which will deliver sustainable growth at high operating margins and strong cash generation in the medium term. Following an initial period of cash outflow to fund the Turnaround Plan, we continue to aim for the Group to be generating cash flow capable of supporting sustainable cash dividends to shareholders by the end of the Turnaround Plan in FY 2022/23.
Pension Deficit - the accounting entries are best ignored, because they’re total nonsense & dramatically understate the real world deficit and huge recovery payments agreed.
All that matters is the cash outflows, read this and let it sink in -
On 31 May 2020, the Trustee and the Company agreed the terms for a schedule of contributions and a recovery plan, setting out a programme for clearing the UK Pension Scheme deficit (the "Recovery Plan"). The last actuarial valuation of the UK Pension Scheme was at 31 December 2019, which was based on intentionally prudent assumptions, revealed a funding shortfall (technical provisions minus the value of the assets) of £142.6m. The Recovery Plan makes an allowance for post-valuation market conditions up to 30 April 2020 (at which point there is an estimated funding shortfall of £190m), including the impact of COVID-19 on financial markets to that date.
The £190m deficit is addressed by payments of £15m per annum (payable quarterly in arrears) under the Recovery Plan payable from 1 April 2020 until 31 March 2023 and then payments of £24.5m per annum (payable quarterly in arrears) from 1 April 2023 until 31 March 2029 (whereas under the recovery plan agreed with the trustee in 2016 ("2015 Recovery Plan"), the payments would have been £22.2 million between 1 April 2020 and 31 March 2021, £23.1 million between 1 April 2021 and 31 March 2022 and £23 million per annum thereafter until 31 March 2028). Additional contingent contributions in exceptional circumstances will become payable by way of an acceleration of the contributions due in later years where: (i) the leverage ratio (consolidated net debt: EBITDA) is equal to or greater than 2.5x in either FY 2021/2 or FY2022/23, up to a maximum of £4m in each financial year and £8m in total and/or (ii) the Company or any its subsidiaries take any action which will cause material detriment (defined in section 38 Pensions Act 2004) to the UK Pension Scheme, of £23.3m (£7.2m in FY 2020/21, £8.1m in FY 2021/22 and £8m in FY 2022/23) over the period up to 31 March 2023.
These are massive planned cash outflows. It’s possible that something might change in future, which could trigger those payments to fall. Since the actuarial valuation is based on April 2020 figures, when equity markets were below current levels, then the next valuation might show a lower deficit. This is so highly material, that properly researching the pension scheme is just as important as analysing the company's prospects.
For me, there’s not really much point in doing more research on the company’s prospects & turnaround, given the sheer scale of the pension scheme cash outflows planned.
Balance sheet - looks OK. Although if we were to replace the absurd £20.5m accounting deficit shown on the balance sheet with what it actually is, £190m actuarial deficit, then NAV would become negative.
My opinion - I recognise this is a very impressive turnaround. However, for me, the cash outflows into the pension scheme are so enormous, that it’s difficult to see much upside in the equity.
DLAR shares might become more appealing if something happened which greatly reduced the cash outflows into the pension scheme. Or, if profitability rose greatly, thus diluting the impact of the pension scheme.
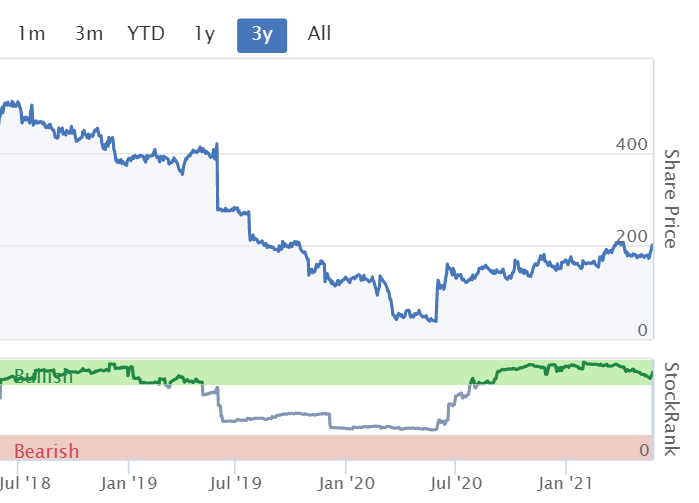
Dilution - pre covid it had about 112m shares in issue. It's now 195.1m, so you need to take that into account when looking at the chart, and valuing this share.
As things stand now though, it doesn’t stack up as an investment for me. Good luck to holders.
.
.
Roland’s section
Zotefoams (LON:ZTF)
405p (pre-open) - market cap £196m
Specialist foam producer Zotefoams has issued a trading update this morning, reporting record monthly revenues and guiding for revenue to be “significantly ahead of market expectations for the full year”. Profit expectations remain unchanged, due to planned capex and cost inflation, but this still looks like a strong update to me.
Zotefoams has been a popular small cap in recent years, but the share price chart suggests growth hasn’t always lived up to expectations:

Does today’s news signal new momentum? Let’s take a look.
Trading
Due to the impact of the pandemic, I feel that comparing performance for the first four months of 2021 with the equivalent period in 2020 is not always very meaningful. So I’ve got into the habit of looking back at 2019 as well.
Happily, Zotefoams’ management has done this work for us today, presenting comparative figures for the last two years.
Revenue for the first four months of 2021 is said to be 60% ahead of the same period in 2020 and c.14% ahead of 2019. Zotefoams generated record monthly revenues in March and April.
Two of the company’s three divisions are reporting strong growth:
High-Performance Products (36% of revenue in 2020): Sales are up by 133% vs 2020 (up 61% vs 2019)
Strong demand for footwear has offset weaker aviation demand.
Polyolefin Foams (62% of revenue in 2020): Sales are up by 32% vs 2020, but down 7% vs 2019.
A good recovery in most markets except aviation. Lower sales in January due to Brexit uncertainty are blamed for the fall vs 2019.
MuCell Extrusion (c.2% of revenue in 2020):Sales up 36% vs 2020 and up 76% vs 2019.
A strong start with good momentum on licence fees, but this division appears to be a startup, making minimal contribution to revenue.
MuCell’s focus is now on a new product, ReZorce packaging. This appears to be a new material for beverage cartons - the photos on Zotefoams’ website look like the ‘Tetra Pak’ type cartons used for products such as fruit juice and UHT milk. However, Zotefoams says that ReZorce solves the recycling problems associated with these laminated products.
The company says that ReZorce could be a circular economy product, whereby used packaging is fully recycled and used to make new packaging. I know this goal is being targeted by a number of larger packaging companies at the moment.
According to today’s update, independent analysis has demonstrated ReZorce’s recyclability and low-carbon footprint. MuCell has now identified commercial partners and is carrying out “market positioning and engagement with potential customers”. A pilot production line is being built.
I’ve not looked into this in any detail, but the best-case scenario appears to be that ReZorce could replace Tetra Pak packaging in some markets. I’d guess that might be a significant growth opportunity, albeit at a very early stage. I’m not sure what other competitors might exist, either.
Outlook
Management are confident in the outlook for the year, despite continuing currency headwinds and Covid-19 impacts. The order book was said to be strong at the end of April, although comparatives for the remainder of the year are tougher.
While it is still early in the year and we are mindful of the volatile macroeconomic environment, we anticipate Group revenue to be significantly ahead of market expectations for the full year, which will offset the short-term inflationary impacts on margins, the weaker US dollar and our planned increase in product and commercial development costs. Consequently, we are comfortable with current market expectations for growth in profit and reduction in leverage for the year and remain confident about the long-term prospects of the business."
My view
Today’s update looks promising to me. However, I think it’s worth taking a quick look back at the 2019/20 figures for a sanity check.
Zotefoams’ 2020 figures were refreshingly free of adjustments and showed only one measure of earnings, which came in at 14.6p per share (diluted).
If this is the correct EPS measure to use, then growth expectations this year (as referred to in today’s outlook) appear to be fairly minimal:

Based on today’s upgrade to revenue expectations, it looks like we can expect Zotefoams’ profit margin to fall this year. Profit margins have been fairly consistent in recent years, but returns on capital have fallen since 2019:

I’d have to do more research to understand the moving parts here, but I assume that the falling ROCE is due to growth capex that has yet to deliver returns. This may pay off over time.
However, as Jack commented in January, cash generation has been consistently poor. Leverage also remains quite high. Net debt was 2.1x EBITDA at the 2020 year end.

Summary: Zotefoams is not a company I’ve followed in detail, but it does seem to be an interesting business with growth potential.
However, earnings are expected to be broadly flat this year and leverage is still relatively high, in my view.
After today’s gains, the stock is trading on 29 times 2021 forecast earnings. That seems high enough to me. Stockopedia’s algorithms are also struggling to find much value:

Zotefoams’ strong rating appears to rely on a much stronger growth performance in 2022. At this stage, it’s not clear to me how likely this is.
On balance, I’d say the share price is up with events at current levels.
.
Cohort (LON:CHRT)
592p (-11.6%) - market cap £243m
This AIM-listed group of six defence companies has issued a subtle profit warning and is one of today’s biggest fallers. I’ve started to follow this business over the last year and have had a favourable impression of it so far.

I don’t own Cohort shares, but they are on my watch list, so I’m keen to understand what’s upset investors today.
Today’s trading update covered the financial year ended 30 April and includes an outlook statement for the current year. It’s this part which has disappointed the market, I think.
- FY21 update: performance in line with expectations for the year
- FY22 outlook: Order delays mean that the revenue mix will change. Although revenue expectations are unchanged, profit growth is now expected to be lower than previously thought.
Some businesses are prone to lumpy order flow. In my experience this can sometimes present buying opportunities for long-term holders. I think this might be the case here.
FY21 trading
Let’s skim over the FY21 numbers. Trading is said to be in line with expectations. I’ve not been able to find a recent broker forecast for this year, so I’ve extrapolated the numbers below from Cohort’s FY20 results and the consensus forecasts shown in Stockopedia:
- FY21 revenue +8% to £141m
- FY21 Adjusted earnings -10% to 33.5p per share
The supporting year-end metrics provided in today’s update look more positive:
- Year-end net cash of £2m (FY20 net debt £4.7m)
- Record order intake of £210m (FY20 £124.4m)
- Closing order book of £240m (FY20 £183.3m)
- The closing order book underpins 60% of FY22 revenue forecasts, in line with historical performance.
FY22 outlook
Despite the increased closing order book, some expected orders with Cohort’s EID subsidiary have been delayed and are now expected to be secured in “2022 and 2023”.
EID is a Portuguese company that makes communications systems. Cohort acquired a controlling stake in 2016.
These delays are expected to result in lower margins and reduced profit growth during the year to 30 April 2022:
While the overall performance of the Group's other businesses means the Group's revenue expectations are unchanged, leading to good revenue growth, the mix of revenues is expected to see a reduction in the Group's overall margin and accordingly a lower rate of profit growth.
Management have not provided any numerical guidance with today’s update, so we’re left guessing about the potential impact of this shortfall.
Assuming that Cohort’s earnings will be 10% lower than expected this year, this leaves the stock trading on around 20 times earnings, with a forecast dividend yield of c.1.8%.
EID problems
I’ve had a look back at Cohort’s results for 2019 and 2020. Both sets of results suggest that EID has been underperforming for a while:
- 2019: “weaker performance at EID” caused by “lower naval activity and slippage of deliveries on a major contract in its Tactical division”.
- 2020: “EID had a stronger year” but COVID-19 caused “delays to orders and deliveries, particularly at EID and SEA”
To put these comments in context, EID generated 17% of group operating profit in 2020, roughly one-sixth of the total. So it’s a material business to Cohort.
Cohort’s business model is built around giving its operating subsidiaries a high degree of autonomy, supported by financial infrastructure and strategic guidance.
I’d imagine Cohort’s board is taking an active interest in the problems at EID, but this isn’t a fully-owned subsidiary - Cohort only owns a majority stake. So the group’s ability to make changes may be limited.
Today’s guidance that the delayed orders “are now expected to be secured in 2022 and 2023” seems fairly broad. My impression is that the cause of these delays may not be resolved that quickly.
My view
As I mentioned, I’ve had a favourable impression of Cohort until today. Has that changed? Not necessarily.
Today’s news is disappointing and Cohort’s acquisitive growth strategy will always carry some risks. But I think the company’s track record to date is good and supports confidence in the firm’s management:

Looking further back, the 10-year stats (available here on Stockopedia) tells us that revenue has doubled since 2011, while net income has risen by 250%.
Cash flow has always been strong too, albeit a little lumpy.

Cohort’s dividend has risen every year since its flotation in 2006:

The balance sheet looks consistently strong and there has been no dilution. I think the firm’s performance has created genuine value for shareholders:

This successful performance may partly be explained by the concentrated shareholder structure with insider ownership.
Fund manager Liontrust is the biggest holder, with over 30%. Cohort’s founder Stanley Carter owns 22% of the stock and remains on the board as a non-executive director:

I try not to invest in companies immediately after a profit warning, because the research shows that the situation often gets worse before it improves.
However, I’m still interested in Cohort and will be watching the firm’s progress closely. Although I think the share price is up with events, I’m impressed by this group’s steady progress over many years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

158 comments
You need to do more work on Zotefoams ReZorce is patent protected and 250 billion Tetra Pak type cartons is a big target market
Revolution Bars (LON:RBG) - don't hold.
Surely at some point in time in the very recent past the prospective book-builders would have reported to the BoD that if they want to go ahead with the placing it would be at a massive discount. So, if I had been a shareholder, I would lay the blame squarely at the door of the BoD. This as a terrible example of the PI being sh*fted as we used to say in the building trade.
Regarding Spire Healthcare (LON:SPI) being reported this evening that ‘Shareholders are angry’ (this one isn’t!) and will try and push the offer up closer to 400p as there is £1Bn of property is assets alone.
No idea how likely this is but may explain some price movement above 240p?
What stock are you referring to? What conversation thread is this part of? Some kind of a clue would be appreciated.
[EDIT] With apologies, I somehow managed to read your message without seeing the reference to Spire Healthcare (LON:SPI). Take it all back. My need for a new pair of reading glasses is a poor and inadequate excuse.
No, was my error, I tried to reply to the spire conversation and hence didn't tag it. When I realised i'd posted rather than replied I added the tag. You're not going mad!
Re: £SDI not sure if one can read anything into this announcement today:
"SDI Group plc announces that it received notification on 26 May 2021, that on that same day Ken Ford, Chairman of the Company, sold 500,000 ordinary shares* of 1 pence each in the Company ("Ordinary Shares"), at a price of 183.15 pence per Ordinary Share.
Following this sale, Ken Ford has a beneficial interest in 750,000 Ordinary Shares representing 0.76% of the Company's issued share capital.
* 250,000 shares sold by Mintonview Ltd, being an investment company wholly owned by Ken Ford and his wife, and 250,000 shares sold from his SIPP"
Revolution Bars (LON:RBG)
I hold and had a couple of quite in depth email exchanges with Rob Pitcher (CEO) overnight, where I made my feelings quite clear but in a measured manner.
I give Rob kudos for taking some time to discuss and provide his rational over the situation. I won't re-post here as I don't think that's the correct thing to do, but the fact that he was prepared to spend time on an existing shareholder at least assuages my concerns that management did/do not feel accountable.
Whilst I understand the reason for the company to raise I am mainly annoyed at the steep discount coupled with the lack of ability to participate as an existing shareholder. The bigger problem here, as Paul has pointed out and Rob inferred too, is the system. It is designed to transfer money from smaller shareholders to bigger ones and to some extent the company gets straightjacketed. Thus if you want to raise a relatively large amount of money the rules act against you, both as a company and an existing shareholder.
I would back a system where the share gets suspended and an ABB is then conducted by the brokers with existing shareholders given preference. This would be easy to administer and wouldn't prevent house brokers getting expressions of interest in advance like they do now. In all likelihood I'd wager that in that system the raise would have been done at a higher price with less dilution , which would have benefited the company and the existing shareholders.
Instead a company is faced with the risk of producing a prospectus (which under current rules can take a long time) and potentially not get fully backed. ie they can't take into account current market conditions in the raise. In this case pre-empting a waning market appetite, or getting in first. This creates further negative downward pressure on the price. and could mean a raise doesn't get completed or at even worse terms. The existing alternative open to the company, and as people have said here, creates a market where some have privileged information, creates a false market and leaves the company more open to hostage on terms. For us shareholders it acts as a mechanism to transfer our wealth to institutions or HNW flippers. Generally doesn't work well for the company or its shareholders but does line the pockets of the system! Needs to change in my view.
Strange old week for £CRL
Share price has been hammered down based on seemingly no news and today recovers by 9% again based on no news.
Anyone able to shed any light on this?
MS.
Anyone tracked the MoU RNS from CyanConnode this morning? CC maybe rather on the small side and not sure it’s Paul’s cup-of-tea as a company style, but it’s not every day that a £15m MC U.K. company signs an MoU with the National infrastructure (Smart Meter) JV company of a 1.4billion population country (India).
Acorns and Oaks Trees anyone......
OT - On my shortlist so didn't buy @ 56 to 60p...
Morses Club (LON:MCL) 67p
Its having a good run!
I’m probably setting myself up for a slating, but I think we’re perhaps being a (tiny) bit unfair on the Revolution Bars (LON:RBG) management here. Pitcher has been calling it as he sees it, and if he’s optimistic about the prospects for the business recovery would you expect any CEO to be anything other than a cheer leader for their business?
From the analysis posted by others on the company’s financials it seems clear that finances were tight as the business was effectively shutdown by the repeated COVID lockdowns and was pretty heavily geared. There was little room for error over the reopening timetable and in the event it was too tight and they’ve gone for a significant fundraise. A 10% placing at a slight discount à la Sosander (say raising £3.5m net after fees) doesn’t look as though it would’ve addressed the issue so having figured out how much cash they need (£20m) they then need their brokers to tell them how many shares to issue. As in any market, you don’t get the highest individual price from every potential buyer you get the(lowest) market clearing price of the £20 millionth pound being requested. Pitcher may be many things but he’s not clairvoyant and I don’t think anyone would have known the market clearing price for 40%/105 million new shares before this sounding was taken. I would be surprised if this fundraising has been on the agenda for more than a couple of weeks so I don’t think Pitcher’s bullish noises when the trading update was given a while back about the future of the business are necessarily inconsistent with the harsh reality that to raise another £20m from more sceptical institutional investors it had to be priced at such a steep discount.
Maybe the whole thing could have been handled better with small shareholders being given a fairer crack of the whip in the offering (especially as the new prospectus excuse for the tiny open offer seems pretty lame) but without being in full possession of all the facts I’m not sure I’m in a position to condemn the company and their advisers so vehemently out of hand. I agree with others that the system for fundraising in the U.K. sucks and that shares should be suspended as and when a significant placement is being executed and pre-emption rights should be better respected but that’s a much bigger issue than this particular fundraise.
Gus.
Despite seeing my modest gains transform instantly into my largest loss position this morning, I actually agree with Gus. Revolution Bars (LON:RBG) (I still hold) have a proven formula for rapidly turning new sites into profit, and the poorly performing sites have disappeared. Unlike Loopup (LON:LOOP) (now sold) which was the worst shock thus far in my short investing career, I think/hope RGB is not irredeemable, as long as the target audience doesn’t desert them. However it will take time and cash which they now have. I agree the process is biased against PIs, but as has been said this is a wider issue amongst many others.
Hi Gus,
Well done for posting something thoughtful, and a bit contrarian, making good points about the Revolution Bars (LON:RBG) placing & OO. We welcome all views here at the SCVR.
I spoke to someone who participated in the placing today, who said that he;
So he feels that the deal overall was a lot fairer than it looks.
The key with discounted placings, is to stand your corner, and participate (providing the company is a good one, of course). If you sit back, and let yourself get diluted, then it's handing some of the upside to someone else.
That said, my criticism of the system are intact, it's awful, and we need to press hard for reform. However, RBG and Finncap worked within the system, and are at pains to explain that they tried very hard to raise money at the best price possible. Unfortunately, there wasn't market appetite at a higher price. 20p was the level where there was meaningful demand.
We all knew that the bank position was tight, and in hindsight, I was definitely too blase about the risk of further dilution, so lesson learned hopefully. I'm going to review all my other holdings, and look carefully about the risk of dilution at an adverse price, and maybe cut back.
All this reinforces my existing very strong emphasis about balance sheet strength. Breaking my own rules has been shown the importance of those rules. There again, people who completely ignored the solvency/dilution risk on say Carclo (LON:CAR) have ended up with a 10-bagger, so you never know really!
Regards, Paul.
Re Revolution Bars (LON:RBG) and other pub groups. I have been to a few local pubs since they were allowed to open up again and have seen little evidence of the talked about 'pent-up demand'. I am currently in quite a large pub in Paddington and am one of only two customers indoors. A few tables of senior citizens sitting outside on a chilly day but that's it deapite reduced competition due to many of the other pubs around here still being closed.
"I have been to a few local pubs since they were allowed to open up again"
I totally agree with you here - i think the limited outside space meant those that were open "outside only" had a bit of a monopoly that is now gone.
My "busy local" during outside opening only is now much quieter and i can see the same crowd are dispersed between the available different indoor locations that were not available.
Note generally most pubs in my area werent ever continuallly full anyway so it does seem to be reverting to the norm with a couple of the "new" or "currently popular" outlets doing well the rest are back to very much tickover already at best. Hopefully tickover is enough to at least keep the lights on for now. Perhaps ref london pubs we should expect lfl's to be much worse than for the rest of the country? due to the obvious lack of tourists and bods still working from home?
I would expect pubs in places like the lake district and other uk holiday type desinations may be the winners at present.
Perhaps england or scotland will win the euros and ensure there is a bumper drinking binge over the next 6 weeks or so.
Pent-up demand is more relevant to nightclubs I think, and younger people.
"Sylvania Platinum (LON:SLP) is a large (9.6% of pf) for me with average price of 59.95p and I am tempted to take a bit off the table say 20% of the holding but I am not sure where I would put the proceeds and my sell timings always seem to be cr@p."
Sylvania Platinum (LON:SLP)
10% of mine @120.92p, currently +2% (negative last night).
It was the best option on my shortlist of 6 and so I'm new in.
I also have 7% of my portfolio in Centamin (LON:CEY) which has moved +14%.
MichaelFB, if your average price is 50p, you could get a cracking return and yields when it hits the promised land of 200p.
Paul, could you take a look at AUCTION TECHNOLOGY GROUP PLC who came out with their interims today? I am a shareholder and believe they have a very exciting future being the dominant company taking auctions from offline to online.
Hi Chris,
I started to look at recent float Auction Technology (LON:ATG) at your suggestion, but I'm too tired to spend several hours ploughing through it, as it's new to me. Also the market cap is just over £1bn now, so doesn't fit our sub-£500m-ish remit here.
Sorry about that. By all means post some bullet points about why you think it's good, and I'll try to give it the once-over when time & motivation permit.
It was a very busy day for other things, so sorry I didn't get round to this.
Regards, Paul.
Revolution Bars (LON:RBG) - Its now uninvestable to me. Good luck to fellow investors and I hope you make your winnings.
Sylvania Platinum (LON:SLP) - I am not worrying. Studying the 6 month chart, for the last 3 months, 120p looks like the mid-line support level. Lower it will rebound back to 120p, higher on froth tests it, until some better fundamentals occur.
Trust in Stockopedia. SLP SR = 99 and RBG SR = 37 for a reason.
Sylvania Platinum (LON:SLP) +7.58% today... so what the market taketh yesterday, it returneth today... Don't sell.
Totally agree with the comments re RBG, and any other company that is more or less trading on a false basis, with such a heavily discounted price being offered.
I got my fingers burned badly with SXX doing a similar thing, fund raising at a heavy discount prior to burning small share holders, although I had a lot of them, as I was convinced the project would go ahead, as it has, and did not allow for a change of owner in my calculations.
It is a shame RBG did not accept the offer of 220p, was it?
"It is a shame RBG did not accept the offer of 220p, was it?"
Shame, it seems completely daft now.
Hi kbkb,
It is a shame RBG did not accept the offer of 220p, was it?
Stonegate bid 203p cash for Revolution Bars (LON:RBG) here on Aug 2017. It was an agreed bid, i.e. the former management of RBG agreed the deal.
What happened next was quite bizarre. A competitor, called Deltic (which recently went bust) gate-crashed the party, and tried to put forward a deal to merge with RBG. I think they undermined the Stonegate deal, which obviously in hindsight, was a good deal!
As a result, RBG major shareholders decided (again, bizarrely), to reject the Stonegate bid, and Stonegate decided to walk away rather than raising its offer. It was all downhill after that. The former CEO, Mark McQuater walked away, trading deteriorated, and then more recently of course the company was clobbered by covid - a great pity, as the new CEO Rob Pitcher was making tangible progress (LFL sales beginning to turn positive, and refurbs generating strong returns) with his turnaround strategy, and they were even sounding out shareholders about dividend policy.
Nobody could have possibly predicted any of this, so personally I don't beat myself up over it. We live & learn!
Regards, Paul.
Re Equals (LON:EQLS) does this happen often from brokers and should one read anything into it, or quite the reverse - just take it at face value as a Cenkos decision?
Equals Group Plc. Termination of coverage. Cenkos Securities plc has terminated coverage of Equals Group plc. Our previous recommendation (BUY) and forecasts can no longer be relied upon. Please contact Cenkos of further information.
Interesting delayed price rise from Gattaca (LON:GATC) today. Over the last few weeks it's been range bound at 149 to 151p. From what I can see on Stockopedia it appears HRnetGroup Ltd selling down its holding whilst MMGG Acquisition Ltd increasing it's stake to over 20%. Possibly resulting in the very tight price for 6 weeks.
Paul commented that there was little reaction to the good news in the recent trading update a couple of days ago but to me it looked like the buyers were supplied by a significant seller. (high volume). Since then the price has risen and today quite significantly. All the metrics on Stockopedia make Gattaca (LON:GATC) good value even after tripling of the share price since the low and now the price appears free to move again.
Building projects hit by lack of supplies and price rises
Re Cohort (LON:CHRT) , I used to hold but sold in 2018. I have met the management, and they are quite impressive. A key strength in my views, is that they are well regarded by our armed forces, and the MoD. Having said that, the defence supply sector is a minefield (joke intended), and I have avoided since. Apart from Mti Wireless Edge (LON:MWE) - which pretends it's not a defence sub-contractor.
Revolution Bars (LON:RBG)
https://www.stockopedia.com/learn/stockranks-&-ratings/the-quality-rank-463098/
Just skim reading the Q metric... Q would not pick up this rotten Management behaviour.
Idea for Stockopedia:-
A Count of the Dilutions / Issues / Offerings etc per company
A History of the Dilutions / Issues / Offerings etc per company
Anyone friends with The Stocko team who want to sponsor this idea... (but then it would only be on the new site... rabbit hole)?
Thank you Paul for your reassuring account of Sdi (LON:SDI) which I hold and wonder if you would take a look at Phsc (LON:PHSC) and its director activities, I also hold this. Then about your concerns for shareholders of Revolution Bars (LON:RBG) which I don't hold but have forwarded the most important part of your note to my member of parliament, Michelle Donelan MP.
Silver Moon
Suggested letter to MPs
Google your post code and parliament to get the name of your MP
Make this letter in your own way. Nothing is so deadening than dozens of the identical letter turning up!
Dear Bloggins:
i have just been ripped off by buying shares in Revolution Bars at 35p when unknown to me - and other smaller shareholders - there was a placing underway at 20p.
The issue here is that of course the insiders knew there was a placing and they knew not to buy shares in the market until the placing was complete: small shareholders like me did not know about the placing and we bought in what vas demonstrably a false market.
This is a manifest disgrace and easily reformed by adopting the Australian system that demands that when there is to be a placing the stock has to be suspended until after the event.
Please can you, as my MP, campaign for this reform for until it in place no small shareholders can safely buy shares in any company unless he or she is faced with a deeply discounted rights issue.
RGB - Revolution Bars .....Pardon my ignorance, are existing shareholders offered any shares at the open offer price (what I presume used to be callede a 'rights issue'). Thanks
Whilst I share the anguish and anger about Revolution Bars with my colleagues on Stocko here, there is other suffering out there too. Many of you may remember that Lord Lee has been trying to get the authorities to oblige companies in serious talks about potential takeovers to make that information known to the markets. I dont think he has been successful, well not yet anyway. PS does anyone know how best to get hold of him with additional information? I am trying through ShareSoc and that may be the best route.
Anyway, the culprit this morning is Vectura (LON:VEC) with an offer out of the blue, at least from my point of view, from Murano Bidco. Yes, another of those. Whilst current holders may be delighted with the 30%+ rise in the share price this morning, I am not. After carefully reviewing where the company seemed to be going and with few hopes of action on either the M&A front (by them!) or much organic growth from the apparently sleep management (not so sleepy apparently), I sold to invest more profitably elsewhere.
Clearly they were active on opening the books to a serious potential bidder and it all looks done and dusted for the AGM in the next few days, perhaps tomorrow. Naturally I think this is scandalous behaviour and I am a big gain loser (, if you get my drift) to the tune of several £000. I feel aggrieved. Thoughts anyone? Anyone else in the same position, or has been recently with different companies?
I wonder if anyone with knowledge and an eloquent way of writing could maybe put a template email to send to MPs? As someone newish to investing I am finding the placing aspect of shares quite frustrating and has put me off investing more of my money.
"I wonder if anyone with knowledge and an eloquent way of writing could maybe put a template email to send to MPs? "
Conservative party members most certainly do care and have the IQ to formulate intelligent economic policies... but The ConSocialist (Globalist) "Conservative" Government is not going to care about shareholders, contractors, small business owners. (These Turkeys shutdown a working economy over a cold-flu, attacked indigenous small business, continue the IR35 war on self-employment, are going to raise Corporation Taxes (from £50K upwards), and may well sign up to Biden's global Corporation Tax handicap).
Labour - the party of the Islington "worker"... good luck dealing with Dodds, McDonnell, Len McClusky, Rayner... they actually think business and capitalists are Satan.
Maybe try wrapping up the issue in some historic crimes, identity, PC, social media politics?
We Shareholders need to be the Regulators and Governors of our Companies.
with knowledge and an eloquent way of writing could maybe put a template email to send to MPs?
Seem like we are missing the knowledge and eloquent request in the post.
BSV
BSV do you need a hug? All you seem to do is add a nasty barb reply to various posts without actually offering any help. Just scroll on, your input is not required.
Are hugs legal yet?
It just an opinion.
I find scrolling on really works.
BSV
Not really sure what I've done to annoy you there BSV. Enjoy your day.
Apologies Carvalio,
For any misunderstanding, I was implying 8888 posts lacked knowledge and eloquent.
BSV
No problem, thanks for posting.
Hello 8888, Cant cope with the rest of your pen name.
One unfortunate thing that affects us all as investors is that company management do quite often get away with financial murder and do not appear to suffer the consequences. How many small embezzlers have a criminal record for really minor crime? Lots I guess. Easily tracked down and pinned on them. How many senior management have a criminal record? The current case of the cladding scandal is unbelievable. Some builders eg Persimmon are finally putting money aside to support any scheme in extremis. I would guess that none of it will be touched in 10 years time. Government should bring the culprits to justice now; and should put a temporary tax on the house building industry to build a fund to fix it NOW.
We have had many financial scandals over the years. It should not be outwith the ability of government to fix this within a short, fixed period. If we investors have to foot the bill indirectly, then so be it. We have made enough from builders in the last 30 years or virtually any period you care to name - and continue to do so with the almost daily rises in company profit forecasts coming out from builders, and the base levels were pretty good already.
Afternoon rid###es,
(UK_Investor does what it says... invests... in the UK... in shares... nothing else).
That's not what Governments do, have the ability to do, or have the track record to do or achieve.
Its also a can of worms that few politicians nor civil servants will particularly want to open.
There is a counter-doctrine that Government will invariably mess up everything it wraps its tentacles around, and unintentionally make things worse.
Re, The Builders, post WWII policy, plus population increase, plus "inflation", (and mediocre "social" housing), and a finite island (planet) size, was always going to benefit private property ownership.
Is it a problem? Even the Marxists all want to own nice houses. McDonnell owns at least two.
Keep investing, making wealth for yourself and loved ones. That's the only way the little guy can win.
Agree totally look at the likes of CAKE and NMC the bar stewards faced nothing, they should be stripped of all their family wealth as no doubt many have homes and other dodgy finances tucked away in others or company names + stick them on the TV, take them through the courts and parade them for what they are - Greedy thieving people
It has taken 3 years but I have just been contacted by my broker to inform me that the SFO is investigating Patisserie Holdings (LON:CAKE) . They provided a link to the "Operation Venom" questionnaire to enable me to register my loss. The SFO is encouraging all affected shareholders to complete the questionnaire, to assist in its investigation.
Link to questionnaire
typical of SFO
Wait three years to do exactly what they should have done the day after the fraud was announced.
typical of SFO
Wait three years to do exactly what they should have done the day after the fraud was announced.
My thought exactly!
However, now that they have started we should provide them with all the assistance we can to bring these criminals to justice. I would encourage anybody who held the shares at the time of the suspension when the fraud was revealed to complete the questionnaire.
Sylvania Platinum (LON:SLP) Down 7.65% yesterday, up 6.39% as I type, on fairly high volume.
Games... Bots...
Hi
Following up on yesterday's discussion.
I still hold Sylvania Platinum (LON:SLP) and Tharisa (LON:THS) this morning, note to give oneself a pat on the back for not panicking and selling!
Though I did exit Ferrexpo (LON:FXPO) today (I booked a small profit, it is down 20% from peak and intend to buy back later probably).
It is worth noting that Tharisa (LON:THS) reports 6 months to 31 March formally tomorrow - the RNS will be out at 07:00, so that might create some interest and movement.
There is obviously a lot of movement in the base metal spot prices which will have an impact on future revenue, depending on hedging and contract t's and c's.
Once things start moving with a larger percentage, the day traders seem to come in, which increases volume and volatility, a lot of shorter holdings, multiple trades on a different basis. This is feeling rather than a specific observation.
It is one of the harder parts of investing, and hence why I am trying to improve my "rules" check sheet especially on the sell side. And probably need to add two parts to that sheet of "high conviction" and "conviction" holdings, sold Boohoo (LON:BOO) on 20% down and hence watch the bounce...
Tommy
Just a blip on the upward curve during profit-taking by astute or nervous shareholders. Rome wasn't built in a day.
Sylvania Platinum is a very volatile share. Over the past five years, as judged by official closing prices, approximately 10% of daily price movements have been greater than ±5%. That's roughly once a fortnight.
interesting, it's a long term holding but I might start looking at trying to trade it as well
Gateley Holdings (LON:GTLY) N+1 Singer has followed up on the trading update with an upgrade to forecasts.
"This comfortably continues an unbroken record of revenue and profit growth, prompting us to upgrade revenue and PBT forecasts by 9% and 34% respectively. "
marks and spencer?
Marks And Spencer (LON:MKS) isn't a small cap yet!
Hi Paul, what are using as a pro forma EBITDA number for "business as usual". Say back to 2019 levels of business .... the estate is 10% slimmer but I guess they will open more bars now ...finger in the air £12m?
So net debt / EBITDA back to pre covid levels ....
10x EBITDA gets you to more like 40p as a price target doesn't it?.
For the disgruntled Revolution Bars (LON:RBG) shareholders amongst us, (I am one but with a very small holding) if this had been a conventional rights issue (which it clearly isn’t as those with preferential access get a bigger proportion of the discounted placement shares) the fully diluted ex rights price would be about 25.4p (say, ((125m x 33p) + (105m x 20p))/230m).
The shares have dipped as low as 21p today, though now back up to about 22.5/23p. At this price, if you still believe in the recovery story that you were backing yesterday at 33p a share then and 25.4p fully diluted now (and that the company can invest the new capital better to achieve this), then rationally it makes sense to buy more today. Then again, if you feel you’ve been completely shafted by the management it’s probably the last thing you want to do.
Gus.
I for one believe a better price could have been achieved. Where 2 weeks ago, investors were buying at 41p
A few months back, I bought Bacanora Lithium (LON:BCN) at 56p, I day afterwards they announced their placing at 45p. So after a few weeks of seething, I bought them back at 40p. They now stand at 55p with Ganfeng's pos. offer of 67.5p. So moral of the story....us small PIs do get shafted ....if u still believe in the company's narrative - as gus1065 said - buy more shares post placing.
Marks And Spencer (LON:MKS) Not a small cap but Paul likes retail. An upbeat sounding research note from Shore Capital.
"We have rarely felt so warm to the M&S investment thesis albeit the consumer economies in all its markets remain fragile. With a stronger balance sheet, encouraging current trade and building cash flows, which could mean dividends in the foreseeable future(we assume FY2023), M&S’ shares could be primed for a strong upward run."
"Ocado Retail traded strongly, with sales reported up by 43.7%. We believe the response to the transfer of supply to M&S has been especially encouraging, with M&S products representing >25% of the average Ocado basket."
"C&H online was a standout positive for M&S, with sales up 53.9%,includingQ4 revenue growth of 105.8%. Customer traffic growth was 35.2%, with active customers numbers up >50% to 9.0m."
Marks And Spencer (LON:MKS) has out performed Boohoo (LON:BOO) in my portfolio
Paul, any chance of looking at Auction Technology £ATG. Results out today. Stockrank not great, but there is huge potential.
Sorry, left out the word future re pay rise or options
Hi Paul
Re Revolution Bars. Thank you for the update. I am appalled by the way private shareholders are being treated and the management, in my option, are behaving in a very unethical way. What % of shares are owned by private shareholders? If over 50 %, I would suggest that private shareholder, who I would hope have a long memory, vote against any pay rise or share options for the board.
Good morning Paul, any thoughts on Mattioli Woods (LON:MTW) acquisition and primary bid offer? (It's still open for 2 hours). The company looks in rude health, and comes with a healthy employee review rating on glassdoor (employees are happy working there). The acquisition of Maven Capital comes with performance conditions over 4 years which is nice.
I wanted to get in on the Primary Bid offering, but didn't make the deadline. However, it has put the company on my radar.
£LON:RBG Revolution Bar Group. Interesting that apparently you can take up an additional 4% of shares under the open offer, even if you only buy your initial shares today. The record date is not until close of business today. Normally under an open offer I believe the offer is only available to people holding shares at the time the RNS is issued, announcing the open offer. Feel free to correct me if I am wrong.
Mark - there's always a snag. Sounds good but if you buy Revolution Bars (LON:RBG) shares today then under standard T+2 settlement you are not on the register until Friday so that is the record date for today's purchases.
Thanks Sharw, I should have realised there was a catch. I rather naively thought that since they brought out the RNS after hours, they were giving a little wriggle room to their army of loyal small shareholders. I should have realised that the late RNS was just another indication they don't give a toss about those unfortunate pesky wretched fools who have financed them thus far.
Genuinely appalled by £RBG. Its not cricket.
Will this garrote the Q rank, thus warning off some new investors?
Jarvis Securities (LON:JIM) strange price action yesterday on no news, I thought it was probably a 'tree shake' but I see they are sliding again today. Anyone have any ideas?
I have been wondering what’s going on as well. Can’t find any news anywhere. (I hold.)
Hi GN100, my opinion of Jarvis Securities (LON:JIM) is that fundamentally the company is in good health but it is overpriced with a PE of 18 and EPS Growth of 7%. I believe Mr Market is shaking the tree and there are probably buyers (aka Smart Money) waiting on the sidelines at around 218p and once their needs have been met I believe the price will be in an upwards trend.
David.
I am currently invested in Jarvis Securities (LON:JIM), having retained half the shares I bought in Apr-20 at the equivalent of circa £1.06. I still have Jarvis Securities (LON:JIM) as I believe the broker forecasts to be notably on the over-pessimistic side.
IMHO, the text in the 2020 results, issued on 11-Mar-21 were significantly more optimistic than has generally been the case in the past...
https://www.investegate.co.uk/...
Circa 5% dividend while I wait for out-performance is fine by me; somebody seems extremely keen to messily sell down their holding currently.
I recently bought Revolution Bars at 40 p which is now worth half this - as you say Paul the system is fundamentally flawed and grossly unfair on retail investors. At least they should have offered some shares to retail investors through Primary Bid at 20p. It is tantamount to theft that retail shareholders have no pre-emption rights.
Morning Chris,
That's very unlucky timing, I sympathise, you must be enraged by the 20p placing, with good reason.
I do think it's important for us to lobby the powers that be, to tweak the system so that shares have to be suspended if a placing at a discount of more than say 5% is being organised. There could also be a requirement to suspend shares if dilution of more than say 10% is contemplated.
Plus we need a legal requirement that shares must first be offered to existing holders.
This could all be done so easily, we've had the technology for over 20 years to do fundraisings quickly & electronically, but I'm afraid juicy fees for the vested interests keep the current, awful system going.
How do they expect London to compete post-Brexit, with such a lousy & expensive system for fundraisings?
Regards, Paul.
Revolution Bars (LON:RBG)
I'll paste the compaint e-mail I sent to FCA yesterday here as it's more topical to this thread. I was angry last night and remain angry, even after the offer on Vectura (LON:VEC) today (I hold quadruple what I hold in Revolution Bars (LON:RBG))
Sent today to FCA >complaints.scheme@fca.org.uk<
"Sirs
I would ask you to investigate suspected insider dealing in the Revolution Bars Group Plc (ticker RBG) share placing today.
On 11/5/21 RBG submitted an rns entitled "Re-opening update", within the strong update was the phrase "we now expect that our full year performance for the year ending 30 June 2021 will be ahead of previous management expectations", the share price consequently and understandably rose sharply on the day. It then started to fall away every day from a high of 41.60p to a close today (25/5/21) of 33.10p, a fall of 22% on a strong update.
After close today we are greeted with an rns confirming a firm placing from RBG to raise £20m with 100m shares at 20p per share, "The Issue Price represents a discount of approximately 41.2 per cent. to the closing price of an Ordinary Share on 24 May 2021".
I would respectfully suggest that clear insider share dealing has been at place here from insiders 'in the know' that the placing was coming and I would respectfully request that you investigate the dealings from sellers between 11/5/21 and 25/5/21
Thank you & Best regards"
Thank you for this threeputt.
Revolution Bars (LON:RBG) was always a further dilution risk, and part of the risk. It clear the raising fund from institutions is much more timely and cheaper than from retail investors, so your can understand companies doing this, another risk for retail investors to consider.
Theft and disgust seem strong language for what seemed like a possible outcome.
As always much better to do your own research rather than depend on 3rd party information.
DYOR
BSV
It was indeed always a risk - but the claims of theft etc come from a 40% dilution occurring whilst private investors are paying 30p+. Moreover, the company has done nothing but indicate good news to all before dropping this on all of those who weren't 'in the know'. I think considering all that, theft and disgust are quite reasonable language.
If the theft is true, who's going to be caught and facing criminal charges?
BSV
You know the answer to that. No-one. And you're focusing on a specific word whilst missing the point. The private investor paying nigh on 40p recently has just seen their holding half within weeks, during a period the CEO has talked about 'outstanding' results. A dilution was a risk - although we've had one already remember when we went from 50m to 125m shares. My point is that language such as 'disgust' and 'theft' is entirely reasonable when you've seen your money halved during a period when the company is selling itself at 20p and the CEO tells you that results are awesome.
Hi Clw349,
Revolution Bars (LON:RBG) has always been bullish on prospects and underdelivered. It's a classic pump and dump share in my view. Best to learn the lessons and move on.
BSV
Maybe mate (though I'm old enough for this to not be my first pump and dump pain!) but just to be clear - though I am a holder - I haven't been leathered by this because my average is thankfully lower. It's those who've been buying at up to 40p on an open market (which is anything but) whilst the CEO is claiming everything is awesome at the same time hawking himself at 20p. That may not be criminal or theft in specific legal terms (though I would argue as a minimum it's dishonest), but it results in small private holders having nigh on half their holdings removed, with no recourse, no method of taking part, and a minimal chance of seeing their money back again (are we really going to trust the management of this company to get that market cap back up after they've pulled a stunt like this?) I'm honestly not sure it's good enough anymore to wearily nod at another pump and dump and move on; I fully agree with people's anger and emotive language on this one.
Yes agree absolutely dishonest, but you can become CEO or even PM with such a trait.
Let hope people and shareholder in the UK prefer someone who is honest and vote accordingly, but I suspect we prefer people who tell us what we want to hear rather than the truth.
BSV
Sadly, yes. Boris appears to have made a career of it.
Revolution Bars (LON:RBG)
clw349
"The private investor paying nigh on 40p recently has just seen their holding half within weeks, during a period the CEO has talked about 'outstanding' results. A dilution was a risk - although we've had one already remember when we went from 50m to 125m shares. My point is that language such as 'disgust' and 'theft' is entirely reasonable when you've seen your money halved during a period when the company is selling itself at 20p and the CEO tells you that results are awesome. "
Apologies for being blunt clw349 but RBG as an investment with debt forecast to go potentially within £1.2 mill of the relevant covenants with no backup plan in place for extended additional lockdown was always a risky investment - its exactly this type of situation where there is large uncertainty that the market hates - the directors didn't dictate that the shareprice rose above the level it was at presviosly and the price they could raise funds at is what it is - you pay your money and you take your chance. Its poor they have shareholder priority near the bottom but keeping the business solvent will always rank first - with regard to the good trading , trading was good so i don't think its fair to say that anything was definately beimng pimped up if the reality is that this situationis factual. Anyone who invests in a company should read the going concern note in the annual report and the risks here on page 60-62 are pretty clear
- note their severe and plausible downside scenario presumed they would be reopen by the start of April - the fact they were presumably a couple of weeks behind that target sort of outlines the fact that they didn't have much wriggle room (stockopedia rightly flags tis up as a high bankruptcy risk company !!)- the fact that they were so close to limits confirms that this debt was an elephant type problem and that then can create the unfortunate position we are in now. Its a fine line though saga and card factory have had similar worries and managed to scrape through so its such a shame they have capitulated now but unfortuanetly with such little wriggle room there is a much higher chance things could end up where we are now. Companies on the edge can have great upside potential that is multi bagger but lets not hide from the downside risks too!
All imho - these are just my thoughts of the situation and no more.
There's nothing blunt in there pal, I agree. My original point was simply about BSV calling out the word 'theft' from another poster. IMHO, such emotive language is to be expected considering what - and how - they've done it. And though the directors don't dictate a share price, thank god, they are aware of it, and their actions absolutely do affect it.
As always much better to do your own research rather than depend on 3rd party information.
You just can't help yourself, can you? Always a little dig at me in every single comment you post. Quite sad really.
It to do with encouraging others to do their own research.
Absolutely nothing to do with you.
BSV
You cannot research some stuff - it depends on what the Board chooses to do.
There was definitely always a researchable risk that Revolution Bars (LON:RBG) would need more funding (eg if COVID hung around through another Oct-Dec High Season) but in the communications to the shareholders (as opposed to private briefings to a select few), there was no indication of a need for such a major capital raise - neither as an emergency measure, carry us through the storm nor to 'seize the moment' - see slide below from April '21 presentation with my highlight.
Probably no more than 10 people initially were involved in this decision: the CEO/CFO and Board plus representatives of the leading institutions they spoke to. Once the decision to raise significant funds was made (ie to significantly change strategy), this was material to the share price (as evidenced by reaction today) and should have been made known to the market.
Furthermore, iIf they believe their own forecasts, even in a downside case, they had headroom and cash saving options (without even considering selling a couple of properties even at a distressed price to raise to raise money when the business was on a former footing again). So frankly, either some important info has not been disclosed (or why do I bother reading the results slides!!!) and/or some very poor, short term thinking and decision making by the Board. I will be writing to the independent Directors on the Board to this effect.
As I should have said clearly when my blood pressure was higher, I hold.
Hi Zipmanpeter,
It seems like you did your research and accepted the risk that there was potential for more fundraising. Materialization of the risk can be disappointing, although, at 40p the upside reward seems limited for the downside risk. see the link to my analysis.
https://www.stockopedia.com/co...
Card Factory (LON:CARD) is going through similar fundraising, the difference is valuation still looks attractive after funds are raised. see link.
https://www.stockopedia.com/co...
The risk/reward for Revolution Bars (LON:RBG) always looked poor, whereas Card Factory (LON:CARD) looks ok from my perspective.
BSV
Agree that £RGB was/is a worse risk:reward than Card Factory (LON:CARD) (which is also risky!). My complaint is not that I lost money by being on the wrong side of a risky bet - it is that I have been on the wrong side of a bet that was unfair. Like being in a casino when some but not all people know a lots of extra reds will be added to roulette wheel.
Bought some Revolution Bars (LON:RBG) as an end of lockdown play around 1 month+ ago - I was one of the lucky ones - sold out 1 day after the recent positive TU - RNS at around 40.65p. Why? 1. I suspected profit taking will occur. ...2. I suspected in the back of my mind that Revolution Bars (LON:RBG) might grab us by our curlies to pay for their ongoing site renovations + shore up their BS exploiting a high SP (noticed in recent times a few companies doing this whilst the market remains bullish). Got lucky here. Sorry for LTH.
Glad to hear you avoided the carnage.
BSV
Revolution Bars (LON:RBG) - does anyone know when the next placing is due?
Revolution Bars (LON:RBG) (I sold my balance this morning). To me it looks like the banks are wanting to de-risk and shareholders are footing the bill. It would appear that the current holders know they are in a tight spot and played hard ball on the price. I would echo Graham F comments on staffing costs too and I hear lack of staff availability in hospitality being mentioned regularly on the news. ( ie cheap labour)
Hi Albm7,
Good point. A placing to get the bank off the hook, and into a lower risk position, is not going to appeal to institutions. Maybe that played a part in the Revolution Bars (LON:RBG) (I hold) placing being at such a deep discount?
Sure there are other reasons for the fundraise (high quality new site acquisitions, urgent refurbs with a very attractive 2-year payback), but the main purpose is bank debt reduction.
Has the bank really been that supportive? Only temporarily. And bear in mind that they shifted a lot of the facilities onto a CLBILS (80% taxpayer guaranteed) loan during the pandemic.
I think this is a great reminder that dilution/placing risk is a very major issue. I wouldn't touch anything like Card Factory (LON:CARD) for example, which has already announced it has to raise £70m. It's just pot luck whether institutions will back it or not. If not, then the discount could be hideous, as we've seen with RBG.
To a certain extent I broke my own rules on balance sheet strength with Revolution Bars (LON:RBG) so this is an important lesson to myself. Although also, I was lucky in that I greatly increased my RBG position at 11p, and reduced it at 30-40p. So overall it's actually worked out alright. Not much solace to people who didn't top slice though, other than to make you even more angry :-(
I also take the point about labour shortages & increased cost, due to some people using lockdown to retrain for other jobs, likely to be a considerable headwind for hospitality/retail sectors. Also one of the key reasons for Brexit was to stem the flow of cheap labour from E.Europe, and make the UK a higher wage, higher productivity economy, a good thing in my view. Hence a bit ironic to hear arch-Brexiteer Tim Martin of J D Wetherspoon (LON:JDW) today belly-aching about labour shortages!!! :-D
Regards, Paul.
Disgusted with Revolution Bars (LON:RBG) but delighted with Vectura (LON:VEC) so that’s life :)
Disgusted with Revolution Bars (LON:RBG) but delighted with Vectura (LON:VEC) so that’s life :)
This is muddled thinking. If someone steals my car, someone else giving me a box of chocolates will not compensate. What Revolution Bars (LON:RBG) did was a legalised form of theft. Can you not see that?
All the best, Si
I was being philosophical. Can you not see that ?
Anyone remember old fashioned rights issues where all shareholders big and small were treated the same?
we are in the samp camp there, vec one of my largest holdings so am well up over both deals
When I said “sell in May and go awa”, I wish I had now.
40% down on Revolution Bars and all my other shares have taken quite a hammering.
Totally with you on that even Sylvania Platinum got hammered yesterday.
Spire Healthcare (LON:SPI) all cash, board recommended take over offer at 240p per share announced this morning. SP went to premium to the takeover price so I sold my holding. Should I have held on for a bit? Surely it's a done deal if recommended by the board and 30% of shareholders have already committed.
I sold half my holding on the news. keeping half in case a bidding war occurs.
I had an operation at Spire in Jan and it was a good experience, to give you some patient feedback!
Hi kbkb - As you had your treatment at Spire Healthcare (LON:SPI) back in Jan (4 months ago), I would consider that you have indeed been quite patient in your feedback
Yes its a grumpy market mood day and it's still bloomin cold. - Seriously though I have had a couple of operations there in the past and concur of the experience
£RBG Still not my cup of darjeeling..I had a meeting with them around the end '18, early '19 when the shares were £1+ and they had a fundamental problem then and pre covid - students were drinking less and less. '21 pent up demand is only short term - avoid.
RBG - Able to top up at under 22p, so thats OK if stock is worth 35/40p in 2 years.
I picked some up at 22p. Brave or foolhardy, I'm just not sure.
I was decidedly grumpy this morning, but myRBG losses are now offset by the Spire Healthcare takeover....you win some....you lose some
So Revolution Bars (LON:RBG) would sooner shaft the owners of the co rather than suspend the shares and issue a prospectus to enable more than a £1m token OO.
What we need is a Revolution!
So Revolution Bars (LON:RBG) would sooner shaft the owners of the co rather than suspend the shares and issue a prospectus to enable more than a £1m token OO.
What we need is a Revolution!
Yes, no one should paint this as anything other than the management of the company shafting retail shareholders. A really pathetic excuse to hide behind legislation. As abtan pointed out, they could have just waited a month before doing a bigger OO. Clearly they were in far more trouble than they let on in recent announcements so had to take what funding they could at any price.
I have no interest here, but am disgusted that once again the pre-emption rights of small shareholders have been trashed. It shouldn't happen. It should be illegal in a modern democracy. The management have no credibility left, so Revolution Bars (LON:RBG) is totally uninvestible for me. I'd much rather hold Diageo (LON:DGE) and Fevertree Drinks (LON:FEVR) if people are going to drink themselves senseless on cocktails.
And don't forget, there is a major football tournament in June/July and we know from previous experience that people drink elsewhere as Revolution Bars (LON:RBG) do not have TVs in their bars.
All the best, Si
Good morning Paul, would appreciate your thoughts on De La Rue (LON:DLAR) (I hold).
De La Rue (LON:DLAR) is on my to do list.
Hi Paul
No flak from me over Revolution Bars (LON:RBG)
I held it once upon a time but we had different views on it in recent times. You had a very clear argument as to its merits. So, there’s nothing wrong with that. We all get caught out from time to time. Personally, I thought Gaming Realms (LON:GMR) was going to go up the other day when they announced they had been awarded a license for Pennsylvania. But the opposite happened. So, I am wrong there for now at least.
I think the institutional investors may be getting twitchy that staff costs are going to go up considerably in hospitality due to the migrant workers who left during COVID only returning slowly (and that return potentially delayed by Brexit). The implication being that while revenues are going to rebound, profits may not. Perhaps there’s also the legacy with Revolution that the previous management didn’t have a good grip on how staff costs change. Unfair on the current management but it may be a factor.
Graham
240p (20% premium) recommended cash offer by Ramsay Health for Spire Healthcare (LON:SPI) https://www.investegate.co.uk/...
Please could you look at the placing and acquisitions by Mattioli Woods (LON:MTW) ? The price paid for Maven at 11.3x EBITDA looks rather expensive to me compared to the prices at which much larger PRE houses are trading
Mattioli Woods (LON:MTW) I used them for some reason for my SIPP (its a long story) and their service is appalling.
Any idea why Sylvania Platinum (LON:SLP) has slipped so much in the past week - and esp yesterday - 10%..? It seems a popular share here so hope someone will have ideas please
the price of rhodium has dropped a little over the last few days! Auto makers not producing many cars due to chip shortage.
Likely nothing to worry about for LTHs
Added kick in the nuts for LTH of Tharisa (LON:THS) particularly after the recency stagnancy due to II's selling out.
I was wondering the same about it and Ferrexpo as I hold both, sorry I can’t help but hopefully someone can! Is it time to sell or hold on?
You might want to buy if you are looking to hold for a while. I hold both and think they will overcome temporary price and political obstacles.
Hold, and maybe add on weakness. That is what I'm doing. Dyor, naturally.
Hi,
I have sold my Ferrexpo (LON:FXPO) this morning, just on the mechanical basis that it is down 20% from peak and cashing in profit (one small and one reasonable as in two family holdings). I will buy back again, but just part of my pain from last year kicking in and still in the build capital back up again.
Ferrexpo (LON:FXPO) will probably bounce massively today as a result of my sale, or maybe it will not.
We shall see!
Tommy
The price of the rhodium is the answer. It was around $7k/oz a year ago, and $25-30k/oz in the last 3 months but in the last few days dropped badly (based on kitco it's 16.5k/oz at the moment).
So 60% of the revenue is from rhodium (19% platinum, 17% palladium) and the reason why Sylvania Platinum (LON:SLP) was flying in the last year was the same!
Johnson Matthey and Trading economics had the price around $25k so not sure why Kitco's price is so low
Are you seeing $16.5K/Oz or £16.5K/Oz?
I've been using www.metalsdaily.com to check prices.
https://tradingeconomics.com/c...
Useful for tracking commodity prices
That's a great commodity collection, but for rhodium check up this one first, it will show more idea about the panic sells:
https://www.kitco.com/charts/r...
Drop in rhodium price, Chinese Communist Party trying to throw cold water on commodity rally by issuing various edicts & tightening credit, general pause in commodity rally after strong run, plus I wouldn't be surprised if there had been a bit of a speculative price squeeze going on in rhodium market as well but just guessing. Drop in rhodium price main reason but probably lots of causes for that.
China are trying to force down base metal prices. Miners are bearing the brunt of this, naturally.
Thanks for all the input - seems you have all been taking the opportunity to buy on weakness - up over5% this morning.....!
Keep the faith! It drops in price to make you panic and sell.
Sylvania Platinum (LON:SLP)
I am not sure of the reasons. The rhodium price is off from $29,800 to $25,000 (The kitco figures are odd/unsettling! Bairdmint https://www.bairdmint.com/live... also has bid/offer of $14,000/$18,000, I cannot figure out which are the correct ones).
Could be profit taking after the IC tip and the fact that it is up five fold since March 20 low?
I think it is best to remember Ben Graham opining on the stock market:
"In the short run, the market is a voting machine but in the long run it is a weighing machine"
However these two articles were brought to my attention on Twitter this morning
https://www.fool.co.uk/investi...
https://www.northernminer.com/...
indicating that PGM's could have a use in battery technology, which should be positive for £SLP. I was not aware of this but quite possible I missed it.
Sylvania Platinum (LON:SLP) is a large (9.6% of pf) for me with average price of 59.95p and I am tempted to take a bit off the table say 20% of the holding but I am not sure where I would put the proceeds and my sell timings always seem to be cr@p.
Regards
Michael
Revolution Bars (LON:RBG) (I hold)
Hi Paul
Thanks for your comments this morning. I had quite a large position so I am rightly pissed off by last night's announcement.
One more thing to add if I may.
You said:
"To be fair, they wanted to do a larger Open Offer (like last time), but apparently were prohibited from doing so due to some ridiculous rule that limits open offers to 8m euros per year."
I believe the last Offer took place in June 2020 (I participated) so the company only needed to wait 1 month if they really did not want to screw over those who provided funds last year.
Given that there was another £12m available from their debt facilities (£40m facility vs £28.5m utilised so far), management could have chosen to wait another few weeks...but they didn't.
It's quite unscrupulous.
For what it's worth, I believe the raise is a good thing in the long run, though I am surprised that such a discount was necessary.
Depending on where the share price settles, and against my better nature, I'm more more inclined to top up, though I'll wait a day or 2 to let emotions subside before deciding my next steps.
A
Abtan - I share your frustration and dilemma £RBG I too might back the business at 20p but may/may not get the chance.
When I got into UK shares, I understood that there was generally a single class of shares. Frankly, this is not true in reality. As in so much of UK political life, insiders get a privileged ride and access to things most of us can't. No wonder so many rail against the "free market", "competition" and "capitalism" . We risk killing the golden goose with this 'crony capitalism' that entitles some to unfair rewards who then portray this as skill. Do we really believe a transparent, digital fund raising could not be put in place if there was a will?
I spent 20 years working abroad in autocratic, so called 3rd world countries where "big men" creamed off the top, supported by a network of technocratic hangers on. Arguably I was one. I came back to the UK in part seeking equality and fairness before the law and competitive markets. Increasingly I feel this slipping away. I may be shot on this site for being "political" but I am not. This insider dealing and structures is affecting my investing behaviour. I am looking for investments where I can control outcomes or somehow be part of the inner circle myself (eg on the flip side where govt creates uncompetitive markets through regulation).
I bought my son some Revolution Bars (LON:RBG) shares a few years ago to get him interested in investing....and he has learnt. He now only wants to hold cash and sees no point in analysing businesses only in building relationships to make a fast buck. What do I tell him different?
I think that a good book to read is the Art of Execution, which gives a good insight into potential pitfalls.
I would be telling your son, the same as I told myself after getting shafted when SXX raised funds at a discount, then shafted all the small shareholders, in my opinion.
Don't make the same mistake twice, and make sure you understand what you did wrongly.
If it was just pure bad luck, that is one thing, but I can understand the frustration of all those who hold RBG.
I bailed out at 17p, and lost some funds, having sold half my holding when the offer was turned down (was it 220p)
The biggest lesson I learned was that having a boring chunk of my portfolio earning me a dividend of 3%/4% a year and growing by 5%/6% a year, is an important component.
But there is no doubt that RBG have been outrageous with their actions
"To be fair, they wanted to do a larger Open Offer (like last time), but apparently were prohibited from doing so due to some ridiculous rule that limits open offers to 8m euros per year."
If this is the issue, then they could commit now to an open offer to shareholders on the register now to run in X months time - even at a slight premium to today's price. Extra funds at a better price held in escrow if needed until it could be executed, with minimal real incremental cost in today's digital world.
If this was a barrier that stopped them raising funds at at all, who thinks they could have found a solution?
Hi Peter, I understand your frustration with regards to shares such as Revolution Bars (LON:RBG) which you bought for your son.
My advice for your son would be:
Buy High Quality companies, which make a Profit, which have a Healthy Balance Sheet and which have Momentum behind them.
Maybe these type of shares won't always 'shoot the lights out' but they seldom let you down and you don't have to worry about horrendous rights issues and terrible dilution of funds which a lot of indebted companies seem to be experiencing at the moment.
David.
If it had been a rights issue at least we would have had a choice about whether to participate or be diluted - that was not the case here.
Thx for advice - re Revolution Bars (LON:RBG) .....actually the wider picture of selecting RBG as part of a mostly sensible 5 share portfolio bought for my son from a small granny inheritance was to generate interest in the share to get him interested in LT wealth building through investing. I figured a bar chain met that bill (and at the time some sound financial prospects).
Perhaps more fortunately, at the same time I bought Boohoo (LON:BOO) for my daughter at 23p! :)
Fear & Greed Index
What emotion is driving the market now?
Fear 33
Previous close Fear 35
1 week ago Fear 38
I month ago Greed 61
1 year ago Neutral 50
(taken from CNN business)
De La Rue (LON:DLAR) results look encouraging for the turnaround. Loss of passport contract made a big hole in the figures. https://www.londonstockexchang...
The market doesn't see it so well - down some 4.5p on the opening.
Morning all,
Another good update from Sdi (LON:SDI), full year revenue and profit before tax both higher than previously forecast. FY'22 expectations unchanged.
I hold.
Regards.
I'll be taking a look at Sdi (LON:SDI) later this morning.
My morning smallcap tweet: GYM re-opening working out
SDI (LON:SDI) Cohort (LON:CHRT) Cyanconnode Holdings (LON:CYAN) GYM (LON:GYM) Zotefoams (LON:ZTF) Finsbury Food (LON:FIF) Gateley Holdings (LON:GTLY) Mattioli Woods (LON:MTW) Judges Scientific (LON:JDG) Tiziana Life Sciences (LON:TILS) Learning Technologies (LON:LTG) Oxford Metrics (LON:OMG)
SDI (SDI) guides FY rev £35.3m and pretax £7.4m, both up on guidance. Guides FY22 in line. [SP=180 Cap=177m]
Cohort (CHRT) guides FY(Apr) in line but FY22 margin reduction due to delays in the placing of certain orders with EID. [SP=670 Cap=275m]
CyanConnode (CYAN) MoU with Intellismart to work on existing Energy Efficiency Services Limited and Intellismart projects as well as new ones, in India and international markets. "Intellismart, a Meter Asset Provider, is focusing on expediting the deployment of 250m smart meters across India." I think that means the total mkt is 250m meters. [SP=7.1 Cap=13m]
Gym Group (GYM) has outperformed mgmt exp since re-opening. Membership down only 8% on 2019. [SP=259 Cap=430m]
Zotefoams (ZTF) guides FY rev significantly ahead of market expectations "which will offset the short-term inflationary impacts on margins, the weaker US dollar and our planned increase in product and commercial development costs". Comfortable with market expectations for growth in profit. [SP=405 Cap=197m]
Finsbury Food (FIF) guides FY(June) pretax at least £15m, ahead of market expectations. Expects to resume divs. [SP=83.15 Cap=108m]
Gateley (GTLY) guides FY(Apr) rev up over 9.3%, pretax up at least 8%. In line? Net cash £20m, significantly ahead of mgmt exp. [SP=196.5 Cap=232m]
Mattioli Woods (MTW) c. £110m fundraise at 660p, a 10% discount, to fund acquisition of Maven, a leading private equity investor in UK SMEs and alternative asset manager. Expected to be earnings enhancing in the first full year. [SP=742 Cap=210m]
Judges Scientific (JDG) new £60m bank facility to provide 'a substantially larger springboard'. Is David Cicurel training for the Olympics? [SP=5940 Cap=375m]
Tiziana Life Science (TILS) further analysis for Phase I study of nasal Foralumab shows immunomodulatory effects capable of providing clinical benefit. [SP=81 Cap=158m]
In line: Learning Technologies (LON:LTG) Oxford Metrics (LON:OMG)
New Capital Employed podcast episode uploaded feat. Jonah Lupton.
Jonah talks about his thesis for investing in Celsius and Upstart Holdings Inc...
https://podcasts.google.com/fe...
Good morning Paul Re:RBG. ANIC came up with a placing I have not come across before. They raised 60 million at 22p ( six times over subscribed for an investment company already 5 x NAV) and have offered warrants at 28p should they wish to raise upto another 80 million in the future. I think shareholders vote on it today.
If you have not heard of them before they invest in start up companies aiming to revolutionise food production, and therefore reducing the need for farmed animals to eat by producing meat grown from stem cells. Most of these companies are at least ten years away from marketing. Californian Bluenalu seem to be closest possibly getting some sample product (seafood meat grown from stem cells) to market next year.
Seems the institutions & HNWs feel that Revolution Bars (LON:RBG) future is in the balance, if the rot has set in and the product / experience isn't what it once was and people are drinking in different ways , then the tough period may just have begun.
I'm a fan because there is a business in there, but this dilution destroys confidence and unless they can improve the product back to normal quickly, trading could continue to be tough and this for me is reflected in the placing.
A lack of quality staff seems to be the next issue businesses is facing, everyone is delivering snacks as opposed to serving customers and brexit seems to have removed the UK's human engine of cost effective workers.
Revolution Bars (LON:RBG) the problem now is to try and look forward after this nasty shock for PIs. Is the operation now a dead duck or do we hold on in the assumption that they will now pull through with a positive affect on the share price? £20m doesn't seem to me to be a large amount to refurb and do deals on new opportunities. However, it's a blessing they didn't try to raise more cash.
I went to a local bar on Saturday night and it was shocking. Looked like a "before" shot of a DIY project and staff where hopeless did not have a clue what they were doing, cocktails were a joke. I won't be going back. What this shows is that in relation to the "reopening" of hospitality venues you have to spend money on decor and staff otherwise you can kill your reputation stone dead right there.
Revolution Bars (LON:RBG) bit of a sneaky shocker following recent RNS and the fact it was done after hours.
If I can get out at a profit I will attempt to today. Adding the new shares to the old ones, I make the average price around 27p. If my memory serves me right, the last placing was also at 20p, with an average of 27p, the share price then fell through the floor to around 9p.
Long term I think this company will thrive, but I no longer trust the management to look after us small PIs, so time to invest elsewhere.
Moring GlucesterBob,
Re Revolution Bars (LON:RBG) (I hold) you said -
If my memory serves me right, the last placing was also at 20p, with an average of 27p, the share price then fell through the floor to around 9p.
You are correct, however circumstances were very different. The second wave of covid happened, and there was no vaccine. That was why RBG shares crashed down to 9p after the last 20p placing.
With vulnerable people now vaccinated, I don't see the price falling below 20p again, unless the virus mutates into a form that beats the vaccines.
RBG should do a roaring trade between now & Xmas, hence why it's such a pity they've diluted holders so much just before bumper cashflows begin to roll in.
Also worth noting that there was a profit opportunity of making 3-4 times our money, from the 9p low, to a recent 40p high. So people could have banked a nice profit if they'd wanted.
Regards, Paul.
Also an interesting rights issue with CCR today... Can I ask if you have any doubts about SAGA Paul or still a good few months room? And basically think twice about any stretched companies at the moment? thanks.
Gloucester Bob
I regard what I paid as sunk money that should not influence whether or when I sell.
I can’t always act unemotionally though!