Small Cap Value Report (Weds 28 July 2021) - OTMP, STAF, MARS, TRCS, APTD

Good morning, it's Paul and Jack here, with the SCVR for Wednesday.
Timing - TBC
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Onthemarket (LON:OTMP) (I hold) from yesterday - my comments on the AGM trading update. Nothing earth-shattering, but this residential property portal seems to have carved out a niche, despite dominant competition from Rightmove and Zoopla.
Marston's (LON:MARS) - trading update, showing a recovery in trading as restrictions ease, but still down on pre-pandemic levels. I can't get excited about this.
Tracsis (LON:TRCS) - a big contract win, which feeds through into a significant increase in broker forecasts.
Jack's Section:
Staffline (LON:STAF) - significant recent dilution here limits the upside but goes some way to fixing the balance sheet. It's a favourable environment in which to execute a turnaround right now for recruiters so things look much more positive these days.
Aptitude Software (LON:APTD) - solid growth and scope for future margin expansion. Its addressable market is expanding. There are plenty of positives here and Aptitude looks like a quality SaaS company, but valuation is a concern.
Onthemarket (LON:OTMP)
(I hold)
95p (up 5% yesterday) - mkt cap £71m
Preamble - For background, there’s a useful recording of an InvestorMeetCompany results webinar here, published on 17 June 2021. The newish CEO looks very young, which I put down to clean living (probably) and favourable lighting/camera angles! Although being more serious, checking his LinkedIn, he’s got a lot of experience in the sector, and subjectively I think he comes across as eloquent and energetic. CEOs come in all shapes & sizes, so it's never certain how anyone will perform.
We’ve also got an extensive archive of SCVR commentary here, over quite a few years.
My last update was here on 8 June 2021, which highlighted a maiden profit, and a healthy cash position. As with other online businesses, the ability to flex overheads considerably in the pandemic (e.g. slashing marketing spend quickly when required) is a big advantage. We also saw this from Sosandar (LON:SOS) (I hold) for example.
OTMP seems to have carved out a niche, despite being in direct competition with near-monopoly price gouger Rightmove (LON:RMV) . OTMP’s market cap is only 1.2% of Rightmove’s market cap. That reflects RMV’s dominance, but also intrigues me, as even a little narrowing of that gap could see a multibagger from such a low base as OTMP’s £71m market cap. Speculative, but interesting.
AGM Statement (trading update)
OnTheMarket plc (AIM: OTMP), the majority agent-owned company which operates the OnTheMarket.com property portal…
- Chairman summarises previously published results for FY 01/2021 - maiden profit achieved, despite the pandemic
- Strong performance has continued in the current year FY 01/2022
- Trading in line with Board’s expectations
Strategy update - I won’t repeat all of the RNS, other than to say I’m not convinced OTMP yet has enough to differentiate it from much larger competitors such as Rightmove & Zoopla. The way I see it, OTMP seems to be sufficiently useful to estate agents, that they think it’s worthwhile paying a much lower monthly subscription, in addition to the major competition’s much higher charges.
Operational metrics are provided, but nothing jumps out at me as particularly significant.
Residential property market - continuing pent-up demand, and low mortgage rates, are keeping the market “very active”, despite tapering of the Stamp Duty holiday. Useful info for wider read across maybe?
Liquidity - cash of £9.7m at 30 June 2021. Sounds fine, although the new CEO has to balance spending the cash pile to accelerate growth, and the need to safeguard the business by conserving cash. In previous years, management squandered a lot of cash on advertising, so personally I’m hoping to see a more carefully planned approach in future. Digital marketing, done well, seems to be the key area.
Broker update - many thanks to Zeus for issuing updates on Research Tree, very helpful.
I’m looking through Zeus’s note from yesterday, which gives useful interpretation of the latest company update. It’s only 6 pages (excl disclaimers), so manageable. Longer notes just soak up too much time & energy, so tend to get printed out & never read, in my office!
As CliffW helpfully pointed out in the comments to yesterday’s SCVR, OTMP could possibly be re-rated substantially upwards (Zeus suggests c.3x future revenues is possible), if investors begin to view it as a subscription revenues business.
Projected revenue this year FY 01/2022 is forecast to rise quite usefully Y-on-Y, from £23.0m to £29.2m. There are some convincing drivers for that growth too, e.g. the two biggest items being estate agents converting from free trials to paying contracts (+£1.9m revenues), and pandemic support measures last year (discounts) of £2.6m no longer being required again (we hope).
Hence I’m saying the forecasts look credible, and are not pie-in-the-sky hockey stick optimism that we sometimes see from small cap forecasts. Overall, I generally find Zeus research notes are really good, and well worth reading, because they're credible, and a lot of work has clearly gone into them.
With its highly variable, discretionary overheads spending, OTMP can dial up or down whatever profit it wants, within a range. That’s often the case with online businesses - it’s a policy decision by management whether to run for cashflow at low growth, or whether to open up the throttle of growth spending, with bigger marketing spend, but then short term losses. Or anything in between. To me, the main thing is that I need to see effectiveness from bigger marketing spend. The worst situation is often when they raise a lot of cash, and squander it, before they’ve really worked out what works best.
Tax losses - Zeus helpfully points out that OTMP has £32.4m of tax losses, which I'd forgotten. So it won’t be paying any corporation tax for a while probably - that's helpful, and should add a bit to our valuation calculations.
My opinion - this is not a value share, so may not appeal to SCVR readers. However, I remain of the view that there’s something interesting going on here. OTMP has got itself into a much more favourable financial position, with fairly secure-looking recurring revenues, and healthy net cash. The estate agents part-own the business remember, so if the share price really takes off, then that could create some excitement, and greater commitment from them to push this portal to the end users.
I have no idea how this will pan out, only time will tell. However, if you take a fresh look at the numbers, things are looking quite promising.
How to value it? No idea at this stage, but obviously I believe there’s more upside than downside, or I wouldn’t hold it personally.
Position size is everything, and for me this is currently a small-medium sized position, that I’ll monitor, and keep a flexible view on it, depending on how the newsflow & finances develop over time.
Even the Stockopedia computers seem to acknowledge that it's not a complete basket case any more, with the resolutely red StockRank breaking out tentatively into lower-middle ground (see below, graph within a graph) -
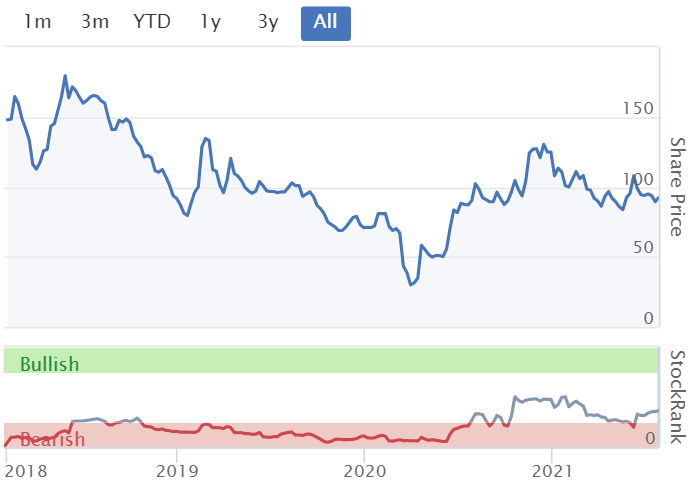
.
Marston's (LON:MARS)
86p (up c.3% at 08:09) - mkt cap £546m
NOTES TO EDITORS
· Marston's is a leading pub operator with a 40% holding in Carlsberg Marston's Brewing Company
· It operates an estate of c1,500 pubs situated nationally, comprising managed, franchised and leased pubs
Marston's PLC issues the following trading update for the 42 weeks to 24 July 2021.
The year end is FY 09/2021.
I like the summary at the top of this announcement -
Significantly improved trading since 17 May, and better than our expectations
- Reminds us that H1 was “significantly disrupted” by the pandemic/lockdowns.
- Restrictions gradually removed in stages - 12 April (outdoor trading began), 17 May (indoor trading allowed, with restrictions), 19 July (most restrictions lifted)
- All sites trading since 17 May
- 90% of sites have outside areas, some enhanced with “Inside Out” programme.
- LFL sales (compared with 2019 pre-pandemic comps) were -23% (12 April - 16 May 2021), improving to -8% (17 May - 24 July 2021) - I can’t get madly excited about that, as trading is still down on pre-pandemic levels, and no doubt costs will be significantly higher.
Current trading -
In the first week of trading since restrictions were lifted on 19 July, we have seen a modest uplift in sales. Whilst this is clearly encouraging, it is too early to extrapolate any meaningful trends at this stage.
Profits/Cashflow -
We have previously reported that we achieved break even from a cash flow and earnings perspective in April, and as a consequence of the easing of restrictions we generated positive earnings and cash flow in both May and June despite operating at around 70% capacity for those months.
Directorspeak - suggests reform of business rates, and a permanent reduction in VAT for hospitality. Good luck with that.
Diary dates - 13 Oct 2021 for year end FY 09/2021 trading update. 30 Nov 2021 for preliminary results.
My opinion - despite the upbeat tone, this all sounds a bit flacid to me. There’s been some interesting commentary lately, suggesting that people are stratifying, using our own risk assessments. I think that’s absolutely right. Some people are partying & almost back to normal (especially younger people), but many are still being cautious, if they feel vulnerable or want to play it safe due to a vulnerable loved one. Maybe that might still be holding back a full recovery for general community pubs like Marstons?
Overall, I don’t know enough about Marstons to form an opinion on the shares, so will just say I’m neutral. There’s nothing in today’s update to excite me.
.

.
Tracsis (LON:TRCS)
982p (up c.4%, at 09:34) - mkt cap £287m
Large RailHub Enterprise Software Contract Win / Updated Forecast
Tracsis, a leading provider of software, hardware, data analytics/GIS and services for the rail, traffic data and wider transport industries, is pleased to announce it has been awarded a new multi-year significant contract in the UK for its RailHub software product suite. This is one of the large rail opportunities that we highlighted in our Interim Results announcement that was in the final stages of contract award.
Trading update -
As a result of this large enterprise licence win, ongoing growth in Rail Technology & Services and Data Analytics/GIS and a post Covid recovery in business activity levels in our Traffic Data and Events business units, we are now expecting full year EBITDA for the Group to exceed market expectations.
It would have been better if this update had provided some numerical guidance.
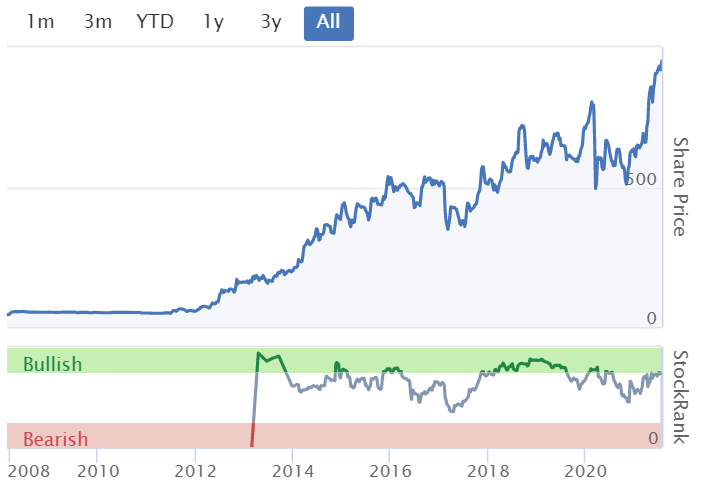
Finncap to the rescue! An update note this morning indicates +£1m in revenues this year, at high margins, for the licence element of the contract, then support revenues in subsequent years.
That drops through mostly to profit, and adj EPS forecast for FY 07/2021 is raised +16% to 29.9p - giving a PER of almost 33 times - not cheap, but the group is performing well, so it’s probably justified.
My opinion - Tracsis is looking good!
.
.
Jack’s section
Staffline (LON:STAF)
Share price: 63.27p (+8.71%)
Shares in issue: 165,767,728
Market cap: £104.9m
It’s been a rough ride at Staffline. It recently launched its second refinancing in 12 months, diluting shareholders further, but providing a more solid foundation for a recovery. The necessary placings have completely transformed what had been a good track record of keeping a lid on shares in issue.
Back in 2011 there were 26.4m shares and by 2018 that had risen to 34.4m. But just a few years later the number has ballooned by nearly 5x to 165.8m. A lot of this happened after a collapse in share price.

While the balance sheet here has been reduced, if we zoom in to a one-year view, it shows that shares have already rerated significantly so it’s not immediately clear that an opportunity remains.

While the shares have slightly more than doubled over a year, the market cap is actually close to 5x higher year-on-year due to shares in issue. Still, the market cap was north of £300m at its height a couple of years back compared to today’s c£100m, so there could still be a case to be made here if the group can fully recover.
Trading has continued to be strong across the first six months of the year to 30 June 2021 and is ahead of expectations with all three of Staffline's core divisions delivering a solid performance in the first half.
Highlights:
- Revenue +4.7% to £450.7m,
- Gross profit +14% to £39m,
- Gross margin up by 0.8% to 8.7%,
- Net cash up by £57.1m to £20.9m.
Strong trading, cost reduction measures, and new higher margin business have allowed for underlying operating profit growth.
The swing to net cash results from £44.4m of net proceeds from the June 2021 equity raise, VAT payment relief of £40.7m (still to be repaid), around £15m of timing benefits (expected to unwind), and improvements in trading cash flow and cash collection efficiency, which have generated an additional c.£10m.
Recruitment GB performed well throughout the first half across food, logistics and e-commerce, with additional margin gains arising from new business wins in online food distribution and after exiting legacy lower margin contracts.
Staffline experienced challenges in its specialist driving division due to the widely reported acute labour shortages.
Recruitment Ireland has seen good trading in its core Northern Ireland business alongside tight cost control and continued growth in the Republic of Ireland.
PeoplePlus also reported an excellent performance from its core 'employability' division, and generated an underlying operating profit compared to a loss in the prior first half.
Conclusion
Based on what other recruiters have recently said, this appears to be a supportive environment in which Staffline can execute its turnaround, with some promising post-lockdown tailwinds.
But these kinds of situations often feel very different depending on the perspective: existing, diluted shareholder or patient observer looking to invest capital in a turnaround.
If you are the latter, it pays to be mindful of the history and the scale of the collapse in value here. Also the fact that placings and the rest, while often necessary, can come at a time of depressed prices, and maximum equity and upside dilution.
And even after the placings, there is still more than £40m of VAT to be repaid. We haven’t seen the ‘fixed’ balance sheet yet but we should get that in the interims, to be released on the 14th of September.
These points do somewhat temper my enthusiasm but the fact remains that if Staffline can stage a full recovery then there is good potential upside even after the dilution. Conditions are currently favourable and the group is trading ahead, so there’s every chance of making it through. Early signs of margin expansion are a positive.
But those margins remain fairly low. Given the events of the past couple of years, I’m waiting for more detail in future updates, signs of further strategic execution, and confirmation of a more entrenched recovery in recruitment - even if that does mean missing out on shorter term share price gains.
Aptitude Software (LON:APTD)
Share price: 602.68p (+5%)
Shares in issue: 56,611,258
Market cap: £341.2m
Aptitude’s software addresses the growing trend for finance automation. Clients include some of the world's largest companies, typically organisations with complex financial data and technology landscapes.
Development, together with a growing number of other services, continues to be performed at the Aptitude Innovation Centre in Poland with sales, support and implementation services provided from Aptitude Software's offices in London, North America and Singapore.
Products include:
- Aptitude Accounting Hub (AAH) - centralises and automates finance, accounting and reporting processes. Its view of financial data enhances business insights to enable decision making,
- Aptitude Revenue Management (ARM) - enables finance teams to further automate their revenue management functions to address the demands of the subscription economy, with the market opportunity now growing into adjacent verticals including high-tech advanced industries and medical devices. The applications simplify the whole revenue lifecycle, from contract order to revenue recognition, and reporting and forecasting,
- Aptitude Insurance Calculation Engine (AICE) - enables data insights and decision support delivering long-term business benefits.
Services include implementation services and solution management services. The latter is growing. These products and services Aptitude Software's target the CFO within large international businesses.
In our most recent coverage we noted that ‘with some share price momentum and potential earnings upgrades, it has all the makings of another High Flyer tech stock.’
That looks to be the case in light of today’s update, but some heat has come out of the share price recently. That’s probably because of the premium relative valuation that has been attached to it by the market.
The group is notably cheaper on a price to free cash flow basis though.

Highlights:
- Annual recurring revenue +11% to £32.2m; total revenue -5% to £27.6m,
- Software and subscription revenue +14% to £16.7m,
- Implementation and solution management services revenue -24% to £10.9m,
- Cash +51% to £46.8m,
- Adjusted operating margin +1% to 18.5%,
- Adjusted operating profit level at £5.1m; statutory operating profit +4% to £4.7m,
- Interim ordinary dividend per share level at 1.8p per share.
Continued new business success across key regions and strategic products driving 11% year-on-year revenue growth on a constant currency basis.
Software and subscription revenue (the strategic focus of the group) now represents 61% of total revenue (H1 2020: 51%), with a number of multi-year subscriptions signed with insurers. Aptitude Revenue Management has attracted a growing number of clients in new industry verticals, ‘increasing the size of Aptitude Software's addressable market’. Clients continue to be upsold.
This growing proportion of revenues should in time lead to an increase in operating margins greater future revenue visibility.
Adjusted Operating Profit of £5.1m is ahead of the board's own forecasts as a result of better than expected implementation services revenue, leading to an increase in profit expectations for the full year of approximately 10%.
The group has net funds of £45.4m (H1 2020: £29.2 million) and no bank loans, freeing it up for acquisition opportunities. It has increased its acquisition activity with a pipeline of actively monitored opportunities.
Conclusion
The shares are expensive but then again recurring revenue is increasing which should increase margins, it looks like there’s good demand for the products, and Aptitude is on the hunt for acquisitions with a net cash balance. Aptitude’s markets are expanding and there’s an increasing demand for smart compliance, finance automation, and finance transformation in the cloud.
So perhaps concerns over relative valuation multiples are a red herring.
The revenue management products in particular are well positioned to address the fast growing subscription economy. The addressable market in North America also continues to grow. This is where the move to finance automation is expanding the fastest.
Given these dynamics, North America will increasingly be a focus for future Go-to-Market investment in the group.
Aptitude is clearly a quality operator - the Quality Rank is 95.

Free cash flow growth has notably outstripped earnings growth (25.7% 5Y compound annual growth rate compared to 6.13% for normalised EPS). Margins are set to expand as subscription becomes a bigger proportion of revenue, and it does seem as though the company can continue to grow steadily via organic demand, with the potential for acquisitions to boot.
But relative to the rest of the market, the shares do look pricey on a forecast PE ratio of 40.6x and a forecast PEG of 5.4x.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Blast from the past in that Touchstone Group accounts are now - previously Touchstone Group PLC.
This company delisted back in 2009 - offering sharholders an exit route via tender at 23p - shareprice was in the high 20 somethings at time of delisting i think judging by other place graph.
This company has been something of a success since delisting - they now have over £18 mill cash in the bank - sharecount is right down after various tender offers over the the years - the last one was for an exit price of 130p
and year end acounts just uploaded to their investor area confirmed that dividend payouts for the year will total 26p.
So for anyone holding shares in a profitable company that does delist there is hope that hanging on in their is not always the worst thing to do. Now if the company could just buy back another 7.94 mill shares at 1.50 per share from current cash resources - that would leave me owning half of the company - i can but dream.
Well I missed the Creightons (LON:CRL) webinar today so hope pi world can post it up. Vote up if you would like to access the webinar. Tks
Hi Paul
Have you managed to take a look at Revolution Beauty?
Is it a coffee can share?
Many thanks
International cruises allowed in England again - should be good news for Saga (LON:SAGA) (I hold). Here's a link (behind paywall) https://www.thetimes.co.uk/art...
Mood must be bullish at Saga (LON:SAGA)
Their International cruises starting end Aug are likely to sell out, already almost 80-90% occupancy?
And then they've just loaded a huge bunch of UK only cruises for early-mid Aug. They must think there is so much pent up demand that they can sell so much capacity in less than a month. For UK only cruising!
£BIG Big Technologies IPO today. They make tags for prisoner tracking and also use their technology to help older people stay in their homes longer by alerting relatives for help if they fall etc.
I mention it as IPO started at £2 (577m MKT cap) so would have qualified for SCVR but is now up 50% already today (£800m or so)
Management looks v experienced and proven track record. CEO Sara Murray founded and sold confused.com and I note the old CFO of Volex (many holders here have mentioned him as v competent) Daren Morris has also turned up here (he’s not retiring after all?!).
Paul is not usually too keen on tech stocks due to valuation but this seems to be a tech company that actually is profitable so looks worth a look. Probably worth looking at competition and how sticky it’s customers are. Market like it so far.
Thanks for flagging. There have been a number of IPOs in recent months - it's hard to keep track of.
I note existing shareholders are selling 92m shares at £2 a pop. Not bad going! £BIG is only raising £14.7m (net of fees) from the IPO, although it has not been floated with a ton of debt. The cash will be used to bolster the Balance Sheet and also to make selective acquisitions which seems reasonable.
One area to watch is the incentive schemes that are in operation and will be created as a result of the float. IPO document talks about this in Part V section 4. There will be a new LTIP scheme. In addition, senior management were awarded "A Shares" on 21 July 2021 in Buddi Ltd (wholly owned subsidiary) which will convert in a maximum of 32.9m BIG shares if the share price is more than £4.45.
Interesting to note Liontrust Investment Partners LLP are a cornerstone investor and subscribed for £60m in shares at the Placing Price of 200p which provide some assurance.
anyone suffering from FOMO from Reach (LON:RCH) ??
Was feeling that too last month so I bought in. Valuation still low IMO
Could be worth taking a look at National World (LON:NWOR) for a company that listed in May that looks to be following a similar strategy with the old Johnstone Press titles such as The Scotsman, Yorkshire Post, Sheffield Star and others.
It's run by David Montgomery who sold his Local World business to Reach in 2015.
yes I like National World (LON:NWOR) too. Bought some at 30p but kicking myself slightly as I was going to get in at 22p a couple of months back but let the trade slide. David Montgomery is very experienced and knows how to run a newspaper house. Also seem to be a lot of sensible small cap investors starting to follow this story.
hi - any view as to why Sosandar (LON:SOS) bounced 10%+ today on over 5x daily volume? Speculative retail investors I guess (not sure how to spot institution action except for RNS). Feels like a bit of a summer 'Roaring Twenties' perhaps, IMHO? (I hold)
I think this is just re-rating as investors start to understand both what's going on in current trading and the future potential. Much as discussed on results day here. Helps that they are now publishing their results call on PI World as more people get to see it. Historically they only did it live so if you missed it you missed it. Current approach is much better.
Anyone heard of In the Style Group? A women's clothing company that listed earlier this year. Market cap of £119m, with sales of £44.7 million (a year on year increase of 132%).
Hi Joeydisco - Paul discussed these yesterday. If you look up their stockreport, then click on the "discussions" tab, you can find when they were last discussed. Hope that helps.
Hi Paul, You mention in your OMTP section above that position size is everything, would you be able to expand further? i.e how do you decide on the initial size and so you monitor as the investment/portfolio changes?
Personally all my purchases start at the same size and are then allowed to run from there, trying to run the winners as long as possible. I don't consider how big the position is relative to the portfolio but this probably isnt the best idea from a risk management perspective?
Hi Paul ,
Thanks for the write up on Onthemarket (LON:OTMP). Like you i think 'there's something interesting going on here'. Whilst it's not a high conviction hold of mine i think the upside far outweighs the downside and would class my position as a 'speculative value bet'.
I come from the world of 'sports gambling' which has been my sole income for 25+ years. If you take a horse race for example i would price up the chances of each horse winning a race as accurately as possible. In the simplest of terms if i priced a horses chance of winning at say 4/1 yet i could back it at 8/1 then i would back it. It certainly does not guarantee that the horse wins but the theory behind it is that if you keep on backing 4/1 chances at 8/1 enough times then eventually you will end up making money. Admittedly, it's a strange concept for some to grasp as you can end up backing horses that you actually don't think will win but their odds make it a value bet.( Apologies for the waffle)
Coming back to Onthemarket (LON:OTMP) whilst there is no guarantee of them becoming a serious competitor to Rightmove i think the odds of them getting there make it a 'value bet'. Their current market cap is £70 million. If in say 3 years it keeps it's current momentum going and hits or exceeds broker forecasts then it could be a '10 bagger'. It's total speculation obviously but i personally would rate its chances of doing so at 10%. There are a whole host of other possibilities here including a very good chance that the share price goes much lower but overall this upside potential is why i hold a small position at this time in Onthemarket (LON:OTMP) and am always looking for other 'speculative vale bets' to hold small positions in.
Best wishes, Cliff
Hi, is anyone able to make complete sense of the update today from Total Produce (LON:TOT), and what it actually means for shareholders of Total Produce today?
I understood from the 17 February announcement that the merger with Dole and subsequent sole listing on the NYSE would result in new shares being issued to existing Total Produce shareholders in the consolidated entity with an equivalent base price of €2.15 p/share. Additional monies would be raised through an IPO, to raise US$500-700m, and a guided price of those was US$20-23 p/share.
Today, Total Produce (LON:TOT) announces that actually the guide price for the NYSE IPO has been dropped to US$16-17 p/share and that various waivers have been given, as well as the result that Total Produce shareholders will own 57.1% of the enlarged entity, rather than the previously given figure of 61.5%. Total Produce shareholders will still receive one share in the enlarged entity for every seven they own.
Clearly, this isn't particularly welcome news and the SP reflects that this morning, but does anyone else understand this better? In particular, is it simplistic of me to take the view that the quoted equivalent based price of €2.15 p/share should actually now be circa 20% lower. No holding as present, but am interested as have owned Total Produce (LON:TOT) previously and am trying to work this is all out.
Sorry for the long post, hopefully of interest to some... All the best, Will
I would second a peek (by anyone really) at Total Produce (LON:TOT) , I think it could be a very interesting food inflation play and I was sniffing around Del Monte before the IPO/merger was announced, however backed up due to complexity.
The GBX price on the London listing seems to basically reflect that $16-$17 pricing, so short term boils down to whether you think the US listing will pop, which looks a bit far fetched given these difficulties, unless retail traders go bananas ;-). Reinforces the long term case though to me (undervalued unfashionable sector). I hold.
Marston's (LON:MARS)
I have been a long term holder here.
Note debt is very high albeit more than notioinally covered by freeholds. Debt is at least mostly longer term bond type debt.
They didn't raise money directly through covid but were presented with an excellent cash offer to kinda sell half their brewing sde to the devli (carlsberg)
That has kept the lights on through coid albeit poart of the crown jewels are gone and they are now aligned with the devil when it comes to beer choices - ouchies !
Although Marstons didn't exactly struggle pre covid - they did spend very heavily to update their very outdated estate of pubs. In theiry about now was when the cvashflow from that investment sghoulkd start bearing fruits - covid has destroyed that plan somewhat. But the devil has kept them at pre covid levels kind of.
I would say in the post lockdown covid near future they could easily still have issues geeing back to they were until such time as everyone forgets. Maybe some will neverr go back to their old lifestill in the next 3-5 years?
Note food figures released today will be massively flattered by temporary 5% vat rate - everyone should bear in mind this is temporary boost to margins that will not last when the vatman gets his extra 12% in the pound spent when vat rates change back to normal.
I have always been happy to stay in for tehn long haul here - although it is a long haul and the high debt probably means this is not a sensible bet for most.
I am also a holder. I bought in last year in the belief that the Carlsberg deal would make them stronger, they were oversold at that point due to Covid uncertainty and that if the hospitality and 'wet lead' pubs really struggled over the next couple of years it would present opportunities to the bigger and stronger chains to buy up good sites on the cheap and expand in a potentially booming future market.
To a certain extent Marstons have already started this when they acquired Brain pubs in March 2021.
I think the trading update today is a little flat and as a regular pubgoer myself I think that Paul has it right in saying there is still a lot of nervousness around. I can only see this potentially increasing as the weather worsens. Every pub I have been to recently has been utilising outside space more than ever and the insides have been virtually empty.
Overall I expect this to be a bumpy ride and potentially more disappointing numbers in the short term but i'm still hopeful that Marstons will be placed better than most in the sector for a strong recovery.
Quite frankly, if they aren't, it will probably means that all of our social lives are well and truly broken for years to come and I can't quite cope with that thought!
Getbusy (LON:GETB) reported this morning. CFO bought some stock on initial weakness. They continue to invest to grow the business. Seeing them later.
(I hold)
Re Tracsis (LON:TRCS)
Just to emphasise MrContrarian's outline (Great work, as ever!), they have announced a contract win which they trailed in their last RNS. Looks they are committing to exceeding market expectations of EBITDA for the year, but do commit the sin of failing to mention what these expectations are.
These were down on the prior year due to impact on the services they provide to large events (managing traffic etc), though perhaps even these are starting to look as if they have slightly more upside as the pandemic ebbs and flows.
I hold
Morning Paul & Jack
A good HY update from EPWIN (LON:EPWN) today.
'Strong trading continues, ahead of previous expectations'
"the Board now expects adjusted profit before tax for the full year to be materially ahead of its previous expectations."
I would be interested to hear your thoughts please?
I have a 1% portfolio position here as a UK value re-opening play, along with a some other similar positions which dovetails well with my mainly high growth approach
Investegate |Epwin Group PLC Announcements | Epwin Group PLC: Half-year Trading Update and Notice of Results
Regards,
Michael
Epwin (LON:EPWN)
I hold , reasonably content holder.
I would say the forecasts were probably there to be beaten anyway as they had 12.7 mill profits pencilled in next year and only 8.7 mil this year - its not a company that is really growing at anything like 40% plus per year. Nice to see that the plans for next year are hopefully arriving soner and that may allow uplift next year - although due to high uplift i am not really expecting anything to change in that regard. In some respects its nice to see that they hid the trading ahead bit at the end of the announcement on this basis.
110p divided by 8.83 epos next yearr = pe of 12.4 - seems reasonable although they do carry a bit of debt that probably warrants some sort of discount.
Slightly disappointed that their prices increasing lag the price increases they have to suffer. I would like any company to be on point passing price increases. Particulalry at present customers arre probably happy just to get their kit. Perhaps they have some fixed price contracts or the quoting to delivery timeframe is such that its not easy to factor in increases - the trick is to see the future price rises coming here i guess. No biggie happy cuystomers is probably more important that anything i guess.
I guess the future direction will depened on whetehr this company can remain in its sweet spot with regard to what it does. Management seem to be doing fine in that regard at present.
Epwin (LON:EPWN)
Ok looks like comments from zeus updated note include the following
The strength of trading in the first seven months of the year lead to an 11% upgrade in revenue and a 17% increase in profitability to £12.9m (prev. £11.0m). Raw material and cost input pressures lead to more conservative increases to FY22 and FY23 profitability.
Ok nice upgrade to this year but as expected muted expectations with regard to 2022 and 2023 uplifts - at present any upgrade at all for next year is pleasing however modest.
@rmillaree Epwin (LON:EPWN)
Thanks for your effort and replies.
Hoping they will continue to get busier and can take advantage and increase prices, reduce debt....
Good morning Paul! You say "This is not a value share, so may not appeal to SCVR readers." I would classify myself as a growth investor, and I am an avid reader of the excellent SCVRs that you & your colleagues produce. It could be that your readers follow a wider spectrum of investment approaches than you might think. On the other hand, one could say that the there is a clue in the title "Small Cap Value Report" Even so, growth shares are discussed, so perhaps the title should be changed to "Small Cap Report" or "Small Cap Investment Report". What does everyone else think?
The SCVR name seems right to me, even for growth investors. If you don't think a growth share is good value, why buy it?
I think we just like the name SCVR, and everyone's used to it. I suppose by implication "value" includes GARP (growth at reasonable price). Let's not over-complicate things :-)
How about Small Unloved Company Investment Tutorial
SUCIT
"may not appeal".
I think he's hedging his bets here, he knows there's loads of "growth" investors here and Paul has brought to our attention stocks like Boo and Sos that don't fall into the traditional "value" bracket (though Paul did often highlight Boo PEG < 1 which is a value measure of a sort in my view).
I like the SCVR name, it doesn't strictly mean we only comment on 'value' stocks (a subjective term in its own right), but we can assess the value of any small cap.
"Small Cap Value Report" Even so, growth shares are discussed, so perhaps the title should be changed to "Small Cap Report" or "Small Cap Investment Report". What does everyone else think?
I think the name as it is now is perfect
How about Small & Smallish Cap Report. SSCR, wouldn't this sit better?
It depends how you define value. For me value is not just low PE or P/B stocks, but anything less than its intrinsic value based on future cashflow - that could include both low and high PE stocks. So a growth stock can also represent good value.
As Charlie Munger said “All intelligent investing is value investing.”
Like to think we are all intelligent investors here :-).
Angle (LON:AGL)
A second major contract announced today. Seems they will be paid to develop and use the assays but will retain ownership.
As part of the contract, ANGLE will develop the two assays to detect the target proteins in four hard-to-treat cancers: triple negative breast cancer, prostate cancer (including metastatic and/or castration resistant), ovarian cancer (including high grade) and pancreatic cancer. The assays will be developed in ANGLE's UK R&D facility before being validated in ANGLE's clinical laboratories.
Once developed, the new assays will remain in the ownership of ANGLE and be added to ANGLE's menu of pre-developed tests that can be offered to other pharma customers.
They are in ongoing discussions to develop further assays for the same company.
Thanks for that on Angle (LON:AGL) JimMcLad. Angle (LON:AGL) needs to keep making progress in alternative directions like this until the anticipated/hoped for (delete as inapplicable in your mind!) FDA approval later this year for breast cancer (the statement by the company some time back was 'second half of calendar 2021').
That should be the first of many applications to the FDA in the coming periods since the Parsortix system has multiple research centres of the highest renown reporting its value for numerous cancer
conditions.
Not everyone has the confidence you and I have since the price till today had fallen from 135p at the last fundraising to around 106p or thereabouts, a big fall given that little or nothing had changed.
That's the market I guess, though if you have a large holding, it can have a big effect on your portfolio's overall paper profitability! Angle (LON:AGL) keep the supportive announcements coming until the FDA big day.
More good results from Oakley Capital Investments (LON:OCI) this morning. NAV now at 445p (current SP is 351p), an increase of 11% in the past 6 months. NAV CAGR in the last 5 years is now 17.4%. What I think is always worth remembering with OCI is that their valuations tend to be conservative, with an average 44% uplift on realisations since inception (which, in my mind, makes the large discount to NAV unreasonable / a good buying opportunity). I believe there is a presentation on InvestorMeetCompany tomorrow. I hold.
Here's a link to the RNS which isnt appearing in Stocko for some reason.
1200 tomorrow IMC. Agree with your thinking. I hold. Better than chasing £BPT !
Thank you, gwilli68, for the information on Oakley Capital (OCI) which I hold. I saw the NAV figure on my folio page but no accompanying statement. I am unsure why, but the Stockopedia provider does not always update on investment trusts. If you are interested, Liberum Capital has provided a research note today on the ResearchTree website. The analyst is forecasting a December 2021 NAV of 481p, implying a discount of around 27% based upon the current share price.
Kind regards
Phillip
Oakley Capital Investments (LON:OCI) is a big holding for me, on the basis of a rationale outlined below in an Investment Trust thread:
https://www.stockopedia.com/co...
I think today's update is good.
By my reckoning they are currently on a 25% discount to NAV (excluding cash). Cash is 90 pence per share at present. So it's a big discount to NAV.
Final Results from Hargreaves Services (LON:HSP) are quite bullish. At first read the bulk of their profits has come from their German joint division. Plus a nice additional divi of 12.0p. Paul - any thoughts?
https://www.londonstockexchang...
My morning smallcap tweet, always scraping the barrel of opportunity.
Tracsis (LON:TRCS) Grafenia (LON:GRA) Hargreaves Services (LON:HSP) Esken (LON:ESKN) GYG (LON:GYG) Trifast (LON:TRI) Diurnal (LON:DNL) Epwin (LON:EPWN) Crossword Cybersecurity (LON:CCS) Staffline (LON:STAF) Angle (LON:AGL) Marston's (LON:MARS) Shearwater (LON:SWG), Trifast (LON:TRI), Pebble Beach Systems (LON:PEB), VR Education Holdings (LON:VRE), Quartix Technologies (LON:QTX)
Tracsis (TRCS) guides FY EBITDA above market expectations. Cites today's large contract win, ongoing growth in Rail Technology & Services and Data Analytics/GIS and a post Covid recovery in business activity levels in our Traffic Data and Events business units. [SP=942 Cap=276m]
Graphenia (GRA)FY(Mar). Outlook - "Trading has improved and the first quarter finished ahead of last year. July started well and should be our best month since September 2020....With our new cost base, modest increases in revenue will improve profitability" [SP=6.5 Cap=7m]
Hargreaves Services (HSP) FY(May) in line with EPS 50.8p (13.4p). Final div 4.5p + 12p special. Outlook includes "HRMS joint venture has the potential to deliver substantial shareholder value in the next few years. The Board considers it likely that HRMS would benefit in due course from being part of a larger, more specialised business and it plans to explore strategic options for HRMS." [SP=478 Cap=154m]. I hold.
Esken (ESKN) raised £55m at 14p, a 37% discount, the bottom of last night's indicated range. [SP=22.25 Cap=140m]. I hold.
GYG (GYG) emergency €3m 10% secured loan taken due to delay in resolving matters with administrators of Nobiskrug Shipyard. Still in offer talks. [SP=86 Cap=40m]
Tricorn (TRI) cash crunch due to continued pressure on operating costs, margins, overdue debts and working capital. "Whilst the Group's principal lending bank is expected to remain supportive, certain restrictions on these facilities are being imposed. It is expected that such restrictions would be eased in the event of a successful sale of one or more of the Company's operations or an injection of funds." [SP=140 Cap=190m]
Diurnal (DNL) guides FY(June) rev down 20%. [SP=60.5 Cap=102m]
Epwin (EPWN) guides FY(Dec) pretax materially ahead of mgmt expectations as H1 rev is up 13% on 2019. [SP=107.7 Cap=156m]
Crossword Cybersecurity (CCS) £5m placing at 30p, a 23% discount, to fund acquisition of a threat intelligence and monitoring services company. Also to increase sales and marketing resource and for product development and support. [SP=37 Cap=21m]
Staffline (STAF) guides H1(June) rev up 5%. [SP=58.2 Cap=96m]
Angle (AGL) wins contract to develop immunofluorescence assays using its Parsortix system. Worth $400k in phase 1. [SP=106.94 Cap=250m]
Marston's (MARS) trading since 17 May better than mgmt exp. [SP=83.55 Cap=530m]
Shearwater Group (SWG) FY(Mar) rev down 4%, U/L pretax £2.4m (£2.2m). U/L EBITDA 3.7m (£3.4m) is ahead of market expectations. [SP=175.27 Cap=42m]
In line: Trifast (LON:TRI) Pebble Beach Systems (LON:PEB) VR Education Holdings (LON:VRE) Quartix Technologies (LON:QTX)
RE: Tracsis (LON:TRCS)
There's an "exceed market expectations" statement at the end of the contract win announcement from Tracsis today:
As a result of this large enterprise licence win, ongoing growth in Rail Technology & Services and Data Analytics/GIS and a post Covid recovery in business activity levels in our Traffic Data and Events business units, we are now expecting full year EBITDA for the Group to exceed market expectations.
The traffic data and events business was essentially shut down by the pandemic so the recovery there was predictable, but dependent on the timing of easing of restrictions.
timarr
Hi Paul, Would appreciate your thoughts on £GETB. Thanks.
Any thoughts on the number of average shares jumping 22% in the last year? Also, the profit estimate for 2023 is half 2022's figure. It's a falling star on Stockopedia.
Morning Johnsy,
Any thoughts on the number of average shares jumping 22% in the last year? Also, the profit estimate for 2023 is half 2022's figure. It's a falling star on Stockopedia.
Which company are you referring to please? If you don't put in the name/ticker, it confuses people.
Thanks, Paul.
Paul - re Johnsy's post - I posted yesterday that:
It would be helpful if you could restore the last para of the 'Explanatory Notes' at the head which used to read:
It's helpful if you include the company name or ticker within reader comments, otherwise some readers may not be aware of what company you are commenting on.
Jack replied "We can certainly put it back in, I hadn't realised it had dropped out somewhere along the line!"
sharw, yes I saw that, and did adjust the "explanatory notes" section today accordingly.
Just a heads up but its the 28th today !
Thanks mark1308, I'm not very good with dates, especially when trying to predict the next day, as copy/paste is too tempting. Have corrected it now ;-)