Small Cap Value Report (Weds 28 Oct 2020) - SHOE, SLP, TRB, SAA

Good morning, it's Paul & Jack here, with the SCVR for Wednesday.
Timings - should mostly be done by official finish time of 1pm. Let's revise that to 5pm, there's a lot going on in the markets that is distracting me, sorry about that. Today's report is now finished.
Agenda - this is what has caught my/our eye(s) today. Jack has come up with an idea for he & I to collaborate on file sharing in google docs, so we can both contribute sections to the same article. We’re testing that out today, let’s see what happens!
Shoe Zone (LON:SHOE) - I hold - as discussed in the reader comments below, a full year trading update
Sylvania Platinum (LON:SLP) - this section written by Jack - Q1 Report
Tribal (LON:TRB) - Trading statement - looks positive
M&c Saatchi (LON:SAA) - Half year report
.
Shoe Zone (LON:SHOE)
Share price: 38p (down 16% at 10:36)
No. shares: 50.0m
Market cap: £19.0m
(I hold)
Shoe Zone PLC ("Shoe Zone") reports on trading for the 52-week period to 5 October 2020 ("FY20"), prior to entering its close period.
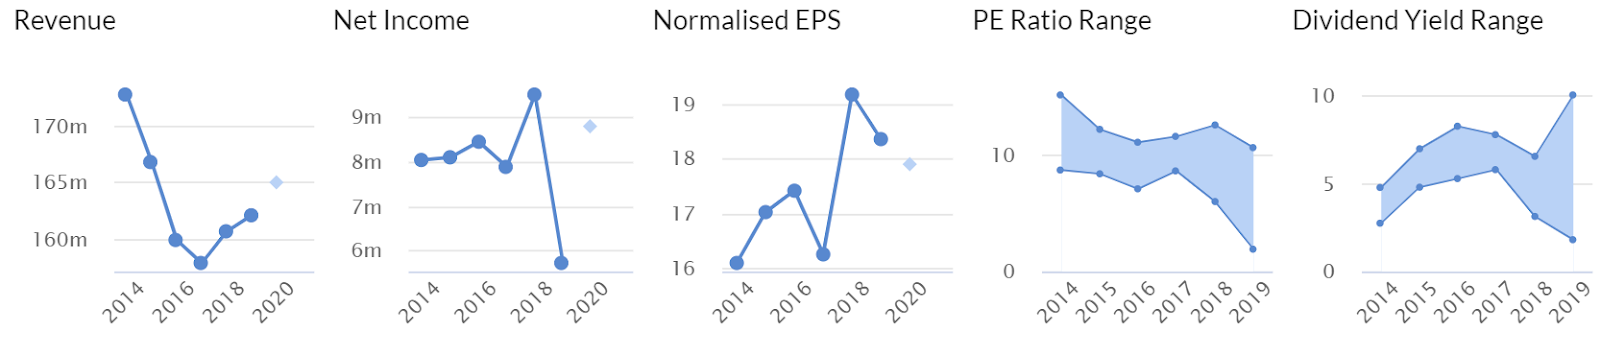
Preamble - It’s remarkable to see the market cap of Shoezone down to only £19m, given that this business used to consistently make £8m+ profit per year, and paid out generous divis. It has entrepreneurial management, Anthony & Charles Smith, who together own 50% of the business. Its leases are short, and fit-out costs are low, so it actively manages the store estate, avoiding the long tail of loss-making sites that plagues (and often destroys) other retailers. Product is cheap & cheerful, and is manufactured in China.
The light blue blobs below look outdated forecasts, so ignore those. Otherwise you can see that, in normal circumstances, this is a decently profitable business. The big question is, can it survive, and recover from covid/lockdown? IF it can, then buying now could lock in a wonderful future dividend yield, and capital appreciation too. If not, then the company could end up going bust, or being taken private for a song.
.
.
I’ve just re-read my notes from 23 June 2020, covering SHOE’s interim results to early April 2020. I concluded that liquidity looked OK, so insolvency risk seemed low back then. Lease liabilities on the balance sheet were higher than I’d imagined, which didn’t seem to tie in with management comments that leases are short term.
Shoe Zone PLC ("Shoe Zone") reports on trading for the 52-week period to 5 October 2020 ("FY20"), prior to entering its close period.
H2 “challenging”
Store trading since reopening in June has been broadly 20% down year on year with digital trading broadly 100% up year on year. While the latter is encouraging, it has not filled the deficit from store sales.
Recent Govt lockdown guidance, etc, is hurting sales, especially in tier 2 & 3 areas
FY 09/2020 is going to show a hefty loss. This is worse than I was expecting. Remember this would also be after receiving the benefit of furlough, and business rates relief in H2;
Shoe Zone generated revenues for the period of approximately £122.6 million (2019: £161.9m). As a result of the closure of its retail estate from 23 March 2020 to 15 June 2020 owing to the COVID-19 pandemic, Shoe Zone expects to report a loss before Tax for the period in the range of £10.0 million to £12.0 million.
Liquidity looks fine, because the company has a good sized Govt-guaranteed loan, hence the gross cash available would be a lot higher than the net cash below;
Notwithstanding the challenging trading conditions, Shoe Zone closed FY20 with a net cash balance of £6.3 million (2019: £11.3m). No dividend will be paid in relation to FY20 as debt repayment is now being prioritised by the Board… The Board does not anticipate Shoe Zone will be in a position to restart a dividend policy until at least the 2024/25 financial year.
This makes sense in the circumstances;
Shoe Zone ended the year with 460 stores, having opened 10 Big Box stores and closed 40 stores during the period. At the year-end 50 Big Box stores were trading. All future new openings are on hold until trading conditions improve whilst a small number of essential relocations will happen as needed.
Outlook - good to see management confirm the business is funded enough to survive.
"Shoe Zone has ended an incredibly challenging year with a robust plan and sufficient funding in place to ensure the future survival of the business. The exceptional growth in digital sales since the start of the COVID-19 pandemic demonstrates the flexibility of our operating model, and follows the decision to create an autonomous Digital department in 2019. However, it is very difficult at this stage to provide meaningful guidance on the future outlook, given the material uncertainty in the wider economy.
Business rates - the company makes the point that reintroduction of business rates from April 2021 will be devastating for the High Street. It would trigger SHOE closing a total of 90 shops by March 2022.
I think it’s absolutely right that retailers lobby the Govt hard over business rates. It would be counter-productive to re-introduce it, and I think the Govt should seriously look at abolishing it altogether, perhaps to be replaced with a hike in VAT that would be fairer being paid by physical and online retailers equally.
I can feel a letter to my MP coming on. I use a terrific platform called WriteToThem which makes it quick & easy to write to your elected representatives. We seem to have a particularly clueless/flexible (delete as you wish) Government, which seems to work on the basis of floating policy ideas through leaks, and then backing down or reversing strategy when there’s a public outcry. I quite like that, as nobody really knows what to do re covid, hence being flexible/pragmatic is surely the best approach? Also it means that writing to your MP is actually worthwhile, because they are listening, and you could help guide policy. I’ve written to my MP several times, about more support being needed for the arts, and for the beleaguered hospitality sector, and policy was changed to give both sectors more support. So plenty of other people must have done the same. They say that for every 1 person who bothers to write, 100 others agree but don't write. Hence one letter effectively magnifies your view/influence 100 fold.
My opinion - I agree with a reader comment below, that the trading since re-opening figures actually look quite good in the circumstances. Also I like the confirmation that liquidity is still adequate to ensure survival of the business. SHOE went into this crisis with a strong balance sheet, and plenty of cash. Therefore it should survive & recover, unlike many other retail/hospitality businesses which entered the crisis with existing debt, and no cash reserves. Nobody knows what the future holds, that’s why it is so important for companies (and households) to have some money tucked away for a rainy day. People used to scoff at such a notion being old-fashioned, or inefficient. They’re not scoffing now.
My one reservation with SHOE, is why the loss is going to be so large, at £10-12m. Although I wonder if that might include some non-cash write-offs (e.g. onerous lease provisions, writing off fixed assets, etc?). The update today is not clear on that.
I agree with reader comments that this update seems to cut a deliberately negative stance. Maybe that is to help increase the company’s leverage in lease negotiations? Or maybe a precursor to a cheeky lowball takeover bid? I hope not. My feeling is that, once a company floats on the stock market, then management have a moral responsibility to stick at it, and work hard to recover things from any setback, not grab the future upside for themselves with a buyout at the lows. But we’re speculating there.
Overall, I’m happy to hold, and might top up on any further weakness, but I don’t see this becoming a large position in my portfolio. It’s small at the moment, and might become medium, but no more than that, as my conviction on it is not particularly strong.
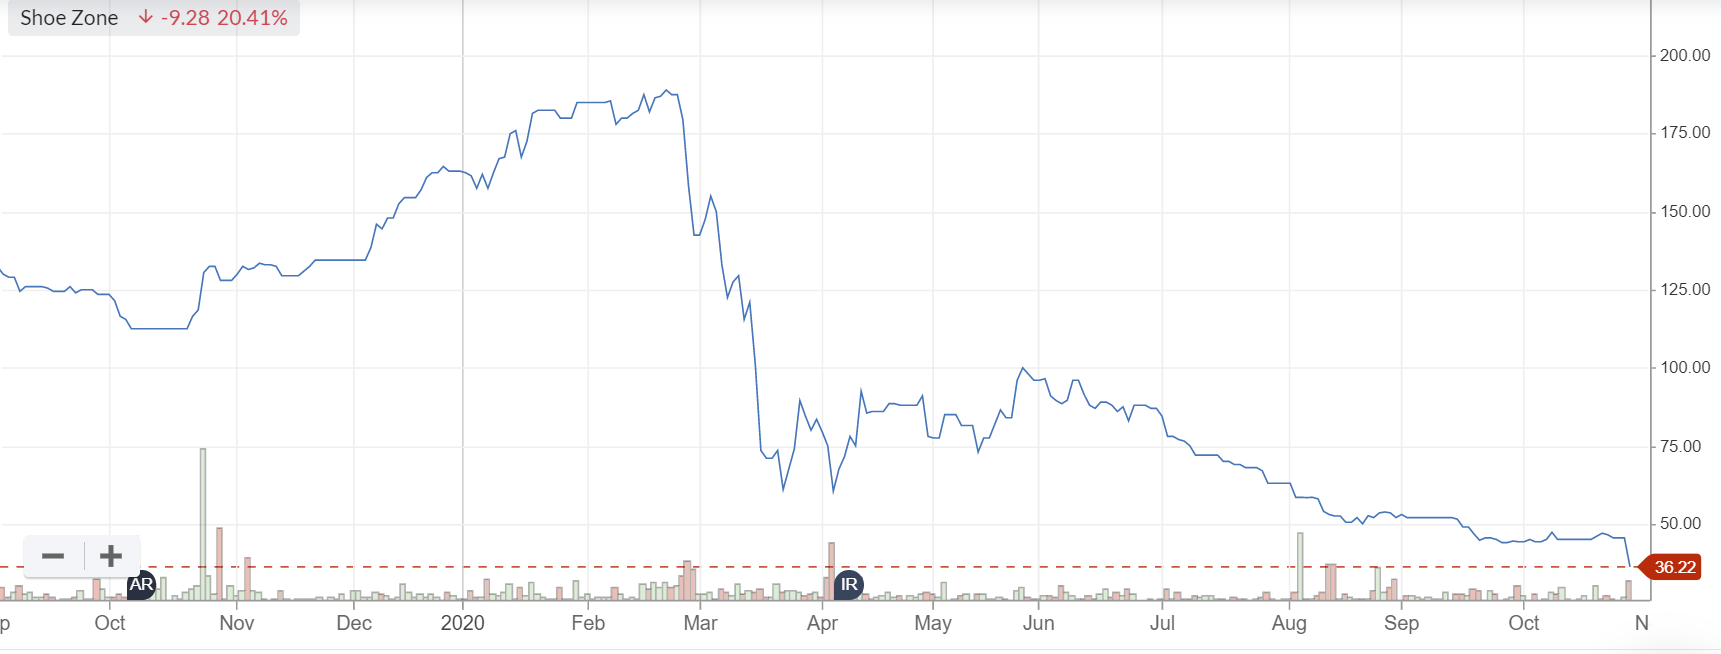
Has the share price overshot to the downside? Quite possibly, in my view, given that trading should recover at least somewhat in 2021, and there doesn't appear to be any insolvency risk. Therefore as a recovery situation, I like the look of this, at 36p. I can foresee 100% upside on that price, once the market becomes more upbeat about covid/economic recovery. That's appealing, if I'm right. Maybe I should be buying more? Can't decide at the moment, I'll have a think about that.
.
.
** This next section written by Jack Brumby **
Sylvania Platinum (LON:SLP)
Share price: 68.33p (-2.11%)
Shares in issue: 271,476,690
Market cap: £185.5m
(Jack: I hold)
Sylvania Platinum (LON:SLP) is a low-cost producer of platinum group metals (PGMs) with dump operations and exploration assets in the South Africa Bushveld Igneous Complex. If you believe that PGM spot prices are set to appreciate, or are even just sustainable at current levels, then the company’s shares are cheap.

Sylvania understands this and has been diligently buying them back.
Today it reports its First Quarter results.
Running through the headline figures:
- Sylvania Dump Operations declared 17,972 4E PGM ounces in Q1 (Q1 FY2020: 20,797 ounces)
- $41.5m of net revenue (Q1 FY2020: $31.2m)
- Group cash costs per PGM ounce down to $652/ounce
- Net profit of $21.0m (Q1 FY2020: $12.5m)
- Cash balance of $60.9m, up $5m quarter-on-quarter
Operational challenges
The global COVID-19 pandemic is a concern but the country remains in Level-1 Lockdown which does not hinder production. This could always change though, as we’re seeing in the UK currently.
Reduced mining operations at some host mines due to the depressed chrome market are leading to lower PGM feed grades and recoveries. This was flagged in a previous update. That update did note some asset writedowns as well but there is no further mention of that in today’s RNS.
Opportunities
Risks remain, but SLP is in such a cash generative position that it has been able to progress its growth capex initiatives while buying back shares. In particular:
- The new Lannex mill and spiral upgrade project is ongoing;
- Design of Lesedi secondary milling and flotation module to is advancing;
- Mooinooi chrome processing modifications and optimisation project is in execution phase and expected to commission during Q3.
Commenting on the Q1 results, Sylvania's CEO, Jaco Prinsloo said:
We anticipate to reach our estimated production target of approximately 70,000 ounces of PGM's for the year. The Company continues to enjoy the benefits of the strong PGM price environment and the 31% increase in gross basket price from Q4 has assisted in boosting our financial performance and cash reserves. The Company remains in a robust financial position with sufficient cash reserves to fund capital projects which will help mitigate any rise in costs and the possible reduction in future cash inflows due to the ongoing uncertainty relating to COVID-19.
Conclusion
Sylvania remains debt free and continues to maintain strong cash reserves, which provides a decent margin of safety. The $60.9m of net cash equates to roughly £45m at current exchange rates, which is about 24% of the market cap.
The share price has recovered well from its last update, which ruffled some feathers due to a lower-than-expected dividend payment. I’m not here for the dividends though. If the share price really is as cheap as it looks then the company is right to be buying back shares instead.
And building up the cash cushion, now more than ever, seems prudent.
Risks remain. The reduced mining operations of certain host mines continues to impact on feed grades and Q1's PGM production decreased 14% year-on-year. This is something to monitor going forwards. There have also been issues with water access and energy supply to its sites in the past.
There is always the big unknown of the PGM spot prices. That’s probably the most important factor in the whole investment case, so you need to take a view here. Mine is that current prices will be at least maintained due to structural demand factors but others may disagree on this point.
In my view the valuation continues to compensate for the risks involved and I’m holding for a sustained rerating.
The near-return to historic levels of production is a creditable performance in light of the COVID disruption and government-imposed industry shutdown faced by this miner earlier in the year. The brokers are targeting 100p+ and, given the low valuation metrics, that doesn’t seem unreasonable to me assuming spot prices are at least maintained and there are no further operational disruptions.
.
Tribal (LON:TRB)
Share price: 70p (up 8% today, at 12:20)
No. shares: 205.7m
Market cap: £144.0m
Tribal (AIM: TRB), a leading provider of software and services to the international education market, today provides an update on trading for the year ending 31 December 2020 ("the Year") and information regarding the reinstatement of the dividend.
As a result of the uplift in revenue from the two new contracts, the ongoing benefit of cost reduction measures introduced at the start of the COVID-19 pandemic, the increased efficiency of the remote delivery of Professional Services and Education Services, and the strength of the Group's recurring revenue model, the Board now anticipates reporting profits for the Year comfortably ahead of current market expectations(1), at approximately £14.8m adjusted EBITDA(2) and £11.5m adjusted EBITA. Total revenue is expected to be in the region of £72m. Annual Recurring Revenue has increased to £44.5m.
(1) In so far as the Board is aware, prior to this announcement, market expectations for the year ending 31 December 2020 were for revenue of £72.1m, adjusted EBITDA of £13.7m and adjusted EBITA of £10.5m.
(2) Adjusted EBITDA is in respect of continuing operations excluding restructuring costs, share based payments and amortisation of acquired (IFRS3) intangibles.
Thank you to the company & its advisers for the footnotes, informing us what market expectations are. This is incredibly helpful, and everyone should be doing it. I’m told that some old-fashioned brokers push back against doing this, which is harming their clients’ interests. Transparency helps us understand the company, and makes us more likely to buy its shares. Why do I need to explain that, it should be obvious?!
Personally, I find EBITDA meaningless for software companies, due to internal development costs being capitalised. TRB capitalised £3.2m development costs in H1 alone, so very material. That’s fine to capitalise development costs, but we have to reflect those costs somewhere when we value the company. EBITDA ignores both current & historic development costs altogether! Which clearly is nonsense.
Therefore I use adj EPS instead, a much more meaningful figure to use in valuing software companies. My thanks go to N+1 Singer, which has kindly made available an update note today on Research Tree. This reflects today’s positive update, with FY 12/2020 EPS forecast now at 4.6p (up from 4.3p in 2019) - not many companies are growing 2020 earnings over 2019, so that’s impressive.
The PER is 70p/4.6p = 15.2 - that’s not expensive at all these days, for a software company with strong recurring revenues. Also the broker indicates further upgrades could be in the pipeline if trading momentum continues.
Balance sheet - is actually quite weak, with negative NTAV. However, like a lot of other software companies, it has a favourable working capital setup, where customers typically pay up-front, therefore it can operate with a decent cash pile, despite having negative tangible assets overall.
There is an argument for regarding software development costs as a genuine asset. We were discussing this the other day. Conventional businesses buy machines which are long-use assets, and capitalise them. Whereas IT companies spend on intangibles by paying developers to produce code, which they then sell as a service, so these costs are capitalised. That’s one way of looking at it.
I understand that point of view, but to my mind, anyone who is on the payroll, should have their salary expensed through the P&L, whatever they’re doing! Also, I see development costs as an ongoing cost of running an IT business. If you stop product development, then the company will go into run-off, and slowly die as competitors overtake.
Current liabilities exceed current assets, for example, so people need to be aware of that too - i.e. even if you want to keep some intangibles on the balance sheet, which would make NAV positive, there’s still a shortfall on working capital, with the net current liabilities position. It’s OK, not a problem, I’m just pointing out that by several different measures, this is not a strong balance sheet.
So instead of claiming to have a strong balance sheet, the company could be more accurate perhaps by saying we know we’ve got a weakish balance sheet, but it doesn’t matter because of inherently favourable working capital flows. That’s nearer to the truth, in my opinion.
The Group retains a strong balance sheet, with a net cash position as at 23 October 2020 of £11.2m. The positive trading has enabled the Group to repay all furlough benefits received (approximately £80k) and all temporary tax deferrals.
So liquidity is fine.
I’m labouring the point here, let’s move on!
Dividends - Tribal is reinstating the divis, with a flat against last year interim divi of 1.1p - not earth-shattering, but it’s an important signal of confidence, and that there’s cash available.
Outlook - I like the sound of this;
"Our priorities for the remainder of 2020 are to continue to protect the business from the impact of COVID-19, win new customers, retain and grow existing customer relationships, and deliver on the Tribal Edge strategy.
"Never has the need for cloud-based solutions for the Education market been more pressing. The investments we have made position us at the forefront of this evolution in our industry, providing for an exciting future for Tribal."
.
My opinion - this is a very good update, considering how covid has impacted the education sector.
I think the valuation looks reasonable, cheap even, if good momentum continues.
This company has never really caught my imagination before, because performance was patchy, and it seemed accident-prone, e.g. that big legal action it ended up with not long ago.
However, today’s update sounds like something more positive is going on under the surface. Winning new customers, offering a cloud product, developing ways of installing it remotely, etc, this all sounds very impressive, and very relevant to the modern world. That you can buy the share on a PER of about 15 now, seems a good deal. Somebody might bid for it.
I’d prefer a stronger balance sheet, but am prepared to ignore that, given that the company is trading well, and has a good outlook.
Therefore I can feel myself turning positive on this share, because the fundamentals and outlook are now looking a lot better than when I’ve looked at it in the past. For that to be happening during covid, is impressive.
Therefore Tribal gets a thumbs up from me. Not a recommendation, as always, just my personal opinion. Over to you, to do your own research on it.
.
M&c Saatchi (LON:SAA)
Share price: 58p (suspended since 1 Oct 2020 due to late accounts)
No. shares: 115.4m
Market cap: £66.9m
This is a very unusual situation, in that the company is publishing its 2020 interim results, but hasn’t yet published its audited 2019 results, due to problems with the audit. It said 2019 accounts would be published “within weeks” on 30 Sept 2020, so hopefully these will be imminent.
I’m struggling to understand how they can publish 2020 interims before they’ve agreed the starting balance sheet with the auditors from the previous accounts. I’m very wary of all situations where something has gone wrong with the accounts, because often it can be a lot worse than originally disclosed (Staffline, Patisserie Valerie, Conviviality, and many others, especially overseas companies on AIM, although the UK ones are often not much better!)
I last covered SAA here on 27 Aug 2020, where I thought it looks potentially interesting, based on a small underlying profit for H1 being in the pipeline, new business wins strong, and a comfortable liquidity position with net cash of £20.0m.
Interim results for the 6 months to 30 June 2020 - clearly this covers the worst of the original covid lockdown, so figures are likely to be poor.
These look OK in the circumstances;
- Revenue down 13% to £103.4m
- Headline profit before tax of £2m before exceptional costs, down 59%
- Costs cut - being a people business, it should have a fairly flexible cost basis - although expensive London offices might be a problem now?
- Current cash position looks healthy;
- £28m at 20 October 2020
- No divi
Outlook comments - very clear guidance here;
Current trading and outlook
· Positive trends have continued into H2, although there remains considerable uncertainty due to the ongoing Covid-19 pandemic
· The Group's clients and revenue are heavily weighted towards resilient industry sectors, such as government, e-commerce and financial services
· Revenues expected to be marginally stronger in H2 than H1 with 2020 full year headline PBT, excluding exceptional items, expected to be at least £4m
· 2020 year end net cash expected to be at least £10m
· Full year operating costs expected to be approximately £30m lower than 2019 as a result of restructuring, the majority of which are expected to be ongoing cost savings
· The Group is in the process of exiting from companies that are expected to generate combined losses of £5m in 2020, with divestment or closure expected to be completed before the year end
Put Options scheme - this is rather confusing, but it seems to be a form of bonus/deferred consideration, payable in shares, which now looks potentially problematic.
There’s an explanation in note 13;
The Company has experienced a significant decline in its share price since 2019, from a peak of 394p per share in March 2019. In many of the share schemes, the consideration is calculated at a fixed multiple of the relevant subsidiary Company's profits - this is effectively a deferred consideration model used by the Company for acquisitions. The consideration is typically paid in shares of the Company, with the result that as the Company's share price has fallen a greater number of shares are needed to be issued as consideration under the schemes. This has a very significant dilutive effect. It is important to note that no transactions have been structured in this manner for several years and no transactions will be structured in this way in future.
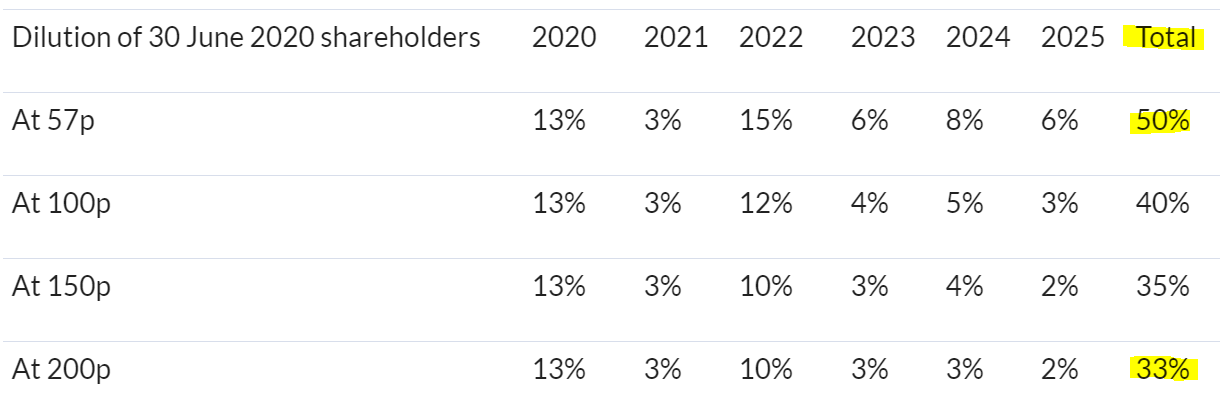
OK, I’ve got my head round this issue now. This table below is the base case scenario, and shows the % dilution of existing shareholders, from the issue of shares that the company is committed to, as reward schemes for management relating to acquired subsidiaries.
As you can see, the dilution is very substantial, even if the share price were to recover strongly from its current 57p level.
Another table is provided, which shows a mitigated case, where the company is negotiating with holders of these put options, to try to get them to move to cash bonuses instead.
.
.
This looks a bit of a disaster for existing shareholders, who look set to be substantially diluted. The table doesn’t show the worst case scenario either. If the share price really collapses, then the dilution could become ruinous. I note their table assumes that the share price won’t go any lower than the current (suspended) level.
Balance sheet - some quite large numbers in here. NAV is £57.1m, less intangibles of £38.7m, gives NTAV of £18.4m.
The minority shareholder put option liabilities seem to have greatly reduced on the latest balance sheet, compared with last year, which I don’t understand given the large dilution that seems to be in the pipeline from these liabilities (payable in shares).
My opinion - definitely too complicated for me to want to get involved.
Whoever dreamed up & agreed to the put option schemes clearly didn’t think it through, and it’s now blown up to be a major problem - with potentially large dilution of existing holders.
If there was no put option problem, then this share would look quite interesting. However, the numbers in note 13 of large dilution in the pipeline, is a major worry, and justifies a big share price discount.
Therefore when looking at this share, it’s vital that people include the dilutive impact of these new shares which could see the share count rise by c.50%, or even more, if the share price falls a lot lower.
It all looks a mess, and puts me off wanting to buy any SAA shares, once it comes back from suspension. Maybe they’ll get it all sorted, but that might involve having to make substantial cash payments instead, to persuade holders of the put options to give them up?
.I've run out of time for today, so sorry I didn't get round to looking at Redde Northgate (LON:REDD)
See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Ft HAVE published new article on Boohoo (LON:BOO) that quotes and summarises Levett report. It is not a picture of a well run machine over there....
"new" LOL!!!!
It was all published in full here, previously. A report commissioned by BOO.
https://www.boohooplc.com/sust...
Old news, re-hashed over & over again, by journalists desperate for page impressions.
BOO is a shockingly badly run group, as the figures below demonstrate. Why on earth would anyone want to invest in this?!
Boohoo (LON:BOO)
I thought the linking of the article was useful - most bods won't have read the full report so no harm in having specific points re-flagged that may have been glossed over as part of the summay picture. The report does highlight the somewhat chaotic nature of how the supply chain used to be - as far as doing bare minimum to avoid any issues with regard to hmrc statutory vat obligations i would say that is something of a spectacular fail - probably not so much of an issue if there are no fraud signals but there deffo are here - and it should be plainly obvious they are almost certain to have neafarious suppliers if they are dealing with 500+ local suppliers. Note i have held boo previously and would hold again so i have no particular axe to grind against boohoo.
https://www.gov.uk/government/publications/vat-missing-trader-fraud
Although not today's news, readers may be interested in looking at Inspiration Healthcare (LON:IHC) a small cap in the healthcare sector with what seems to be a global reach and patents backing them up. They seem to have eventually turned a corner after years of sideways movement. I took a position today after all the steam of yesterdays spike had settled down.
Although they have benefited from some one off covid related sales, their non-covid growth via both organic and acquisition led activities seems to be giving them the catalyst to get some proper SP movement. The balance sheet has had a spike of intangibles presumably as a result of the acquisitions, but they are sitting on net cash so I'm not too fussed about that. They have now broken through a level of persistent technical resistance. If you have access to Research Tree I'd recommend having a read of the recent broker notes. DYOR
This Share is not for me. It has had a recent surge in volume and often when Simon Thompson of Investors Chronicle (IC) publishes a subscribers only report there is enhanced chat on Stocko forums / LSE etc and thus the share price. This share got my attention a few days ago from IC but I will not be investing as it does not pass my screen.... I.e. ROCE to low, yield to low, operating cash flow yield to low, F-Score to low. Be wary of moving with the sheep as recommendations from magazines are often more wrong than right in my experience. E.g. JOG & LIT & Rosenblatt was recommended and look at the state of them. Go solely from multiple sources.
This Share is not for me....
I'm sorry but these kind of posts are infuriating. What effing share!!!! Surely it's just as easy to type the name of the company than "This Share"!? I don't know how many times Paul and others have to ask before the penny drops. I worry about the intelligence of some contributors. Please make clear which company you are referring to.
Si
Christ man it's a reply to a thread. Change the box to 'threaded'. Do I have to regurgitate everything from the OP of the thread????
Christ man it's a reply to a thread. Change the box to 'threaded'. Do I have to regurgitate everything from the OP of the thread????
So you have problems with basic comprehension too. Just name the bloody share for those people viewing unthreaded or using the old site. The onus should always be on the writer to make clear what company they are talking about in a post, not the reader. I imagine most people like me just ignored your post rather than go to the trouble of finding what company you were talking about.
Put it this way, it says 'in reply to' right in front of you which is an instant identifier of a conversation. Do you often jump into conversations when the full picture is not clear to you and risk embarrassing yourself / being irrelevant? Adding the ticker should definitely be mandatory in an OP or mention of a new company in a reply. Otherwise I simply do not agree with this policy.
The only issue with that is if the person you are replying to has not put the share then you don’t know what the share is unless you go back to the previous post they are replying and so on, sometimes it is still not clear what the share is. I have given up on a few and so has Paul.
Put it this way, it says 'in reply to' right in front of you which is an instant identifier of a conversation.
It actually says in reply to user, users may have made multiple contributions and so it instantly identifies nothing. Furthermore people reading these comments may do so in different ways, In an ongoing post we may save time by just looking at new or recent comments, in a historical post we may use threaded display to try and follow sub-conversations.
This is not a new problem and it is a long established convention that when responding to threads it is considerate to include enough context so that it is clear what exactly you are replying to (see above). This saves others from having to read or reread old posts just to make sense of yours. Quoting everything became as poor netiquette as quoting nothing. Again, just because you have just read something just before replying doesn't mean that others will have done the same when reading your piece.
The issue this clearly demonstrates is that we need to be able to filter out those users who are not worth reading. Anyone who is asked to make themselves clear and responds by doubling down with "well, I know what I was replying to" should be ignored and left to themselves. A good test of "a user not worth reading" is that even after all this back and forth we STILL don't know what share was being referred to and so this particular diversion has become almost comical.
spglet - You almost persuaded me to buy some Tribal (LON:TRB) . After all isn't:-
The issue is that universities don’t really have the budget to warrant the investment to encourage a new entrant with a modern product. Setting up Tribal is like setting up SAP, once you have done it once; you don't want to do it again and you're happy to forget the experience and often live with a partially satisfactory system.
almost one definition of a moat?
I would agree with you if it came with a good customer experience. See my much longer reply to Paul's question.
You are right Laughton - that is the definition of a switching moat and they can be a bitch to cross for new entrants. However, Paul asked the most pertinent question here - why are new universities still signing up? Thats what led to my somewhat tongue in cheek enquiry above - I know nothing about the company, sector or software but I have to guess there is some sort of advantage to signing up. My guess is there is some sort of network effect here - info sharing across platforms perhaps?
For anyone thinking of investing in £(LON:TRB) Tribal I’ve got some experience working with this software. Much of Tribal’s software is really old fashioned. It has a command line interface, which you have to use for the sophisticated functionality. There are GUI interfaces that look like they were developed using Visual Basic back in the day, there are a few .Net libraries and a few Web front ends. The underlying database is UNIFACE of all things.
The thing with the Higher Education software space is there haven’t been any new entrants for student enrolment, fees, finance and record systems for decades (this is the space Tribal dominates). The market is small, and Tribal have 50% (from memory). They do most of their business in the UK, but also have some accounts in Australia, NZ and Canada. The issue is that universities don’t really have the budget to warrant the investment to encourage a new entrant with a modern product. Setting up Tribal is like setting up SAP, once you have done it once; you don't want to do it again and you're happy to forget the experience and often live with a partially satisfactory system. Many university IT systems are very clunky as a consequence.
Oracle used to have a higher education package but pulled out some years ago because they couldn’t make it pay. Having experienced Tribal’s software first hand I wouldn’t ever consider investing in Tribal as a business.
How fascinating, thanks spglet.
Have you come across the new cloud-based product from Tribal (LON:TRB) ? Maybe there's scope for moving over the trapped existing base onto a more modern platform? Also, how come they're winning new business, if the product is no good?
Regards, Paul.
I think they get new accounts because there isn't anything off the shelf that's any better. Tribal have a lot of experience in the university space, but very few institutions have any love (at all) for the product. University technical staff will put up with it because it's a way of getting relatively good pay in a generally poorly paid sector. Directors of Academic Registry and IT won't admit what they have bought into because they made the decision to buy it in the first place. But to be fair to these decision makers, they have precious few choices other than doing as little as possible with Tribal by just sticking to a few basic modules to retain student records, and enroll students. The best choice is to do everything else "outside" Tribal using standard industry software from Microsoft, Salesforce or whoever. But unfortunately that's not what happens. Universities are very political places, and many make poor infrastructure choices. This is because of the way power is spread across different university departments, each department also uses a different part of the system. (i.e. one department for applications, another for enrolment, another for fees and finance.) This complicates matters. I think other industry sectors wouldn't put up with this level of antiquity in a system.
Dealing with Tribal themselves is pretty frustrating, there are just maybe one or two independent consultancies and a small number freelancers who can provide an alternative. This leaves Tribal in a monopoly position for consultancy.
Tribal charge £1200 a day consultancy, and it isn't great quality. A lot of it is someone coming in and pontificating about a particular SITS module (SITS is the name of the Tribal product), then more often than not sitting on the fence when it comes to advising how to get round a particular problem. There are good Tribal consultants, but also many bad ones. Quite a lot of egos.
Tribal don't run a proper academy system like Microsoft, Salesforce, or Oracle where people learn the products properly and have to pass exams to prove their competence before going out and helping clients.
I don't think there is an effective product management or product roadmap from Tribal themselves either. I suspect the whole Tribal product set is enhanced by maintenance engineers piecemeal to add in little features in the hope they don't introduce issue around regression because of the complexity of the whole thing. There is documentation but it's not great.
The place I worked at had a cloud-based implementation, but it is the same old vintage software, just hosted in a different way. Getting staff who understand SITS is another issue, it uses a complex pre-built file and record structure that you have to understand before starting the deployment. You need to get a good Tribal consultant from day one, and have to think a long way forward about something called the "academic model" which is the SITS representation of the university's course structure, comprising module dependencies, credits and the like with multiple hard links between each record instance. The database relationships are added manually by the technical staff and data entry specialists working on the system. Get the design of this wrong, and you're stuffed!
Modern systems are much more forgiving and allow you to learn as you go and simply rectify mistakes at an appropriate juncture. Not so with Tribal. Cost of ownership is generally pretty high. I hope this gives you an idea of what Tribal's software world is like.
I’m finding this feedback fascinating spglet. I have multiple experiences of being trapped with poor software in various businesses so I understand your pain. I’m missing the why - why do these universities not use Microsoft/ sales force etc. rather than tribal? There must be a “killer app” - something this software does that others can’t so you put up with/ install it as new even though it is so obviously antiquated.
I only ask because despite having no background in the sector or technology I’m thinking of forming a startup “Phuntt Uni Software Inc” - sounds like an awesome opportunity
There is an opportunity to move universities off this stuff – I think Paul asked the same question, but I didn’t really answer it. The barrier to doing this is data migration from Tribal SITS to something new.
What Tribal does isn’t very complex – it’s just old fashioned data processing – but the issue is this: Tribal don’t publish their database schema, then they allow users to add a finite number of custom fields (to whatever it is) and define their own database links (relationships). This would make it quite hard to design/reverse engineer a universal SITS schema that would allow you import all the Tribal data for ANY institution’s implementation into a single standardised database schema on the new system. But, if you can crack this you are 75% there.
Then all you need to do is go to the Tribal user base and offer them a usage based, cloud hosted pricing model for a system that allows them to get off this Tribal stuff onto a modern easy to use web based system. The new system would have to come with some migration wizards so that each institution could cutover from Tribal between the end of one academic year and beginning of the next before the new students enrol, with minimum effort and cost.
If you could package this business offering up well, and get a few decent reference sites, that would be it for Tribal. When I was working in the university sector – and thank god I’m not anymore – this question came up a lot. Nobody likes Tribal, and it would be such an easy sell.
Remember this moment, everyone...
When in a few years' time Phuntt-spglet Software is renowned as the system to have, dominating the UK Higher Education market with an easy-to-use, cloud-based student admissions and finance system... you can look back and say: I was there! I witnessed the coming together of these great minds, to create something better!
Thank you both, your exchange has cheered me up and I needed it.
I did some work for a training organisation which maintained their records on a Tribal system. The organisation saw this as a very peripheral activity and would have shied away from any migration which involved difficulty or uncertainty. Add to this that the staff operating the system are usually low level clerical personnel who would need extensive retraining for a new system and the lock-in is near perfect.
So yes, Tribal have a stranglehold on a market which is not huge, expensive to enter and expensive to migrate from.
Thanks for sharing.
The best choice is to do everything else "outside" Tribal using standard industry software from Microsoft, Salesforce or whoever. But unfortunately that's not what happens. Universities are very political places, and many make poor infrastructure choices.
I always wondered about this, Microsoft / Google / etc already provide you with the required tools, it's not an out of the box solution but with little effort will get you flexible and personalized solutions, I would expect professors coming from new generations to be more tech savvy and exited about developing their courses their way. That's why I'm skeptical of the success of these educational software companies.
Any gents (or ladies) actually customers of Shoe Zone? Having bought a pair of cheapo shoes in the past I find that footwear is a false economy; a good quality pair will outlast a low quality one several times over. And they also look better, in my opinion - the intangible benefit is hard to price.
This effect doesn't automatically apply to everything though, for instance I like Primark for their t-shirts - superb value and not really that much different from one that costs five times the price with a small logo on the chest.
Think there are some parallels between Shoe Zone and Card Factory, in that they have over-relied on their large shop network and are relatively underdeveloped online.
But at least with Card Factory there is a competitive advantage in that they are lowest cost producers. They have seen off competitors who couldn't live with their prices.
I don't get where the moat is with Shoe Zone - it's a cheap place for shoes, but then again so are Matalan and Primark. Having had a mooch around it strikes me that their shops are not in prime positions in town and their products are pretty undifferentiated.
I agree Snoo and this point (cheap footwear is a false economy) is also an important economic theory, best expressed by the great Terry Pratchett in the Captain Samuel Vimes 'Boots' theory of socioeconomic unfairness.
Here's the full version for those that haven't seen it.
"The reason that the rich were so rich, Vimes reasoned, was because they managed to spend less money.
"Take boots, for example. He earned thirty-eight dollars a month plus allowances. A really good pair of leather boots cost fifty dollars. But an affordable pair of boots, which were sort of OK for a season or two and then leaked like hell when the cardboard gave out, cost about ten dollars. Those were the kind of boots Vimes always bought, and wore until the soles were so thin that he could tell where he was in Ankh-Morpork on a foggy night by the feel of the cobbles.
"But the thing was that good boots lasted for years and years. A man who could afford fifty dollars had a pair of boots that'd still be keeping his feet dry in ten years' time, while the poor man who could only afford cheap boots would have spent a hundred dollars on boots in the same time and would still have wet feet."
I like Shoe at this level but not going to pay a 10% spread.
Yes its a stretch, and usually way beyond what I would be willing to consider, and I most definitely didn't like the immediate red P&L, but for the opportunity that may eventually unfold, a 10% spread may become somewhat irrelevant, horses for courses.
Shoe Zone (LON:SHOE) I have taken a small position today, very speculative from my perspective, however the things that have grabbed my attention are the significant increase in online, although no actual numbers stated ( I calculate this to probably by £10m revenue) and the expectation of a continuing reduction in physical shops ( 45 to April 21 and another 45 the following year). Also the asset swap that occurred on 26 August almost exactly two months ahead of today's RNS at a significant higher share price than todays.
On that latter point, great if we think that occurred because management have a high confidence in the future. Maybe not so great if my hopeful interpretation is incorrect.
I think in a recent results, Online was 10%. So would be 20% now. So not huge by any means. And their website needs investment.
Surprised no words given to their online plans. Maybe they don't have any plans to grow online...
On SHOE....large institutional investor tells me he cannot get the number given in the RNS picked up to discuss. The rates blast is not new & usually reported 50% annual rent reductions, playing hard ball with the freeholder, who are often private individuals. Rent or no rent stuff?? Tenancy is usually short hence ability to cut 20% of the estate in 2 years. Guess little shopping for flip flops ( holiday wear) & school shoes the year and a bad selection of home wear sliders. Nice write up but sort of un-investible!
Its fortunate that Stockopedia allows one to up vote articles twice, albeit I suspect that's a bug. So that's one up vote each for both Paul and Jack.
Hi Paul & Jack, its nice to see the new format were Paul concentrates on his 500 or so stocks and Jack writes about mining stocks, this is something I suggested to Stockopedia last year. I believe it will work very well. Also, it means Paul can concentrate on writing more in-depth reports such as Shoe Zone (LON:SHOE) which thankfully I don't hold but Paul's writeup today on this company is highly educational, thumbs up from me.
Likewise, Jack's writeup on Sylvania Platinum (LON:SLP) (I hold) is excellent. Today, I have added more shares to my portfolio as a long term hold and to take advantage of it going ex-dividend tomorrow.
Going forward, will Jack be covering financials as well as mining stocks?
Hi All,
Looking at indices and the general market, even very large caps, and the level they have dropped in the past 2-3 days, do you think a similar wholesale panic selling (but just a bit less aggressive) like March sell-off is happening?
I think that is the case. With England-wide-lockdown idea creeping up and more likely than ever before, and US election uncertainty, and contradictory /not clear vaccine news from here and there, I think people are just thinking they're better off with cash.
What do others think? Jack and Paul please give your idea too if you would, I think it's important and significant to have some sort of support around each other mentally to avoid a disaster in our Portfolios!
All ideas appreciated.
Hi mort1980,
Yes I'm definitely seeing some signs of a few people panic selling in small caps today - there are some sharp price movements today on great companies which have reported strong trading (e.g. Volex (LON:VLX) which I hold) that are not affected by covid, yet the price has gone down 10% for no fundamental reason.
It's all just background noise for long-term investors, and these dips can present some nice buying opportunities. I find it's usually best to do the opposite of what my emotions tell me! (i.e. buy dips, rather than panic selling into them).
Whoever gets into the White House is going to unleash huge new stimulus packages, so all that is in question is the timing. The downside scenario is a contested result, with log jam on new economic stimulus.
Covid is a worry for all of us, but we already know which companies & sectors are impacted by it, so can avoid those if we wish.
Regards, Paul.
thanks a lot Paul for your comments as always!
Lockdown coming. Prices will fall further, therefore Sales Time coming up.
And as someone else mentioned, it probably won't be the last lockdown.
Please manage your risks carefully.
The FTSE100 hit 5580 today. No panic; which suggests to me the market has some way to fall yet.
I took the dog in to be washed and nails clipped on Monday. An old Labrador. He does not mind this time because he gets so much of a fuss made of him. I live in a small town on the South Coast and while waiting for the dog, I nipped in to a local pub for a pint. A couple of people in there and I wore gloves and a mask as requested.
Today the pub posted: "Several of our staff have tested positive for COVID-19, so we feel it is the responsible decision to close the pub and have it deep cleaned. We have notified Public Health England and Track and Trace, so anyone who has been affected will be notified. The decision to close the pub was made by us, we were told by PHE we could remain open. However, we feel we have a duty of care to you all and will be closing for a few days, deep cleaning and ensuring everything is as safe as possible".
Really? Heard nothing myself yet from track and trace. It amazes me that a place where SEVERAL of the staff are positive can stay open? This town has been low risk for Covid so far so it seems the virus is spreading to those areas.
Whilst it seems there are track and trace procedures in place its shocking to hear that you haven't been notified. It amazes me the amount of places still require you to write your details down on a piece of paper, this is so antiquated.
We have some great technology at our fingertips with smart phones yet we don't use them to their full potential.
For example there is an app called what3words which applauds its self with its accurate GPS results, if this was used in conjunction with NHS test and trace app which was rolled out across the nation then your phone could ping up once the app recognise's its been close to an area which had a covid outbreak, and notify s users instantly. Another example would be that once you have been tested +ve and alert the app, it back tracks over the last 5 days (I think that is the incubation period?) and notifies anyone else who has been within your coordinates.
I am not saying this is simple and it could potentially get very complicated, also there could be alot of privacy and legal issue to be worked out, but this process needs to be so much more efficient.
Maybe I should use Pauls advice using the 'Writetothem' website and give the MP's a nudge.
Re Sylvania Platinum (LON:SLP) which I hold. From my memory of the last earnings webinar they didn't expect the current Platinum Group Metal prices to appreciate. They were reluctant to buy more rights to process tailings because the mine owners were looking to price based on PGM metals values that Sylvania didn't see as commercially sustainable. If Sylvania are right then share buy-backs make sense. If they are wrong on PGM pricing then they should be using their money to grow by buying into more processing opportunities.
Many thanks to the readers who have flagged Sylvania Platinum (LON:SLP) today. It is a sector I wouldn't dare approach, my only interest in mining is a small holding in Anglo Pacific (LON:APF). Yet I've looked at the SLP stock report today and it is stunning and ticks so many of my boxes. Also great to see it qualifies for 10 screens.
I've read the announcement today and it seems focused on the movement between Q4 2020 and Q1 2021 which is a notable difference but is it fair to compare due to the pandemic?
Thanks again, I've added this to my watchlist for further investigation and maybe a dabble with play money. It isn't really a sector I understand and can see mining/geographic and currency risks which makes me come out of my comfort zone. However will certainly research further and build up my knowledge of the company.
"I agree with reader comments that this update seems to cut a deliberately negative stance". Paul, I don't think anyone whose investment in Shoe Zone (LON:SHOE) has lost 81% would agree with this sentiment. I was so incensed I wrote to my MP at 9.01 am today, quoting Shoe Zones comments on business rates.
Silver
Great to see you both contributing and therefore covering businesses that wouldn't otherwise be covered by Paul. Google system seems to be working and a big thumbs up from me. Thanks both!
Whatever you are doing today, whatever side of the lockdown debate you are on, I recommend watching the Sumption lecture from last night. In a world where politicians are offering us the choices of Fear or More Fear, this was an articulate expression of an opposing viewpoint.
You can find it on YouTube “Government by decree: Covid-19 and the Constitution”.
Couldn't agree more. It was both riveting and horrifying. I've written to my MP and will be donating to the Simon Dolan legal cause.
Many thanks for bringing this to my attention, very thought provoking what ever your views on lockdown.
Whatever you are doing today, whatever side of the lockdown debate you are on, I recommend watching the Sumption lecture from last night.
For those not interested in following the link, Sumption isn't an anti-lockdown sceptic. It's a reasoned legal argument about the nature of sovereignty in the UK and the way that ministers have exceeded their powers in order to exercise power by decree during the pandemic without proper democratic oversight.
As we all presumably know, sovereignty in the UK rests in Parliament where our directly elected representatives are supposed to hold ministers to account on our behalf. Sumption argues that lockdown was deliberately executed under a statute for which it wasn't designed in order to ensure ministers could avoid Parliamentary scrutiny - and which they've exceeded their powers in exercising. He also points out that alternative primary legislation already existed under which they could have implemented lockdown legally - but that would have required regular Parliamentary reapproval which the government presumably wished to avoid.
Beyond that he argues that the police have exceeded their authority in the way that they've enforced the very large powers that they already have. And this has all been done in the name of protecting us from ourselves - which he points out is the justification of authoritarian states everywhere.
And much, much more. No matter which side of the debate you fall on it's worth listening to.
timarr
I haven’t watched/listened to the Sumption lecture yet, but you maybe interested in another viewpoint:
http://files.brontecapital.com...
HI stegga
The Bronte piece is really interesting - although it mainly makes a completely different point. Sumption isn't debating about whether lockdown was right or wrong, he's mainly arguing that it wasn't legal - and that the longer term consequences of that for our democracy are corrosive.
The one crossover is this comment from Bronte:
You can however control this virus if you are prepared to trample civil liberties enough. China did. Suffice to note authoritarianism is good for the virus and the virus is good for authoritarians. The virus has cemented Xi’s power in China for instance.
The Bronte view is balanced - there's a very good argument for why the Swedish model wouldn't have worked elsewhere, and they make the point that anyone can find evidence that supports their predetermined position, if they search hard enough for it. Cherrypicking evidence is the norm, sadly.
The behavioural model of epidemiology is completely new to me, so will need further research. It's superficially attractive - by which I don't mean it's superficial, but that it makes immediate sense, which is usually a sign I haven't thought hard enough about it.
But there clearly are limits to it - I know vulnerable people who are exposing themselves to CV19 risk because they don't feel they have a choice due to lack of support or a need to earn a living. As I noted yesterday, we could have provided shielding for those people who wanted it at far lower cost than the economic shutdown we appear to be blindly careering into again - again, without any democratic mandate.
Anyway, this is way off topic. But thanks for the link.
timarr
Thank you Tim.
Morning Paul,
I’d be curious your thoughts on £ZOE
Best wishes,
J
Interesting update from Shoe Zone (LON:SHOE)
Surprised by the very overly sombre tone, and the dedication of a large part of it attacking rates instead of going into more detail on the business performance.
Retail trading at -20% YoY in the last few months doesn't sound too bad compared to other retail chains. Net cash actually increased. They probably did breakeven one or two months, given the direction of net cash, would have been good to know.
Ability to close up to 20% unprofitable stores in the next 1.5 years as well as very likely rent renogiations on a big part of their estate (their avg lease length is low, less than 2 years avg I believe) should mean they at least get back to positive profitability next FY.
I get the feeling this TU has been put up with extreme pessimism, almost to force the SP downwards... But to what end? Management picking up shares more cheaply? Buyout coming?
I too thought it was deliberately negative. I think it is more a case of hammering the landlords with rent reduction requests will be more effective if they put out results that have a negative emphasis rather than a positive emphasis.
Thats a good hypothesis!
Especially when you compare this TU to previous ones, where they balance out negatives with some positives - so it was a little unsettling to see them not even try to put a positive gloss on anything. I was half expecting phrases like:
" we have short length leases and will look to renegotiate or exit. We achieved - x% rent reductions last year on renewals, expect greater going forwards"
"we will continue to invest in online"
"our big box stores, in retail parks out of city centers are performing better, supporting our shift to more big box stores"
Etc. The usual positive spin you get in TUs, completely missing from this one!
Hi dahokolomoki - re Shoe Zone (LON:SHOE) - I though actually the main pessimism was focused on unfair business rates. - my highlighting below
In 2015 the government delayed the rates revaluation by 2 years which cost our business £1.25 million per year (£2.5m in total). The latest revaluation delay will be even more costly as rents during the period have fallen significantly further and consequently rateable values should have fallen broadly in line with rents. Never has the rating system been more unfair. Our rates as a proportion of rent have increased from 26.4% in 2009 to 54.3% in 2019 and forecast to be close to 60% in 2021.
This is unsustainable for most high street retailers and closures will continue unabated until the government makes substantial changes.
I HOLD and am waiting for the right time to increase
Did they say why cash increased when sales were down? Could it be deferrals of rent and rates which will bounce back on them?
Their general point about business rates is correct. If ever there was an out of date tax business rates are it. A radical change to business rates and VAT by introducing a general sales tax at the retail level, including online sales more than overdue.
My feeling was that it was positioned to justify to the family that there would be no dividends until 2024/5. Partly blaming the government for that in not adjusting business rates downward.
dahokolomoki, may I ask if you are a holder of Shoe Zone (LON:SHOE) and if so, for some duration?
I hold.
Silver
Been holding on and off for the last few years. Currently a holder, bought in early Sep when back to school season risk was eliminated. Down about 20% though.
Sadly I bought at rising prices in 2017, 2018, and 2019, the result of which my capital invested in Shoe Zone (LON:SHOE) has lost 81% of it's value. I'm trying to apply stop-losses here and there but it's so hard to do when a share is already all but lost.
I've also been a holder of SHOE at various times over the last year (I don't currently have a holding), one of the concerns (IMO) is that the shoes are typically bought for the office workers (myself included) and I've had no real reason to go into the shop whilst working from home. It's not somewhere I'd shop (either online or in the shop) for trainers, casual wear or night out heels. I was tempted to buy in the drop today, but I personally feel I'd rather wait to see it picking up, before buying.
Overall positive trading updates from Redde Northgate (LON:REDD) and £HSP. In my view two underappreciated small caps with significant turnaround potential.
I hold.
Yes, Redde Northgate (LON:REDD) seem to have coped well with the Covid issues so far although they do say that prolonged lockdowns could affect them. I think the addition of the Nationwide chain of garage repair businesses was good news bearing in mind that they have over 100,000 vehicles on hire that will require maintenance and apparently a large number of vehicles (presumably which they have sold) where they offer maintenance. As a holder I am hopeful of a significant increase in price over the next two to three years when everything is back to something like normality although I guess it will continue to go down with the market if we have further falls.
Redde Northgate (LON:REDD) seem to have coped well with the Covid issues so far although they do say that prolonged lockdowns could affect them. I think the addition of the Nationwide chain of garage repair businesses was good news bearing in mind that they have over 100,000 vehicles on hire that will require maintenance and apparently a large number of vehicles (presumably which they have sold) where they offer maintenance. As a holder I am hopeful of a significant increase in price over the next two to three years when everything is back to something like normality although I guess it will continue to go down with the market if we have further falls.
Sylvania Platinum (LON:SLP)
I too hold SLP although noted a fly here "the reduced mining operations of certain host mines continued to impact on feed grades as expected and consequently Q1's PGM production decreased approximately 14% on the corresponding quarter of FY2020"
Regardless they generated USD $21m net profit for the quarter and hold USD $60.9m in cash versus a market cap of GBP £189m
Sylvania Platinum (LON:SLP) Yes also not sure how the proposed South African tax on Chromium exports will affect production/price.
My morning smallcap tweet: Shoe pasty
Maestrano (LON:MNO) Mirriad Advertising (LON:MIRI) Amiad Water Systems (LON:AFS) WANdisco (LON:WAND) EKF Diagnostics Holdings (LON:EKF) Zoetic International (LON:ZOE) Tribal (LON:TRB) Centaur Media (LON:CAU) SysGroup (LON:SYS) Omega Diagnostics (LON:ODX) Shoe Zone (LON:SHOE) ULS Technology (LON:ULS) Image Scan Holdings (LON:IGE), Franchise Brands (LON:FRAN)
Maestrano (MNO) Q to Sept rev £436k (£101k). EBITDA -£346k (-£316k). "The board continues to be delighted with not only sales growth but also customer appetite for our solutions..." [SP=9.5 Cap=15m]
Mirriad Advertising (MIRI) two-year commercial agreement with one of the largest and best-known US-based content producers and distributors to develop its in-video advertising on a number of entertainment series. No immediate income, contact sets out T&C for doing business. [SP=32 Cap=68m]
Amiad (AFS) CFO leaves end of year. He is thanked. [SP=240 Cap=73m]
WANdisco (WAND) go-to-market launch of LiveData Platform for Azure, in public preview. "The Platform is being launched by Microsoft as the preferred solution for Hadoop data lake migrations to Azure." All in line with mgmt expectations. [SP=450 Cap=236m]
EKF Diagnostics (EKF) two year marketing and distribution agreement with Kantaro Biosciences. EKF will have exclusive rights to market and distribute COVID-SeroKlir covid IgG (single) antibody test kit in the UK and Germany and non-exclusive rights in Europe. Also non-exclusive rights to distribute COVID-SeroIndex (quantitative) test across UK and Europe for research. [SP=64.5 Cap=293m]
Zoetic (ZOE) significant order to roll out Chill range of tobacco-substitute CBD products in a number of convenience store outlets throughout the USA. Sale of legacy DTU and the Kansas Nitrogen Assets will miss long-stop of Oct 31. [SP=44.5 Cap=87m]
Tribal (TRB) guides FY comfortably ahead of market expectations* with rev in line at c.£72m and adj EBITDA c.£14.8m. Will reinstate divs with interim div 1.1p. * rev £72.1m, adj EBITDA £13.7m. [SP=67 Cap=138m]
Centaur Media (CAU) Q3 'resilinet' with rev down 16% (Q2 down 24%). Guides FY rev-cont at least £32m and adj EBITDA margin c.10%. Further exceptional charge of £0.6m. In line? No guidance. [SP=21 Cap=33m]
SysGroup (SYS) guides H1 rev broadly flat, adj EBITDA up at least 15%. "This performance has continued into H2." Guides 'a good outcome' for FY. [SP=35 Cap=16m]
Omega Diagnostics (ODX) guides H1 in line with rev down 29%, EBITDA -£1.3m. Expects 'significantly improved performance' in H2. Various updates including covid tests. [SP=91.11 Cap=163m]
Shoe Zone (SHOE) gloomy. Guides FY rev down 24%, pretax -£10 to 12m. . Tiers 2 and 3 covid regions 'greatly impacted'. One of the legacy pension schemes will need extra funding. No divs until at least the 2024/25. "Very difficult at this stage to provide meaningful guidance on the future outlook." [SP=44.9 Cap=22m]
ULS Technology (ULS) guides H1(Sep) rev down 31%, U/L pretax £0.1m. Co "delighted with the resilience of the Group". [SP=53.24 Cap=35m]
Image Scan (IGE) guides FY(Sep) rev up 50% and pre-tax trading profit £112k (-£402k) above prev guided £0 to £100k. [SP=2.37 Cap=3m]
In line: Franchise Brands (LON:FRAN)
Resilient seems to be the iconic corporate communications word of the moment. It may have even overtaken unprecedented.
I note that Sylvania Platinum (LON:SLP) have reported a positive 1st quarter result.
Paul will not respond but there are a few of us who have Sylvania Platinum (LON:SLP) here, and you never know, Jack may make an appearance in the comments.
The Q1 results certainly do look good again,
* Q1 NET PROFIT 21 MILLION USD
* Q1 EBITDA ROSE 55 PERCENT TO 29.7 MILLION USD
* Cash balance now up to $61m
Sylvania Platinum (LON:SLP) has grown to be to be my largest holding by a country mile, circa 31 per cent of my portfolio, we have had a good run this year, so I need to slice some off the top, but being a mechanical investor, when I run my screen, Jim Slater with some added Stocko brucie bonuses added, Sylvania Platinum (LON:SLP) is the one to invest in by a country mile, so I am a bit of a quandary.
It refuses to break out above 70p, but with these results, it may get the final push, but its xDivi day tomorrow, but suspect we will need to wait for news on the special dividend, as this company appears to like to hoard its money rather than invest or return to shareholders.
Sylvania Platinum (LON:SLP) I am in exactly the same situation. Also now at over 30%. Watching closely over the next few days.
Sylvania Platinum (LON:SLP) has been on an excellent run and valuations don't seem stretched. Let hope it breaks out from 70p soon.
BSV
There is a, as usual, succinct and clear trading update out from Next (LON:NXT) which overall seems quite positive but I would imagine a lot will depend on whether the country is put back into lockdown. Possible? Without wanting to make this a Boohoo (LON:BOO) post, does the strong online growth read across as a positive for Boohoo or is a negative as a sign of increased competition?
This is slightly off piste but I think there is a read a cross to U.K. policy; What a French virology professor said yesterday was quoted as follows:
“Prof Pialoux head of the infectious diseases dept Tenon hospital in Paris calls for the country to “return to lockdown” we "must leave the economy aside” adding "The economy can be recovered but people lives in intensive care cannot”.
To me it is obvious that certain (many) drivers of policy do not appreciate that “the economy” is not really an homogenous mass but an entity made up of business owners, employees and customers. If your company has gone bust/you can’t make the next mortgage payment because you have lost your job etc through government policy, it is little consolation that in 2021 2022 or 2023 that “the economy” has “recovered”.
I am trying not to political/controversial here (I know difficult sometimes for me) but just pointing out that if the prevailing view is similar in the the U.K. to medical opinion in France, then another lock down is much more than just a possibility with all the potentially dire consequences that will have on the U.K. “economy”. And of course lockdowns in the rest of Europe can have a knock on effect on companies in the U.K.
I hold Boohoo (LON:BOO) I do not hold £NXT
Regards
Michael
Yes Michael,
The prognostications from Drs/academics re lockdowns are unhelpful, not least as so many of the jobs lost to lockdown are ones that young people would usually access early in their careers.
Re: Next (LON:NXT) and Boohoo (LON:BOO), whilst the current conditions continue, clothing is one of the things that people can continue to spend their money on, given that so many activities that would normally complete for one’s spend are now either curtailed or prevented altogether.
(I hold Boohoo (LON:BOO))
Regards
Martin
Can't envisage that Boohoo (LON:BOO) and Next (LON:NXT) are competing for the same customer. What I can envisage is an online Christmas like never before. The risk for fashion retailers is mix. Next has the capacity to switch between sectors, whereas Boohoo, (I hold) has to work out what to replace it's Christmas party dress sales with.
Agree - and it should be pointed out these Drs/Academics have near 100% job security and often <10% knowledge of how the economy works!
It's worth reading up what what Dr. Mike Wheadon is saying on lockdownsceptics.org about the numbers SAGE are using. I haven't read anything on the rest of the site so am not endorsing it, but numbers are my trade and he makes a lot of sense.
It is not worth reading up on anything at lockdownsceptics.org. Being anti-lockdown I can sympathise with, despite the wrongheadedness of the position; but also they are confusingly anti-Black lives matter (because that's a big driver of COVID right?).
It's the usual cherry-picking nonsensical screed from the libertarian right.
My former colleagues are building some of the models used to evaluate the upcoming COVID vaccinations. The best case is that the vaccines last for a year, but more like 6 months. Privately they believe that the virus will circulate for years and we could be looking at snap lockdowns well into 2022.
The general public just aren't grasping how long this will go on for.
The general public are and have decided that we have to live with it. We are not libertarian right wingers. We just think the government has to balance Public Health with running an economy that pays for it and be mindful of the longer term impacts of their short term regulations.
I (a 67 year old so mildly at risk if I got it) thinks the balance is wrong when 99.7% of people who contract it survive.
Privately they believe that the virus will circulate for years and we could be looking at snap lockdowns well into 2022.
The general public just aren't grasping how long this will go on for.
I am no expert in this area but i simply don't understand the logic of this thinking with regard to any need for ongoing lockdowns - its pretty basic maths that if we can for a sustained period get the r0 below 1 then the virus should dwindle away to minimilistic levels- if it needs ongoing boosters every 6 months to keep the r0 below 1 that should be pretty simples to organise - i don't see any scenario where we don't do whatever is needed to avoid the need for future "large scale" lockdowns presuming a vaccine is effective.We have also proven in many countries that the rates can be kept to low background rates by using sensible measures - so it's not as if we are lacking options - biggest problem in uk is bods doing their own thing. So imho i will choose to take the viewpoint that the vaccine is coming will work and will hopefully when generally available avoid the need for ANY further lockdown - feel free to come back in 12 months and tell me my comments were nonsensical. Note the amount of people who have been re-infected with covid is remarkably low % - so i would go as far as saying its not even a given that even if the direct efffects of the vaccine wear off that this means everyone will be liable to get re-infected it could be that the bodies own t cells may be able to do some sort of ongoing preventative measures. The one elephant in the room is if the virus mutates to such a degree that vaccines won't work - if that happens we may have ongoing issues.
I think we agree but the premise that I am challenging is that we are all going to get it and when we do we will die. Surely by now we know that it isn't that dangerous to the vast majority of us and that the situation we now have where covid is being prioritised over the economy and medical issues like cancer screening is going to be very damaging in the medium to long term.
I am no expert in this area but i simply don't understand the logic of this thinking with regard to any need for ongoing lockdowns - its pretty basic maths that if we can for a sustained period get the r0 below 1 then the virus should dwindle away to minimilistic levels- if it needs ongoing boosters every 6 months to keep the r0 below 1 that should be pretty simples to organise
No vaccine is 100% effective. Let's be extremely generous and assume the first-in-trial vaccines, those bundled into trial with no real clear understanding of how COVID works, have an efficacy of 80%, which is greater than our influenza vaccines. This despite the fact that the FDA and EMA have indicated they are willing to accept vaccine response levels of 50%. That won't deliver herd immunity.
The UK has one of the highest levels of influenza vaccine coverage in the world- between 70-75% of over 65s depending on the year. Let's be generous and say that we can get to 80% coverage of over-65s once all the anti-vaxxers and no-maskers have finished ranting.
0.8 x 0.8 = 64% of over 65s covered by a vaccine that lasts between 6-12 months maybe. That's probably not going to be enough to generate herd immunity and that's under generous assumptions, and would only even be feasible if over 65s interact solely with over 65s. If they are in circulation with under-65s who very likely won't even get the vaccine in 2021 then the herd immunity idea is in tatters. Population protection requires all ages to be vaccinated. Best case is you reduce the numbers of at-risk pop churning through the NHS. The good news is deaths will likely be mitigated.
Any vaccine is going to be the world's most in-demand drug for all of 2021. How many units can be physically manufactured and distributed? People are talking about the possibility of the government making accessing certain public services contingent on getting a vaccine- that will be impossible in 2021, and maybe not until well into 2022 at best.
A vaccine is not a silver bullet. In my humble opinion, a rolling schedule of lockdown and release is on the cards for well over a year if not more.
As ever, DYOR.
I cannot imagine 20% of the high risk population deciding to refuse a Covid vaccine.
If they do refuse a vaccine, then that should be their decision and the rest of the population should neither worry about it nor be expected to adjust their behaviour to protect the anti-vaxxers. Arguably those who refuse a vaccine should be charged for any covid treatment, if a vaccine was repeatedly refused without good medical reasons.
What I would also like to see is more transparency about vaccine supply and schedules.
e.g.
(i) When do Astra Zeneca expect to submit results ? [A while back, "as early as October 2020" was mentioned]
(ii) What's the schedule for manufacturing doses, including prior to approval ? Somewhere in the Astra Zeneca reports is a reference to 200 million by the end of 2020. Is this still on schedule ?
(iii) How long will the UK regulator take to approve this ? The government should ensure the regulator is prepared to evaluate very quickly, but of course without the government interfering in the decision.
(iv) Who will organize the vaccination programme ? If we do the maths, once a supply is available, there is no excuse for delays of more than ~2 weeks in actually vaccinating people. They need some people with a "can do" attitude & management capability running this. Unfortunately politicians and the people they select seem to fail on both counts.
Berksbee
This has been debunked. I don’t want to clutter the board up with Covid stuff, as happened in the spring, so I’ll just suggest that the Huffington Post has an article that explains where Mr Wheadon has gone wrong if you are inclined to look at it.
I will try not to clutter up too much with Covid stuff either, but the Huff Post article you refer to is pretty long-winded and the rebuttal is actually far simpler.
The assertion from Heneghan and Yeadon is that IF the test produces a false positive in 1% of instances, then if 1,000 people are tested and 11 people produce positive tests (a 1.1% reported test positivity), then 10 (1% of 1,000) are false positives.
So of the 11 positive results 10 are false - so 91% of the positives are false.
The maths is sound; although they don't explain how the test positivity rate could have been consistently below 0.5% of the summer with 1% false positives.
However if we assume that some statistical anomaly that persisted for over 60 days and move on.
So coming up to date in the last 7 days; there have been 2,178,983 tests (so "theoretically" 21,790 false positives) resulting in 153,050 reported positives. So on the Heneghan / Yeadon view now only 14% of positives are false.
It also means that the actual prevalence of the disease has increased by significantly more than the official figures suggest.
The important thing here is not so much debunking this particular theory. It is more about questioning the intelligence and/or integrity of Heneghan & Yeadon if they are still touting this line.
I know less about Yeadon, but Heneghan is a regular on TV & in press and comes across as a credible voice. Based on this, however, if he is still maintaining this line or even failing to confess "oh yes we got that one wrong" then frankly I would not trust him to tell me the time.
I do not necessarily trust everything the Government or SAGE tell us either, but at least to some extent they are accountable - if it can be proven they have wilfully lied or misled there will be consequences, I am not convinced the same is true for Heneghan & Yeadon.
What I like about NXT is the customer experience. IMO they seem to have mastered this. I've recently purchased a new house and have been furniture shopping - Next Home stands out from the crowd, they keep up with the trends, their shops are bright, laid out well and give you great ideas for furnishing, furniture is decent quality & affordable, their service is excellent and you can buy sofas/furniture in 5 weeks (not the typical 12 to 16 weeks quoted by other retailers). I've been round most of the usual shops over the last few months (DFS, SCS, Oakland Furniture etc) and the contrast was obvious, queue's at the door for Next and they appeared to be selling furniture every 5 minutes whilst we were there - there was a real buzz about the place. Going to DFS, SCS etc we were followed around the shop, no real character, dark lighting, hardly any customers, and more dated furniture (IMO). I'm also a big fan of Next clothing and their annual sales. I believe there is also a shareholder perk - if you hold 100 shares you are entitled to a voucher for 25% off a one time purchase. (I hold both NXT and BOO).
I wonder will there be a read across to Ted Baker (LON:TED) Ted Baker - who are transforming?
Anyone any ideas on this one?
I think it would take quite a read across to impact £TED My wardrobe used to be full of Ray's wonderful silk lined jackets and those cleverly edged shirts but then I would go in a few times and find nothing I liked and after that I would just walk by. The brand was failing big time well before Covid and in IMHO high street clothing brands have one purple patch but rarely two.
Macron prooved that tonight.
UK not far behind.
Madness.
Good morning! Below covers today's regulatory and potentially price-sensitive announcements.