Small Cap Value Report (Weds 3 Feb 2021) - SAGA, SUR, DISH, DEV

Good morning, it’s Paul here with the SCVR for Wednesday.
Thanks to Tamzin & Tim at PIWorld for another utterly brilliant chat with Andy Brough. This is pure gold, I recommend everyone listens to it -
Timing - I started early today (too tired yesterday to do any more), so will be finished by lunchtime.
Agenda -
Latest covid/re-opening thoughts - bullish news
Quick recap on Saga (LON:SAGA) (I hold, my 2nd largest holding after Boohoo (LON:BOO) )
Sureserve (LON:SUR) - preliminary results for FY 09/2020
Bigdish (LON:DISH) - changing the business model yet again!
Dev Clever Holdings (LON:DEV) - shares going exponential. Looks very flimsy to me at >£100m mkt cap, buyer beware!
.
Covid/vaccine news
Seems to be very encouraging. Today’s papers are talking about “coming out of lockdown as soon as possible” (Sir Iain Duncan Smith). Vaccinations - 10 million people have now been vaccinated - if you’d told me a few months ago, that the vaccinations would be so well progressed by early Feb 2021, I’d have scoffed, and seen you as wildly optimistic. Yet that’s where we are. Hence share prices should be buoyant to reflect this.
Today, the press are reporting that a major study has shown the Oxford-AstraZeneca vaccine prevented all hospitalisations after 22 days, and that a single dose prevents two thirds of onward transmission. Obviously check the precise details yourself, I’m just regurgitating what’s in the Telegraph, and they have been known to get things wrong on occasion.
The above clearly means that we should be pricing in a return to near-normality into shares. Not at some distant point in the future, but imminently, i.e. the next 2-3 months. This is good for travel, leisure, hospitality, retailers (maybe), and the economy generally. I see a lot of pent-up demand, and a desire to splash out on luxuries, being unleashed. Although many shares have already anticipated recovery, so how much upside is left, I wonder? The opportunity is to find shares that haven’t yet anticipated a full recovery, with lots of upside to be had as they catch up. I've just this morning booked flights for a month in Malta in Sept/Oct. Why not?! I reckon we could see a stampede for holiday bookings.
eCommerce
I’m pondering how eCommerce might be affected? Personally, I’ve found ordering online for home delivery so convenient, and everything from Next (LON:NXT) and Joules (LON:JOUL) (I hold) is good quality product, and fits me like a glove, so I never need to return anything. Therefore, apart from buying a few basics from Primark, maybe twice per annum, I doubt whether I’ll go back to regular clothing shops much again, if at all. I wonder how many other people feel the same? I.e. the pandemic may have triggered a permanent change in consumer behaviour. For that reason, I’m generally not backing any physical retailers to make a big recovery. My money is on Joules (LON:JOUL) (most sales are now online), and Boohoo (LON:BOO) of course. Next (LON:NXT) is tempting, but it’s gone up too much, and I’ve missed the boat, for now anyway.
Travel shares
In terms of travel shares, Jet2 (LON:JET2) is my favourite on fundamentals & track record, but again, the price has now probably baked in most of a recovery. To make it appealing as a buy now, we would have to assume the share price would break into new highs - possible, but I don’t want to make heroic assumptions to make a buy case stack up, there needs to be some margin of safety.
Saga (LON:SAGA)
(I hold)
For me, the stand out bargain is still Saga (LON:SAGA) (I hold) . There is obviously a selling overhang in the market, as the price keeps getting bashed down again, whenever it tries to recover. Looks like Setanta Asset Management is selling down its position, now just below 7%. Hopefully the house broker might be able to place that with another institution, and clear the way for a share price recovery. I’m happy to just wait, this one should produce a good return over my 2-3 year timeframe, if things recover as they should. I remain of the view that the upside could be a 4-5 bagger in the long-term, on the basis that 100p EPS per share is possible, with 140m shares in issue, hence a PER in the teens gets us up to a price target of 1000-1500p per share. As opposed to 253p now. It’s just the wrong price, in my view, but at the moment my view seems an outlier!
This is where patience could be a great virtue. Lots of investors don’t seem to be able to look beyond covid, with Saga shares. Travel should resume for summer 2021, but I think the full benefit is likely to be next year, so calendar 2022, being FY 01/2023.
Debt is mainly just asset funding for the 2 owned cruise ships. Plus a £250m bond they reckon can be repaid from cashflows. None of that should be a problem, why would it?
Hence why I can’t see the point in looking for other covid recovery shares, when what I think is the best one (Saga) is already in my portfolio. I just need to buy more.
Last night, Joanna Lumley's latest travel show did a feature on Tilbury Docks, and I noticed that one of Saga's two ships made a cameo appearance, but sadly Joanna's usual sense of breathy wonderment, did not extend to the Spirit of Discovery - she didn't mention it at all, as the camera panned past. How disappointing! Maybe we should get her onboard with a complementary state room, or if she's busy, then maybe Jane McDonald could be hired to burst into song randomly, and accost any fellow travellers with Wakefield accents?
Carnival (LON:CCL)
I’ve also looked at recent results from Carnival (LON:CCL) expecting to find a basket case. Actually, the figures pleasantly surprise. Yes it has a lot of debt, some of it quite expensive, but it also has a massive cash pile. So liquidity is not a problem, and once customer bookings recover, then the cash pile would recover to a point which would enable Carnival to pay off a lot of its debt, or at least cherry-pick the expensive debt (assuming no early payment penalties), and repay that.
The ships should generate a lot of cashflow once they’re operating again, and the numbers suggest to me a healthy business once again, in a couple of years’ time perhaps. Hence it’s worth a closer look, in my view. It’s funny how we all have preconceptions about companies, and we imagine what the numbers might look like. It’s only by actually digging into the numbers that you sometimes find reality does not match those preconceptions, creating potential investment opportunities. Think I’ve talked myself into buying some Carnival shares!
As always, please do your own research (DYOR). I cover c.500 companies, so can't possibly research every detail of all those, hence why it's vital that you check everything for yourself. Also always bear in mind that sometimes I get things right, but also get plenty of things wrong - same as everyone, as buying shares is all about trying to predict the future, not just on fundamentals, but also on market sentiment, which is unknowable with any degree of certainty. Sentiment can turn on a dime, at any time.
.
.
Sureserve (LON:SUR)
63p - mkt cap £99m
This share floated in 2015, originally called Lakehouse. I followed it for a while, met management because it looked cheap, but my views were inevitably tarnished by very poor performance, and all sorts of problems that emerged which needed sorting out.
It’s time for a fresh look, because the share price has been recovering strongly (although what hasn’t, in recent months?!) and the StockRank is now very high.

.
Sureserve, the compliance and energy services Group, is pleased to announce its preliminary results for the year ended 30 September 2020.
Strong performance ahead of expectations; stable platform for growth
Revenue down 7.7% to £195.7m
“Significant” covid impact
Adjusted PBT (profit before tax) £9.4m (up 13%) - a good performance in the circumstances, I’m impressed. Although furlough support helped.
Adj EPS up 11% to 4.9p
PER of 12.9 - looks about right for this sector, which doesn’t tend to attract high multiples due to being lowish margin, and things often going wrong
Net cash of £9.8m is good (removes IFRS 16 lease debt, as I always do, because it’s nonsense, and isn’t interest-bearing debt). It says this figure is “allowing for deferred VAT payments”, which is ambiguous. Net cash on the balance sheet itself seems to be £9,679k cash, and no reported bank debt. Yet the cashflow statement says about £6m VAT has been deferred. It’s not clear how this has been accounted for. Anyway, the overview is that the net cash figure is a temporary, artificially favourable position, due to creditor stretch.
Order book of £355.8m (up 6.8%) - demonstrates strength of what must be multi-year contracts, giving good visibility I imagine
Note 35 shows that Bob Hold provides consultancy services at a rate of £1,595 plus VAT per day! Who does he think he is, a partner at an auditing firm?! Oh no sorry, it’s per day, not per hour, so he’s a bargain in comparison with the audit partner.
Dividend of 1p is being recommended. Historic divis have been very small, suggesting to me that it’s not a very cash generative business.
Divisional performance - compliance did very well, with EBITA up 40% to £11.8m, and a decent 8.6% profit margin. Energy services did badly, hit by covid in H2, with EBITA down 82% to only £0.8m (a 1.3% profit margin)
Outlook comments -
We have started FY21 strongly and, with 77% of revenues covered by our £355.8m order book, we look forward to the business continuing on this growth trajectory."... well-positioned for further organic growth in a fragmented and regional market”
Going concern statement seems OK, but note bank facilities are due for renewal by 31 Jan 2022, with initial discussions having taken place and the company says it does not anticipate any challenges.
Balance sheet is adequate, but not strong. NAV £50.1m, but intangible assets are £43.0m, so NTAV is quite small at £7.1m.
Bank debt has disappeared temporarily, but trade payables look high,
Note that right of use assets is mostly commercial vehicles, plus some leasehold property, just mentioning it as that’s unusual, but OK.
Receivables are high, and includes £17.3m of accrued income - i.e. services provided, but not yet invoiced.
Ageing of receivables (note 21) looks good - i.e. most customers are paying on time, which suggests a blue chip customer base.
Trade & other payables are high, at £42.8m, which includes the late VAT. Taxes due has gone up from £5.1m LY, to £10.5m this year. Remember this will unwind in due course, reducing cash.
Cashflow - exceptionally cash generative this year, due to stretching its creditors. This will unwind in future, remember.
My opinion - this is better than I expected.
Temporary creditor stretch flatters the cash position, but once it normalises the debt position looks fine.
There could be scope for FY 09/2021 performance to beat 2020, if the energy division is able to recover. Although with autumn/winter lockdowns probably restricting activity, earnings recovery might have to wait until the following year maybe?
Overall, I don’t tend to invest in this sector, as things often go wrong, and margins tend to be under competitive pressure, with not much in the way of differentiation or pricing power, for companies offering these services.
Although taking it as a given that this is not an appealing sector, then Sureserve looks OK within a not very good sector.
Why would anyone buy this share though? For me, investing is about trying to find exceptional companies, or super-cheap companies which are priced far too low. Sureserve doesn’t fit either mould. It’s just an OK company, in a fairly poor sector, that doesn’t even pay decent divis. I cannot see why anyone would pick this share ahead of all the other, superior companies out there. There’s nothing in particular wrong with it, but there’s not much right with it either. So why get involved? It would have made a cracking buy at the height of the crisis in March 2020 (what wouldn’t though?) and has tripled in price since. I think that’s probably as good as it gets, and can’t see any reason why it would rise any furthe from the current level of 63p. That looks a fair price, so personally I’d be looking to sell out after the big recent price rise, and find something with more exciting upside and better divis.
.
Bigdish (LON:DISH)
(I hold)
1.35p -mkt cap £5m
Another day, another business plan! To summarise the latest update today -
The restaurant dining app has now been put on hold.
The newly created "venture builder" - "to be spun out into its own listing"
Another new business is being created in the Philippines (where the Chairman/biggest shareholder lives), a JV (70% owned by DISH) to manufacture plant-based meat products, it's called Amala Foods Inc. It says no additional funding will be needed during the 6-month setup period.
My opinion - I haven't really taken this in yet. This share was always a punt, but what I'm actually punting on keeps changing!
People keep telling me it's going to 0p, but they've missed the main point. The Chairman is very entrepreneurial, and will use the listing to do something else, if the original plan doesn't work. He's well connected too, and has proven the ability to access funding.
You might understandably scoff at the above, but bear in mind that in a bull market like this, there have been some spectacular profits made when an interesting new business is reversed into an existing cash shell, particularly if it's something tech, or another fashionable sector.
I'm happy to hold, and see what happens. It's just a complete punt, nothing more than that.
.
Dev Clever Holdings (LON:DEV)
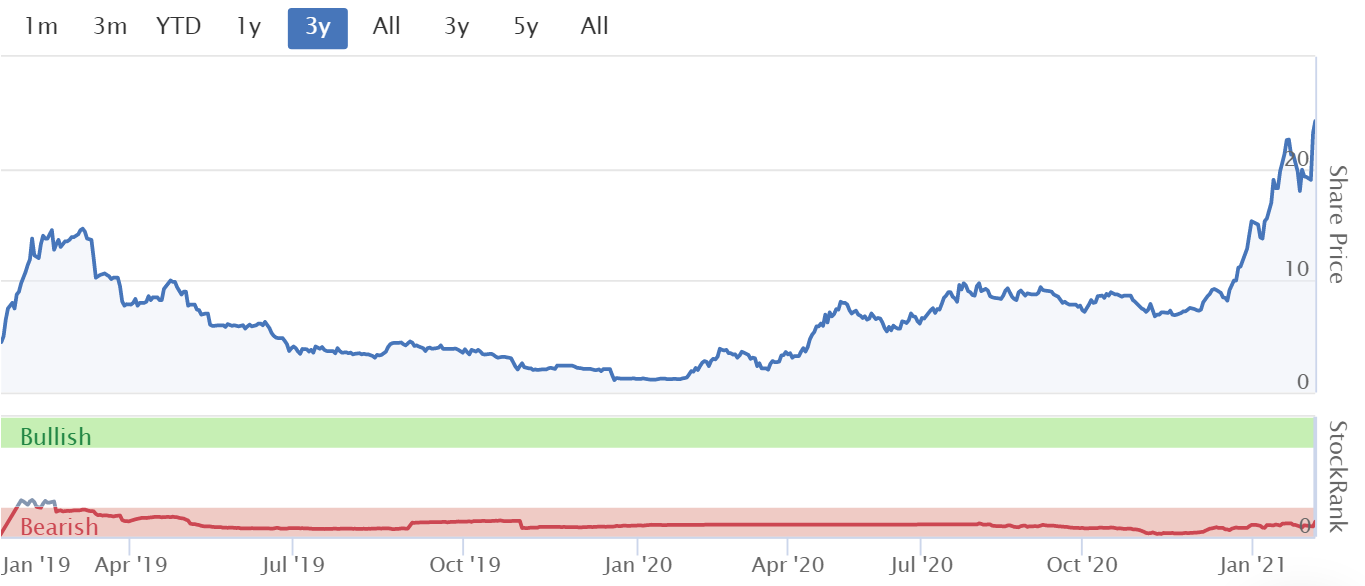
23.75p - mkt cap £114m
A reader has asked me to take a look at this. I’m not familiar with the company, which listed in Jan 2019.
Background - Graham looked at it about a year ago, here, when the price was only 3.45p - I bet we’re all wishing we’d had a punt on it then, as it’s nearly 7-bagged since!
Of course that doesn’t mean it’s any good, it could just mean that people may have chased the price higher in a roaring bull market for speculative shares.
Graham concluded that it was too early stage to form a view, a year ago, with negligible revenues, but some potentially interesting projects in the pipeline.
I've reviewed the company's announcements, and summarise them as follows -
Interims - to 30 April 2020 - nothing much here, only £383k revenues, operating loss of £613k in H1, so a tiny business, little more than a startup judging from these numbers. Nothing on the balance sheet either.
29 July 2020 - raised £250k at 10p. Plus the CEO converted £21k of loans into equity. 441.1m shares in issue, in total at this point.
3 Sept 2020 - £1.75m raised at 10p per share. More warrants exercised at 1p (check how many are outstanding). Total now 470.m. Seems to be part of a 10p funding line of up to £10.0m from a Jersey-based investor.
10 Sept 2020 - Trading Update - FY 10/2020 in line with management expectations “Acceleration in forward momentum over the past several months”. “Materially significant contract win” of $1.2m, to “undertake two COVID-19 careers impact assessments” in USA & India. Mentions partners Lenovo, and Veative.
17 Sept 2020 - Partnership agreement for non-core product. £115k fee, and revenue share, for “PubWars”
2 Nov 2020 - Extended agreement with Intrinsic Capital Jersey Ltd (ICJL) for more funding at 10p per share.
6 Nov 2020 - Heads of terms signed for online careers advisor software, in India. No financials disclosed.
1 Dec 2020 - ICJL puts in another £2m at 10p/share. Has the right to buy another 60m shares. NB 50m warrants issued at 25p per share.
21 Dec 2020 - follow on from 6 Nov announcement. Deal now signed, 5 years. No financial terms provided.
27 Jan 2021 - Funding agreement with ICJL tweaked yet again! Notes “substantial increase in the Company’s share price since the start of 2021”
2 Feb 2021 - Fundraising with a different investor, called One Nine Two Pte Limited. £4m going in at 20p per share. Then a further £6m at 30p per share, if the share price gets to 34p or above for 5 days. 40m warrants with an exercise price of 50p per share granted. Funding will be used to further accelerate growth strategy.
3 Feb 2021 - Trading Statement.
Dev Clever (LSE: DEV), a leading developer of online and immersive career guidance and development platforms and consumer engagement experiences, is pleased to provide the following trading update:
The Company made significant progress in the last financial year, ended 31 October 2020 ("FY 2020"), and achieved accounting revenues of £1.2m, subject to audit, and booking revenues of £2.4m. This represents an increase from £480k and £500k respectively from the previous financial year and is in line with management's expectations, reflecting the considerable progress the Company made during the year.
Still trivial revenues, considering the market cap is now £114m.
Current trading -
Q1 2021 revenues are c.£1.2m, up considerably (but still small)
Booking revenues were substantially ahead of management's expectations and, as a result, the Company expects the rapid acceleration to continue throughout the remainder of FY 2021.
Funding secured, and in the pipeline -
… enables the Company to accelerate investments in additional complementary growth and value generating initiatives.
So we can expect lots more exciting announcements, no doubt! That’s a tried & tested way to keep punters interested in the shares.
It lists all the deals done in FY 10/2020, but with no financial details given for any. So how can we possibly value the shares?
My opinion - I’ll keep an open mind until we get some meaningful numbers from the company, over the next year or two.
For now though, it looks to me like a jam tomorrow ramp! Contracts & unquantified deals, frequent announcements, but negligible revenues & no profits. The funding structure looks odd. Why on earth would you want to invest more money at a higher share price? Possibly so that the shares could be profitably flipped somehow? Or as a device to lead the share price higher? Logically, the trigger for new share subscriptions should be based on how the company performs (profit, revenue, EBITDA targets, etc), not based on a rising share price.
The rapidly growing number of shares in issue, combined with a share price going exponential, means that this share already looks as if it’s detached from reality in market cap, and that could continue - after all look at Tesla. Inevitably though, gravity reasserts itself at some point. It looks like a speculative bubble to me, but good luck to anyone punting on it! It’s a good strategy to get your cost money out I think, with this type of thing, then run the profit for free. That way, when it does crash, no harm done. Plus of course, in this type of frothy market, people can make a ton of money on speculative stocks - and good luck to them!
I remain to be convinced that there's any substance (excluding its cash pile) to this company to justify even a £10m market cap, let alone £100m.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

128 comments
At the end of the pandemic, I hope that someone is going to collect all the arguments on all sides about the Covid data, the deaths, the testing, the lockdowns, the vaccines, the risks, and clearly demonstrate why some were wrong and others turned out to be right.
But I’m probably being naive in thinking that it would get those who called it wrong to admit that they did so.
Too many of us are like the person who believes that they can drive safely having had three or four pints of beer and therefore have a right to flout the laws around drink driving.
What with the idiots holding mass events such as weddings, people who don’t want to “be a guinea pig” for the vaccines ignoring that 1000s of volunteers in trials have already been the guinea pigs on their behalf, to those who believe the tests are simply wrong and the hospitals are empty, too many of us would just believe that a fringe view on the net is more credible than a whole team of scientists working for the government. And so the government have got no chance of getting a good outcome to this.
We need to stop pussyfooting around with the vaccine. If you’re in a front line job meeting lots of people you must be vaccinated. If you don’t want to do that, sorry but you cannot do that job anymore than a person with defective eyesight could be allowed to drive a bus.
As a community, I imagine we collectively should have an above average ability to process information, to separate the proven, the probable, the possible and the implausible and to form a rational risk assessed view of things.
It is not easy to reconcile this view with some of the Covid related discussions in the comments today.
I do absolutely understand that there are valid differences of opinion as to where priorities should lie (and should have laid thus far). When expression of these issues decay to plain disinformation, I have to reflect on how sophisticated we really are in this forum and how we should not be surprised that disinformation permeates in the broader (less discerning?) community.
To come back to investment relevant matters ; I humbly suggest (not for the first time), we might be better focussed on what restrictions are likely to be increased or relaxed. Whilst what any of us think SHOULD be done might be "interesting", what is far more relevant is what is actually likely to happen.
Been offline all day, as the latest this is my first post read. Should be an interesting scroll down :-)
Its not been a bad day on the bourses. +1.3% on top of yesterday's +1.6% for me.
EVRAZ (LON:EVR) down 3% - possibly sanctions against Russia spooking investors.
Plus500 (LON:PLUS) +1.2% - second day out of the doldrums.
XLMedia (LON:XLM) - 1,000,797 shares traded today, probably The Mitterand's buying up Axion's stock, +6.32%.
Your narrative gets my vote Gromley. Much common-sense, which unfortunately is not always so common.
Also I cannot help but agree with the views expressed by GrahamF. While Graham's final paragraph in respect of making vaccination a pre-requisite for certain types of employment may sound somewhat draconian it is perfectly rational, in my view.
I shall leave the Covid debate there and get back to trying to better understand the investment merits of UK small caps.
"false equivalence"
That's precisely the point. COVID-19 is an elevated crisis because other equally horrid conditions are lowered.
I don't see this as anything more than an extreme end of the routine. Bad bugs come along occasionally like bad weather, bad stock markets, bad governments.
Saga (LON:SAGA)
My view is that demand will be bigger than it was before covid, not just returning to normal. There will be a lot of folks that will entertain a no stops cruise with some nice views in a floating hotel, of all ages as a way to get a change of scene, long before they will venture onto a plane or into a holiday destination. I think SAGA may well appeal to a younger demographic from now on as a consequence. It isn't just the old crumblies :)
We took my mother on Danube/Douro/Greek Island cruises over several years. The perception that these are for the older generation is frankly a peculiar british caricature in my experience. Cruisers were typically well heeled and cosmopolitan. What's not to like about drinking a bucket sized gin and tonic on top of a nice boat by the pool watching a castle float by. SAGA is aimed at the over 50s, not the over the hills.
(I hold)
Highly likely that people who refuse vaccine will not be able to get travel insurance and/or will be refused admission into multiple countries around the word and/or "at a minimum" will have to quarantine on return to the UK. I certainly would not want to be on a plane with any such person.
Indeed I think is a very strong argument for refusing such people access to all sort of venues where people are heavily concentrated, as it will enable us all to be more confident about getting back to life as normal. Obviously there would have to be an exception, at least for UK citizens in the UK, who are advised medically that they should not be vaccinated,
If you have been vaccinated why would you be concerned about another individual being on the plane who has opted not to be?
If we move towards discriminating against people who choose not to take a vaccine it is a very dangerous step in my opinion. It's outrageous.
I'm no crazy anti-vaxxer by any means but refusing to be a guinea pig for a cobbled together, unproven vaccine should not result in being refused entry to any event, travel scenario or employment situation.
So, this is the park story
Stockton 'riverside park' to replace shopping centre approved - BBC News
As for Nottingham, I wasn't thinking of any particular part of the city centre - it has everything one needs for retail as a leisure activity, easy transport (train and tram), plethora of watering holes, awesome shops including a designer area with boutiques as well as the big chains, restaurants, cinemas, theatres, ice rink for extending your trip into the early evening. It hasn't been too blighted by ugly architecture either and there's lots of pedestrian only areas. The local council are generally rubbish, but they've got the best city centre in the midlands so deserve some credit I suppose.
As someone who has done plenty of cruises (I am approaching mid 60's), I think there is huge pent up demand....even if getting off at the various ports is limited. Indeed, even before the pandemic the "all aboard" time was often 4pm so plenty of older cruisers do not get off the ship anyway or just go onshore for two or three hours. For many, the "experience" matters more. The huge number of food and drink outlets, the variety of events, entertainment, meeting people, quiz, relaxation, dancing, the spa, onboard shopping, art, casino and so on. There is a feeling of safety too (always a doctor on board) and security. Many older people plan their life around cruising as the numerous forums testify.
This group of people have generally done very well financially during lockdown (pensions have been unaffected) , have little debt and are itching to spend. As soon as the ships are given the all clear, the older generation will be happily trooping on board, vaccine passport at the ready, heading for the buffet, having paid for a double length cruise. They wont really care too much where the ship is going. Smiles aplenty. My wife and I will be among them.
I expect cruise companies to make a lot of money as soon as the ships can set sail again.
So a cruise that cost £5k will now cost £10k. A flight to Mauritius £700 now £3k. A caravan on the Dorset coast £50 a night now £150 - guessing but maybe set up a website to 'auction ' holidays - boom.
Paul Thank you so much for your views on Dev Clever Holdings (LON:DEV) have been buying since 2p but my analysis was similar to yours so very pleased to have it confirmed. Could I be greed and ask you to look at Zaim Credit Systems (LON:ZAIM) its 4th quarter results are out today it lends money in Russia and the headline figures all look interesting
Wow! Thanks Paul for the top slot on today's billings! Agreed Andy Brough and Tim Steer make accounting red flags wonderfully entertaining.
Idox (LON:IDOX) released and presented FY20 results yesterday. Here's the analyst presentation. Video & podcast. I love the terminology - they've gone from the 'Walk' and 'Run' phase, to the 'Fly' phase! A new management team headed up by David Meaden, CEO working with Rob Grubb, CFO. Revenue +4% with Adj EPS+39%. Some IFRS16 accounting adjustments have benefited them, but even so things seem to be heading in the right direction. Recurring revenues increasing nicely.
As regards comparison between Carnival and Saga I think that Carnival is in the much stronger position. If I recall correctly, it recently said that it had enough funding to go throughout 2021 without cruises. It also seems to be able to readily raise significant capital when required
Cruising is tricky. The vaccine doesn’t guarantee that people won’t get Covid. If say 1 in 1000 oldies gets Covid after vaccination (possible) statistically this could then happen every once every 3 or 4 cruises? What happens onboard in such a situation? Does the cruise just continue?
Plenty of questions re cruising in my view.
I think you are missing the point intuitive6191. Saga (LON:SAGA) remains cashflow positive and profitable even without ships sailing. That's because of its insurance division.
Carnival (LON:CCL) on the other hand has a better balance sheet than the basket case you'd expect it to have but has a mass of debt and is entirely dependent on sailings for income/profitability.
Thus delays to cruising might well delay the Saga (LON:SAGA) recovery but to Carnival (LON:CCL) could potentially sink it if it became long term!
btw I don't think that's likely, and certainly not a base case, but shows why Carnival (LON:CCL) is not in a much stronger position. at all.
Interesting stuff Paul/ TStubs. It seems to me that the real competitive advantage of online shopping is the sheer range on offer, it's adaptability and it you can do it 24/7.
And don't have to worry about parking tickets. High Streets were dying long before covid.
Recent news from Parity (LON:PTY) suggests that there is a successful turnarround underway. (I have no position, unfortunately).
It doesn't surprise me that many male shoppers are happy with online purchases. I do get a sense from some women that they are bursting to go to Town Centres and shop, have coffee , meet friends in town etc.
Last emergence from Lockdown and it was heaving in my town, but then the weather was better.
I wouldn't count against people hungering to get out and about, and go into shops. Whether they buy anything is moot.
M&c Saatchi (LON:SAA) Paul wrote in Jan: "Personally I'm giving SAA shares a wide berth for now, due to accounting problems, and some nasty dilution potential from poorly structured options-based acquisition payments. Although advertising & marketing are obviously good cyclical sectors in an economic recovery."
Today we see a 5.6% dilution from options based acquisition payments... I think if I've understood that correctly and dun alrite on me maths?... Paul what do you think the overall dilution potential is? I've done well on this share, it's nearly doubled, but would like a fuller picture on this issue, but not sure how to find it in the stock report.
Afternoon TStubbs, Paul covered the dilution potential in some detail back in October:
https://www.stockopedia.com/co...
The total dilution could be as much as 40% over 5 years at current price levels. I too did very well out of this share, but sold out completely a couple of weeks ago as I had Paul's warning firmly in mind.
Thanks for that, sorry Paul et al for not spotting that.
Jet2 (LON:JET2) mentioned by Paul, and I like the chart on this one.
Forming a nice base on tight volume after heavy volume on the previous leg up.
It's been moving almost vertical for the last week or so, so ideally i'd be looking for it to pause for a week or so at the resistance level (as I've sketched on the chart), then a push through into the buy zone on good volume. That would be an entry point for me.
Note: 'Buy Zone' is the resistance level +5%.
Paul: "we should be pricing in a return to near-normality into shares. Not at some distant point in the future, but imminently, i.e. the next 2-3 months"
In my view prices should reflect the substantial risks that still remain. For the moment I'll ignore a long list of other risks and focus on covid. I don't think we should ignore some of the other less welcome news recently, including:
- No one knows how effective the AZ vaccine is for over 65s. There is not enough data to be confident either way. Contrary to what you might read in the Brexit press, various EU countries are making rational decisions in not giving this to over 65s (yet). All that we know is that many vaccines are substantially less effective (e.g. half as effective) in this age group.
- The great hope for treatment, as opposed to vaccines, was the antibody drugs. These have (broadly) failed aginst the current mutations that are becoming the dominant forms of covid. The fact that antobodies generated by plain vanilla covid do not work against current forms should give pause for thought in celebrating vaccines. It doesn't mean that they wont work at all, but it probably does mean that they are significantly less effective.
- The Brazilian city of Manaus should also give pause for thought. The city was devastated by covid last year, around May time, and it was thought by many observers that about 75% of the population contracted covid and that they had "achieved" herd immunity. Today they are being devastated by a second wave, driven by 2 new variants, with a death rate even higher than last year. To me (no relevant qualifications) this looks like strong evidence that current vaccines will fail against the new variants.
This looks increasingly like a race between a rapidly evolving virus and the rather cumbersome process of vaccine development. I have faith in society's ability to make rapid technological progress, but equally I have no faith in this country's ability to keep new variants out. Even if we managed to keep out the pesky foreign viruses, our domestic version would probably evolve to do the job itself. The Kent variant seems to have already evolved again in an equivalent way to the South African mutation.
I hope that we are on the way out of this mess, but the history lesson here is that many people have been too optimistic about this disease before and fallen flat on their faces. Putting the pieces together (too many to list here) I would say that there is a chance that a return to pre covid lifestyles is still a long way off - a big enough chance to not be ignored.
"Putting the pieces together (too many to list here) I would say that there is a chance that a return to pre covid lifestyles is still a long way off - a big enough chance to not be ignored."
And that's what concerns me.
No politician will want to take the blame for unlocking. They'll pay it safe. Politicians will go for "herd immunity" of lockdown doctrine.
The number of votes in it for them from the "granny killers" is less than number of votes from the "lock up the young and create unemployment" brigade.
This is a lot more complex than that. My Mum has been incarcerated in a care home for the best part of a year now. I think all corners both young and old are going to start pushing for release as soon as there is credible evidence that the vaccination strategy is providing sufficient protection to the vulnerable. So much so that the government won't be able to stop it without taking pretty draconian steps. Lockdown is going to have to end and it ultimately won't be down to politicians particularly those on a populist agenda.
We know from first principles that the vaccine will work in the over 65s. but that clearly this will tail off the frailer someone's immune system gets. There is no conceivable rational reason to think it will behave any differently to any other vaccine in this respect. The lack of data relates solely to the low numbers in this age group in the original trial cohorts and that when the numbers in this age group did start to be included it was at a time when the covid incidence in the UK was lower over the summer. I think it is right to watch and wait, however. There was some pretty encouraging news yesterday about the relative admission rates .
The challenge currently is to work out how effective the strategy is. We have vaccinated 10 million people in the last 5 weeks or so but some of them might have already been incubating covid, some will have contracted it in the early days before immunity kicks in so we are realistically only just now getting to the stage where we have a clean set of data.
I think that we will have a much clearer picture in a couple of weeks.
Early indications from Israel are pretty positive too with infection rates being 11x higher in an unvaccinated cohort compared to a vaccinated cohort.
Moreover, anxiety about variants is being overplayed at the moment imo. The main objective is to save lives. Whether a vaccine neutralyses less variant virions in a test tube is a measure, but ultimately it will be how this translates into severe morbidity or mortality impacts. All the vaccine has to do is reduce virus replication to the point where a cytokine storm is prevented for an individual and reduce the levels in the population that unprotected individuals are not exposed. I am of the view that it will, that we will be able to keep pace with variation by modifying the vaccine. This might end up driving the frequency of revaccination, but an increased frequency of revaccination is a lot more preferable than the social and economic costs of future lockdowns.
My concern at the moment revolves around the alarmingly high number of people that appear to be reluctant to have the vaccine. This is the biggest threat to our exit from this pandemic by a country mile in my opinion and this is not confined to the UK. Even at 92% efficacy, this will not prevent carnage if 40% of the population refuse to take it. This is being driven by a combination of fake news and by media reporting by people that do not understand the data and are looking for sensationalism. Hopefully this number will come down if the strategy can be seen to be working. It is for this reason that I am a bit more cautious about the short term.
In terms of UK, should we be anticipating a wave of job losses at the end of furlough. What will that do to stock market confidence? What if we do not get a deal on services? Is a deal priced in or is no deal priced in. The current tensions (vaccines, NI, mussels etc, jingoistic Johnson) strike me as not being particularly conducive to constructive discussion. What about IndyRef2 and Irish union? What if the impacts on cross border trade do not resolve or more likely get worse?
I know this is a SCVR board, but even when trying to read analyst opinion or even annual reports for that matter, their opinions on forward projections are inevitably clouded by sentiment. Saga (LON:SAGA) is up by 7.8% as I type. (I hold) We all know that SAGA isn't 7.8% more promising today than it was yesterday. The day to day fluctuations in mid caps is frankly bonkers. Always has been. Covid recovery and its impact on stocks I think will present some exciting opportunities, but some companies are just crap. My fear is that there will be some out there that are many poorly performing for other reasons, and that it is being masked by covid, masked by furlough, debt, vat deferral etc.
Interestingly just watching Bloomberg. They are having a discussion about wondering what fundamentals are in this day and age? I read the SCVR as part of my efforts to beat the market. This necessitates the market getting it wrong. The market looks at the same fundamentals so it has to be about whether we agree with market sentiment. Paul feels that SAGA is due a rerate and I agree but how can the market be so wrong? these are all grown ups setting the price aren't they?
The take up of the vaccine has been high, in the older age groups, one poll said 81% in over 65s would have it, think you will find it much higher in the over 80s, just read over 90% have already had the first dose. Yes take up in younger people, may well be lower but they have less risk of dying.
I'm not really concerned, if virtually all the over 60s have it then the death rates should fall dramatically.
From what I understand, there is more resistance to vaccination in BAME for example and this also appears to be a more at risk group. Don't know what the actual % needs to be to get herd immunity but I think it must be more than 70% now with the increased R of the Kent variant. If 81% is reflective with a vaccine of c90% efficacy this still means c25% of the vulnerable population 'vulnerable' This feels too high to me.
The issue about less take up in the younger groups is that this inevitably means there will still be a lot of circulating virus especially when people start to take their foot off the gas re social distancing and masks and the like, we could easily end up with the same number of deaths. Tackling refusers will be key imo, and this means tackling and silencing antivaxxers and correcting media misinterpretation. If we don't and the rates go up, the vaccine will get the blame.
I am frankly shocked that 19% of vulnerable adults would say no to the vaccine but then this is the same mad world that gives us Trump and Brexit (oops bit political)
Right, but this goes back to people not understanding what efficacy means. All the research so far shows that 100% of people, after the 22 period needed to gain the benefits of the vaccines, do not end up in hospital.
The efficacy number doesn't lead to a binary outcome for the recipient
"The issue about less take up in the younger groups is that this inevitably means there will still be a lot of circulating virus especially when people start to take their foot off the gas re social distancing and masks and the like, we could easily end up with the same number of deaths."
I don't think that is correct, most of the deaths have been in the over 65s, believe the figure is over 90%. If the vaccine is 94% effective, then the number of deaths will fall, it won't be the same.
I agree the take up needs to be as high as possible. I think in the over 65s it will be high, some had concerns but I think most will come round to having it, 10m people already have.
Over 80% of over 65s had the flu jab this winter which is a record.
Point accepted. Quite agree that number of deaths will come down, but there will remain a cohort that are not protected because of the efficacy rate and the refusals in the at risk group. These people are still at risk of getting infected and a % will still die. I am not sure what 94% effective means to be honest. What is it measuring?
The point I was trying to make, perhaps rather inelegantly was that imo vaccination will work, but it will work even better if we have a high uptake. My experience with vaccinations (veterinary) is that a 94% efficacy rate translates into 6% will still be vulnerable to infection not that they will only get 6% worth of the disease each but I accept that this might not be the only interpretation. We should at least agree easily that people not vaccinated cannot expect protection from the vaccination. 19% of 100K is still 19K if the overall vaccine in circulation remains the same.
These people are still at risk of getting infected and a % will still die. I am not sure what 94% effective means to be honest. What is it measuring?
It's the difference in infections detected between the control group, who didn't get the vaccine, and the vaccinated group, who did. Clearly that means that some in the vaccinated group still contracted CV-19. The good news is that the vast majority of those vaccinated who caught CV-19 didn't become severely ill.
However, people not vaccinated are still protected, en-masse, if we reach herd immunity levels. If I catch it and give it to 3 people (R=3) of whom 2 are vaccinated (because two-thirds of people have had the vaccine, assuming it's 100% effective) then the actual R rate is only 1. If more than two-thirds of people are vaccinated then R falls below one and the prevelance of the disease in the community drops.
Obviously the vaccine is not 100% effective, so the numbers need to be adjusted a bit.
At herd immunity levels unvaccinated individuals are still at risk, but it's a much, much lower risk. If we vaccinate everyone at risk then severe cases and death rates should collapse. They won't be zero, but they'll be easily at a level that the NHS can cope with alongside normal services.
If a mutation escapes the vaccines entirely then we're back in the same situation, but with the knowledge that a vaccine can be developed that will block it, hopefully quickly.
Oh, and it looks like vaccinated people are less infectious, so a vaccinated person would (say) have an R of 1.5 instead of 3. Every little helps.
timarr
"If a mutation escapes the vaccines entirely then we're back in the same situation, but with the knowledge that a vaccine can be developed that will block it, hopefully quickly."
Throughout history and human existence, that has always been the case.
I don't think it wise to be living in fear of a "what if"?
It sounds like an Orwellian nightmare vision of enforcing compliance so that "Europasia"/"the bug"/xxxxxxx/yyyyyyy and zzzzzz doesn't get us.
From my side: We humans are smart enough, self-aware enough, brave enough, inventive, and collagic enough to solve these technical problems. That's why we are in charge of The Planet and the other organisms are not.
The same "what if" arguments were being used by The EU Remoaners.
94% effective means if you are infected with Covid-19 only 6% will develop it. Recent tests are showing that people who have been vaccinated and after 22 days none will need hospital treatment or die from Covid but it is very early days. AZ tests are also showing that the vaccinated will not transmit the virus as much. So the vaccinated will give be some protection to the unvaccinated.
"vaccination with the Oxford-AZ jab could cut transmission by up to 67%."
If take-up is as high as 81%, those unvaccinated can expect to benefit from herd immunity inhibiting the virus transmission through a lack of sufficient numbers of new hosts, hence damping down and eventually snuffing out the contagion; unless they are unlucky. What vulnerable (and other) people should do is accept the vaccine when offered.
I don't think that is correct, most of the deaths have been in the over 65s, believe the figure is over 90%. If the vaccine is 94% effective, then the number of deaths will fall, it won't be the same.
That is true, but the issue of the infection rate amongst younger age groups remains serious. If unvaccinated virus circulates widely amongst younger people, and in particular if they start travelling widely, then the risk of more dangerous variants increases - and some of those may lead to more deaths or more economic harm for a variety of possible reasons.
If unvaccinated virus circulates widely amongst younger people, and in particular if they start travelling widely, then the risk of more dangerous variants increases - and some of those may lead to more deaths or more economic harm for a variety of possible reasons.
That's true, and the risk of younger people not getting vaccinated is a problem. But ...
We haven't studied the progression of a pandemic disease in real-time before so it'll be interesting to see how it progresses. However, the theory is that if children get repeatedly infected while young they develop increasing immunity so that if they catch variants later in life they don't get seriously ill, and pandemic diseases "disappear".
That runs counter to protecting the older population, who don't want anyone getting the disease because it could be fatal for us. But that's not fair on younger generations.
I think we have to accept that as older people we'll need to have an annual jab and may face occasional restrictions - or be prepared to take the risk. The incredible improvements in vaccine technology that we've seen in the last year - particularly using mRNA - offer a lot of hope that any limitations will be relatively short-lived.
Personally, I think young people have already done more than enough. I know the papers are full of stories about reckless behaviour but an R rate consistently half or below of the natural rate tells the real story. As soon as over 50's are vaccinated and the NHS is protected it's time to move on, release lockdown measures and let the kids have their fun.
timarr
not to mention global warming!!
I read a report about Poland, which has a very high % of Anti vaccine believers, However when people were not taking up the vaccine, high profile celebs and Politicians found they could jump the queue and now the demand is considerably higher.
Great depression
Hi Millbank
Great article and agree that it is hard to understand the future, post Covid.
My worries are that we are all expecting a boom in the leisure industry, and that post Covid, there will be a bounce in the stock market as a result of the Fed creating loads of $.
Perhaps and certain companies such as £Saga will do well, but I think we are being optimistic re a return to normal.(I hold)
My question is that a lot of these service sectors have been decimated, and unemployment will rise sharply in the USA ,UK, and Europe. Think of the High Street shopping chains. This is not a political statement , but if you have no consumers ,the baby bloomers retiring, and hence a dramatic reduction in their spending, how will the economy grow. I believe it is correct that the service industry, makes up 80% of our economy. Also the younger generation, and here I refer to my children, have left university with debts in 50K range, both in professional style jobs with salarys in the range of 23- 26K. One living in Dublin and the other in London. Not a lot of spare consumer spending there.
My thoughts are that this community ,which I love ,should be having a running blog in which opinions regarding the future are discussed, allowing us to identify future trends and companies.
I also think that there is the likely hood of a major correction, starting in the USA, and that we are in a bubble market.
Robin Hood and Reddit being good examples
I am basing this on partially on Jeremy Grantham and the levels of the USA Stock Market. If there is going to be a 50% reduction, how do I prepare and get insurance.
U Tube-Why Grantham says the next crash will Rival 1929.
Could one of our smart investors, or our leading feature writers like Paul or Jack or Ed Croft do a series of articles and advice on this.
I am getting very scared.
Thank you
As a Dr who has seen preliminary evidence, I do not agree entirely
The vaccines have been shown to be efficacious against the variants, albeit less so.
The J+J vaccine was acutally trialled in South Africa and is thought to therefore reflect activity against the mutant. People were disappointed that is was only c66% effective; however it was 85% effective at preventing serious COVID and nobody died. I see the glass very full
Novovax also saw reduced but good efficacy against variants.
However, as long as the virus is raging around, the risks of new variants developing is very real and worrying.
For this reason, I am not as optimistic as Paul -but not as pessimistic as others!
Are you aware of any testing against the Brazil variants? My point about the current vaccine not working (as opposed to being less effective) was in relation to the Brazil variants. It is hard to explain what has happened there without concluding that any current vaccine would have failed. Other evidence is also starting to point to the virus mutating in the same way independently in different geographies, so what happens in Brazil could happen here.
I am not predicting doom and gloom, merely saying we should take in all the evidence. Neither am I a pessimist, though I fully expect to be labelled as such! That's what happened last year when Paul said a second lockdown was impossible and I offered evidence as to why he was mistaken.
I make no claims to know what will happen, but I do know that there is a wide range of possible outcomes.
On the news yesterday I think it was they said all these variants are being tested. Results are too early to tell. There are a number of variants, Brazil, SA and 2? UK ones now.
My point about the current vaccine not working (as opposed to being less effective) was in relation to the Brazil variants. It is hard to explain what has happened there without concluding that any current vaccine would have failed.
I don't think that's a given conclusion, although it's clearly a concern. This Lancet paper outlines the four possible reasons for a resurgence of CV-19 in Manaus despite the prior evidence that the region had already reached herd immunity levels.
https://www.thelancet.com/jour...
None of this guarantees that vaccines won't be at least partially effective and none of it means that we can't adjust the vaccines to cope with the variants, although that will take time and lead to more restrictions. It also demonstrates the vital need to vaccinate the whole world to reduce community transmission and the opportunity for further mutations.
What is does show is the utter imbecility of the herd immunity hypothesis, the crass stupidity of leaders like Bolsonaro with his "little flu" and the scientific madness of the "Swedish model". None of us are safe until we're all safe.
timarr
Is Sweden any worse than most other EU countries? I just looked at a chart and after increases in December the numbers of new cases and deaths have dropped off very significantly.
Is Sweden any worse than most other EU countries? I just looked at a chart and after increases in December the numbers of new cases and deaths have dropped off very significantly.
Hi doublelutz
Sweden had to introduce new CV-19 measures on December 14th following a rapid increase in cases, which necessitated Norway and Finland providing medical support :-/
timarr
Just as many local health authorities (and Police and Fire departments) have peer aid arrangements, small countries also have peer aid. Its entirely normal. Its a tiny country by EU and UK standards. This is not indicative of failure. Its routine.
"What is does show is the utter imbecility of the herd immunity hypothesis, the crass stupidity of leaders like Bolsonaro with his "little flu" and the scientific madness of the "Swedish model". None of us are safe until we're all safe."
That is what I think some people call "passive aggressive", Timarr.
Good day Sir.
Thanks for the link to the 27th January Lancet article timarr. One recommendation from this article which is worth reporting is "Sustained serological and genomic surveillance in Manaus and elsewhere
is a priority, with simultaneous monitoring for SARS-CoV-2 reinfections
and implementation of non-pharmaceutical interventions. Determining the
efficacy of existing COVID-19 vaccines against variants in the P.1
lineage and other lineages with potential immune escape variants is also
crucial." This emphasises what I suggested a couple of months ago that, despite the impression sometimes given by mainstream media, there is still a large amount which is not know about this virus, particularly in relation to its ecology. This makes it difficult to predict how its interactive behaviour with us will translate into death rates and even more diffult to work out the impact on share prices in a given sector. However, some of the best bargains are to be had when there is a lot of uncertainty, so perhaps this lack of knowledge could be regarded as an opportunity by brave investors.
Thanks, I saw that paper. To cut to the chase, while they don't dismiss these options, they seem to pour cold water on the likelihood of an overestimated infection rate and that of dwindling immunity, hence why I said "hard to explain". The other options would be bad news for current vaccines (as would dwindling immunity btw, I find it hard to see a 4 monthly injection cycle being successfully maintained).
Even if it can't be explained in a way that is positive for current vaccines, that still leaves open some possible solutions including a reengineered vaccine, but it would suggest there is a problem to be solved.
I am not capable of being so pessimistic. It is not just the "Brexit press" that are optimistic. On the BBC this morning Oxford University are saying there is evidence the vaccines quite apart from protecting the person receiving it can have a substantial effect on reducing transmission to other people. There is a high degree of confidence that the vaccine works on all ages. I don't understand the comment regarding "cumbersome process of vaccine development". The development has been nothing short of dynamic and those produced by biotech companies such as Pfizer will probably be amended to deal with any dangerous variant in short order.
I suspect some of the EU concerns are partly politically motivated. Obviously, the developers are going to be careful as to the claims they make regarding the vaccine as those in the US in particular would not want to leave themselves open to legal issues should anything go wrong. However, I am 76 and I have 100% confidence the vaccines will work and that I will be going out for meals and holidays immediately I have had the second dose and venues are open.
Looking at diversifying outside UK but struggling to get good info.
I bought Micron recently but took a bit of digging to understand why it was at such a discount to its peers on a forward PE multiple. Not trying to ramp it. I could be backing a loser what with the geopolitical tension stuff around Taiwan and the US China disagreements.
Does anyone have a suggestion for a good source? Anyone on here use the stocko international bolt ons for example?
From a female perspective (I hold ;-) I wouldn't write off the high street quite so readily. The Saturday shopping trip when you're young and single or want to meet up with friends is a pleasure to a huge percentage of the population, literally millions of people. There is only so much coffee you can drink or food to consume, hitting the shops is a day out, and part of that day is shopping for clothes and accessories. Then there are the days you go to town for a hair cut etc and a mouch around the shops.
It is not the people killing the high street but outside factors such as high rents & business tax v. low cost internet offerings who can discount for the moment as it kills off the old school competition. Unless the playing field is levelled off this isn't going to change. But the loss of tax after the horse has bolted from the high st, will concentrate government minds on how to get the tax revenue out of the internet companies. Maybe a delivery tax or a cardboard tax, who knows, but they will work it out eventually when they have too? Rents post covid will come down considerably. When these changes are made hopefully the high street will flourish again. I personally would much rather buy in a shop than online, see the item, it's actual colour, feel the material, check the quality, try before I buy. Flit quickly through a shop and not spend an hour online fruitlessly clicking in and out of boxes. Plus it gets you out of the house into the fresh air. Did I mention you can meet your friends!!!
Asos (LON:ASC) have, at great, cost picked up the name Topshop etc, but don't plan to keep any of the shops open. This is a massive loss to the high street shoppers, who are going back post Covid to an empty high street, and have lost a well loved shop. Is it the right decision? I am convinced the demand for a trip out shopping hasn't really gone. I would not be surprised if we saw a fresh chain of clothes shops start up in the void. What is to stop Topshops ex-staff and designers not being that competition? It is Covid that put the nail in Topshop (etc) coffin, not 'inevitability' which is an unproven theory.
I agree the platforms Asos (LON:ASC) Boohoo (LON:BOO) and Next (LON:NXT) even Marks And Spencer (LON:MKS) are creating an online high street experience with multiple 'shops'/ labels, with one check out. Asos (LON:ASC) and £BOO (I hold), are currently cherry picking the profit margins not having the costs of the shops. Next (LON:NXT) are keeping a symbiotic foot in each camp, they are the oldest players of this game having always had a catalogue business running alongside. I think Next (LON:NXT) would have been the better choice for picking up Philip Green's brands/shops, Topshop anyway.
It's going to be interesting to see how things play out. There are always going to be new kids on the bloc filling the voids. I think Asos (LON:ASC) massively overpaid for Topshop and co, and I hope that Boohoo (LON:BOO) keep their heads as they are maybe buying up more dated names. But they have a fantastic platform from the Debenhams purchase at a good price, in which to build an online shopping centre from. They are just going to have to strip out the dated brand, and use the tech.
Hi TStubbs,
Thanks for your thoughts, very interesting. You're right of course, that for many people, going into town for a shopping trip, is a social, pleasurable experience with friends. The CEO of Asos (LON:ASC) was on TV recently, saying he always thought (and still does) that clothes shopping is likely to reach, then settle at, half physical stores, half online. That sounds credible to me.
My theory is that some small towns could fizzle out completely as shopping destinations, and turn into residential, leaving people needing to travel further afield for shopping trips. That way there's more business for the survivors, who can make the business work with higher footfall in fewer locations.
As regards cost structure, I don't think online retailers do have an advantage. Many complain that they can't do it profitably (e.g. Primark said that's why they don't sell online - huge returns rate, logistics costs, etc, make it uneconomic). So perceived wisdom that online retailers have a cost advantage, is wrong.
A physical retailer has to pay rent & rates, but then the customers come to them. So the rent & rates are really just their marketing costs.
Whereas an online retailer only pays for a warehouse & HQ rent & rates, but has to spend millions instead on marketing, to drive traffic to its website. A lot of small to medium clothing retailers spend hardly anything on marketing.
I seem to recall that Boohoo (LON:BOO) (I hold) spends about 8% of revenues on marketing? Or was that Gear4music Holdings (LON:G4M) (I hold), I can't remember? Could have been both. That's similar to the % that a successful physical retailer would spend on rent+rates combined. I remember from my Pilot days, that our best shops (since defunct) would have rent+rates of c.10%, and the worst ones could be up to 20% (which was not economic). But we spent literally nothing on marketing (mind you, the internet didn't really exist then lol)!
The core problem is with commercial leases. What we need is a mechanism by which rents can flex upwards or downwards - turnover rents, in other words. Retailers can work profitably from stores, if they have a turnover rent, with a low base rent. But the landlords don't want them, because it lowers their capital values. They only agree to turnover rents in extremis, if the alternative is an empty unit. Then when things recover, they push the tenant back onto a standard lease.
Hopefully we might see landlords finally accept that things have to change permanently onto turnover rents across the board, otherwise the damage to High Streets and shopping centres would be permanent.
That's the big problem though, not that eCommerce has any advantage, which it doesn't, in overall cost terms.
Regards, Paul.
Edit: I forgot to say, with online fashion, the customer returns rate is typically 40-50%, whereas physical stores it used to be c.10% at the cheaper, younger customer end of the market where I worked. Probably lower than 10% for older, more affluent customers. Since you try the clothes on in the shop, the only reasons for later returning it, is if you change your mind, it's faulty, or run out of money & want your money back. We used to have a regular problem with youngsters using us as a hire shop, for a new outfit on a Saturday, then they would bring it back on Monday for a refund, having unpicked a hem and claiming it was faulty. But in the main, over 90% of sales in a physical store are final. The online retailer has to deal with up to half the stuff coming back, with 2 lots of postage & handling costs, then they have to sell it again.
Online really doesn't have the cost advantages that people think, just because they pay less in rent/rates. You have to think through the whole business model.
With online returns would there also be costs involved in repackaging? I would also be very surprised if there were not people who ordered a reasonably expensive item for a night out, wore it once, then returned it.
Thanks Paul for colouring in the detail and sharing your retail experience from the business side of the counter. Looking forward to shopping, socialising, lunch and cocktails again when ever that might be... in the meantime to making some money to pay for it!
Turnover rents are fraught with issues for a landlord and for a tenant. I am a veterinary landlord with a corporate tenant in several sites. I am pretty confident that my tenant will not want to go down this route anyway as they have weathered the storm well, and have growing footfall and client yield so I have not had to face this issue head on.....yet
But conceptually, the challenge would be how to measure site turnover and how the tenant would demonstrate that to the landlord. Would the site turnover for example include work recommended at that site but carried out at a hub site?, would the site turnover include pet health scheme income etc. The same principle must occur in say I don't know Next. If someone looks at something in the store but then orders it online, where is the revenue recorded? - this latter is my wife and I's modus operandi.
As a landlord I would be frankly suspicious of a tenant that wanted to move to turnover rent as it would imply that the tenant was anticipating a worsening situation. I would also not be happy if my income was dependent on the competence of the tenant. Pretty sure that landlords are only agreeing to them because they are backed into a corner at the moment. Being a landlord is meant to be low risk low yield. This turns it into high risk variable yield. How does a landlord get funding to leverage on a turnover rent lease?
From a tenant perspective, companies going for turnover rents may come to rue the day especially those with growth prospects unless there is a cap and collar arrangement as they could end up paying way over the market rate further down the line. If I was a landlord at the moment I would be looking for guarantees or guarantors and I would be looking for no break deals or I would be looking for a new tenant or a redevelopment option. It is just as cyclical as anything else. The tables will turn. I am not convinced at all that turnover rents are a universal panacea.
From an investor perspective, I am inclined to avoid any company looking to engage in them (unless early stage) because it implies they don't beleive their own bullshit about future growth. If they did, why on earth would they commit to an ever increasing overhead?
Every female i know well would agree with you that they prefer buying clothes in an shop rather than online.Admittedly all the females are over 40 so possibly the younger generation might have a different view
so pleased to read your comments on Carnival Paul as it’s my fourth largest position after Boohoo,Saga and Polar Capital . It’s nice to get some confirmation that I am not completely off my trolley ;)
I am in the 70 plus age group and am well aware how many of my acquaintances are desperate to get away on cruises etc .
I jumped on On The Beach (LON:OTB) today for similar reasons.
Bigdish (LON:DISH) another day another business plan.
Please read the Small Cap Dog of the Day before thing about investing.
https://www.stockopedia.com/co...
As always DYOR and avoid costly mistakes.
BSV
Nwf (LON:NWF) Interim results presentation given to analysts yesterday 2.2.21, by Richard Whiting, CEO & Chris Belsham, CFO.
Results in line with expectations albeit hit by Brexit and Covid. Richard and Chris run through the main highlights of the half year to November 30th, including more detail on the cyber attack (6m37s). Richard covers the strategy, including an overview of the UK fuels market and the acquisition activity (13m17s). Video & podcast.
Hopefully, you've seen The Signs Were There interview with Andy Brough and Tim Steer here, published last Friday. Artfully entertaining, which makes some accounting red flags easy to understand. piworld will have another fun interview this Friday.
Thanks Tamzin, you've reminded me to put in a link about your latest Andy Brough video, it is absolutely brilliant! Everyone should listen to it, full of pearls of wisdom, especially about balance sheets. Many thanks for the reminder, and keep up the great work!
Best wishes, Paul.
Thank you Tamzin,
I find your videos and podcasts invaluable.
The book "The Signs Were There" by Tim Steer is worth a read.
Very easy to read and full of insight about the troubles that business hide away on their balance sheet - real life examples from companies that we have seen over the years.
Morning Paul,
Thanks for the sterling job you and Jack do every day here - always educational, informative and enjoyable.
You commented - "I doubt whether I’ll go back to regular clothing shops much again, if at all. I wonder how many other people feel the same?"
I asked my far better half about this very same point last week and she said she may now do a trip to the shops once or twice a year going forward but that will be it.
She feels that she is limited by the physical outlets obviously holding fewer lines of stock than the online offering, that it is easier to order several sizes of the same item online to make sure she is completely happy with the fit, with relatively hassle free returns - those that companies where returns are more hassle are avoided for future online purchases, that she can try the items on in the comfort of our own home using several mirrors and with the option of pairing the items with other already owned items of clothing to see how they go together rather than squeeze into a small, cramped changing room with one mirror right in front of you.
In her view, other than a day out once in a while at the shops, why would you go to the high street?
For my own part, I hate going shopping and would much prefer to order online but again am careful to ensure that any items purchased can easily be returned, especially bulky or high ticket value items.
Richard
I thought, for some people, shopping was a social experience. It was more about being with your friends and having a giggle than it was about actually buying lots of clothes.
Probably worth trying to work out where these social shoppers are going to be placing their footfall, once we're out of lockdown, and trying to get in on the ground floor.
Retail and online cloths shopping? Sexist yes, but maybe for men online cloths shopping will be long term but for women I suspect not.
I wouldn’t write off the high street yet.
Well, I agree, but my counterpoint would be there needs to be a critical mass of shops to make it worthwhile - so your big "experience" hubs will probably survive, where one can go and have a large choice and do more than just shop, but the local town centre is pretty much finished imo.
So large experience centers like MeadowHall and Trafford Centre, as well as the better city centres (Nottingham is my favourite) will probably survive but rents will be reduced. But places like Gosport, Burton-Upon-Trent, Rotherham, Stockport and the like are probably finished in big name shopping terms. I note that somewhere (might have been Stockton on Tees, someone will correct me I am sure) has just knocked down their shopping centre and is turning it into a park. They won't be the last I am sure.
You may have been thinking of Nottingham's Broadmarsh centre? It was half way through a revamp when Intu Properties (LON:INTU) went out of business. Discussions continue as to what its future should now be https://www.bbc.com/news/uk-en...
Spot on iain1234.
The nemesis of the highstreets is Business Rates.
How can a business that has to pay Rates and employ many people compete with a centralised warehouse that uses robots and sub-contractors?
Royal Caribbean Cruises have their Q4's later today.
I'm almost equally as optimistic as Paul above regarding the easing of restrictions but I cast my mind back to last summer/ Autmun when weddings above 50 (or was it 100) people couldn't take place and wonder how they'll manage to get 400-800 people on a cruise ship anytime soon. Granted it's a floating hotel and I believe some of them are still open but a few hundred people clamouring for breakfast, lunch and dinner over the same two hour interval will surely be hard to manage. I suppose if transmission is indeed slowed by the vaccine and few to none of the people who contract it are hospitalised then perhaps it becomes a benign risk.
One of the developing problems I see is the public sector debt with the continual requests for money in the current climate. Government income must be set to fall over the medium term as their receipts are under attack from tobacco, alcohol and gambling issues and the loss of fuel tax due to increased use of electric vehicles over time. I think the burden of extra tax may well fall on the travel industry and I do worry about Saga longer term (I hold)
On your question "how eCommerce might be affected" - the IKEA shopping experience has improved during Covid. I used to despise visiting IKEA, but their click and collect service is outstanding - constant communication and quicker than the old days.
It will be interesting to see if other large goods retailers can also improve their experiences and ultimately their business models.
Their business model was to send you all around the showroom, that is why it was so horrendous, and time consuming. They have to change, they can't get away with it anymore, and they can now days, as they have the option to do so with an online catalogue, that is all they were trying to do anyway with the shops, present all their faire to you in the pre-internet shopping age.
"Maybe we should get her onboard with a complementary state room, or if
she's busy, then maybe Jane McDonald could be hired to burst into song
randomly, and accost any fellow travellers with Wakefield accents?"
(re Saga (LON:SAGA)). Jane McDonald? Please no! She's a brick through the TV in our house!
I laughed when AA Gill of the The Times said Carol Voderman's TV personality was like that of a Bus Tour Host on a Pensioner excursion. Jane MacDonald likewise!
Hi Paul
I’ve realised that I’m much more risk averse than you in my stock picks so in general I see the glass rather more half empty. Hence my differing view on many occasions. I appreciate where you’re coming from now with regards to BigDish (LON:DISH). There would be no point in selling out now and crystallising a loss, the earlier investment is effectively a sunk cost.
However, I’m just wondering whether, if you have large gains on some other stocks, it might be safer to crystallise some of those gains as well as taking a loss on BigDish (LON:DISH), then using the losses to offset this years gains to lower your CGT bill for this year. Although the talk around changes to the CGT regime in the coming budget has mainly been about the rate of CGT, I would not be surprised if other changes were made such as cutting the tax free allowance or putting a limit on the amount of losses that can be used to offset gains. So, it could make sense to take some additional gains now and use some losses to lower the tax bill in case that is restricted in the future.
On the subject of travel, you mentioned the fantastic roll out of the vaccines but what’s your view of the potential impact of virus variants on the travel industry? We’re seeing more discussion of stopping flights from countries with variants we want to keep out (and vice versa) and more talk of quarantines. How have those things affected your view on the industry?
Good morning Paul. Re Sureserve (I hold), you mention Bob Holt's consultancy. In my view, he has been a, if not the, major contributor to the turnaround. He previously built up Mears, taking the share price from 10p to over £4, leaving well before its current problems. He came on board as chairman at Sureserve on what looked like an expensive deal, but he and his team have turned the company around. The turnaround might not be over yet. It's difficult to disagree with your view of the sector, other than to add that management is key. A well run company can prosper.
Paul Would you be so kind as to look at today’s trading statement from Dev Clev Dev Clever Holdings (LON:DEV) which is a large holding for me. It seems to have plenty of cash, and lots of new contracts recently signed in the online education/career sector especially in India - be interested in your thoughts
Hi Cleeve,
I think you might regret asking me to look at £DEV ;-)
Section now published. Assume the brace position before reading it LOL!!
Regards, Paul.
Saga (LON:SAGA) - Paul your view is "I’m happy to just wait, this one should produce a good return over my 2-3 year timeframe, if things recover as they should. I remain of the view that the upside could be a 4-5 bagger in the long-term". Why not sell today and buy back in once it is on a new uptrend? In the meantime buy a share which is on the rise.
Why not sell today and buy back in once it is on a new uptrend? In the meantime buy a share which is on the rise.
Because I'm an investor, not a momentum trader!
I cannot predict short term price movements, so I just buy things that have good long-term upside. The short term share price doesn't matter to me, indeed I'm perfectly tolerant of short-term paper losses. In fact, I don't even record my buy price on my spreadsheet, because it doesn't matter, because if the market price is below what I think the company is worth, then I decline to sell at that price. Therefore the market price is irrelevant to me. Although it can sometimes be a warning that I've made a mistake in my analysis, so if something keeps falling, I revisit my research.
Everyone's got their own way of doing things! As my mentor once said to me, "Just keep doing more of whatever works!"
Regards, Paul.
Morning Paul - I know you like good book I am currently reading "The Art of Execution" by Lee Freeman-Shor. (A seven year period of analysis of 1,866 real investments by 45 of the worlds top investors)
Your description of yourself here exactly matches his most successful type - The Connisseurs
Saga (LON:SAGA) has been in uptrend since Nov 2020.
When will you buy £SAGA?
Exactly, I bought at 159p on Nov 9th and have enjoyed the uptrend with a 77% return so far. There is a definite uptrend but the ride is a volatile one based on Covid/Vaccine based news. I am with Paul and herbie47 on this one.
I have been mulling over an investment in Saga (LON:SAGA) for some time triggered by the comments in the SCVR.
In addition to the uncertainty over when travel will be able to resume (which of course gives the opportunity to acquire Saga shares at a lower price) a number of items have been holding me back:
I will be interested to hear the thoughts of others.
Hi Steve
Not a complete basket case, but It's just too indebt to consider for me.
My valuation model suggests not much upside from 250p based on EV/EBITDA valuation. (See graph).
It ranks 258 in my system which means I can find 257 better opportunities to invest in.
As always DYOR
BSV
The underlying profit of Saga for the 6 months to 31 July 2020 is £15.9m. This takes into account one off costs and profits and the write off of goodwill. I think this makes the adjusted EBITDA £36m which annualised is £72m.
The business is focussing on cost reduction, improving margins and rolling out new products and services. This should improve profitability.
If we take the EBITDA as static but add in the cruise ships running normally (hopefully this will be the case in 2022) this would give us EBITDA of £152m. The enterprise value is currently £1.1bn. This gives us a EV/EBITDA of 7.4.
What would be a sensible EV/EBITDA? 10? This would mean a EV of £1.5bn, so assuming the debt remains the same, a market cap of £715m giving a share price of £5.10. This is over double the current share price assuming normality in 2022.
Would be grateful Paul if you could cast your eyes on Vodafone’s (LON:VOD) trading update today (I hold).
This is meant to be a small caps report, hence the title.
I sometimes stray out of small caps into larger things, if I have a particular sector interest (e.g. retailers), but a £34bn market cap telecoms company doesn't come into that category, sorry!
Brief comment on Vodafone (LON:VOD) from TechMarketView's morning email. My cynical view is the giant telecos are essentially multinational utility stocks now. OK, fewer direct price controls but competition makes it hard for them to raise prices. I'm not a huge believer in the 5G revolution (though if it comes off it could provide a far more cost effective route to fast broadband than continuing to dig up last mile streets) as there is vast infrastructure investment required that ultimately has to be paid by consumers and businesses who perhaps are reluctant to pay the underlying cost for a minor lift in performance. Different considerations might apply outside the UK though.
Vodafone UK sees flat Q3
Martin Courtney, 09:40, 03 February 2021
It’s either a glass half empty or a glass half full depending on which way you look at it, but we suspect that a third quarter trading update indicating 0.4% year on year decline in service revenue for Vodafone UK will be welcome news for its management team.
The Vodafone Group as a whole saw organic Q3 turnover dip 0.3% yoy with a strong performance in its single largest market Germany (up 1%) offsetting bigger shortfalls in Italy, the UK, Spain and elsewhere in Europe. The mobile operator’s share price rose around 3.5% on the news as investors recognised things could have been much worse given the lockdown restrictions and subsequent economic disruption in most of Vodafone’s operating territories.
In the UK, sales of iPhone focussed consumer contracts and business demand for virtual call centre, productivity and security solutions helped to offset declines in visitor roaming revenue. It will be interesting to see if that momentum continues beyond April 2021 however, when Vodafone will impose a 3.9% price hike on all of its UK broadband and mobile contracts signed from 9th December onwards. That’s a strategy which would risk significant customer churn in any situation, more so in the current economic climate when many consumers are looking to shave costs wherever they can.
Vodafone insists it is necessary to fund further investment in fifth generation (5G) network infrastructure rollouts. Like telcos the world over, Vodafone is betting that enhanced revenue from 5G products and services in the long term will more than make up for any shortfall in the meantime – the big question is exactly when the perfect combination of 5G coverage, handset availability and consumer demand will kick start those returns.
Totally (LON:TLY), two positive RNS's this week (Monday and today). Small cap worth a look at.
Hi mercury61,
There's a good introduction to Totally (LON:TLY) on InvestorMeetCompany here.
My impression from looking at this share at the time, is that it's an interesting sector (outsourced services for the NHS), but that it doesn't really make any profit. Lots of revenue, but negligible margin. Management didn't float my boat particularly, but that's purely subjective. Although I can imagine them saying the right things in the right way, to fit in well with NHS authorities.
So it's not clear to me what the point is?
Still, the share price is going up, so could be a nice momentum trade, like lots of other things at the moment.
Regards, Paul.
Thank you Paul. Stay well.
My morning smallcap tweet:
BigDish (LON:DISH) Dev Clever Holdings (LON:DEV) Totally (LON:TLY) STM (LON:STM) Open Orphan (LON:ORPH) Time Out (LON:TMO) OTAQ (LON:OTAQ) Marechale Capital (LON:MAC), MJ Hudson (LON:MJH)
BigDish (DISH) continues to diversify from its loss-making core and is forming food technology JV with startup Amala Foods. "Amala is being established for the production and distribution of minimally processed plant-based meat products initially within Asia." Also Venture Builder to be spun out into its own listing. That was quite readable, Zak Mir must have mislaid his big book of business BS. Still a bargepole of course. [SP=1.35 Cap=5m]
Dev Clever (DEV) guides FY(Oct) accounting rev £1.2m (£480k). "Booking revenues" £2.4m. 21Q1 accounting rev broadly the same as FY20 and expects the rapid acceleration to continue. [SP=23.2 Cap=114m]
Totally (TLY) wins six-month contract extension worth c. £7.2m for urgent care. Planned Care div wins 3 year contract to provide occupational physiotherapy services to four police forces. No figure for that. [SP=32.4 Cap=59m]
STM (STM) guides FY in line with rev £24m, pretax £2m. CFO resigns, will stay for handover. She is thanked. [SP=26.56 Cap=16m]
Open Orphan (ORPH) opens quarantine clinic with up to 19 quarantine rooms. [SP=24.95 Cap=167m]
Time Out (TMO) mgmt contract for new Time Out Market in Abu Dhabi, opens 2023. Planned sites are now Planned - Dubai (TMO), London (TMO), Porto (TMO), Abu Dhabi (TMO), Prague (TMO). [SP=35.1 Cap=99m]
OTAQ (OTAQ) five-year £2m Coronavirus Business Interruption Loan. "Board continues to monitor and explore its financing requirements, particularly to fund further acquisitions." [SP=28.5 Cap=9m]
Marechale Capital (MAC) not aware of any specific reason for SP rise. [SP=5.08 Cap=3m]
In line: MJ Hudson (LON:MJH)
This is good for travel, leisure, hospitality, retailers (maybe), and the economy generally. I see a lot of pent-up demand, and a desire to splash out on luxuries, being unleashed.
We need to be careful of home bias - the UK is ahead of most countries in its vaccination program and travelling to places where the virus is still out of control will be difficult. The government, including (amazingly) the Prime Minister have been playing down the possibility of foreign holidays this year. That aside, I can see a big surge in the spring and summer as people are released from lockdown. Non-substitutable leisure companies - pubs, restaurants, UK hotels, entertainment - should see a big reversal of fortunes.
On retailers, I've been of the view for a year that the changes will be largely permanent. A year ago the science pointed to at least a year of restrictions and that was going to lead to irreparable damage to weak high street chains and a permanent change in way people shop.
Downsides (always invert)? I can think of two.
Firstly, while the virus is still able to spread anywhere then there will be mutations and it's inevitable at some point that one will escape the current vaccines. Expecting a complete return to normality this year is optimistic, but it's hard to believe we'll see another full lockdown.
Secondly, when restrictions are lifted there's going to be a surge in infections in younger, unvaccinated people. Will they lift before all over 50's are vaccinated - which roughly means April? Not sure, I don't think the government is in any hurry to loosen restrictions.
As for Iain Duncan Smith - well, here's what he said in November (writing in the Telegraph):
"The PM's announcement of a month-long lockdown is a body blow to the British people. Just as the economy was picking up, even giving cause for optimism, we are now to impersonate the Grand Old Duke of York - giving in to the scientific advisers and marching England back into another nationwide lockdown.
The way that the Government's Scientific Advisory Group for Emergencies (Sage) has pressurised the Government into taking this decision has been unprecedented.
Normally, advisers advise and ministers decide. Yet that system has broken down with Sage believing its advice to be more like commandments written on stone and its members publicly lecturing the Government over the airways when it disagrees.
This is despite the fact that many of its recommendations have been hotly disputed by other reputable scientists."
Not a mention of lives lost or the pressure on the NHS. It's pure motivated reasoning based on an ideological bias for libertarianism and free markets. Most of the time those are admirable traits, but not during a contagious pandemic when the actions of a few can cost the lives of many.
Libertarians need to re-read the Harm Principle and take it back on board. If they can't they're just shrills for the business lobby.
timarr
Libertarianism is a luxury best saved for the good times. It isn't going to work in a crisis, war, or global pandemic, which means to my mind, that it doesn't work at all.
I don't see a return to normal this year. Another year of managing risks.
The degree of concern about variants is palpable. The only successful ways of managing covid so far worldwide have been keeping it out completely (closed borders) and substantial lockdowns. The first hasn't been achieved in many large economies (China exception?) and the second is unacceptable for too many people long-term. Vaccinations have been recognised as the only practical alternative for the UK. We're still putting in new vaccine orders with an expectation that we might need different types to tackle newer variants and we'll need an annual booster programme. Eventually there's an expectation that we can get on top of mutations, but no confidence we'll manage this year. Getting track and trace working more effectively would help, but that seems a long way off.
So I see limited relaxation of travel restrictions this year. And that will likely be true for most developed economies. Night clubs and lying on crowded beaches in countries with lower vaccination levels (ie virtually everywhere), mixing with tourists from everywhere is likely to be out. Did that last year and within a few months prevalence was rising sharply with the Spanish beach strain dominant. Rishi's dishis isn't viewed as helpful now, even if it was seen as successful at the time.
There ought to be substantial easing within the country (though adult vaccination programme unlikely to be completed before autumn), but even that would be threatened by a variant that was unaffected by the vaccine. And the evolutionary pressure on the vaccine will be to achieve exactly that once a substantial proportion of the population has been vaccinated (this would be considerably mitigated if we could get prevalence really low - but, that would then make it even more important to avoid importing such variants from outside).
I've not seen many recent comments that it will burn itself out after a year or so, like 1918. And the 'there won't be a second wave'rs have gone quiet too. Morphed into conspiracy theorists and antivaxers. Worriers about the economy and libertarians remain, but the government was severely burned by giving into pressure for early release last year. Backbenchers don't care because no-one remembers what they said or voted for and they take no responsibility for outcomes, so noise in all directions will persist.
In other words, Timarr...
If you're against the lockdown (I comply as per my duty), you're "granny killers" and "baby killers".
"Not a mention of lives lost or the pressure on the NHS."
Mentioned at the start of every Downing Street press conference, and most MPs will have this at the top of their newsletters.
You are being selective to only listen to the soundbites. I believe Parliamentary "debates" are limiting MPs questions to 180 seconds in some debates. Are they meant to babble like on a radio advert?
And when do you mention the costs on society? Don't answer.
I have a friend who has made repeated suicide attempts during this crisis. Invisibly, real people are getting hurt by this.
As I said on Monday, few people will speak out against lockdown. Look at the +50 votes ups for you, and -5 and a "review" for me.
And when do you mention the costs on society? Don't answer.
I have a friend who has made repeated suicide attempts during this crisis. Invisibly, real people are getting hurt by this.
Yes sadly, people are getting hurt by this. No one is suggesting otherwise. But that doesn't mean the general course isn't correct. There's a load of evidence that the countries that have done best at controlling covid have also had the least economic impact. Failing to control it effectively leads to more economic damage, and sadly the problem in the UK is not that there have been lock downs, but that action has been to slow, and too little at times, and that there has been little attempt to control entry of the virus, and variants, into the country.
We might not be in this position now if action had been firmer earlier, but it's where we are, and the options are now limited. Removing restrictions too early will lead to a massive increase in infection rates, some of that will spread to vulnerable groups yet to be fully vaccinated, but also many in younger cohorts will be very ill. But more importantly still is that the faster rate of reproduction will lead to a faster rate of mutations and variant production. Many of those won't matter, but some will likely be more infectious, more lethal, more dangerous to younger people, and quite likely less well controlled by available vaccines. The alternatives to controlling the virus lead to more damage and more harm to real people.
And trying to write off people who support controls as people who accuse others of being "granny killers" does nothing to contribute to serious debate on the issue.
Fully agree Timarr (re. your home bias comment). Cross border travel and dealing with COVID measures and quarantines in other jurisdictions is going to be a minefield for a very very long time to come and may make recovery for travel stocks slower than many are bargaining for. Interestingly this is another tick in the box for the cruise lines. Singapore have been running 'cruises to nowhere' lasting several days and nights for quite a while this year and they are proving popular - gives people a way to go 'away' on holiday without having to deal with any other countries as long as you stay in international waters or even just outside port limits etc. I can see this meaning cruise companies will likely be first out of the blocks among travel and holiday sector in terms of a resurgence after lockdown, and also that this could squeeze demand in the short term due to lack of other options for eager holidaymakers...
Cross border travel and dealing with COVID measures and quarantines in other jurisdictions is going to be a minefield for a very very long time to come and may make recovery for travel stocks slower than many are bargaining for. Interestingly this is another tick in the box for the cruise line
Hi BIACS
I agree - athough I would as a Saga (LON:SAGA) holder.
I think Paul is too optimistic about cruising resuming - most of Europe won't be vaccinated until the autumn. But there's plenty of scope for round UK tours and I'd expect Scandinavia and Iceland to be open by the late summer. Southern Europe looks more tricky, but they'll be desperate for the tourism revenue.
However, the South American cruise next January involving a stop in Manaus ... ain't going to happen.
timarr
"It's pure motivated reasoning based on an ideological bias for libertarianism and free markets...
... If they can't they're just shrills for the business lobby."
Come on, really?
God forbid someone actually has a deeply held belief that people should be free to make their own choices in life with respect to their personal risk and that, perhaps, sacrificing over a year of our liberty and ceding extraordinary powers to government might have long term consequences.
Impossible. No, no, we're just 'shrills' for the business lobby!
That you have strongly held views on the topic is reasonable - it is extremely emotive - but deriding people who disagree with you by casting aspersions on their motives is really poor form for someone with your evident intelligence and usual balance.
God forbid someone actually has a deeply held belief that people should be free to make their own choices in life with respect to their personal risk and that, perhaps, sacrificing over a year of our liberty and ceding extraordinary powers to government might have long term consequences.
To be clear - private individuals have the right to take any position they choose, public figures need to be a lot more careful. The average individual has little influence over public policy or behaviour and, presumably, isn't directly or indirectly compensated for taking a position contrary both to science and the fundamental tenets of the ideology to which they claim to support.
However, anyone with a passing understanding of the Harm Principle recognises that there are instances - rare ones, but instances - in which individual freedoms need to be sacrificed for the greater good. A contagious pandemic where someone can pass the disease onto countless other people without knowing so would usually count as such an instance. In such a case your right to personal freedom conflicts with a risk of exposing numerous other people to a deadly disease. Where is the greater harm?
Another one, for instance, was World War 2 where people voluntarily - and temporarily - gave up freedoms in the greater cause. We had identity cards, restrictions on movements, enforced conscription, censorship, rationing, etc, etc.
But you're absolutely right that we need to be careful that government doesn't attempt to maintain its powers once the crisis has passed. That's the real threat to liberty and that's where the likes of IDS should be focusing their energies, not on forcing a reopening while the scientific data doesn't support it.
timarr
"However, anyone with a passing understanding of the Harm Principle recognises that there are instances - rare ones, but instances - in which individual freedoms need to be sacrificed for the greater good."
Err, so its ok for your side to harm other people but the harm your side does doesn't count.
The issue from my side is that the only metrics that count at present are "COVID-19" deaths and cases. To a lesser extent, NHS capacity. The other harms, the other 85% cause of deaths, are ignored.
Where is the media coverage of the annual flu season gone?
Hi UK Investor. Media coverage flu cases (UK) Quick sample..
https://news.sky.com/story/cov.... 130 year low
https://www.dailymail.co.uk/ne... drop 95%
Related to our changed behaviour this winter ? I am not qualified to make an argument
You cannot simply cite the Harm Principle and brazenly declare that you have decided that this is the level of harm which warrants the imposition of a second harm through lockdowns. You start from the supposition that this disease is bad enough to warrant a lockdown. You give it no second thought. We do not lock down for flu season every winter, or for bad outbreaks of the common cold - also contagious diseases.
Why do we not? We would save lives, right? Well, obviously because there is a clear trade-off between the imposition on personal liberty and the healthcare benefits. COVID is certainly worse than flu and the common cold, but you have not even acknowledged that these trade offs create a grey area where reasonable people - even public figures! - can have different views.
The question as to where that line is drawn - what level of infectivity or harm warrants a year of massive restriction of personal liberty - is an incredibly difficult one, particularly since the costs are hard to gauge. Have we doomed children to worse life outcomes after a year of poor quality, disjointed education? Will smaller infants have longer-term consequences from a lack of socialisation? What is the broader health damage to the population, both mentally and through obesity and lower activity levels?
These are all unknowns, and your 'take-no-prisoners, everyone who disagrees is a shill for big business' line is both unhelpful and, frankly, smacks of the sort of one-sided zealotry that is so pernicious to genuine debate.
You start from the supposition that this disease is bad enough to warrant a lockdown. You give it no second thought.
Of course I do. With an unknown disease of indeterminate danger then there's always a difficult judgement to be made based on limited evidence and unknown outcomes. I'd submit that somewhere there is a level of threat that would justify the measures that have been taken. We can argue over where that is.
However, in the UK we know what the level of justification is. It's at the point at which the NHS is in danger of being overwhelmed that the clear and present danger is judged to outweigh the future impacts. On the three occasions we've locked down that's why we've done it. We were late on each occasion, even though the science told us going earlier rather than later would be better. The economic advantage of being late to lockdown was minimal, maybe even negative, given that Christmas was lost.
But to be clear - and to repeat - I'm not saying that every individual that disagrees is a shrill for business. That would be a logical nonsense - I don't, for instance, think Piers Corbyn is being paid to have his beliefs. He's as mad as a box of frogs, but he's certainly not in anyone's pocket.
However, I think the vast majority of public commentators who've failed to change their positions while changing their reasoning as the months have gone on are highly suspect. If it isn't motivated reasoning then it certainly looks like it.
timarr
Its not an unknown disease. It pre-existed and has appeared in previous forms and strains.
Who says we are late (apart from the usual anti-Conservative anti-Boris crowd who will weaponise anything to attack)?
The "danger" was never clear cut, with evidence of many people being asymptomatic and the vast majority of sufferers recovering without consequence or the need for medical attention.
From my - minority - point of view, the real crisis has been the over-reaction to the bug, not the bug.
They would bankrupt businesses, make unemployment, pseudo debt, abandon education, limit routine health care, god-forbid end family life and our social lives, and close the pubs and gyms for this?
Covid Deaths vs Our Currently Restricted Lives
My wife works as a clinician in an acute NHS hospital. A single shift on a ward of covid wracked patients would change your priorities - it could be you.On the issue of statistics I am advised that unless the patient has tested positive for Covid their death is not allowed, by Dept. of Health dictat, to be classified as Covid related despite clear medical evidence to the contrary.
Yes this pandemic has caused a lot of suffering to those fortunate enough not to need medical care; but a policy of let the devil take the hindmost is not one for a civilised country.
Bonitabeach
"My wife works as a clinician in an acute NHS hospital. A single shift on a ward of covid wracked patients would change your priorities - it could be you."
Because that is what bugs - any bugs - do.
Has there even been a year without an NHS winter crisis, nor an election where one side didn't pitch that the other side are bastards because they didn't do x,y, and z for The NHS, or some emerging super bug fear story?
"it could be you"
Fine. Bring it on. Kill me if you think you can. I think statistically, I'd be more worried about the roads, the effluent coming out of the back of cars, and the evil of unemployment and recession.
Ah, good old "false equivalence", where we compare the risk of ongoing chronic conditions that affect the NHS with an acute crisis that will wreck the NHS ability to cope if it gets out of control.
And of course, there's the argument "why not worry about all of them"? In priority order of course.
Lastly, has there been a year, without a winter "crisis". Yes. Many without a "crisis" though the primary care system and hospitals suffer winter pressures of course, but you don't see entire wards closed down because the staff are all so ill, or so many people in intensive care the oxygen has to be rationed (if we did, they would've improved the oxygen supply).
God forbid someone actually has a deeply held belief that people should be free to make their own choices in life with respect to their personal risk
The point being, of course, that it is not a question of making choices with respect to their personal risk! We live in a crowded society where we interact. One person's choice with respect to their behaviour affects others.
If you want to go and live on a desert isalnd on your own, that's fine, you can choose to behave as you wish. If you are living an a society in which a contagious and harmful infection is prevelant, then you can't make such simplistic judgements.
Morning Paul, thanks again for the early write up.
It's a long time since you looked at Stm (LON:STM) (Looks like you used to own it) but wonder if you could have a look again - Initial glance at the RNS this morning seems to indicate Net Cash = Mkt Cap on a PBT of £2m or so, seems a little odd (a bargain even!).
Thanks, if you have the time or inclination to revisit (and, even if you don't).
Hi matylda,
Yes I remember looking at Stm (LON:STM) and holding for a while, but in the end the unpredictability and seemingly regulatory minefield of QROPS scared me off. If the business model looks wobbly in some way, then I usually tend to steer clear.
Best wishes, Paul.
Thanks for looking Paul - Cheers!
These are very helpful, thanks for posting them again, Dan. I skim them each morning to see if there's anything in my universe that I missed on my own initial trawl of the RNS. I really dislike the 7-8am mad rush, as there's too much to handle - how can we possibly read & digest sometimes dozens of announcements so quickly, to make investment decisions?
Suggestion - is it possible to manually over-ride the market caps of anything that appears at the bottom with £0 mkt cap, as those are clearly some kind of anomaly?
Best wishes, Paul.