Small Cap Value Report (Weds 30 Oct 2024) - BUDGET. NXT, TMO Briefs: AML, CABP, EQLS, HSP, ECK, SALT

Good morning, and happy budget day from Paul & Graham!
As usual I'll be posting my immediate notes on the Budget speech in this article shortly after the Chancellor sits down - as I type it up in real time anyway, so might as well share my notes with you here. EDIT: Done - published at 14:08.
Then at 5pm, Megan and Mark will be doing a webinar - details here - with more in depth analysis, so I'm looking forward to tuning in to that.
Budget speech -
Summary
Not as bad as the worst fears - has already triggered a big rally in some AIM shares.
Taxes will be raised by £40bn, the bulk coming from Employers NICs at £25bn.
I think this is a fairly balanced set of measures, but it’s going to hurt business profits due to higher labour costs & taxes.
AIM loses half its IHT relief, from 40% to 20%, so still worth holding good AIM shares. Pity she didn’t commit to no further changes in future.
So uncertainty will continue, but AIM lives to fight another day!
Increases to CGT, but not particularly big.
Pensions will become subject to IHT - a big change (not immediate though - subject to consultation).
Employers NICs will go up by 1.2% from 13.8% to 15.0%. Thresholds also lowered - a heavy extra cost for employers.
Big increase in minimum wage, as expected. So this is going to be very expensive for struggling hospitality & retail companies. Expect broker forecasts to be slashed in some sectors.
Corp Tax will remain at 25% for full parliament. Lowest in G7. Confirms what has previously been announced, but it’s clearly good news.
What it didn't do (which had been feared) - no changes to tax relief on pension contributions, and I didn't hear anything about betting taxes either. Also ISAs left alone, which was another fear. Also apparently no change to the 25% tax-free lump sum on pensions, and no change to the tax relief on money going into pensions.
Budget Speech Detail
Starmer:
Our no.1 mission is growth.
Budget Speech, Rachel Reeves
Political stuff - change, mandate for renewal, last 14 years, rebuild Britain, fairer society, austerity broke our NHS, harmed business, mini Budget, higher mortgages, black hole, etc.
Growth is only way to improve living standards. “Invest, invest, invest”.
Public finances - £22bn black hole - OBR will publish line by line detail.
OBR review also published - claims old Govt didn’t provide all the info, and “materially different” forecasts in March 2024.
£10bn cut to Employees NICs was “height of irresponsibility”.
Will implement all 10 of OBR’s recommendations.
Broken public services. NHS & schools run down, prisons & rivers overflowing, etc.
[PS: This so far is a party political broadcast. Rachel - remember you’re governing now, not campaigning!]
Finance needed for 2 large compensation schemes for injustices - infected blood scandal & post office Horizon. £11.8bn (did I hear that right, that’s huge!) provided in this budget for infected blood, plus £1.8bn for post office scandal.
[And she’s back to political point-scoring now - seriousness of what we’ve inherited, hole in public finances, etc]
Raising taxes by £40bn.
Rebuilding public services, and stabilising public finances.
Thanks Andrew Bailey & policy committee. 2% inflation CPI target retained.
Thanks Treasury & officials, and previous CoEs for invaluable advice, including Kwarteng (“My mini budget wasn’t perfect!”).
Thanks Richard Hughes & OBR team.
OBR Forecast - CPI will average 2.5% 2024, 2.6% 2025, 2.3% 2026, 2.1% 2027 & 2028.
Economic growth - OBR new 5 & 10 year forecasts, will become permanent framework.
Forecast GDP growth: 1.1% in 2024, 2.0% in 2025, 1.8% in 2026, 1.5% in 2027.
This budget will increase supply capacity, hence long-term growth, says OBR.
7 key pillars to growth strategy:
1 - restore economic stability.
2 - new infrastructure, £70bn through national wealth fund. Planning rules changed.
3 - work with devolved authorities for local growth plans.
4 - Skills England & tackle worker inactivity.
5 - Industrial strategy & SMEs.
6 - Funding for R&D.
7 - Maximise clean energy investments, eg carbon capture.
Intl investment summit - £64bn investment committed by businesses.
Economic growth is key strategy.
Confirming rules - taxes in balance with day-to-day spending. Will be met in 2029/30. Tougher constraint on day-to-day spending. £26bn deficit in 25/6, £5bn deficit year after, then moving into surplus. Will meet stability rule 2 years early.
Govt borrowing running ahead of plan. OBR - £127bn borrowing this year, blamed on Tories. 4.5% of GDP deficit this year, will fall to 2.1% by end of forecast.
Efficiency & wasteful spending. £5.5bn savings already announced. 2% productivity target to be met by next year, all depts.
Covid corruption commissioner to uncover waste/fraud, get money back.
New office of value for money.
Welfare spending - reform work capability assessments. Crackdown on welfare fraud, expand teams. Will save £4.3bn pa by end of forecast.
Get Britain Working white paper, re worklessness, focus on health education & welfare, to reduce benefits bill.
Tax collection - invest to modernise HMRC systems & recruit extra staff. Increase interest on late tax. Go after promoters of tax avoidance. Raise £6.5bn by end forecast.
Family finances are stretched. Cost of living support - minimum wage going up. Low pay commission recommendation to raise Min Wage by 6.7% will be done. Single adult rate will be phased in. 18-20 year olds will rise by 16.3% to £10 p/hr. (These increases had already been announced earlier this week).
Carers allowance - £81 pw now. Will go up a lot today, and allow increased hours. Cliff edge & overpayments to be reviewed.
£1bn from next year for household support scheme.
Reduce debt repayments from universal credit. Will help reduce child poverty. Want to make work pay.
Unfair dismissal & bullying measures for workplace. Jokes about Tories being grateful for these protections as they lose their jobs!
Mineworkers pension scheme measures.
Triple lock - commitment. Pensioners will be given +4.1% - gain up to £470 next year, above inflation.
1.7% working benefits upped, in line with CPI.
Fuel duty - surprised by keeping the freeze on fuel duty, when tax was expected to go up.
NIC Employees 2% cuts by Tories were unaffordable. Confirms she will not increase Ees NIC, VAT or income tax, honouring manifesto commitments.
Employers NICs will be raised - increase by 1.2% to 15.0% from April 2025.
Will also reduce secondary threshold from £9,100 to £5,000 pa.
This will raise £25bn pa by end of forecast period.
Increasing employment allowance from £5k to £10.5k, reducing NICs for smallest businesses.
Capital Gains Tax - need growth & entrepreneurship. Lower rate rises from 10% to 18%. 20% to 24% higher rate. 18% & 24% rates on property retained.
Lowest CGT rate of G7 countries.
Lifetime limit retained at £1m.
Business asset disposal 10% this year, 14% next year, 18% year after.
Will raise £2.5bn by end forecast.
EIS & VCT schemes already extended to 2035.
Positive environment for entrepreneurship.
Inheritance Tax - only 6% of estates pay it. Balanced approach. Freeze extended to 2030 at £325k. £500k if includes a property.
Close loophole - April 2027 - inherited pensions will become taxable.
Business agricultural relief - Apr 2026 first £1m will pay no IHT. For assets over £1m - IHT will apply with 50% relief, at 20%
50% relief for AIM shares. IHT at 20% (from current zero on most AIM shares).
These CGT measures will raise £2bn by final year.
Air passenger duty, tobacco duty, etc. I missed this bit, as was digesting the IHT news.
Business rates - 2 permanently lower rates for smaller retail, leisure & hospitality. Paid for by higher multiple on most valuable properties. 40% relief provided to help these sectors.
Alcohol - will increase with RPI for non-draught drinks. Draught duty being cut by 1.7%. So 1p off pint in the pub (Tim Martin will be pleased LOL!)
Corp Tax will remain at 25% for full parliament. Lowest in G7. (Great to have stability, so businesses can plan ahead).
Non-doms. If UK is your home, you pay taxes here. Non dom will be abolished, and remove concept of domicile. Will bring in residence based scheme, internationally competitive for temporary residents. OBR says this will raise £12.7bn over 5 years (we'll see!).
Fund management - vital for economy. But carried interest CGT rates will rise to 32% from April 2025. Further reform from 2026.
Stamp Duty land tax - 2nd homes going up, by 2% to 5% wef tomorrow. Will help boost first home buyers she says (but hurt buyers of BTLs & holiday homes).
Energy profits levy - will go up to 38%, expire March 2030. Remove 29% investment allowance. Will maintain 100% 1st year allowance.
Children - 94% attend state schools. Will bring in VAT on private schools from Jan 2025 & remove their business rates relief. Will raise over £9bn (multi-year I think).
Income tax - extending threshold freeze? Not in favour of it, so no extension in thresholds beyond existing, so will start going up from 2028/9, "to protect working people"!
Spending plans - no return to austerity. Further pledges to some departments.
Increased spending on defence & support for Ukraine.
Real terms increase for local Govt spending.
Taking action on shoplifting.
Talks about fiscal rules being changed for infrastructure.
Investment plans - gigafactories, ports, green hydrogen. Modern industrial strategy, to work with businesses on biggest growth potential. Nearly £1bn for aerospace R&D. Over £2bn for automotive sector in UK. £520m for life sciences. Creative industries support for TV & film. R&D: £20bn funding, engineering, medical, biotech.
£5bn for housing. Affordable homes programme up by £3.1bn. £3bn support for small housebuilders.
Council houses - right to buy discounts will be reduced, and LAs will retain full receipts.
Social housing settlement of CPI + 1%
Hire hundreds of more planning officers to accelerate housebuilding.
£1bn for removing dangerous cladding next year.
Transport - potholes - £500m increase in funding, to fix 1m potholes per year. Other funding increased.
Bus fare cap - missed this bit sorry.
Energy - carbon capture projects to create jobs.
£3.4bn for warm homes scheme, 350k homes, mostly social housing.
GB Energy to be set up in Aberdeen.
OBR says investment will raise GDP.
School buildings crumbling. £6.7bn of capex for Dept Education next year, 19% real increase on this year. Rebuild over 500 schools in greatest need.
NHS - 10 year plan. Vital reforms needed. £22.6bn increase in day-to-day health budget. £3.1bn increase in capital budget this & next year. Largest real times increase since 2010 (outside of covid). £1bn for repairs to hospitals. Increase capacity, new beds & diagnostics. Will bring down waiting times faster - target is <18 weeks.
(apologies for any errors or admissions)
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
Summaries
Next (LON:NXT) - up 2% to £102.30 (£12.8 billion) - Trading Statement- Graham - AMBER/GREEN
Nudging my stance on this down to AMBER/GREEN but more positive than Paul’s AMBER. Next have released yet another ahead-of-expectations trading update: the full-year adj. PBT forecast is now over £1 billion. I continue to rate this very highly but the valuation is not so cheap anymore.
Time Out (LON:TMO) - up 8% to 49p (£167m) - FY 6/2024 Results & Launch of Placing- Paul - AMBER/RED
A big improvement in adj EBITDA, but it remains heavily loss-making at PBT level, due to big depreciation & finance costs. Stretched balance sheet is helped by an £8m placing, supported by the 2 (combined) controlling shareholders. Small free float, so it's really a private company with a listing. Business model is not yet proven, so I'm a bit sceptical.
Paul's Section:
Time Out (LON:TMO)
Up 8% to 49p (£167m) - FY 6/2024 Results & Launch of Placing - Paul - AMBER/RED
Time Out Group plc (AIM: TMO), the global media and hospitality business, today announces its audited preliminary results for the twelve months ended 30 June 2024.
This group is media (Time Out magazine), and international food markets - the more interesting, and growing part of the business -
Here’s the floor plan of its Boston (chosen at random by me) site -
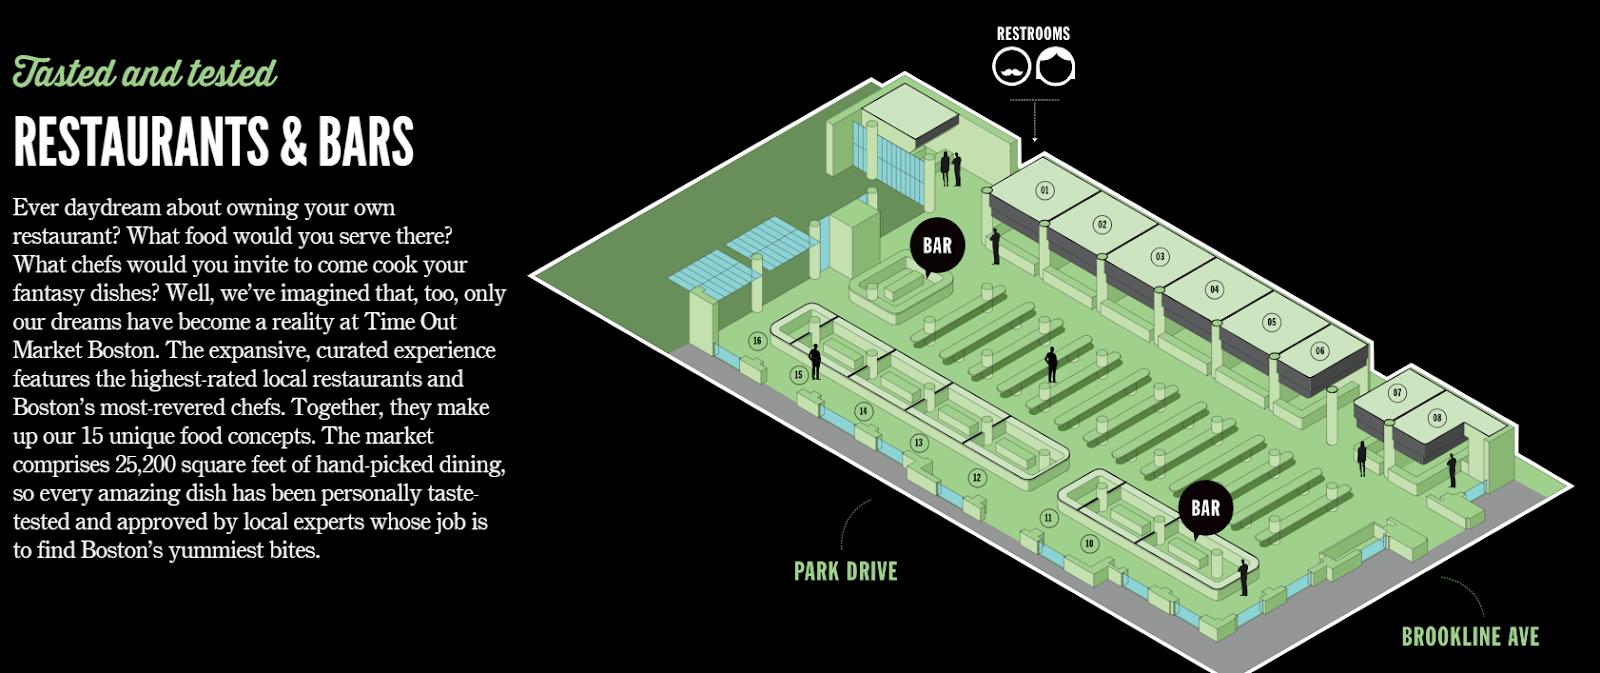
Each of the numbered units above is a different restaurant operator - some examples below -
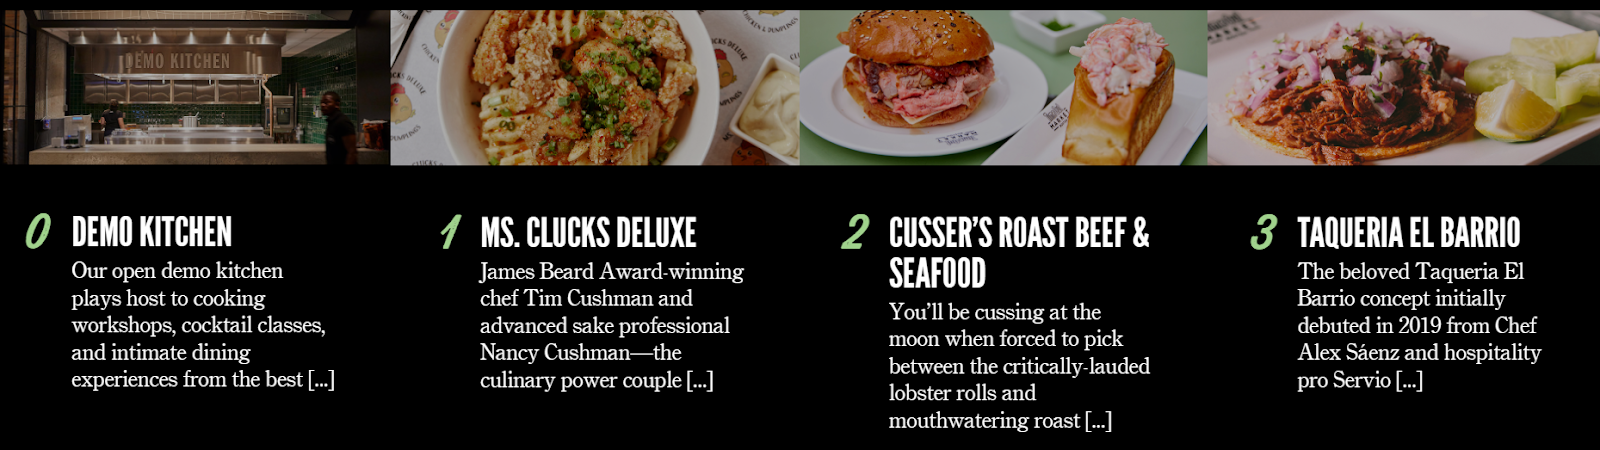
I think that gives a flavour for what Time Out markets does. Hardly earth-shattering, I’ve seen things like this elsewhere. So its business model would be renting & fitting out each site, then try to generate more income from it than it costs. A bit like serviced offices, but for food. Doesn’t sound a particularly exciting business model to me, although I suppose the argument is that the well-known Time Out brand might add appeal.
Does it make any money? Only at the EBITDA level - and with strong growth helped by reduced costs -
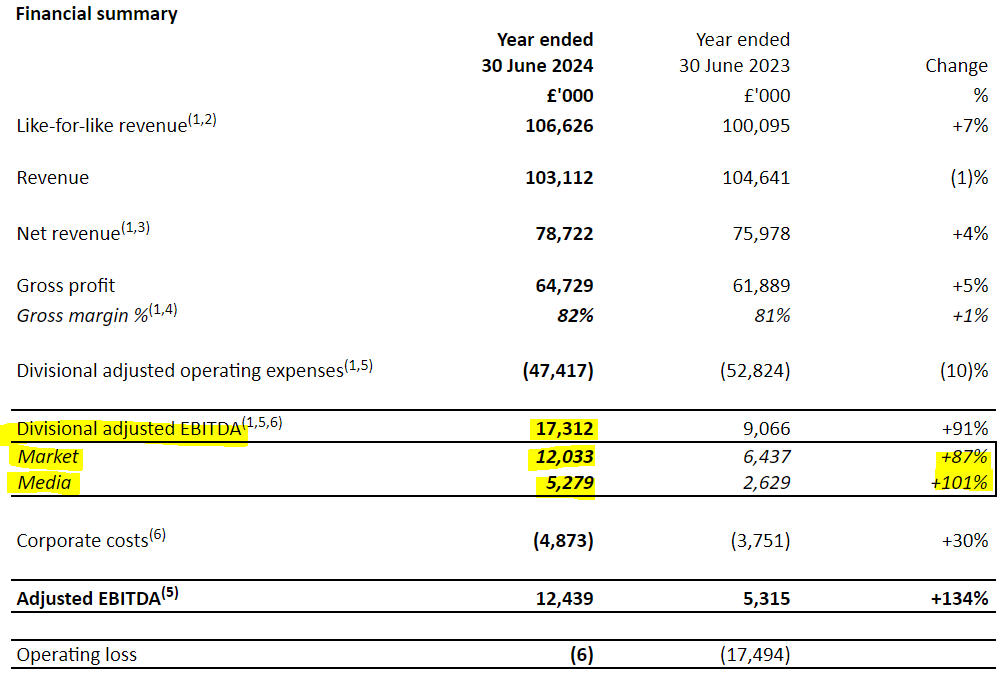
However, those numbers ignore the substantial depreciation and finance charges.
Media division - I always thought this was a dead loss, but the growth in EBITDA here is impressive -
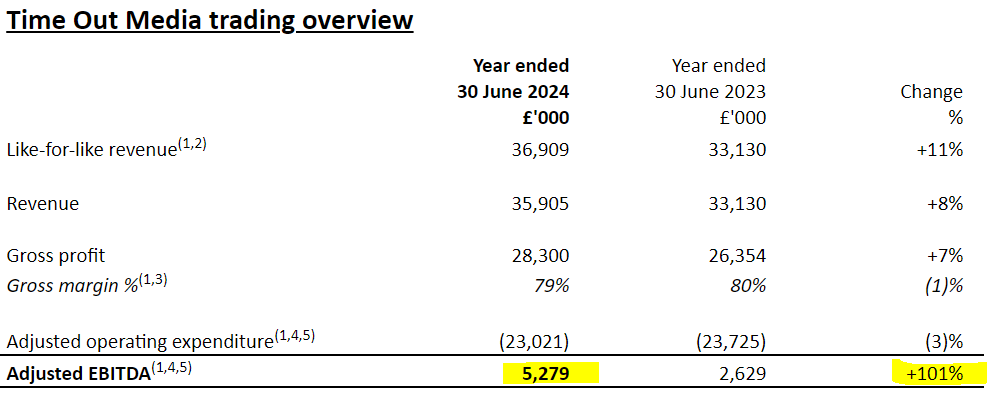
Overall group results take the £12.4m adj EBITDA and it quickly evaporates with a £9.5m depreciation/amortisation charge and large £9.0m finance costs doing most of the damage to deliver a hefty loss before tax of £(8.5)m - although much improved from the horrendous LY comparison of £(25.0)m LBT.
Net debt strikes me as too high (and it’s expensive) - note that some of the debt is provided by 38% shareholder, Oakley Capital, at 8% above SONIA (down from 10%) -
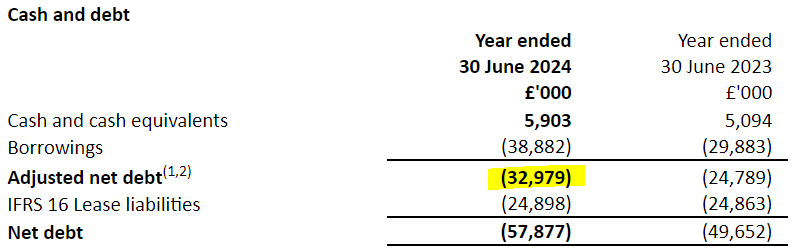
Warrants - just to flag up the existence of these, which could cause dilution. 2.55m new warrants are to be issued in Nov 2024. It doesn’t say how many are already in existence, that would need to be checked.
Loans from shareholders, and warrants kicking around are usually signs of a company that is, or has been financially distressed.
Going concern statement is clean, no doubt helped by the placing also announced today.
Balance sheet - is weak. NAV of £28.8m includes £35.0m intangible assets, so NTAV is negative £(6.2)m, not good. Although the £8m placing today should turn that slightly positive.
Its £31m fixed assets have been funded with debt, not equity.
Cashflow is positive, at £9.7m, but I would deduct £(4.3)m lease repayments from that, giving £5.4m positive cashflow. It then spent £10.6m on capex, so expansion is not being self-funded, it required increased borrowings in FY 6/2024, and a small equity raise. Which raises the question, how will its debt be repaid in future?
Placing - raising £8m at 50p per share, so 16m new shares (existing: 340.3m) 4.7% dilution is OK. Price of 50p is a premium of 10% to yesterday’s share price, which had been falling rapidly, so this seems as if the big shareholders want to draw a line at 50p to try to halt the decline maybe?
The shareholding structure is dominated by two largest holders, also note the well-known Richard Caring holds 5.9%. So this is really a private company with a listing, hence everyone else is along for the ride - and the share price may not necessarily be a logical valuation given the fairly small free float -
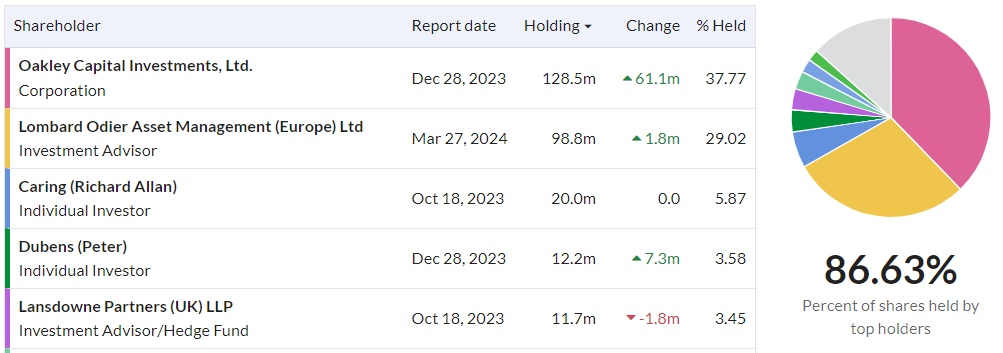
The two largest shareholders are cornerstoning (can that be a verb?) the placing.
Directors are also saying they will invest “up to” c.£0.9m in the placing, which reassures.
Outlook - reassures trading is in line -
“Current Trading and Outlook
The Group has a clear plan to drive like for like growth in existing Markets, whilst continuing to convert the strong pipeline of potential new Market sites and large media advertising deals and trading for FY25 remains in line with management expectations.
Having opened seven Markets in 10 years, we expect to open seven Markets in the period from November 2023 to November 2025 and reach a minimum of 16 Markets by 2027. When coupled with a continued pipeline of new opportunities, this growth can rapidly improve the operational gearing of our fixed cost base, meaning we have the potential to continue to grow profitability at a faster rate than sales. We continue to receive approaches from commercial parties keen to work with the Time Out brand and are increasingly confident in our global strategy.”
Paul’s opinion - it’s not clear from these numbers if Time Out is a viable business or not. It’s making hefty pre-tax losses still. To assess it properly, I would need to understand the economics of the individual sites, which is not information that would be publicly disclosed. I’m generally not keen on loss-making, capital-intensive businesses rolling out more new sites. Surely it’s best to get the existing ones into profit first?
How much upside is there on current trading? I imagine revenue growth would mainly come from opening new sites, because existing sites are presumably generating a fairly flat level of revenue from rents to the individual units in each market, I presume?
It’s been heavily loss-making ever since it listed, with a highly indebted, negative balance sheet that shows the scars.
The placing today probably won’t be the last.
The major shareholders clearly believe in the concept, and have supported the company (and its share price).
As the business model is still unproven, I can’t go above AMBER/RED. But some investors value things on EBITDA multiples, and might be happy with a higher valuation, and a stretched balance sheet.
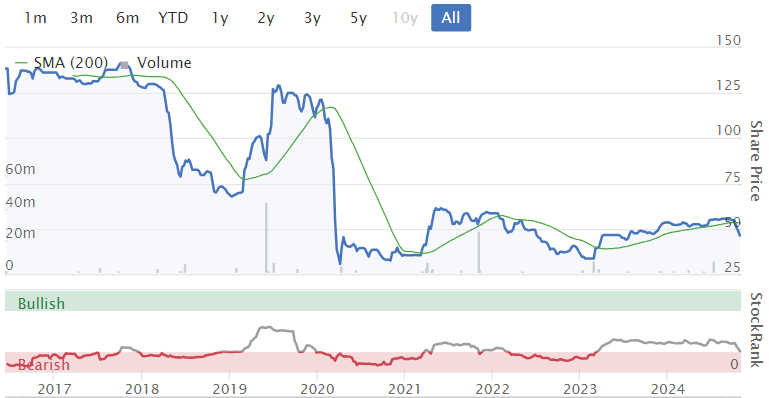
A poor track record of destroying shareholder value since it listed - although to be fair this includes the pandemic period, which would have obviously done a lot of damage to this type of business -
Graham's Section:
Next (LON:NXT)
Up 2% to £102.30 (£12.8 billion) - Trading Statement- Graham - AMBER/GREEN
At the time of writing, Graham has a long position in NXT.
Another positive update from Next, which has a tendency to under-promise and over-deliver on its very clear guidance.
Key points:
Q3 full price sales +7.6% (guidance: +5%), helped by the early arrival of colder weather.
Increased guidance for Q4, now +3.5% (previously: 2.5%).
As a result of the above, full-year guidance for FY January 2025 gets a boost. Full-price sales are boosted by £43m and adj. PBT by £10m to £1,005m.
An excerpt from the first table in today’s update:
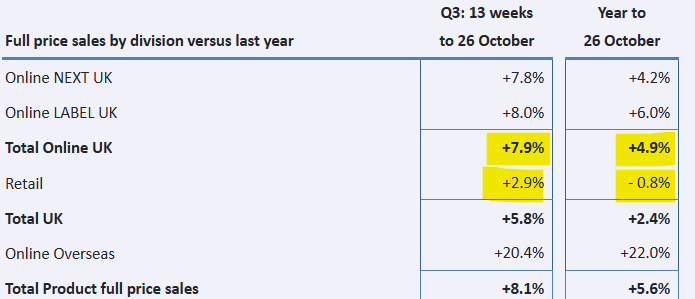
We have online UK growth of 4.9% year-to-date, offset by a 0.8% reduction in sales at retail stores - a normal continuation of the long-term trend.
Next then provides a clear explanation of where their Q4 growth forecast comes from, along with a nice graphic. It’s so simple but at the same time so rare for companies to provide shareholders with this level of high-quality, transparent forecasting and analysis.
Full-year guidance: again for the full-year figures, Next provides a level of clarity that should be commonplace but unfortunately is not. They provide clear sales, PBT and EPS (pre-tax and post-tax) estimates:
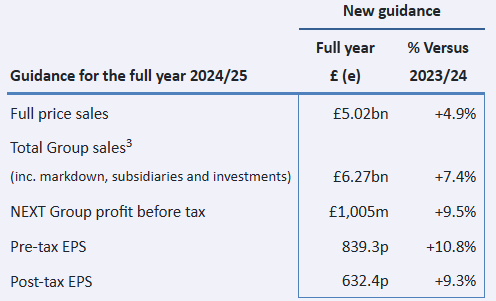
Total group sales are boosted by acquisitions, i.e. this is not a fully “organic” number. It includes Fatface and an increased ownership of Reiss.
Graham’s view
The list of things I like about Next is a long one. Here are a few off the top of my head:
best-in-class guidance
under-promises and over-delivers
careful management of retail stores with clear criteria for closures (and the ability to close them by exiting short leases)
Top-class online operations. Has the ability to manage and improve the performance of 3rd-party brands
acquisitions at attractive valuations from a position of strength, typically when the investee needs new financing.
sensible use of buybacks to reduce the share count.
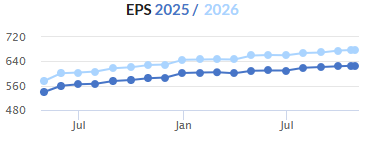
Few companies have EPS forecast charts that look like this:
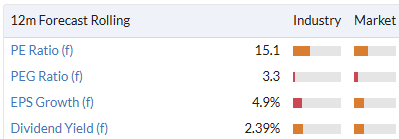
The valuation is admittedly a little high now, relative both to Next’s own history and to the market as a whole:
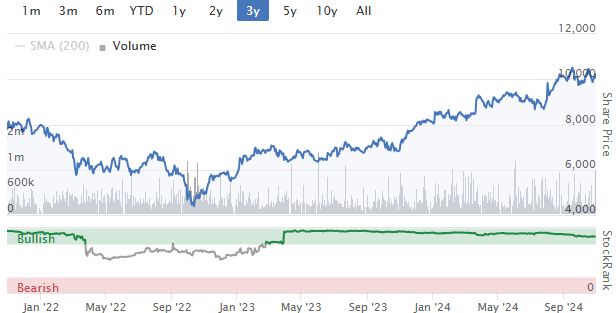
The share is categorised as a “High Flyer” thanks to its very strong momentum:
Paul (who first explained to me the bull thesis for this stock) has been neutral on it recently. In August he reported on an equal pay employment tribunal that went against it. In May he observed that EPS growth was “fairly modest”.
Personally, I’m inclined to give this an AMBER/GREEN today as I acknowledge that the valuation does not offer the sort of value that it did before. But I still see this as a special company, and I think that AMBER would downplay its special status. But then I’ve been a long-term shareholder here, so I would say that!
Next does of course face plenty of economic risks, including the management of a large wage bill (the latest minimum wage increase has been announced this morning). It won’t be plain sailing, but it never has been - and I sincerely trust this management team.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

215 comments
I can see the following businesses doing a roaring trade.
De La Rue (LON:DLAR) - Print money
Basildon Bond - Make Envelopes
Yale - household safes
I guess its inevitable and amusing that after today’s events that certain posters have come on here and boasted about how clever they are and how they ‘read ‘ the market correctly beforehand. And made a killing. They cant help themselves but to share their special qualities with those less fortunate than themselves.
The reality is completely different. They completely switched into gambling mode . They got incredibly lucky. They abandoned the rules of Buffet, Munger, Graham and Lynch. Betting and gambling on daily price movements are not the actions of proper investors. Nothing wrong with that but don't describe yourself as an investor - you are a trader.
A trader becomes an investor when the trade has gone wrong, as they say.
The reality is completely different. They completely switched into gambling mode . They got incredibly lucky. They abandoned the rules of Buffet, Munger, Graham and Lynch. Betting and gambling on daily price movements are not the actions of proper investors. Nothing wrong with that but don't describe yourself as an investor - you are a trader.
Not sure if this is aimed at me, but surely the test is whether the investor/trader holds onto the shares for the long term, as I intend, having followed them for years looking for an entry, or sells in the next month for a quick profit. I would also argue that an investor buying just before the budget was doing so when there was blood on the streets, very much in the spirit of Buffet.
So you were gambling after all. Just before an event that had an unknown outcome. Buffet would never do that, and you know it. However bloody the streets were.
I enjoy your posts mostly, Bnb. A little dose of humbleness might serve you well, though.
Im going to the Derby event in a few weeks. Would be good to meet you if you were attending.
So you were gambling after all
I disagree. I’ve been through goodness knows how many budgets in my career. And it was clear to me in the run up that Labour were very wary of spooking the market - witness Kier’s soothing comments on the likely extent of CGT rises. I specifically targeted shares with CGT and/or IHT risk that I coveted. In the case of CGT targets there were a number that had sold off so badly as to no longer pose a CGT-specific risk, ie such was the sell-off that there were no more gains for anyone other than very long term holders to realise. Look at the charts of Tristel, Bioventix, Global Data for an illustration and others I considered such as Keystone Law and AB Dynamics, both of which I concluded were riskier on the CGT realisation profile and therefore avoided (to my cost as it turned out). These were high quality businesses at knock down prices with little additional downside potential, absent a general sell-off affecting markets beyond AIM. Every trade is a gamble in the sense that we cannot know the future. But this was an opportunity to enter good businesses with an enhanced risk/reward. Names that I will hold for years if their trading progresses as their track record promises.
That said, point taken about the tone of the post and it wasn’t my intention to tout my good fortune, rather to highlight the importance of calm calculation during volatility. Yes, I’m at Derby and look forward to meeting you, where we can continue this conversation and initiate new discussion. I appreciated your vigilance when the forum got hijacked by political nonsense a short while ago.
Hi Paul - you’ve gotta be commended on that summary so quickly, very impressive.
Thank you for doing that.
Best
David
Pensions - What I've been unable to find clarity on is the treatment of AIM shares held within a SIPP. I'm hoping that they will be recognised as due a 50% "discount". But fear that pensions might simply be regarded as a single number in the IHT calculation.......
Has anyone spotted anything?
Pensions - What I've been unable to find clarity on is the treatment of AIM shares held within a SIPP. I'm hoping that they will be recognised as due a 50% "discount".
Somewhat unlikely, I would think. I believe the pension assets are technically in trust (ie not yours, even though you put them there) so the allowances you qualify for would not necessarily apply to those assets. I doubt, however, that this has been thought through, so it will have to be tested in a tax assessment and counter argument.
Budget printed copy PDF, the whole nine yards here
Thank you Paul for an amazing budget summary. The best I’ve read anywhere.
On farm land:
“Business agricultural relief - Apr 2026 first £1m will pay no IHT. For assets over £1m - IHT will apply with 50% relief, at 20%”
Very few farms below the £1m mark which means farms will have to be sold on death to pay the IHT bill.
This is a disaster for farming in the U.K. most farmers have their wealth tied up 100% in their land.
This is an ill thought through policy from Labour but why am not surprised.
I’m not a farmer.
Regards
Michael.
Looks like food prices will go up even more.
Michael you are spot on.
When you consider that for livestock farming 300 acres would be a minimum viable unit size which in England certainly would put a farming estate well above the threshold, then there is the value of the farmhouse, and the value of the equipment.
Given farming doesn't generate meaningful returns on assets employed there be many farmers forced out of business and away from their livelihoods.
What a day ....
I am glad I did nothing and had the dopamine hit of seeing some of my portfolio constituents move sharply upwards: Filtronic (LON:FTC) +17.5%, Intercede (LON:IGP) +12.2%, Niox (LON:NIOX) +5.6%, Journeo (LON:JNEO) +7.8% .....
However, all this pales into insignificance, now I discover that our 2 family farms are going to be hit with IHT on any valuation on death > £1 million. My phone has been ringing red hot this early evening from the NFU and fellow travellers in the art of making little return from our rain soaked land. So much for "workers" ... we get up at 6 am every morning and work 7 days a week. There is a lot of anger in the farming community. Will it matter? Will it make one jot of difference? Of course not, but I note that this government no longer considered me or my family workers.
I have yet to muster the courage to see what impact this budget has on our forestry holdings.
BTW Paul ... I almost forgot to thank you for your excellent budget summary.
I am now off to feed the livestock (because apparently it is not work).
Really sorry to hear how you and your family are affected by the IHT changes. I had arranged for my children to inherit a pension that would undergo no drawdown in my lifetime. It’s not a living business like your farm but the companies it owns all are. And now that bit of tax planning is in tatters*. Solidarity, brother!
In those moments what can you do other than to simply prize the gift of life and keep smiling, even if it is through gritted teeth?
*Wondering now if I can gift the pension to them on a timely basis as a PET?
"*Wondering now if I can gift the pension to them on a timely basis as a PET?"
Please do post if you find a way to do this!
"*Wondering now if I can gift the pension to them on a timely basis as a PET?"
Please do post if you find a way to do this!
Initial google and ChatGPT searches suggest it is not possible
Thank you BnB.
Tomorrow is another day ...
However, all this pales into insignificance, now I discover that our 2 family farms are going to be hit with IHT on any valuation on death > £1 million. My phone has been ringing red hot this early evening from the NFU and fellow travellers in the art of making little return from our rain soaked land. So much for "workers" ... we get up at 6 am every morning and work 7 days a week. There is a lot of anger in the farming community. Will it matter? Will it make one jot of difference? Of course not, but I note that this government no longer considered me or my family workers.
With stuff like this there is always the chance it may never see the light of day or be rescinded before it hits (that may take a different government). It will be interesting to see if the tories make specifioc promises to repeal some of these more aggressive tax raising plans similar to what labour have done with rwanda. They have a decent opportunity to do that in the very near future.
One the thats strikes me as being particularly unfair is the double taxation of pensions being passed over - hey ho is that much different to soemone who cashes in pension pays tax and then pops their clogs and pays IHT - linked to on event though creating tax aftre tax seems wrong.
Think the apparent double taxation is simply a function of offsetting the original tax relief when the money goes into the pension.
Ignoring the 25% tax free lump sum, pension vehicles to my thinking largely just defer your taxes rather than avoid them.
Pensions are a great vehicle as they give you flexibility - eg retire young and you can use up your Pa - some can avoid ni that would have been charged when adding - and also h rate relief on money in and draw when baud rate taxpayer - plus some ability to recycle money back in - so there are many more options than just the 25% for some be peeps - that’s without the up till now generous hit exemption (never made much sense not defacto collecting tax at point money passed on to relatives - spousal exemption and 25% aside perhaps)
Or the whole issue of CGT on an asset that has increased in value due to inflation. Government collecting money on a BTL property you may have had for 20 years and paid for out of taxed income.
I worked for a farmer who passed on his farm to his daughter 10 years before he died and she did not have to pay inheritance tax. I think the law then was he had to live for at least 7 years after passing it on. Does this law not apply anymore?
Jamesalastair,
Sorry to hear that you and your fellow farmers have been thrown into this uncertainty. I've always viewed the farming community as custodians of the landscape, one of the country's greatest assets. We should all be hugely thankful for the hard work that you guys put into preserving this green and pleasant land.
Hopefully, time, and common sense, will lead to a reversal of this misguided tax grab.
Well after the threat of the budget I sold out of most except for Equals (LON:EQLS) , Vistry (LON:VTY) , Osb (LON:OSB) , Avation (LON:AVAP) , TP Icap (LON:TCAP) Spectra Systems (LON:SPSY) ME International (LON:MEGP) all of which I thought had a margin of safety. Sitting on cash now with no purchases today.
If anyone is wondering how CGT works in a split rate year, I found this guidance on the gov.uk website....
"The existing provisions under which losses, the Annual Exempt Amount and any unused income tax basic rate band can be used in the most beneficial way will remain in place, with amendments to reflect the changed rates."
https://www.gov.uk/government/...
If growth does not increase, and I have to say the projected 5 year growth rates don't suggest powering growth resulting from significant increased Govt borrowing, then we are relying on fairly thin gruel to repay the growing interest payments bill.
Should Govt allow itself the illusion it powers growth anyway? Mostly it gets in the way of growth based on ideological allocations of money. Its a gamble with significant stake money at risk.
Hi Trident,
Indeed. What could possibly go wrong with taking even more money away from the private sector (productive part of the economy) and redistributing it to the public sector (unproductive part of the economy). It they wanted economic growth then they'd be encouraging the private sector to invest, take on and train more people etc.
The massive injection of funds into infrastructure projects is a bold move- and if delivered will create growth in the economy. After years of moribund policies I applaud the Gov for taking this on. There are risks- shortage of materials, skilled labour etc but in my opinion this is the only way to try and get us out of what has been a 20 year period of poor growth , increased taxation and lack of direction. It seems very calculated move to help the less well off as well as keeping trying to sort the NHS and education. Probably the last chance before we will see Healthcare increasingly being paid for.
Successful private companies normally seem to be able to manage these tax changes and the changes in N.I do come through to Corporation tax bills.
The Government have to deliver- otherwise the polls in 5 years will remove them, so a very ambitious budget.
You are right, it is a brave, much needed budget. So good to see "grown ups" in power.
Ha ha!
SRT Marine Systems (LON:SRT)
Be interesting to see analyst forecasts now this is signed. From memory (and assuming same still applies - there are others on here that know this company much better than I) I reckon the contract is likely split 50% first 2 years and then the remaining 50% over 10 years as maintenance. The former I seem to think should attract margins of c. 25-30% and the latter closer to 60%.
If I am correct (and that’s a big “if”) then I’d expect to see this translate to £11m p/a PBT followed by £4m pbt for 10 years. Then we add in the other contracts which are material in themselves. Of course I highlight this because the 2 years are essentially exceptional, in that they need to replace with new contracts to keep growing.
I will watch out for the new analyst forecasts to see if their projections tally with my fag packet version.
Speedy Hire (LON:SDY) Is a rare big loser in today’s budget shake-up. Shares fell as RR got into the detail and continued to sell into the close. Can anyone suggest a reason? I enjoyed a good trade in this from mid-20ps up to 40p and could be tempted back in near 30p.
Speedy Hire (LON:SDY) is inconsistent and accident prone.
VP (LON:VP.) is a better bet IMHO (I hold) and only up 1.25% on Budget day
Speedy Hire (LON:SDY) is inconsistent and accident prone.
VP (LON:VP.) is a better bet IMHO (I hold) and only up 1.25% on Budget day
Completely agree. But there is more upside in SDY for a cyclical trade. Not my normal style, clearly. But I’ve been vocal about a cyclical twist all year and it has paid off well. Wondering about a second bite at this cherry/rotten apple
Did anyone notice a good number of AIM shares bouncing in the hour or so before the budget?
well us bottom feeders are always the last to know arent we (budget not as bad as it could have been) - so par for the course.
Brickability (LON:BRCK)
Up 9%, I assume on the basis of the funding for cladding remediation. The shares remain cheap, but given that I have a reasonable I would think so.
Much to digest.
SRT Marine Systems (LON:SRT) I hold
breaking news - according to local press the contract to supply a maritime system has been signed.
https://www.kuna.net.kw/Articl...
The recent fund raising was required in order to provide Kuwait with a Performance Bond and given the speed with which Kuwait expected the project to start, the normal UKE Finance was impossible to arrange.
I believe this contract validates SRT's ability to "meet the highest maritime quality standards" as this article says. It also makes it more likely that the planned fund raise will be fully subscribed.
SRT watchers have noted that after the fund raise, Ocean Infinity will own in the region of 23% of the company prompting speculation that it could lead to a formal takeover in due course.
https://www.kuna.net.kw/Articl...
Edit ; RNS issued here - extract says :
"The contract is for a state-of-the-art national maritime surveillance system for the Kuwait Coast Guard and other relevant agencies. The system will incorporate a broad range of sophisticated sensor systems, USV's, Ai Analytics, augmented reality and integrated command & control systems as well as new supporting civil infrastructure. The contract forms a 12 year partnership with implementation expected to take up to 2 years, followed by 10 years of support, training and maintenance.
Simon Tucker, CEO of SRT Marine Systems, commented:
"Winning this landmark contract is a huge honour and achievement for SRT and reflects our many years of technology and project delivery capacity investment. This system will undoubtedly be amongst the most sophisticated maritime surveillance system in the world, incorporating several significant innovations along with full integration and digitisation of surveillance and command and control which will provide a powerful tool to enhance national security and maritime safety and environment protection and sustainability. We look forward to working with our new sovereign partner to deliver this contract and more in the coming years."
I have been badly bitten in the past by contracts in Kuwait. I hope SRT Marine Systems (LON:SRT) (no position} get the performance bond back. I have the same concern too about Hunting (LON:HTG) which I hold.
Richard
..The contract is for a state-of-the-art national maritime surveillance system for the Kuwait Coast Guard and other relevant agencies. The system will incorporate a broad range of sophisticated sensor systems, USV's,* Ai Analytics, augmented reality and integrated command & control systems as well as new supporting civil infrastructure.
*That must be Ocean Infinity's new add-on...
The contract forms a 12 year partnership with implementation expected to take up to 2 years, followed by 10 years of support, training and maintenance...
Interesting to see also that there's a UAE connection...
.."Kuwait's First Deputy Prime Minister, Interior and Defense Minister Sheikh Fahad Yosuf Al-Sabah signed separate deals on Wednesday with the UAE and Britain as part of efforts to beef up the national coastguard's capabilities.
The agreements with Abu Dhabi and UK-based SRT Marine Systems meet the highest "maritime quality" standards, representing a step towards enhancing Kuwait's maritime security, according to an interior ministry statement.
The deals are part of a broad "overhaul" of the nation's maritime security apparatus, added the statement, singling out the agreement with Abu Dhabi as being a testament to the camaraderie shared between the two Gulf Arab neighbors.
After Bahrain, Saudi and (now) Kuwait, are we going to see a GCC-wide ( ie Qatar, UAE, Oman) roll-out of SRT's MDA system ?
GLA
Hi Paul,
Thanks for the budget summary. Very useful and relevant.
Many small caps look like they've bottomed out today. Not sure where to put the last of my cash. (Like being a kid in a sweet shop!) Love a discount.
2.48 ......CGT, which is paid on the increase
in value of an asset when it is disposed of, is paid by fewer than 1% of adults each
year. The main rates of CGT are currently charged at a lower rate of 10% and a
higher rate of 20%, and these will be increased to 18% and 24% respectively from 30
October 2024. These new rates will match the residential property rates, which are
not changing.
--buried on page 52. The increase begins today.
https://assets.publishing.serv...
For details re IHT on unused pensions from 6 April 2027:
Technical consultation – Inheritance Tax on pensions
Case examples are given towards the end which answer the questions regarding spouse/civil partner exemption and treatment for non-spouse beneficiaries if deceased is 75+.
Ref. Pensions subject to IHT. It seems for the over 75s the total tax take will be 64% ???? !!!! I would be grateful for views on this. Thankyou.
There seems to be a lack of clarity on this . One source says could be double taxation (see my comment further down the thread) - now another source Citywire says there won’t be. As always the devil will be in the detail!
RR announced that she was providing a 50% relief on IHT for AIM shares, she managed to make it sound like a rebate when in fact it is a new tax i.e. 20%.
It reminds me that a number of people give Gordon Brown the credit for introducing ISAs. In fact all he did was rebrand PEPs as ISAs and reduced the tax free allowance from £9K to £6K thereby increasing the rate of taxation.
People on this site will understand what's happened but many members of public will think RR has provided some real relief.
I’m just going to step back from the detail in the budget and alight on a point that might be of interest to some. The uncertainty around the fiscal detail created some really interesting buying opportunities in quality small/mid caps and it was important to grab those potential bargains before the event if you were to have a chance to benefit from a relief rally. Of course, that approach carried a fair degree of risk: the detail could have been every bit as bad as feared, and shares would have fallen further. But it was my impression - strengthened by the palpable nerves evident in these pages - that much of the downside was in the price by the start of this week, and that consequently the risk/reward was skewed towards the upside. In the last few days, and at the expense of US and EUR names that were lower conviction, full positions for the BnB fund were built in the following, usually quite high multiple, names:
Tristel (LON:TSTL) , GlobalData (LON:DATA) ,Tracsis (LON:TRCS) ,
Bioventix (LON:BVXP)
I also added to several existing positions, such as Luceco (LON:LUCE) , Beeks Financial Cloud (LON:BKS) , hVIVO (LON:HVO) , Journeo (LON:JNEO), Judges Scientific (LON:JDG)
And I had just enough time to complete stakes in FW Thorpe (LON:TFW) and Animalcare (LON:ANCR) this afternoon in the 5 minutes before the news hit the tape.
None of these purchases has left the fund notably higher in value. Today’s 5% upwards move in the fund’s second largest position Alphabet (NSQ:GOOG) has probably added as much today. But the expeditious action has put the fund into new names and increased existing positions that strengthen the overall portfolio. Positions that it would have been psychologically much harder to adopt post-today’s relief rally. It’s the old adage: buy when fear turns to panic.
Well done BnB - you seem to highlight some good quality companies in your posts, which I always enjoy reading and adding to my watchlist for further research. I have been reducing exposure to AIM over the past month and let's face it, it could have gone either way today, so wanted to reduce my risk and sleep better at night - however the market will always throw up opportunities - so happy to sit on a bigger cash weighting and let the bargains come to me. I did buy some North Atlantic Smaller Companies Investment Trust (LON:NAS) because it isn't really up at all and holds both Oryx International Growth Fund (LON:OIG) (up 5%) and Odyssean Investment Trust (LON:OIT) (up 5%) NAS sits on a big discount and I like their idiosyncratic portfolio run by Christopher Mills. Happy that the AIM shares I hold are up well - Cavendish Financial (LON:CAV) was a worry as the complete removal of business relief on AIM could have been catastrophic for them. I tried to get the balance right between being over exposed to AIM and being hit if the worst did happen. I did think that business relief on AIM wouldn't be removed because RR wouldn't want to spook the markets and cause a rerun of the Truss budget, especially after talking up growth and investment and speaking with people in the capital markets. I thought she would increase the holding period to 5-10 years.
Thanks for all the hard work again Paul and Graham. Hope you both enjoy a glass of something this evening.
EDIT : Forgot to say - I thought we would see more of a negative reaction in the hospitality/retail sectors.
Have a cookie from the cookie jar
BnB, your thoughts are very much appreciated.
Good for you Bnb
Personally I didn't want to get into any situations that might resemble gambling or betting on a hypothetical/hoped for upside. I have always tried to resist this temptation when share investing.
I did top up some small amounts to some of my holdings in the build up to the budget. But purely on the basis that their shares had fallen so much, without any noticeable change in the business’ prospects, that a 10 - 20% + decline in the share price represented a decent opportunity to buy something that I already thought was good, for a reasonable discount.
Today’s bounce in my portfolio of small caps ( all of which get mentioned regularly on here) was very welcome, although also a relief. The reality is that it only gets me back to pretty well where I was before this budget-fear madness started !
Hopefully things will now settle down now and maybe some lessons have been learned by the senior members of the government.
You cant blame the senior members of govt for the amount of speculation and fear mongering that has been around for the last few weeks. If you want to believe the tory press then more fool you. This is a government that need to be given a chance and the constant criticism does not help. Judge them in 5 years or hopefully 10 when the fruits of this budget should yield some fruit.
I can 100% blame the government yes - they could have had earlier budget or been clear on areas they were not going to change like pension 25% lump sum - it’s simple sensible communication - ok some unnecessarily panicked - but the obvious concerns were real and not addresssed adequately - yes the paranoia didn’t help - but we have similar nonsense every year in run up to bugldget that’s real and politicians beed to deal with that and be clear - over now though do we can all climb back in our hole. Don’t tell me labour did not make a meal out of what they inherited - they happily whipped up the narrative we are in the shit when it’s pretty much business as it always was with quite calm waters -
10-yr gilt rates nudged higher than the Liz Truss fiasco!
https://tradingeconomics.com/u...
Yip. The 10 year yield is now shooting up, currently up almost 2% :-(
Time to bail out of the U.K. I have sold all my UK equity and am invested now mainly in the USA. Hence I will not be renewing my Stocko subscription but I thank all contributors for their input over the last few years, especially of course Paul, Graham and Roland .
Hi Casper4,
I left the UK a long time ago but there are still some good companies with LSE listings so don't completely give up on the UK:-) Also you've got to consider withholding taxes when you buy dividend paying stocks. For example Woodside Energy (LON:WDS) are leaving the LSE (de-listing) and keeping their Woodside Energy (NYQ:WDS) and their Woodside Energy (ASX:WDS) listings. I consequently sold my LSE listing and bought their primary listing in Australia but I'll now get hit with their 30% withholding tax (same as the US withholding tax at 30%)...
I have to ask - which subscription are you replacing Stocko with?
Stocko provides zero US coverage or next to zero and most of the comments on here are naturally UK small/medium caps . I obtain a hell of a lot of US info without subscription but do pay for CNBC and am considering others .
I wish you well but I would urge caution. The UK markets are criminally under-valued. The polar opposite of the US markets. On top of this you have a stable and (arguably) competent government for the next 4 years, compared to a psycopath likely to lead the US into an abyss.
You also have the comparison between our stable government and those of our European neighbours.
I struggle to see why the UK markets should not be a haven for investment over the next few years.
Of course that psychopath was President for 4 years and in spite of all the bluster his administration did a reasonably competent job . Market’s certainly want another 4 years of Trump rather than a left wing Government.
Neither candidate is particularly attractive but I still back US entrepreneurs over the U.K. post Brexit .
Was gonna post the same - one can hate the guy but even if he is obnoxious that doesn’t mean he will do worse job than the other candidate - if nothing else I think he was the one recent us president who didn’t start a new war- on any level kudus for that fact. And he has already done the job for 4 years so predicting an abyss seems to make me question the logic of the original poster rather than trump
Good luck, but I am sticking to what I know and where valuations are attractive, but require patience. The frustrating investment environment that is UK small caps. There are many very good companies on attractive ratings, sevral with exposure to North America. Volex (LON:VLX) and Avingtrans (LON:AVG) and MPAC (LON:MPAC) for example.
Yes but it’s so slowwwwwwwwwwwwwww. Do you really think UK plc will achieve the growth that Labour promises or budgets for ? Not a chance in my view and the economy will quickly be up shit street and the currency with it .This is of course just the first budget——expect far more tax rises in the next few years .
I have been an investor in the US for many years and my returns are so much greater than from my UK portfolio . Now is the time for me to take a rational pragmatic decision and not an emotional one .
Do what is best for you.
But Stocko cover the US equally well!
You MUST be joking .
Do they?
There is hardly any coverage and the performance of the top ranked stocks is quite poor. If l only invested in the US, l would not be renewing.
Surely it matters where the uk shares markets are rather where they are listed?
e.g. Games Workshop (LON:GAW) only 20% of revenue is from U.K. 42% from U.S. 22% from continental Europe. So while have a good %age of pf invested in the states I’m not going throw the baby out with bath water.
That said it is small U.K. businesses, hospitality and farmers that I feel for. This budget is a disaster for them.
Regards
Michael.
£408.8 billion of additional borrowing 25/6 to 29/30 PLUS the cash to redeem expirations.
From a different (lower)level when Truss announced
10-yr gilt rates nudged higher than the Liz Truss fiasco!
Ironic I know. But it’s the rate of change in yields, not the level, that matters to markets
AIM index +4% now. I would expect further strong gains in the days and weeks ahead.
With pensions being subject to IHT from April 2027 the demand for AIM investments may actually increase, at the margin. If pensions were being accessed last or left untouched during lifetime because of the IHT benefit, some of that value may be moved to AIM IHT Portfolios instead, with the likes of Octopus and others, for the 20% tax saving.
All clear, till New Year! Bring on that year-end rally.
Good point Chris but need to be careful about which AIM shares as the rules are not so clear - a lot of AIM shares are excluded and HMT refuse to publish a list of qualifying AIM shares. Wonder if those of us lucky enough to have built up a large SIPP will be able to reduce effects of IHT by investing in AIM shares - same as you can within an ISA...? FWIW - see my post below re spouse inheriting a SIPP - another area I reckon needs clarification.
So, AIM shares only to be exempt from 50% of 40% IHT. Like me, the market reacted to RR's speech which did NOT make that clear at all.
I wonder how Octopus et al will react. They can still sell the IHT benefits of AIM stocks but the benefit is 50% of what it was previously. Perhaps that will still be enough to maintain flows into AIM stocks or will potential investors see this as a half-way house to full withdrawal. Her lack of clarity (candour?) doesn't inspire confidence that that's it now for the term of this government. So the drip, drip of money away from Aim stocks may continue without that clarity.
Against that, I would say that there's plenty of aspiration to capture inward investment and plenty of taxpayers' money being chucked at infrastructure and digital connectivity in government so perhaps the benefits to some AIM company P&L will counteract the partial loss of IHT relief
is this a turning-point for sentiment? The relief rally will probably fade somewhat by the end of the day but the gloom that has been hanging over the market should now dissipate and we can get back to focusing on company performance. Oh, and the multitude of geo-political risks and the US elections which are and always were, arguably, more important to prices here.
On balance, I don't see that this Budget will halt the outflows from the UK market but it might just provide a temporary base for prices
Ref. The over 75 person ..a double whammy???!!! Pensions now subject to IHT. Also person receiving it still subject to Income tax at their marginal rate????
do you have link to anything on official site confirming this ?
No - but thats how things work currently and I don't think there is any intention to change this - not that I have seen anyway!
Paragraph 2.10 of this document would suggest there will be potential double taxation for beneficiaries withdrawing income from an inherited pension:
https://www.gov.uk/government/...
I think Para 2.10 refers to what would happen under current rules, but with pension brought into IHT. And it focuses on how the IHT due on the pension element would be paid, not subsequent income withdrawal.
Para 2.16 explains that (as I understand it) the pension administrator would be able to pay the IHT due in respect of the pension directly from the pension funds
At a quick scan, I can't find any commentary about changes to how beneficiaries inherit, so I'd guess it will remain as currently - so, yes, income would be subject to income tax iro inheritances from people >75.
I believe the Budget intends to remove the anomaly where there is currently potential for double taxation (IHT plus income tax) solely on non-discretionary schemes. In future inheriting from non-discretionary schemes will be treated the same as inheriting from discretionary schemes and both may be subject to IHT (and possibly income tax) and paid out net. Pity the poor pension administrators with yet another complication.
Yes- person receiving also pays income tax - but only when they actually take the money. They can do so in stages over several years - in effect creating a new SIPP for themselves. Thats how I understand things
Thankyou Bohenie
64% total tax take is draconian.
Did anyone see if there was any change to the uplift in share price purchase to current price on death ... ? Ie you can bequeath shares to a spouse iht free and get a new, current purchase price ... so no CGT ...
It appears that this is the case from one source at least. (Forvis Mazars budget update):
Taxation of death benefits
The taxation of pension death benefits has long felt overly generous with tax relief on contributions, tax-free investment growth and funds able to be passed on tax-free at death. It is therefore of little surprise that Labour has announced that pensions will now form part of the estate for IHT purposes from April 2027. Initial announcements also confirm that IHT and Income Tax could be payable for death after the age of 75. This could create an effective 67% tax charge on pension death benefits. As ever, the devil is in the details and any changes to legacy plans must be thoroughly considered before taking action.
The 67% assumes a 45% taxpayer - for a 40% taxpayer it is slightly less at 64%. If the detail confirms this then there are going to be some major implications for inheritance tax planning!
So, the £20,000 ISA allowance looks locked in until 2030:
https://www.scribd.com/documen...
5.58 Individual Savings Accounts, Lifetime ISA, Junior ISA and Child Trust Fund Allowance –Annual subscription limits will remain at £20,000 for ISAs, £4,000 forLifetime ISAs and £9,000 for Junior ISAs and Child Trust Funds until 5 April 2030
Thank you Paul for that fantastic speedy summary - my brain was fried by RR's preamble, I don't have the patience for reality TV;-0
First £1 million
The existing 100% rate of relief will continue to be available for the first £1 million of property qualifying for business property relief and agricultural property relief.
The existing rate of relief will continue at 100% where it is currently this rate. The exception is for shares designated as “not listed” on the markets of recognised stock exchanges, such as the AIM, where the rate of relief will be 50% and will not be affected by the new allowance.
The existing rate of relief will continue at 50% where it is currently this rate and will also not be affected by the new allowance.
Brilliant, “Instant” summary, thanks Paul.
NHS to receive £1.5bn for new beds, surgical hubs and scanners, but guaranteed military support to Ukraine of £3bn per year.
The present value of a perpetuity of £3bn, using a cost of capital of 5% (BOE base rate) is 3/0.05 = £60bn !
It seems investment in arms manufacturers is always a safe bet. Now what sort of world would it be if we banned them.
https://www.gov.uk/government/...
from 6 April 2026. Relief of up to 100% is currently available on qualifying business and agricultural assets. In addition to existing nil-rate bands and exemptions, the 100% rate of relief will continue for the first £1 million of combined agricultural and business property to help protect family farms and businesses, and it will be 50% thereafter. The government will also reduce the rate of business property relief available from 100% to 50% in all circumstances for shares designated as “not listed” on the markets of recognised stock exchanges, such as AIM.
The £1 million allowance
A new allowance will apply to the combined value of property in an estate qualifying for 100% business property relief and 100% agricultural property relief.
....Where the rate of relief for the agricultural property or business property is at 50%, for example quoted shares in company giving the transferor control, the rate of relief will not be affected by the new allowance.
....so no £1 mil allowance for AIM shares.
deleted
thanks laurie:
"
First £1 million
The existing 100% rate of relief will continue to be available for the first £1 million of property qualifying for business property relief and agricultural property relief.
The existing rate of relief will continue at 100% where it is currently this rate. The exception is for shares designated as “not listed” on the markets of recognised stock exchanges, such as the AIM, where the rate of relief will be 50% and will not be affected by the new allowance.
The existing rate of relief will continue at 50% where it is currently this rate and will also not be affected by the new allowance."
I also read this to mean there is a blanket 50% relief on AIM shares and not eligible for the 100% relief up to £1m as part of BPR?
Everyone else is saying its over £1m so have I got this wrong?
Well at present AIM or at least my portfolio of 24 shares of which 17 are AIM listed appear to like the budget, I suspect it is more relief that the outcome was feared to be much worst that it is.
However I haven't yet summoned sufficient bandwidth to properly understand the full implication. I look forward to this afternoon's (5pm) presentation by Ed and Megan.
Lots of rumours pre the budget regarding pension tax free lump sum. I could see no reference to this. Are these rules likely to be addressed in the days ahead or do we take it there are no changes?
is there still 100% IHT relief on the first £1m in AIM shares? I can't tell if thats for just agri + business property or also for AIM. Please can someone clarify
No unfortunately.
https://assets.publishing.serv...
2.51 ....The government will also reduce the rate of business property relief to
50% in all circumstances for shares designated as “not listed” on the markets of
a recognised stock exchange, such as AIM....
5.54 ....The rate of relief will be 50% thereafter,and in all circumstances for quoted shares designated as “not listed” on the markets of recognised stock exchanges, such as AIM...
Under "The London Stock Exchange" AIM is designated as "Not Listed"
https://www.gov.uk/government/...
Pensions liable to IHT from 2027. Didn't hear a mention on a reduction to the max cash withdrawal of £268k currently. Lot better than expected. AIM index up sharply.
Can we have another budget next week?
One a week until Christmas and I might break even!
Don't joke. Rachel from Accounts might read your posts.
reTime Out (LON:TMO) perhaps Paul could take a weekend break to Lisbon (lovely) then visit the Time Out Market (it's brilliant) which might help inform his understanding of the product and he'll have a great time out in the process....
Thanks Shrubby, that's a nice idea actually, I've never been to Lisbon and would like to visit, and checking out the Time Out market would be a bonus. Improving my understanding of the company would be helpful, but my main concern remains that it doesn't actually make any profits!
I've been and it's a great concept
The Time Out Market, that is, Lisbon is a pretty good concept too :p
Unless I've missed it nothing mentioned regarding gambling - Gaming Realms (LON:GMR) is looking better
5.107 Remote gambling duty reform – The government will consult next year on
proposals to bring remote gambling (meaning gambling offered over the internet,
telephone, TV and radio) into a single tax, rather than taxing it through a three-tax
structure. This will aim to simplify, future-proof and close loopholes in the system.
page 139 here: https://assets.publishing.serv...
My PF is going gangbusters, best day of the year...
have I missed something :) Beeks Financial Cloud (LON:BKS) Filtronic (LON:FTC) Team17 (LON:TM17) all over 10% rise, everything else upto 5% up happy days
I did a comedy double look when I saw the share price of Liontrust Asset Management today.
Nevermind
Possibly balanced down by the preceding 2 months trepidation.
All equity investors need to know is that up to £1m of AIM shares are free of IHT and above that the tax is due at only 20% and only than after April 26. So it’s a nothing burger for the vast majority of investors. IHT shares are up!!
Meanwhile CGT goes from 20% to 24% out of respect for the Laffer curve. Another nothing burger and it is safe to buy UK shares IMO
I didn't hear the ref to the first £1m being 0% - see colin1862 post below - are we sure its above £1m?
Yes, from April 2026 the first £1m of an estate will continue to attract no IHT. The 50% relief for AIM shares (which takes the effective tax rate to 20%) kicks in over £1m.
No wonder IHT qualifying shares are having a nice day!
thanks
...unfortunately not correct. R Reeves wasn't clear. I wasn't sure so I've looked up the published documents. My post has links to the government wording.
repeated here so you don't need to look for it:
https://www.gov.uk/government/...
deleted
Deleted
" I can also announce that we will apply a 50% relief in all circumstances on inheritance tax for shares on the alternative investment market, and other similar markets, setting the effective rate of tax at 20%."
Update. I have now consulted someone who knows far more about BR than I do. The £1m threshold is set for all estates. But because of the way BR works on AIM shares, it's likely IHT will need to be paid (with the 50% relief) on the whole portfolio.
ok thanks - think that is correct:
First £1 million
The existing 100% rate of relief will continue to be available for the first £1 million of property qualifying for business property relief and agricultural property relief.
The existing rate of relief will continue at 100% where it is currently this rate. The exception is for shares designated as “not listed” on the markets of recognised stock exchanges, such as the AIM, where the rate of relief will be 50% and will not be affected by the new allowance.
The existing rate of relief will continue at 50% where it is currently this rate and will also not be affected by the new allowance.
I presume 50% is still good enough - what do people think? Are there better IHT relief mechanisms out there to draw the funds out of AIM , or is 50% better than anything else?
Guess it depends when you think you'll die. AIM is 2 years to get out of your estate, the rest are the 7 year scale. If over 7 years then trusts and gifts might be used more. There will be more pressure to buy farms, forestry, EIS or into a business maybe - they would give the first £1mil at 100% relief - which would be a difference of £200k. I think EIS might be more attractive - this would probably drive growth more than AIM as people would invest in start-ups. I suspect the whales will go which could be a problem. "68 estates were able to shelter £1.8 billion from inheritance tax using business relief."
"68 estates in question in the tax year 2020-21 represented just 2% of claimants, but 57% of the assets which benefited from the tax break." Now if you where those 68 would you leave your £1.8 bill in AIM or use some very smart professionals to get round it another way? So maybe half the IHT funds could leave AIM
Personal pensions now liable for IHT. A massive change…..
Personal pensions now liable for IHT. A massive change…..
They were already if you live beyond 75 years for obscure reasons I’ve never understood. Nevertheless it is a significant change.
Note: Inherited pensions (upon death after 75yo) were subject to Income Tax at marginal rate previously, not IHT.
Even more complicated and opaque than I recalled!!
of course things are complicated, but, I think IHT will still not apply if you have a spouse / civil partner. (if IHT does apply i will join you in outrage/protest)
SPOUSE INHERITING SIPP Think this needs careful study. Current rules allow a SIPP to be passed on after the age of 75 free of IHT - but the recipients pay tax on whatever they withdraw - they can keep the SIPP running and thus only pay tax on their total income year by year. So - with SIPP now being subject to IHT - I suspect that even a spouse will inherit the SIPP subject to IHT and be obliged to pay tax on the funds as withdrawn, year by year.
If a 40% taxpayer; so total tax will be 80%?????!!!
I think it would be 64%, as post IHT pot would be 60% which would then be subject to income tax, so 40% + 60% x 40%.
I'm pretty sure they will intend for pensions to be covered by the spousal exemption. So you will be able to pass the pension to your surviving spouse without IHT being charged. It would then be taxed when the surviving spouse dies.
Sorry, I wasn't clear. 64% applies to non-spousal beneficiary. Spouse would be exempt from IHT but, liable to income tax on drawdowns.
Condoc at https://www.gov.uk/government/...
Correction and thanks to others for their comments - When a spouse or civil partner inherits a SIPP then no IHT to pay - just income tax on withdrawals - which can be phased to reduce tax payable.
Excuse my amateur question but... Should there have been a reaction yet?
If i heard that right - re. IHT, 50% relief on AIM - was there reference to a timeline to implement?
Over £1m the 50 % relief on AIM kicks in - I think April 2025.
so still 100% under £1m - i missed that!
That refers to Agricultural Relief.....'I can also announce that we will apply a 50% relief in all circumstances on inheritance tax for shares on the Alternative Investment Market (AIM), and other similar markets, setting the effective rate of tax at 20%'. ...Could have been a lot worse as they could have removed it completely. Not sure when it will apply from
RR lead with - investment, investment, investment - like Blair's Education, Education, Education.
I haven't been so nervous watching a budget before...
As an aside - how long does the shadow chancellor get to prepare?
As they will acknowledge in their response, they are given the budget speech on the morning of Budget day itself
Yes, great company but not much margin of safety. Developed a lot of grey hair before learnibg that.
Team17 (LON:TM17) . Some might be interested to consider this as an investment. Interesting management change RNS today. New CFO will be Rashid Varachia, previously CFO at Codemasters until it was acquired in 2021. This appointment brings 2 of the Codemasters management team back together. Frank Sagnier, non-exec chair at TM17, was CEO at Codemasters when Rashid was CFO. This appointment completes a refresh of the BoD at TM 17 with Steve Bell replacing Debbie Bestwick as CEO at the start of this year when she stepped back to non-exec role. She remains the biggest shareholder. 2 funds have been adding recently - Octopus, which is interesting as a fund focussed on AIM shares for BPR, and Gresham House, with Janus Henderson reducing. The share price is bouncing around all time lows.
Team17 (LON:TM17) I thought this line was hilarious:
”Mark Crawford, the Group's current Chief Financial Officer, is stepping down on 31 October 2024 to pursue other business interests and is working with the Company to ensure an orderly handover.”
In other words he leaves immediately…. :)) but that wouldn’t have sounded so good.
Team17 (LON:TM17)
Is it just me or are they not saying that he will still be available to ensure handover is orderly - normally they dont mention orderly handover that i can think of ??- imho if he goes tomorrow and will have no further contact that does not sound like orderly handover to me ? - so it sounds like he "might be available to speak to" at minimum (hopefully more if needs be) kind of situation which presumably can be very helpful compared - new bod going wtf is this and they cant ask any questions as he has gone.
I would say no specific red flag as such - but deffo a general red flag for someone leaving at such short notice - until next trading update is released i would be slightly worried there may be kitchen sinking turning up for new replacement - or there might be behind the scenes reasons for him leaving dressed up as something innocent.
If there was a reason for Mark leaving that affected forecasts etc they would have to announce that at the same time wouldn't they??the new guy is also COO so maybe he's making big changes, starting with saving a lot on a CFO wage Team17 (LON:TM17)
Team17 (LON:TM17)
If there was a reason for Mark leaving that affected forecasts etc they would have to announce that at the same time wouldn't they??
in theory yes - however often the company results can be as much akin to a piece of artwork as it can to being simply spreadsheet additions. So if finance person A (going now) has maxed out profits (because they can) and finance person B chooses not do so (because they can) the obvious thing to do is once they get their feet under the table is to throw the prior cfo under the bus and make changes straight away to policies "more conservative" - heck if that makes prior years stuff look worse it makes this years (and future years possibly) look better - so reflects better on them. I have zero indication any of that would sepcfifically be going on here - so no specific concerns ref this company - just thats there is always the possibility that when the cfo leaves at short notice that there might be something up not as of yet made public hence the "general red flag" - note they do have alot of capitalised intangibles here (over £200 mill) so there are some big numbers involved - the value of this did actually drop per the most recent 6 monthly figures - normally one would probably start to worry if the sum total was growing .
I am not sure how the new guy comes into it either if they have someone in place already perhaps its innocent and that facilitated this guys ability to leave now without anythinmg being impacted.
cfo's dont stay forever so their change is something every company will need to cope with periodically
My God, PMQs really is dreadful.
No opposition as they are reading from the same script. All smoke and mirrors.
It was better than the budget so far. Blame, blame blame.
The whole thing is insufferable. Hundreds of adults on both sides chatting and heckling like children.
I feel a bit sorry for Paul S. He’s been waiting over 20 minutes to type something specific …
How have we ended up with such a low calibre of politicians?
Why would anyone better want to be an MP?
what about The USA
I don't think we are allowed to tax them any more.
My observation so far would be that I'm surprised at how many buyers there have been this morning!
BKS, FTC and CRW have all bounced 6%+, I can't understand why you would be a buyer before the statement, but potentially they are pre-empting it being all bark and no bite?
Either way, the market makers will be laughing today if they've got their books in order ;)
My suspicion is that some of those who sold out a month ago are buying back in having locked in the capital gain - and getting back in at a lower price? I did consider this - but I am so bad at market timing I decided just to sit and watch the fun instead,
cheers
Mark
Well we went for an amazing afternoon Turkish bath and there I was hoping for blood on the street but alas my folio is up 10% today. What a double edge sword! I’m actually cool with that as it encourages me to work a bit harder looking for something new and undervalued. However still value in Filtronic (LON:FTC) and Beeks Financial Cloud (LON:BKS) . I’m taking a deep dive Cordel (LON:CRDL) and Gulf Marine Services (LON:GMS) is something that’s well investable but I want it at 15p!
Once upon time to have car meant you had to have someone walking in front of you with a red flag. I suspect Govt is increasingly of this persuasion when it talks about growth strategies.
I was just out with the dogs catching up with Paul’s podcasts, thanks for getting up to speed Paul and chapeau to your frank honesty re Plexus Holdings (LON:POS) , hopefully things will turn there for you and all investors. I thought I’d add to the anecdotal discussion re Bloomsbury Publishing (LON:BMY) . Each Saturday The Times , in their Weekend pullout, have a bestseller list for fiction/nonfiction paper and hardback and as a previous holder of Bloomsbury Publishing (LON:BMY) I watch it every week and I noticed that they hardly ever have a book in the top10 or a new publication in the list. Yes Sarah J Maas has been in and out all year but not top 3 and earlier in the year the Chinese author published under Zeus, but still a Bloomsbury book was in the top 10 but hasn’t reappeared and from what I can see the Netflix show hasn’t been a barnstormer. Of course it’s anecdotal but there isn’t a SJM book this coming year, so they may struggle. It’s a hard call because to be fair to management they haven’t done much wrong.
Just another relaxing day in the markets...what could go wrong?
Avation (LON:AVAP) Azorra, which has been backed by Oaktree since 2021, is interested in a takeover of commercial aircraft lessor Avation, Sky News understands.
Blimey, I'm not hot on timing but only bought these last week.
Centamin (LON:CEY) - Has anyone any idea where we are with the Ashanti bid please... is it going through - or is it stuck ?
My understanding is that it has been approved.
As Bill Blain often says "it's never as bad as you think it will be, and equally it's never as good".
"Prepare for the worst, hope for the best". Disraeli
"If you want peace, prepare for war". Attributed to many, but arguably Roman general Vegetius.
"Whether we’re talking about socks or stocks, I like buying quality merchandise when it is marked down" Warren Buffet
Best keep the brown corduroys on today. Either way will the brpkers be able to deal with the flood of orders.
I'm less concerned by the brokers, but worried about the Market makers taking the proverbial.... although tbf to them, we're in a fairly binary situation with big volatility likely in both directions... given how bad the liquidity usually is, today will be horrendous...
I know that we usually frown on people reporting trades, but can we agree that just for this afternoon it's acceptable... would be really useful to hear when people have found bargains / pockets of liquidity ....
One thing is for certain - it's the one day of the year when the market makers are not on the p**s at lunctime!
Re yesterday's topic.
Incanthera (inc on Aquis) price has halved for no specific reason . Starting to climb again this morning. Big orders from AS Watson, had promised update on timing by end October which has small delay. Risky, but huge potential
It's the uncertainty that has spooked the shares. Why the delay after the ratcheting up of orders from Marionnnaud. I expect a bounce when the clarification comes, but their pointing to the fact that they can't say more for now has encouraged dark imaginings as to what exactly it is they are not saying. Still the 1.5x sales price looks attractive again based on a sanguine approach to the delay in communications.
Missed all the fun yesterday .
My top selection of Wealth and Health for a Wednesday morning
National World - I think Rockwood are going to drive the value out and that muppet David Montgomery (who wasted 800k on aborted ego driven attempt to buy the telegraph).
Phenolic Olive Oil - always worth buying and going to make you healthier .
Centaur - can't get away from its break up value and chairman has walked .
Titon - high risk nut very big director buys yesterday
Honey from the Dayak tribe of Borneo - massive anti inflammation properties (off there next week)
Saatchi - had to listen to Richard Staveley wax lyrical
Avingtrans / Capital / Hargreaves / MSI / Billington - all rock sold just pick up on the over reactions .
Honey?!
Keluluk honey from stingless bees from the nomadic dayak of Borneo .
An awful lot of common sense in the comments of early posters; flying to the Canary Islands, gentle walk to the pub etc. As for me I am off to the gym then going to meet my wife for a bite to eat and some very modest retail therapy.
Hargreaves Services (LON:HSP) good update, as expected. Again like most small caps, especially on AIM has been battered. I have a little cash to deploy and will be lookin to add to existing holdings once the dust settles.
Polar Capital Holdings (LON:POLR) Restore (LON:RST) and Hargreaves Services (LON:HSP) and Kier (LON:KIE) are among those on the watch list and possibly buying back into Card Factory (LON:CARD)
Retail sector will be interesting today after the Budget . How will the excellent results from Next (LON:NXT) play out against any employer National Insurance rises or other cost increases it imposes ?
I wander if the ever increasing wage costs will speed up the drive towards automation - i know you can only go so far with automation but perhaps there is scope here for mitigation by improving efficiencies via more automation. I note Ultimate Products managed to up profits per employee - ok thats a different busines type from retail. But if you take your average spoons now (£JWD for the non regulars) - app orders must be aprroaching something like 50% of sales and they are done in back room out the way - one would think it would be possible for robotic beer pouring on say the most popular drinks would be possible. I think robotic waiters is perhaps a step too far at present - albeit it would be comical too see 5 of them (suitabley named up - Brexit Bob - Halve Vat Val) interacting with your average 6 pints in spoons customer in your local.
A couple of years ago, when we were in a NewZealand Indian restaurant, we had all our food delivered by robots, which emerged from the kitchen and went straight to the correct table. Not only did it save staff but the owner reckoned the novelty of it brought in extra customers
'I wander if the ever increasing wage costs will speed up the drive towards automation'
I have long been thinking the same. Partly because I when I started in the aerospace/defence sector in the early 80's it was in the midst of a previous upheaval in the industrial base. It really isn't different this time?
I think its inevitable. Failure to plan and invest for this will see a lot of business models turn upprofitable. You could say that the rise of cheaper imports has already achieved a lot of this. Now it may be the turn of sectors where cheap imports have not yet left their mark?
I struggle to understand how economies with much higher employment costs
than the UK - have improved productivity at a higher rate than the UK
in the last decade? We are regularly told it should be the other way around?
It can be no great surprise that an incoming left of centre government will push up the costs of employment through tax and minimum wage? A rational response is to look to boost productivity - particularly in industries which have tended to rely upon low cost labour? Not just hospitality and retail but also logistics, heatlh and care, support services, farming, FMCG .... and of course manufacturing - whats left of it is going to look very different before long?
As we exit the first quarter of the 21st century and head towards the middle - it seems inescapable to me that by mid-century we'll be a lot more automated. Will we more productive enough to raise all living standards? Remains to be seen? But if we aren't much more productive then I really fear for our future?
So what does that mean for my portfolio?
For the last few years I've been looking for UK small cap companies which are investing heavily on the productivity theme - both for themselves and their customers. My preference is for a profitable, but perhaps declining business which is funding a transformation into new more productive markets. The relative improvement in revenue and profit per employee is a KPI for me. Very Philip Fisher (Common Stocks and Uncommon Profits)? Businesses like MPAC (LON:MPAC) spring to mind although its one thats always been on my watchlist and nevery quite made it to me dozen UK small-cap portfolio. Also Eleco (LON:ELCO) in the construction industry which I held for some years.
So whilst waiting for budget I thought I'd highlight where I've been looking for productivity gain - future as much as now among those that I have currently hold :
Vianet (LON:VNET) - not an obvious bargain after rising 2.5x from its lows - is a play upon rising productivity in hospitality and retail. Transformation from a hardware manufacturer and vending machine filler to a mobile payments services, data management and analytics platform is remarkable. As always it remains to be seen whether the transformation will allow the company to capture the opportunity with an accompanying transformation in revenue and profits - I can't tell the future. Sadly.But I know that it will be interesting.
Celebrus Technologies (LON:CLBS) - similarly this ex-managed IT services company is not obviously cheap now its risen close to double its recent lows. The continuing transformation to a private cloud platform for first party (cookie less) customer data analytics and fraud detection and prevention raises the productivity of both the company and its customers, though has - yet - to transform revenues and profits. Again. These things always take longer than I expect. But with current yoy ARR gorwth of >20% - quality compounding will do the job.
1Spatial (LON:SPA) - After years on my watchlist I finally bought on the recent lows. Why> Well its now profitable and the recently launched SaaS applications demonstrate the potential for its customers. As an example - the demonstrated improvement in productivity by its recently launched 1Streetworks SaaS platform is remarkable - UK Power Networks has been the launch customer and demonstrated 40% reduction in road closure time together with halving the delivery time to their customer from two weeks to one week. The productivity improvement seems to be a win-win all around and to say the SaaS platform subscription more than pays for itself is quite the understatement? Not cheap but a very interesting opportunity in the support services (hole digging) sector and the spatiale data management more generally?
Cyanconnode Holdings (LON:CYAN) - A long term disappointer and serial fund raiser of the first class. I first bought CYAN back in 2003 - I had a lot to learn then, of course I still do - but so did CYAN. The small holding devalued so fast I never quite managed to sell it and in the end it wasn't worth the cost of selling it.
In the last couple of years in an attempt to clear out some rubbish I took another look and discovered a business transformation hiding in plain sight? Over the last 20years this wannebe RF component manufacturer for automated meter reading has pulled itself up the value chain to turn itself into a software data management and analytics platform for networks (either RF Mesh or Cellular or both) of installed meters. I am - again - a little previous in my re-entry as the company is not yet profitable - AFTER 20 YEARS on AIM !!!! - but with 80% of this years revenue already contracted and more contracts won recently I jumped in. Installing millions, actually tens of milions, of meters is only the start. As CYAN will earn as much if not more from the continuing data management and support of the networks through its platform. And thats the bit that I'm most interested in. Ironically the UK has been a long running disaster for CYAN - we do it so well don't we? - it's in India, the Middle East and North Africa where going straight to automated meter reading is really taking off?
Synectics (LON:SNX) - despite its strong rise the recent fall back leaves this looking weirdly cheap - especially as its just entered a potential 'upgrade' cycle. The opportunity for 'digital twin' asset management and security is enormous. long term investment in the high spec camera product - but more importantly the software platform looks to be putting Synectics (LON:SNX) in a good position especially for critical infrastructure - something that's being revisited a lot thanks to the ongoing war in Ukraine.
Software is an obvious place to look for the picks and shovels of productivity gains - both for the high margin SaaS sellers and the customers. But in manufacturing I hold some unloved companies that have invested heavily in productivity not just through employees, but also energy costs, automated production, logistics, direct online sales channels and the like.
Portmeirion (LON:PMP) - I know everyone loves to hate the company right now. But that always whets the appetite of the contrarian in me. Dangerous I know. The recent change of bank to Barclays to Lloyds removes the audit 'going concern' question and provides a longer term more supportive facility. The recent interims were terrible but 'in-line' with always heavily H2 weighted FY expectations.
If Portmeirion (LON:PMP) do achieve their FY expectations of increased eps to 25p on slightly reduced £100m turnover it will be in large part due to the large investment in their manufacturing - improving productivity through automation, energy efficiency, raw material usage, lower wastage and more efficient logistics, sales and marketing. Took 10%, £4m out of the fixed cost base just in the nick of time?
With the shares trading on 6x (12mth fwd) P/E, P/S 0,32x (ttm) , P/fcf 6.4x (ttm) and P/NAV 0.58x it will be a remarkably transformation - IF - they succeed.
I use a score card approach to measure the relative attractions (or otherwise) of the companies I hold and that includes multi-bagging potential. According to my score-card Portmeirion (LON:PMP) has a very high multi-bagging potential due to the small increase in revenue leading to increased operating leverage over reduced cost base.
With the new bank facility, in-line interims and order books ahead of this time last year - the odds gainst appear to be shortening. I couldn't resist adding a few. Just in case. But as always - I get it wrong more often than I get it right!
Airea (LON:AIEA) - has a product line of 'zero carbon' carpet tiles which is selling well. But the product costs them far too much to make with increases in raw material, labour and energy. The company is using its cashpile to transform it's cost base with automated manufacturing, reduction of waste, more efficient use of materials and processes. While the solar array installed on the roof massively reduces the energy costs and contributes to the 'carbon zero' products.
Goodwin (LON:GDWN) - compared with some it's taken me far too long to recognise the potential of this century old foundry business. Huge ongoing investment in the facilities has created a unique foundry needed by large longterm defence and nuclear programmes as well as transforming the productivity of the operations. Buying the shares even though they have fallen from recent highs does require some visibility of the potential - I recommend reading Alex Sweet's take 'Breaking Good'
Although I've gone on far too long already - as usual I can't finish without mentioning the transformation in productivity at MS International (LON:MSI) - in all divisions, the forging, superstructures and branding as well as at the defence division whose automated anti-drone weapon systems have been capturing some attention recently.
This hasn't happened overnight. I am generally far too impatient. these changes take far longer than I expect. Or want. I recently became aware that the management at MS International (LON:MSI) started this business transformation 30years ago (and have no intention of stopping yet just when its starting to bear fruit) - really got my attention. Another gem is that productivity at Defence has increased enormously as product deliveries increase. They've reduced the delivery of the land-systems three-fold from 12months to 4 months. Whilst still working just one shift. Though to be frank there is not a lot of alternative as the labour pool for this talent is very constrained and in high demand right now. Fascinating! I look forward to what they come up with next?
I could go on! But my huge apologies to anyone who manages to read this far! Didn't intend to write so much. I guess you can see that I reckon transforming productivity is going to be pretty central to the companies that survive in the coming decades? A lot won't but we might be surprised by some that do?
cheers
Mark
Thanks for sharing, really interesting
I'm having a wonderful time in Turkey and won't be watching the budget - although I will be looking for opportunities tomorrow having now 20% cash and some more available, unless Reeves does something really daft like not letting me top up the kids ISA's!
Supreme (LON:SUP)
Filtronic (LON:FTC)
Beeks Financial Cloud (LON:BKS)
Kier (LON:KIE)
Are what I'm looking at adding to. That said, I'm also no longer wed to the idea of having to buy UK given the success of US shares this year and I've also doubled my bitcoin holding this year on the back of an extremely successful 5 year holding of Etherum. May go long on silver too.
The above demonstrates that actually, there are many more instruments that one can use to make money, depending on the economic climate and personal situation. I'm toying with the idea of moving 80% of all my money into a larger property assuming CGT isn't an issue then waiting for a drawback on the SP500 and then letting all that ride and do nothing at all and revisit in 20 years.
My morning smallcap tweet: Budget brings blizzard of biz sale completions.
Time Out (LON:TMO) Cab Payments Holdings (LON:CABP) MicroSalt (LON:SALT) Eckoh (LON:ECK) ValiRx (LON:VAL) B.P. Marsh & Partners (LON:BPM) Nexus Infrastructure (LON:NEXS) OptiBiotix Health (LON:OPTI) Rua Life Sciences (LON:RUA) Caffyns (LON:CFYN) Gooch & Housego (LON:GHH) SDI (LON:SDI) Venture Life (LON:VLG) Zinc Media (LON:ZIN) Equals (LON:EQLS), Hargreaves Services (LON:HSP)
◄Time Out (TMO)► £8m placing at 50p, a 10% premium, to "two new potential markets in London and New York, and to accelerate Media technology investments". [SP=44 Cap=150m]
◄CAB Payments (CABP)► offeror StoneX conducting due dil. Warns FY-Dec rev below exp after weak Q3. Also dilution in overall take-rates. "Reason to believe that this pick-up in volumes in Q4 is unlikely to materialise owing to changing global macro-economic and political factors." [SP=120.4 Cap=306m]
◄MicroSalt (SALT)► wins orders which may lead to volumes of 840000 lb PA. [SP=45.2 Cap=22m]
◄Eckoh (ECK)► rec offer of 54p, an 11% premium. [SP=41 Cap=119m]
◄ValiRx (VAL)► update on proposed sub-license of VAL201 - exclusivity of talks has been extended until end Dec. [SP=1.56 Cap=2m]
◄B.P. Marsh (BPM)► buys 30% Cumulative Preferred Ordinary shareholding in SRT & Partners, a start up UK Retail and London Market broker. The funds have been used by SRT to complete its first two acquisitions. [SP=606.1 Cap=225m]
◄Nexus Infrastructure (NEXS)► buys Coleman Construction & Utilities for £5.4m max. Trading in line. [SP=135 Cap=12m]
◄OptiBiotix Health (OPTI)► advisor to ProBiotix Heath has refused to allow OPTI to vote its shares in the GM it requisitioned to remove the CEO. [SP=12 Cap=12m]
◄RUA Life Sciences (RUA)► guides H1-Sep pretax £0.4m (-£1.4m). Moves FY end to Sept 25 from March "to better guide business planning and international business unit assimilation". Well, I'm glad there's a compelling reason. [SP=12.6 Cap=8m]
◄Caffyns (CFYN)► sells freehold in Lewes for £4.65m where it has a Lotus dealership. [SP=410 Cap=12m]
◄Gooch & Housego (GHH)► buys Phoenix Optical for £3.4m plus £3.35m earn out. [SP=428 Cap=110m]
◄SDI (SDI)► buys InspecVision for £6.1m. [SP=53 Cap=55m]
◄Venture Life (VLG)► buys Health & Her for £7.5m plus up to £2.5m contingent. [SP=41 Cap=52m]
◄Zinc Media (ZIN) ►buys Raw Cut for £1m plus £5.5m earn out.
◄Equals (EQLS)► extends PUSU to 20 Nov. Due dil done and 2p div sweetener. Is this a dozen times now? Unbelievable. [SP=111 Cap=211m]. I hold.
In line: HSP
The Equals saga is like Coronation Street. I have held but my instinct is that something smells.
Eckoh (LON:ECK) are pleased to announce that they have reached agreement on the terms of a recommended cash acquisition by Bidco of the entire issued and to be issued share capital of Eckoh (the "Acquisition").
· Under the terms of the Acquisition, Eckoh Independent Shareholders will be entitled to receive:
for each Eckoh Share: 54 pence in cash
As all grey-haired investors like myself know 'Patience = Profits'.
Sure Equals (LON:EQLS) 's 12 month strategic review may have taken a little longer than originally anticipated.
Yet today, this rapidly expanding B2B foreign exchange & international payments platform said that the bidding Consortium (ie JC Flowers & TowerBrook Capital Partners L.P.) had nudged up their indicative non-binding, all cash offer to 135p/share, plus a 2p special dividend.
The latter to be paid at completion, and probably reflecting the group's prolific cash generation.
The Consortium confirmed too, it has now completed its due diligence and is advancing necessary transaction documentation.
Meaning subject to any last minute hitches (god forbid) in this lunchtime's Budget, then I'd expect a formal agreed offer to be submitted to shareholders sometime over the next fortnight.
As such, the PUSU has been extended again to 5pm 20th November 2024.
Disclosure: #EQLS is my largest personal stock holding and is a
Vox Markets client
Well done Paul H, it does look as if patience has (almost!) paid off with Equals (LON:EQLS) which I'm pleased to see. What a bizarre situation though, in many ways!
Agreed Paul
12 months is a little extreme - albeit nothing in the world of smallcaps should now surprise us two old timers!!
A little hat tip here Paul, I opened mid size position in Equals (LON:EQLS) just over a month ago at 114p, this was primarily after reading a detailed piece you put together on the risk reward at Equals and how the chances of the deal falling through looked slim. Not over yet but looking good. Cheers.
Many thanks BenHazz. Good luck too with all your investing. Nothing comes easy in this game
As a holder though Paul you and I both know this is an opportunistic bid at well below the real value of Equals (LON:EQLS)
What I will be interested in is whether the board is staying with the company to drive growth and how much they get on that. Ie is this actually going to be in shareholders best interests or directors best interests?
To me, the Board have done a sterling job keeping the business humming - amid pretty challenging macro conditions & distractions from the Strategic Review
But that doesn’t really answer the question Paul
Yes, the board have done a great job growing value whilst coping with the distractions and challenging macro BUT appear to be looking to offer the business to a seller at a discount to its real value…… Why?! That is the question……
Then factor in that this has been going on a year so the buyer has had all that growth for no risk and essentially for free. Well aside from this 2p divi we might get.
Sorry for the negative tone but on the one hand you reckon the business is worth north of 175p (I agree btw - I think your analysis is bang on) but management are happy to take 137p? Why would you do that unless the PE coming in are giving you some nice upside terms? Which then begs the question - who are the board working for - themselves or shareholders?
I’d like to understand that dynamic.
Hi Paul...I assume that there is still time to top up? Currently 120p so the delta here is 15p and the spec div. Or I am missing something?
Well the price ended at 124p but something says the market is still not buying the story.
For my money, in addition to questions around the motivations of Equals (LON:EQLS) management along the lines of davidjhill’s post, the wording of these announcements continues to contain deliberately slippery language.
Putting aside the interminably long process, if this was a straight forward situation, the announcement could, would or should simply say the board has received a non-binding indicative offer of x pence in cash, plus dividends of x pence etc. But it doesn’t. It adds an extra caveat of an indicative non-binding proposal…..regarding a “possible” all-cash offer….
Why put the extra word “possible” in there? It’s either a cash offer or it isn’t.
I still think the final offer will not be cash. I expect it will instead be new shares in some obscure holding company in some private equity friendly jurisdiction (e.g. Guernsey or Jersey) where accounts are not published and you’ll never know what value the offer truly represents. Shareholders doubtful that 135p is fair value will be told they can continue to share in the future upside by rolling into the new holding company. Institutional shareholders may or may not like it but as a minority shareholder in an unlisted entity there’d be plenty not to like for small retail shareholders.
The situation is a sham on lots of levels in my view.
Does anyone have any idea at which point in the budget the possible notes around AIM tax exemptions could be brought up? Like many I want to be on the buzzer in order to respond with dry powder if it looks like it's not being removed. But I also recognise that waiting until the budget speech has finished might mean some meaningful gains have already been lost. Any thoughts much appreciated this is not an area of expertise for me!
I shall be missing the budget today as I will be sat on a plane on the way to the Canaries. I however feel that this might not be a bad thing. It will remove any temptation to start day-trading and make a hash of things.
I will though be carefully poring over the numbers tonight before deciding what to do. Having looked at all of the ideas posted across the last few weeks there are certainly some potential opportunities out there, but I shall simply be using this opportunity to top up on some of my holdings - I already have enough and don't want to add any more.
The main question I need to answer will be; "have any recent price-drops been overdone, and the core business is still a quality business with good future prospects and now is the time to take advantage of any short-term pricing misalignments. Are any of todays decisions likely to impact the business model adversely in the long-term". Therefore my main areas of focus will be;
Ramsdens Holdings (LON:RFX)
Intercede (LON:IGP)
Niox (LON:NIOX)
Beeks Financial Cloud (LON:BKS)
Eurocell (LON:ECEL)
Mortgage Advice Bureau (Holdings) (LON:MAB1)
If I miss out by being slow, so be it - I am still a holder and any price-increase will be gratefully received.
Wish I was on a plane to the Canaries. Great shout and great post. We should all take a breath and see what’s comes out of the budget speech.
I agree. Maybe best to let dust settle, whatever the news?!
I shall be in the office, glancing at stocko whilst I'm supposed to be working!
One way plane ticket?
Good luck today everyone. 10% swings incoming! Hold on to the reins!!
Good luck today everyone. 10% swings incoming! Hold on to the reins!!
I will be going out for a long walk with a nice pub lunch and phone switched to airplane mode. I will return late afternoon and take stock and reflect on the way forwards. I don’t think there’s anything to be gained by acting in haste unless you’re a trader.
Good advice simoan - By the historically accepted (?) version of the phrase - as a working person, I shall be earning my month end sort of cheque and ignoring my investments today, safe in the knowledge that they will enable me to fund any living cost difficulties
Often the case, agreed. However, sometimes initial seller-driven mark-downs overshoot and you only get the best pricing within limit order on the way down. Let's see
Personally, I'm somewhat conflicted.
My parents have a large AIM portfolio largely driven by IHT mitigation, and that planning will be impacted or even wrecked if today goes the wrong way.
Simultaneously, I'll be a buyer on value-opportunity grounds.
I feel like I'm waiting for exam results or similar. However, my gut instinct is that even if BRP is removed immediately the impacts won't be as bad as worst predictions (initial mark-down by 25-30%).
Let's see and hope.
Could be argued that a lot of shares have already had a 25% mark down over the last month or so so seems unlikely it will stretch to 50%. You never know though...
Agreed Kouremenous, a lot of the bad news is already in prices.
That said, I'm intrigued that there remain a few AIM stocks not too far off their 2024 peaks - Time Finance (LON:TIME) being one of mine.
I've created a raft of limit buy order at the minus 20-25% level, and this often catches things lower still when they fall rapidly. Let's see, but after the initial panic/despair of a bad outcome this afternoon, I'll then hold back and see how the dust settles.
I'm currently 10% liquid which is unusually high for me and the risk is that if AIM BRP remains fully intact I expect a buyers' panic which is equally bad for those in cash.
"AIM BRP remains fully intact I expect a buyers' panic"
Sounds great Jayman :-)
Let's hope for the best! Good luck and enjoy the ride everyone.