Small Cap Value Report (Weds 4 Nov 2020) - MTO, STVG, WIL, GATC

Good morning, it's Paul here with the SCVR for Weds.
Timings - most of today's report is done (at 13:48), but I need to take a break for lunch now. I'll finish off the 2 last sections later this afternoon, which should only be quite short, as neither STOB nor WIL look particularly interesting!
Update at 16:14 - I've decided to abandon STOB, it's just too complicated, and I've done enough work for one day. Therefore today's report is now finished.
I finished off yesterday's SCVR quite late yesterday, so here is the link, in case you missed the new sections. Companies covered were:
ACRL, VCP, TCM, UPGS, WHR, OMG
.
US Election - Exciting news overnight, that the US Election is tight, with the betting odds having switched around, with Trump now the favourite. We're only interested in shares here, there are plenty of other places to discuss the politics. So as regards my shares portfolio, I really cannot see any reason to make any changes, or that the election result would make much difference to my portfolio at all. Hence I've not made any changes to my shares portfolio. It is an uncertainty factor though, so we could see a market bounce once the result is known, as people put money back to work in UK small caps, maybe?
EDIT: Note that the betting odds have now switched back again, with Biden in the lead (at 11:59). I only mention this because the volatility in the betting markets has given us a rough idea of how the futures markets are likely to react to the outcome, and the answer seems to be: very little. A few single digit percentage points on the main indices, nothing more than that, is what I've observed in recent days. That's reassuring, as I think it means we don't have to particularly worry about the outcome re our shares. Nothing like the massive gyrations we saw in 2016 anyway, it would seem. End of Edit.
Covid testing - I feel the outlook re covid is now getting to the point where we can start to anticipate the benefit on share prices of mass testing, which in my view is probably more important than a vaccine in getting control of the situation. So I'll be looking to increase my positions in the best recovery situations for 2021. Markets are supposed to be forward-looking by about 6 months, hence we're overdue another rally in bombed out sectors that have been damaged by covid, in my opinion.
Agenda - these trading updates/results have caught my eye today;
Marks And Spencer (LON:MKS) - looks much better than I was expecting, for 26 weeks to 26 Sept 2020. I probably won’t do a section on it in this report, but just wanted to flag that it’s worth a look, having just skimmed through the announcement
Mitie (LON:MTO) - H1 trading update (Done)
Stv (LON:STVG) - Trading statement (Done)
Stobart (LON:STOB) - Interim results (Sorry, I've abandoned this one, as it's complicated & I'm tired, having spent all day on the other companies)
Wilmington (LON:WIL) - Trading statement (Done)
Gattaca (LON:GATC) - Results FY 07/2020 (Done)
.
Gattaca (LON:GATC)
Share price: 62.5p (up 42% at 09:16)
No. shares: 32.3m
Market cap: £20.2m
Preliminary results for year ended 31 July 2020
I normally start off with the small caps, and work my way down to the micro caps. However, this share has moved up 42% this morning, so I’ll prioritise it, as there might be a buying opportunity here, possibly?
I was completely avoiding the recruitment/staffing sector, but recently heard some interesting comments on a Cloudcall (LON:CALL) (I hold) webinar. Although the comments pertained to the USA, it could still be relevant. The head of Bullhorn (a big partner to CloudCall, which sells software to the recruitment sector) was saying that recruiters are generally the first into, and the first out of recessions. He said the sector was coming alive again. Also, that unemployment may be rising, but it’s concentrated in relatively unskilled people, whilst white collar and more skilled staff had not been impacted much by covid/lockdown (outside of the obvious bad sectors like travel, hospitality, retail, etc). In fact, wages were having to rise, to coax people out of their homes, and there are many skills gaps, meaning that a lot of sectors are struggling to recruit people with the right skills & experience they need. Hence a potentially good & recovering market for recruitment companies.
For this reason, I’m thinking about possibly dipping my toe into the water with a smallish initial purchase of a recruitment/staffing business in the UK, but which one, is the question?
Well done to anyone who spotted the Gattaca results and bought first thing. The market cap (still) looks cheap, in my view.
Key points for FY 07/2020 -
- NFI (revenues, once pass-through contractor wages are removed): £54.3m (down 21% on LY)
- Underlying profit before tax (continuing ops): £4.6m (down 61%)
- Underlying EPS 10.3p (down 64%) - giving a PER of 6.1 - looks cheap, and that’s before we factor in an economic recovery and possibly higher future EPS
- Net cash of £27.3m - a staggering improvement on previously £24.8m net debt! This has mainly occurred due to a large reduction in the receivables book. Remember that staffing companies are cash generative in recessions, as receivables turn into cash
- Cash has also temporarily benefitted from £10.3m tax deferrals - remember this will unwind by March 2021
- RCF bank facility paid off in Oct 2020, so now covenant-free - a very good development which de-risks this investment considerably
- Balance sheet looks OK to me. NTAV of £27.0m is quite decent actually, below the market cap
- No divis for now, but want to reinstate them. I think the group should be in a position to pay divis again in 2021
- Outlook - encouraging signs, but mgt is cautious about outlook, given uncertainties.
- Cost savings achieved, with another £4m p.a. due from Nov 2020 - that could strongly boost profits in future
- Leases - work from home means that leases could now be seen as a nuisance, but amounts are not excessive
- Dept of Justice (DoJ) legal case worries me - substantial legal costs in last 2 years - what potential liabilities could this incur? An important issue that needs to be properly researched.
.
My opinion - this looks very interesting, and still seems cheap, even after this morning’s 42% rise. Therefore, I think readers might want to take a closer look at this. I’ve got to move on to other stuff now.
As always, please remember that I'm only giving a quick view here on things. They're not recommendations, they're just my initial impressions of announcements. Its vital that readers do your own, more in depth research, as there could be things I've missed due to the time pressure I have to work under here, to cover 5-10 companies every day.
Interestingly, GATC crops up on a Benjamin Graham NCAV bargains stock screen. Looking at other companies which are picked up by that screen includes some housebuilders: Redrow (LON:RDW) , Crest Nicholson Holdings (LON:CRST) , and Cairn Homes (LON:CRN) - that is another sector I’ve been meaning to look at for potential bargain/recovery situations.
This screen is worth a look, although apparent bargains in a deep value screen like this, can often have something seriously wrong with them! (value traps), so extra careful research is needed, these should be treated as special situations (the smaller ones anyway);
.
Mitie (LON:MTO)
Share price: 28.85p (up 6% at 10:58)
No. shares: 1,171.0m
Market cap: £337.8m
I haven’t looked at Mitie for 4 years, because its market cap got too big, but has now come back down again into the small caps area.
Scanning through the RNS, it did a highly dilutive rights issue in the summer;
11 for 5 rights issue of 805,069,771 New Shares at 25 pence per New Share announced on 25 June 2020
This raised £201m in gross proceeds, and was linked to an extension of the £250m bank facility (RCF) to Dec 2022. Covenant waivers from the bank, and loan note holders were secured as part of the fundraising.
£80m of the fresh equity is being used towards part of the acquisition cost of the facilities management division of Interserve.
Acquisition of Interserve fm div is a big deal - involving the issue of c.358m additional shares (as part consideration, but see below this figure has been renegotiated in Mitie's favour), and £120m in cash. This will bolt on £1.37bn revenues, and £42m EBITDA. Thus considerably increasing the scale of the combined business.
Balance sheet - I recall Mitie has a weak balance sheet, so have checked it out. NAV was £80.5m at 31 March 2020. Take off goodwill/intangibles of £329.5m, and we get NTAV of negative £(249.0)m - rather grim. This will have improved since the recent rights issue though.
Note the £74.0m actuarial pension deficit (as at 31 Mar 2017, an updated triennial valuation is pending), with Mitie committed to paying £55.4m in recovery payments to 31 March 2025, so a significant drain on cashflow.
OK, that’s the background so on to today’s update -
Mitie Group plc: H1 FY20/21 trading update
Much improved second quarter performance
Trading has continued to be more resilient than expected. Second quarter revenue was up 12% on the first quarter, with monthly sequential improvements in sales particularly across Cleaning, Security and fixed Technical Services contracts.
Our public sector contracts have shown good resilience during this challenging period and we have also seen strong performances from our food retail, online retail, healthcare and pharmaceuticals customers. However, demand from our property and finance & professional services clients remained weak, although the second quarter was somewhat better than the first quarter as office space reopened.
Group revenue from continuing operations for the second quarter was £514m versus £458m in the first quarter of FY20/21. For the six months ended 30 September 2020 revenue from continuing operations was £972m, which was 9.8% lower than the same period in the prior year. This revenue decline includes 3.8ppts from the known loss of the MOJ contract and the reduced scope of the NHS Properties contract.
Business services seem to be quite resilient, because new business is being won for increased cleaning, related to covid.
Technical services has suffered a 22% fall in H1 revenues, due to it being more project, and discretionary services for clients.
All the above is very interesting, but it doesn't tell us anything about what really matters - profitability!
Net debt - quite a few moving parts in here, particularly large tax deferral. I’m not sure whether the Interserve cash acquisition monies have been paid out yet or not? Which is a material amount.
For the six months to 30 September 2020 average daily net debt on a post IFRS16 basis was £69.3m (£351m for the six months to 30 September 2019). During this period we received £191.8m from the net proceeds of the Rights Issue and benefitted by £130.3m from the HMRC 'Time to Pay' tax deferral scheme.
Excluding the benefit of both the Rights Issue proceeds and the Time to Pay benefit, our underlying average daily net debt would be at a comparable level of £253m, with the c. £100m improvement in the period a result of better working capital management and the net proceeds from M&A.
*Note: Adoption of IFRS 16 has added c. £90m of additional lease liabilities to net debt.
Why are they quoting net debt including lease liabilities? Strikes me as an own goal.
No guidance, and no dividends.
Revised terms for Interserve acquisition - there’s a rather good RNS out separately today, which indicates Mitie has negotiated better terms for the acquisition;
"However, Mitie, in particular, has been successful at renewing strategic contracts and winning new business during this period. Recognising this momentum, we have renegotiated the terms of the Interserve Facilities Management transaction, reducing the vendor's consideration shares by 31% (110 million shares) to 248m shares (17.5% of the Enlarged Group), valuing the current consideration at £190m. [2] Mitie's existing shareholders will therefore hold a greater proportion (82.5%) of the Enlarged Group and enjoy a greater share of the benefits of the transaction.
That looks quite a coup by Mitie. Its share price has crashed in recent months, therefore I would have expected the Interserve deal to be renegotiated so that the vendor receives more Mitie shares, because they are worth so much less now. To twist their arms into accepting considerably fewer shares, is impressive negotiation!
My opinion - it would take me all day to properly dig into all the detail here, as this is quite a big, and complicated, business. Hence I’ve got to say I’m neutral on a rational basis, having only scratched the surface of it above.
However, as a punt, I think this looks interesting, and think I’ll pick up a little scrap of shares for my punting spread bet account.
The worry is that work might dry up over time, as offices close and get converted into residential, due to covid. But personally, I don’t think that’s such a big threat. Work from home clearly works quite well, but as covid hopefully disappears in 2021, then I reckon more & more companies are likely to want people back in the office, at least some of the time. Hence demand for office services provided by Mitie, could continue. Who can say, it’s unknown at this stage. Hence why I think this share can only really be seen as a punt. Not a bad one though, given the balance sheet partial repair earlier this year, and a big acquisition at what might turn out to be a fire sale price perhaps?
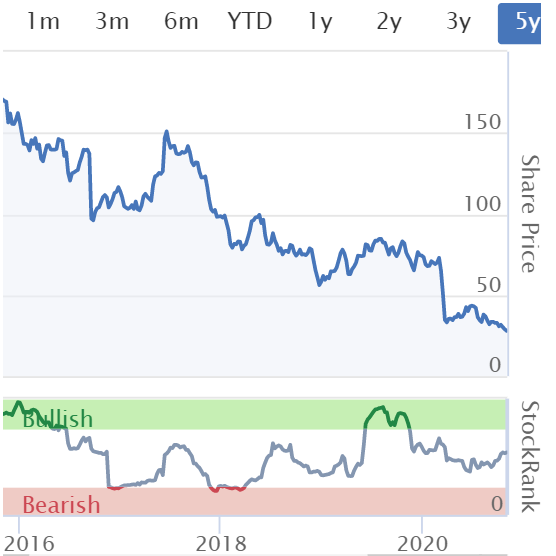
A dismal 5-year chart below, but remember that the heavily discounted 25p rights issue has reset the bar. Most shareholders will have paid 25p for most of their existing shares, in the rights issue. Therefore a recovery in the share price to say 50p, would generate a substantial profit for shareholders, equivalent to a much higher share price before the rights issue. Therefore the chart doesn't always tell the full picture, where there's been a large issue of new shares, like here.
Let's illustrate this with some numbers. Say you bought 10,000 Mitie shares in early 2018 at 100p per share, so a cost of £10k.
Your rights issue entitlement of 11 for 5 new shares would be 22,000 new shares at 25p each, costing £5,500.
You now have 32,000 shares in total, total cost £15,500. That's 48.4p average cost price.
So to breakeven on your investment, you don't need the share price to recover back to the 100p original purchase price, you only need it to recover to 48.4p, at which point the profit on the rights issue shares equals the loss on the original 100p shares.
.
.
Stv (LON:STVG)
Share price: 260p (down c.1% at 13:11)
No. shares: 46.24m
Market cap: £120.2m
This is another share which I haven’t looked at for about 4 years, so it’s taken me ages to re-familiarise myself with things, having to go through the last interim figures.
Pension scheme - by far the most important issue with this company, is the defined benefit pension scheme, which is massive. On an accounting basis (which is often under-stated compared with the actuarial basis, which drives deficit recovery payments), the scheme assets were (at 30 June 2020) £402.9m, and scheme liabilities were £479.8m.
Deficit recovery payments in H1 this year were £3.0m, but this seems to benefited from deferral of the Q2 payment until Dec 2020. Last year in H1 alone the deficit recovery payment was £4.5m.
In 2019, the full year deficit recovery payments totalled £10.3m. Huge numbers. STVG somehow managed to pay divis as well, in the past, but those seem to have stopped. They insulted the intelligence of shareholders by paying a meaningless 3p dividend in bonus shares this year. Since everyone gets bonus shares then nobody is any better off, and the share price just drops to offset the increased share count. Pointless!
All of the above is rather a pity, as the pension deficit problems are likely to linger for many years, and could get worse, as it looks like we’re in a permanently low interest rates environment - which inflates pension scheme liabilities. For me, the huge scale of the pension schemes, mean that this share is uninvestable for me. Which is a pity, because the company seems to be trading fairly well in the circumstances, and got through, and is recovering from covid, pretty well.
Interim results to 30 June 2020 showed that STVG remained profitable, although obviously down on 2019.
Exceptional charge of £8.7m being a receivables write-off called ELM, which looks like a sale of STVG’s lottery business, which appears to have fallen through?
Last reported NAV was negative, at £(63.0)m, reflecting the large pension deficit.
A placing this summer will have improved that 30 June 2020 balance sheet position, by about £15m (assuming costs of c.£1m), This placing at 230p happened after the half year end, and triggered a £20m extension in bank facilities.
Ad revenues were recovering strongly in July & August, and audiences have been good.
Today’s update -
Excellent viewing performance continues; advertising recovery ahead of expectations; short-term outlook still uncertain due to Covid-19
Ad revenues are now running only slightly below LY, which is good.
Viewer stats also sound good. The death of TV seems to have been greatly exaggerated!
Record viewing growth on TV and online continues
Outlook comments sound upbeat, but unless I missed it, I can’t find any financial guidance in today’s update;
Despite the ongoing challenges around Covid-19, I'm encouraged that the advertising market has recovered strongly across the summer and autumn, demonstrating the enduring power of television and our ability to come through further uncertainty with confidence. In particular, STV-controlled Scottish advertising and digital advertising have returned to year on year growth during the autumn, fuelled by our Growth Fund and the excellent performance of our streaming service STV Player.
We remain confident in our prospects for growth, and look forward to finishing the year strongly on screen with November traditionally our biggest month of the year thanks to the return of I'm a Celebrity; while in STV Studios our 14 new commissions so far this year means that 2021 promises to be our most successful year yet."
My opinion - this is all academic, because it doesn’t really matter to me whether the business is doing well or not. That’s because the vast pension scheme is a deal-breaker for me.
If interest rates were set to rise, then pension deficits would melt away. Trouble is, the opposite is happening in many cases deficits are rising.
As there is such material doubt over what the future holds, I really don’t want to get ensnared in anything where the pension scheme swallows up much, or even most, of the long term cashflows.
I wonder if some of the people buying on the recent bounce, may not have been aware of the huge pension deficit, or not realised its significance perhaps? Or alternatively, maybe investors might be hoping that the Govt could be persuaded to allow pension schemes to value liabilities on a reduced basis, thus requiring reduced cash contributions? I seem to recall a Scandinavian country did that a while ago, Sweden perhaps?
.
I'm taking a break now, will be back later.
Since it’s the last day before lockdown 2.0 kicks in, I’ve decided to support my new favourite local in N1, The De Beauvoir Arms, and help put a bit of money in the till before they have to close again. I did plan to print off some copies of the lyrics to “We’ll Meet Again”, hand them out to everyone in the pub, and have a jolly good, albeit tearful, sing-song just before closing time tonight, but my friends all said that was completely over-the-top, even by my standards, and definitely not to do it. Aren’t people awfully reserved? It’s like when a gameshow contestant refuses to do their party piece on camera, for our amusement. It’s just disappointing. I’m all for a bit of Latin style exuberance.
Actually, it’s not really lockdown 2.0 is it? Many/most businesses will just carry on as normal this time, and people have found workarounds in other areas. I was talking to a barber/hairdresser yesterday, and probed about how they had managed during lockdown, with the shop closed. He told me that many people had made private arrangements via social media, and hairdressing continued largely unhindered, but by private appointments in people’s houses.
I also noticed yesterday, that on many busy buses in London, passing by, plenty of people were completely ignoring the requirement to wear masks, and nobody was enforcing the rules. Anyway, back to shares, I’d better speed this up, or pint number 3 which is pending, might impair my impartiality, (and ability to type).
.
Wilmington (LON:WIL)
Share price: 128.6p (down c.1%)
No. shares: 87.56m
Market cap: £112.6m
I don’t know what’s going on today, but this is another share that I’ve not looked at for years, here are my notes from Feb 2014, for what it’s worth - I didn’t like the balance sheet, and see the share price has halved since then (although WIL has been generous with divis).
Wilmington plc, the provider of data, information, education and networking services in Risk & Compliance, Healthcare and Professional knowledge areas today announces an update on trading for the three months to 30 September 2020.
This is Q1, of FY 06/2021.
It sounds quite positive;
The Board is pleased to announce that financial results for the quarter have been encouraging and were ahead of management's previous expectations. Adjusted PBT was ahead of the corresponding period in the last financial year despite revenue being down around 6% on an underlying basis at constant currency due to the inability of the Group to run face-to-face training and events in the period.
This sounds like the type of business which could benefit from lockdown & Zoom/Teams, etc, moving to doing things online which they confirm today;
The Group's Preliminary Results announced on 17 September 2020 demonstrated the extent to which the digital transformation of face-to-face events and training to virtual formats had been successful. The speed with which this transformation was delivered helped to mitigate a significant element of the potential first quarter revenue impact from Covid-19.
Decisive action to reduce costs has also continued - the savings in direct costs as a result of this transition were augmented by an overhead reduction exercise that was undertaken over the summer resulting in the improved year-on-year profitability.
Each of the Group's three divisions has seen trading ahead of internal expectations. Notable performances were seen in our core subscription-led data businesses, which make up around 50% of Group revenues and which have continued to hold up well during the pandemic.
Debt is still quite significant, albeit reduced, and it seems with plenty of headroom;
Cashflow in the quarter was also better than previously expected with net debt as at 30 September 2020 of £28.0m (30 September 2019: £41.2m). In October, to secure its headroom, the Group extended by twelve months the term on its existing £65.0m revolving credit facility by exercising the pre-existing option that it had to do so. The facility will now expire on 3 July 2024.
Outlook - I’ll reproduce this in full, as it’s interesting, and has potential read-across for other companies -
Following the strong first quarter trading performance the Group is on track to at least achieve the expectations for the half year that it set out in the Preliminary Results announcement on 17 September 2020. This is for revenue and profit in the first half to be in line with that achieved in the second half of the year to 30 June 2020.
Predictions for second half performance remain difficult at this current time due to the uncertainty over the extent to which the Group will be able to run face-to-face events in that period. Recent lockdowns and developments globally in the spread of Covid-19 are likely to delay the resumption of face-to-face activities and it is not possible to say at this stage when that resumption will be. The Group is currently in active discussions with customers over its key H2 events such as RISE National and is considering all alternatives around format and timing.
In the Preliminary Results announcement we set out a range of potential outcomes for H2 depending on whether or not we could run face-to-face events and training. Recent trading experience leads us to believe that a fully virtual H2 would deliver better revenue and profitability than we guided to at that time as the lower end of the potential range. So whilst the chances of that scenario occurring have increased in recent weeks as the pandemic has developed, we feel increasingly confident in our ability to mitigate some of the associated financial effects of that potential outcome.
My opinion - I know little about this company, but have to say this update today has piqued my interest. One of my main investing themes at the moment, is to look for companies that are successfully migrating online. I think companies which move fast in this way, and establish dominance, could be the big winners of the future, in whatever niche they operate in.
Wilmington sounds as if it’s embracing moves online, whilst keeping its options open about resuming face-to-face activities. Whether people are WFH, or WFP (working from pub) as I am at the moment, it’s obvious that previously face-to-face events could be done much more economically online, if they’re done well.
Overall then, this share might be worth a closer look. Over to you!
.
I'm calling it a day here, sorry but STOB interims look complicated, and I'm tired now.
See you in the morning!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

55 comments
Gattaca (LON:GATC) - doing some research on it and found this - I dont hold
https://research.equitydevelop...
With regards to Pauls comment about the recruitment/staffing sector, I have been tracking SThree (LON:STEM) for the last 3 weeks since it joined my screen process (basically Jim Slater with strong Stockranks and Stockrank Style added.
Shares magazine did a buy recommendation on it back in Jan (price then was 365, 256 today) and highlighted it has a presence in Europe and the US, though a recent news artilce said it was pulling out of Australia, so certainly not just UK based. Hardly moved above its march drop, but if we are coming out of this recession, is this small cap due a revaluation?
Anyone else had any experience of owning SThree (LON:STEM), but probably going to pull the trigger tomorrow.
Hi GloucesterBob, I bought SThree back in early 2019. The shares went sideways during the time I held them. When I joined Stocko in September last year the metrics were poor in my opinion and so I sold them for a very small gain. Looking at the Stocko graph, SThree has been going sideways since 2010. Its only my opinion but if SThree has mainly gone sideways for 10 years since the last recession, what suggests they will rise following this latest (and worse) recession??
Hey, Im new round here - and new to this game - so forgive the potentially newbie question. But should I be able to see, within Stockopedia, the info you mention about the pension scheme / deficit at STV? I feel like this is a big issue that I'd have potentially missed, so just want to know where I should be looking when it comes to assessing other companies. Thanks!
There is no substitute for my forensic analysis of balance sheet issues. It's the USP of the Small Cap Value Reports.
Proper research is needed, partly because the accounts don't always show the problems in full, you have to delve into the Annual Reports, etc.
This year's covid/lockdown has shown the importance of balance sheet strength to us all.
Hi gwilli68,
You can find some of the pensions information in the StockReport - if you go into the balance sheet section under "other liabities, total" you will find the pension deficit. (£64m at the last year end for STV (LON:STVG) )
However this only gives you part of the story, if you want to know the full detail, you need to go the the Report and Accounts. For STV you will find the latest here.
Just search the document for the word "pension" - there are 69 instances in the STV R&A (not unusal) so in fact it is best to search from the end of the document - as that is where you'll find the important info.
For STV it is in note 26 to the Accounts "Retirement benefit schemes" Page 102 (but page 106 of the pdf - why cannot companies understand PDF page numbering?)
Scheme Liabilities of £445.9m vs assets of £381.9m given the deficit mentioned above. There is actually though a tax asset on this deficit of £10.9m so net of this the deficit is £53.1m
Of second order interest, you can see various details of the assumptions and how the pension scheme funds are deployed.
You can also see here how much the company is paying into the scheme. (Last year £11.6m made up of £1.6m operating expenses and £10 deficit reduction plan).
Edit : Actually this last point does not quite stack up, the P&L & CashFlow statements shod £2.0m of pension management costs and £10.3m of deficit reduction payments. I'm not totally sure on the difference there, but maybe it relates to the tax impacts?
The presentation may differ from company to company, but you should always be able to find this information in the notes to accounts for any company with a Defined Benefits pension scheme.
Tks Grom, vv thorough
Thank you! Really appreciate the thorough reply.
The lazy way is c and p for u from Stv (LON:STVG) - its on the RHS of the page around the middle - see what it states Pension
Listening to CNBC and others today they appear to be interpreting the election result as a decisive vote against a new lockdown. This could be good for those businesses who would benefit most from this like hotels and airlines. I wonder if this will have an impact over here, particularly with the reports that the 'r' rate may be coming down rather than going up and the lack of appetite in the Conservative Party for a prolonged lockdown. Just a thought. (I bought Marriot and SouthWest Airlines).
Hi kbg1953 - Re our American Cousins but slightly off topic
Today’s situation reminds me of a short sketch from Not the Nine O’clock News (10-11-1980 S3E3 for those pedants amongst you and about 8 minutes in - it's on youknowwhotube)
Scene – Men sitting around a large conference table – Room labelled TUC Head Office
Chairman – “Right before we get on to any other business I think we have earned a Tea break, Tea or Coffee? - Let's vote, those in favour of Tea”.
(ALL hands in the room raised part from Chairman)
Chairman – “I make that 1.5 Million votes for Tea, Right those in favour of coffee”
(Raises his own hand)
Chairman – That’s 5 million votes for Coffee, motion carried Coffee it is”
Accepting that this is strictly off piste for the SCVR, sadly I am old enough to remember it well. However, I'm not sure the TUC, or any UK political leader (well Farage maybe!), ever advocated not counting votes in a democratic ballot claiming that they had already won. Well at least not since the days of the 1832 Great Reform Act which abolished the 'rotten boroughs'! If Trump wins this time round could we see him adopt the approach seen in the Ivory Coast Election. Extracts from the BBC web site:
Ivory Coast's President Alassane Ouattara has won a controversial third term in office in an election boycotted by the opposition.
He took 94% of the vote, even winning 99% in some of his strongholds....According to the constitution, Ivory Coast has a two-term presidential limit. Mr Ouattara - who has been elected twice - initially said he would stand down....His supporters argued that a constitutional change in 2016 reset the clock and that his first term did not count.
Sounds like the ideal playbook for Trump overturning the US constitution, and if he wins this time round, seeking a third term! What that will do for markets through to 2028 I have no idea!
I'm not sure why you got voted down for that - it seems a reasonable summary of the mood to me. Of course the virus doesn't care what way anyone votes and will continue to have an impact while we spread it.
Air Partner (LON:AIR) (I hold)
An update on their Private Jet offering was published yesterday:
https://www.theguardian.com/bu...
I had no idea the company "supplies planes to Premier League footballers, celebrities, the royal family and six of the eight governments in the G8" but now that I know I'm even more convinced to hold.
Air Partner (LON:AIR) (I hold)
Sorry, another update with an Air Partner source, this time explaining that freight prices are back to their high mid-covid prices.
https://www.lloydsloadinglist....
Hi abtan,
It surprises me that all those idle passenger jets haven't been re-purposed for carrying freight. It can't be that difficult to unscrew all the seats, and carry pallets of cargo instead? Or maybe the cost of converting into a cargo carrier, then back again, wouldn't be economic over a (say) 1 year timeframe?
Air Partner (LON:AIR) is nice, but I think we have to be careful about ascribing much value to temporary factors. We saw that with its last results - they looked fantastic, but it's a one-off, and the underlying business is really quite ordinary. Hence why the share price quickly lost its spike up.
Regards, Paul.
You can unscrew the aircraft seats easily enough, but you won't get pallets through passenger doors.
So you need to fit a new door, strip out all the cabin fixtures, seats, galleys, overhead lockers etc, fill in the windows, and then fit a new high strength floor.
Conversion to freighter use is a one way process to extend the life of a passenger jet at the end of it's life. I expect some of the BA 747's that used to be my favourites may go that route.
Hi John, Re Airfreight
A quick non scientific Mr Google research also tells me Air is 4 to 6 times the cost of Sea
That takes me back to calculating volumetric weights. There's a sweet spot for the weight per cubic metre that works best for each mode of freight - if you don't hit that then they charge by volume or weight, whichever is the higher cost.
The last four paragraphs of the Lloyds List article referenced in Abtan's original post relates specifically to "P2Fs" - passenger to freight. The article is quoting Mike Hill (VP of Air Partner (LON:AIR) in Singapore). It seems that a number of planes were repurposed short-term in Q2 and he is expecting the same upto Christmas.
The weird things you learn while researching shares. I never knew that passenger jets nearly always have some air cargo in the hold on routine flights - it’s normally relatively cheap (compared to proper air freight) and airlines use it mostly for ballast. There actually has been a massive increase in the price of airfreight over the past 7 months because of the passenger routes cancelled.
I remember reading the world gold market was disrupted at the start of the pandemic because it's usually shipped in passenger aircraft holds. They had to get insurances arranged to send it by private flights so maybe Air Partner (LON:AIR) picked up some work there that they can't talk about.
They were even considering allowing "London delivery" to take place in Australia and Canada.
Air Partner (LON:AIR) Is the underlying business quite ordinary? The line of best fit drawn over a graph of normalized eps is going in the right direction at a reasonable pace [1-2p in the mid ’90s, 5-7p recently, while paying a reasonable dividend], although lumpiness is in evidence. Cash has been used to buy related businesses, which may even out the lumpiness and add income. This year there will be enough cash generated to account for at least a quarter (perhaps a half?—there have been no recent updates) of the current market cap, yet this company is trading at c. 10xs the average operating profit over the past couple of years, when the PE range has been 12-18 times.
Air Partner (LON:AIR) benefits from both emergencies (e.g. Ebola, COVID, unrest) and the good times (transporting football teams, orchestras, freight, the wealthy, the impatient, the discreet, etc.).
An enormous amount of freight is transported in the belly of passenger jets; it might be some time before that capacity returns. AIR is building up a substantial cash pile which can be used to buy more income-producing assets and to provide the dividends that help to keep us all cheerful.
I accept that this will not be the next super-compounder, but at a price of 60-some pence, with dividends in the recent past of 5+p, and with the promise of a bumper year or two, it isn’t a bad place to put some money.
Disclosure: I own some.
Air Partner (LON:AIR) issued a flurry of very positive updates in the early summer which drove the price up and straight into a placing - which explains a substantial part of the substantial cash pile.
Its acquisitions of the last few years can hardly be deemed that successful. I hold some too, but nervously.
Exactly - Air Partner (LON:AIR) did a placing because its NTAV was negative. The cash belongs to other people, and its balance sheet is actually (still) quite weak. See the archive here. Not a bad business, but nowhere near as good as bulls imagine.
Air Partner (LON:AIR)
Hi Paul,
I agree regarding the need to be wary of one-off bumper years.
After accounting for this it comes down to:
1 - it will definitely survive. It has so much cash and looks like it will have at the very least a decent H2 based on those articles I shared today, which show that 2 of the 4 divisions are in a sweet spot right now (Private Jet + Freight).
I'm expecting all divisions to be profitable in H2.
2 - I believe things will return to "normal" for the company. Disasters will still happen, lots of events are taking place in 2021 and 2022, the world will start returning to its old self (can you imagine people/goods still not travelling/moving around in 3-5 years?)
3 - the share price when everything kicked off was c100p vs 65p we see today. Since then the company has made serious cash, done a fund raise, and has the ability to invest some of its cash so that when "normality" returns it should in theory be making even more money than before (when I thought 100p was too cheap - NB: I held then and I hold now). Then of course there's the stonking dividend yield, which, when it is reinstated, is c.9% at the current price.
Based on all the above, I'm a happy holder for now.
A
Re: Air Partner (LON:AIR) (I also hold) - I think people started taking notice of this when the CEO spoke on Radio 4's Today programme on Tuesday last week : https://www.youtube.com/watch?v=6g1lUTCfprg
Medica (LON:MGP) (I hold)
In case anyone missed it, there was a trading update at the end of today's acquisition announcement.
https://www.stockopedia.com/po...
Thanks! Missed that. I think there should be clear protocols on the top of announcements, to say if it contains a trading update.
As it happens it says that trading is "in line". Should be at the top of the announcement!
Looks like there's a big overhang in Medica at the moment. Been slowly drifting downwards. Thought it was bad trading / profit warning coming. But this in-line trading update should have seen it recover to 120p, or more. Especially with a promising acquisition. Indeed the early trading was 10% up at 110p, but then drifted back down again even as the market went up today.
Both Aberfoth and Gresham House have increased stakes in Medica (LON:MGP) recently too.
With the top 4-5 holders now over 50% of total shares, it won't take much for Private Equity or other buyer to get Medica at a small-medium premium, for what should be quite a defensive business churning out good free cash flow.
(I hold).
Medica (LON:MGP)
I remain a fan of the company (hence my holding) and continue to believe it is significantly undervalued.
This year's performance is satisfactory, and one would hope the growth continues from next year again with even greater cash generation than in FY19 (£8.5m).
Like you, I'm surprised the price hasn't recovered more in the latter half of this year, and even after today's announcement, but I'm happy to wait until it does.
Cheers
A
Medica (LON:MGP)
I remain a fan of the company (hence my holding) and continue to believe it is significantly undervalued.
Agreed.
If we think about this in a slightly wider context companies in this space ought to be seeing a couple of tailwinds in 2021. Firstly, they've seen a reduced market this year as lots of healthcare provision has been pushed back to deal with CV19. The demand hasn't gone away and one of the clear aims of lockdown #2 is to ensure that the NHS can continue with business as usual.
Secondly, it's really hard to believe that public healthcare won't be a recipient of increased funding going forward - and part of that will be about the increasingly efficient use of medical technology. Taken all in all you have a sector where the earnings have been artificially and temporarily depressed but which is likely to see increased levels of investment going forward if you can look though the immediate challenges.
I think this looks like a safer way of playing the post-CV19 recovery - whenever it comes - than trying to figure out what will survive in the retail, leisure and travel sectors, where future demand is uncertain anyway.
timarr
Proactis Holdings (LON:PHD) FY20 results presentation by Tim Sykes, CEO & Richard Hughes, CFO, given last week on announcement of results. Video or podcast.
Covers strategy, bePayd, TCV & ARR performance, financials & outlook.
c. 30 mins
Hi Tamzin,
I do think Proactis Holdings (LON:PHD) are very much glossing over the reality that the business doesn't generate any free cashflow at all, and is swimming in debt. Very high risk.
Regards, Paul.
Paul, Just had look Tekmar (LON:TGP) is down approx 50% since your recent (goodish) review - I think it looks bargain now. Perhaps you could update us folk. PS Anybody else have views on this ?
Hi Voodoobar,
I don't understand your post. When Paul reviewed Tekmar (LON:TGP) the SP was 42.5p. Since then it has risen not fallen 50% as you say (it was down 41% when he wrote the post).
cheers
Francis
I think Voodoorar must have been referring to Paul's original review (aug 3) when the shares were up at 110p. Fwyburd refers to the follow up, after the savage fall following what appears to be a fairly mild PW - and where I was one of those buying!
Hi voodoobar,
You obviously missed my recent comments on Tekmar (LON:TGP) here on 30 Oct 2020;
https://www.stockopedia.com/co...
For future reference, you can check for my (and others) comments on any company, by looking up its StockReport, then clicking on "Discussions". That should bring up all my commentary on the company, over the last 6-7 years.
Regards, Paul.
Paul
I use the old site and unfortunately quite often when clicking the "Discussions" heading your more recent comments are no longer there. Now to access them I resort to checking the date of the most recent trading pr results update and then go to the SCVR for that date to find your comments.
A general observation that stems from Paul's comments about Oxford Metrics yesterday:
"It looks a long way short of the forecasts shown by Thomson Reuters, but with only 2 brokers reporting, it could include an out of date number perhaps? So I’m going to ignore that".
I have pointed out to Stocko before that their forecast feed never changes the figures when forecasts are suspended - placed "under review". Sometimes it is obvious as in this case where the market didn't react to results being way out from forecasts or in such cases as Eddie Stobart Logistics (LON:ESL) which show a forward p/e of 0.55 and yield 92%.
More difficult is where it is not so obvious - although a forecast with no changes for a long period can be a clue. Hence I never trust the Stocko figures until I have checked elsewhere. I use Sharecast (ex WebFG ex DigitalLook) but that is not without faults (although it did get Oxford Metrics (LON:OMG) right https://www.sharecast.com/equity/Oxford_Metrics).
Sites giving free consensus are thinning out - does anyone know of others?
Hi All,
Here's today's SCVR heat map (prices as at 10:15am):
The above heat map is filtered to names that are 'interesting' (to me... meaning reporting, trending, breaking out, moving beyond 20d EMA of ATR)
This one is unfiltered, but limited to the top 80 items:
Both heat maps are ordered by Stock Rank™, and again, here is a key:
In reply to requests to publish it early, every day, I'm afraid that with parenting / school runs and a full-time day job (not in finance) I cannot commit to contributing to any schedule.
However if others find them useful I'm happy to keep posting on a 'best endeavors' basis.
Take care all.
Greensiax
[edited to add unfiltered heat map and key]
Very useful - where do you get these maps from? Thanks for posting it
Thank you Cleeve,
I generate them myself from my database.
Cheers,
Greensiax
Hi Greensiax, no worries - appreciate the heat maps appearing any time of day when you can :)
Cheers, Forbsy.
Thank you Forsby ;)
I have read various views on the US election outcome and the below article from Joachim Klement CFA seems fairly balanced (for transparency: I have no interest in Joachim business, nor am I receiving any financial gain from this article):
A win for Republicans (but not Trump)
Note: This is the last post until Monday, 9 November 2020 since I need a couple of days off after this madness…
Republicans outperform again
As I write this commentary (8.00am GMT), it is too early to call the election results in the United States. Yet, there are some clear trends emerging by now that allow us to narrow the outcomes down to two to three main scenarios. Being mindful that everything remains in flux, I note the following major trends:
In my view, the three most likely outcomes in descending order of likelihood are currently:
At this point in time, my base case scenario is scenario 1, which would put Washington into continued gridlock and basically a return to the Obama years where the President has to rely mostly on executive orders to force change, but no major laws can be passed. At the end of this post, I will look into the implications for US growth, the US Dollar and stock markets, but first, I show why I think these three scenarios are the most likely outcomes.
Presidential race: Biden likely to win
Before the election, the FiveThirtyEight forecast gave Biden an 89% chance of winning the election. As of the time of writing, including all states and districts that have been called by at least one media outlet, FiveThirtyEight gives Biden an 88% chance of winning, Trump a 6% chance of winning and a 6% chance of a tie. As a reminder, in the case of a tie in the Electoral College, the presidency would be decided by the House of Representatives by state delegation, which would hand the presidency to Trump.
Compared to the opinion polls and projections, Joe Biden is outperforming in Arizona, Minnesota, Wisconsin and Michigan. He is also performing well in Pennsylvania and Georgia.
Donald Trump is outperforming his polls in Florida, Ohio, and North Carolina. However, that is unlikely to be enough to win the Electoral College.
Joe Biden has several ways to win the Presidency: i) winning Arizona, Michigan, and Wisconsin, in which case he does not need either Georgia or Pennsylvania, ii) win Georgia, Wisconsin and Michigan, in which case he would not need Pennsylvania or Arizona (Arizona has already been called by Fox News and the AP for Biden), and iii) win Pennsylvania, Wisconsin and Michigan, in which case he would not need Georgia (where Trump leads by 3 points but the outstanding votes are all in deep blue Atlanta) or Arizona.
Most troubling, Donald Trump falsely claimed that he won Pennsylvania, Michigan, and several other states that he is unlikely to win. To provide some clarification, Biden won Minnesota by 8 points. In 2016, the difference between Minnesota and neighbouring Michigan was a mere 3 points, which indicates that Biden is likely to win Michigan by 5 points or so. This chimes well with the current projections for Michigan, where Trump is currently in the lead by 8 points based on the votes that have been counted. However, the outstanding votes are from Detroit, which so far seems to go 5-to-1 for Biden. Biden needs to win Michigan by about 3-to-1 to 4-to-1 to win the state overall. A similar picture is in place in Wisconsin where Trump is currently ahead by 4 points, but Dane County (Madison) and Milwaukee County are still open and both are deep blue. With Trump leading by a mere 119,000 votes at the moment, Wisconsin may well swing for Biden if the outstanding 211,000 ballots that have to be counted are 3-to-1 for Biden, which seems likely, though it is too close to call.
Trump also threatened to go to the Supreme Court to intervene in the counting of votes and stop the counting of votes in crucial swing states. This is very unlikely to succeed since state laws are very clear on that matter, but the legal actions and false claims by Trump that he won several states he did not win or is unlikely to win serve the purpose of creating uncertainty and doubt about the election outcome, thus further undermining institutions and setting markets up for an extended period of uncertainty.
Senate race: Republicans likely to hold on to majority
Unlike the Presidential race, Republicans are outperforming across the board in Senate races. Before the election, Democrats were projected to be favoured to win the majority in the Senate. For that to happen, they would have to flip four seats while losing their one senate seat in Alabama. As of the time of writing, Democrats have managed to flip a senate seat in Colorado and lost their senate seat in Alabama. Meanwhile, Joni Ernst managed to retain her senate seat in Iowa, which was a must-win for Democrats. The other very close race that Democrats hoped to win was Susan Collins’ seat in Maine. Collins currently leads her senate race by 7 points and remains on course to re-election.
At the moment, the best possible outcome for the Democrats would be a tie in the Senate, which will crucially hinge on the second Senate seat in Georgia where Democrat Raphael Warnock and Republican Kelly Loeffler are on track for a run-off in December. If Democrats manage to win the Presidency and win a tie in the Senate, the Vice President could act as a tie-breaker in the Senate and open up a way out of legislative gridlock. However, in that case the moderate Democrats in the Senate would hold the key to power, blunting any efforts by the left wing of the Democratic Party to push through ambitious projects like a Green New Deal or significant tax hikes.
The most likely outcome, though, remains that the Republicans hold on to a slight majority in the Senate, which would give them the power to block any ambitious legislative agenda originating in the House of Representatives or the White House.
House: Democrats hold on to clear majority
Democrats were highly favoured to retain control of the House of Representatives. It is virtually certain that Democrats will retain control of this chamber, though their majority is likely to decline somewhat, yet not enough to put them into any kind of trouble.
Implications for the US economy and the US Dollar
At the time of writing, the US Dollar Index (DXY) is up 0.6%, up 0.9% vs. Sterling, and up 0.5% vs. the Euro as uncertainty remains high, while 10-year Treasury bond futures are up 1.5%.
In my main case scenario of a Biden Presidency with a Republican Senate, I expect to see a return to the Obama years with the Senate blocking any major legislation by Democrats. This would mean that the President has to rely largely on executive orders to enforce changes in the health care system or to enforce environmental protections. However, a Biden presidency would at least end the threat of erratic trade wars and international relations and while we expect Biden to remain sceptical in his dealings with China, it seems likely that he will try to roll back tariffs implemented against China, which would be good for US consumers.
However, more ambitious goals would likely fail in the well-known gridlock. The Democratic plans to hike corporate taxes would be dead on arrival, which is marginally positive for stocks, but any fiscal stimulus package would likely be smaller than currently expected, as Senate Republicans will try to prevent Democrats from claiming victory on the economic recovery. Thus, in this scenario, the growth prospects for the United States in 2021 diminish somewhat. This, in turn, puts more of the burden to stimulate the economy in the current economic crisis on the Fed and monetary policy, which means that we will likely see even more aggressive QE than currently anticipated. In sum, in such a scenario I would expect the US Dollar to weaken in 2021 under the influence of weaker than expected growth and more aggressive monetary stimulus.
In the case of a Trump presidency and the Senate under Republican control, it would be a continuation of the policies of 2017 to 2019 with the 2018 tax cuts remaining in place but an intensifying trade war with China that frequently rattles stock markets. As Democrats are likely to restrict the manoeuvring space for Senate Republicans in terms of fiscal stimulus measures we should expect a moderate fiscal stimulus package based on a deal between the House of Representatives and the Trump White House as was expected in the past couple of months.
Finally, in the case of a Biden presidency with a tied Senate, Democrats would have the ability to hike corporate taxes and increase the stimulus spending on infrastructure, green technologies and other projects. However, the narrow majority of Democrats in the Senate would thwart any attempts by the party’s left wing for more ambitious projects like an large Green New Deal or the expansion of Medicare to all citizens.
Implications for stocks: Ho-hum
As can be expected in a highly uncertain environment, stock markets declined while the US Dollar and bonds rose. Futures on the Dow Jones Industrial are currently down 1.2%, while futures on the S&P 500 are down 0.6%. Tech stocks reacted positively to this uncertainty with Nasdaq futures up 1.0%.
From a sector perspective, the strength of the Republicans in the Senate mean that regulation for health care stocks and oil & gas will likely be limited. Thus, on the margin, the current situation looks slightly positive for health care and energy. Meanwhile antitrust action against technology companies will likely have less teeth than previously anticipated under a Biden presidency, which is marginally positive for tech stocks. The current situation is also marginally negative for green technology stocks, which can rely on supportive regulation but not on massive fiscal spending.
Overall, however, we do not think that the outcome of this election has any significant impact on different sectors. With gridlock highly likely in Washington over the next two years, we anticipate top line growth for companies to be marginally lower due to a slower economic recovery after the pandemic, while profit margins remain high as tax hikes are off the table.
In the UK and Europe, the impact on stock markets is likely to be even less pronounced than for US stocks. On the margin, health care, miners and oil & gas might benefit as typical Dollar earners, but in the end, this election is likely to be a non-event for UK and European stocks.
What to do?
Overall, the election is not going to have much of a long-term effect on stocks. Given that we will have to wait for several days for the results to come in and for litigation to be settled, investors should remain calm and not change their portfolios too much (if at all). Instead, take deep breaths, relax and remember that in New Jersey a ballot initiative to legalise recreational use of marijuana has been accepted with 60% of the votes – though the corresponding changes will likely come too late to calm people down while waiting for the results to trickle in.
I'm not commenting on the Presidential election but wanted to point out that the 'Blue Wave' which was supposed to happen didn't. This likely means that if Biden gets in he won't be able to introduce some of his policies like hiking corporation tax and capital gains tax and that large government expenditures might not happen. This is held to be positive for the market.
Maybe the 'Blue Wave' is still in the not yet counted postal votes ?
Argentex (LON:AGFX) have just announced H1 20 results will be released 20th November 2020. Carl Jani, Co-CEO will give a H1 20 results presentation followed by Q&A, at 11am on 20.11.20. Register here.
The piworld Thursday webinar/interview tomorrow 5.11.20, 1pm, is with Paul Jourdan, CEO Amati Global Investors. He'll cover how he selects investments. His views on how the industrial age is evolving, and how he's positioning for that. He'll discuss how he reacted to CV19, and how that's worked out. He's a brilliant investing mind and a great communicator. We're in for a treat. Do register to join here.
Hi Tamzin
I love your webinars. I found it difficult to hear some of what Paul Jourdan was saying as there was a lot of echo and I assume he was in a large room? Perhaps a thought for the future?
Although usually too large for this report I'd be really interested in any views you have on Marks And Spencer (LON:MKS) H1 2021 half year report this morning - both for the business and the wider read across for retail.
Positives:
Negatives:
I hold. It is quite hard to value in the short-term with further lockdown(s?) and I still need to do further research and thinking. But if store sales can recover into 2021 the share price could have a very decent rise off the back of Ocado growth as well.
Given the unprecedented nature of the covid/lockdown period being within MKS's H1 results, I thought the numbers were stunningly good! I've just bought a few at 93p. With such large stores, and greatly reduced footfall, I was expecting MKS to report a gigantic loss, but it hasn't. Also net debt reduced from £1.6bn to £1.4bn (excl. lease liabilities) means it's securely funded, with plenty of cash/borrowings headroom. I think there's everything to play for, once they can trade normally again (maybe spring 2021?), plus as you say the new Ocado relationship driving online growth. Meanwhile, there's bound to be less competition by the time things get back to normal, with so many retailers needing to restructure & close stores.
Another thing to consider is that older people are itching to be able to get back out there. My Mum for example has barely left her flat since February. She's being very stoical about it, but when things return to normal, or at least safe enough for her to go out again, she'll be itching to use her free bus pass and go out shopping 2-3 times per week. There must be millions like her,so I reckon 2021 could be a surprisingly good year, with pent-up demand for all sorts of things, and people maybe having a greater propensity to spend, on the basis that we've been deprived of many things we enjoy (pubs, restaurants, shopping, travel, etc), so let's live for today, and spend, you cant take it with you, etc.
Regards, Paul.
any other views in 'bombed our recovery sectors' paul? I can be a bit of a contrarian when it comes to investing and like spotting value also. I think monday AM first thing was good for value but didn't make the most of it when all shares dipped before people realised that furlough payments would mean many hospitality/retail businesses would actually be better off in some cases, and that as you say with vaccines/mass testing getting closer then 2021 could be more rosy. What are the main bombed out recovery plays? I had been heavily short Trainline (LON:TRN) but thinking of reverseing position, still looks fairly expensive, could be one of them. Restaurant (LON:RTN) just maybe Sure there are lots of others to consider
My morning smallcap tweet: STV trumps expectations
Mitie (LON:MTO) ECSC (LON:ECSC) Strathdon Investments (LON:STV) Coral Products (LON:CRU) IQ-AI (LON:IQAI) Bango (LON:BGO) Wilmington (LON:WIL) Escape Hunt (LON:ESC)
MITIE (MTO) Trading has continued to be more resilient than expected with Q2 rev up 12% on Q1. No H1 div. [SP=27.25 Cap=319m]
ECSC Group (ECSC) Q3 rev up on average quarterly revenue for 2019. Adj EBITDA over £50k per month. [SP=69.95 Cap=7m]
STV (STV) ad rev ahead of expectations, with Q3 -4% and Oct -2%. YTD TV viewing up 13% and online viewing up 82%. Expects to "finish year strongly on screen with November traditionally our biggest month of the year thanks to the return of I'm a Celebrity; while in STV Studios our 14 new commissions so far this year means that 2021 promises to be our most successful year yet."" [SP=NA Cap=NA]
Coral Products (CRU) wins renewal of a 3-year supply contract with a major international telecommunications group. Guides £3m PA av rev but no g'teed rev. [SP=4.75 Cap=4m]
IQ-AI (IQAI) FDA approves Liver Surface Nodularity software application which gives a new way to use CT scans for virtual liver biopsy [SP=4.5 Cap=7m]
Bango (BGO) BT partnership sees first launch with BritBox. BT customers will get Britbox 6 month trial for free. [SP=153 Cap=114m]
Wilmington (WIL) Q1(Sep) ahead of management expectations with rev down 6% but adj pretax up. Co on track to at least achieve the expectations for H1 which is for rev and pretax equal to H2 2020. [SP=122.8 Cap=108m]
Escape Hunt (ESC) recent 1 week rev (in half term) up 25% but LFL down 4%. EBITDA conversion ratios substantially better than in prior periods. Sites will cloe in lockdown. [SP=10 Cap=8m]
// Half-year Report
// The business has performed better than expected during the first half with revenue down 15.8%, outperforming the Covid-19 planning scenario by 22.8%. As a result, the Group exited the period with reduced stock levels year on year and generated free cashflow. Group net debt reduced £118.5m and at the end of the period we had £1.4bn of cash and available facilities including the £1.1bn undrawn revolving credit facility.The Food business has performed strongly despite substantial Covid headwinds during the six-month period achieving 2.7% LFL growth or 6.6% when excluding hospitality, which was largely closed during lockdown. It adapted rapidly to the change in shape of demand to deliver improving LFL growth across the period. //
// Third Quarter Trading Update
// As expected, customer booking volumes for the quarter were lower year-on-year, in-line with the tighter underwriting standards enacted earlier in the year. Customer spend increased by c.31% on the previous quarter but remains c.15% lower year-on-year, in-line with trends seen across the credit card market.//
// Trading Update
// In Construction & Infrastructure, the Infrastructure activities have continued to trade strongly, with revenue and margin well ahead of prior year. With the Construction activities also recovering well, it is expected that the overall divisional margin for the year will be in excess of 2%, reflecting the high quality of client relationships, operational delivery and risk management in the division.In Fit Out, there have been no significant changes to market dynamics or customer behaviour. Although the secured order book at the end of September was 15% lower than at the same time last year, this is more than offset by the value of projects at preferred bidder stage. In addition, the value of tenders due in the final quarter of the year is 18% higher than for the same period last year.//
// Final Results
// It is remarkable how quickly things can change. In my statement at the half-year, the IMF had predicted global growth at minus 3%; their latest forecast has put this at minus 4.4%1. During March 2020 global stocks saw a downturn of at least 25%, 30% in most G20 nations, and the Covid-19 pandemic continues to inflict rising human costs worldwide. It has had a more negative impact on activity than anticipated and recovery is likely to be more gradual than previously thought.The Asia Pacific region, though, has to date suffered less from the disease than other parts of the world by containing its spread through a combination of stringent mobility restrictions and extensive testing-based programs. Domestic activity is reviving, but the region's economy is heavily dependent on the rest of the world.//
// H1 FY20/21 trading update
// Trading has continued to be more resilient than expected. Second quarter revenue was up 12% on the first quarter, with monthly sequential improvements in sales particularly across Cleaning, Security and fixed Technical Services contracts. Our public sector contracts have shown good resilience during this challenging period and we have also seen strong performances from our food retail, online retail, healthcare and pharmaceuticals customers. However, demand from our property and finance & professional services clients remained weak, although the second quarter was somewhat better than the first quarter as office space reopened.Group revenue from continuing operations for the second quarter was £514m versus £458m in the first quarter of FY20/21.//
// Trading Statement
// Q3 total advertising revenue was -4% year on year, with July -7%, August +1% and September -5%. October improved further to -2%, with revenues seeing a meaningful step up in the important autumn months, even taking account of tough comparators with Rugby World Cup 2019. Total advertising revenue January to October stands at -13%.//
// Interim Results
// Ah yes, the reason why you cut your losers and run your winners. It’s only had a handful amount of days above the 200d ma in the past to 2 years, and if you run a regression line through it, it will reach 0p on 01/01/2021. Aviation -48.9% Energy -22.5% The trading outlook for Stobart Air has deteriorated significantly since the capital raise//
// Trading Statement
// The Board is pleased to announce that financial results for the quarter have been encouraging and were ahead of management's previous expectations. Adjusted PBT was ahead of the corresponding period in the last financial year despite revenue being down around 6% on an underlying basis at constant currency due to the inability of the Group to run face-to-face training and events in the period.//
// Preliminary Results for year ended 31 July 2020
// Theres some companies+charts where nothing released in the RNS will change anything. Recruitment groups is one of them areas, somewhat stuck in the past in the way they operate with no ambition to change. Don’t really agree with the high Stockrank here, but that only because it doesn’t rank in story, but rather impressive metrics such as revenue to market cap. Well, impressive for the wrong reasons. //
Code missed this one
// Smurfit Kappa (LON:SKG) is one of the world’s leading providers of paper-based solutions, (not to be confused with Papa Smurf who is the oldest Smurf) has published EBITDA of €1,125 million for the nine months. Looking back at their Half-year Report published on Wednesday 29th July, the Group reported EBITDA for the first half of €735 million, down 13% on 2019, but their share price has climb close to their all time highs achieved 2 years ago.
Cheers!