Small Cap Value Report (Weds 4 Oct 2023) - SDRY, ALFA, BELL, SPT, TPT, VTU

Good morning, it's Paul and Roland today - welcome back Roland!
All done for today!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
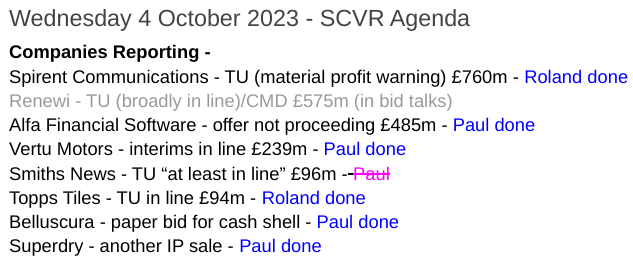
Superdry (LON:SDRY) - up 27% to 55p (at 09:36), mkt cap £54m - Paul - AMBER/RED
Another IP sale, netting £28m. Clearly there is some value in the brand, internationally. This buys it time I think, to see if it can turn the loss-making core business around. For that reason I've relented, from RED to AMBER/RED, to recognise that this is a significant cash injection.
Alfa Financial Software Holdings (LON:ALFA) - down 11% y’day to 165p (£486m) - Paul - AMBER
Announced yesterday that early stage bid talks are off. Shares don't look very interesting to me, as detailed below.
Belluscura (LON:BELL) - 35p (£47m) - Fundraise - Paul - AMBER/RED
Some interesting elements to this fundraising for this jam tomorrow company. Including the acquisition of a listed cash shell with £4.7m cash in it, so a backdoor fundraise that reminds me of the 2001-3 bear market, so I reminisce below about my 5 shareholder action groups targeting cash shells.
Spirent Communications (LON:SPT) - down 32% to 89p (£508m) - Q3 TU (profit warning) - Roland - AMBER
A “material” profit warning from this FTSE 250 engineering group, which says Q3 order intake fell well below expectations. My sums suggest earnings could halve this year, but I think Spirent could be worth further research as a recovery/value play.
Topps Tiles (LON:TPT) - up 3.7% to 50p (£98m) - Q4 trading update (in line) - Roland - GREEN
This tile retailer has issued a reassuring full-year update, confirming that profitability improved as expected during the second half of the year. There’s some risk from reduced homeowner spending, but I think the 7% dividend yield looks relatively safe and remain positive.
Vertu Motors (LON:VTU) - up 2% to 71.5p (£244m) - Interim Results - Paul - GREEN
Solid H1 numbers, and an in line with expectations full year outlook. Balance sheet remains very good, with loads of freehold property, although note that net debt has risen following acquisition of Helston. More acquisitions are planned. Divis & buybacks combined are equivalent to a c.7% yield. Outlook sounds fine. Potential bid target, as whole sector is in play. Plenty to like here, for value investors.
Paul's Section:
Superdry (LON:SDRY)
Up 27% to 55p (at 09:36), mkt cap £54m - Paul - AMBER/RED
Sky news reports that it is about to announce another IP sale, to a partner in India, for £25m. SDRY had previously indicated that more IP sales were in the pipeline, on top of the net £34m supposedly received post year end from its Far East IP sale. These amounts are surprisingly large, and do clearly show that the brand does have value still. If this deal completes, it gives management more time to turn around the loss-making core business. Potentially interesting, maybe we’ve been premature in writing it off? Could go either way, I think.
SDRY confirms with an RNS this morning - it’s set to receive a net £28.3m from the sale of IP to a JV in which it will hold 24%. This is significant I think - we could see a pop in the share price today - whether it holds though, is another question - as we’re seeing at many companies, rallies can often be rapid, but short-lived, depending on the circumstances. Good examples of that recently were Videndum (LON:VID) and Victoria (LON:VCP) which plunged on bad news, then furiously rallied, but have since fallen back again. In both cases the prices looked to me like they were being manipulated by persons unknown. One that hasn’t rallied yet, on recent bad news, is XP Power (LON:XPP) . This bear market shows no sign of letting up right now, really tough conditions, especially for overly-indebted companies that encounter harsher trading conditions - these are the things to carefully avoid, I think. Debt is now expensive, and equity is hard to raise if companies get into trouble with too much debt.
Alfa Financial Software Holdings (LON:ALFA)
Down 11% y’day to 165p (£486m) - Paul - AMBER
Announced on 27/9/2023 (after leaks to the press) that it was in preliminary talks following an unsolicited possible offer from THL. It now says that talks have been terminated.
Interesting comments ALFA says it has “an exceptionally strong late-stage pipeline”, and “strong confidence in the outlook for the business”.
Paul’s view - I’m not familiar with this company, but on reviewing the StockReport it’s difficult to see any attractions from the historic numbers - profit has only really gone sideways for the last 6 years, there’s only a 1% divi yield, and we’re being asked to pay 22x forecast earnings. Negligible asset backing too, with a price to NTAV of 33x.
There might be more to it than those numbers suggest, but I have to see something attractive in the figures to make me want to research it more, which is not the case here.
Belluscura (LON:BELL)
35p (£47m) - Fundraise - Paul - AMBER/RED
A flurry of announcements from this jam tomorrow Adam Reynolds company. There’s no track record, so the market cap is based entirely on contracts for its oxygen enrichment technology, which sound exciting, but as yet unproven.
Quite a creative (or desperate?!) refinancing, containing 3 elements -
Placing of £0.6m at 32p, so minimal dilution from this.
Convertible (at 40p) loan notes (10% coupon) raising £2.7m, and
Acquisition of a listed cash shell ( Tmt Acquisition (LON:TMTA) ) with £4.7m cash in it, using BELL paper. This reminds me of the 2001-3 bear market, where a lot of failing internet startups had large cash piles of 2-3 times their entire market caps. I ran 5 shareholder action groups targeting these, all of which achieved 100%+ profits for shareholders (Expocentric, Protagona, Actinic, PPL Therapeutics, Teamtalk Media). The reason I mention it here, is because several of the successful outcomes of my action groups, were all-paper takeover bids by other listed companies which needed the cash piles of the target companies, and didn’t have any other way to raise fresh cash. The Belluscura takeover approach for TMTA is exactly the same - shareholders in TMTA holding a dormant cash shell, swap their shares for a jam tomorrow project in the shape of BELL, which may or may not work out, depending on what happens.
The devil is in the detail, so it's always worth carefully reading fundraise announcements, in case there are dilutive elements like warrants buried in the detail.
Paul’s opinion - I’m keeping an open mind on BELL, although it’s not the sort of thing I’d want to get involved in at this stage. I’d rather pay more, once the business is actually generating cash, rather than taking a punt on a startup project. Why? Because hardly any of them actually deliver what they promise, so things like this are usually terrible investments! There's the odd rare exception though, and often even failing projects can be temporary multibaggers when people believe the hype.
Anyway, I just thought BELL’s unusual refinancing was interesting. Maybe we’ll see more similar deals (backdoor fundraisings) from cash-rich companies being taken over primarily for their cash piles? I’m not sure how many cash shells there are currently listed? Not as many as there used to be, because the rules were tightened up, so they have to do something with the cash pile, or face delisting, after a certain period of time.
Vertu Motors (LON:VTU)
Up 2% to 71.5p (£244m) - Interim Results - Paul - GREEN
Vertu Motors plc, the automotive retailer with a network of 190 sales and aftersales outlets across the UK and with sector leading brands, announces its interim results for the six months ended 31 August 2023
Company’s headline -
"Record revenues, year-on-year profit and dividend growth"
A long-standing SCVR favourite value share, this car dealers. It’s been a safe port in the small cap storm of the last 2 years, being around a 5-year high presently, despite not managing to catch a takeover bid, unlike several of its peers.
Here are my notes from reviewing the H1 results -
H1 revenue £2,423m (up 21%, helped by large acquisition of Helston, included for the full 6-month period after being acquired in Dec 2022)
Adj PBT £31.5m (up 12%) - very low profit margin, as much of the revenue is the full value of new & used cars, so really I see the gross profit figure as being more meaningful than revenues.
Note that adjustments both this year and last, are very small.
There seems to be an H1-weighting to profits, judging from last year’s numbers.
Finance charges - have tripled, reflecting higher interest rates and the fresh debt to buy Helston. Finance charges now consume a quarter of operating profit.
Corporation tax is also now biting at most companies, VTU shows that its effective rate has gone up from 20% last year, to 25% H1 this year, taking quite a bite out of earnings (PAT).
Net debt has risen considerably, to £90.7m (was net cash of £17.8m a year earlier. This is due to the Helston acquisition). Not a problem, but of course servicing debt comes at a price.
NTAV by the company’s calculations is 70.9p, so about par with the share price, mainly being freehold property, so this share remains full tangible asset backed, very nice.
Share buybacks - notable as having bought back 14% of the whole company in 7 years, and ongoing.
Outlook comments seem generally positive -
FY 2/2024 is proceeding in line with market expectations. VTU has a pretty good track record of setting expectations at a reasonable level, then upgrading/beating expectations, helped by favourable market conditions in recent years.
Strong September (registration plate change month, so important)
New & used vehicle supply improving.
More acquisitions identified.
Agency model - closely monitoring - do any readers have an expert view on this change to car dealer/manufacturers relationships?
Cautious about customer confidence.
Balance sheet -
Pension scheme is fully funded.
NAV strong at £356m. I’ll deduct £130m intangibles (growing, due to acquisitions), and also cancel the (usually related) £21m deferred tax creditor, giving NTAV £247m, which is healthy, and is mostly freehold property, with large working capital debits and credits roughly offsetting each other and continuously rotating, so that’s as I would expect.
Note long-term borrowings has risen to £122m from £55m a year earlier.
Overall, it’s a strong & healthy balance sheet, I reckon.
Cashflow statement - all looks straightforward. Note that working capital increased a fair bit in H1. Also note that divis and share buybacks are similar £ amounts, so the overall yield is a lot better than the 3.5% headline divi yield would suggest.
Broker update - Zeus (many thanks!) updates us, only slightly tweaking figures to reflect share buybacks (hence slightly higher EPS). It reckons 10.0p for FY 2/2024, rising to 10.6p next year.
That puts VTU on a PER of only 7.2x, which continues to look cheap I think. Especially with bidders sniffing around and pouncing in the sector.
Paul’s opinion - I remain positive, so it’s GREEN again.
What we like about Vertu -
Sector is in play, so could attract a premium takeover bid?
Low forward PER
Forecasts have been rising (helped by a largeish acquisition too)
Rock solid balance sheet, with price to NTAV only about 1x
Dividend yield of 3.5% is covered 4x, plus similar amount of buybacks on top.
Management come across well on webinars, as hands-on and energetic, with sensible strategy (subjective).
Downside risks -
Higher profit margins on used cars may diminish over time.
Threat from direct to customer supply of EVs?
Unknown impact of changes to agency business model.
Suggestion that EVs may require less servicing, although contrary indications also suggest there may be more going wrong with them, and harder to fix, maybe?
Higher cost of borrowings, and vehicle stocking loans.
Low margins overall.
Energy costs from multiple large premises - although this is only 2.2% of total overheads, so immaterial really..
Cost of living rises for staff, and shortages of suitably trained mechanics.
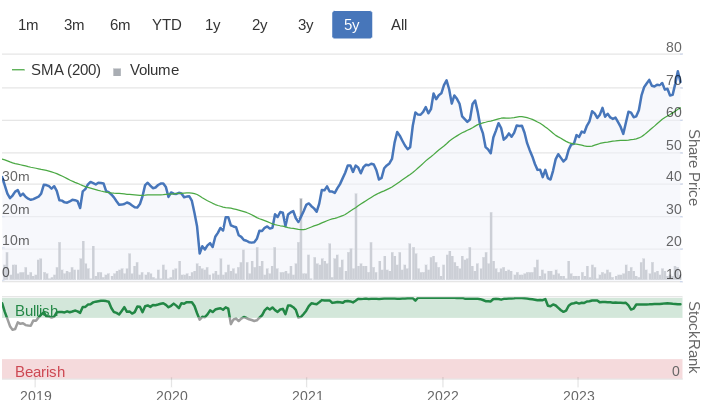
Nice high StockRank too -
Roland’s Section:
Spirent Communications (LON:SPT)
Share price: 89p (-32% at 08.30)
Market cap: £508m
Trading impacted by very challenging telecommunications market conditions
Today’s trading update from this FTSE 250 network testing and assurance specialist is unfortunately a material profit warning. A shortfall in Q3 orders means that the order book no longer supports expectations for full-year trading.
Spirent shares have fallen into our market cap range thanks to a share price decline that had already seen the stock halve this year, prior to today’s slump.
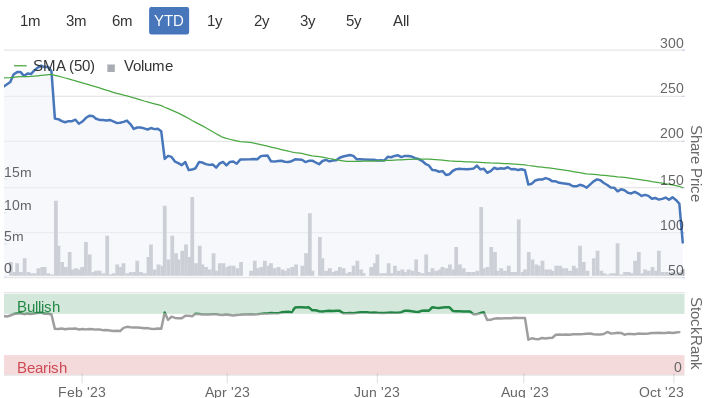
Let’s take a closer look at today’s news.
Order shortfall: Spirent says that improved order intake momentum in the second quarter did not continue into the third quarter.
The company says order intake for the first nine months of the year was down 24% compared to the same period last year. This is blamed on key telecommunications customers “delaying their investment plans”.
The Chinese market is said to represent “a large proportion” of the revenue shortfall, due to a reduction in Chinese government spending plans.
Revenue for the nine months is expected to be down by c.20%, consistent with the first half of this year. Full-year revenue is also expected to be c.20% lower than last year.
Management says that gross margins are tracking “to plan” and cost savings are underway. However, they warn that the group’s fixed cost base will result in a material hit to operating profit:
negative operating leverage will impact operating profit very materially
I don’t have access to any updated broker forecasts for Spirent and today’s update doesn’t provide any revised profit guidance for investors. However, I think we can gauge the likely scale of the damage using the information provided.
FY22 revenue was $607.5m. This year’s result is expected to be down by 20%, suggesting a figure of around $486m.
Gross margins were 72% in H1, so I’ll assume a similar result in H2. That would give a full-year gross profit of c.$350m.
Checking back to last year’s accounts, adjusted operating costs were $308m in 2022 and $306m in 2021. The figure for H1 2023 was $149m.
Given this consistency, it seems reasonable to suggest that adjusted operating costs for 2023 could be c.$300m, less any short-term cost savings that can be made.
This suggests an adjusted operating profit for the full year of around $50m, compared to a 2022 figure of $129.5m.
Statutory operating profit will be lower, due to the inclusion of adjusting items including amortisation and share-based payments. Last year, these totalled $17m.
Based on an adjusted operating profit figure of $50m, I estimate full-year adjusted earnings might drop out at about 8 cents per share. This is roughly half the consensus estimate shown in Stockopedia prior to today’s results:

Balance sheet: Fortunately, Spirent had a net cash balance sheet position at the end of June 2023. Management says that the balance sheet “remains strong”, although today’s update does not confirm whether Spirent still has a net cash position.
Share buybacks: the company has spent $72m buying back shares this year. Given the uncertainty in its underlying markets, I would have preferred a more cautious approach to preserving cash. But to be fair, Spirent has been highly profitable and cash generative in recent years.
Outlook: management remains confident that the rollout of 5G networks will be “an enduring growth driver” and believe that “core network spending” is also “poised to increase through to at least 2027”.
Stronger activity is expected in 2024, but order intake does not yet reflect this and Spirent warns of “the lack of certainty in the timing of our customers’ technology roadmaps”.
Today’s trading update did not include any new guidance for 2024.
Roland’s view
Today’s profit warning should probably be seen in the context of the company’s updates throughout 2023. In January, Spirent warned of a greater second-half weighting than usual – always a risk.
In March, the company noted “delays to some of our customers’ decision making”.
Full-year expectations were left unchanged when the half-year results were issued in August, but with revenue down by 20%, it was clear that Spirent was placing a heavy dependence on a stronger second half.
The question now for investors is whether this is a temporary setback, or a sign of deeper problems within this business.
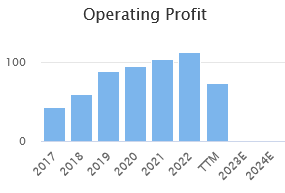
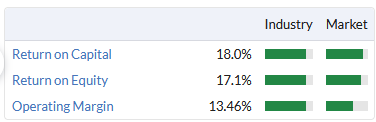
Spirent’s progress has been good in recent years and the company’s quality metrics have been excellent, in my view:
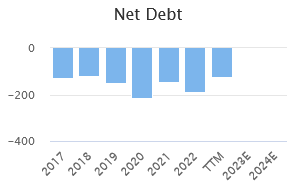
A track record of net cash is also reassuring, as it should give the company breathing space and allow time for it to return to growth:
On balance, I think there’s a reasonable chance Spirent shares could offer decent recovery potential from current levels. However, I’m a little concerned by the group’s apparent reliance on Chinese government spending.
I’d also want to do a little more research into the company’s product offerings and competition before forming a strong view.
Despite its long history, Spirent’s business model has changed several times over the years. I’m not entirely convinced this business has the long-term pedigree of some other UK-listed engineering groups.
On balance, I’m going to stay neutral on this. As far as I can see, Spirent’s previously strong balance sheet should mean the company can avoid financial difficulties. If profits recover in 2024, the shares could be cheap at current levels.
On the other hand, the near-term outlook clearly remains very uncertain.
I think it probably makes sense to stay on the sidelines and await the full-year results.
Topps Tiles (LON:TPT)
Share price: 50p (+3.7% at 09.45)
Market cap: £98m
Third consecutive year of record sales; FY23 profits in line with market expectations
Tile retailer Topps Tiles has issued a confident Q4 update, reporting record sales and confirming that full-year profits (y/e 30 Sept) should be in line with previous expectations.
Today’s update is clear and nicely consistent with previous updates this year, allowing us to track progress against previous management commentary.
Trading summary: sales results for the year look positive to me and suggest the company is maintaining its position as a market leader:
Group sales up 6.4% to “approximately £263m”
Third consecutive year of record turnover
Expect to report “a strong increase” in market share from 19% reported last year
The company says that sales growth moderated during the final quarter, mainly due to a reduction in residential RMI spend (Repair, Maintenance, and Improvement). In other words, squeezed homeowners are spending less on their properties.
However, performance across the group’s businesses appears to have remained on track:
Topps Tiles: like-for-like sales rose by 3.1% last year in the core business, with average sales per store up 30% vs FY19. Gross margins improved through the year as shipping and product cost inflation eased.
Pro Tiler Tools & Tile Warehouse: these online-only operations delivered 40% sales growth last year.
Parkside: this commercial brand suffered problems earlier this year but returned to profitability during the fourth quarter, thanks to a 35% reduction (!) in operating costs.
Profitability: Topps’ half-year results included guidance for improved profitability during the second half of the year. Today’s Q4 update confirms this:
Profitability improved in H2 as expected and adjusted profit before tax for the 52 weeks ended 30 September 2023 is expected to be in line with market expectations4. Our cash flow and balance sheet are also in line with our expectations.
The company helpfully includes a footnote specifying a consensus pre-tax profit estimate of £11.8m for FY23.
However, it’s worth viewing this in context. Profits are expected to fall sharply this year:
FY22 pre-tax profit £15.6m / adjusted earnings: 6.14p
FY23 forecast pre-tax profit £11.8m / adjusted earnings: 4.14p
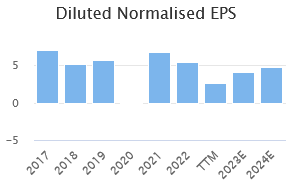
Unsurprisingly, Topps’ profit margins over the last 12 months have come under pressure from inflation. Reassuringly though, today’s update suggests to me that the worst may be over and that profitability could continue to recover next year.
Roland’s view
Topps Tiles looks quite reasonably priced to me, based on the full-year guidance that’s been confirmed today. Assuming the dividend is maintained, the shares offer a tempting 7%+ dividend yield:
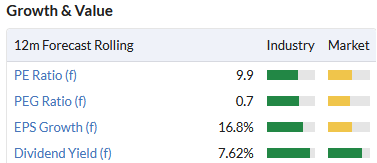
When I last looked at Topps Tiles in April, I noted that cover for the dividend was starting to look slim, with expected earnings covering the dividend around 1.2x.
That still seems to be true, but if profits start to recover next year as now seems likely to me, then cover could improve without requiring a cut. Free cash flow cover for the payout also looks reasonable to me.
The main risk that seems to be flagged up in today’s commentary is the possibility that spending by homeowners could suffer a longer and deeper slump than expected.
That’s certainly a possibility potential investors should consider, in my view.
However, today’s update seems to confirm my previous view that Topps Tiles is a well-run retailer with good market share and growing online operations. With the shares still trading well below pre-pandemic levels, I’m going to stay positive on this stock.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
So today I was a customer of Marks Electrical (LON:MRK)
Our tumble dryer failed, so did the can I get one the same day from the local Currys (LON:CURY) and the answer was no, wait for a few days and look at how many things are showing as you can buy, but are not in stock, and the one you want is delivery only and that is £35+++ no options matey.
So finally my brain went I am sure there is something that has been discussed here, hence Marks Electrical (LON:MRK)
It was a different brand and model than the one I had found, but A+++ rated, 10kgs load very good feedback when I looked it up, no delivery charge, £100 cheaper and no constant do you want it fitted etcetera, you have all those options but not constantly having to say no.
They delivered within 36 hours of ordering. You get a delivery day when you order, the night before about 18:30 in my case a message with your two hour slot for the following day, on the day both email and text giving you a time within the slot.
The chaps were about 15 minutes after that specific time, but turned up, very friendly, put it exactly where I wanted it and happy to do exactly that and appreciated that I had moved the old one and there is where it is to fit. Explained the delay was they had 6 recycles on their load, so having to do a rearrange as they were mainly in the early part of the run when the van was full if that make sense.
Anyway, Marks Electrical (LON:MRK) is now on the research list!
Customer survey of 1, good company!
Sorry no Greggs (LON:GRG) today as working at home waiting for the delivery and school runs and kids activities to do too!
Tommy
Ouch.
This market sell off is really dragging on now - how much longer? FTSE 250 down around 27% from its 2021 peak, but down well over 40% in real terms once you factor in high inflation.
While not quite as bad as 2008 yet, it's starting to feel worse in some ways - certainly dragging on longer. Importantly bonds rallied in 2008 and provided a very nice cushion, but they're getting crushed this time around.
I think last year was the worst for all asset classes in last 100, again from memory possibly worst for US treasuries in last 200, 2008 as you say bonds soared to parry a lot of the equity loss. This years been no picnic either broad brush you have the big seven going up and maybe ultra short bonds but most other sectors off 5-10% again. Surely 2024 has to be better.
History does not repeat itself but it does rime
Thanks Wolf, slowly I am getting better at Charts, sometimes a few days, weeks or months later, but hit a lot of sell buttons today on my Vanguard SIPP for exactly what you are showing
Cheers
Tommy
Diversified Energy (LON:DEC) Not a small cap but does anyone know why there has been such a big drop in Diversified over the last few days. Quite big volumes.
HI Ned
I sold on a manual stop my loss, and currently watching from the sidelines. Overall should benefit from the current oil and gas prices added the coming winter weather, but the rise in debt level is the key question...
Add in a lot of things seem to being sold!
Tommy
Looks like Hedin is bowing out from the Pendragon (LON:PDG) takeover battle -
Hedin and PAG confirm that they do not intend to make an offer for Pendragon.
Source: https://www.londonstockexchang...
Vertu Motors (LON:VTU) - I hold
Thanks Paul for your review. Not sure I agree that EV's are more likely to go wrong. They cost more to fix, that's probably true as parts/materials are more expensive, hence a bit more costly to insure.
I think the reliability reputation is distorted by the poor record of Tesla's which according to Which? magazine is by far the most unreliable EV, lots of electrical issues I seem to recall.
I own an EV, a BMW i3 and it's a joy to drive and so far totally reliable.
hi rwh3ue
Vertu Motors (LON:VTU)
As someone who would be unable to charge from home I am not currently attracted to buying an EV due to the lack of an adequate charging infrastructure.
Additionally, particularly in the secondhand market, I guess you need to consider the potential future need to replace the battery, the cost of which seems exhorbitant. I have seen this quoted as being anything between £5k and £12k.
This seems rather scary for anyone buying a secondhand EV who might soon be unexpectedly faced with paying for a new battery.
What is the expected life of an EV battery?
How long is the guarantee on a battery on a new EV?
I can't imagine there being a great demand for secondhand EV's if there is a chance you might need to fork out for a new battery after only a short period of ownership and are outside any warranty period. In some situations that could effectively make the car a write off.
Where is the incentive?
Maybe I'm missing something?
Snazzy
Just to add to rwh3ue's comments ref Vertu Motors (LON:VTU) I own a Tesla model S which I have had since 2016. Now have over 150 000 miles on the clock. Still has same brake pads and brake discs. Had a few minor items replaced but it has never had a regular service. Has proven to be very reliable with maintenance costs negligible. I fear for the future of all our service garages. Opex costs a fraction of a diesel / petrol car.
Anyone have views on Jupiter Fund Management (LON:JUP) which Graham reviewed positively at the half way stage? Since then price has collapsed and now yields over 8%. We all know there have been massive outflows from UK funds over many months but price around 3yr low with StockRank of 94. Are investors too pessimistic now?
Jupiter is pretty cheap but markets are falling and PI's are selling funds, so fees will go down. Dividend policy is 50% through the cycle so dividend cuts are possible. Analysts are cooling. I still think that the firm is offering fair value. One thing that I don't like is that the firm has far fewer Investment Trusts than I would like. The institutional side is holding it's own. In summary I would rate it as a weak Hold. Markets could go lower still. Despite my rating I might pick up a few shares. The new management is doing the best job that it can.
I believe they are due to release a trading statement in next week or two, so the picture may become clearer then.
Re: Vertu Motors
'Corporation tax is also now biting at most companies, VTU shows that its effective rate has gone up from 20% last year, to 25% H1 this year, taking quite a bite out of earnings (PAT).'
This makes it even less attractive to hold UK stocks right!?
What's the bull case for holding UK stocks right now? Many are finding it hard to keep generating profits while any profits generated will be taxed at 25% from 20% last year. Most companies are now like running hamsters on a wheel?
For me the bull case for UK equities is threefold - very cheap valuations, the prospect of further M&A and the possibility of some sort of policymaker intervention to make the UK equity market more appealing.
I'm increasingly of the view that we'll see some sort of action on that last point given the number of high profile companies fleeing the UK market to list in the US. Perhaps some sort of incentive for pension or insurance funds to hold more UK equities, reversing the trend of the last 2 decades.
Government needs UK financial institutions to keep buying bonds to finance public spending and tinkering around edges won' t change issue's why international investors rate the Uk market so lowly.
Been trading too much in attempt to keep head above water and with mixed reults. For every sell, whether profit or loss, at least 60 to 70% will be going abroad. Just seems no reward in taking the risk and sadly investing in well regarded UK companies these days and with any gains soon taken back with selling to profit take. Sorry for pessimistic opinions and own view..
Anyone know why Calnex Solutions (LON:CLX) is down 13% today? Can't see any news.
Similar business to Spirent, which had a profit warning today
I think (from memory) that Spirent Communications (LON:SPT) is one of Calnex Solutions (LON:CLX) biggest customers.
Roland
Industry read across... Spirent Communications (LON:SPT) is taking a hammering on a material profit warning today. Investors are clearly jittery in this industry with many headwinds at play here. The fact that Calnex Solutions (LON:CLX) warned on profits in March doesn't bode well.
Calnex Solutions (LON:CLX) supplies Spirent Communications (LON:SPT)
Spirent read across
Does anybody know of an AIM collective/ETF (excl spread betting) Regards SL
Thats a No then LOL !
Congrats to Paul on Plexus Holdings (LON:POS, great find and even better timing. Sadly I have managed to miss out and only just catching up.
Interested in any views out there re the convertible and how it plays from here.... it looks to me like since the shares trade above 4p for all of September and dated back to Aug 22 ... conditions for a trigger to convert will be in place by mid month. This would be matched by an equal offer to shareholders to match the £1.5m raise but the conversion takes place at a 20% discount. I guess given the rise and demand for stock this can easily done as a quick 10% placing now.... potentially repaying the loans from September from proceeds and cleaning up the balance sheet. Given the rise maybe another contract is coming to sweeten the deal further....
Absolutely, I agree. Best trade of the year by some distance.
Takes some balls and conviction to go in big.
All credit to Paul, but I don't think the Fat lady has sung yet regarding Plexus Holdings (LON:POS) and the market capital was so small, his buying and subsequent discussion of it has driven the price rather than any improved trading.
Hi iain1234,
All credit to Paul, but I don't think the Fat lady has sung yet regarding Plexus Holdings (LON:POS) and the market capital was so small, his buying and subsequent discussion of it has driven the price rather than any improved trading.
I hear what you're saying, but all I did was shine a light on very significant newsflow over the last year from Plexus Holdings (LON:POS) which had been almost completely ignored by the market. Especially the game-changing £5m rental deal, subsequently increased to £8m, which is high margin rental, all recognisable in FY 6/2024, forecast by Cenkos to take Plexus from £4m pa losses, to breakeven this year.
Also the 6-year extension to the licensing deal with Schlumberger (world's largest oil services technology group) is great validation of Plexus's IP, although we don't yet know what the royalties are likely to be, when the products are launched (globally) maybe in 2024. Mgt says testing has so far been very encouraging.
So I do accept your point that me shining a light on such a tiny, illiquid share, is bound to have had an effect. But equally, as I mentioned in this weekend's podcast, everyone can read all the RNSs, and the Cenkos notes (on RT), watch the Proactive CEO videos, and it's obvious that there's a potentially big, speculative opportunity here.
I don't know how it will turn out, so as you say, the fat lady is still limbering up and gargling with some TCP.
Very volatile share price, but given all the tailwinds, £21m mkt cap still looks bargain basement to me, but I would say that, as it's (by far) my largest holding.
Convertibles - the interesting thing here is that the CEO who bought £1.5m of the £1.55m total, could have locked in a low conversion price, with massive dilution. But he didn't. He committed to doing (I assume) an open offer to allow other shareholders to stand their corner without being diluted, and he didn't lock in a low share price, which again he could have done. It's dependent on the prevailing share price, which of course has risen a lot recently.
Is it a speculative bubble? I don't think so. It's more a question of the stock being so small, it was totally under the radar. I just pointed out that the newsflow had been very encouraging, and clearly other investors agree with me. Although from the high volumes, it's also clear plenty of traders are nipping in & out too.
For another big leg up, I think it would need more contract wins.
Anyway, exciting stuff!
Regards, Paul.
P.S. So I think in terms of accusations of ramping, my conscience is clear because I've only pointed out facts already in the public domain in RNSs. I'm not putting any positive spin on it, or making exaggerated claims, I've always said that we don't yet know how the contracts or Schlumberger deal will pan out. There's certainly potential here, but it depends on how the company executes, so considerable risk still.
Absolutely! I think my portfolio is so far under water today I'll be needing some of Plexas subsea tech just to access it.
Smiths News (LON:SNWS) operating profit of £38.3m is just ahead of the previous year's £38.1, so it is probably safe to assume that adjusted EPS will be similar to last year's 10,9p and means the 4p dividend is well covered.
Net debt will have also reduced but as it's not mentioned, we don't know by how much.
This year has benefited from cover price increases, which I think are unlikely to recur to the same extent in the current year, making this years profits much tougher to match and on an inflation adjusted basis, SNWS may have possibly reached the point of peak profits. The company doesn't breakdown revenues from their ancillary businesses, so they are likely to be still small but it looks like they will become increasingly important going forward, as it looks like a step change is needed
It will be interesting to see what they say about that in the finals
Smiths News (LON:SNWS) are a distributor. I don’t believe they get paid based on the cover price unless they get a %age of that but I didn’t think that was the contractual basis?
Nonetheless even if 11p eps is the peak it is clear they will throw off far more net cash than 3.5* peak earnings so obviously the wrong price. They will move into net cash too very soon and pay a 10% dividend.
I don’t currently hold but think I probably should. Get paid 10% p/a whilst waiting for a re-rate feels like a good return. Need to do some more research but I don’t think there are any funnies with this share accounts wise either. A 6 or 7* PER I could understand but 3 does look cheap/miserly.
Agree. I see 40-0% upside to the high 50s/60p level as they become debt free, they lift the dividend covenants and attract yield hunters. So 10%+ divi plus 40-50% equity upside
Hi david,
Thanks for that. I didn't get round to looking at Smiths News (LON:SNWS) today, and the share price didn't move, thus making it low priority for us. We've covered the turnaround there loads in the last few years, so know the story well.
One quuestion - why do you think cashflow would be so much better than profits? If I recall, there's nothing much in fixed assets (hence little depreciation charge), so surely cashflow would be similar to profits?
A bit like newspapers themselves, the profits/cashflow have continued for far longer than anyone imagined, thanks to cover price rises. But it's only the rate of decline that we're really talking about. Unless Smiths can come up with inspired fresh use for its fast delivery network, then surely those 10% divis are really only temporary? That's why the PER is so low.
Regards, Paul.
Hi Paul
I didn’t mean cash flow is greater than profits.
What I meant was that with this business the profits predominantly turn into cash flow.
So if 11p eps is equiv to peak cash flow per annum then the market is assuming this company has about 4 or 5 years left of profitability before it all stops and everyone goes home with no newspapers/magazines etc.
This is clearly wrong - at current rates of print decline this business could happily go on for a decade plus at EPS not massively far away from where it is now. Is it going to grow big time? No! But it can distribute cash flow to shareholders at a significantly greater rate than a 3.5PER suggests.
So I think you can get paid 10%+ p/a for a long time with this share and it could happily rerate to 60p at some point too. The main issue I see is management splurging cash on some harebrained scheme leading to wealth destruction like the last lot did but having listened to them speak it seems they are acutely aware not to do that.
As I say I don’t hold but am considering buying some at this sort of level in an ISA where the income is tax free. I can see it compounding 20% returns a year over 3 or 4 years when divi is taken into account and the downside risk appears quite small at this level.
And they can diversify as a distributor and warehouse storage if I remember correctly. I agree feels like a very safe 20% compounded for 3-4yrs tempted to whack a major part of sipp in it as I did in 2022 from 35p-52p plus a divi (the only good trade of the year offsetting all the other rubbish ones) and sit back
I would look at the article Mark did a while ago it gives a good take on the how long this will last, or not, or maybe
Stockopedia | Smiths News: Cash cow or investment dog? | By Mark Simpson
Tommy
ps. I hold (well Mum does)
Diversified Energy (LON:DEC) has fallen quite dramatically over the past few days, down 16% despite no RNS or company specific news. I hold a small-ish position, but must admit I was in for the large dividend and don't have extensive knowledge of the company. I am interested to hear from any holders, particularly anyone who has sold out in the past few days, i'd be interested to know their reasoning - I am assuming there are worries about the dividend being maintained under tough macro conditions, although 16% in two days with little new macro economic data seems a drastic reduction. Is there something else in the news that I have missed? Thanks in advance.
this is one of many price alerts (in my case designed to prompt a look) to have rung in recent days. So I too would be interested in readers and holders views on this. Brokers still forecasting divis to continue as far as I can see. Until of course they dont! Perhaps there is a fear that their frenzied M & A will (or has) go(ne) too far?
Lots of expensive debt and complicated hedging makes it a difficult one to get your head around. Plus I believe the CFO recently left and there was also a placing I believe. Overall just too difficult for me, although I did hold in the past and keep a vague eye on it.
Ben, there is a lot of DEC posts on LSE.co.uk today. Most commentators seem to think the drop is caused by a coming tightening of the clean air rules. However, it is not necessarily clear these would hurt DEC. See link below.
https://www.edf.org/sites/defa...
That, and the fact there has been no comment from the company.
Apologies to all, I forgot to say it was Vertu shares I was referring to in my reply to planetx.
Is it just my watchlist & holdings or are a heck of a lot of companies doing share buy backs right now.
Most of these are bombed out companies buying at historically low levels that seem to keep getting lower! We see the equity withdrawal stats others have posted, is this stopping them falling further!? Or is the strategy not working... Yet
Buying companies hoping for a takeover or at a NAV discount (or just a low PE and/or high do yield) as a value investor doesn't seem to be going well of late but there has to be a bottom somewhere on a lot of these! Seems some incredible value around in small caps but of course it did get worse last hear around this time with the disaster Kwasi/Truss budget!!
Problem Is liquidity - there is none.
You have funds with redemptions dribbling out persistent sells. Some of this gets mopped up in buy backs but all it is doing is stopping prices falling further. There is almost zero fund buying and volumes are well below 50% of a couple Years back.
So cash rich companies are enhancing their EPS through buy backs but the PER gets persistently de-rated so net effect is still down. Until buying returns none of this changes irrespective of buy backs.
we saw a couple of weeks back around £250m of inflows (highest in 18 months) as interest rates were seen to peak. This put a rocket under a number of shares as the liquify effect reversed gear. However, it was short lived and with long dated rates rising again we are back where we started.
At some point, in the UK, my guess is we are going to see some very big gains as liquidity returns but it will probably be a very fast re-rate to more historic levels. Quite when that will happen though who knows……
The only things I have made any money on recently are Georgian banks, Kazakhstani cement makers and English wine !!!
Georgia Capital (LON:CGEO)still looking at a sizeable discount below £10 so added thst also.
This has bothered me for a long time now. I used to be bothered about companies buying back their own shares at high price levels and thought they should be buying at low levels like at present for instance. But I can see now that it is like running water into a bucket with a big hole in the bottom and think that companies should have been giving that cash back to the owners of its shares. Especially when dividends on average have been at a far lower percentage than inflation. Basically the practice is dishonest as the only ones to benefit are company directors who get some protection for their bonuses from it.
I am in complete agreement on the volume of share buybacks and have not seen any benefit for me the private investor I would prefer the money spent on buybacks as a dividend regardless of the tax position so that I could decide where I wanted to invest it
For most companies the effect of buybacks disappears very quickly I totally agree on “for the benefit of directors”
We've had 27 consecutive months of equity fund withdrawals. No wonder UK equities are under the kosh:
https://www.investments.lloyds...
Bought some shares in Greggs after talking to the manager of a new small outlet in a filling station who said they were taking £2k a day they have 8 in our area now very profitable I think
There is nothing like doing your own research ...
Crumbs!
love it!
every Greggs you pass by - including Motorway stops - are crowded all day....
That’s why the U.K. is full of fat bastards!
Alfa Financial consistently pays special dividends. The late stage pipeline is very exciting and the b/sheet is net cash. As a software business they don’t have much in the way of tangible assets
Volex (LON:VLX) has rolled over - below 50d MA. Read across from XP Power (LON:XPP) ?
Sector under pressure?
Given the market rout in UK small and mid caps I think you would be hard pressed to find a handful of related shares that are not in a downtrend.
Yu (LON:YU.) has bucked the trend
Rockwood
Looks like two new holdings Restore and James Fisher (think they are new but I could be wrong ).
Always worth keeping an eye on Richard Staveley
Rockwood Strategic (LON:RKW)
I agree, Mr Staveley supported by a well informed advisory group at Harwood has done an excellent job in an awful market environment. Staurt Wiiddowson at Odyssean Investment Trust (LON:OIT) has an 8% holding in James Fisher And Sons (LON:FSJ) . Both trust are held in family portfolios.
Vertu
Quick scan of vertu showing a lovely set of results and seems such a well run company .
I’m quite happy for vertu to remain listed as there is a reasonable chance the other players that are being taken private are going to have new management / owners , this leaves vertu to carry on doing the day job and running a good business .
And some good cash generative disposals all at above book value coming up implying that book value is understated
Upcoming sales -
”Cash proceeds of £7.3m are anticipated, circa £2.5m in excess
of book value. “
Looks such a solid business with a good CEO and just basically right on top of their game stuffed with assets and making money, think they are in a sweet spot with their competitors being taken private .
And accounts that it’s a joy to read and analyse as there is nothing to hide in them. Hopefully it will not be bought at a cheap price as I strongly believe this can easily reach the £600 market cap in 2-3 years.
Happy to concur planetx, it's our biggest holding which just got slightly bigger at 71.4p per share. Also added to our Ramsdens holding, their shares for no announced reason I'm aware of has joined the general sell-off. Castings is another I'm watching with a mind to add. Tough times for all small caps even the Green ones!
Spirent Communications (LON:SPT) May soon end up a small cap on the back of todays nasty Profit Warning
Order intake -24% on last year
As a result, “The impact of negative operating leverage will very materially affect operating profit in this financial year”
Potential read across to others in the sector
Ouch
Yep, that'll gap down. One of Robbie Burns latest buys I read last night, I'd suggest anyone paying to go to a Spanish investor retreat would be better served not buying anything in such an obvious downtrend.
SPT is a high quality company caught by bigger events. Leverage works both ways. Has fallen too far for me to sell now.
I am watching to add over the next few weeks.
To be fair on Spirent Communications (LON:SPT) management they made it very clear that their guidance was far from "in the bag" by cautioning investors on several occasions that there was a H2 weighting:
On 13/7/23, Q2 trading update:
"The Board's expectations remain unchanged for the full year, albeit, as previously stated, the trading performance will be significantly more weighted to the second half of the year than usual."
2/8/23 Interims:
expectations remain unchanged for the full year, albeit, as previously stated, the trading performance will be significantly more weighted to the second half of the year than usual.
Sadly H2 didn't come to the party. With hindsight we now know the lowish P/E wasn't low enough to account for the risk to the E bit.
A sobering reminder that you can still lose a lot of money on low P/E stocks where you suspect the market may have priced in some doubt over earnings. Also - there was significant director buying back in March (3 directors buying £50k chunks).
Synthomer (LON:SYNT) would be another low P/E tempter that floated to the top of Roland's screens some time back (he exited from his rules-based portfolio on the back of poor share price performance, before the rights issue).
Spirent Communications (LON:SPT) This is my biggest loss yet. I bought ahead of resultsbut it fell when they reported poor profits. I should've taken my losses then but they were optimistic because their order books were full. Then it drifted down further but not much more than similar stocks in the present market.
Today it seems those orders are not going to materialize. That is lesson one for me (that orders can amount to nothing). Also I shouldn't have bought ahead of results without better research.
So I've taken my losses now but I agree that it might be a good one to buy before the year end...
Spirent Communications (LON:SPT) is a perfect example of the lottery Directors enter when buying back shares on our behalf. They have no greater knowledge of future share price performance and when in a case like this they are already warning that trade is running below budget they should surely have paused the programme. £56m now worth 1/3 less just today. And it has dropped steadily through this year. I'd suggest either the advisers or the sponsoring director should fall on his sword for this.
Yes there are examples of successful buybacks but how many are luck and how many good judgements? If I were a shareholder here, and fortunately I've been following but not bought, I'd rather have received that cash in dividends. At least then I would have it to spend or reinvest. A marginally higher EPS would be little solace.
And I very much doubt he managed to get out of the stock at the 123p stop he has listed on his trade list.
I do wonder to what degree traders with stops cause share price overshoots on gaps down like this.
Anyone using a stop loss especially in such negative markets has to be spot on with the buy point. Personally I'd rather wait for the trading update and pay 5-10% more if it gaps up than randomly buy if its in a downtrend. It removes, at least short term, the chance of a profit warning.
long term holders can just hold if they still see good prospects and they're looking out 5 years or so. Tho I'd say quite a few long term holders are really traders.
If I'm buying this in the last few weeks and have a stop loss in place then the higher probability play is I'll get stopped out. News trumps any chart, but it has to be stand out good news right now.
My morning smallcap tweet: London's Ultra Low Bullshit Zone
WANdisco (LON:WAND) Superdry (LON:SDRY) Renewi (LON:RWI) Sabien Technology (LON:SNT) Topps Tiles (LON:TPT) CAP XX (LON:CPX) Smiths News (LON:SNWS)
◄WANdisco (WAND)► completes rebrand as Cirata. Ticker CRTA (not pronounced 'crater') from tomorrow. Remember "Cirata reflects the updated vision for the Company, its values and future growth plans." IE forget about all the WANdisco unpleasantness. [SP=63 Cap=73m]
◄Superdry (SDRY)► sell brand IP into JV with Reliance Brands in India, Sri Lanka, and Bangladesh. SDRY will hold 24% of JV. SDRY will net £28.3m after fees and taxes. Reliance will continue to oversee brand operations in the Territories. [SP=41.9 Cap=41m]
◄Renewi (RWI)► guides FY-Mar broadly in line with mgmt expectations. "Increasing contribution from cost actions anticipated to largely offset current demand conditions persisting during H2." YE cash €10-15m better than previous guided. [SP=715.5 Cap=574m]
◄Sabien Technology (SNT)► rollout of its M2G Cloud-enabled gas boiler energy saving solution in US. Expects additional rev at least £100k in the current FY. [SP=8 Cap=2m]
◄Topps Tiles (TPT)► guides FY-Sep rev c.£262m, up 6% but only 3% in Q4. Strong increase in mkt share. Adj pretax in line with mkt exp of £11.3-12.3m. [SP=48.1 Cap=95m]
◄CAP-XX (CPX)► hires first direct sales reps in North America, adding to distributors. [SP=1.54 Cap=11m]
◄Smiths News (SNWS)► guides FY-Aug adj op profit at least in line with market expectations of £38.3m. Rev flat. Final div 2.7p. [SP=40.8 Cap=101m]. I hold.
In line: VTU
Apparently 'Cirata' in Hindu (re #WAND's new name) translates as: "A mosquito, a midge or eye-fly".
https://www.wisdomlib.org/defi...(Usually%20cila%E1%B9%ADa%20q.%20v.),midge%20or%20eye%2Dfly%20%26c.
Superdry (LON:SDRY)
Superdry brand to accelerate growth in India with new IP Joint Venture
Superdry plc is pleased to announce that it has signed an IP joint venture agreement with Reliance Brands Holding UK Ltd (“RBUK”), and agreements for the sale of Superdry’s intellectual property assets, including the SUPERDRY brand and related trademarks (together, the “South Asian IP”) in India, Sri Lanka, and Bangladesh (the “Territories”) to the joint venture vehicle (together, the “Transaction”). RBUK and Superdry will own 76% and 24% of the joint venture vehicle respectively.
RBUK is held by Reliance Retail Ventures Limited (“RRVL”) through its subsidiary Reliance Brands Limited (“RBL”), Superdry’s exclusive franchise partner in India since 2012.
The consideration for the sale of the South Asian IP is £40.0 million, which is estimated to result in Superdry receiving gross cash proceeds of £30.4 million (approx. £28.3 million net of fees and taxes).
https://www.investegate.co.uk/...
Really don’t get this! Why don’t they just buy a huge chunk of the business and essentially take over the whole enterprise?
What they’ve paid isn’t far off the market cap
BBC News - Petrol prices rise for fourth month in a row - RAC
https://www.bbc.co.uk/news/bus...