Small Cap Value Report (Weds 5 Aug 2020) - LGRS, LSL

Good morning, it's Paul here with the SCVR for Weds. Please see the header for trading updates & results that I'll be looking at today.
Today's report is now finished. There's very little small caps news today.
As usual, this is initially a blank post (which we call a placeholder), for you to add your comments from the 7am RNS releases.
Top Tip - if you set a friend/family/your landline as emergency contacts on your mobile, then if an honest person finds your phone when you lose it, they can contact your emergency contacts when not possible to unlock the phone. Struck me as a good idea, so I'm passing it on.
.
Loungers (LON:LGRS)
Share price: 107.5p (pre market open)
No. shares: 102.4m
Market cap: £110.1m
Loungers, the operator of 165 neighbourhood café / bar / restaurants across England and Wales under the Lounge and Cosy Club brands, announces the following update.
- All 165 sites now open
- LFL sales from re-opening (4 July) to now (2 August) slightly negative, at -1.7% - this is really impressive in my view
- Nothing said re costs, profitability, or liquidity
- Fuller guidance to follow in late Sept, with full year results (19 April 2020 year end)
My opinion - this update is light on information, but the LFL sales number is the key one, and that's remarkably good. Given all the distancing restrictions, and lower footfall, to be delivering sales only a whisker below last year, is really outstanding. I see this as strongly bullish for the share price. It's a pity then that it's so illiquid.
There's a very helpful update note on Research Tree, which puts today's news into perspective - namely that LGRS is trading way ahead of industry average data of c.30% minus LFL sales. It benefits from having off-pitch sites, in suburban locations, rather than town centre sites. Also it points out that LGRS sites are outside London, and transport hubs. Therefore its community sites might be a beneficiary from work from home, and benefit from lack of competition.
Overall, very positive. However, the downside risk is that bars/cafes could be forced to close again, as we're seeing in some countries abroad. Therefore I can understand why many investors just want to avoid this sector altogether. My sector expert tells me that Loungers management are the best in the business.
.
.
Lsl Property Services (LON:LSL)
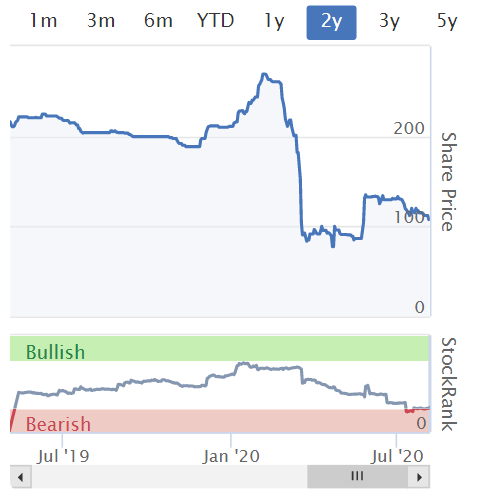
Share price: 209p (up 2.5% today, at 10:53)
No. shares: 102.7m
Market cap: £214.6m
This is a chain of estate agents, surveyors & financial advisers. It's reporting today on H1 2020, being the 6 months to 30 June 2020.
The heading sounds too good to be true, so I'll do some digging to verify this;
LSL reports Underlying Operating Profit 3% ahead of 2019, with strong trading in June and July following resilient performance during the Covid-19 lockdown
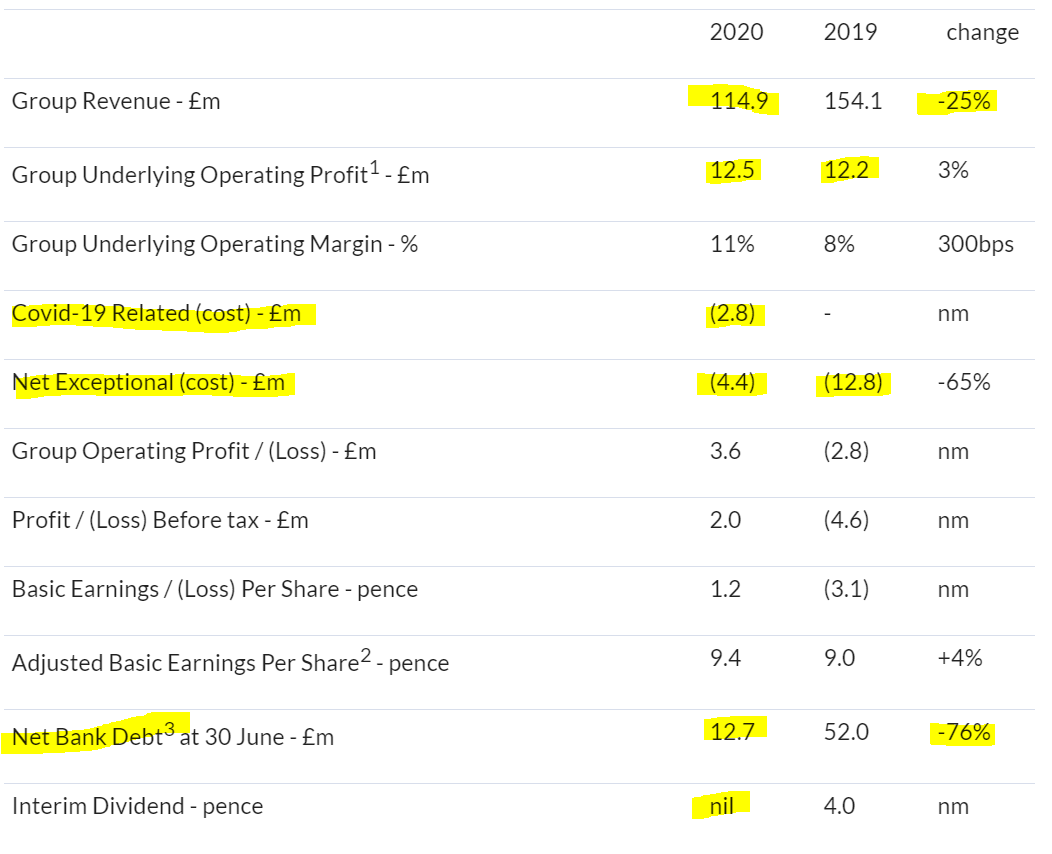
Here is the highlights table, with my comments below;
.
.
How come underlying operating profit is up 3%, if H1 revenues are down -25%? As footnote 1 explains, it's because £13.8m income is included from the furlough scheme, plus a load of other costs are stripped out;
1 Group Underlying Operating Profit is before exceptional costs, Covid-19 related costs, contingent consideration, amortisation of intangible assets, share-based payments and includes £13.8m of amounts receivable pursuant to the Coronavirus Job Retention Scheme and utilised to pay employee salaries for those placed on furlough (as set out in Note 6 of the financial statements). Segment Underlying Operating Profit is stated on the same basis as Group Underlying Operating profit.
Therefore I'm largely taking these H1 figures with a pinch of salt. It's not reflective of how the business would operate normally, hence best disregarded in terms of how we value the business on future performance.
Current trading/outlook - of more importance. More evidence that the Stamp Duty holiday has turbocharged the property market;
Current trading conditions are extremely encouraging, with strong front-end metrics in all three divisions. The introduction by the Government of a Stamp Duty Holiday for properties up to £500,000 is expected to provide further support to the principal markets in which the Group operates.
Further out, the company refuses to give guidance, due to uncertainty over covid. Although the Directorspeak sounds bursting with confidence, so a bit of a mismatch there. I really think companies should be resuming guidance now, it's been too long to opt out of informing investors about the future prospects. There's no reason at all why companies cannot give 3 scenarios, depending on how the future virus develops. Many have adapted to working from home, etc, so even if we have a bad second wave, then companies should be able to tell investors how that would impact their results. It's not right to leave investors completely in the dark, after all they own the business! Edit: I've just found the going concern note, which does give scenario planning details, and saying there would be at least 12 months liquidity under a negative scenario. Good stuff.
We've heard from other property companies recently, that the residential property market is recovering strongly. Although it does take time for the sales pipeline to rebuild, with enquiry to completion taking c.3 months.
Divis - no interim divi this time, but it sounds like they want to return to paying divis in future.
Net Debt - good transparency here. The reported net debt of only £12.7m (down from £52.0m a year earlier) was clearly boosted by tax deferrals. The company discloses just how large this temporary benefit has been;
Net Bank Debt reduced between the end of Q1 and the end of Q2 2020, with careful cash control and cash conservation as well the receipt of Coronavirus Job Retention Scheme payments. The Net Bank Debt position was further reduced by payment deferrals put in place to conserve cash, mainly in relation to tax payments due, with deferrals agreed with HMRC. Adjusting for Covid-19 related payment deferrals, the underlying Net Bank Debt position at 30 June 2020 was approximately £45.6m, with notional adjusted gearing2 at 1.12 X Adjusted EBITDA1, and representing a fall on the equivalent position in 2019.
That's highly material. LSL has therefore deferred £32.9m in mainly tax payments. That's all going to have to be paid in due course, with 31 March 2021 being the very latest to catch up with VAT. Hence when valuing this company, we must use the £45.6m adjusted net debt figure, and not the artificially low £12.7m net debt.
Balance sheet - it's got through the covid crisis, so how do the finances look now? Pretty awful, is my view. This is a weak balance sheet. NAV: £141.9m, but it's stuffed full of intangibles, totalling £188.4m. So NTAV is negative, at £(46.5m).
As business returns to normal, cash will be sucked into trade receivables, and more cash will disappear paying down the bloated trade & other payables, leaving it much more heavily dependent on bank debt.
Therefore, I imagine an equity fundraise is quite a high probability here. That's not necessarily a problem though. With a £215m market cap, and a hole in the balance sheet of about £40-50m by my assessment, that would only be about 20% dilution - not ruinous by any means, and if it makes the balance sheet strong enough to withstand future problems, then it's worth doing.
My opinion - the big question is how to value this share? I think it's fair to ignore 2020 results for valuation purposes, providing they're not horrendously loss-making, which shouldn't be the case here. Maybe we should look at 2019 results instead, and value the share on a moderate multiple of that? Taking 2019 adj EPS of 28p for the full year, put that on a multiple of 10-12, and we get a price target of 280-336p per share. That's usefully above today's price of 209p per share. Hence on this valuation basis, which you may not agree with, this share looks quite good value.
Although I wouldn't be interested myself, because it fails my balance sheet testing.
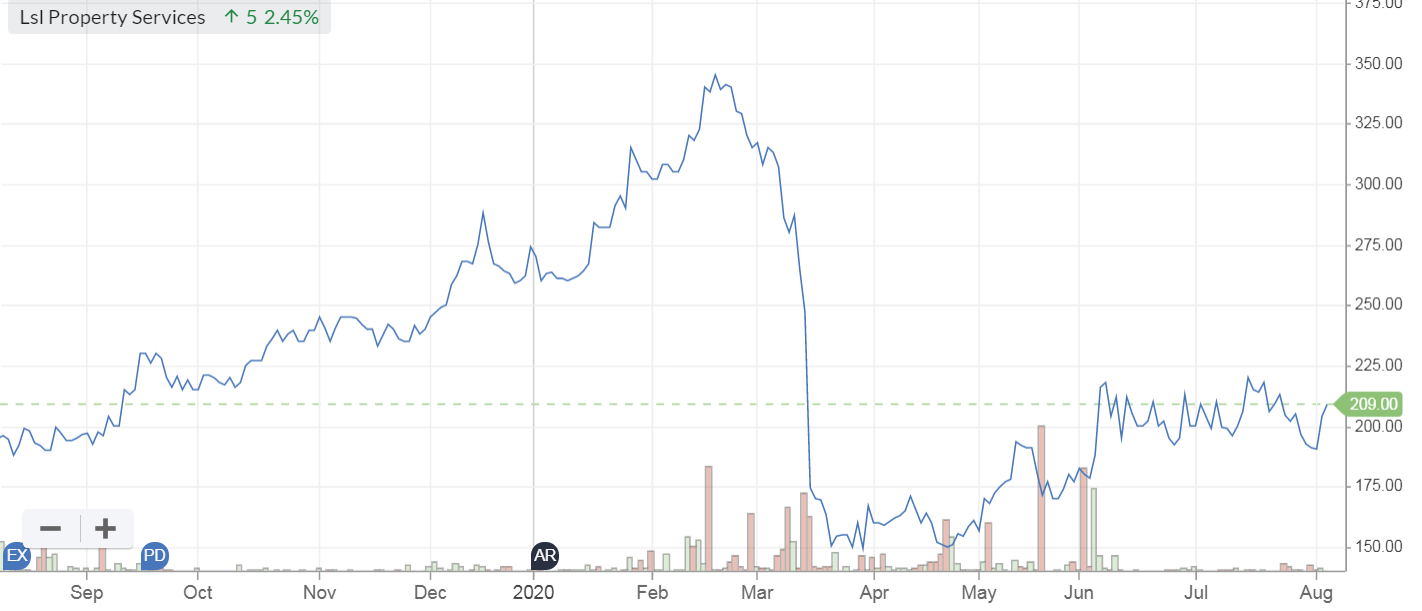
The chart looks encouraging to my untrained eye;
.
.
I'll leave it there for today, as there's very little small cap news of interest today.
I've got to pick up the XJS from the repairers, it's finally got through its MoT, and had the handbrake rebuilt, so I'll be mobile again, hooray!
See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
Don't understand the anti resource posts. If they are of no interest just ignore them don't spoil a potential debate for others. If they are small cap, released some new info, then they belong on a small cap blog, there may be a gem in there somewhere.
We all know Paul will not comment but Jack might.
Why all the nastiness all of a sudden, must be cabin fever taking over.
Id love more on resource stocks but thats not this report & hole in ground and lies spring to mind.
But .... you just have to have money in the miners as part of a balanced portfolio......
Jeremy Grantham:
Well, the long-term argument is outrageously simple and unarguable. That is, you can't have compound growth on a fnite planet. I always lead very quickly, my quick demonstraton. Just imagine that the Egyptan Empire which lasted for 3,000 years by the way, with the same religion, the same pharaohs, and the same culture, same language. For 3,000 years, let's just imagine for a second that its populaton had grown at 1% a year. The world's populaton has grown faster than that during my lifetme, when it just tripled. 3,000 years later, that multplies by nine trillion tmes, the populaton of Egypt. There would be nowhere to put them on this planet or several other planets.
Jeremy Grantham:
If you do the same with physical output, a lousy 1% a year. 1% a year increase in physical outputs. You start with enough goods to fll one of the giant pyramids. You come back 3,000 years later and you've grown at one miserable percent, breaking all the economists' heart. You have enough physical goods to fll up the solar system. It doesn't take as long as you think, to compound into craziness.
Jeremy Grantham:
You can't have compound growth on a fnite world. Very quickly, you start to run out of this, that, and the other. When I grew up we had a coal fre. Since we were kind of middle class, the coal we aforded was anthracite which is denser than oil, it's relatvely clean, hasn't got much dust. Black shiny stuf they now use for jewelry sometmes. It's gone. It was burned enough in our North Country, England freplace in 1944 and it's now disappeared. It's all been used up. It happens. Most of the high-quality coal in the UK which drove the Industrial Revoluton has gone. The same in Germany. Their high-grade coal has simply disappeared.
Jeremy Grantham:
You develop the cheapest, shallowest, thickest ore mines frst, and every succeeding mine has lower quality ore. The copper mines today have 10% of the ore that you could fnd in 1900. It contnues as far as the eye can see. Each generaton of mines is lower quality. In the case of oil, a deeper, and ofshore, and more technical. In the case of fracking, you've had to develop ways of using energy to squeeze the solid rock into giving up its oil. That's the way it always goes, untl eventually the cost and the energy cost of getng that low-grade copper ore from a deeper and deeper mine, and shipping it around in these trucks where the wheels are bigger than a house, is simply too energy-intensive
Worth a read http://investorfieldguide.com/wp-content/uploads/2020/06/Jeremy-Grantham-Edited-Transcript.pdf
Just published Panoply Holdings (LON:TPX) FY20 results presentation, by Neal Gandhi, CEO & Co-founder and Oliver Rigby, CFO & Co-founder
Revenue up 43%. Normalised adj EBITDA +62%.
Moved to £2.7m profit (FY19: -£0.2m).
Ajd diluted EPS 3.6p.
Cash conversion 91%.
Sales backlog at 1 April 20 £15m (to March 21).
Video or podcast
Separately, we have a piworld webinar tomorrow:
Just published Nwf (LON:NWF) FY20 analyst presentation, given yesterday, by Richard Whiting, Chief Executive & Chris Belsham, Group Finance Director. A strong set of results ahead of expectations.
Video or podcast
Separately, we have a piworld webinar tomorrow:
LSL Property Services (LON:LSL)
Fantastic post on this company Paul - bit of benchmark analysis here that illustrates just how hard it is at present to get any handle of anything financials wise. As you mention it really doesnt help that companies are refusing to even give us billy basic forecasts for current year as thats exactly what we need with the current updates being so confusing number wise . Billy basic 3 scenarios for profits pre exceptional and post exceptional - ie range between a and b like next (bring back fyffes who also did that nicely) . Or even worst case scenario as things stand with roiom for upside.
Any first year finance trainee at any company should be able to knock up something that can easily be monitored / revised and then market updated as appropriate. It should be communicated to FD's that forecasts are only that and may not be accurate and if they swing materially in short space of time thats not a bad reflection on them under present circumstances I.e they shoulnt be scared to try just because the numbers are hard to forecast. Perhaps CEO's need to be pressed to press their FD's to earn their big bucks :)
thankfully ref LSL Property Services (LON:LSL) they have gven some extra useful info - will most companies go to this trouble? i doubt it. Unfortunately now i am past the 50 mark it starts to hurt my head when there is too many adjustments to adjustments to remove this add that back in and work out how that impacts cash - hopefully you have a nice limoncello sprizter or similar to get you through the day.
.
Hi Lee, I'm not sure you are aware that the SCVR covers small caps and rarely (unless Paul is not writing it) commodities or mining stocks.
Probably frustrating for those who would like these sectors covered but as Paul says, he already covers over 500 stocks in traditional businesses.
Furthermore, I expect you will get a few thumbs down because frankly your post feels 'rampy'. People here are (probably) experienced enough to know what is going on with gold and silver, they certainly don't want to be told not to hold stocks (that's why they are here) and the last thing people like is others crowing about their amazing successes in commodities which, as I say, are not covered here.
cheers
Francis
EDIT: I see Lee has now deleted his post so my reply probably makes no sense at all!
I saw Lee's post Francis and I agree with your comments. I'm sure readers will get the gist of it from your response!
It was merely to highlight the opportunity. I don't see many in the UK market at the moment. Clearly if you don't wish to make big profits in another area then that is your call.
Didn't wish to offend and certainly wasn't ramping. Intended as something for people to look at.
In all fairness, other than the rampy aspect to the post (which we do see from time to time as people enthuse on all sorts of stock sectors, some of which sectors appeal to some of us, some of which don't), there shouldn't be any harm in asking.
This is as we know not the place to be expecting resource stocks to be covered - fair enough to Paul and the occasionals since they have expertise in other areas and already cover a vast portion of the market; it wouldn't be fair to ask for more on this report.
I would be delighted to see some commentary on resource stocks via another "Report" series if at all possible;
We all know that gold is the buzz word on the street at the moment, however with recession and recovery battling it out there are likely other resources that will be worth a watch for the future and will still make a good investment - I'm sure a good number of us here hold some stocks of this sort and would welcome the opportunity to have commentary of the quality we do here.
I for one don't mind the enthusiasm and people having a "high five" when having a big win...even though this actual column does not cover commodity stocks there are other writers on here that do.
Gold is currently above $2050 and all the "gold bugs" are coming out into the sunshine from the bleak winter when gold was ridiculed as much of an investment and saying "told you....its our day". Many of us here have a few dodgy gold stocks tucked away I am sure and have forgotten about them as losing investments. Now we can dust them off and congratulate ourselves on our "shrewd investment". Early this year I wondered how stupid I was to have paid so much last year for a tiny Australian miner Thor mining. Today as I cashed some in for a thumping profit it did not seem quite so much of a high price after all. Have to laugh at yourself sometimes .....
Thanks. I deleted as did not want to offend/ get thumbs down. It was meant to start a discussion! Of course I got a bit gung ho with the post so apologies.
Thanks - did not mean to be rampy. Just trying to help out!! With gold at an ATH there is hardly any coverage. There is also the wider issue of the Fed (and other central banks) destroying the economy in my opinion.
Hi Lee,
Please don't be discouraged posting here. It was neither 'rampy' nor unwelcomed. I am very interested in this part of the market as well.
My grandpappy use to says 'only gold and land have any real value'. Gold has definitely kept its value over 400 hundred years so maybe he was right. Worth having some exposure in these times.
Kind regards
BSV
Wise words and thanks!
Surprise news from Innovaderma (LON:IDP) that their CEO, Kieran Callan, is stepping down with immediate effect and the Chairman is taking over while they look for a new CEO. "He is thanked" as MrContrarian would say, but it's clearly unplanned. This does not do much for continuity:
The announcement makes much of the internal promotion of the Group Financial Controller to CFO, which at least suggests there have been no financial surprises. Reading between the lines it sounds more like a disagreement over strategy.
SP is down 7% which is an understandable reaction and good value at that level, in my view. The track record of Innovaderma (LON:IDP) of year-on-year growth in sales is continuing (most recent TU was on 10 July), it has demonstrated its ability to innovate and it has a well-established website that accounts for a good proportion of sales. I think a competitor might buy it, it would be a good bolt-on acquisition for a personal care products or cosmetics business. I hold.
It's interesting that an individual, Mark Ward, has been buying shares recently and now owns 10.9% of the company. (last holdings RNS 31 July) There has been speculation on other share boards about who Mark Ward is but no details from the individual or the company.
I thought Kieran Callan had bought some stability to the company so surprised by the announcement. There have only been 8 trades today, so far, so no current rush to sell on this news.
Ecsc (LON:ECSC) ( a UK based cyber security firm, with two arms - one managed services, that is 3rd party management of cyber defence, inc incidence response andthe other a cyber security consulting business) had an H1 trading update today which said the show was still on the road. ( I hold). The cash position looks moderately comfortable (although flattered by Government schemes) and at the dreaded adj EBITDA level, the business is once again mildly profitable.
This is a share which has got minimal coverage here, probably because of its tiddly size (<£10m market cap), low liquidity, its poor share price performance over the years since IPO and the boardroom bust-up a couple of years ago, which saw founder and CEO Ian Mann resign, only to be reinstated shortly afterwards.
There was a £500k capital raise at 55p, in the height of the Covid first wave, which with hindsight may have been unnecessary.
Today’s update shows revenue flat with H1 2019, which itself was weak - with H2 2019 much stronger when the consulting side recovered. H1 2020 has seen weak consulting understandably, as it often means needing to visit a clients’ premises. Consulting is still key to ECScC as it is a path for future managed services clients.
I hold as I feel the stock is in an interesting space, which could benefit from home working (more worries about cyber security) and the company has significantly reduced cash burn and the managed services business should have operational leverage as it grows.
DYOR
I went out to dinner in Crouch End last night, the area was buzzing and most venues busy, especially for a Tuesday night. I think the £10 off deal could be self funding in higher cost areas like the south east. No listed operators but clear that well run establishments will get through as long as no reversal of lockdown measures.
The Loungers LFL numbers seem almost to be good to be true even given their logistical advantages. Time will tell.
Not share related but Crouch End has a great Lido AND its open !
Thought it was time to venture out last night so took myself off to the RBG in Cambridge to see how they are getting on. Lady on intros was very open "doing a lot better than expected." She showed me reserved tables. In Cambridge 3 floors top floor a sort of disco so that is out but on both the other two floors it was more than 50% booked. I counted on the ground floor whilst I was there an average of 47 people in the room over a couple of hours. Given I ordered a pint of Camden Ale and a bottle of Peroni and it cost £10.90 so 3 rounds cost £31. The average spend in there would be well beyond that given next to us was a group of 5 lads drinking cocktails at £8 and £9 a shot. In the corner a group of 6 girls also drinking cocktails. Quite a lot of 2s eating. Overall quite a positive experience and I would say they are making a profit given had 5 staff I counted on last nights evidence. But hey it was a boring Tuesday night!! Anyway if anyone else has a local RBG I would be interested to hear your experience.
What!! 11 quid for a pint and a bottle? Come on over to Scunthorpe and you’d get change enough from a fiver for a taxi home as well.
I was brought up in Pocklington Robert. Fish n Chips, a pint and a trip to the cinema those were the days!! I have to say though as a shareholder I don't feel so bad paying the exorbitant price. I will warn my lad off RBG when he comes of age (but then we know how much good that will do!)
Hi Camtab, how interesting, thanks for posting.
Obviously Revolution Bars (LON:RBG) has been a disastrous investment for me so far, but the original investment case was entirely logical & correct - the business was turning around into positive LFLs, and modestly rising profits, driven by refurbs with a high ROI. So I'm not beating myself up about it at all, because my rationale for investing was correct. Covid was the unforeseen factor which smashed up RBG's business model, and caused the share price to crash.
Your post reminded me of a Zoom that I had with RBG mgt a little while ago. They admitted that the business had become too reliant on Fri & Sat late night business, which is very lucrative, and had become too complacent about the daytime trade. Under covid restrictions now, they're not doing the late night trade any more, but are opening conventional pub hours, closing at 11pm (presumably so that the sites are classified as pubs, and not nightclubs which face more restrictions).
The CEO indicated that he saw it as a potentially useful long-term move, to really crack the daytime & early evening trade, then once covid is history (hopefully), the late night business can be bolted back onto a much stronger daytime business.
Most Revs sites are large, which makes social distancing much easier.
We'll have to wait for the next update, but in my view the business has a fighting chance to get through this crisis. The placing & extended bank facilities give it cash runway into about Q2 of 2021.
Worst case scenario is a second wave of covid, and rampant well into 2021. In that scenario RBG would need another placing, we've got to be realistic about that. Maybe even a prepack admin? But in anything less severe than that scenario, I think the future looks OK.
In an upside scenario, e.g. if the Oxford/Astrazeneca vaccine is as good as hoped, then the stock market would go crazy for category 3 shares like this one, restaurants, cinemas, etc, and price-in a full recovery of trading well before it actually happens.
Risky no doubt about that, but there's a chance the bold (or foolish!) could recoup a lot of our losses on stuff like this.
Regards, Paul.
Thanks for your comment. I'm in the foolish category Paul. That said if we get a 15min antigen test at a price the consumer can work at and tie that to a passport I think it will provide a filip. My investigations suggest scientists think a vaccine is likely to be back end of 2021 (although I am sure they will improve on this). That said I wouldn't participate in the Russian option although I suspect they don't have mush choice!!
This article on the BBC (of which I am not normally a fan) is much more rational as to where we might well be:
https://www.bbc.com/news/healt...
Regards
Michael.
Saw that and surprised it was fairly balanced, and a slightly less heated view of the 'facts' or such facts as we currently have
The point that the recent rise is, overall, statistically insignificant is fair (though that is certainly not the case in some localities), but the article ignores the issue that cases in the UK levelled out well above zero at the end of the initial stages of lockdown. Lockdown was eased in the UK at infection levels well above those in most other European countries, and as restrictiions are eased there is no likelihood of them falling further, and real risk of significxant rises. That is very concerning as we approach autumn and winter, with people spending far more time indoors and the probability of other infections like flu spreading, and hitting health care capacity.
The possiblity of much higher levels of infection under those circumstances is very real. And we may well need to see ongoing and more widespread and stricter local or specific restrictions which will continue to cause problems to many sectors of the economy. There is a clear argument that stronger action earlier, and not relaxed as quickly may in the end have reduced economic damage.
Not a great beer drinker and no fan of J D Wetherspoon (LON:JDW) but surely clientele prepared to pay Revolution Bars (LON:RBG) prices are a small target market. Particular when J D Wetherspoon (LON:JDW) is describing Rishi Sunak as a ‘legend’ and consequently advertising beer at less than £2.00 a pint.!!
I think it's worth taking another look at ALM Paul, Allied Minds. The old board have been cleared out a while ago. The new board are doing what they say:- returning value to investors. Today's RNS they have sold their stake in TableUp for a decent return. awesome considering the current economic situation.
Hi PDiddy,
I saw the RNS from Allied Minds (LON:ALM) today, but thought it looked fairly immaterial. Although it did arouse some interest, because the deal seems to be not dissimilar to the space that one of my largest personal holdings operates in, Bigdish (LON:DISH)
I generally don't cover investment companies, because you have to value them on a sum-of-the-parts basis, drilling down into what speculative valuation you might put on each investment. That's not feasible for me to do here, as it's so much work. Hence why I tend to focus on conventional trading companies, where I can fairly quickly assess & report on their performance. I'm covering something like 500 companies, so clearly that means I have to pick the fairly straightforward ones, not special situations that need a ton of work!
Sorry about that.
Regards, Paul.
ok cheers for the comments Paul can definitely see your point. I had a good read of Simon Thompson's article of IC which was only last week and his crystal ball seems to be coming true on this one.
Phone Emerg Contacts : Good Call! (Not that easy to find tho...on my Samsung its PHONE>CONTACTS>GROUPS>ICE emergency contacts> then add the number or use the suggested contacts.
Loungers (LON:LGRS)
Is this LFL on last year, not clear ? If so these are surely to bounce higher this morning, been trending down?
Like for like sales have been -1.7% over the period from 4 July, when our phased re-opening commenced, through to 2 August. Whilst these are still early days, we are encouraged by the initial strength of our trading performance to date and remain confident the Company will emerge strongly from this period.
LFL sales are always this year vs last year sales.
LFL sales is worked out on a site-by-site basis, weekly, then aggregated. So sites that were trading this year, and in the equivalent week last year, are the only sites which are included in LFL (like-for-like) sales figures. In this way, the effect of new site openings & closures is stripped out, to give the underlying performance of the business, in revenue terms anyway.
Thanks for clarifying that Paul, those loungers results then are extremely good, just as well a lot of commentators on here ‘im never going out again’ are as suspected, not the majority, so far! And bounce those shares did!
My morning smallcap tweet:
Yourgene Health (LON:YGEN) EKF Diagnostics Holdings (LON:EKF) Eden Research (LON:EDEN) Loungers (LON:LGRS) Iconic Labs (LON:ICON) Falanx (LON:FLX) ECSC (LON:ECSC) Mediazest (LON:MDZ) LSL Property Services (LON:LSL)
Yourgene (YGEN) £16.15m placing at 17p, a 3% discount.
EKF Diagnostics (EKF) wins £3m order for PrimeStore MTM, a novel patented sample collection device, to be used in a COVID-19 testing programme for UK staff. Also bungs exec directors £237k each.
Eden Research (EDEN) gets Greek authorisation to sell Cedroz pest control bionematicide.
Loungers (LGRS) LFL sales -1.7% since 4 July reopening. All sites open but one.
Iconic Labs (ICON) ultra-tinpot wins £150k contract for social media content.
Falanx (FLX) guides FY(Mar) rev up 11%. Recent Q1 rev up 5%. Increase in sales has continued into Q2.
ECSC (ECSC) guides H1(June) rev flat. Adjusted EBITDA into profit (not specified) from a small loss.
MediaZest (MDZ) ultra-tinpot places £150k convertibles with strike of 0.01p. Yes, 10 milli pence, an 80% discount. CEO 'delighted'.
LSL Property Services (LSL) H1(June) rev down 25%, adj EPS 9.4p (9p). No div. July trading is 'extremely encouraging'.
Hi HollandSmith,
Many thanks for your helpful lists.
I wonder, is there any way you could add a market cap column, and sort the list by descending market cap? MrC worked out something like that a while ago, and it was really useful for me in particular, as it helped me quickly identify the small caps, and ignore everything else.
Best wishes, Paul.
I added the share price and cap to my Tweets but forgot to make the change here. Will appear from tomorrow.
Good shout! Consider it done. :)
Thanks for adding the column HollandandSmith this is really helpful!
good effort, I do like the StockRank column
I preferred your format with a brief extract from the RNS, since it is more differentiated from the Investegate offering.
However, it must also be said that both McContrarian and HollandSmith have formats which are useful and therefore infinitely better than that currently offered by the London Stock Exchange website.