Small Cap Value Report (Weds 6 Oct 2021) - LOOK, NET, MMH

Good morning, it's Paul & Jack here with the SCVR for Wednesday.
We'll leave it there for today. I hope subscribers are not getting too despondent about the damage to our portfolios in this current sell-off.
Agenda -
Paul's Section:
Lookers (LON:LOOK) - Q3 update - the good times continue to roll. Despite a huge fall in volumes of cars sold, high margins mean that FY 12/2021 profit expectations are "materially" raised. Zeus upgrades by 34%! Remarkable stuff. The party has to end at some point, but car dealers are becoming more valuable by the month. They're on very low earnings multiples still.
Marshall Motor Holdings (LON:MMH) - another car dealer, with a similar story - bumper Q3 profits due to profit margins rising more than enough to offset lower volumes. Profit guidance upped from >£40m, to >£50m. Sees no immediate end to extraordinarily inflated used car prices. Similar valuation to LOOK, so an interesting value share. Bear in mind that profits will probably at least halve in future, once things normalise.
Jack's section:
Netcall (LON:NET) - provides software solutions to customers with large, complex ecosystems in the financial services, healthcare, and public sectors. The trading momentum looks good and it could be that the group is approaching an inflection point, but the valuation looks full.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Lookers (LON:LOOK)
60.7p (pre-market open) - mkt cap £238m
Lookers plc, one of the leading UK motor retail and aftersales service groups, today provides a trading update covering the three month period ended 30 September 2021 ("Q3" or the "Period") and an increase in the Board's expectations for underlying profit before tax for the full year.
Strong performance in challenging conditions and increase in full year expectations
Just to make sure we get the point, they tell us twice at the top of the announcement!
I enjoyed the interesting discussion we had yesterday about new & used car sales, supply constraints (due mainly to semiconductor shortages), and electric vehicles. Some readers reckon that generating enough electricity for all these EVs won’t be a problem. Good luck with that. I’ll believe it when I see it, given this country’s tendency to mess up things like that.
Probably like a lot of other subscribers here, I’ve got an EV on order. Much though I love conventional cars (especially classics), now that we have the technology to avoid pumping filthy fumes into the air, we really should adopt it where possible. Something like 30-40% of the UK’s electricity now comes from wind turbines, so the argument that you have to pollute at power stations, in order to generate the electricity for EVs, is not true any more.
Totally bizarre and “unpredented” (CEOs of both Vertu Motors (LON:VTU) (I hold) and Lookers (LON:LOOK) have used this word in quotes) conditions in both new and used car markets continue.
This is what Lookers says about Q3 (July-Sept 2021) -
Supply shortages led to higher margins
Strong demand for used cars
UK new car market declined 31% in Q3
Lookers outperformed by 3.4%, implying it was down c.28%
(it’s not clear if this is a decline by value, or volume? I assume it’s probably by volume of cars sold. The decline by value might be less, because I’ve heard that manufacturers are prioritising production of higher value/profit cars over cheaper, lower margin production)
Supply of used vehicles also restricted
Used vehicles LFL unit sales down 16.9% in Q3
Volume drop more than offset by higher margins (reinforcing the point I made yesterday)
Unprecedented conditions
Aftersales revenue holding up comparatively well, down only 3.5% on LY
Net cash of £30.0m - a big improvement on net debt of £25.9m a year earlier
CJRS (furlough) received of £4.1m this year has been repaid
Electric vehicles are popular
Outlook -
The Group has a strong new car order bank which is above normalised levels. However there remains material and increasing uncertainty as to the availability of these vehicles which is dependent on specific brand and model related factors. The Group continues to work closely with all its OEM brand partners and customers to minimise the impact wherever possible, which is now widely expected to continue into next year.
Notwithstanding this considerable uncertainty for the final quarter of the year, given the strength of performance in the Period, the Board now expects underlying profit before tax for 2021 to be materially ahead of its previous expectations.
Electric vehicles -
Interest in electric vehicles continues to grow, particularly in light of the UK wide fuel shortage, and the Group remains well positioned to benefit from this exciting growth opportunity moving forward.
Broker update - many thanks to Zeus for issuing an update note.
It’s a massive upgrade (given where we are, ¾ of the way through the year - FY 12/2021 PBT (underlying) is upped by 34% to £81.4m. That’s a staggering number for a company valued at only £238m, and with net cash.
Forecasts for future years are left “unchanged for now” - which hints at possible future rises maybe?
In EPS terms, FY 12/2021 is now forecast at 16.7p, so at 60.7p share price, the PER is 3.6!
Obviously there’s a catch. Everyone knows that current highly profitable market conditions are a one-off, of unknown duration.
Therefore, when valuing car dealers, it makes sense to use more modest future earnings expectations. In this case, Zeus has EPS dropping from 16.7p this year, to 10.9p next year & year after. Nobody really knows, because we don’t know when supply of vehicles is likely to normalise.
EPS of 10.9p would raise the PER to a still tiny 5.6
My opinion - I can’t remember ever coming across a situation like this.
Investors have assumed that supply constraints would damage car dealers, but the opposite has happened. Strong demand, combined with limited supply, has driven up prices, and profit margins. Remember when supply is plentiful, car dealers only scrape off a small profit per car. In current conditions they seem to be able to name their price, and customers pay up.
Even when market conditions do normalise, this bonanza period now will leave a permanent strengthening of dealers balance sheets. Remember that the balance sheet grows each year by the same amount as retained profit (after tax) on the P&L. That’s the way double entry bookkeeping works. This opens up the possibility of future enhanced divis, buybacks, etc. Vertu Motors (LON:VTU) (I hold) has done buybacks in the past, and I would like to see it use some of the cash pile to do more aggressive buybacks now it must be trading at below 1 times NTAV.
Car dealers also have big freehold property assets too.
There’s a lot to like in this sector in my opinion. There must be takeover activity rumbling away in the background too. Those balance sheets groaning with freeholds (and now cash too) won’t escape the attention of private equity forever, in my opinion.
Fascinating times. We all know the party’s going to end at some point, but when, and how much cash will the dealers have accumulated when the good times do come to an end? The value of these companies is rising with each month of bumper profits that passes.
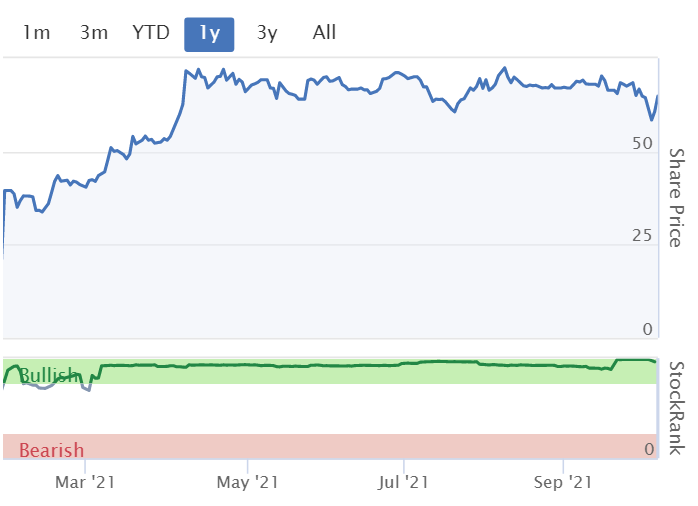
StockRank is consistently very high -
.
Marshall Motor Holdings (LON:MMH)
221p (up 6.3% at 08:54) - mkt cap £173m
Another car dealer reporting. Marshalls is about ¾ of the market cap of Lookers. It’s handy when companies in the same sector report on the same day, maybe there could be a bit more co-ordination, as it helps investors focus on that sector & make comparisons whilst it’s fresh in our minds.
Ha! I see that Marshalls also tells us twice that it’s doing well. Maybe these RNSs are written by a descendent of Fred Elliot?! -
Trading Update - further increase to FY2021 expectations
Marshall Motor Holdings Plc, one of the UK's leading automotive retail groups, provides the following trading update and announces a further increase to its full year expectations for 2021.
My summary of today’s update -
Old guidance (August) - FY 12/2021 profits >£40m
New guidance (today) - FY 12/2021 profit before tax >£50m
New vehicle supply has deteriorated in August & Sept, and expected to continue “through 2022” (ambiguous - does that mean into 2022, or for the whole of 2022?)
Customer demand & orders are strong, but delivery times “significantly extended”
Marshalls says it outperformed new car market by 13.0% in Q3 (much better than +3.4% indicated today by Lookers), and 11.6% YTD
New cars - “... exceptionally strong new car margins as a result of supply shortages which has offset the impact of reduced volumes”
Used cars - the same situation - “Exceptionally strong margin performance in used cars in Q3 2021, more than offsetting a decline in volumes”
Outlook - this is important, suggesting no immediate end is in sight for bonanza profits, driven by strong demand and supply shortages.
However, the scale of the rise in used car prices is clearly absurd, and can’t possibly last -
… the impact of any downward price realignment in Q4 2021 is not anticipated to be significant. In Q3 2021, used vehicle values rose by an average of 12.7%*. This was the seventh month of consecutive growth in used vehicle values and over this period, used vehicle values have appreciated by 26.3%*; an unprecedented position.
Valuation - good old Zeus are being super-helpful today, with an update on this one too. It’s upgraded FY 12/2021 profit to £52.1m, up 24% on previous forecast.
That equates to 51.1p adj EPS, for a PER of 4.3 - similar ballpark to Lookers.
There are no forecasts from Zeus for 2022 or beyond as yet.
Interestingly, the analysts Mike Allen and Rachel Birkett comment -
… we do not see used car prices coming under pressure during the foreseeable future.
That’s important for valuations, and is a significant change today from what has been said by car dealers in the recent past.
My opinion - there’s not a lot to add, this update is very similar to the one from Lookers. The main difference seems to be that Marshalls (13%) is much further ahead of Lookers (3.4%) in outperformance against industry data on new car sales volumes.
Both Lookers and Marshalls are raking in spectacular profits, due to extreme market conditions (very high margins on new & particularly used) car prices, due to supply shortages.
Investors are sensibly treating this as a one-off, although I think valuations now look so low, that I’d say there’s scope for another decent leg up in prices across the sector.
Plus investors should be in line for bumper divis/buybacks and maybe takeovers in 2022. It’s certainly an interesting sector for value investors right now. Do bear in mind though that profits are not sustainable at this level in the medium, let alone longer term.
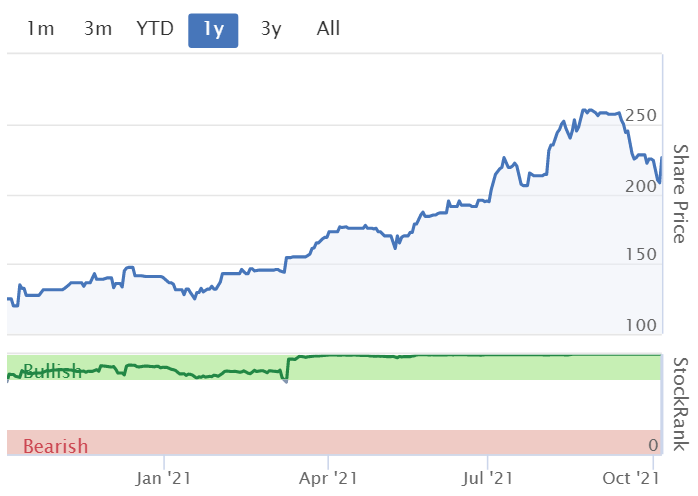
Note the StockRank is jammed on maximum -
.
I've shortened the usual 3-year charts I tend to use here, to just 1 year (above), so that today's fairly big price rise shows up clearly.
Jack’s section
Netcall (LON:NET)
Share price: 81.56p (-4.61%)
Shares in issue: 149,020,267
Market cap: £121.5m
There’s been some share price recovery at Netcall, which has more than trebled in value since its 2020 lows. The StockRank has also improved markedly, and the group is now firmly in ‘High Flyer’ territory with Quality and Momentum Ranks of 94.

And, while the forecast rolling PE ratio looks very high at more than 50x, the trailing twelve month free cash flow measure is far more reasonable. So whether or not the shares are good value depends on which of these metrics - earnings or free cash flow - are more representative of Netcall’s economic reality and future earnings power.

The group provides omnichannel messaging and contact centre solutions and ‘takes the pain out of big change projects’ for over 600 organisations in financial services, insurance, local government and healthcare.
Its Liberty Platform aids companies’ customer-facing and IT teams to implement changes and solve operational issues without embarking on costly and complex transformation programs.
This platform is built around two areas:
Intelligent Automation: low-code software solution enabling customers to automate workflows and processes, plus an ‘AI-powered robotic process automation solution’ that can act as a personal assistant of sorts to contact centre agents.
Customer engagement: an omni-channel contact centre solution for customer engagement including automated speech bots, plus a cloud messaging and bot platform that can be used across social media.
Netcall’s focus is primarily on sectors characterised by large, complex ecosystems of customers, suppliers or staff, which are often subject to high levels of regulation. The three largest are healthcare, public sector and financial services.
These three core market segments continue to see significant new demand and today represent 85% of group revenues.
The top line gapped up in 2018 (thanks at least in part to a c£11m acquisition by the looks of it), so it looks like there is demand for its services.

Highlights:
- Revenue +8% to £27.2m,
- Cloud business revenue +26% to £8.3m,
- Total annual contract value (ACV) +10% to £18.5m (30 June 2020: £16.8m),
- Cloud services ACV +25% to £9.4m,
- Adjusted EBITDA +21% to £5.34m and profit before tax +98% to £0.99m,
- Group cash up from £12.7m to £14.5m, offset against £6.86m of borrowings (up slightly from £6.75m),
- Final dividend of 0.37p, +48%.
ACV is the total of the value of each cloud and support contract divided by the total number of years of the contract.
Netcall notes the significant growth in cloud business, which now contributes over half of total ACV and improves future revenue visibility. There have been new customer wins across several verticals, including Financial Services, Utilities, Healthcare and Public Sectors. The cloud net retention rate increased from 113% to 116%, which is very healthy and confirms a growing business.
Furthermore, there’s been ‘continued cross-selling success’ with 22% total ACV from customers who have purchased both Intelligent Automation and Customer Engagement solutions, and the group notes ‘increased momentum’ in customer migrations from on-premise to cloud solutions (a favourable dynamic leading to higher quality revenue and earnings).
You can see this migration to Cloud in the following table:

Netcall points to a ‘significant increase in profitability’ but the PBT figure is still very low at less than £1m, especially against a market cap of c£121m, so against all the good news is still the question of whether or not the shares are good value.
Gross profit margin is very high, up by 2% to 90% (FY20: 88%) mainly due to higher margin media channels driving revenues within Communication services.
And the group is cash generative: cash generated from operations was £5.69m (FY20: £9.39m), or £6.72m (FY20: £7.18m) after adjusting for the effect of a VAT deferral scheme and a recent acquisition.
Balance sheet - some 58% of the £51.8m total assets is made up of intangible assets, although a further 28% is cash (£14.5m), set against current liabilities of £18.8m. Net assets are £24.6m but net tangible assets are therefore negative at -£5.5m. The group’s cash generation characteristics are an asset in this regard, so perhaps it can justify a lighter balance sheet but I’d want more security here at the current price.
Outlook
The Group's target markets represent a substantial and growing opportunity with our Liberty platform being well positioned to support customers' digital transformation strategies. Our growing cloud business is delivering enhanced profitability and revenue visibility which, combined with our product innovation, produces new growth opportunities. This, combined with a robust foundation of recurring revenues and a cash generative business model, provides the Board with confidence in the Group's growth prospects.
Conclusion
These come across as good results and there’s positive momentum in the 116% retention rate, conversion to cloud and accelerating ACV rates, and new customer wins.
How much business can Netcall win? With less than £1m in PBT for a market cap of more than £121m, that’s obviously an important consideration as a lot of growth is priced in. Cash generation is strong and gross margins are very high, so holders will be expecting profits to expand quite quickly.
The group’s focus is on sectors characterised by large, complex ecosystems of customers, suppliers or staff, often subject to high levels of regulation, such as healthcare, public sector and financial services. That suggests quite a large and potentially high margin addressable market.
The tricky thing about this type of company is it can reach an inflection point that drastically improves profitability. I think it’s worth investigating the scale of the opportunity and the depth of competition here for that reason, but the valuation looks pricey and I can’t see too much of an opportunity in the near term at these levels. Counter arguments regarding valuation are always welcome, of course.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

161 comments
Hi Paul and other subscribers,
Is anybody aware of the London Electric Cars Company?
I suspect that one of the things Paul likes about his Double Six is the sound of the engine. I suspect that silently gliding wouldn't quite cut it.
Their website shows a conversion to a 1993 mini - not sure I’d waste 30k of my money on that. If you’re going to convert anything it would have to be a Delorean. A car with looks but atrocious performance (60 in 9 secs), imagine a nice twin motor Tesla unit in that.
Late in the day, Gresham House announcement that they’ve picked up just under 14% of dog’s dinner Parsley Box (LON:MEAL) . Presumably they’re seeing something that the rest of the market has been missing.
https://www.investegate.co.uk/...
Still holding a few from the original IPO - not my finest stock picking moment! First thing food related I’ve managed to slim down in the past few years.
Gus.
FCCN - Paul Do I see a RNS statement on behalf of your good self on FCCN and you have exited stage left!
Hi Cleeve,
Well spotted!
Yes that's right, I decided that 29p was a good point to exit French Connection (LON:FCCN) (I no longer hold) - am happy to let someone else have the 1p remaining in the 30p takeover bid, so I can recycle the money now into something with better risk:reward - I've already put the whole lot into Scs (LON:SCS) - where I see an irrationally low valuation, bulletproof balance sheet, a 4% divi yield - likely to rise considerably in time, potential for buybacks/takeover bid, and no credible bear points at all (I've listened to, and dismissed all the negative views as irrelevant to me personally, as a long term holder).
I reckon that a higher competing bid for FCCN is probably extremely unlikely, as the business has been up for sale for years now, and nobody else has wanted to take it on. There's always the risk someone might pop up now with a blockbuster higher bid, but I'm happy to run that very small risk, and won't care even if it does happen. We make rational decisions, based on the facts, and then just live with the consequences, with no what-ifs, or I wish I hads being contemplated. It's done, ovah!
Overall, whilst 29p for FCCN is a lot lower than originally hoped for, we have had a pandemic which has destroyed many larger & better competitors. So the fact that FCCN has survived, and a bidder still sees value in it, is not a bad outcome, and sort of vindicates the bull case (of there being value in the brand, wholesale & licensing divisions).
With all the remaining risks, and supply chain problems, I think Mr Marks made the right decision to sell up.
FCCN is a good reminder that a strong balance sheet, with loads of cash, gets a business through even a multi-year downturn - it under-performed for many years, never having to dilute shareholders.
The timing was also great, as it's helped offset some losses I seem to have incurred on plenty of other shares recently - quite a nasty correction going on at the moment, so a takeover bid was most welcome.
Thank God I won't have to write about FCCN shares here ever again! Praise the Lord!!! :-D
Best wishes, Paul.
Paul you certainly have worked hard over the years for this one and I am sure it was frustrating at times but the result as you say not too bad given circumstances. As. A point of interest when you have a stake that needs to be declared is the onus on you to do that or your brokers to work it out? Thanks steve
Housebuilders are tanking but it appears the directors are starting to buy up shares at what they consider cheap prices, which is interesting.
Taylor Wimpey (LON:TW.) director just bought £100k worth
Ouch!!
Polarean Imaging (LON:POLX) has turned bolx !
my commiseration to holders. The FDA approval process is fraught with risk. I made a similar mistake with Motif Bio thinking approval was a slam dunk and they effectively went bust went it went the wrong way! At least Polarean Imaging (LON:POLX) has a decent cash pile and it appears the issues are technical and requiring clarification around manufacturing and not necessarily a problem with the tech. Damage done certainly but doesn't appear to be fatal. Not ideal on a day like today though. (no position personally but feel for those that have)
Mmm. The dreaded hand of the FDA. I'm beginning to get a bit paranoid about the FDA and wonder if large companies with current inferior techniques in similar market secgments have some lobbying influence which affects the response of the FDA to new technology which potentially offers really significant improvements in both effectiveness / health benefits/ unit costs. I can think of one or two more like £POLX but I hope I am wrong about the FDA. The trouble is that the US market is so huge that no wonder applicant companies regard it as the gold standard, and the golden key to open the golden gates!
All the way back to the Boston Tea Party. That was really about supporting smugglers profiteering not tax! And the protectionism continues. Hope Polarean Imaging (LON:POLX) find a way through
Having seen the mess with the FAA and Boeing over the 737 Max crashes I incline to the view that all of the US FxA agencies have issues with regulatory capture - being controlled by the incumbent interests that they are supposed to be regulating.
Let's see if they prove me wrong with Angle (LON:AGL)
See also the SEC, NHTSA and the Fed itself which many people have concerns about. How the recent articles about people who set the national budgets and interest rate policies effectively insider trading are mind boggling and I have no idea why it isn't a massive scandal. It's almost like the media themselves have been captured. I'm not one for conspiracy theories, but something, well a lot of things, stink.
Well I’ve been looking in from the sidelines at your comments from the start of 2020 but today is my first comment here.
Firstly a huge thanks to Paul Jack and Roland for the excellent daily SCVR which I find fascinating and useful at the same time.
I am personally seeing the current market as a tentative buy opportunity. I am not diving in but using my cash to dip my toe in the water and then my foot and possibly my calf should the price drop further. I have learnt from the past that catching a falling knife is lethal hence why my moves are more cautious nowadays.
The following stocks I am presently buying into cautiously and looking in my view good quality, strong with balance sheets valued reasonably and looking increasingly cheap for a long term hold.
SCS
G4M
QUIZ
LUCE
JOUL
I would welcome your views!
Thanks
Andy
Hi Andrew,
I think wise approach at the moment. Paul recently mentioned something similar with a 3 stage buying approach when picking up Luceco (LON:LUCE) , I can not remember the technical term he used. I am looking a similar buying opportunities, looking at companies like Supreme (LON:SUP) , Cambridge Cognition Holdings (LON:COG) , Volex (LON:VLX) , Saga (LON:SAGA) , but with a very nervous approach I have to say.
I think this is a good approach especially in these markets. I often found after I bought shares they went down, so buying in stages can help, so long as your transaction costs are fairly low.
If you have made a mistake then it's a smaller hit than buying in one go.
For those prepared to be brave the current market sell-off is generating some nice opportunities. Best Of The Best (LON:BOTB) (I hold) is now trading at 11x current year expected earnings - for an online business that throws off cash! Negative sentiment following the fall in profits following the pandemic won't help the share price, and maybe the new car shortages won't help the business, but I think the market price looks a bit daft right now.
Best Of The Best (LON:BOTB) If it so good why are the directors not buying? They sold off about £70m worth earlier this year.
Best Of The Best (LON:BOTB)
Raystraw
Best Of The Best (LON:BOTB) If it so good why are the directors not buying? They sold off about £70m worth earlier this year.
Have you not answered your own question here ?? they sold up to presumably "sort themselves for life" - now they have done that they have no NEED whatsoever to buy back in to try and make a quick buck. Being honest if they bought back in now and the sharprice recovers former glories they would possibly get criticised by some for dragging the price downto make that quick buck??. Their sales were flagged up and other holders had the chance to get out for a price well above the director sales.
Best Of The Best (LON:BOTB) (I hold)
Hi Patrick
I agree with you, BOTB is, surprisingly, on my top-up radar again too!
CPMs look to have fallen, summer holidays are over and ad hoc prizes are increasing again.
I'm also thankful that directors are not buying. They don't need to sell more and they own enough of the company as it is (c50%.)
Similarly I am thankful that they are not selling now either. If they were I'd be more concerned.
H1 is almost over so hopefully there will be an update soon too.
Cheers
A
I like the idea of Best Of The Best (LON:BOTB) however what puts me off is the sheer range of similar competitions I now see on Facebook etc. I don't know if regulations have changed around running what are essentially mini lotteries but over the last year I've seen alot of unregulated £10 or £20 entry competitions with the prize generally being a flash car. The name being drawn 'at random' at a later date. This surely can't just be confined to my locality? and if it isn't then surely BOTB are losing market share?
Not interesting for most of the users here. New 10-year high for CPO (Crude Palm Oil) price today (Very close to all time high)
https://www.rea.co.uk/websites...
Malaysia Palm oil production has been reducing due to labour shortage (2019 - 19.1 mil , 2020 - 18 mil , 2021 (E) - 16.3 mil ). Source - Malaysian Palm Oil board.
Palm oil shipment has been heavily disrupted due to shipping companies focusing on more profitable products. Palm oil shippment/trade flow (2016 shipping routes)
Major supplies for Europe/North America are from Malaysia and Indonesia. Unlike Asia or Africa where Palm oil is used in daily food consumption, in Europe/North America high consumption come from major manufactures.
With consumpution YoY to grow 15% CAGR, CPO prices to remain at this level atleast for the next 12 months.
M P Evans (LON:MPE) has a market cap that fits the remit here and has been one of my better performers on the back of this.
The producers that work predominantly in Indonesia (3 or 4 of the London based palm oil companies) only benefit partially from high prices as the Indonesian government has a complicated tax arrangement which takes a chunk. Having said that I believe that the benefit from any price above $1000 goes mostly to the producers (presumably until the Indonesian government changes the rules).
I have holdings in £RE.B Anglo-eastern Plantations (LON:AEP) and my preferred pick Dekel Agri-vision (LON:DKL) which has invested heavily in a new cashew processing facility which is just about tho start up and the value of which isn't recognised in the share price. An unrecognised value and growth share.
Looking at my stocks and the comments here it seems like the capitulation phase has begun, sell anything seems to be the mood. I do lie as Cake Box Holdings (LON:CBOX) seems to be doing okay... I guess we all still need cake
portfolio goes up, celebrate with cake. portfolio goes down, comfort eat with cake. There's a cake for every occassion.
Marie Antoinette was right!
Except she didn't in fact mention the word cake.
I'm not sure that people are grasping what is happening in Natural Gas, the price is up over £4 a therm, from £2 a therm last week. This isn't 'an economy reopening' or 'growing pains' this a market pricing nat gas for demand destruction; the concern among buyers is not that supply is tight, but that supply is finite and they won't get theirs.
If this persists for even days critical industry will either stop operating or need multi-millions in injections from central gov't, assuming that the nat gas is even available. Even large, hedged energy providers are going to be cutting it close to folding.
On the one hand I'm delighted as I have large holdings in Jkx Oil And Gas (LON:JKX) and Gazprom Pao (LON:OGZD) but on the other hand I'm not a total sociopath and this is going faster/worse than even a nat-gas bull would have guessed.
And we haven't done oil yet.
Where do you get the Natural Gas price from? Because the price I'm looking at, NG has not has increased, anything like that. On IGG NG is 6405 and last week it was 5778 although it was higher 8-9 days ago.
Are we talking two different things? £/MwH vs. futures with November delivery.
Were above £4 this morning.
Yes, I see you are talking about futures, the prices I'm looking at are based prices today.
But were they not $6 the other day?
I can't see them doubling in the last week, we must be looking at different prices?
From the FT today - https://www.ft.com/content/c94cee7d-4ffe-4946-a83b-b4f85026b74f
European gas contracts for delivery in November leapt 23 per cent to €117.50 a megawatt hour, up from just €18 six months ago, on the prospect of supply shortages over winter. UK prices also soared, breaching £3 a therm for the first time, with prices tripling in the past two months. $200 a barrel of oil equivalent.
Paul mentions that we now live of a large amount of renewable energy but thats not strictly true - today it accounts for just 20%.
Whats No1?
46% of today's electricity is being generated by gas (source https://grid.iamkate.com/)
Hi Leebod,
Paul mentions that we now live of a large amount of renewable energy but thats not strictly true - today it accounts for just 20%.
Yes the figure obviously fluctuates considerably depending on how windy it is! I've heard the average for wind power is 30-40% of UK electricity generation, hence my figure was correct.
Regards, Paul.
Paul, I think your figure will inc. solar as well, it's not just for wind.
In 2020 in UK, "Wind energy generation accounted for 24% of total electricity generation"
Once floating wind & battery storage takes off in next few years then renewables should provide 100% of electricity in UK. Marginal cost of electricity production from renewables will trend towards zero - wind & sun is free. Imagine the extra value that will be unlocked in economy with next to nothing electricity power prices !? Road to get there may be bumpy but future possibilities are quite exciting imo. When in history of mankind was power available for next to nothing ?
If wind and solar is free, which I don't believe anyway, why are electric prices soaring, up around 50% this year? There are infrastructure costs and maintenance and it does not last forever, wind turbine about 20 years? Solar was also about 20, although new panels may last longer. The problem with wind and solar it is not constant, if it's cloudy and still weather then output is much lower. I think it still needs to be backed up with other forms of power such as nuclear/gas. Imagine when it is freezing cold and still, which it can be in winter and there is not enough electric.
While the UK is not blessed with a lot of solar, it has plenty of wind. The presentation here https://www.youtube.com/watch?v=Kj96nxtHdTU&t=23s shows (amongst many other things) how the whole of the US can be powered by solar, wind and batteries cheaper than any other power system. Having closed my renewable energy business in 1991 because nobody in the UK gave a toss, I am now much more optimistic. This is a big field to analyse, but there are SO many versions of 'Batteries' being scaled up now, I think you will be surprised how fast this can turn. For anyone who watches Tony Seba's lecture, I'm happy to set up a separate forum for energy/battery company discussion. But this is for investment, not short-term trading. I think that will be a mug's game.
Thanks> i would be interested in such a forum
Unfortunately this lovely scenario has to eventually come face to face with reality. At present we have a maximum wind capacity of about 25 gw but it is very rare for us to get much more than 13gw , and mostly much less ( I believe the all time record is a brief period of 17gw).
So to get the 36-40 gw regularly that we need now we would have to triple the capacity. In itself this is difficult and expensive and by the time we do it the current capacity will need replacing, the 20 year life being about as much as we can expect. With around 4% needing major servicing each year, and the lack of ability to recycle the blades, and the high cost of offshore support and the high cost of the initial offshore building and …well you get the idea. There is zero chance of offshore wind power being anything but expensive, and we are now far enough down the learning curve to be clear about that.
We need, and any politician with sense knows this , to adopt Small Modular Nuclear Reactors (SMNR). These are basically land based nuclear submarine reactors, about which we now know quite a lot ( including the long term storage requirement for decommissioning). Each reactor would provide about 400 mw for 40 years so in batches of 6 around the country we could completely handle the base load requirements. The modular design would leave entirely manageable long term storage. I am encouraged that Rolls Royce has a preliminary study to acquire 22 reactors but am a pessimist so expect the government to flunk the backbone needed to face down media ignorance when faced the word “nuclear”.
Maybe 40 years is then enough to get to fusion.
SMRs are different to nuclear submarine reactors as far as I understand. The SMR will consume all its fuel and shouldn't create the long term decommissioning costs and problems of the nuclear submarine fleet. The only problem being, these SMRs don't exist and are thought to be 10 years away if we start making the investments today.
For clarification, the proposed SMR power-gen reactors are pressurised water reactors (PWRs). I'm sure they will be designed for their fuel to last the lifetime of the reactor but this does not mean end-of-life decommissioning issues are simpler - they will be comparable to those of decommissioned submarine reactors.
Nuclear has many problems...but it is a solution we need and can understand and implement. We will use it more and SMRs will become common place (safety, cost, portability). IMO there is great cost savings to be had from a more up to date regulatory and safety perspective that is aligned with modern design and safety. The price of nuclear engineering will fall drastically as we embrace it (not that I'm an expert)....
But I'm talking my own bias...and I have significant position in uranium miners....bought more Nak Kazatomprom Ao (LON:KAP) today on market falls (I've got over 15 uranium miners in a basket of them).
Anyway, IMO more nuke is unavoidable and I wouldn't be surprised if something emerges from COP26 on it given the global energy pressures. Without we cannot plan the 'transition'...of course, we may have massive innovation leaps around storage and renewables but we cannot plan on that yet. Renewables >>>> that nuke and of course fossil fuels but we've got to get there first rather than dream sequence it
I'm not up to date on today's chat here but I suspect some of it on market falls. My other purchase today was K3 Capital (LON:K3C) which I have owned from around its lows in the last few years. Its not blindingly cheap obvs but I don't see why its business is -10% sensitive on a choppy day. Sub 330p I've been happy to buy a bit more.
What I despair about is that government cannot get all the scientists and leaders in the field of energy around a table to do brainstorming of the best way forward. Instead government seems fixated on a certain idea, like solar and windmills and goes full steam ahead only further down the line to figure out that might not work after they have spent billions of taxpayer money.
The same with electric cars. Is that the only solution for the future and have they consulted with the right people? Or is it just another government spin so they can say they are doing all they can to get to carbon neutral. Meanwhile the citizens are paying for the mismanagement and the mistakes in more ways than one.
https://www.strategic-culture....
Just because it might be free does not mean it will be passed on free to the customer. Companies are in it to make money not to be a charity.
Hi Paul,
This is the National Grid information on electricity generation https://grid.iamkate.com/ which might be useful in current discussion.
In the last year wind accounted for 18% of electricity generation, fossil fuels (primarily gas) 42% and Nuclear 17%. Then there were other bits and bobs (biomass, solar, coal!, inter connectors, hydro). In the past week when it has been pretty windy wind generation has contributed nearly 35%. All suggests to me if that going to go 100% renewable any time soon a lot of battery storage is going to be needed both to store excess electricity and balance the grid as necessary. Vanadium redox batteries don’t seem to be the way forward if my holding in Bushveld Minerals (LON:BMN) anything to go by - down 50% + YTD. Perhaps a better bet would have been the Canadians stock £LGO or probably a different battery storage technology altogether!
And a larger part in other countries by coal.
I found the following: https://assets.publishing.serv...
It shows in 2020 c.43% of electricity was produced from renewable sources.
The UK is unusually blessed in its weather and geography for wind. Obvs solar less good for us. Not everyone has this blessing. For example, Germany is deficient in both wind and sun for sustainably high renewable generation.
I wouldn't include 'other renewables' as that is likely to be significantly biomass (eg old coal power stations running on wood chips etc)
Hi realized its going nuts but where have you seen its doubled again in a week ?
Thanks Andy
it hit 404p at 09:30 up 40% on the day but is currently back around 343p p/therm (+10% on the day)
strikes me the flurry was correlated to panic around the French muttering about consequences over fishing licences (ffs) than it had to do with demand, not that 343p isn't already too high. Though European gas prices are rising as well so that might shoot my theory about todays spike.
EDIT : has gone up 7* in 3 years though most of this from July.
It's partly about Gazprom's Nordstream 2 pipeline isn't it? The Russians are throttling the flow of gas through the existing pipeline to exert pressure on the Europeans to open the new pipeline.
and now they are negative on the day at £2.90 therm
volatile........
Presumably WisdomTree Natural Gas (NGSP) (tracking the Bloomberg Natural Gas Subindex plus a collateral return) measures some other dimension of the natgas market (?) because although it's risen quite a bit in the last few months it's only back up to 2019.
ResourceMan
We are in a mess here too. About 15% off Peak Value, still dropping, no sign of the turnaround yet.
Sitting this out calmly.
Calmly??? Lies, all lies!
The last 18 moths have been a real rollercoaster. I currently hold 31 stocks and since my year high on 14 June I am down 7.4%
Year to date I remain up by 7%. Looking back to March 2020 I am up 105%.
The market is producing some extraordinary situations. BP and Shell are going up rapidly after 2 years of pain for many holders including my wife.
Car dealers are enjoying unprecedented profits against all the odds.
Entain has a massive decision to make. I hold. You cannot say the market is dull because there are so many fascinating things going on. This is why Stockopedia is so good as contributors are well informed and Paul & Jack and Roland work extremely hard to ensure we keep up with events. Keep up the good work guys.
Retailers getting pummeled right now and Boohoo (LON:BOO) (I hold) and Asos (LON:ASC) are now down 50% y/y. Boohoo (LON:BOO) sp now at its lowest level since the selloff in March 2020 but valued in line with Asos (LON:ASC) and Jd Sports Fashion (LON:JD.) despite vastly superior margins, growth and ROCE. Starting to look attractive at the moment and given the above I think it should be trading around 25x, so 235p is my target price at the moment.
Down 5% this week after getting rid of the disastrous Loopup (LON:LOOP) and Boohoo (LON:BOO) performance, as well as small falls on Chrysalis Investments (LON:CHRY) and Arix Bioscience (LON:ARIX)
I am beginning to think danjamesbaker and others on this Boohoo (LON:BOO) subject that the market is starting to think that what they stand forr, they are really not a good company, not doing good things for the environment, for society - buy now, send 60% back, throw away after x weeks/months.
Couple that with the press really regarding them as the den of iniquity, and looking for the smallest chink in their already damaged armour. They are making great strides in the E category, working conditions etc, but at the back of the mind, perhaps is starting to creep in the thought that their concept is still exploiting the worst consumer features of our current society.....and that that will have to change.
I have been a Boohoo (LON:BOO) investor, but got out for financial and social reasons. Fortunately, the two coincided. Maybe, just maybe, we are seeing a step change in our western society thinking.
On the other hand, probably not, and it is just one of those Paul blips and I should be ready to leap in with my ready cash to take full advantage of the upward correction in the SP, putting my socially minded thoughts aside as irrelevant and wont happen anyway because we all do what we want to do in the end, and we cant personally affect climate change etc etc!!!
Isn't the weakness in Boohoo (LON:BOO) due to a lack of institutional backing? There's only so much weight small investors can wield.
The ESG funds were shown up as superficial tick-box merchants greenwashing where they could to attract well meaning investors. They won't want to risk being burned again until the company has been convincingly rehabilitated. So it will probably be activist investors or PE that make the first moves.
The ESG stuff is a red herring re Boohoo (LON:BOO)
It's a sector move. Online fashion, and other eCommerce businesses have generally moved down, in lock-step. Here's the proof - BOO is -38% in the last year, others in the sector are broadly similar -
Re Boohoo (LON:BOO) there you go, I said Paul would say it was a blip, but in fact he has been more definite than - it is a red herring!
may well be elements of the reopening trade rather than the macro supply chain/energy/forex pressures. YTD heatmap below for the sector does show a bit of brick and mortar bounce though there's probably a fair bit of mean reversion on boths sides of the online/offline trade. Just Eat Takeaway.com Nv (LON:JET), Thg (LON:THG), Boohoo (LON:BOO), Asos (LON:ASC) , £AO are all down 30-60% YTD while Next (LON:NXT), Jd Sports Fashion (LON:JD.), Marks And Spencer (LON:MKS) are in the green (though obviously different mixes)
(click images to enlarge)
The small cap (<£500m) end of the sector has some stunning outperformers not least the car dealers though Lookers (LON:LOOK) takes the pole position on +189% YTD French Connection (LON:FCCN) on +186% and Quiz (LON:QUIZ) on +160% not too shabby
could be part reopening trade as the bricks'n'mortar retail businesses seem to be outperforming the pure ecomm players this year: a reversion to mean of sorts given last year's extraordinary nature
: Here's a heatmap YTD for the sector with Thg (LON:THG) and Boohoo (LON:BOO) down around -44% with Asos (LON:ASC) -41%: Ao World (LON:AO.) is off -60% with £JE down 32%. Next (LON:NXT) and £JD are up 8 and 19% YTD with other multichannel players also in the green.
(click to expand)
Smaller caps show some great outperformance YTD
(click to expand)
Today marks a few retailers making a 52 week low .... and a few bouncing off the bottom: may well be signs of capitulation and the darkest hour before the dawn...
Boohoo (LON:BOO) sp now at its lowest level since the selloff in March 2020 but valued in line with Asos (LON:ASC) and Jd Sports Fashion (LON:JD.) despite vastly superior margins, growth and ROCE
You forgot the word historic in this sentence. Clearly the market feels that it's past performance is no guarantee of continued future performance.
Thanks for the write up on Lookers Paul. This is a sector im particularly interested in at the moment. Just on this point:
"Investors have assumed that supply constraints would damage car dealers, but the opposite has happened. Strong demand, combined with limited supply, has driven up prices, and profit margins."
I've not really heard many people say used car dealers would suffer from the shortage. In fact, myself and others who have discussed it, thought it was a fairly simple supply and demand issue. Margins were inevitably going to increase and i was hopeful net profits would sky rocket. For businesses already trading on low PER, we should see some decent gains in the short term. My personal opinion is that Vertu Motors (LON:VTU) is a good bet but (LON:MMH) is not a bad shout either.
This supply issue is important, as you have rightly highlighted above, and needs to be factored in to anyone's investment decision. Supply of new cars will eventually normalise and we will see a pullback in profits as people return to buying them. I see this as inevitable and I don't see significant value in long term play of used car dealerships (i believe long term, my money is better off for growth elsewhere).
I expect to see a chart similar to Sylvania Platinum (LON:SLP) or that of Lumbar prices. once supply normalises, basket price comes crashing down. I expect Investors will move out of their positions and the SP will drop back. maybe not all the way, but im hoping to take a healthy profit rather than a 5% gain.
~Above is just my thoughts and opinions, DYOR as usual ~
The car companies are learning some lessons from all this. Daimler and BMW both say they will consciously limit supply in future to lock in the premium pricing they have achieved in the pandemic.
The market may make that more difficult of course - we've queried here before whether those badges deserve their premium prices over the improving South Korean competition or even Chinese made vehicles. But I imagine they will all want to squeeze as much profit as they can from their final runs of internal combustion cars.
FT link for those who can access it:
https://www.ft.com/content/f55...
Volatile times are back and as ever mid-caps and small-caps tend to get a good battering when there is macroeconomic uncertainty in the air. If you are feeling bad now, just think how bad you will feel if you capitulate to this volatility, sell out, only to see your holdings correct higher when the macro news (supply chains, energy prices) recedes as it always does.
If someone knocks on my front door today and offers to buy my house at a discount to what its worth I will politely send them away. I intend to do the same for my share holdings.
Whilst in the long term you are right regarding long term holdings, comparing it to selling your house is not correct. You can buy and sell your shares which have no purpose beyond a financial instrument at will. If you think you can buy them 25% cheaper in future then you should sell – it is no different to thinking a share will go up by 25% and buying.
There are a number of very real macro pressure that for the foreseeable future will not be abating and change the fundamentals of companies.
There are further issues facing UK business in particular, minimum wage rises, business rate relief ending, VAT relief ending, repayment of government covid loans, inflation etc.
Almost every company that imports is reporting issues, almost all are reporting staffing, supply, port and distribution issues. The assumption I am reading in company reports are we expect all these to return to normal over the next 6 months – there may be some relief but I very much doubt that they will return to the price of 6 months ago.
Given the above it should come as no surprise that AO world & Boohoo (for example) had to warn (especially after ASOS warned recently), yet the market act surprised and continues to be. Mid last week I sold most my holdings of made.com, Volex, G4M (I still hold a small holding), Boohoo and Joules, not because I think they are bad businesses (in fact I think the opposite) but because they were all yet to warn and if they haven’t already I think they will likely have to. Paul mentioned Portmeirion the other day which is another. Could I be wrong – of course, some will have significant pricing power and will emerge stronger, however you should reassess the fundamentals when they change and act accordingly. That is the advantage of shares - I can decide I am wrong tomorrow, change my mind and buy back.
With regard Scs (LON:SCS) discussion yesterday I would add that;
In the Q&A the FD said that a normal customer deposit balance is £20m Vs £37m. This isn't really a bear point as the market clearly gives the equity little value for the cash held....but I think when 2019, 2020, 2021 WC cycles normalise the net cash on balance sheet number will be lower. Like I say not really a bear point.
Also, bear in mind the current performance of housing related stocks. For several reasons the market is getting somewhat bearish the UK and the relative performance of the housing sector. This traditionally is not a great backdrop for furniture although, normally the housing market proves more resilient and will no doubt have traded perfectly fine come the trading statements and fun year results in Q1 next year. At some point the housing stocks will start to reflect this again ... and then Scs (LON:SCS) will likely perform better.
The UK housing market has to absorb the perfectly normal transition from Summer into Winter that happens every year (school years being a big factor). Of course The Housing Market will slow down for the next 2 quarters. It always does.
The market will also need to absorb about 1.5% difference as The Stamp Duty (rip off) holiday is now over, and the surge in activity this stimulated.
Many smart minds argue Stamp Duty needs reforming to speed up housing turnover.
I got an email from Hamptons the other day estimating around 4% annual growth in UK House Prices.
Well my overall portfolio of 14 diverse stocks is -26% now and -34% on boohoo and I feel like a total bag holder every day at the moment. Really struggling with the concept that it is all irrelevant. Hope others are having a better time.
Resource Man, it is very painful at the moment. I am down 10% from my all time high, but I think I have got off lightly. It is difficult to ignore, despite the fact everything you read advises you to sit tight.
Still up 26% yoy and 4% ytd but I've lost over 10% in the last 5 days which has been brutal.
Boo, growing at 20% in H1 now on a p/e for Feb 22 around 20 assuming an eps 9.5p which a lot of people think they'll beat. It's a grim feeling.
(edited to fix typo, I stated a p/e of 9.5 but meant eps - now fixed).
Hi,
Am sorry to hear that your diversified portfolio is down - I am sure most investors are in the same boat (currently).
If I was an investor (I am not one - so an opinion that may not be worth much) I would imagine there will be times when the market is down but unless the company you have in your portfolio has fundamentally changed there is no reason to sell as you are in it for the long haul. In fact, I would guess a major reason for realised losses in a portfolio is as a result of stress selling when the overall market is dropping only to see the price go up a short time later as the company you own is fundamentally strong. This is not advice to buy or sell - DYOR
I would point out that I am not an investor and this is one of the reasons as it doesn't suit my psychology.
It may be interesting to start a thread and ask opinions of other investors with years of experience how they deal with the market downturn with there investment portfolios.
Finally, I was watching Bloomberg this morning and the presenters opinion was this drop is just a blip and the market with continue to rise - his reasoning was that there is currently too much liquidity on the sidelines for a major crash (but that will eventually come).
Good luck to all - DYOR
The tide pulls back... before it surges in.
Is what investors have been conditioned to believe over nearly 40 years, but central banks can't print oil and gas.
There's plenty of Oil and Gas (and Uranium).
We have indigenous reserves of Oil and Gas on UK territory.
The politics of it though is we are choosing Green doctrine over using domestic energy resources.
Hey Resource Man, thanks for sharing and try not to let it get you down. I’m in a similar position - I have a portfolio of 14 stocks which is £10k down since Sept 1st (£82k down to £72k) and year to date performance at now only +5%.
I take a long term view, which given I’m relatively new to investing I’m hoping pays off in 3-5 years time.
Thanks yep I’ve lost £52k of what I put in so far
It isn't easy at the moment is it. I was doing really well but now most of my holdings are in negative territory. I think that as long as the companies we hold are of high quality then they will bounce back in time. Perhaps we need to take this opportunity to learn more about valuations?
Yep, i'm also having a terrible time of it. I started investing towards the end of 2018 and have now see all my gains wiped out (I was +30% back in June). I now at break even, which is likely to carry on drifting down in the immediate term. I think I have quality picks (appx 40 small caps, with a few mids). I'm going to hang on in there, not selling anything! I'll keep reading the RNS feeds (for my stocks) and the SCVR, but, really need to stop looking at my portfolio as much as its not helping.
Relax Andy Sav.
You can't undo past errors, but there is an equilibrium and I like that you mentioned "Quality" picks.
You will get your money back, with dividends.
Hi Resource Man,
Investing in stocks can be psychologically demanding. You go into the process in the knowledge that there is a certainty you will have periods, possibly sustained periods, of poor returns, and that you need to be prepared to endure these. That is easier in prospect than in reality, however, and I certainly find the psychological burden of losses is greater per £ than the psychological pleasure from gains. I think that most people feel the same.
The one thing you do have in your favour is that you are in the right place, on Stockopedia. It is by far the best site I have found for sourcing ideas and getting advice.
My advice, for what it's worth, is simply to batten down the hatches and stick with it. If your underlying investments are sound, and they likely are since you're on this site, then they will come good eventually.
Good luck!
Irrespective of the inexorable trend towards more electric vehicles as the only way to manage air pollution in cities, noise and perhaps help save the planet even, I merely write to say that my own EV is the best car I have ever owned. It's a VW id4 and is a revelation to drive. Being able to totally avoid fuel queues in the recent panic was a bonus.
My wife is so unusually enamoured of it that I can see that before long we will become a 2EV household and all my friends are gaining confidence about making the change. This must eventually lead to a rise in demand for new cars and, you would imagine, a fall in value of increasingly unwanted used cars with liquid fuel. Whichever motor retail company best manages the sea change we should see once the superconductor supply issue is resolved should make a tonne of money. Lookers will do for me.
We have the Ford Mustang Mach E extended range first edition and totally loving that too. We don’t get the 340+ mile range advertised but about 285 miles and that is pretty consistent however we drive it and whatever the weather is etc so at least it’s pretty dependable. That said I have 15% of my portfolio in PAH3 DE so I am backing VW
Nissan Qashqai 1.5 Diesel... 62MPG average (I drive slower than an old lady).
730 miles on a tank of diesel.
Brilliant, when was the last time you drove from Penzance to Inverness non stop?
I can't help it if I am a slow, safe, controlled, economical driver!
So never then. So what's the point in having a 700+ mile range?
Because you rarely have to visit a fuel station. You just get in, press start, it goes, for 730 miles. An easy economical life.
Lol, I never go to a fuel station. No getting my hands covered in diesel, no having to make special trips. I just get in, press start. Nothing happens. No one walking past is breathing in my toxins. It goes for as far as I need it to. I get home, if necessary take a few seconds to plug it in with my nice, clean connector that doesn't cause fuel to run down my car and need wiping up.
Sometimes, I'll need to do 300 miles, and yeah I need to plan in a stop somewhere. Maybe two / three times a year. So I find somewhere like Tebay, or Gloucester services, have a nice meal whilst looking at the ducks and then crack on.
I'm sold!
Well when I've paid my Corporation Tax, Income Tax, Dividend Tax and for my over-leveraged positions, and get my profits back. we will get one. Until then, I lead a very modest lifestyle for a multi-millionaire. I could probably make a profit if I lived on "bennies".
I'm like "Gus" in "Breaking Bad" (Volvo) - drive the most ordinary boring inconspicuous safe car.
Brilliant, when was the last time you drove from Penzance to Inverness non stop?
Never, but I drive 120+ miles to W Cornwall a few times a year, and I'd have to recharge to get back. Currently that means either hoping to find a free charger in one of the car parks and leaving the car there, or finding and paying for a hotel with chargers. At the moment that would be a pain in the ..., but I expect that by the time my trusty 11 year olld diesel Golf is fit for the scrap heap the picture will be different. And the environmental impact of probably scrapping a working car to replace it with a new EV one now is going to be a lot larger than a few more years of lowish mileage diesel use.
Why do you have to find a "free" charger? Is your diesel free?
A quick look at Zap Map suggests there's loads of fast chargers in West Cornwall - Lands End, Penzance, Camborne, Redruth, Falmouth, St Erth, Truro. And lots of 7 / 11Kw chargers for grazing on when visiting the shops.
It goes like this, shall we go for breakfast / dinner somewhere? We'll charge the car whilst we're doing something else. Oh, we need to go to Tesco, lets nab a quick 10 miles of range whilst we're here.
I did a 400 mile round trip to Porlock recently. On the way down, nice breakfast at Gloucester Farm services, got myself upto 80%. Decided to have a day in Minehead, put it on the fast charger for half an hour in MInehead even though I didn't really need to. Stopped at Gloucester on the way back for a coffee and a bio break. 20 minutes later on the road, got home with around 50% charge, enough for the next week or so but as it was sunny the next day, I just put it charge anyway.
He clearly means "available to use" not "free of charge".
And no problem finding Diesel on Sunday night at an affordable price.
The issue is you have to keep stopping all the time. If I had a e Golf and drove to Fort William (about 510 miles) I would have charge up about 5 times on the way. I prefer to drive with stopping often, as it's adds too much time to the journey. I read you should only charge up to 80% to prolong battery life.
When was the last time you went to Fort William? And if you're thinking of going to Fort William why are you buying an E-Golf? Oh, wait, you're not buying an E-Golf because you buy cars that are £8k so again you're arguing about something you'll never do. This is getting silly now.
You're supposed to stop every two hours to stay safe (in accordance with HSE recommendations) but my car happily goes for three hours. In 40 minutes or so, it's good for another 2-2 1/2 hours. So, two twenty minutes stops in 6 hours of driving seems reasonable to me.
Sure, on a daily basis you shouldn't rapid charge and you're advised to limit to 80%. However if you need the range going to 100% is fine.
This is like the weird conversation I had in the pub the other month. Him - "You can't tow a caravan with your iPace". Me - "No I can't, what sort of caravan have you got as some electric cars can tow". Him - "Oh, I don't have a caravan". Me *walks away shaking head*
Why do you have to find a "free" charger? Is your diesel free?
I meant "free" as in "available"
As Paul pointed out...
We can not count on UK power infrastructure.
The games with fuel supply recently are equally possible with electricity.
Supposing those eco-terrorist were to target some key National Grid distribution trunks such as Bolney (The London Trunk), or Sizewell, Hinkley Point, Dungeness or Drax.
Liquid fuel... is actually good. It can sit in your tank for days, weeks, months, years.
Get an Electric and Internet infrastructure outage, the power goes off immediately, (no debit or credit cards, no credit), no lights, no internet, no telecoms, ... and people will be knifing each other for a takeaway within 48 hours of going stoneage.
A few years ago when I had my diesel I only filled it twice in a year.
Now my petrol one I seem to be filling it up all the time.
Changing from an 8 year petrol to EV does not make sense to me. Looking at a Golf EV, its about £28k and only has a 144 mile claimed range.
The Golf EV has been replaced with the ID3 - range over 200 miles, and about 250 miles with the larger battery option
I see. The Golf EV is still on the VW site. The ID3 is about £33k, wow.
Golf EVs are old technology and I don't think you can buy them anymore so not a great comparison and TBH a range of 144 is more like 100 in real life!
There is no doubting EV's cost a premium and with electricity prices going up they are not as cheap to refuel as a couple of years ago (I know economy 7 and electricty tariffs do cater for cheap OOHs which does make a big difference - if you can get on them - BUT then your electricity prices during the day are a lot higher).
The new MG electric cars are reasonable for the money but there is no doubting that a new petrol / diesel equivalent is a lot cheaper. Getting rid of the EV grant for cars above £40k was a mistake.
That's why I would not buy a used EV, because it's old tech. Then there could be battery issues. I don't even buy new petrol/diesel, they are too expensive as well.
Hello UK_Investor8888. Good job someone else is breathing your exhaust fumes!
EuroCat 6 and driven as economically as possible, up for replacement when I pay off my debts, my taxes and my shares come back to life.
Guilty... but I comply with all current legislation and rules. Speed limiter in use.
We as a household love the idea of owning an electric vehicle or two but currently own two diesels. I recently did a bit of digging into the issue and in all scenarios an EV was too expensive to justify and near term obsolescence of combustion vehicles was inconclusive. Pound for pound on the used car market ULEZ diesels seem to offer the best value in spite of a change in government messaging about this fuel type and its widely reported harmful effects. There is also a possibility that electric car prices may go down more quickly than the combustion types that they are replacing. The reasons for me are fivefold: 1 We are now able to purchase new EVs much cheaper than a few years ago. The Skoda Enyak for example retails at £32k (depreciate that over three years and you have a very affordable aspirational used SUV EV - assuming cars start to depreciate again) 2. EV volume is increasing. 3. It costs significantly more and it is significantly more harmful to the environment to produce EVs in lieu of the typical combustion car they are replacing (FT have an excellent piece on this currently). Surely producing an entirely new car can't be better for the environment than running an older ULEZ combustion type into the ground. 4. There are a whole host of relatively new technologies that will add strain the electricity infrastructure e.g. Air source heat pumps. Will the capacity be there for every house to have 1 or 2 cars? 5. Diesel isn't going anywhere fast: Construction, agri and quarrying etc for example are heavily reliant on it. Although I believe there is a upcoming change next year which will mean that red diesel will no longer be available for some of these purposes. White diesel will be required which will drive up the cost of these activities. If this happens there maybe more of a swing towards electric excavators etc but I believe the cost and the practicality of the latter isn't quite there yet and will need time.?
In summary I would dearly like to buy an EV but feel that 3 to 5 years from now will be a more opportune time to do so.
Our other car is a diesel so we are riding the twin horse approach. The EV is on a two year finance plan with Ford so we have the guaranteed minimum future value and option to hand the car back in the back pocket which is totally the plan with the EV unless selling it makes more. Either way we will go to a new EV at that point as the tech is moving on so fast. The diesel on the other hand we may keep
"like to buy an EV but feel that 3 to 5 years from now will be a more opportune time to do so."
Agree - I am a pro-market tree-hugger by politics but a skinflint by nature. Fortunately, the 2 overlap currently.
I will nurse my modest 8 year old petrol car for another 8 years to 150,000 miles, avoiding early scrapping - unless the govt gets serious about the environment (unlikely!) and raises fuel duty/CAZ zone charges etc, making the much lower running costs argument dominant . (As a good Stockopedia reader, I have a spreadsheet that evaluates these trade offs!)
This is a 15 year transition process - rapid in historic terms but glacial in investment horizons.
'and raises fuel duty/CAZ zone charges' .
I know you're saying it is unlikely but I wonder what the government would gain from this move? It seems obvious the economic impact of running a ULEZ combustion vehicles is less than manufacturing a new EV. Also in 15 to 20 years combustion cars shouldn't be widely available or accessible on the used car market as many manufacturers have already started to cut them from their range. If it was a tax grab the amount raised would diminish very quickly as more people switch to EV. I'd say what more likely is a new tax which is applied to EVs and is also applied to combustion cars on to top of the tax they are already paying. Something like the much touted pay per mile etc.
I must caveat this by revealing that government's do in fact do things that don't make sense but for the time being I shall drive my diesels.
It would be great if the messaging was clear on this topic because if everyone knew a great swathe of taxes were going to be applied to combustion cars in say 5 years then they would be more likely to entertain buying used EVs for x amount more than their equivalents.
Thank you dhanaway58156, An interesting and useful treatise, but how about doing something NOW for emissions, and from my experience safety on the roads. We too have an ageing VW Golf turbo diesel - for the dog who needs a ladder to even to climb into that (true!) - but we find we drive the electric car we have in quite a different way. It truly is calming, and I drive slower and more considerately. Strange but true and though not a statistically sound sample, several friends say/feel the same in their electrics.
I can vouch for that. Combine the lack of lag and the torque that allows such a swift acceleration away from lights with an undoubted calming quality, the ability to chat even to a passenger in the back seat, the ability to sit in a parked, warm or cooled vehicle without engine vibration and pollution, the superb cruise control with the car dealing with changes of speed restrictions and in relative position and behaviour of other vehicles, makes for far greater driving comfort.
Just a brief comment - because it's only tangental to investment - on replacing cars for environment/ emissions motives.
1) Energy & CO2 cost to manufactucture a new car is vast, so unless you're a taxi/limo service doing, say, 250k miles a year or more, if you want to help the environment you're better off running your old car for a very full lifetime (keeping it well serviced of course).
2) If you're a proud EV driver for eco reasons, remember you need a renewables energy contract at home & seek eco-electricity charging points away from home. Though even without it, you're helping to improve air quality in urban areas.
3) You also need to over-look the ecological destruction of lithium mining, and the wars that will be fought over Li & other EV resources such as copper & nickel - that's not to suggest that mining resources for internal-combustion-engine vehicles isn't also destructive, and probably more so, just that being 'eco' is usually a lot more nuanced than most folk realise.
Hi Tangodoc,
Great point - I've not driven many EVs, but did test drive a base model Porsche Taycan, and it was utterly extraordinary to drive. Instant torque at any speed, incredibly smooth - there's nothing you can do with the accelerator that will cause any jerkiness. Fast, obviously. Almost silent inside, very comfortable, beautifully built from high quality materials, and of course stunning to look at, inside & out. But above all what staggered me was how you can chuck a >2 tonne car around like a go-kart. I think that's because the batteries are heavy, and are mounted at floor level, giving the car a super-low centre of gravity.
Overall then, I agree with you that once people have test-driven electric cars, they might end up buying them because they're so damned good to drive! Not just for ecology reasons.
Although I would miss the V8/V12 burble/roar of a big engined car, so am keeping my Daimler Double Six for very occasional use (under 500 miles per annum), and I manage to eke out 18mpg from it, surprisingly.
Although a fun optional extra on the Taycan is a fake engine noise, customisable, one of which sounds like a spaceship from Star Trek or Blakes 7! A bit too gimmicky for my taste, but good fun! A friend showed me this feature, on his top-spec Taycan "Turbo" (ridiculous to use that name for an EV). It was an incredible drive.
Another friend has a Tesla, which he absolutely loves, which he says has utterly stunning acceleration.
Sorry to ramble off topic, but we are having a car dealership SCVR today!
I remain of the view that EV take up could be a lot quicker than anticipated, because they're so much better than conventional cars (not for everyone though, esp if range anxiety is an issue, eg for high mileage drivers).
Best wishes, Paul.
I'm not sure about EV take up because of the costs. Most people buy used cars, not sure I would buy a used EV. I think the range needs to be improved and the charging infrastructure in some areas is still very poor. Depreciation how much will they be worth in 3-5 years time, maybe leasing makes more sense?
Charging at home takes a long time and is not suitable for many UK houses. Surge in EV recently could be because they are available whilst petrol/diesel have a long waiting list.
My E class had a minimum guaranteed future value of around 40% after 4 years. My iPace has a MGFV of around 40% after 4 years. Depreciation, meh.
Charging at home happens whenever you want. It's sunny right now, my car (3.5KW charger) is happily sucking up electrons from my solar panels. I'll turn it off when it gets dark. Oh dear, I'll only have around 180 miles of range by the time it gets dark - however will I cope with the anticipated 80 miles I'll do between now and the end of the week. Well, I suppose I could plug it in again tomorrow if it's sunny. Maybe, maybe not.
People who've never had an electric car, don't get that you don't fill it up like a petrol car and think it's either empty of full - nope it's usually somewhere between 20 and 80% unless going on a run.
If you're a high mileage user, sure EVs aren't for you, but otherwise they're great. And no more trips to stinky fuel stations and getting your hands covered in manky diesel. Urgh.
iPace costs around £60k, 60% of 60k is £36k over 4 years, is £9k per year. Sounds a lot of money to me. I tend to buy used and then sell after about 7 years, depreciation then is low.
I would have thought high mileage is what you need to do in an EV to get the cost per mile down.
So how do you top up your EV on a longer trip?
Nissan Qashqai, 7 miles on the clock, sat in Nissan's car park for a year. £17990 first owner.
And £20 road tax.
So my dirty diesel is 1/3 the price of an EV and not caught by the premium vehicle VED.
How do I top it up on a longer trip? Er, I plug it in at one of the rapidly expanding number of fast or rapid chargers.
Sure, it costs me a lot. But if I didn't have that, I'd have the same depreciation with a different car.
There aren't any decent EVs in the price bracket it sounds like you want to pay. But in that price bracket depreciation isn't a major factor anyway so why mention it as something you care about?
Depreciation is something I care about. Why waste money and why tie up so much money in something that depreciates? For me with the amount of mileage I do, it's not worth buying anything over about £8k. Most of my local journeys are by bicycle.
Right, you said “what’s the depreciation like”. And when given the answer the depreciation cost is similar you go on to say (paraphrasing) “yeah I don’t buy cars that depreciate massively”.But at the price point you’re paying, the depreciation is relatively meaningless. So you’re asking a question about EVs that you don’t apply to ice vehicles. I already stated there aren’t good EV options at the price you want to pay currently.
It’s the same old problem, people ask the wrong questions about evs and hold them to a standard that they don’t need to match.
iPace costs around £60k, 60% of 60k is £36k over 4 years, is £9k per year. Sounds a lot of money to me. I tend to buy used and then sell after about 7 years, depreciation then is low.
One thing that does help at present is if you expense company car through business as owner or employee hmrc may be funding 35% + of the costs for you. At present the car benefit rules are very generous for company cars - ie this year benefit charge is only 1% (2% next year) of car list price to fully expense car costs (other than poss use private electop up) with potential 50% vat claim to boot if vehicle is leased.
'I'm not sure I would buy a used EV'.
I can see the rationale here given the cost of a battery replacement being £12k plus from memory and I suppose their usable life is still tbc for the newer models. I've read of battery leasing options at around £50 a month which protect owners greatly. I often baulk at leasing in general as paying more % interest than the yield of the indexes is hard to balance from an opportunity cost perspective. Especially as a lowly paye employee.
Frightening... and the shitty poor quality software to the standards of Microsoft, Facebook and Amazon.
I would never trust a US built car again having had a Jeep in the past.
I have yet to see a Nissan Ariya actually be driven by a journalist on a road. (The equivalent to the rubber tank brigades in WWII that deceived The Nazis.)
Charging at home with a Pod point is fast and mine gets fitted next week. Meantime, I find that being able to keep topping up to 80% (212 miles) using off peak via a conventional 3 pin lead is very practical. It charges at about 8 miles every hour. Best yet was leaving to shop at a Tesco 10 miles away. Left home with 150 miles in the battery. Did a Tesco shop while plugged in, FREE, remember, and drove home. 20 mile round trip. On arrival home, I had 160 miles in the "tank"!
Leasing may make more sense if batteries turn out to be duff after a short while. I looked at that option very closely before rejecting it this time. I think that, as long as we never abuse batteries by stuffing them to 100% too frequently or allowing them to flatten, our experience of phones and laptops might suggest that we'll be reasonably OK and this is an area of technology that is advancing as fast as possible. I remain optimistic while enjoying motoring as I haven't for so long.
Don't forget, phones and laptops don't have sophisticated charging circuits generally, they just stuff the battery any old how. Cars monitor the cells, monitor temperature and a whole load of other things I haven't bothered to investigate and protect cell life. For example you can't charge at the full rate if the battery is too hot or cold.
Yes but you have to shop in Tesco, I would rather shop elsewhere and also the nearest Tesco to me is about 17 miles away, I can go to Aldi, Lidl, Asda and Morrisons which are much closer. But depends where you live, are Tesla still doing free charging? I looked before and the nearest one to me was about 50 miles away.
Some batteries it does not matter how you charge them up but I have found camera batteries only last about 6 years and most are down the red recharge performance within 3 years. Battery costs are getting really high, can you believe a Canon camera battery costs around £114? If car battery do start failing after about 10 years then it could cause a real problem. Ipad battery is not good after about 6 years either.
There are environmental issues with some of mineral in batteries such as Lithium and Cobalt.
But I agree about the pollution benefits in out cities. I'm sure the pollution in London did cause some of my health issues, since moving out into the sticks my health has improved.
Why are you needing to charge at the supermarket in your home town? Oh, and a lot of Morrissons now have fast chargers, I've used two recently, one in Hereford and one in Tamworth.
See TangoDoc post which I was replying to. Charging at Tesco is free, that was his point.
My Morrissons does not have any charging points yet.
But you don't need a charging point at your Morrisson's - you'll be charging at home.
You are missing the point.
The point was you can drive 10 miles to Tesco and charge up free, whilst you are doing your shopping and then drive home and it has not cost you anything in fuel.
But you don't shop at Tesco. This is getting surreal. And the Morrissons chargers you have to pay for.
I was replying to someone who does.
You said "you have to shop in Tesco". No you don't. His point was that he does shop in Tesco and gets free energy to boot. Your point "I would rather shop elsewhere" so don't get the benefit of the free charging for the car you haven't got and have no intention of getting.
Surreal.
Look they said "Best yet was leaving to shop at a Tesco 10 miles away. Left home with 150 miles in the battery. Did a Tesco shop while plugged in, FREE, remember, and drove home. 20 mile round trip. On arrival home, I had 160 miles in the "tank"!
Yes to get the free top up you have to shop at Tescos.
Tescos would be my last choice of supermarket. Benefit for some is not a benefit for others.
So it is not an incentive to me to buy an EV.
2 tonnes
The laws of physics! Can you remember when small ICE cars were under 1 tonne?
Sure, I remember the time when cars were built out of tin foil, had no abs, power steering, rubbish suspension, small wheels, skinny tyres, had no crumple zones or airbags. I seem to remember them being death traps.
You should try a bicycle for safety: Almost 1mm of lycra for protection.
Can't remember the last time I did 70mph on a bike. Done 80 on skis though. That was scary.
I haven't done above 60MPH in a car for a long time!
"Probably like a lot of other subscribers here, I’ve got an EV on order. Much though I love conventional cars (especially classics), now that we have the technology to avoid pumping filthy fumes into the air, we really should adopt it where possible."
Hi Paul and other subscribers,
Is anybody aware of the London Electric Cars Company?
London Electric Cars - Convert your car to electric!
You keep your existing fossil fuel car such as a Daimler Double Six, the engine and fuel tank are removed but you keep your clutch, gearbox and transmission. The company fits an electric motor inside the engine compartment which is connected directly to the car's transmission. The company fits a battery where the fuel tank was previously located. This solves a lot of problems such as, no filthy emissions, no expensive costs associated with building a new car from scratch, such as all the energy costs and mining costs. It also means you don't have to buy a new or used car in order to drive an EV.
David.
I may convert my recently acquired V8 when I get bored of the grunt...or petrol gets too expensive :) ...but I have a feeling the attraction for me and others will live a while longer.
But I agree with the shift away from fossil fuels as an essential thing...however I do not think its easy to say that EVs are so environmentally superior. In fact, the optimum thing to do for the environment is run your old fossil car into the ground
Sounds like a good idea but price is very high and the range on some cars is low. If you do put large batteries in surely they need to do some major work on the suspension.
I'm going wait until prices come down. If I can get a used VW ID.3 for about £12k in 4-5 years time then I will consider it. By then we may know about how long batteries will last etc.
Paul. Your thoughts on this morning's Marshall Motor Holdings (LON:MMH) trading update would be very much appreciated.
As someone who worked in the electricity supply industry (a long time ago) the idea that we are going to seamlessly convert to electric cars is fanciful. The supply system was struggling to meet demand in a mild September. Some nuclear power stations are off load, the cross channel link is out of action and there has been little wind.
We need more base load generation either nuclear or fossil fuel with carbon capture.
When everyone down the street wants a 7KW charging point the network will have to be reinforced. The margin of safety in the supply system has gradually been reduced.
Plus just from yesterday’s news a French minister is threatening to cut off the cross channel link as leverage in the fishing row. And the newly opened link to Norway which is an excellent idea to exchange our excess wind for their hydro has immediately run up against the snag that it hasn’t been raining there due to record warm weather at the time their reservoirs would normally be filling up.
That would be stupid of them. If they have excess power and don't sell it to the highest paying bidder on the european grid, then they would be losing money. Also, EDF are big in The UK, so they could be damaging their own UK subsidary.
Never let politicians make engineering decisions. We end up with Fukashimas.
It will be interesting to see how electricity is going to be taxed for charging EV cars and it can’t be a general tariff as this will affect the poor disproportionately who can’t afford a fancy car.
Going along with Group Think,I’m saving the planet by not buying an EV and keeping my old car thus avoiding the pollution of manufacturing an EV car.
It will be interesting to see how electricity is going to be taxed for charging EV cars
Road pricing makes more sense than trying to replicate fuel duty revenue on recharging.
I just sold £17K's worth 29p limit order on open, happy with that over 100% profit, I amazed the the SP has not budged, I've had too much bad luck being a veteran of CAKE & NMC.
I guess you are referring to £FCCN. I’m also mighty relieved I didn’t hang on for the last penny, selling yesterday. I guess the acquirer has orders in to mop up shares in the market but if I was them I would be putting a quick hold on that.
Maybe they already know what the concerns are.
French Connection (LON:FCCN)
News of the FRC investigation into the French Connection (LON:FCCN) 2020
I just sold £17K's worth 29p limit order on open, happy with that over 100% profit, I amazed the the SP has not budged, I've had too much bad luck being a veteran of CAKE & NMC.
If i held i would be doing exactly the same - pure speculation but unless there has been anything else amiss flaggged up previously i would guess this has most likely been directly triggered by MIP looking at the books (and one would gues they may not be happy) and i would suspect that MAY give them reason to change offer made perhaps if it does turn out ?
The only thing that could perhaps indicate otherwise is the fact this news has turned up only 1 day after the offer . Whatever the reason not sure i would even wait for my coat before exiting (then again living in the north east i don't genereally do coats anyway so nowt missed there)
The cynic might suggest MIP saw something in their due diligence on £FCCN and tipped the FCR off about the need for an enquiry! Interesting way of stampeding reluctant shareholders into a sale.
Given the number of parties pawing over the data room during the acquisition process for the past several months it would seem unlikely that an accounting audit would find something material that everyone else has missed but stranger things have happened. I should probably sell my small position given the price hasn’t budged but haven’t done so yet.
Gus.
Well something made the historical potential bidders walk way over the past few years. I have kept a small amount but may flog it. This could rumble on for a while. Presumably the company needs to make a statement?
According to the FT the FRC decided to investigate at their July meeting. Now they tell us.
If that is the case surely the proposing buyers would be aware of this - or is this a surprise to them also? If the latter is the case then it is a bit more concerning.
News of the FRC investigation into the French Connection (LON:FCCN) 2020 accounts looks like a potential stick in the spokes to the sale. At the very least it would presumably be a MAC that would allow the buyer to walk away if there is something material in the FRC investigation (which will presumably take a fair bit of time). Just when we thought the fat lady might be warming up her tonsils ….
https://www.stockopedia.com/sh...
Gus.