Small Cap Value Report (Weds 8 Dec 2021) - QUIZ, MORE, EQLS, DWHT

Good morning, it's Paul & Jack here with Wednesday's report.
Poor Jack messaged me at 05:45 to say that he's not got a wink of sleep due to an alarm going off all night. Plus I have to dash off for an investor lunch, which means I'll only have a couple of hours, so today's report might be a little sparse. We'll do our best!
Agenda -
Paul's Section:
Quiz (LON:QUIZ) (I hold) - interim results show a convincing turnaround, despite the impact of restrictions on social gatherings in the first couple of months. Balance sheet is strong, with growing net cash. Current trading excellent. There's lots to like here, on a tiny valuation. However, any renewed covid restrictions remain a risk for the sector.
Hostmore (LON:MORE) (I hold) - inaugural trading update comes across positively. This company looks far too cheap to me, due to an overhang of sellers from the badly handled demerger. Details also provided of new site roll-out accelerating, for both its brands. Quite exciting I think.
Jack's Section:
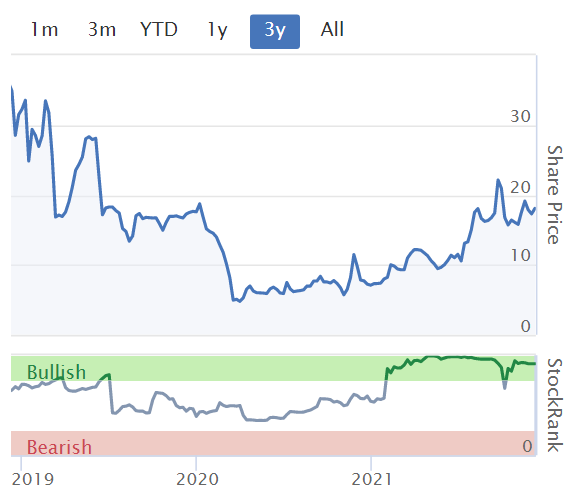
Equals (LON:EQLS) - strong update reporting accelerating growth trends, with FY revenue and EBITDA to be ahead of expectations. The share price fell dramatically in early 2020, but was also falling in H2 of 2019 (before Covid). However, a strategic pivot towards B2B opportunities appears to be paying dividends, so worth re-appraising the group’s prospects.
Dewhurst (LON:DWHT) - solid results with record adjusted operating profit but a more cautious outlook. Shares are illiquid and thinly traded, so it’s more appealing as a buy and hold candidate, though even then, building a position might take a while.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Quiz (LON:QUIZ) (I hold)
19.5p (up c.8% at 08:14) - mkt cap £24m
I have to keep this brief due to time constraints today.
There’s a presentation from QUIZ today at 09:30, on InvestorMeetCompany, which should be well worth looking at.
Key points from today’s interim results -
Revenues strongly recovering at £36.0m in H1, up 109% on the more pandemic disrupted prior year comps. Note that QUIZ specialises in special occasionwear, so it was particularly hard hit by the pandemic, when parties/weddings etc dried up.
Trading in the first 3 months of H1 was disrupted by pandemic restrictions on social gatherings, which were only lifted fully in late June 2021. Hence there’s further upside on these numbers, providing there are no more Govt imposed restrictions on social gatherings, which remains uncertain. Here’s a handy timeline of pandemic restrictions, as it’s getting more difficult to remember exactly what happened.
Underlying EBITDA has returned to profitability, after the heavy losses of the previous year - at £0.7m (H1 LY: £(3.3)m
Statutory loss of £(1.3)m in H1, although I would expect this to have been profitable, if we take into account the restrictions which impacted the first few months
Online growth of +43% through own website, which is now the focus. Including third party websites, total online sales +27% - this is encouraging, as I think investors are more interested in online than physical stores
Store restructuring last year means that all stores are now on short (2-year at inception) leases, and rents are turnover rents, not fixed. This is a big competitive advantage, as it has roughly halved rents payable on a typical store. There’s also some benefit from reduced business rates.
Liquidity is fine - currently (7 Dec 2021) £4.6m net cash, plus £2.5m headroom on bank facility - cash has been growing each time it’s reported this year
Balance sheet - looks strong to me, no issues at all - this is a well-financed business, which might surprise many investors, who seem to think the company is a basket case, when actually it’s recovered very well
Broker forecasts - I understand Panmures has raised its forecasts this morning, and sees profitability of £0.9m next year (which starts in April 2022) and £1.8m the following year.
Current trading - looks excellent, back at pre-pandemic levels, and bear in mind this is now on a much reduced cost base (halved rents). Really good online growth could excite investors, although it’s obviously coming from a low base -
.

.
My opinion - this is panning out exactly as I hoped, with a strong turnaround underway.
The market cap of just £24m looks way too low, compared with other small online fashion retailers such as Sosandar (LON:SOS) (I hold) and In Style (LON:ITS) . I think QUIZ has potential to re-rate considerably, once more investors latch onto the excellent turnaround. Although the poor track record is bound to weigh on sentiment for some. Personally, I'm not interested in the past, it's the future that matters, and the previous problems have been fixed (mainly onerous leases). Plus QUIZ was unlucky with the demise of Debenhams, which was about a quarter of its revenues at the peak.
Obviously since QUIZ is one of my biggest positions, I'm talking my own book here, but nonetheless everything is (as always) my straightforward opinion. It's not the best business in the world, and I'm targeting an eventual exit at c.40-50p, to be completely transparent.
I’ll read the announcement again, more slowly, on the train to my investor lunch today, so might comment further if anything fresh crops up.
Downside risk in the short term is clearly that the Govt gets bounced into more lockdown measures, as seems possible given that the omicron variant appears to be highly transmissible (although so far, also appears milder). So still some uncertainty, although QUIZ is clearly strongly financed to weather any further storms, so not a major issue.
There's so much less competition now too, it's quite amazing that QUIZ survived, whilst Arcadia & Debenhams closed for good - who'd have thought?
.
.
Hostmore (LON:MORE) (I hold)
Trading Update
Its first since demerging from Electra Private Equity (LON:ELTA) (I hold).
Obviously share price performance has been very poor so far, but I think that presents an opportunity, with the market currently pricing it incorrectly due to forced sellers who can’t hold individual shares for technical reasons.
Key points -
Oct & Nov 2021 - trading ahead of pre-pandemic level EBITDA
Xmas bookings “remain encouraging”
Recruitment challenges are being “navigated well”
Electricity & gas costs have been hedged
Progress on rent concessions with landlords, and constructive way handled, means landlords favour MORE for new sites
New openings accelerating - now have 3 “63rd+1st” bars operating, and another 2 in the pipeline. “Potential for rapid expansion”. 4 new Fridays sites are in solicitors hands
Improvement in guest satisfaction scores (lots has been done to rejuvenate the product, and the customer experience)
Ending of rent moratorium in March 2022 should provide more opps for new sites
My opinion - I think MORE is a cracking business, and the shares seem woefully undervalued.
As more investors learn about the business, I suspect the current price could end up looking a tremendous bargain. We don’t know how long it’s likely to take, for the shareholder register to sort itself out. Personally I don’t mind waiting - it’s too cheap on fundamentals, and sooner or later that ends up reflected in the share price.
Jack’s section
Equals (LON:EQLS)
Share price: 69.9p (+10%)
Shares in issue: 179,341,807
Market cap: £125.4m
Apologies for the delay - the building’s fire alarm went off for about six hours’ with no way of turning it off, so a night to forget! Thankfully, we’re well-stocked for coffee.
Equals is a fintech company focused on the SME marketplace offering things like multi-currency cards and travel cash. Some might remember it as FairFX a few years ago (which is now Equals’ consumer related travel division).
The StockRank is a middling 56, dragged upwards by strong momentum, but if we zoom out on the share price chart we can give a bit of context to that recent positive momentum.

Revenue has grown at an impressive 5y compound annual growth rate of 31.2%, but the company has so far struggled to translate this into cash generation. That picture has changed on a trailing twelve month basis though, and brokers are forecasting profitability in FY21E and FY22E.


Equals... is pleased to announce that is has significantly exceeded full-year expectations for both revenues and Adjusted EBITDA
This update covers most of the financial year ending 31 December, from 1 January through to 6 December. Revenue year-to-date was £40.4m, up 51% from £26.8m, and comfortably ahead of full-year forecasts.
It appears to be an accelerating trend too, as revenue from 1 October to 6 December (‘the period’) was £11.6m, up 105%.
These significant increases have been largely driven by strong demand for the 'Equals Solutions' proposition, which is a new multicurrency product aimed at larger businesses. This generated £3.1m in the year to date and £1.2m in the period alone. There’s also been ‘substantial’ growth in both Equals' Spend platform and its white-label business.
B2C travel-money products represented only 5% of total revenue in the period. This will rebound whenever travel normalises, presumably.
Importantly, ‘the group has now exceeded full-year profitability forecasts’. That goes some way to validating broker forecasts anticipating an inflection point in profits, and makes the stock much more interesting.
In order to drive further growth, Equals is re-investing and upgrading its sales functions, which will be reflected in higher staff costs in 2022.
Ian Strafford-Taylor, Chief Executive Officer, says:
I am delighted to be able to inform the market that the strong performance we saw in September and October has continued and allowed us to significantly surpass the market expectations for the full year in early December. Our results show the results of strategic steps we undertook three years ago to pivot the business to a B2B-focus and to invest into our platforms and connectivity.
Equals last reported a net tangible asset value of £7.4m after stripping out £34.1m of intangibles, with cash of £10.1m set against current liabilities of £16.2m. A little light, but then again this was never going to be an asset-intensive business. Hopefully the group is on the cusp of more dependable positive free cash flow generation. Net cash from operations has actually been positive for the past four years.
Conclusion
A great update for holders and one that suggests it’s time to reappraise the investment case here. Equals is well ahead of consensus estimates - with around three weeks to go it is reporting £40.4m of revenue - and the growth trend has been accelerating.
I tend to spend more time on profitable companies as this greatly reduces the risk in a single stroke, but it does mean I miss out on some promising turnarounds and aggressive growth stocks when they are valued most attractively. This could be a case in point.
Heading back three years to when Equals took ‘strategic steps… to pivot to a B2B-focus’ sounds like a good place to start in terms of re-familiarising myself with the company.
It’s the new multicurrency service for large corporates that is moving the dial, alongside white label partners and increased activity on the Spend platform.
The stock doesn’t look dangerously expensive even after today’s c10% rise to 69.9p given the growth rates. It could be that I’m missing some material risks, so I’d want to investigate the bear case too, and DYOR as always. The group has increased shares in issue over the years, and it looks as though the share price was starting to slide in 2019, before Covid, so H2 2019 is also worth looking into.
But on the basis of this update, Equals is worth spending some more time on in my opinion.
Dewhurst (LON:DWHT)
Share price: 1,464.1p (-0.4%)
Shares in issue: 8,081,398
Market cap: £118.3m
Looks like a fairly sensible company. Reliably profitable, good margins and returns on capital, solid cash generation. The thing that jumps out for now is: where is the growth coming from?

It’s not the kind of track record that deserves such a high rating as far as I can see, at least as far as growth is concerned. There are things to like about Dewhurst, however, and it’s worth monitoring due to its prudent nature and straightforward communication.
Back in July, the forecast PER was 31.4x, which was probably too high. Even now, at 18.4x, that’s affording a premium to the rest of the market. There has been a general expansion in multiples over the past few years, deserved to a degree, and you can appreciate the rerating in the long term share price chart.

So valuation and growth are my key questions here, although the company itself looks good. The shares are also illiquid - a 544bps spread and an EMS of 75 suggesting you can reliably trade around £1,100 worth of stock.
Highlights:
- Revenue +1.1% to £56.2m,
- Adjusted operating profit +6.8% to £9.2m,
- Profit before tax +41.9% to £9.6m, including £1.8m gain on disposal of property,
- Basic and diluted earnings per share +68% to 87p,
- Net cash from operating activities down from £9.3m to £5.5m (due to working capital changes).
Increased sales and record adjusted operating growth
Transport and Highways fell back 19% in the year after a strong year in 2020 supported by Government funded cycleway schemes in the UK. Keypad sales stabilised after the fall in 2020 and were broadly flat. The Lift division bounced back 4% from the fall in 2020 to achieve sales very similar to those in 2019. The recovery was primarily in the UK and Canada, which were the markets hardest hit in 2020.
Adjusted operating profit is before amortisation of acquired intangibles and pension GMP equalisation.
Further reflecting the long-term management focus is the completion of Dewhurst’s new facility:
The major project to build a new factory for Dupar Controls continued into this year. With some inevitable Covid-19 related delays, the completion of the building was a little later than planned, but we managed to move into the new premises during April. The sale of the old premises was completed in June. The total cost of the building (excluding land) was within expected parameters at a little over £5 million.
Outlook - sounds cautious, but I suspect a cautious tone might be par for the course at Dewhurst.
Sales in the first quarter of 2022 are expected to be lower than last year in most of our businesses, with the absence of the bounce back from lockdowns and lower demand for cycleway products. Market conditions are uncertain and difficult to predict further into the year.
Balance sheet - very strong, as you might expect from such a company. The current ratio (current assets / current liabilities) is 4.4x. Cash has increased from £18.1m to £20.5m, with no borrowings. Net tangible asset value of £43.1m.
The only real notable in Liabilities is the pension deficit, which has improved from £11.3m to £4.7m (with the discount rate raised from 1.6% to 2.05%). Dewhurst pays about £1.4m annually in contributions, which is manageable but a pain nonetheless.
Conclusion
Dewhurst comes across as a sensibly run, family owned industrials company. The valuation is more modest now than it was when I last covered it, and that was the real sticking point back then. Add to that the liquidity though, which remains a real issue.
This has some of the hallmarks of a good long-term buy and hold. I’m not dogmatically against debt but this is nevertheless good to see:
The Group is not subject to externally imposed capital requirements and the Group's philosophy is to have minimal or no borrowing where possible.
My sense is that it would take a lot to severely derail this enterprise, which suggests a stable and profitable base from which to continue operations. The key from here is to identify and quantify the group’s growth prospects. It stays on the watchlist.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Lord Gnome the W8-BEN Forms do last 3 years but I noticed today that having bought Somero Enterprises Inc (LON:SOM) yesterday and having signed the W8-BEN Form which is valid to 31/12/24 HL updated my other US Stock Newmont to 31/12/24.
I rarely hold stocks more than 3 years.
A word of warning about W8-BEN declarations - they do expire.
I think from memory they have a three year life (please check) and need to be renewed periodically. I use ii and they did not tell me when my W8-BEN was out of date. The first I got to know of it was when my dividend arrived and it was rather less than I had expected.
Surprised to see Solid State (LON:SOLI) price down close to 25% in last 3 weeks (I hold). I know Jack said at most recent trading update that price was probably up with events and there maybe short term issues re global semiconductor supply chains (that one again!). However, October 22 trading update and yesterdays's H1 interims indicated that managements's view on full year profitability were intact. Free research from House analyst, Edison, also seemed positive with 2022 H2 anticipated performance possibly ahead of expectations. Despite this general positivity the share price has reacted as though there was a medium profit warning. Be interested to hear what Jack and/or Paul think about Solid State (LON:SOLI) following the interim announcement.
It's all on tiny volume. The stock is illiquid so you've got a few retail investors selling post results, that's all. They probably bought anticipating an uplift a few weeks ahead of results and sell out after.
For me Solid State (LON:SOLI) is a good, steady medium/term business capable of generating 10-15% returns each year. Extremely well run, lots of management skin in the game and good at acquisitions. Management believe they can double over the medium term and I wouldn't bet against them having met the CEO previously (though not for a few years now).
Its not a fancy stock, management is conservative but it is illiquid so not unreasonable to expect 25% moves up and down as being par for the course.
Am expecting circa 60p eps so sitting on 15* now with a strong balance sheet and cash generative. Roughly on par with peers but probably merits a bit of a premium for me as it is higher quality than most.
I just wanted to add to yesterdays debate on Withholding Tax on US Stocks.
I bought Somero Enterprises Inc (LON:SOM) yesterday for my SIPP Account with HL having completed Form W-8BEN.
Today HL confirmed to me by secure message that as a result Withholding Tax would be reduced to NIL.
Thank you to the subscribers who brought this to my attention as I had in fact forgotten that on US Stocks you have to remember to buy in your SIPP assuming of course you have one.
This is another example of the benefits of Stockopedia due to the knowledge and wisdom of so many subscribers.
Indeed! Have to watch out as there's no heads-up on stocko stock pages (that I know of) that W-8 is required and the hassle of withholding taxes.
Another share like this is Spectra Systems (LON:SPSY)
The FT is reporting gov is about to implement plan B restrictions (in nakedly transparent attempt to distract form xmas party train wreck).
Hold on to your hats.
Apparently under the new restrictions we will still be allowed Christmas parties but they will have to be re-branded as "Christmas work related meetings" to ensure that there is no transmission of the virus at these events. A successful trial of this approach was conducted by the government last year.
Re Hostmore (LON:MORE) and its trading update. Biggest news - no skeletons emerged in first update post demerger! So no reason to distrust the more complete info in the prospectus etc
However, not sure what "new news" it brought in to justify the update and there there was not the transparency that would have really settled nerves. (I hold)
I would have liked a nice simple table of LFL vs 2019 vs the more ambiguous "greater EBITDA than 2019".
However, in this they follow many operators. Personally, I do not buy that this is commercially sensitive - what action can a competitor take that they would not already be doing if they learn LFL are up or down 2%.
Re Hostmore (LON:MORE) I agree with Zipmanpeter. Confident management who are doing a good job don't need so much to hide behind the commercially sensitive excuse. Whenever I see that I tend to think it's management that is sensitive about their performance.
Hostmore (LON:MORE) Agreed - seems strange not to publish LFLs on a regular basis.
I previously backed the sectors top two fast-casual brands imho (Wagas and Nandos) and tracking of LFLs is clearly a key KPI for the management team. Especially with roll-outs where you need to disaggregate LFL growth of the core estate, vs sites not yet mature and newly opened sites.
I don't buy into the 'commercial sensitivity' argument as most of the large brands feed their data into the "Peach tracker" which aggregates LFL data across the industry to show current trends https://www.coffercorporate.co...
They would always provide the LFL data of peers back to the businesses that contributed to the tracker as a way of 'keeping score' for management teams and Private Equity.
It's how I know that Wagamama had phenomenal LFLs (~+10%) for 3 years running pre-Covid vs competitors where LFLs were barely increasing above inflation (and so just offsetting increased cost).
LFLs data is increasingly important in the current environment where both wage, energy and food inflation means that if you are not increasing LFLs in mature sites (via volume ie better operational gearing and efficiency against fixed costs or price increases), you are effectively becoming less profitable over time!
Good interims from Ms International (LON:MSI) , chairman gives an unusually chirpy commentary.
Hi Paul!
Enjoy your party.... oops, I mean business meeting with cheese and wine. :-)
Hargreaves Services (LON:HSP) An inline trading update and Singer have introduced a buy rating and target price of 560p.
I thought the headline of the news Brief for Hargreaves Services (LON:HSP) this morning (screen capped below) was really disingenuous, given the content of the trading update which started as follows:
"Whilst, as expected, Revenue will be lower than that which was reported for
the six months ended 30 November 2020, due to the disposal of coal trading
activities in December 2020, Profit before Tax ("PBT") will be higher. This
improvement in PBT compared to the previous period is reflected across each of
the three business units."
Engage Xr Holdings (LON:EXR) presentation by management. This was fun and fascinating to do! We had the Oculus glasses to experience some of ENGAGE's metaverses, which was awesome. VR is a really exciting space. The applications for this are unlimited, from training and education right through to socialising! Read (and watch) Ready Player One, if you haven't. NFTs (Non Fungible Tokens) are somewhat bonkers, a virtual apartment being sold for $500k! I must emphasis having had the Oculus experience first, then being part of this presentation bought it to life. Without viewing in VR it looks a little more like a cartoon. EXR's clients include BMW, 3M and Facebook. Their revenue model is one off, subscription and market place including NFTs. This is worth a watch. Video (there is a podcast, but if video doesn't do it justice a podcast certainly doesn't!) Warning, there's now a Tamzin avatar!
Mind Gym (LON:MIND) interim results presentation from 3.12.21. New CFO is introduced. Some interesting insights into coaching and what makes a difference, alongside a financial and strategic update. Video & podcast.
WH Ireland interim results presentation from 7.12.21, with CEO, Chairman, CFO and Head of Wealth Management. The turnaround is yielding results, with revenue +38% and underlying PTP +70%. Discretionary AUM +67%. A good update across both Wealth Management and Capital Markets. Video & podcast.
Tomorrow, we will be posting an Andy Brough interview: 2021 markets and learnings!
Quiz (LON:QUIZ)
Paul
Balance sheet - looks strong to me, no issues at all - this is a well-financed business, which might surprise many investors, who seem to think the company is a basket case, when actually it’s recovered very well
Personally i would say the balance sheet of quiz is functional at best - certainly not strong.
If we say keeping inventories at current levels are fundamental to the business continuing to exist looking at the rest of the balance sheet we have the following.
I will ignore property and plant at £4.6 mill - this may seem harsh but is probably is fair in that it probably has little real value.
Also ignoring inventories of £9.6 mill we have
cash and debtors £10.7 mill
trade and other payables £11.4 million (excludes leases)
and loans £1 mill
so amounts owed out ignoring leases is £12.4 mill
So in steady state position they owe out £1.7 mill more than the have as liquid funds to carry on trading (ignoring inventories). To me i don't see how this position can be called "strong".Not a great position for a company making no profits. They have the £9.6 mill of inventories as backup but if thats needed to keep business "making profits" then position at present is that they are in hoc to bods they owe money to practicably speaking , unless they can deliver some much needed "profits" in the near future.
Note they do have £5 mill of cash in the bank so at least on that score the most important number is at least a tidy sum. I won't argue that funtionally speaking the current situation does not cause me any specific concerns - i am just slightly (or more than) picky when it comes to calling a balance street strong.
All IMHO - balance sheets can be very subjective things.
rmillaree,
You can't ignore inventories, that's crazy! Inventories turn into cash on a daily basis for a retailer. There's a healthy surplus on net current assets with QUIZ, and a healthy NTAV position for the size of the business.
Hence I think for most people, QUIZ's balance sheet would seem strong. It's fine for you to have a different view though, we all look at things our own way. But I have no reason to change my view, as QUIZ has a strong balance sheet by my metrics (strong NTAV for size of business, and a healthy working capital position - net current assets)
P.
Quiz (LON:QUIZ)
You can't ignore inventories, that's crazy!
"Inventories turn into cash on a daily basis for a retailer."
Well no they dont practicably speaking ,as you well know , as that cash is used to replace the inventory stock - if i have £10 mill of inventories at start of period and £10 mill of inventories at end of period - inventories has provided nil cashflow. You can realise cash but you have less items to sell and that will likely impact sales and profits.
To me inventories for quiz is like a factory for company that manufactoures goods - or planes for an airline. These items are necessary for the buisness to perform its basic functions. They are fine when it comes to having some clout to satisfy those that give you tick - but you don;t want to be selling them down to keep the roof over your head.
I won't argue such a situation is 100% perefectly normal for retailiers - lets be frank though when retailers go pop its rarely anything other than wipeout for shareholders. Being less bad that Mccolls or Supedry doesnt make it good though IMHO.
Hi rmillaree,
Your argument doesn't make any sense at all to me.
Inventories turn into cash on a daily basis, which is used to pay the creditors. So both constantly rotate. Hence the only logical way to view a balance sheet is to link the two.
Your approach is completely illogical to my mind. Why would you pretend that the inventories suddenly vanish, yet all the creditors have to be paid in full!? Maybe if they had a fire, and had no insurance, but in any other situation your view is illogical & erroneous.
I suspect you've dug yourself into a trench, and don't intend to budge an inch, so I'll leave it there. But you're wrong!
Paul.
I'm with Paul on this. Stock is valued at net realisable value, so this is effectively cash on the balance sheet.
...and if I was running the accounts, that net realisable value might be at cost or lower (firesale) not at retail sale price. So every time I sell £1 of stock on book for £2 retail sale price I generate £2 of cash. £1 is recycled back into stock and £1 margin. If you value retail business stock as firesale, most would be uninvestable other than the likes of SCS who is groaning with cash and suppressing ROE at the expense of investors.
Quiz (LON:QUIZ)
"Well no they don't practicably speaking ,as you well know , as that cash is used to replace the inventory stock - if i have £10 mill of inventories at start of period and £10 mill of inventories at end of period - inventories has provided nil cashflow."
Well where is the cash flow coming from then??
Also, I have been retailing for over 30 years. If you can't include the value of your stock as a current asset in the balance sheet then I've been bust for the past 30 years!!
Excuse me as I need to go and lock the doors now and speak with my landlord.
Quiz (LON:QUIZ)
Norfolk'n'Good
Well where is the cash flow coming from then??
You just need to look at the cashflow report to see where the cash is coming from - cash increase was £2 mill and payables increased £3.1 mill. So the improved cashflow was simply due to higher level of monies owed out to suppliers and the like - note nothing wrong with that particularly as i would be expecting them to increase paaybles as sales come back to more normal levels tahn was the case previously.
Also, I have been retailing for over 30 years. If you can't include the value of your stock as a current asset in the balance sheet then I've been bust for the past 30 years!!
I just chose to remove it from my simplistic valuation for the reasons i outlined. It seems fairly sensible to point out that they cannot pay what they owe on demand without selling or refinancing ref stock or getting money from other sources(i presume we would all agree).I even specifically said this is normal in retail situations and is normally tolerated by all parties . Practicably speaking probably not an issue but the mix of loss making and such a situation is certainly worth pointing out IMHO.
Re £quiz, Agree with rmilll and also what if the inventory doesn't sell. V easy in fashion esp with Boris winding Xmas work events down....
Yes, but only if the stock is now a write-off. It does happen, I agree, but not if a company is trading well and prudently.
An example of this situation I would point to is Pittards (LON:PTD)
At first glance they have a strong balance sheet, with lots of inventory (£13-15m if I remember correctly, last accounts?)
But the management have publicly stated that much of this inventory is leather they cannot shift or use for their products - they're trying to shift - and they also haven't taken a big provision against it. In theory it is worth something, maybe to the right buyer, but one now has to use a better estimate than what is publicly stated on the balance sheet, for this inventory.
Hi Suita5,
Re £quiz, Agree with rmilll and also what if the inventory doesn't sell. V easy in fashion esp with Boris winding Xmas work events down....
What the auditors required me to to, when I was CFO of a similar business to QUIZ, was that inventories have to be valued at the lower of cost and net realisable value. That's on a line by line basis.
Therefore, the risk of inventories not selling has to be provided for in stock provisions.
Hope that helps.
Regards, Paul.
Anyone else seeing that all the share prices, are yesterday’s on here?
possibly last night's AWS outage.
Yes. The feed seems to have broken. My other site for live prices seems to be working fine.
Yes, prices don’t seem to be updating.
Had an update from Support, there are some technical issues following last night’s maintenance. They are working on them now.
Indeed I'm still seeing yesterdays prices I was initially very pleased to see my account plus 1.9% again ! alas
Had same response, suggested they have a service announcement section on the front page for this sort of thing so they don't have to respond to multiple individual queries.
Hi Skweeka
I had a message pop up on my screen with a warning about the prices.
Encouraging update possibly from Hostmore (LON:MORE) this morning, however, whoever wrote it needs some pointers on communicating to shareholders. In terms of style and ease of interpretation it’s pretty dire - I’m going to need to re-read it several times and cross check with a lot of other information for it to be in any way meaningful to me.
Whilst the initial impression was good, it’s so convoluted I’ve got my spidey senses tingling that they’re trying to hide something, why else would you write in such a way? My colleagues, if I presented something that badly written to them would feedback with “word salad, try again”.
So, thanks for communicating with shareholders, please make it more digestible next time.
My experience at TGI Fridays in Bristol Cribbs Causeway yesterday evening was horrendous at best.
Greeter dressed very oddly and no smile or welcome worth mentioning. If it had not been my daughters birthday and we had booked I would have left there and then. All seemed like too much effort. Definitely nothing compared to the Fridays of old which was outstanding.
The server was very nice, gave a great impression from the off. However, the service was slow, no attention to detail. Food was cold, our food had to be replaced. We could see it was all backing up on the pass and not being managed well so I would expect they had numerous complaints, this would be true for any diner expecting a decent meal for the price paid.
Tables were not cleaned and setup for new customers. The tables around us were dirty when we arrived and still dirty when we left 2 hours later.
All in all one of the worst dining experiences I’ve ever had. I’m not expecting Michelin star food or service but I am expecting a quality meal and service for a fair price. Reading the comments about improved scores does not resonate with me.
Failed on all accounts and I shall consequently be selling my shares today.
Hostmore (LON:MORE) Tripadvisor does have terrible recent reports on service here, worse than of other branches. The reviews of. Nando's (for example) seem not as bad overall but still some dreadful experiences eg in Cambridge.
Is TGI managing the shortage of staff worse than its competitors?
https://www.tripadvisor.co.uk/...
https://www.tripadvisor.co.uk/...
Hostmore (LON:MORE) (I hold, for the moment anyway)
Most recent Trip Advisor reports on the Guildford branch are mostly and sadly v. poor. Long waits, cold food, cold restaurant and dirty lavatories etc. Seems to have been ok until recently.
Look like the new management have an issue to resolve and need to do it quickly if reputation is not to be ruined in the important pre Christmas spend period.
Nice one!!!!!
This is what investing is all about!!!
I do not look at the accounts, I do not compare the valuation with its peers , etc , etc , etc . I just buy or sell simply because I like or I hate the product.
It’s like trying Marmite and then going short on Unilever.
Morning IGPJ,
I'm not sure why you feel that way about Hostmore (LON:MORE) trading update. It all seemed very straightforward to me. Have just published my summary of it, hope that helps!
Best wishes, Paul.
Hi Paul, thanks for the reply and for summarising the RNS succinctly.
It might just be me getting out of the wrong side of bed, but it's just overly wordy, referred to things that weren't readily accessible and they use metrics that are meaningless on a standalone basis. I mean, a "cover" is pointless if we don't know what the average spend of a cover is. Same with some of the other figures they put in - there's no context to them, they're just numbers on a page without adding some comparatives, which means I need to go and find the prospectus and work out if we're in line or not. Some of that could be because casual dining isn't a sector I usually invest in so maybe not used to the jargon in this sector, but a lot of it feels like waffle and padding.
I mean your re-write says everything they needed to say in a much more readable way. The style struck me as "look how clever I am using big words" rather than an open communication to peers. I suspect the person who wrote it has a degree in English or Law! :)
Hi
Games Workshop (LON:GAW) trading update today. Too large for the SCVR, but I know a lot here follow it.
Looks not too great IMO. An 'in line' update. This is often not great news for Games Workshop (LON:GAW) share price. Price down -6.40% and falling, at time of posting.
Good news is licensing income is up, which I believe points to recurring revenues.
Portion from TU is this ....
Licensing income has increased to c.£19 million (2020: £8.7 million) driven by significant computer game licensing deals with Nexon and other major licensees. The related guarantee income is recognised on signing the contract in line with our usual accounting policy.
This bit is less encouraging though .....
As always, we remain focused on our core business metrics and are working tirelessly to improve the ones that are in our control. Our operating profit-pre royalties receivable is estimated to be down c.£15 million. However, excluding foreign exchange movements, increased carriage costs and the costs of paying more to our great staff, our core business operating profit is broadly in line with last year's exceptional performance.
Full RNS is here
https://www.investegate.co.uk/...
Regards
Howard
Howard I think that's a tad negative about £GAW. No doubt the market is seeing today's announcement very much as 'glass half empty'. Adding this morning's fall the SP is down c. 20% in the last 3 months. But that's on the back of recent market / analyst commentary that fans have gone on 'strike' following the IP crackdown. Today's update should be reassuring in that regard; the sales just don't bear this out and have held up well. Instead, as you say, the company has been primarily affected by a number of exogenous shocks: FX (well that's a random walk), higher carriage costs (surely transitory; they will eventually normalise), etc. I would argue that on the flip side the steadily growing royalties are incredibly encouraging - what better third party validation of the (growing) value of their IP. Step back from the noise and I think the current share price represents an excellent entry point. 25x PE for a company with a Gross Margin over 70% and a Net Income Margin over 30%. Deep double digit ROCE. A rock solid B/S. A more than decent dividend yield (albeit delivered a bit randomly). And strong growth optionality, although I appreciate that this is the unknown part.
I would argue the market, as so often, is being ultra short term. On a 5 year historic view the shares are obviously up hugely which no doubts adds to the nerves. Is recent performance just a flash in the pan? Nothing in the latest trading update suggests that's the case. I think for the patient holder this one has the potential to compound for some time to come, although like their dividends the journey will be lumpy. Sorry, I should add for transparency that 'I Hold'
Hi Phil117
Thanks for your response.
I do not disagree with your points at all.
Yes, my post was not upbeat. I have held/sold Games Workshop (LON:GAW) a lot over the years and am a fan of this great UK success story. My negativity got prompted by a number of observations.
Short term their increased operating costs, struck me as being not so short term. They wrote ....
Our operating profit-pre royalties receivable is estimated to be down c.£15 million. However, excluding foreign exchange movements, increased carriage costs and the costs of paying more to our great staff, our core business operating profit is broadly in line with last year's exceptional performance.
I do not sense that any of these three are necessarily short term. Are FX costs going to improve, I'm not at all sure. Are supply chain costs going to reduce, I'm not at all sure. Are staff costs going to rise further, I think they certainly will.
Taking a longer term view, Games Workshop (LON:GAW) s share price is now about where it was in Sept 2020. Yes it's risen but its also fallen back. This prolonged period of share price consolidation (15 months) is not a usual thing for Games Workshop (LON:GAW) s price. Alongside this, the Stocko factors (QVM) have fallen out of the bullish range since Oct 2020 and are continuing to fall towards the bearish range. Again, not a usual status for the Games Workshop (LON:GAW) factors.
There are other points I could pick out which prompted my not too positive post, but I sense that now Games Workshop (LON:GAW) is such a large market cap it needs to provide more in-depth details of its progress (assuming there is some) if they are to help the market to understand the strength of the investment case. My concerns are that they have lived on sentiment for quite a while and got a catalytic bounce as a stay at home stock in 2020 with the Covid lockdowns which catapulted them from a 7,000p range to a 10,000p range. But I am not sure they are providing sufficient information to the market to explain why they ought to remain in this 10,000p range.
I fear they are still behaving as a smaller entrepreneurial start up company, but they are no longer that.
Regards
Howard
PS I hold (much reduced holding though) and do believe Games Workshop (LON:GAW) demands a longer term view.
Howard. Thanks for the comprehensive reply! There is nothing like having your rationale challenged. So thanks in advance! I hear you and can definitely appreciate how one could read some of the issues you mention cautiously / negatively. If you allow me let me come back on your points with a more bullish interpretation:
1. FX - My only point here is that FX (especially in the short term) tends to be pretty random. A tale wind in one year can come become a head wind in another and vice versa. I don't believe it should really impact a LT investment decision. We do know however that Games Workshop (LON:GAW) is making a growing proportion of sales from international customers. And over the long term GBP has generally been in decline against many important currencies - Note: not to get into a political / economic discussion but given the UK's persistently large (unsustainable?) trade deficit, fiscal deficit, etc, perhaps it's not that surprising. Hence, to the extent this trend continues and manufacturing remains in the UK whilst revenues are earned in 'harder' currencies this should presumably be broadly LT positive.
2. Carriage Costs - Can't remember where I read this (John Authers?) but one of the big driving forces of the supply chain bottlenecks has been the relative huge growth in demand for goods vs. services due to Covid. This makes sense. For example, that cancelled £'000 family holiday / short break buys a lot of equivalent 'physical stuff'. And the evidence is that as people have switched consumption from services to goods this has driven the supply chain bottlenecks. I would argue that as the pandemic effect fades and spending on services returns this will normalise. Although I appreciate this could also have a marginal negative effect on demand for GAW's products.
3. Staff costs - OK. But this factor is impacting all businesses. It's not a GAW only effect. And employment costs are still a much smaller proportion of GAW's costs than say supermarkets, restaurants, airlines, etc, etc. They start with the benefit of an exceptional margin position with which to help absorb this cost
4. Share price - I just can't get too hung up on this. The share price has gone up significantly because the business has outperformed significantly and its unique characteristics have arguably finally been discovered by the market. Take any successful company which has compounded over the years and at some point you could say the price was X and it's now 3X. To which I would say and what's your point if that increase is merited. As an aside I do wonder with GAW whether there is an added psychological element at play with the high nominal share price per unit i.e. £95 per share sounds more 'serious' in some way than 95p. Would a stock split open them up to more investors who prefer to buy 100 shares at X rather than 10 shares at 10X. Obviously I have no proof of this. But they are definitely an outlier in their nominal share price versus most other listed companies
5. Shareholder Engagement - I'm not unsympathetic here. Yes, it could be better. But then there are countless examples of companies that have great IR departments, glossy presentations and are still total dogs. I would much rather have the converse. Management focused 100% on delivering value added rather than sucking up to the analyst community. In the end the numbers will speak for themselves
I still stand by my earlier post. On financial metrics this is an absolutely cracking business. If you believe that automation will continue to lead to increased leisure time, as hours worked continues to fall, as flexible working continues to rise, etc, etc, and as unique content has ever increasing value in an ever globalising world then GAW is a genuinely unique franchise, at least on the LSE. In a world of insane unicorn valuations, jam tomorrow stocks you can have a piece of this 'real' unicorn for 25x PE. I will put my neck on the line and say that in 10 years time when a lot of today's speculative Cr*p has long fallen back to earth today's entry price for GAW will be seen as an incredible bargain. Cheers
In a world of insane unicorn valuations, jam tomorrow stocks you can have a piece of this 'real' unicorn for 25x PE. I will put my neck on the line and say that in 10 years time when a lot of today's speculative Cr*p has long fallen back to earth today's entry price for GAW will be seen as an incredible bargain
Games Workshop (LON:GAW) is a good company which has performed extremely well historically, but its prospective revenue and eps growth at less than 10% is bog standard for most S&P500 members available on the usually pricier US market at a PER 10% lower. It’s fairly priced for the growth and a little bit better priced for the margins but it doesn’t have the operating leverage of software and data companies on richer multiples. A good company (and maybe a good investment) it is - but a bargain? Not any more.
Hi Phil117 (again)
Many thanks for a comprehensive and thoughtful response about Games Workshop (LON:GAW) . I do concur with you that I prefer Games Workshop (LON:GAW) s honesty over glossy PR speak. But too much brevity at their current stage of development might just be beginning to be an impairment. Obviously I can only speculate about this.
I think our respective views/posts have offered a reflective perspective of Games Workshop (LON:GAW) at the moment, and BnB has chipped in usefully with a post. Whereby that post concludes with this line which I think quite pertinent ....
'A good company (and maybe a good investment) it is - but a bargain? Not any more.'
I hope Games Workshop (LON:GAW) have a good Christmas selling season and with todays speculation about further Covid restrictions (Plan B, and now PLan B+ !!!!), then their sales could be strong and thus catalyse renewed interest from investors. I await their half yearly report 11th Jan with interest.
Many thanks for your posts/interactions.
Regards
Howard
[edit] Also Amala Foods (LON:DISH) raises a pitiful £210k at 0.3p, a sick 54% discount. Also £100k loan at 8%. Will keep it going till June. Super!
Just do what you can Paul, the quantity of reports on the SCVR has been monumental the last few weeks, I feel like we've been spoilt. No need to overdo it. Hope Jack has got his head down for a sleep.