Small Cap Value Report (Weds 9 June 2021) - BLTG, VP., GPH, DWHT

Good morning! It's Paul & Jack here with the SCVR for Wednesday.
I didn't finish yesterday's report until 16:30, so there were 6 companies covered in total. Here's the link, in case you missed the extra sections added yesterday afternoon.
Timing - I've got 2 company zooms to prepare for later today, and it's quiet for company news. So we're aiming to rattle through everything & have this report finished by 10:30 - tough target, let's see if we can actually do it! Today's report is now finished.
Agenda -
Paul's Section:
Blancco Technology (LON:BLTG) - FY 06/2021 trading update. Revenue meets, profits beat forecast (not stated). Cost-cutting related to the pandemic drove this out-performance. I'm not keen on the aggressive accounting at BLTG, and the patchy track record. Although it is now demonstrating growth, and meaningful profits, so could become interesting if growth continues. High PER (c.45) looks too pricey to me.
Vp (LON:VP.) - today's companies look generally dull, so I've gone back to this equipment hire company's update from yesterday. It looks good to me - a reasonable forward PER of 12, divis coming back, soundly financed & seems well run (apart from a fine from the competitions watchdog). Thumbs up from me!
Jack's Section:
Global Ports Holding (LON:GPH) - quarterly update light on financial data. The sale of Port Akdeniz helps the financial position but it's still too early to point to any meaningful improvement in trading.
Dewhurst (LON:DWHT) - interesting family-owned industrial company, but one whose share price has more than doubled recently and now finds itself facing some potential trading volatility in the short term. As with other companies, supply chain issues are flagged.
Paul’s Section
Blancco Technology (LON:BLTG)
270p (pre market open) - mkt cap £204m
Blancco Technology Group PLC (AIM: BLTG, "Blancco", the "Company" or the "Group"), the industry standard in data erasure and mobile device diagnostics, is pleased to provide the following trading update for the year ending 30 June 2021 ("FY2021").
Revenues - in line with the Board’s expectations. Significant growth in H2, despite sterling strengthening (bad for US denominated revenues)
Strong structural tailwinds (e.g. ESG)
Sales through channel partners has driven growth
Higher profit margins due to cost-savings, driven by the pandemic (e.g. less travel)
Overall - this is positive -
As a result, adjusted operating profit and cash are now expected to be significantly above the Board's expectations.
Capitalised costs - I’ve re-checked the last interim results, and the P&L and Balance Sheet look fine, no issues there. However, the cashflow statement reveals the truth - that this company doesn’t generate as much cash as it initially appears from EBITDA.
H1 saw £5.3m EBITDA, but lower down it capitalised £2.6m development spend onto the balance sheet, and £554k of property lease costs are now (ridiculously, under IFRS 16) shown in finance costs. Deduct those, as they’re just operating costs, and there’s only £2.1m of that EBITDA remaining in H1, less than half the headline EBITDA number.
Hence valuing the business on a multiple of EBITDA would lead to you over-valuing the shares.
My opinion - it’s a pity this update doesn’t contain any actual numbers! That wastes time, as investors have to dig out information from other sources, e.g. broker notes. I can’t find any recent broker research on BLTG.
Broker consensus shown on Stockopedia is for revenue growth of 10.5% to £36.9m for FY 06/202, and 5.12p adj EPS.
What does significantly above that mean? And does it matter, since out-performance is due to cost-cutting that might reverse in future years? Let’s guess at 6p EPS, which gives a PER of 45 - very rich, given that BLTG has had issues with its accounting in the past.
Overall then, given my concerns about the cashflow, and the high PER, I can’t get excited about this. I suppose the upside case, is if you think the story about strong structural growth for data deletion, could lead to continued performance improvements in future maybe?
There’s some evidence that might be the case - revenue and profitability are much improved from the rather dismal performance of the past, so if growth continues, then BLTG shares could become more interesting.
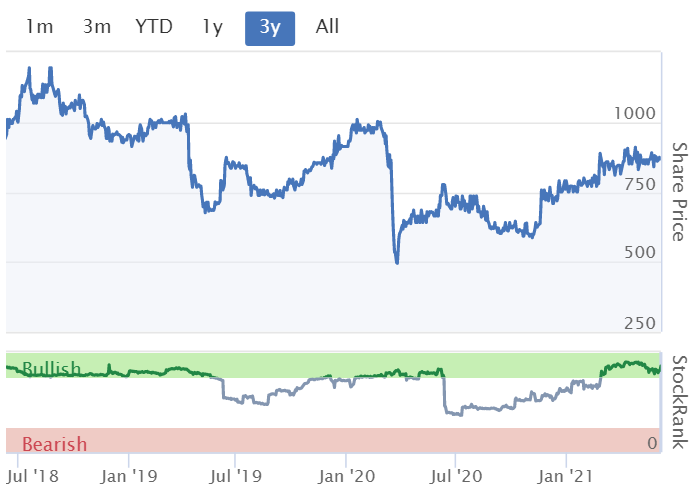
Shareholders certainly won’t be complaining about the recent share price performance. Although note that it has seriously disappointed in the past (2017) so cannot be seen as a consistent performer -

.
Vp (LON:VP.)
865p - mkt cap £349m
I’m not really interested in other companies reporting today, so thought I’d go back to this one from yesterday.
Vp plc, the equipment rental specialist, today announces its audited Final Results for the year ended 31 March 2021 (FY-2021) and an update on the Group's trading to date in FY-2022.
The PR summary says -
'PBT ahead of market expectations, debt significantly reduced, strong start to new financial year and supportive market backdrop'
I think a bit too much spin has been applied to that ball! Results are actually quite bad, but that’s clearly due to the impact on business of the pandemic -
Revenues down 15% to £308m
Loss before tax of £(2.3)m, vs profit of £28.4m last year (pre-pandemic)
Exceptional items of £14.9m - see note 2 - relates to a hefty fine from the competition watchdog in a regulatory review, and £7.4m in restructuring costs
Profit before tax, amortisation & exceptional items was £23.3m (LY: £47.1m)
So a bad year, no doubt about that. Does it matter though? I’m treating bad pandemic years as a one-off, because even if covid does persist, it doesn’t seem likely to cause another lockdown anything near as severe as lockdown 1. Subsequent lockdowns seemed to have little impact outside of the obvious sectors (travel, hospitality, retail, etc).
Restructuring - as with many businesses, the pandemic seems to have triggered cost-cutting, and efficiency gains e.g. from making greater use of technology. So this looks like a business that could emerge from the pandemic as more efficient & possibly more profitable.
Therefore, let’s skip to the outlook, as there’s not much point in poring over now historic, disrupted year’s figures.
Outlook & current trading -
Strong start to the new year FY 03/2022 (no figures provided)
Positive markets - e.g. construction & infrastructure sectors buoyant
Good customer contract renewals
“Increasing confidence in the prospects for the coming year”
"We have exited the year at nearly pre-Covid levels which is a better recovery than we anticipated at the beginning of the pandemic.
“We finished the prior year well and I am pleased to confirm that we have maintained this into April and May of the new financial year, which has started strongly for us.”
Dividend - final divi of 25p “reflecting our confidence in the prospects of the Group”
Balance sheet - looks OK to me. Obviously there’s a fair bit of debt, as I would expect for an equipment hire group. However it doesn’t strike me as excessive, and the overall balance sheet has a healthy NTAV position.
Dilution - I always check if companies have issued more shares in the pandemic, as that’s key information re the future share price. More shares = lower EPS, which means a lower share price, because most shares are valued on a multiple of EPS. Apart from technology shares, where a range of wacky alternative measures are used!
The good news here, is that VP seems to have had a roughly static share count of c.40m shares, and the current number in issue is 40.15m (near the bottom of the StockReport - be sure to check the historic sequence of shares in issue, and the current position further down). So no dilution - good news!
Forecasts - the heavily adjusted EPS is 46.8p, which looks a small beat against 45.2p broker consensus on the StockReport.
A punchy forecast of 71.5p for FY 03/2022 is about 7% above peak earnings in FY 03/2019. That’s probably justified, given the restructuring that’s been done, and strong outlook comments. That makes the forward PER 12.1 - good value I’d say, although hire businesses don’t tend to command big ratings.
My opinion - I like VP, and imagine there could be further upside.
It looks a good value share, is soundly financed (as opposed to Hss Hire (LON:HSS) for example), appears well run, and should provide a decent flow of probably growing divis in future. It's also proven the business model & finances are resilient in a (fairly short-lived) recession, as we've just seen.
Management seem good at making acquisitions too.
There’s a results video put out by Equity Development, which I’ll check out later, maybe at the weekend.
There could be further upside on this share, I reckon. 1000p looks achievable, with patience.
.
.
Jack’s section
Global Port Holdings (LON:GPH)
Share price: 132p (-1.49%)
Shares in issue: 62,826,963
Market cap: £82.9m
Global Ports Holding (LON:GPH) is a cruise port operator with a presence in the Caribbean, Mediterranean, and Asia-Pacific regions. The group positions itself as ‘the world’s leading cruise port brand’, with 19 cruise ports in 13 countries.
It also offers commercial port operations which specialize in container, bulk and general cargo handling.
This has not been the most successful IPO. Understandably, Covid has had a massive impact, but you’ll find that the decline began long before that.

As a result of this precipitous fall, GPH now offers striking value on a forecast basis. But can we trust these forecasts given the track record so far?

A Quality Rank of 39 seems flattering, given that the group qualifies for the Altman short selling screen, has negative ROCE and ROE, a negative operating margin, and has recently been spending far more cash than it generates.
The group has managed to keep shares in issue steady through this period, but debt has gone up. While this is exaggerated by more than £60m in capital lease obligations, the fact remains that debt now dwarfs equity, which is never a comfortable situation (although it can make for outsized returns if investors get it right).
Highlights:
- General & bulk cargo -31.7% to 12,700 tons,
- Container throughput +3.4% to 12,200 tons
- Total revenue +9.4% to $13.9m (cruise revenue +9.1% to $12m but down to $2m excluding construction revenue; commercial revenue +11.8% to $1.9m),
- Adjusted EBITDA down from $4m to a loss of $2.6m
- Net debt ex IFRS 16 capital leases down from $386.9m to $316m,
- Cash up from $99.5m to $170.7m.
I’m wary of the adjusted EBITDA measure given the nature of GPH’s business. Operating cruise ports must be fairly capital intensive and so I would want to focus on profits after depreciation. In FY19, for example, the group spent $45.3m on the purchase of fixed assets and so I’d like to see the replacement cost of its asset base in the headline profitability figure.
That aside, the increase in cash and decrease in net debt is encouraging.
I won’t dwell on the results too much as they are heavily affected by Covid. Suffice to say that cruise passenger volumes for the three month period fell by -99% YoY. GPH does say it has restarted some activities in its Mediterranean ports and in Singapore, though.
Total container volumes (TEUs) grew by 3.2%, and General & Bulk volumes fell 31.8% in certain low margin cargo items.
Probably the most significant development in the period was the completion of the sale of the Group's largest commercial port, Port Akdeniz, for an enterprise value of $140m. The equity value of Port Akdeniz after deducting net debt and debt-like items of Port Akdeniz at closing was $115m, with the buyer withholding $11.5m, which will be released in Q4-2021.
That’s close to the group’s entire market cap.
After paying transaction-related expenses and costs from the net proceeds at closing, this must explain the change in cash and net debt.
The group appears to have withdrawn from a $250m refinancing of unsecured notes ‘after a period of extensive engagement with noteholders, including certain key noteholders who formed an ad-hoc group’. Detail here is brief. What was the rationale? Did management agree with the ad hoc group’s points, or was this more of a confrontation?
GPH has also entered a five-year senior secured loan agreement for up to $261m with investment firm Sixth Street, conditional on a number of factors ‘which are expected to be satisfied shortly’. Warrants will also be issued over its shares to the lender.
Conclusion
It seems as though, while other areas of certain economies are seeing a recovery, GPH is still waiting.
The group did have just over $200m of net property, plant, and equipment on its balance sheet at the midpoint of 2020, but this figure will have changed following the sale of Port Akdeniz. Assuming its other ports make up the bulk of this PPE though, there are some hard assets here supporting the balance sheet.
That said, there is also some $435m of intangible assets making up around 50% or so of total assets. Alongside the net debt and other factors, I remain slightly wary of the financial position and will wait for more detail in future audited updates.
GPH could be in for a rebound in trading if everything goes well regarding Covid vaccinations. But I wouldn’t want to count on such an important external variable, particularly given that the company has not been a good investment during more ‘normal’ years.
There’s a dominant shareholder here, too - Global Yatirim Holding AS, with 62.5% of the shares. And the Major Shareholders tab shows Jupiter has been selling down in a hurry.
Admittedly this is just a quarterly update (which a lot of companies don’t even bother with) but reference to a single ‘Adjusted EBITDA’ measure of profitability means I can’t take this much further. Add to that the refinancing withdrawn at the last minute, with little by way of explanation, and I’m happy to move on to other opportunities for now. It will all come out in the wash.
All in all, there’s a possibility GPH trade could rebound handsomely in the future, but there are financial matters to wrap your head around and a lack of important detail in this update. It could be that there's good upside here, but there's also risk. There are probably better safer candidates out there.
Dewhurst (LON:DWHT)
Share price: 1,960 (-6.22%)
Shares in issue: 8,081,398
Market cap:
Dewhurst (LON:DWHT) is an independent global supplier of quality components to the lift, transport, and keypad industries. The Dewhurst family continues to make up the majority of its Major Shareholders.
Several positive elements jump out straight off the bat. A Quality Rank of 81 and double digit ROCE, ROE, and operating margin figures over the years. Earnings per share comfortably covered by operating cash flow per share. Steadily increasing revenue. Consistent dividend payments, stable shares in issue, and an habitual net cash position. All clear indicators that this could be a company where the investor’s money will be well looked after.
The only initial drawback is valuation, with a PEG of 1.8 and a forecast PE ratio of 27x. This comes after a strong run up in the share price, which boasts a 1Y relative strength figure of +99.5%.
All of those buyers back in the latter half of 2020 look to have done well to pounce on a quality business trading at a temporary discount.

There are two additional points to bear in mind here though: 1) the company has a dual share structure with voting and non voting shares (4.5m voting and 9m non voting), and 2) there is a pension scheme, currently in deficit to the tune of £7.5m.
These issues are worth investigating in more detail and might rule Dewhurst out for some.
Highlights
- Revenue stable at £28.88m (H1 20: £28.17m),
- Operating profit +28% to £3.53m,
- Net profit +22% to £2.13m (this anticipates a rise in tax rate from 29% to 37%)
- Basic earnings per share +27% to 26.38p,
- Dividend per share +13.3% to 4.25p,
- Net cash of about £16.6m, pension obligation of £7.5m
Dewhurst has been fully operational throughout the first half of the year.
Lift Division sales have been at similar levels to the prior year, with growth driven by the Transportation Division.
Deliveries of cycleway products have been strong, which is unsurprising given the well flagged cycling boom. This growth was partially offset by a further reduction in Dewhurst’s Keypad Division though.
Demand for cash and ATMs is still depressed and is expected to remain low. Whenever I resort to drawing cash out these days, the process does seem surprisingly quaint and archaic. Now to pay I just tap my phone on the nearest available surface and it seems to work out ok.
I assume others have developed similar habits and I wonder how much of this behaviour will stick post-lockdown.
In other news, the strengthening Australian dollar improved revenue to the tune of £0.3m.
The group flags ‘a release of pent-up demand during the first half of the year’ as some of its markets gradually relaxed restrictions.
Forthrightly, Dewhurst adds:
However there are now signs of some of that peak petering out. We expect there to be a lull in demand until economies fully open up again and customers start commissioning new projects. In the meantime we expect sales could be a bit choppy and unpredictable, particularly in regard to timing.
This is good communication and gives shareholders a sense of the outlook. As with Tandem recently, the group adds:
The pandemic has severely disrupted supply chains and it is taking time to get used to new arrangements. Lead times have extended and purchase prices are rising, which we expect will start to squeeze margins. Fortunately we held reasonable stocks going into this period, but it is proving challenging maintaining stock at the level we would like.
This is clearly an issue many enterprises are faced with at present. My guess is that this is temporary volatility that will work its way through the global supply chain, but there is a decent chance it could transform into something more meaningful so it is certainly worth monitoring.
Conclusion
Scrolling through the balance sheet, there is a £7.5m retirement benefit obligation to be aware of.
Pensions complicate equity investments, as they are a drain on cash flow and represent another stakeholder in the company, generally with more of a say than the shareholders. What’s more, the assets and liabilities of these schemes are often complex and hard to discern. Interest rates have a huge impact on the valuation of the liabilities.
That said, Dewhurst is clearly a healthy, profitable, cash generative company. In the period it made £683,000 in contributions to its pension scheme but generated a net £2.36m in cash from operations.
The group has been fairly active in terms of capex as well, though. A total of £2.47m was spent on investing activities. Add on nearly £1m in dividend payments and we see the group is dipping into its cash reserves to cover all the costs.
I’m not too concerned by this. The group has built up a healthy cash buffer of £17.6m over the years and has arguably earned the right to prudently use those reserves in order to maintain pension contributions, dividend payments, and a healthy level of investment into its operations.
The capex is largely to do with ‘developing Dupar's new property which is now complete and in use’. So we could see capex ease going forwards.
While this update sounds notes of shorter term caution that should not be ignored, this company bears more than a few of the characteristics required for longer term success.
If the price had not already more than doubled in six months, I would be quite interested to take this one further (due more to the clear language, guidance, and longer term operating and financial characteristics of the company rather than the cautious short term guidance itself).
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

25 comments
Details of the Cambria Automobiles (LON:CAMB) MBI emerged late this afternoon.
https://www.investegate.co.uk/...
In addition to the previously flagged recommended cash offer of 80p a share there is also an alternative (with strings attached) that will allow investors to convert into shareholders in the bidco. The strings are, at least, that the conversion shares are non-voting and limited to not more than 20% of the new share capital of bidco. Also the new shares will not be listed/readily tradeable (at least initially). At face value it’s not an especially attractive alternative but there may be more to it when full details emerge.
Gus.
Thought where had I heard of Dewhurst before, butchers came to mind from old adverts -
Dewhurst, the chain of butcher shops that disbanded in 1995, is set for a return to the high street after the rights to use the brand name were bought by a marketing start-up. ... The company has acquired 9 other brands, including Glen Rossie Whisky and Zorbit, the original manufacturer of towelling nappies.
Presume another branch of the family who liked electrics.
Presumably Sloth, on the comfy sofas.
Dewhurst (LON:DWHA), Dewhurst (LON:DWHT)
Very useful write up by Jack. I like conservatively run family companies like Dewhurst holding net cash & being run for the long term.
I can understand the objection to dual share structures - the NV shares are very much at the mercy of the (family) holders of the voting shares.
However, if you become comfortable with the concept, company & main shareholders, which shares to hold? Personally, I nearly always hold the NV shares :
Jack has reservation about value for DWHT - DWHA is a lot more attractive in this respect. IF you're comfortable with holding NV shares.
We hold DWHA
Hi garbetklb.
I also hold Dewhurst (LON:DWHA) in preference to Dewhurst (LON:DWHT) for the reasons you outline. While I like the company and am happy with it as a long term hold, it seems hard to justify an 11% bid/offer spread given the reasonably high (45%) level of the free float. Makes it a bit of a lobster pot share.
Gus.
Paul/Jack,
Thank you both for your excellent reviews of SCV companies - an excellent read each and every day.
As it’s particularly quiet today, would either of you mind reviewing the final results from ZPHR, published on Monday. I know this is a tiddler, but it appears to be on the cusp of something bigger with decent revenue streams starting to come through on tap (pun intended) and some serious Carbon-Neutral intentions announced yesterday. The SP has steadily increased by c.35% in less than 2 months.
Many thanks
Zephyr Energy (LON:ZPHR)
Would that be the Zephyr Energy that used to be Rose Petroleum and was Vane Minerals before that, it has total value destruction writ large (joined the 99% loss club) and still continues... It is a lifestyle company for the directors.
Sorry, I don't look at anything with the words "Resources", "Mining", or "Energy" in the name, because that's a specialised sector, where I have little to no expertise.
Sorry about that.
Regards, Paul.
SCS (LON:SCS)
Shareholder The LORD Almighty himself has reduced his holding from 3% to 2.4%.
https://www.stockopedia.com/share-prices/scs-LON:SCS/news/scs-group-plc-notification-of-major-holdings-urn:newsml:reuters.com:20210609:nRSI3065Ba/
That very much made me chuckle.
I wondered what cardinal sin SCS had committed
I wondered what cardinal sin SCS had committed
I heard even God needed to do a bit of topslicing on his/her day off , so it may not be a bad reflection on the company.
That's the trouble with omniscient dieties - you're always worried that they might know something you don't.
For one minute I thought you meant Michael Burry (Scion Asset Management) until I read the RNS... he owns some stock in SCS.
Hi Paul,
Itaconix (LON:ITX) did a small placing at 12p a share following their trading update yesterday. Definitely worth taking a small look. Potentially a coffee can share for me.
Thank you for all your invaluable insights - it's all very much appreciated.
Hi joshwood,
You probably need to read the 100 Baggers book again, because Itaconix (LON:ITX) is nothing like a coffee can stock! Tiny company, loss-making, making big promises for new products. Hence to me it looks a highly speculative jam tomorrow, story stock type of share - which proliferate in bull markets, then fizzle out over time usually. Hardly any of this type of share succeeds as promised.
Why on earth is it valued at £54m when revenues in 2020 were only $3.3m, and it made a $1.6m loss for the year?
Very much at the speculative end of the market, and I've learned from experience that this type of share is very rarely a long-term winner. They're often good for short-term trades though, as waves of speculators pile into sexy sounding stories. Then they crash when reality bites some time later, usually.
Definitely not for me. I hope you've also got some better quality stuff in your coffee can! I'd call this own-brand instant coffee, at best! Or maybe the dregs from a used filter? ;-)
Alternatively, you might have found the proverbial needle in a haystack, possibly. Very occasionally, a jam tomorrow stock does well long term, as opposed to short term spikes which can be lucrative for nimble traders, who get out before they crash.
Regards, Paul.
The coffee can case for Itaconix (LON:ITX) would be that its speciality chemicals are being designed into an increasing number of consumer products, and therefore there is a long runway of virtually certain growth as these formulations have long life spans. Combine that with a megatrend towards more sustainable and natural ingredients and there is a sensible case for some spectacular revenue growth here for years to come . Speciality Chemicals companies like Croda International (LON:CRDA) are sneakily brilliant businesses that trade at very high multiples, so an emerging small cap chemicals company with an ESG tailwind with triple digit revenue growth is worth paying attention to .
Caution is always sensible, but ITX is currently my loss making story stock of choice. Why? Well unlike tiddlers announcing "partnerships", you can plot the future with ITX because every time one of their ingredients is included in a product formulation it becomes visible via the FDA product codes.
it inevitably takes time for product adoption to turn into revenues, but they are winning serious clients. Long term, substituting organic for petroleum derived ingredients looks like a hot spot to me.
But yes, tempest any interest with extreme caution.
Jon
My morning smallcap tweet: Gulf Marine Services torpedoes holders with 52% discount fundraise
Gulf Marine Services (LON:GMS) Seeing Machines (LON:SEE) Tungsten (LON:TUNG) Cloudcoco (LON:CLCO) H C Slingsby (LON:SLNG) Yourgene Health (LON:YGEN) Itaconix (LON:ITX) SIMEC Atlantis Energy (LON:SAE) Newmark Security (LON:NWT) Blancco Technology (LON:BLTG) Remote Monitored Systems (LON:RMS) Dev Clever Holdings (LON:DEV), Anexo (LON:ANX)
Gulf Marine Services (GMS) £11m placing & OO at 3p, a disgraceful 52% discount, to cut debt. Why be 'pleased to announce' this? [SP=6 Cap=21m]
Seeing Machines (SEE) A$1m 5 year contract from CAE Australia to integrate precision eye-tracking technology for an Australian defence industry customer. [SP=9.6 Cap=365m]
Tungsten (TUNG) CEO scarpers, new one appointed. He is thanked. [SP=38.5 Cap=49m]
CloudCoCo (CLCO) CFO scarpers 'for personal reasons'. He is thanked. [SP=1.48 Cap=7m]
Slingsby (SLNG) Jan-Apr rev up 6% cf 8% Jan-Mar. Margin still under pressure, likely to persist. "Whilst the Group's sales grew in 2020 due to demand for Coronavirus related products, the Group has not experienced the same level of orders in April and May 2021...also heightened potential for credit related issues should customers become insolvent.." [SP=221 Cap=3m]
Yourgene Health (YGEN) licence and supply agreement with a leading US precision medicine co for an initial term of three years from Apr 2022. Licenses Flex Analysis Software. Co will supply sample preparation reagents and instrumentation to support the planned launch of a new clinical reproductive health screening service across all US states. "We look forward to enabling our partner to launch a competitive clinical offering into the US market in 2022 and we anticipate that this partnership will generate accretive multi-million dollar revenues for Yourgene in the years to follow." [SP=13.39 Cap=97m]
Itaconix (ITX) £1.1m placing at 12.1p, a 3% disc, for working capital and new product development. [SP=12.55 Cap=54m]
SIMEC Atlantis Energy (SAE) re SIMEC UK Energy Holdings (the major shareholder of SAE) - proceedings to challenge the validity of the receiver's appointment. Also receivers apply for a waiver from the Singapore Securities Industry Council which requires them to make a mandatory general offer for SAE. [SP=6.95 Cap=36m]
Newmark Security (NWT) H2 broadly in line with management's expectations. Guides FY(Apr) down 6% and a marginal profit. Outlook 'optimistic'. [SP=1.15 Cap=6m]
Blancco Technology (BLTG) guides FY(June) rev in line, adj operating profit and cash significantly above mgmt expectations. [SP=270 Cap=204m]
Remote Monitored Systems (RMS) gives up on Gyrometric Systems and hands it back to founders for nominal sum, cancels loan. "Gyrometric has some world class technology and a number of potential opportunities exist to exploit this intellectual property. However, it would have required significant investment over the next 12 months to take advantage of these opportunities." [SP=1.25 Cap=26m]
Dev Clever (DEV) Indian JV student careers platform has now gone live. Also "recently secured a material Indian contract valued at $1.5m, to implement the Company's Immersive Careers guidance and STEM-based virtual reality educational library at schools under central and state governments in India." [SP=25.5 Cap=152m]
In line: Anexo (LON:ANX)
Anexo (LON:ANX) - results as expected. The roads are extra busy out there (London / Dartford Bridge / M20 - GDP nightmare - the one thing that could probably have been worked on during lockdown? but that too much common sense for government) - so busy busy and lots of 'accidents' for these guys to sort out. Backlog from last year courts shut and also picking up VW emissions claim.
Credit Hire vehicles, repair and recovery, claims management services, legal support for recovery of costs through settlement or court action, personal injury claims.
Maybe the 'muckier' end of the insurance market, or less glamarous, but as they say 'where theres muck ....'
Need to find out who the competition is.
Their competition is: Auxillis which is part of NorthgateRedde, Accident Exchange (once listed publicly but now back private), Enterprise (car rental company), insurance companies (if they “intervene” in a claim then Anexo do not provide the hire and repair services etc). Also, the damages for whiplash for accidents from 31 May onwards have been severely reduced by the Government. Anexo are quite clever though and innovative. They have a heavy focus on hiring scooters to food delivery drivers which seems very profitable. My concern is that the Government still has a Part 2 of a review to complete. Part 1 led to the whiplash reforms stated above. Part will focus on hire and repair services. Could be bad for companies like Anexo.
Looked into this briefly a while ago and seems Anexo specifically focuses on sub prime customers involved in an accident and is able to charge insurance companies extremely high rates of interest for the credit hire - didn't look much further as felt they were basically exploiting a loophole and could easily face a regulatory clampdown. I avoided Amigo on a similar same basis. Happy to be corrected if this is not an accurate reflection of their business model.
Yes you are pretty much correct. I would say they are clever in what they do from a marketing point of view. I work in this area for many years and I would hold the shares but I am (or try to be) a long term holder. IMHO Part 2 of the Review will damage their business. The question is how much damage will be done? Part 1 stopped lawyers getting any costs for a standard whiplash claim and changed what would have been say £2500 in damages to a fixed £900. The lawyers only get a slice of this £900 now. The insurers are a powerful lobby voice! So now the most expensive head of claim after a road traffic accident is the credit hire element. Part 2 will look at this. Of course there is a chance that Part 2 never comes to fruition but Part 1 was still implemented during the pandemic. Part 2 suggests to me that the shares cant be a long term hold and the outcome of Part 2 would send the shares freefalling. But until then it may be ok…
Anexo (LON:ANX) - thanks. Up today so doing the 'run your winners' thing but now with a more careful eye.