Sosander - Weather-related Q2 sales delay ups the risk of a FY miss
Analyst’s view:
Some basic maths shows that Q2 was relatively poor, generating flat sales compared with the year before. The reason given is the hotter weather in September, which delayed sales of colder-weather clothes. The big question for me is whether these sales were merely deferred, or whether it is too much to catch up now that the weather has turned. So far, they have avoided discounting to clear stock, but if the stock doesn't shift in time, they may be forced into more promotional activity.
These risks make the current share price not particularly attractive given the high rating, as it leaves little room for an unexpectedly weak period, even if it is weather-driven. Confidence isn't improved by the lack of forecasts beyond the current fiscal year. This looks like it may be yet another stock that bought back shares at a value that ultimately proved far from the bargain management thought it was at the time!
We've not reviewed this on the DSMR for a while, and last time we viewed it largely negatively due to a profit warning. A lot has changed since then, and recent renewed growth trends mean that retaining this view is probably a bit harsh. However, with a weak Q2 and the risk of a warning increasing today, the best I can get is neutral.
Down 5% at 9.5p (£21.5m) - Half-Year Results
This seems a reasonable H1 revenue growth figure:
Revenue growth of 11% year-on-year to £20.8m (H1 FY26: £18.7m)
However, it looks a little underwhelming compared to what we knew about Q1 from the Full Year Results:
Net revenue of £11.6m, a 22% increase versus the prior year (Q1 FY26: £9.5m), which was a period where minimal sales were made through M&S due to their cyber incident
This compares to 14% revenue growth for the last full year.
The implication is that Q2 revenue was flat on the year before:
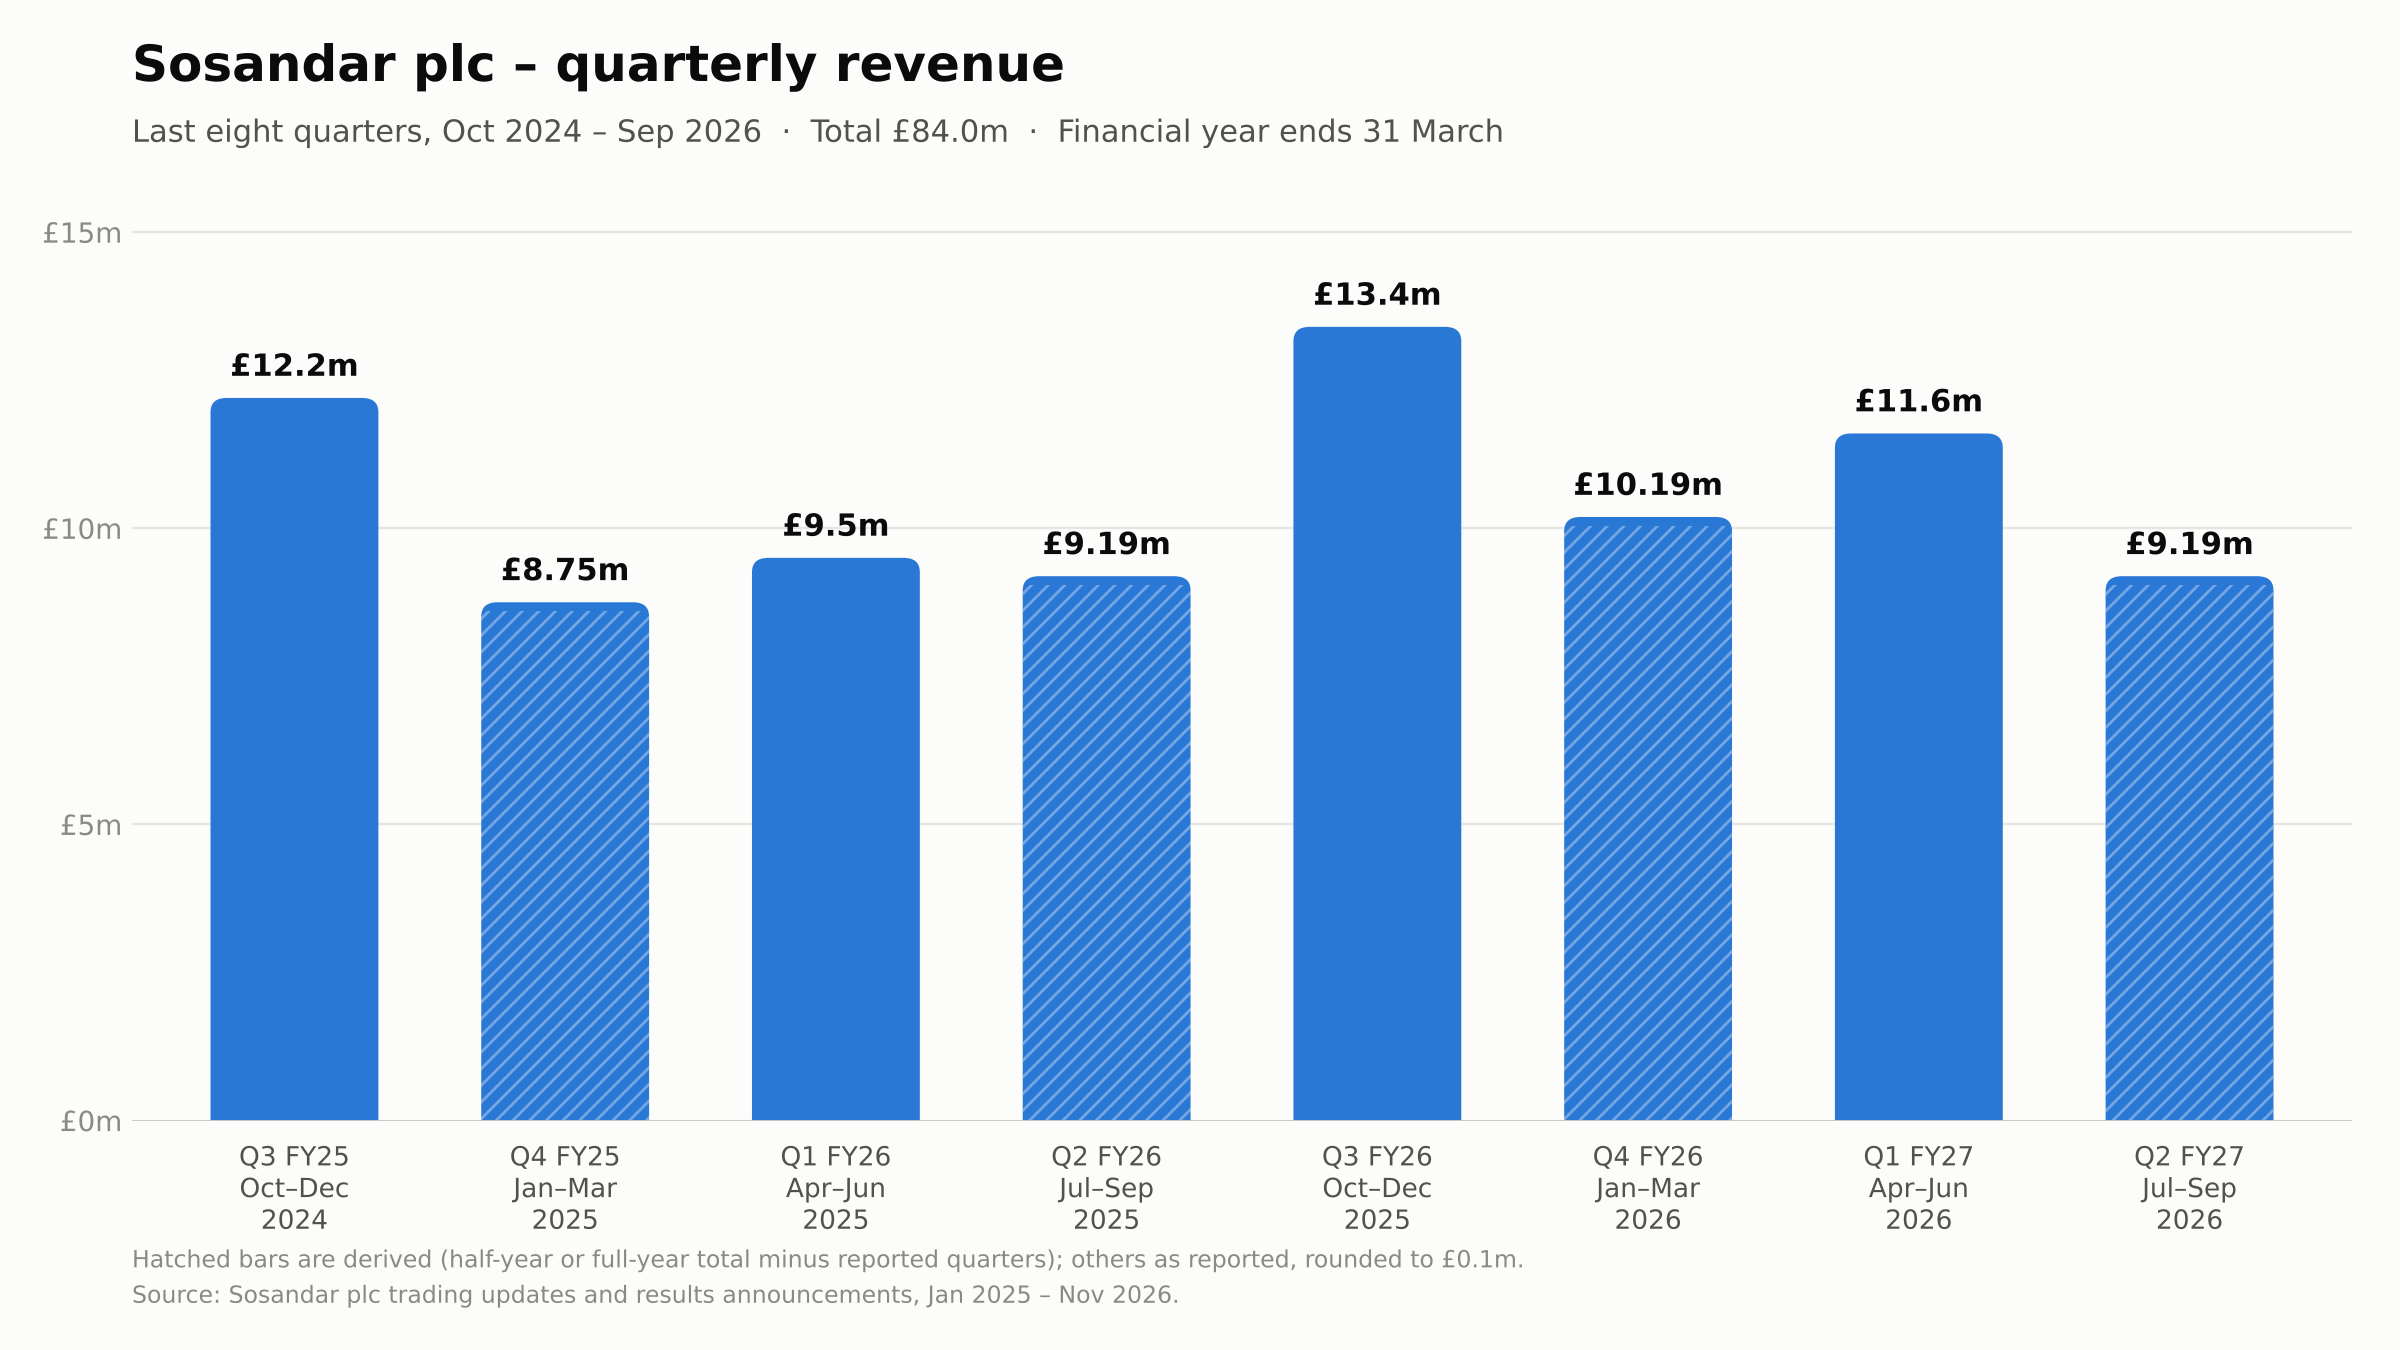
I think part of the impact can be explained by mild weather into mid-October delaying colder-weather range sales, as the company highlights. They suggest that this was merely sales delayed, although they are a little coy with any actual figures:
As anticipated, as more Autumnal weather has been seen, trading has strengthened significantly through October and is in line with expectations.
So far, the company appears to have avoided discounting to clear stock to keep margins:
Importantly, gross margin [post-period end] has remained strong at 68.0% (LY: 67.2%)
Forecasts:
This is a seasonal business, where H1 is typically loss-making, so this is not surprising:
Improvement in Adjusted loss before tax to £0.7m (H1 FY26: £1.1m loss), with profitability traditionally weighted to H2
They guide in line for the Full Year, and their broker Zeus says:
FY27E revenue of £47.0m, adj. EBITDA of £2.4m and adj. PBT of £1.1m are unchanged.
Zeus calls Q3 the key quarter, and the January trading update will reveal it. A weak Q3 leaves a lot for Q4 to make up. So I think risks remain if the delay in colder weather arriving leads to weaker Q3 sales overall, rather than merely sales deferred.
Even if forecasts are met, they don't seem particularly challenging, as it puts them on a forward P/E of over 20, and Zeus doesn't seem willing to put its name to forecasts beyond the current fiscal year.
Cash:
Cash has declined, but the bulk of this is due to buybacks during the period:
Cash balance of £7.1m (£8.4m as at 31 March 2026), reflecting expected working capital cycle in H1 and £0.9m returned to shareholders through share buybacks in the Period
Inventories increased by £1m over the last year, but this was funded by a £1m increase in Payables, making the overall net working capital position neutral year-on-year.
However, by the end of October this has seen a further decline:
Cash balance of £6.4m reflecting timing of inventory payments
This remains around 30% of the market cap, which makes the valuation multiple a bit more reasonable. However, I question whether a company should buy back shares at the current forward multiple, as it requires significant growth assumptions baked in (which their broker isn't willing to forecast) to make this the best use of spare capital.
Stock Ranks
Interestingly, the algorithms like this one call it a Super Stock. The Value Rank is picking up the low book value, despite looking expensive on earnings. And the share price performance gives a reasonable Momentum Rank:
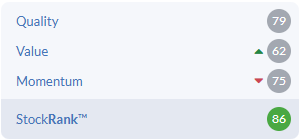
However, I'm not sure this designation will survive today's share price weakness, let alone a profit warning if the expected big recovery in Q3 sales doesn't materialise.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Sosandar (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?