SRT Marine Systems - excellent growth in revenues and profits but with lingering questions around cash outlook

Analyst’s view:
These results once again include a going concern warning, an identical one to last year. Given the enormous cash flow figure provided in the highlights, I find it odd that the company can't avoid a going concern warning in its accounts. It turns out that most cash flow is in the form of upfront customer payments, creating large contract liabiltiies on the balance sheet. But at the same time, the company also has very significant receivables of over £60m, which are worth reflecing on. Once again, I have quibbles and concerns when it comes to SRT, especially around how it communicates with investors, and so I'm inclined to leave our neutral stance unchanged.
Unchanged at 68.6p (£187m) - Final Results
SRT Marine Systems is "a global provider of intelligent maritime surveillance systems for sovereigns and maritime navigation safety systems".
I've spent many years being rather sceptical of its prospects, as an enormous pipeline of opportunities took time to convert into real revenues.
Serious revenues have now materialised for FY June 2026:
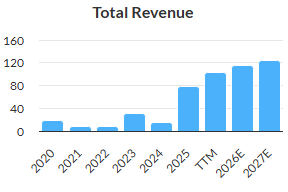
The company has delivered remarkable growth:
Revenue +46% to £114.1m.
PBT +653% to £10.7m.
£37.7m of after-tax net cash generated from operating activities (FY25: £1m).
Over £100m of revenues came from the company's "systems" business, as opposed to its "navigation safety" business.
The company's so-called "pipeline" is always the bit where I've thought investors needed to be sceptical.
Today SRT says there were "£218.4m of system contracts converted from £1.8bn validated opportunity pipeline during the year, increasing the Company’s total contracted order book to £539.5m." So roughly 12% of the pipeline has been converted into contracted orders.
There are now "validated new prospect contract opportunities" of some £2.4bn. I'd continue to treat this number very cautiously.
CEO comment is characteristically optimistic on the prospects for this pipeline:
“These results demonstrate how rapidly we are developing and growing as a global leader in sovereign civil defence systems. Despite converting 12% of our previously reported £1.8bn pipeline during the year we have grown the pipeline itself to £2.4bn and I expect to see conversion to continue at pace.”
Cash: £57.1m at June 2026, of which £27.4m is held as security for project performance bonds (insurance against a project going wrong).
The cash being held as security will be released back to SRT as it delivers on its contracts, "but we expect will be recycled as new contracts are signed."
Guidance: H2 weighting
No detailed guidance is provided but there will be a loss in H1 (July to Dec) due to "a heavy weighting of low margin infrastructure completions but balanced by higher margin SRT Tech Modules deliverables in H2."
Strategy: following a strategic review, they will "follow existing and new customer demand direction and expand into land and ‘low altitude’ air border surveillance and intelligence". They will also provide "a range of supplementary services such as UAV, USV and data services." UAV typically refers to drones, with USV being its seaborne equivalent.
Estimates: thanks to Cavendish for updating on this. They have increased their revenue estimate for FY27 by a massive 45%, to £179m, but they also see gross margin falling due to higher costs, and higher operating expenses. Their adjusted PBT estimate for the year increases by just 4% to £11.6m. They also reduce their cash estimate from £50.4m to £33.3m, of which they forecast that £23.4m will be restricted cash.
Graham's view
I've taken a fairly harsh line on SRT over the years, as I've always felt like its communications haven't quite matched up to financial delivery. This stance has been tested by the company's recent surge in revenues and profitability.
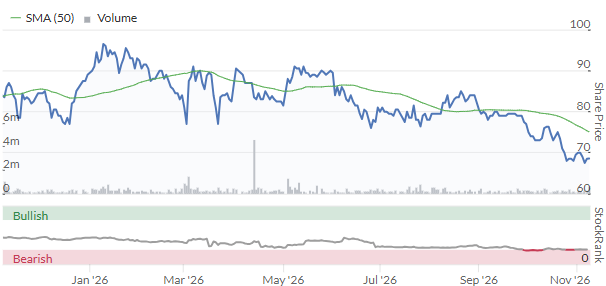
In April, for example, I maintained a neutral view on the stock on the news that it was raising fresh equity at 82p for reasons that seemed rather vague to me.
Investors at 82p remain offside for the time being:
Again, looking at today's results, I have some quibbles.
For a start, let's reflect on the fact that it took over four months to publish these numbers. That length of time would not be allowed on the Main Market, but it's permitted on AIM. Last year, the company managed to get its full-year results out on 22nd October.
Secondly, these results once again include a going concern warning.
Last year, the going concern warning was due to "the current rapid growth phase and the possibility of a mismatch between customer receipts and supplier payments which could require bridging finance". The company did end up diluting its investors during the following year.
This time around, we have an identical warning.
Given the enormous cash flow figure provided in the highlights, isn't it odd that the company can't avoid a going concern warning in its accounts?
Today's cash flow statement shows £37.7m flowing in from operating activities. Check the notes and you find that £34m of this is thanks to an increase in payables - mostly representing customer cash, paid upfront, that creates a liability to provide a service.
That happened last year, too, with a £38m increase in trade and other payables in FY25.
So customers are paying large amounts upfront, but the company still has a going concern warning. What gives?
I think there are a few reasons.
Firstly, the gross margin on the company's sales is 32%. The operating margin is 10%. Therefore, a large customer advance is not simply providing surplus cash which the company can use as it sees fit: it's funding a contract where SRT's final profit margin is not so large.
Secondly, despite SRT receiving large amounts upfront from its customers, it also has a significant amount of value tied up in receivables. Trade and other receivables now exceed £61m (last year: £52.6m).
If I create a receivables turnover ratio using these numbers, I get 2x. Roughly speaking, this implies that across all sales, SRT takes about six months on average to collect on invoices.
The combination of a large amount of cash received upfront from customers, and a high "receivables days" figure, is an unusual one to me.
Thirdly, there are the project performance bonds which help to protect SRT's customers and which tie up a large amount of cash.
Putting it all together, we can start to understand why the company might find that it's a little short of cash this year, even if it is profitable.
In conclusion, I'm inclined to leave our neutral stance unchanged here today.
Based on an EPS forecast of 4.2p for the new financial year, the shares are trading at 16x earnings. Not cheap, but also not expensive if it can continue to grow.
Personally, I would still be a little concerned about the level of customer concentration involved - it has six active sovereign customers. Hopefully this number will continue to grow.
I also continue to have reservations about how the company communicates with investors. For example, it led today with "£37.7m of net cash generated from operating (sic)" as its third major bullet point. Investors are left to remind themselves that the vast majority of this cash flow brings with it contract liabilities. And the "validated opportunity pipeline" continues to strike me as a rather unhelpful figure. I'm sure there are plenty of other companies that could talk about their potential sales in this way.
Overall, therefore, I remain very neutral on this share. It might prove to be a winner, but it's not a stock that tempts me personally.
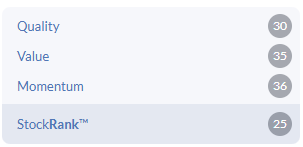
This is actually a much kinder view than the StockReport, which calls it a "Sucker Stock" due to a lack of Quality, Value and Momentum!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on SRT Marine Systems (4)
Comments here are also visible in the Daily Stock Market Report
SRT Marine Systems (LON:SRT) I hold
I would appreciate the team taking a detailed look at these excellent results. SRT is growing rapidly and evolving into the civil defence market using the same unique technology of its GeoVS system to collate and analyse data from a variety of sensors.
I'm on it, rwh3ue!
I hold as well and would be interested in views
SRT Marine Systems (LON:SRT) I hold.
No concerns about the systems, the main issue is finance up front as I'm sure Graham will highlight.
The company’s auditors issued an unqualified opinion but included a material uncertainty clause regarding going concern. This stems from rapid scaling: a potential timing mismatch between hefty supplier payouts and incoming customer milestones, compounded by loan note repayments falling due within the next 12 months.
Management emphasizes its strong historical record of securing bridging finance and notes it has remaining capacity under its secured loan note programme, though it explicitly states refinancing is not guaranteed.