Stock in Focus: Can Somero Enterprises continue to grow?

In 2006, concrete floor laying specialist Somero Enterprises was flipped back onto the AIM market by its private equity owners.
During its short period of private ownership, Somero’s balance sheet had been loaded up with net debt of about $20m. At the same time, western economies were hurtling with eyes closed towards the biggest financial crisis since 1929.
The result was inevitable. Somero came close to insolvency, but just managed to survive. The group has since repaired its balance sheet and benefited from the cyclical upturn. Somero shares have risen by 850% over the last five years and offer a bulletproof dividend.
Yet as shareholders will have noticed, Somero’s share price has fallen by 20% since hitting a post-2007 high in June. The shares have now given up all of this year’s gains. Concerns over the China-led emerging market slowdown are probably to blame, as are fears that the market may be approaching a cyclical peak.
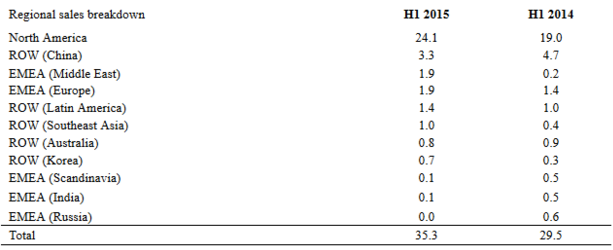
Are these fears justified? Somero’s interim results suggest a mixed picture. Sales in North America rose by 27% during the first half, delivering 68% of the group’s total revenue. The second biggest single contributor was China, where sales fell by 30% to account for 9% of group revenue. Sales were up in some other regions, but outside the US the picture seems very mixed, with limited growth:
However, despite Somero’s more uncertain outlook, Stockopedia’s rankings continue to rate this stock highly, with a StockRank of 97. The question is whether this year’s falls are a buying opportunity, or a warning to take profits while the going remains good.
Value opportunity?
Somero’s ValueRank has been rising as its share price has fallen. The fundamentals have remained strong and the stock now trades on about 9 times trailing earnings and trailing free cash flow. This free cash flow has been used to eliminate debt, accumulate net cash of $9m and fund a well-covered dividend.
Somero’s 3.2% dividend yield is quite respectable for an AIM-listed small-cap. Based on the firm’s cash generation, valuation and income, the stock looks cheap to me. Indeed, when the shares were trading at 143p in September, small cap editor Paul Scott described Somero as “apparently overlooked and mispriced”.
However, as Paul commented at the time, one reason for the apparently modest valuation is that P/E ratings and cash flow can be false measures of value for cyclical stocks. If the underlying market conditions change, then historical earnings are not an indicator of future earnings potential.
This point is well illustrated by the fact that Somero stock trades at a lofty 3 times book value. In my view, this premium is only partly due to its market-leading floor levelling technology. The valuation is also driven by Somero’s strong earning power during a cyclical upturn. A similar situation currently applies to UK housebuilders, most of which trade at more than twice their book value.
As was the case with housebuilding stocks, for much of the time between 2009 and 2012 investors could have bought Somero stock for significantly less than its book value.
Precise quality
Like Somero’s floors, the firm’s financials are of a very high quality.
Somero’s QualityRank of 98 indicates that Stockopedia’s algorithms can find almost nothing to be concerned about:
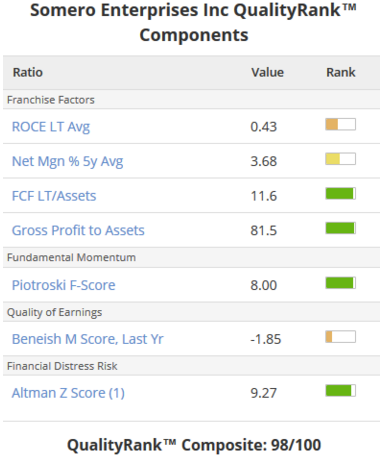
I’d tend to agree. The firm’s profit margins have recovered strongly since 2009, debt has been repaid and free cash flow generation is very strong.
One indicator of the sweet spot Somero is currently in is that last year’s gross profits were 81% of the firm’s total asset value (Gross Profit to Assets in the image above).
Other highly-ranked stocks in this sector generally seem to have a Gross Profit/Asset ratio of 30-50%, highlighting how well Somero’s business is working at the moment. This is reflected in an operating margin of 22%. However, I can’t emphasise enough that these are likely to be cyclical peaks, not long-term averages. Three years ago, Somero’s operating margin was just 4.4%.
Fading momentum?
With such a cyclical stock, strong momentum is more important than ever. Anyone, like me, who has bought into big mining stocks against the tide this year will understand this.
Somero’s MomentumRank of 69 is still respectable, if not outstanding. Here’s an overview of the numbers behind the rank:
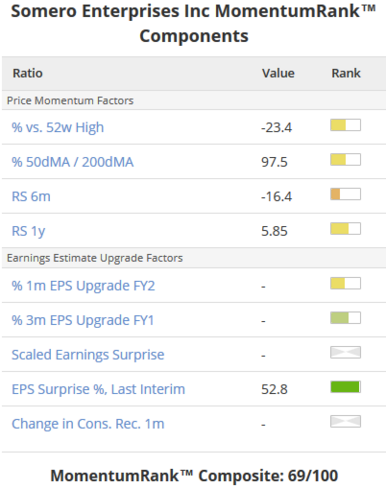
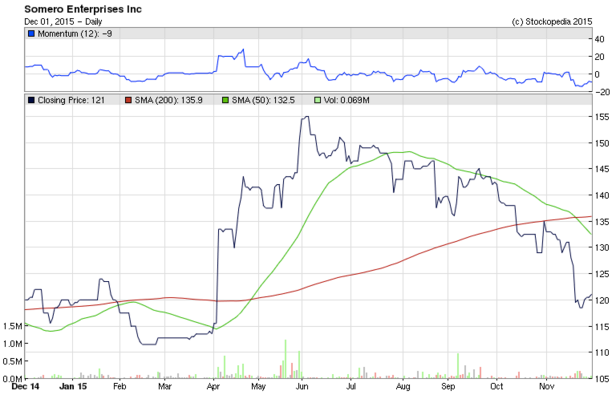
On the technical front, price momentum seems pretty limited. The shares are well off their 52% high and the 50-day moving average (dMA) is now slightly below the 200dMA. The other technical indicators I like to use, momentum and RSI, are also quite poor.
Although the last set of earnings came in ahead of expectations, earnings forecasts have not been upgraded since a modest boost in August. However, as broker coverage is restricted to the firm’s house broker, Canaccord Genuity, this isn’t necessarily surprising. I did notice an RNS on Tuesday announcing the appointment of finnCap as joint broker alongside Canaccord, so coverage -- albeit paid for -- may improve.
The latest forecasts from Canaccord suggest that even Somero’s house broker has a fairly cautious outlook. Earnings per share are expected to fall by 17% to $0.21 for 2015, and to remain largely flat in 2016. If Somero delivers on this, however, it won’t necessarily be bad news. On nine times forecasts earnings and perhaps 10 times free cash flow, I think the shares may be cheap enough to be appealing.
What’s the outlook?
The North American commercial property market appears to be very strong at the moment. This is supporting Somero’s profits in the face of weakness elsewhere, notably Russia and China.
Trading is strong in Europe, southeast Asia and the Middle East. Despite the current weakness in China, there are longer-term opportunities for growth in this market. Somero’s brand recognition is still low in China, but understanding of advanced standards of flatness is growing and the firm is investing in marketing to capture this growing demand.
There’s also the appeal of the dividend. Investors who bought Somero shares when they started to rise three years ago could now be enjoying a yield on cost of 8-12%. That’s worth holding onto for a little longer, in my opinion.
Overall, my view is that Somero’s strong balance sheet and modest valuation offset the cyclical risks, and provide worthwhile growth potential.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Thanks for the comment Roland nothing to argue with there. I always remember Rothchilds advice when asked how he made so much money. "I always left the last 10% for someone else" and the Analyst in 1989 when I asked on what criteria could he possible see Japan rising above 40000 plus " it's different this time" he said. So when I see a new system I like to test it just in case it's "different this time". Thanks for sharing your thoughts and hard work, if I didn't expect a correction I would be a buyer. Then again my caution has cost me millions over the years, but at least I'm still here.
Thanks for the analysis Roland but as I read through it I got that old gut feeling of "it if sounds too good" you know the rest! I guess it is no secret that I am uneasy about stock ranks but analysis is pointless without proof. Do you mind creating a Folio using the following simple screen Aim Cap >45 SR>95 and QR>90 SHORT. Obviously if momentum is strongly upwards this screen will probably fail, but I have been running it for the last 2 weeks and Somero is obviously in it.
Ken,
Thanks for your comment, I always appreciate feedback from investors with a different view.
I fully agree that there is a risk that Somero has reached the top of the cycle and could be approaching a cyclical downturn. Having said that, the balance sheet is very strong and I don't see this as a 'too good to be true...' situation.
Somero has a market-leading product and a strong domestic market. There is evidence of growth in some smaller overseas markets, too. The valuation is modest, but is not so cheap as to be an obvious warning of trouble ahead, in my opinion.
As regards StockRanks and proof, the only problem with waiting for proof is that by the time it appears, you've missed the chance to make a profit!
Regards,
Roland
There is no "AIM CAP' ratio and where does "SHORT" go please ?
LLG
Aim Mkt only Cap = Mkt Cap
SHORT = to sell shares that are not owned in the hope that the shares will fall in the near future. So the transaction page shows sell not buy. This will only work if the general trend is down or the specific share is overbought or bad news of some description is anticipated. Not recommended as the loss that can be incurred is unlimited, whereas if you "buy" the maximum loss is your stake.
The screen I was asking Roland to save is only a test and not recommended as a guide to wealth accumulation. As things stand I cannot back test StockRanks, hence the screen. The Aim market is extremely volatile and I am testing to see if the higher StockRank Quality combination is an indicator of a share being overbought. This test will obviously be effected by the market direction. But the Aim market has had a long bull run and as a result distortions can occur. Hope this answers your question and I apologies if it is over simplistic.
Ken
Roland,
Thank-you for this excellent bit of analysis. My finger was hovering over the 'sell' button. It is no longer...
Jasperthedog,
Thanks, although remember this isn't a recommendation, only my thoughts!
Roland