Stock in Focus: Skyepharma delivers a dose of growth

Shares in small-cap drug delivery specialist Skyepharma have risen by 915% in five years. Results like this sometimes make me wonder why I tend to invest in value and income shares. Yet the truth is that five years ago this was a pretty risky investment. Skyepharma could have been one of the many small-cap pharma stocks that has since fallen by the wayside.
We now know that’s not likely, thanks to a strong product range and partnerships with big companies such as GlaxoSmithKline. However, this doesn’t necessarily mean that it’s too late to see big returns from a new investment in Skyepharma.
Gathering momentum
This firm’s specialty is drug delivery. Skyepharma doesn’t develop medicines of its own, it finds new ways of formulating and delivering existing drugs to patients, using in-house technology such as specialist inhalers and oral capsules.
Skyepharma’s latest results make it clear that the firm’s portfolio of young products are gathering momentum. Revenues rose by 19% compared to the first half of last year, while adjusted pre-tax profits rose by 17% to £9.1m.
One of the firm’s big hopes for the future is flutiform, which combines two established treatments for asthma in one inhaler. Skyepharma’s inhaler technology is also used under licence in a number of Glaxo’s respiratory treatments.
The firm is investing in additional manufacturing capacity for its flutiform product and expects trading for the year to be ahead of expectations. Sales of flutiform are 129% higher than during the same period last year, suggesting the product is gaining market share from alternative treatments.
In this week’s column, I’ll ask whether the data back up the market’s expectation that the shares will continue to outperform.
Elevated rank
At the time of writing, Skyepharma’s StockRank has risen by 36 places to 80 over the last 30 days. Value, Quality and Momentum ranks have all risen sharply.
This is a good example of how a single set of results plus strong price momentum can trigger major changes to a company’s StockRanks. This comes about because the StockRanks are calculated using sets of financial ratios, plus price and earnings momentum indicators.
Does this make Skyepharma a better stock than a month ago? Possibly not, but the difference is that bulls now have more evidence to back up their case.
Even value is improving!
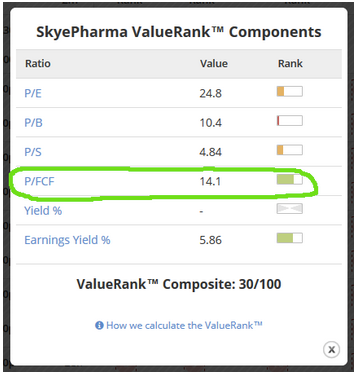
Value and growth stocks don’t often go hand in hand, but Skyepharma’s trailing P/E of 24.8 doesn’t seem outrageously expensive to me.
The firm’s ValueRank has risen by seven places to 30 over the last month - still at a premium to the market but not as high as it was. This is mainly thanks to a very decent price-to-free cash flow ratio of 14.1, and a reasonable 5.9% earnings yield:
Just a reminder that you can find these breakdowns for each rank by going to a stock’s sector page, clicking on the ‘Ranks’ tab and then clicking on each individual rank number.
Skyepharma’s strong free cash flow hints at the quality of this firm -- despite being in growth mode, it is generating positive cash flow. In my view, this is key to the firm’s valuation.
Although Skyepharma trades on 10 times its book value, in a sale situation the real value of its assets would probably be dictated by their expected future cash flow. A valuation of 14 times free cash flow seems pretty reasonable, given the firm’s likely growth.
A dose of quality
One characteristic that should appeal to almost all investors is quality. By this I mean financial health, profitable operations and the ability to generate free cash flow.
Skyepharma appears to have this in spades. The firm’s QualityRank has shot up 22 places to 93 over the last 30 days. One key element of this is a high Piotroski F-Score of 8 (out of 9).
Stockopedia weights this factor quite heavily because it highlights improving fundamentals using tests across many key aspects of a healthy business including;
- Ability to generate growing cash profits
- Reducing debts, improving liquidity and the ability to self finance
- Operating efficiency
You can see a breakdown of the F-Score by clicking on the link in the Health Trend box, on the right-hand side of each StockReport. Here’s how Skyepharma’s looks at the time of writing:
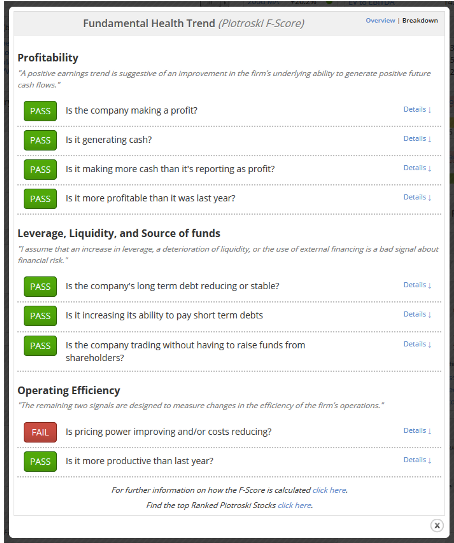
The single fail is the result of Skyepharma’s gross margin (revenue less cost of sales) falling from 56.5% to 50.5%. This is a crude but effective measure of pricing power, as it simply compares sales price to direct production costs.
However, I don’t think this is a big cause for concern. Skyepharma’s growth and changing product mix is likely to affect its gross margin, and may well explain this fall. My calculations indicate a gross margin of 53.6% for the first half anyway, suggesting that pricing and costs are stable.
An additional comfort is that the firm’s operating margin, which includes R&D, marketing and corporate overheads, is fairly stable.
Stockopedia figures show an operating loss for Skyepharma in 2014, which is due to the treatment of a £25.1m non-cash exceptional cost relating to the firm's refinancing last year. Skyepharma's own reported figures exclude this from operating profit. Stripping out the exceptional cost, the firm’s results show a reported operating profit of £21.6m, giving an operating margin of 29%, which is in-line with the 30% reported for the first half of the current year.
Momentum is king
A growth stock without momentum is like a fish out of water. It’s no good having a good story if the market isn’t buying it. That’s not a concern for Skyepharma. The firm’s MomentumRank of 80 indicates strong earnings and price momentum. The brokers are upgrading their forecasts aggressively and the company is beating estimates.
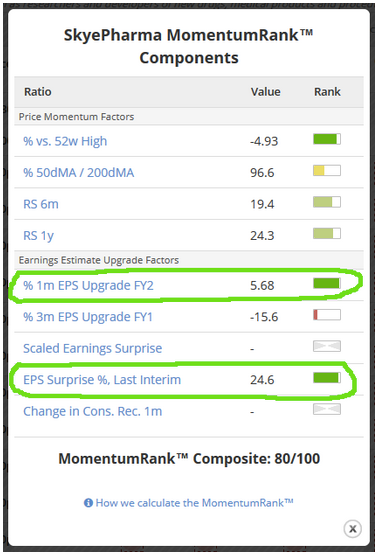
In my view this kind of strong, broad-based momentum could support further growth. Additional single-product acquisitions are possible, as of course is a takeover bid.
Skyepharma currently trades on a 2015 forecast P/E of 23.8, falling to 16.6 in 2016. I don’t think that’s excessive and I wouldn’t be surprised to see further gains. Please DYOR as always.
Disclosure: Roland owns shares of GlaxoSmithKline
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?