Stock in Focus: Will Zulu stock SThree recruit a profit in 2016?

I recently re-read Jim Slater’s growth investing classic, The Zulu Principle. This inspired me to take a fresh look at some of the UK stocks which the great man might have purchased.
This task was made much easier by Stockopedia’s Jim Slater ZULU Principle Screen, which saved me the effort of creating a suitable screen. The Zulu Principle screen has delivered annualised gains of 23% since its inception, making it the fifth best-performing Guru Screen on Stockopedia.
I was surprised to see that only eleven stocks currently qualify for the Zulu screen. This suggests that for growth investors at least, the recent market sell-off may not have been a great buying opportunity. Many stocks seem to remain fully valued or have an uncertain outlook for earnings.
Of the eleven stocks which qualify for the screen, only six have StockRanks of more than 80. One of these is recruitment firm SThree. This is a FTSE Small Cap-listed group with a market cap of £394m, and a StockRank of 93.
SThree owns a fairly diverse mix of recruitment businesses, which operate in a mix of geographies and sectors. The group’s main brands are:
- Computer Futures (IT/Europe);
- Progressive Recruitment (engineering/energy/W. Europe, Asia, M. East);
- Huxley (finance/W. Europe, Asia, M. East)
- Real Staffing Group (Healthcare/Life Sciences/W. Europe/Asia/USA)
I’ve listed each of these to provide an idea of SThree’s diversity. This is important because at this potentially late stage in the economic cycle, investing in such companies carries the risk of being too late to the party.
In my view, SThree’s diversity should provide some protection from this risk. Here’s a screen grab from January’s final results, showing how SThree’s gross profit breaks down across different sectors and geographies:
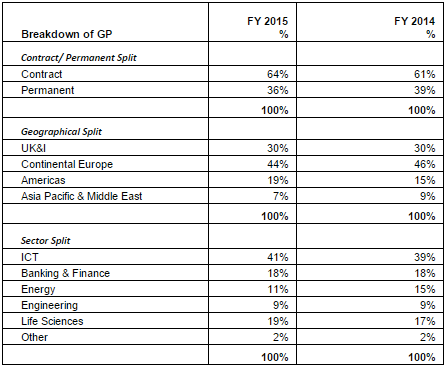
These figures suggest that IT and Life Sciences may be able to pick up some of the slack from the energy sector.
There’s more…
SThree has two other characteristics which suggest to me that the interests of the group’s management may be well aligned with those of shareholders.
Chief executive Gary Elden owns 2.8m shares. This gives him a 2.2% stake that’s currently worth about £8.5m. Mr Elden’s dividend income in 2015 was roughly equal to his basic salary, which rose by a comparatively modest 4.7% last year. This suggests to me that he’s likely to be keen on maintaining an affordable and progressive dividend.
Mr Elden and two of the three other executive directors have all worked at SThree for at least 20 years. According to SThree’s website, more than 90% of the firm’s senior management have spent their entire career at the firm. This kind of stability seems to suggest that decisions are likely to be made with long-term goals in mind, rather than short-term gains. Although there is a risk of self-serving groupthink, a full slate of non-executive directors should provide some protection against this.
The other thing about SThree is that it is not a heavily traded stock. According to Stockopedia, the three-month daily average trading volume is just 42,535 shares. That’s around £ 131,000 worth of stock at current prices:
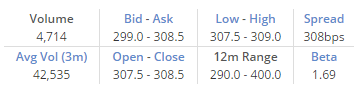
This means that patience may be required to build a substantial stake, but it could also be good news. As value investors know, there’s plenty of evidence that such cheap, unpopular stocks tend to outperform the market.
Is SThree cheap?
SThree has a Stockopedia ValueRank of 76. That’s not extremely cheap, but in my view some of the key value metrics are quite attractive:
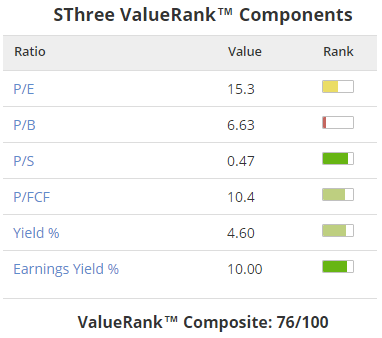
The highlights for me are a price/free cash flow ratio of 10.4 and an earnings yield of 10%. These confirm that SThree is a profitable business that throws off plenty of surplus cash. Given this, the stock’s above-average yield of 4.6% isn’t a big surprise.
However, it’s worth noting that free cash flow is not consistently this strong. Cash flow was very poor in 2014, for example. The main reason for this seems to be that the firm pays contractors before it receives payment from clients. This creates big shifts in working capital, which sometimes overlaps with year ends.
To smooth these numbers out, I calculated SThree’s six-year average earnings and free cash flow per share. Earnings per share averaged 13.8p, while free cash flow averaged 11.7p per share. These numbers suggest to me that medium-term cash generation is pretty healthy.
Quality characteristics?
According to Stockopedia’s algorithms, quality is SThree’s most appealing attribute. The stock has a QualityRank of 98. This is mainly thanks to its solid balance sheet with net cash, improving profitability and last year’s strong cash generation.
A Piotroski F-Score of 8/9 is complemented nicely by SThree’s Magic Formula score of 439, which puts it in the 86th percentile of UK stocks.
Both the QualityRank and Joel Greenblatt’s Magic Formula use return on capital as a ranking factor. SThree is able to generate a high return on capital because the level of capital deployed is quite low. That’s why this business generates high returns despite a very ordinary operating margin of 4.6%.
Asset-light businesses can be good companies to buy in a downturn, as they’re able to scale back their cost base far more easily than asset-intensive industrial firms.
Growth & Momentum
I don’t normally discuss Stockopedia’s GrowthRank, as it isn’t currently used in the overall StockRanks calculation. However, I find it a useful way to add context to the value and momentum ranks, so I thought I would highlight this newish feature.
GrowthRanks aren’t shown on StockReport pages in Stockopedia, but you can see them on the sector or index pages (SThree’s is here -- to see the breakdown of the rank as shown below, click on the rank number itself).
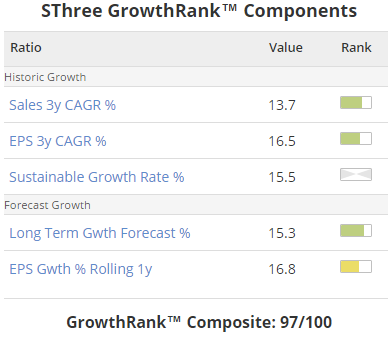
SThree’s GrowthRank is 97, thanks to a remarkably consistent run of sales and earnings growth over the last three years:
The outlook also appears strong. This isn’t obvious from the MomentumRank, which is dominated by the stock’s recent decline:
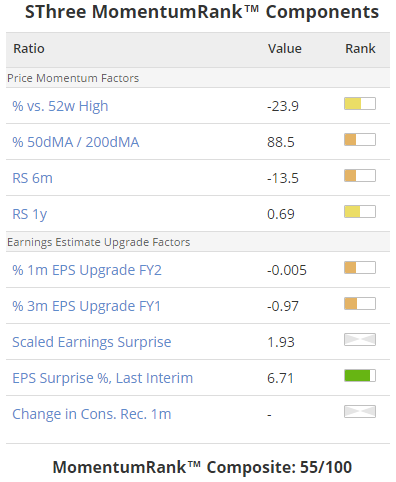
The one bright spot here is that SThree’s latest results were ahead of expectations.
Further earnings growth is expected this year. Earnings per share are expected to rise by 15% to 23p, putting the stock on a forecast P/E of 13.2. There’s also an attractive forecast yield of 4.7%.
The only question is whether the global economy will continue to support SThree’s growth. The firm struck a cautious note in its outlook statement in January:
"While the trading environment remains broadly positive in the majority of our territories, we note that the global macro-economic uncertainties we identified in our last trading update have increased further recently, with greater risks to global growth. Oil & gas market conditions remain challenging and FX volatility persists.”
At the current valuation I believe there is the potential for further gains, but we’ll learn more on 11 March when SThree delivers its Q1 trading update.
As always, this is only my opinion and certainly not advice. Please DYOR and share your views in the comments below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Anthony Miller of TechMarketView writes today:
If you want to know who’s winning share in the traditional UK ICT staffing market you don’t have to look much further than UK-headquartered, international multi-discipline recruitment firm, SThree. While most of its peers registered single-digit ICT net fee income (gross profit) growth, SThree recorded a 20% leap in its first quarter (to 29 Feb ’16). The only recruitment firm seeming to do better was FDM Group with its non-traditional employed contractor model.
But in the UK market overall, SThree appeared to underperform peers, with NFI down a tad in the quarter on a yoy basis, though a distinct improvement on the 6% decline the prior quarter. SThree CEO Gary Elden echoed peers, alluding to ‘signs of slowing growth in our UK Permanent business’.
Balancing the swings (most sectors) against the roundabouts (Energy sector – down 34%!), aggregate group NFI growth of 10% is still a pleasing result in what Elden refers to as SThree’s ‘seasonally least significant quarter’.
FREng,
Thanks for posting this, the trading update these comments refer to is here:
http://www.investegate.co.uk/sthree-plc--sthr-/rns/trading-update/201603110700097567R/
Regards,
Roland
Roland, it was not in the Zulu screen on 2nd February 2016 and 2nd January or December either? It may have been in November as it did qualify for 2 screens then but I can only see 1 of them.
I tend to agree there is still not much value around, I think in early February there was a few opportunities such as Marshalls (LON:MSLH), also Telit Communications (LON:TCM) and Trakm8 Holdings (LON:TRAK), have fallen back considerably. Some housebuilders also are looking better value now but I don't Jim does those?
So what is the reason for SThree disappearing from the Jim Slater Zulu Screen today?
Johnbush,
Murphy's law strikes, I'm afraid. SThree (LON:STHR) isn't in the list of stocks demoted in the last 24 hours so I think it must actually have disappeared on Wednesday -- within hours of me writing this piece!
Screens are of course purely mechanical, so the inclusion or exclusion of a stock doesn't necessarily mean a dramatic change in the outlook for a company. Instead, it may just mean that the value of a certain ratio has moved above or below the inclusion threshold.
The exclusion of SThree from the ZULU Principle screen appears to be a good example of this.
As far as I can tell, this stock has dropped out of the screen because its 1yr Relative Strength has dropped below 0 (it's -1.1% as I write).
SThree still appears to comfortably meet all the other requirements for the screen:
http://www.stockopedia.com/screens/jim-slater-zulu-principle-screen-19/
I hope this is of some help!
Regards,
Roland
Thank you Roland. STree seems to have a lot going for it, but I shall stick with the Empresaria momentum for the moment.