Stock Pitch - Codemasters (LON:CDM)

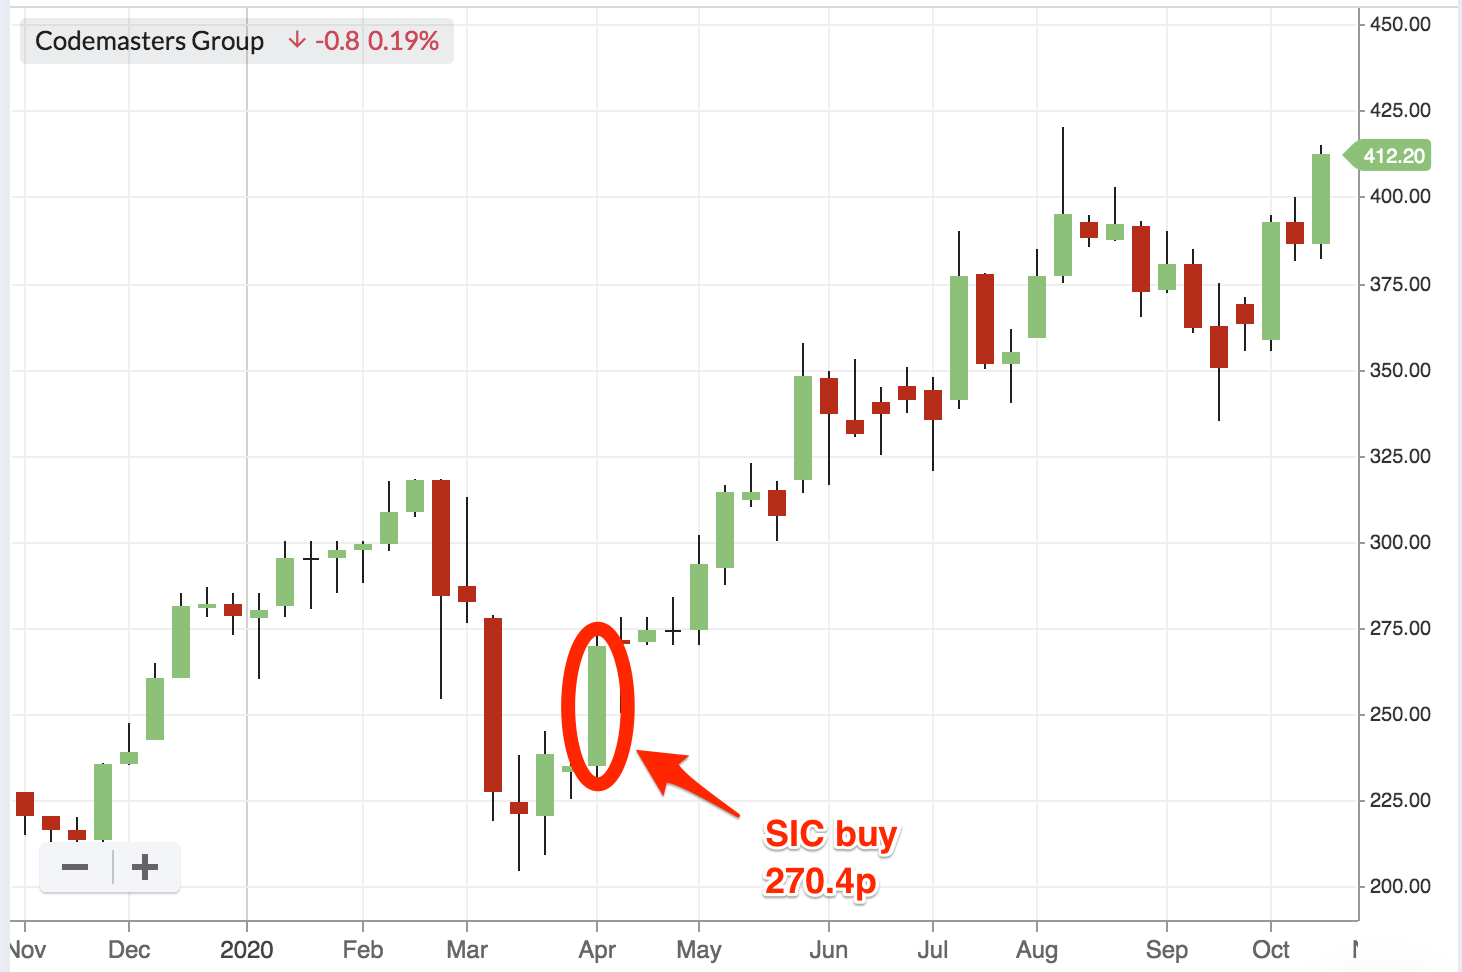
Video game developer and publisher Codemasters was pitched to the Stockopedia Investment Club on 7th April 2020. With a lockdown in place and the economy in turmoil, one of the first sectors to see a boost from the unusual conditions was the video games industry. The shares were bought at 270.40p and they currently trade at 400.00p. NB - CDM is from our archive of several pitches made earlier in the year. In future, stock pitches will be published immediately after meetings.
TLDR;
Codemasters Group Holdings plc: a mid-cap growth stock offering exposure to the burgeoning video gaming and e-sports industries.
- Bull Points: Strong niche position in "racing" games, strong brand connections, multiple growth levers, becoming more profitable, Covid beneficiary.
- Bear Points: Potentially over-reliant on the success of a few games, competitive market, shares could be expensive, CEO and CFO both sold shares in January 2020.
Profile
- About the Stock: Codemasters is AIM listed and classified in the Technology sector. It develops and publishes video games that are either bought by consumers from retail outlets or digitally via games platforms. It currently trades at 400.00p per share and has an EMS of 3k.
- Opportunity Type: This is a Mid Cap with a £629.5 million market cap and is classified as Adventurous on the RiskRatings spectrum. The StockRank is 74, with quality and momentum being the strongest factors - qualifying it as a High Flyer.

Business & Model
- Company History: Thirty year track record as one of Britain's best known video games developers, specialising in high quality racing games. Founded in 1986, based in Warwickshire and floated on AIM in June 2018.
- It manages four main games franchises, including ‘DiRT™, GRID™, Project CARS and F1®. Earlier this year it won the right to develop and publish games and e-sports tournaments under the FIA World Rally Championship brand (coming in 2023). It also has a growing back catalogue of ~15 profitable titles plus many others. It is growing well organically but has made acquisitions and intends to make more.
- Business Model: Codemasters owns the IP to DiRT, GRID and Project CARS and licences the IP to F1. It has teams of developers introducing new versions of the games, often annually. Distribution to traditional retailers is handled through a third party, Koch Media. But distribution through the increasingly important online games platforms - including Microsoft (Xbox), Sony (PlayStation), Apple, Google (Stadia) and Amazon (Luna) - is handled by Codemasters itself. In addition, Codemasters plans and executes all its own marketing in-house.
Market & Competition
- Market: Global games market is estimated to be worth ~$137 billion and anticipated to grow by 10% per year in coming years (research by Newzoo). China is becoming an increasingly important new market and the industry is being driven by new developments in streaming and mobile.
- Xbox and Playstation are launching new gaming systems (Xbox Two and Playstation 5) this year, which usually boosts games sales.
- Xbox and Playstation are launching new gaming systems (Xbox Two and Playstation 5) this year, which usually boosts games sales.
- According to a report by Newzoo, global esports revenues are projected to break the $1 billion barrier ($1.1 billion) for the first time in 2020, up 15.7% from the previous year (Codemasters annual report). By 2023 the figure is expected to rise to $1.55 billion.
- Competitors: There are other games/developers in the racing games space (such as Forza Horizon and Gran Turismo). But there's no doubt that Codemasters benefits from specialising, and growing a stronger presence, in the racing genre.
- More of a risk is the potential to lose the F1 licence (although it was recently extended from 2021 to 2025 with an option over the 2026 and 2027 seasons) or for F1 to become less popular. It's also at risk of poorly received new titles, which require significant upfront investment.
Strategy & Competitive Advantage
-
Strategy:
- In the past Codemasters made games across a number of different genres but has opted in recent years to specialise (in racing games). It now aims to have products that appeal to anyone from casual game-players right through to e-sports professionals.
- Digital sales are an increasingly important factor in the industry - known as "games as a service" (GaaS). Digital sales represented 67.7% of total revenue in 2020 (total revenue was £76 million), up from 59.2% in 2019.
- Looking closely at mobile offerings. The company has a partnership with Chinese developer Netease for mobile gaming, expected 2022.
- Esports - Already growing before Covid, esports has been a boost for Codemasters. The company filled the postponed F1 calendar with the F1 Esports Virtual Grand Prix, which got 30 million views.
- The company is aiming to build out its titles (while continuing to profit from its back catalogue), and dominate the racing game niche.
- In 2019 it acquired the racing game developers, Slightly Mad Studios, which added the Project CARS and Fast & Furious game franchises. The company has seen strong organic growth in 2020 but further acquisitions - adding either IP or studio skills - are possible.
- The main priority is to grow its audience and increase average revenue per user. This is happening through the more profitable digital downloads and the introduction of "add-ons" and in-game purchases.
-
Competitive advantage
- Strong positioning and expertise in the racing game niche. Thirty years of experience in this area meaning that it has developed proprietary gaming engines that are optimised for the graphically demanding racing genre.
- Strong IP and licences IP with F1.
- By fully focusing on building its brand in racing games, Codemasters says it's aiming to be the "go to racing channel for both gamers and licensors hence raising competitive barriers to entry."
- Constantly increasing size of its back catalogue gives it a growing source of high margin tail-end sales. It also improves its marketing abilities (options to offer free games as a teaser to buy new titles).
Financials & Ownership
-
Codemasters recently turned profitable - Sales have been growing consistently over the past five years and in 2019 - the year it floated - it turned profitable. In 2020 (results were announced in June 2020) it posted sales of £76 million and a net profit of £11.6 million. Forecasts indicate that will accelerate in the current 2021 financial year. 2020 margins were strong, at 20.9%, with ROCE of 12% and ROE of 17% all encouraging quality clues.
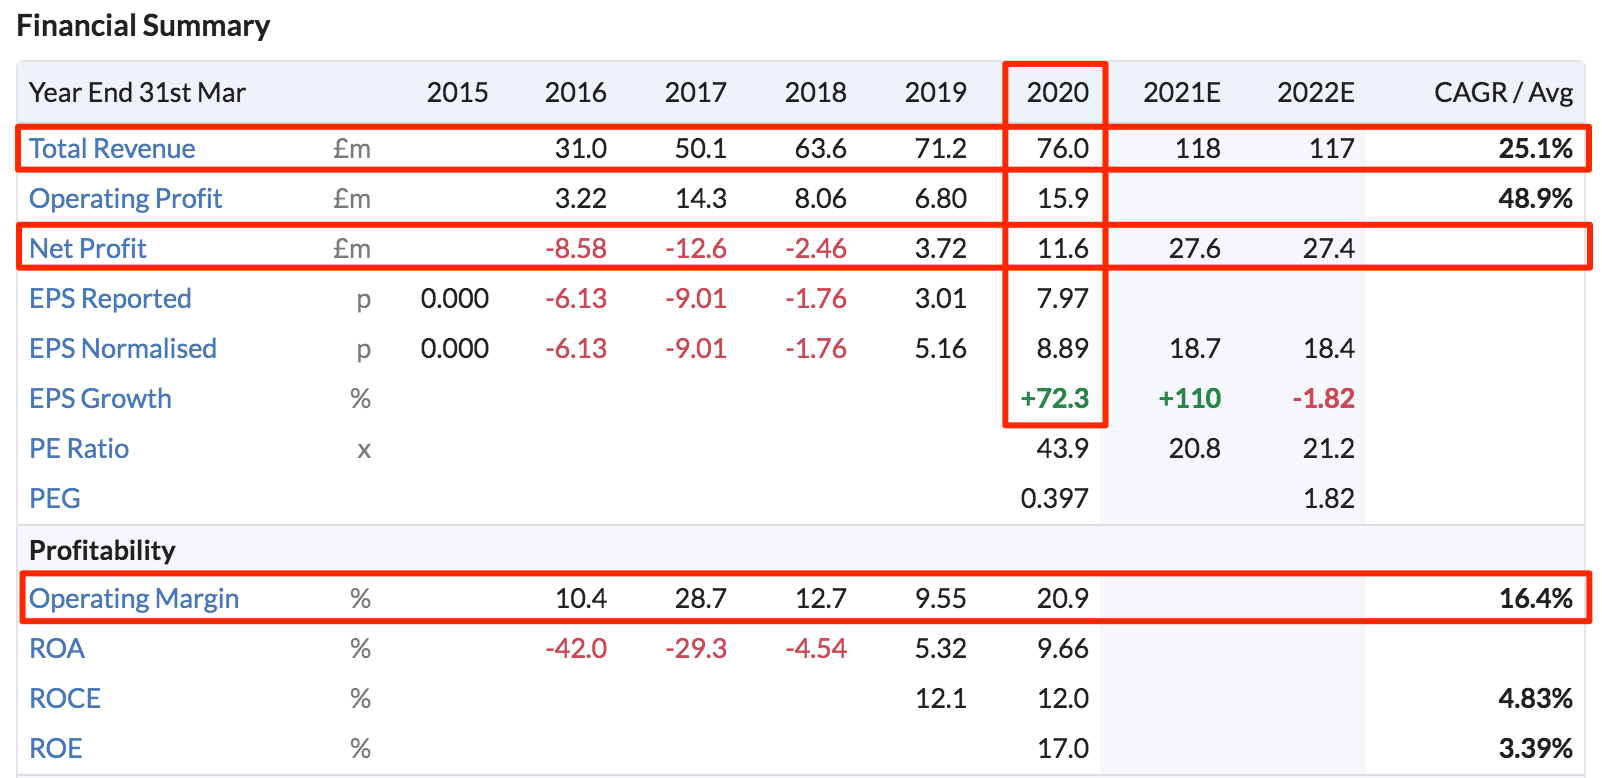
- Balance sheet strength - Cash is solid at £25.6m. Capex is stable and the business is now cashflow positive. It's debt free. The F-Score is a mediocre 5/9.
- Share dilution - It raised £20 million of equity last year to fund the Slightly Mad Studios acquisition. With more acquisitions potentially on the way, there's a risk of more dilution, although the cash position has improved a lot, so it appears to have options.
- Ownership structure - Slater Investments in the largest institutional holder with a 9.91% stake, followed by Soros Fund Management with a 9.5% stake. Overall, 48.5% of the shares are held by the top holders.
- When it floated in 2019, 50% of Codemasters was owned by Reliance Big Entertainment. That holder has now exited. CEO Frank Sagnier reportedly made £10.1million at IPO.
- In January 2020, Sagnier sold £1.2m of his holding, leaving him with a 2.1% stake. CTO Rashid Varachia sold £0.52m leaving him with 1%.
Valuation
Relative Valuation
- Codemasters has a ValueRank of 12/100 - down from 23 at the start of 2020 and down from 40 when it floated in 2018. This suggests it has always had a slightly premium rating but is currently as expensive as it ever has been.
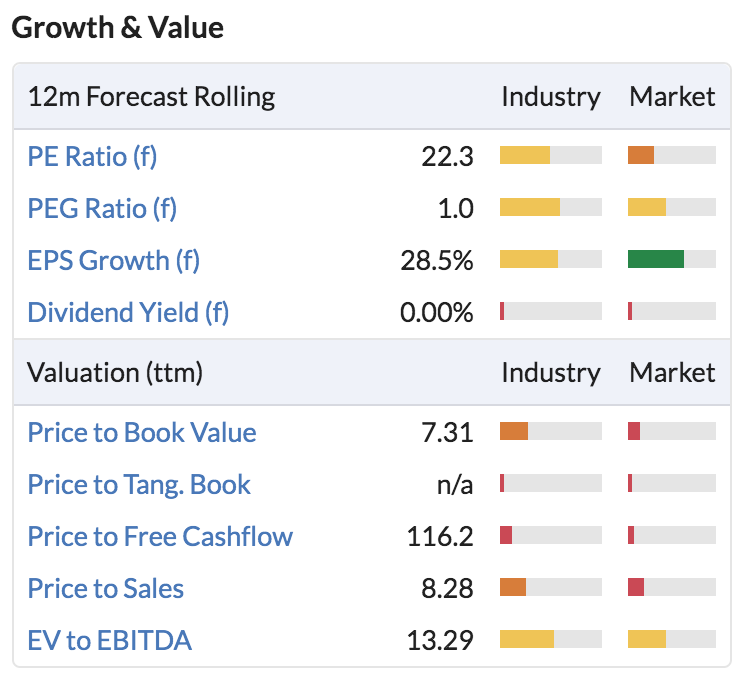
- The current P/E ratio of 46.5x falls to a forecast P/E of 22x, which is more reasonable. That's based on the EPS more than doubling from 8.9 in 2020 to a forecast 18.7 in 2021. The question is whether the company can continue to meet and preferably beat forecasts with its growth ambitions.
- A forward PEG ratio of 1.0 is slightly shy of Jim Slater's preference for <0.75, but this still falls into the "Zulu" stock category that would have appealed to him - and explains why Mark Slater has a 9.9% stake.
Intrinsic Valuation
- Liberum (the nomad and joint broker with Jeffries) research note on the H1 2021 results on 7 October set a target price of 435.0p (against the publication price of 359.0p). It says CDM has closed its discount to the wider UK gaming sector over the last year but still trades on 20x CY21 EPS, c.30% below UK peers.
Recent Trading
- In its half-year 2021 trading update on 7 October 2020, the company said:
- Trading was strong throughout H1
- H1 revenue would be ~£80.5 million (up from £39.8 million in H1 2020)
- Digital sales had risen to ~73% of revenue (up fro 61.7% in H1 2020)
- Cash at H1 was £49.8 million (up from £24.6 million in H1 2020)
- F1 2020 game had boosted sales
Trends & Catalysts
Are there any catalysts that could drive a rerating in the short or medium term?
- Codemasters' focus on racing games gives it a very strong position in a highly popular gaming genre. Short term, with new Xbox and Playstation platforms on the way, the company looks well placed to benefit over Black Friday, Christmas and New Year.
- Longer term, the company appears to be benefitting from growth in digital distribution, GaaS and in-game purchases and post-sale add-ons. This should see the company increase revenue per user and lead to higher margins.
- Sales in the US have been stronger than expected. But there is also strong growth in China. New markets should be a boost for the company's customer base.
- Codemaster released its full year results in June. A H1 2021 update was published in early October. The official H1 figures for the six months to September 30 are expected on November 23.
What are the biggest risks?
- Valuation - The shares currently look expensive as momentum in the stock is building. So far, the company has over-achieved on revenue and sales growth, but any mis-steps over the next 18 months could affect the price. While the company has benefitted from Covid circumstances, high momentum stocks could be sold-off if the market falls.
- Execution - Codemasters has a solid base of IP and games titles, but constant development demands upfront investment and failure here could be damaging. The F1 licence has been extended, and fortunately the F1 continues, but any disruption there could affect games sales.
- M&A - Codemasters says it's on the look out for acquisitions, although strong organic growth means that it can be picky. Acquisitions come with deal risk, and while Slightly Mad Studios is reported to be trading in line, there are no guarantees that acquisitions will always work.
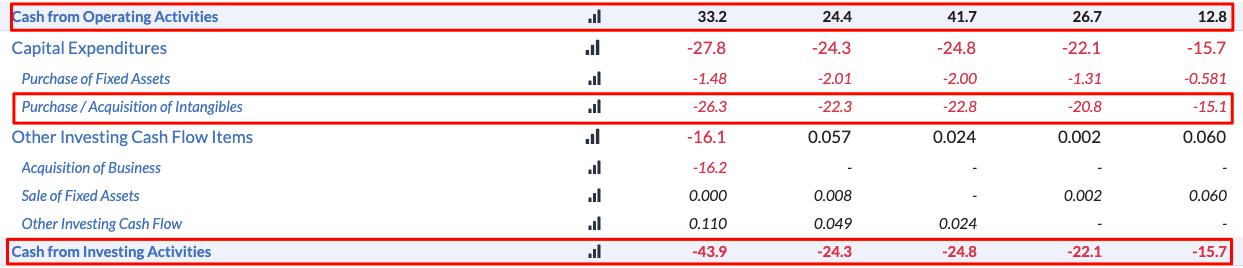
- Acquisition of intangibles and lack of resulting free cash flow - on a technical point, there is an 'unknown' concerning the consistent acquisition of intangibles (shown below on the cashflow statements) and the resultant impact on cash flow. Is Codemasters running to stand still?
Sentiment
-
Liberum's most recent note stated: "Importantly, today’s update highlights the potential of the F1 franchise (the company has grown it to over £50m of annual revenue a couple of years faster than we expected) and the opportunity to develop and expand other franchises. We reiterate our BUY recommendation and Target Price of 435p."
-
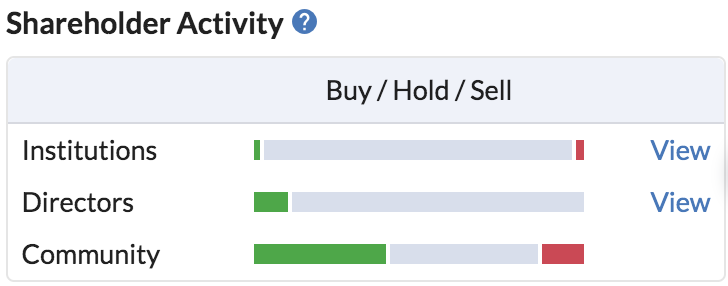
Solid community support suggests that private investors are encouraged by the story
-
Director dealings - CEO, Frank Sagnier and CTO Rashid Varachia sold considerable holdings in January 2020, leaving them with stakes of 2.1% and 1% respectively. Arguably they are still meaningful stakes and the timing of those sales wasn't brilliant (given the subsequent price rise), suggesting that there may have been personal reasons behind the sales.
What would the person selling to us be thinking and who are they?
- Profit takers looking to shift out of small- to mid-cap tech-oriented stocks, perhaps selling on the price looking "full"
- Those who looking to de-risk portfolios from more speculative momentum shares ahead of any market disruption caused by Covid
The verdict
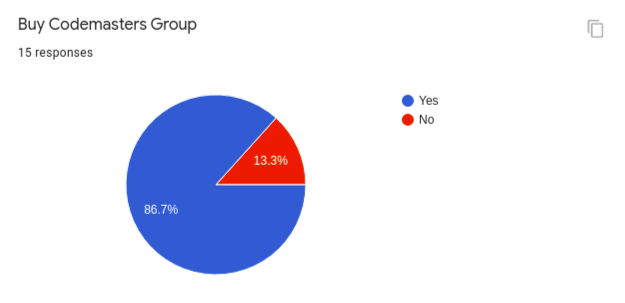
Overall, the Stockopedia Investment Club were positive on what they saw and a purchase was made the following day.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
The scheme document dated 7/1 has now been published and can be found at:
https://www.codemasters.com/investors/#electronic-arts
The key date, the Court meeting, has been set for Wednesday 3rd Feb.
As a reminder the current offer was made just a week before the Court meeting on the Take Two offer was due so there is still plenty of time for another counterbid - indeed the share price says that the market expects one.
As a newbie trader can anyone provide links to what happens in a takeover? Much appreciated!
Rival in the sector #SUMO are presenting with a Q&A at the MelloMonday Christmas Special this evening.
https://melloevents.com/mellomonday-14th-dec/
It is a great line up with Sumo at 6.55pm but starts at 6pm so worth tuning in. Stockopedia readers get half price tickets with the code MMStocko21
There she blows ...
https://www.londonstockexchang...
604p cash offer from EA.
timarr
Shares are now around 637p.
Here is the link for this latest possibility - let's see what happens in the morning:
https://news.sky.com/story/games-giant-electronic-arts-gatecrashes-725m-codemasters-takeover-12160582
Edit - Dustyie you beat me to it by posting while I was typing!
Sky news is reporting a second bidder is emerging for Codemasters .. see link below
https://news.sky.com/story/games-giant-electronic-arts-gatecrashes-725m-codemasters-takeover-12160582
with broadband speeds increasing worldwide especially in less developed counties .. the gaming market has hugh growth potential the next ten years ... Codemaster potential future earnings is very much under estimated in my opinion
New name on the list this morning. Alpine Associates Management Inc., a New Jersey hedge fund, has declared 1.29% after buying 500,000 @ 517.588p. At the same time they have increased a short position in $TTWO. This is their speciality: http://www.alpineassociatesmanagement.com/documents/FG/alpine/news/465866_Alpine1115_asi.pdf
Thanks to Peter M who posted this link on SCVR:
https://www.thetimes.co.uk/article/watch-for-white-knight-says-odey-p8vspb7j5
There is enough text before the paywall to get the gist of it with the owner of Formula One motor racing and Ubisoft, the French video games group being named as possible counterbidders. Stpcko gives the latter a MCap of £8.81bn.
Odey declared today that it has reached 3%. At the same time there have been some large deals going through today with 1,150,635 shares changing hands at 10 16 and 400,000 at 15 56.
Damn nearly bought on this link but held off. Rumor today is EA is about to get involved - good luck to all here
I sold today for an 86% gain on my holding. I don't really want Take Two shares at the moment and although the price could continue to go up in an Xmas rally I think I have reached my risk/reward balancing point and so i'm going to look for other places for the profit,
At 16 00 GMT today $TTWO was trading at $184.28 making the bid worth about 511p. Meanwhile the quote is 512-520.
I have come across an article by Edmond Jackson dated Friday 4th in which he discusses various aspects of the bid, including Slater selling vs, Odey/Sand Grove buying. If you're following the bid it is worth a read: https://www.ii.co.uk/analysis-commentary/stockwatch-red-hot-sector-risk-and-opportunism-ii514396
$TTWO closed last night at an all time high of $181.3 = £134.86 making the bid worth 502.2p but it is trading at 504/506 at the moment so someone is buying thinking it will be worth more so let's look at the declaring holders:
Sellers - the big one is Slater, the largest holder at the start with 9.32% but now 6.03%
BlackRock Group 4.20% to 3.34%
AXA Investment Managers SA 3.03% to 1.45%
Buyers - Artisan Partners 7.99% now 8.776%
Kite Lake Capital Management (UK) LLP 1.16% now 2.06%
Sand Grove Capital Management 3.15% now 5.99%
Carlson Capital, L.P. 1.1459% now 1.903643%
Odey Asset Management LLP 1.49% now 2.05%
$TTWO was $177.7 at London Close making the bid worth 497p.
The prospectus was published today - key dates:
Court Meeting 10:00 a.m. on 21 December 2020
Last day of dealings in Codemasters Shares 1 February 2021 (provisional on Court Sanction Hearing 10:30 a.m. on 28 January 2021).
So we should be getting our voting intentions from brokers soon?
$TTWO was $175.51 at London Close making the bid worth 494p. Clearly anyone buying above that thinks that either there is more upside to the TTWO share price or that the bid value will have to be sweetened to get it through.
Sold out the rest of my holding today on this rise, fed up with it!
Codemasters price up to 500p today ..... what ?
Take Two shares are up.
An interesting item posted by ACounsell here https://www.stockopedia.com/content/re-small-cap-value-report-tue-24-nov-2020-mcb-carr-trak-cbox-igp-tet-cwd-707948/?comment=33#33 regarding yesterday's RNS about options for the new non-exec director. This led me to check the last annual report for the other two:
Non-Executive Directors
Gerhard Florin NED 350,000
Ian Gomes NED 210,000
Both are excercisable until 31 May 2028 at 200p so if deal is worth say 500p that is a bonus for approving it of £1.05m and £420k respectively.
This stinks.
TTWO $167.12 = £125.71 at London close today making the offer worth 476p but CDM closed at 496/500 so the market definitely sees an upward revision.
The third largest holder Artisan Partners (initially 7.99%) now has 8.64% (paid up to 489p)
The now fourth largest is Sand Grove Capital Management with 4.58% (initial 3.15%)
The closing UT today was at 492p. This reflects TTWO moving up to $171.5 at that time making the bid value around 487p.
The TTWO price today gives a value for the bid of about 464p per CDM share. Interesting that two institutions have been buying above this at 478p indicating that they will be holding out for a higher price.
Carlson Capital, L.P. has increased from 1.1459% to 1.47266% but more importantly 3rd largest Artisan Partners is up from an initial 7.99% to 8.27%.
I have been looking at the form 8.3 declarations. The top 3 holders are:
Slater Investments 9.32%
Swedbank Robur Fonder AB 9.5%
Artisan Partners 8.14%
26.96% between them - enough to block the court resolution.....but will they?
In today's SCVR Nick Hewett points out this article:
https://www.dailymail.co.uk/money/markets/article-8939649/Codemasters-faces-investor-backlash-726m-deal.html
There have been numerous Form 8.5 reported for Codemaster (see News section in Stocko). Does anyone know what these mean?
Form 8.5 Public Dealing Disclosure by an exempt principal trader with recognised intermediary status dealing in a client-serving capacity
I bought a small holding in December and also some for my grandaughter in June, we will definitely be voting against these proposals.
Is there a chance the board, whilst recommending acceptance, they are really just displaying a willingness to work with new owners. But, if they openly rejected it it might put off others.
I think this purchase is about the future Esports element. Codies expertise In driving games is unrivalled and whoever owns them is the main player in the competitive driving element. Being the case, surely Actvision Blizzard etc... are watching
Can’t see institutions supporting the current offer, so worst case scenario, the deal falls through without any other offers, and your still left with a strong growing company with an edge over the competition.
This is at present being done as a 'Scheme of Arrangement' and so nobody is at present accepting or refusing. They could, like the directors, give an undertaking as to which way they will vote at the Court meeting but there is no incentive to do so. This route is quite demanding as it is one time where small shareholders come into their own - 75% of shares must be voted for AND 50% of shareholders.
Yes, today's fall resulted from the exact terms being published after the market had opened. We now know the factor for the TTWO share element so the market is going to track that from now on. We are told that it is based on the closing share price of US$168.68 on 5/11.
With the last price at $159.99 that gives 342p at £1 = $ 1.32. Add the 120p cash and you have 462p cf the headline 485p when announced.
The good news is that the only irrevocable undertakings to accept so far are from 3 directors amounting to 4.34 per cent of the company. Let's hope Slater et al hold out for something better.
How do we keep track of who has accepted and who has refused? This offer looks terrible on first reading.
On Tuesday I estimated the value of the bid at 462p based on TTWO at $159.99. Last night it closed at $160.22 so hardly changed.
On Tuesday and Wednesday CDM was trading below the estimated 462p, which is what you would expect for an uncontested bid, the difference being due to the time element. However, today it is trading above - high 480 low 469 - suggesting that the market anticipates a higher bid.
Is the fall today away from the 480 region due to the offer being part cash part shares for all shareholders?
Not sure, peers are also down such as £TM17, Sumo (LON:SUMO) and Frontier Developments (LON:FDEV).
But Take Two were down around 9% yesterday.
On the shouty forum (we all know which one I mean), they were saying the nominal £4.85 is now around £4.60 because of the fall in price of Take Two.
The offer is an insult if it was all cash, it's even worse now. We really have to hope the big holders realise and vote to reject the proposal.
And another thing....
They recently announced a huge uplift in sales, doubled over the last 12 months. That trend is likely to continue over this long horrid Covid winter.
They reported having net cash of around £50m recently up from £25m 12 months previous - given costs won't have risen but sales are massively increased I can see that rising to £75-£80M by FY end.
In that context, an offer of £4.85 when there's likely more than 50p per share of cash on the books in short order is an absolute insult. WTF are the board playing at?
Also, the offer is only £1.20 in cash and £3.65 shares in Take Two
Yeah, most of us will lose a fair chunk of the "premium" in converting the currency back from sales back into £s.
I'm really peeved.
Good news is board don't hold much of the company. Lets hope the instis demand a higher price.
If it is worth more then other bidders made come out of the woodwork. If not then fair value is probably 485p. The share price has risen a lot lately. The news may have leaked out.
I don’t agree, it is not just about other companies taking it over. The shares will probably be higher than that price this year or next. The shares have not gone up much recently they were 400p in August and you can compare them with others such as £TM17, Sumo (LON:SUMO) and Frontier Developments (LON:FDEV). I think around 600p would be a fairer price.
I don’t know anything about Take Two but I will probably sell before the deal goes through.
Why are they accepting such a low offer?
This sector is doing very well at the moment, it is usual the offer is around 25-30% above the current share price.
I have my suspicions. This needs investigating - it doesn't pass the smell test.
Hi IGPJ & Herbie
This says it all to me, 'here guys, cash out your options & we'll load you up with a load more & just carry on as normal' - heads you win, tails you win. It doesn't pass the smell test because this type of deal stinks for shareholders.
Frank Sagnier, Chief Executive Officer of Codemasters, and Rashid Varachia, Chief Financial Officer of Codemasters, along with the senior executive management team of Codemasters intend to remain with Codemasters following completion of the Acquisition and will continue to lead the Codemasters business within Take-Two's organisation and its 2K label.
what a mean offer from take two!
Nice rise today on news of offer for company, however seems a low-ball offer to me. The CDM board are recommending it.
So, this is the second time I've had a share that's had a low ball offer accepted by the board.
There needs to be some way of investigating what inducements the Board get from the pursuing company to recommend offers to their shareholders. Especially as this company is already on a much lower multiple than most of its UK listed peers.
Thanks for posting Ben, clearly a great decision to buy in. Quick question - once the verdict is in after the vote, how do you decide on position sizing? Do you have set % rules for small, medium and large positions?
Hi harvs - thanks.
Good question on position sizing. So far we've defaulted to equal weighting the portfolio. This made sense while we've been building it up. However, at the last meeting we discussed and voted on a new way of risk-weighting the positions from here. This is based on some classic trader techniques for limiting the amount of capital at risk on any one single trade. So we've made a decision, for now, on a limit to the number of positions and we're using the Risk Ratings as a framework for deciding how to weight each new position. We'll get this written up as an article in much better detail in the near future.
Ben
One thing you, and many others have overlooked, is the ability to sell advertising space inside the games.
I have no clue how to value that, but they work with Bidstack on Dirt and I see no technical reason why Codemasters, Bidstack and F1 can’t split the revenues on live advertising inside games and e-sports. I think a whole new revenue stream is opening up.
Disclosure: long Codemasters Group (LON:CDM) and Bidstack (LON:BIDS)
Ben - congratulations - that is a very good increase you are sitting on although I found it a little confusing in that the pitch has been updated as of now whereas the vote at the end would, I presume, have been on the original pitch with different figures and at a lower price.
You refer to the 7/10/20 trading update when there was some discussion on the SCVR and fwiw I made these points:
When the company put out a "significantly ahead of current market expectations" statement on Aug. 11th the sp went above 400p but has drifted down since and today's uptick looks rather muted. I think the reason is that today's announcement says things about H1 that were already in the revised forecasts and little about expectations for H2. As it stands revenue in H2 only has to equal last year to meet the £115m shown on the SR.
Looking at estimated Y2 p/e the company looks relatively cheap and David Thornton in his interview with Tamzin labelled it as a GAARP share: https://www.piworld.co.uk/2020/07/03/piworld-webinar-david-thornton-small-is-beautiful-why-small-caps-what-to-buy-now/
Codemasters Group (LON:CDM) 20.3
Sumo (LON:SUMO) 27.2
Frontier Developments (LON:FDEV) 34.3
Team17(LON:TM17) 39,4
Thanks Ben - nice pitch / review. For a non-accountant, would you be so kind as to explain in a little more detail what you mean by "Acquisition of intangibles and lack of resulting free cash flow - on a technical point, there is an 'unknown' concerning the consistent acquisition of intangibles (shown below on the cashflow statements) and the resultant impact on cash flow. Is Codemasters running to stand still?"
I've heard this criticism levelled at Codemasters before but I'm ashamed to say I don't understand it.