Stock Pitch - Sylvania Platinum (LON:SLP)

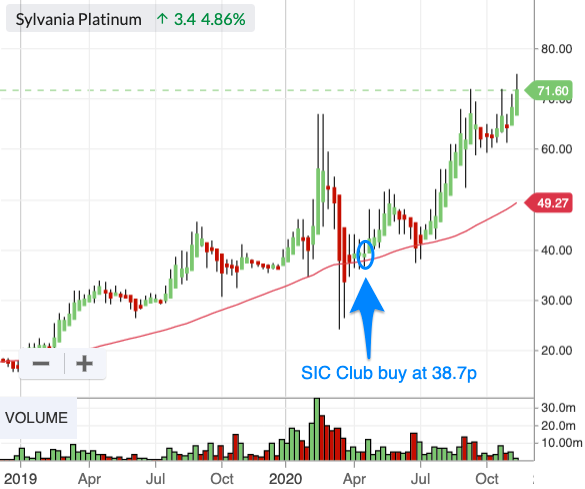
Sylvania Platinum (LON:SLP) was pitched to the Stockopedia Investment Club on 23 April 2020 when the share price was 38.7p. At the time of writing, approximately five months later, the share price is 76.3p. That is a material rerating and a 97% gain over that timeframe.
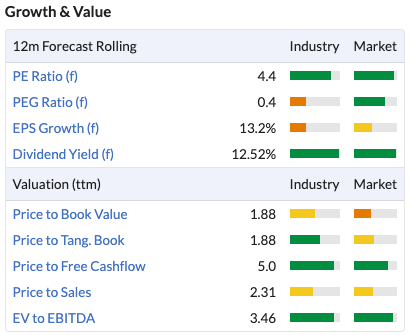
And yet even now Sylvania's Value scores are striking, with a forecast PE ratio of 4.4, a forecast PEG of 0.4, and a price to TTM free cash flow of 5.0. You might argue it continues to be cheap, but there are also valid risk reflected in this valuation which we will explore below.
The April pitch to the Club was that Sylvania was priced incorrectly and was due a rerating. Here we revisit that pitch and update it for new information as we explain why we have not sold this Platinum Group Metals (PGM) play quite yet.
Are we right to hold on, or should the Club bank profits while it can?
TL;DR
Sylvania Platinum, a small-cap PGM producer with operations located in the South African Bushveld Igneous Complex, offers striking value and exposure to growing markets such as electric vehicles.
- Bull Points: Low-cost producer, strong PGM demand and spot prices, cash generative, broad factor exposures, qualifies for nine Guru Screens, developing exploration assets
- Bear Points: operational disruption, depressed chrome market, dependence on host mines, profitability driven by PGM spot prices, finite life and lack of scalability of dump operations
Profile
What is the opportunity type?
Sylvania Platinum produces and sells 'Platinum Group Metals' (PGM), which are platinum, palladium and rhodium. It is a small cap Super Stock in the Basic Materials sector and comes with a Speculative RiskRating.
With a market cap of £190m, a share price of 76p, and an EMS of 20,000, liquidity is not so much of an issue as you can buy around £14,000 without moving the market.
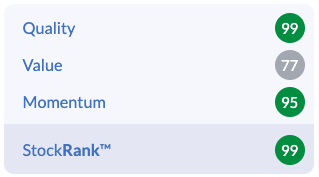
The StockRank is 99 thanks to strong Ranks across the board, with a Quality Rank of 99, a Momentum Rank of 95, and a Value Rank of 78.
Trends/Market/Competition
Competition
Sylvania operates with a natural geographic moat, as PGM metals can only be mined in a few locations. This means both competition and opportunities are relatively scarce.
Competitive advantages
Sylvania has two distinct lines of business: the re-treatment of PGM-rich chrome tailings material from mines and the development of shallow mining operations and processing methods for low-cost PGM extraction.
PGM metals are tricky to produce and there are only a few known producing areas, including the Bushveld Igneous Complex (BIC) in South Africa. This is is the world's richest source of PGMs and is where all of Sylvania's operations are located.
Some 80% of the world’s economically viable platinum-bearing deposits are located in the BIC. The balance is largely in Zimbabwe (the Great Dyke deposit), Russia, and North America. Southern Africa is the only primary source of platinum, with platinum in Russia and North America mined as a by-product of other metals (mainly nickel and palladium, respectively).
It is estimated that about 38.1 kilotons of platinum metal in mineral reserves and resources reside in the Bushveld. Sylvania Platinum currently targets annual production currently of 74,000 - 76,000 ounces per year.
Strategy
Sylvania is a low-cost producer of PGMs, which are currently benefitting from strong spot price trends.
The group aims to create shareholder value through high levels of free cash flow generation and opportunistic share buybacks when the share price is lower than the internal company valuation. The most recent share buyback update on 2 October shows Sylvania bought back 168,694 shares at AUD $0.9195 (around 51p) in September.
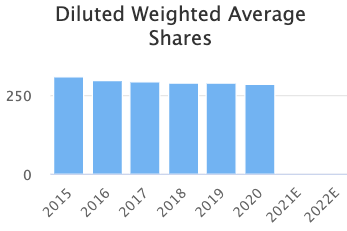
This programme has now ended, with the group acquiring 63.5% of shares on offer, taking the total number of shares with voting rights to 271,476,690 (compared to an FY20 average of 287,572,262).
Beyond this, the group intends to step up dividend payments and plans to pay a ‘metal price windfall dividend’ in HY2 FY2021, to be based on any excess cashflow generated from palladium and rhodium prices achieved above longterm broker consensus prices for these metals for the 2020 calendar year. Any windfall will be calculated on an “achieved basis” and Sylvania is aiming to pay this in Q3 of 2021.
The group has growth capex projects like additional milling and flotation operations and Project ECHO, designed to optimise existing operating assets. These projects are only commissioned if they pass an internal hurdle rate.
It is continuously exploring and evaluating additional tailing treatment deals in the area, and is developing the commercial value of its exploration assets.
Financials & Ownership
What is the company's track record of growth and profitability?
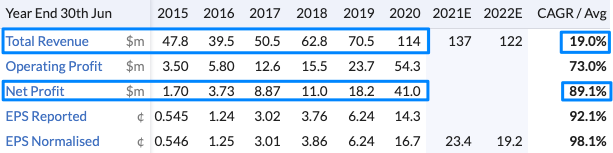
Sylvania has a good track record, driven both by operational competence and favourable PGM market dynamics. 2016 through to 2019 shows revenue growing at increasing pace, while net profit is up even more due to strong basket prices and operational gearing.
The average gross basket PGM price for SLP in FY20 was $2,015 per ounce, up 58% on the previous year's $1,217. In Q1 of FY21, this was even higher at $2,834 per ounce.
This compares very favourably to all-in sustaining costs (AISC) of $654 per ounce in FY20, up 13% from $578.
This considerable gap between basket prices and AISC provides some margin of safety to investors.
What is the company's financial status and balance sheet strength?
In addition to a healthy income/cashflow statement, the balance sheet looks good too. They have no debt and an increasing cash balance. At FY20 the cash balance was $55.9m and in Q1 of FY21 this had increased to $60.9m. This is encouraging cash generation from a c$200m market cap company.
SLP also comfortably passes the F-Score and Z-Score hurdles and has very strong liquidity ratios.
Ownership
Directors have been selling stock rather than buying.
Some major shareholders, including Premier Miton, Fidelity, and Hargreaves Lansdown, have been increasing their stakes in the company.
The company also has a history of buying back its own shares.
Valuation & Sentiment
There are a few potential drivers of value at Sylvania.
- PGM price movements.
- Dump operation life extensions and development of exploration assets.
- General improvement of investor sentiment with regard to corona crisis (this would likely be reflected in the PGM price).
You could also frame them as risks if they fail to arise. That said, it's worth noting that SLP currently qualifies for nine Guru Screens:
- Greenblatt's Magic Formula
- Martin Zweig Growth Screen
- T Rowe Price Screen
- 52 Week High Momentum Screen
- Piotroski F-Score Price to Earnings Value Screen
- Philip Fisher Growth Screen
- Neglected Firms Screen
- Cash Accruals Screen
- The Screen of Screens
- Benjamin Graham Deep Value Checklist
By most relative valuation metrics, Sylvania continues to look cheap.
The group's revenue and profitability is materially driven by PGM spot prices though, so taking some kind of view on demand for those industrial metals is necessary in order to gauge true value.
What do brokers say?
The most recent broker note is a Q1 review from Liberum, published on 30 October 2020. To summarise:
- Sylvania has achieved a strong operating performance in a challenging environment as production levels ramp up to pre-lockdown levels,
- The group is significantly cheaper than other PGM plays and 'even in a flat PGM price environment, Sylvania should significantly re-rate and deliver large dividends in the years ahead.'
- PGM prices enable continued impressive cash generation, and
- The price target has been upgraded from 115p to 140p.
It's worth noting that this is a marketing communication rather than independent investment research.
Risks
While the PGM metals Sylvania produces are in demand from auto industries for their pollution-reducing properties, it is worth remembering the Sylvania, as a low-cost operator, is operationally geared. That means profits that seemingly materialise out of nowhere can evaporate just as fast.
The group has also flagged and is managing persistent operational issues - namely water shortages, power outages, the possibility of strike action, and disgruntled communities.
Finite life of tailings projects. The company estimates that the tailings projects have got another 10 years in them - at this point, if other developments have not come to fruition, revenue will dry up and the company would shut down.
Political risk. They are based in South Africa - while this is about as stable as Africa gets, it's hardly stable, and things could go wrong in this regard. Companies based in Africa do typically earn a discounted valuation for this reason.
Conclusion
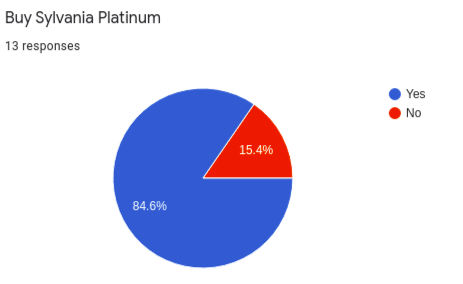
Based on the apparently cheap share price, in late April 2020 the Stockopedia Investment Club voted 11-2 in favour of purchasing Sylvania shares at 38.9p.
Since then the shares have rerated and Sylvania has successfully weathered a Covid-related lockdown in South Africa. With shares now at all time highs, has the easy money been made or does this rerating have further to run?
Disclosure of interest - I hold shares in Sylvania Platinum
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
I've been resisting the temptation to take profits on Sylvania Platinum (LON:SLP) . The recent trading update doesn't reflect the recent surge in rhodium price cos it takes a while for Sylvania Platinum (LON:SLP) to receive the cash from the refiners. The fundamentals for PGMs look robust. Most of the world can't afford $50k+ EVs which may become obsolete anyway if fuel cell cars take off. Fuel cells and green hydrogen production will need lots and lots of platinum. Battery powered aviation and HGVs are a non starter but hydrogen is a viable option.
Sylvania Platinum (LON:SLP) Q2 update out today - there's a write up in the SCVR here: https://www.stockopedia.com/co...
(LON: SLP) I have bought these shares and they have done well for me. Most investments carry a risk. I have put my money here. I would not add my shirt.
I am very bullish for precious metals and from 2025 for platinum in particular.
There are however two problems for SLP: -
The first applies to all the platinum producers, which is Country Risk. Higher metal prices fall straight through to the bottom line, particularly for low cost producers. There is ample evidence that governments, in cash-strapped countries like S. Africa move to expropriate such "windfall gains".
The second is Mine Life. SLP's mine life is so short that it can only be viewed as an annuity.
Stockopedia is wonderful platform but it has limitations when it comes to Miners. It cannot value exploration potential, reserves, country risk or prospects for metal prices.
A Stock Rank of 99 does not reflect these risks. My advice to the Investment Club is to sell half the holding and take a free ride. Invest the profits in another low-cost PM miner without Country Risk but with exploration potential and long-term existing reserves.
Remember, the definition of a mine: -
"A hole in the ground with a liar at the top".
Thanks for this observation, I think I will follow your advice and sell half of my holding in SLP now that it is up 103%. Any suggestions for alternative PM miners for further research?
That's also what I like to know - there is Jubilee Metals (LON:JLP) and Tharisa (LON:THS) but both in S.Africa jurisdiction
Thank you for the great write up on £SLP. I hold.
And I should add some equally excellent comments from readers!
I currently hold SLP
My main reason hold buying is I'm a medium term bull on industrial metals. Next year, I would expect the ongoing China inflation story to rumble on supported by a global economic recovery.
That said, there are a couple of things I'm wary of.
Firstly, the share buybacks, while described as "The group aims to create shareholder value through high levels of free cash flow generation and opportunistic share buybacks when the share price is lower than the internal company valuation" I can't find any internal company valuation, rather SLPs last annual report seems to focus somewhat on share buybacks to reduce the dilution impact on staff remuneration than shareholder returns, but Chairman does state:
The Board will continue to buy shares (rather than issue new shares)
to top up the share schemes on an ‘as needs’ basis. In terms of a
more general buyback I note this shareholder’s recent comment:
“Management are unlikely to be buying shares into a rising market,
they are too prudent for that. They’ll wait for a dip.” I concur with this
comment! We will evaluate any buyback (opportunistically).
It's an interesting one, mgt deserve to share in the rewards, but when mgt ramp employee share schemes it can signal an top sometime next 1-2 years.
The finite lifespan "Finite life of tailings projects. The company estimates that the tailings projects have got another 10 years in them". Simplistically, SLP needs to pay high dividends for investors to get their money back and make a return, given a suitably high discount rate for various operational, political and metals price uncertainties. As we get closer to that date, SLP shares will become more 'bond coupon' like.
Currently the earnings are there, so I'm a holder albeit with a wary eye.
As for the finite lifespan, do you know how probable it is that Sylvania will gain access to the tailings from other mines over the next few years?
They said in their results webinar that the mine operators were looking for more than they are currently willing to pay. The mine operators are looking to sell rights based on higher PGM pricing than Sylavania believe will persist through a cycle. Basically they don't want to overpay at a market top.
Thanks for such a comprehensive article, Jack.
As a long-term holder, having bought in at 16p in February 2018, I have been watching the slow progress for the first year of holding the stock, only to endure the wild ride of 2020. It is now my second largest holding, after Tristel (LON:TSTL)
Whilst the growth has been strong this year, I still feel it is good value, and am only frustrated that I didn't top up during the huge (unwarranted) spike down in March and July this year.
The fundamentals look strong, underpinned by the (current) all time high of Rhodium price, so in answer to your question "With shares now at all time highs, has the easy money been made or does this re-rating have further to run?"
I believe it has much further to go.
Thank you Jack for an excellent article. I have held this share since it was in its late teens and taken the opportunity to take some profit and buy back in at advantageous prices.
I look everyday and cannot find another share with such a compelling Investment case and it is worth highlighting the key points that will lead to this company continuing to print cash:
o Ongoing annual supply deficit of Rhodium , that is going to remain for at least 3 to 5 yrs (and probably longer). No near term substitute for Rhodium as regulations in effect demands its use in autocatalytic converters - notably regulations in China, where car demand remains strong. Given the average price of Rhodium tends to rise month on month to December in late Q3 and Q4, we will probably see a new "all-time" high in Rhodium prices in December, in excess of $16k an ounce is my guess.
o Another major PGM producer has had to shut down recently a material amount of its production, this will just add to demand for Sylvania's PGMs and like Rhodium, Palladium is also likely to have an annual deficit for the next few years.
o By my estimates, it is highly likely that if Sylvania achieves its forecast production for the FY to June 2021, EPS will be over 22 pence (not cents), as the EPS for HY to December 2020 must be on course for 12p , 5.8p Q1 and Q2 PGM prices are stronger. The only negative that I am aware of is an adverse movement in the USD:Rand exchange rate.
o As highlighted by Mr Eustice below, hydrogen fuel cells are expected to require material PGMs and in this respect, demand may well be sufficient to see an end to the annual "surplus" in platinum (over 60% of Sylvania's production). Many industry experts have been calling a recovery in Platinum prices, with a breakout potentially on the cards.
o The vast majority of the company's EBITDA (say USD100m in current FY) will end up increasing cash balances, after cap.ex of less than USD10m pa and payment of 28% tax on profits. Q1 cash increase was low because of the WCapital build up brought about by the significantly reduced Q4 production (covid related SA shut-down) in the last financial year.
Sylvania Platinum has excellent operational management and prudent financial management, reflecting I suspect the cyclical nature of this business and what happen in the years post 2010 when PGM prices were very weak.
However, in my opinion the company should pay a material one-off Metals Dividend (say 10p @ a cost of GBP27m) as the past cash generation and that generated in the current year supports this and will still allow for a much lower "regular" dividend. Even allowing for the potential decline in PGM prices (however unlikely in the next 2 years), the company has more than adequate cash reserves. The only unknown in this respect are new Cap Ex projects the cost and nature of which have not been detailed to shareholders.
A significant "one-off" Dividend would materially boost the undervalued share price, reward loyal shareholders and endorse the reasons why the Stockopedia Investment Club are correct in retaining this name.
Thanks for this Robin. I agree with your analysis.
I was sceptical about the Green Hydrogen thesis, but with the Biden win in US, Carrie taking over Government policy in U.K., plus EU with its usual desire to intervene in all things ‘green’ substantial expenditure (and it would have to be because its expensive!) on green hydrogen seems both feasible and now likely in the next 2 - 5 years.
I then saw a news story re BP signing a deal on the production of green hydrogen in Denmark!
Finally as a store of value, platinum historically is usually is more valuable than gold, now it's
half the price. But platinum is much rarer and it makes just as nice jewellery. Covid has put Governments around the World on a path of massive expansion of debt that they will never repay at current values so their policies must be to reduce the value of the debt through Magic Money Tree policies. I find it difficult to imagine a World where this does not help support the platinum (and indeed palladium and rhodium) price over the next decade.
I hold and will continue to do so.
One of the demand drivers that was delayed due to the pandemic this year was the tightening of car exhaust emission standards in China. Meeting the higher standards requires more PGM use in the catalytic convertors. The new regulations are now due to come in effect in January 2021. Only cars that meet the new China 6 standard can be sold or registered after Jan 1st.
Excellent analysis. Thanks! Any thoughts on this company being bought by another?
I have traded these since the beginning of the year, top slicing and buying on pull backs lower levels. The main price driver is the price of Rhodium. SLP is one of the main producers. Take a look at the chart . It is more valuable than Platinum and palladium and this is the jewel in the crown. It has been my most heavily traded share this year! I am not a seller but a trader of this stock, keeping an eye on the 8 & 20 EMAs.
I´m holding SLP since late 2019, when you wrote about this company (thanks for that!), and bought some more in late march. It´s the best position in my portfolio atm. Beside the good valuation there is the strong momentum to mention: today SLP crossed a pivot point and seems to be ready for further gains. So if you missed the bus, it might be a good opportunity to get it now.
Nicely timed article for me. I've been giving some thought recently about what to do with SLP. I bought in Aug 2018 at 17.4p and have held since. I'm obviously delighted with the performance, and looking at the fundamentals am happy to hold and think it is still underpriced. My issue is from a portfolio risk management perspective as SLP is now my largest holding at 15% of my overall portfoilo, and I generally like to keep my portfolio quite diversified. I've considered top-slicing, but can't really see anything compelling I'd prefer to be invested in. After reading the article and the comments I think I'm just going to let it run for now and revisit when I think the price is closer to fair value.
I hold and it's rapidly coming to the top of my individual company holdings. Thanks to Invested Geordie, John Rosier and Simon Thompson for the tip in December 2019.
This article doesn't seem to have done any harm to the share price today either.. ;-)
Great write up Jack. Thanks. I've held since January 2019 after Simon Thompson tipped it in IC and have no plans to sell. I think it could go to 100 pence in the next 12 months. As others have pointed out, there's no good reason to sell a winning share until the fundamentals or technicals change.
Jack, I can't seem to find a way to get the Liberum research. Do they not provide it to private investors?
It is available on Research Tree. I don’t know if available for free elsewhere.
Regards
Michael.
Where can I find more about the Stockopedia Investment Club? Is it something on the site?
Snoo - it's a staff club.
Ed wrote about it here https://www.stockopedia.com/co...
and gave a bit more detail about the process here https://www.stockopedia.com/co...
Been in and out a few times for £3k profit. Sold 10k at 72.5p looking to buy back in at 65p
Great write up.
Let hope we see Sylvania Platinum (LON:SLP) reach its potential valuation soon.
BSV
Jack - Great article. I have been in and out of Sylvania Platinum (LON:SLP) since early 2018 but decided in the autumn to stay invested. It's become my biggest holding since. My contemporary buying notes....
Sep 20 Slight broker EPS miss. Generally strong results considering COVID closure, with some production cavats. Possible large Q3 2021 deferred Divi depending on PGM prices. Company seem to be playing down expectations, perhaps to better manage their share buy-back programme. Smooth momentum over last 5 years, so don’t get shaken out. Unlikely to ever be a high PE share because of mining related risks.
Oct 20 – Great metrics and passes 9 long screens inc Zulu and F Score, so brought again after another ahead update 3rd wk Oct.
There is no other way of saying it, SLP is cheap. I bought in as this is one of the most bought stocks in the Stockopedia competition. Glad I did really. I listened to the company podcasts and was surprised that SLP was greatly effected (to a bigger extent than I expected) by Rhodium pricing and production.
PS is the div forecast right - my broker screen shows 2ish %
Apparently the dividend is 1.6p, so no it is not right, Stockopedia has 12.5%, my broker has 2.05% which looks right.
Unless there is a special dividend?
The management have been weighing up paying a special divi and I believe will reveal their conclusion in January. My reading was that it was quite likely, so may be the analyst at Liberium has already forecast it. (I would be less confident though of their being another one the following year.)
The management conducted a recent webinar and did mention the possibility of a special dividend. I hold quite a large number from 2017 and 2018.
I think a 2021 P/E of circa 7 wouldn't be out of order so somewhere north of 150p on current forecast. Time will tell....
Thank you Jack. Excellent piece as always.
I traded Sylvania Platinum (LON:SLP) back in February with a 22% gain in 16days.
I bought back in during March & April and added last month based on the Stockopedia Rankings. My target was £1.00 but I have revised my target as I think this share is mispriced by the market. New target 125p
and now showing a 91%profit + nice graph - it's a keeper for me currently. Thanks for the good article
Great company. Bought some in April and more in July when it dipped to 38p. Dividend is due next month I believe
For me, Sylvania Platinum (LON:SLP) was a good learning experience about anchoring bias.
I looked at buying when the share price was c.35p and then held off when it got to 40p as I figured I had missed the boat. I nervously pulled the buy trigger at 45p and it's gone pretty well since then.
In summary - anchoring bias can cloud your judgement of a quality company and can mean you miss out on some great opportunities.
Indeed. I'm still waiting for Sylvania Platinum (LON:SLP) to come down to the 40s. Might as well wait until the cows come home.
I've been in and out in the last year, making a profit. I'm back in small and will probably sell when my indicators turn. Often I think that shares like this are too good to be true. So I'm trying not to get too attached and letting my profits run. I'm finding this very difficult. Jam in 9 months is not much of a carrot [partly because of my age >75].
Simon, even though 76, my time horizon is a lot further out than 6 months, it has to be as that trench-shaped recovery is veiled in the mists of time. I do hold Sylvania Platinum (LON:SLP) and a dog-pack.
Silver
Simon I think you should be more ambitious. :-) I am nudging 60 but expect to be around for another 40 years! There is no reason that a reasonably fit and healthy year old who looks after themselves cannot expect the same! A 25+ year time horizons!
Hold onto your winners and let them run, at least until Sylvania Platinum (LON:SLP) has re-rated. I banked profits with Games Workshop (LON:GAW) and Boohoo (LON:BOO) and can't even bear to look now : ) ....I hold Sylvania Platinum (LON:SLP) on the basis of its Quality & Momentum Ranking only.
It's a long-term issue, but a major use for both platinum and rhodium is the manufacture of catalytic converters. As electric vehicles become more common, the price of these metals is bound to decline. Too soon to sell yet, I think, but something to be aware of.
I don't know how demand will balance out, but a lot of the hydrogen fuel cell designs use precious metal catalysts.
Ceres Power Holdings (LON:CWR) use cerium instead as it is relatively cheap and abundant. I spoke to their previous COO at their AGM last year and he said he was constantly pushing back against designers who wanted to incorporate some precious metals in their designs to boost the power output.
I have been in and out of this a couple of times in the last few years and hold at the mo - and intend to do so. Another low cost metal producer, CAML, is another of my main holdings.
Mine too - we must think alike!
Good write-up. I hold and it is now my biggest individual holding. Even accounting for the risks, I believe they are still seriously under-valued. I note that resistance at 70 p has been taken out this morning (perhaps prompted by this article???).
Thanks Jack for a great write-up as always. I also hold Sylvania Platinum (LON:SLP) as do many readers I would think hence this is a live issue. I agree with all your points, including geographical moat, good management and operational competence. It reminds me a little of Kenmare Resources (LON:KMR) in that respect, with similar single-country and commodity price risks.
My conclusion when I asked myself the same question was to keep holding. Three main reasons:
1. The business is good value based on market cap. Yet a significant proportion of that is cash, which the business does not need for investment and has said it will return. So I reckon there is no reason for the price after I've had the cash back to be much different from where it is now. What is more likely I think is a spike up when the company finally confirms the special dividend, then it will fall back once its paid.
2. Diversification - I don't own many natural resource stocks (recently sold all of my Trans-siberian Gold (LON:TSG) which had been the second-biggest holding in my portfolio) so it's useful to own something with little or no correlation to the UK economy, Brexit, etc.
3. 'Run your winners' is a principle that I am trying to practice more and be more disciplined about. I would consider selling Sylvania Platinum (LON:SLP) in favour something else I didn't already own with a more compelling investment case. That opportunity hasn't yet arisen...
The investment club's timing was excellent and a lot of the gain is to do with market movements after the April dip. I wouldn't really say that Sylvania Platinum (LON:SLP) has properly re-rated yet relative to the market, in my view it's part-way through a re-rating with more to come.
Looking forward to your Volex (LON:VLX) write-up. There's another really well-run company.
Doubled my holding 2 months ago. Pleased that I did.
I added to my holding this morning and then logged on to Stocko to find this article just posted. Sometimes timing does line up!
Consider JBL - Jubiliee metals a turn round situation from poor managment the same PMG processing on a larger scale with copper added - simliar chart . Also consider DRD for gold and Tharisa for PMG but there is a lack of liquidity .The short market for Rhodium is likley to continue for a year or two .There are some supportive write ups on the US on SYL so the buying is not just UK
I hold both SYL & JBL on the basis that risng metal prices will mean improved free cashflow and ROC.
I am still holding in and showing a good profit, but it really worries me that the directors of such an apparently successful company do not appear to want to buy and hold their own company shares. If it’s almost as if it is too good to be true ?