StockRanks for income: where are the opportunities today?

In two recent pieces in the Stockopedia Academy, I suggested some simple StockRank-based screening approaches to find good quality dividend growth and high-yield stocks.
In this piece, I’m going to take a look at some examples of shares from these screens that I think could be interesting opportunities today. I’ve selected 10 in total – five for high yield and five for dividend growth.
As always, these are only my thoughts, not recommendations. Please DYOR and form your own views before making any investment decisions.
5 dividend growth stocks
Here’s a quick reminder of the screening criteria I used to help create a shortlist of dividend growth stocks for further research. You can see (and copy) the screen here.
TI Fluid Systems (LON:TIFS) - yield 4.1%
This British engineering group has a long and illustrious track record in the automotive industry. It’s a leading manufacturer of thermal management and fluid-handling systems for cars, notably fuel systems.
However, TI suffered a spell in private equity ownership from 2015-2017 and has struggled since its return to the UK market – not helped buy a notable debt burden.
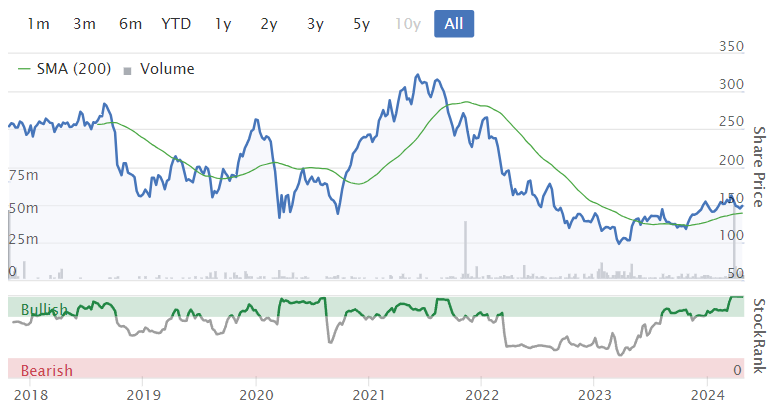
The business has also been forced to face up to the need to diversify its product range, in order to reduce its historic dependence on fossil-fuel powered cars. Fuel systems generated about half the group’s profits last year.
This turnaround is still underway, but I’m encouraged by progress – 43% of new order bookings related to electric vehicles last year.
From a dividend perspective, last year’s strong cash generation supported debt repayments and a useful 6.8p per share payout, giving a 4% yield.
The shares remain modestly valued on a forward P/E of 6. If the company can deliver on its plans, I think there could be an attractive dividend growth opportunity here.
Ultimate Products (LON:ULTP) - yield 4.2%
This housewares group – whose brands include Beldray and Salter – floated on the London market at around the same time as TI Fluid Systems. It also suffered a post-IPO slump but has since been a much more successful investment.

One reason for this might be the presence of owner management in the boardroom. Founder and CCO Simon Showman is the group’s largest shareholder, controlling more than 20% of the stock.
Ultimate outsources manufacturing to China, resulting in a capital-light business model that generates excellent quality metrics:

Cash generation is good and the share price looks undemanding to me. 2024 forecasts point to a P/E of 11 and a 4.4% dividend yield.
My main concern here is the risk that the group’s competitive advantages may be limited to the strength of its brands and its marketing distribution reach. Most of Ultimate’s products could be easily duplicated by competitors, in my view.
This dependence on commercial excellence might explain why the founder occupies the CCO role.
Even so, I think Ultimate’s owner management, steady progress and strong financial metrics make this business an interesting option for dividend growth.
Computacenter (LON:CCC) - yield 2.7%
This FTSE 250 valued-added IT reseller is another founder-owned business with an impressive long-term record of growth. Computacenter’s dividend record speaks for itself and the shares have four-bagged over the last 20 years.

One constant during this period has been the leadership of CEO Mike Norris. He’s been supported by founders and non-execs Sir Peter Ogden and Philip Hulme, who control about 22% of the shares.
I think there’s some key person risk here – Mr Norris would be a tough act to follow – but Computacenter’s recent trading has been strong and the group has substantial net cash and a stable outlook.
Margins are inevitably low in this business, due to the resale element. But Computacenter’s returns on capital are consistently high. I see this as a quality operation with long-term growth potential.
Coca Cola HBC AG (LON:CCH) - yield 3.1%
This FTSE 100 firm is one of Coca-Cola Co (NYQ:KO) regional bottling companies. CCH has an exclusive licence to distribute Coca-Cola products in a range of western, central and eastern European countries, plus some African markets. The group also continues to operate in Russia, selling local brands only.
I see this as a classic defensive consumer goods business, relying high-volume, low-cost branded sales. I think the group’s relatively stable profit performance during the pandemic supports this view:

Quality metrics and cash conversion are consistently strong and the group has established a solid dividend growth record since it switched its listing from Greece to the UK in 2013:

In my view, CCH makes an interesting alternative to consider alongside homegrown UK soft drinks businesses Britvic (LON:BVIC), A G Barr (LON:BAG) and Nichols (LON:NICL).
B&M European Value Retail SA (LON:BME) - yield 2.8%
This discount general retailer is familiar to a growing proportion of UK (and French) shoppers. B&M’s clever and ever-changing ranges of food and non-food products keeps shoppers returning regularly. It also allowed the group to qualify as an essential retailer and keep its stores open during the pandemic, triggering a remarkable run of growth.

B&M’s product ranges are masterminded by Trading Director Bobby Arora, who bought the group with his brother Simon in 2004. While former CEO Simon Arora stepped down in 2023, Bobby Arora remains locked in through a lucrative retention deal that was felt to be important enough to warrant its own RNS. I don’t disagree.
This business is well run, in my view, and enjoys significantly stronger profitability than UK supermarkets. Dividends have always been prioritised, with special payouts on occasion. Consensus forecasts suggest a 4.2% yield for the current year.

B&M shares look reasonably valued to me at current levels, and think the business has scope to continue growing.
5 high-yield dividend stocks
Here’s a quick reminder of the screening criteria I used to help create a shortlist of high-yield dividend stocks for further research. You can see (and copy) the screen here.

VP (LON:VP.) - yield 5.7%
Specialist equipment hire group VP is another business with founder management – chair Jeremy Pilkington controls just over 50% of the stock.
While this gives him effective control of the company, I don’t find this too much of a concern. This business has been listed since 1973 and has established an excellent record of profitable long-term growth.
As far as I can see, the dividend hasn’t been cut for 30 years, except during the pandemic:

In addition to competing in the general equipment hire market, VP has built a portfolio of niche hire businesses that serve higher-margin segments in a range of end-user sectors. These include water and civil engineering, rail and offshore oil and gas.

Although VP isn’t the cheapest stock in this sector at the moment, I feel it’s an above-average quality business. I would argue that the current valuation offers good value and the near-6% dividend yield looks sustainable.
Imperial Brands (LON:IMB) - yield 8.1%
This FTSE 100 tobacco group needs little introduction and will divide opinion. But its credentials as a high-yield dividend stock are strong, in my view.
Imperial’s performance has improved significantly since CEO Stefan Bomhard took charge in 2020. Profits have returned to growth, debt levels have fallen and the stock’s 8%+ yield looks well supported to me for the foreseeable future.
The word foreseeable is probably key to the risk inherent in this investment. Imperial’s earnings are concentrated in developed markets ,where more restrictive regulations on tobacco sales are a constant risk. Declining smoking rates are also a concern.
Imperial shares currently trade on six times forecast earnings and boast a price-to-free cash flow ratio of six.

While I wouldn’t want to pay a high price for this stock, I think much of the risk is priced in at current levels. I suspect Imperial will remain a cash cow for some years yet.
PayPoint (LON:PAY) - yield 7.1%
Graham included this UK fintech in his top 10 ideas for 2024. I also think that it is a good business that’s probably undervalued by the market and currently hold the shares in my rules-based SIF portfolio.
One caveat I’d add to this positive view is that there are quite a lot of moving parts to this business. This means that tracking like-for-like progress isn’t always easy. But recent results have been positive and PayPoint’s strong profitability and cash generation isn’t in doubt, in my view.

PayPoint’s dividend was cut before the pandemic as the group’s business was reshaped. But the current payout gives a 7.5% yield and looks sustainable to me, with some growth potential.
Robert Walters (LON:RWA) - yield 6%
Recruitment is an intensely cyclical business. If Robert Walters’ share price action is to be believed, the business is close to the bottom of the cycle at the moment:

Such dramatic cycles mean that this stock is arguably not well suited as a buy-and-hold position. But I would expect to see gains from current levels, when market conditions improve for the sector.
In the past, Walters has managed to maintain its dividend through downturns before increasing the payout during the next upcycle.

I expect this record to be maintained this time round. The group reported a net cash balance of £80m at the end of last year and its dividend remains largely covered by earnings. The 6% yield looks safe enough to me.
M&G (LON:MNG) - yield 10%
This retirement savings and asset management group is perhaps unlikely to be a dividend grower. But the 10% yield provides sufficient return in itself if it’s sustainable, which I think it is.

M&G shares have gone nowhere since its 2019 demerger from Prudential (LON:PRU). But the company’s guidance on cash generation and dividends has been consistently met.
More recently, the company’s asset management business has attracted new inflows and reported more positive investment performance than some UK rivals.

As a pure high-yield play, I think M&G makes sense. While such a high yield will never be without risk, this is an old and well-established business with reasonable scale and a sensible strategy. I’d be happy to buy at current levels.
Please let me know what you think in the comments below. Where are the best dividend growth and high-yield opportunities today?
Disclosure: Roland owned shares in Ultimate Products, Computacenter, PayPoint and Imperial Brands at the time of publication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
Cancun…….and for anyone else vaguely interested in these, here are (as promised) the big dividend paying shares and Investment Trusts I hold. Some are much better quality than others. Paul and/or Graham’s comments where they’ve commented will be useful. I’ve saved time by using the Stockopedia dividend yield figure. It’s not always correct but for all of these it seems about right.
INVESTMENT TRUSTS
Aew UK Reit (LON:AEWU) 88p. 9.1% dividend paid quarterly.
Alternative Income REIT (LON:AIRE) 68p 7.2% dividend paid quarterly.
Supermarket Income REIT (LON:SUPR) 74p. 8.3% dividend paid quarterly.
Tritax EuroBox (LON:EBOX) 60p. 7.2% dividend paid quarterly. Unfortunately it has risen fast recently so the great buy oppportunity has gone.
Twentyfour Select Monthly Income Fund (LON:SMIF) 83p. 9.2% dividend paid monthly.
European Assets Trust (LON:EAT) 87p. 6.7% dividend
Henderson Far East Income (LON:HFEL) 231p. 10.6% dividend. Lousy performance record but significant improvement since new Manager and strategy change. Quarterly dividend and they’ve increased it every year for multiple years.
CQS New City High Yield Fund (LON:NCYF) 51p 8.8% dividend paid quarterly. Very little capital gain ahead.
Bluefield Solar Income Fund (LON:BSIF) 107p 9.1% quarterly dividend.
Foresight Solar Fund (LON:FSFL) 91p. 8.9% quarterly dividend.
BlackRock World Mining Trust (LON:BRWM) 600p 5.6% quarterly dividend. But dividend higher in good years.
Amedeo Air Four Plus (LON:AA4) 39p. 20% quarterly dividend and they’ve committed to paying this big dividend until early 2026. WARNING. How much of the 39p investors will get back depends on the final value of the planes leased to Emirates.
SHARES.
Gulf Keystone Petroleum (LON:GKP) 115p. 0% dividend BUT! GKP paid huge dividends until their key pipeline was closed. It’s likely to reopen at some point. Gulf Keystone Petroleum (LON:GKP) paid 88p in dividends in 2021 ahead of the pipeline closure. So it’s a punt UNTIL the pipeline issue ends, but could rocket when it does.
Glencore (LON:GLEN) 455p Only 3% dividend but sometimes pays specials as well.
Harbour Energy (LON:HBR) 282p. 7.5% dividend.
Ithaca Energy (LON:ITH) 116p. 18% dividend.
Reach (LON:RCH) 81p 9.25% dividend. Declining business but digital moght compensate for that.
Smiths News (LON:SNWS) 56p. 8.8% dividend and they’ve just announced an increase. Again declining business……but add on acquisition if wise could help.
Serica Energy (LON:SQZ) 186p. 13.4% dividend.
Thungela Resources (LON:TGA) 553p 10.1% dividend.
Abrdn (LON:ABDN) 155p 9.4% dividend.
Barratt Developments (LON:BDEV) 479p. Dividend only 3.9% but it’s much higher during the good times for housing market.
Chesnara (LON:CSN) 252p Dividend 9.9% and they’ve increased it multiple years in a row, but share price performance poor. Bid candidate?
M&G (LON:MNG) 200p. 10.2% dividend
Phoenix group (LON:PHNX) 520p 10.6% dividend
Premier Miton (LON:PMI) 70p 8.7% dividend
Polar Capital Holdings (LON:POLR) 538p 8.6% dividend
Persimmon (LON:PSN) 1367p. 4.6% dividend …but again much higher in the good times.
Petrotal (LON:PTAL) 48p 8.3% dividend
Aviva (LON:AV.) 472p 7.6% dividend
Legal & General (LON:LGEN) 241p 9% dividend
Liontrust Asset Management (LON:LIO) 694p 10.4% dividend
Rio Tinto (LON:RIO) £54.67 6.2% dividend but much higher in the more profitable years including specials.
Very helpful indeed Ken... thank you so much... really appreciate your time taken...
Hi Ken,
it's a good list. Mainly as a result of your posts in the past, I currently hold BlackRock World Mining Trust (LON:BRWM), Aviva (LON:AV.) and Legal & General (LON:LGEN).
I'm looking at European Assets Trust (LON:EAT) as I understand the holdings are high quality from a ROCE and margin perspective.
M&G (LON:MNG) has come off more than the dividend announced back in late March. The downside here is that the second dividend for the year is much smaller. So I think I have time to see if the SP slips further.
With the shares in your list, it would be interesting to put them in order by StockRank. Maybe something I will take a look at next weekend if I have the time.
SSB
An excellent post Ken, just a quick caveat on Ithaca in case anyone is looking to buy to do your own research .....that future dividend is likely to be lower as a result of the combination with ENI. Ithaca Energy’s dividend policy is targeted annualised dividends of 15-30% of post-tax net cash from operating activities. They previously paid out $400million (although it was paid in three installments that went beyond the financial year and therefore wouldn't be a sustainable timetable of annual payments) and have stated their "ambition for up to $500 million total dividends each year in 2024 and 2025" to the increased shareholder base inc ENI. A 10% div may be realistic depending on operations, but the market hasn't responded well to the ENI agreement and the share price is down 36% over six months. I hold.
Thanks Rob for pointing that out. It was just a list of my big dividend payers. without any analysis on any of them other than to be careful with Amedeo Air Four Plus (LON:AA4.
It’s a must imo for investors here tempted by any of them to check out at least the most recent Company update and to scroll through it for the latest dividend policy. Some e.g Aviva (LON:AV.) and Legal & General (LON:LGEN) are very clear about their dividend policies…I.e further increases year on year. Others hide that important information or don’t cover it, and that can be a sign of a cut or cancellation ahead. I usually sell on a dividend cut or cancellation, and also on any warning in a Company update, of a cut ahead.
I’m confident about most on my list, but it was a surprise that Serica Energy (LON:SQZ) maintained their dividend and the Thungela Resources (LON:TGA) dividend depends on the spot coal price. It’s easy to keep an eye on that by using this list:-
https://tradingeconomics.com/c...
Click “more” (it’s on the right hand side) and all the key commodity prices appear.
Also this site is superb for right up to date information on dividends:-
https://www.dividenddata.co.uk...
ALL the headings at the top are well worth checking out.
Hi Ken,
Do you have any thoughts on the announcement by CQS New City High Yield Fund (LON:NCYF) regarding the issue of new equity 4.85m shares today at 51.2p http://newsfile.refinitiv.com/...
The issue is at a slight premium to NAV and is for cash but the SP dropped a little bit and is below the issue price.
I hold these and am up about 10% but not sure whether to continue to hold or take the small gain. I wouldn’t like to see them just dwindle down.
Graham.
Graham.
Investment Trusts issuing new shares when the share price is at a premium is quite common. Just as it is for those at big discounts to go for buybacks to try and reduce that discount.
THE thing to note with CQS New City High Yield Fund (LON:NCYF) is that the vast majority of their investments are in bonds. That makes CQS New City High Yield Fund (LON:NCYF) a low risk Investment Trust as bond prices don’t rocket, but it also means limited share price upside. The share price tends to move between 45p and 55p.
There are two obvious ways to play CQS New City High Yield Fund (LON:NCYF) . The first is to buy (as I did and you must have too) on a dip to the mid to high 40s which maximises the dividend yield and means a regular 9% a year in income, and to hold long term.
An alternative is to buy the dip and sell in the 50s if looking to trade, rather than hold.
With so many Investment Trusts with far more potential share price upside still available I go for the hold CQS New City High Yield Fund (LON:NCYF) long term hold option, but those monitoring for the buy the dip and sell the bounce option, there’s definitely a good chance of getting more than 9% a year profit.
Hope that helps.
Thanks Ken,
That does help.
I did, as you say, buy in the mid 40’s, so getting a good dividend whilst also got some upside with the share price gain. They have gained back the loss of SP yesterday, so no panic.
Graham.
Graham
A key point in my reply was for reasons explained then, there’s no need to panic about CQS New City High Yield Fund (LON:NCYF) as it’s a low risk/ relatively low reward, Trust where share price moves should be modest. It’s unexciting but a good one for the very cautious.
Thanks Ken,
It has started to edge back up a little and the fact that it’s trading at a premium, before and after the share placing, bodes well for the trust. Hopefully when interest rates finally come down its returns will seem greater.
Graham.
You've given me heart palpitations positioning CQS New City High Yield Fund (LON:NCYF) as low risk, Ken.
I see some bright flashing amber warning signs here, notably the lack of dividend cover in recent years. I see the miserly 0.01p increases in the annual dividend (done probably to make sure they stay in the coveted AIC dividend hero list) as a clear sign the dividend is stretched. And within the world of bond portfolios, I don't think it has too much toward the investment grade end. It's higher yield which is normally for a reason.
If interest rates do come down, short term they'll likely get a boost to their asset prices which will help sustain the dividend cover - but that could be short-lived.
To sustain the dividend yield longer term, I see a risk the managers chase after more and more risk.
Anyone buying this would need to pay attention to what's going on I feel.
M48.
That’s all fair comment about CQS New City High Yield Fund (LON:NCYF). And yes, the dividend has been barely covered for a years…..but still they’ve managed to maintain or very slightly increase it.
Obviously there’s always the risk (think of Neil Woodford) of Managers making bad decisions, but I can’t see why it would be necessary for big risks to be taken to maintain the dividend. E.g they could increase equity exposure a bit with shares like M&G (LON:MNG) paying 10% dividend.
The share price has ranged from roughly 45p to 65p for around 20 years, except for a very temporary drop lower at the start of the covid crash. My key point in replying to Graham was that for those of us buying around 45p the risk of significant share price fall looks low. That’s not the case for anyone who paid 60p or more…….and the yield at that price was lower too.
CQS New City High Yield Fund (LON:NCYF) is trading at a bigger premium than usual and there’s certainly a risk of a pull back to around 45p.
Finally whenever the facts change for the worse I sell. So if your concerns are shown to be justified in an update from CQS New City High Yield Fund (LON:NCYF) that’s when I would sell. I don’t sell because of fear of something bad happening that hasn’t yet, and quite likely won’t.
Interesting in that I have just bought TI , but not for income - price growth. I am just part time investor so I aim at getting shares with dividends of 7% or more to pay Stockopedia Costs (smile). Then my short term and growth strategies do the rest. Sad that so many companies have suffered under the Private Equity regimes.
I must admit to being a bit confused about the notion of income investing in equities - especially in dividend growth stocks. It seems to me that if place cash on deposit I get income and my capital back and current returns can be greater than some of the dividends offered here. If I were to hunt the same or greater income in some of these shares I might get income but at a risk of capital due to volatility of SP. So in general 'what's the point?' As always happy to be educated
Many equities pay more that you can earn in a UK bank account. Personally I don't own any of the companies above however.
So lets say inflation in the UK is 4.7% p.a. as per the BOE.
If your bank pays you a rate of return of say 4% p.a., then your real rate of return (i.e. post inflation rate of return) is -0.7% p.a.
If you buy an stock that yields > 4.7% then your real rate of return is positive.
In other words you are losing purchasing power leaving cash in the bank over time, whereas with the equities you can achieve a positive real rate of return (and hopefully some growth too).
Some companies pay out very large dividends and are solid but you need to know where to look and they are generally in unpopular sectors e.g. Ecopetrol SA (NYQ:EC) ,Yankuang Energy Co (HKG:1171) ,Geo Energy Resources (SGX:RE4) ,Kenmare Resources (LON:KMR) ,Nordic American Tankers (NYQ:NAT) ,I could go on....
alsy933
Here is brief proof that dividend investing works.
Games Workshop (LON:GAW) share price was around £4.60 just 8 years ago. It is now £90! The current dividend is £4.50 a year. That’s almost the entire stake back every year just in dividends for anyone who bought just 8 years ago. AND the share price has gone up 20 times.
My portfolio is now full of big dividend payers and Companies and Investment Trusts increasing their dividends year after year. Many of the holdings are profitable and annual dividends as high as 20%. Had I woken up to this sooner, then by now I would be holding shares where the annual dividend yield is more than I would have paid for the share!
Lord John Lee, the first ISA millionaire has holdings in his portfolio paying over 100% in dividends AND those shares have all multi bagged.
And dividends now finance the new portfolio buys and the portfolio is now self financing with no need to add any new money.
I might post a few current quality big dividend paying shares and Investment Trusts another time.
That would be amazing when you get a chance please Ken ... many thanks indeed for all your insights...
Cancun. I haven’t forgotten and will post on high yielders in our portfolios sometime over this long weekend.
That would be amazing whenever you get a chance Ken... many thanks indeed
I think that Paul is right Ken and we're just starting a multi year bull run in small and mid caps ... technically and sentiment wise, the set up looks appropriate... I'm holding too high a % in cash at the moment , so wanted to get into some decent dividend payers with some growth prospects... not the special situations of Reach, Smiths News etc... I probably ought to buy 1 UK small / mid company investment Trust as well , to let the professionals take some of the strain though haha... although I do prefer the fun of taking responsibility myself of individual stock decisions ... as a consequence I have never read the investment Trust thread I am embarrassed to say... presumably I will find suggestions on there for a suitable discounted Investment Trust with decent prospects...
Many thanks indeed for your help and time....
Hi Cancun,
Fidelity Special Values (LON:FSV) is an investment trust with small and medium UK businesses (I hold). You’ll recognise many of the companies on its full list in the annual report, page 11. There was some discussion on it on April 4th in both April’s Investment Trust post and the SCVR.
For a fuller list of suggestions, I recommend you ask the question in the May IT post. There are v helpful and knowledgeable people there. And of course it has a link to the AIC website for further research on all things Inv Trust.
Wishing everyone good outcomes to their decisions.
Cancun
There are a lot of big dividend paying Investment Trusts and they are a way to invest all round the World. Why stick only to the underperforming UK market? There’s a very good Investment Trust thread here updated every month. It’s well worth looking at it. Having just read your latest post my list of big dividend payers may not appeal to you.
We have a fair bit of exposure globally, but at this point in the cycle the UK just seems relatively inexpensive.... I probably need to buy more of the fund managers ... low pe, high dividends and growth if the cyclical argument pans out ...
Just want to say thanks to the people who replied, certainly given me food for thought and some areas to investigate; your help and advice sincerely appreciated
Games Workshop (LON:GAW) ( i own) worthy of mention here with a ttm yield of c. 4.2% and terrific growth prospects.
Thanks Roland. I found this a very interesting piece what with interest rates hopefully now on a downward trend. I have been looking to place some high yielders into my ISA whilst looking for some sustainability of payout as well as some GARP features.
Some of your selections are in my portfolio but I have not looked at B&M or Coke before so some research now needed. A few of my own selections don’t feature in your list and I would mention Aviva and L&G as standouts.
Thx again
Mark
Thanks for the screens and analyses, Roland.
I have been investing in higher yielding stocks expecting that they will also attract a higher share price as gilt interest rates fall. Meanwhile, the dividend flow is very useful.
I think there's a lot of opportunities in the REIT and renewable energy sector right now. Discounts very wide, but should tighten when rates fall - while you wait you can get a c.8% yield. You need to avoid some of the dross, but there's plenty of high quality companies paying very attractive dividend yields. I focus on those with reasonable levels of debt, fully covered dividends and a good track record. My top picks include Urban Logistics Reit (LON:SHED) Supermarket Income REIT (LON:SUPR) Greencoat UK Wind (LON:UKW) and Bluefield Solar Income Fund (LON:BSIF)