S&U expecting a return to form as it outgrows broader motor finance sector

Analyst’s view:
I've made no secret of being a fan of this one. It currently offers a P/E multiple of 8x and a small discount against tangible balance sheet equity of £251m. Quality metrics should improve now that the company is free to grow thanks to a settled regulatory environment - assuming no major uptick in arrears. I'm staying fully positive on this.
Up 1% at £19.45 (£236m) - Trading Update
It's a pleasant Q3 update from this family-run motor finance and property bridging company.
The long-term chart (for five years) shows that the company has struggled to make much headway in terms of capital appreciation:
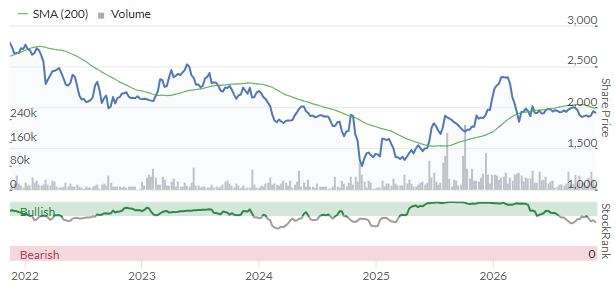
There have been many external factors at play, not the least of which was the regulatory intervention into motor finance - and specifically the investigation into S&U by the FCA.
Fortunately, that is now behind it, and improved profitability should follow:
The Group continues to lay the foundations for a return to the levels of profitability achieved before the disruptions, both regulatory and macro-economic, in the motor finance and residential property markets we serve.
Let's review some of the highlights from this Q3 update for FY Jan 2027:
Advantage Finance: receivables up 12.4% year on year, and loan advances up 20%, despite contraction in the used car finance market.
"Up-to-date receivables have improved to 73.5% compared to 72.5% this time last year." (N.B. this is a subprime lender.)
Similarly, "Our year-to-date collection rate on live accounts stands at a healthy 91.6% compared to 90.4% last year".
The distinction between 73.5% up-to-date receivables and the 91.6% "collection rate" reflects that some customers will make occasional or partial payments, even if their account as a whole is in arrears.
Overall, I'm enthused by the improvement in the numbers here, which has accompanied the growth in the overall size of the business. Hopefully the new loans have a similar creditworthiness - S&U's track record would suggest that they are comparable.
There is one warning light in relation to arrears:
The past quarter has seen a temporary uptick in early arrears, primarily related to our planned credit scorecard updates in late 2025 and potentially impacted by cost-of-living pressures from the Iran war. While S&U's historically prudent provisioning naturally treats early arrears conservatively so that bad debt accounts running even a minor 99 over budget in October, have a small impact on short-term profits, appropriate adjustments are already in place. We anticipate these trends will normalise as customer payment patterns stabilise, leaving our long-term strategy and confidence unchanged.
So there is some cause for concern here - but at the moment it's not serious.
Aspen Bridging: "continues to trade satisfactorily despite the current chronic state of the residential property market in the UK which it serves".
Capital receivables to increase by about 20% year on year.
Late payers are "well within budget".
Comment by Chairman Anthony Coombs:
“Our confidence throughout the Group in its profitable growth is evident, both in the unprecedented investment of nearly £100m in the past year and in the new funding facilities making it possible over the next three years. As always, such investment is conditional on a profitable return. Our focus is on achieving this in the years ahead and we are confident of doing so.”
Graham's view
I've made no secret of being a fan of this one.
It currently offers a P/E multiple of 8x and a small discount against tangible balance sheet equity of £251m.
The StockRanks are less impressed than I am:
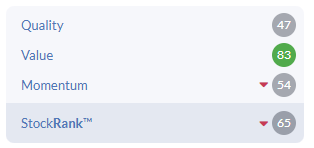
However, it's my belief that Quality metrics should improve now that the company is free to grow thanks to a settled regulatory environment - assuming no major uptick in arrears.
As for Momentum, I would expect the share price to take care of itself if quality and earnings materialise as expected.
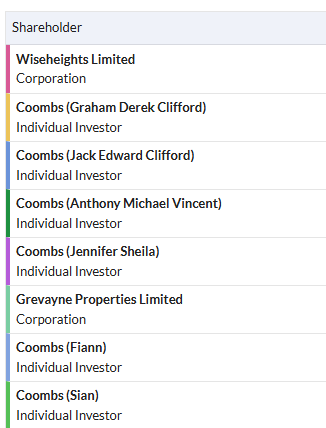
I'm staying fully positive on this. A great example of a family business, in my book:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on S&U (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?