The Evolution of a Super Investor: How Warren Buffett Learned to Love Quality

Warren Buffett may be a successful investor, but he has made mistakes. The journalist, Becky Quick, once asked him about his blunders. Buffett said, ‘the dumbest stock I ever bought— was— drum roll here— Berkshire Hathaway’. This snippet of information surprised me. Buffett started buying Berkshire in 1962, at $7.50 a share. It now trades around $750,000! Yes — that’s the share price, not the market cap! And yet, Buffett called Berkshire Hathaway a $200 billion blunder. When he first saw the stock, he saw a bargain. Later in life, he said, ‘I would have been better off if I’d never heard of Berkshire Hathaway.’ He would always resent the fact that a large chunk of cash had been sunk into an unprofitable business — cash which could have been invested elsewhere at high rates of return. Was the writing on the wall? To answer, we must return to 1962 and see the world as Buffett once saw it.
A value opportunity?
Back in 1962, Buffett was a zealous disciple of Ben Graham and David Dodd — the founding fathers of value investing. He had memorised their textbook, Securities Analysis, and once admitted, ‘I knew the book even better than Dodd.’ The principles of value investing were drummed into his head. Buffett was attracted to Berkshire Hathaway because he saw a value investing opportunity. Berkshire was a struggling textile company, selling at a discount to the value of its assets (i.e. mills). Warren connived a plan to buy shares on the cheap, in the hope that Berkshire would buy them back at a premium. This made sense. Berkshire had previously been selling off mills, before using the cash proceeds to buy back its own stock. This reasoning led Buffet to believe that Berkshire was worth $19/share, even though it was trading at $7.50.
Or a value trap?
It was an elaborate plan, but it didn’t quite work out, in part because Warren’s emotions got the better of him. We may think of Buffett as a folksy, grandfatherly figure, but they say we look at history through tinted glass. Buffett was once a young corporate raider, charging around, selling off this and that company and firing people along the way. When Buffett fell out with the management at Berkshire, he decided to buy up the whole company and fire the managing president. He won the boardroom battle, but it was a Pyrrhic victory.
Warren’s original plan was for Berkshire to buy the shares back from him. This plan quickly unraveled; Buffett had become Berkshire’s largest shareholder and would, in effect, be buying the shares from himself. Furthermore, Buffett had lumbered himself with a declining company in a dying industry. Berkshire Hathaway’s old financial statements are now preserved online. Using these, we can reconstruct the financial landscape of the ‘swinging sixties’. Even a quick glance reveals several red flags that should have been obvious to the Oracle of Omaha…
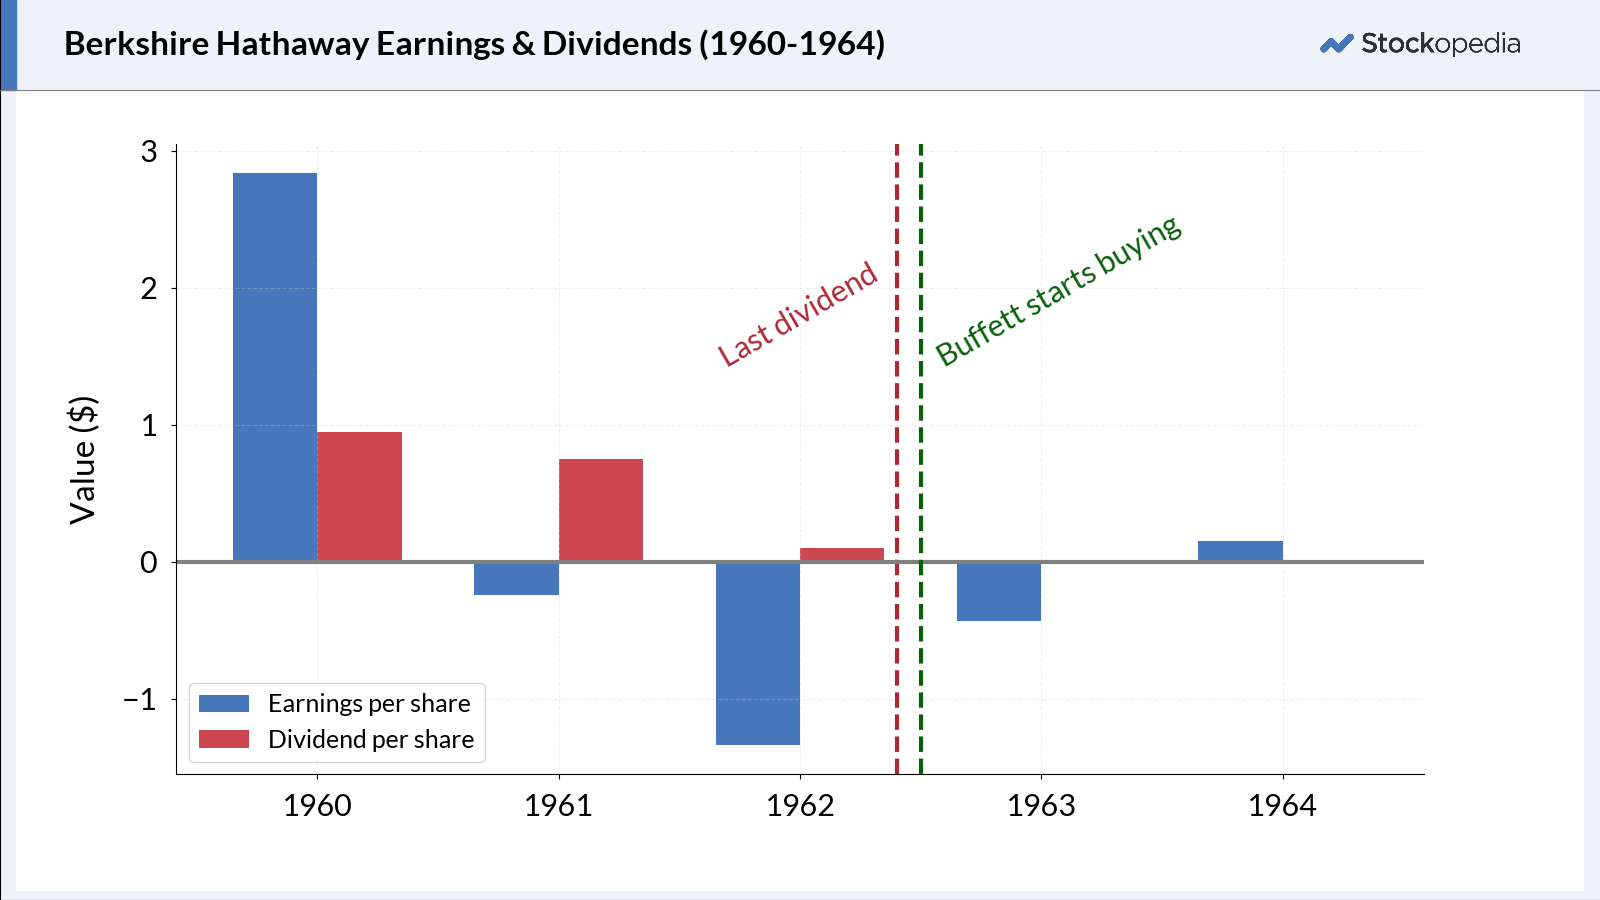
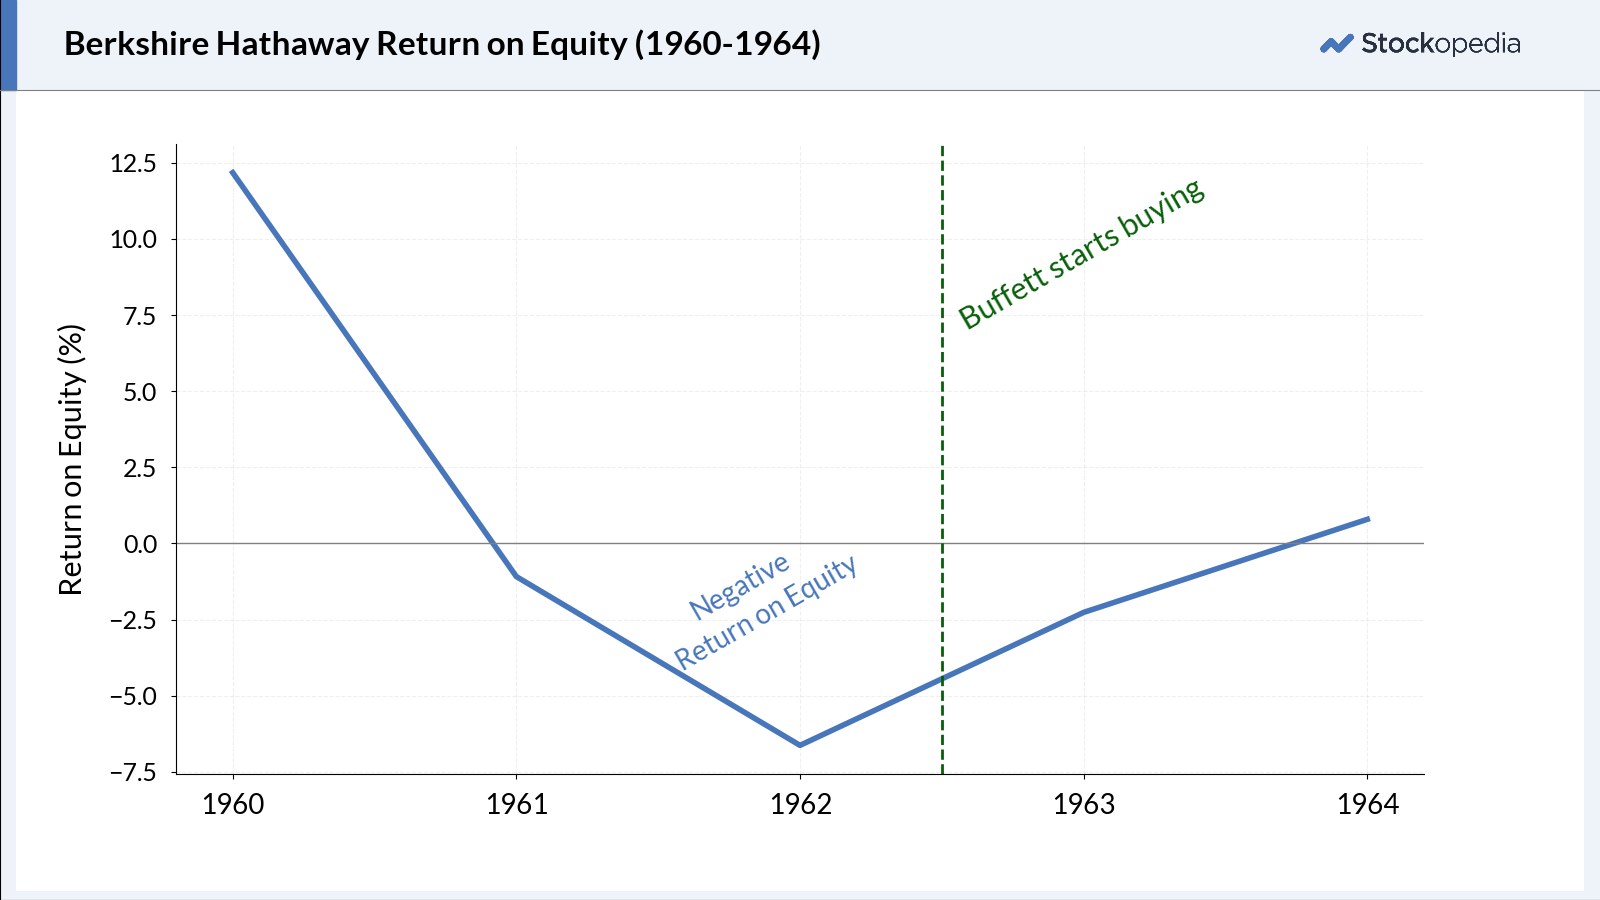
Reflecting on the episode, Warren said: ‘I bought my own cigar butt and I tried to smoke it’ — alluding to the idea that if cigar butts on the pavement are free, then you can get one last puff for no price. That was his idea of a bargain investment. The problem was that Berkshire didn’t have any more puffs. ‘All you had was a soggy cigar butt in your mouth’.
Shedding old skin
Like all great people, Buffett learned from his mistakes and reinvented himself. He did not neglect his old, value investing self. Instead, he integrated the best of value investing with a new approach. His philosophy became a blend of quality and value. He started to focus on cheap companies with strong, sustainable competitive advantages and the potential for long-term growth. A key influence was Charlie Munger, Buffett’s longtime business partner. Warren later said:
‘I was in this Charlie Munger-influenced type transition—sort of back and forth. It was kind of like during the Protestant Reformation. And I would listen to Martin Luther one day and the Pope the next. Ben Graham, of course, being the Pope.’
This back-and-forth conversion went on until Buffett could clearly articulate his philosophy in one line: ‘I like buying quality merchandise when it is marked down.’
The Washington Post newspaper perfectly exemplified Buffett’s idea of quality merchandise. Here was an established brand with wide circulation and a loyal customer base. The newspaper had a mile-wide moat, but the company went through a rough period in 1973 after exposing the Watergate scandal and incurring the wrath of President Nixon. The stock fell from $38 to around $15. Buffett recalled that ‘when we were buying that stock at $20 a share, if you’d asked the people how much the company was actually worth, they would have said $100 a share. But they sold it anyway.’ So there you have it. Quality merchandise, marked down.
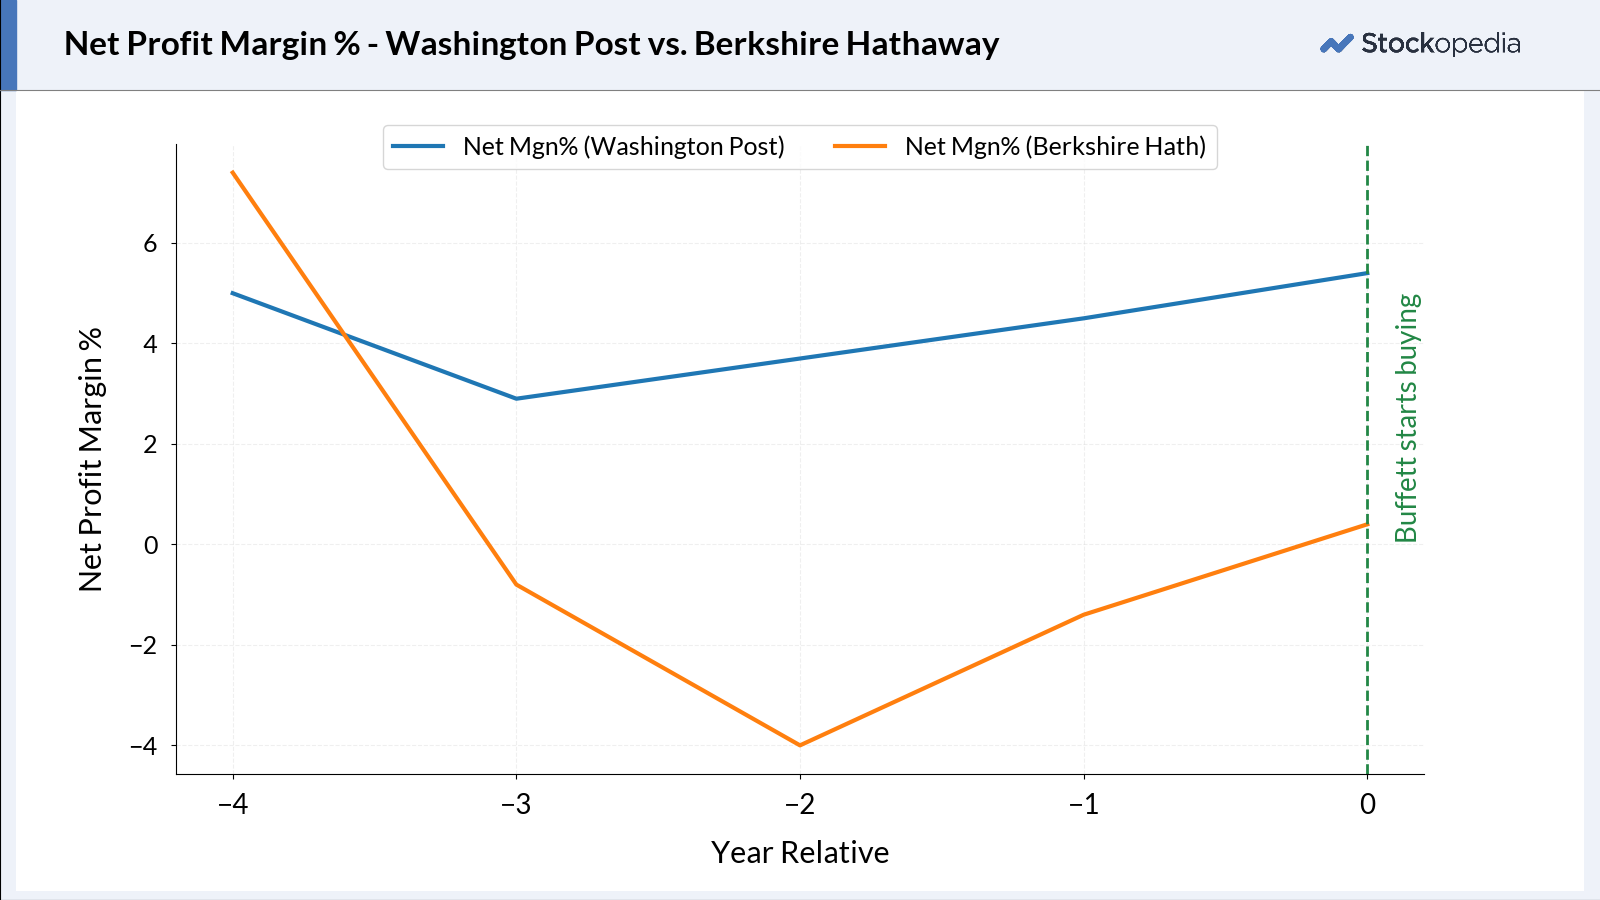
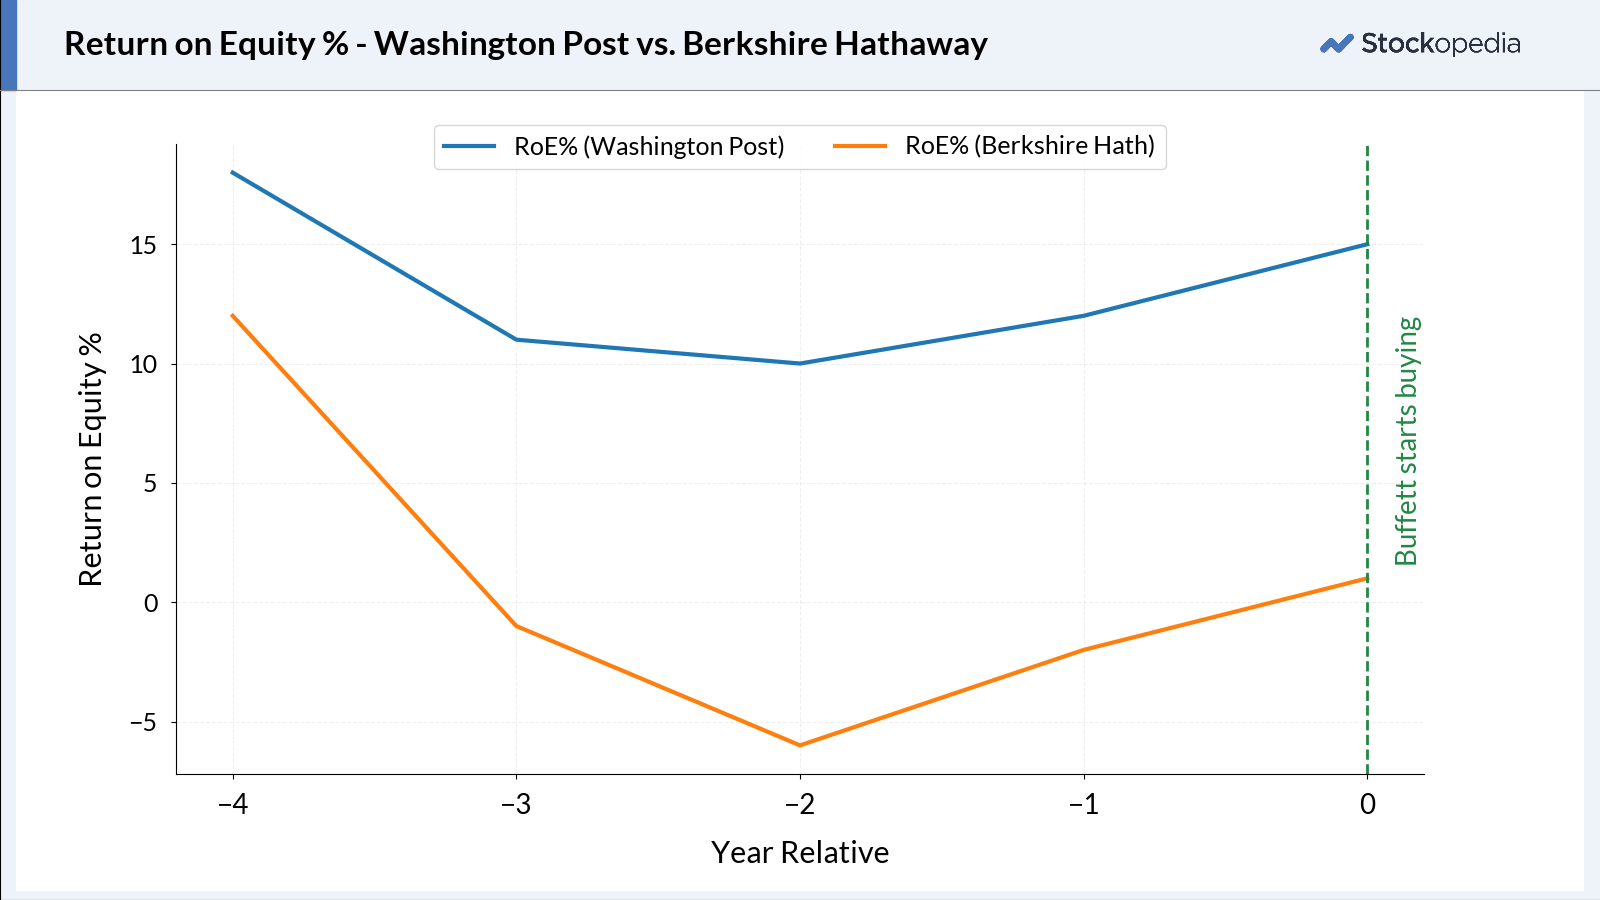
To understand how Buffett’s view of quality evolved, it is useful to compare the profitability of Berkshire Hathaway and the Washington Post in the years preceding his investment. The Post consistently delivered higher margins and returns. Furthermore, the Post’s returns and margins were fairly steady, while Berkshire’s profitability had declined noticeably from earlier periods.
From Value to Quality-Value
If we were to impose the technical language of today on the investment universe of the 1960s and '70s, we would say that Buffett was shifting from a Value strategy toward a Quality-Value strategy. These are the terms we might use in the framework of a factor investing — a systematic approach that quantifies the characteristics (i.e. factors) associated with outperforming stocks. One factor is value; cheap stocks tend to beat expensive stocks. Another factor is quality; companies that are profitable, financially stable and cash generative tend to outperform those that are loss making, highly leveraged and cash-strapped.
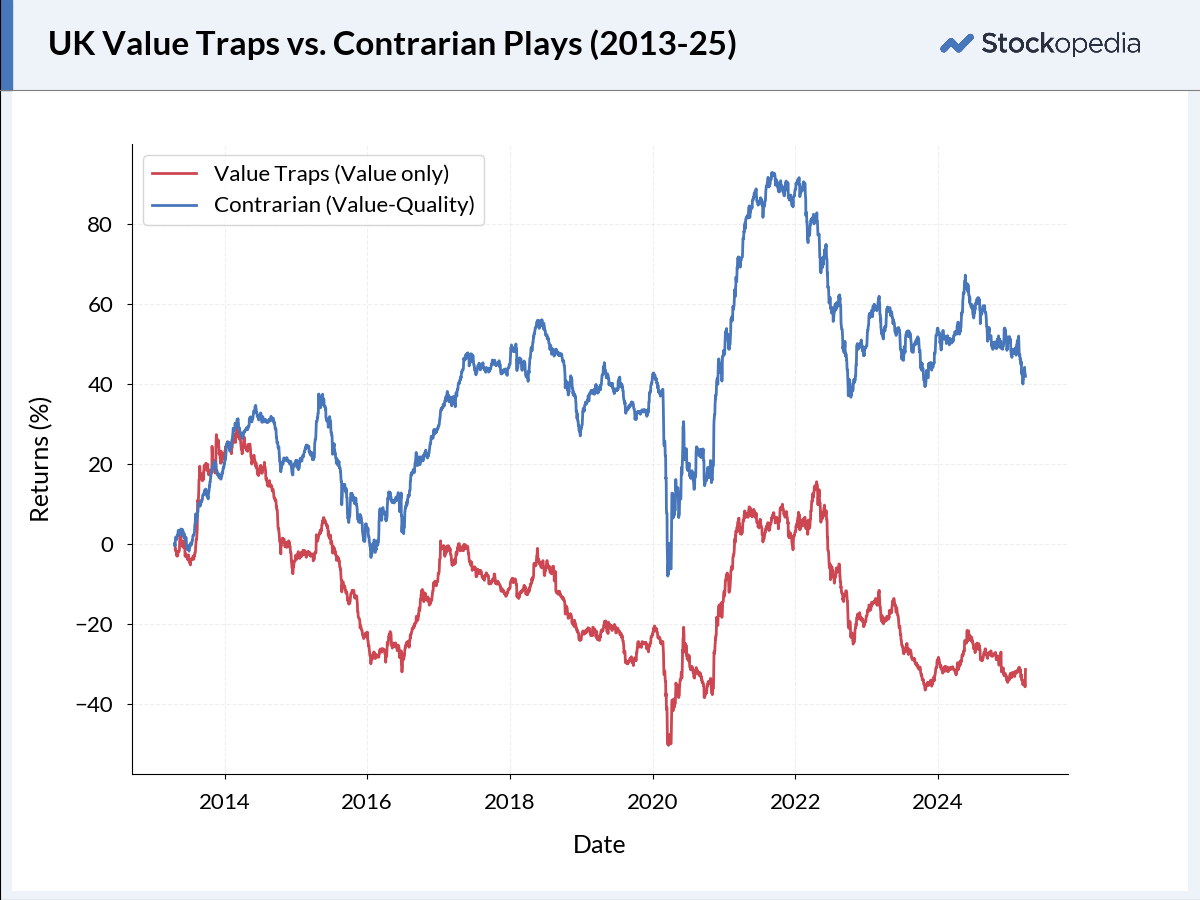
Berkshire Hathaway was only exposed to one factor, namely value. It was trading below asset value. Quality metrics, like profitability, were weaker. The Washington Post was exposed to two-factors, Value and Quality. It was cheap, having fallen from $38 to around $15. It was also a profitable company with an established brand. Berkshire Hathaway was what we might call a Value Trap. The Post was a Contrarian play. These labels are part of our categorisation system, which can be used to separate the wheat from the chaff — or separate the Washington Posts from the Berkshire Hathaways. Value Traps are cheap for a reason. To extend Buffett’s analogy, these are cigar butts with no puff left. By contrast, contrarian companies are cheap, but they are also profitable, cash generative and financially stable. The term is a play on Buffett’s maxim: be fearful when others are greedy; be greedy when others are fearful.
These labels — Contrarian and Value Trap — are shown on every StockReport.
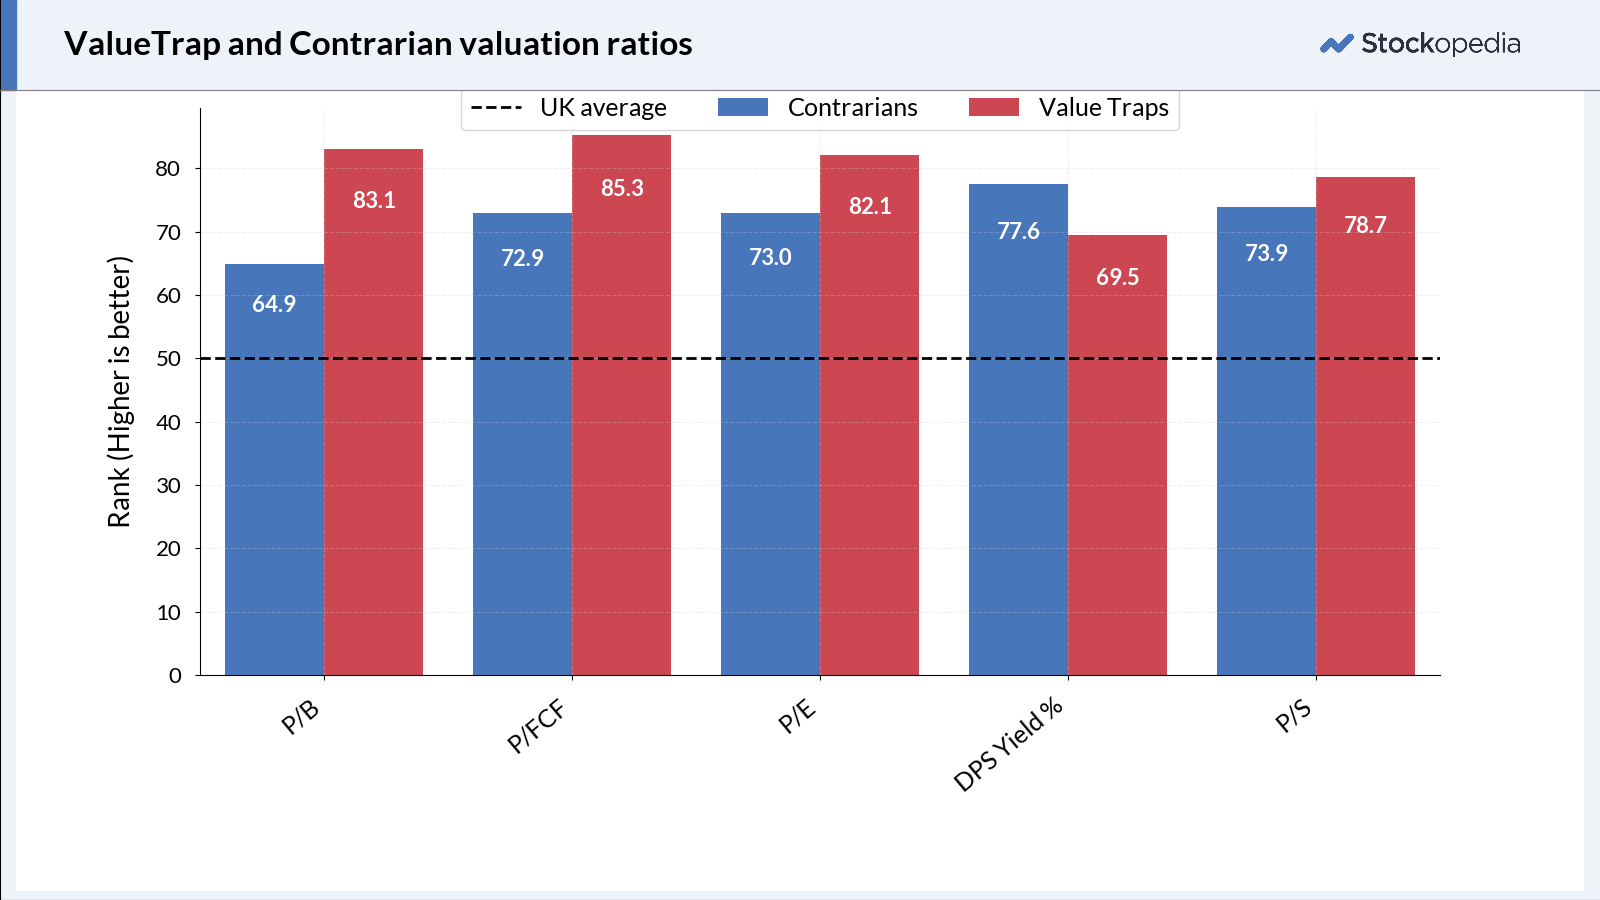
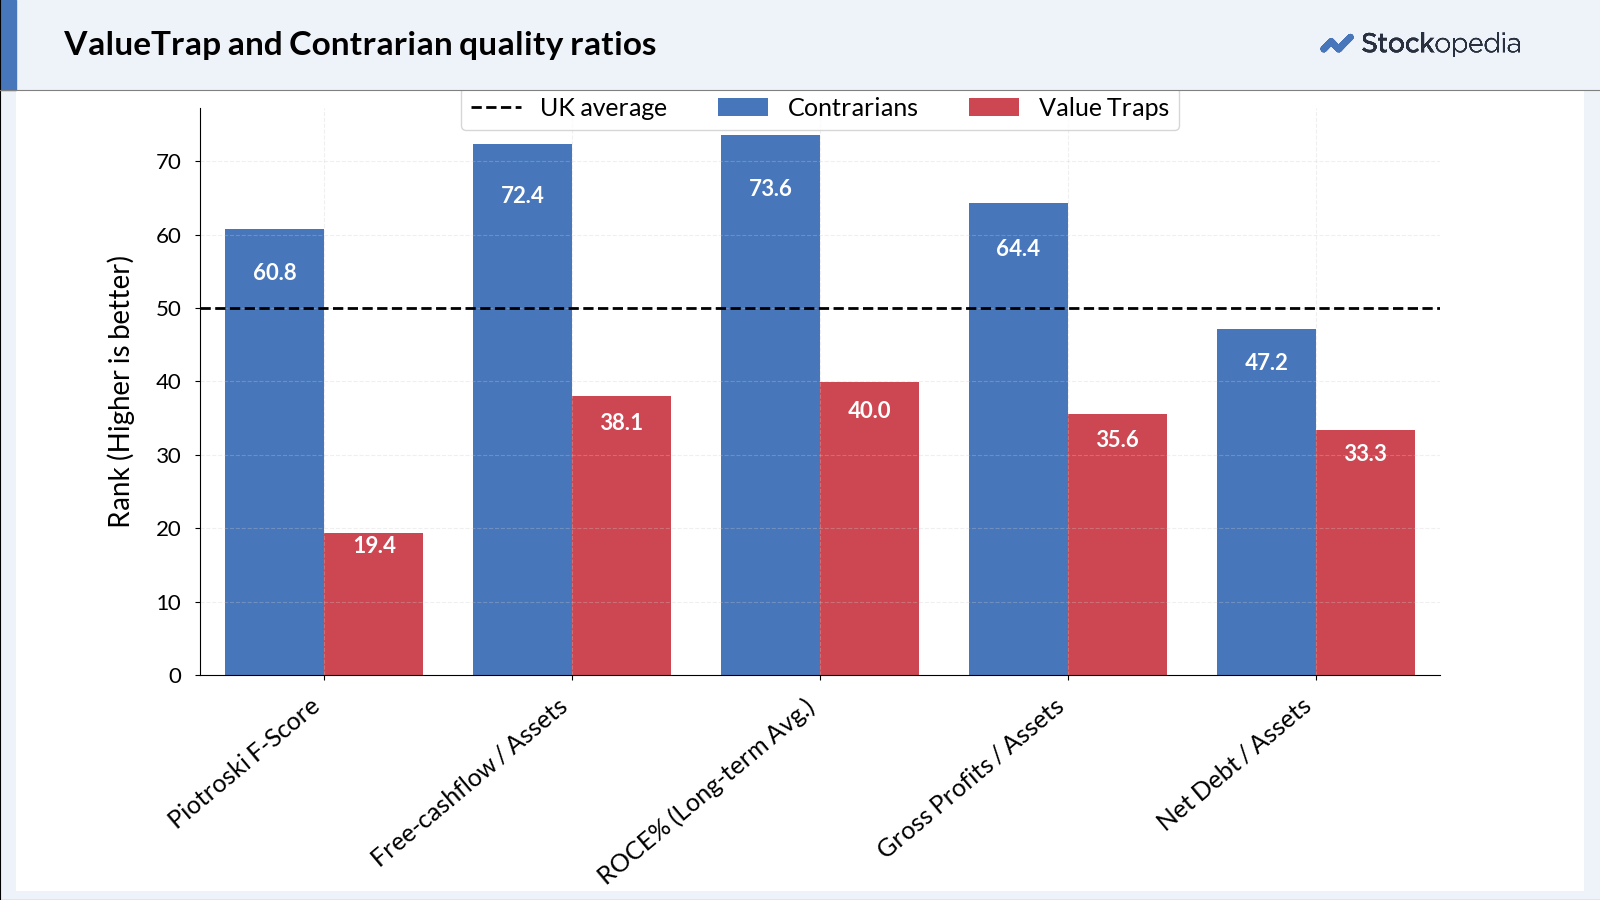
Generally speaking, Value Traps will only have better than average value ratios. Contrarian stocks will better than average value ratios and quality ratios. As such, the difference is in quality.
What is your story?
A key part of growing up is learning the balance between doing things ‘by the book’ and doing things your own way. Various anecdotes suggest that young Warren was a ‘by the book’ value investor — the kind of guy who would hold up The Intelligent Investor, wag his finger and say, ‘You see, Ben Graham said so!’ For example, in 1950 Buffett met with Lou Green, one of Graham’s business associates. Green asked, ‘Why did you buy Marshall-Wells?’ Warren replied, ‘Because Ben Graham bought it.’
Later in life, Buffett described his investment style as 85% Ben Graham, 15% Phillip Fisher. Fisher enhanced Buffett’s approach by focusing on quality companies with strong growth potential and strong financials. This shift is just a reminder that no philosophy is static, especially in investing. Everyone evolves—Buffett did, and so will you. We believe this evolution is worth talking about. Whether you're early in your journey or have decades of experience, we invite you to share how your own philosophy has changed. What ideas have you held onto? And what works best for you now? Let’s learn from each other.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Berkshire stake in Google parent Alphabet grows 83% to 106 million shares
Berkshire sheds Constellation Brands, adds to Delta, Macy's stakes
Stock investments grow as Berkshire's cash pile declines
Adds details on Coca-Cola and Bank of America in paragraph 3
By Jonathan Stempel
Aug 14 (Reuters) - Berkshire Hathaway BRKa.N said on Friday it boosted the size of its investment in Alphabet GOOGL.O by 83% in the second quarter, making the parent of Google and YouTube its third-largest stock holding.
Berkshire said in a regulatory filing that it owned nearly 106 million Alphabet shares worth about $37.8 billion as of June 30, up from 57.8 million shares three months earlier. The stake included a $10 billion investment announced in June, to help Alphabet expand its AI infrastructure.
Apple AAPL.O remained Berkshire's largest stock investment, worth $66 billion at the end of June, followed by American Express AXP.N at $51.3 billion. Coca-Cola KO.N ranked fourth and Bank of America BAC.N was fifth.
Berkshire also said it eliminated its year-and-a-half investment in alcoholic beverages producer Constellation Brands STZ.N, while adding to investments in Delta Air Lines DAL.N and Macy's M.N that it began in the first quarter.
The changes were disclosed in a filing describing Berkshire's U.S.-listed stock holdings as of June 30, which comprised most of its $323.8 billion equity portfolio.
BUFFETT CLAIMED CREDIT
Berkshire bought $23.5 billion and sold $3.7 billion of stocks in the second quarter, ending a 14-quarter stretch when it sold more stocks than it bought.
Chief Executive Greg Abel has begun reducing the enormous cash pile that his predecessor Warren Buffett left him when the legendary investor stepped down at year end.
Berkshire's cash stake fell to $364.7 billion on June 30 from $380.2 billion on March 31, a decline also reflecting $4.5 billion of stock buybacks.
Buffett remains Berkshire's chairman. He told CNBC last month it was his idea to invest in Alphabet, a stake Berkshire began building in last year's third quarter. Buffett also said he and Abel consult on how Omaha, Nebraska-based Berkshire allocates capital.
SEVERAL TWEAKS
The Delta investment grew 44% in the second quarter to 57.3 million shares worth nearly $5.4 billion, while the Macy's investment more than doubled to about 7.3 million shares worth $173 million.
Berkshire also bought more shares of home builder Lennar LEN.N and disclosed a tiny — $580,000 — stake in another home builder, D.R. Horton DHI.N. It reduced its holdings in Ally Financial ALLY.N, Bank of America, Capital One COF.N, kidney dialysis provider DaVita DVA.N, grocer Kroger KR.N and steel maker Nucor NUE.N.
Abel said in February he oversaw 94% of Berkshire's stock holdings, while investment manager Ted Weschler handled 6%.
Friday's filing does not say who bought and sold which stocks.
Berkshire also owns dozens of businesses including the BNSF railroad, Geico car insurance, energy and manufacturing companies and retail brands such as Brooks, Dairy Queen, Fruit of the Loom and See's.
https://tinyurl.com/zxeu2nhz
Useful read on the latest Berkshire Hathaway (NYQ:BRK.A) results, Warren Buffett's last as CEO.
https://tinyurl.com/54mjwp42
Report is available for all to read. My only complaint is I can't find a table of the equity holdings by percentage holding. If anyone else can see this please post.
https://tinyurl.com/mvzdv669
Long-term performance versus the S&P 500 Index (SP:SPX) is decent :-)
I don't have access to the US markets in Stockopedia but recent performance doesn't look disastrous, maybe just treading water ?
https://tinyurl.com/bddmhcat
Jan 2 (Reuters) - Berkshire Hathaway's (NYQ:BRK.A) BRKa.N, BRKb.N post-Buffett era began quietly Friday, as shares slipped slightly after the "Oracle of Omaha" handed Greg Abel the top job following six decades at the helm.
The world's most famous conglomerate now must protect its record without its chief architect, who remade modern investing and transformed the company from a struggling textile business into an investment giant worth more than $1 trillion.
Known for a long-term strategy and a focus on buying high-quality businesses at reasonable prices, Warren Buffett delivered steady gains that outpaced broader markets and made him a trusted steward of capital.
But Buffett's longtime lieutenant Greg Abel takes over at a sensitive time for the company. Berkshire shares underperformed the benchmark S&P 500 .SPX index in 2025, and Buffett has said that it is difficult to find an acquisition that "moves the needle" for the conglomerate.
RECORD CASH, FEWER DEALS
Berkshire has been whittling down its stake in Apple AAPL.O and Bank of America BAC.N, while building a record cash pile that has worried some investors.
The company held $381.7 billion in cash and equivalents, as of September 30. Berkshire has not said who will take over its equity portfolio, which totaled $283.2 billion at the end of September.
Still, Abel, 63, inherits one of corporate America's biggest war chests. He joined Berkshire in 2000 after it acquired MidAmerican Energy, now known as Berkshire Hathaway Energy.
He has served as vice chairman overseeing Berkshire's non-insurance businesses since 2018.
Berkshire's Class B shares, which trade at a more accessible price point, edged down 0.3% in New York on Friday. Class A shares also traded 0.4% lower.
Wall Street's main indexes, meanwhile, rose on Friday. .N
Berkshire Hathaway owns a sprawling collection of businesses, including insurer GEICO, BNSF Railway, dozens of manufacturing and energy operations, and consumer brands such as Dairy Queen, Fruit of the Loom and See's Candies.
Buffett will remain chairman and has said he plans to continue coming to Berkshire's office in Omaha each day, about 2 miles (3.2 km) east of his home, to support Abel.
Berkshire’s long-run performance has eclipsed the S&P 500 https://reut.rs/4pmBec7
(Reporting by Niket Nishant and Manya Saini in Bengaluru; Editing by Tasim Zahid)
((@thomsonreuters.com">Manya.Saini@thomsonreuters.com; X: manya__saini;))
Enjoyed the article Alex. I follow very closely the principles of Buffet / Munger / Lynch and Terry Smith (who’s mantra of buy good companies / don’t overpay / do nothing) seems very sensible to me!
You have to invest in a style that suits your personality. At the same time doing what is easy does not pay very well. Glamorous sexy shares that have glowing articles written each day are comfortable and easy to buy but have bad returns. A north sea diver earns a lot because he does a job few want.
This implies that you need to have an usual personaility to do well in the market. Which seems to be true. Buffett would be the first to admit he is an oddball who lives and breathes the market.
This is a strong argument for quantative rules based investing. Being forced to look at firms that no one likes is a good discipline. In short if you do what everyone else is doing you will get the returns that everybody else is getting.
Great article Alex. I have tried several different investing styles over the last 25 years including small-cap investing, value investing, and dividend growth investing but in recent years have settled on a quality/growth strategy.
In short, I like to find high-quality companies (wide moats, high ROCE, etc.) in growing industries that I can buy at reasonable valuations and hold for many years as they compound their earnings and get bigger. It’s quite similar to Buffett’s strategy but a little more growth focused.
Sorry - some links I meant to attach to last post highlighting some of Berkshire's impressive lending deals. This Reuters report is a quite a good example.
https://www.reuters.com/articl...
This article refers to the investment side of the Berkshire business but does not seem to recognise that Berkshire has made a lot of good deals as a lender.
During the financial crisis Berkshire did a number of deals which went very well. Often described as a lender of last resort ( arguable) they put together funding packages which give a good rate of return for a relatively low risk.
Worth a thought when trying to document the evolution of the business.
Great article thanks Alex!
Warren Buffet is an odd one. Huge survivor bias. They invested in 100's of companies and by their own admission only a dozen worked out. What really worked out was compounding over time, with huge gains in the last few years. Even Munger with characteristic humility said “If you remove just a few of Berkshire’s top decisions, its long-term track record is pretty average.”
On balance I have come to terms with investing as a scam. Not intentionally but with all the hindsight factors/backward looking reports/metrics - still no one can predict the future. And yet they over promise or stick a finger in the air and often under deliver. The numbers are backward looking / the future narratives are guesswork.
All us humans crave is control. And a big part of that is being able to predict the future. We do a rain dance and it rains. So we dance again.
Cause and effect get confused with correlation in a complex world. Information is soooo asymmetric; we cannot really know what regulation is around the corner, what embezzlements the FD is up to, who is planning to acquire who, who has the next killer app in the pipeline. Sadly we don't live in Back to the Future.
But enough gloom on the human condition. I'm doing ok. +22% two years straight. I have changed from tech momentum investing (with products I know/like and use; Spotify Technology SA (NYQ:SPOT) Duolingo (NSQ:DUOL) Alphabet (NSQ:GOOGL) to more of a mix including small caps. Sadly all too often momentum tends to end in hype and getting over your skiis... So I have a quality-reality check and try to run winners without being greedy.
It's interesting how simple parables and epigrams stand the test of time (obvs) ; Cashflow is king / turnover is vanity-profit is sanity (EBITDA is just funny). So I now tend to watch EPS upgrades, FCF yield , low debt, large moats and big runways. Small Caps are great at big runways if they have a moat. Sounds simple but it's noisy out there.
My tech guru is Paul Graham who's tech start up mantra is simply 'Make What People Want' which is beguiling in it's simplicity. (think Airbnb/Doordash/Coinbase/Stripe/Reddit)
People want cheap food Tesco (LON:TSCO) people want rare books delivered next day Amazon.com (NSQ:AMZN) Bezos said I think- no one ever said they want less choice at a higher price. So I look for flywheels where cashflow is reinvested in driving prices down with more choice. The old Nomad fund was big on this too; Scale Economic Shared (SES)..
I find stocko and factor investing really useful as a start point but everything ends up for me now as a special/unique situation. Think Ebay divesting Paypal. I'm watching Alphabet closely now (NSQ:GOOGL) anticipating an anti trust break up which would release huge value.
I also factor in ethics since every investment is a vote for the future. I find it amazing IG group (LON:IGG) type companies trade so well when by their own admission 75% of their customers lose money. Disappointing the majority of your customers most of the time is not my prefered business model no matter how profitable.
Finally I think you should write an article on the main much ignored factor; Luck. Most successful investors would say they have had a healthy dose of luck. Also having the resilience to deal with bad luck for long periods is key. In summary a great article Alex, lots to think about. Evolution of trading strategies is key, never stop learning. As Eric Hoffer said ;
“In times of change, learners inherit the earth, while the learned find themselves beautifully equipped to deal with a world that no longer exists.”
Hi,
That’s a great response. Thanks for taking the time to write it.
If you have not already read it, you may like The Quants, by Scott Patterson. He covers the themes you touch on, including the idea that we humans crave control in areas which are simply unpredictable. His argument is that the financial crisis of 2008-09 happened because we placed too much faith in financial models; we leveraged large parts of the economy on the basis that the financial models were scientific and their predictive power was ‘deterministic’ (i.e. for a given input, we get a given output).
My own take is that you have two domains: the deterministic-scientific domain, and the random-chaotic domain. In the deterministic-scientific domain, you have consistent laws that can be understood, predicted, and explained. In the random-chaotic domain, you have a situation where uncertainty, unpredictability, and complexity dominate. So you have two domains… and ‘wisdom’ is knowing where one domain begins and the other domain ends.
People like Nassim Taleb argue that the stock market belongs in the random-chaotic domain. He is arguably rallying against the ‘Homo Deus’ line-of-thinking, which implies that through technological advancement and scientific progress, humans are increasingly able to push deeper into the deterministic domain and tackle challenges that once seemed mystical, divine, or impossible (e.g. the challenge of immortality). If the past few years have taught us anything, it is the undeniable limits of our human abilities. We are Human Only, not Homo Deus (godlike).
At the same time, I would argue that the stock market is semi-deterministic. You do not have hard and fast ‘iron laws’, but you do get ‘rules of thumb’. Factor investing is a big part of this. On average, and over the longer-run, cheap stocks have outperformed expensive ones, etc… not always and not in every instance, but generally speaking it is better to align with that rule than to fight against it. Warren Buffett is a case in point…
A great paper called “Buffett’s Alpha” (Frazzini, Kabiller, Pedersen 2012) investigates how achieved his success. They argue that his performance can be explained quantitatively by his exposures to certain ‘factor premiums’. Buffett consistently tilted his portfolio toward:
• High-quality companies (profitable, stable, low-risk, with strong balance sheets).
• Low beta stocks (less volatile than the market).
• Value stocks (cheap relative to fundamentals).
https://www.tandfonline.com/doi/full/10.2469/faj.v74.n4.3
You also have Buffett’s essay, The Superinvestors of Graham-and-Doddsville. Buffett directly challenges the idea that his investment success (and that of others like him) is just luck, as the Efficient Market Hypothesis (EMH) might suggest. Instead, he argues that the success of value investors stems from a shared, repeatable method — not randomness; these investors are all aligned with a set of principles, including those taught by Benjamin Graham.
https://www.scribd.com/doc/236910578/The-Superinvestors-Of-Graham-and-Doddsville
Of course, Buffett was very lucky. He had opportunities others did not have, but at the same time… I don’t think his success can be explained simply by survivorship bias.
Keen for your thoughts.
Alex
At the same time, I would argue that the stock market is semi-deterministic. You do not have hard and fast ‘iron laws’, but you do get ‘rules of thumb’.
Aka heuristics.
The stock market is a complex adaptive system. The behaviour of participants impacts the behaviour of the market which in turns affects the behaviour of participants. Rather like the weather we can make reasonably accurate short-term predictions and discern longer term patterns - but this can be up-ended by major events (think volcanos and asteroid strikes) and affected by outbreaks of mass human stupidity from razing forests to dotcom crazes.
In the midst of all this humans are predictably irrational in multiple ways. We discern patterns where none exist and project temporary trends indefinitely into the future. You don't have to be particularly clever to have an edge, you just need some insight into these biases and lots of patience.
Factors work, on average, because they amplify the signal behind these behaviours and patterns and flatten out the noise. They're heuristics, not iron laws. That's why they don't work at the individual stock level.
As for Buffett - well, you can't invest like him without being him. Exceptional investors tend to have unusual personalities and psychological make-ups.
Of course, you can't really talk about Berkshire's success without acknowledging the importance of their insurance float or their diversification (over 60 wholly owned companies and up to 40 more market holdings). Always important to look at what people do, rather than what they say ...
timarr
Thanks Alex, I will check out the buffet links. On the macro - I think buffet was primarily lucky not being born a rural indian farmer in Andrah Pradesh with no electricity; but instead being born white middleclass, post great crash in 1930s america with a stockbroker father.. That's quite a genetic lottery he won.
Thanks for your thoughful response ; I'm still a little confused by things being semi deterministic and semi chaotic instead of either/or. Surely a 'rule of thumb' cherry picks the few successful outcomes and ignores the others?
To me the problem with decision making lies more in the homo economicus of the 'rational person' not really existing. Again Munger writes well on biases and bounded rationality (as do Kahneman & Tversky) - our worst enemy is ourselves. So I don't think the skill is in knowing where deterministic scientific method ends and where random chaos starts - but rather accepting they overlap. We are both rational and irrational most of the time. Or at least I am. I am just a bag of skin of contradictions.
Apparently you can win a Nobel prize in determinism (Black Scholes Options Pricing) and then watch in horror as LTCM fails. Then learn nothing and repeat the errors in 2008. There's money in determinism.
As an amateur I can admit to luck being a large part of my performance. In contrast maybe a pro trader/fund manager would have trouble admitting in a billion pound prospectus print that their strategy involved luck. But how refreshingly honest that would be :)
Hey, I guess human nature is complex and it doesn't fit into the either-or classification of, deterministic vs. chaotic. It's more of a continuous spectrum, less of a boolean choice between two, neat boxes. That's why I say the skill is in knowing where deterministic scientific method ends and knowing the limitations of models. Could someone use a financial model to build a portfolio? Yes. Should someone use a model to gamble life savings? No. So models have their usage, but they are just tools which have their time and place. The best analogy is Taleb's 'map vs territory' analogy. Maps have their uses, but don't confuse a map for the real thing.
Hey, I guess human nature is complex and it doesn't fit into the either-or classification of, deterministic vs. chaotic
Chaos theory is a branch of physics that explains how non-deterministic behaviour can arise from deterministic rules. Small differences in initial conditions can lead to vast differences in outcomes. Hence that bloody butterfly causing hurricanes ...
... but basically chaos theory and determinism aren't on a spectrum and aren't mutually exclusive. However, chaos theory does provide a framework for understanding complex adaptive systems such as the weather, the human brain ... and the stockmarket.
timarr
I'm shifting more towards quality/growth at reasonable price. Occasionally I will dabble in contrarian plays, like oil when it was $40 per barrel. I still have a holding in the bank STAN, for example. Banks are crummy businesses, but if you buy at the right time you can do well.
I think Intelligent Investor can actually be damaging, as it makes you focus on cheapness rather than quality. You end up buying a lot of stuff that goes nowhere, or even down.
You can also end up buying a lot of frauds. Chinese frauds for example, although the market has mostly flushed them out. Quindell would have been another one (remember them?). Cheap, sure, but there were problems with them.
There aren't really any what I call obscure companies listed on the LSE. Eyeballs run over all of them. As Whitney Tilson once said, if you think you've found a bargain then there's a 90% chance you are wrong.
Value investing is a style that works for a spell, stops working, and starts working again. You think you've found the magic formula, become religious about it, but then find your returns aren't so spectacular.
In some respects, I don't think finding quality companies is impossibly hard. Stocko's Quality score is a reasonable place to start looking, but I wouldn't be too religious about it. Listening to portfolio managers talk about their holdings is useful, too. Sometimes they'll say something that just clicks and you realise they're onto something. Something like they have a niche, or a tough market has lowered their profits but they've gained share. Or it is apparent they have network effects. Something like that.I don't claim to have any special insight into businesses, but you do get a general feel for what's likely to be good.
I'd say, too, look for a company that has doubled its EPS over 10 years and has an interest cover of at least 7. Don't buy the shares when they are too expensive. Look for a forward PE of at most 18, for example.
To give an example, Pets at Home (LON:PETS) is a company that I picked up late last year. Everyone was worried about the CMA investigation. But, well, it seems to have economies of scale, so should do OK. And no-one is going to stop feeding their dogs, are they?
I think the thing is you're not trying to get too clever here. I have in the past overanalysed the numbers. Looking at the numbers is good, but you also have to ask yourself the question "do I think this is a good company that has room to grow?"
You have to be prepared to make mistakes, which is why I think diversification is important (I'm with Ed here!). I think there are many good companies on the LSE, and you never really know what the best 10 will be, so I am happy with people looking for a well-diversified portfolio. It also increases your chance of finding a stock that goes to the moon, the one that makes up for all the other duds and then some.
I also think calling Buffett a "value investor" is a little misleading. More specifically, he was a special situations investor. It's a subtle difference but accounts as to why Buffett was able to compound at 20% as opposed to a couple of percentage points over the index.
I morphed from value and income to value and momentum. Much better now!!
That`s a great article Alex, thank you. It`s a sobering thought that even the `Gods` of investing have learnt to bend with the wind, over time. As a relative newbie to investing, and having dabbled in Shares in the past, my current philosophy is to favour Companies that display the characteristics of a) Momentum and b) Quality. My thoughts are that if the `Value` aspect is marked down low on Stockopedia, then the Momentum (which is already embedded into the price and is already present), will set it on its way - after all other considerations have been appraised and factored in, of course. Well, that`s the theory, anyway.
Time has already told me not to be too `kneejerk` and sell straight away if my Share price falls, and to give it time to recover. I now always set my Stop Loss as soon as I purchase, in case I forget to set one later. By setting a Stop Loss, does that mean I`m happy to lose `X`%? Certainly not. And I always have the option to manually sell if bad news strikes soon after my investment.
I`ve created a Stocko Folio named `Sold`, and when I look back at some of the Companies I sold . . . . guess what? A good proportion are doing fine now, having recovered over a relatively short period of time.
I used to work for a large Japanese corporate. Golf Days at a very prestigious UK course were always popular with our clients, and I used to host one of the four-balls. Amongst my clients were some exceptionally good golfers, and on the first tee, they would tell me how nervous they were, and how they didn`t want to show themselves up. I used to try and relax them, and I would say something along the lines of `Don`t worry about it. If any the guests here today were that good, they`d be full-time out on the Tour . . . just relax and enjoy yourself`. It seemed to work a traet.
I guess that sums up investing. I don`t beat myself up if it doesn`t go to plan. I`m not a City trader with all their tools (not that they get it right, even most of the time). It doesn`t mean that I don`t get upset if all my time & research falls flat on it face. I try and keep it all in context. As long as I can still feed the cat, it`ll all be ok.
And If my predictions go terribly wrong? Hey, there`s always the `Sell` button.
Oh, and I would need to buy a cat.