The Week Ahead (10-14 Nov): Budget uncertainty, VOD, BME, QQ

The Bank of England left its main interest rate unchanged at 4% this week, but it was a finely-balanced decision – the Bank’s Monetary Policy Committee voted 5-4 in favour of a rate freeze, with four members supporting a cut to 3.75%.
Arguably, this makes a rate cut in December more likely, assuming the Bank’s view that inflation has peaked proves correct.
Interestingly, two members of the MPC already believe that monetary policy [interest rates] are “significantly over-restrictive”. In their view, this has the potential to “unduly damage [economic] activity and possibly lead to an undershoot in inflation in the medium term”.
A post-2003 chart of interest rates suggests that the current rate is in a relatively normal range, with plenty of room to move lower if needed:
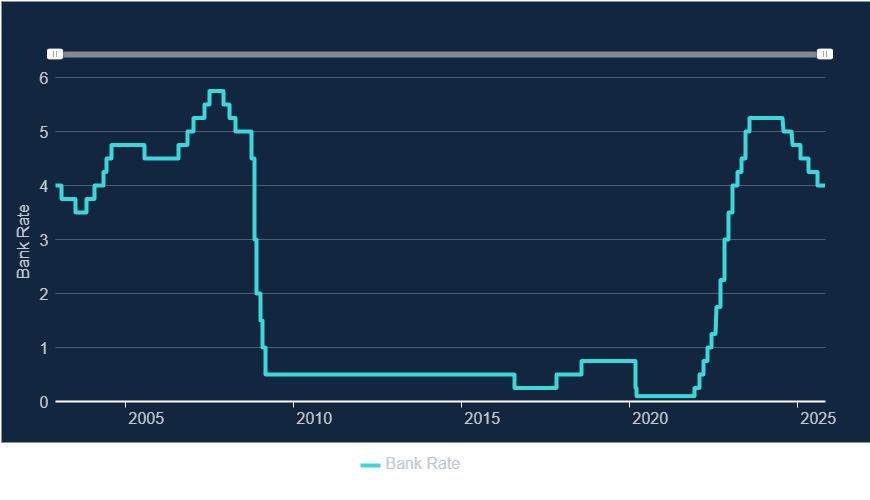
Source: Bank of England
However, this chart from the Office for National Statistics (ONS) suggests that weakening inflation isn’t yet making its way through to the official stats, except in relation to home ownership:
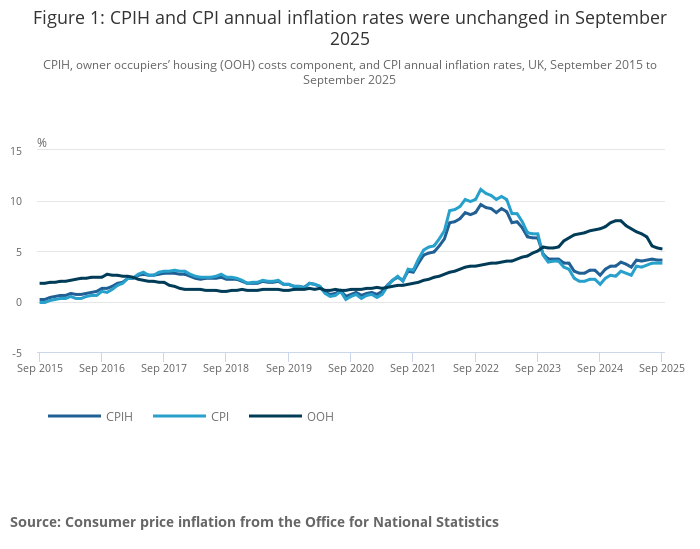
We’ll have to see if inflation data for October and November support the view of some MPC members that inflation is weakening.
My impression is that managing interest rates and inflation is as much art as science, but I am inclined to think that a rate cut is increasingly likely once the uncertainty attached to November’s Budget has passed.
Looking ahead, I suspect that UK economic data published over the next couple of weeks – including GDP – is likely to continue being overshadowed by speculation and leaks about the content of the Budget.
Debate has continued this week over whether the Government will break its election pledge not to raise Income Tax, or find other ways to control inflation while supporting the economy. Measures rumoured in the press this week have included per-mile charges for electric cars and the removal of VAT from utility bills.
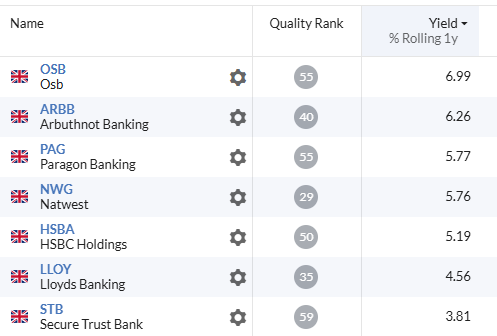
Fortunately for investors, the big UK banks are expected to avoid any additional profit levies. That should help to support the generous dividends on offer from several of these lenders:
Not all companies are expecting to escape scot-free from the Budget, while some are already suffering due to consumer uncertainty. In the DSMR this week, we’ve seen companies including J D Wetherspoon (LON:JDW), J Sainsbury (LON:SBRY) and housebuilder Barratt Redrow (LON:BTRW) warn that Budget changes – and consumer caution in the run-up – could impact this year’s results.
ITV (LON:ITV) went further, guiding investors to expect a 9% drop in fourth-quarter advertising spend due to “consumer and corporate” uncertainty in the run-up to the Budget.
UK company news
Vodafone (LON:VOD)
For many years, FTSE 100 telecoms giant Vodafone was rightly seen as a destroyer of shareholder value, thanks to its sluggish growth and dire profitability metrics. But things seem to be turning around under CEO Margherita Della Valle.
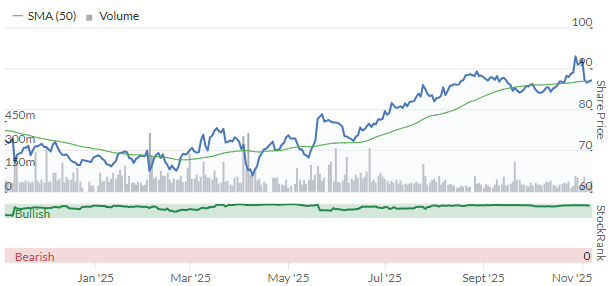
In May I highlighted the unlikely Super Stock status of both BT and Vodafone. I’m happy to see that Vodafone retains that styling today and has performed well so far this year:
Ms Della Valle’s achievements have included the sale of the group’s Italy and Spain businesses, but perhaps her biggest success has been the merger of the Vodafone and Three networks in the UK.
The deal was completed in June and has reduced the number of physical mobile networks in the UK from four to three. Consolidating the market in this way had previously been seen as unpalatable by UK regulators on competition grounds. However, Vodafone appears to have persuaded the CMA that the low returns on capital being generated across the sector could imperil further investment unless something changed.
There’s not yet much concrete evidence that Vodafone’s profitability is improving. Last year’s return on capital employed of 4.4% is still far too low to cover the group’s cost of capital. But I’m hopeful that the impact of the changes made over the last few years will soon start to trickle through.
I’m also keen to see if Vodafone can engineer a return to growth in its largest market, Germany, where the company is a big player in broadband as well as mobile. Achieving a turnaround in Europe’s largest economy is Ms Della Valle’s stated priority this year.
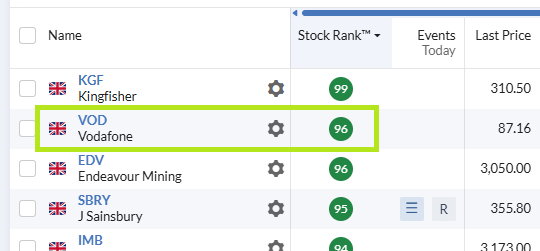
Vodafone is currently the second-highest ranked stock in the FTSE 100 – will this position be maintained following Tuesday’s results?
B&M European Value Retail SA (LON:BME)
Value retailer B&M had already suffered a string of profit downgrades this year. But things took a turn for the worse in October when new CEO Tjeerd Jegen revealed a £7m accounting error and slashed profit guidance again.
Weak trading is never good news, but accounting problems are a more serious concern for me, as they hint at possible management failings.
When I reviewed this update in the DSMR on 20 October, I took the precaution of adopting a RED view on the stock. One reason for this was that I couldn’t quite make the numbers add up in the company’s revised guidance.
This particular accounting error is blamed on a system change, but it was still seen as serious enough to warrant the departure of the CFO and an external investigation.
It’s also worth remembering this profit warning came just two weeks after a previous profit warning, when Mr Jegen highlighted various operational failings he’d identified in his initial review of the business. Amazingly, these issues included an emphasis on store presentation which “prioritised the look of a full shelf over actual stock availability”.
Viewed as a whole, these problems give me the impression that this previously well-run business has gone downhill since former co-owner and CEO Simon Arora stepped down in 2022.
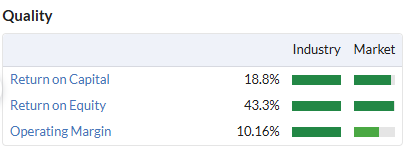
The new CEO is highly experienced in value retail and I remain confident a turnaround should be possible. Quality metrics were previously formidable and remain tempting to me, especially as this business has paid very generous dividends in the past.
However, I expect to see a sharp fall in profitability as the downgraded FY26 results make their way into the stats:
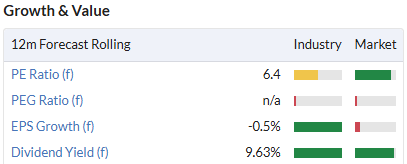
While the 9% yield seems tempting and is covered by forecast earnings, B&M’s rising leverage and falling profits suggest to me that a dividend cut might also be needed to help repair the balance sheet.
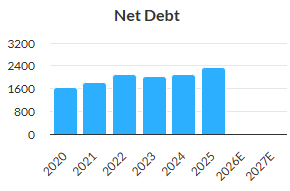
The Contrarian styling here could be highlighting a potential buying opportunity. But B&M’s MomentumRank of zero is relatively unusual and suggests to me that the tide has not yet started to turn.
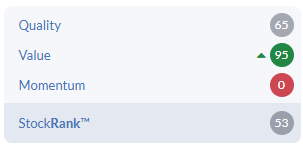
Next week’s interim results will hopefully shed more light on the company’s accounting problems. I’ll certainly be watching with interest in the hope that we’ll be able to moderate our view on this former strong performer.
Qinetiq (LON:QQ.)
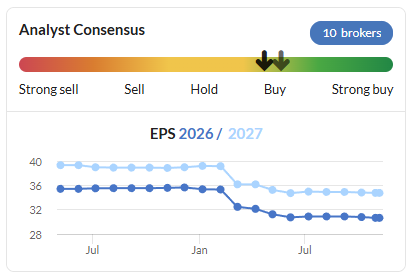
Many defence stocks have been big winners this year, but FTSE 250 group Qinetiq has bucked the trend, suffering problems in the US and multiple earnings downgrades:
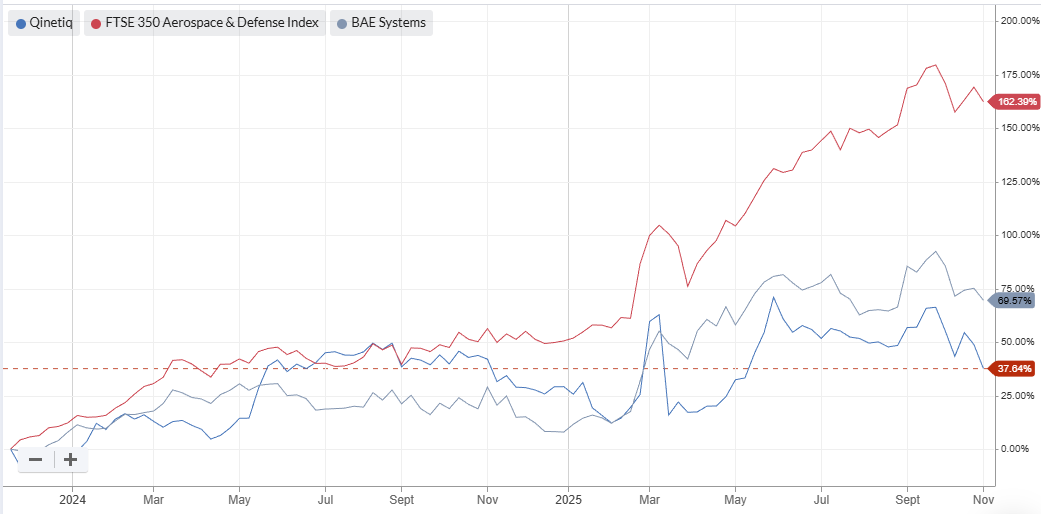
As a result, the shares have significantly underperformed the FTSE 350 Aerospace & Defense Index and its FTSE 100 peer, BAE Systems:
This week’s interim results will provide the first update from the firm since July, when management said trading was in line with (revised) expectations.
If this outlook is maintained, I think the stock’s valuation could start to look quite reasonable for a defence business in the current market:
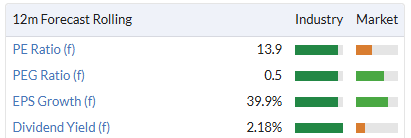
However, the low StockRank and Neutral styling mean that I’m not tempted to try and front run this week's numbers:
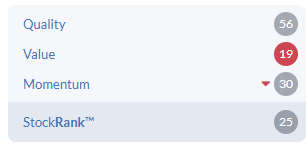
In fairness, Qinetiq’s reported losses in FY25 have probably depressed the StockRank. These were due to impairment and restructuring charges that were mostly related to the group’s legacy US operations.
If the H1 26 accounts are cleaner and free of any further large adjustments, then I’d expect the StockRank to improve somewhat once the algorithms have digested the fresh accounts. One to watch on Thursday, perhaps.
Here’s a summary of what’s expected next week - in the meantime, I hope you enjoy the weekend.
Economic Calendar
Date / Time (BST) | Country | Event |
10 November | - | - |
11 November | ||
07:00 | UK | Unemployment |
10:00 | Germany/EU | Economic Sentiment Index |
13:15 | US | ADP Employment (weekly payroll change) |
12 November | ||
07:00 | Germany | CPI |
21:30 | US | API Crude Oil stocks |
13 November | ||
00:01 | UK | RICS House Price Survey |
07:00 | UK | GDP |
13:30 | US | Inflation |
13:30 | US | Initial Jobless Claims |
17:00 | US | EIA Crude Oil stocks |
14 November | ||
02:00 | China | Industrial Production |
13:30 | US | Retail Sales |
Companies Reporting
Date | UK Trading Updates and AGMS | UK Financial Results | International Financial Results |
Monday 10 Nov | Caledonia Mining (LON:CMCL) Alternative Income REIT (LON:AIRE) | Applied Nutrition (LON:APN) Kainos (LON:KNOS) | CoreWeave (NSQ:CRWV) Occidental Petroleum (NYQ:OXY) Tyson Foods (NYQ:TSN) |
Tuesday 11 Nov | GSTechnologies (LON:GST) Made Tech (LON:MTEC) Rainbow Rare Earths (LON:RBW) Thor Energy (LON:THR) | Ab Dynamics (LON:ABDP) Abingdon Health (LON:ABDX) Oxford Instruments (LON:OXIG) Shearwater (LON:SWG) Vodafone (LON:VOD) | SoftBank (PNK:SFTBY) Anglogold Ashanti (NYQ:AU) |
Wednesday 12 Nov | Flutter Entertainment (LON:FLTR) Marshalls (LON:MSLH) Mothercare (LON:MTC) Taylor Wimpey (LON:TW.) | Avon Technologies (LON:AVON) Castings (LON:CGS) Experian (LON:EXPN) Fuller Smith & Turner (LON:FSTA) Motorpoint (LON:MOTR) SSE (LON:SSE) Ten Lifestyle (LON:TENG) Volex (LON:VLX) | Cisco Systems (NSQ:CSCO) Manulife Financial (NYQ:MFC) |
Thursday 13 Nov | Alfa Financial Software Holdings (LON:ALFA) Atalaya Mining Copper SA (LON:ATYM) Aviva (LON:AV.) ConvaTec (LON:CTEC) Endeavour Mining (LON:EDV) Fonix (LON:FNX) Galliford Try Holdings (LON:GFRD) Greatland Resources (LON:GGP) Kier (LON:KIE) | B&M European Value Retail SA (LON:BME) Burberry (LON:BRBY) 3i (LON:III) Marks Electrical (LON:MRK) Premier Foods (LON:PFD) Qinetiq (LON:QQ.) United Utilities (LON:UU.) | Tencent Holdings (PNK:TCEHY) Alibaba Holding (NYQ:BABA) Siemens AG (ETR:SIE) Walt Disney Co (NYQ:DIS) Palo Alto Networks (NSQ:PANW) Brookfield (NYQ:BN) JD.Com (NSQ:JD) |
Friday 14 Nov | DFS Furniture (LON:DFS) Ferro-Alloy Resources (LON:FAR) MJ GLEESON (LON:GLE) | Land Securities (LON:LAND) | Ubiquiti (NYQ:UI) |
Disclosure: Roland owned shares in ITV at the time of publication.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
There are a few companies reporting this week with a construction theme, Marshalls, Taylor Wimpey, Galliford Try and MJ Gleeson.
The S&P Global UK Construction PMI® report for October ( released 6/11/2025) suggests that it might be too soon for a turnaround in the sector, although it does report lower cost inflation..
https://www.pmi.spglobal.com/P...
I think a few of you are coming to Mello in London in 10 days time. Some very good companies will be there and we have 16 with very high Stockopedia rankings. There are eight with scores above 90
Time Finance 91
Personal Group 92
B.P. Marsh 92
Gattaca 97
Staffline 98
Seraphim Space 98
Orchard Funding 99
Serabi Gold 99
Lots of cracking keynotes including all the Stockopedia favourites....Ed, Graham and Mark and six panels with two BASH sessions too. Do give MelloLondon a try. It is two days full of investor engagement and we have entertainment on the middle evening and our own MelloBar for socialising and networking...
Https://www.melloevents.com/mellolondon2025
Monday 5pm is the latest time that Blackstone (or its Funds) needs to declare its hand over Big Yellow (LON:BYG).
I hold it and Safestore Holdings (LON:SAFE) , which has also risen as a result of the speculation. Not out of the question that either could be of interest, now that LOK has been taken out. Big and boring Businesses, immune from the AI froth.
Read this column every week, always enjoy it and always learn something so thanks for continuing with it.
Hope the Aviva (LON:AV.) trading update on Thursday includes something on the integration of Direct Line. Something along the lines of lots of additional revenues and lots of cost efficiencies. Both the CEO and the CFO are high quality people in my opinion.
The following is a good interview with the CEO, Amanda Blanc. Very little mention of the Direct Line acquisition as that may break market rules.
https://tinyurl.com/h4xuhaje
On the subject of the upcoming budget and the probable reduction in spending happening right now in the UK high street, I couldn't help myself.... if the following is true then it's pure madness but nothing surprises me about the over-reaching British state machine, regardless of which political party is in government.
https://tinyurl.com/dm6hxsh5
Did enjoy the planning video Shoeshine £250 mil on paperwork alone no wonder where bankrupt x 10.
As one who does all the food shopping and used to eat out all the time, things ain't getting any better, bills still getting higher even if most items bought are from Lidl! £25 for a takeaway fish & chips now although I've managed to reduce our energy bills significantly with a new boiler and smart meter. It's tough out there for the ordinary Joe
The killer in my opinion for the UK weekly shop recently has been dropping the employer ni threshold from 9k to 5k given supermarkets run on part timers. I think it was BnB that highlighted this stroke alone made everyone earning more than 5k per annum £625 pa more expensive to employ before you added on min wage and pension increases.
In a business like food retail working on average 3-5% margins they were never going to be able to swallow that.
I am under the impression that Brookfield (NYQ:BN) have announced their results today.
All the best
Hi yiannos1,
I think it's BROOKFIELD ASSET MANAGEMENT (NYQ:BAM) that is announcing Q3 results today.
According to its IR website, Brookfield (NYQ:BN) Q3 results are scheduled for 13 Nov.
All the best,
Roland
You are absolutely correct!
All the best
Anecdotal evidence from local retail outlets, including pubs and restaurants, is that customers are increasingly reluctant to spend. In part this seems a reflection of the perceived cost of living (many people I meet refer to it being well above the ONS published inflation rates) and a ‘hold’ whilst they await the Budget which is expected to hit their pockets. The more elderly cohort (I’m 71 so many of my contacts are pensioners) are increasingly mindful of what they will be passing to their children when the Grim Reaper arrives. Some of them will reduce future spending, to pay for any tax rises, so as to, in their minds, retain the value of inheritances.
Agree.I used to head out with a friend once or twice a month for a meal (shes a teacher) . We agreed to cook for each other or go to cinema ongoing (she gets a great deal on cinema tickets) as the cost of eating out in London now is so high .