The Week Ahead (17 – 21 Nov): Mello, US Housing, UK Inflation, NVDA, US Value Retail, LIO, CML, MTO

Mello
The Stockopedia content team will be attending this investing conference next week on 18 and 19 November. The full schedule has now been released. Ed will be doing a talk on Wednesday at 15:25, and I will be doing one at 16:45 on the Tuesday. Do come and say hi if any subscribers are planning on being there too.
Markets
After a reasonable start to the week, it has been a weak end for the major indices. Hawkish commentary from the US Fed has dampened expectations for an interest rate cut in December. Only three stocks in the FTSE100 were blue this morning, with the banks particularly badly hit:
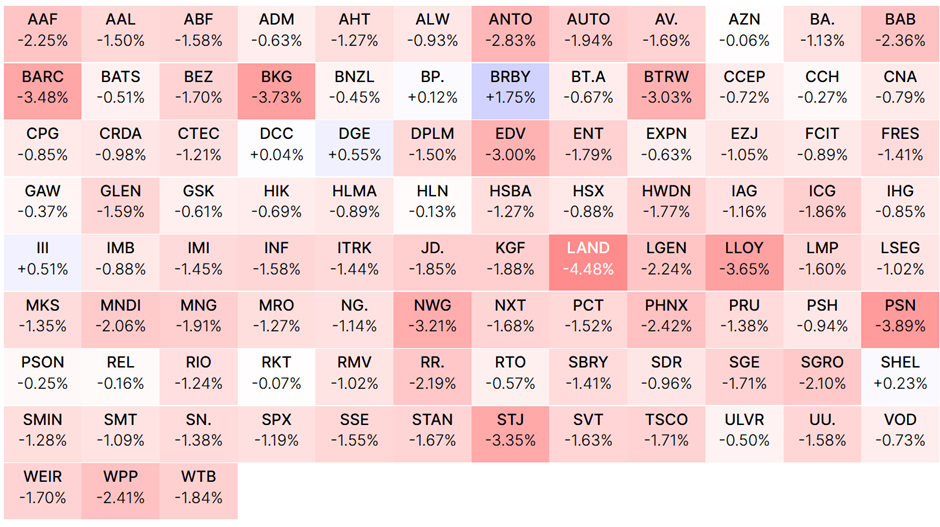
[Heat map: Hargreaves Landsdowne]
Here's what we can look forward to next week:
Economic Calendar
Monday 17 Nov |
||
Tuesday 18 Nov |
||
21:30 |
United States |
API Crude Stocks |
23:50 |
Japan |
Balance of Trade |
Wednesday 19 Nov |
||
07:00 |
UK |
Inflation Rate |
13:30 |
United States |
Housing Starts Building Permits |
19:00 |
United States |
FOMC Minutes |
Thursday 20 Nov |
||
08:00 |
Euro Area |
ECB General Council Meeting |
15:00 |
United States |
Existing Home Sales |
23:30 |
Japan |
Inflation Rate |
Friday 21 Nov |
||
07:00 |
UK |
Retail Sales |
09:30 |
UK |
Purchasing Managers Index |
14:45 |
United States |
Purchasing Managers Index |
US Housing
Housing will be a key focus in the US, with forward-looking indicators of Building Permits and Housing Starts being reported on Wednesday and Existing Home Sales on Thursday.
The most forward-looking of the indicators, Building Permits, were weak in August and came in slightly below consensus:
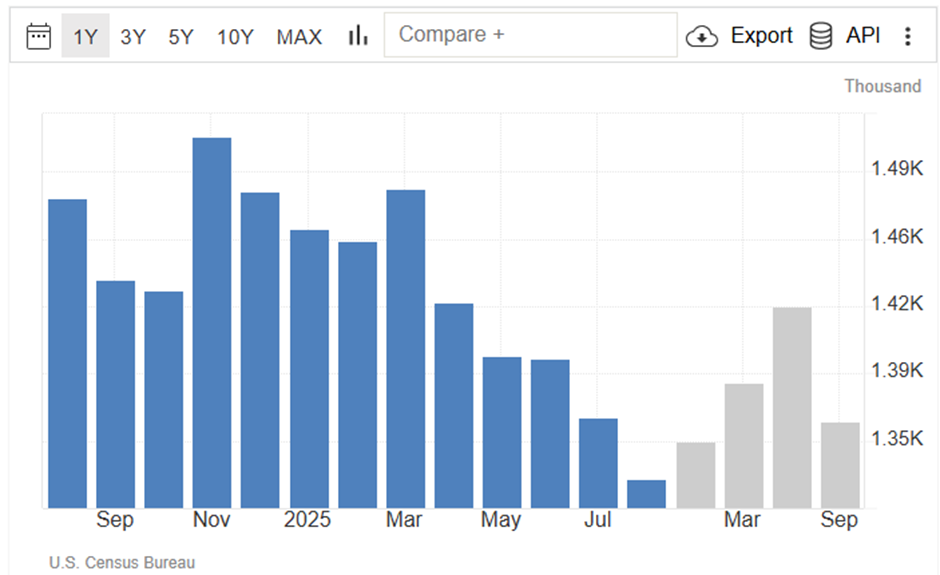
[All charts in this section: Trading Economics]
Forecasts are for this to be flat when September's figures are released next week, but pick up towards the end of the year. Another miss may indicate underlying weakness in the US economy. It is a very similar, but noisier picture for Housing Starts:
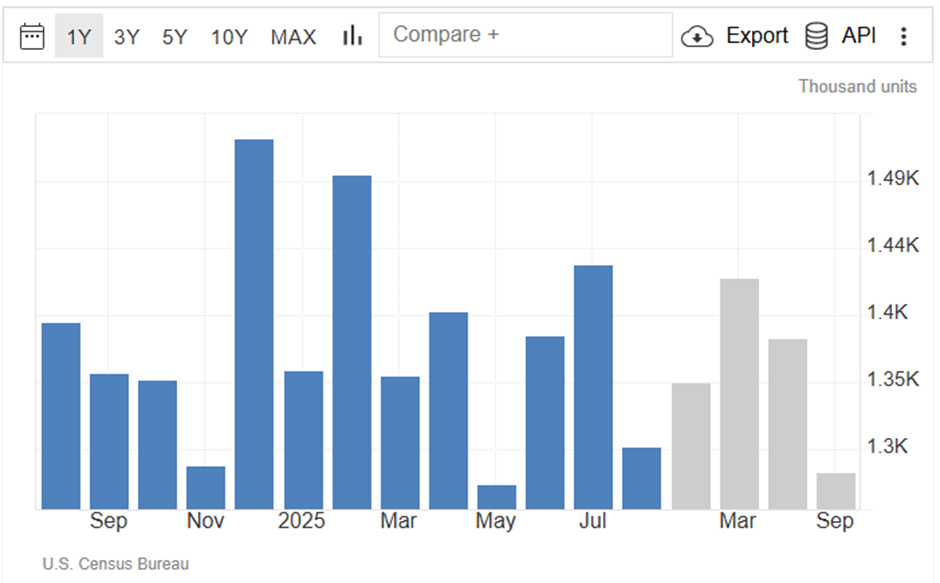
It is a slightly cheerier picture for Existing Home Sales:
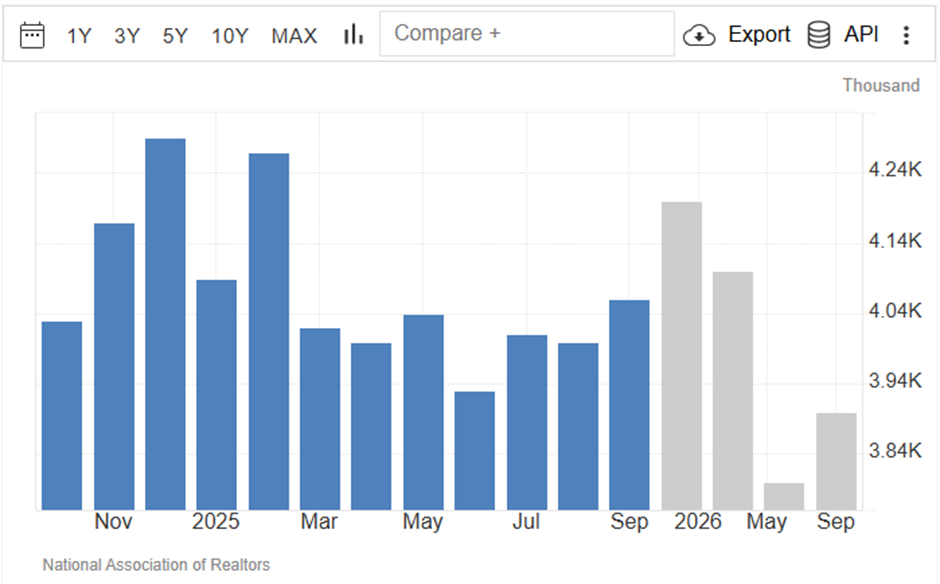
Although figures around the current levels are largely supportive, rather than bullish for US house prices.
UK Inflation
In the UK, Inflation will be the key print next week. It has remained stubbornly above the Bank of England's 2% target rate, although it came in below consensus in October:
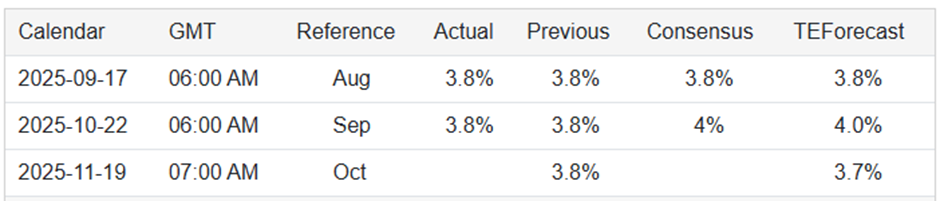
Avoiding the headline of negative real interest rates (where the Bank's headline rate is lower than inflation) is thought by many to be why the Bank ultimately held interest rates at 4% in the last rate decision meeting:
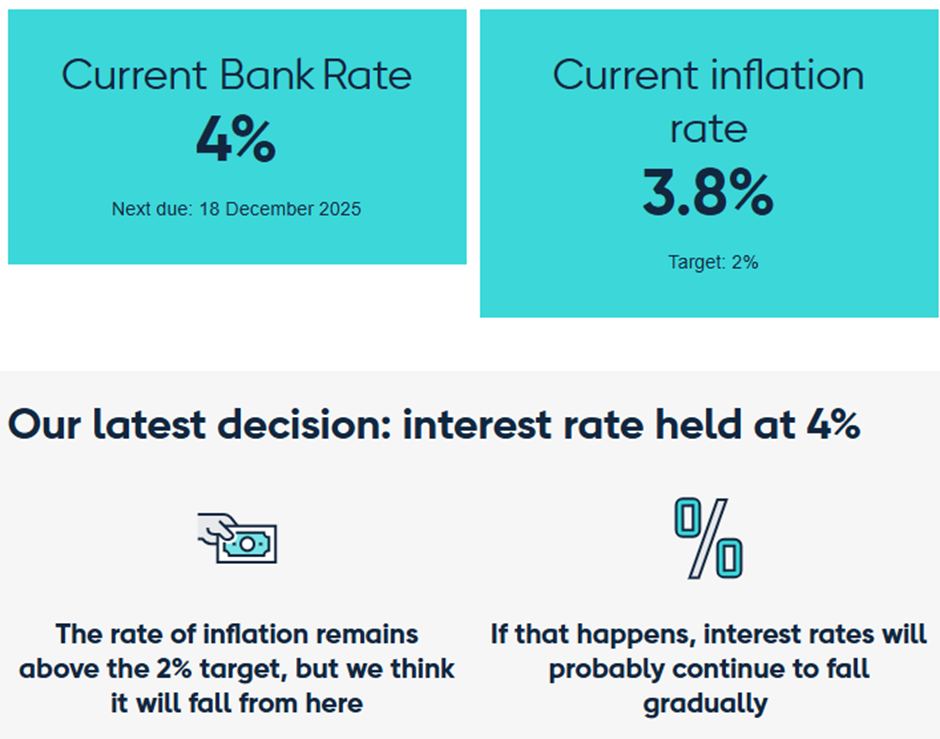
It was a tight run thing with four members choosing to eschew the optics and vote for a cut. Thier reasoning was that:
Disinflation had become better established, and current and prospective slack should allow underlying inflation to return to target-consistent rates. These members attached a greater weight to downside risks, given that these would reflect a continuation of current trends, with particular concerns that household saving would remain elevated and weigh on consumption.
Core inflation has also just started to come in below consensus:
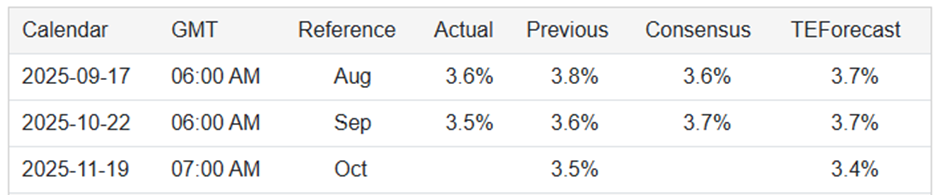
This means that forecasts for inflation moderating towards the 2% target over the next year are starting to look credible:
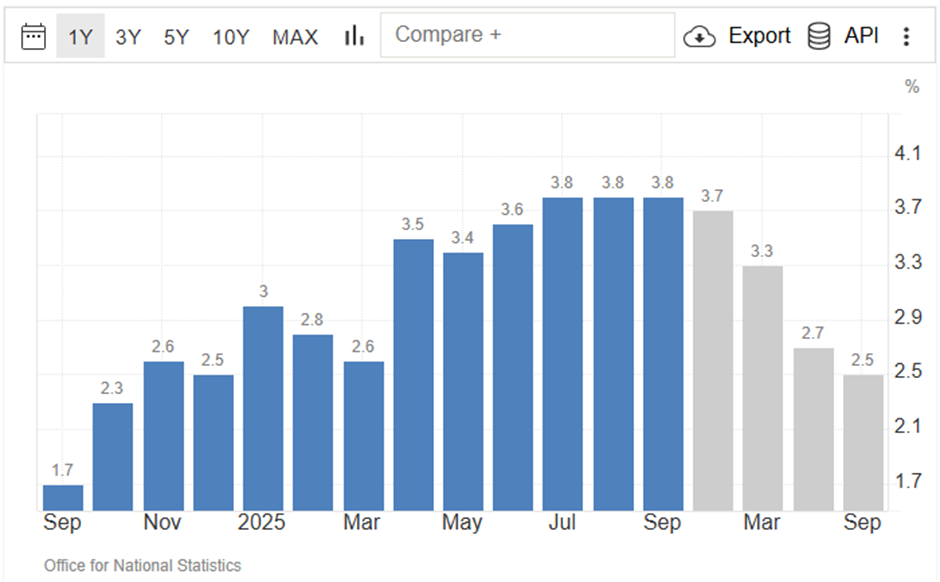
The current forecast is for the BoE to follow through with that 25bps cut on 18 December. However, next week's inflation print may have an outsized effect on the Monetary Policy Committee's willingness to follow through on that.
Companies Reporting
UK Trading Updates |
UK Financial Results |
International Financial Results |
|
Monday 17 Nov |
Rosslyn Data (AGM) |
Sirius Real Estate (Interims) Big Yellow (Interims) J Cropper (Interims) |
|
Tuesday 18 Nov |
Calnex (Interims) CML Microsystems (Interims) Diploma (Finals) Firstgroup (Interims) Gear4music Greencore (Finals) Imperial Brands (Finals) Trifast (Interims) |
AECOM (Q4) Home Depot (Q3) Medtronic (Q2) |
|
Wednesday 19 Nov |
Dunelm (AGM) Genus (AGM) Hays (AGM) Smiths Group (AGM) Sovereign Metals (AGM) |
British Land (Interims) Manolete Partners (Interims) Sage (Finals) Severn Trent (Interims) Zoo Digital (Interims) |
Deere & Co (Q4) Nvidia (Q3) Target (Q3) TJX Companies (Q3) Lowes Companies (Q3) Palo Alto Networks (Q1) |
Thursday 20 Nov |
Close Bros (AGM) JD Sports (TS) McBride (AGM) Mosman Oil & Gas (AGM) Origin (AGM) Pan African Resources (AGM) Pz Cussons (AGM) FW Thorpe (AGM) Wetherspoons (AGM) |
Babcock (Interims) Grainger plc (Finals) Halma (Interims) Investec (Interims) Johnson Matthey (Interims) Liontrust Asset Management (Interims) LondonMetric (Interims) Mitie (Interims) Norcros (Interims) Tracsis (Finals) Xps Pensions (Interims) |
Walmart (Q3) Intuit (Q1) Ross Stores (Q3) Veeva Systems (Q3) Jacobs Solutions (Q4) |
Friday 21 Nov |
Craneware (AGM) Celtic (AGM) Provexis (AGM) |
PDD Holdings (Q3) |
Quarterly reporting in the US has quietened down by now, but UK reporting is picking up steam for companies reporting results to 30th September.
If any investors think I've missed some upcoming news or included a red herring, then feel free to correct this in the comments.
NVIDIA (NSQ:NVDA)
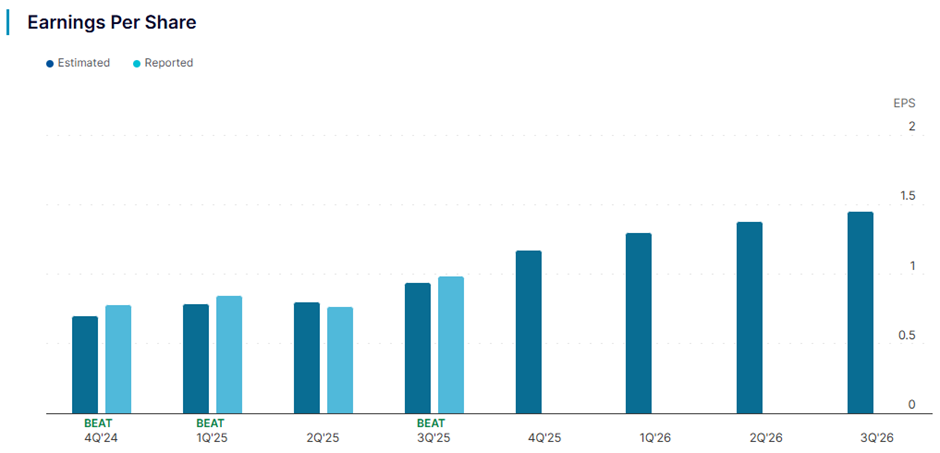
When I previewed Q3 results in August, I noted that Q2 had missed expectations and the Momentum Rank had waned somewhat. However, with those Q3 results, the largest listed company in the world was back to winning ways:
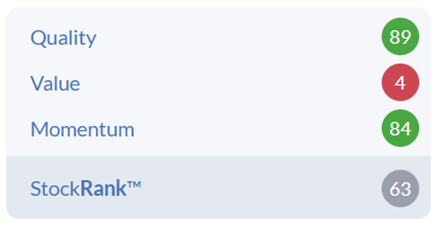
While this was always going to be a High Flyer, given the historical value metrics, the StockRank is looking better going into Q4 results:
That valuation actually looks reasonable (for US tech) on a forward basis. Especially given the forecast EPS growth rates:

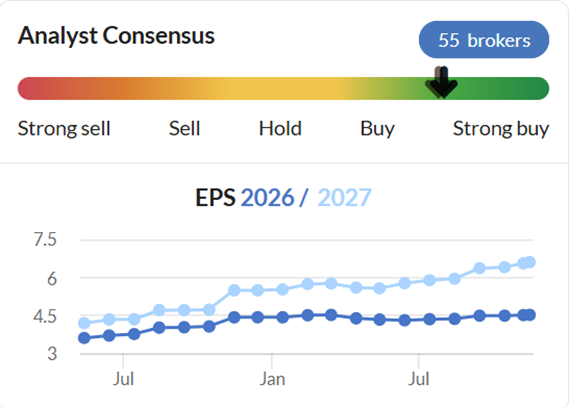
Despite some concerns over the sustainability and payback on the significant AI investments being made, FY27 forecasts have been continuously upgraded:
Some caution is required, as AI can't be both a boon for companies that provide the computing hardware, such as Nvidia, and for those spending big on capex to deliver AI functionality. This is especially true if users are not willing to pay any more for AI-based solutions. However, so far, the signs point to Nvidia winning this battle. Investors will be looking for a further beat in Q4 to show they remain on track with this phenomenal transformation.
US Value Retail
Next week appears to be the time when US value retailers report, with Target (NYQ:TGT) , TJX Companies (NYQ:TJX) (owner of TK Maxx in the UK), Walmart (NYQ:WMT) , and Ross Stores (NSQ:ROST) all reporting then. The Quality Ranks considers all of these high-quality businesses:
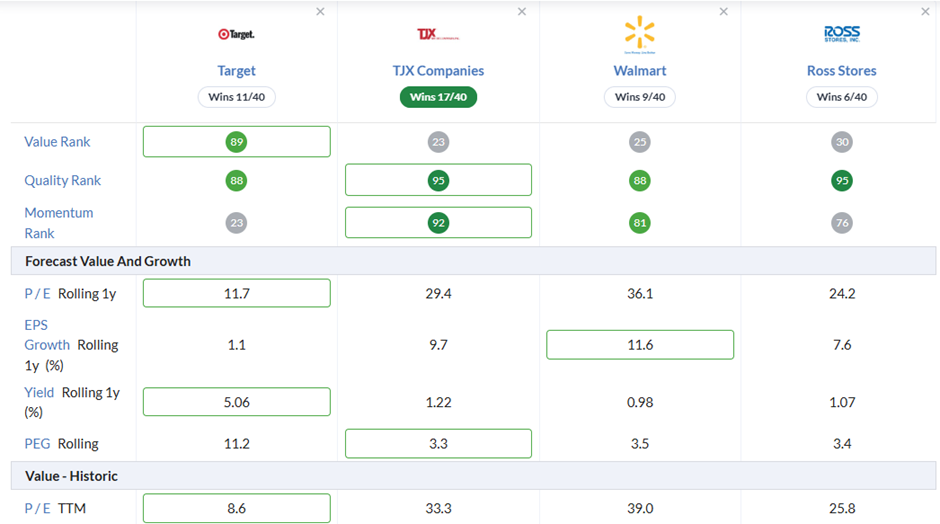
However, there is quite a difference between the Value and Momentum Ranks. Walmart is classified as a High Flyer, but the consensus trend isn't particularly exciting:
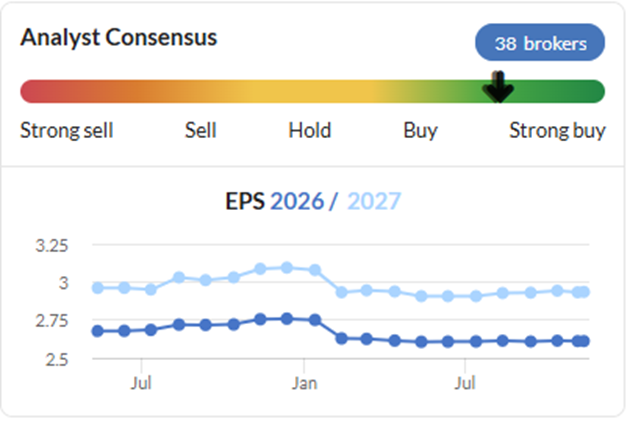
Their Q3 results missed expectations for the first time in a while.:
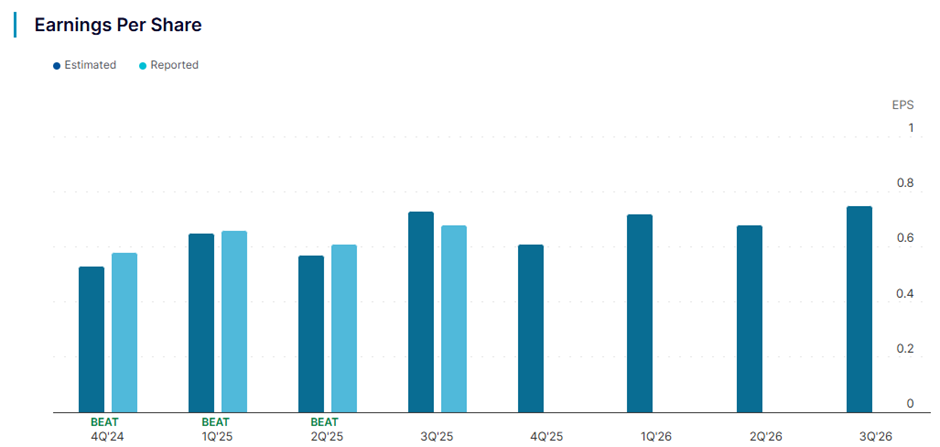
This miss doesn't seem to have caused a significant sell-off, and Q4 results are forecast to be down. However, on 36x forecast earnings, this would seem to have a long way to fall if it moves from a High Flyer to a Falling Star.
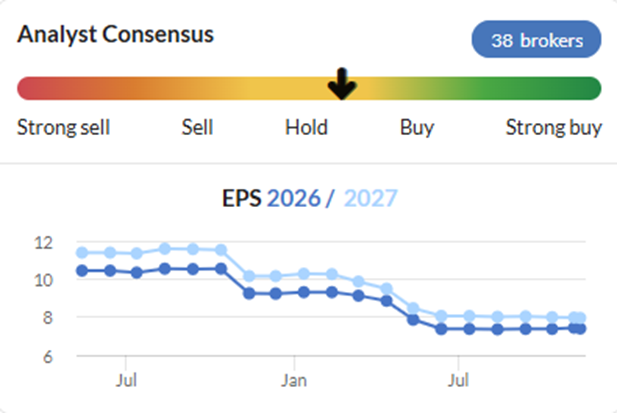
Target is the contrarian pick on a low (for the US) forward P/E of 12. The brokers' trend has been negative:
And the historical quarterly performance against expectations has been mixed:
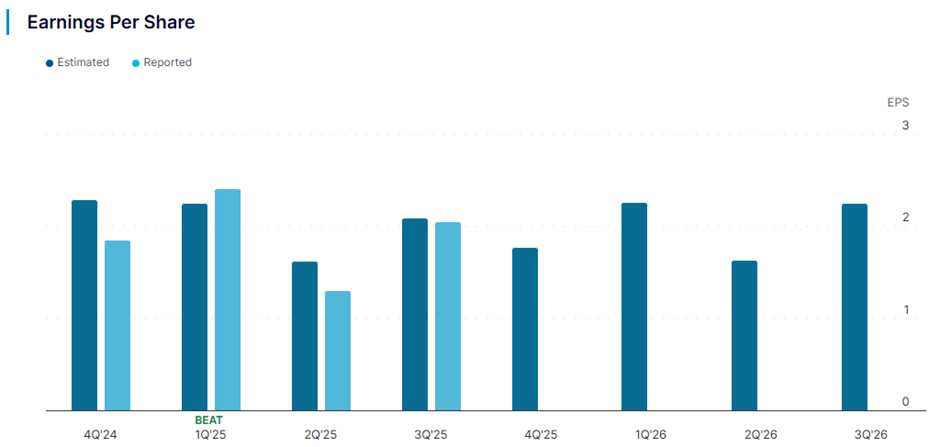
Walmart has a core grocery business that is consistently profitable, with additional lines boosting sales. Whereas Target only sells apparel, home décor, seasonal and electronics. Target is also positioned as "affordable style", a mid-tier aspirational brand that loses appeal when budgets are tight. However, Q3 was broadly in line with expectations and the consensus has not been reduced since the Summer, so if Q4 comes in line, this could mark the bottom for corporate performance (and the stock price).
UK Shares
Liontrust Asset Management (LON:LIO)
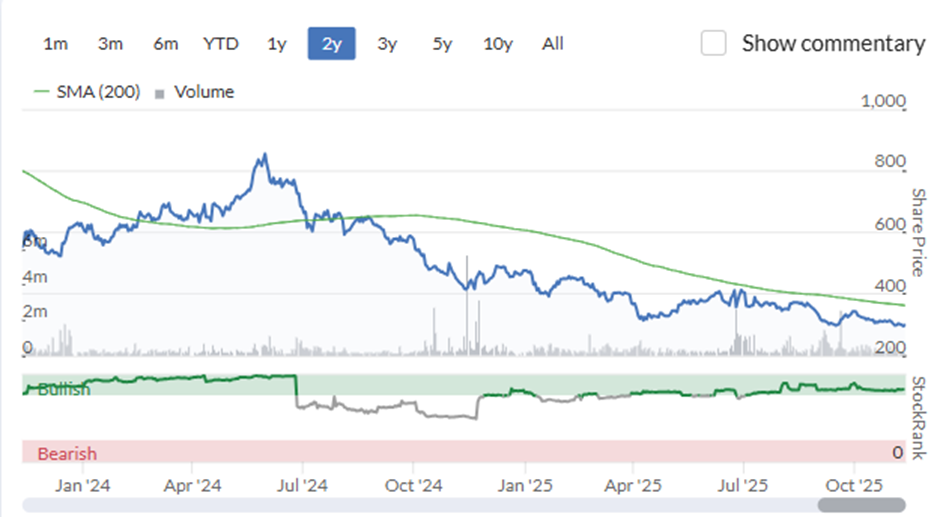
Like many asset managers, Liontrust continues its march downwards:
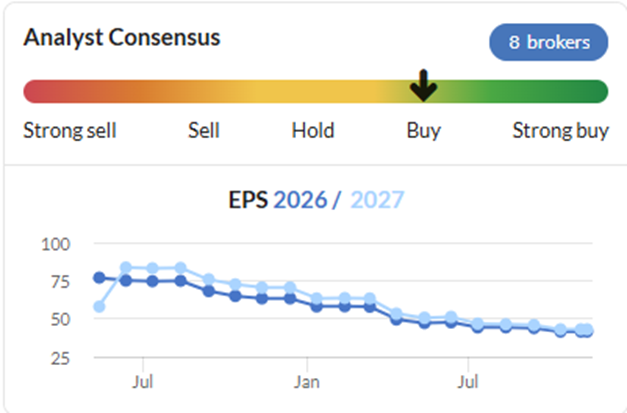
Driven mainly by continuous downgrades in broker consensus:
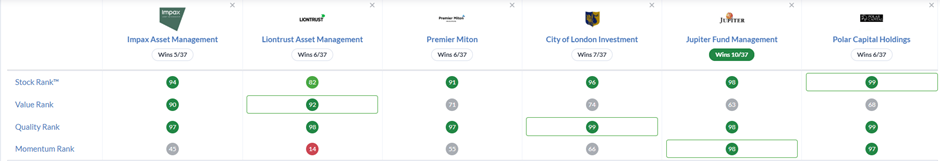
The weak momentum here means that this has the weakest StockRank in the sector:
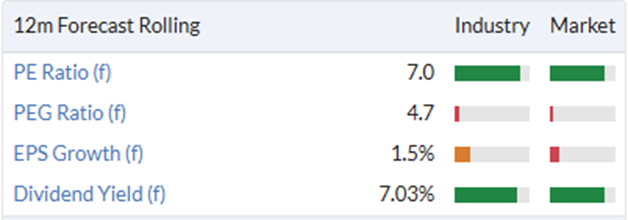
However, if forecasts are to be believed, it is also the cheapest, so it has the greatest potential to recover. The dividend yield is now back above 7% despite a considerable cut to the payout recently:
Next week sees Interim Results, and the focus will be on their ability to take costs out of the business and generate performance fees. We have already had Q3 AuM released, so there will be nothing new to report on that side. Q3 showed modest investment performance but continued net outflows, so it may be too early to call the bottom (although it is worth noting that Impax has bounced strongly off the bottom on very similar quarterly performance and flows.
CML Microsystems (LON:CML)
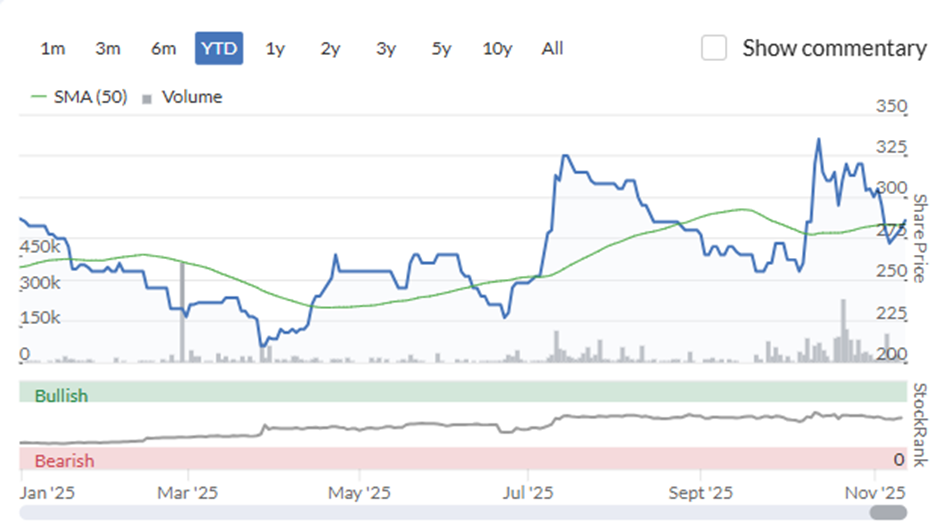
This company reports interim results next week. The share price is flat YTD, which is actually good for a UK small cap stock price!
While it may be green compared to its industry, a Price Earnings ratio of 43 is certainly punchy:
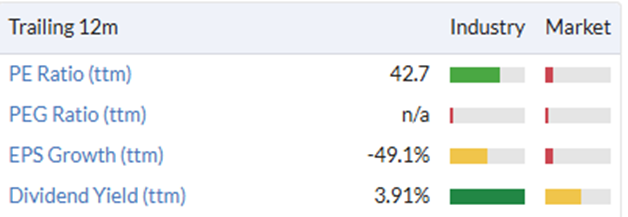
There are no forecasts in the market, so the StockReport is using historical figures. There is a decent yield, but it appears to have been paid out of a cash balance over the years rather than cash flow:
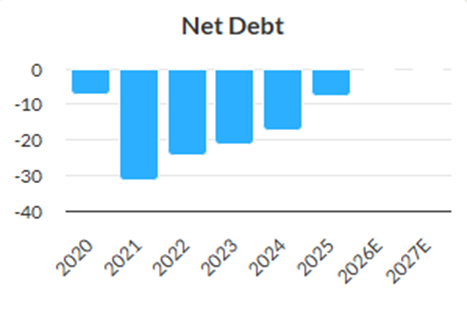
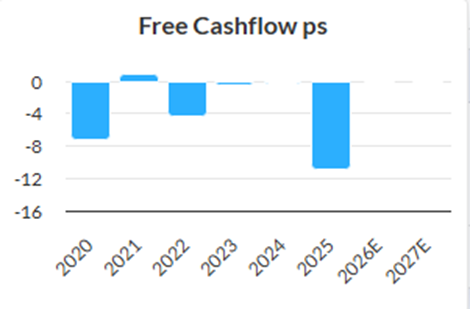
The dividend doesn't explain the whole reduction, and with Fixed Assets essentially flat, at least £20m has gone into intangible assets since 2021:
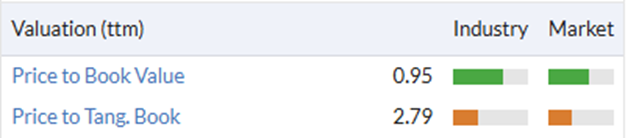
This means that the company compares favourably to its book value but not its tangible book value:
Their broker Shore explain the lack of forecasts:
At this stage, we are not providing forecasts for FY26F, reflecting ongoing market uncertainties and the company's currently limited visibility on forward demand. We anticipate being in a position to revisit our stance on forecasts as conditions evolve, with the aim of providing greater clarity during the course of calendar 2025. The recent binding agreement to dispose of surplus land clearly provides a meaningful boost to CML's already robust balance sheet.
The company announced that on 14 July, they had agreed to sell surplus land at its Group headquarters, with proceeds of £7m expected to be received within the current financial year. This means that they will still have a significant cash balance to keep going without requiring fresh equity. However, Shore also flag a second-half weighting, and that the company will be marginally profitable. This likely means that the result next week will be loss-making.
The algorithms still rate this as a High Flyer, but only just:
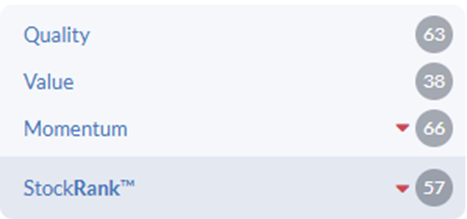
None of the Ranks here are particularly noteworthy and could well decline further if next week's results show a loss. The investment case appears to hinge on the significant investments made in intangibles over the last few years, starting to pay back eventually. However, with their broker reluctant to forecast even a few months ahead due to limited visibility, this looks more like a faith position than an informed one. Next week's results would need to be unusually strong to prove me wrong on this.
MITIE (LON:MTO)
This has been a strong performer since the Trump Tariff Tantrum in April:
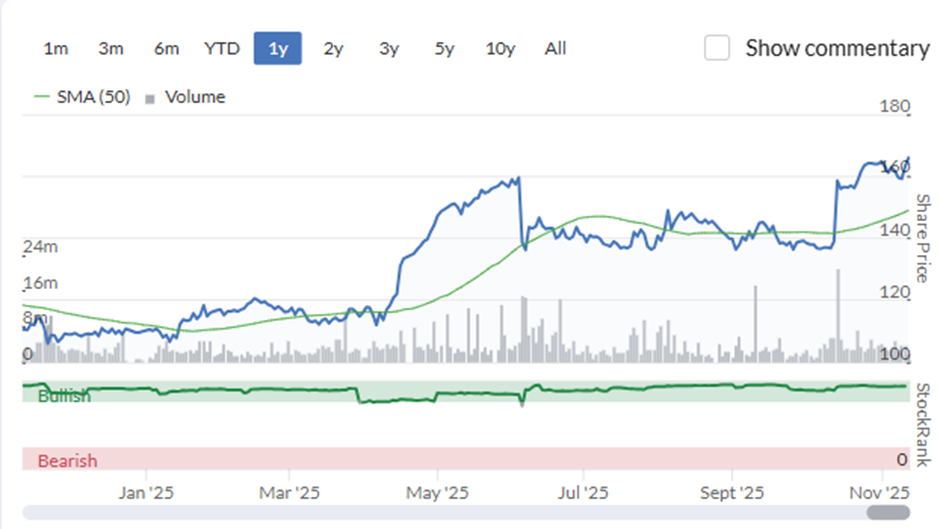
This has made it a superstock:
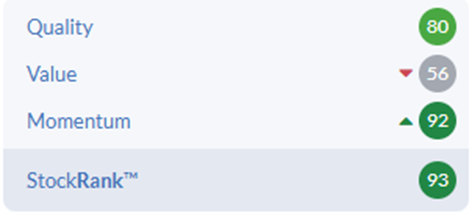
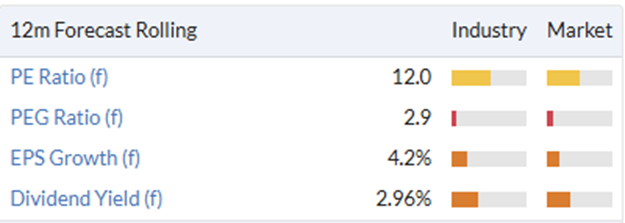
While not expensive overall, the cheapness of its industry and the UK markets means that the valuation metrics don't stand out:
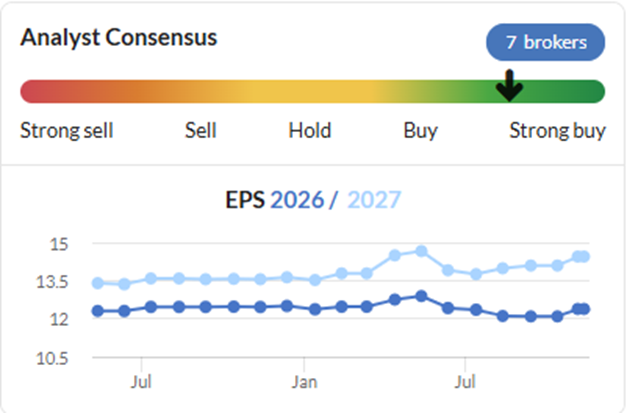
There has also been some weakness in broker forecasts since earlier in the year, but more recently these have been heading back in the right direction again:
It is often said that this type of company is only one onerous contract away from insolvency, and it has had to raise fresh equity over the years to rebuild its balance sheet. Net debt has been rising again more recently:
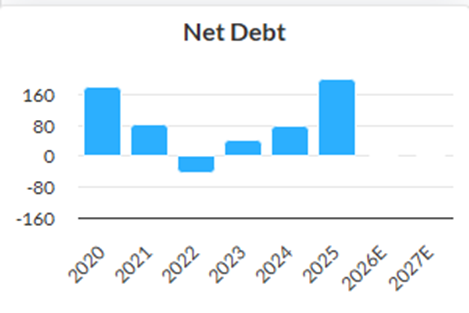
More recently, the company has been buying back shares rather than issuing new ones, so management are clearly comfortable with these levels of debt. Although the absolute value seems small compared to the current market cap, the gross gearing may be considered a little high:
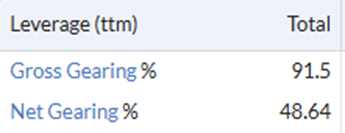
This means that the balance sheet may be as much a focus for investors in next week's interims as the earnings.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Mark,
Your 'heat map' table at the top only show 99 companies.
Do we get a prize for spotting the missing company? Lol
Cheers,
Jeremy
I hope I can meet you all at Mello
Trading update from Bodycote (LON:BOY) on 18th November too.
Thanks Mark. I believe Polar Capital Holdings (LON:POLR) will report half year results on Monday (17th) & Jet2 (LON:JET2) on Wednesday (19th).
Add Softcat (LON:SCT) Q1 Tues. 18th
Hi Mark - PayPoint (LON:PAY) Half year 20/11/2025 (website) and CMC Markets (LON:CMCX) stocko dates
Hi Mark :
Thanks for this summary.
I also have Tatton Asset Management (TAM) listed as publishing their interim results on tues 18th.
ATB
Geoff
Tatton will be featured on the BASH panel session on Tuesday at the #MelloLondon show so great timing if results out that day MELLOLONDON — Mello Events