The Week Ahead (23 – 27 Mar): Iran War, UK Inflation, US Employment, Carnival, Next, Gattaca

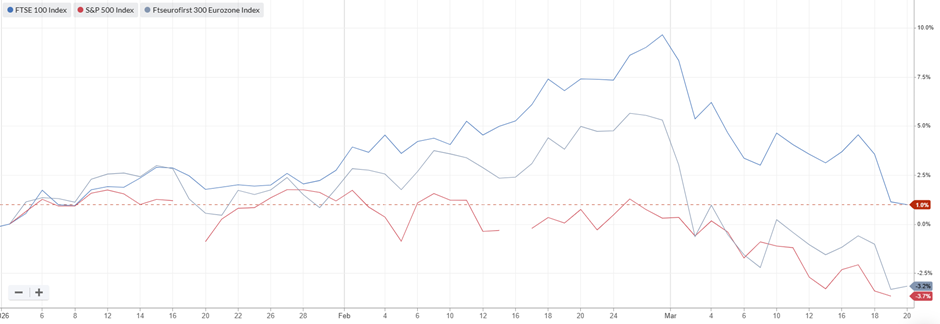
It's been a pretty crazy week for global markets, as equities sold off in response to global events and worries that higher energy prices will feed through to higher inflation and rates. The S&P 500 and Eurozone index are firmly in the red YTD, and the FTSE 100 only just clings on to a small gain due to its oil and mining constituents:
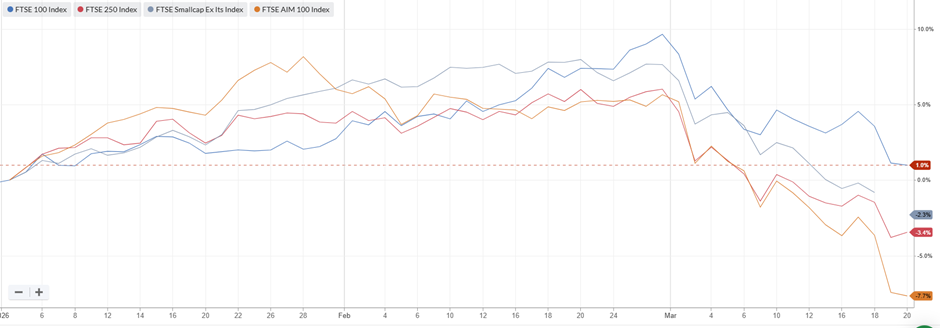
Things get worse as we go down the market cap level in the UK, with the FTSE 250 going negative YTD. AIM in particular has taken a battering (although the AIM 100 is a slightly strange index dominated by a smaller number of large companies that have chosen to remain on AIM):
Perhaps the biggest surprise, given global uncertainty, is the drop in the gold price over the past week:
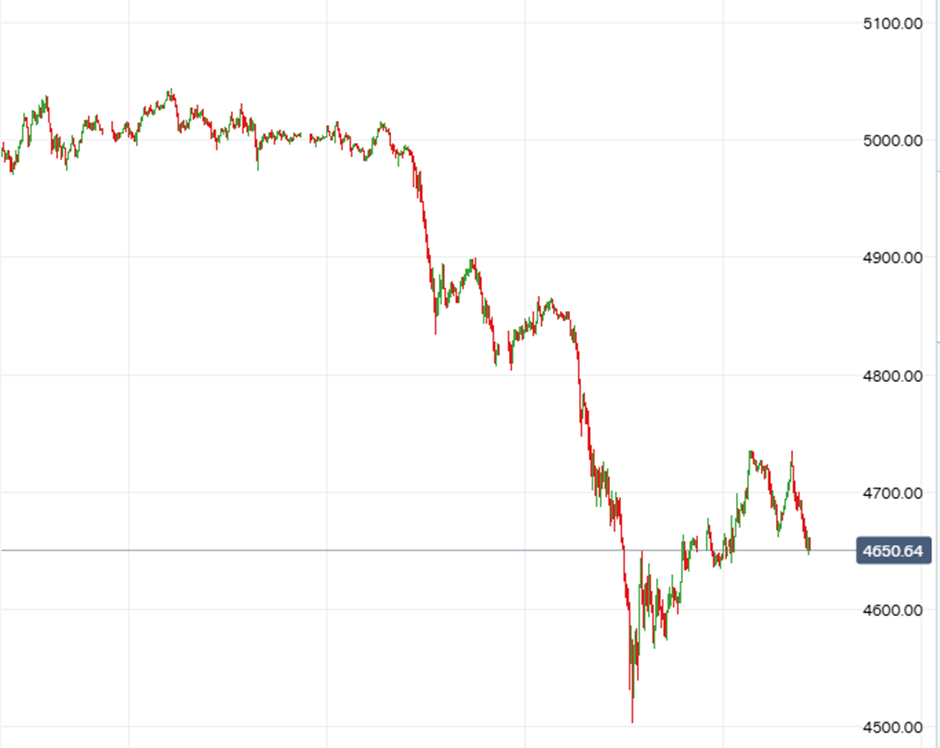
It seems that Gold’s status as a safe haven has been overwhelmed by Gulf countries' need for cash after losing short-term oil and gas revenue, plus potentially margin calls on commodity traders caught short oil into the crisis.
In the case of oil itself, the market initially priced this as a short-term issue. Whereas this week, prices have moved upwards across the forward curve. Oil futures are above $70/bbl out to September 2028:
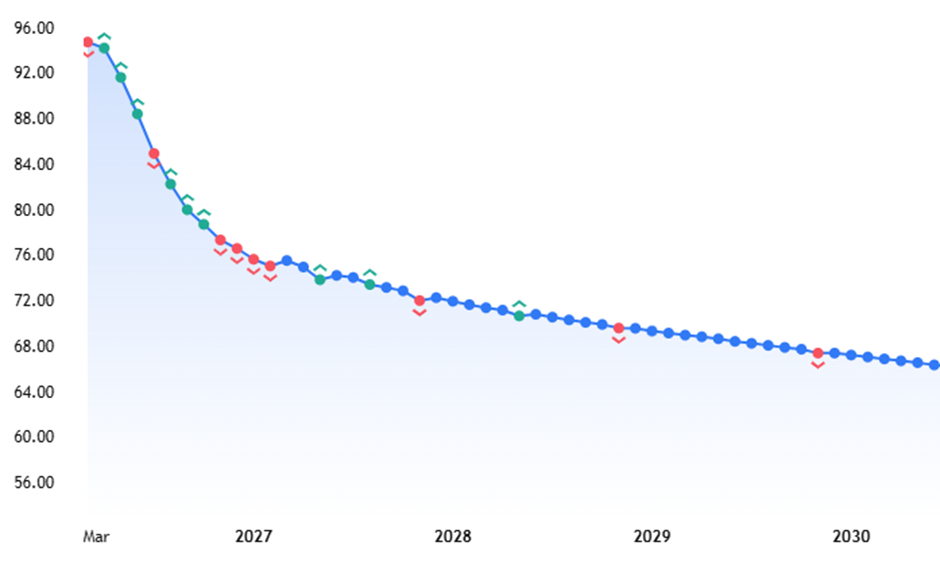
This means producers should be able to hedge strong prices into the future, making hay for several years, not just while the sun shines for them in the short term.
Here's what we can look forward to next week:
Economic Calendar
Monday 23 Mar |
||
15:00 |
Euro Area |
Consumer Confidence |
23:30 |
Japan |
Inflation Rate |
Tuesday 24 Mar |
||
09:30 |
UK |
Manufacturing PMI Services PMI |
12:30 |
United States |
Retail Sales |
20:30 |
United States |
API Crude Stocks |
23:30 |
Japan |
BoJ MPC Meeting Minutes |
Wednesday 25 Mar |
||
07:00 |
UK |
Inflation Rate |
09:00 |
Germany |
Business Climate |
12:30 |
United States |
Current Account |
14:30 |
United States |
EIA Gasoline Stocks EIA Crude Oil Stocks |
Thursday 26 Mar |
||
07:00 |
UK |
Retail Sales |
12:30 |
United States |
Retail Inventories Durable Goods Orders Initial Jobless Claims Continuing Claims |
Friday 27 Mar |
UK Inflation
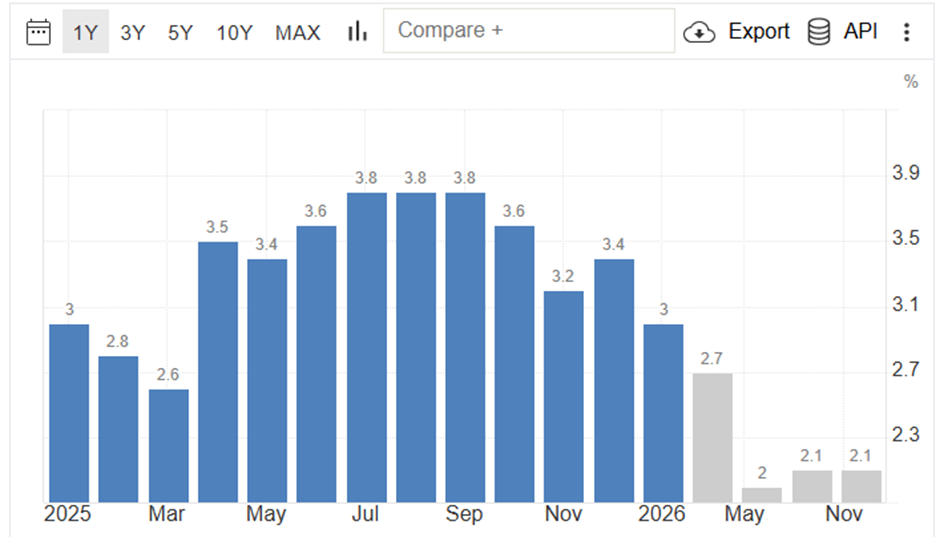
UK inflation had been forecast to decline towards the Bank of England’s 2% target:
[All charts in this section: Trading Economics]
Recent global events may well have thrown a spanner into the works. However, this week’s data is from before these events. The Bank of England cares most about the sticky components of core inflation, such as wages, services and housing costs. If these are unexpectedly high, then this, combined with the as-yet-unseen effects of higher energy prices, may well spook the market (further!)
US Employment
The latest US data from February was unexpectedly weak, with non-farm payrolls losing 92k jobs versus an expected 60k gain. The unemployment rate rose to 4.4%. Companies appear not to be firing aggressively, but neither are they hiring, creating a grinding deterioration, not a crash. Initial jobless claims are forecast to rise, though:
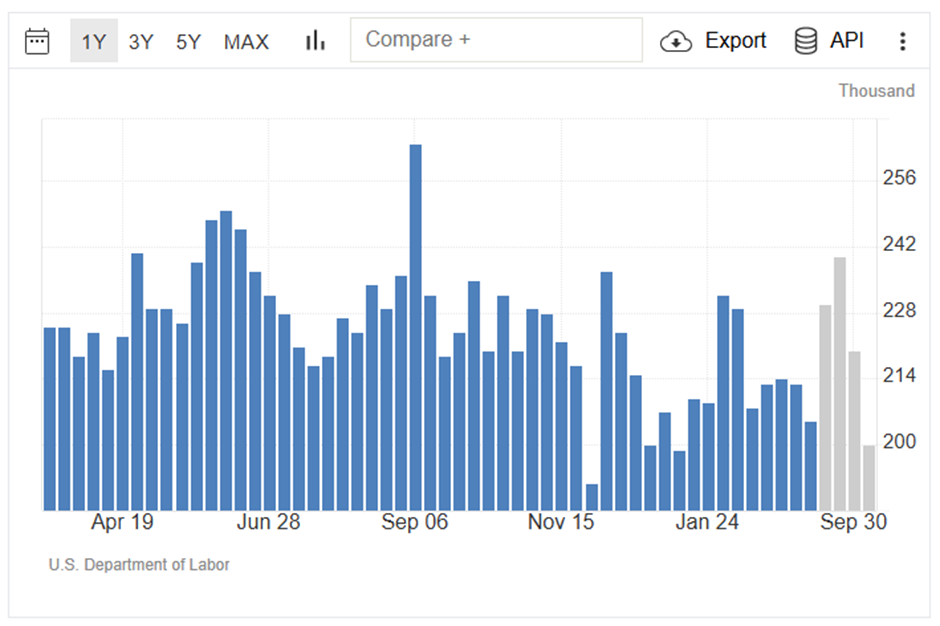
Any big jumps in either reported figures or forecasts would indicate that the impact of higher oil prices and rates is starting to impact the US domestic economy.
Companies Reporting
Another very quiet week for US stocks, due to their quarterly reporting schedule. However, there will be a huge number of UK companies releasing results in the coming week:
| Date | UK Trading Updates & AGMS | UK Financial Results | International Financial Results |
|---|---|---|---|
Monday 23 Mar |
Applied Nutrition (LON:APN) (Interims) Blackbird (LON:BIRD) (Finals) Caledonia Mining (LON:CMCL) (Finals) Distribution Finance Capital Holdings (LON:DFCH) (Finals) Pennant International (LON:PEN) (Finals) Public Policy Holding (LON:PPHC) (Finals) Quartix Technologies (LON:QTX) (Finals) RTC (LON:RTC) (Finals) Thungela Resources (LON:TGA) (Finals) Tandem (LON:TND) (Finals) |
PDD Holdings (NSQ:PDD) |
|
Tuesday 24 Mar |
Hardide (LON:HDD) (AGM) RC Fornax (LON:RCFX) (AGM) Time Finance (LON:TIME) (TS) Wynnstay (LON:WYN) (AGM) |
Henry Boot (LON:BOOT) (Finals) Bellway (LON:BWY) (Interims) Corero Network Security (LON:CNS) (Finals) Chesnara (LON:CSN) (Finals) EKF Diagnostics Holdings (LON:EKF) (Finals) Everplay (LON:EVPL) (Finals) Fevertree Drinks (LON:FEVR) (Finals) Flowtech Fluidpower (LON:FLO) (Finals) Foresight Solar Fund (LON:FSFL) (Finals) Gamma Communications (LON:GAMA) (Finals) Gattaca (LON:GATC) (Interims) Getbusy (LON:GETB) (Finals) Itaconix (LON:ITX) (Finals) Journeo (LON:JNEO) (Finals) Kingfisher (LON:KGF) (Finals) Michelmersh Brick Holdings (LON:MBH) (Finals) M P Evans (LON:MPE) (Finals) Octopus Renewables Infrastructure Trust (LON:ORIT) (Finals) Personal group (LON:PGH) (Finals) Regional REIT (LON:RGL) (Finals) S4 Capital (LON:SFOR) (Finals) Staffline (LON:STAF) (Finals) Mission (LON:TMG) (Finals) TMT Investments (LON:TMT) (Finals) Ultimate Products (LON:ULTP) (Interims) Xaar (LON:XAR) (Finals) YouGov (LON:YOU) (Interims) |
H & M Hennes & Mauritz AB (STO:HM B) (Sweden) |
Wednesday 25 Mar |
Crest Nicholson Holdings (LON:CRST) (AGM) Mediazest (LON:MDZ) (AGM) Nexus Infrastructure (LON:NEXS) (AGM) Sunrise Resources (LON:SRES) (AGM) |
WAG Payment Solutions (LON:EWG) (Finals) Franchise Brands (LON:FRAN) (Finals) Headlam (LON:HEAD) (Finals) Kenmare Resources (LON:KMR) (Finals) Norman Broadbent (LON:NBB) (Finals) S4 Capital (LON:SFOR) (Finals) TT electronics (LON:TTG) (Finals) |
|
Thursday 26 Mar |
Haydale (LON:HAYD) (AGM) InvestAcc (LON:INAC) (AGM) LPA (LON:LPA) (AGM) Treatt (LON:TET) (AGM) |
Airea (LON:AIEA) (Finals) Amaroq (LON:AMRQ) (Finals) Arbuthnot Banking (LON:ARBB) (Finals) Ceres Power Holdings (LON:CWR) (Finals) Mears (LON:MER) (Finals) Next (LON:NXT) (Finals) Oxford BioMedica (LON:OXB) (Finals) Serica Energy (LON:SQZ) (Finals) Tribal (LON:TRB) (Finals) |
|
Friday 27 Mar |
Eco (Atlantic) Oil & Gas (LON:ECO) (AGM) ECR Minerals (LON:ECR) (AGM) |
Carnival (LON:CCL) |
As usual, let us know via the comments if you think we’ve missed anything of note.
Carnival (LON:CCL)
This is the only US company of note reporting next week. It is on a fairly low earnings multiple for a US large cap:

However, it also has a huge debt and negative working capital, making it look more expensive on an Enterprise Value basis:

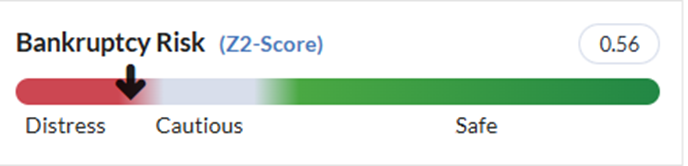
And the algorithms flag it as risky for those reasons:
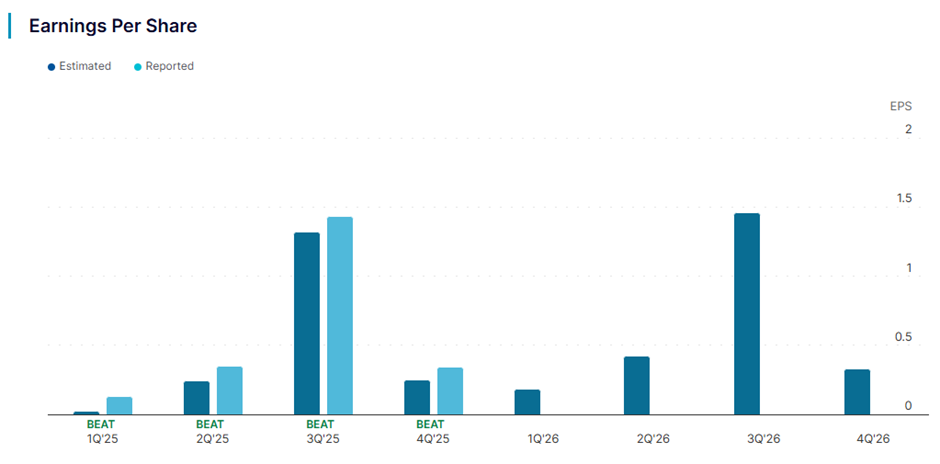
This is a highly seasonal business, so the Q1 results themselves are unlikely to be that important. What investors will be looking for is the streak of beating estimates to continue:
Plus forward indicators, such as booking curves for summer 2026 and early 2027. Carnival has prioritised a “price over volume” recovery since COVID, so pricing strength and any requirement for discount will be key to the outlook.
Any commentary or adapted guidance regarding recent geopolitical events will also be closely watched. There are cost risks associated with fuel, food, and interest expenses at the moment. While any mention of itinerary adjustments due to waterway closures or increased risk could be received badly.
Next (LON:NXT)
UK retail giant Next continues to be the exemplar for both trading through difficult market conditions and the detail of its financial reporting. Strong Christmas trading led to an upgrade in guidance in the January trading statement, so the key numbers will not be a surprise:
- FY PBT expected £1.15bn (+13–14%)
- Full-price sales +10–11% YoY
- EPS +16% YoY
However, it trades on a heady valuation for a company expected to grow EPS by low-to-mid single-digit percentages over the next few years:
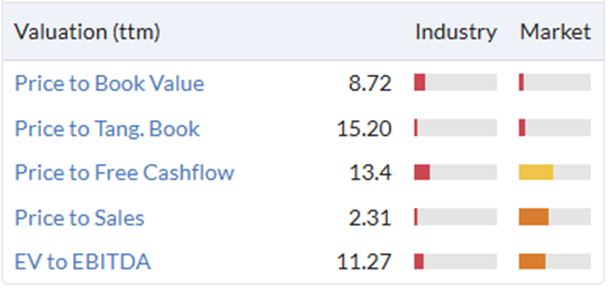
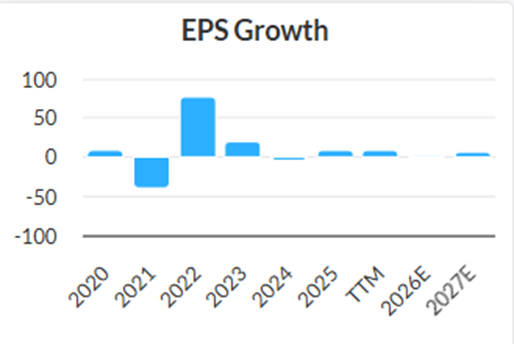
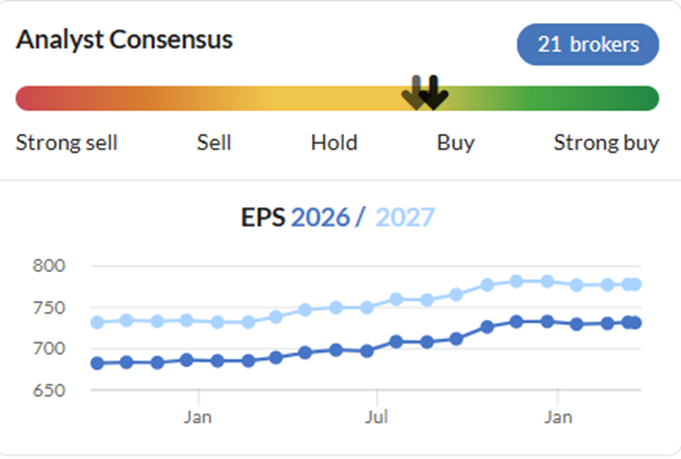
The company tends to guide conservatively and upgrade during the year. So, investors will be looking for guidance that suggests that upgrades are to come, and the EPS forecasts to return to the previously upward trend to justify the current valuation, let alone a step upwards:
Specifics to look out for are:
- UK: Any change to guidance based on recent trading conditions and economic factors such as wage growth and employment levels.
- International Online: This has been the standout growth area recently, with 30%+ increases. Guidance is for this to slow, but by how much can make a big difference to the value of this part of the business.
- Shareholder returns: Whether they declare a special dividend or prefer further buybacks.
- Brand acquisition: Ability to keep adding distressed brands and comments about the pipeline of such deals.
- Disruption: Any FX or commodity impacts from recent world events.
Gattaca (LON:GATC)
Personally, I am looking forward to seeing the results from this Super Stock holding. This was one of Ed’s NAPS for 2026, and has an impressive StockRank, so I’m sure many subscribers will be following this, too:
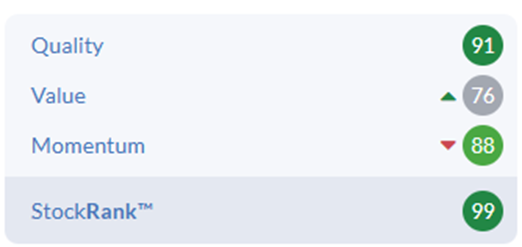
So far, this company has bucked the trend seen in larger recruiters, which have seen their prospects (and share prices) decline. Despite recent upgrades, this remains very cheaply valued on many metrics:
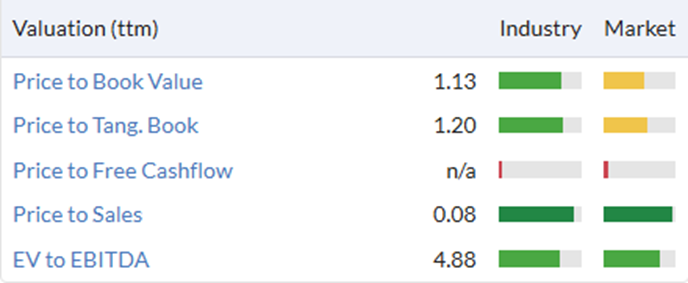
EPS is forecast to grow 30% for the Full Year, so investors will want to see these H1 results show signs of that growth potential. As well as the financial numbers, they will be looking for progress on their ambition to expand into adjacent markets and grow headcount, so the segmental reporting will be closely watched.
While the company has significantly outperformed the sector recently, there is no doubt that overall end markets for recruitment are weak. This bodes well for the business's performance during a cyclical recovery, but investors will be wary about when that might occur. After all, hiring headcount ahead of a cyclic bounce that never happens can be a recipe for weak short-term profitability.
[Disclosure: Mark owns shares in Gattaca (LON:GATC) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Serica Energy (LON:SQZ)
Looking forward to Thursday for the results day.
Should be hearing confirmation of a move to the main market and the overall corporate picture for the year ahead after a busy year m&a wise. Just a word of caution don't expect any of the recent prices to be on the ledger yet, so far Ithaca Energy (LON:ITH) and Harbour Energy (LON:HBR) both fell on their results days.
Don't be shy if you see a fall on results day, it could be a great buying opportunity and for full disclosure I hold all of the three mentioned.
Gold prices have been very interesting this week, I agree with you Mark the fall in price this week is a liquidity sweep with a lot of people being caught unawares - completely took me by surprise but I bought the dip with Thor Explorations (LON:THX) and feeling comfortable for the week ahead.
The Elephant in the room next week, is going to be those Brent Futures. Just for full disclosure I worked out the dates when refineries were going to be receiving the last of their gulf oil at sea, the range of dates given coincide with next weeks market. In other words the conveyor belt is empty $200 barrels have been felt globally at the exact points of my timeframe.
Don't believe any of the propaganda about the Straight of Hormuz or "oil releases" to quote Daddy its all "fake news", there is nothing apart from total victory (which requires boots on the ground), to change Iran dictating the flow of traffic. Best piece of news as an investor to use right now is a Marine Traffic app, literally nothing Western-aligned is moving yet BRICS nations flow peacefully - in particular oil tankers with Chinese crews.
Once we all get bored of thinking about the oil and gas stuck floating there... just remember the world has a finite amount of oil tankers to transport oil and gas. So imagine the logistical nightmare to say if 10% of those oil tankers were stuck somewhere... or even imagine the remaining 90% had to reroute around an entire landmass because usage of a canal was currently uninsurable - that adds weeks on to the delivery time.
These are very very dark waters we are heading for... always do your own research like what other important commodities are stuck on water in the gulf (give it a few weeks before fertiliser is in the news) - remember cash is always a position in your portfolio!
Excellent post I hold SQZ -IHT - TXY