The Week Ahead (5-9 May): interest rate cuts and trade talks?

After a volatile start to April courtesy of tariff Liberation Day, most major indices ended the month broadly flat – perhaps a good argument in favour of buy-and-hold investing.
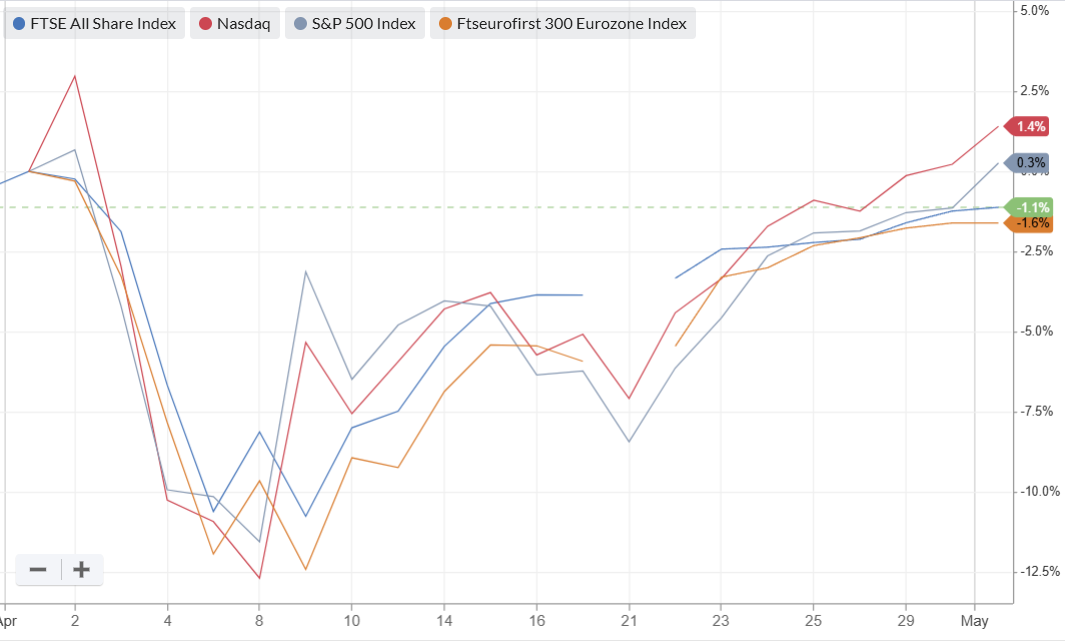
Despite relative calm in the markets this was a busy week for UK company news, with 130 UK company updates summarised at the top of our daily reports!
Across a broad range of companies reporting, we noted mixed results from the big UK banks and encouraging progress for pharma giant GSK (LON:GSK). An AGM vote at Rio Tinto (LON:RIO) also revealed strong shareholder support for maintaining the FTSE 100 miner's London listing.
Housebuilders Taylor Wimpey (LON:TW.) and Persimmon (LON:PSN) both left full-year expectations unchanged. Meanwhile, comments from Lloyds Banking (LON:LLOY) suggested it was a strong quarter for mortgage lending, with buyers racing to complete before Stamp Duty returned to pre-2022 levels on 1 April.
For smaller and mid-sized UK firms, tariff uncertainty was a key theme, contributing to a number of profit warnings and uncertain outlook statements.
This uncertainty now also seems to be affecting companies in the US. Mcdonald's (NYQ:MCD) reported a 3.6% drop in like-for-like sales for the first quarter – apparently the biggest quarterly drop since the pandemic. The fast-food group’s CEO said its customers were “grappling with uncertainty”.
However, Meta Platforms (NSQ:META) and Microsoft (NSQ:MSFT) reported quarterly earnings ahead of expectations this week, perhaps suggesting that some areas of the US economy remain healthier – and that the tech boom may not be over yet.
Next week’s news could provide more insight into the actual and expected impact of tariffs on major US firms, with a broad range of businesses due to report. Names such as Ford Motor Co (NYQ:F), Walt Disney Co (NYQ:DIS) and Anheuser-Busch Inbev SA (NYQ:BUD) may provide further insight into the health and sentiment of US consumers.
Several major US oil and gas companies are also reporting, providing further context to this week’s mixed updates from UK–listed BP (LON:BP.) and Shell (LON:SHEL).
After another long weekend here in the UK, next week's newsflow from the London market looks likely to be a little quieter. However, there should be some interesting small and mid-cap names to discuss in the daily report.
Economic news could also prove interesting. Press reports suggest that China is considering whether to begin trade talks with the US, providing a possible boost to investor sentiment.
Meanwhile, interest rate decisions are due from both the Federal Reserve and the Bank of England next week. Current expectations suggest that the Bank of England could cut the Bank Rate by 0.25% to 4.25% on Thursday, while the Fed is expected to leave its main policy rate unchanged at 4.25%-4.5% on Wednesday.
Economic Calendar
Monday 5 | ||
14:45 | US | Markit Services PMI |
15:00 | US | ISM Non-Manufacturing PMI |
Tuesday 6 | ||
09:30 | UK | Services & Composite PMI |
Wednesday 7 | ||
09:30 | UK | Construction PMI |
19:00 | US | Federal Reserve interest rate decision |
Thursday 8 | ||
07:00 | UK | Halifax House Price Index |
12:00 | UK | Bank of England interest rate decision |
13:30 | US | Initial jobless claims |
Companies Reporting
UK Trading Updates | UK Financial Results | International Financial Results | |
Monday 5 | Palantir Technologies Cummins Ford Motor Vertex Pharmaceuticals CRH | ||
Tuesday 6 | IWG | Facilities by ADF Huddled Group Kosmos Energy | Advanced Micro Devices Duke Energy Marriott International Marathon Petroleum Electronic Arts Ferrari |
Wednesday 7 | JD Wetherspoon | Card Factory 1Spatial CT Automotive Smiths News Georgia Capital Flutter Entertainment Burford Capital Trainline Maxcyte | Uber Occidental Petroleum Walt Disney BMW Barrick Gold Novo Nordisk |
Thursday 8 | Rathbones IMI InterContinental Hotels Derwent London Mondi Harbour Energy S4 Capital | Polarean Imaging Lords Group Trading Airtel Africa TBC Group Helios Towers 3I Infrastructure | ConocoPhillips Toyota Siemens Energy Coinbase Global Infineon Anheuser-Busch Inbev AP Moeller-Maersk |
Friday 9 | International Airlines Group |
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Hi Roland, thanks for the censorship, allowed I might have got egg on my face!
Lyn Alden's May newsletter gives an interesting view on the US tariff situation and possible implications for investing.
Written from a US perspective...
https://www.lynalden.com/may-2...
You can't rule out people boycotting mac ds due to trump
I cannot connect the dot with Mcdonald's (NYQ:MCD) and tariffs. Imported Argentinian beef, ok, buns from the Ukraine, ok. No wonder US needs on-shoring - perhaps the Bison burger will re-emerge (copyright alert - I said it and will sue your donkey).
Sentiment imo is key - if the health push in US is real then of huge long term benefit to health care budgets, humanity, etc etc. (but not to the industries that are supported by our bad habits).
Imperial Brands (LON:IMB) seems to be doing well.
I think MCD have raised their prices a lot and seeing a push back from Joe Public. Not Mr Trump or Mr Macro.
Greggs may also find this out at some point where we i.e. customers, not investors, clearly not spending money willy nilly. Coffee may also need to up its game - a lost leader to bring you in to buy the sandwich is now the main event.
RFK hopefully makes a positive in the world - not all the false covid prophets and other snakes in the world.
Agreed re McDonald’s think they have got to greedy on their price hikes and are no longer that cheap. - looking at their prices pre covid vs now is eye watering. Think Greggs pricing is currently ok but they will need to be careful when implementing price increases as their value pricing is a big part of their USP.
Agreed Greggs (LON:GRG) are the Wetherspoons of the bakery sector you put up with the fact the premises are all a bit down market due to fact the snacks are decent quality and relatively cheap.
They've been refurbing there stores down here recently. They are pretty smart. Get a 'free' treat every week if you sign upto Monzo Perks!
Its not so sharp where I am Paul near Norwich some of the stores now have the problem of aggressive beggars going round the customers looking for money, sausage rolls or coffee's.
Hi Paul, if you are with Octopus Energy and you sign up to its free Octoplus scheme, you can claim each week either a free Caffè Nero hot drink or a free Greggs hot drink. That's 2 x free Greggs hot drinks per week.
David.
If they offered muffins i'd go for it!
Hi Paul,
O2 have recently launched Blue Mondays.
At 12noon every Monday O2 offers 7,500 £2 Greggs eGift Vouchers for free which entitle you to £2 off more or less anything in its shops, including coffees!!!
Im with Lebara. Never got a good signal with O2
I assume you are discussing UK coverage Paul. - Lebara don't use O2's network, they use (The poor cousins priority connection) to Vodaphone's. Based 100% on your experience Vodaphone network coverage is better than O2's?
I know. Yes I'd say Lebara is better. My wife is on the same and only pays about £3 a month sim only. Never had a problem unlike with O2 previously
When they first opened in the UK a hamburger was 18p, a cheeseburger 21p and I think a Big Mac, in a collar was 45p. Mind you, pay then was 65p an hour!
I suspect McDonald's got a little greedy but by and large they must have lost a lot of the big advantage they had with their supply chain, no doubt all their suppliers put up costs due to Covid and they've not gone back down, nor will they. Probably spend the next 10 years reoptimising their supply chain (figuring out who to exploit next)
No comments showing on the app