The Week Ahead (8 – 12 Dec): US Interest Rates, Costco, Adobe, Moonpig, RWS

Markets
The FTSE100 is largely flat this week as lower financials were a drag, despite support from commodity producers. U.S. indices fell earlier in the week as the market priced in higher global risks. However, it rebounded midweek as US rate-cut expectations increased.
Here's what we can look forward to next week:
Economic Calendar
Monday 8 Dec |
||
03:00 |
China |
Balance of Trade |
Tuesday 9 Dec |
||
07:00 |
UK |
Retail Sales |
07:00 |
Germany |
Balance of Trade |
15:00 |
United States |
Job Openings |
Wednesday 10 Dec |
||
01:30 |
China |
Inflation Rate |
12:00 |
United States |
Mortgage Approvals |
19:00 |
United States |
Fed Interest Rate Decision |
Thursday 11 Dec |
||
00:01 |
UK |
RICS House Price Balance |
Friday 12 Dec |
||
07:00 |
UK |
Industrial Production |
US Interest Rates
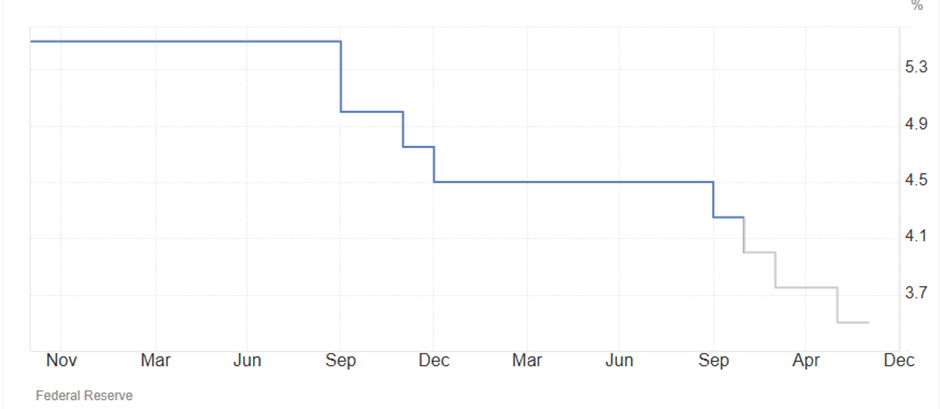
The US Federal Funds Rate is forecast to be cut by a further 25bps to 3.75% on Wednesday:
[All charts in this section: Trading Economics]
However, due to the recent government shutdown, the October 2025 CPI report was cancelled, and CPI data for November is scheduled for 18th December. This means up-to-date inflation data will not be available to base this decision on, and the Fed will instead have to rely on other indicators, such as jobs data released over the last week. The uncertainty means there is a wider scope than usual for a surprise decision, and markets may react more strongly to any shock.
UK Figures
It is a fairly quiet week for UK economic data. However, with the recent Budget adding to the economic uncertainty for many companies and individuals, a few data points may indicate how this is being perceived and reflected in economic activity.
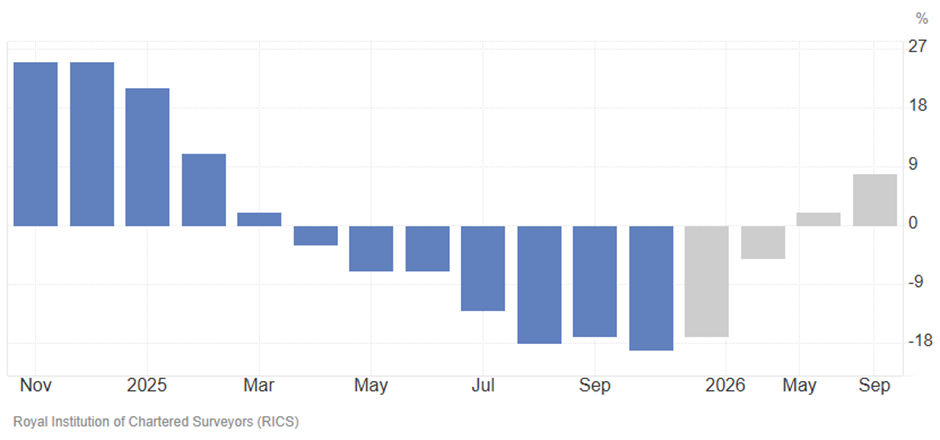
The RICS house price balance, released on Thursday, is a survey-based indicator from the Royal Institution of Chartered Surveyors that shows whether more surveyors reported a rise or a fall in house prices in their area. It is considered a leading indicator for house prices because it includes forward-looking sentiment on price and sales volume expectations for both the near-term and the coming 12 months. Recent trends here have not been particularly promising:
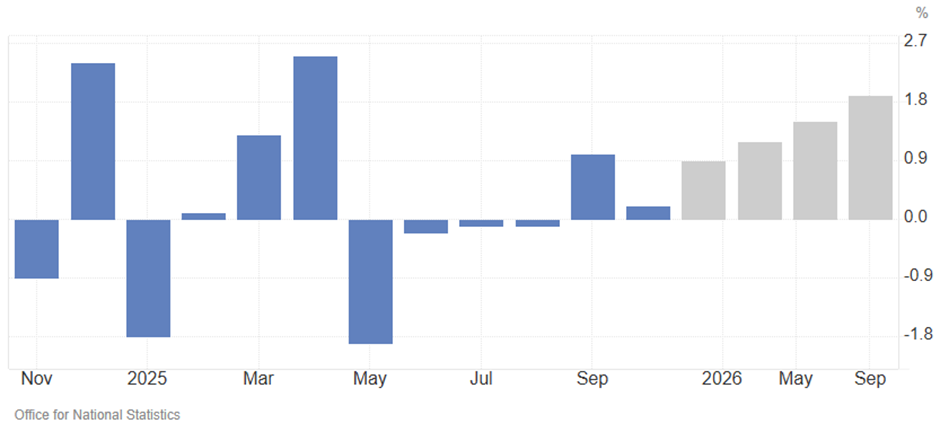
Retail Sales data has been more variable, but with the same underlying trend:
Finally, UK Industrial Production saw a big dip in September. However, it is forecast to return to growth in December:
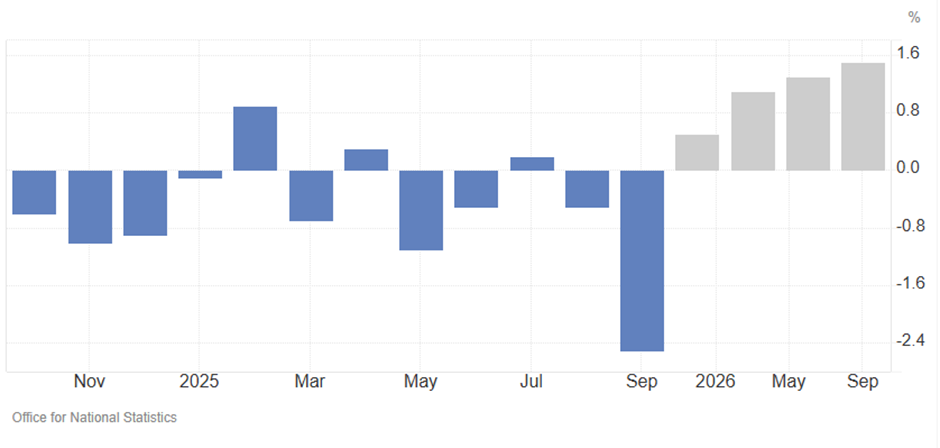
All of these leading indicators may give advance warning as to whether the UK has been naughty or nice when GDP figures are released just before Christmas!
Companies Reporting
| UK Trading Updates | UK Financial Results | International Financial Results | |
|---|---|---|---|
Monday 8 Dec |
Toll Brothers (Q4) |
||
Tuesday 9 Dec |
Asiamet Resources (AGM) |
Ashtead (Interims) Ixico (Finals) |
AeroVironment (Q2) |
Wednesday 10 Dec |
Gattaca (AGM) |
Berkley Group (Interims) |
Nordson (Q4) |
Thursday 11 Dec |
dotDigital (AGM) |
NCC Group (Finals) |
Broadcom (Q4) Lululemon (Q3) |
Friday 12 Dec |
Ultimate Products (AGM) |
It is forecast to be a relatively quiet week for planned news, with just a few quarterly reports in the US and a few companies reporting Final/Interim Results to 30th September.
If any investors think I've missed some upcoming news or included a red herring, then feel free to correct this in the comments.
Costco Wholesale (NSQ:COST)
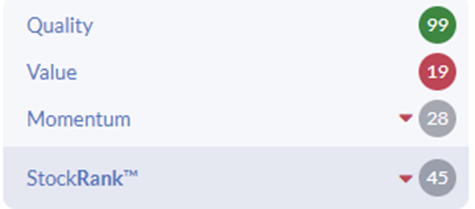
Costco is considered an exceptional business. Its ability to deliver retail at scale and keep its margins constant means that it largely earns its money from the subscription fees. This subscription model means it has consistently high returns on capital, and it is one of the highest Quality-Ranked stocks in the database:
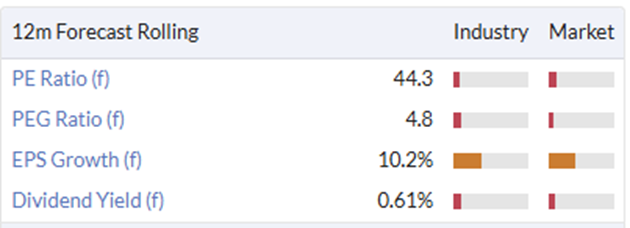
However, it is not cheap:
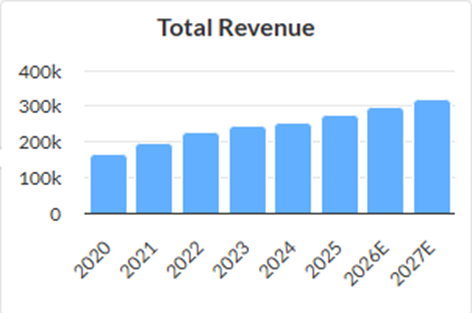
Revenue growth comes in at 10% CAGR over the last 5 years:
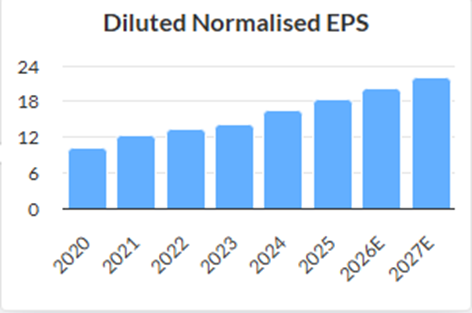
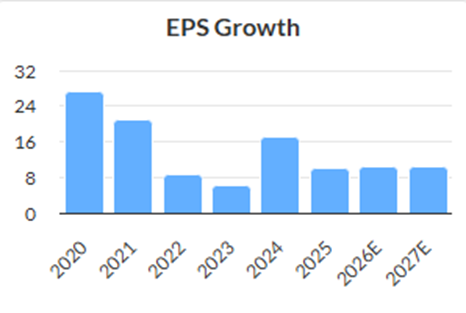
And a little bit of operational gearing leads to a 12% 5-yr EPS CAGR:
Looking forward, analysts are predicting similar growth figures going forward, meaning its PEG ratio is unimpressive at over 4:
It has beaten forecasts over the last year, but only very slightly:
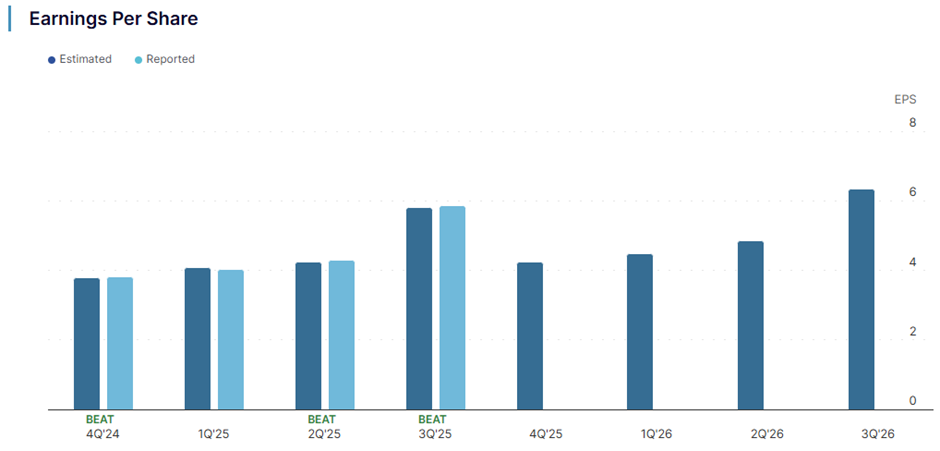
[Source:NASDAQ]
Investors have started to baulk at this valuation, and the shares have started to decline. The three-year chart looks very much like a “hump”, which implies negative Momentum characteristics:
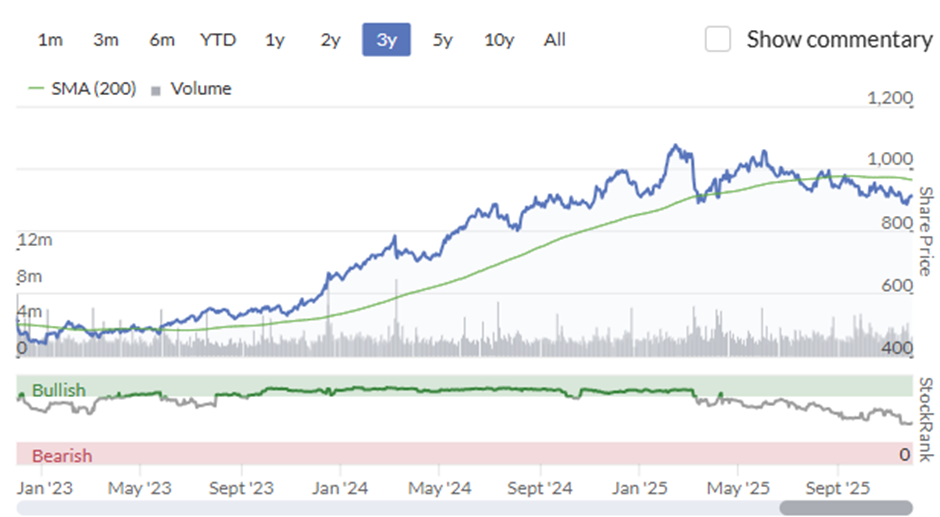
Management will need to show accelerating growth beyond current forecasts to reverse this trend.
Adobe (NSQ:ADBE)
When I reviewed this US software provider in the run-up to its Q3 earnings release, I said:
When the company reports Q3 earnings on Thursday, any further beat will make the company look exceptional value. Especially to investors, like myself, who think that AI productivity gains are equally likely to accrue to companies adapting existing strong products and extensive customer relationships, as to new start-ups.
Earnings did indeed come in ahead of consensus:
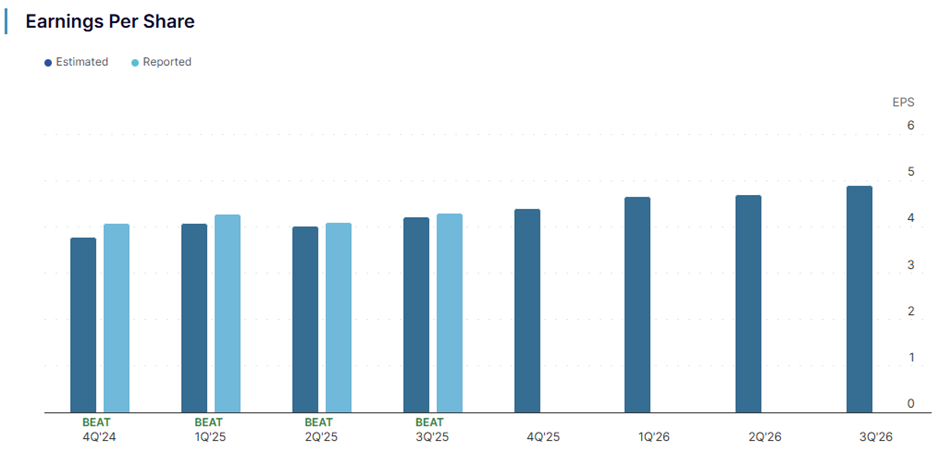
[Source:NASDAQ]
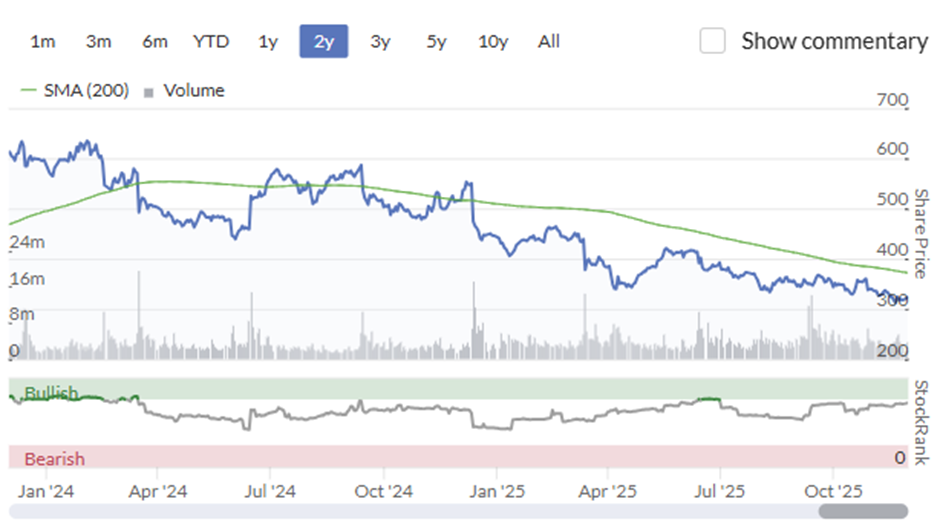
However, this didn’t stop the share price decline:
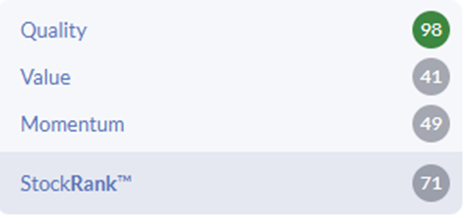
Comparing Adobe with Costco shows how much narrative drives stock market valuation. Both are very high-quality subscription model businesses, with Adobe only very slightly behind on the Quality Rank:
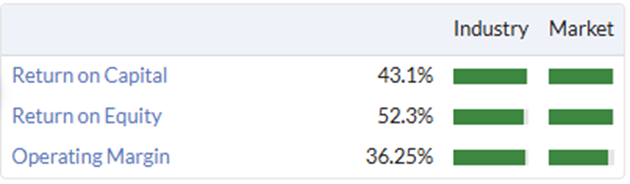
Adobe tends to earn higher Returns on Capital:
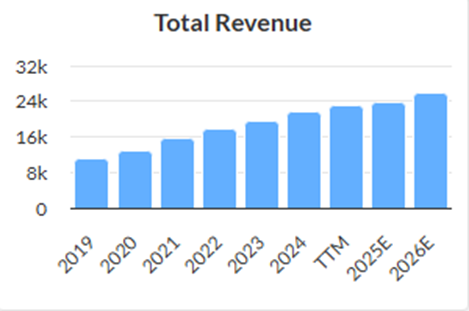
And its 5-yr revenue CAGR is higher at 14%:
Again, it has modest operational gearing leading to a 5-yr EPS 17% CAGR:
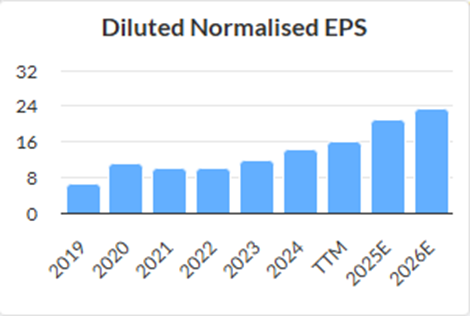
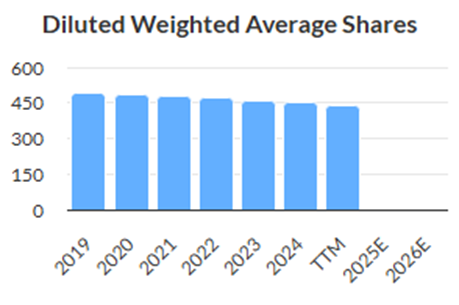
There’s no dividend, and part of this EPS growth is due to a 2% CAGR reduction in shares in issue, but even accounting for this, the EPS growth rates are higher:
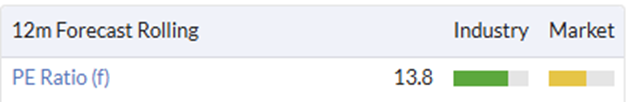
Looking forward, 2-yr EPS CAGR is forecasted to be even higher at Adobe, yet the shares trade at a material discount to Costco and other software peers:
It seems market participants who fear the impact of AI on businesses such as this won’t hold at any price, even if there is no sign of that disruption in the current forecasts. This may provide an opportunity for investors willing to take the other side of that trade.
Moonpig (LON:MOON)
In the UK, Moonpig is showing signs of a bowl-shaped share price recovery (although that seems to have flattened off more recently):
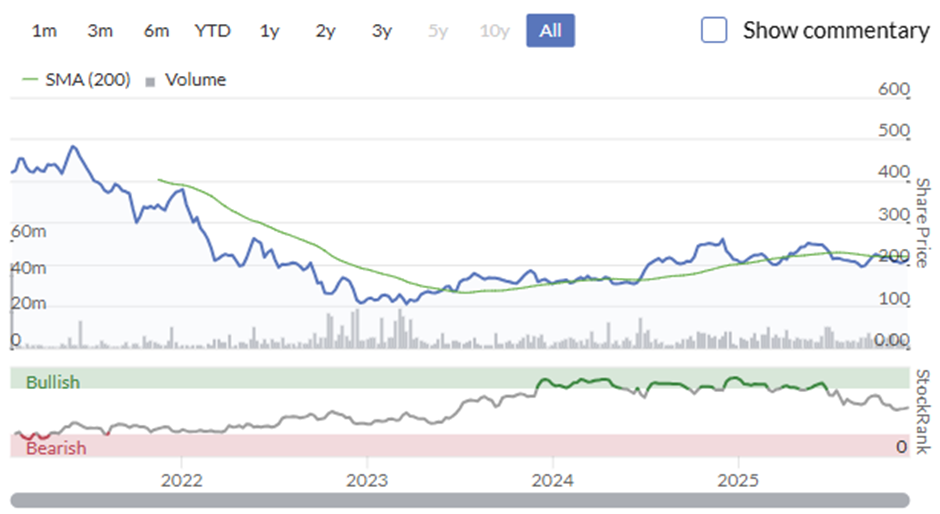
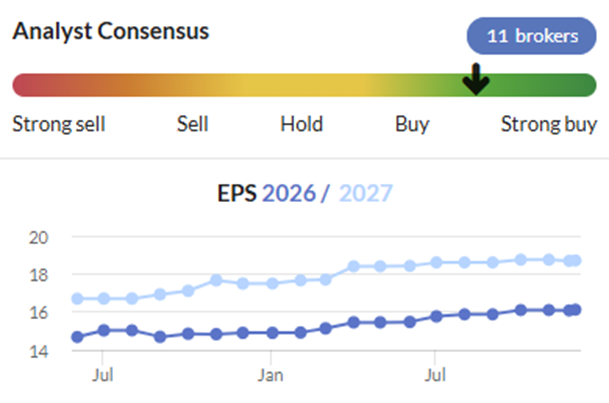
Like many businesses, it seems to have been floated on an optimistic multiple, and the hangover of that has taken time to work through. More recently, trends are exactly what investors like to see, with mostly continuous upgrades in EPS for both forward years:
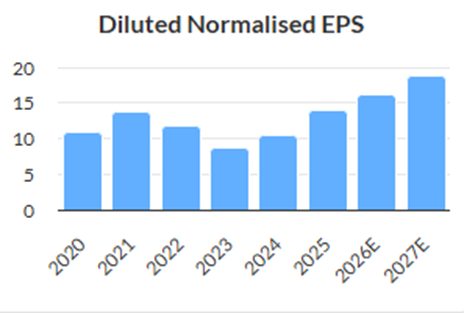
This looks good in a historical context, too:
It isn’t particularly cheap for a UK stock, and especially a retailer:
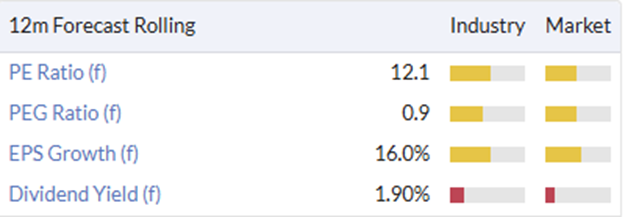
However, a 16% 2-yr forecast EPS CAGR makes it look reasonable value on its PEG ratio if that outcome is achieved. However, the recent trading statement was less impressive for FY26, guiding:
For FY26, we continue to expect Group Adjusted EBITDA to grow at a mid-single digit percentage rate and growth in Adjusted earnings per share at between 8% and 12%. Strong free cash flow generation is expected to fund both ongoing investment in our growth strategy and returns to shareholders, comprising dividends and our FY26 share repurchase programmes of up to £60m. Our medium-term targets remain unchanged.
That is a relatively large range for adj. EPS growth and investors will be wanting to see signs that they can deliver in the upper end of that when the interim results are released next week.
The forecast growth is partly due to an increased take-up of attached gifts from partnerships with major brands. Again, from the recent trading statement:
Average order value is rising at Moonpig and Greetz, reflecting uptake of Moonpig Guaranteed Delivery and gift attach rate growth consistent with H2 FY25. Following on from the successful launch of Hotel Chocolat and the Entertainer in FY25, we expect upcoming trusted brand launches in flowers and gifting - including Laura Ashley Flowers, Next Flowers and JoJo Maman Bébé - to support continued attach rate growth during the key Christmas, Valentine's Day and Mother's Day trading periods.
This is one area where being the market leader helps, as brands are much more likely to want to access the current large customer base of Moonpig. However, with Card Factory having bought Funky Pigeon from WH Smith, they may be facing increased competition from a retailer that also has a significant market share, although this time in physical retail. It will be interesting to see if they comment on the competitive landscape in next week’s results.
RWS Holdings (LON:RWS)
RWS is another stock suffering from negative AI sentiment. The broker consensus has certainly not been kind recently:
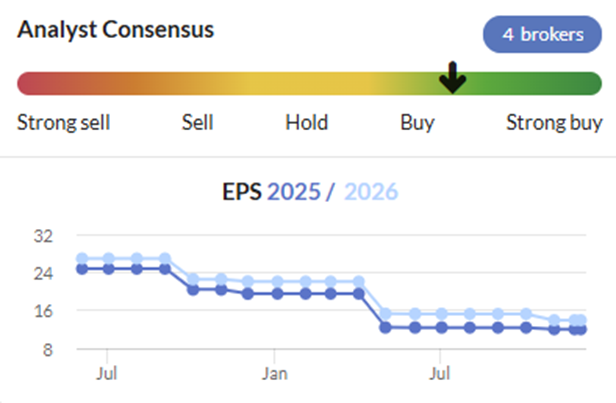
However, it is hard to judge if that is due to AI disruption or simply because, in a poor economic climate, businesses are spending less on marketing and R&D, things that typically require high-quality translation. Whichever it is, this has been reflected in the recent share price:
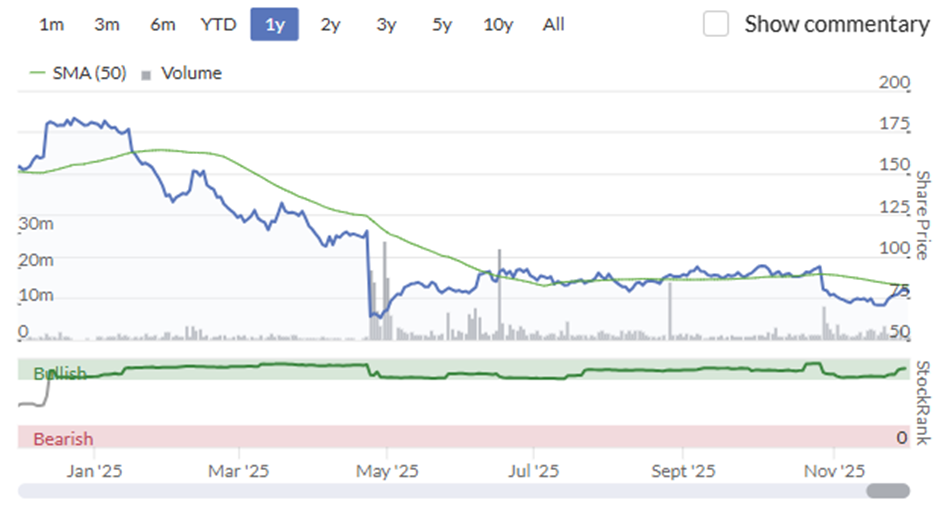
Headline numbers released next week shouldn’t be a surprise. The trading Statement at the end of October said:
The Group expects to deliver adjusted PBT² of c.£60m reflecting a significant improvement from H1 (£18.0m) to H2, as the Group executed the efficiency plan that we announced in June...The Group had net debt⁴ of c.£26m at the end of September 2025 (31 March 2025: £27m net debt).
Adjusted PBT was at the bottom of the previous guidance range, and this news caused the shares to sell off by around 25%. This seemed a little harsh given the current very modest rating:
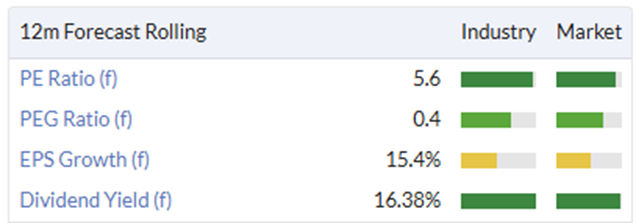
And, indeed, the shares have recovered somewhat since. There are three things I will be looking out for. Firstly, what are the adjustments, and how do these impact cash flow? We already know that recent trading has pushed the company, which is normally highly cash-generative, into a modest net debt position.
Secondly, they promised us an update on their medium outlook with these results:
The implementation of the new strategy we introduced in June 2025 is on track. A major step was the launch of our new organisational structure on 1 October. This structure streamlines how we sell, integrates our product and technology teams and organises our business into three segments: Generate, Transform and Protect. We intend to provide medium-term financial guidance and new performance targets when we release our FY25 results.
Finally, this has a phenomenal record of paying an increasing dividend. This, combined with the share price fall, means it is currently forecast to pay a 16% dividend yield.
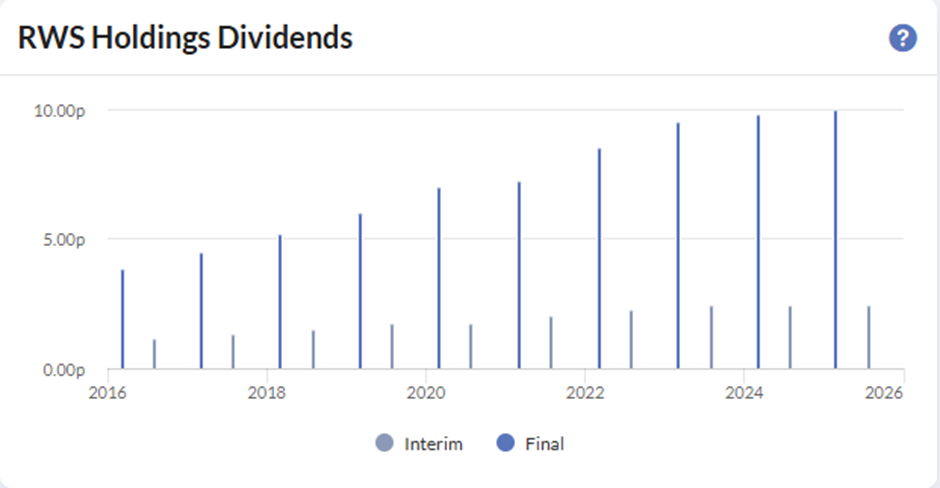
Brokers' forecasts are for a very slight increase in the payout for the full year. If the final dividend declared next week reflects this expectation, then we can expect the share price to respond positively, whatever the rest of the results reveal.
[Disclosure: Mark holds shares in RWS Holdings (LON:RWS) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
For cyclical investors looking at Construction, the S&P Global UK Construction PMI for November was released on Dec 4th.
Perhaps understandably, the mood just prior to the budget was somewhat negative.
https://www.pmi.spglobal.com/P...
Thank you for supplying this report.
I initially believed that given the Government's intention to build 1.5m homes over 5 years that Housebuilding was an attractive sector to invest in. However given that the Housing Sector Index is languishing at a PMI of 35.4 and 50 is required to indicate growth it appears that this sector has gone in the opposite direction. Tim Moore's comments suggest that confidence is at its lowest point for three years.
It is up to the Government to create the conditions whereby Housebuilding can take place. To date it appears that the policy is largely based on wishful thinking and nothing concrete has been done to enhance Housebuilding in the UK.
With so many adult children still living with their parents well into their thirties it appears that this area is ripe for progress but the Government needs to tackle fundamental issues including affordable mortgages, the supply chain and workforce productivity. Increased employers national insurance contributions and increases to the minimum wage have not helped. Housebuilding is also an important component of GDP which incidentally has been negative in the last two months.
I am looking for some help. I wish to make contact with a contributor who is knowledgeable with which AIM shares are/ are not eligible for BPR and hence are/ are not IHT exempt.
Thankyou. KB.
Hi KBR
There is no definitive list - and the shares that qualify can change. You only find out for sure when you die and HMRC make their determination. Also a number of AIM listed shares that did qualify have decided to move to the main market - Gamma Communications (LON:GAMA) and (soon) GlobalData (LON:DATA) for instance. This looks like an increasing trend.
Most AIM shares will qualify but a few categories don't: investment companies, property companies and financial companies mainly. You're best off looking for technology, healthcare, engineering and consumer goods companies. Some, but not all, energy companies qualify.
So it depends, I'm afraid. Plus the rules are changing in April to restrict relief to 50%.
timarr
Hello timarr
Thankyou very much for your response.
You indicate the main 'problem' areas are property/ financial/investment companies.
Do you have any further comment in respect of:
Springfield Properties , Watkin Jones.
Peel Hunt, Cavendish.
Polar Capital , Premier Miton. Impax Asset Man.
Tatton Asset, Mercia Asset.
Duke, Time Finance.
Begbies, MP Marsh.
Thankyou again. KB.
Mr ChatGPT looks and sounds like he is knowledgeable, but I have no idea if he talks with forked tongue...........a very long response was curtailed when I cut & pasted it here, but in summary it said "yes" to Springfield Properties (LON:SPR) & Watkin Jones (LON:WJG) and probably "no" to the rest.
Good question. It’s not possible to definitively say that any given company you list will qualify for Business Property Relief (BPR) — qualification depends on the nature of the company’s activities, not just the fact it’s on a certain exchange. That said: under the (new) BPR rules for Alternative Investment Market (AIM) shares, here's how to think about which of those companies might be eligible — and where there is a potential problem.
✅ Key BPR eligibility principles for AIM shares
Given that, whether each company on your list is eligible depends on whether it’s a genuine trading business (not mainly investing, property-holding, or asset-management for external clients).
The question I posed was....................Which of the following would be eligible for BPR relief on the AIM stock exchange; xxx, xxx, xx etc
Hello KevinS1
Thankyou for your efforts on this and the information you have provided. Very helpful. Thanks again.
KB.
Hi KBR
WIthout being able to be definitive the majority of those stocks won't qualify for BPR as they're primarily investment companies. Springfield Properties (LON:SPR) , Watkin Jones (LON:WJG) and Begbies Traynor (LON:BEG) are probably safe, any of the others you'd need to get professional advice on.
Given the constant rule changes I wouldn't be using BPR on AIM stocks anyway unless I was near end of life.
timarr
Hello timarr
Thankyou very much again for your input; much appreciated.
I take your point on 'near end of life'. A friend says i am already in 'The Departure Lounge'. !!!! I disagree but who knows!!!
KB.
Re: Reduced IHT-liability for some AIM-listed shares: Note that to qualify, companies must NOT be dual-listed (listed also on another Exchange other than AIM) and, as Timarr implies, it must be an operating (trading) company, rather than merely making its living via holding income-generating assets.
Whatever are you thinking of KBR? the facts are that you cannot take it with you and when gone 4 out of 5 heirs will blow what you left behind. There must be more attractive options for you to concentrate on.
COSTCO
Costco has been an amazing company looking after all stakeholders well : the customers first, employee second and shareholders third. I have been happy to be in first and third categories!
Whether or not you think the RICS house price figures are "promising" depends on whether you own a house or not!
Yes, and whether you live in the largest house you ever hope to! It also seems to me that our obsession with house prices in this country crowds out more productive investment, but that's an entire rant on its own!
The Costco writeup is headlined as Costain!
Good spot, thanks. Now corrected.