TheWorks: a destination for consumers looking to escape the digital world
In this week’s Stock Pitch, I’m going to dive back into the pool of ‘Speculative, Super Stocks.’ The focus is on TheWorks (LON:WRKS), which currently commands a StockRank of 94. Here’s what this under-the-radar small-cap name has to offer investors.
[Disclosure: At the time of publication, Ed Sheldon had no position in WRKS.]
- Share price at the time of publication: 109p
- Market cap: £68m
The Pitch
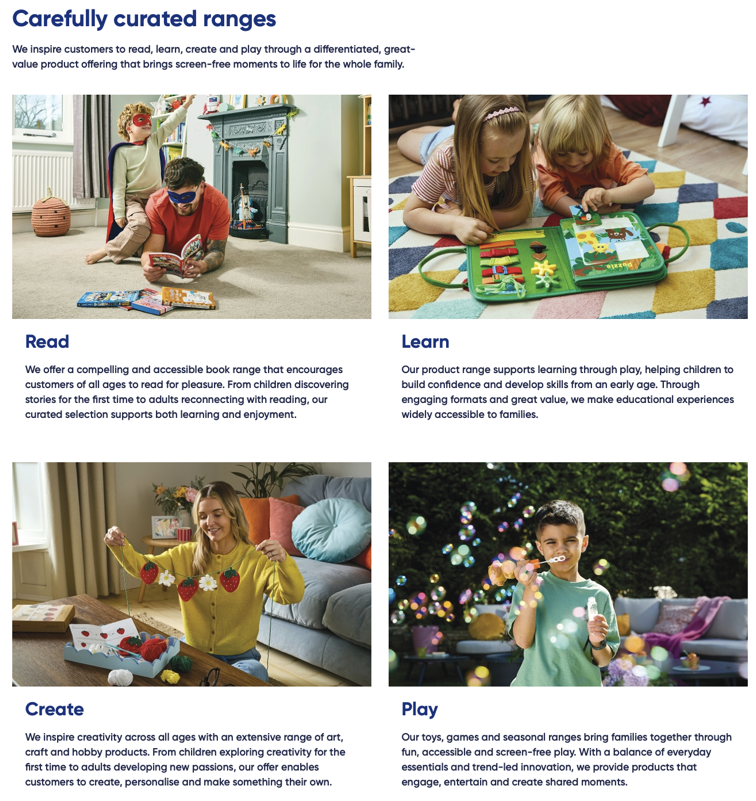
TheWorks is a UK retailer that specialises in affordable, screen-free activities for the whole family. Its goal is to inspire reading, learning, creativity, and play.
Founded in 1981, the company has over 500 stores across the UK today, 98% of which are profitable. Previously, it sold its products through both its stores and its website, however, earlier this year, it made the decision to cease trading of its online channel and transition to a non-transactional website.
The Big Picture
Taking a big-picture view here, there are several things to like:
- Consumers are increasingly looking to escape the digital world: There is a measurable, widespread shift toward screen-free, analogue, and in-person activities, driven largely by digital fatigue, declining trust in algorithm/AI-powered feeds, and a desire for tangible human connection.
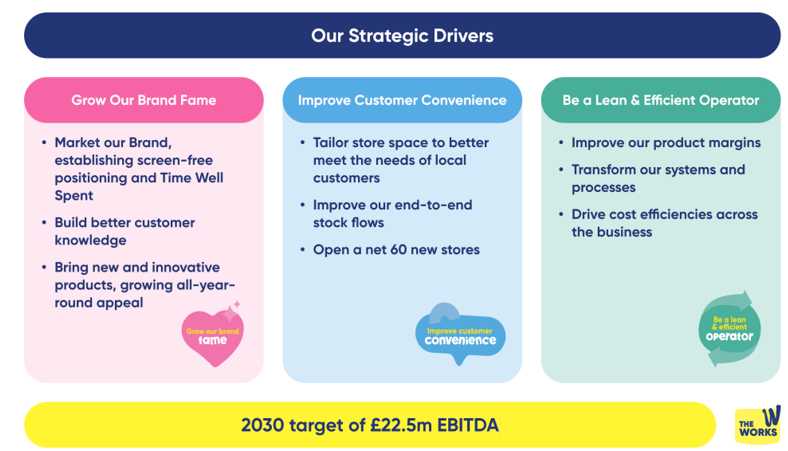
- The company is expanding its store footprint: TheWorks sees the opportunity for a further 100 new stores over the medium term, with a net 10 new stores planned in FY27, and 60 new stores to be opened by FY30.
- It has a five-year strategy to transform the business: TheWorks’ growth strategy, ‘Elevating The Works’, is focused on growing the brand, improving customer convenience, and being a lean and efficient operator. A goal of this strategy is EBITDA of at least £22.5m in FY30.
Going Deeper
This year, TheWorks has posted numerous positive updates.
In March, it advised that it was:
- Upgrading FY27 guidance to pre-IFRS 16 adjusted EBITDA of £15m from previous guidance of £12.7m.
- Ceasing trading of its online channel, to transition to a non-transactional ‘shop window’ website (operational challenges experienced by two different third-party fulfilment partners significantly impacted the online channel's performance for several years, outweighing the progress made) and free up capital for its store expansion.
- On track to deliver its medium-term EBITDA goal of at least £22.5m by FY30.
In May, it told investors:
- It generated like-for-like sales growth of 3.3% in FY26 against the British Retail Consortium (BRC) reported decline of 0.1% for the UK non-food retail market.
- As a result of revenue growth (3.2%), improvements in product margin, and cost reduction programme, it was expecting FY26 pre-IFRS 16 adjusted EBITDA to be approximately £14.0m (FY25: £9.5m), a 47% increase year on year and ahead of market expectations at the time of £13.5m.
“Our outperformance against the broader high-street supports our strong conviction that The Works' brand and product proposition, which is aligned to families' growing demand for affordable screen-free activities, is increasingly relevant and underpins our plans for further growth.”
In September, it advised that:
- During the first 18 weeks of FY27 to 6 September, it saw a 10.4% increase in like-for-like sales (FY26 comparable period: +5.9%).
- It was expecting FY27 pre-IFRS 16 adjusted EBITDA to be at least £16.0m (ahead of market expectations at the time and up from previous guidance of £15m).
More recently, in an H1 trading update on 12 November, it told investors that:
- Total sales from continuing operations increased by 10.1% to £128.8m in H1 (H1 FY26: £117.0m) with like-for-like sales increasing by 9.8% (H1 FY26: 4.0%).
- It now expects pre-IFRS 16 adjusted EBITDA for FY27 to be at least £17.0m (ahead of market expectations at the time).
“We are well positioned as we enter the key Christmas trading period and focussed on giving our customers more inspiration and choice for enjoying Time Well Spent together this Christmas.”
Looking beyond this operational momentum, other attractions of WRKS shares include:
- Decent ROCE: Over the last five years, return on capital employed has averaged 18%.
- Solid balance sheet: The group ended H1 FY27 with £3.5m of net cash (H1 FY26: net debt of £5.3m), driven by increased levels of profit as well as improved stock management.
- Low valuation: The forward-looking P/E ratio is currently 10.2 while the PEG ratio is about 0.6.
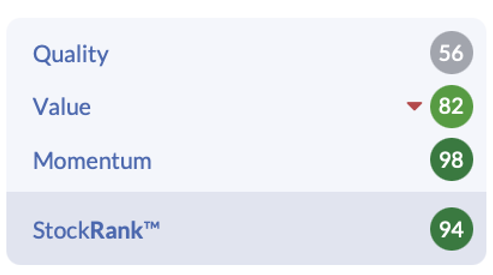
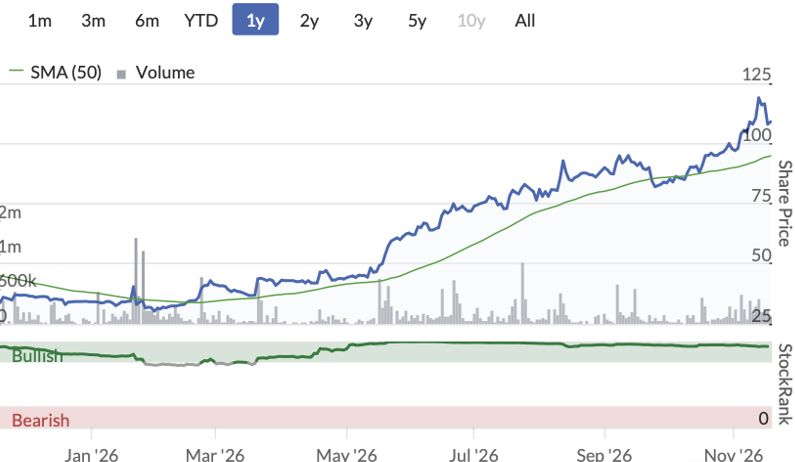
- High StockRank: The StockRank is currently 94.
- Rising share price: The share price is in a strong upward trend.
What the Brokers Say
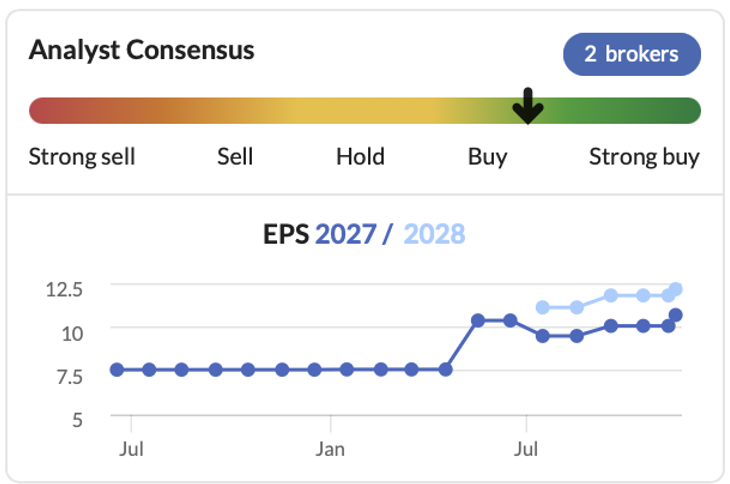
There is not a lot of broker coverage here given the company’s market cap. However, Stockopedia shows:
- An average analyst price target of 134p (23% above the current share price).
- Rising earnings forecasts.
The Bear Case
Risks to consider with TheWorks include:
- Consumer spending weakness: In the UK, high interest rates and mortgage costs threaten to impact consumer spending power.
- Reliance on high street footfall: Now that the company’s website is no longer transactional, TheWorks is more exposed to high street footfall patterns.
- Competition: TheWorks is competing against online retailers (Amazon*, eBay), supermarkets, general discounters (B&M, Poundland), and specialty retailers (Hobbycraft, Waterstones).
- Rising costs: Margins are low (Pre-IFRS 16 adjusted EBITDA margin in FY26 was only 5.4%) so increases in costs (freight, labour, leases, etc.) could impact profitability.
- Modest cash buffer: Cash and cash equivalents as at 3 May were only £3.6m.
The Bottom Line
Recent updates from TheWorks show that the retailer is performing well at present. Growth is accelerating and profit forecasts are rising.
There are risks around consumer spending, costs, and competition. Yet with the stock trading at an undemanding valuation, there appears to be scope for further upside.
[*Disclosure: At the time of publication, Ed Sheldon had a long position in Amazon.]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
6 comments
Thank you for the write up. I was sceptical of TheWorks (LON:WRKS) when buying as part of a VM Screen portfolio on 1 July, using NAPS like rules. Since visited the shop and added 3 times! Sentiment is (thankfully!) with them and they have some real bargins, stationary is good value and things like Sudoko books excellent. Momentum is great, impressive number of "ahead" announcements, growing LFLs and the best season ahead for them. I am a fan!
Thanks for sharing your experience Muzzer!
I have seen research for Works Media (LON:WKS^D11) over the last couple of years.
I was tempted so decided to go into one of their shops.
To me it was totally unorganised, just cram as much as you can into a tiny shop.
There were a few people in but they couldn't browse as people had to squeeze past them
So for me it still is a no.
For those that do buy or hold maybe I am wrong
I can spell just can't tpye
I meant TheWorks (LON:WRKS)
Having 6 grandchildren and 5 greatgrandchildren I hope this company does well, I've watched the harm too much phone and screen time can do. Thank you for this post Ed, I think our constant use of Amazon might be helping your shares, albeit it's of course in some conflict with TheWorks admirable mission. Well done Felix, we might join you.
Thank you for an insightful write-up of TheWorks (LON:WRKS). It's just further cemented my conviction in what has been one of my best performing shares this year.