Trading the Trend - Stage 2 Kings

There are many ways to skin a cat in the stock market, but one of the best ways to do so has been to find an early stage 2 stock and ride it upwards.
If you’re an investor – it doesn’t matter how undervalued your stock is – to realise a gain on that investment the market needs to notice and then narrow the value disconnect.
This is often one of the complaints of the value investor. There is comfort in the margin of safety, but it can be a lonely wait.
In the recent decade, momentum has trumped everything. And more than momentum – a good story.
This is why companies like ITM Power have a market cap of over £1 billion. Total income in its half-year report was £3.8 million, of which only £2.4 was revenue, and £1.4 million was grant income!
I’m no great investor but it doesn’t take a Warren Buffett to see that the share price may be rich and much of its potential success could well be priced in.
But as much as anyone wants to crow about how it can’t last – the real winners have been ITM Power’s shareholders.
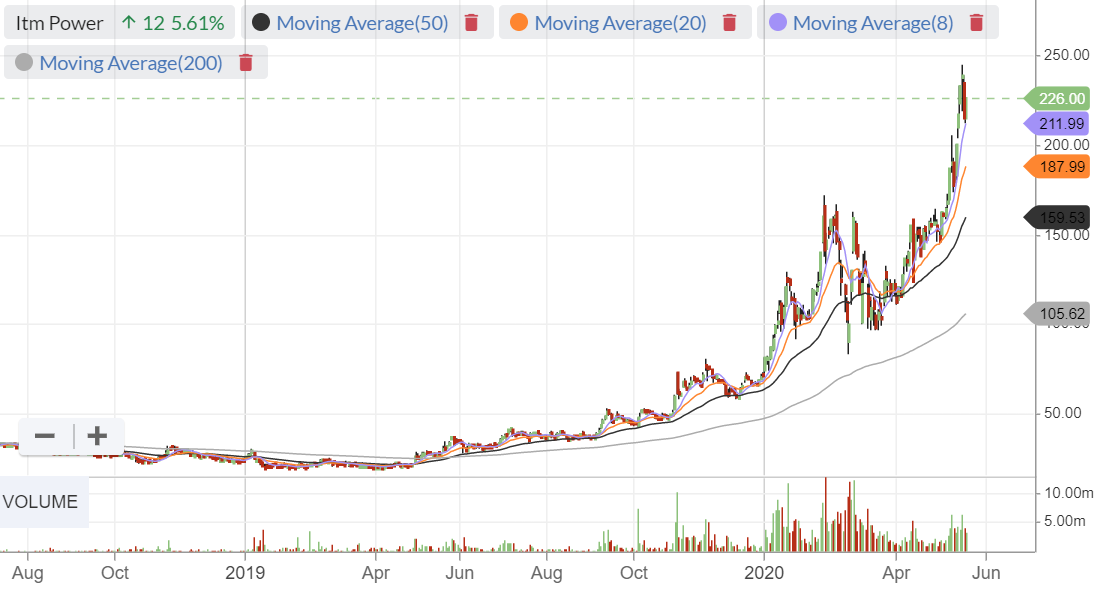
Here’s a chart of ITM Power since 2019. It’s surged from 25p to a high of 240p. This chart alone explains why trading stocks that are in stage 2 is a great strategy. It’s one that has been employed by Weinstein, O’Neill, Minervini, and countless others.
Identifying stage 2 stocks early is a key ingredient to stock market trading success, as these stocks offer plenty of breakout opportunities to trade or even average up.
Nearly three years ago now, I bought my first shares in Future Group. I believed it had a scalable business model, and it had nearly trebled from the lows and so the stock was clearly in a stage 2 uptrend.
I was sadly stopped out of my last lot when some chap across the pond had a pop at Future and derailed the price, and the stock has gone one to post even bigger gains.
There may be a lot left in the business, but it’s certainly better to be buying closer to the start of the move than after the move is well-documented. It’s fine to be late to the party – the price was up nearly 200% before I bought my first share – but don’t overstay your welcome.
I like to nail down profits into strength, and my stops take care of the rest. When the fish are biting – keep feeding.
No longer Majestic
One stock I bought recently that I did not think I’d ever own is Naked Wine. It’s the old Majestic Wine that I believed to appear to be a bunch of boring wine warehouses that struggled to actually make any money.
As it turns out – it did struggle to make money, and Majestic Wine has now been sold off with management going all in on its small online subscription brand of Naked Wines.
Majestic Wine started as a disruptor to the industry. Management now intend to do it again with Naked Wines.
Recurring revenue model
One of the benefits of a focus on Naked Wines is that it is a scalable online business model; a pure play retailer. Instead of carrying the burden of large fixed costs, Naked Wines has the biggest potential to deliver value to shareholders on account of larger addressable markets and by virtue of its rapid growth in the US.
Success is measured in various factors. Sales to new customers (naturally), the investment in new customers, the life time return of this investment, repeat customer sales, repeat customer sales retention, and the repeat customer contribution.
Is the model defendable? Anyone can create an online wine subscription, right?
They can. But Naked Wines funds independent winemakers, who produce exclusive wins at preferential prices. The company then uses economies of scale to pass on the savings to customers.
The competitive advantage here is that the model (in theory) delivers better wines for cheaper prices. For wine lovers, there’s a story – support winemakers to produce great wines.
Key drivers of growth in the business
Naked Wines intends to grow its customer base, but already it is seeing customers spending more each year.
Customer investment is now being hiked up by £5 million from £14.1 million to £19.1 million in order to drive future growth. The company says that its investments are generating a payback of 4x showing an attractive return. However, the company thinks it can go even faster. It wants to continuously increase investment in order to dramatically increase future contribution and value.
This is because the customers have high loyalty value to Naked. The business also tests everything, and lets data lead the way. Every quarter the best performing investments are doubled up on and the worst performers are cancelled.
Strength in stock price
In recent weeks WINE’s stock price has surged and nearly doubled.
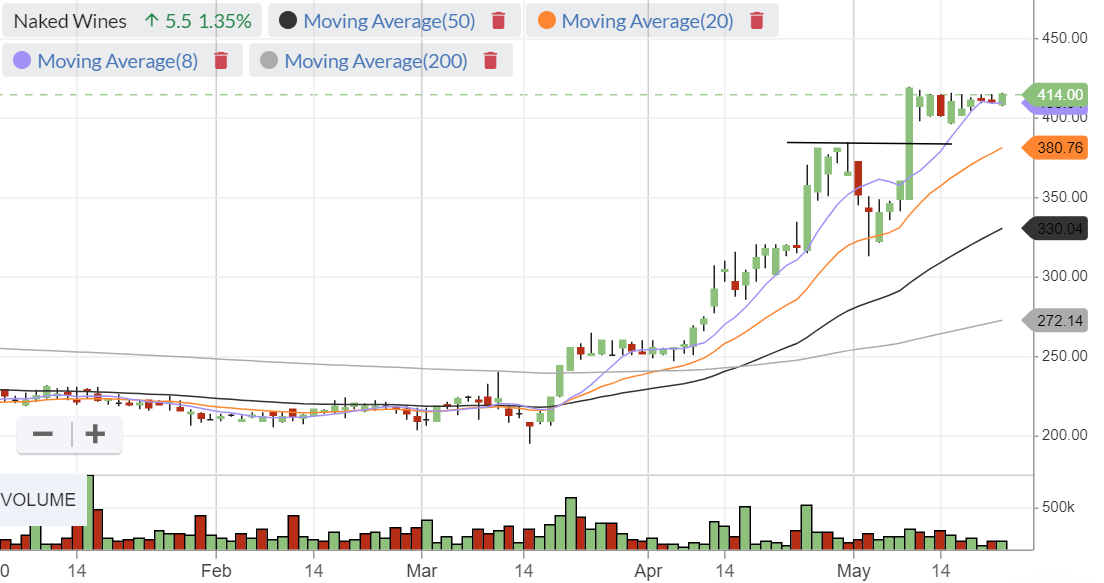
I am now long from 380p having bought the breakout of the recent high. I’m running a wider stop on this position and would exit around 315p. The reason for this is because the stock is strong, and I realise a large run up is likely to have a volatile pull back at some point, and also because my position size is small for now.
Ideally, I want to scale it up. There is a clear fundamental reason for the drive in the share price as the business has shed the Majestic brand, and is now a fully focused machine intent on creating value by scaling up Naked Wines. I want to add to this position if the opportunity presents itself.
It is my opinion (although I am prepared to be wrong and cut my losses as this is a trade for me only) that there is significant upside in the business if:
Naked Wines can continue to generate 4x payback on investment
Loyal customers remain loyal and average spend stays high
Update on recent trading
Covid-19 does not appear to have impacted WINE negatively at all.
“Since restrictions on social gathering began, we have seen higher levels of demand from both new and repeat customers in all of our markets, particularly in the US, and as a result we are finishing the year with good momentum and expect revenue for FY20 to be in excess of £200m, which is slightly ahead of current consensus1. We have continued to invest aggressively in new customer recruitment and now expect our total investment for FY20 to be towards the middle of the £20-25m range we indicated with our interim results, with our key payback measure being above our 4x target.”
Revenue is growing better than forecasted, and more importantly the payback measure is above the company’s 4x target.
Valuation
In fairness, the valuation here leaves a lot to be desired. In FY20 Naked Wines is projected to make £0.9 million in post-tax profit.
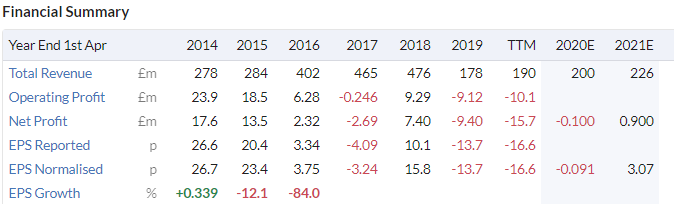
At the current market cap, that means a PE ratio of over 300.
Granted, those expectations can always be beaten, but one could argue that the valuation for the business is richer than the wines that it produces.
But when has valuation ever mattered?
You can download your free copy of Ten Habits of Highly Profitable Traders from Michael’s website at www.shiftingshares.com
Twitter: @shiftingshares
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
17 comments
There is an interesting development in the US where Naked is looking to grow, Constellations Brands $STZ has just bought Empathy Wines, a similar proposition to Naked although only founded last year.
I have taken some of my profits on Naked. I see more upside elsewhere. I have switched to Motorpoint and Ally Financial (US online bank).
Thanks for the article. I am right in the middle of one of Mark Minervini's books where he talks about stage 2 stocks. For me it makes sense, good companies with potential showing significant momentum on volume. I can't analyse a balance sheet as well as others but can apply logic. Increasing revenues and earnings accompanied by a breakout equals a good entry point for me. If company reports are bullish then it is worth considering. Ultimately a stop loss generally will protect and provide confidence to ride the wave. Easier said than done but a skill that can be replicated many times over when honed.
This looks to me like a post-lockdown short back down to 320
It is a really interesting story for Naked Wine. The Direct-to-Consumer wine market in the US is enormous. The wine distribution model is also interesting and naked Wines strip out a lot of the middlemen. They consider themselves to be like Netflix in that they create 'original content'.
I think they have huge potential to continue growth. Looking at the TR-1's there are some high profile investors that feel the same way.
An important factor is that the main cost is marketing for new customers. If this was suspended the profits from existing customers would be much higher. This is where the value is.
It is CamRaid - hence why I am hoping I can ride the trend upwards. I don't mind holding overvalued stocks so long as I'm with the trend. Very few posts on the bulletin boards too - surprising given that it's been one of the year's top performers so far.
Thanks for this. I was hoping someone would cover Naked Wines (LON:WINE) but I didn't like to ask. :-)
Feel free to request!
It was a bit of a joke. I did ask a few times which resulted in my post getting a pile of negative marks. I didn't mind. I was sitting on an 80% return so while I was a bit disappointed I was smugly disappointed. :-)
I have seen a couple of write ups saying this could go to £6 and even £10.
Majestic Wine did not struggle to make money, you may need to revisit historical RNS statements.
You're right Jeremy - I thought I recalled a recent profit warning though I think that was four or five years ago now. Next time will check before assuming!
I am a simple investor, new to Stockopedia, and always like to know as much as possible about the companies I invest in on the ground.
Majestic bought Naked in 2015 and this enabled them to develop Naked's smaller but rapidly growing on line business. This has been their success strategy in the US and now Australia.
. Majestic had 640,000 customers and Naked 300,000. Majestic have more than 100 retail outlets in the UK, usually very low cost simple, no frills warehouses. Their staff are all graduates who know and understand their products which is why they retain customers so well. This year is perfect for the "stay at home" holiday as sales of wine to private customers are doing extremely well and lower margin hospitality sales have dried up.
I do see Naked as a momentum trap with "deteriorating fundamentals and stretched valuations" to quote Ben Hobson's excellent article "Momentum Traps - how to avoid the siren song of overhyped stocks." This has a great wine analogy as well!
But momentum traps can be great sources of short term profits, Reckitt Benckiser are a classic example with some poor fundamentals but their share price has advanced 11% over the last month on the back of worldwide demand for cleaning products such as Jeyes and Dettol. When Trump suggested that bleach might be injected into us to kill Covid 19, allegedly, it was RB who went public with "do not try this at home." The share price went + £2 that day to over £70 and I am targeting £80 by end July. That will be time to take the profit.
I think the valuation is stretched definitely, but it seems to me the company is growing.
Momentum is definitely a potential indicator of short term profits - in my earlier articles we looked at the Momentum factor as a way of finding uptrending stocks to trade breakouts from.
Naked Wines is at 95 on the Momentum rank.
Well done on the Reckitt trade!
I don't understand why it (NW) is still ranked a momentum trap by stockopedia
Hi Simon. Stockopedia automatically classifies all shares based upon the values for the Q, V & M ranks. High values for M, and low values for Q & V are classified as momentum traps. There is a lot of information in the "Learn" section about how the stock ranks are calculated, and how this is then used to put the share into a particular classification.
Dear Michael.
As ever your articles are extremely good and your style of writing is both entertaining and informative.
Whilst I know very little about charts, your detailed analysis on the companies you highlight is so compelling , such that to me ,it’s clear there is more to charts than most investors appreciate.
In addition ,your recents results highlight that you are constantly casting your fly into deep waters full of big fish, ready to strike....but as you have explained in your books ( which are excellent) even if the fish gets off the hook before you land them, your exit strategy ensures you have saved your tackle to get fishing again.
I write as a fisherman, really only interested in catching and landing big fish...I have met many fisherman technically far more superior to me...however, they regularly caught fewer and less big fish....for one simple reason, they simply refused or were unwilling to listen to their more experienced river guide...he knew about the river, the flies needed and where the fish were resting....you are like a great river guide and I believe many on these pages can learn so much from you Michael.
I wish you wrote more on these pages...
Thank you.
Tony - thank you very much for your kind post.
I do believe that charts provide an edge for the investor (though I am a trader and not an investor). The goal of both traders and investors is to make money, and whilst an investor may be holding for years, getting a better entry into a position can make a significant percentage different in profit.
For example, rather than buying and averaging down into stage 4 stocks - why not wait for the accumulation to appear that can be spotted with increasing volumes and the stock price flatlining and being supported? Or even better, buy once the stock starts advancing into stage 2. However, everyone is different and my way is not the best way - it's just my way.
Your analogy of fishing for risk management is excellent - yes, I am very protective of my capital having realised how much you can lose by complacency and leverage.
It's not an experience I would wish on anyone, as it give my crippling chest pain, a constantly tense stomach, and sleepless nights. I was so anxious by my losses I was in a paralysis where I didn't sell either as everything went down further. But that experience served me well, as this crash has provided the best market for trading in my career so far - and if I had blown my account or lost a significant chunk I wouldn't have been able to take advantage.
If you can guard your capital fiercely, and stay in the game, then you can win. The market is inherently bullish. Anyone can make money in a bull market - if you can avoid blowing up then you stand a high chance of success.