Ultimate Products: solid outlook as new CEO takes reins

Analyst’s view:
On balance, I'm inclined to raise our stance on this share by one notch today. It's a low-margin business but I believe that its core brands do benefit from consumer familarity and trust. On top of that, the stock is cheap and the balance sheet is only modestly leveraged. As such, let's nudge up our stance on it to AMBER/GREEN.
Up 5% at 47.4p (£40m) - Audited Results for the Year Ended 31 July 2026
Ultimate Products is "the owner of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872)".
These results for FY July 2026 are not very pleasing to the eye but as always, markets are forward-looking.
Key points from the results:
Revenue down 3% (£144.9m)
Adjusted EBITDA down 20% (£10m)
Adjusted PBT down 28% to £6.3m
Excluding adjustments, the statutory PBT figure comes in at a respectable £5.1m.
Net debt improves to £8.6m (last year: £14.1m), with a modest leverage multiple of just 0.9x. This includes the benefit of lower stock levels.
Echoing the sentiment in today's Shoe Zone update, there was "subdued consumer demand for general merchandise".
However, that doesn't tell the whole store: there was strong growth in international branded sales (up 20%), helping to offset the decline in UK branded sales (down 7%).
The company's new CEO started this week, "bringing extensive leadership, operational and commercial experience". He spent many years at Coca-Cola Europacific Partners (LON:CCEP) before joining Princes (LON:PRN) where he rose to become CEO.
I'm a little puzzled as to why he left Princes (market cap over £800m) to join Ultimate Products (market cap £40m) - it would be helpful to understand his motivation. At the time of his appointment to Ultimate Products, he described it as "an exciting personal opportunity".
Current trading and outlook: in line with expectations.
The outlook statement doesn't give too much away:
Whilst the current backdrop of subdued consumer demand and geopolitical uncertainty continues to persist, the Board is confident that the ongoing investment in the Group’s operational capabilities and commercial function will position the Group to maximise future growth opportunities.
The CFO says:
“FY26 was a year of important strategic progress for Ultimate Products against a challenging consumer backdrop. Our proprietary brands continued to grow, particularly across our strategically important international segment, while we took the difficult but necessary decision to exit third-party clearance. This has sharpened our focus and reinforced the central role our proprietary brands will play in the Group’s long-term growth."
Estimates: thanks to Equity Development for covering this stock today. They see EPS of 5.4p this year (FY July 2027) rising to 6.4p the following year.
Based on the current share price, that impies the PE ratio will fall from about 9x to about 7.4x, if estimates are hit.
Graham's view
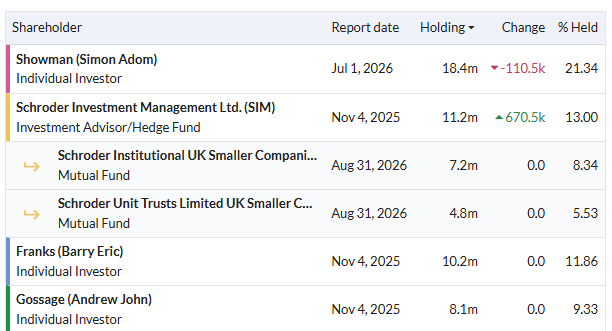
The key story here is about leadership transition, as two long-standing executives (Simon Showman and Andrew Gossage) have now both moved into non-executive roles. They previously ran Ultimate Products together since 2005. Simon Showman founded the company back in 1997.
They are also important shareholders: Showman owns 21%, and Gossage 9%.
On balance, I'm inclined to raise our stance on this share by one notch today.
It's a low-margin business but I believe that its core brands do benefit from consumer familarity and trust.
On top of that, the stock is cheap and the balance sheet is only modestly leveraged.
As such, let's nudge up our stance on this to AMBER/GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Ultimate Products (1)
Comments here are also visible in the Daily Stock Market Report
I am concerned why Shoe Zone (LON:SHOE) warned today on rising container costs and Ultimate Products (LON:ULTP) did not. I perceive risk that if rates are rising that this may impact ULTP before long also. Perhaps one to keep an eye on?