Victoria plc - trading ok and bondholders not pulling the rug out

Analyst’s view:
Our stance on this financial fiasco will remain fully negative for the time being, but it should be instructive to see how it is eventually resolved. I am still betting that more dilution will be needed in order to fully stabilise the company. While I've written very negatively in the past about Victoria's approach to leverage, I am surprised and impressed that existing shareholders have not already been diluted to a much greater extent. Investing in the discounted bonds could be an interesting investment idea, rather than investing directly into the equity.
Up 6% at 40.95p (£47m) - Graham
Victoria PLC issued its H1 trading update this morning, along with formal consent requests to bondholders as it works to refinance its debt.
It "continues to take market share in the UK, North America and Australia businesses despite end market pressures.".
Some highlights for the period to the end of September:
Organic revenue growth 5%
H1 EBITDA is "slightly ahead" of the result in H1 last year, excluding the impact of Balta (the rugmaker that has been relocated to Turkey).
H1 EBITDA including Balta is £3.8m behind last year.
For context, H1 underlying EBITDA last year was £53.5m.
The relocation of Balta has now completed and it is expected to hit target production volumes before the end of the financial year (FY March 2027).
Input prices have risen, which is not a surprise:
Oil and gas related input prices have risen rapidly in recent months. Pricing and cost saving initiatives are mitigating the impact, but the Board notes the potential negative impact of higher input prices should they persist.
Comment from Exec Chairman Geoff Wilding:
"Operational progress has been strong this year with sales initiatives growing market share, improved factory productivity, and lower overhead costs. It is frustrating that the sharp rise in energy and raw material costs are masking much of the improvement, but we are focussed on securing price increases and additional efficiencies to compensate, and I am confident in the direction of travel.
Refinancing update - bondholders owning the 2028 notes are now being formally asked to consent to the proposed refinancing.
Graham's view
Net debt at the last full-year results looked like this: £1,456.7m, of which less than £200m related to leases.
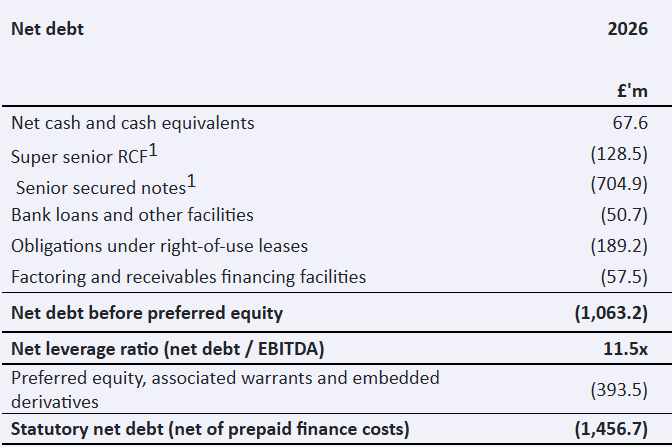
As we discussed here in September, the proposed refinancing is of enormous benefit to shareholders, and this net debt figure has been moving downwards.
For a start, the preferred shareholders have already taken a huge hit, in exchange for equity.
As for the 2028 noteholders, their bonds are trading at 27 cents on the euro (source: Deutsche Borse), and they are understandably quite amenable to a deal.
Most of them have already agreed to exchange their bonds for 12% notes maturing in 2031. These new bonds are "PIK notes", i.e. they pay interest in the form of more bonds, rather than in cash.
Bondholders who agree to this deal will receive €750 of new PIK notes in exchange for every €1000 in face value of 2028 bonds that they exchange. They will also receive new shares so that, in aggregate, they own 19% of Victoria's diluted share count.
While I've written very negatively in the past about Victoria's approach to leverage, I am surprised and impressed that existing shareholders have not already been diluted to a much greater extent.
The Victoria share count is currently about 114 million: I think 68 million new shares are being printed for the preferred shareholders, and then I estimate that there could be another 42-43 million new shares printed for consenting 2028 bondholders. So the share count will approximately double and the company will still be very highly leveraged. But to my eyes, the outcome could have been much worse.
Our stance on this financial fiasco will remain fully negative for the time being, but it should be instructive to see how it is eventually resolved. I am still betting that more dilution will be needed in order to fully stabilise the company. Investing in the discounted bonds could be an interesting investment idea, rather than investing directly into the equity.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Victoria (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?