Vodafone H1 revenue up 11% from acquisitions and stronger growth, but profitability remains challenging

Analyst’s view:
Much of the information needed to support today's upgraded guidance had already been factored into consensus forecasts, which I expect to be largely unchanged. However, I'm encouraged by stronger revenue growth and stable margins and don't see any reason to alter our broadly positive view.
Down 1% to 116p (£27.1bn) - Half-Year Results
The key headline from today's results is that Vodafone has upgraded its profit and free cash flow guidance for the current financial year. However, the reality seems to be that consensus forecasts were already within the new guidance range, so the upgrade to market expectations may be less than suggested.
I'll return to the outlook in a moment, but first I want to take a quick look at the key points from the company's half-year performance.
These are the numbers the company wants investors to focus on - and they do indeed represent progress:
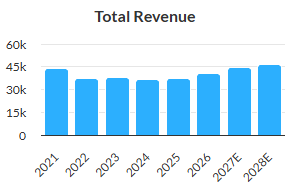
Revenue up 4.7% to €19.6bn
Organic service revenue up 5.8% to €16.3bn
Adj EBITDAaL up 6.4% to €5.7bn
A return to positive revenue growth has been a key element in the group's recovery and improved profit performance:
However, regular readers will know we are not generally fans of adjusted EBITDA-type measures, especially for capital-intensive businesses like this one.
Scrolling further down the accounts highlights the reason for this. The company booked €4.5bn of depreciation and amortisation charges on its asset base during the period and paid €1.2bn in financing costs.
Estimating operating profit on an underlying basis gives me a figure of €2,367m, which is 9% ahead of the £2,162m reported last year. That's equivalent to an H1 operating margin of c.11%, unchanged from last year.
Unfortunately, reported profits for H1 were complicated by two large, non-cash accounting items:
€4.85bn impairment of Germany business, due largely to higher German bond yields;
€3.0bn non-cash accounting gain relating to the consolidation of Safaricom.
Netting these off gives a reported operating profit of just €517m, leading to an H1 pre-tax loss of €373m.
Divisional performance
CEO Margherita Della Valle has made good progress with Vodafone's turnaround and restructuring but admits that Germany remains a challenge:
I am very happy about our overall Group performance, but Germany is not yet where it needs to be. We have a clear action plan in progress, which is structurally simplifying our German operations and improving customer satisfaction across all of our services.
A quick look at divisional performance shows how this business is split into two streams, with rapid growth in Africa and fairly dismal performance in Europe:
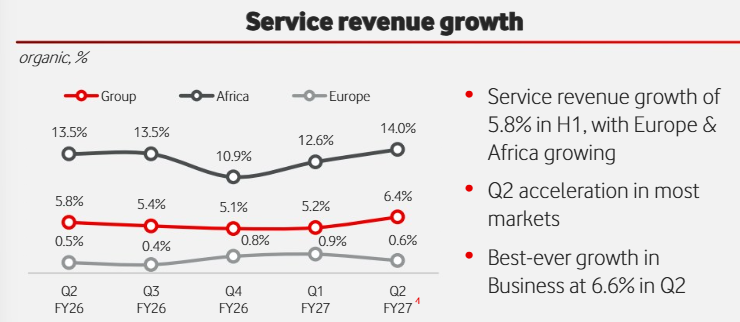
Africa was Vodafone's second-largest profit contributor in H1 and is now only slightly behind Germany, previously the group's largest market (all figures are H1 27 adj EBITDAaL):
Germany down 2% to €2,139m
Africa up 53% to €2,058m (+18% organic growth)
UK up 11% to €984m
Other Europe down 8% to €772m
Turkey up 9% to €531m
Africa is was the group's most profitable region in H1, with an adj EBITDAaL margin of 37.9% compared to 35.3% for second-placed Germany.
Growth metrics for the African business are remarkable and highlight the structural opportunity in this area. The company's mobile subscriber base in the region has risen by 12% to 255m over the last year, while organic service revenue grew by 14% in H1.
Vodafone's African markets are still digitising and are also benefiting from rapid growth in demand for the mobile money services provided by the company's M-Pesa subsidiary. I expect this to become the most profitable part of the business in the not-too-distance future and I see this division as a key attraction for investors.
Business: "best-ever growth": one highlight from today's results is a 5.8% increase in business service revenue.
Business revenue is included in reporting for each geographic segment, but checking the footnotes shows that total business revenue rose by 11% to €4,413m in H1 - around 20% of total group revenue.
Germany: Della Valle is keen to flag some small wins in Germany. Service revenue rose by 0.4% in H1 and the company says that mobile performance improved across all brands. However, Vodafone continued to lose broadband subscribers during the half year and also faced pressure on average revenue per user (e.g. pricing pressure) in both mobile and broadband.
I think it's fair to say Germany remains a drag on growth. I was hoping for slightly stronger numbers for this region today.
Outlook & Consensus Estimates
Vodafone headlines today's results with a "FY27 guidance upgrade":
FY27 adj EBITDAaL now expected to be €13.2bn to 13.4bn (+1% at the midpoint versus €13.0-13.3bn previously)
FY27 adj free cash flow now expected to be €2.8bn to €3.0bn (+5% at the midpoint versus €2.6-2.9bn previously)
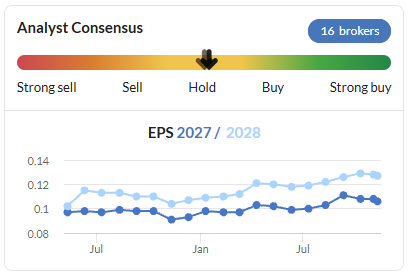
The problem is that this information already seems to have been factored into analysts' forecasts. The consensus estimates available on Vodafone's website for October 2026 already fell into the revised ranges:
FY27E adj EBITDAaL: €13,284m
FY27E adj free cash flow: €2,836m
This morning's share price fall suggests to me that markets aren't expecting a meaningful upgrade to consensus.
Roland's view
A good part of Vodafone's improved performance reflects corporate activity over the last year, rather than any increase in underlying organic growth. For example, today's statutory revenue was boosted by full ownership of Three UK and the acquisition of Safaricom and Telekom Romania for the full period.
Largely for this reason, my impression is that most of today's upgrade was already known to analysts and priced into consensus forecasts.
My main concern is that improvements to profitability are taking longer than (I) expected to be delivered.
Vodafone's own adjusted measure of return on capital employed for its controlled business fell by 0.5% to 6.7% in H1. I don't know what the group's cost of capital is, but I would guess that it's c.8%, so my assumption is that this business is continuing to struggle to generate real economic returns.
My hope is that the FY27 results will show more positive progress in this area, as guidance implies a modest H2 weighting to profits.
For now, I'm happy to to leave my previous broadly positive view unchanged. Turning around a supertanker-sized business like Vodafone isn't a quick process. Plenty of other businesses in this sector are struggling with similar problems.
I remain impressed by the progress Della Valle has made since taking charge and excited by the potential in Africa. Closer to home, achieving the consolidation of the UK mobile market to three operators is a real milestone, in my opinion. I believe it should support higher returns over time.
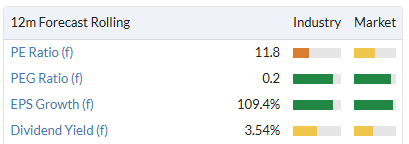
Vodafone's valuation doesn't seem too unreasonable to me, either, on a medium-term view:
I'm staying AMBER/GREEN today.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Vodafone (2)
Comments here are also visible in the Daily Stock Market Report
Vodafone (LON:VOD) positive H1 FY27 results today driven by growth in Africa. Europe still struggling for growth. European operations to be improved through increased efficiency (AI) cost savings (redundancies) forecast.
"Today, we are upgrading our guidance for both profit and cash flow for the year, and we now expect to deliver over 20% organic Adjusted Free Cash Flow growth in year one of our multi-year double-digit cash flow growth trajectory.”
Your thoughts would be appreciated.
Morning Revs8,
Vodafone (LON:VOD) is on the list this morning!
Roland