Watches of Switzerland Group: A Play on the Top End of the K-Shaped Economy
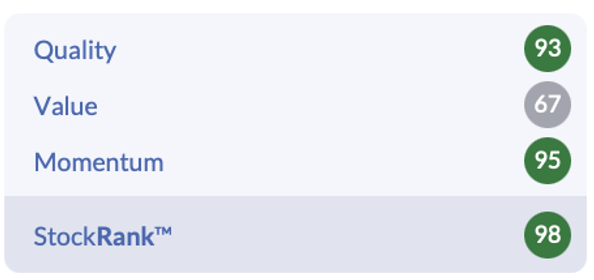
In a recent article, Ed Croft highlighted the potential of ‘Speculative Super Stocks’. Between April 2013 and September 2026, this group of stocks delivered superior returns within the UK market. Given this interesting finding, I thought I’d cover one of these stocks in this week’s Stock Pitch. The company in focus is Watches of Switzerland (LON:WOSG) , which currently sports a StockRank of an eye-catching 98.
- Disclosure: At the time of publication, Ed Sheldon had no position in WOSG.
- Share price at the time of publication: 708p
- Market cap: £1.6bn
The Pitch
Watches of Switzerland Group is a UK-headquartered luxury watch retailer. Operating in the UK, Europe, and the US under a range of brands – including Watches of Switzerland, Goldsmiths, and Mappin & Webb – it sells watch brands such as Rolex, Patek Philippe, Omega, Cartier, Tudor, and TAG Heuer.
Geographically, the US is the company’s most important market – it’s a core driver of expansion and now contributes more than half of total group sales. In terms of watch brands, Rolex stands as the retailer's most dominant partner, single-handedly accounting for around half of total revenue.
The Big Picture
Zooming out and looking at the big picture, Watches of Switzerland Group has three main things going for it, in my view:
- The affluent consumer in the US has money to spend: The US has more affluent consumers than any other country in the world (24 million individuals with a net worth of over $1 million in 2025). Fuelled by record equity markets (the ‘wealth effect’), generational gains in mega-cap tech stocks, lucrative corporate compensation packages, and IPO wealth, these consumers continue to spend money on luxury goods.
- Demand for Rolex remains sky-high: For around five years now, virtually all Rolex models have required a waitlist. This high level of brand-specific demand is a major plus for Watches of Switzerland given that it’s a key Rolex distributor.
- The company is diversifying its revenue base: Luxury jewellery, pre-owned watches (including the Rolex Certified Pre-Owned programme), and ecommerce are growth drivers for the group. Together, these accounted for 24% of group revenue in FY26 and management expects these categories to continue to outpace overall group growth going forward.
“The US offers significant opportunity for both market share gain and structural market growth, supported by a luxury consumer increasingly allocating discretionary spend to watches and jewellery.”
- Watches of Switzerland Group FY26 results
Going Deeper
Recent results from Watches of Switzerland Group have been solid.
In July, the company posted total revenue of £1,828 million for FY26, up 13% year on year at constant currency, with US revenue of £927 million, up 24%. Group adjusted EBIT was £155 million, up 6%, while free cash flow was £162 million versus £98 million in FY25.
In terms of guidance, the company said that it is targeting 5-10% revenue growth for FY27 along with 40-80bps adjusted EBIT margin expansion from FY26.
More recently, in September, the company said that performance during the 17 weeks to 30 August 2026 remained consistent with the positive trends reported in its FY26 results, leaving the company well positioned to deliver on its FY27 guidance. It noted that trading in the US had remained strong with its strategic growth pillars of luxury jewellery, certified pre-owned, and ecommerce contributing good, diversified growth across the group.
Looking beyond this operational momentum, attractions here include:
- Low P/E ratio: The shares currently trade on an undemanding forward-looking P/E ratio of 12.6.
- Low PEG ratio: Given that earnings per share are projected to rise 13.7% this financial year, the PEG ratio is only 0.92.
- Solid ROCE: Over the last five years, return on capital employed has averaged 14.5%.
- Strong balance sheet: Net debt at 3 May was only £57 million (down from £96 million in FY25).
- Insider buying: On 21 September, Non-Executive Director Paul Edgecliffe-Johnson purchased £50,000 worth of stock. Note that Paul has served as CFO of Rentokil Initial, Flutter Entertainment, and InterContinental Hotels Group, and was also an Associate Director in Corporate Finance at HSBC.
- Takeover speculation: In July, it came to light that talks over potential offers to take the company private had taken place.
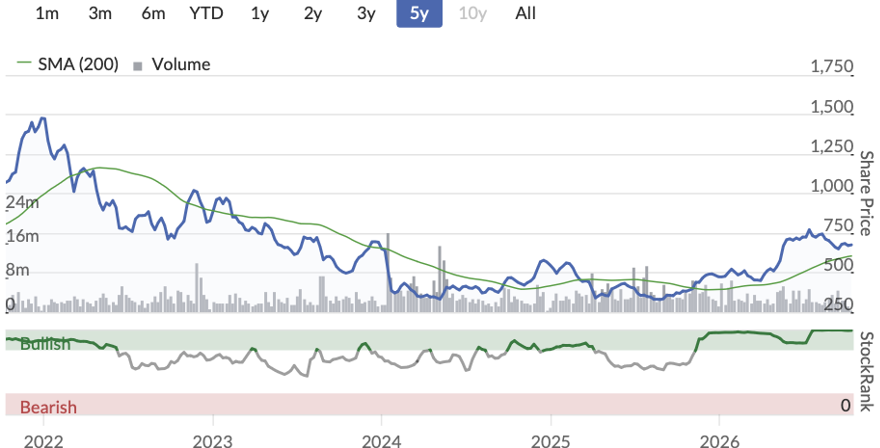
- High StockRank: WOSG currently sports a StockRank of 98.
What the Brokers Say
Brokers are generally bullish on the stock:
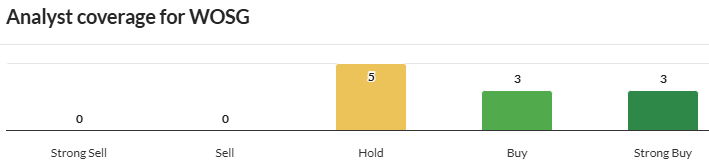
- Multiple Buy ratings: Of the 11 brokers covering it, three have Strong Buys, three have Buys, and five have Holds (which leaves some room for upgrades).
- Bullish price targets: The average price target is 820p – roughly 16% above the current share price.
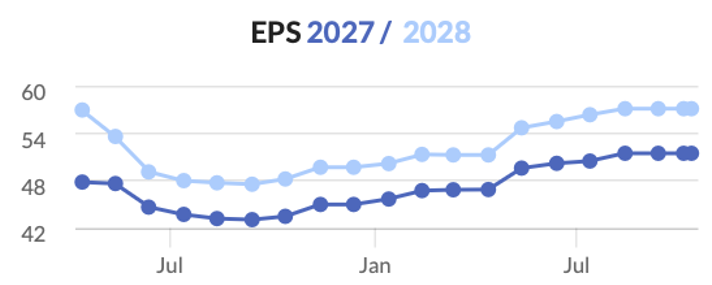
- Rising earnings forecasts: EPS forecasts for FY27 and FY28 have been trending up.
The Bear Case
Key risks with this stock include:
- Distribution risk: If a major watch brand was to alter its distribution model, it could have implications for Watches of Switzerland. It’s worth noting here that in 2023, Rolex acquired Swiss-based retailer Bucherer, gaining direct access to consumers.
- Economic/financial market weakness: While the top end of the K-shaped economy has money to spend today, scenarios such as a major stock market collapse or a sharp increase in AI-related job losses could hurt demand for luxury watches (especially the less exclusive brands).
- Lease liabilities: As of 3 May, the company had lease liabilities of £428 million – these could become a burden in a downturn.
- Inventory management/supply constraints: Some luxury watch manufacturers intentionally keep supply constrained to protect brand equity and to maintain pricing discipline and if supply constraints were to tighten excessively, revenue growth could stall due to a lack of product availability.
- Tariffs: With the US accounting for over 50% of group revenue, additional US tariffs on Switzerland are a risk.
- FX risk: The group is exposed to movements in the GBP/USD exchange rate when translating the results of its US operations into Sterling.
The Bottom Line
Given its ‘Speculative Super Stock’ classification and StockRank of 98, Watches of Switzerland Group could be worth a closer look. With the company targeting 5-10% revenue growth for FY27 along with 40-80bps adjusted EBIT margin expansion, the set-up looks relatively favourable at the current valuation.
There are risks around the economic backdrop. However, with more than half of sales coming from the US – where there is no shortage of affluent consumers – the group should be able to grow further in the years ahead.
Disclosure: At the time of publication, Ed Sheldon had no position in WOSG.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Whilst not a convert I appreciated the Article and do have some sympathy with the bull case for this stock. Arguably the US AI generation have plenty of cash and love to flash it around so you can see ready demand for the top tier time pieces. I like my Garmin sports watch but have friends who think Rolex and other well known names are where it is at.......
I think if Anthropic float goes well there maybe more mileage in WOSG
Great article, Ed!
Graham already pitched this stock back in January.
Since then it is up over 50%.
Hi Rusty2,
Yes that's right. It has been a big outperformer this year. It still looks good value though, in my view.
Many thanks for your detailed analysis of this particular stock, which it seems I had wrongly ignored for too long, but following Ed Croft's winning and losing talk only a week ago have purchased and already seen grow by 4%. Whoever would have imagined the US consumer might have money to spare..
Thank you Ed - an interesting Fundamental case. ... and an interesting Technical case as well:
Looking at the long term and short term charts, the 200d average is turning up, it's pulling back nicely and looks ripe to breakout above the 801p resistance. Price closed above the 50d today ... if that holds, it's on the Buy List for me.