Water Intelligence: another $4.7m franchise buy-back adds to our doubts
Analyst’s view:
It is clear from the rating, that what shareholders want is organic growth, debt paid down, and free cash flow generation that is directed towards shareholder returns. Instead, we are getting more cash going out the door to reacquire franshises, and no dividend. If they can generate FCF while growing sales and earnings this is undoubtebly too cheap. However, I see absolutely no sign that they are willing or able to do this, and the more I see deals like the one today, the more I struggle to justify this as an investable company.
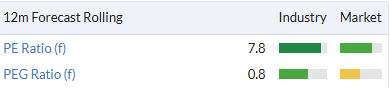
Water Intelligence is an incredibly cheap stock for a business whose revenue has grown 19% CAGR over the last few years:
Even though the EPS hasn't shown signs of operational leverage, it has still grown in the mid-double digits and is forecast to grow strongly in the future:
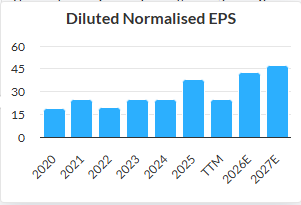
However, I am pretty wary about this company, because much of this growth has come from deals such as the one announced today:
...the strategic reacquisition of its fast growing franchise in southern Alabama within the Group’s core American Leak Detection (“ALD”) subsidiary....
The purchase price for the franchise is $4.7 million in cash with $2.5 million at completion and the remaining payments spread through 2029. The purchase price is based on trailing twelve-month performance of $2.15 million in revenue and $815,000 in adjusted EBITDA. As part of the transaction, the owner Ryan Speir will be joining the management team as Vice President for the Southeast U.S. Mr. Speir will receive stock options priced at 10% above the market price at completion as incentive to accelerate organic growth of corporate and franchise locations throughout the Southeast.Claude tells me that they have made 19 of these franchise re-acquisitions since the start021. The company argues that this model is a great way to gain access to new territories with minimal risk. However, as an external observer, it is almost impossible to tell if these are done at a fair price on an arm's-length basis.The headline numbers don't suggest that they are paying particularly high multiples, but then with any owner-operated business, you have to wonder how much of their salary is excluded from an adjusted EBITDA (business owners tend to pay themselves dividends out of profits, not large salaries). They are also giving their new VP share options, and will presumably ask us to exclude SBP from our analysis.
The net result of all of these deals is that despite generating what appears to be strong operating cash flow, more than that goes out on investing and deal flows:
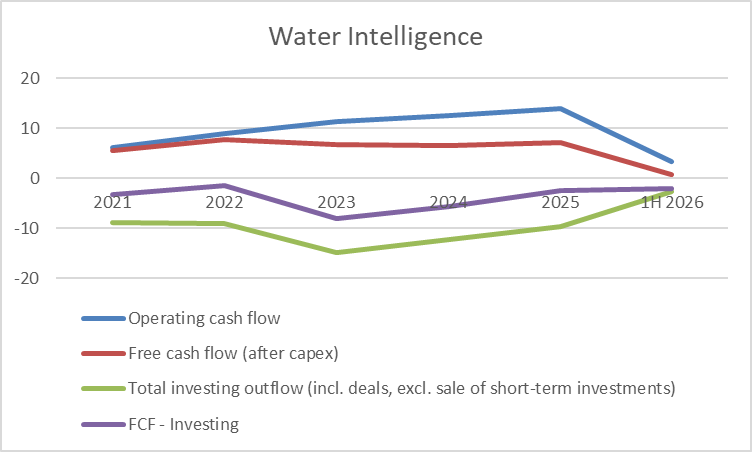
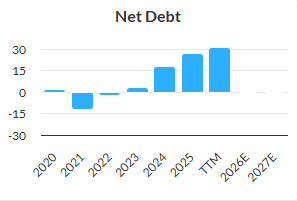
With these characteristics, it should perhaps not be surprising that net debt continues to increase every year:
Existential threat?
Even if they are paying relatively low multiples, last time I looked at this on the DSMR, I mentioned a brilliant substack article written last year that argues that the company is at a fundamental crossroads, and there are huge long-term risks to the business. You can see why franchisees may be keen to sell the businesses they built back to the company for multi-millions and a salary.
H1 Results:
Looks like we didn't comment on the H1 results at the end of September (it was one of the busiest reporting weeks of the year). However, these didn't look great, with adjusted profits again rising more slowly than revenue and statutory figures down significantly. The RNS nor the Interim Report on their website don't provide a reconciliation between the two figures, but it's safe to say that I would probably disagree with the adjustments!
This adds to the risk here.
Mark's view:
When I reviewed this following final results in June, I gave them the benefit of the doubt and kept our broadly positive view. But the more I see deals like the one today, the more I struggle to justify this as an investable company. It is clear from the rating, that what shareholders want is organic growth, debt paid down, and free cash flow generation that is directed towards shareholder returns. Instead, we are getting more cash going out the door to reaquire franshises, and no dividend. The founder's large stake gives confidence that the company is thinking about the long-term, but it also means that external shareholders are likely to have no influence on the direction of the company. If they can generate FCF while growing sales and earnings this is undoubtebly too cheap. However, I see absolutely no sign that they are willing or able to do this. AMBER
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Water Intelligence (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?