Daily Stock Market Report (Mon 12th Oct 2026) - POLR, SDG, WATR, AOM, THRU

Yemen’s Houthis attacked Saudi Arabia’s main airport over the weekend, threatening to inflame tensions in the Middle East further.
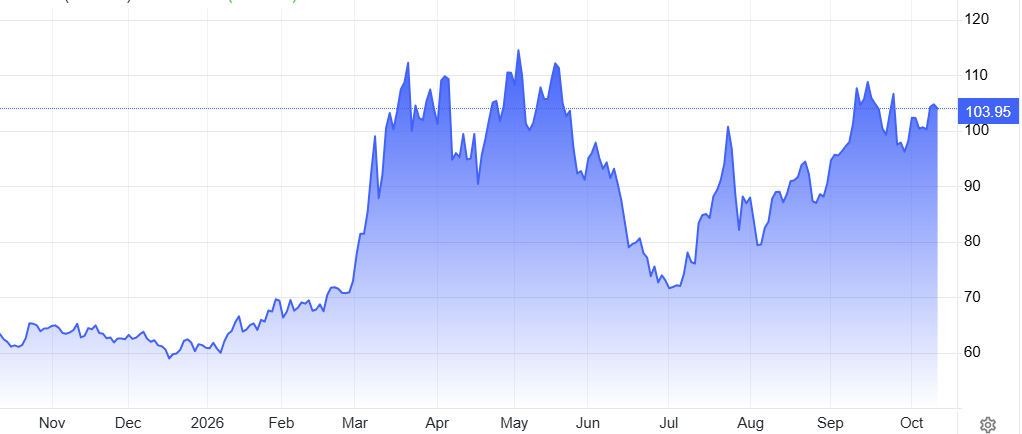
From a financial perspective, this hasn’t yet sent the oil price to new highs. Brent crude for December delivery is trading just below $104. It did spike up close to $106 a few hours ago.
The 1-year chart from Trading Economics shows that we are still below the highs set earlier this year, although at the same time far above the pre-Iran war levels:
One calming factor is President Trump’s claim that there is an “energy ceasefire” between Russia and Ukraine, with Ukraine refraining from hitting Russian oil assets. However, it’s not yet clear if any such agreement has actually been reached.
In the US, bond markets are closed for Columbus Day today. Other markets will open as per usual.
Overnight market movements:
The FTSE is up 0.3% at 10,590
S&P 500 is up 0.3% at 7,830
Brent crude (December) is down 0.8% at $103.95/bbl
Gold is down 0.1% at $4,190oz
Bitcoin is up 0.4% at $83,950
Mark Simpson joins me today.
Done for today, thanks! Spreadsheet accompanying this report: link.
Companies Reporting
Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Metlen Energy & Metals (LON:MTLN) (£5.87bn | SR65) | Collaboration agreement to jointly prepare for potential opportunities in the frame of the future Greek defence telecommunications space program. The agreement envisages the potential use of METLEN's gallium production capabilities for future Thales Alenia Space-built satellites delivered globally (among other elements that METLEN will bring to the consortium). | ||
Ithaca Energy (LON:ITH) (£4.72bn | SR93) | Amendment and restatement of its US$1.8bn senior reserve based lending facility. Provides for an extension of the final maturity date to 31 December 2032, improved pricing terms and updates to permit an increase of up to US $1bn. | ||
Atalaya Mining Copper SA (LON:ATYM) (£1.65bn | SR88) | Proyecto Touro, through its local entity Cobre San Rafael, has been designated as a Strategic Project by the European Commission. This “recognises the strategic importance of Proyecto Touro in contributing to a secure and sustainable European supply of copper”. | ||
Hays (LON:HAS) (£1.01bn | SR57) | Net fees down 3% like-for-like, down 5% total. Consultant net fee productivity up 8%. £45m net debt (June 2026: £20m net cash) is in line with expectations. “Our medium term targets can be achieved through our own actions.” | ||
Polar Capital Holdings (LON:POLR) (£801m | SR86) | Net inflows of £1.2bn in the quarter. Net inflows of £3.6bn over six months. Over the quarter, AUM fell from £45 billion to £43.7 billion, due to negative market movement/performance. | GREEN = (Graham) | |
AEP Plantations (LON:AEP) (£747m | SR67) | 9 months to September: own FFB (fresh fruit bunches) production up 13.3%. Mill FFB processed up 15.9%. Average crude palm oil ex-mill price flat year-on-year. The prevailing El Niño conditions and prolonged dry weather may affect FFB yields in 2027. Should yields be impacted, supply and demand dynamics would likely see some support for CPO pricing. Remains confident in delivering results in line with market expectations for the full year, 2026. | ||
ITM Power (LON:ITM) (£649m | SR19) | ITM’s subsidiary, Hydropulse, has signed Heads of Terms with a European oil refinery for a large-scale green hydrogen project. Targeting Final Investment Decision in 2027, with hydrogen production expected to commence in 2029. | ||
IP (LON:IPO) (£627m | SR83) | IPO has led an oversubscribed £4m pre-series A funding round into Matter Machine, an AI-driven materials discovery company spun out of the University of Liverpool. | ||
Big Technologies (LON:BIG) (£276m | SR67) | BIG has been served with a Claim Form against the Company by former Chief Executive Officer, Sara Murray in respect of the Litigation Update announcement that was released on 12 September 2025. The Claim Form asserts that Sara Murray is entitled to damages for libel (as well as other relief). | ||
AdvancedAdvT (LON:ADVT) (£245m | SR47) | Revenue is expected to be not less than £28.5m. Adjusted EBITDA¹ is expected to be not less than £8m. Net cash and investments of £113.2m. | ||
Ramsdens Holdings (LON:RFX) (£206m | SR81) | Profit before tax for FY26 will be between £32m and £35m. Gross profit in the precious metals segment in FY26 has doubled to c£36m (FY25: £18m). FY26 Gross profit in jewellery retail was approximately 20% ahead of FY25. Currency exchanged has remained broadly in line with FY25. | TAKEOVER | |
VP (LON:VP.). (£206m | SR49) | Remains on course to perform in line with market expectations for FY27 (Revenue £351.3m, Adj PBT £32.5m and pre-IFRS 16 net debt £154.4m) with H2 FY27 expected to outperform H2 FY26. | ||
Afentra (LON:AET) (£200m | SR44) | Impala-2: Immediate rig move to drill and complete Impala-2; first oil expected in January 2027 | ||
Activeops (LON:AOM) (£161m | SR37) | H1 Revenue +21% to £25.3m, including one-off £1.5m termination receipt; without it, growth was 14%. Organic SaaS revenue grew 19%. | PROFIT WARNING (AMBER ↓) (Graham) | |
KEFI Gold and Copper (LON:KEFI) (£82.9m | SR15) | Re-commencing development at the Company’s Tulu Kapi Gold Project in Ethiopia after 7 Sep suspension following what has come to be known as “the Genji Incident”. | ||
Intercede (LON:IGP) (£80.2m | SR43) | RNS Reach: launch of MyID Authenticate, a FIDO passkey authentication solution that gives governments and enterprises phishing-resistant sign-in to Windows desktops, cloud services and on-premise applications from a single platform. | ||
Borders & Southern Petroleum (LON:BOR) (£72.6m | SR43) | £2m before expenses raised by a direct placing of shares to a single investor at 11.5p, a 42% premium to the Company's closing price of 8.1p on 9 October 2026, but also includes 1 for 2 warrants at 20p. | ||
Vast Resources (LON:VAST) (£68.2m | SR8) | Kansai Tailings mined increased +44% QoQ to 137,964 tonnes. Ore mined +14% to 65,796 tonnes. Gold production increased 5% to 2,701 oz due to lower grade tailings. | ||
Zephyr Energy (LON:ZPHR) (£58.8m | SR31) | Chris Eadie has stepped down as Group Finance Director and Company Secretary from Oct 9. | ||
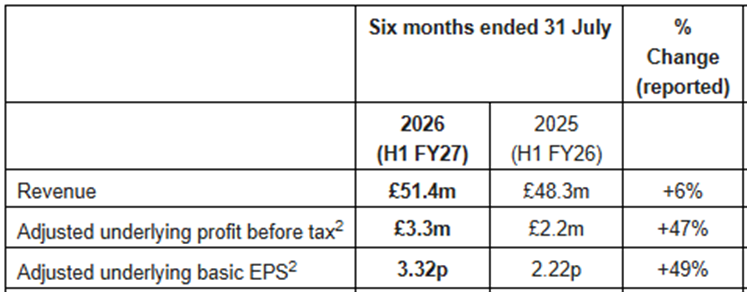
Sanderson Design (LON:SDG) (£55.6m | SR97) | Revenue +6% to £51.4m. Brand +2% (NA +16%), 3rd party manufacturing +19%, Licensing +13%. Adj. PBT+47% to £3.3m. Net cash £10.4m (31 Jan: £9.8m). The Board expects full-year trading to be in line with market expectations (adjusted underlying PBT £6.5m, and revenues of £102.0m). | AMBER/GREEN = (Mark) | |
Water Intelligence (LON:WATR) (£45.8m | SR98) | Reacquisition of its fast growing franchise in southern Alabama within the Group’s core American Leak Detection subsidiary for $4.7 million in cash with $2.5 million at completion and the remaining payments spread through 2029. Franchise owner joins as Vice President for the Southeast U.S. and issued options. | AMBER ↓ (Mark) | |
hVIVO (LON:HVO) (£41.3m | SR27) | Angela Hildreth appointed Chief Financial Officer and Board Director, with effect from 18 November 2026. | ||
Enwell Energy (LON:ENW) (£36.9m | SR24) | The MEX-GOL, SV and VAS production licences have remained suspended and, accordingly, there was no production from those licences. | ||
Blencowe Resources (LON:BRES) (£31.1m | SR13) | Cameron Pearce has resigned as Executive Chairman and as a director of the Company with immediate effect. Sam Quinn, currently a Non-Executive Director, has been appointed Non-Executive Chairman. CEO appointed to the board. | ||
Harena Rare Earths (LON:HREE) (£19.8m | SR13) | Formal exploitation permit is a major milestone towards development of the local processing of the Ampasindava Project. | ||
Tialis Essential IT (LON:TIA) (£14.4m | SR38) | New contract valued at c.£7.6 million over a five-year term, together with the extension of an existing customer agreement worth c.£1.2 million per annum. | ||
RC365 Holding (LON:RCGH) (£14.2m | SR20) | As electronic payment usage continues to develop, the virtual card is being introduced as an additional option alongside the Group's existing physical card offering. The current soft launch is limited to several users and does not represent a full commercial rollout or general availability to customers. | ||
Arkle Resources (LON:ARK) (£13.9m | SR21) | Uranium mineralisation has been intersected on six of the ten drill fences across the Paleo East channel and in four step-out holes between them, over 2.9 km of the channel. All of the mineralised intervals begin within five metres of surface, and the best interval is 6 m at 102 ppm. | ||
Mila Resources (LON:MILA) (£11.2m | SR20) | Assay results have now been received for four holes of the nine-hole Q3 RC programme including 43m at 1.06g/t from 45m. | ||
Thruvision (LON:THRU) (£10.1m | SR37) | H1 Revenue flat at £2.6m in line with Board expectations. Backlog +100% to £2.6m. Cash £1.6m (31 Mar: £2.0m). “FY27 full year revenue expectations remain unchanged at £8.0 million.” | AMBER/RED = (Mark) Although the company say H1 was in line with their expectations, this leaves a huge amount to in H2 to hit the £8m FY number. The order backlog figures given today cover less than half the required amount of revenue and strangley don't appear to include all of the recent contract wins that they say will be delivered in H2. |
Mark's Section
Sanderson Design (LON:SDG)
The headline figures look good, with revenue up 6% year-on-year, leading to a 47% improvement in Adj. PBT:
However, this remains a tale of two regions. UK sales continue to be weak, whereas US sales are driving all of the growth:
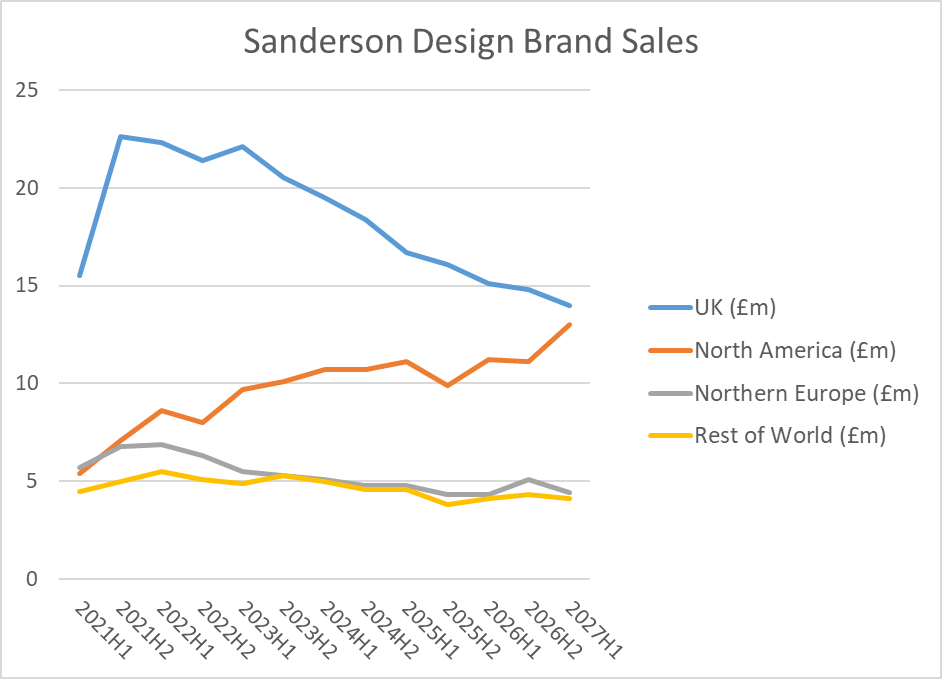
The US is likely to overtake the UK in sales in H2 this year.
In terms of Brands, Morris & Co continues to maintain its recent recovery, but the big jump came from the core Sanderson.
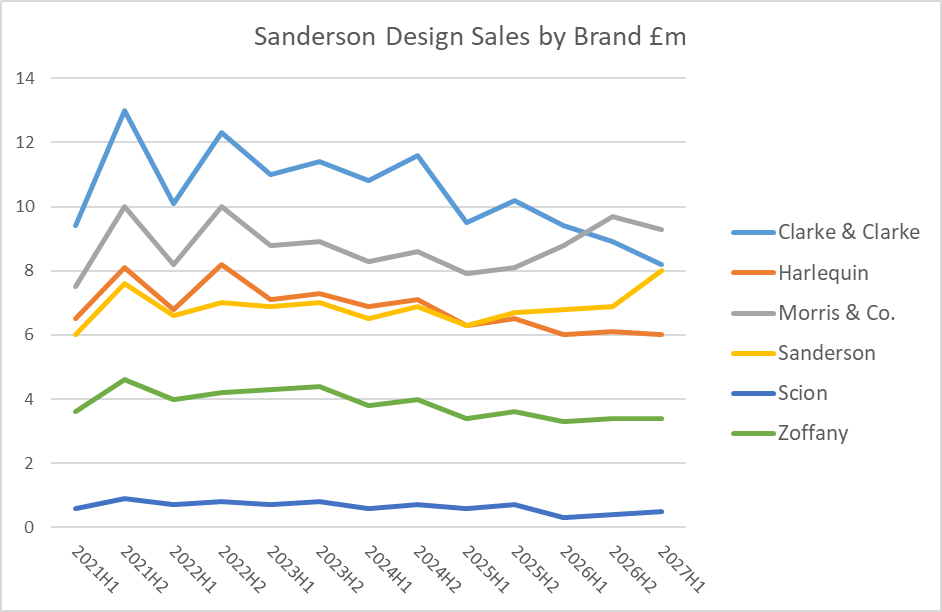
It seems that despite 250 years of independence, the US attraction to the UK Royal Family remains:
The Highgrove by Sanderson collection has been the most successful launch to date and created a clear halo effect on the broader Sanderson brand.
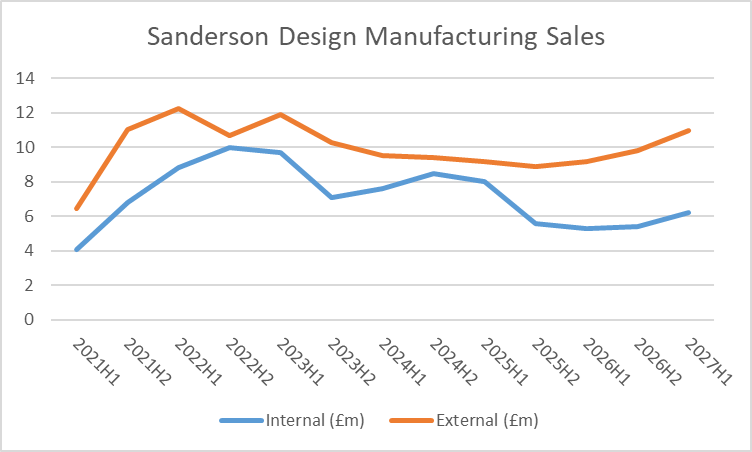
External Manufacturing is another highlight, with revenue recovering close to recent highs:
Licensing:
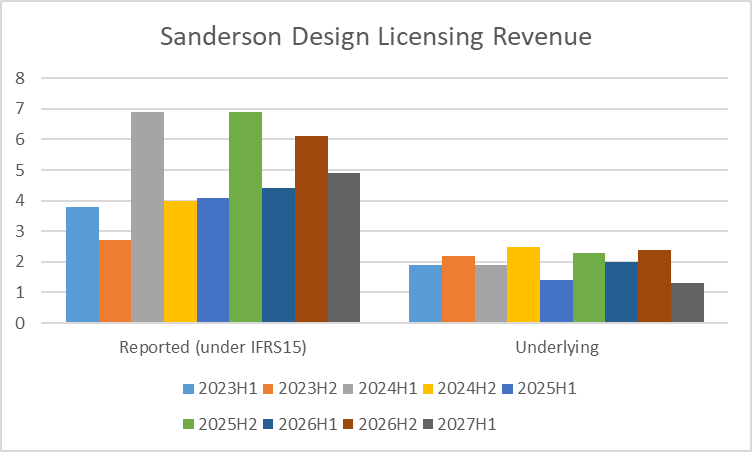
This remains strong on an IFRS15 basis. However, taking away the accelerated revenue figure from the total suggests that this may have been a weaker half for sales above contracted minimums:
Profitability:
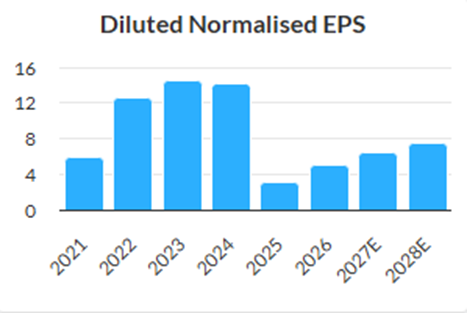
In the past, I have suggested that Sanderson may have been caught out by the sudden decline in their revenue, and managemnet were a little slow to cut costs to reflect this, in my opinion. Combined with a relatively high gross margin, this means that the StockReport shows a huge decline in EPS on a relatively slight revenue fall:
While the Gross margin for the branded business has remained consistently high, Manufacturing has been a lot more variable:
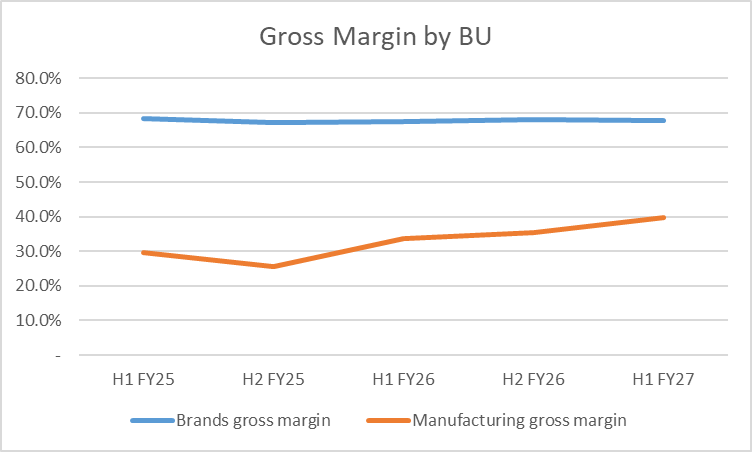
From a low of around 25% in 25H2, this figure now stands at a much more acceptable 40% in these results.
That focus on costs in the manufacturing division also aids the recovery in profitability there:
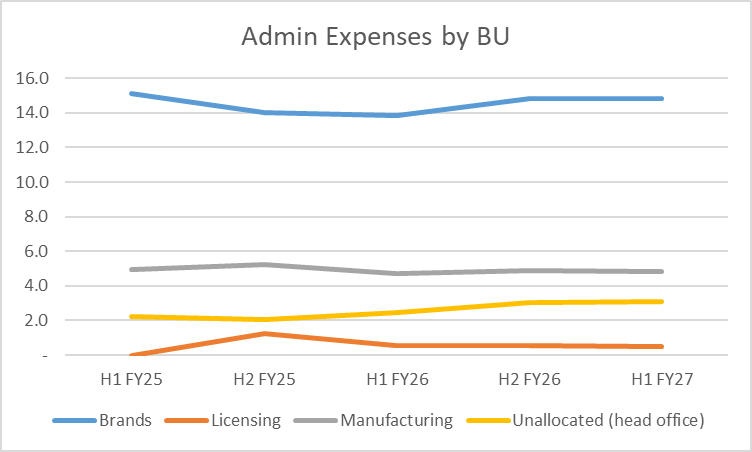
Although it is one of the smaller costs, Head Office costs appear to have increased by about 50% in the last 18 months or so.
Despite the high gross margin and strong US sales growth, Brands continue to be loss-making, and it is the strength of the recovery in Manufacturing that is driving these positive results:
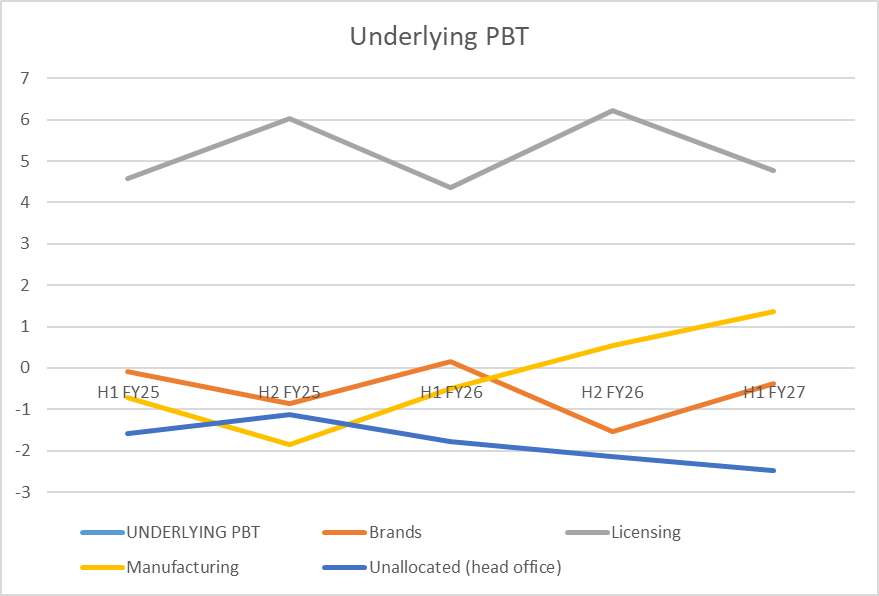
Overall, this remains highly dependent on licensing revenue, and while the businesses can't really be separated, it shows how important this part of the business is.
One thing I think is missing from the reporting is what the licensing revenue would be from a pure sales perspective, excluding the minimum licensing guarantees. This would give us a measure of actually how profitable each period is based on sales. At the moment, it is almost impossible to tell, given the huge impact of licensing sales on the results, and that is skewed by IFRS15 revenue recognition requirements.
Adjustments:
All of this is on an adjusted basis, and it is important to look at what goes into these adjustments:
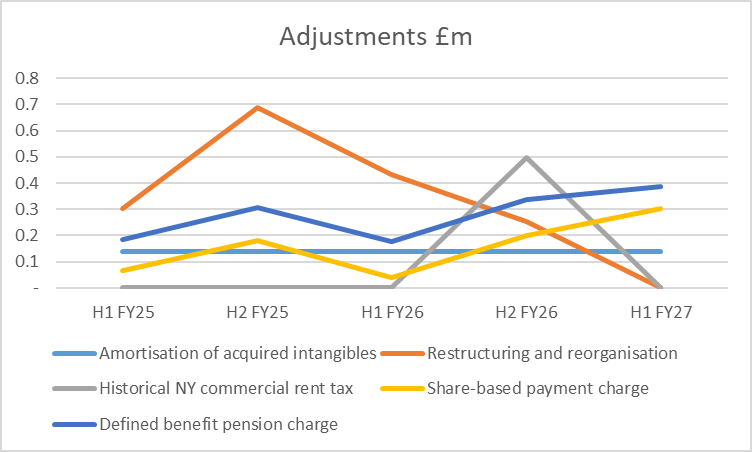
It is good to see the restructuring charge go to zero, as many companies restructure every year and ask us to ignore these costs. Share-based payments jump, perhaps due to the higher share price; at the very least, we should take the fully diluted share count in any valuation.
The defined benefit charge remains. While the company says it is in an accounting surplus and doesn't have to make recovery payments, these administration costs will continue until it gets a scheme buyout, so it seems unrealistic to exclude them.
The alternative in any valuation is to exclude the cost of any buyout from the net cash. Management has previously guided that this will cost high-single-digit £m.
Balance Sheet:
The good news is that the company has the cash to enable that buyout:
Net cash increased to £10.4m (31 January 2026: £9.8m) after £1.3m of EBT share purchases
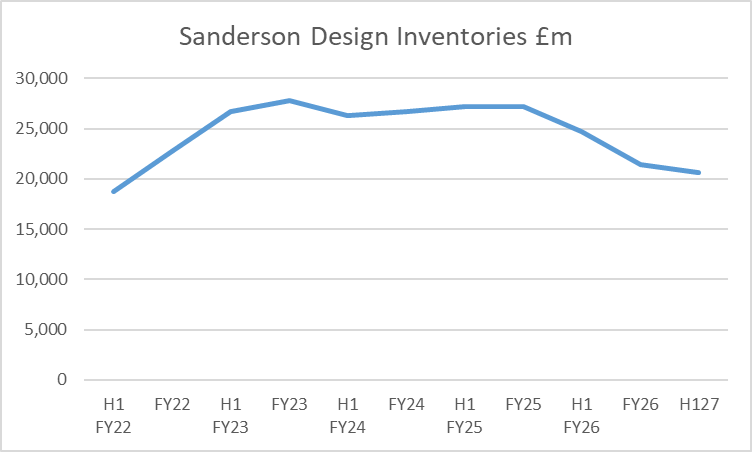
Part of this cash rebuild reflects efforts to reduce SKUs and, therefore, inventory holdings. They make some further progress in this H1 on that front:
There is also a significant "minimum guaranteed licensing receivables" asset, which represents the cash that will be received in the future from licensing sales, where the revenue has already been booked under IFRS15. The current value has risen to £5.3m from £4.4m a year earlier, and the non-current figure has risen from £12.6m to £13.3m. Since these are guaranteed payments, they could be treated as cash.
The company is keen to point out that cash generated has gone into EBT share purchases. However, their behaviour here looks a little strange. We only found out that the EBT had been lent money to purchase shares and was active in the market in the Final Results, when they said:
Post year end, the Group has provided funds totalling £1,400,000 to the EBT for the purchase of shares to satisfy the future vesting of share schemes, as set out in our capital allocation policy. As at 23 April 2026, 1,513,683 shares had been purchased using these funds at a total cost of £855,000.
Most companies RNS this sort of event separately before purchases start, and announce each purchase. Given the scale and the speed of these EBT purchases, I don't think we can rule out this having an impact on the strong rise in the share price during this period:
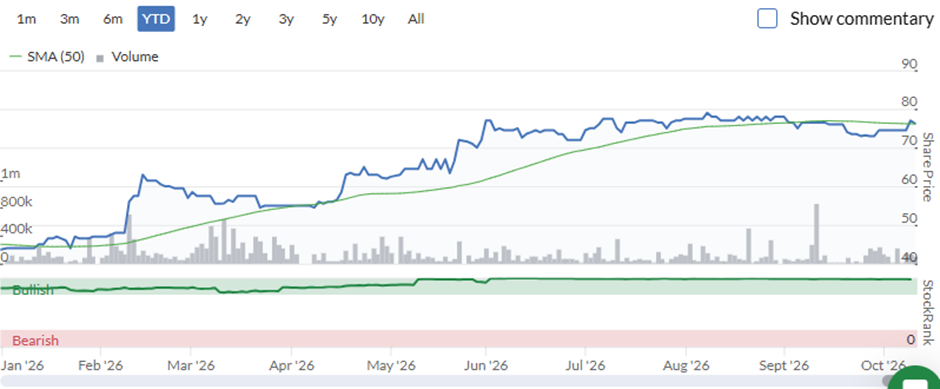
After all, there is no sign of any changes to trading being reflected in broker forecasts in this period:
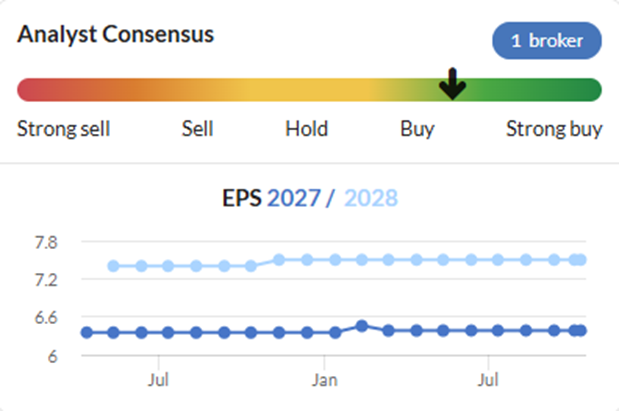
The company doesn't appear to give any update on this today, beyond saying that £1.3m had been spent in the reporting period to 30th June.
Management changes:
The other keen buyer during this period appears to have been LBV Asset Management:
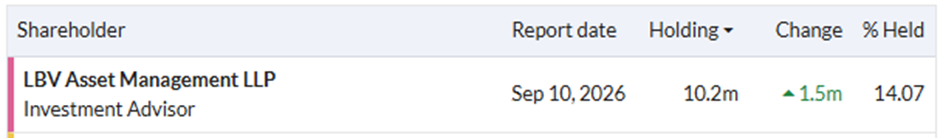
They are a London-based fund manager, and have been trying to remove the Sanderson Chair. A separate announcement today sets 29th October as the date for the requisitioned GM to vote on removing Dianne Thompson and appointing Stephen Brooke to the Board.
LBV says the company has drifted into "inaction and inertia" and needs new leadership to push through change. Shareholders backing it have criticised the cost of fitting out the Voysey House headquarters, slow progress in the US, and executive pay. They say the CEO and CFO packages amount to about 36% of group profit, and quote the CEO's package at £729k.
With my conspiracy-theory tin-hat on, I wonder whether the EBT purchase timing has also been about strengthening the Board's hand in this battle as well as offsetting dilution. Typically, shareholders need 20%+ of the equity to have the right to appoint a board representative, and LBV has not managed to reach that level of holding.
Anyway, Dianne Thompson appears to have agreed to bow out gracefully, as in today's results, they say:
Dame Dianne Thompson, Non-Executive Chair, will have reached nine years' tenure in the role in February 2028. In line with corporate governance best practice, the Board is managing Chair succession in an orderly and considered manner, and intends to appoint independent consultants in January 2027 to oversee the search for a successor for Dame Dianne. The focus will be to appoint an individual who brings the required skillset, experience and independence to support the continued delivery of the Group's stated strategy.
However, I'm not sure this will placate LBV. After all, removing a board Chair is often the first step in forcing out a CEO and CFO. If one of their main critiques is the scale of board pay relative to corporate delivery, that won't change with a Chair retirement and a new Chair appointed by the same Board.
Outlook:
They are guiding in line for the full year:
We are pleased to have delivered a solid performance in the first half of the year and that the positive momentum we've seen across Manufacturing and US sales has continued into the second half of the year. We are on course to deliver full year results in line with current market expectations.
I can't see any updated note on Research Tree. The last substantive note from Singers in April kept the FY27 revenue assumptions the same at £102.9m, but cut adjusted EBIT from £6.2m to £5.7m. However, higher interest assumptions kept the PBT forecast at £6.5m. (The dividend assumption was cut from 2.2p to 1.5p, and today's flat 0.5p dividend declared looks in line with the reduced figure.)
This means that the full-year target needs very little from H2. H1 adjusted PBT of £3.3m is already 51% of the £6.5m forecast. Today's release says the market consensus is still £6.5m PBT, on slightly lower revenue of £102.0m. At that revenue level, H2 revenue would fall about 1% vs last year. Either way, hitting the full year only requires H2 PBT of about £3.2m, roughly in line with H2 FY26.
A H2 fall in licensing is already expected and in forecasts. However, manufacturing sales in the note now look too low, creating potential upside to these forecasts. The H2 for Brands implied in the in-line statement is undemanding, but again will be highly dependent on continued US momentum. Central cost estimates now look a little low given this H1, so they may offset potential sales upside.
Overall, I see these as comfortably in line on the key adjusted PBT metric.
Valuation:
Assuming no change to forecasts today, the forward P/E is around 12. I don't think we should count the net cash, as most of that is earmarked for a pension buyout. This isn't expensive, but this has rarely traded at high multiples:
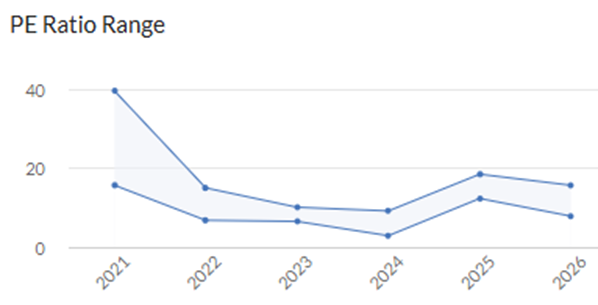
At 1.5p forecast for the full year, the dividend yield is only 2%. A reluctance to raise it suggests a recovery in the declining UK and ROW markets is further away than the company would like.
Brokers are forecasting a P/E of around 10 for FY28, and the high gross margin means that if core branded sales can return to growth in more than just the US, then the increased sales will probably drop to the bottom line quite quickly.
Mark's view:
I am a little sceptical of the recent rise in the share price, which has now almost doubled on no increase in broker forecasts (indeed, EBIT was downgraded, and only increased interest on their cash position keeps PBT at previous levels). Recent demand for shares appears to come from two sources: EBT purchases and a fund trying to kick out the Board.
The good news is that if the fund is successful in their aims, then cutting board pay will drop directly to EPS, as will any recovery in trading. The current valuation is higher than it has been for a while. However, it probably isn't excessive if we view this as a largely recurring licensing business, with a consumer business tacked on the side.
While the current valuation looks up to date with current events, there are enough potential catalysts that would improve things going forward (e.g. a recovery in UK-branded sales, or board salaries slashed) that I am happy to stick with the Stock Ranks on this one. AMBER/GREEN =
Water Intelligence (LON:WATR)
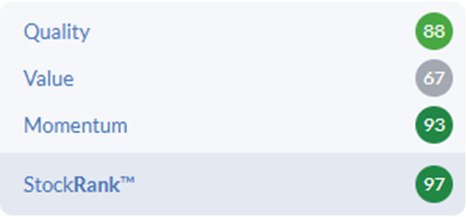
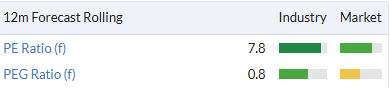
Water Intelligence is an incredibly cheap stock for a business whose revenue has grown 19% CAGR over the last few years:
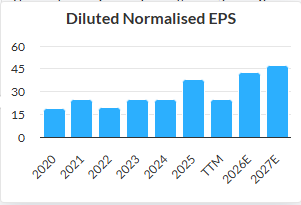
Even though the EPS hasn't shown signs of operational leverage, it has still grown in the mid-double digits and is forecast to grow strongly in the future:
However, I am pretty wary about this company, because much of this growth has come from deals such as the one announced today:
...the strategic reacquisition of its fast growing franchise in southern Alabama within the Group’s core American Leak Detection (“ALD”) subsidiary....
The purchase price for the franchise is $4.7 million in cash with $2.5 million at completion and the remaining payments spread through 2029. The purchase price is based on trailing twelve-month performance of $2.15 million in revenue and $815,000 in adjusted EBITDA. As part of the transaction, the owner Ryan Speir will be joining the management team as Vice President for the Southeast U.S. Mr. Speir will receive stock options priced at 10% above the market price at completion as incentive to accelerate organic growth of corporate and franchise locations throughout the Southeast.Claude tells me that they have made 19 of these franchise re-acquisitions since the start021. The company argues that this model is a great way to gain access to new territories with minimal risk. However, as an external observer, it is almost impossible to tell if these are done at a fair price on an arm's-length basis.The headline numbers don't suggest that they are paying particularly high multiples, but then with any owner-operated business, you have to wonder how much of their salary is excluded from an adjusted EBITDA (business owners tend to pay themselves dividends out of profits, not large salaries). They are also giving their new VP share options, and will presumably ask us to exclude SBP from our analysis.
The net result of all of these deals is that despite generating what appears to be strong operating cash flow, more than that goes out on investing and deal flows:
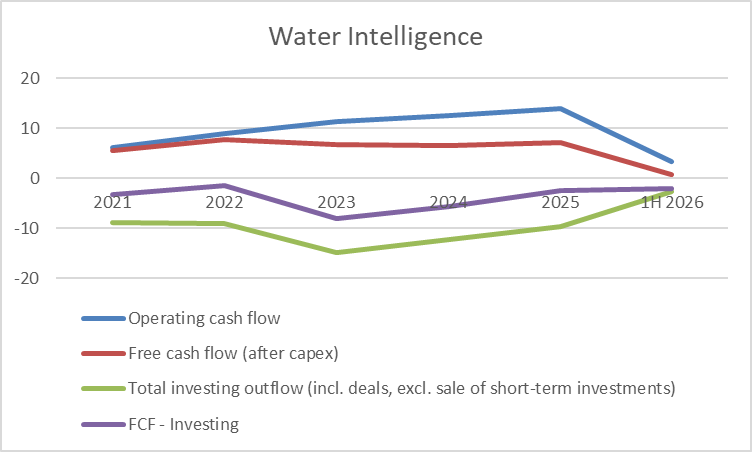
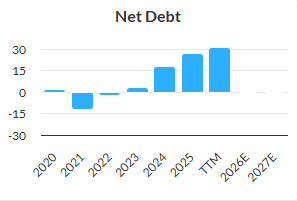
With these characteristics, it should perhaps not be surprising that net debt continues to increase every year:
Existential threat?
Even if they are paying relatively low multiples, last time I looked at this on the DSMR, I mentioned a brilliant substack article written last year that argues that the company is at a fundamental crossroads, and there are huge long-term risks to the business. You can see why franchisees may be keen to sell the businesses they built back to the company for multi-millions and a salary.
H1 Results:
Looks like we didn't comment on the H1 results at the end of September (it was one of the busiest reporting weeks of the year). However, these didn't look great, with adjusted profits again rising more slowly than revenue and statutory figures down significantly. The RNS nor the Interim Report on their website don't provide a reconciliation between the two figures, but it's safe to say that I would probably disagree with the adjustments!
This adds to the risk here.
Mark's view:
When I reviewed this following final results in June, I gave them the benefit of the doubt and kept our broadly positive view. But the more I see deals like the one today, the more I struggle to justify this as an investable company. It is clear from the rating, that what shareholders want is organic growth, debt paid down, and free cash flow generation that is directed towards shareholder returns. Instead, we are getting more cash going out the door to reaquire franshises, and no dividend. The founder's large stake gives confidence that the company is thinking about the long-term, but it also means that external shareholders are likely to have no influence on the direction of the company. If they can generate FCF while growing sales and earnings this is undoubtebly too cheap. However, I see absolutely no sign that they are willing or able to do this. AMBER
Thruvision (LON:THRU)
Having seen its share price pretty much decline continuously this year through to the start of August, Thruvision suddenly came to life:
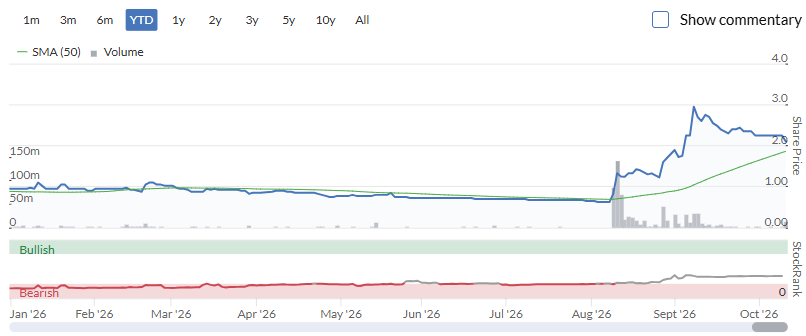
The rise was kicked off by the anouncement of a £3m+ South-East Asian airport worker screening contract. They said that delivery is expected during the second half of the financial year ending 31 March 2027. Hence, we shouldn't expect any impact of this in H1.
However, this H1 trading update still seems a little lacklustre for a company where the share price has risen 231% more than the market in the last three months:
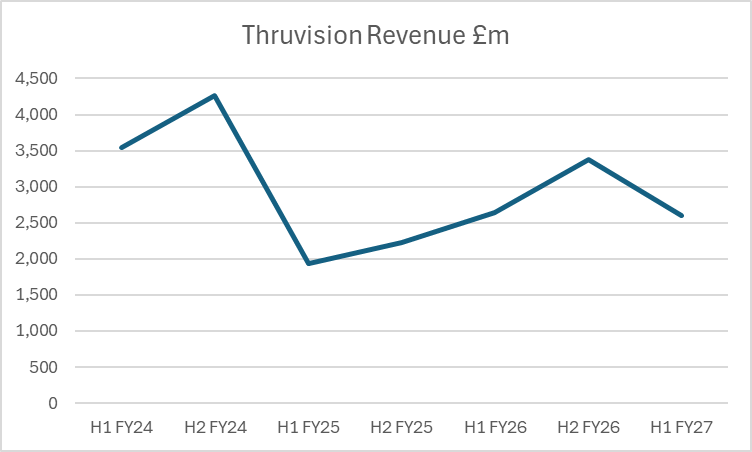
- FY27 H1 revenue was £2.6 million (FY26 H1: £2.6 million; FY26 FY: £6.0 million), in line with Board expectations.
This is better than some recent halves, but hardly seems evidence of a return to growth:
Which means the following lines leave more questions than answers:
- Order backlog has increased significantly, and as of 30 September was £2.6 million (31 March 2026: £1.3 million; 30 September 2025: £0.2 million) providing good revenue visibility for the second half of FY27 during which the current order backlog is expected to be delivered.
- FY27 full year revenue expectations remain unchanged at £8.0 million.
If the order backlog is £2.6m, what has happened to the supposed £3m+ South-East Asian airport worker screening contract? Was some of this delivered in the £2.6m H1 figure, making this look particulrly poor? Or has the contract been down-sized, or delayed? But then they reiterate the £3m+ and H2 delivery in this RNS.
Then they say this gives good visibility on H2, but then their order book coverage is less than 50% of the required £5.4m in H2. This would represent their best ever half for quite some time:
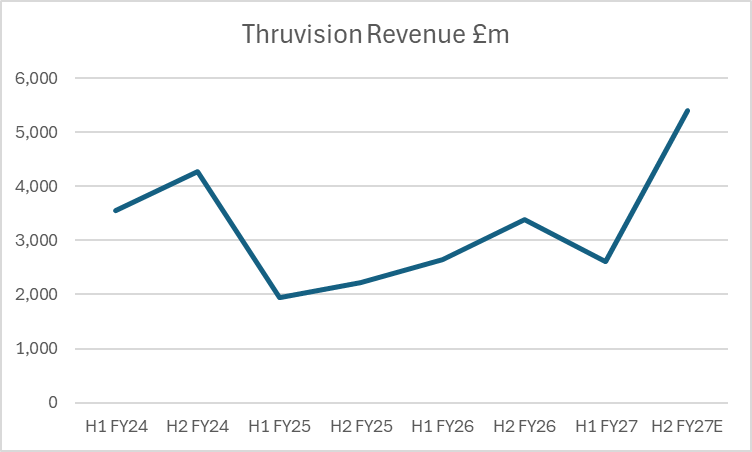
The company doesn't have a great track record of delivery against targets, even after a management changes and a rescue fundraising:
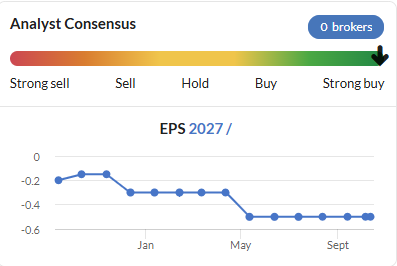
The bigger problem is that even if they hit the £8m revenue number, they will still lose about £900k before tax, according to their broker Allenby. So while they only appear to have had cash outflow of about £400k in H1, and have net cash, it is not clear when they will reach cash flow breakeven:
- The Group’s latest cash balance as of 9 October 2026 was £1.6 million (31 March 2026: £2.0 million).
Mark's view:
We tend to view companies that have been listed for a long time and still generate negative EBITDA pretty poorly on the DSMR. It seems that this should be a bare minumum for a company to be considered investable. So while I don't doubt the technology looks interesting (it always has), and we've not looked at the company for a while as it hadn't made our £10m market cap minimum until investors got excited about the Southeast Asian Airport deal, I think we should remain broadly negative. AMBER/RED
Graham's Section
Polar Capital Holdings (LON:POLR)
Down 2% at 791p (£787m) - AUM Update - Graham - GREEN
There's been a slowdown in quarterly net inflows at this fund manager, but they do remain positive.
Q2 (July-Sep) net inflows £1.2bn
Financial year-to-date net inflows now £3.6bn
As for overall assets under management:
Q2: AUM falls from £45bn (end of June) to £43.7bn (end of September), due to moderately negative market movements/performance.
Financial year-to-date: AUM is still up massively from £30.6bn (end of March), with an extraordinary £9.5bn of positive market movements over the past six months.
The figures seem to be distorted by the fact that the end of March was around the low point for equity markets this year. The S&P 500 reached its low for 2026 that day, before Trump made what in hindsight sounds like an April Fool's Day joke: that the war against Iran was "nearing completion" and that he was planning to wind it down within "two to three weeks".
Stocks have soared since then, and especially the sectors in which Polar invests. So while Trump may have been wrong about the war neatly concluding, it is true that equity markets have become much more relaxed when it comes to assessing the long-term consequences of the war.
Performance fees: at first glance these might seem disappointing, with £8.8m of performance fees accrued by Polar in H1, compared to £15m in H1 last year. But last year was exceptionally strong and also very H1-weighted. Predicting full-year performance fees based on the position at H1 comes with a great deal of uncertainty.
Estimates: thanks to Equity Development for maintaining coverage here. They confirm that Polar's performance fee result in H1 was not bad at all; ED had only pencilled in £4.8m of performance fees for the year as a whole. With £8.8m of performance fees having already accrued in H1, they increase their full-year forecast to match that figure.
That strikes me as a nice, conservative way of predicting this unpredictable number.
Excluding performance fees, ED's adjusted EPS forecast for the current financial year is unchanged at 88.7p (and for next year, it's unchanged at 107.5p).
Including performance fees, the adjusted EPS forecast for the current year increases by 3% from 94.3p to 97.2p. But they emphasise that it's still to soon to say whether the performance fees that have been accrued thus far will ultimately crystallise. That mostly depends on fund values at the end of the calendar year.
CEO comment excerpt:
Demand was strongest for our differentiated specialist strategies, led by Global Technology and Artificial Intelligence. Healthcare, including Biotechnology, Smart Energy and several other strategies also contributed to net inflows. Client engagement remained high, particularly in Europe and Asia, while the geographic mix of new business continued to broaden.
Graham's view
The PE ratio for the current year is about 8x or 9x, depending on whether or not you include performance fees.
Based on expected AUM growth towards £50 billion next year, the PE ratio is expected to fall closer to 7x.
But I'll be the first to admit that this is highly uncertain: it depends to a large extent on sentiment towards the global technology boom.
As a reminder, here's the split of Polar's AUM in March:
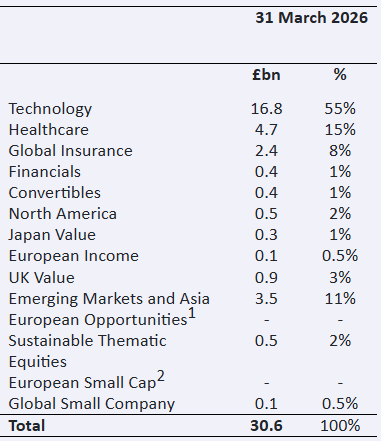
As you can see above, Technology soared to represent more than half of AUM. And that was before the boom that occurred from April. Healthcare, Insurance and EM/Asia provide a limited degree of diversification.
Polar's success has flowed in part from its reputation as a sector specialist. So ending up with a highly concentrated AUM is perhaps inevitable. But it's the key risk here, from my point of view.
I'm still going to be GREEN on this stock, as I was before. The big picture is that its forecasts have just been upgraded and it's still trading on a single-digit PE multiple.
The music may stop playing at some point. But it hasn't stopped playing yet.
Activeops (LON:AOM)
Down 46% at 121.9p (£87m) - H1 FY27 Trading Update and Notice of Results - Graham - AMBER
ActiveOps plc (AIM: AOM), a leading provider of Decision Intelligence software for service operations, today provides an update on trading for the six months ended 30 September 2026 ("H1 FY27").
This update starts out innocuously:
H1 FY27 trading in line with expectations (revenue up 21% to £25.3m), including a £1.5m "termination receipt".
FY27 expectations unchanged even though "new customer wins and implementations have been lower than in the prior year"
Then the bad news:
Major customer unlikely to renew. The customer has shared its intent not to renew its contract when it ends in March 2027. This has no impact on FY27. The contract is worth £3.8m of annual recurring revenue (“ARR”).
FY28 change to expectations. The Board expects FY28 revenue and adjusted EBITDA to be significantly below market expectations1 reflecting both the potential customer loss and lower new business activity in H1 FY27.
The market cap has reduced by over £70m today, and yet the major customer was only providing £3.8m of ARR.
So it's definitely the combination of the major customer loss and the reduction in new business activity that has resulted in today's enormous sell-off.
Also consider the earnings multiple at which this was trading as of Friday night:
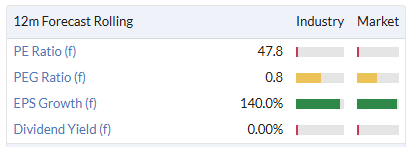
And yet according to the StockReport, despite the stock's sky-high valuation, markets were pricing in revenue growth of less than 10% in both FY March 2027 and FY March 2028.
When I checked AOM's full-year results in July, ARR had just grown at the rate of 46% year-on-year, and revenue had grown at 48%.
I can only conclude that on the back of strong FY26 results, the market has been expecting AOM to beat the very modest FY27 and FY28 expectations.
Instead, it is now going to miss FY28 by a wide margin.
Estimates: many thanks to Canaccord Genuity for publishing on AOM today. Their note has the almost humorous headline "Bump in the upward slope". The key takeaways are the revenue forecasts have been slashed:
The FY28 revenue forecast has been cut by 14% to £44m, which is 8% lower than the FY27 revenue forecast (£47.8m).
The FY29 forecast similarly gets cut by 16% to £46.8m.
So the stock has suddenly gone from a growth story into a story of decline, at least in the short-term.
Cash is £19.6m and thankfully this is not a concern. The company is forecast to remain profitable, albeit at a lower level.
Outlook remains positive in the medium-term:
While some cost action will be taken as a result of the contract non-renewal, the size of the opportunity ahead, the breadth of the extensive customer base and strength of the Group’s balance sheet mean the Board intends to continue with its planned investments in growth initiatives, as it remains confident this will drive increased shareholder value in the medium term.
The business remains strongly cash generative and continues to benefit from an extensive and engaged global customer base, for whom its software delivers measurable returns on investment
A reminder of what the company does: it has a software platform that is supposed to organise a customer's data and helps them make better, faster decisions. The sectors it serves include banking, fund administration and insurance.
"Using ML, AI and data models, we extract insights that enable you to make strategic and tactical decisions in the moment." - its adjacency to AI doubtless helps to explain how it achieved such a prime valuation up to this point.
Comment by Exec Chair Richard Jeffery, who owns 12% of the company:
While the potential non-renewal by a major customer is a setback to our near term revenue growth, we remain strongly cash generative, with a robust balance sheet and a growing, global opportunity. The need for organisations to measure productivity gains from AI is a compelling driver for our software and one which we are uniquely able to meet, given our deeply embedded position within the heart of the operations of our customers. While cognisant of the disappointment that I and other shareholders feel at today’s news, the outlook for the business remains one of great opportunity, which we have the financial firepower, offering and dedication to exploit.
Graham's view
I was moderately positive on this stock in July. I noted that it was trading at about 4x ARR, " which in a SaaS context is not expensive, but what that does require is some conviction in the stickiness of revenues and the growth opportunity".
Unfortunately, that revenue has proven to be less sticky than expected, and it is now ex-growth, at least in the short-term. The loss of a major customer proves that recurring revenue is sometimes not all it's cracked up to be: it sometimes does not recur!
Given the seriousness of this profit warning I do have to downgrade our stance on AOM today, but I don't see the point in going any lower than neutral.
At an £87m market cap, it's now only trading at 2x ARR, which is well below the lower limit of where successful software businesses are supposed to trade. In other words, it's no longer being priced for success.
In P/E terms, it's trading at 23x FY March 2028 forecasts.
But remember that it also has a very decent cash balance, which covers nearly a quarter of the market cap and is expected to grow by year-end.
Once you account for that cash, the stock is trading at less than 20x forward earnings.
That doesn't make it necessarily a bargain, but I think RED or AMBER/RED would be overly negative for a profitable, cash rich business that has still made significant progress in recent years and which I suspect could fetch a decent takeover price, if it was up for sale. So I'm neutral.
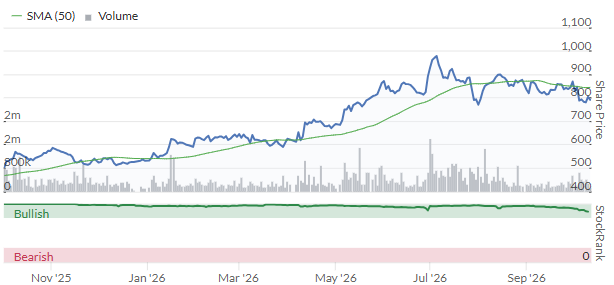
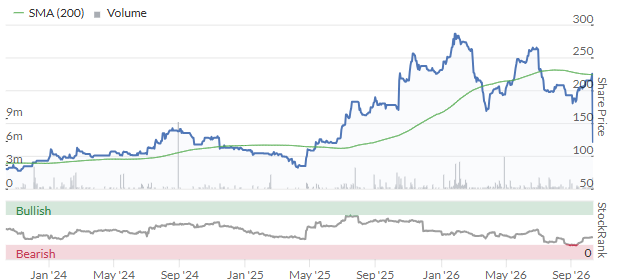
3-year chart:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

18 comments
Please forgive me if I take this opportunity to thank Ed and the team for their excellent daily analysis of stocks affecting us all. especially in light of what l learned from Ed's webinair just days ago highlighting the different catagories and risk applied to them allowing us to choose the most likely to provide winners. Today's stock report provides a classic case in point judging by several comments from those of us who have chosen between what seem to be identical pairs of companies such as AEP and MP Evans and in my own case some months ago POLR and FEML.
In the case of AEP they are labelled as Adventurous with Neutral risk while MP Evans are judged a Super Stock with Balanced risk.
Likewise despite, potentially hoped for success and a large shareholding of large investment companies POLR are deemed Adventurous with a neutral risk, while FEML enjoy a Super Stock label with conservative risk, despite being involved in similar enterprise. Luckily for me I have already followed much of the advice provided just days ago, with good result and would strongly advise anybody who never got a chance to read up on Ed's last posting at their earliest opportunity. Great stuff.
Polar Capital Holdings (LON:POLR) and Fidelity Emerging Markets (LON:FEML) are not similar enterprises at all.
FEML is an investment trust - it invests in stocks and shares in emerging markets with the fund's managers coming from Fidelity, a large US investment manager.
Fidelity have other UK listed investment trusts such as Fidelity China Special Situations (LON:FCSS) or Fidelity Special Values (LON:FSV).
POLR is a UK investment manager who have several UK listed investment trusts of their own such as Polar Capital Technology Trust (LON:PCT) and Polar Capital Global Healthcare Trust (LON:PCGH).
Polar and Fidelity are in the same business, albeit at different scale.
n.b. the investment managers, Nick Price and Chris Tennant, of Fidelity Emerging Markets (LON:FEML) are interviewed in the latest edition of the Money Makers podcast.
(I do not hold any of the stocks mentioned)
Where you are trying to decide between a similar pair of companies why not buy a half position in each?
Later if it becomes clear one is the winner then sell the lost and double up.
I have sat in presentations in which investors are really partisan about their company Vs another similar quoted competitor but generally the real competition is off market!
Further to Graham's comments prompted by Dame Julia Hoggett's BBC interview last week, Charles Hall of Peel Hunt has weighed in, as reported today by CityAM:
https://www.cityam.com/london-stock-exchange-faces-material-depopulation/
Activeops (LON:AOM) nasty update. Clients cancelling/ not signing up to a service which should obviously have demand seems strange to me. A bit like an ice cream van having no demand during the heat wave
Hi Graham would be interested in your thoughts re AEP Plantations (LON:AEP) . I'm not clear whether El Niño impact is good (push prices up) or bad (crop disruption). I currently hold.
The concerns expressed by AEP Plantations (LON:AEP) about next year's climate would be expected to affect M P Evans (LON:MPE) (I hold) as well, yet AEP is down 15% as I write and MP Evans has barely moved. I wonder if there is a company-specific issue here that I'm not getting? Overall, I would expect lower yields to be equally bad for everyone. If either company can achieve more resilient yields than their competitors, that's good and they would benefit from rising prices. I have no idea what agricultural techniques could be used - irrigation is surely impossible across such vast areas of oil palm plantation.
I had also been looking at both AEP Plantations (LON:AEP) and M P Evans (LON:MPE) recently and noticed that AEP’s stock ranks had completely tanked pretty much overnight but couldn’t really work out why? Again today it isn’t the worst looking news being pretty much “in line” but the stock ranks movement is worrying. MPE stock ranks still looking good so it’s a bit of a head scratcher for me…
Palm oil is found in around 50% of all packaged supermarket goods nowadays and Unilever alone, use it in everthing from toothpaste to margarine. Indonesia and Malaysia provide around 85% of the World supply, but like all agriculture it will struggle with climate changed weather conditions. In addition since the country economy is entirely dependent upon the successful crop, there is a certainty it will not be overlooked or allowed to fail, but a more likely result of a poor harvest next year will be a shortage and higher prices for the consumer, rather than long term lowered share values of either AEP or MP Evans. For myself I have enjoyed the steady growth of MP Evans over the last 6 months and winced over the last couple of days, but there is no readily available alternative to persuade me to sell.
Much of what Trump spouts is pie in the sky - 'However, it’s not yet clear if any such agreement has actually been reached.'
Or just more lies and opportunity for the Trump crime family to make more money.
"A White House official told Axios it is really a proposed halt to refinery strikes, which Russia has not agreed to"
The amout of diesel is not enough to tip any price of diesel, Russia have limited diesel to sell and already have fuel restrictions, apparently the 1st ship delivering diesel has already been at sea for 2 weeks! Witkoff, Kushner and co likely to make a killing buying Lukoil assets.
Really is about time McDonalds works its wonders and or the US step up and use their election and amendments to do the honourable thing..
What is not widely reported about the Saudi attacks is that they have had 3 significant attacks on refineries. One of them is Khurais refinery of crude oil, the biggest in the world that produces 7% of the crude refined. There is not another refinery in Saudi that does the same job, so the oil can not just be redirected to another refinery in Saudi.
Sanderson Design (LON:SDG): Given in H2 last year they achieved £3.1m adjusted PBT, and this HY is £3.3m, full year expectations of £6.5m implies just £100k H2 growth. I initially assumed maybe they weren't expecting a good half for licensing but looking at the HY results their profitability has increased across categories and the outlook sounds positive. I'm therefore assuming they're being conservative with their full year expectations unless I am missing something?
I hold and feel a global buyer for SDG could emerge.The success in building the US business makes this more likely-in my opinion.
Excellent, in-depth analysis on Sanderson Design (LON:SDG) today - many thanks Mark.
Now I know why we didn't get paid out by BIDCO on Ramsdens, it's subject to approval by the competition and markets authority. Ah well, great company, we're happy to hold.
Jasvfs
Don't understand your comment. Can you explain please
The US buyer of Ramsdens Holdings (LON:RFX) already bought a UK listed pawnbroker last year. The takeover of Ramsdens needs CMA approval so JASVFS is happy to hold the shares while the approval process is ongoing.
(I do not hold)