Daily Stock Market Report (Thur 2nd July 2026) - CNC, TRI, CURY, PIN, LTHM, AOM

Aside from football, there isn’t much overnight news. On the football front, I’m curious to know how many of you will be staying up on Sunday night to watch the Mexico match - is it too late to declare Monday a Bank Holiday?
As there is little news, let’s take a moment to see how my 2026 watchlist performed in H1.
Mortgage Advice Bureau (Holdings) (LON:MAB1): total return minus 22.9%
Hostelworld (LON:HSW): minus 9.3%
Cavendish (LON:CAV) minus 8.8%
Mercia Asset Management (LON:MERC) minus 8.5%
Peel Hunt (LON:PEEL) minus 2.4%
Nichols (LON:NICL) +2.0%
B.P. Marsh & Partners (LON:BPM) +5.3%
PayPoint (LON:PAY) +23.2%
CMC Markets (LON:CMCX) +53.2%
Polar Capital Holdings (LON:POLR) +67.5%
I think this gives an average result of 9.9%, highly concentrated in the top three names.and slightly better than the FTSE All-Share (7.2%).
But if I’m allowed to cherry-pick slightly, I’d also point out that Polar’s year-to-date return improved to +74.6% yesterday, while CMC improved all the way to 117% - so it was an exceptionally nice start to H2! Unless my sums are wrong, the average year-to-date return as of last night was 17.4%.
Overnight market movements:
The FTSE is down 0.1% at 10,470
S&P 500 is unchanged at 7,490
Brent crude (September) is down 1.2% at $70.90/bbl
Gold is up 0.8% at $4,060/oz
Bitcoin is up 0.9% at $60,650
Thanks everyone! That's all for today.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Halma (LON:HLMA) (£15.0bn | SR76) | Acquired itemedical and Naslund Medical for its Healthcare Sector companies SSG and IZI Medical. Cash consideration for itemedical is €23m (£20m), cash consideration for Naslund Medical is $45m (£34m). | ||
3i Infrastructure (LON:3IN) (£3.5bn | SR49) | Received proceeds of €1.1 billion on 17 June 2026 for TCR. Repaid revolving credit facility in full. Expects to complete €300m investment in LMD, a data centre campus in Norway. Portfolio performing well and income in line with expectations. | ||
Currys (LON:CURY) (£1.79bn | SR92) | Building an ever-stronger Currys (FY Results) & Launch of £50m Share Buyback Programme | Revenue +6%, like-for-like +4%. Adjusted PBT +18% (£191m). Year-end net cash £176m. New £50m buyback. Outlook: trading in new financial year has been very solid, comfortable with market consensus. New CEO starts in August. | AMBER = (James) Currys posted an 18% rise in adjusted pre-tax profit to £191m and launched a new £50m buyback, yet shares fell 1.5% after a ~30% run since March. Revenue rose 6% to £9.3bn, adjusted EPS up 19% to 13.4p. At 11.8x forward earnings it looks cheap, but £764m of debt (once leases are included) and thin 2.35% margins temper that. This should put a cap on how high the stock can really go. It’s now trading 8.5% below the average share price target, reaffirming my own belief that the momentum may slow. Amber: genuine turnaround, but limited margin of safety at this price. |
Pantheon International (LON:PIN) (£1.55bn | SR N/A) | NAV per share +1.2% for the month of May driven by foreign exchange movements (+0.8%) and buybacks (+0.5%). | GREEN = (Graham - I hold) | |
Great Portland Estates (LON:GPE) (£1.35bn | SR27) | 21 new leases and renewals signed in the quarter. Market lettings on average 3.7% ahead of March ERV. | ||
Supermarket Income REIT (LON:SUPR) (£1.1bn | SR64) | £375 million syndicate and £70 million bilateral loan will refinance all of SUPR’s existing unsecured loan facilities maturing over the next two years. | ||
Baltic Classifieds (LON:BCG) (£866m | SR37) | Revenue +7%, EBITDA margin stable. Operating profit +13% (€60.4m). Outlook: revenue growth of around 10% in 2027, with growth anticipated to be slower in the first half and faster in the second half of the year. Full-year margin to be in line with previous medium-term guidance of mid-70s. | ||
Neuberger Private Equity Partners (LON:NBPE) (£594.5m | SR69) | Neuberger Private Equity Partners Announces H2 2026 Dividend | Neuberger Private Equity Partners Announces 2H 2026 dividend of $0.47 to be paid on 28 August | |
Puretech Health (LON:PRTC) (£321m | SR32) | PRTC’s founded entity Celea announced the completion of a $180 million financing. “This transaction establishes Celea as an independent company with dedicated capital to advance deupirfenidone and a high-quality syndicate to support the company's continued growth.” | ||
Concurrent Technologies (LON:CNC) (£232.7m | SR48) | $9.4m order from a major US defence prime contractor. Order relates to the supply of standard product computer plug-in cards, and a commitment by the customer to procure components to support potential future production requirements (with a short-term cancellation period). | AMBER = (James) Concurrent Technologies secured a $9.4m US defence order, adding to a c.£17m European contract won in June, pushing shares up 1.8%. Both follow strong FY25 results – revenue up 14% to £45.9m, pre-tax profit up 25% to £6.5m – with order intake at a record £47m. The valuation already reflects a lot of this growth (45x trailing earnings, falling to 29.3x for FY27), and Systems remains the key swing factor. Amber: strong execution, but priced for it. | |
James Latham (LON:LTHM) (£206m | SR89) | SP +8% Revenue +7.2%. PBT £25.1m (FY25: £24.3m). “The momentum that we saw in the final quarter of this financial year has carried on into the current financial year, with a slight improvement in the margin and also the volume per working day… Customer demand is quite patchy, with some customers reporting strong order books, while others are somewhat quieter.” | GREEN ↑ (Graham) [no section below] A significant competitor went bust in H2 (National Timber Group?), which "did cause a few short term pressures on the margin on some product groups, but these became opportunities in the final quarter of the financial year." The end result was a resilient financial performance. I note in passing that there are balance sheet net assets of £232m, fully tangible and primarily in the form of large working capital items (inventories, receivables and cash). Bad debts have remained low for now, which speaks well to the value of receivables, but the cash balance will not be here for long as the company prepares to set up its National Distribution Centre. We've only been AMBER/GREEN on this, despite its "Super Stock" status, and I'm in two minds about what to do with this stance today. It's a close call. On the bright side, the results are very clean - no funny business with adjustments, just pure profits. On the other hand, while cash conversion was effective in terms of operating cash flow, the heavy and capital-intenstive nature of the business is evident with £26m of capex, so there isn't much free cash flow to cheer about. Let's temporarily and tentatively go GREEN on the basis that the opportunities from the loss of a competitor could create a steady stream of new business opportunities for the rest of the year. | |
Activeops (LON:AOM) (£188m | SR49) | ARR +46%. Adjusted PBT -23% (£1m). Statutory loss £2.3m after £3m of exceptional costs relating to an acquisition. Trading in the first few months of FY27 has been in line with the Board's expectations. | AMBER/GREEN = (Graham) [no section below] Estimates at Canaccord Genuity have been upgraded today with 4.3p of EPS now pencilled in for FY March 2027 (previously 3.9p). This provider of "decision intelligence" software has gone from strength to strength since I looked at it last year and I won't stand in the way of that trend by taking a neutral view today. The organic growth rate is 25%, with inorganic growth on top that, and the market clearly loves the story and is not valuing it on current-year earnings. Instead, it's trading at about 4x ARR which in a SaaS context is not expensive, but what that does require is some conviction in the stickiness of revenues and the growth opportunity. With net revenue retention of 119%, customers appear to be very satisfied. I'm therefore willing to look past the poor profit figures in the short-term and stay AMBER/GREEN here, but I must emphasise that this market cap only makes sense in the context of a software-led, growth company valuation. | |
Genel Energy (LON:GENL) (£145m | SR29) | RECOMMENDED CASH ACQUISITION of Capricorn Energy plc by Genel Energy No.9 Limited | US$4.74 in cash for each Capricorn Share held. | TAKEOVER |
Sintana Energy (LON:SEI) (£103m | SR16) | Sintana Energy announces mid-year operational update with milestones across its Namibia, Uruguay, and Angola portfolio. In Namibia, TotalEnergies farmed into PEL 83 (taking operatorship). | ||
Trifast (LON:TRI) (£96m | SR84) | Trifast FY26 (to 31 March 2026): revenue down 6.7% to £208.4m as it prioritised revenue quality over volume. Underlying EBIT rose to £16.3m (margin up to 7.8%) and underlying PBT to £12.3m. Management points to momentum continuing into FY27 and the strongest pipeline since its strategy began. | AMBER = (Graham) I have zero criticism of anything I’ve read here, in terms of what management are attempting to do strategically: focusing on the quality of revenues, and using EBIT margin and ROCE and their key performance indicators. I’m just not convinced that this stock deserves to trade at a much higher earnings multiple than it already does, given the type of business that it is. | |
Braemar (LON:BMS) (£79m | SR92) | Braemar issued an AGM trading update: positive momentum continuing into the new financial year, with the board confident of delivering profitable growth for FY27 in line with consensus (revenue £139.7m, underlying operating profit £14.2m). James Gundy steps down as Group CEO/director today (staying on for shipbroking activities), succeeded by Grant Foley (previously Group CFO/COO). | ||
Zephyr Energy (LON:ZPHR) (£71.8m | SR33) | Zephyr Energy has acquired another 2,294 acres of TLA leases in the Paradox Basin, Utah. It adjoins its White Sands Unit. It was won via sealed-bid auction, 5-year primary term, 16.67% royalty, funded from cash. | ||
Clean Power Hydrogen (LON:CPH2) (£68.2m | SR N/A) | Clean Power Hydrogen is launching a Retail Offer via BookBuild – new shares at 1.5p each, open only to existing shareholders, targeting a minimum of £0.5m. This is separate from a wider fundraising announced on 1 July. | ||
James Cropper (LON:CRPR) (£33m | SR91) | James Cropper has completed a refinancing: a new £15m invoice discounting facility (committed 3+ years) plus a £7.1m part-repayment of its UK bank loan with the remainder repayable quarterly to March 2030. | ||
PCI- PAL (LON:PCIP) (£32m | SR35) | PCI-Pal has retained HMRC as a customer after a competitive re-tender via a reseller partner. The new deal is an 8-year term with revenue expected broadly in line with the existing contract. CEO notes this is the third of PCI-Pal’s largest customers re-secured on mutli-year terms since the start of FY25. | ||
Insig Ai (LON:INSG) (£16m | SR0) | MoU signed with a new Far East macro fund: Insig AI will build and host its “Fund Engine” – a web app centralising data sources with LLM-based analysis tools. Expected revenues of $240,000 with $120,000 expected in the first three months and $120,000 in the following 12 months. |
Graham's Section
Trifast (LON:TRI)
Down 2% at 68.9p (£94m) - Final Results - Graham - AMBER =
We have FY March 2026 results from Trifast, “the international specialist in the design, engineering, manufacture, and distribution of high-quality engineered fastenings”.
At the trading statement in February, I was neutral, due to a perceived lack of growth, with shrinking revenues and a track record of very average economic returns.
The share price is lower since February and the market doesn’t seem terribly impressed with these full-year results, so maybe my first impressions of the stock were reasonable?
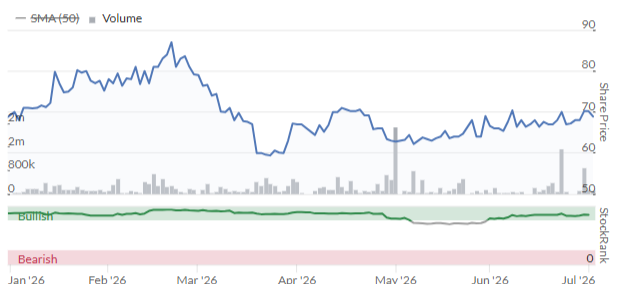
Quick overview of FY26:
Revenue fell 7.3% at constant exchange rates “as anticipated, reflecting softer market demand alongside the strategic decision to focus on the quality of revenue.”
Gross margin improves from 28.3% to 30%.
Underlying EBIT up 9% to £16.3m.
ROCE comes in at 8.5%, improved from 8.1% the prior year.
This is higher than Stockopedia’s calculation from the statutory numbers:
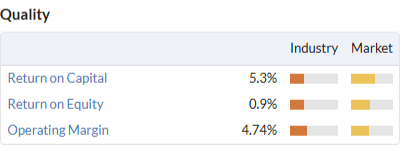
Regardless of whether a fair ROCE number is 5-6% or 8.5%, it’s clear that these are fairly ordinary returns - and in the ballpark what you might expect from a company that designs, engineers and manufactures “industrial fastenings”.
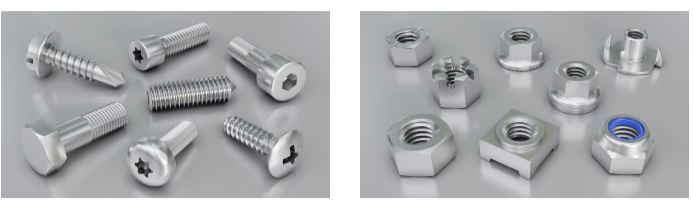
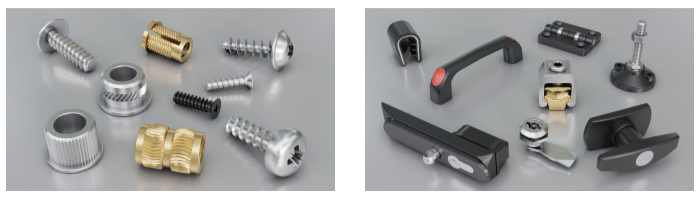
Pics from their product page:
Statutory numbers
The actual PBT result is only around breakeven at £0.1m, despite an "underlying" PBT of £12m.
This is due to c. £12m of "separately disclosed items”, i.e. adjustments to the accounts.
Of these, by far the biggest is £6m spent on something called Project Ignite: “the implementation of the Group's cloud-based ERP system, Microsoft Dynamics 365.”
There’s another £2.4m on “restructuring and transformation costs”. The previous year, there were £2.6m of such costs.
Another big item is a £1.4m write-off after the company ceased manufacturing in Malaysia.
Trifast has also been losing money to something called “facilitation payment fraud”. I believe that a facilitation payment is a form of bribery - has Trifast been fraudulently induced to make such payments?
Overall, the level of adjustments to these accounts is very high.
In general, I do not allow companies to adjust out their ERP software costs or their “restructuring and transformation” costs, as these types of costs seem to occur every few years, or even every year in some cases. I see them as a normal cost of running a business, not an exceptional cost, and I'm frankly a bit sick of companies telling us that they are exceptional.
The only compromise I’d be willing to entertain is to maybe spread out the cost of a very large ERP software expense over more than one year. So if you really wanted to spread out the “Project Ignite” costs over a few years, rather than putting them all in a single year, I could go along with that.
Outlook sounds fine:
The Group enters FY27 with improved operational and financial strength, structurally stronger margins, enhanced earnings visibility and a clear path back to profitable top-line growth, focused on key growth regions of North America and Asia.
Positive momentum has continued into FY27, with the commercial pipeline the strongest since the strategy was implemented.
Looking further ahead, “The Board remains confident in achieving the Group's medium-term EBIT margin target of >10%, underpinned by structural improvements in efficiency, mix and pricing.”
EBIT margin for FY26 was 7.8%, up from 6.7% the prior year.
CEO comment:
We are delivering what we said we would do: improving EBIT margins through disciplined, sharper execution and focused strategic change.
FY26 demonstrates that the Rebuild phase is working. We grew profits and expanded margins in a softer revenue environment, reflecting a deliberate focus on quality of revenue over volume.
Graham’s view
I have zero criticism of anything I’ve read here, in terms of what management are attempting to do strategically: focusing on the quality of revenues, and using EBIT margin and ROCE and their key performance indicators.
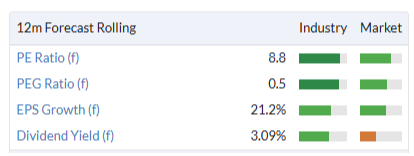
I’m just not convinced that this stock deserves to trade at a much higher earnings multiple than it already does, given the type of business that it is:
If the results were completely clean, I might be able to take a mildly positive view. And for future reference: if we see really clean profits in H1 or at the next full-year results, I should consider that. I'll keep a close eye on the "separately disclosed items", as always.
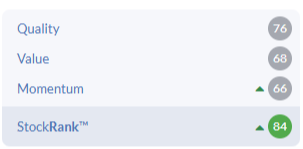
For now, however, I’ll stay neutral on this Super Stock. The algorithms like it more than I do:
James's Section
Concurrent Technologies (LON:CNC)
Up 1.3% at 271p (£232.7m) - Concurrent Technologies secures $9.4m order from US Defence Prime Contractor - James - Amber
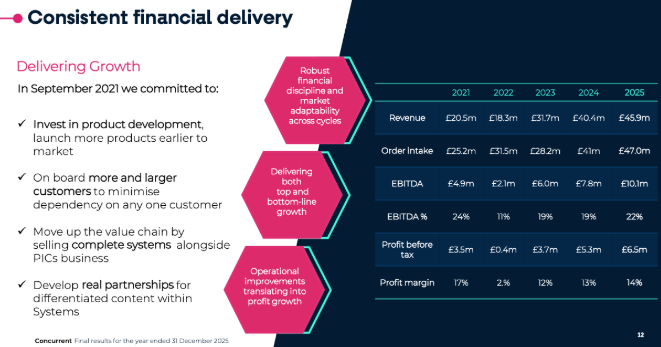
Concurrent’s announcement of a $9.4m US defence production order pushed the stock into positive territory for the day. The order – its share price up around 1.8% at the time of writing – adds to a circa £17m, four-year European defence contract announced on 11 June to supply over 3,400 VME-based computer board units for ground-based air defence systems.
Both these announcements follow a strong set of full-year results, where revenue rose 14% to £45.9 and pre-tax profit up 25% to £6.5m. The company said it was confident of delivering results in line with market expectations for FY26 – Cavendish have forecasted revenue at £52m and EPS of 7.8p.
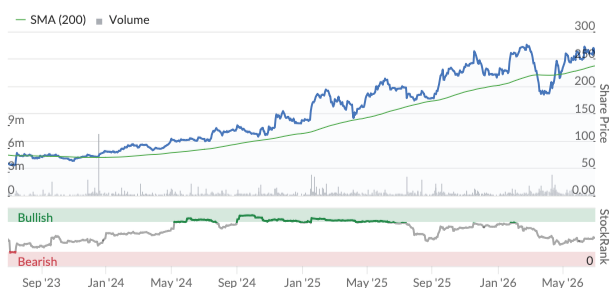
A broader look at the business's performance since the turn of the decade is very reassuring. Revenue has grown from £21.1m in 2020 to £45.9m in FY25. The consensus forecast sees that figure hitting £59.7m by FY27. Over the same period, net profit has shifted from £2.75m to a projected £8m.
This is the type of growth that investors are willing to pay handsomely for… and that’s exactly what’s happening here. The stock is trading at 45.5x earnings from FY25, and the projected earnings see that figure fall to 36.6x for FY26 and 29.3x for FY27. Coupled with a PEG ratio of 1.48, there’s no clear value signals.
Living up to the valuation
Can it satisfy the valuation? This is the million dollar question. Let’s take a closer look at the business.
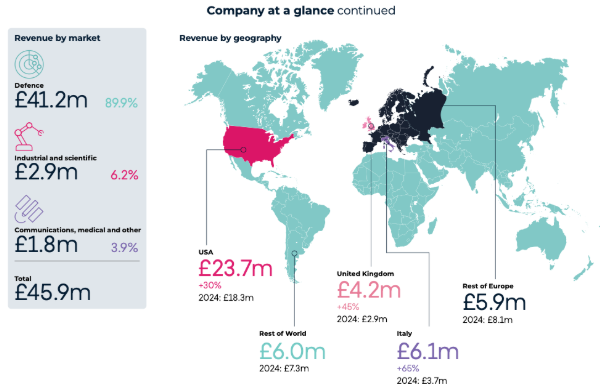
Concurrent designs and manufactures rugged embedded computer technology – hardware built to survive extreme environments and combat conditions. Unsurprisingly, defence is by far the company’s largest segment, representing 89.9% of sales, and its customers include some of the largest primes including Raytheon, MBDA, and BAE Systems.
Interestingly, its largest customer represents 13% of sales, and its second largest at 6% – this suggests sales aren’t overly concentrated as they can be in the defence sector.
Source: FY25 Report
Once a customer designs Concurrent's hardware into a programme, it typically stays there for that programme's life – often seven to ten years. That's the source of the group's order visibility: FY25's design wins alone carry an estimated £145m of lifetime value, work that hasn't been booked as revenue yet but is expected to convert over the coming years. Record order intake of £47m in FY25, plus the two contract wins since the year-end, suggest that pipeline is still growing rather than plateauing.
Source: FY25 Report
However, the margin picture tells a two-speed story. Group gross margins rose to 53.3% in FY25, driven almost entirely by Products, which runs a 57% gross margin. The Systems business is the drag: its gross margin sits at just 16% (up from -7% in FY24) and it posted an operating loss of £0.3m.
It’s the Systems business that offers a lot of the company’s potential, however. Systems revenue rose 160% in FY25 although profitability was delayed due to slower than anticipated contracting. It’s a “watch this space” type thing.
Another factor in the company’s favour is the balance sheet: £14.4m in net cash and no debt, giving management room to keep investing in Systems and new facilities without needing to raise equity.
James’s view
Concurrent's order book and margin trajectory both point the right direction. What’s more, today's contract win is more evidence the pipeline keeps converting rather than plateauing. The margin picture is also largely positive, with the 14.1% operating margin ahead of the industry average according to Stockopedia data.
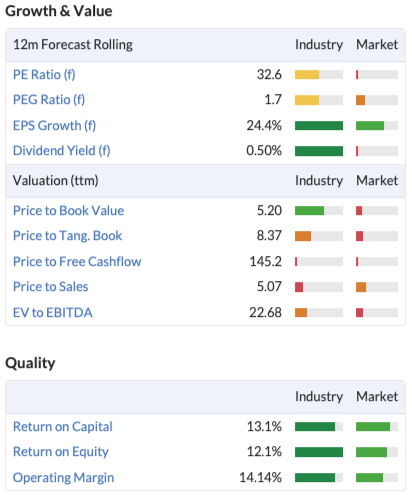
However, at 45x trailing earnings and a PEG above 1, the market has already given the company credit for a lot of this and potential catalysts look to be priced in –Systems reaching profitability and more design wins continuing to convert at pace are now expectations
I'll keep Concurrent at Amber: a well-run, genuinely growing business, but not one I'd chase at this price without evidence the next leg of growth is landing.
Currys (LON:CURY)
-1.5% at 161.2p (£1.79bn) - Building an ever-stronger Currys (FY26 Results) - James - AMBER ↓
Currys shares fell 1.5% today despite an 18% rise in adjusted pre-tax profit to £191m. This isn’t an unfamiliar story to those of us who watch the market closely – the stock has surged approximately 30% since early March and investors seemingly wanted more to keep that bull run going.
The results reaffirmed that this is a business on the right track. Revenue rose 6% to £9.3bn with like-for-like sales up 4%. Adjusted EBIT rose 13% to £255m and adjusted EPS rose 19% to 13.4p. Both divisions grew: UK&I gained 60bps of market share in a market that actually shrank 1.3%, while the Nordics delivered EBIT growth of 26% (currency-neutral) on revenue growth of just 6%.
Beyond core electronics, iD Mobile subscribers grew 18% to 2.6m, credit sales rose 10% to £1.2bn, and Services revenue grew 7%.
Currys also announced that it’s launching a new £50m share buyback (via Panmure Liberum, cancelling all shares bought), immediately following the successful completion of its previous £50m programme on 2 April 2026.
The broader picture
The company has delivered improving results since a post-pandemic nadir around 2024. Since then, revenue has risen from £8.5bn to the £9.3bn posted today. Forecasts point to that figure hitting £9.6bn in FY27. Net profit has been very irregular, but a growth pattern could be emerging with analysts pointing to FY27 net profit of £150m, up from £108m in FY25.
However, as the data suggests, there’s certainly not enough evidence to call Currys a consistent compounder yet.
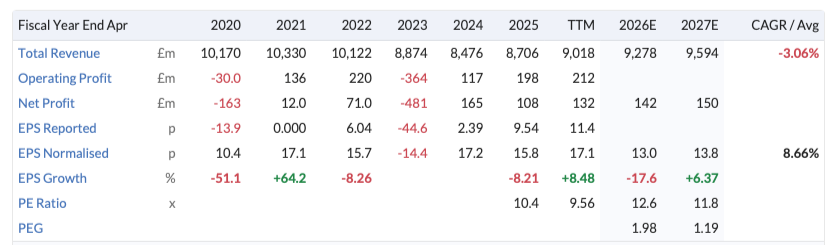
The broader irregularity of the numbers represents a few things. Firstly, Currys sold its Greek and Cypriot operations to Public Power Corporation in April 2024 for £175m – it contributed £637m of sales in FY23.
The wider environment was also quite weak after the pandemic. People had already bought laptops, TVs and home-office kits during the pandemic, so demand normalised down hard. This was compounded by the UK and Nordic cost-of-living squeeze hitting discretionary electronics spending specifically.
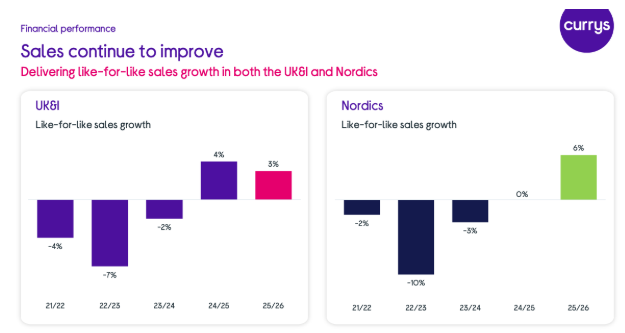
Source: FY26 Results
What’s the business really worth?
Shares are up over 300% over three years. It’s a spectacular turnaround story. Of course, these bull runs don’t go on forever – even “king of the turnaround” Rolls-Royce has plateaued in recent months.
I think there’s cause to look a little more critically at the proposition Currys presents. My take: it’s a mixed bag. Some positive signs, some less positive signs.
It's currently trading at 11.8x forward earnings, around average for the industry. But the business carries more debt than the headline suggests: Currys highlights net cash of £176m, but that figure excludes lease liabilities. Once those are included, the group sits at a net debt position of £764m – a very different picture, and one that needs factoring in. On that basis, I don't think the headline PE makes this look particularly cheap.
Earnings growth is fine, but still relatively modest. Analysts are projecting 6.4% growth going into FY27 which points to a PEG ratio of 2. That said, it outperforms on other valuation metrics such as price-to-book (0.8) and price-to-free-cashflow (5.1x).
Then we need to consider the margins. Retail doesn’t generate big margins, we know that, but Currys’ 2.35% operating margin is slightly below the market average, according to Stockopedia data. Margins like this will put a cap on the multiple investors are willing to pay. It's still a low-margin, high-volume retailer at heart, selling low-differentiation electronics in a category prone to price wars and thin gross margins. Growth alone doesn't change that; it just means more revenue flowing through the same tight margin structure.
The dividend yield is modest, but a possible growth area. The forward yield sits at 1.7%, but with coverage at nearly 5x, there’s scope for Currys to raise payments and potentially attract dividend investors even at this more elevated price.
James’s view
To me, the data suggests that this is a business that’s edging towards fair value. Analysts appear to agree. While there are 4 Strong Buys, 3 Buys, and 1 Hold on the stock, the share price target is 8.5% above the current price, implying a limited margin of safety. I’m by no means bearish on Currys, however, looking at the valuation picture coupled with broader macroeconomic observations – let’s be honest, this economy certainly isn’t flying despite the AI revolution – I think it’s prudent to turn Amber
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
Concurrent Technologies (LON:CNC) James - looks like the pundits have taken time to read your analysis and come to much the same conclusion - too highly priced - so the early gain has now gone to a small dip!
Currys (LON:CURY) the comments on Currys seem reasonable, but I notice that both the share price and the EPS were double current levels 10 years ago. Is this because customers started buying mobile phones at other shops online?
Retail was a different ball game back then, businesses struggle to keep up with change.
On Currys (LON:CURY) - there's a big elephant in the room. Which I was musing about a week ago.
I'm not an expert in consumer buying behaviour and mindset for expensive electronics/white goods. But my personal view is that if there's a sharp price rise, people will:
None of which is good for a fixed-cost business of a big store network and delivery trucks. At least the pain should be temporary with all three above.
I remember reading earlier this year that the phone industry is expecting a decline in units sold this year? Due to the chip shortages driving up prices and people choosing to defer their handset refresh. This logic probably then extends to other electronics... laptops, cameras, TVs, etc...
Apple raised the price of iPads 20% last week, blamed the cost of the computing chips. This must be bound to be repeated across the board.
there was me hoping ipads would coem down in price they all looked uber expensive teh other week when i was looking - must have been looking at the ferrari verson rather than the skoda - of to tick tock to get 7th generation for 80 quid.
Currys (LON:CURY) May I ask if including leases in debt figures, as James did today, represents a change in
strategy for the DSMR?
Personally I exclude them (as they are a future liability not yet due & no cash proceeds have ever been received) and looking back at other commenters they seem to do so too
I appreciate that each write has their own style of analysis (& the site is richer for it) but for the sake of consistency and comparison it would be easier if the same measures were used
Good Q, AstonGirl! I think it's OK for each writer to make up their own mind on this. Obviously there is a loss in terms of consistency, but overall I think it's better for everyone to see multiple perspectives on a stock. Open to hearing other people's views on this! G
Open to hearing other people's views on this! G
I think if there is no indication that the stuff being rented may be obsolete i would always exclude leases from debt calcs - its a bit nonsensical if you know you will be using premises for next 10 years arent paying any actual finance charges to default to this nonsensical situation. Note its good to know what the data is - and i might worry more if i though they might be tied into long leases they couldnt use. so i dont see why it couldnt simply have suplementary note ref leases - heck even include teh debt figure but dont include in the headline number as it really will nealry always be a future profits and loss bog standard expense.
I am presuming there is no funny business with regard to rent costs hitting the profit and loss - i remember been slightly perplexed how GYM (LON:GYM) were treating their lease stuff
i guess each to their own is ok as long as leases included in debt are flagged up
Hi Graham,
During Currys (LON:CURY) sale of their Greek and Cypriot business (well known to me!) the leases were taken out of the EV.
Only from that, one should regard the leases from this company as debt. But there is also a figure in the accounts that interest is paid on most of these leases so IMO we shouldn’t even be discussing this.
I agree 100% with James, the writer of the DSMR report.
All the best
I often use ChatGPT now to understand parts of businesses better than I would if I just read their annual report/looked at their website, as well as expanding possible investment opportunities and ideas. It's all great, but none of it feels like a particular edge in investing.
Is anyone using AI in a way that they feel is giving them an investment edge or using particular prompts that they find are giving an edge?
I use Gemini and Claude. Use both to challenge the other . Is it useful ? , saves hours of research. Like all research though the choice is ours- depends on risk appetite, income requirements etc. So it does help look at a company. Gemini is the best, Claude is a bit USA biased.
I keep hearing about this World cup thing but really have not got a clue. When does it start?
Anyway, if grown men enjoy watching 22 blokes in shorts chasing a piece of leather about, well, fair play to them. Personally I'd rather sit back and watch a good match of Beach volley ball.
It was one of the highlights for me of the 2012 London Olympics, Beach Volley ball on Horseguards parade! I’m not sure what Liz and Phil thought but I loved it!
Baltic Classifieds (LON:BCG) FWIW this company is on my radar. It's a holding of Baillie Gifford UK Growth Trust (LON:BGUK), which has a quality bias.
It has a massive 42% operating margin. Iit has been growing its revenues and operating profits well into double-digits and looks like it has moved into a net cash position. It has also been buying back its shares.
I don't own, but I find it interesting.
Share price has flatlined since Dec 2025. It's reminiscent of the charts of AUTO , RMV, EXPN, RELX, SGE and maybe a few others. Some of the charts are almost suspiciously too flat. Valuations seem fairly reasonable as well. I've been wondering if a lot of these kind of quality shares are quietly undergoing accumulation.
Anyway, just my 2 cents.
Hey, Mark. How do you feel about the disintermediation risk in the marketplace segment? I actually cover marketplaces -- with another hat on -- but never BCG
It looks interesting especially based on the margins. I had a quick skim of the results and I calculate an op margin of 68%. How did you arrive at the 42% out of interest.
Also any ideas as to what's caused the decline in share price? Fears of AI and the impact on their business. I note the commentary confirms they have initiated a further buy back subject to shareholder authority to purchase a further 15% of the shares, albeit they will take on additional debt to achieve this. Certainly one to keep an eye on.
I agree with your comments about the stocks with high operating margins and were previously viewed as "quality stocks". I purchased Autotrader (LON:AUTO) a few months ago and added a few more based on the recent dip. I note earnings forecasts have largely remained the same, but the SP has bounced back recently. I can only assume these are being accumulated by others in the market.
Re: margins. Yes, you're right, 68%. I was looking at the 5-year average.
Fears of AI are the likely culprit. The other stocks I've mentioned all have AI fears in them.
I too bought into AUTO, once on 7 May at 524p, and a bigger amount on 21 May at 462p. So I'm down a little on the first purchase but up on the second lot. I had been reading a little on technical analysis and it looked a good setup. A consolidation setup. 28 May is interesting because it reached a low of 427p, below the support level of 450p. But it was actually a false breakdown, and I heard it was a sign that the shares are going higher.
And indeed they did bounce. 511p now, and there is resistance around 520p. Maybe the shares will break down again there and the consolidation pattern will extend, but around 520p seems to be the magic number where it could pop after that.
It's all magic tea-leave reading on my part of course. I wouldn't necessarily put too much credence into it, but maybe in future I could use it as a guide to what might happen next if I like the fundamentals.
Given that AUTO has a forward PE of 12.8 and earns monster returns on equity and has been growing rapidly, the odds looked really good to me. The technical set-up was just a little icing on the cake.
Also, the fact that these "digital companies" fell as a group suggested to me that there was a lot of fear in the market. I'm actually quite surprised as to the magnitude. I think it is safer to invest in sectors that have sold off en masse than ones where the sell-off is isolated. It means that market psychology is in effect.
Amazons announcement that they are getting into cars is an additional factor that is weighing on AUTO. Plus you have the whole fear about AI affecting these shares in general.
We've seen with the TMT shares in the late 90's that the tech that was supposed to help companies (esp. publishers) turned out to be their downfall.
So there's an element of risk here. But then look at the other side of the argument. When the likes of Fevertree (and in fact former darlings like RMV, etc.) could do no wrong and there was only blue skies ahead, that's when valuations were crazy. Now the narrative has reversed, so has the share price.
Maybe that threat won't materialise until a couple of years, maybe never. Take a company like RMV, for example. Competitors have been trying to take a piece of their pie, but the network effect have proven too powerful.
It sometimes pays to have a little fear in the market.
It's all a calculated risk where one is trying to be more right than wrong.
The takeover offer for Capricorn Energy (LON:CNE) doesn't seem particularly generous.
As a holder I'm tempted to waIt it out and see if other firm offers materialise. Only yesterday they issued a PUSU extension to another suitor, so I think I'll see if anything comes of that.
Adding a starter position in Polar Capital Holdings (LON:POLR) today. Will add more if we get some vol as I see the price was all over the place yesterday.
Thanks for the analysis yesterday. Have held previously and took profits but I'm happy to reenter with how positive things look.
Just be aware that the big rise in AUM has been largely driven by the boom in AI and tech stocks. If you think this boom can continue then POLR will continue to do very well, but it is very exposed to this part of the market. I personally sold out recently after a nice run, but I do like the company and will continue to monitor its progress.
Indeed, personally I'm expecting big vol but new ATH by end of year. I don't want 100% tech exposure but I don't want 0% either.
Yes if you want a bit of tech exposure then POLR is a good and cheap way to get it. That was basically the reason I held
I bought CMC Markets (LON:CMCX) some time ago as a sister stock to my longer held IG group (LON:IGG) holding. Sure enough it was mainly negative in terms of capital appreciation for quite a while, and I did think of binning it, -especially with some negative views heard of the main shareholder. But either through indecision/apathy, I did nothing, and it now stands at a 171% gain!
As far as my PayPoint (LON:PAY) holding goes this remains in negative territory despite some averaging down and dividend reinvestment.
I don't know what this tells us about shares, and what strategy to have- probably nothing other than blind luck applies.
Now the decision arises on when to sell £CMCX ? I conform to the cliche of not wishing to crystalise a loss on my PayPoint (LON:PAY) shares.
I topped up my CMC Markets (LON:CMCX) holding this morning, following Ed's theory that once a significantly ahead of expectations trading statement has been made, more of the same often follow.
Yesterday's trading statement contained the following - "The strength of this performance reflects the scale of our B2B platforms driving operational gearing and delivering higher profit margins as income growth is delivered against a largely fixed cost base.
Our B2B platform business is well positioned to scale with several important milestones expected over the next 12 months and a continuous pipeline of new B2B opportunities.
Operational gearing and investing for growth through B2B platforms, products, technology and partnerships continue to drive profit margins higher."
In other words, not only have they put in place new systems which improve profit margins but they have new clients in sight which will expand their profits.
They have risen a couple of per cent since I topped up this morning.
It is difficult to know when to sell you do need to have a goal when you purchase. The rise in CMC Markets (LON:CMCX) (I don’t hold) is extremely sharp and may be due to the gambling customers using their website. This share did drop quite quickly after its last peak!
I bought into PayPoint (LON:PAY) 18 months ago as part of an income dividend strategy and am planning to hold long term. My only negative view on it is they are buying back shares and growing debt which I’m not convinced is good long term but feel there is still some growth potential.
Ref CMC Markets (LON:CMCX) I sold my stake yesterday after one bagging and then some. As a NAPS stock, should have held until the end of the year, but by removing my stake, the sheep I count at night jump higher and are fluffier.
Third one bagger this year thanks to STOKO, despite the odd gremlin, I do not understand the criticism of the site.
Thanks to all the STOKO gang.
Graham, fully expect your Mortgage Advice Bureau (Holdings) (LON:MAB1) position to revert to gain at some point
Hi Graham, I don't know if this is the right place to ask but it might be of interest to other people. I'm interested to know when Stockranks are updated with new company financials. If a company releases eg. H1 results, and they exceed expectations, when does that get crunched into the Stockranks? And what releases qualify? Presumably trading updates are out, but H1 & FY prelims are in? Or do you wait for the annual report?
Seeings as this question is being asked ...
I'm a bit confused as to how forward PEs are being calculated. On the top-right of a stock sheet under Growth & Value there is a forward PE. But this generally disagrees with the the PE ratio estimated for the next year under the Financial Summary/Fiscal Year End estimated data. It's a bit puzzling. Two different EPS figures seem to be used to get the forward PE.
I believe it's a blended average of the next two years depending on how far into the first year one is.
My understanding is as follows:
Stocko takes a data feed from (i believe) LSEG (formerly Refinitiv) on a daily basis each evening. This should include results data released that day, Interim and Full Year results for UK stocks, quarterly for US.
Stocko runs an overnight process which updates each stocks data for everything you see on an individual Stock Report. If a Stock releases results on a Monday then this should be reflected in that companys' stock report when you view it on the Tuesday. If the SR appears out of date then that may well be the fault of LSEG rather than Stocko.
Trading updates will generally not be reflected as they don't contain hard data.
Graham , may be strange but I have no interest in the football, other than
how well Young & Cos Brewery (LON:YNGA) do out of it. England women play South Africa for a place in the T20 world cup final this evening at 18:30. Venue Oval .
Hi Charles
I am a long term customer of Young & Cos Brewery (LON:YNGA) pubs, I live in their heartland of SW London (I am not a holder).
Doing some field research, over past couple of weeks I have tried out three of the Cubitt pubs. The small chain of central London focussed pubs Young & Cos Brewery (LON:YNGA) have recently bought.
All three are excellent, in superb locations (one in Mayfair, two in Belgravia). They have a great feel about them. I sense they will fit very nicely into Young's. Also knowing where the others are located I can see these as great additions to the estate.
If you visit a Cubitt's the Alsop's bitter is excellent. The Cubbitt's Claret superb :). And, the white wine also excellent.
Regards
Howard
Keep up the good work!
Thank you.
The UK would be in a better place without the new religion, football.
Not true. Watching England brings people together..... and living in Scotland as I do, it brings Scots together in supporting the team England are playing!
Why would it be a better place? New religion? I've been watching / playing football for 50 plus years!
A better place would be one where everyone eligible would vote in General Elections and had a serious interest in the direction our country takes.
I would hardly call it a new religion. Football has bound communities together across generations and is part of life in even the remotest places. I have played football with the kids in the depths of the Amazon jungle on a lined pitch with white painted wooden goalposts and on the beaches of Brazil. Football has given me some great memories and life skills that I applied to running a business. Leadership, team work, camaraderie and humility. Football unites people across race, religion and social background.
Well done on your H1 performance of your 2026 watchlist Graham!
I'd just like to take this moment to thank you and the team at Stockopedia for the ideas generated from which I have profited. Not more so than yesterday when CMC Markets (LON:CMCX) rocketed up.
I first bought CMC Markets (LON:CMCX) in January 2025 having reviewed your 2025 watchlist and decided later on in the month to invest when the share price was at 258p. I held on to the share at the end of the year when you rolled it over into your 2026 watchlist, and this decision was supported by the happy coincidence that it also appeared on my (and Ed's) NAPS 2026 list. So this has been a "one-bagger" for me.
Thanks again, and keep generating the ideas from which we can assess ourselves and make our own decisions.
Lovely comment Marcus, thanks very much and well done - you've made more profit out of CMC than I have! Diehard IGG shareholder here. G
James Latham (LON:LTHM) I hold
Mildly optimistic commentary in these solid results? Another dividend uplift too and the new distribution centre soon to be operational. I feel very comfortable holding this stock through ups and downs.
Yes agree with your sentiments. They have a strong cash position and so can ride out the tougher times unlike some of their competitors. No reason to sell in the short to medium term
How nice to see clean numbers, no adjusted EBITDA here. If I read the balance sheet correctly (minimal intangibles) current market cap well is below Enterprise Value in a business which has consistently been a solid cash generator. Big investment in National Distribution Centre looks their main challenge over next year or two. Held since 2002.
I will be watching England at 1am on Monday morning. It is never easy viewing but as they say "60 years of hurt never stopped me dreaming"
You've got me thinking back 60 years when I was 21 with my new girlfriend on my arm, a lovely Swiss exchange student, walking through town on a sunny day. I already felt like a winner and the football got no more attention than a minute watching the game on a screen in a TV shop window.
Fantastic anecdote. That is what i call winning, pales compared to the stock market.
Don't keep us in suspense, what happened to the Swiss student?!
Back to Geneva, might as well have been Mars, no cheap air flight in those days, but it was the swinging sixties, so many girls, so little time.
Amen to that....
https://www.youtube.com/watch?...
Wonderful film and music
No chance, up for work at 0600
It is Monday 1.00 am, so Bank Holiday would be better on the Monday if you can pull a few strings.
you're right! Monday 6th July, 1am.
I plan to be safely tucked in bed Sunday night. Think the team aren’t playing well and playing Mexico at altitude will be a step too far but will keep my fingers crossed while sleeping
So often I see that commentators and stock pickers achieve above average returns by picking one or two stocks that get spectacular returns with no disasters in the others. Well done. CMC Markets (LON:CMCX) boosted my portfolio yesterday.
CMC Markets (LON:CMCX) started the day 20% up and just carried on motoring to an eyebrow-raising 40% intraday stormer. Extraordinary. With EPS at 50p not looking expensive either so a likely beneficiary of Ed's post-results drift. Three upgrades in succession (so far).
It's just become a high QM (growth) stock
It was anyway before yesterday.
It CMC Markets (LON:CMCX) also passes 23/24 of the Phil Hoffer screen. I might be late to the party, but at least it as started!
I bought CMC Markets (LON:CMCX) into QM Growth Blueprint on the 8th June at £4.65
There is a scenario where the SP goes above 800p but it may not be straight up. Price exploration territory.
RE: CMC Markets (LON:CMCX)
There is a scenario where the SP goes above 800p but it may not be straight up. Price exploration territory.
Based on their figures yesterday and making a few estimates around tax rates and variable remuneration costs then it looks like they'd hit about £170m profit after tax for a PE of 11. That's slap bang in the middle of their PE range (although it maxed out at over 20 in pandemic times).
Historically, CMC's earnings have been highly cyclical so going much above this assumes either some investor exuberance or that their revamped B2B business lines will be more sustainable. The latter will only become visible over time, but I'm reasonably hopeful that the business will be a bit stickier going forward.
Against this CMC has a habit of surprise earnings announcements - in both directions. While yesterday's announcement was very pleasing I'm not counting future earnings or dividends just yet. To go from expecting £460m-£480m net operating income a month ago to over £550m yesterday says all we need to know about their earnings visibility. However, the operational gearing is very impressive and speaks volumes to the work they've done over the past five years developing their platforms (and for which investment the market punished them at the time).
I've held since 2019 and it's been a bumpy ride, although consistently picking up stock up at under £1.50 has proven to be very lucrative. Dividends now cover 50% of my purchase costs and on yesterday's figures next year's income will take it over 75%.
Peter Cruddas owns 60% of the stock and is 72.
timarr
Jeffries just put a price target of £7.30 on CMC Markets (LON:CMCX)