Webinar Discussion: Four kinds of share lose money. Do you own one?

Thanks to all 650 of you who joined us for the StockRank Styles webinar live last night (Thursday 8th). It was a topic we haven't covered in years, plenty of great questions, and a great deal of honesty in the polls. I promised to open a thread this morning so we could discuss.
Before we went into the depth of the topic, I asked which of four sentences sounded most like a share you had lost money on - there was a good spread of answers:
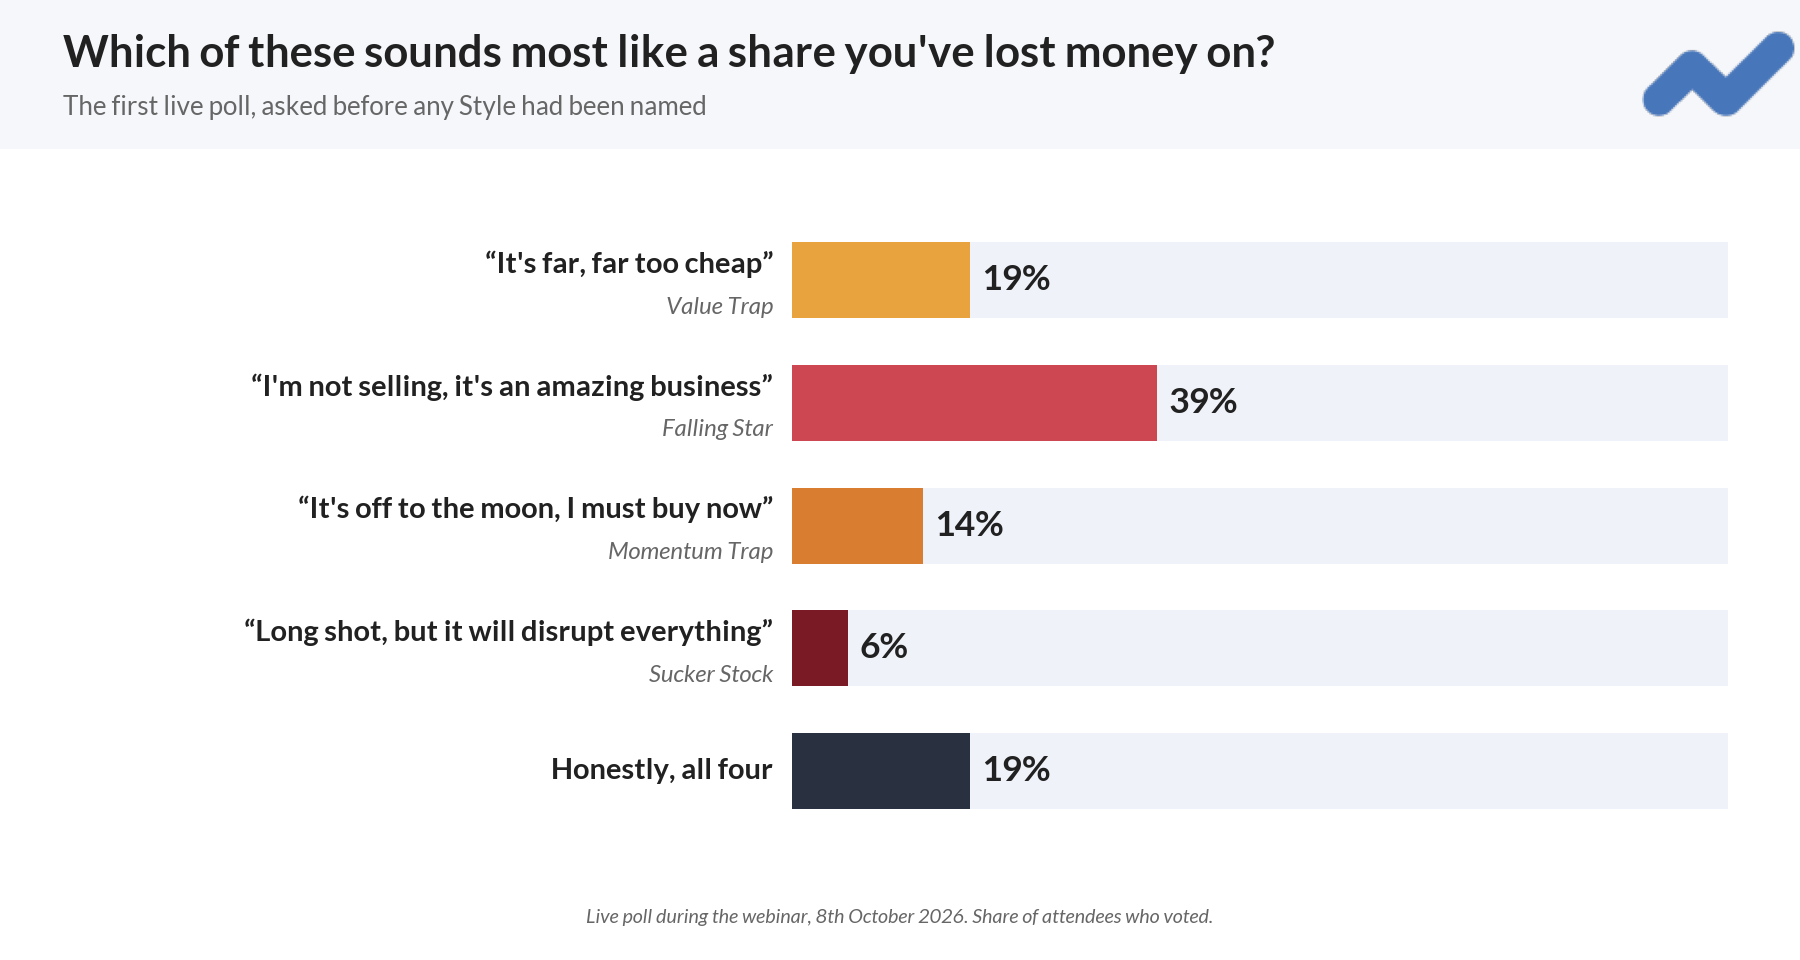
43% of you picked "I'm not selling, it's an amazing business". But interestingly, one in five of you admitted to all four. The idea behind the question was that all these investing errors map to one of the Style Classifications. I wanted to bring the psychology to life a bit - as frankly that's what normally gets us into trouble. I have owned shares of all the losing Styles - in some ways the toolbox here has evolved to help solve these investing mistakes.
We looked at a few case studies of the Losing Styles to bring them to life:
- "It's far, far too cheap" is a Value Trap. Cheap, and nothing else. Metro Bank was in the deck as an illustration - recovering somewhat now, but a long trap share period illustrated.
- "I'm not selling, it's an amazing business" is a Falling Star. A good business that gets too high a valuation and starts disappointing. Boohoo at 337p in 2021, 27p in 2024.
- "It's off to the moon, I must buy now" is the classic Momentum Trap. A rising price with almost nothing holding it up. ITM Power rose twenty-fold, then gave most of it back.
- "Long shot, but it will disrupt everything" is what we call a Sucker Stock. Low on all three of the ranks. Purplebricks was the case study.
Why this all matters
Ultimately - the losing styles really do underperform. Here's a chart of the last 13 years of stock market data - showing the average performance of each style if held for a 1 year holding period on UK data.
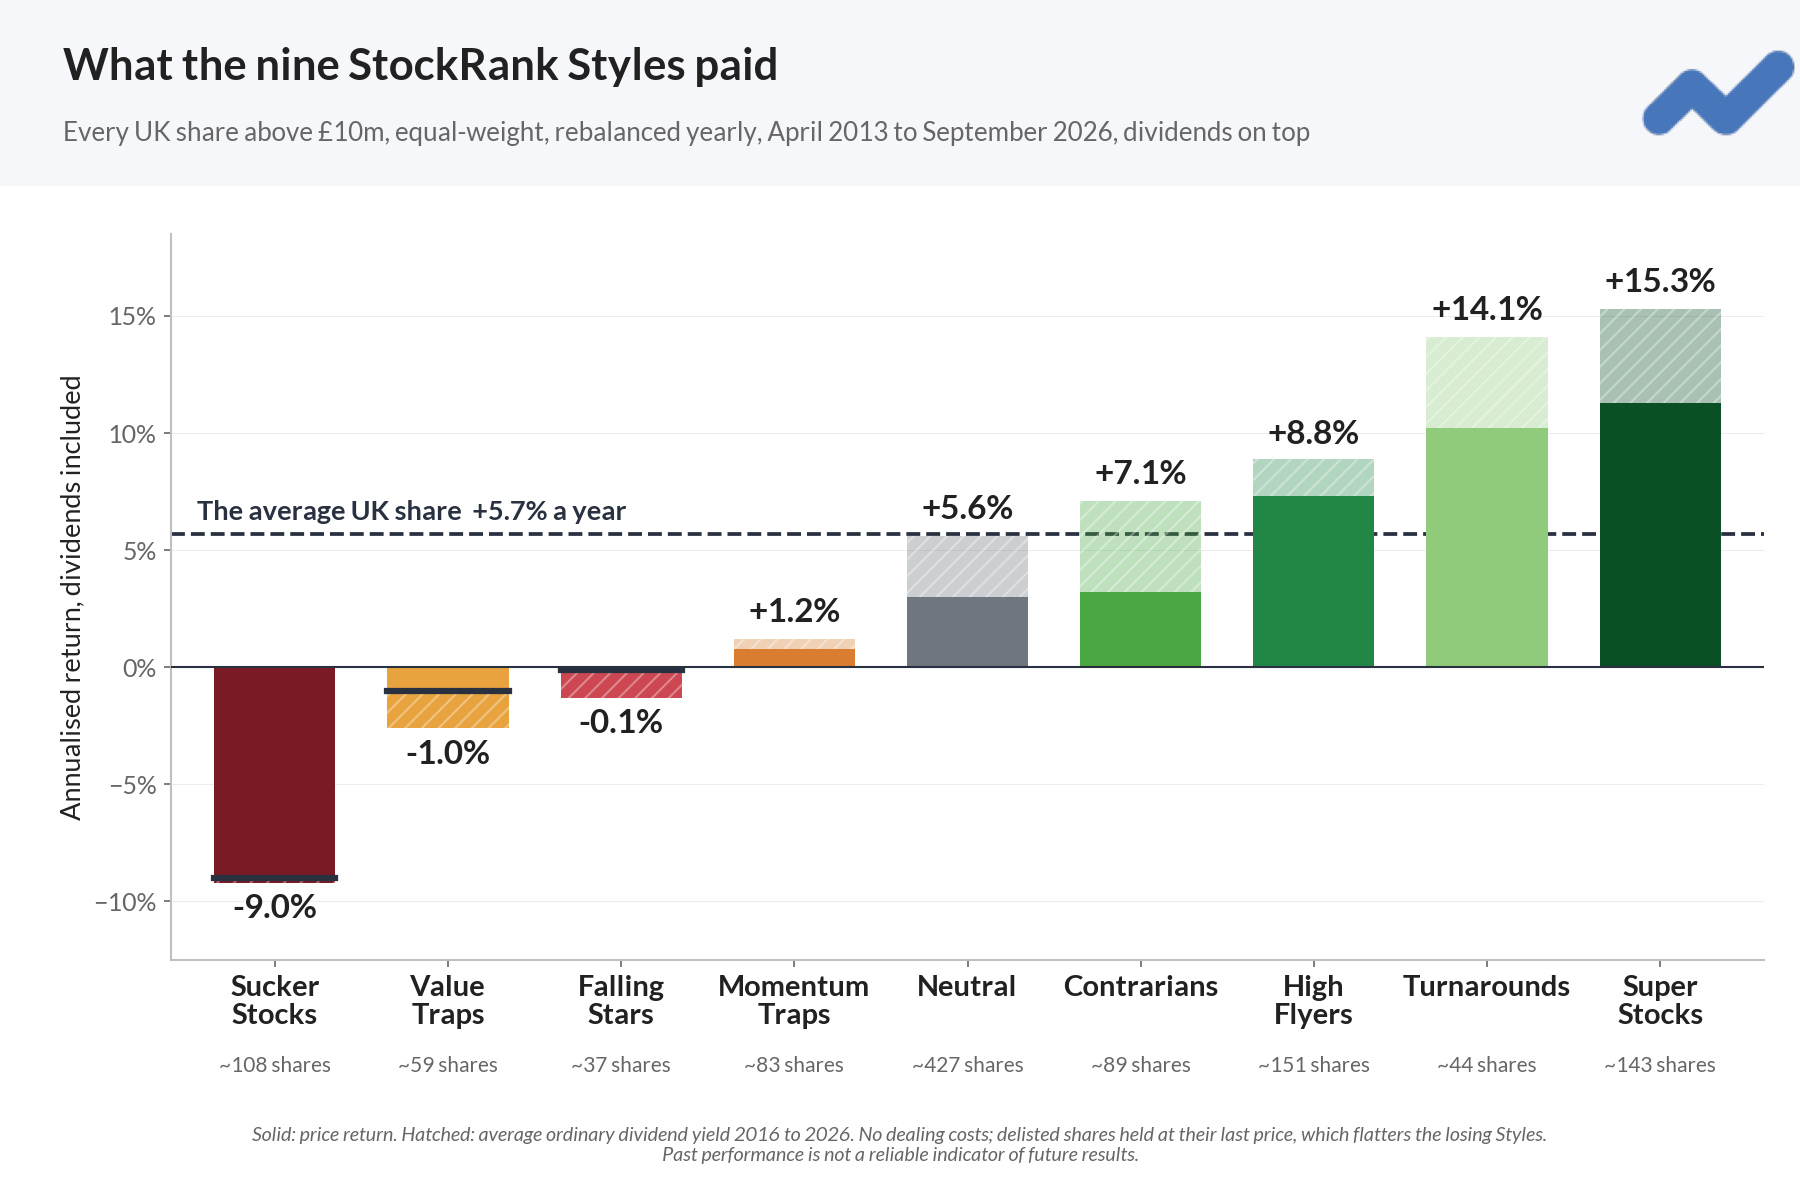
The average UK share made 5.7% a year. All four losing Styles trailed it; Sucker Stocks turned £100 into £28. All four winning Styles beat it. This leads to my core investing rule: never buy a share with fewer than two strong ranks - that's generally what "Winning Styles" display.
Do you own one?
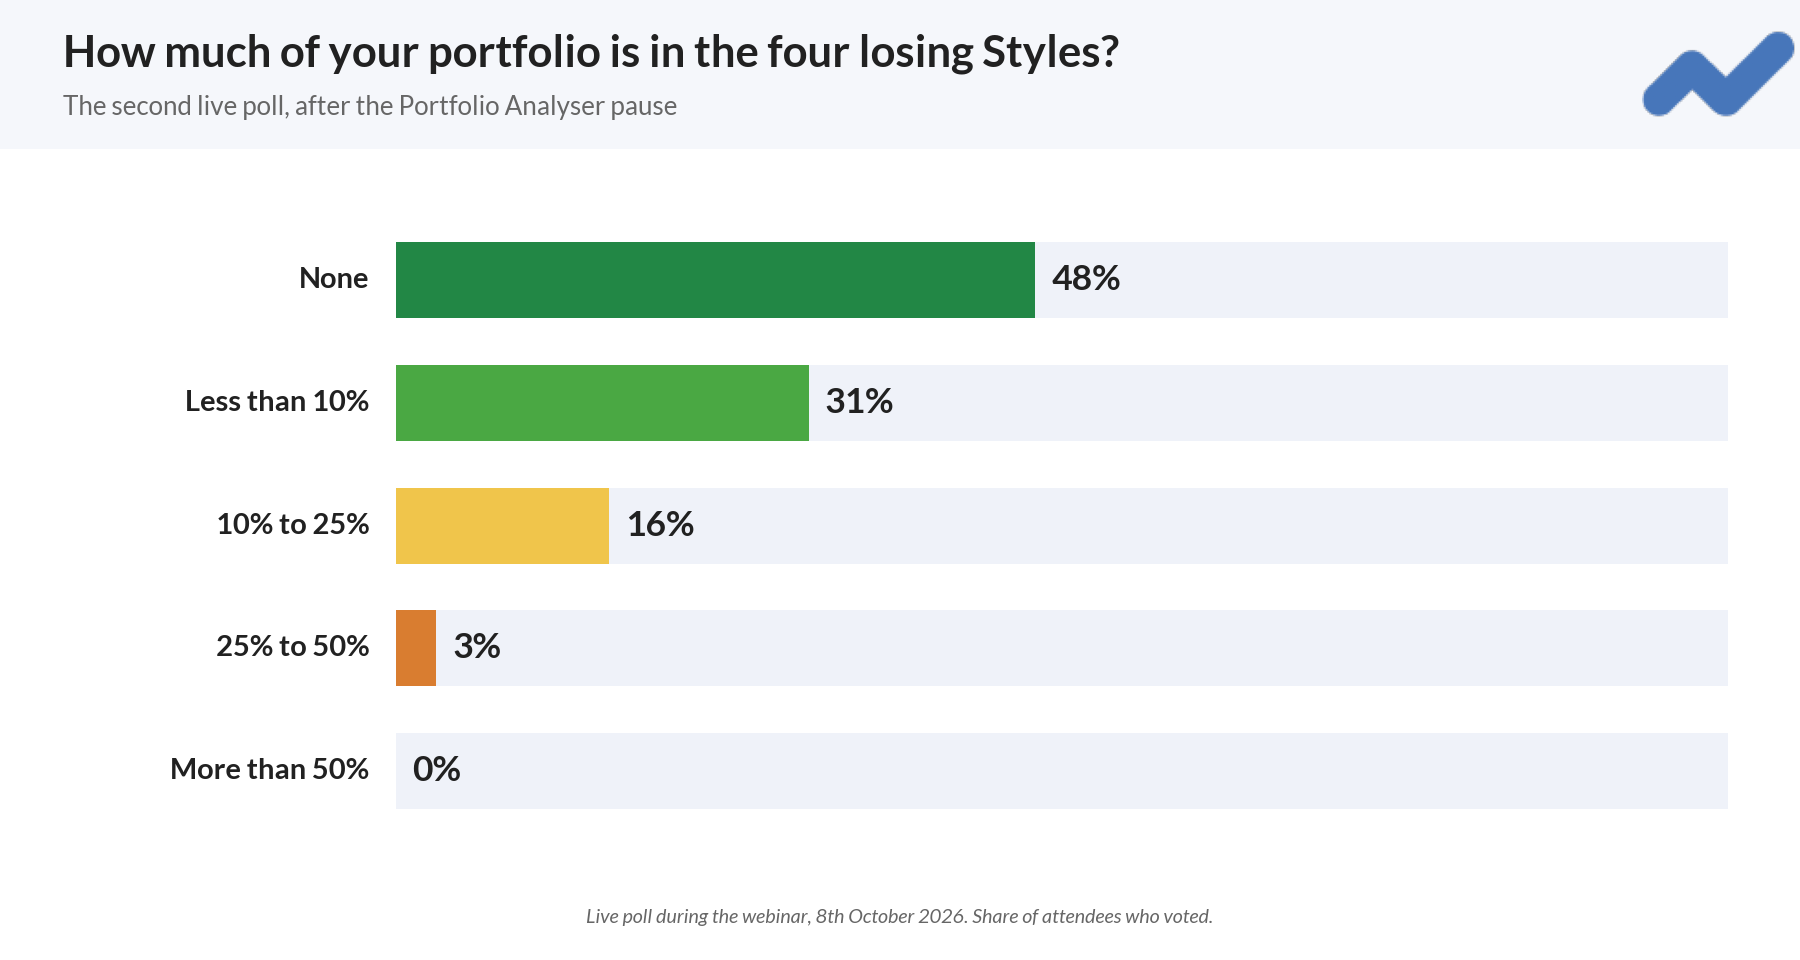
Halfway through I asked everyone to open the Portfolio Analysis tab and to view the Style pie chart - which shows your proportion of losing styles held. Half of you held no losing Styles at all which at least helps minimise a few headwinds. Of course, shares of any classification can do remarkably well - momentum traps may double, value traps can indeed recover - this is where good stock picking, research and judgement come in. So don't blindly go selling shares you know a lot about just because they are classified red - just use it as a flag to deepen your research.
Watch the replay
If you missed it live the Video is up on Youtube now - and you can download the slide deck here. The last ten minutes illustrated how to set up a stock screen to find the best performing Style/Risk combo of Speculative Super Stocks - and what a portfolio of those shares did every year since 2013. There's a stock screen to illustrate at this link too.
Please do discuss below - and if there are any follow on topics you want to see, please just ask and we'll consider.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

37 comments
Would be interesting to see how the style changes over time. Are subscribers able to create charts like this one?
I like this one, but with the ability to set the line at which the momentum rank (or whichever rank you choose) flips between Green & Red
I’d prefer the Ranks and Styles to be an indicator that you can add to the charts, so that we can also see in the top chart the moving averages, donchian channels, candles etc etc
There's a lot we want to squeeze in - but yes I'm keen to bring a few new additions to charts - whether on the Stock Reports charts and/or in the technical Charts themselves! I'm experimenting with various share price chart ideas through the newsletters and editorial - so if you enjoy them please do say and it all feeds back into product prioritisation. I personally do want to see company guidance changes on charts, and perhaps the style in some way - if space allows.
Pleasantly surprised to note that nothing below neutral in my portfolio.
wrt to charts. I doubt there is much mileage in trying to compete with Trading View for charting. However, finding a way to link new guidance with chart moves would be something that I don’t believe is currently available.
Currently I’m sure we all look for the stock rank changes and see how they align with SP moves (or not). Any easily viewed additional info would be welcome.
hi Ed.
As mentioned, I’d love to see the Ranks (including the combination Ranks such as VM) and Styles available in the charting tool as an indicator at the bottom on the chart like MACD, Volume etc. so that we can see how they correlate with price (and volume, ATR etc). The chart format you shared in your post last Friday was great (with change of colour +/-).
The only thing I’d add is the ability to define the level of the x-axis …eg. I’m more interested in when the Momentum Rank passes through 90 and 80 than 50, so I’d like to be able to set that number.
Thanks for all the great work!
-A
Great analysis
I was pleasantly surprised when i checked my portfolio just now that i didnt have anything below neutral in my portfolio - i must admit ihave a few trash holdings left that i wouldnt really ecxommend to my worst enemy. Must admit though i have in last couple of years tried to get rid of any dross that doesnt have some obvious redeeming features.
I probably still too many in the neutral category myselkf - they arent all bad companies though from my persepctive - eg i have B.P. Marsh & Partners (LON:BPM) and Zotefoams (LON:ZTF) and On Beach group (LON:OTB) - which i think are fairly decent companies - i have some long term stalwartds like J D Wetherspoon (LON:JDW) and Legal & General (LON:LGEN) which have done ok over the years. then i have the dross that somehow is lucky enough to have a neutral rating.
pretty sure up till recently i would have had a few more of the crapola style shares.
I think if one is happy for ones own reasons ignoring te ranks well - but i think thats some remarkably compelling data that suggests basket of the good uns will probably do better than what you may acheive on your own if you do go aff piste - more the fool us if we think we know better !
Hi rm, I would be interested in your thoughts on Zotefoams (LON:ZTF) .
I agree it seems a good business with a strong future. But I just cant bring myself to buy it yet, when the two top executives in the business have not put their hands in their own pockets to buy some shares in their own business personally. They rely wholly on options etc. This suggests to me that they may know something about future risk to the business that outsiders do not.
Hi Lochinver,
You weren't addressing me, but I thought you might be interested in my thoughts on Zotefoams (LON:ZTF). I sold out in summer, my reason being their outlook didn't sound too upbeat and even softening up shareholders for a potential warning.
Roland's write up in the DSMR very well summarises my thoughts:
https://www.stockopedia.com/content/daily-stock-market-report-wed-5th-august-2026-ztf-nxt-lgen-sfor-tpfg-vid-four-1055467/
https://www.stockopedia.com/content/daily-stock-market-report-wed-5th-august-2026-ztf-nxt-lgen-sfor-tpfg-vid-four-1055467/?source=stockreports_chart&scrollToTicker=LON%3AZTF
I have a feeling that there will be a better (re-)entry point in the not too distant future. I do agree that it is a good business and their expanding product line and strategic direction appears to be good, but there remains, in my view, a strong hint of a warning, or at the very minimum a slow down in the near future.
I expect a market update in early November, if last year is anything to go by.
Jon
PS, I hope those links work, but if not the report is accessible from the ZTF Stock report page, 5th Aug.
No sooner commented and a news announcement of what looks to be an interesting acquisition :
https://www.stockopedia.com/a/share-prices/zotefoams-LON:ZTF/news/01a1359e-5f50-7448-a444-73a5acb6ae9c
Just had a look at this Jon.
It will be interesting to see how they intend to change the acquired company from a very small, loss making enterprise to a larger, profitable one, with the same management as before running it.
This seems a complete no brainer investment.
$5 million is rump change - maybe they are pimping it out a bit but compared to $20 mill cost of them geting to similar position its obviously a bargain if those figures are correct and presuming they have the need to this add on niche.
In that regard they say the cross selling potential is obvious.
Many of the Group’s North American converter customers purchase both block and roll foam. The Acquisition allows the Group to offer these customers a complete technical foam solution. Prior to the Acquisition, Zotefoams could supply only one of these two formats in North America. The Group’s North American sales team can now offer both, while Verttec’s customers will gain access to Zotefoams’ application engineering, technical service and testing capabilities.
Plus it seems clear the plant is not running at anything like potential capacity - so hopefully any extra sales will have great operational gearning benefits ref more of extra droppig to bottom line.
The plant’s two extrusion lines have capacity to support several times the current production volume.
Reading between the lines perhaps its the case that the business was struggling to get the sales it neeed to push on whreas Zote should have the firepower to get that facility up to full capacity - hopefully.
I doubt its a game changer in itself but clearly they are looking to hugely expand their Us presence over time - so snaffling up stuff like this aids expansion and takes out possible competitor too.
I am not too much of a fan of over optimisitic targets that can perhaps only be acheived by perhaps issuing silly amount of new shares and debt that might risk bringing down the entire business if they tried to double up in one go via acquisition. I am slightly torn here - its great that they think they nearly treble profits medium term - but i would be slightly worried as to how risky their plan to get their might be. Ideal scenario would be long term contract similar to Nike that allowed them to simply build the extra capacity needed safe in the knowledge it would deffo sell - not sure if some of their presentations might have more detail with regard to how that cunning plan would work - lets just hope they dont treble the shares in issue to treble the profits. sometimes i think over promising stuff like that can be a noose round ones necks.
Fair, valid and useful comments rm.
I guess I got an immediate turn off from the announcement which tried to define profitability as EBITDA. Which is not appropriate for a manufacturing business. It makes me even more concerned about top management in Zotefoams.
I agree that Zotefoams should be able to leverage its sales contacts and channels to grow volumes. The problem you have is the incumbent management. They will find it very difficult indeed to adapt to their new world. They are no longer the boss, must get used to reporting to their new bosses, reporting numbers to HO and it will be interesting to see how they react to the new corporate world they now find themselves in.
This is one of the reasons why acquisitions and earn outs often fail. The goalposts have been completely moved for the incumbents, and resentment about how their lifelong ‘baby’ is now being treated can rapidly grow.
At the end of the day, though, in the big scheme of things, this is an almost irrelevant acquisition, so you may well be right that there is only an upside outcome.
we live in a big bad EBITDA world nowadays long live the bottom line "net profit" stat stocky still default to.
Ref the new acquisition clearly there is potenbtial for the prior bod in charge to be like a throraway toy if they are not needed - reality is though if the person in charge "knows their foam inside out" it could be a really useful person to have. One things americans will normally do is understand that they only have a job as long as they perform and keep managment happy and even then it may be gone tomorrow or today.
interesting thoughts rm.
I've had quite a lot of experience of American business culture, having been an FD of Uk manufacturers owned by people like Cinven, 3i, Barclays Capital and others.
One thing they most certainly do not respond well to is being told what to do by people ‘over the pond’
It would be useful rm to get some insight into your knowledge. You clearly have a lot of experience of dealing with US businesses. Would you mind sharing your background ?
Ref my knowledge well its kinda like someone down the pub - so i wouldnt really pay too much attention to what i say - i have zero expertise ref the us kinda the opposite really so in that regard its just only from following shares and the like that i get my picture of how i think it works - if i have an opinion i will voice it and often many disagree with what i say quite often (i dont mind being disagreeable my opinion is worth no more tha anyone elses and may be wong).
I dont think there is a need to overthink things in business - ideally you want 3 simple - things do what you do well and make decent margins and try and keep it as simple as possible. If you look at zote managmennt seem to be doing ok - and there doesnt seem to be shortage of demand for their products - i think its specialsed enough to provide some protection against uber cheap competitors - no gaurantess in life - at pe of 10 and with more "capacity" tuning up - and new ties ins and the like it looks ok - are they perhaps over reliant on nike well clealry thats given thme a great boost in soem respects its good that the tailwinds have died downa bit there and they have manged to still do ok.
One thing they most certainly do not respond well to is being told what to do by people ‘over the pond’
Yes you are right the history of uk companies pushing into the us has often been disastrous - i remember Tesco trying to do fresh and easy back in the day - with the backing of Tesco it should have been a roaring success (Trader joes has done just fine i think) - Tesco management just werent up to the job though so it certainly is different way of working on each side of the pond.
Great comments rm
I for one really value your contributions on Stocko
Many thanks for your thoughts Jon.
Zotefoams (LON:ZTF)
But I just cant bring myself to buy it yet, when the two top executives in the business have not put their hands in their own pockets to buy some shares in their own business personally.
I would be interested in your thoughts
I simply don't have this necessary demand myself - facts are not all people who are directors running business now will want to have the "skin in the game" - i am more interested in how good the directors are there are delivering profit improvements and running buisness fundamentally. I aint trying to sell the way i do it to anyone though - but when company has large valuation and original owner menagers are gone - well thati quite often what we have now. I am not epecting currently much to happen until they can evidence further improvement into 2028.
Note i am slightly lucky here i did buy at average price of under 360p - so it was materially cheaper when i bought in than it is now.
They rely wholly on options etc. This suggests to me that they may know something about future risk to the business that outsiders do not.
Well that can be said for anyone running a business - not sure what i am meant to say to that. I have seen nothing from management that would make me want to go into paranoia mode in that regard. I hope they have integrity ref their actions. Are people who have higher % of their wealth invested in business not more likley to play funny buggers? ok you can see them selling. Each to their own here.
Ref this bit by Jon F
my reason being their outlook didn't sound too upbeat and even softening up shareholders for a potential warning.
Well as luck has it they have done a random in day update here this afternoon where they have said - with only 2.5 months of the year to go i would be surprised if they were to warn this year from where we are now.
per company today
accordingly, the Group’s full-year expectations remain unchanged.
To be fair to the managment here they have reasonably well flagged up that the footwear stuff was running at an exceptionally high rate and normalisation would be expected - they have also been really clear that moving manufacturing around will deffo cause some issues. To me the positive impact of having materially higher capacity and presumably having capacity in place where its well placed and probably uber cheap - imho leaves them well placed to be positive even if there are teething issues ref the new new. imho the outlook ref 2028 when it comes on screen if its expected to be positive should be good news - with higher capacity i am expecting 2028 to be good year albeit until i see actual broker notes i aint gonna worry too much - with p/e of 11 i am happy to hold.
It doesnt appear to me that they are short potential customers so i can only see the extra capacity as being win win unless we get some bad news.
dont get me wrong it is some uncertainty and one may take the viewpoint that Nike are still doing pants which aint good for their Nike agreement. And they do have alot of moving parts ref capital expansion partners and cusrtomers .
In summary do i think they have any need to be "pimping up this years and next years forecasts" - absolutely not. I am hoping the forecasts are reasonably cautious and realistic as one would hope.I take comfort from the fact they have delivered and expectations over last 12 months have increased rather then a decreased.
Interesting bolt on qcquisition today too.
Many thanks for your response, rm, very helpful
For those not able to open the screen link, there was a post in another thread (I forgot who wrote it now), but if you click the link, then edit the "www" part to "app" it should work. See below:
https://app.stockopedia.com/a/screens/p-speculative-super-stocks-by-rank-1429873?view=auto&viewType=table&page=1&range=1year
My wife (admin department) found the seminar on YouTube Ed, she handles our cash, I do shares. So Liverpool v Man City was exchanged for your seminar and worryingly my wife (more geeky than me) suddenly found equities and Stockopedia interesting! After we'd watched it all I was challenged as we checked our portfolio on why I'd bought several value traps many years ago WJG for example. Who knows were this interest will end.
Outpacing you on returns if I know anything about other halfs!!! ;)
That was an easy target for your wife to pick up on, like you I shaould have sold my Watkin Jones (LON:WJG) years ago and she would never have known what a dead loss bought at the wrong price it was.
Ed - One problem wth the sector analysis is that a portfolio with a significant exposure to investment trusts places them all in financials. Which is an unfortunate distortion because the IT's will obviously be spread around different sectors; commodities, emerging markets etc. Some IT's still dont have stock ranks.
What happened to the stock screen link, appears to have been removed.
Hi Ed
In your weekly email ‘The trend is your friend - stop fighting it’, you showed charts with Style and Rank changing over time as an indicator at the bottom of the chart. That’s what we need!! Are you planning to release that in the product? (Or is it there already and I’ve missed it?). Thanks.
yes pls. I 2nd and 3rd this !!
Must say I'm surprised this isn't higher in the priority list unless it is too resource hungry
Thanks for the webinar Ed, lots to consider.
The link above to the stock screen doesn't seem to work though.
I found your presentation last evening first class and blindly ticked the box claiming to have no losing style investments at all, having enjoyed a particularly good couple of months following on from your last presentation on big jumps and the importance of swiftly picking up on the daily reports and bold sentences telling me that a company is reporting, "profit well ahead of expectations". However the analytical tools supplied by Stockopedia and highlighted by you soon showed me that I was in a classic momentum trap with RGG. I scored heavily on this just before the recent alteration to the renters act, but this is what the meteoric rise in turnover and growth of the share value probably relied upon and following a 3.5% rise yesterday and my second thoughts this morning. Together with reading that the CEO has recently offloaded £1m of his own shareholding, I have taken a more cautious approach using your guidance and screen filter help to swap my own holding in this company for Steppe cement and GFRD. The tools have further shown me how without active rebalancing success by companies such as SEPL, CMCX and MPE can soon leave a portfolio with an overweight position in just a few successful stocks. Please do keep on at us all to think actively about our investing rather than be passive. All the very best to you and the team.
It was a very interesting and instructive Seminar/Presentation. Very revealing. I will look forward to watching the recording when it is available on the site, as I missed the last 10 mins. Suffice to say, even though my portfolio hasn't quite had the stellar returns of some, I'm fortunate to say, that none of my portfolio is in either of the 4 losing styles too. Maybe there's some luck there, as opposed to good sound judgement. Anyway, excellent stuff. Thank you Ed.
Very interesting webinar - thank you Ed.
I'm pleased to say that I don't have any of the losing styles in my portfolio - but I am screening on Momentum Jumps and Momentum Rank, with a Quality threshold of 60, so perhaps that is not a surprise - I'm naturally filtering them out.
I haven't really paid much attention to the risk profiles, so that was interesting. My portfolio is mostly Speculative, Adventurous and High Speculative - a refection of the momentum-focus, I guess.
There was a question (from Boris?) regarding when to sell ... I am trading Momentum Rank Jumps and also have a Rotational System based on top 10 Momentum Ranks (spreads by sector - sort of like NAPS but different). They are both 90/80 systems - so I am exiting on Momentum Rank (MR) <= 80. It seems to be working well.
The problem I have is that I don't yet have enough historic data (like you do!!) to understand the relationship between price and MR. It would be great to backtest it. Consequently, I can't really track the risk in my portfolio in the same way as I would be able to with a stop loss. I would REALLY like to see Momentum Rank as an indicator in the charting tool and/or the ability to access historical MR data in some way (other than downloading loads of PDFs!!). Is that on your development list?
Andrew - "The problem I have is that I don't yet have enough historic data"
There will be a lot to come on strategy simulation - I've been working very hard on this personally - and we want to get the systems deployed. There are a few data gremlins to work through - so it will take some time. And we have a packed delivery roadmap - so got to clear some space next year for the work.
Nonetheless the prototype is working - so if you want me to test something - do ask and I'll do my best to share stats.
Sounds like a back testing mechanism which would be amazing. I sometimes find my self asking, this time last year what would have this screen shown, to see how it would have done since then. Almost like being able to set a date also on a screen. I find myself using the print option to try and look back in time to see a share without the recent bias of knowing how the share price has since moved. Keep up the good work, first year using stocko and can't say I've put performed the market, I have learnt a lot.
Hi Ed,
Many thanks your reply and for offering to run some tests. The strategy simulation ideas sounds exciting ... let me know if want help with the user testing!
I'd be really interested in testing two MomentumRank (MR) strategies that I'm currently running live, ideally over a 10-year period (ie. including market reactions Covid, Brexit, Tariff Tantrums, Iran war etc) ...
A. Rotational Momentum. Rules are:
B. MomentumRank Jumps
What I'd particularly like to investigate is risk management and drawdown control.
My main questions are:
Ideally, I'd like to compare the original strategies with these risk-management variations, rather than undertake extensive parameter optimisation.
I appreciate there is a lot there, but anything you provide to help show whether MomentumRank alone provides sufficient downside protection or whether a simple additional risk-management mechanism would materially improve results.
Would this be feasible with the historical data you have available?
Many thanks,
Andrew
Not sure if my sim engine can do all of this... but this is a good test to see. Can you answer these questions.
Thanks Ed - excited to see what the system can do! Answers to your questions as follows ...