What's the right strategy for a newbie investor?

I recently wrote about a screen and a number of stocks that were making 52-week lows. One of the comments on the article series asked a thought-provoking question (reworded for clarity):
Should this type of investing (unhealthy companies and negative trending eps performance) be avoided by new investors?
I thought this was a topic worth exploring further.
Strategies we write about
First up, it's worth noting that we are unlikely to write about losing strategies on Stockopedia. We may write about the warning signs that tend to indicate poor investment outcomes, for example, my Gearing up to Fail article from a while back. However, we tend to avoid writing about shorting stocks (profiting from the share price going down) as this is a very advanced (and often risky) strategy. Hence, we tend not to screen for losers.
If we write about a strategy, in this case, 52-week lows, it is because it has some attractive qualities. Usually, the strategy is backed by academic studies showing outperformance against market averages. For 52-week lows, the seminal paper is one called Volume and Price Patterns Around a Stock's 52-Week Highs and Lows: Theory and Evidence, where Steven Huddart, Mark Lang, and Michelle Yetman found that buying a basket of stocks that hit 52-week lows outperformed the general market.
Of course, academic evidence alone doesn't guarantee outperformance. Sometimes the market adapts. For example, when Richard Sloan published their research into the accrual anomaly in 1996, the effect promptly stopped working. (The accrual anomaly found that stocks where cash flow more closely matched earnings outperformed those that didn't. The thesis was that investors focused too much on accounting earnings and not on cash generation.) It stopped working because, presumably, practitioners read the paper and adapted to focus more on cash flow and not just reported earnings. Momentum is the strongest-performing academic anomaly, yet funds created to exploit this have largely failed to outperform the market. It seems that the impact of costs, or other factors, may mean that a strategy fails to deliver in practice, at least when implemented in line with the academic research..
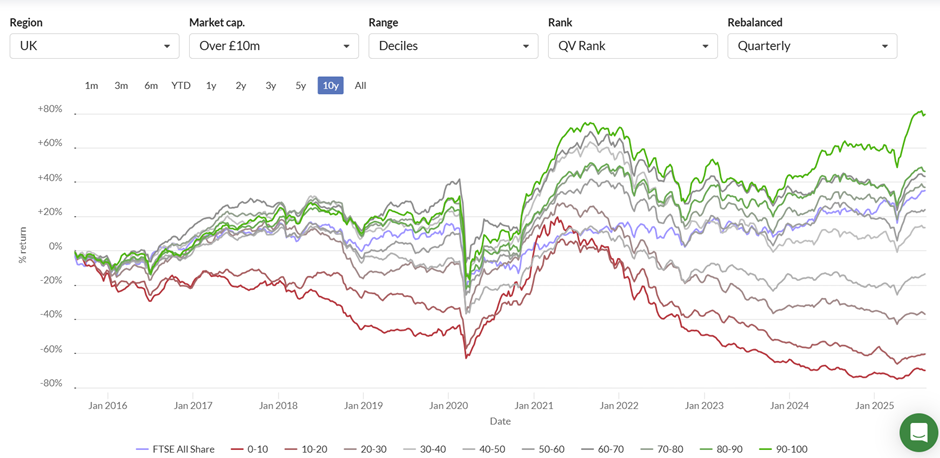
In addition, Stockopedia has tools that show how different strategies perform. For example, the Contrarian style of investing that most closely matches a 52-week low has a good track record of beating the market over the last 10 years:
There are also a number of Guru screens, based on the writings of successful investors, and these can make for interesting articles. The assumption is that by trying to replicate some of the ways of successful investors, we may see similar success.
While all of this is intended to give investors a chance of beating the market, it doesn't mean that all of these are suitable for newbies. Before I look into what these strategies might be, here's a sobering thought:
Expect to lose money!
It takes time to develop the skill of being a successful investor, even if success here can be well-defined. What makes investing such a fascinating pursuit is that we are competing against other knowledgeable and motivated individuals. Investing differs from gambling in that it isn't a zero-sum game (or negative if you exclude the role of a bookmaker), and we all benefit from the tendency for GDP to grow and be reflected in positive returns on equity. However, if investors want to beat the average market participant, i.e. beat the market, this is a difficult task over the long term, precisely because other investors tend to be intelligent and motivated. Being likewise isn't enough; investors need an edge. That is, the ability to know something others don't, analyse information more effectively, or behave more rationally than the average investor. While the Stockopedia tools can certainly help with the latter two of these, the reality is that newer investors probably won't have the skills to employ them effectively. They also won't have the experience to know what they don't know.
Looking back to my own formative years, when I first started to buy individual stocks, my investments included a prospective gold miner with a vast resource, which was popular with a well-known resource investor at the time, but the company operated in risky lands and had no financing in place. I have a First in Maths from a good university, so even as a newbie, the mathematical part of investing came naturally to me. For example, I easily created extensive discounted cash flow models of another resource company where I had invested based on the prodigious cash flow they were generating from a direct shipping operation. However, I failed to realise that when the commodity prices fell in response to the Great Financial Crisis, the company wouldn't just face reduced demand for their product, but no demand. Needless to say, I lost almost all my money in these first investments.
The good news is that investing is a marathon, not a sprint. It is the long-term consistency of results that matters when compounding wealth. I was in full-time employment at the time, so I could rebuild my capital, and I learnt from my mistakes: to be more sceptical with pre-revenue companies, to trust my own judgement not rely on others, and to understand the underlying economics of a business rather than rely wholly on the false precision of a model. Given that these mistakes are now around 20 years ago, having a long-term investment horizon means that the daily noise of price moves in my portfolio today dwarfs what I lost in those initial learning exercises.
Investors absolutely need to be prepared to lose money, or at least underperform the market, in those early few years as they develop their edge. They shouldn't be disheartened by losses but treat them as learning exercises. Indeed, perhaps he worst thing that can happen to a newer investor is a string of initial good investments. While this may sound great and a sign of success, it is equally likely to be due to luck or very strong market conditions. The problem is that when early wins become losses, the investor has already probably become overconfident (as we all tend to do), and the size of the eventual losses are much larger. With investing, it is better to fail early, as long as investors learn from the failures and keep going. This is also why investors who start with a large sum compared to their income, say from an inheritance, need to be especially wary – unless they are careful, the price of their lessons may be much higher than most.
Diversification as a learning opportunity
One of the other lessons I learnt early on was the importance of appropriate diversification, having been painfully under-diversified at times! For most investors, there is a trade-off between the costs of investing (broker fees, stamp duty, spreads, etc.) and the benefits of diversification. There is also the risk that those with a huge number of holdings simply track the market. I believe newer investors are better off holding more holdings, even if the amount they have in each is somewhat suboptimal compared to the trading costs and time to do detailed research. As well as limiting the negative impact of a single poor investment decision, more diversified newer investors are also gaining far more learning opportunities. Of course, Stockopedia allows subscribers to have multiple portfolios, and there is nothing wrong with using this feature to have paper portfolios. However, in my experience, nothing matches having actual money on the line for learning quickly.
Lean but don't rely wholly on the Stock Ranks
The Stock Ranks give investors a great way to assimilate many pieces of important investment information into some simple metrics. Given the long-term performance of the high Stock Rank shares, it may be tempting to be a quant investor and only buy Super Stocks. There are a few issues with this, including possible crowding in specific sectors or people businesses. (I looked into this in more detail here.) The biggest issue for a newbie is likely to be long periods of underperformance. The 5-year chart for the QVM Rank shows the usual picture:
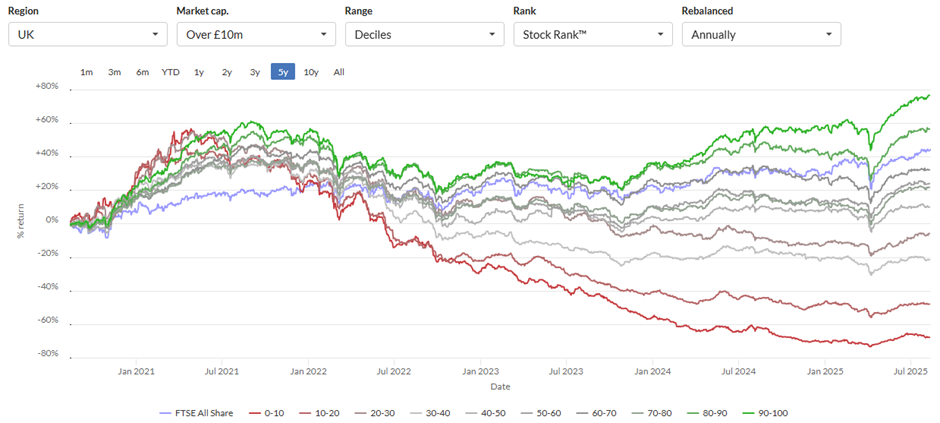
High Stock Rank stocks perform well, low ones don't, on average. Looking in more detail, there is a considerable period where the top decile underperformed. Investors who were buoyed by the strong performance of the annually rebalanced superstock portfolio in early 2021 would see the strategy underperform for four years, only reaching new highs recently. It would also have underperformed the UK indices during most of this period (on a price basis). While experienced investors will know that this is what can happen even with known market-beating strategies, a newer investor may be put off by this and bail just as the strategy starts to perform again.
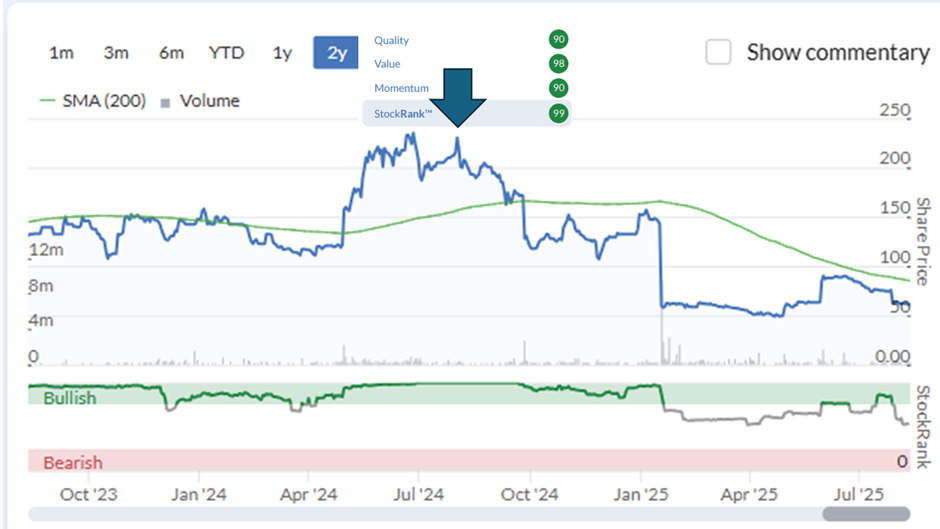
The other issue is that having a high Stock Rank doesn't preclude a company from issuing a big profits warning. Take IG Design (LON:IGR) , for example. The stock had a 99 Stock Rank in August 2024 and lost investors 75% of their money over the following six months:
This doesn't mean that the Stock Ranks don't work on average, just that the variation in performance of a single Super Stock is still very wide. The Stock Ranks are incredibly useful for new investors as they enable them to easily avoid the types of stocks most likely to be losers. However, buying into one or two of even the highest-rated Super Stocks isn't enough to guarantee success. The evidence points to Super Stocks outperforming on average, and over long periods of time.
Find your style
One of the implications of the original question was that buying stocks at 52-week lows would be psychologically challenging for newer investors. This is true. However, it is true because all winning styles are psychologically hard. Buying stocks that are hitting 52-week highs is also difficult for many investors, which is why this strategy is also a winner. Momentum investing is also tricky, as it requires the discipline to exit a winning stock after the share price has peaked. Newer investors who bought into Warpaint London (LON:W7L) during its phenomenal rise are probably still holding, as the share price has halved and the Momentum disappeared, as they lack the market experience of how these things tend to play out. Quality investing, holding good stocks for the long term, sounds easy, but spotting companies with a genuine moat and having the nerve to hold is genuinely difficult. Strangely, Quality Investing may be the style that least suits newer investors. This is because the skills of analysing a business, its true moat, and its ability to reinvest capital at high rates, are very hard to do for any extended period of time. Newer investors are unlikely to have developed these skills.
With almost all successful styles of investing psychologically hard to implement, the focus of the newer investor should probably be on finding the style that suits them best. The benefit of finding a style that works for them is that investors will be far more sanguine when the periods of underperformance occur. Over the last few years, my focus on smaller stocks, where I believe I can have an informational or analytical edge, has cost me performance, as larger UK companies have significantly outperformed. I've worked hard to generate index-like returns. However, my experience tells me that these conditions don't tend to last forever. The valuation gap between the larger companies and the small caps is now so large that it would be hard to envisage this situation continuing over the next five years. However, if it did, I would be relaxed about it, as I would be compounding large dividend payouts into stocks at ever lower valuations and higher yields. Eventually, this type of anomaly tends to correct itself, but I just don't know when it will. Less experienced investors may not be able to have this perspective.
Conclusion
I don't think any particular style of investing is more or less suitable for newer investors. When starting out, the key aims should be to gain as much knowledge and experience as quickly as possible. This is done by having a more diversified portfolio, even if it ends up suboptimal from a trading costs perspective. The increased learning opportunities are likely to outweigh the negative impact on performance. The Stock Ranks can certainly help newer investors, and if investors simply didn't invest in stocks with a low Stock Rank, they will almost certainly do better overall. However, the focus of newer investors should be on finding a strategy that is a good fit for their unique personality and circumstances. For some, like me, that may be a more contrarian approach. Others will find a more natural fit with Momentum or Quality styles, or a mix of these. Finding a good approach and sticking with it is likely to be the key to generating good investment results for decades to come.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

31 comments
A very simple strategy for a beginner would be to buy and hold in an ISA and/or SIPP a global index-tracking ETF, such as iShares Core MSCI World UCITS ETF USD (Acc) (ticker code SWDA). Unlike shares there's no stamp duty of 0.5% to pay when buying it because it's an ETF, it's extremely well diversified because it invests in over a thousand companies worldwide, and its total expense ration is just 0.2% per year. It's boring, but it's likely to beat most fund managers and private investors in its total return over the long term.
Alternatively, if a beginner investor would like a portfolio that provides an income, another very simple strategy would be to buy and hold in an ISA or SIPP a global dividend paying ETF, such as the VanEck Morningstar Developed Markets Dividend Leaders UCITS ETF (ticker code TDGB).
I think that even ETF investing requires some knowledge of what you are investing into and how concentrated the ETF is. This experience may also take a while to understand/learn.
There are numerous different types of ETF eg. synthetic. In addition the concentration in certain markets may not suit the individuals risk profile eg. SWDA has nearly 70% in the US (in line with the MSCI Global index), but some may say that this is a very high-risk approach currently.
Whilst I agree an ETF potentially is an easy and possibly cheap way to spread risk, it by itself can also create concentration risk.
KevinS1 made the good point that: "the concentration in certain markets may not suit the individuals risk profile eg. SWDA has nearly 70% in the US (in line with the MSCI Global index), but some may say that this is a very high-risk approach currently."
Another global ETF that's worth considering is iShares MSCI ACWI UCITS ETF USD (Acc) (Ticker SSAC), which invests in emerging markets as well as developed ones, so its US holding is 60% rather than 70% and therefore perhaps less risky than SWDA.
Another approach would be to buy four ETFs, one which invests solely in the US stock market, e.g. iShares Core S&P 500 UCITS ETF USD (Acc) (Ticker CSP1), another which invests in large companies in the developed world excluding the USA, e.g. Xtrackers MSCI World ex USA UCITS ETF (Ticker XMWX), and a third which invests in short-term GBP bonds, e.g. iShares GBP Ultrashort Bond UCITS ETF (Ticker ERNS), and a fourth which invests in gold hedged to GBP, e.g. WisdomTree Physical Gold - GBP Daily Hedged (Ticker GBSP), and weight them according to one's judgement of risk, for example having a target of 25% of the portfolio in each ETF, and rebalance once a year to the target weightings. However, this approach is more complicated.
I agree. I only started understanding about investing about 6 years ago (I’ve always had a pension but I didn’t understand the benefits of investing in shares) and stated buying vanguard funds. I now believe I’m ready to start investing in individual stocks.
timarr
1 to 8 absolutely. 9? this should be the hobby.
I agree this should be the hobby Silver Moon. ;-)
I have a few other hobbies though too. :-)
Hi Tim
Thanks for these points (and Ronald for a thought provoking article).
‘Utilise tax shelters - SIPPs if you have self control issues, ISAs if you don't. If you hit the 40% tax bracket focus on SIPPs.’
Can you elaborate on this a little? Why do you need better self control for an ISA? Also I thought it was always better to fill an ISA first regardless as whilst you pay tax on the £20K you put in, the eventual profits are tax free?
Thanks
D
Hi David
On self-control - with ISAs you can withdraw as you want, with SIPPs you're locked in until 55, so you can't simply withdraw the funds because you're worried or decide you want to buy a new Ferrari.
The tax benefits are roughly equivalent. With ISAs you're investing income you've paid tax on but can withdraw with no tax. With SIPPs you get tax relief on the way in and pay tax on the way out.
If you're paying 40% income tax on earnings then SIPPs are clearly the better way to go, as you receive tax relief at 40% on the way in and can control your tax rate on the way out (20% tax applies up to about £51K in annual withdrawals assuming no other source of income). In the same situation on ISAs you'd pay 40% on the way in and nothing on the way out.
On the other hand, the benefit of receiving a tax free income from ISAs can't be underestimated, so if you are able to control the spending impulse then there's great benefit in utilising the tax break if you have the spare funds to do so. I've seen commentators here argue that £20K a year isn't worth bothering with, but as someone who's been putting money into them for 30 years I can assure you that they're wrong.
There are other considerations, of course. Governments have interfered more with pensions than ISAs, but that may not hold going forward. The tax relief benefits on offer are among the best in the world but they are in the gift of the politicians, so it's always best to err on the side of caution.
Personally I have about 50/50 in SIPPs and ISAs but that's an accident of history more than any kind of smart planning. It does give me enormous flexibility as I head towards retirement.
I should perhaps add that I have never paid capital gains tax at any point in my long investing career, and never will. But to get to that point you need to start young and keep going.
timarr
The ISA vs SIPP choice has indeed become quite complicated now Rachel from Accounts is seeking to bring pensions within the scope of IHT (inheritance tax). In some scenarios the possible tax haircut is quite astounding.
It used to be that SIPPs were the better option - you got tax relief on the way in and your beneficiaries could access what you left behind tax-free if you die before 75, or if you live longer, then at their marginal rate of income tax (which could easily be zero should one of your children spend years at home raising grandchildren).
Now everyone will be emptying their SIPPs as quickly as is tax-efficiently possible, leaving the ISAs to fund later life.
And yes, if you have a spouse then a joint £1m ISA pot is well within reach - you don't even need to marry Lord Lee. If you have the ability to put aside 2 x £20k = £40k each year then it only takes around 14 years at 7% returns to exceed the £1m mark.
Putting aside £40k a year is probably the greater challenge, rather than achieving the 7% return. We just have to hope that 7% exceeds inflation over the coming years.
The ISA vs SIPP choice has indeed become quite complicated now Rachel from Accounts is seeking to bring pensions within the scope of IHT (inheritance tax). In some scenarios the possible tax haircut is quite astounding.
Tax relief is always within the government's gift, it's never a right.
Wealthy retirees have tended to get beneficial treatment because they're more likely to vote but stretched government's finances strongly imply that that group will be targeted going forward by governments of all hues. The rolling commentary around property taxes is an indication of where the next set of changes will be made.
The general rule is that never expect that any tax relief benefit will be maintained indefinitely so don't operate as though it will. Pensions are for funding retirements, not for giving to children. Homes are for living in, not financial investments. Etc, etc.Going forward if you want to give children money then the time to do it is while you're alive, not when you're dead.
timarr
Giving money away early sounds all very sensible, until you find yourself in the business of writing a £7k cheque every month for dementia care (for my mother, I should hasten to add, rather than myself!)
Balancing inheritance tax against care costs in later life is a very miserable dilemma.
By bringing pensions into IHT the government is incentivising people to deplete their pensions and fall back on the state for care costs in later life, rather than self-fund. It will not end happily, for the elderly or for the Treasury.
The UK is sitting on a ticking time bomb of care costs for the aged and the arbitrary divide between NHS and council funding can't be ducked for ever.
As ever, wise words Tim!
The question "What is the right strategy for a newbie investor?" is a very difficult one to answer. I will have a go even though I know my answer will be far from perfect. 1) consider your own situation with questions like: Do you have a steady job and predictable income? What are your debts? What are your assets? Have you got a pension plan? Do you expect any inheritance ? Do you have dependents that rely on you to support them? 2) What are you looking for eg capital growth or income? 3) What level of risk are you willing to take on? Would you lose sleep if your portfolio lost 10% in a week, or 25% since you bought it? 4) What is your anticipated holding period? Day trading or buy and hold for ten years? 5) How are you going to achieve a reasonable degree of diversification? 6) Are you living at home with parents, or renting, or do you have a mortgage? Do you have a plan to change that situation? You may need a financial advisor to get you through this maze! Finally review all your answers and consider whether they fit together in a coherent manner. Eg it might not work if you income is unpredictable, you have no savings or pension plan, your investments are very high risk, and you don't know whether you will hold them for a day or a decade. What if you are forced to sell at a big loss to pay the rent? In my opinion deciding upon your individual strategy is the most important and most difficult thing to do. I haven't even scratched the surface here! How does you strategy fit with Quality, value and momentum ranks? I expect that Stockopedia has videos and ebooks to get people through this maze. Also, before you buy anything, you should have well developed criteria about the situations in which you would sell.
The answer is to begin investing half-way up the ladder. Save cash while following at least one hundred good companies. Sure it will be boring but you need to get to know your chosen companies like your back yard. Self-discipline will be at a premium but there will be at least two opporunities to Buy the Dip every year and this is where having the cash comes in. The Trump Slump back in April and the threat of ligitation regarding car showroom commissions four or five months prior to that can give the lift a newbie investor needs. Or anyone else come to that. Today's Secure Trust Bank (LON:STB) 5-year chart is proof thta this can work:
Your article is a great read Mark, guaranteed to get the grey matter moving in the Stocko direction. I'm the last person to heed my own advice, never have much more than the latest dividend payments to play with.
There are so many points here to unpick, I can't get into it all.
Although I'll start from the beginning and then try and least narrow down things I would be asking as many of my friends often want investment advice (which I do not want to give).
First is - why do you want to invest? Seems a silly question but different folks, different strokes. As has been alluded before, if you come into a decent inheritance - what you wanting to risk that for? Buy some BTL's/trackers/gilts etc sleep soundly and worry about how you will pass that on to you family.
If, on the other hand, you're a keen and eager 20 something that has never had any wealth history and want to be in a position to make something to both enjoy in future years and pass on the answer will be different.
Hows much you earn and your risk profile will also play a big factor.
Do you own a house? How big is your mortgage and what kind of rate are you paying? For some people using the 'investment' money, may be better off paying down a higher interest mortgage, as invariably houses as an asset are pretty much bullet proof - and you get to live in what you invest and aren't generally bothered about negative equity over the long term, where as you should see some people who lose 10-20% in a month on equities and get massively stressed.
Diversified portfolio should just be that. Are you putting enough away in your pension? Other assets are available, I've long said rightly or wrongly, I like a nice watch. If I come into some money I might buy 'insert overpriced luxury brand' but, I've never lost any money on a watch and generally make 200-500% over 20 years (jesus am I that old!).
Cars, whisky, wine, if it all goes tits up, you do still have tangible assets that you can still use and enjoy.
And even if you choose to focus and concentrate on stocks - then even maths bods don't get it right all the time :)
Take time, relax, don't rush and try to enjoy the smaller things too - as a former poker player I used to get caught up with the seriousness at big games, big money and lost all the enjoyment I had. It began to feel like 'work'. Unless you want this to be a job, then have a flutter now and again (although go back to the reasons why you want to be in the 'making money' business') cause it's not for everyone.
Really great article Mark. It pretty well describes my journey down to a tee.
The only things I would add are :
- it took me a few years to focus on only what I knew and understood and to ignore everything else. In my case it was smaller manufacturers, a sector where I spent my career as an FD
- the importance of Director share transactions. Again, it took me a good while to take an extremely sceptical view when Directors made large sales, instead of just taking in the PR guff and fellow shareholders’ inherent bias. Its often about the timing of the sale as much as the reason, I personally have found.
Lord Lee advocates watching director buys. There may be a non commercial reasons for sells.
Thats why I said Directors transactions
And why I said its the timing of sales as much as the reason to sell
djl - the whole point of this article is about finding what works for you. Its purely personal and not meant to be a universal solution for everyone.
Dear me, this site is really hard work at times…..
Excellent article.
I wonder if it is possible to learn about investing without having a sizeable number of losses. I suspect not.
In which case the key to learning is to invest only a relatively small amount in the first couple of years.
Personally when i started i had a run of wins. Which as Mark notes is very poor training, it leads to over confidence and an inevitable large loss later on.
Better to lose a small amount at the start. And combine this with reading at least 20 of the top books on investing.
Good point on reading lots of books. I hope mine makes the top 20 ;-)
A few years ago, I came up with a list of my own book recommendations here: http://excellentinvesting.org/...
There may be a few I'd add now, but in general, it remains a good list of books to build investing skill, including the psychology and portfolio management side, which often gets missed IMO.
Nice article. I'm impressed with a first in maths. I really struggled with higher level maths when studying engineering but found my niche in computers where understanding the binary number system is important. There are 10 sorts of people in the world, those that understand the binary number system and those that don't.
LMAO I’m a 1 definitely
Actually, there are three types of people in the world, those who can count and those who can't.
The best thing a new investor can do is buy a fund(s) or investment trust while they harness their skills. Instant diversification. Keep it simple and low cost. Choose shares over time but make these a low proportion of your investments. In fact, you can choose shares and check which funds broadly mirror your preferences. I'm not sure funds and share picking are mutually exclusive. If you choose funds you still need to pick good funds. My preferred share investment style is now dividend investing. Quality investing requires some insight into the future, momentum investing (following the crowd) never made sense to me and contrarian investing requires good sales growth predictions. I got hit with ultimate products recently using this contrarian approach despite a low EV to sales metric. On dividend investing I try to use the stock rank (75+) coupled with stocko dividend screens or metrics. Also read as much as you can. 'The little book of big dividends' by Carlson is great, Algy Hall '4 ways to beat the market', 'Equity edge' by Mark Jeavons and the stock screens on here. Roland Head's/Mark S dividend screens are really good. Lord Lee ' How to make a million slowly') is good book and a good read too from a personal perspective. The other tip is be patient and don't chase losses. You don't need to have a high IQ to be a good investor but you do need to be disciplined in pursuing best returns.
I expect there are one or two views on momentum and quality investing expressed by you here that might encourage a debate...
I would fully expect that. There are far greater brains than mine own who advocate momentum investing and the evidence is certainly there. I think style can be a matter of temperament. I'm a half glass empty kind of person which may explain my caution.
100% agree on the book reading for new investors. The Naked Trader, Zulu principle, Trade like a stock market wizard, The art of execution, are other good books that will show different techniques and could help newbies find their own style
First class article, with much I have already found mirrored by my own feelings and experience of being a "newbie investor". I only wish I had discovered Stockopedia some years earlier before losing real value through relying on fund managers to look after my investment needs, while taking their own cut for mediocre and self interested performance.
Great article many thanks. I just enjoy it win some lose some, pick your self up, I far more wealthy now than I’d of ever been saving away in a deposit account.
I wish though corrupt Directors lost everything house the lot !