Wise share price up 5% with outlook at top end of the range

Analyst’s view:
It did take me a little while to warm up to this one. But the share price has made weak progress over the last three years and I believe it has now "grown into" its valuation. Indeed, I would argue that it offers the valuation metrics of an established, quality business, but also offers the growth prospects of a younger and more exciting business. Unless there is a dramatic change, I'll be staying positive here.
Up 5% at 869.8p (£8.9bn) - H1 FY27 Results
This currency specialist continues to grow at impressive rates. Let's give you the highlights table:
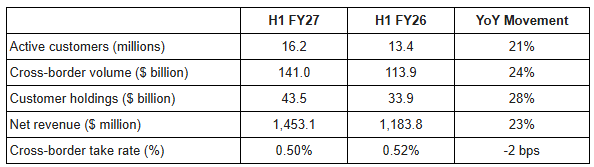
While cross-border revenue growth was strong at 19% (to $705m), it's the growth in "Card and other revenue" that really impresses (up 36% to $397m).
Comment by co-founder, CEO and 18% shareholder Kristo Käärmann:
“More than 16 million people and businesses used Wise in the past six months. These customers moved $141 billion across borders, up 24% year on year. Customers also used Wise for more, spending $27 billion on Wise cards and increasing holdings by 28% to $44 billion, including $11 billion held in Wise Assets.
We expanded the infrastructure behind this growth. We added our ninth direct connection in Malaysia, reducing our reliance on intermediaries and helping us move money faster and at lower cost. 78% of transfers are now instant, while customers paid an average fee of only 50 bps to move money around the world in the period.
Note the deliberate decline in the "take rate" (fee for moving money), a theme we have revisited here many times.
Wise has sacrificed this in favour of growth - a bet that has been paying off as it continues to grow both the top and bottom lines at impressive rates.
Also note the reference to their "ninth direct connection in Malaysia, reducing our reliance on intermediaries".
The big disappointment for Wise this year was their failure to achieve the same in the United States. The application for a national trust bank charter failed, so they continue to rely on intermediaries and remain for now merely a money "transmitter" rather than anything that resembles a bank.
Outlook
FY27 results are heading for the top end of target ranges:
Wise expects FY27 net revenue growth to be in the upper half (17.5-20%) of our 15-20% medium-term target range on a constant currency basis[1]
Wise expects FY27 income before tax (‘IBT’) margin** around the top of our 20-25% range
Graham's view
We've had a positive view on this one in 2026 - my last coverage was in October at a share price of 882p.
It did take me a little while to warm up to this one. But note that the share price has made weak progress over the last three years:
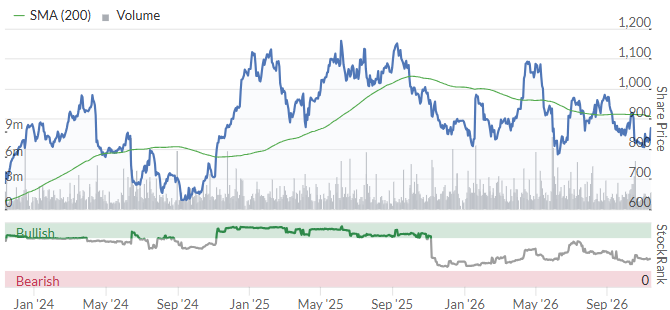
During this time, revenues have made impressive progress:
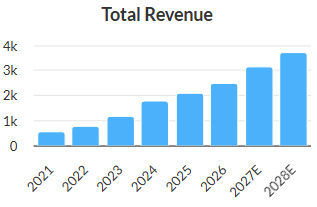
With profits holding up their end of the bargain - $600m+ forecast this year - the earnings multiple has compressed.
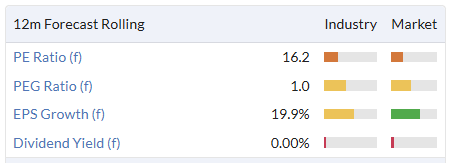
16x is actually below the bottom end of the range for the last 1-2 years, according to this chart:
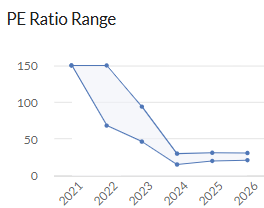
Therefore, I see Wise as an example of a company that has "grown into" its valuation over the last few years.
It's now offering the valuation metrics of an established, quality business.
But to my eyes, it also offers the growth prospects of a young and more exciting business.
There is no funny business in the accounts. Just clean profits ($249m in H1, up 6%).
And for a financial business of this type, management do not attempt to blind investors with complexity. It could be argued that the commentary provided by Wise with these interim results is a little sparse, but at least it is straightforward and easy to understand - I would argue that it's easier to understand than the commentary we receive from many simpler businesses.
Unless there is a dramatic change, I'll be staying positive on this.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on Wise (4)
Comments here are also visible in the Daily Stock Market Report
Graham, have you pasted the Wise (LON:WISE) summary into the Aviva (LON:AV.) notes?
Good news that the Wise (LON:WISE) Belgian prosecutors office probe is in the rear view mirror, with no blame apportioned. The business is growing as planned alongside the ongoing buyback. They just need to achieve the US banking licence to get positive sentiment back on track.
Wise (NSQ:WSE)
i would agree its excellent news ref belgium - if nothing else the belgium issue will have been a wake up call for directors that potentially every country they deal with may have spats with them. their ability to manage these obstacles in their path without material wosrt case downside is key - money laundering is such that that the highest of the high standards are expected in many jurisdictions - not easy when you are a volume provider charging low fees.
Interesting article yesterday here
https://s-curve.news/articles/2026-11-12-wise-account-closures
ref volumes etc of people having their accounts closed with no warning (and funds potentially frozen) - in some respects this is excatly what Wise need to be doing - if there are any doubts put a hold ask questions and provde you are not blindly letting any funds flow through that may look sketchy. customers wont like it but thats just the risk they take if they are transferring stuff all over the world - volumes flagged seem uber uber low - well below and level that would worry me.
the longer the shareprice flatlines whilst they are increaisng profits at a lick each 6 months tne better value the shares look- i am still on the sidelines here at present.
Wise (LON:WISE)
Morning all
Wise (WISE) — H1 FY27: Belgium, Big Banks and Building the Railway
TL;DR:
Wise has settled its Belgian prosecutor investigation without admitting wrongdoing in a ‘financially immaterial’ way. This removes a significant legal uncertainty; separate regulatory remediation remains outstanding.
Two of North America’s 20 largest banks have also gone live on Wise Platform.
Net revenue grew 23%, cross-border volume 24%, and Platform volume nearly 50%.
The infrastructure thesis continues to strengthen.
1. Belgium — an important distinction
The most reassuring development was Wise Europe’s agreement to fully settle the Brussels prosecutor investigation, without admitting wrongdoing.
During the earnings-call Q&A, CFO Emmanuel Thomassin confirmed that the settlement terms were confidential but financially immaterial.
This removes an important source of legal and reputational uncertainty.
There remains the separate National Bank of Belgium supervisory proceedings concerning AML/KYC shortcomings; The NBB’s remediation deadline of 31 January 2027 remains in place.
One significant risk has been resolved; the wider regulatory issue has not yet been completely closed.
2. Two major North American banks
Including Morgan Stanley, Wise now works with three of the region’s twenty largest banks. The new relationships went live on Wise Platform during H1.
The identities and commercial economics of the two new relationships remain undisclosed.
During the Q&A, Kristo Käärmann explained that Wise may already capture most eligible international-payment flows at some smaller banking partners. Early penetration at major banks currently remains relatively limited.
Wise Platform volume grew nearly 50% year-on-year, roughly twice the rate of Wise’s overall cross-border business (24%).
Its share of total volume has consequently risen from 4% to 6% in just eighteen months, reinforcing its emergence as a second growth engine.
3. Building the railway
Wise delivered 23% net revenue growth and 24% cross-border volume growth while maintaining a 23% pretax margin.
Transaction expenses benefited from direct payment-system connections and greater bargaining power with banking partners, although accounting effects flatter the headline year-on-year reduction.
Wise’s nine direct payment-system integrations progressively reduce reliance on intermediaries, allowing Wise to lower customer prices while expanding its network.
Conclusion
The Belgian settlement removes a meaningful legal overhang, although NBB remediation remains a timely milestone in early 2027.
The arrival of two major North American banking partners provides further evidence that Wise’s infrastructure is gaining institutional acceptance.
The long-term opportunity isn’t persuading banks to adopt Wise, but becoming increasingly integral in international-payment flows.
Wise is still building the railway. Increasingly, other banks are choosing to run their trains on it.
Disclosure: Long Wise.